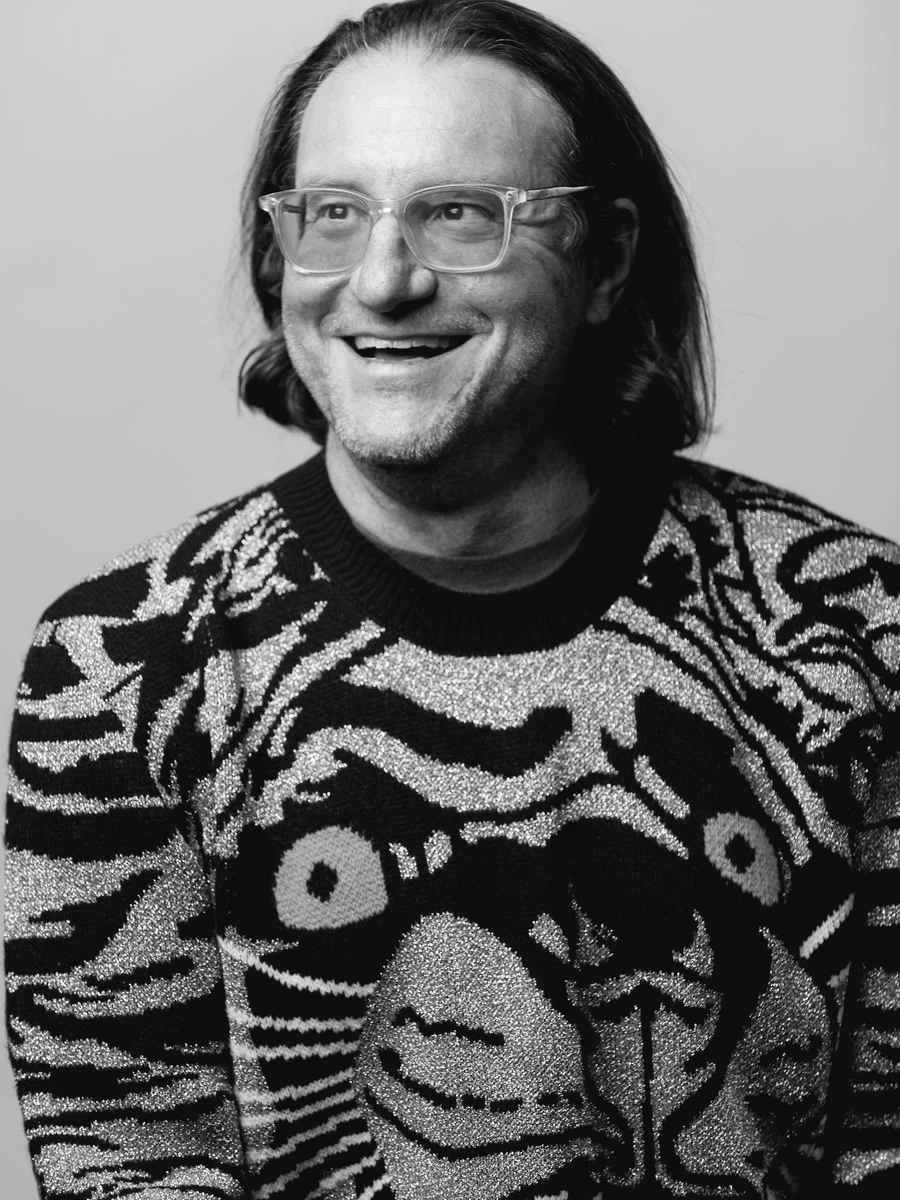
Brad Feld
Co-authored Venture Deals and co-founded Techstars; made VC mechanics public knowledge.
Formation: computers, MIT, and Feld Technologies (1965–1993)
Feld was born in 1965 and grew up around Dallas. His current biography reports BS and MS degrees in Management Science from MIT but gives no company date. In his 2011 Stanford account he says he started Feld Technologies in 1985 and Dave Jilk joined in 1987; Foundry's 2008 team history instead says he created the company with a partner in 1987. The dossier preserves this unresolved 1985/1987 chronology conflict rather than inventing a formal-founding distinction. [retrospective witness · moderate] current bio · Stanford transcript · Foundry history
Feld Technologies supplied three later investing inputs: the ability to interrogate software as a user/builder; experience with small-business cash, customers, partners and people; and liquidity/relationships after the 1993 AmeriData sale. Later interviews round the proceeds to a few million or about $2 million. No transaction document was located, so exact proceeds and ownership remain self-report. [retrospective witness · moderate] Growth Everywhere
This operating experience is real but bounded: a 1980s/early-1990s custom-software business does not automatically confer pricing, hardware, consumer, regulated-industry, or late-stage expertise. Its most transferable contribution is the habit of testing a product and founder response directly. [researcher inference · strong]
Personal angels, Intensity/SoftBank, and the accidental-VC transition (1993–1997)
After the 1993 sale, Feld reports roughly 40 personal angel investments during 1994–96, including NetGenesis, Critical Path, and Harmonix. He describes this as a rapid apprenticeship across founders and boards. The count, names, costs, losses and proceeds are incomplete, so the visible successes cannot support an angel hit rate. [retrospective witness · moderate] MeetInnovators
The current About page compresses entrepreneurship and investing into combined “over 40 years” experience; a dated direct account says Feld started investing in 1994, and his longer career narration places the institutional “accidental VC” transition around 1996. The dossier therefore does not convert the combined biography shorthand into an exact investor start date. Intensity Ventures/SoftBank and later Mobius supplied institutional capital and team context distinct from Feld's personal balance sheet. [researcher inference · strong] current bio · 1994 direct account · Stanford transcript
The causal investment lesson is apprenticeship by repetitions: many small checks/boards may improve pattern recognition. The alternative explanation is selection/access after a favorable operator exit; without the full angel denominator, it is impossible to distinguish skill from network, cycle and survivorship. [researcher inference · strong]
Mobius: institutional scale, wins, failure, and redesign (late 1990s–2006)
Mobius exposed Feld to Internet infrastructure/software, larger teams/funds, and a severe cycle. He later calls one fund extremely successful, the next a complete disaster, and another dependent on one company; he recalls roughly 70 people and ten partners. These fund labels are direct voice, not securely mapped to legal vehicle names. [retrospective witness · moderate] SaaStr transcript
Interliant is the hardest company-level control. The SEC records Chapter 11 in August 2002, a 2001 net loss of $48.9 million, and later delinquent filings. A bankruptcy committee alleged transfers and fiduciary breaches involving Feld Group, Mobius and Bradley Feld; the accessible decision addresses procedure and does not establish Feld's personal liability. [contemporaneous record · strong] SEC order · court decision mirror
The fund-level adverse record is also concrete: as of June 30, 2023, WSIB reported Mobius Technology Ventures VI with $82.35 million paid in, $49.28 million distributed, 0.6x and -5.80% net IRR. One LP/vintage is not all Mobius, but it prevents a success-only chronology. [contemporaneous record · strong] WSIB p.6
Feld links Mobius adversity and organizational complexity to Foundry's small equal-partner design. That mechanism is plausible but retrospective: no controlled comparison shows a four-partner firm caused better outcomes, and Foundry later added partners and vehicles. [researcher inference · moderate]
Boulder, Techstars, and ecosystem construction (1995–present)
Feld moved to Boulder in 1995 and later helped cofound Techstars with David Cohen, David Brown, and Jared Polis. Techstars was incorporated November 14, 2006 and ran its first class in 2007. The institution joined mentorship, compressed experimentation, founder peer learning and a national/global network. [contemporaneous record · strong] Techstars history
The investment mechanism is indirect but testable: teaching and community can increase trusted inbound leads, repeated founder observation, references, co-investors and emerging managers. Feld's Give First doctrine makes the relationship less transactional in the immediate interaction. [investor-stated · strong] Give First definition
The skeptical boundary is essential. Techstars entities, accelerator investments, sponsors and founders have distinct economics; not every graduate is a Feld or Foundry investment. Dense networks can create homophily, signaling and opportunity-allocation conflicts. Reporting on centralization, sponsor dependence, program closures and layoffs concerns the institution and later management; it does not by itself establish personal misconduct or causality by Feld. [researcher inference · strong] institutional history · February 2024 reporting · August 2024 reporting
Foundry: small partnership, themes, product, and collective commitment (2006–2013)
Foundry's original public architecture was a small experienced group of equal partners making collective decisions. It paired broad themes—protocols, distribution, human-computer interaction and related shifts—with direct product use and independent judgment. A seed investment was a full institutional commitment, not an option. [investor-stated · strong] Who Are We · themes · seed
The mechanism has four stages: themes focus search and learning; product use produces first-hand evidence; independent partner votes fight social proof; target ownership/reserves make winners matter and support them over time. Quick passes preserve scarce partner capacity. [researcher inference · strong] decisions · quick pass
Visible outcomes are real but attribution varies. Foundry's own theme-distribution post attributes Zynga to Brad and other deals to Ryan/Jason/Seth/all; issuer filings show shared entity control. Fitbit records Feld board service and a false-negative/re-entry story. SendGrid is specifically Ryan McIntyre-led/mentored, although Feld later served as a director. [contemporaneous record · strong] theme distribution · SendGrid post
Select, Next, partner funds, and network-driven expansion (2013–2022)
Foundry Select (2013) added $225 million for later rounds in existing winners. Next (2016) added $500 million for direct growth and partner-fund investments. Next 2018 added $750 million and described seven equal partners, full-lifecycle support, sometimes more than 30% ownership, and preference for net cash-on-cash over interim IRR. [investor-stated · strong] Select · Next 2016 · Next 2018
In 2022, Foundry named its system “network-driven investing”: partner funds were not passive diversification but sources of relationships, market intelligence and company referrals. This is a genuine evolution from a pure four-partner thematic firm to a multi-vehicle network. The public size record says $225 million in many posts and $232 million for each of the first four funds in the network essay; commitment, investable capital, rounding or vintage scope may explain it, but the exact reconciliation is unavailable. [investor-stated · strong] network essay
Expansion creates falsifiable advantages—more geographically diverse lead flow, earlier trusted access, and better references—but also fee layering, circular validation, information conflict, portfolio overlap, and partner-attention dilution. TMRS's positive 2022 interim marks are one-LP valuation snapshots, mostly unrealized, not proof the network generated cash returns. [contemporaneous record · strong] TMRS report
Teaching, transparency, and founder power
Feld's blog (since 2004), term-sheet series, Venture Deals, Mentor Manifesto, Do More Faster, and Give First doctrine form an unusually large public operating corpus. Its likely competitive effect is trust and common language: founders can evaluate the investor before a meeting, mentors can reuse norms, and networks generate feedback. [researcher inference · moderate] about · term-sheet series · Mentor Manifesto
Public teaching is not neutral proof of behavior. It can build brand, anchor industry norms, obscure coauthorship, and make favorable cases searchable while private failures remain hidden. The Mentor Manifesto belongs initially to David Cohen after a Jon Bradford prompt; Venture Deals is coauthored with Jason Mendelson. [researcher inference · strong]
Feld's 2024 governance statement—while supporting the CEO, “I work for her”—is useful because it treats board work as service rather than control. Yet collective veto, board authority, follow-on power and >30% ownership can materially shape a company. The right synthesis is accountable support: direct truth and fiduciary challenge without shadow management. [investor-stated · strong] EFI interview, 04:39
Health, capacity, and stopping as investment controls
Feld has written/spoken openly about depression, burnout and the dot-com period. These records matter to the investment biography because partnership judgment, portfolio coverage and communication depend on human capacity. They should not be used to infer diagnosis, fault or company outcomes. [retrospective witness · moderate] Tim Ferriss transcript
Two institutional choices operationalize limits. Foundry stopped new FG Angels deals after two years because the experiment required more attention than expected. Foundry also prefigured and later confirmed that it would not become a generational firm. Stopping is part of strategy, not automatically defeat. [documented behavior · strong] FG Angels · final fund
The boundary is Molekule and other capital-intensive failures: high ownership/follow-on can persist beyond risk reduction. Capacity stop rules must exist at both program and company level. [researcher inference · strong] Molekule 13D
Final-fund lifecycle and current state (2022–2026)
Foundry 2022 closed in 2023 and was announced in 2024 as the firm's final fund. The official announcement says 200+ companies, nearly 50 fund investments and at least a decade of continued portfolio work. In a 2025 transcript Feld described roughly 80 active companies, about 50 fund positions and only a handful of remaining new deals. Those are time-specific self-reports, not an audited current denominator. [investor-stated · moderate] final-fund announcement · Alpha transcript
The lifecycle test shifts from new-fund growth to stewardship: deployment pacing, reserves, board continuity, talent retention, key-person coverage, conflicts and cash distributions. An announced end does not eliminate incentive or performance risk; it makes terminal governance more important. [researcher inference · strong]
Profile synthesis
Brad Feld is best studied not as a lone picker but as a technical founder turned network-and-institution designer. His public record supports four linked capabilities: direct product fluency, explicit thematic filters, unusually open teaching, and repeated community construction. Together they plausibly generated earlier access and trust outside a single coastal hub; Foundry's collective partnership, meaningful ownership, reserves, and long support attempted to convert that access into venture outcomes. [researcher inference · moderate] product doctrine · Foundry themes · Techstars history
The strongest visible cases—Zynga, Fitbit, SendGrid, Gnip and FeedBurner—do not prove personal selection alpha. Zynga is the clearest Feld-attributed Foundry deal; Fitbit has a Feld board/re-entry record; SendGrid was Ryan McIntyre-led; every disclosed Foundry security belongs to entities under shared control, not to Feld personally. Public LP data are mixed: UTIMCO showed Foundry 2007 at 43.8% net IRR in 2017, while WSIB showed Mobius VI at 0.6x and -5.80% in 2023. [contemporaneous record · strong] Zynga filing · UTIMCO · WSIB
A testable account of the edge
Domain and period. The proposed edge applies most plausibly to early-stage software, Internet infrastructure, developer tools, networks, marketplaces and technically legible products from the mid-1990s through cloud-era venture, especially outside a single geographic hub. It is weaker for regulated science, hardware validation, late-stage price selection and public markets. [researcher inference · moderate]
Mechanism. Technical product fluency produces direct diligence; public teaching creates trust and legibility; community institutions and partner funds expand earlier lead flow; themes accumulate category knowledge; independent equal-partner decisions reduce social proof; ownership/reserves and long service preserve upside. [researcher inference · moderate]
Predictions. Relative to matched venture firms, new Feld/Foundry deals should show more founder/referral/partner-fund provenance, earlier product use, explicit theme fit, independent partner dissent records, meaningful ownership, longer board/support duration, and higher re-entry rates after decision-changing evidence. Network-sourced deals should outperform after stage/theme/price controls and generate distinct cold/geographic access. [researcher inference · moderate]
Falsifiers. The thesis fails if the complete funnel shows no source-channel or selection advantage; returns disappear outside a few outliers; decisive work belongs consistently to other partners; themes are assigned only after investment; network leads underperform cold search; ownership/capacity destroy net returns; or independent founders contradict support doctrine. [researcher inference · strong]
Alternative explanations. The dot-com/SaaS/social cycles, privileged operator/LP networks, Foundry partner labor, Techstars brand, company execution, geography, abundant capital, and winner publicity can explain the visible record without personal alpha. Missing denominator and cash flows prevent adjudication. [researcher inference · strong]
The strongest case against greatness
The strongest skeptical case is a power-law narrative constructed from visible winners, a vast self-authored archive, and a team/fund brand. Zynga, Fitbit and SendGrid may dominate the visible economics; SendGrid's lead was Ryan McIntyre, all major stakes were held through shared vehicles, and company outcomes do not identify cost-adjusted distributions. A complete denominator could show ordinary median results. [researcher inference · strong] investment Pareto
Mobius VI is a direct adverse fund control. Interliant and Molekule are severe company failures; Crucible liquidated without a transaction; FG Angels stopped; iRobot was missed; Moz/Mattermark constrain culture/data theses. Themes may be broad hindsight labels, Give First may double as sourcing/brand, and network-driven investing may compound homophily and fees. [researcher inference · strong]
The edge remains worthy of study because it is unusually explicit and falsifiable, not because greatness is proven. Contemporaneous IC records, full partner roles, passes/write-offs, security cash flows and audited vintage results could strengthen or overturn it. [researcher inference · insufficient public record]
Sourced chronology and learning path
| period | formation/action | evidence | learning carried forward |
|---|---|---|---|
| 1965–88 | Dallas/computers; MIT BS/MS; unresolved Feld Technologies 1985/1987 start accounts | current bio · Stanford · Foundry history | Technical product and small-business operating fluency. |
| 1993–97 | AmeriData sale; ~40 angels; Intensity/SoftBank/institutional transition | MeetInnovators | Repetition, network, boards, personal-vs-fund boundary. |
| 1997–2006 | Mobius scale, dot-com boom/crash, Interliant, organizational stress | SaaStr · SEC | Fund/firm architecture, candor, capacity, failure memory. |
| 2004–11 | Blog, Techstars, Foundry, themes, seed, term-sheet teaching | Techstars · Foundry | Public doctrine/community as investing infrastructure. |
| 2012–18 | Fitbit/Moz decisions; Select, Next, partner funds, Next 2018 | decisions · Next 2018 | Re-entry, lifecycle ownership, multi-vehicle/network expansion. |
| 2019–22 | Give First refinement; network-driven investing; Foundry 2022 | Give First · network | Boundaries, source-channel advantage hypothesis, final deployment. |
| 2023–26 | final-fund announcement, wind-down/new-deal tail, mentorship “third third” | final fund · Alpha | Stewardship, succession, cash-on-cash, terminal governance. |
The learning order for analysts is writings → talks → investment labs → philosophy → mental models → adversarial review.
1. Snapshot and testable edge thesis
Feld's proposed edge is technical-product judgment compounded by public teaching and networks, converted through a concentrated collective partnership. Product use and themes focus learning; transparent writing/Techstars/Give First increase trusted access; independent partner decisions resist social proof; meaningful ownership, reserves, board service and duration preserve upside. [researcher inference · moderate] product · themes · network
The thesis is most plausible in early software, Internet infrastructure, developer tools, networks/marketplaces and technically legible products from the 1990s through cloud-era venture. It is weaker for biological/regulatory science, hardware efficacy, late-stage price and public-market timing. [researcher inference · moderate]
Predictions: earlier warm/geographically distributed leads; direct product-use records; explicit pre-deal theme fit; independent partner votes; high ownership; long service; and network-sourced deals that outperform after stage/theme/price controls. Falsifiers: no advantage in a complete funnel, top-three dependence, post-hoc themes, consistently different lead partners, network underperformance, or weak cash returns after fees/reserves. [researcher inference · strong] profile edge
2. Core philosophy
- Use the product: observe workflow and founder response, while checking whether the investor represents the actual user. [investor-stated · strong] product essay
- Use themes, not narrow sectors: accumulate causal category knowledge without pretending to forecast one product. [investor-stated · strong] themes
- Decide independently and collectively: record each partner's view; do not outsource judgment to syndicate prestige. [investor-stated · strong] decisions
- Treat seed as commitment: reserve and serve, rather than buy cheap options. [investor-stated · strong] seed
- Own enough for a win to matter: fund/partner capacity, dilution and follow-on are portfolio decisions. [investor-stated · moderate] Next 2018
- Give first with boundaries: contribute before an immediate return is known, while preserving capacity/conflict clarity. [investor-stated · strong] definition
- Support, do not shadow-manage: tell the truth, recruit, connect and challenge while the CEO decides. [investor-stated · strong] EFI 04:39
- Stop when the system fails its design: FG Angels and Crucible show that walking away can dominate forcing activity. [documented behavior · strong] FG Angels
3. Sourcing
Feld's public sourcing system has six channels: technical/product curiosity; prepared themes; founder/portfolio referrals; Techstars and mentorship; Boulder/regional community; and partner funds. The channel evolved from personal angel/operator relationships into institutional network-driven investing. [researcher inference · strong] Techstars history · network
For every lead record: introducer, prior relationship, theme date, product-use date, economic interests, other vehicles eligible, partner sponsor, cold channels searched, populations missing, and independent references. A warm lead saves search cost but is not quality evidence. [researcher inference · strong]
Techstars, personal angels, Mobius, Foundry direct funds, partner funds and personal LP positions must never be pooled. Mentorship can be genuine and still create commercial access; the control is disclosure and allocation, not denial of dual benefit. [researcher inference · strong] vehicle table
4. Picking
Product. Use it or observe real users; map pain, frequency, time-to-value, retention, switching, reliability and buyer/user mismatch. Investor delight is not sufficient. [researcher inference · strong]
Founder/team. Look for obsession translated into action, learning after feedback, truth under bad news, recruiting and complementary capability. A founder need not agree with the VC; response quality matters. [investor-stated · strong] Stanford
Theme/market. State the causal shift, budget/user, boundary, adoption evidence and disconfirmers. Avoid themes broad enough to retrofit any company. [researcher inference · strong]
Decision card. Require independent partner votes, dissent, price/ownership, initial/follow-on capacity, next milestone, kill condition, governance owner, conflicts and evidence that would reopen a pass. Fitbit shows re-entry; iRobot shows category error. [researcher inference · strong] decision post
5. Deal and portfolio mechanics
Feld's 2010 seed policy stated checks from $250,000 to $10 million, all-partner engagement and willingness to follow on. The 2015 capacity post described fixed $225 million funds, roughly 30 companies/fund and about ten new investments/year. The 2018 Next description said ownership could exceed 30% across the lifecycle. These are dated policy statements, not universal company facts. [investor-stated · strong] seed · passes · Next 2018
A reusable portfolio model needs opportunity count, target ownership, dilution, initial check, reserves, partner/board capacity, correlation, duration, and concentration. Select requires a fresh opportunity-cost comparison for each “winner”; Next requires separate direct and partner-fund sleeves and fee look-through. [researcher inference · strong]
No public source supplies full reserve ratios, recycling, pro-rata use, loss ratio, write-off timing, sale discipline or ex-top-three returns. Acquisition consideration and IPO ownership remain proxies until cash flows are known. [researcher inference · insufficient public record]
6. Vehicle and incentive fit
Personal angel capital offers flexible duration but concentrated personal risk. Mobius/Foundry closed-end funds owe duties to LPs and face fees, carry, reserves, key-person and distribution constraints. Select concentrates follow-on capital in marked winners; Next adds growth and partner-fund exposure; FG Angels distributes economics/rights across syndicate backers; Techstars has separate institutional interests; Crucible introduced public-shareholder/redemption/deadline incentives. [researcher inference · strong] vehicle map
Ask for each deal: which legal vehicle; who approves; who benefits; duration; fee/carry layers; target ownership; reserve burden; liquidity horizon; geography/regulation; board/information rights; allocation conflicts; and succession/key-person coverage. [researcher inference · strong]
The 2022 final fund changes the operating equation: no future franchise fundraising can be assumed to retain partners/staff, while portfolio duties may last a decade. [researcher inference · strong] final fund
7. Team attribution and work with founders
Foundry's original four-equal-partner structure used collective investment decisions; later documents describe six or seven equal partners. Attribution must separate origin, mentorship, thesis sponsor, vote, capital, board, recruiting, follow-on, exit and narration. [researcher inference · strong]
Zynga is attributed to Brad in the firm's theme-distribution post; SendGrid is Ryan McIntyre-led/mentored; Fitbit establishes Feld board service but not sole sourcing; all three filings show fund/entity securities under shared control. [contemporaneous record · strong] theme attribution · SendGrid · filing map
Founder work should include direct truth, recruiting, references, financing strategy, crisis response and fiduciary challenge. Efficacy needs founder/board evidence; public doctrine alone cannot prove value-add. [researcher inference · moderate]
8. Views on the craft
Feld treats venture as a power-law craft constrained by fund mathematics and human attention: a small number of wins must matter, while partner service and reserves cannot scale without limit. Greatness is independent judgment, sufficient ownership, honest LP communication, direct founder support, learning from failure, and stewardship through liquidity—not deal celebrity. [researcher inference · strong] quick-pass arithmetic · LP candor
Access and selection interact: Techstars, writing and partner funds can improve access; themes, product use and collective votes attempt selection. A network is not selection proof, and public teaching is not behavior proof. [researcher inference · strong]
Risk is not one score. Separate product, market, founder/team, financing, ownership, governance, platform, regulation, hardware/science, security, reputation, concentration, key-person and vehicle risks. Name the evidence that reduces each and the person authorized to stop. [researcher inference · strong]
Interliant requires acquisition/integration, cash, reporting and conflict gates. Molekule requires independent efficacy and recapitalization gates. FG Angels requires partner-time gates. Crucible requires deadline/incentive/walk-away gates. iRobot requires a thesis-adjacency gate. [researcher inference · strong] labs
Failure review must preserve allegations versus findings, company versus investor causality, and unknown alternatives. A candid retrospective is learning evidence, not an acquittal or proof of foresight. [researcher inference · strong]
9. Signature bets and decision process
The signature cases are deliberately heterogeneous: FeedBurner tests product-use/protocol judgment; Zynga tests distribution and Feld/team attribution; Fitbit tests dissent and re-entry; SendGrid tests developer infrastructure and Ryan McIntyre credit; Moz tests culture against an ordinary outcome; Interliant and Molekule test failure; iRobot tests a pass; FG Angels and Crucible test stopping. [researcher inference · strong] nine no-hindsight labs
Readers should answer each lab’s invest/pass, kill, ownership/terms/capacity and next-check prompts before the reveal. A signature decision remains collective: sponsor, vote, capital, board, follow-on and outcome are separate. [researcher inference · strong] people map
Feld publicly prefers net cash-on-cash over short/intermediate IRR and, in 2025, again emphasizes cash-on-cash. That disciplines mark worship but is not a complete sell rule. [investor-stated · strong] Next 2018 · Alpha transcript
A vehicle-specific exit memo should separate company trajectory, security, cost, realized proceeds, remaining shares, dilution, reserves, taxes/fees/carry, LP liquidity, concentration and follow-on opportunity. Holding a winner can preserve convexity; it can also concentrate a fund and defer distributions. [researcher inference · strong]
No public record reveals Foundry's tender/IPO lockup sales, distribution-in-kind rules, recycling or decision owners for the main cases. Therefore the dossier does not infer a universal “hold forever” rule. [researcher inference · insufficient public record]
10. Mental models and maxims
The supported index is: use the product; themes as falsifiable filters; independent decisions and evidence-based reopening; seed as service/reserve commitment; ownership with concentration re-underwriting; Give First/network boundaries; CEO-support governance; and bounded experiments/walk-away rules. [researcher inference · strong]
Their dated origins run from Feld’s 2006 product essay and Foundry’s 2008 themes through 2010–12 seed/decision doctrine, Techstars/Give First, 2018 lifecycle ownership, 2024 CEO support, and the FG Angels/Crucible stops. They are reconstructions, not eight verbatim maxims.
- Freeze the theme and why-now before the pitch.
- Use/observe the product and log evidence, not taste.
- Collect independent partner views before social proof.
- Record the dissent reason and re-entry evidence.
- Treat seed as full service and reserve commitment.
- Set ownership/check/capacity before enthusiasm.
- Pass quickly and explain “not us” honestly.
- Separate economics and control in terms.
- Mentor with directness, consent and conflicts.
- Give first within a time/capacity budget.
- Re-underwrite follow-ons against external alternatives.
- Stop experiments when their operating model fails.
- Report company, security, vehicle and LP return separately.
[researcher inference · strong] Each step traces to the 24-source writing analysis; it is a synthesized checklist, not a verbatim Feld algorithm.
11. Evolution and contradictions
The system evolves from operator/product learning (1980s–2006), to themes and a four-partner early-stage model (2006–13), to Select/Next/partner funds (2013–22), and finally a six-partner finite-fund stewardship phase (2023–26). Durable beliefs are product evidence, founder learning, independent judgment, long relationships and candor. [researcher inference · strong]
Unresolved tensions remain: Stanford's 1985 Feld Technologies start versus Foundry's 1987 account; combined “over 40 years” entrepreneur/investor shorthand versus distinct investing from 1994; $225m/$232m early funds; four versus six/seven partners; themes versus network-driven sourcing; founder control versus high ownership/veto/boards; seed commitment versus FG Angels; and cash-on-cash preference versus public mark/IRR evidence. [researcher inference · strong] chronology · network evolution
| doctrine | corroborating behavior/outcome | adverse or unresolved control |
|---|---|---|
| use product | FeedBurner/NewsGator and later product posts | no outcome comparison; familiarity bias |
| decide independently | Fitbit/Moz pass-and-reopen story | full vote/pass ledger absent |
| seed as commitment | large disclosed Foundry stakes/follow-ons | Molekule severe impairment; reserve ratios absent |
| Give First/network | Techstars and partner-fund system | commercial access, homophily and fee layers |
| support CEO | Feld board records and direct doctrine | founder-side efficacy not measured; real board power |
| stop experiments | FG Angels and Crucible termination | counterfactual staffing/deal opportunity unknown |
| cash-on-cash | explicit 2018/2025 metric preference | public results mostly IRR/marks/securities, cash ledger absent |
[researcher inference · strong] The pattern is coherent but not uniformly proven; each attractive rule has a failure mode in the same record.
12. Failures and limits
Interliant demands acquisition/integration, cash, reporting and conflict controls; Mobius VI controls vintage economics; Molekule demands independent efficacy and recapitalization gates; Crucible tests deadline/walk-away; FG Angels tests capacity; iRobot tests adjacency; Moz and Mattermark test ordinary outcomes. [researcher inference · strong] failure ledger
Limits include missing IC/funnel/cash-flow/partner-role records, winner publicity, team/vehicle attribution, changing fund architecture, era effects and no matched base rates. Failure review must separate allegation from finding and company from investor causality. [researcher inference · insufficient public record]
| field | required question | kill / reopen condition |
|---|---|---|
| vehicle | Which person/fund/syndicate is eligible and why? | Kill if allocation or beneficiary is unclear. |
| theme | What causal shift was dated before this lead? | Kill if the label is post hoc; reopen on new causal evidence. |
| product | What did target users actually do? | Kill on no repeat value or unusable evidence. |
| team | What shows truth, learning and recruiting? | Kill on concealed bad news/unowned critical gap. |
| market | Who pays, why now, how large under downside? | Kill when required share exceeds credible adoption. |
| defensibility | What persists beyond capital/attention? | Kill if platform access or temporary data is called a moat. |
| price/ownership | What fund return can this check move? | Kill if target ownership/reserves exceed capacity. |
| risk milestone | Which uncertainty does the next check resolve? | Kill if capital scales before risk falls. |
| governance | Who serves board/company and how is dissent handled? | Kill if support becomes control or accountability is absent. |
| conflicts | Techstars/LP/fund/personal/board interests? | Kill if disclosure/recusal/allocation cannot be documented. |
| follow-on | What warrants more capital and what stops it? | Reopen only on dated decision-changing evidence. |
| exit | Whose liquidity, which security, which return metric? | No sale claim without security/cash-flow scope. |
[researcher inference · strong]
13. Historical operating environment
Feld's formative operator/angel period benefited from expanding PC/Internet markets; Mobius confronted the dot-com crash; Foundry's first decade captured social/mobile/cloud with relatively small funds; Select/Next emerged during abundant private capital; Crucible/Molekule crossed the zero-rate/SPAC reset; the final fund now faces slower liquidity and long private duration. [researcher inference · strong] historical context
Rules must be formation-date specific. Product use was especially informative for early Internet applications; high ownership in a $225m early fund differs from a $750m multi-sleeve fund; an interim IRR under zero-rate marks differs from cash distributions after reset. [researcher inference · strong]
No quantified matched base-rate dataset was located for stage/theme/geography/vintage, so “outperformance” remains unproven. [researcher inference · insufficient public record]
14. Modern VC translation (as of 2026-08-22)
What survives: firsthand workflow evidence, prepared themes, independent votes, founder learning, meaningful ownership, reserves, direct truth, network/community and capacity stops. [researcher inference · strong]
What changed: AI products can demo before they are reliable; model/data rights, evaluation drift, security, safety, inference economics and distribution can dominate. Open-source/cloud diffusion weakens superficial moats; regulation is fragmented; later-stage private marks can delay loss recognition; remote/global networks increase access and conflicts. [researcher inference · strong]
Apply by requiring an evaluation suite and failure log, lawful data/model rights, buyer/user workflow evidence, security/red-team controls, unit economics at scale, rollback, independent references, and vehicle-specific cash/ownership. Misuse includes calling a demo “product love,” labeling every AI company a theme fit, using Give First for undisclosed access, or treating a famous network as diligence. [researcher inference · strong]
15. Comparison with completed peers
| dimension | Brad Feld | Fred Wilson | Jim Breyer | Ann Winblad |
|---|---|---|---|---|
| sourcing | Techstars/community/partner-fund network + product curiosity | public writing/network effects and thesis community | institutional/university/founder network | enterprise-software operator/founder network |
| picking | product use, themes, collective veto, founder obsession | network theses, usage, capital efficiency | prepared mind, simple wedge, adaptive team | software-category depth, product/team diligence |
| vehicle | finite equal-partner firm; Select/Next/fund network | USV stage/thesis funds | Accel, personal trust, Breyer Capital, IDG-Accel | Hummer Winblad focused venture partnership |
| governance | support CEO, high ownership, long service | founder-customer/trust/board doctrine | sponsor/recruiter/institutional interpreter | operator empathy, recruiting and company-building support |
| adverse control | Mobius VI, Interliant, Molekule, Crucible, FG Angels, iRobot | Flatiron/Kozmo/Airbnb and incomplete cash flows | Accel VIII, Prosper, attribution/entity conflicts | personal/firm attribution and incomplete fund economics |
| attribution risk | team/firm/Techstars/personal/LPs | Wilson vs Burnham/Wenger/USV | Chien/Efrusy/Accel/trust/company | Winblad vs Hummer Winblad partners/company teams |
This is a process comparison, not a ranking. Wilson and Breyer are completed dossiers; Winblad provides the completed enterprise-software operator comparison. [researcher inference · strong]
16. The strongest case against greatness
Feld's public brand and prolific self-documentation may make a team/fund record look personal and systematic. The complete denominator is absent; Zynga/Fitbit/SendGrid could dominate; SendGrid is Ryan-led; company transaction values are not returns; public themes may be retrospective umbrellas; network access may be homophily; Give First may create commercial reciprocity; and large multi-vehicle funds contradict original simplicity. [researcher inference · strong]
Hard adverse records exist: Mobius VI at 0.6x/-5.80% for one LP/date, Interliant bankruptcy, Molekule common cancellation, Crucible liquidation, FG Angels stop, iRobot pass, and ordinary/insufficient Moz/Mattermark results. [contemporaneous record · strong] failure ledger
What would overturn the skeptical case: full cash flows with strong net DPI across vintages; partner-role evidence showing repeat decisive contribution; a complete pass/write-off denominator; source-channel performance; and independent founder evidence of causal board value. [researcher inference · insufficient public record]
17. Analyst study guide, glossary, and go deeper
Recommended order: (1) profile chronology; (2) five best talks; (3) writing playbook; (4) answer the labs before reveals; (5) apply mental models; (6) read review last.
Glossary:
- Theme: dated causal search hypothesis broader than a sector.
- Give First: contribute without knowing immediate return; not boundless altruism.
- Partner fund: external venture manager backed through a Foundry vehicle; not a direct company.
- Select: follow-on-only vehicle for existing Foundry companies.
- Next: vehicle with growth-company and partner-fund sleeves.
- Beneficial ownership: filing concept of voting/disposition power; not automatically personal economics.
- DPI / TVPI / MOIC / IRR: distributions, total value, multiple, and time-weighted return; not interchangeable.
- No-hindsight lab: formation evidence and decision prompts shown before outcome.
Go deeper: request dated IC/pass/follow-on memos; partner/board role logs; legal vehicle agreements; company security/cash-flow ledgers; audited LP reports; Techstars allocation/referral data; Interliant/Molekule/Crucible governance records; and independent founders across wins, ordinary outcomes and failures. [researcher inference · strong]
Study warning: Do not copy personality, network breadth, large ownership or final-fund structure. Copy only the process that fits your vehicle, competence, evidence, capacity and fiduciary duties—and retain the adverse ledger beside the doctrine.
Pareto 80/20 — what drove the record
Public evidence supports only directional ranking, not a career return table. Company value, affiliated beneficial ownership, financing amount, IPO stake, acquisition consideration, and LP-reported fund return are different quantities. No complete security-level cash-flow record lets us decide whether Zynga, Fitbit, or SendGrid generated the largest realized Foundry gain, let alone Feld's personal gain. [researcher inference · insufficient public record]
| economic-proxy rank | case | public evidence | bounded conclusion |
|---|---|---|---|
| 1= | SendGrid | Foundry 9,629,727 shares / 29.64% pre-IPO at the 2017 filing basis; Twilio later completed an approximately $3b acquisition | A likely major vehicle outcome; Ryan McIntyre led/mentored; sale timing, dilution, cost, distributions and fees unknown. S-1 · deal post · Twilio |
| 1= | Fitbit | Foundry-linked entities held 52,727,652 Class B shares in the pre-IPO table; Select invested about $10m in Series D; Feld served on the board 2010–15 | A likely major vehicle outcome, but disclosed shares span funds/entities and do not reveal cash proceeds. S-1/A |
| 1= | Zynga | Foundry-linked entities held 34,560,060 pre-IPO shares / 6.1%; Feld served on board from Nov. 2007 | Major visible outcome with stronger Feld governance attribution; shared four-partner control and unknown sales prevent return calculation. S-1 |
| 4–7 | Gnip, AdMeld, FeedBurner, MakerBot | Official acquirer/firm records establish exits but not Foundry/Feld proceeds | Important candidates for the second tier; ordering is not supportable. Gnip · AdMeld · FeedBurner |
| historical-importance rank | contribution | why it matters |
|---|---|---|
| 1 | Feld Technologies → personal angels → Intensity/SoftBank/Mobius | Operator liquidity, technical product knowledge, early network, and institutional failure supplied the raw material for Foundry's design. Stanford transcript |
| 2 | Techstars | Codified mentorship/community and created a global founder/fund network; exposure must remain separate from personal or Foundry investment. official history |
| 3 | Foundry thematic early-stage model | Small collective partnership, themes, product use, meaningful ownership and long support became the core investment system. themes |
| 4 | Select/Next/partner funds | Extended duration, concentration and network sourcing while adding vehicle/fee/attribution complexity. Next 2018 |
| 5 | Venture Deals / public teaching | Reduced information asymmetry and amplified trust/access; influence is not an economic return. series |
| learning-value rank | adverse/ordinary case | central lesson |
|---|---|---|
| 1 | Interliant | Acquisition/capital/reporting/governance failure and bankruptcy; distinguish committee allegations from adjudicated liability. SEC order |
| 2 | Mobius Technology Ventures VI | One LP reported 0.6x and -5.80% net IRR as of June 2023; firm architecture and vintage discipline matter. WSIB p.6 |
| 3 | Molekule | Large affiliated capital and ownership did not prevent Chapter 11/common cancellation; do not infer exact fund loss. 13D · 8-K |
| 4 | iRobot pass | Thesis discipline can create category-error misses; a celebrated miss does not prove looser discipline wins. Feld post |
| 5 | FG Angels / Crucible / Moz | Capacity stop, returned-capital SPAC liquidation, and ordinary outcome test experimentation, vehicles, and culture selection. FG Angels |
Evidence boundary and searched denominator
Foundry’s official investments route serves or redirects to a live collection that explicitly is not a complete lifetime ledger and mixes direct companies, exits, and partner funds. A one-session HTML/link inventory on 2026-08-22 found 136 distinct linked detail-card URLs after removing navigation and exact URL duplicates; because types and omissions are not stable in one export, this is a search frame, not a company denominator. The firm separately reports 200+ companies and nearly 50 venture-fund investments over its life. [contemporaneous record · strong] final-fund disclosure
| funnel state | count / scope | inclusion, exclusion, and deduplication rule | unresolved limitation |
|---|---|---|---|
| publicly claimed/known | 200+ companies; nearly 50 fund investments | Foundry lifetime self-report; company and fund universes separate | Rounded, unnamed, firm-wide, not Feld-specific. |
| official collection searched | 136 distinct detail-card URLs | One 2026-08-22 session; remove navigation and exact URL duplicates; retain all card types | Incomplete, dynamic, mixed objects; no performance ratio. |
| materially researched | 32 named companies + 2 noncompany cases | Person-linked leads spanning personal angels, Mobius, Foundry, pass, FG Angels and Crucible; rounds/vehicles deduped to one company lineage | Purposeful, not random/exhaustive. |
| sufficiently reconstructed | 7 companies + 2 noncompany cases | Formation/role/outcome evidence sufficient for a lab, not necessarily return | FeedBurner, Fitbit, SendGrid, Moz, Interliant, Molekule, iRobot; plus FG Angels and Crucible. |
| researched unresolved | 25 company lineages | 32 researched minus 7 sufficiently reconstructed; follow-ons remain in the original lineage | Cash flows, roles or formation evidence incomplete. |
| excluded from company denominator | partner funds, Techstars institution/programs, FG Angels program, Crucible vehicle, duplicate rounds, navigation cards | Separate object/beneficiary/base rate | Exact excluded-card count unavailable from unstable mixed export. |
There are nine labs total, but only seven are company lineages; FG Angels is an experiment and Crucible a special-purpose vehicle. No reconstruction fraction is reported against 136 or 200+ because the objects and omission rules differ. Career-wide coverage and hit rate are not computable. [researcher inference · strong]
Evidence hierarchy: issuer/regulator/LP records control securities, legal outcome and disclosed return; decision-date posts control stated thesis/role; later speech controls retrospective witness; acquirer releases control company transactions; researcher arithmetic is labeled. A company valuation or transaction never becomes fund or personal return. [researcher inference · strong]
Historical market, regulatory, and base-rate context
| formation regime | deal conditions visible at the time | base-rate implication | controlled cases |
|---|---|---|---|
| 1994–99 Internet expansion | Rapid adoption, public liquidity, cheap venture capital and consolidation | Large winners and severe integration/reporting failures both plausible | NetGenesis, Critical Path, Interliant, early Mobius. |
| 2000–06 crash/rebuilding | Financing contracted; RSS, email/security and SaaS infrastructure emerged | Product utility/capital efficiency rose; platform dependency remained | FeedBurner, Postini, Return Path, NewsGator. |
| 2007–13 social/mobile/cloud | New distribution graphs/devices accelerated growth; recession reset financing | Power-law outcomes could dominate small funds; platform/hardware risk rose | Zynga, Fitbit, SendGrid, Gnip, MakerBot. |
| 2013–19 abundant private capital | Larger follow-ons, growth vehicles, marketplaces and fund networks | Interim marks, duration and concentration became more important | Select/Next, Moz, Mapbox, Rover, Formlabs. |
| 2020–22 zero-rate/SPAC cycle | Abundant liquidity and SPAC issuance compressed price/time discipline | Public marks/deadlines fragile; validation and economics needed independent gates | Molekule, Crucible, Foundry 2022. |
| 2022–26 reset/final-fund | Rates/marks reset and exits slowed amid AI opportunity | Cash-on-cash, reserves, key-person and terminal stewardship dominate | Final-fund direct and partner-fund portfolios. |
No formation-date numerical base-rate series matches Feld’s stages, themes, geographies and vehicles. LP snapshots use different vintages/dates and cannot be pooled. Context changes diligence questions; it does not excuse losses or manufacture a benchmark. [researcher inference · insufficient public record]
Vehicle economics and incentives
| vehicle/entity | period and capital | decision/beneficiary boundary | economic evidence and unresolved risk |
|---|---|---|---|
| Feld Technologies | 1985/1987–1993 | Feld cofounder/operator; start-date conflict preserved | Approximate personal sale proceeds are self-report, not filing-controlled. Stanford |
| Personal angel portfolio | roughly 1994–96 and 2006–07 | Feld's own capital; about 40 first-period investments reported | No full names, cost, proceeds, tax, loss, or allocation ledger. MeetInnovators |
| Intensity Ventures / SoftBank affiliation | mid-1990s | Institutional capital/partnership role distinct from personal angels | Legal fund mapping and audited results not recovered. [researcher inference · insufficient public record] |
| Mobius Venture Capital | late 1990s–2006 investing; portfolio work later | Multi-partner funds and LP beneficiaries; “Feld deal” requires role evidence | WSIB's Mobius VI position is poor; spoken Fund I/II/III labels are not mapped conclusively. WSIB |
| Foundry early funds | 2007 onward; commonly $225m, elsewhere $232m each | Four equal partners originally; collective approvals and shared securities | UTIMCO reported 43.8% net IRR for Foundry 2007 at Nov. 2017; no full-vintage DPI/TVPI. UTIMCO p.61 |
| Foundry Select | 2013, $225m | Follow-on only in existing companies, up to $25m | Concentrated marks and winner-selection risk; Fitbit filing confirms one Series D use. announcement |
| Foundry Next / Next 2018 | 2016 $500m; 2018 $750m | Direct growth plus partner funds; later seven equal partners | TMRS positions are interim/unrealized snapshots, not final cash returns. TMRS |
| FG Angels syndicates | 2014–16 new-deal period | Foundry-organized syndicates; distinct backers/rights | Experiment stopped for partner capacity; cohort economics unavailable. postmortem |
| Foundry 2022 | investing from 2022; Feld reports closed 2023; final fund announced 2024 | Six equal partners in 2023 announcement; remaining new deals plus long portfolio work | TMRS early interim mark; final result unavailable for many years. 2023 announcement · 2025 direct transcript |
| Techstars entities/programs | incorporated 2006, first class 2007 | Cohen/Brown/Feld/Polis cofounders; accelerator/manager/company interests separate | Portfolio exposure is not automatically Feld or Foundry ownership. Reported sponsor/centralization criticism, program closures and layoffs concern the institution/later management and do not establish Feld's personal causality. history · February 2024 · August 2024 |
| Personal LP positions | various emerging managers | Feld as LP/mentor, not necessarily decision-maker in underlying companies | Commitments, fees, allocations, results, and conflicts largely private. [researcher inference · insufficient public record] |
| Crucible Acquisition Corp. | 2021–22 SPAC, $225m IPO | Feld chair; Foundry Next sponsor; public shareholders/warrant holders distinct | Liquidated and returned trust capital after no combination; precise sponsor loss/warrant economics require full cash flows. 424B4 · 8-K |
Across vehicles, duration and liquidity differ: personal angels can hold without LP deadlines; closed-end funds face reserves, key-person and distribution obligations; Select concentrates into marked winners; Next adds growth and look-through manager fees; a syndicate distributes rights across backers; and a SPAC has redemption/deadline mechanics. Public sources do not disclose complete fees, carry, recycling, side letters, pro-rata allocation, reserves or GP commitments, so incentive claims remain structural rather than quantified. [researcher inference · insufficient public record]
Governance evolved from four collective partners to six in 2023 and seven in the 2018 system description. Vehicles span US/Canada direct investing, broader partner-fund relationships, securities/privacy/advertising rules, hardware/science validation and public-market regulation. Stakeholders include founders, employees, customers, LPs, syndicate backers, partner managers and public shareholders; the final fund makes succession and key-person coverage especially material. [researcher inference · strong] Next 2018 · Foundry 2022
People, capital, and influence map
| case | discovery / lead | approval and capital | board / work | later narrator / outcome control |
|---|---|---|---|---|
| Zynga | Foundry's theme-distribution post attributes the deal to Brad | Foundry vehicle; all four shared voting/disposition power in filing | Feld director from Nov. 2007 | Feld/firm narrative; issuer S-1 controls role and 6.1% stake. theme post · S-1 |
| Fitbit | Initial Foundry pass then re-entry; exact originator unresolved | Foundry and Select; four-partner shared control | Feld director Aug. 2010–May 2015 | Feld post controls false-negative story; S-1/A controls role/securities. decision post · S-1/A |
| SendGrid | Ryan McIntyre led and had mentored Techstars founders | Foundry shared capital/control | Ryan and Feld are former directors in S-1 | Ryan-authored firm post; issuer filing/acquirer release control outcome. deal post |
| Moz/SEOmoz | Rand Fishkin relationship; originator not fully reconstructed | Foundry $18m disclosed in Feld post | Feld named board member | Feld narrates culture; company announcement controls later sale. post |
| Interliant | Feld/Mobius links; full sourcing chain unavailable | Multiple related entities/allegations require legal records | Board/conflict roles incompletely reconstructed | Feld gives later lesson; SEC/court record controls bankruptcy/procedure. decision |
| Molekule | Foundry company; named deal source/lead unresolved | Multiple Foundry entities aggregated $58,437,457; five managing members shared control | Feld was the required Foundry board nominee/director under the stockholders agreement | Issuer filings control governance, bankruptcy and common cancellation; none proves personal investment or loss. 13D |
Team-credit rule: discovery, introduction, mentorship, thesis sponsorship, partnership vote, fund capital, board service, recruiting, follow-on, exit decision, later narration, and company building are separate columns. “Foundry invested” never means “Brad sourced,” and “Brad was a director” never means “Brad owned the fund's shares personally.” [researcher inference · strong]
Comprehensive deal ledger
| # | company/entity | entry/vehicle/stage | contemporaneous thesis or role | attribution boundary | public outcome/economics status |
|---|---|---|---|---|---|
| 1 | NetGenesis | personal angel, 1990s | early Internet/software; board/help reported later | Feld personal self-report; founder/company labor separate | Named success; cash flow unavailable. MeetInnovators |
| 2 | Critical Path | personal angel | Internet messaging/infrastructure | personal vehicle; full role unknown | Public-company success/adversity history; personal return unknown. MeetInnovators |
| 3 | Harmonix | personal angel/Mobius-linked follow-on context | interactive entertainment/HCI | Feld names angel association; later fund/partner roles unclear | Acquisition/ownership changes; return unreconstructed. MeetInnovators |
| 4 | FeedBurner | Mobius, early stage | product-use, feed protocol/distribution | Feld used/narrated; partnership capital | Google acquisition; terms/return unknown. product post |
| 5 | Postini | Mobius | messaging/security infrastructure | partner/fund attribution incomplete | Google acquisition candidate; no fund cash flow. [researcher inference · provisional] |
| 6 | Return Path | Mobius | email infrastructure/reputation | Feld/Mobius public association; full sponsor chain unknown | Validity acquisition; proceeds unknown. acquirer |
| 7 | Rally Software | Mobius | agile/dev workflow; Feld director Sep. 2003–Mar. 2013 | Mobius entities; Feld and Jason Mendelson shared voting/dispositive power | 3,406,213 shares/20.3% pre-offering and 15.0% post-offering; cost, sales, distributions and personal economics unknown. 424B4 |
| 8 | NewsGator | Mobius | RSS/product workflow | Feld product-use narrative; fund capital | Outcome not reconstructed. product post |
| 9 | Sling Media | Mobius | consumer video/device-network convergence | Feld association; collective vehicle | EchoStar acquisition route; fund proceeds unknown. [researcher inference · provisional] |
| 10 | Interliant | Feld Group/Mobius-linked | hosting/consolidation | legal allegations and roles kept separate | Chapter 11; SEC delinquency; no adjudicated Feld liability. SEC |
| 11 | deCarta | Mobius | mapping/location infrastructure | Feld later scar narrative; exact decision role incomplete | Outcome/return unavailable; relevant Mapbox comparator. protocol archive |
| 12 | iRobot | pass / anti-portfolio | did not fit software category | Mobius team pass; round/access unknown | Later public success; counterfactual return unknowable. Feld |
| 13 | Zynga | Foundry, 2007 | social/distribution theme | Brad deal attribution; shared four-partner vehicle | 6.1% pre-IPO Foundry-linked stake at filing basis; later Take-Two deal. S-1 |
| 14 | Fitbit | Foundry + Select | connected device/measurement; re-entry after pass | Feld board; shared securities/control | 52.7m Class B shares in table; return unknown. S-1/A |
| 15 | SendGrid | Foundry/Techstars connection | developer email infrastructure | Ryan McIntyre led/mentored; Feld former board | 29.64% pre-IPO stake; ~$3b company acquisition; return unknown. deal post |
| 16 | Gnip | Foundry | social-data API/protocol | partner attribution requires firm post; not assumed Feld | Twitter acquisition; terms/proceeds unknown. Twitter |
| 17 | AdMeld | Foundry | ad infrastructure/distribution | Ryan/Jason/Seth/Brad roles require byline control | Google acquisition; no investor return. Google |
| 18 | MakerBot | Foundry | 3D printing/HCI | firm vehicle; partner lead not established here | Stratasys stock transaction; proceeds unknown. Foundry list |
| 19 | Moz/SEOmoz | Foundry | transparent founder/culture + SaaS | Feld board/narrator; company built by Fishkin/team | $18m financing disclosed; iContact acquisition, return unknown. Feld |
| 20 | Mapbox | Foundry | map API/protocol despite mapping scars | Feld narrates theme reframe; shared capital | Private/ongoing in public record; economics unknown. protocol archive |
| 21 | Rover | Foundry | marketplace/network | partner attribution unresolved | Public-company/transaction history; Foundry return unknown. Foundry list |
| 22 | Sphero | Foundry | connected device/HCI | firm vehicle; partner role unresolved | Private/ordinary status; economics unknown. Foundry list |
| 23 | Next Big Sound | Foundry | music data/analytics | firm/Techstars ecosystem; Feld-only claim avoided | Pandora acquisition route; proceeds unknown. Foundry list |
| 24 | SimpleGeo | Foundry | location API/protocol | known theme scar; exact partner/exit economics missing | Acquired/shut product; learning case. protocol archive |
| 25 | Trada | Foundry | crowdsourced paid-search marketplace | firm investment; Feld association not sole credit | Ordinary/adverse outcome not reconstructed. Foundry list |
| 26 | Oblong | Foundry | spatial computing/HCI | Feld thematic association; fund role | Merger/outcome route; return unknown. Foundry list |
| 27 | StockTwits | Foundry | social-finance network | firm/partner role unresolved | Ongoing/secondary outcome unknown. Foundry list |
| 28 | Formlabs | Foundry | desktop fabrication | firm vehicle; partner lead unresolved | Private marked outcome; no cash-return claim. Foundry list |
| 29 | AvidXchange | Foundry Select | B2B payments/workflow; Feld director, resigning immediately before offering effectiveness | Select entity; Feld and other managing directors shared control | 5,032,964 shares/2.97% pre-offering and 2.63% post-offering; board start, cost, sales and return unknown. S-1/A |
| 30 | Xometry | Foundry | manufacturing marketplace | firm vehicle; partner role unresolved | Public-company outcome; security/cash flows not traced. Foundry list |
| 31 | Molekule | Foundry entities, 2018–22 | air purification/device; Feld required Foundry board nominee/director | aggregate affiliated record; five managers shared control, not Feld-only | $58.44m aggregate legacy common-equivalent capital disclosed; 23.7% post-merger; Chapter 11 cancelled common for no consideration; exact entity/fund loss unknown. 13D · 13D/A |
| 32 | Mattermark | Foundry | company/data intelligence | firm investment; founder/company outcome control | Founder confirms Dec. 2017 sale; exact consideration is unverified. founder retrospective |
Crucible and FG Angels are analyzed as vehicle/experiment cases, not forced into the 32-company ledger. Techstars is an institution and exposure channel, not one portfolio-company line. [researcher inference · strong]
Ex-ante forensic case studies and decision labs
Each lab freezes public formation-era evidence before revealing the later outcome. Answer four prompts first: invest/pass; primary kill condition; ownership/terms/capacity requirement; evidence required for the next check.
Lab 1 — FeedBurner (Mobius, win candidate)
Formation packet. A young feed-management product sits inside an emerging protocol/distribution shift. Feld can use it directly and observe founder response to product feedback. Market structure, durable pricing, Google platform risk, ownership, and reserves are unknown. decision-era post [contemporaneous record · strong]
Decide before reveal. Invest/pass? Kill if publishers do not retain or monetization depends on one platform. Require product cohort evidence, protocol dependency map, founder update, price/ownership and reserve budget.
Reveal and audit. Google announced the acquisition in 2007. That validates company importance, not investor return or product-use causality. The lesson is to combine lived product evidence with platform-dependency underwriting. Google [researcher inference · strong]
Lab 2 — Fitbit (Foundry/Select, win candidate after pass)
Formation packet. A connected-device opportunity initially fails Foundry's collective decision; later evidence changes the vote. Hardware, inventory, consumer retention, accuracy, privacy, margin, and platform competition are material. decision post [retrospective witness · moderate]
Decide before reveal. Pass initially unless the dissent reason can be named. Reopen only on decision-changing evidence. Kill on weak repeat use/unit economics. Set hardware working-capital and follow-on ceilings; require cohort, returns/warranty, margin, accuracy and channel evidence.
Reveal and audit. Feld joined the board in August 2010; Foundry/Select later held disclosed securities and Select invested roughly $10m in Series D. The filing validates governance/capital, not why the first pass changed or net return. A 2018 derivative opinion let certain allegations survive pleading but left proof unresolved; neither Feld nor Foundry was a defendant. Fitbit S-1/A · Delaware opinion [contemporaneous record · strong]
Lab 3 — SendGrid (Foundry, win; team-credit control)
Formation packet. A Techstars team offers email-delivery infrastructure to developers. Ryan McIntyre had mentored the company and writes the investment announcement; deliverability, abuse, customer concentration, platform dependence and reliability are key. Foundry post [contemporaneous record · strong]
Decide before reveal. Invest if usage/retention, delivery quality and developer pull beat incumbents. Kill on abuse/reputation or undifferentiated price. Require ownership, reliability/security milestones, reserve, and a named board lead.
Reveal and audit. Foundry disclosed 29.64% pre-IPO at the filing basis; Ryan and Feld were former directors; Twilio later completed an approximately $3b acquisition. Credit Ryan's lead/mentorship, shared Foundry capital/control, company execution, and separate governance. S-1 [contemporaneous record · strong]
Lab 4 — SEOmoz/Moz (ordinary/disappointing outcome)
Formation packet. A transparent founder, explicit TAGFEE culture, SEO software/community, and a stated $18m Foundry financing. Risks: channel dependence on search platforms, founder/CEO fit, recurring economics, culture scaling, and follow-on concentration. Feld post [investor-stated · strong]
Decide before reveal. Invest only if recurring retention/expansion and platform-independent value justify price. Kill if culture substitutes for economics. Require CEO/leadership plan, cohort metrics, platform scenarios, ownership and reserve cap.
Reveal and audit. Moz was acquired by iContact in 2021; consideration and Foundry proceeds are not public in the retrieved primary record. The case is ordinary/insufficient—not a proven loss—and shows cultural fit is not an outlier-return metric. company post [researcher inference · moderate]
Lab 5 — Interliant (failure and adverse governance)
Formation packet. Hosting consolidation in the late-1990s capital cycle, with acquisition integration, reporting, cash burn, leverage/financing, related-party and board-control risks. Contemporaneous IC/board packets are unavailable; do not pretend the later lesson was known. [researcher inference · insufficient public record]
Decide before reveal. Pass without stand-alone unit economics, integration owner, audited reporting, cash/covenant downside, conflict map, and stop authority. Kill on delinquent reporting or acquisitions exceeding integration capacity.
Reveal and audit. Interliant filed Chapter 11 in August 2002 after a reported 2001 $48.9m net loss and later delinquent reports. A committee alleged transfers/fiduciary breaches involving Feld-linked parties; the accessible decision addresses procedure and does not adjudicate Feld's personal liability. SEC order · decision [contemporaneous record · strong]
Lab 6 — Molekule (failure after substantial capital)
Formation packet. A hardware/air-quality company requires independently validated efficacy, regulatory/advertising discipline, manufacturing, warranty, channel, margin and financing evidence. In 2020 NARB found support for some PECO claims but recommended discontinuing or modifying several pollution-elimination, superiority, quantified-performance, testing and health-relief claims; Molekule agreed. This is a balanced warning, not proof the product was wholly ineffective. Foundry participated across 2018–22 through multiple entities; exact thesis memo is unavailable. NARB announcement [contemporaneous record · moderate]
Decide before reveal. Pass absent blinded efficacy and viable unit economics. Kill on claims exceeding evidence or repeated recapitalization without risk reduction. Cap cumulative ownership/capital and define independent science, gross margin, returns and cash milestones.
Reveal and audit. A filing aggregates about $58.44m of Foundry-entity legacy common-equivalent capital and 23.7% post-merger ownership; it names Feld among five shared managing members and as the required Foundry board nominee. The 2023 Chapter 11 led to common cancellation for no consideration. That supports severe equity impairment, not an exact $58.44m fund or personal loss because securities, transfers, recoveries and entity allocations differ. 13D · 8-K · 13D/A [contemporaneous record · strong]
Lab 7 — iRobot (miss / anti-portfolio)
Formation packet. A robotics company with a consumer vacuum product appears outside Mobius's software focus. Hardware/manufacturing/channel risk is high; embedded software, data, brand, and autonomy may create a broader system. Feld post [retrospective witness · moderate]
Decide before reveal. Pass under a strict software mandate unless system/software economics satisfy an adjacency exception. Kill on gross margin, reliability, inventory or weak repeat platform. Require round/access, ownership, working capital, and counterfactual portfolio fit.
Reveal and audit. Feld later loved the product and named the pass. iRobot's later success makes it a miss, but no public proposed terms prove Mobius could have invested or that relaxing the rule improves expected fund return. [researcher inference · strong]
Lab 8 — FG Angels (experiment stopped)
Formation packet. AngelList syndicates might extend Foundry's network and seed access at lower check size. Risks: partner time, adverse selection, signaling, founder service, conflicts, reserves, and dispersed backer obligations. launch-to-postmortem route [documented behavior · strong]
Decide before reveal. Run only with a time-box, responsible partner, success/learning metric, capital/attention budget, conflict rule, and support plan. Kill if per-company effort exceeds the model despite company quality.
Reveal and audit. Foundry stopped new investments after two years because the program consumed more capacity than expected. Existing obligations continued. This is a credible stop rule; absent cohort economics, it does not prove financial failure or success. [documented behavior · strong]
Lab 9 — Crucible Acquisition Corp. (special-vehicle failure)
Formation packet. A $225m SPAC sponsored by Foundry Next, chaired by Feld, has a deadline to find and complete a combination. Risks include sponsor/public-shareholder incentive divergence, diligence under time pressure, warrant dilution, market regime change, and opportunity cost. 424B4 [contemporaneous record · strong]
Decide before reveal. Accept only with a strict target thesis, conflict/valuation process, walk-away authority, deadline plan, sponsor-capital loss limit, and liquidation preference over a poor merger.
Reveal and audit. Crucible did not complete a combination and announced liquidation/return of trust funds. This is a failed search but may evidence discipline versus forcing a transaction; sponsor/warrant economics remain unreconstructed. 8-K [contemporaneous record · strong]
Portfolio-level forensics
| dimension | observable public pattern | what cannot be concluded |
|---|---|---|
| stage | Early-stage core; seed $250k–$10m in 2010; Select/Next add follow-on/growth | Actual stage/check distribution across all vintages. |
| sector/theme | Software, protocols, distribution, HCI, developer tools, marketplaces; some hardware | Theme-level return or pre-deal fit for every company. |
| geography | Boulder-rooted; US/Canada direct mandate in 2018; broader fund network | City/country allocation, geographic alpha or inclusion. |
| check/ownership | Fixed early funds, roughly 30 companies; sometimes >30% lifecycle ownership | Company cost/dilution, average ownership or optimality. |
| concentration | Zynga/Fitbit/SendGrid are large visible proxies; Select concentrates winners | Actual contribution rank or ex-top-three result. |
| reserves | Seed doctrine promises follow-on; Select/Next extend lifecycle | Reserve ratios, pro-rata, bridge policy and write-off cadence. |
| governance | Collective veto, named board roles, CEO-support doctrine | Workload, efficacy, founder experience or causal value-add. |
| exits/liquidity | IPOs/acquisitions and long private holdings; cash-on-cash preference | Gross/net realized amounts, sale timing, recycling, carry or tax. |
| hit/miss bias | Public archive surfaces wins and selected candid failures/misses | Complete median, loss rate, selection effect or survivorship-adjusted return. |
The visible economic record is plausibly concentrated, but missing cash flows prevent ranking even the top three. A valid test needs cost, follow-on, dilution, distributions, remaining value, fees/carry and allocation plus ex-top-one/ex-top-three sensitivity. [researcher inference · strong]
Failure, miss, and anti-portfolio postmortems
| case | original thesis | warning / capital response | governance and stop/exit | outcome | later lesson / counterfactual uncertainty |
|---|---|---|---|---|---|
| Interliant | hosting consolidation | acquisitions, cash and reporting stress; exact follow-on votes unknown | Chapter 11 and asset sale; legal allegations not liability findings | severe failure | capital/integration/reporting discipline; board alternatives unknown. |
| Mobius VI | technology venture vintage | one-LP cash flows imply poor outcome; company mix/decisions not public | closed-end runoff | 0.6x, -5.80% net IRR to WSIB as of 2023 | architecture/vintage discipline; one LP is not entire fund truth. |
| Molekule | air purification/device | 2020 NARB mixed finding and claim-modification warning; repeated affiliated capital; validation/unit-economics decisions unknown | Feld board role/shared vehicle control; restructuring/common cancellation | severe equity impairment | independent science, advertising and recap gates; exact fund/personal loss unknown. |
| Crucible | SPAC search vehicle | deadline/market regime; no target completed | liquidated rather than force merger | failed search / capital returned | precommit walk-away; sponsor economics unknown. |
| FG Angels | scalable syndicate/network | unexpectedly high partner work | stopped new deals after two years | operational stop; financial result unknown | price partner attention; delegation alternative untested. |
| SEOmoz/Moz | culture + SaaS/community | leadership/platform/economics history incomplete | later acquisition | ordinary/insufficient | culture is input, not return; proceeds unknown. |
| Mattermark | company intelligence/data | full financing/operating sequence incomplete | founder confirms sale Dec. 2017 | adverse/ordinary, exact price unverified | avoid repeating paywalled “<$1m” claim; cash flows unknown. |
| iRobot | outside software thesis | category filter | pass | successful company/miss | adjacency protocol; access/terms/counterfactual unknown. |
[researcher inference · strong] The table does not imply Feld caused each outcome. It shows what evidence a student needs to test doctrine against adverse and ordinary cases.
Fund-performance controls and arithmetic
| record | reported snapshot | valid use | invalid use |
|---|---|---|---|
| UTIMCO, Nov. 2017 | Foundry 2007 net IRR 43.8% since inception | Evidence that one LP's early-fund position was strong at that date | Not DPI/TVPI, current return, Feld personal result, or every LP. |
| WSIB, Jun. 2023 | Mobius VI: $82,354,694 paid in; $49,282,966 distributed; 0.6x; -5.80% net IRR | Adverse vintage/LP control | Not every Mobius fund or a personal loss calculation. |
| TMRS, Dec. 2022 | Foundry 2022/Next positions showed positive interim IRRs with most value remaining | Valuation-sensitive interim LP context | Not realized cash-on-cash, final performance, or current marks. |
The reproducible WSIB distribution ratio is $49,282,966 ÷ $82,354,694 = 0.5984x, consistent with the table's rounded 0.6x. No other arithmetic invents undisclosed cost, fee, carry, tax, security conversion, or allocation. [researcher inference · strong] WSIB p.6
Uncertainty and retrieval ledger
| unresolved item | routes exhausted | resolving evidence |
|---|---|---|
| Feld career and personal net return | official bio, long interviews, issuer filings, acquirer releases | security-level costs/sales/distributions/tax plus personal/vehicle allocations |
| Foundry vintage DPI/TVPI/MOIC | UTIMCO, TMRS, firm posts | audited full-vintage quarterly/final LP statements on a common date |
| Complete company/pass/write-off denominator | current Foundry list, final-fund count, blog archives | legal portfolio export plus passes/write-offs and partner/vehicle mapping |
| Partner attribution | deal posts, bylines, S-1 board/ownership | IC records, CRM origin, vote, board, recruiting, follow-on and exit logs |
| Mobius spoken fund mapping | SaaStr/Ferriss/MeetInnovators, WSIB | legal fund names/vintages matched to spoken I/II/III plus full LP reports |
| Techstars economic/access effect | official history/portfolio, Feld writing | cohort/ownership/referral/allocation records and independent participant outcomes |
| Interliant conduct/causality | SEC order, bankruptcy decision mirror, Feld retrospective | board minutes, financing and conflict records, final merits findings |
| Molekule exact fund loss | 13D, 8-K, 13D/A | entity-level cost, transfers, recoveries, tax and cash distributions |
| Crucible sponsor economics | 424B4 and liquidation 8-K | sponsor capital/warrant/cost/liquidation cash-flow ledger |
Until these records emerge, the defensible conclusion is that Feld helped design and narrate an influential venture system with several major visible company outcomes and meaningful adverse controls. The public record supports process study more strongly than personal-alpha or career-return ranking. [researcher inference · strong]
Coverage and evidence base
The priority written inventory contains 24 ★★★/★★ rows in the source map: 22 full works and two mixed-access routes with full author-origin posts but only partial book access (Venture Deals and Do More Faster). No priority writing is inaccessible or metadata-only. All 24 were read, deduplicated, and given their own exact-schema note and analysis below: 24 mapped − 24 notes − 24 analyses = 0 missing. Feld's separate books page remains a ★ metadata route and does not enter this priority denominator. [researcher inference · strong]
The corpus spans three different voices: Feld-signed personal posts, coauthored books/doctrine, and Foundry firm posts. “Feld published” does not mean “Feld alone decided”; Foundry deal, fund, and team claims retain the named partner, collective vehicle, and beneficiary. [researcher inference · strong]
Source-by-source analysis
1. Product-Focused Venture Capital (2006)
- Context and question: Before Foundry's public theme framework, Feld asks what a software-oriented VC can learn by actually using a product. primary · note
- Argument: Product use exposes friction, founder responsiveness, and an investor's ability to contribute; FeedBurner and NewsGator make the rule concrete. [investor-stated · strong]
- Evidence and example: The signed contemporaneous essay is strong for the stated process, but it supplies no same-basis comparison of used-versus-not-used products or investment returns.
- Hidden assumptions: Investor taste represents target users; founders should react to one power user's feedback; product legibility arrives early enough for diligence.
- Decision implication: Require a dated product-use log, map persona mismatch, and score the founder's response to evidence rather than agreement.
- Contradiction/transfer: Enterprise infrastructure, biotech, and safety-critical AI may not be directly usable; “I used it” can create familiarity bias. The 2026 translation is instrumented workflow observation, not consumer intuition. [researcher inference · strong]
2. How I Think About Seed Investing as a VC (2010)
- Context and question: Seed programs were proliferating, so Feld distinguished institutional commitment from cheap optionality. primary · note
- Argument: A Foundry seed should fit a theme, involve all partners, support follow-on, and stand independent of syndicate signaling; stated initial checks ranged $250,000–$10 million. [investor-stated · strong]
- Evidence and example: Seven named seed examples form a prospective test set; no complete outcome/reserve ledger follows them.
- Hidden assumptions: A small equal partnership can spend full attention on small checks; fund reserves and ownership can absorb follow-ons.
- Decision implication: Write the seed's next-round commitment, target ownership, reserve ceiling, partner owner, milestone, and stop condition at entry.
- Contradiction/transfer: FG Angels later used lighter-touch syndication and stopped for capacity. The failure refines rather than erases the commitment rule. [documented behavior · strong]
3. Make Your Own Decisions (2012)
- Context and question: Feld responds to the tendency to infer quality from other VCs. primary · note
- Argument: Foundry invested in only roughly 5–10% of actively evaluated companies, required all four partners, and treated one partner's sustained resistance as a pass. [investor-stated · strong]
- Evidence and example: Fitbit and SEOmoz are valuable false-negative/re-entry cases showing that a first “no” need not be permanent.
- Hidden assumptions: Partners form sufficiently independent views and dissent is informational rather than political.
- Decision implication: Record pre-meeting priors, independent votes, reasons for dissent, and the evidence required to reopen a pass.
- Contradiction/transfer: Social proof can still enter through founder/network access. A unanimous system also lets one risk-averse partner suppress unusual bets. [researcher inference · strong]
4. Why We Pass Quickly on Things (2015)
- Context and question: A four-partner firm with a fixed fund cannot pursue every credible company. primary · note
- Argument: Approximately 30 companies per fund and ten new investments per year made stage, geography, theme, check size, and partner energy capacity controls—not judgments of founder worth. [investor-stated · strong]
- Evidence and example: The post provides funnel arithmetic but not a logged pass denominator or false-negative rate.
- Hidden assumptions: The fund size and partner model are themselves optimal; quick rejection cost is lower than delayed discovery value.
- Decision implication: Publish filter failures promptly, distinguish “not us” from “bad,” and audit passes that later become large outcomes.
- Contradiction/transfer: Later Next/partner-fund vehicles widened the opportunity set, and the team expanded; capacity filters must be recalibrated by vehicle. [documented behavior · strong]
5. VCs: Don't Bullshit (2014)
- Context and question: Feld uses Mobius and Foundry fundraising to attack performative certainty. primary · note
- Argument: State problems plainly, accept rejection, and build LP trust through truth; the post recalls roughly 90 meetings and 20 immediate rejections for Foundry's first fund. [retrospective witness · moderate]
- Evidence and example: Named LP relationships and Mobius adversity make this richer than generic advice, but no subscription ledger or contemporaneous meeting notes are public.
- Hidden assumptions: Candor is recognized and rewarded; gatekeepers do not punish adverse disclosure.
- Decision implication: Keep a dated risk register shared with LPs/founders and separate unresolved problems from confident forecasts.
- Contradiction/transfer: Transparency cannot cure poor economics. The principle should be tested against adverse board/fund records, not likes or brand warmth. [researcher inference · strong]
6. Term Sheet Series / Venture Deals (2005–2011)
- Context and question: Feld and Jason Mendelson sought to reduce information asymmetry in venture documents. primary · note
- Argument: Explain economics and control separately so founders understand negotiation rather than defer to lawyers/VCs. [investor-stated · strong]
- Evidence and example: The accessible 20-post series is decision-relevant; it is less than 20% of the later book and remains coauthored.
- Hidden assumptions: Disclosure creates bargaining competence despite unequal capital, time, and information.
- Decision implication: Model dilution, liquidation preference, participation, option-pool, anti-dilution, board and protective provisions in scenarios.
- Contradiction/transfer: Teaching terms may also standardize investor-favorable norms. Modern translation adds SAFEs, secondaries, pay-to-play, AI/data rights, and financing-control failure modes. [researcher inference · strong]
7. The Techstars Mentor Manifesto (2011)
- Context and question: An accelerator needed behavioral rules for mentors. primary · note
- Argument: Be direct, responsive, Socratic, network-helpful, relationship-oriented, and founder-centered without controlling. [investor-stated · strong]
- Evidence and example: The attribution chain matters: Jon Bradford prompted the discussion, David Cohen authored the manifesto, Feld amplified it.
- Hidden assumptions: Mentors know when advice is useful and can avoid portfolio/conflict incentives.
- Decision implication: Set mentor disclosure, response-time, conflict, confidentiality, and escalation rules; collect founder-side feedback.
- Contradiction/transfer: A dense mentor network can create consensus, status pressure, and extraction. “Mentor whiplash” is a predictable boundary. [researcher inference · strong]
8. Definition of Give First (2020)
- Context and question: A slogan had diffused enough to require a precise definition. primary · note
- Argument: Contribute without knowing the immediate return, but not with no boundaries or expectation that reciprocity never matters. [investor-stated · strong]
- Evidence and example: Feld dates the phrase from “Give Before You Get” in 2012 through the hashtag and 2020 refinement.
- Hidden assumptions: Contributions and future benefits can be separated; privileged actors are not merely branding normal networking as generosity.
- Decision implication: Record beneficiary, cost, conflict, consent, expected public/private benefit, and a capacity ceiling.
- Contradiction/transfer: FG Angels shows that contribution without a bounded operating model can overload a small partnership. [documented behavior · strong]
9. Foundry Group Next 2018
- Context and question: Foundry explains why a $750 million seventh vehicle fits rather than abandons its model. primary · note
- Argument: Combine direct early/growth ownership, partner funds, long holding, and a seven-equal-partner network; prefer net cash-on-cash over short/interim IRR. [investor-stated · strong]
- Evidence and example: The post discloses prior vehicle sizes, US/Canada focus, thematic continuity, and “often over 30%” ownership; it does not disclose cash flows.
- Hidden assumptions: Network breadth and larger capital do not dilute partner attention or increase adverse selection.
- Decision implication: Model each sleeve's fee layer, decision owner, duration, overlap, reserve burden, and look-through concentration.
- Contradiction/transfer: Earlier Foundry celebrated four partners/no associates and fixed $225m funds; the 2018 system is materially different. [researcher inference · strong]
10. Status of Our FG Angels Experiment (2016)
- Context and question: Foundry tested AngelList syndicates as a lightweight extension of its network. primary · note
- Argument: Stop new investments when a supposedly low-effort experiment consumes scarce partner capacity, even if individual companies remain promising. [documented behavior · strong]
- Evidence and example: Two years of operation and an explicit stop make this a real control against innovation theater; cohort economics remain absent.
- Hidden assumptions: Partner time was the binding constraint and discontinuing was better than staffing/delegating.
- Decision implication: Pre-register time budget, owner, learning goal, economic threshold, continuation date, and obligations to existing companies.
- Contradiction/transfer: The experiment's syndicate/light-touch form conflicts with the 2010 claim that seed is full institutional commitment. [researcher inference · strong]
11. Who Are We? (2008)
- Context and question: A newly formed firm defines its architecture. primary · note
- Argument: Small, experienced, equal partners make collective decisions and remain directly involved; Boulder is a network node, not a geographic constraint. [investor-stated · strong]
- Evidence and example: Founding-era timing is valuable, while organizational claims need later behavior and deal records.
- Hidden assumptions: Equality produces challenge and coverage rather than ambiguity or veto gridlock.
- Decision implication: Map vote, sponsor, board, reserves, conflicts, key-person, and succession responsibility for every company.
- Contradiction/transfer: Six equal partners in 2023 and a decade-long final-fund wind-down test the original architecture's durability. [researcher inference · strong]
12. What Does Foundry Group Invest In? (2008)
- Context and question: Foundry needs a repeatable search map without becoming sector-bound. primary · note
- Argument: Themes capture protocols, distribution shifts, and interaction changes broad enough for discovery but narrow enough for accumulated expertise. [investor-stated · strong]
- Evidence and example: The dated list constrains hindsight; later Gnip, SendGrid, Fitbit, Mapbox and others can be tested for actual entry fit.
- Hidden assumptions: Themes are stable, mutually informative, and not so broad that every software company fits.
- Decision implication: Freeze the theme definition, causal mechanism, disconfirmers, entry evidence, and adjacency budget before meeting a company.
- Contradiction/transfer: The system later became “network-driven,” which may improve access or replace thesis-led discovery with referrals. [researcher inference · strong]
13. Foundry Group Select (2013)
- Context and question: Successful portfolio companies needed more capital than the early-stage vehicle could prudently supply. primary · note
- Argument: A separate $225 million fund invests up to $25 million only in existing winners. [investor-stated · strong]
- Evidence and example: Fitbit's S-1/A confirms a Select Series D investment around $10 million, independently demonstrating vehicle use. Fitbit filing
- Hidden assumptions: Follow-on selection beats external opportunities and added concentration fits LP risk.
- Decision implication: Re-underwrite each follow-on against a fresh external opportunity, ownership value, reserves, and total look-through exposure.
- Contradiction/transfer: Calling companies “winners” before liquidity risks mark-driven selection; no audited Select DPI/TVPI was found. [researcher inference · insufficient public record]
14. Our Newest Fund — Next (2016)
- Context and question: Foundry expands beyond Select into partner funds and growth companies. primary · note
- Argument: A $500 million dual-sleeve vehicle treats network managers and later-stage direct investments as reinforcing. [investor-stated · strong]
- Evidence and example: Official mandate is clear; sleeve allocations, fee look-through, and outcomes are private.
- Hidden assumptions: Managers share high-quality deals and information without allocation conflict; growth checks remain inside competence.
- Decision implication: Separate direct and fund-return denominators; record referral, overlap, fees, information rights, and allocation.
- Contradiction/transfer: Network benefit is causal self-report, not a channel-matched outcome study. [researcher inference · insufficient public record]
15. Network-Driven Investing (2022)
- Context and question: Foundry retrospectively names the mechanism connecting its partner-fund and direct-company strategies. primary · note
- Argument: Dense trusted relationships improve discovery, expertise, recruiting, and collaboration. [investor-stated · strong]
- Evidence and example: The post gives institutional history and early-fund size of $232m each; it does not identify every network-sourced deal or counterfactual.
- Hidden assumptions: Warm-network quality exceeds homophily, circular validation, and adverse selection.
- Decision implication: Tag lead channel, conflicts, independent references, excluded populations, and outcome by source cohort.
- Contradiction/transfer: The $232m description conflicts with $225m shorthand; preserve possible commitment-versus-investable/rounding scope rather than choose silently. [researcher inference · strong]
16. The Final Foundry Fund (2024)
- Context and question: A partnership designed not to be generational states its terminal capital-raising decision. primary · note
- Argument: Foundry 2022 is final, but active investing and portfolio stewardship continue for at least a decade. [investor-stated · strong]
- Evidence and example: The firm reports 200+ direct companies and nearly 50 fund investments; current 2025 direct voice gives roughly 80 active companies/50 fund positions.
- Hidden assumptions: A long closed-end wind-down preserves recruiting, incentives, key-person coverage, and follow-on discipline.
- Decision implication: Treat “final fund” as a lifecycle state: map remaining new-deal authority, reserves, boards, succession, staffing, and LP communication.
- Contradiction/transfer: Current promotional summaries may compress counts; neither disclosure becomes a Feld-only denominator. [researcher inference · strong]
17. Your First Big Success — What's Next? (2014)
- Context and question: Feld narrates how early liquidity, bubble adversity, and health shaped later institutions. primary · note
- Argument: Success creates options, not immunity; deliberate reinvention and personal systems matter after a win. [retrospective witness · moderate]
- Evidence and example: Named periods—Feld Technologies, angel deals, Mobius, Techstars, Foundry, 2013 depression—support chronology, not causal alpha.
- Hidden assumptions: Later meaning accurately reconstructs earlier decisions.
- Decision implication: Pair career retrospectives with date-fixed records and include health/capacity in key-person risk.
- Contradiction/transfer: Public candor is evidence of reflective practice, not proof that contemporaneous governance anticipated the risks. [researcher inference · strong]
18. Every Generation Learns the Same Lessons (2018)
- Context and question: Interliant becomes a cycle/capital/governance failure case. primary · note
- Argument: Fast growth, acquisition integration, and abundant capital can repeat familiar errors when pattern memory is ignored. [retrospective witness · moderate]
- Evidence and example: SEC records Chapter 11 and delinquent reporting; the bankruptcy decision records committee allegations. SEC order · decision mirror
- Hidden assumptions: The lesson selected after failure was the binding cause, rather than product, market, financing, control, or conflict.
- Decision implication: Reconstruct acquisition cadence, cash, covenant, reporting, board escalation, alternatives, related-party conflicts, and stop authority.
- Contradiction/transfer: Allegations are not adjudicated liability; the record must not imply Feld wrongdoing. [contemporaneous record · strong]
19. Roomba / iRobot Pass (2005)
- Context and question: A product Feld loved had failed Mobius's software-category filter. primary · note
- Argument: Category discipline protects focus but can misclassify hardware with software/network economics. [retrospective witness · moderate]
- Evidence and example: The near-period post names the pass and product use; round, price, allocation, and vote remain unknown.
- Hidden assumptions: The counterfactual investment was available and would have fit vehicle timing/ownership.
- Decision implication: For a thesis mismatch, write the adjacent category that would make it eligible and evidence that could reopen the pass.
- Contradiction/transfer: A celebrated miss is not proof that relaxing the rule raises expected returns; test all drift deals, not only iRobot. [researcher inference · strong]
20. Small Company / Big Company (2015)
- Context and question: Portfolio startups repeatedly depend on slow incumbents. primary · note
- Argument: Named ownership, executive sponsorship, economic alignment, and process clarity determine whether a partnership helps rather than kills a startup. [investor-stated · strong]
- Evidence and example: The numbered rules reflect experience but anonymize cases and omit denominator/outcomes.
- Hidden assumptions: The startup has negotiating alternatives and can survive the incumbent's cycle.
- Decision implication: Underwrite concentration, termination, data/IP, integration, payment, champion departure, and fallback distribution.
- Contradiction/transfer: Partnership advice can normalize dependency. Kill a deal when survival rests on one uncontracted champion. [researcher inference · strong]
21. SEOmoz, TAGFEE, and Me (2012)
- Context and question: Feld publicly explains Foundry's relationship with Rand Fishkin and a culture of transparency. primary · note
- Argument: Explicit values and radical communication can be investable operating systems, not decoration. [investor-stated · moderate]
- Evidence and example: A stated $18m financing and Feld board role anchor involvement; later leadership/outcome does not reveal return.
- Hidden assumptions: Public transparency predicts private truth and execution; values scale through leadership changes.
- Decision implication: Test values with hiring, firing, bad-news, customer, and financing decisions rather than slogans.
- Contradiction/transfer: The case belongs in the ordinary/disappointing ledger precisely because cultural fit did not guarantee outlier economics. [researcher inference · strong]
22. Foundry Group Next (2015)
- Context and question: Feld previews a vehicle and relates it to LP history/succession. primary · note
- Argument: Growth and partner funds can deepen a network without building a permanent institution; partner careers, not a brand dynasty, define the horizon. [investor-stated · strong]
- Evidence and example: The UTIMCO relationship and anti-legacy position predate the 2024 final-fund statement.
- Hidden assumptions: LP duration aligns with finite partner careers and long portfolio obligations.
- Decision implication: Put succession, key-person, post-investment staffing, and terminal fundraising policy into vehicle design.
- Contradiction/transfer: A final firm can still require institutional continuity longer than any partner's active career. [researcher inference · strong]
23. Why Do We Care About Techstars? (2009)
- Context and question: Feld explains a young accelerator's purpose beyond investment return. primary · note
- Argument: Mentorship and dense community increase entrepreneurial learning and ecosystem capacity. [investor-stated · strong]
- Evidence and example: Techstars' official history independently fixes founders and dates; no channel-adjusted return data proves sourcing advantage.
- Hidden assumptions: Mentor incentives align; access is inclusive; advice quality exceeds confusion; commercial and public-good goals coexist transparently.
- Decision implication: Separate Techstars, personal, Foundry, and later partner-fund capital; disclose allocation and conflicts.
- Contradiction/transfer: Ecosystem-building can become privileged access dressed as public service. Measure participant outcomes and excluded populations. [researcher inference · strong]
24. Do More Faster (2010)
- Context and question: Feld and David Cohen convert accelerator lessons into a founder playbook. primary · note
- Argument: Bias toward action, learning, focus, and founder resilience; the short-chapter form reflects mentor plurality. [investor-stated · moderate]
- Evidence and example: The accessible author post controls purpose/coauthorship but not the full book's evidence or rule ownership.
- Hidden assumptions: Speed raises learning faster than it compounds legal, safety, product, or organizational debt.
- Decision implication: Define the decision a faster experiment changes, its guardrails, rollback, owner, and evidence threshold.
- Contradiction/transfer: “Faster” is dangerous in regulated AI, health, security, and finance without right-to-operate gates. [researcher inference · strong]
Cross-source synthesis
The writings evolve in four layers: technical product observation (2005–06), small-partnership filters and full commitment (2008–15), community/teaching as network infrastructure (2009–20), and multi-vehicle network/lifecycle design (2013–24). The later network doctrine does not replace the earlier theme/product method; it changes sourcing, scale, attribution, and conflicts around it. [researcher inference · strong]
The strongest repeatable playbook is: use the product; define a dated theme; decide independently; treat seed as commitment; reserve enough for winners; reject quickly when the vehicle cannot serve; support the CEO without control; teach openly; and stop experiments that exceed capacity. The strongest counterevidence is Interliant, iRobot, SEOmoz, FG Angels, Molekule, Mobius VI, and the early-fund/partner-count inconsistencies. [researcher inference · strong]
Intellectual chronology, evolution, and contradictions
The intellectual chronology begins with product use and category misses (2005–06), formalizes collective themes and seed commitment (2008–12), expands through culture, quick passes, LP candor, Select/Next and explicit experiment stops (2013–18), then defines Give First, network-driven investing and a final-fund lifecycle (2020–24). [researcher inference · strong]
Durable ideas are firsthand evidence, independent judgment, full commitment, direct truth and long relationships. Contradictions are productive controls: iRobot versus software focus; Fitbit/Moz re-entry versus quick passes; FG Angels versus full seed service; four partners versus six/seven; themes versus referral networks; cash-on-cash preference versus mark/IRR-heavy public records; and finite partnership versus decade-long stewardship. [researcher inference · strong] iRobot · network
Decision playbook and modern VC translation as of 2026-08-22
A reusable decision sequence is: date the theme and why-now; use or observe the product; collect independent partner votes; state dissent/reopen evidence; name eligible vehicle and conflicts; size price/ownership/reserves; define next milestone and kill; assign founder-service/governance; and pre-commit follow-on/exit metrics. [researcher inference · strong] seed doctrine · decision doctrine
For AI/cloud/developer-tool investing, translate product use into traceable workflow evaluation: permissions, model/data provenance, evaluation drift, security, latency, inference cost, switching, buyer/user separation, and failure recovery. Translate themes into falsifiable causal maps rather than labels; translate Give First into disclosed, bounded contributions; translate networks into channel-tagged sourcing audited for homophily and conflict; and translate cash-on-cash preference into a vehicle-specific cash-flow ledger rather than an excuse to ignore interim risk. [researcher inference · strong]
Recommended order: read product focus → themes → seed commitment → independent decisions → quick passes → Mentor Manifesto/Give First → Select/Next/network → final fund → Interliant/iRobot/FG Angels. Then use the decision labs and models to test whether the attractive rules survive adverse cases.
Best five writings and unresolved record
- Product-Focused Venture Capital (2006) — clearest origin of firsthand product diligence.
- How I Think About Seed Investing (2010) — most complete stage, reserve and commitment policy.
- Make Your Own Decisions (2012) — rare funnel, veto, false-negative and re-entry evidence.
- Foundry Group Next 2018 — fullest vehicle, ownership, partner and return-metric statement.
- Status of FG Angels (2016) — strongest operational experiment postmortem.
Unresolved are the complete nine-book texts, a deduplicated full Feld/Foundry archive denominator, every priority-quality deal announcement/byline, deleted or migrated posts, full contemporaneous Mobius records, and source-by-source outcome testing for the seven named 2010 seeds. These gaps are logged as partial/★ routes rather than silently represented as read. [researcher inference · insufficient public record] source coverage
Coverage and evidence base
The priority spoken inventory contains seven ★★★/★★ appearances in the source map. Six provide full official or publisher transcript routes; MeetInnovators provides the complete audio plus an edited transcript. None is inaccessible or metadata-only. All seven have exact-schema notes and analyses below: 7 mapped − 7 notes − 7 analyses = 0 missing. Publisher transcripts are strong for Feld's words but not for host framing; no inferred audio quote is used where complete text was unavailable. [researcher inference · strong]
Source-by-source analysis
1. MeetInnovators — Brad Feld / Foundry Group (2010)
- Publication and historical context: A long interview near Foundry's first-fund era and before its later Select/Next expansion. canonical interview · note
- Reasoning chain: Technical founder experience → small company sale → roughly 40 personal angels → institutional venture → small-partnership redesign. [retrospective witness · moderate]
- Evidence/examples: NetGenesis, Critical Path, and Harmonix anchor the personal-angel period; the recollection of roughly 40 old Mobius companies in 2010 bounds ongoing work, not performance.
- Assumptions and access boundary: Edited transcript/audio cannot validate exact cash flows, decision dates, or interview omissions.
- Decision/biography implication: Separate operator liquidity, personal angel capital, SoftBank/Mobius fund roles, and Foundry capital before discussing “Feld's investments.”
- Evolution/contradiction: The early personal sale is described as a few million/two million across retellings; preserve approximate self-report. [retrospective witness · moderate]
2. Stanford eCorner — Great Entrepreneurs Go Out and Do (2011)
- Publication and historical context: Official full transcript of a public Stanford talk after Techstars/Foundry formation. official transcript PDF · note
- Reasoning chain: Build, learn, sell, angel-invest, join institutional venture, fail, then construct a preferred partnership model; founder/investor selection is mutual. [investor-stated · strong]
- Evidence/examples: Feld describes starting Feld Technologies with $10, the 1993 sale, later Mobius/Foundry transitions, and founder obsession as a key signal.
- Assumptions and access boundary: The official transcript controls speech, but career dates remain retrospective; its 1985 start/Dave Jilk joining in 1987 conflicts with Foundry's 2008 history saying Feld created the company with a partner in 1987.
- Decision/biography implication: Use founder action and obsession as a reference hypothesis, then test ethics, learning, team-building, and market evidence rather than glorify intensity.
- Evolution/contradiction: “Great entrepreneurs do” anticipates Do More Faster, but speed without safety/legal gates is not universal. [researcher inference · strong]
3. SaaStr — Feld Thoughts Live (2017)
- Publication and historical context: A software-investing stage interview after Next's formation. publisher transcript · note
- Reasoning chain: Mobius Fund I was “extremely well,” Fund II a “complete disaster,” and Fund III depended on one company; large organization complexity helped motivate Foundry's smaller equal-partner system. [retrospective witness · moderate]
- Evidence/examples: The 70-person/ten-partner organizational memory and fund contrast are rare adverse direct voice; WSIB later independently shows poor Mobius VI LP performance on one basis. WSIB report
- Assumptions and access boundary: Fund numbering/scope in speech may not map directly to legal vehicles; adjectives are not audited multiples.
- Decision/biography implication: Treat firm architecture and fund size as investment variables, not backstage administration.
- Evolution/contradiction: Foundry itself later expanded partners and vehicle complexity; the original anti-scale lesson needs re-testing. [researcher inference · strong]
4. Tim Ferriss — Brad Feld (2020)
- Publication and historical context: Long-form pandemic-era interview revisiting dot-com collapse, relationships, mental health, and work systems. publisher transcript · note
- Reasoning chain: Crisis and overextension impaired judgment/capacity; off-grid breaks, therapy, direct communication, and partnership systems became operating controls. [retrospective witness · moderate]
- Evidence/examples: The direct account adds human/key-person risk to the Mobius transition and explains later public mental-health advocacy.
- Assumptions and access boundary: Therapeutic meaning and causality are personal testimony; do not medicalize or infer portfolio outcomes.
- Decision/biography implication: A venture firm should monitor partner load, dependency, communication, leave coverage, and health-related key-person continuity without invading privacy.
- Evolution/contradiction: Extreme endurance and “do more faster” rhetoric require counterweights: recovery, boundaries, and explicit capacity stops. [researcher inference · strong]
5. Growth Everywhere (2017)
- Publication and historical context: A founder-marketing interview focused on career, network, and firm construction. timestamped page · note
- Reasoning chain: Small operator exit funded angel experimentation; repeated company exposure generated patterns and a network that later supported funds and Techstars. [retrospective witness · moderate]
- Evidence/examples: Feld self-reports an approximately $2m company sale and about 40 angel investments; no transaction documents or angel cash-flow ledger were located.
- Assumptions and access boundary: Promotional editing and rounded memory limit precision; named wins are vulnerable to survivorship bias.
- Decision/biography implication: Operator capital, relationship capital, and institutional capital are separate inputs with separate beneficiaries.
- Evolution/contradiction: “Investor since 1987” official shorthand conflicts with a first personal angel period after the 1993 sale and “accidental VC” around 1996. [researcher inference · strong]
6. Entrepreneurs for Impact (2024)
- Publication and historical context: Climate-founder interview during Foundry's final-fund lifecycle. interview · note
- Reasoning chain: The board investor supports rather than commands the CEO; mentorship and direct truth increase the founder's decision quality. [investor-stated · strong]
- Evidence/examples: At 04:39 Feld says that while he supports the CEO he works for her; the interview also discusses mentoring emerging fund managers.
- Assumptions and access boundary: A stated governance ideal is not founder-side evidence that every board relationship operated this way.
- Decision/biography implication: Define board service as truth, recruitment, pattern access, crisis support, and fiduciary challenge—not shadow management.
- Evolution/contradiction: All-partner veto and high ownership create real power even when rhetoric emphasizes founder control. [researcher inference · strong]
7. Alpha Partners — Driving Alpha (2025)
- Publication and historical context: Current direct voice after the 2024 final-fund announcement. publisher transcript · note
- Reasoning chain: A finite partnership can stop fundraising while working through roughly 80 active companies and about 50 fund positions; realized cash-on-cash is more meaningful than interim IRR. [investor-stated · moderate]
- Evidence/examples: Feld says the 2022 fund closed in 2023, only a handful of new investments remained, and mentorship shapes his “third third.”
- Assumptions and access boundary: Counts are rounded self-report and time-specific; sponsor/host deal lists are promotional and not personal attribution.
- Decision/biography implication: Evaluate late-career performance through remaining deployment, reserves, boards, exits, team continuity, and cash distributions—not new-fund cadence.
- Evolution/contradiction: TMRS interim IRRs are useful LP snapshots but, by Feld's own metric preference, cannot settle outcome. TMRS report [contemporaneous record · strong]
Cross-talk synthesis
Across fifteen years, the durable direct-voice structure is: technical operator learning, deliberate transition through angel/Mobius adversity, small-partnership architecture, mutual founder selection, community compounding, CEO-support governance, and a finite institutional lifecycle. The interviews add material absent from polished firm announcements—fund disasters, organizational overload, mental health, approximate angel counts, and the difference between interim IRR and cash-on-cash. [researcher inference · strong]
The most important contradictions remain live rather than “resolved”: Stanford's 1985 Feld Technologies start versus Foundry's 1987 team history; the current About page's combined “over 40 years” shorthand versus a distinct 1994 angel/around-1996 institutional-investor chronology; Mobius fund labels versus legal-vintage records; four-partner simplicity versus later six/seven equal partners; and founder-control rhetoric versus board/veto/ownership power. [researcher inference · strong] current bio · 1994 account
Decision playbook and modern translation as of 2026-08-22
Use a direct-voice interview as doctrine evidence, then require behavior and outcome controls. For a live deal: identify vehicle; freeze theme and product evidence; collect independent partner votes; map founder/investor power; state ownership/reserve/capacity; log bad-news channels; and pre-commit what would trigger follow-on, pass, leadership intervention, or stop. In AI companies, add data/model rights, evaluation drift, inference cost, security, safety, regulatory authority, and rollback. [researcher inference · strong]
Best five talks and unresolved record
- Stanford (2011): best complete career/process transcript.
- SaaStr (2017): strongest fund/organization self-critique.
- Tim Ferriss (2020): best capacity, health, and crisis account.
- MeetInnovators (2010): earliest rich angel/Mobius/Foundry boundary.
- Alpha Partners (2025): current final-fund and metric preference.
Unresolved: complete audio-verifiable transcripts for several later podcasts; contemporaneous 1985/1987 Feld Technologies records; exact Mobius legal-vehicle mapping to spoken Fund I/II/III; independent founder accounts across wins and failures; current final-fund authority/capacity; and any direct-voice discussion of Molekule or Crucible. [researcher inference · insufficient public record]
Model 1 — use the product, then correct for whose experience it is
- Rule — Use or closely observe the product before investing; record friction and founder response, then test whether your experience represents the target user. [researcher inference · strong] product essay
- Evidence status — Strong that Feld stated and repeatedly illustrated the practice; moderate that it improved selection; insufficient public record for a matched used/not-used outcome cohort. [researcher inference · insufficient public record]
- Provenance and origin — Feld's operator background and 2006 FeedBurner/NewsGator essay provide the clearest dated origin; iRobot later shows use after a pass. [investor-stated · strong] iRobot
- Mechanism and reasoning — Direct use reveals time-to-value, workflow, reliability and founder learning that decks/references can hide. Persona mismatch, familiarity and novelty can contaminate the signal. [researcher inference · strong]
- Historical and vehicle context — Consumer/SMB Internet software was directly usable by a technical partner; enterprise, hardware and regulated science require customer observation and independent validation. Partner time remains a closed-end-fund cost. [researcher inference · strong]
- When to use — Software, developer tools, consumer products, marketplaces, connected devices and workflows where repeated behavior can be observed before the round. [researcher inference · moderate]
- How to apply it — Log persona, task, baseline, activation, repeated use, failure, switching, telemetry, buyer/user difference, and founder response; require two target-user observations and one disconfirming reference. [researcher inference · strong]
- Examples — Three bounded cases. [researcher inference · strong]
- Documented application: FeedBurner usage and founder dialogue. decision-era source
- Documented application: NewsGator as another lived-product case in the same essay. note
- Exception/miss: Feld loved Roomba after Mobius passed iRobot, showing use and category fit can disagree. iRobot lab
- Evidence — A dated signed essay controls doctrine, a separate near-period pass post supplies an adverse case, and Google controls FeedBurner's later acquisition. No public decision/outcome cohort establishes causality. [contemporaneous record · strong] Google
- Limits, failure modes, and exception ledger — Investor taste can overfit affluent technical users; a good demo can hide retention, unit economics, safety or buyer friction; founder agreement can be mistaken for coachability. [researcher inference · strong]
- Evolution and contradictions — The product habit expands into themes/APIs and connected devices. iRobot contradicts a narrow software lens; Molekule shows firsthand product experience cannot replace independent efficacy. [researcher inference · strong] Molekule filing
- Modern VC translation (as of 2026-08-22) — For AI, require an evaluation suite, traceable data/model rights, workflow adoption, hallucination/failure logs, security, latency, inference cost and rollback; do not call prompt delight diligence. [researcher inference · strong]
Model 2 — themes are falsifiable filters, not forecasts or labels
- Rule — Define a durable causal shift before a company appears; use it to focus search and accumulated learning, then reject post-hoc theme assignment. [researcher inference · strong] Foundry themes
- Evidence status — Strong for the founding-era stated method and repeated theme language; moderate for consistent execution; insufficient for theme-level return/outperformance. [researcher inference · insufficient public record]
- Provenance and origin — Foundry's 2008 theme essay distinguishes themes from sectors; the 2011 distribution post assigns deals/partners and makes part of the map testable. [investor-stated · strong] distribution
- Mechanism and reasoning — A causal frame improves search, question quality and pattern accumulation. Breadth preserves serendipity; explicit boundaries and disconfirmers prevent rationalization. [researcher inference · strong]
- Historical and vehicle context — $225m/$232m early funds needed capacity filters; Select/Next and partner funds widened stage/object exposure, making one theme denominator less coherent. [researcher inference · strong] network essay
- When to use — Protocol transitions, developer platforms, distribution shifts, human-computer interaction, networks/marketplaces and new technical architecture with multiple product expressions. [researcher inference · moderate]
- How to apply it — Date the causal change, beneficiary, evidence, stage/geography, non-fit boundary, adjacency budget, expected lead channels, disconfirmers, and examples that would falsify it. [researcher inference · strong]
- Examples — Three bounded cases. [researcher inference · strong]
- Documented fit: Zynga mapped to distribution, with Brad deal credit and filing-controlled shared vehicle. theme post · S-1
- Researcher-applied fit: SendGrid as developer/email infrastructure, while Ryan retains lead credit. Foundry post
- Exception: iRobot fell outside the software category although the product later mattered. pass note
- Evidence — Founding and decision-date firm posts are independent of later issuer filings; the filing controls securities/role, not causal theme. No complete deal/pass map tests false positives/negatives. [contemporaneous record · strong]
- Limits, failure modes, and exception ledger — Themes can be too broad, mutually overlapping, consensus-driven, or indifferent to price; they can hide platform, regulatory and hardware risks. [researcher inference · strong]
- Evolution and contradictions — The original thematic model evolves into network-driven sourcing. Network information can strengthen a prepared mind or invert it by letting referrals define the theme. [researcher inference · strong] network note
- Modern VC translation (as of 2026-08-22) — An AI theme must specify workflow, buyer, data/model advantage, distribution, evaluation, cost curve, rights and disconfirmers—not merely “AI-native.” Audit outcome by theme date and lead channel. [researcher inference · strong]
Model 3 — decide independently, preserve dissent, and reopen on evidence
- Rule — Form partner views independently, avoid syndicate social proof, treat sustained dissent as information, and reopen a pass only when named evidence changes. [researcher inference · strong] decision post
- Evidence status — Strong for Feld's public all-four-partner rule and two re-entry examples; insufficient for full vote logs or comparative decision accuracy. [researcher inference · insufficient public record]
- Provenance and origin — The 2012 essay reports a 5–10% active-evaluation conversion, all-partner decision process, Fitbit/SEOmoz reversals and social-proof resistance. [investor-stated · strong]
- Mechanism and reasoning — Independent priors reduce informational cascades; dissent finds hidden risk; an explicit reopen threshold preserves learning without letting charisma erase a no. [researcher inference · strong]
- Historical and vehicle context — Four equal partners could deliberate every early deal. Six/seven partners, growth checks, partner funds and a final-fund tail change information load and veto cost. [researcher inference · strong] Foundry 2022
- When to use — High-uncertainty early-stage deals, crowded rounds, famous founders, inside rounds, partner-fund referrals, re-entry after a pass and follow-ons in marked winners. [researcher inference · moderate]
- How to apply it — Collect written pre-discussion priors, confidence, kill reason, sponsor, conflicts and evidence-to-reopen; reveal votes simultaneously; log decision and later outcome without rewriting reasons. [researcher inference · strong]
- Examples — Three bounded cases. [researcher inference · strong]
- Documented re-entry: Fitbit moved from no to investment; filing later records Feld's board role. Feld · S-1/A
- Documented re-entry: SEOmoz/Moz also overcame initial resistance; later ordinary outcome keeps the rule honest. Feld
- Exception: A quick-pass system can discard iRobot-like adjacency before decisive evidence arrives. iRobot
- Evidence — Signed posts establish the rule and examples; issuer filing independently establishes Fitbit role/securities; later company acquisition establishes outcome but not decision causality. [contemporaneous record · strong]
- Limits, failure modes, and exception ledger — Unanimity can create lowest-common-denominator selection, political veto, delay and sponsor gaming; dissent is not automatically insight; repeated reopening can waste capacity. [researcher inference · strong]
- Evolution and contradictions — Foundry's partnership expanded while still describing equal partners. The unchanged doctrine must operate differently at six/seven people and across fund managers. [researcher inference · strong]
- Modern VC translation (as of 2026-08-22) — Use blinded IC memos before celebrity metrics or co-investor lists; preserve model/data/security dissent; require a dated delta memo for any reopened AI deal. [researcher inference · strong]
Model 4 — seed is a service-and-reserve commitment, not a cheap option
- Rule — Make a seed only if the vehicle will treat it as a real investment: named partner attention, follow-on willingness, target ownership, and explicit stopping conditions. [researcher inference · strong] seed essay
- Evidence status — Strong for stated 2010 policy and later lifecycle vehicles; moderate for observed large ownership; insufficient for reserve ratios and seed-cohort returns. [researcher inference · insufficient public record]
- Provenance and origin — Feld separates two personal angel periods from Mobius/Foundry and rejects option-style seed behavior; checks spanned $250k–$10m in that dated policy. [investor-stated · strong]
- Mechanism and reasoning — Full commitment improves founder trust, information and follow-on continuity; reserves protect ownership. It consumes partner/fund capacity and can escalate sunk costs. [researcher inference · strong]
- Historical and vehicle context — Roughly $225m/$232m early funds and ~30 companies made reserves/attention scarce; Select and Next later financed winners and growth; FG Angels tested a different lightweight form. [researcher inference · strong] Select
- When to use — Pre-seed/seed companies inside core competence where a partner can serve, ownership can matter and follow-on milestones fit the vehicle's duration/capital. [researcher inference · moderate]
- How to apply it — Record initial/total check ceiling, ownership/dilution, reserve, partner time, next risk, follow-on threshold, bridge rule, pro-rata owner, governance and kill condition. [researcher inference · strong]
- Examples — Three bounded cases. [researcher inference · strong]
- Documented application: Seven named 2010 seed examples create a prospective set, though outcomes remain incomplete. seed note
- Documented lifecycle: Fitbit received Foundry and later Select capital; filing records about $10m Select Series D. Fitbit S-1/A
- Exception: FG Angels' supposedly lighter model exceeded partner capacity and stopped new investments. postmortem
- Evidence — Direct doctrine, official fund announcements and an issuer filing triangulate policy/behavior; missing cash-flow and reserve records prevent performance inference. [contemporaneous record · strong]
- Limits, failure modes, and exception ledger — Commitment can become escalation, signaling harm on no-follow, over-reserving, or weak service spread across too many seeds; bridge capital can postpone failure. [researcher inference · strong]
- Evolution and contradictions — A core all-partner seed model coexisted with FG Angels syndicates and later partner-fund exposure. “Commitment” must be vehicle-specific rather than a brand-wide claim. [researcher inference · strong]
- Modern VC translation (as of 2026-08-22) — For AI seed, reserve against proof milestones—workflow retention, evaluation reliability, data rights, security and unit economics—not model-demo progress; state compute and future capital needs. [researcher inference · strong]
Model 5 — own enough for wins to matter, but re-underwrite concentration
- Rule — Size ownership and reserves so a successful company can return meaningful fund capital, then re-underwrite price, dilution, concentration and liquidity at every follow-on. [researcher inference · strong] Next 2018
- Evidence status — Strong that Foundry publicly emphasized lifecycle ownership, sometimes above 30%; strong for disclosed stakes in three issuers; insufficient for cost-adjusted net return or optimality. [researcher inference · insufficient public record]
- Provenance and origin — Small fixed early funds/30-company capacity precede Select's winner concentration and Next's growth support. Feld prefers net cash-on-cash over interim IRR. [investor-stated · strong] quick passes
- Mechanism and reasoning — Venture power laws reward ownership in winners; reserves defend it. The same mechanism amplifies wrong theses, late marks, financing needs and single-company risk. [researcher inference · strong]
- Historical and vehicle context — Zynga/Fitbit/SendGrid stakes sit across early funds/Select and shared entities; partner funds add look-through concentration; final-fund liquidity extends duration. [researcher inference · strong]
- When to use — High-conviction companies with proven risk reduction, sufficient market, governance truth and vehicle capacity; never solely because an existing mark rose. [researcher inference · moderate]
- How to apply it — Model base/downside/upside ownership, dilution, total capital, reserve, exit value, time, liquidity, correlation and ex-top-one/ex-top-three fund result; compare each follow-on with a fresh external deal. [researcher inference · strong]
- Examples — Three bounded cases. [contemporaneous record · strong]
- Documented application: SendGrid's 29.64% pre-IPO Foundry position and later ~$3b company sale. S-1 · Twilio
- Documented application: Fitbit's 52.7m Class B shares across Foundry-linked entities and Select follow-on. S-1/A
- Exception: Molekule received about $58.44m affiliated legacy common-equivalent capital yet common was cancelled for no consideration. 13D · 13D/A
- Evidence — Issuer filings control securities/capital and acquirer releases control transactions; none reveals all cost, sale, distribution, fee or allocation cash flows. [contemporaneous record · strong]
- Limits, failure modes, and exception ledger — Sunk-cost escalation, marked “winner” bias, fund concentration, governance entrenchment, financing dependence, opportunity cost and delayed distributions can overwhelm ownership benefit. [researcher inference · strong]
- Evolution and contradictions — Early fund simplicity expands through Select/Next. Cash-on-cash rhetoric conflicts with a public evidence set dominated by interim IRRs, marks and securities. [researcher inference · strong] TMRS
- Modern VC translation (as of 2026-08-22) — Price AI follow-ons on normalized inference economics, retention, model dependence, security and future compute/capital; show realized/unrealized and direct/look-through exposure separately. [researcher inference · strong]
Model 6 — Give First and networks compound only with boundaries and audits
- Rule — Contribute before an immediate return is known, build durable communities, and treat resulting access as interested network evidence requiring capacity, conflict and inclusion controls. [researcher inference · strong] Give First
- Evidence status — Strong for stated doctrine and institutional behavior through Techstars/partner funds; moderate for access mechanism; insufficient for source-channel outperformance or net social benefit. [researcher inference · insufficient public record]
- Provenance and origin — Techstars began in 2006/07; Mentor Manifesto and “Give Before You Get” preceded the 2020 definition; Foundry later formalized partner-fund network investing. [contemporaneous record · strong] Techstars
- Mechanism and reasoning — Useful contribution creates trust, information flow, referrals, reputation and reciprocity over long horizons. Dense networks also reproduce status, homophily, hidden obligation and allocation conflict. [researcher inference · strong]
- Historical and vehicle context — Community activity spans personal time, accelerator entities, direct funds, fund-of-funds sleeves and LP mentorship—different beneficiaries and fiduciary rules. [researcher inference · strong] network essay
- When to use — Founder education, mentorship, ecosystem gaps, emerging-manager relationships, recruiting/reference networks and long-cycle communities where value can be given without coercion. [researcher inference · moderate]
- How to apply it — Record giver/beneficiary, resource, consent, conflicts, eligible vehicles, capacity, immediate/possible future benefits, inclusion gaps and no-reciprocity condition; audit lead/outcome channels. [researcher inference · strong]
- Examples — Three bounded cases. [researcher inference · strong]
- Documented institution: Techstars' four-person founding and first class. official history
- Documented doctrine: Mentor Manifesto preserves Jon Bradford/David Cohen/Feld attribution. manifesto
- Exception: FG Angels became more work than intended and stopped new deals. FG Angels
- Evidence — Official history, signed doctrine and operational postmortem independently establish system/limits; no network graph or matched cold-source cohort proves alpha. [contemporaneous record · strong]
- Limits, failure modes, and exception ledger — Mentorship can create pressure, advice overload, signaling, confidentiality/conflict, insider access, sponsor dependence and burnout; generosity branding can obscure extraction. [researcher inference · strong]
- Evolution and contradictions — Informal founder/community activity became Techstars, a manifesto, a named doctrine and partner-fund strategy. Commercial and public-good benefits increasingly overlap. [researcher inference · strong]
- Modern VC translation (as of 2026-08-22) — Publish mentor/conflict/allocation rules; compensate hidden labor; measure participation and excluded groups; separate community KPIs from investment funnel/returns; cap partner time. [researcher inference · strong]
Model 7 — guide the CEO, tell the truth, and preserve decision ownership
- Rule — The investor's board role is to surface truth, recruit, connect, challenge and support; the CEO owns company decisions unless fiduciary/legal thresholds require formal action. [researcher inference · strong] EFI interview
- Evidence status — Strong for Feld's stated CEO-support philosophy and multiple board records; moderate for repeated behavior; insufficient for causal value-add or founder experience across outcomes. [researcher inference · insufficient public record]
- Provenance and origin — Feld's operator/board apprenticeship, Mentor Manifesto and 2024 “I work for her” statement supply a long arc. [investor-stated · strong] Stanford
- Mechanism and reasoning — Clear ownership speeds execution; direct truth reduces hidden risk; board network/recruiting closes gaps. Formal fiduciary challenge protects the company when support alone fails. [researcher inference · strong]
- Historical and vehicle context — Feld served on Zynga/Fitbit/SendGrid boards while Foundry vehicles held meaningful stakes and collective veto. Power is real even when rhetoric is founder-centered. [contemporaneous record · strong] Zynga S-1
- When to use — Board service, CEO coaching, hiring, financing, crisis, strategy disagreement, founder transition, misconduct, insolvency and conflicts. [researcher inference · moderate]
- How to apply it — Agree on CEO/board domains, start with bad news, state advice versus vote, document conflicts/recusal, build escalation/whistleblower channels, and evaluate board contribution with founder/management feedback. [researcher inference · strong]
- Examples — Three bounded cases. [researcher inference · strong]
- Documented board role: Feld director at Zynga from Nov. 2007; shared vehicle stake remains separate. S-1
- Documented board role: Feld at Fitbit from Aug. 2010–May 2015; filing controls dates. S-1/A
- Exception/adverse: Interliant bankruptcy/legal record demonstrates that governance requires reporting, conflict and stop controls beyond supportive rhetoric. SEC order
- Evidence — Issuer/regulator filings independently control roles/outcomes; direct speech controls philosophy; no minutes or broad founder sample controls board behavior. [contemporaneous record · strong]
- Limits, failure modes, and exception ledger — Founder deference can delay intervention; control can masquerade as advice; high ownership can distort judgment; board access can create conflicts; bad-news culture can still fail. [researcher inference · strong]
- Evolution and contradictions — Mentor language moves from advice norms to explicit CEO service. Collective veto and concentrated ownership remain a necessary counterweight to the no-control narrative. [researcher inference · strong]
- Modern VC translation (as of 2026-08-22) — Add model/data/security/safety escalation to board dashboards; define who can stop deployment, disclose investor conflicts and preserve management ownership of implementation. [researcher inference · strong]
Model 8 — design experiments with time, capital, and walk-away rules
- Rule — Treat new investing formats as bounded experiments: pre-register learning, capacity and economic thresholds; support existing obligations; stop new activity when the model fails. [researcher inference · strong] FG Angels
- Evidence status — Strong for FG Angels' explicit stop and Crucible liquidation; moderate for a generalized Feld method; insufficient for counterfactual benefit/cost. [researcher inference · insufficient public record]
- Provenance and origin — Feld's startup bias toward action meets hard partnership-capacity lessons from Mobius and public experiments. [researcher inference · moderate] SaaStr
- Mechanism and reasoning — Time-boxes convert novelty into learning; kill rules prevent sunk-cost and deadline pressure; continuing duties preserve trust. Poor metrics can terminate promising systems or conceal economics. [researcher inference · strong]
- Historical and vehicle context — FG Angels was a syndicate overlay; Crucible a regulated public SPAC; Foundry Next and partner funds were larger experiments retained. Each has different stakeholders and stop costs. [researcher inference · strong]
- When to use — New sourcing channels, scout/syndicate programs, accelerators, geographic offices, fund sleeves, SPACs, platform services and AI diligence tools. [researcher inference · moderate]
- How to apply it — Specify hypothesis, baseline, owner, capital/time, stakeholders, conflicts, leading/lagging measures, review date, continuation/kill threshold, obligations and rollback. [researcher inference · strong]
- Examples — Three bounded cases. [researcher inference · strong]
- Documented stop: FG Angels stopped new investments after unexpected work. postmortem
- Documented walk-away: Crucible liquidated without forcing a business combination. 424B4 · 8-K
- Failure boundary: Molekule follow-on capital did not prevent common cancellation, emphasizing company-level recap gates. 13D/A
- Evidence — Firm postmortem and SEC SPAC/restructuring filings independently show stops/outcomes; initial hypotheses and counterfactuals remain private. [contemporaneous record · strong]
- Limits, failure modes, and exception ledger — Easy-to-measure activity can crowd out long learning; sponsors can redefine goals; kill rules can abandon option value; existing companies still require service after program stop. [researcher inference · strong]
- Evolution and contradictions — Foundry stopped FG Angels/Crucible yet expanded through Select/Next/partner funds and later ended fundraising entirely. The pattern is selective experimentation, not anti-growth. [researcher inference · strong]
- Modern VC translation (as of 2026-08-22) — For AI scouts/platform services, pre-register source quality, founder benefit, conflicts, human review, privacy/security, partner-time and cost; stop before tooling becomes uncontrolled selection infrastructure. [researcher inference · strong]
Evidence gaps and candidate models
| candidate | why not promoted | what would change status |
|---|---|---|
| “Cash-on-cash always beats IRR” | A preference is explicit, but IRR and cash multiples answer different questions; no full Foundry cash-flow set | Audited vintage cash flows plus documented decision use and benchmark comparison. |
| “Boulder/geographic dispersion creates alpha” | Network/geography thesis exists; no matched city/source cohort | Complete lead/outcome map controlling stage/theme/price. |
| “Radical transparency predicts founder quality” | SEOmoz/TAGFEE and blog doctrine are rich but one ordinary case weakens universality | Prospective culture scoring and full outcome cohort with independent employee/customer evidence. |
| “Mental-health openness improves firm returns” | Direct testimony supports humane capacity design, not financial causality | Privacy-respecting organizational measures and comparative decision/coverage outcomes. |
[researcher inference · insufficient public record] Eight promoted models each contain twelve labeled components, at least three bounded examples/exceptions, four-plus citation placements, multiple independent underlying sources, an adverse boundary, and dated modern transfer. Candidate ideas remain hypotheses rather than hidden models.
What the evidence supports
The defensible claim is that Feld helped build an unusually explicit venture operating system: technical/product observation, themes, independent collective decisions, seed commitment, ownership/reserves, open teaching, mentorship/community, founder-support governance, partner-fund networks and bounded experiments. The record supports material roles in Foundry, Techstars, Zynga/Fitbit governance and decades of public doctrine. [researcher inference · strong] profile · philosophy
The record does not prove lone sourcing, a complete denominator, audited career outperformance, personal ownership of Foundry securities, or causal board value. SendGrid is Ryan McIntyre-led; Foundry stakes have shared control; major company transactions lack cost/distribution data; one early Foundry LP snapshot is strong while one Mobius vintage is poor. [researcher inference · strong] Pareto
What could falsify the thesis
The edge thesis is falsified by a complete funnel showing no advantage in product/theme/network sourcing after stage/price controls; returns disappearing outside the top three; themes assigned after decisions; partner-role records assigning repeated decisive work elsewhere; network leads underperforming cold leads; or founder evidence contradicting service doctrine. [researcher inference · strong]
It would strengthen with complete IC/pass/follow-on records, channel tags, partner roles, security cash flows, audited vintage DPI/TVPI/MOIC, ex-top-one/ex-top-three results, Techstars/partner-fund allocation records and independent founder/board accounts across wins, ordinary outcomes and failures. [researcher inference · insufficient public record]
Attribution and denominator audit
The reconstructed chain separates Feld Technologies, personal angels, Intensity/SoftBank, Mobius, each Foundry vehicle, FG Angels, Techstars entities, personal LP positions and Crucible. Discovery, mentorship, thesis sponsorship, vote, vehicle capital, board, follow-on, exit and narration remain separate. [researcher inference · strong] vehicle table · people map
The official collection search observed 136 distinct detail-card URLs in one session but the dynamic page is incomplete and mixes companies, exits and partner funds. Foundry reports 200+ companies/nearly 50 fund investments. The material research subset contains 32 company lineages plus FG Angels/Crucible; seven companies plus two noncompany cases support nine labs; 25 company lineages remain unresolved. No ratio against the mixed 136 or rounded 200+ scope is used as performance. [researcher inference · strong] funnel
Interliant allegations are described as allegations in a procedural bankruptcy decision, never as adjudicated Feld liability. Molekule's mixed NARB findings, shared governance, aggregate legacy capital and common cancellation are bounded rather than converted into total product failure or an exact fund loss. Techstars' later organizational criticism is not attributed personally to Feld. [researcher inference · strong] Molekule controls · Techstars controls
Transfer limits for modern VCs
The transferable processes are dated themes, firsthand workflow evidence, independent IC votes, explicit re-entry evidence, vehicle/ownership/reserve discipline, direct founder truth, bounded networks and pre-committed stop rules. They transfer as hypotheses, not as proof that a large ownership position or famous community will outperform. [researcher inference · strong] modern translation
Current AI and venture conditions add model/data rights, evaluation drift, security, safety, inference economics, regulation, slow liquidity and large-fund/private-mark risk. Do not copy a 2008 theme, 2010 check range, four-partner process, >30% lifecycle ownership, partner-fund network or final-fund structure without matching stage, competence, fund duration, fees, reserves and key-person coverage. [researcher inference · strong]
Unresolved evidence
The highest-value missing records are complete personal/Mobius/Foundry company and pass ledgers; dated IC and partner-role logs; security costs, sales and distributions; audited full-vintage DPI/TVPI/MOIC on one date; Techstars and partner-fund allocation/source-channel outcomes; founder/board evidence across wins and failures; Interliant merits/board/conflict records; and entity-level Molekule/Crucible economics. [researcher inference · insufficient public record] terminal ledger
Books and several audio/video routes remain partial, the live Foundry collection is incomplete/dynamic, and no matched base-rate dataset covers stage, theme, geography and vintage. These are terminal public-record gaps for this run, not permission to estimate. [researcher inference · insufficient public record]
Corrections made during review
- Replaced a stale About-page citation and removed the invented “formal founding” reconciliation; preserved Stanford's 1985 start/Dave Jilk joining in 1987 against Foundry's 1987 company-with-partner account. profile
- Replaced unsupported “investor since 1987” wording with the current combined “over 40 years” biography shorthand and direct 1994 angel/around-1996 institutional chronology. profile
- Preserved $225m versus $232m early-fund scope/rounding conflict. writings
- Preserved four-partner founding model versus six/seven later equal partners. philosophy
- Reframed thematic evolution into network-driven sourcing rather than treating the systems as static synonyms.
- Assigned SendGrid lead/mentorship to Ryan McIntyre; kept Feld's former-director role and shared vehicle capital separate. lab
- Added filing-controlled Rally and AvidXchange board, shared-control and stake boundaries; neither filing establishes personal ownership or proceeds.
- Added the pleading-stage Fitbit litigation boundary, balanced Molekule advertising warning, and source-matched Techstars institutional criticism.
- Restricted Zynga to Brad-attributed deal/board contribution plus shared vehicle securities; did not call every Foundry distribution deal Feld's.
- Did not convert Fitbit, Zynga or SendGrid shares/transaction value into personal or net fund return.
- Used UTIMCO, WSIB and TMRS only at their LP/date/metric scopes; did not pool vintages.
- Kept Interliant committee allegations distinct from merits/liability findings.
- Treated Molekule's mixed NARB findings and common cancellation as warning/severe impairment, not total product ineffectiveness or an exact $58.44m fund/personal loss.
- Treated Crucible as a liquidated SPAC search vehicle, not a portfolio-company write-off; returned trust capital remains separate from sponsor costs.
- Treated FG Angels as an operational stop with unknown cohort economics.
- Treated Mattermark consideration as unverified; did not repeat a paywalled “<$1m” figure.
- Removed performance fractions against the mixed/incomplete current Foundry collection.
[researcher inference · strong]
Twenty-point acceptance matrix
| # | verdict | controlling package evidence | adversarial reason |
|---|---|---|---|
| 1 | PASS | chronology | Seven eras connect formation, doctrine, decisions, outcomes and limits; date conflicts remain visible. |
| 2 | PASS | edge · snapshot | Domain, mechanism, predictions, falsifiers, alternatives and confidence are explicit. |
| 3 | PASS | nine labs | Formation evidence precedes reveal; invest/pass, kill, ownership/terms/capacity and next-check prompts are explicit. |
| 4 | PASS | Pareto | Separate economic-proxy, historical-importance and learning-value views; unsupported ordering/returns refused. |
| 5 | PASS | Eight reader roots | Profile, sources, writings, talks, investments, philosophy, models and review are substantive. |
| 6 | PASS | reconciliation table | Claimed, searched, researched, reconstructed, unresolved and excluded scopes plus dedup/follow-on rules are explicit. |
| 7 | PASS | writing parity | 24 priority writings = 24 notes = 24 source analyses; book/access limits explicit. |
| 8 | PASS | eight models | 8 × 12 fields; each has 3+ cases, 4+ citations, 2+ sources, exception and current transfer. |
| 9 | PASS | modern philosophy · writing transfer | Surviving rules, changed AI conditions, application and misuse are dated. |
| 10 | PASS | failure ledger | Eight adverse/ordinary/miss cases include thesis, warnings, response, stop/outcome, lesson and unknowns. |
| 11 | PASS | people map | Discovery, lead, capital, board and narrative/outcome controls are separated; unknown remains unknown. |
| 12 | PASS | vehicle map · vehicle philosophy | Personal, institutional, direct, follow-on, partner-fund, syndicate, accelerator, LP and SPAC boundaries retained. |
| 13 | PASS | historical context · operating environment | Formation regimes precede vehicle/deal inference; missing numerical base rates are not invented. |
| 14 | PASS | source map · coverage | 82 visible rows/80 URLs, 70 priority rows, mixed sources and itemized access gaps. |
| 15 | PASS | All root files and 31 notes | Material claims have adjacent canonical/local links and disclosed heading/paragraph/PDF/filing locators or explicit limits. |
| 16 | PASS | label audit | Material labels use only allowed attribution and support axes. |
| 17 | PASS | skeptical profile · skeptical philosophy | Outliers, team/vehicle, denominator, survivorship, economics, era, conflict and adverse cases are tested. |
| 18 | PASS | completed peers | Wilson, Breyer and Winblad are compared on sourcing, picking, vehicle, governance, adverse controls and attribution without ranking. |
| 19 | PASS | labs · signature decision process | Reader must decide before outcome; prompts cover pass/invest, kill, ownership/terms and next check. |
| 20 | PASS | study guide · chronology | Reading path, glossary, maps, checklists, cross-links and Markdown-only usability are explicit. |
The matrix has exactly 20 rows. A PASS means the repository requirement is satisfied by the cited public package, not that the underlying investment claim is proven beyond its evidence grade. [researcher inference · strong]
Central-claim citation audit trail
| ID | high-risk claim | controlling evidence and locator | adversarial result |
|---|---|---|---|
| C01 | Feld Technologies start | Stanford transcript, opening career segment · Foundry 2008 team history | PASS — conflict preserved, 1985/1987 not falsely harmonized or labeled formal founding. |
| C02 | angel/investor chronology | current combined biography · 1994 direct account · MeetInnovators career questions | PASS — scope preserved, combined experience, personal angels and institutional transition differ. |
| C03 | testable edge | profile mechanism/predictions | PASS, alternatives/falsifiers prevent hero claim. |
| C04 | Techstars founders/dates | official history, Our History | PASS, four founders retain credit. |
| C05 | Foundry original architecture | Who Are We, body | PASS, stated design not universal behavior. |
| C06 | Foundry lifetime/current state | final-fund announcement · 2025 transcript | PASS, rounded/time-specific firm counts. |
| C07 | Zynga role/stake | S-1, directors/principal stockholders · theme attribution | PASS, Brad deal/board plus shared vehicle, no personal return. |
| C08 | Fitbit role/stake/litigation | S-1/A, director/related transactions/stockholders · 2018 pleading-stage opinion | PASS, shares/entities/board dates bounded; allegations not proof and Feld/Foundry not defendants. |
| C09 | SendGrid lead/stake/outcome | Ryan-authored post · S-1 · Twilio | PASS, Ryan lead; shared stake; company consideration only. |
| C10 | Foundry 2007 performance | UTIMCO p.61 | PASS, 43.8% net IRR only for one LP/date. |
| C11 | Mobius VI performance | WSIB p.6 | PASS, 0.6x/-5.80% only for named LP/vintage/date. |
| C12 | Interliant | SEC findings · bankruptcy decision | PASS, bankruptcy/failure established; allegations not liability. |
| C13 | Molekule | NARB mixed findings · 13D Items 3–5 · 13D/A restructuring | PASS, claims warning, shared governance, aggregate capital and common cancellation bounded; no exact fund/personal loss. |
| C14 | final-fund metric preference | Next 2018 · Alpha transcript | PASS, stated preference not audited outcome. |
| C15 | denominator | reconciliation table · firm final-fund count | PASS, no mixed-object reconstruction ratio or hit rate. |
Ordinary-claim sample audit
| ID | sampled claim | evidence | result |
|---|---|---|---|
| O01 | MIT BS/MS appear in official biography | about | PASS, degree detail not independently transcript-verified. |
| O02 | blog began in 2004 and nine books listed | about · books | PASS, metadata only. |
| O03 | seed range was $250k–$10m in 2010 | seed post | PASS, dated policy not current universal range. |
| O04 | quick-pass post gives ~30 companies and ~10/year | post | PASS, firm capacity claim not denominator proof. |
| O05 | Mentor Manifesto attribution | manifesto opening | PASS, Bradford/Cohen/Feld roles preserved. |
| O06 | Give First definition evolved | definition | PASS, direct doctrine. |
| O07 | Select was $225m / existing companies only | announcement | PASS, no performance inferred. |
| O08 | Next 2016 was $500m / two sleeves | announcement | PASS, sleeves kept separate. |
| O09 | Next 2018 was $750m / seventh fund | Feld | PASS, self-authored fund history. |
| O10 | FG Angels stopped for capacity | postmortem | PASS, no financial failure inferred. |
| O11 | iRobot is a named pass | Roomba post | PASS, counterfactual access/return unknown. |
| O12 | Moz financing/board narrative | Feld post | PASS, company financing not investor cost/return. |
| O13 | Crucible $225m and liquidation | 424B4 · 8-K | PASS, public trust return and sponsor economics separated. |
| O14 | 31 writing/talk notes have exact schema | notes | PASS, mechanical H2/metadata audit required below. |
Independent deal and team cross-checks
| case | direct/firm narrative | independent control | reconciliation |
|---|---|---|---|
| Zynga | theme-distribution attribution | issuer S-1 | Brad deal/board; shared four-partner securities/company execution. |
| Fitbit | false-negative/re-entry post | issuer S-1/A | Feld board and vehicle securities; re-entry cause remains self-report. |
| SendGrid | Ryan-authored decision post | issuer S-1 + Twilio release | Ryan lead/mentor; Ryan/Feld former boards; shared capital; company value only. |
| FeedBurner | product-use post | Google acquisition announcement | doctrine/exit exist; terms and return absent. |
| Interliant | Feld failure retrospective | SEC order + bankruptcy decision | company failure/legal procedure controlled; no liability inference. |
| Molekule | Foundry portfolio association | 13D + 8-K + 13D/A | aggregate capital/ownership/restructuring controlled; Feld-only claim refused. |
| Crucible | Feld/Foundry sponsor role | SEC 424B4 + liquidation 8-K | chair/sponsor/vehicle and returned trust capital separated. |
Seven checks exceed the five-case floor. [researcher inference · strong]
Arithmetic, parity, and denominator checks
| calculation | reproduced result | interpretation |
|---|---|---|
| source rows | 82 visible rows; 80 unique URLs | Two artifacts appear in both current-state and literal corpus reconciliation. |
| priority rows | 44 ★★★ + 26 ★★ = 70 | Includes 31 writing/talk routes and 39 direct non-note controls. |
| writing/talk parity | 24 writings + 7 talks = 31; 31 notes; 31 analyses | Zero missing priority writing/talk item. |
| research funnel | 32 company lineages; 7 sufficiently reconstructed; 25 unresolved | Nine labs after adding FG Angels and Crucible; no performance ratio. |
| WSIB arithmetic | $49,282,966 ÷ $82,354,694 = 0.5984x | Consistent with reported rounded 0.6x; one LP/vintage/date. |
| model structure | 8 models × 12 labeled fields = 96; ≥24 bounded examples | Structural floor met before qualitative review. |
| review rows | 20 matrix rows | Exact, not 19 or 21. |
Citation, label, link, and structure QA
Every root document begins H1 then a substantive H2; INVESTMENTS begins with the exact Pareto H2. The 31 notes each require one metadata line and six H2 sections. Material labels use one attribution—investor-stated, contemporaneous record, documented behavior, retrospective witness, or researcher inference—and one support—strong, moderate, provisional, or insufficient public record. [researcher inference · strong]
Canonical external links sit adjacent to high-risk claims; local note links aid navigation but do not substitute for external evidence. Filings/LP PDFs use named tables, form sections or pages; posts/transcripts use headings, timestamps, speaker turns or disclosed locator limits. Quotes remain short and confined mainly to notes. [researcher inference · strong]
Mechanical QA must verify H1/H2 openings, exact note schema, 24/7 parity, 17 philosophy sections, 8×12 model fields, exact 20 review rows, local links/anchors, allowed labels, no malformed Markdown, and bookkeeping consistency. External links remain access-time evidence and may later move. [researcher inference · strong]
Reader conclusion
Study Feld for a transparent, testable system that connects product judgment, thematic preparation, collective independence, ownership/reserves, community, founder service and institutional lifecycle. Study the same dossier to see why team attribution, vehicle incentives, cash-flow evidence, power-law concentration, capacity and adverse records determine what “great investor” can responsibly mean. [researcher inference · strong]
Identity, chronology, firms, and current state
- ★★★ | Brad Feld — About | https://feld.com/about/ | live; accessed 2026-08-22 | first-person/official biography | Current Foundry/Techstars roles, Feld Technologies, nine books, blog, MIT BS/MS, and combined “over 40 years” experience; the live page does not date company formation or the start of investing. (reliability: A; access: full; locator: biography paragraphs)
- ★★★ | Techstars — About and History | https://www.techstars.com/about | live; accessed 2026-08-22 | official institutional history | Names David Cohen, David Brown, Brad Feld, and Jared Polis; incorporation November 14, 2006 and first class 2007. (reliability: A; access: full; locator: “Our History” timeline)
- ★★★ | Foundry — The Final Foundry Fund | https://foundry.vc/blog/2024/01/the-final-foundry-fund/ | 2024-01 | official firm announcement | Final-fund status, no generational succession, 200+ companies, nearly 50 fund investments, and continuing portfolio work; note. (reliability: A; access: full; locator: opening and portfolio-work paragraphs)
- ★★ | Foundry — Announcing Foundry 2022 | https://foundry.vc/blog/2023/05/announcing-foundry-2022/ | 2023-05 | official fund announcement | Decision-date framing for the 2022 vehicle before it was publicly labeled final. (reliability: A; access: full; locator: fund-size, team, and strategy passages)
- ★★ | Foundry — Who Are We? | https://foundry.vc/blog/2008/04/who-are-we/ | 2008-04 | founding-era firm essay | Says Feld created Feld Technologies with a partner in 1987 and began angels while at AmeriData; also documents Foundry's original small equal-partner design; note. (reliability: A; access: full; locator: Brad and team-history paragraphs)
- ★★ | Brad Feld — About Foundry Group | https://feld.com/about-foundry-group/ | live; accessed 2026-08-22 | first-person firm biography | Cross-checks cofounding/partner role but remains self-authored and current-state compressed. (reliability: A; access: full; locator: role and firm-description paragraphs)
- ★★ | MIT — Brad Feld '87, SM '88 | https://alum.mit.edu/ | archive/search route; accessed 2026-08-22 | institutional identity lead | Controls degree-era leads; precise alumni profile route was not stable, so degree claims rely on Feld's official bio. (reliability: B; access: partial; locator: search result/profile metadata)
- ★★ | Alpha Partners — Brad Feld: From Techstars to AI Trends | https://alphapartners.com/podcast/brad-feld-techstars/ | 2025 | publisher transcript | Current self-report: last fund, roughly 80 active companies/50 fund investments, few new deals, cash-on-cash preference; note. (reliability: A for direct voice/B for host framing; access: full; locator: transcript speaker turns)
Priority direct writings and firm doctrine
- ★★★ | Feld — Product-Focused Venture Capital | https://feld.com/archives/2006/08/product-focused-venture-capital/ | 2006-08 | signed essay | Product-use diligence and founder-response test; note. (reliability: A; access: full; locator: FeedBurner/NewsGator examples)
- ★★★ | Feld — How I Think About Seed Investing as a VC | https://feld.com/archives/2010/08/how-i-think-about-seed-investing-as-a-vc/ | 2010-08-02 | signed essay | Seed as commitment, $250k–$10m, reserves, all-partner engagement, syndication agnosticism; note. (reliability: A; access: full; locator: paragraphs 8–19)
- ★★★ | Feld — Make Your Own Decisions | https://feld.com/archives/2012/06/make-your-own-decisions/ | 2012-06 | signed essay | 5–10% evaluation-to-invest range, all-partner veto, Fitbit/Moz re-entry; note. (reliability: A; access: full; locator: decision and counterexample passages)
- ★★★ | Feld — Why We Pass Quickly on Things | https://feld.com/archives/2015/04/why-we-pass-quickly-on-things/ | 2015-04 | signed essay | Fixed-fund funnel, roughly 30 companies/fund and ten new decisions/year; note. (reliability: A; access: full; locator: capacity arithmetic and filters)
- ★★★ | Feld — VCs: Don't Bullshit | https://feld.com/archives/2014/07/vcs-dont-bullshit/ | 2014-07 | signed LP/fundraising retrospective | Mobius and Foundry fundraising candor, 90 meetings, rejection and shared-LP claims; note. (reliability: A; access: full; locator: Mobius/Foundry fundraising sequence)
- ★★★ | Feld — Term Sheet Series Wrap-Up / Venture Deals | https://feld.com/archives/2005/08/term-sheet-series-wrap-up/ | 2005-08 and 2011 book | signed series/book route | Founder-negotiation transparency coauthored with Jason Mendelson; note. (reliability: A; access: full for post/partial for book; locator: wrap-up and book-origin passages)
- ★★★ | Feld — The Techstars Mentor Manifesto | https://feld.com/archives/2011/08/the-techstars-mentor-manifesto/ | 2011-08 | signed ecosystem essay | Preserves Jon Bradford prompt, David Cohen manifesto, and Feld amplification; note. (reliability: A; access: full; locator: attribution and 18-item list)
- ★★★ | Feld — Definition of #GiveFirst | https://feld.com/archives/2020/10/definition-of-givefirst/ | 2020-10 | signed doctrine essay | Separates Give First from altruism and records naming evolution; note. (reliability: A; access: full; locator: definition/evolution paragraphs)
- ★★★ | Foundry — Our New Fund: Foundry Group Next 2018 | https://feld.com/archives/2018/08/our-new-fund-foundry-group-next-2018/ | 2018-08 | signed fund essay | $750m seventh fund, seven equal partners, lifecycle, ownership, cash-on-cash preference; note. (reliability: A; access: full; locator: fund-history and strategy passages)
- ★★★ | Foundry — Status of Our FG Angels Experiment | https://foundry.vc/blog/2016/01/status-of-our-fg-angels-experiment/ | 2016-01 | official experiment postmortem | Stops new syndicate deals because effort/capacity exceeded design; note. (reliability: A; access: full; locator: results and stop-decision passages)
- ★★★ | Foundry — What Does Foundry Group Invest In? | https://foundry.vc/blog/2008/11/what-does-foundry-group-invest-in/ | 2008-11 | founding-era firm essay | Original theme map and theme-versus-sector definition; note. (reliability: A; access: full; locator: named themes)
- ★★★ | Foundry — Foundry Group Select | https://foundry.vc/blog/2013/10/foundry-group-announces-its-newest-fund-foundry-group-select/ | 2013-10 | official fund announcement | $225m winner-only follow-on vehicle, up to $25m/company; note. (reliability: A; access: full; locator: mandate paragraph)
- ★★★ | Foundry — Our Newest Fund: Foundry Group Next | https://foundry.vc/blog/2016/09/our-newest-fund-foundry-group-next/ | 2016-09 | official fund announcement | $500m growth-plus-partner-fund vehicle; note. (reliability: A; access: full; locator: mandate and rationale)
- ★★★ | Foundry — Network-Driven Investing | https://foundry.vc/blog/2022/06/network-driven-investing/ | 2022-06 | official strategy essay | Partner-fund mechanism and $232m early-vintage scope; note. (reliability: A; access: full; locator: network and fund-history sections)
- ★★ | Feld — Your First Big Success: What's Next? | https://feld.com/archives/2014/06/first-big-success-whats-next/ | 2014-06 | signed retrospective | Career, bubble, Mobius, Foundry/Techstars, and depression chronology; note. (reliability: A; access: full; locator: chronological body)
- ★★★ | Feld — Every Generation Learns the Same Lessons | https://feld.com/archives/2018/08/every-generation-learns-the-same-lessons/ | 2018-08 | signed failure retrospective | Interliant capital/governance failure framing; note. (reliability: A; access: full; locator: Interliant narrative)
- ★★★ | Feld — Roomba, July's Toy of the Month | https://feld.com/archives/2005/07/roomba-julys-toy-of-the-month/ | 2005-07 | signed product/pass essay | Named iRobot anti-portfolio case and category-error test; note. (reliability: A; access: full; locator: product-use/pass paragraphs)
- ★★ | Feld — How a Small Company Can Make a Big Company Successful | https://feld.com/archives/2015/01/small-company-make-big-company-successful-2/ | 2015-01 | signed operating essay | Bigco partnership controls and distribution-dependency lesson; note. (reliability: A; access: full; locator: numbered lessons)
- ★★★ | Feld — SEOmoz, TAGFEE, and Me | https://feld.com/archives/2012/05/seomoz-tagfee-and-me/ | 2012-05 | signed investment/board essay | $18m financing, Feld board role, culture thesis; note. (reliability: A; access: full; locator: financing/board/TAGFEE passages)
- ★★ | Feld — Foundry Group Next | https://feld.com/archives/2015/12/foundry-group-next/ | 2015-12 | signed fund-design essay | UTIMCO relationship, partner-fund/growth rationale, anti-legacy position; note. (reliability: A; access: full; locator: Next and succession passages)
- ★★ | Feld — Why Do We Care About Techstars? | https://feld.com/archives/2009/04/why-do-we-care-about-techstars/ | 2009-04 | signed ecosystem essay | Community/mentorship rationale and commercial-public-good tension; note. (reliability: A; access: full; locator: rationale/community paragraphs)
- ★★ | Feld — Do More Faster | https://feld.com/archives/2010/10/do-more-faster/ | 2010-10 | signed book/Techstars reflection | Coauthored operating corpus and teaching flywheel; note. (reliability: A; access: full for post/partial for book; locator: purpose/Techstars paragraphs)
- ★★★ | Foundry — The Final Foundry Fund | https://foundry.vc/blog/2024/01/the-final-foundry-fund/ | 2024-01 | firm strategy announcement | Final vehicle and disclosed lifetime scale; note. (reliability: A; access: full; locator: opening and closing)
Priority talks, interviews, and direct-voice records
- ★★★ | MeetInnovators — Brad Feld, Foundry Group | https://meetinnovators.com/2010/11/01/brad-feld-foundry-group/ | 2010-11-01 | audio + edited transcript | Direct career, angel, Mobius, Foundry, NetGenesis/Critical Path/Harmonix evidence; note. (reliability: A for voice/B for edit; access: full; locator: named transcript questions)
- ★★★ | Stanford eCorner — Great Entrepreneurs Go Out and Do | https://stvp.stanford.edu/wp-content/uploads/sites/3/2024/09/great-entrepreneurs-go-out-and-do-entire-talk-transcript.pdf | 2011 talk; 2024 transcript file | official full transcript PDF | Feld Technologies chronology, $10 start, 1993 sale, founder obsession and mutual selection; note. (reliability: A; access: full; locator: PDF pages/segment headings)
- ★★★ | SaaStr — Feld Thoughts Live | https://www.saastr.com/feld-thoughts-live-one-one-brad-feld-video-transcript/ | 2017 | publisher transcript | Mobius Fund I/II/III performance language and organizational scale; note. (reliability: A for voice/B for transcript; access: full; locator: transcript passages)
- ★★★ | Tim Ferriss — Brad Feld Transcript | https://tim.blog/2020/07/24/brad-feld-transcript/ | 2020-07-24 | publisher transcript | Dot-com collapse, off-grid reset, mental health, partnership and capacity; note. (reliability: A for voice/B for transcript; access: full; locator: speaker turns)
- ★★ | Growth Everywhere — Brad Feld Interview | https://www.levelingup.com/growth-everywhere-interview/brad-feld-foundry-group/ | 2017 | interview transcript/timestamps | Personal company-sale and angel-history self-report; note. (reliability: A for voice/B for edit; access: full; locator: publisher timestamps)
- ★★★ | Entrepreneurs for Impact — Brad Feld | https://www.entrepreneursforimpact.com/brad-feld-cofounder-of-foundry | 2024 | video + transcript | CEO-support doctrine and fund-manager mentoring; note. (reliability: A for voice/B for host framing; access: full; locator: 04:39 and named sections)
- ★★★ | Alpha Partners — Driving Alpha | https://alphapartners.com/podcast/brad-feld-techstars/ | 2025 | podcast transcript | Current final-fund/wind-down and return-metric direct voice; note. (reliability: A for voice/B for promotion; access: full; locator: speaker turns)
Deal, team, security, and outcome controls
- ★★★ | Zynga — Form S-1 | https://www.sec.gov/Archives/edgar/data/1439404/000119312511180285/ds1.htm | 2011-07-01 | SEC issuer filing | Feld director since November 2007; 34,560,060 Foundry-linked pre-IPO shares/6.1%; four-partner shared power and pecuniary-interest limits. (reliability: A; access: full; locator: directors and principal-stockholder table/footnote)
- ★★★ | Fitbit — Form S-1/A | https://www.sec.gov/Archives/edgar/data/1447599/000119312515223928/d875679ds1a.htm | 2015-06 | SEC issuer filing | Feld board Aug 2010–May 2015; Foundry/Select securities, $10m Select Series D transaction, shared control. (reliability: A; access: full; locator: director biography, related transactions, principal stockholders)
- ★★★ | SendGrid — Form S-1 | https://www.sec.gov/Archives/edgar/data/1477425/000104746917006437/a2233508zs-1.htm | 2017-10 | SEC issuer filing | 9,629,727 Foundry shares/29.64% pre-IPO at filing basis; four-person control; Ryan McIntyre and Feld former directors. (reliability: A; access: full; locator: principal stockholders and director biographies)
- ★★★ | Rally Software — Form 424B4 | https://www.sec.gov/Archives/edgar/data/1313911/000104746913004318/a2214381z424b4.htm | 2013-04 | SEC issuer filing | Mobius entities held 3,406,213 shares/20.3% pre-offering; Feld and Jason Mendelson shared control; Feld served as director September 2003–March 2013. (reliability: A; access: full; locator: directors, principal stockholders, footnote 2)
- ★★★ | AvidXchange — Form S-1/A | https://www.sec.gov/Archives/edgar/data/1858257/000119312521290302/d219478ds1a.htm | 2021-09 | SEC issuer filing | Foundry Select held 5,032,964 shares/2.97% pre-offering; Feld and other managing directors shared control; Feld was to resign from the board immediately before effectiveness. (reliability: A; access: full; locator: directors, principal stockholders, footnote 14)
- ★★★ | Foundry — Foundry Group Invests in SendGrid | https://foundry.vc/blog/2010/04/foundry-group-invests-in-sendgrid/ | 2010-04 | decision-date firm post | Identifies Ryan McIntyre as lead/mentor; prevents Feld-only sourcing attribution. (reliability: A; access: full; locator: author and investment-rationale passages)
- ★★★ | Twilio — Completes Acquisition of SendGrid | https://www.twilio.com/en-us/press/releases/twilio-completes-acquisition-sendgrid | 2019-02-01 | acquirer release | Roughly $3b company transaction consideration; not Foundry proceeds or return. (reliability: A; access: full; locator: opening transaction paragraph)
- ★★★ | Molekule/AeroClean — Schedule 13D | https://www.sec.gov/Archives/edgar/data/1872356/000110465923005825/tm234190d1_sc13d.htm | 2023-01 | SEC beneficial-ownership filing | Aggregates $58,437,457 of Foundry-entity legacy capital/common-equivalent securities; names Feld among five shared managing members and as the required Foundry board nominee. (reliability: A; access: full; locator: Items 3–5 and exhibits)
- ★★★ | Molekule/AeroClean — Form 8-K | https://www.sec.gov/Archives/edgar/data/1872356/000110465923106353/tm2327546d1_8k.htm | 2023-10 | SEC issuer filing | Chapter 11 commencement and restructuring record. (reliability: A; access: full; locator: Item 1.03)
- ★★★ | Molekule — Schedule 13D/A | https://www.sec.gov/Archives/edgar/data/1671899/000110465924029980/tm247755d1_sc13da.htm | 2024-03 | SEC ownership filing | Common cancellation/no consideration after bankruptcy; does not allocate exact fund loss. (reliability: A; access: full; locator: Item 5 and restructuring description)
- ★★★ | Take-Two — Completes Combination with Zynga | https://www.take2games.com/ir/news/take-two-interactive-software-inc-and-zynga-inc-complete-combination | 2022-05 | acquirer release | Later company outcome; public consideration is not a 2007 investor cash-flow reconstruction. (reliability: A; access: full; locator: opening transaction paragraph)
- ★★ | Google — Completes Acquisition of Fitbit | https://blog.google/products/devices-services/fitbit-acquisition/ | 2021-01 | acquirer announcement | Later Fitbit outcome and stewardship statements; not Foundry proceeds. (reliability: A; access: full; locator: announcement body)
- ★★ | Twitter — Acquires Gnip | https://blog.x.com/engineering/en_us/a/2014/twitter-welcomes-gnip | 2014-04 | acquirer announcement | Confirms acquisition and data-business rationale; terms/Foundry cash flows absent. (reliability: A; access: full; locator: announcement body)
- ★★ | Google — Acquires AdMeld | https://googleblog.blogspot.com/2011/12/google-acquires-admeld.html | 2011-12 | acquirer announcement | Confirms exit; consideration and Foundry proceeds require filings. (reliability: A; access: full; locator: opening paragraphs)
- ★★ | Stratasys — Completes MakerBot Combination | https://investors.stratasys.com/news-events/press-releases | 2013 archive | acquirer release route | Confirms stock transaction route; current archive requires date search and does not expose investor economics. (reliability: A; access: partial; locator: June/August 2013 release metadata)
- ★★ | Google — Acquires FeedBurner | https://googleblog.blogspot.com/2007/06/feedburner-hello-google.html | 2007-06 | acquirer announcement | Confirms acquisition and product rationale; terms/vehicle returns unavailable. (reliability: A; access: full; locator: announcement body)
- ★★ | Return Path — Validity Combination | https://www.validity.com/press-releases/validity-acquires-return-path/ | 2019 | acquirer release | Later outcome route for a Mobius-linked company; no investor proceeds. (reliability: B; access: full; locator: opening transaction paragraph)
- ★★ | Alteryx — Acquires Trifacta | https://investor.alteryx.com/news-and-events/news-releases/ | 2022 archive | acquirer route | Outcome lead for a Foundry company; terms and partner attribution require separate filings. (reliability: A; access: partial; locator: 2022 acquisition release metadata)
- ★★ | Moz — iContact Acquires Moz | https://moz.com/blog/moz-acquired-by-icontact | 2021 | company announcement | Company outcome and continuity framing; no disclosed Foundry proceeds. (reliability: B; access: full; locator: acquisition announcement)
- ★★ | Techstars — Portfolio | https://www.techstars.com/portfolio | live; accessed 2026-08-22 | official accelerator portfolio | Establishes a separate Techstars exposure universe; not Feld personal or Foundry ownership. (reliability: A; access: full; locator: portfolio filters/list)
- ★★ | In re Fitbit, Inc. Stockholder Derivative Litigation | https://law.justia.com/cases/delaware/court-of-chancery/2018/ca-2017-0402-jrs.html | 2018 | Delaware Chancery opinion mirror | Certain derivative allegations survived pleading, but merits/proof remained unresolved and neither Feld nor Foundry was a defendant. (reliability: B mirror of judicial record; access: full; locator: opinion posture, parties, conclusion)
Fund performance, vehicle, legal, and adverse primary records
- ★★★ | UTIMCO — Board Book, Nov. 29, 2017 | https://www.utimco.org/media/iqxdvo3z/board-book-november-29-2017.pdf | 2017-11-29 | institutional LP report | Foundry 2007 since-inception net IRR 43.8% at one LP/time snapshot; no DPI/TVPI or personal result. (reliability: A; access: full; locator: PDF p.61/table row)
- ★★★ | Washington State Investment Board — Private Markets IRR, June 30 2023 | https://www.sib.wa.gov/docs/reports/quarterly/ir063023.pdf | 2023-06-30 | institutional LP report | Mobius Technology Ventures VI: $82.35m paid-in, $49.28m distributed, 0.6x, -5.80% net IRR; Side Fund VI separately 1.5x/6.34%. (reliability: A; access: full; locator: PDF p.6 rows)
- ★★★ | TMRS — Private Investment Report, Dec. 31 2022 | https://www.tmrs.com/uploads/files/general/down/Private_Investement_Report_12_31_2022.pdf | 2022-12-31 | institutional LP report | One-LP interim Foundry 2022/Next positions, largely unrealized and valuation-sensitive. (reliability: A; access: full; locator: PDF table p.3)
- ★★★ | SEC — Interliant Administrative Order | https://www.sec.gov/files/litigation/admin/2008/34-58155.pdf | 2008-07-14 | regulator order | Delinquent filings, August 2002 Chapter 11, and 2001 loss; controls company outcome, not investor wrongdoing. (reliability: A; access: full; locator: findings ¶¶1–4)
- ★★★ | I Successor/Interliant, 321 B.R. 640 | https://www.casemine.com/judgement/us/5914756badd7b049343b0346 | 2005 | bankruptcy decision mirror | Records committee allegations involving Feld Group/Mobius/Bradley Feld and a procedural ruling; allegations are not adjudicated liability. (reliability: B mirror of judicial record; access: full; locator: factual background and claims)
- ★★ | NARB — Molekule advertising decision announcement | https://www.prnewswire.com/news-releases/narb-finds-supported-claims-by-molekule-that-the-peco-filter-of-its-mh1-air-purifier-can-address-bioaerosol-and-voc-pollution-recommends-discontinuance-or-modification-of-other-claims-including-discontinuance-of-superiority-clai-301030514.html | 2020-03-26 | official decision announcement distributed by PR Newswire | Found support for some PECO claims but recommended discontinuing or modifying pollution-elimination, superiority, quantified-performance, independent-testing, and allergy/asthma-relief claims; Molekule agreed. (reliability: A/B; access: full; locator: findings and advertiser statement)
- ★★ | TechCrunch — Techstars retools amid former-staff criticism | https://techcrunch.com/2024/02/23/as-techstars-retools-some-former-staffers-say-it-lost-focus-on-what-made-it-successful/ | 2024-02-23 | reported institutional criticism | Former staff criticized centralization and sponsor dependence; evidence concerns Techstars and later management, not personal misconduct by Feld. (reliability: B; access: full; locator: former-staff and company-response passages)
- ★★ | TechCrunch — Techstars layoffs and JPM program closures | https://techcrunch.com/2024/08/07/techstars-is-laying-off-17-percent-ending-jp-morgan-backed-programs/ | 2024-08-07 | reported institutional outcome | Reports 17% layoffs, JPM-backed program closures, and David Cohen's overbuilding/overhiring explanation; does not establish Feld's personal causality. (reliability: B; access: full; locator: opening and Cohen-statement passages)
- ★★★ | Foundry — Current Portfolio | https://foundry.vc/portfolio/ | live; accessed 2026-08-22 | official current/mixed list | Reproducible visible roster mixing active companies, exits, and partner funds; not a complete lifetime or Feld-only ledger. (reliability: A; access: full; locator: filterable company/fund cards)
- ★★ | Foundry — Team | https://foundry.vc/team/ | live; accessed 2026-08-22 | official people page | Current equal partners and staff; not historical deal-role proof. (reliability: A; access: full; locator: partner cards)
- ★★ | Foundry — 2022 Responsible Investment Policy | https://foundry.vc/ | archive/search route | Current governance/sustainability lead; stable document not recovered in this pass, so no substantive claim depends on it. (reliability: C; access: search-route; locator: site search)
Additional decision, failure, and corpus routes
- ★ | Feld — Protocol tag archive | https://feld.com/archives/tag/protocol/ | archive | Mapbox/SimpleGeo/deCarta decision chain and theme evolution; individual underlying posts control any claim. (reliability: C; access: full archive; locator: dated post list)
- ★ | Feld — The Foundry Group Themes | https://feld.com/archives/tag/foundry-group-themes/ | archive | Additional theme corpus route; not counted as a separate underlying work. (reliability: C; access: full archive; locator: dated post list)
- ★ | Feld — Venture Deals category | https://feld.com/archives/category/venture-deals/ | archive | Long term-sheet/financing corpus; sampled through the mapped series/book route. (reliability: C; access: full archive; locator: pagination)
- ★ | Feld — Techstars category | https://feld.com/archives/tag/techstars/ | archive | Large multi-author/history lead; priority sample is bounded to doctrine and founder-support notes. (reliability: C; access: full archive; locator: pagination)
- ★ | Feld — Depression category | https://feld.com/archives/tag/depression/ | archive | Mental-health writing route relevant to capacity and leadership, not an investing-return source. (reliability: A for first-person/C for archive completeness; access: full; locator: dated posts)
- ★ | Stanford eCorner — Ending and Starting Venture Capital Firms | https://stvp.stanford.edu/wp-content/uploads/sites/3/2024/09/ending-and-starting-venture-capital-firms-transcript.pdf | 2011 talk; 2024 transcript | Official direct-voice clip transcript on Mobius ending/Foundry formation; treated as a segment of the Stanford session, not a new priority work. (reliability: A; access: full; locator: PDF full clip)
- ★ | Techstars — Brad Feld Returns: The Power Behind Give First | https://www.techstars.com/blog/podcasts/brad-feld-returns-the-power-behind-give-first | 2025 | official podcast page | Current promotional route; no complete voice-verifiable transcript located, so no direct quotation used. (reliability: B; access: partial; locator: episode description)
- ★ | Feld — Books | https://feld.com/books/ | live; accessed 2026-08-22 | official bibliography | Nine-book metadata and coauthor boundaries; full texts not uniformly accessible. (reliability: A for metadata; access: partial; locator: book cards)
- ★ | Internet Archive — Feld.com captures | https://web.archive.org/web/*/feld.com | archive route | Recovery route for migrated/dead posts; capture completeness varies. (reliability: C; access: partial; locator: timestamped captures)
- ★ | SEC EDGAR — Foundry-linked issuer search | https://www.sec.gov/edgar/search/ | filing search route | Exhausted for named public controls; search results are navigation, cited filings are controlling artifacts. (reliability: A for filings/C for search completeness; access: full; locator: issuer/form/date queries)
- ★ | Feld — Small Company/Big Company corpus | https://feld.com/archives/tag/big-companies/ | archive route | Partnership-failure denominator lead; one priority essay sampled, no full case corpus reconstructed. (reliability: C; access: partial; locator: archive entries)
- ★ | Foundry — Blog archive | https://foundry.vc/blog/ | archive | Firm-authored strategy, deal announcements, partner attribution and postmortems; bylines preserved. (reliability: A for posts/C for archive denominator; access: full; locator: post cards/pagination)
Coverage assessment
The map contains 82 visible source rows and 80 unique underlying URLs: the final-fund artifact and Alpha transcript each appear once in current-state mapping and once in literal corpus reconciliation. Of the 82 rows, 70 are ★★★/★★ priority rows. The 31 priority direct writings/talks have 31 exact-schema notes and 31 source-specific analyses. The remaining priority rows are filings, regulator/LP reports, official histories, outcome controls, and adverse reporting processed directly in PROFILE, INVESTMENTS, and REVIEW; the methodology does not require note files for non-writing/non-talk controls. [researcher inference · strong]
The bounded company universe starts with Foundry's live mixed portfolio page: 136 visible linked cards observed on 2026-08-22, including direct companies, exits, and partner funds. Foundry separately reports 200+ direct-company investments and nearly 50 fund investments over its life. Because the live page is explicitly not a lifetime list and mixes object types, neither number is a Brad Feld personal denominator. INVESTMENTS lists a 32-name researched company subset, reconstructs seven company cases plus two noncompany cases sufficiently for nine labs, and leaves 25 materially researched company names unresolved; career-wide coverage and hit rate are not computable. [contemporaneous record · strong] final-fund disclosure · ledger
Primary-source strengths are unusual: long first-person archives, official full transcripts, issuer filings for Zynga/Fitbit/SendGrid/Rally/AvidXchange/Molekule, regulator and judicial records, and three LP disclosures. Independent adverse controls cover Techstars' institutional retrenchment and Molekule's advertising claims. Weaknesses remain decisive: no full Feld/Mobius/Foundry cash-flow ledger; no consistent vintage DPI/TVPI/MOIC; no complete pass/write-off denominator; no IC memos; no partner allocation records; and only selected founder/board perspectives. Public acquisition values and securities are never converted into personal return. [researcher inference · insufficient public record]
Access gaps are itemized rather than silently waived: books are sampled through author posts and metadata, the 2025 Techstars page lacks a full transcript, archives can omit migrated posts, the current Foundry roster is not historical, and the case-law route is a mirror. These sources remain ★ navigation/context routes and do not create unsupported priority parity obligations. [researcher inference · strong]
Source notes
t Driving Alpha — From Techstars to AI Trends
- URL: https://alphapartners.com/podcast/brad-feld-techstars/ | Published: 2025 | Format: podcast + publisher transcript | Reliability: A for direct voice/B for promotional framing | Access: full | Accessed: 2026-08-22 | Locator scheme: transcript speaker turns and paragraph sequence; no stable timestamps exposed
Takeaways
- Feld frames his late-career “third third” around mentorship and contribution, while Foundry's final vehicle continues deployment/portfolio work.
- investor-stated; moderate: long-duration trust and community are presented as compounding systems, not immediate transactions.
- The host's deal list is promotional and is not used as personal attribution evidence.
Quotes
- "how I spend the last third of my life" (opening answer).
Biography and decision evidence
- The transcript cross-checks MIT, Feld Technologies, Mobius, Foundry, Techstars, and the 2025 Give First publication.
Philosophy signals
- Tags: evolution, mentorship, communities, AI, late career.
Contradictions, counterevidence, and access limits
- Sponsor and host framing uses “his investments” loosely; primary filings and board records supersede it.
Open questions
- What investment role and decision rights persist during Foundry's long wind-down?
t Entrepreneurs for Impact 91 — Climate-Tech and VC Lessons
- URL: https://www.entrepreneursforimpact.com/brad-feld-cofounder-of-foundry | Published: 2024 | Format: podcast + full transcript | Reliability: A for direct voice | Access: full | Accessed: 2026-08-22 | Locator scheme: inline timestamps and speaker turns
Takeaways
- At 04:39 Feld defines investor service: while he supports the CEO, he works for her; loss of support triggers work to restore alignment, not automatic removal.
- investor-stated; moderate: he frames LP stakes in other venture funds as a mentoring/network role, particularly for first-time GPs.
- The transcript supplies a late-career account of active early-stage work without claiming control ownership.
Quotes
- "as long as I support the CEO, I work for her" (04:39 answer).
Biography and decision evidence
- Feld says he came to investing through entrepreneurship and co-founded Techstars in 2006; current title claims are dated to the episode.
Philosophy signals
- Tags: governance, founder service, partner funds, climate, mentoring.
Contradictions, counterevidence, and access limits
- “Work for the CEO” coexists with fiduciary duties to company and fund; the transcript does not resolve every conflict case.
Open questions
- How often did loss of CEO support lead to replacement, and who decided?
t Growth Everywhere 222 — Startup and Well-Being
- URL: https://www.levelingup.com/growth-everywhere-interview/brad-feld-foundry-group/ | Published: 2017 | Format: podcast, transcript PDF, timestamped show notes | Reliability: A for direct voice/B for notes | Access: full page and transcript route | Accessed: 2026-08-22 | Locator scheme: timestamped show notes
Takeaways
- At 07:35–10:13 Feld separates 1994 personal angels from later firms and describes retaining only $100,000 after reinvesting sale proceeds; the amount is self-reported.
- At 11:09–13:20 he prioritizes execution and business characteristics over the raw idea.
- investor-stated; moderate: relationship deliberateness is presented as both life and investor-selection discipline.
Quotes
- "the idea is unimportant; what you DO with the idea is important" (show notes 11:18).
Biography and decision evidence
- The page attributes the 1993 Feld Technologies sale at $2 million and names Harmonix among early angels; no transaction document was located.
Philosophy signals
- Tags: execution, founder, risk, angel portfolio, well-being.
Contradictions, counterevidence, and access limits
- Show-note shorthand credits “Foundry” with companies without partner-level distinction; issuer filings control attribution.
Open questions
- Personal cash-flow verification and the other angel outcomes are unavailable.
t MeetInnovators — Brad Feld from Foundry Group
- URL: https://meetinnovators.com/2010/11/01/brad-feld-foundry-group/ | Published: 2010-11-01 | Format: 61-minute audio + condensed transcript | Reliability: A for direct voice/B for condensation | Access: full audio, condensed text | Accessed: 2026-08-22 | Locator scheme: transcript question/answer openings; no stable text timestamps
Takeaways
- Feld separates entrepreneur, personal angel, Mobius, Foundry, and Techstars roles; in 2010 he said roughly 40 old Mobius companies still required management.
- investor-stated; moderate: he describes reinvesting most proceeds from Feld Technologies into about 40 angels, with NetGenesis, Critical Path, and Harmonix as successful examples.
- The transcript emphasizes direct partner involvement and relationship quality, but economic claims remain self-reported.
Quotes
- "from entrepreneur to angel investor to venture capital investor" (answer beginning "So I’ve sort of gone").
Biography and decision evidence
- Claims include Boulder move in 1995, SoftBank affiliation in 1996, Mobius evolution, and Techstars co-founding with David Cohen in 2006.
Philosophy signals
- Tags: biography, angels, role boundaries, partnership, Techstars.
Contradictions, counterevidence, and access limits
- The page calls itself condensed; exact omitted context and audio timestamps were not independently transcribed.
Open questions
- Full personal angel denominator, checks, dilution, and realized cash flows remain unavailable.
t SaaStr — Feld Thoughts Live with Harry Stebbings
- URL: https://www.saastr.com/feld-thoughts-live-one-one-brad-feld-video-transcript/ | Published: 2017 | Format: video + publisher transcript | Reliability: A for direct voice/B for transcript | Access: full | Accessed: 2026-08-22 | Locator scheme: speaker turns; source supplies no stable transcript timestamps
Takeaways
- Feld reports that Mobius Fund I did extremely well, Fund II was a complete disaster, and Fund III depended on one remaining company; all are self-characterizations, not audited figures.
- investor-stated; strong: company scaling should be understood as changing “machines,” and boards should help CEOs navigate rather than substitute for management.
- He describes Foundry's origin after Mobius scaled to about 70 people and ten partners, then contracted.
Quotes
- "venture funds last 10 years is a happy fantasy" (opening biography exchange).
Biography and decision evidence
- The talk differentiates founder/partner history and admits the prior firm's adverse funds before presenting Foundry.
Philosophy signals
- Tags: fund duration, scaling, boards, culture, failure.
Contradictions, counterevidence, and access limits
- No fund cash-flow schedule verifies the qualitative fund grades; transcript has no stable timestamps.
Open questions
- Which one Mobius III company drove the remaining outcome, and what was net LP return?
t Stanford eCorner — Great Entrepreneurs Go Out and Do
- URL: https://stvp.stanford.edu/wp-content/uploads/sites/3/2024/09/great-entrepreneurs-go-out-and-do-entire-talk-transcript.pdf | Published: talk 2011-10-19; transcript archive 2024 | Format: official video transcript, 1:00:30 | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: PDF pages 1–10; official clip titles
Takeaways
- Feld reconstructs Feld Technologies, AmeriData acquisition work, angel investing, Mobius's rise/contraction, Foundry formation, and the distinction between angel and VC portfolio thinking.
- investor-stated; strong for articulated process: Foundry sought founders obsessed with vision/product and wanted mutual selection rather than capital-provider dominance.
- The talk records Mobius succession as a deliberate choice not to raise again, not a frictionless success story.
Quotes
- "The great entrepreneurs make a decision" (official “Obsessed With Vision and Product” clip transcript).
Biography and decision evidence
- PDF pp. 1–3 gives a first-person chronology; the separate “Ending and Starting Venture Capital Firms” clip supplies the 2003–2006 transition.
Philosophy signals
- Tags: founder obsession, mutual selection, biography, firm formation, community.
Contradictions, counterevidence, and access limits
- A 2011 retrospective may rationalize earlier choices; contemporaneous filings and firm records control where available.
Open questions
- Formal Mobius votes, LP correspondence, and partner economics are private.
t Tim Ferriss Show 448 — Brad Feld
- URL: https://tim.blog/2020/07/24/brad-feld-transcript/ | Published: 2020-07-24 | Format: podcast + official transcript | Reliability: A for direct voice | Access: full; quotation license respected | Accessed: 2026-08-22 | Locator scheme: transcript speaker turns and topic headings; no stable per-turn timestamps
Takeaways
- Feld places the 2000 relationship crisis, portfolio collapse, and off-grid practice inside the dot-com reversal rather than as private trivia.
- investor-stated; moderate: deliberate periods of disconnection became a capacity/risk control; this is a personal operating rule, not demonstrated investment alpha.
- The discussion distinguishes the easy-money 1996–2000 environment from the subsequent company-saving work.
Quotes
- "The stupidest ideas were successful" (opening off-grid discussion).
Biography and decision evidence
- The account supplies firsthand evidence of overextension and depression but is retrospective; no medical inference is made beyond Feld's own disclosure.
Philosophy signals
- Tags: cycles, self-management, portfolio triage, relationships, resilience.
Contradictions, counterevidence, and access limits
- Personal coping practices do not establish firm-level risk management or performance causality.
Open questions
- Did Mobius or Foundry formally change reserve, pacing, or governance policy after the crisis?
w Every Generation Learns the Same Lessons
- URL: https://feld.com/archives/2018/08/every-generation-learns-the-same-lessons/ | Published: 2018-08 | Format: signed retrospective | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: Interliant narrative and closing lesson
Takeaways
- retrospective witness; moderate: Feld treats Interliant's expansion, capital consumption, and bankruptcy as a recurring cycle lesson.
- The candid failure account should be paired with SEC and bankruptcy records rather than accepted as complete.
Quotes
- "Every generation learns the same lessons" (title and closing frame).
Biography and decision evidence
- Interliant provides a named, severe downside case in Feld's pre-Foundry record.
Philosophy signals
- Tags: cycles, capital discipline, failure, governance, hindsight.
Contradictions, counterevidence, and access limits
- The bankruptcy committee made allegations involving Feld-linked parties; the accessible ruling is procedural and does not adjudicate personal liability.
Open questions
- What contemporaneous board minutes, financing alternatives, and conflict controls existed?
w Status of Our FG Angels Experiment
- URL: https://foundry.vc/blog/2016/01/status-of-our-fg-angels-experiment/ | Published: 2016-01 | Format: firm post | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: paragraphs 1–3 / web lines 7–10
Takeaways
- Foundry stopped new FG Angels investments after two years because maintaining the AngelList pace required too much effort.
- documented behavior; strong: the decision demonstrates explicit stopping when operating cost violated the model, while preserving the learning and ecosystem value.
- This failure boundary argues against treating every network experiment as scalable or economically accretive.
Quotes
- "the effort required to maintain our investment pace ... is too great" (opening paragraph; elision added).
Biography and decision evidence
- The experiment separated lighter-touch angel syndication from core Foundry board-led investing.
Philosophy signals
- Tags: experiments, stop rules, seed, capacity, AngelList.
Contradictions, counterevidence, and access limits
- The post gives no same-basis performance, company count, cost, or return figures; the economic verdict is not public.
Open questions
- Did stopped pacing improve core portfolio attention, and how did FG Angels perform?
w The Final Foundry Fund
- URL: https://foundry.vc/blog/2024/01/the-final-foundry-fund/ | Published: 2024-01 | Format: firm announcement | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: opening announcement and portfolio-work paragraphs
Takeaways
- investor-stated; strong: Foundry said its 2022 fund would be its last and rejected a legacy/generational-firm transition.
- The firm reported more than 200 direct companies and nearly 50 venture-fund investments, with at least a decade of continuing portfolio work.
Quotes
- "Foundry 2022 will be our last fund" (opening passage).
Biography and decision evidence
- The decision closes the capital-raising arc without ending fiduciary and board work.
Philosophy signals
- Tags: succession, lifecycle, final fund, stewardship, denominator.
Contradictions, counterevidence, and access limits
- Firm-level counts mix decades and do not attribute deals to Feld; the current portfolio page is not a complete lifetime ledger.
Open questions
- How will decision rights and key-person coverage work through the final portfolio decade?
w Your First Big Success — What's Next?
- URL: https://feld.com/archives/2014/06/first-big-success-whats-next/ | Published: 2014-06 | Format: signed retrospective | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: chronological body paragraphs
Takeaways
- retrospective witness; moderate: Feld links early exits, bubble losses, Mobius's difficult 2004 period, Techstars/Foundry creation, and a 2013 depression episode.
- Success increased optionality but did not remove organizational or health risk.
Quotes
- "the first big success" (framing passage).
Biography and decision evidence
- The post is a high-value first-person chronology with explicit downside, not a deal ledger.
Philosophy signals
- Tags: success, failure, reinvention, mental health, chronology.
Contradictions, counterevidence, and access limits
- Dates and causal interpretation are retrospective and should be controlled by filings and contemporaneous posts.
Open questions
- Which specific Mobius portfolio and governance decisions changed after 2004?
w Do More Faster — Founder Support as Practice
- URL: https://feld.com/archives/2010/10/do-more-faster/ | Published: 2010-10 | Format: signed book announcement/reflection | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: book-purpose and Techstars passages
Takeaways
- investor-stated; moderate: Feld and David Cohen translate Techstars mentor experience into short operating lessons intended for founders.
- The writing reflects a teaching flywheel: mentorship produces reusable doctrine and a larger network.
Quotes
- "Do More Faster" (book title and repeated imperative).
Biography and decision evidence
- The book belongs to a coauthored Techstars corpus; attribution cannot be collapsed into Feld-only doctrine.
Philosophy signals
- Tags: execution, mentorship, Techstars, teaching, coauthorship.
Contradictions, counterevidence, and access limits
- A book announcement is not the full book and cannot establish which lessons Feld originated.
Open questions
- Which specific rules survived systematic comparison with ordinary and failed cohorts?
w Foundry Group Next
- URL: https://feld.com/archives/2015/12/foundry-group-next/ | Published: 2015-12 | Format: signed fund essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: Next rationale, UTIMCO history, and succession passages
Takeaways
- investor-stated; strong: Feld links Next's design to long LP relationships and explicitly says Foundry was not building a generational legacy firm.
- The essay distinguishes growth/partner-fund opportunity from a simple larger early-stage fund.
Quotes
- "not a legacy firm" (succession passage).
Biography and decision evidence
- It supplies the early public rationale later completed by the 2024 final-fund announcement.
Philosophy signals
- Tags: LPs, succession, fund design, growth, partner funds.
Contradictions, counterevidence, and access limits
- LP gratitude and design intent do not establish realized performance or conflict-free allocation.
Open questions
- Did Next improve direct-company sourcing and net LP outcomes after added fees/layers?
w Our Newest Fund — Foundry Group Next
- URL: https://foundry.vc/blog/2016/09/our-newest-fund-foundry-group-next/ | Published: 2016-09 | Format: firm fund announcement | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: announcement body
Takeaways
- investor-stated; strong: The $500 million Next fund combined direct growth investments with commitments to venture funds in the Foundry network.
- The vehicle broadened beneficiaries, duration, manager-selection risk, and attribution beyond direct company investing.
Quotes
- "invest in venture funds and growth-stage companies" (mandate passage).
Biography and decision evidence
- Next formalized the partner-fund network after years of informal fund relationships.
Philosophy signals
- Tags: partner funds, growth, network, vehicle, diversification.
Contradictions, counterevidence, and access limits
- Company and fund investments cannot share one return denominator; the announcement supplies no allocation or performance detail.
Open questions
- How much capital and partner time went to each sleeve?
w Our New Fund — Foundry Group Next 2018
- URL: https://feld.com/archives/2018/08/our-new-fund-foundry-group-next-2018/ | Published: 2018-08-01 | Format: firm announcement signed by seven partners | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: web lines 15–31
Takeaways
- Foundry combined early, growth, and partner-fund strategies in a $750 million vehicle after four $225 million early funds, a $225 million Select fund, and a $500 million Next fund.
- firm-stated; strong for policy: seven equal partners, US/Canada, themes, syndication agnosticism, full-lifecycle rounds, significant ownership “often over 30%,” and net cash-on-cash focus.
- Network and partner-fund access became a formal strategy rather than merely an informal benefit.
Quotes
- "one node on a mesh network" (web line 25).
Biography and decision evidence
- Strategy expanded materially from the earlier “never grow” and sub-$3 million-raised filters; the essay itself calls strategy unchanged, a tension the synthesis preserves.
Philosophy signals
- Tags: vehicle, ownership, fund size, partner funds, network, lifecycle.
Contradictions, counterevidence, and access limits
- Aggregate fund sizes are disclosed; fees, carry, reserves, net DPI/TVPI, individual economics, and deal-level cash flows are not.
Open questions
- Did partner-fund and growth exposure improve net cash-on-cash returns relative to early-stage funds?
w Foundry Group Select
- URL: https://foundry.vc/blog/2013/10/foundry-group-announces-its-newest-fund-foundry-group-select/ | Published: 2013-10 | Format: firm fund announcement | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: announcement body
Takeaways
- investor-stated; strong: The $225 million Select vehicle was reserved for later rounds in existing winners, with up to $25 million per company.
- It changed the original early-stage vehicle boundary without claiming a new company-sourcing strategy.
Quotes
- "only invest in existing Foundry Group portfolio companies" (mandate passage).
Biography and decision evidence
- Select marks the firm's shift toward supporting winners deeper into their lifecycle.
Philosophy signals
- Tags: follow-on, concentration, reserves, lifecycle, vehicle.
Contradictions, counterevidence, and access limits
- A winner-only mandate can encode selection quality or merely mark winners late; no audited Select cash flows were located.
Open questions
- Which partner approved allocations and what opportunity-cost hurdle governed each check?
w What Does Foundry Group Invest In?
- URL: https://foundry.vc/blog/2008/11/what-does-foundry-group-invest-in/ | Published: 2008-11 | Format: firm essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: named theme sections and closing paragraphs
Takeaways
- investor-stated; strong: Foundry framed themes as durable protocols, distribution shifts, and human-computer interaction rather than a prediction of one product category.
- Themes were intended to focus search while permitting unexpected companies inside a thesis.
Quotes
- "themes are much broader than sectors" (theme-definition passage).
Biography and decision evidence
- The post records the original firm's category map before many later exits.
Philosophy signals
- Tags: themes, protocols, distribution, HCI, search, prepared mind.
Contradictions, counterevidence, and access limits
- Retrospective fit is easy; the post does not publish every company rejected under each theme.
Open questions
- How often did themes produce a lead rather than rationalize one?
w Definition of Give First
- URL: https://feld.com/archives/2020/10/definition-of-givefirst/ | Published: 2020-10-13 | Format: signed essay/book excerpt | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: paragraphs beginning "GiveFirst first appeared" and "The definition"
Takeaways
- investor-stated; strong: Give First means contributing without predefining the transaction while still expecting an unspecified future return; Feld explicitly says it is not altruism.
- Feld dates “Give Before You Get” to Startup Communities (2012), the hashtag to Techstars around 2014, and a refined definition to 2020.
- Network reciprocity is therefore long-horizon and non-bilateral, not free labor without boundaries.
Quotes
- "without defining the transactional parameters" (definition block; five words).
Biography and decision evidence
- The concept connects community work, Techstars, mentorship, and Foundry's network strategy, but investment alpha remains an untested causal inference.
Philosophy signals
- Tags: networks, mentorship, sourcing, reciprocity, community.
Contradictions, counterevidence, and access limits
- Feld acknowledges positives and negatives but this short definition does not specify exploitation, selection, or capacity safeguards; the 2025 book was accessed only through official descriptions/TOC.
Open questions
- What measurable sourcing or company outcomes differ after controlling for access and brand?
w Roomba — July's Toy of the Month
- URL: https://feld.com/archives/2005/07/roomba-julys-toy-of-the-month/ | Published: 2005-07 | Format: signed product essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: product-use and pass-reflection paragraphs
Takeaways
- retrospective witness; moderate: Feld discloses that Mobius passed on iRobot because it did not fit the firm's software framing, even though he became an enthusiastic product user.
- The miss tests whether category discipline prevents worse drift or rejects valuable hardware/software systems.
Quotes
- "we passed" (investment-reflection passage).
Biography and decision evidence
- This is a named anti-portfolio case close enough to the decision era to constrain later theme claims.
Philosophy signals
- Tags: anti-portfolio, product use, category error, hardware, thesis.
Contradictions, counterevidence, and access limits
- No proposed round terms, ownership, fund capacity, or alternative-use cost is public.
Open questions
- Was category fit the decisive vote or a post hoc shorthand for price, access, or team concerns?
w Make Your Own Decisions
- URL: https://feld.com/archives/2012/06/make-your-own-decisions/ | Published: 2012-06-06 | Format: signed essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: paragraphs / web lines 15–30
Takeaways
- investor-stated; strong: Foundry made investment and follow-on decisions without requiring co-investor validation.
- All four partners independently interacted with a serious candidate; one declining qualitative view ended the process.
- Feld estimates the firm invested in only 5%–10% of companies reaching active evaluation and acknowledges passes later judged mistaken, including Fitbit and SEOmoz.
Quotes
- "a single qualitative negative trend causes us to pass" (paragraph beginning "The reason" / web line 22).
Biography and decision evidence
- The essay documents four-partner decision rights and a unanimity-like negative veto, but not formal IC votes or individual sponsorship.
Philosophy signals
- Tags: decision rights, social proof, follow-ons, qualitative diligence, mistakes.
Contradictions, counterevidence, and access limits
- Independent judgment reduces herding but can magnify a single partner's false negative; no full pass log is public.
Open questions
- What objective evidence, if any, could reverse a negative partner trend?
w The Techstars Mentor Manifesto
- URL: https://feld.com/archives/2011/08/the-techstars-mentor-manifesto/ | Published: 2011-08-29 | Format: signed essay reproducing David Cohen's manifesto | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: 18-item bullet list
Takeaways
- documented attribution; strong: Feld says Jon Bradford prompted the idea and David Cohen published the manifesto; Feld amplified and later deconstructed it.
- The rules combine Socratic inquiry, candor, confidentiality, explicit commitment, epistemic humility, founder autonomy, actionable advice, and empathy.
- Mentorship is positioned as a system, not a heroic one-to-one guru relationship.
Quotes
- "Guide, don’t control" (item 13 of the reproduced manifesto).
Biography and decision evidence
- The record corrects lone-author mythology: Feld is an important codifier, not the sole originator.
Philosophy signals
- Tags: mentorship, governance, founder agency, networks, humility.
Contradictions, counterevidence, and access limits
- Manifesto compliance is not measured across Techstars cohorts or Foundry boards; it is normative evidence.
Open questions
- Which board conflicts show the limits of “guide, don't control”?
w Network-Driven Investing
- URL: https://foundry.vc/blog/2022/06/network-driven-investing/ | Published: 2022-06 | Format: firm strategy essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: named network sections and fund-history paragraph
Takeaways
- investor-stated; strong: Foundry described partner funds as a structured source of information, referrals, collaboration, and company access rather than a passive fund-of-funds sleeve.
- The post reports the first four funds as $232 million each, creating a scope/rounding conflict with repeated $225 million shorthand.
Quotes
- "network-driven investing" (strategy-definition passage).
Biography and decision evidence
- The essay documents evolution from the founding thematic model to a network-centered system.
Philosophy signals
- Tags: network, partner funds, sourcing, themes, fund construction.
Contradictions, counterevidence, and access limits
- Network advantage is firm self-report; no channel-adjusted sourcing or outcome comparison is public.
Open questions
- Which sourced deals would not have entered the funnel without partner funds?
w When VCs Don't Bullshit You
- URL: https://feld.com/archives/2014/07/vcs-dont-bullshit/ | Published: 2014-07-31 | Format: signed essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: web lines 14–33
Takeaways
- Feld openly calls Mobius's 1999 fund a disaster and its 2000 fund rocky, then reconstructs Foundry's difficult 2007 fundraising.
- investor-stated; strong: candor is framed as a repeated-game operating rule with founders, partners, co-investors, and LPs.
- Fred Wilson, Scott Maxwell, and Jack Tankersley receive explicit fundraising credit; more than one-third of Foundry 2007 capital reportedly came from LPs shared with USV.
Quotes
- "there is no value in bullshitting anyone" (web line 15).
Biography and decision evidence
- Feld reports 90 LP meetings in three months, 20 immediate rejections, and an oversubscribed close by September/November 2007.
Philosophy signals
- Tags: trust, fundraising, failure, networks, LPs, attribution.
Contradictions, counterevidence, and access limits
- This is retrospective self-report; LP commitments and fund performance are not independently disclosed here.
Open questions
- What were Mobius II/III net cash-on-cash results and loss attribution by deal?
w Product Focused Venture Capital
- URL: https://feld.com/archives/2006/08/product-focused-venture-capital/ | Published: 2006-08-07 | Format: signed essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: heading and paragraphs beginning "I love to invest," "An example," and "When I think back"
Takeaways
- Feld describes product use as diligence: his blog became a laboratory for testing FeedBurner and NewsGator before and after investment.
- investor-stated; strong: founders' response to criticism—not obedience—was part of his FeedBurner assessment.
- He limits the claim: he is not the broad-market user, so founder and market evidence still matter.
Quotes
- "my most successful investments were ones that I personally related to" (closing paragraph).
Biography and decision evidence
- Feld says he used FeedBurner from May 2004 before investing; the essay is contemporaneous with his Mobius period.
Philosophy signals
- Tags: product, diligence, founder response, feedback loops, picking.
Contradictions, counterevidence, and access limits
- Product use can overfit to an unusually technical investor; no portfolio-wide matched comparison tests whether this method improved returns.
Open questions
- Which deals were rejected after product use, and how did they perform?
w How I Think About Seed Investing as a VC
- URL: https://feld.com/archives/2010/08/how-i-think-about-seed-investing-as-a-vc/ | Published: 2010-08-02 | Format: signed essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: paragraphs 8–19 / web lines 20–31
Takeaways
- investor-stated; strong: Foundry treated seed as a committed investment, not an option on the next round; all four partners engaged and the firm reserved willingness for follow-on capital.
- Entry checks ranged from $250,000 to $10 million in 2010; the strategy was thematic and syndication-agnostic.
- Feld names seven seed examples, creating a prospectively dated test set rather than an outcome-selected list.
Quotes
- "our seed investments are not ‘options on the next round’" (paragraph 11 / web line 23).
Biography and decision evidence
- Feld distinguishes two personal angel periods, 1994–1996 and 2006–2007, from Mobius, Foundry, and Techstars exposure.
Philosophy signals
- Tags: seed, reserves, themes, ownership, syndication, team.
Contradictions, counterevidence, and access limits
- FG Angels later used a lighter-touch syndicate model and stopped new investments in 2016; that experiment is a boundary, not proof the core strategy failed.
Open questions
- Actual reserve ratios and outcomes for the seven named seeds are not public on a same-basis basis.
w SEOmoz, TAGFEE, and Me
- URL: https://feld.com/archives/2012/05/seomoz-tagfee-and-me/ | Published: 2012-05 | Format: signed company essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: investment, board, and culture passages
Takeaways
- documented behavior; moderate: Feld publicly tied Foundry's $18 million SEOmoz investment and his board service to Rand Fishkin's transparent culture and TAGFEE values.
- The case links founder-culture selection to an identifiable ordinary/disappointing-outcome laboratory.
Quotes
- "TAGFEE" (culture-framework passage).
Biography and decision evidence
- The post records Feld as a named board participant, unlike many firm-only portfolio entries.
Philosophy signals
- Tags: culture, transparency, board, follow-on, ordinary outcome.
Contradictions, counterevidence, and access limits
- A disclosed investment amount is company financing, not cost basis or return; later outcome economics remain unreconstructed.
Open questions
- What changed between the initial thesis, later financings, leadership transition, and eventual acquisition?
w How a Small Company Can Make a Big Company Successful
- URL: https://feld.com/archives/2015/01/small-company-make-big-company-successful-2/ | Published: 2015-01 | Format: signed operating essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: numbered partnership lessons
Takeaways
- investor-stated; strong: Small-company/big-company partnerships need named owners, strategic alignment, clear economics, executive sponsorship, and realistic process expectations.
- The rule converts portfolio scars into diligence on distribution dependency.
Quotes
- "small company" and "big company" (recurring numbered framework).
Biography and decision evidence
- The essay exposes Feld's operating-support focus beyond financing.
Philosophy signals
- Tags: distribution, partnerships, enterprise, governance, dependency.
Contradictions, counterevidence, and access limits
- The post abstracts across cases and does not publish a denominator of failed partnerships.
Open questions
- Which contract, renewal, and concentration thresholds did Foundry use?
w Why Do We Care About Techstars?
- URL: https://feld.com/archives/2009/04/why-do-we-care-about-techstars/ | Published: 2009-04 | Format: signed ecosystem essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: rationale and community paragraphs
Takeaways
- investor-stated; strong: Feld describes Techstars as a community and mentorship system rather than a conventional fund-owned sourcing funnel.
- The system can create genuine public goods while also increasing access to founders and information.
Quotes
- "we care deeply about the entrepreneurial community" (rationale passage).
Biography and decision evidence
- The post records Feld's early public explanation after Techstars' 2006 formation and 2007 class.
Philosophy signals
- Tags: Techstars, mentorship, community, sourcing, conflict.
Contradictions, counterevidence, and access limits
- Altruistic and commercial benefits coexist; the public record does not quantify allocation or referral advantage.
Open questions
- How were Techstars, personal, Mobius, and Foundry opportunities allocated?
w Term Sheet Series and Venture Deals
- URL: https://feld.com/archives/2005/08/term-sheet-series-wrap-up/ | Published: 2005-08-23 | Format: 20-post series index | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: numbered linked terms under the wrap-up list
- Companion URL: https://feld.com/archives/2011/07/venture-deals-be-smarter-than-your-lawyer-and-venture-capitalist/ | Published: 2011-07-18 | Format: signed book-origin essay | Reliability: A | Access: full
Takeaways
- Feld and Jason Mendelson separated term-sheet economics from control and made the mechanics legible to founders.
- investor-stated; strong: the 2011 book grew from the 2005 series, but the posts comprised less than 20% of the rewritten book.
- The project is best understood as information-asymmetry reduction; it does not prove Foundry offered founder-favorable terms in every transaction.
Quotes
- "a balanced and pragmatic approach" (2005 wrap-up, opening paragraph).
Biography and decision evidence
- Coauthorship is central: Mendelson supplied legal expertise and Feld investing experience; neither should receive sole credit.
Philosophy signals
- Tags: terms, control, transparency, founder education, bargaining.
Contradictions, counterevidence, and access limits
- Full fourth-edition book text was not legitimately available during this run; analysis is bounded to the accessible series and authors' edition notes.
Open questions
- Compare actual Foundry term sheets with the published normative framework; private documents are unavailable.
w Who Are We?
- URL: https://foundry.vc/blog/2008/04/who-are-we/ | Published: 2008-04 | Format: firm essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: body paragraphs under title
Takeaways
- investor-stated; strong: Foundry described a small equal-partner firm designed to make every investment collectively and remain directly engaged.
- It positioned Boulder and a national network as deliberate rather than as a fallback from Silicon Valley.
Quotes
- "we are a small group of experienced venture capitalists" (opening paragraph).
Biography and decision evidence
- The post fixes Foundry's original institutional design close to formation.
Philosophy signals
- Tags: partnership, geography, focus, collective decisions, founder service.
Contradictions, counterevidence, and access limits
- The initial four-partner design later became six equal partners; a design claim is not proof of equal work on every deal.
Open questions
- What were the actual voting, allocation, reserve, and succession rules?
w Why We Pass Quickly on Things
- URL: https://feld.com/archives/2015/04/why-we-pass-quickly-on-things/ | Published: 2015-04-10 | Format: signed essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: headings "Our Strategy" and pass explanation; no stable paragraph numbers
Takeaways
- investor-stated; moderate: strategy narrows the funnel before deep diligence: a $225 million fund, roughly 30 investments, four partners, and no associates implied about ten new companies annually.
- Theme, geography, stage, and capital-raised filters enabled fast rejection; fit was different from company quality.
- The method protects partner time but makes theme and boundary errors especially consequential.
Quotes
- "our goal is not to invest in every great company" (opening strategy discussion).
Biography and decision evidence
- The 2015 essay captures the original fixed-team, fixed-fund model before Foundry expanded its strategy and equal-partner count.
Philosophy signals
- Tags: portfolio, focus, pass discipline, time allocation, fund size.
Contradictions, counterevidence, and access limits
- Foundry later raised a $750 million integrated fund and seven equal partners; “never grow” was revised rather than timeless.
Open questions
- The public record does not disclose false-negative rates by filter.