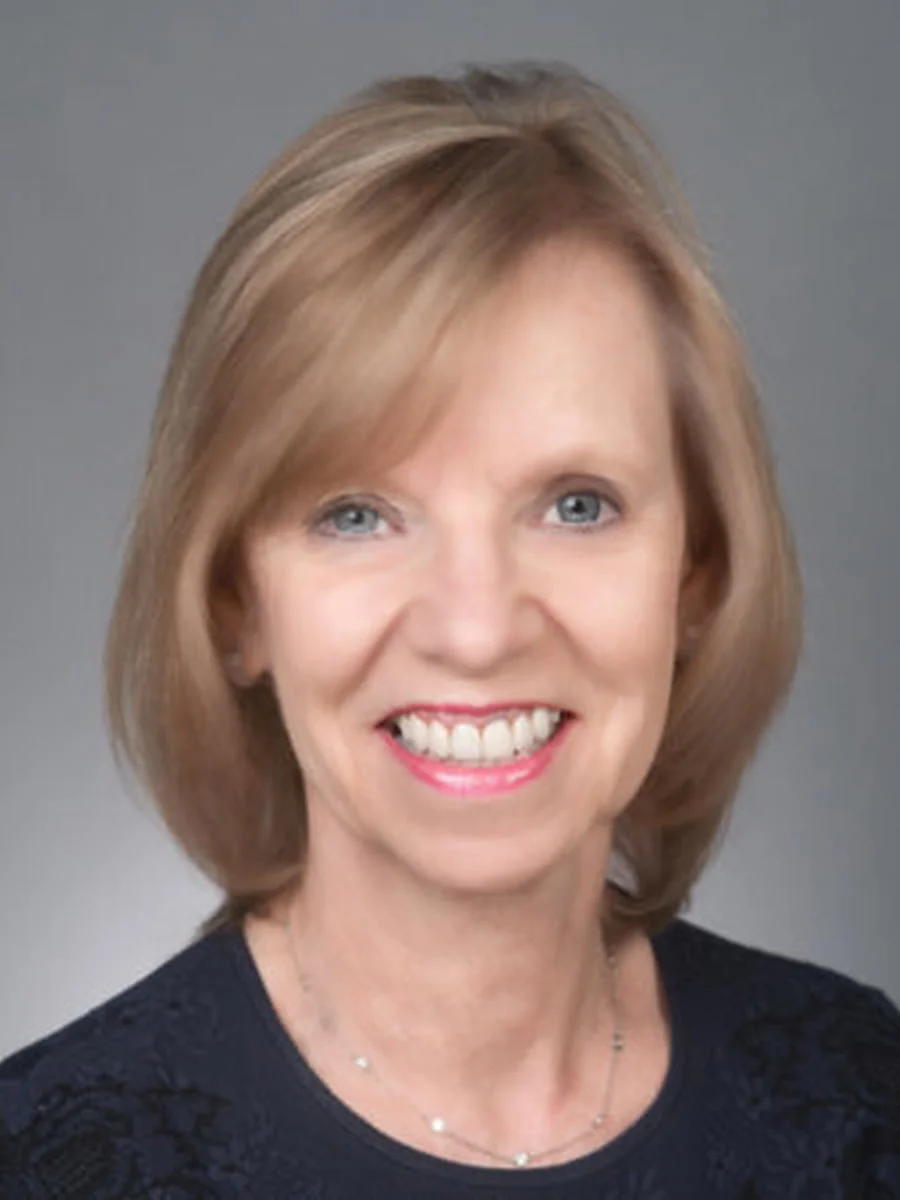
Ann Winblad
Co-founded Hummer Winblad, a pioneering software-exclusive US venture firm; operator-turned-investor and board builder.
From Minnesota mathematics to software operations, 1950–1984
Ann Winblad was born in Red Wing, Minnesota, in 1950 and grew up in Farmington as the eldest of six children. At the College of St. Catherine she combined mathematics and business and used the Twin Cities consortium for computing courses, graduating in 1973; the record does not support the common shorthand that her degree was in computer science. Berkeley oral history, printed pp. 1, 4–6 Because the Bancroft manuscript’s printed p. ii requires permission for publication quotation, this biography paraphrases it. These facts are retrospective witness · strong for her recollection and contemporaneous record · insufficient public record for diploma-level verification.
She joined the Federal Reserve Bank of Minneapolis as a systems programmer, left after roughly thirteen months, and completed a master’s degree at the University of St. Thomas. Berkeley oral history, printed pp. 6–8 · St. Thomas profile The work placed her inside business systems before personal-computer software had an established venture category. Linking that experience to her later preference for software specialists who can evaluate products and buyers is researcher inference · moderate: the chronology fits, and Winblad later made operating competence explicit, but no contemporary memo states the causal link. WilmerHale interview, printed p. 16
In 1975 or 1976, Winblad and three former Federal Reserve colleagues founded Open Systems to build accounting software for emerging microcomputer systems. Her oral history describes responding to an accounting-system request, working with CADO, and meeting Sequoia-associated Don Valentine. Berkeley oral history, printed pp. 7–11 The exact start year remains unresolved. So does the sale: public accounts place UCCEL’s acquisition between 1982 and 1984 and report consideration around or above $15 million, but the oral history conflicts internally and no acquisition filing was found. Berkeley oral history, printed pp. 11–13 · St. Thomas profile The operating achievement is retrospective witness · moderate; the exact date, consideration, ownership, and Winblad’s personal proceeds are insufficient public record.
Open Systems is important less as an origin myth than as a boundary on later inference. It documents product building, selling into business workflows, and managing a software company; it does not prove that those experiences later generated superior venture returns. The supported causal proposition is narrower: operating credibility plausibly improved access to software founders and the ability to ask product, customer, and organizational questions. Researcher inference · moderate.
Becoming a technical author and venture-firm founder, 1985–1989
After moving to California, Winblad consulted for Price Waterhouse and worked on the book later published as Object-Oriented Software with Samuel D. Edwards and David R. King. Berkeley oral history, printed pp. 13–17 · KIT catalog The catalog confirms a 1990 Addison-Wesley volume of xviii + 291 pages; no legitimate full text or chapter-level attribution was retrieved. It establishes technical authorship, not which ideas belonged to Winblad or influenced a specific investment. Contemporaneous record · strong for metadata; researcher inference · insufficient public record for intellectual contribution and investment causation.
Winblad and former NBA player John Hummer began raising a software-focused venture fund. Later accounts describe 113, 130, 133, or 150 fundraising meetings or rejections, depending on venue and wording. Stanford introduction page, inline transcript · WilmerHale, printed p. 16 · Berkeley, printed pp. 17–19 · Charlie Rose, 09:36–10:00 These are investor-stated · provisional; no pitch log survives publicly. Her accounts consistently credit Hummer and endorsers Bill Edwards, Pitch Johnson, and Don Valentine, which makes the formation story collective rather than a solo breakthrough. Berkeley, printed pp. 17–19
The early-LP identity also conflicts: the oral history names St. Paul Companies, while the 2019 essay names State Farm Insurance. Berkeley, printed pp. 18–19 · Winblad 2019, institutional-backing paragraph Similar names are not interchangeable; the subscription record is missing.
Hummer Winblad is widely reported and firm-claimed as the first venture firm or fund focused exclusively on software. The exclusive mandate is well documented; historical priority is investor-stated · provisional because no exhaustive census of pre-1989 firms was produced. WilmerHale, printed pp. 16–17 The safer historical description is an early prominent software-specialist partnership with a woman cofounder. It is not accurate to call Winblad the earliest woman to found a major US venture firm: Annette Campbell-White founded MedVenture in 1986, while Patricia Cloherty and Mary Jane Elmore predate Winblad in venture leadership. Campbell-White archive · Cloherty oral history, career chronology · Elmore history Documented behavior · strong for the earlier chronology.
Fund I: specialization gains evidence—and ambiguity, 1989–1999
Winblad dates Fund I’s close to September 1989 and the first investment, T/Maker, to November 1. She reports a $300,000 Series A lead check and joining the board; St. Thomas reports $750,000, perhaps a different tranche or total, but the record does not resolve it. Winblad 2019, T/Maker paragraphs · St. Thomas profile Later outcome accounts conflict at reported 3x in 2019 and 5x in 2004. Winblad 2019 · Stanford introduction page, inline transcript The date/board link is investor-stated · strong; check and return magnitude are provisional without cash flows.
Fund I backed sixteen companies. Its economics appear in three incompatible reported forms: $27 million investable returning $252 million in 2019; a $35 million fund returning about $250 million and 50% annually in 1996; and a $35 million fund returning over 10x in 2005. Winblad 2019, Fund I paragraphs · Wired 1996, Fund discussion · WilmerHale, printed p. 17 Commitment, investable capital, fees, recycling, timing, gross/net basis, and methodology remain unreconciled. The 2019 essay reports six IPOs; the oral history says half of sixteen became public. Berkeley, printed pp. 21–23 Each is retrospective witness · moderate; neither supports a personal Winblad return.
The company record prevents heroic attribution. Hyperion/Arbor has strong Winblad director evidence; the official page’s 1991 IPO date is contradicted by SEC records pointing to 1995. Hyperion decision lab · Wired 1996, Arbor passage · Arbor filing, registration history. Powersoft and Wind River are firm/John Hummer cases, while Scopus remains partner-unassigned. Fund I attribution labs Later acquisition values—about $3.3 billion for Hyperion, $884 million for Wind River, and $381.4 million for Scopus—are company outcomes, not HWVP proceeds. Oracle exhibit · Intel 10-Q · Siebel completion 8-K
Slate supplies the counterexample. A 1996 profile reported that HWVP lost about $1.2 million; later Winblad accounts called the pen-computing product thirteen or twenty-five years early. Wired 1996, Slate paragraphs · Stanford, “Are Technologies Ahead of Their Time?” · Berkeley, printed pp. 21–23 The loss is contemporaneous record · moderate and the timing explanation retrospective witness · moderate. No memo shows whether customer/platform readiness was tested ex ante or whether the failure changed process.
The most defensible Fund I conclusion is not that specialization mechanically caused returns. It is that a narrow mandate, operator network, and company-building posture coincided with several material software outcomes and at least one visible timing failure. Researcher inference · moderate. The missing sixteen-company cash-flow and attribution ledger prevents a stronger causal claim.
Scaling the institution and confronting the dot-com boundary, 1997–2006
By 2000 a St. Thomas profile reported roughly eighty firm investments; Stanford reported more than ninety in 2004, Berkeley’s 2012 preface said 100-plus, and Winblad claimed 150-plus in 2019. The live directory now contains 98 companies. St. Thomas profile · Stanford introduction page, inline transcript · Berkeley oral history, prefatory biography · Winblad 2019 · official directory These are definition-sensitive firm counts, not a personal denominator. The reconstructed current ledger covers 98/98 displayed companies but only nine are sufficiently reconstructed; lifetime coverage is not computable. Investments denominator
Napster tested the limit of treating adoption as market proof. Hummer Winblad invested about $13 million in May 2000 while copyright suits were pending, entered a common-interest defense agreement, and installed partner Hank Barry as interim CEO. 2005 order, Background pp. 3–4 · 2006 sanctions order, Background pp. 3–5 Napster ceased operations in July 2001. The 2006 court found a preservation duty and granted preclusion, adverse inference, and attorneys’ fees while denying default; the order discusses Winblad’s June 3 email. 2006 order, Duty to Preserve, Sanctions, Conclusion A conditional Universal/EMI settlement followed on undisclosed terms. Los Angeles Times, 2006-12-13
The legal boundary is exact: allegations of investor control, Barry’s operating role, Winblad’s email, sanctions against Hummer entities, and copyright merits are distinct. The reviewed record does not establish a personal copyright-infringement judgment or settlement amount against Winblad. Contemporaneous record · strong for procedure; personal liability and economics are insufficient public record. Nor did later public materials disclose a Napster-driven change in legal diligence, document retention, or IC process. Treating Napster as proof that Winblad “learned” a specific rule would be researcher inference · insufficient public record.
Liquid Audio adds a narrower governance warning. Its 2003 preliminary proxy describes 2001 fiduciary-duty complaints, Winblad as a former director, and dismissal of those actions with prejudice under a January 2, 2003 settlement agreement. The same filing separately describes a patent suit settled through a $150,000 payment to Network Commerce; that amount was not the shareholder-litigation settlement. Liquid Audio PRE 14A, Legal Proceedings and board disclosures The filing proves the disclosed allegations and procedural routes, not their truth, a personal payment, or personal liability. Contemporaneous record · strong for issuer disclosure; investment thesis, response, and economics are missing.
Pets.com is an ordinary failure that corrects selection bias and personal misattribution. HWVP III/Technology entities held 13.5%, John Hummer was the documented director, operations ceased in November 2000, delisting followed, and the initial liquidation distribution was $0.09 per share. Pets.com 10-K, business/liquidation/principal holders This is a firm/John case, not a Winblad personal miss. It also shows that a “software” institution participated at the capital-intensive internet-commerce perimeter; whether that reflected a changed thesis is researcher inference · provisional.
From articulated process to cloud-era governance, 2004–2014
The 2004 Stanford session is the earliest accessible extended, relatively contemporaneous account of Winblad’s venture process. Across thirteen clips from one classroom session, she described software innovation, early-stage investing, customer testing, technology timing, standards, outsourcing, and repeated testing of core assumptions. Stanford session entry The session should be treated as one witness, not thirteen independent sources.
Her accessible operating system begins with markets and stage-calibrated proof. EIX later records the compact rule that markets come first; Full Ratchet explains why very early companies such as Hyperion and NuoDB could lack ordinary traction if founders could articulate a large market, technical capacity, and customer need. EIX, 07:01–07:27 and 23:29–26:18 · Full Ratchet, Hyperion/NuoDB discussion That is investor-stated · strong as a framework and retrospective witness · moderate as applied deal evidence.
Customer evidence is the bridge between possibility and budget. In “Customers Are Key,” she described exposing Voltage to roughly twenty CIO organizations and asking whether buyers would allocate budget; WilmerHale gives the 2003 HWVP/Morgenthaler setting. Stanford “Customers Are Key,” inline transcript · WilmerHale, printed pp. 17–18 The firm page names Winblad and says HP acquired Voltage in 2015. Voltage decision lab The diligence account is retrospective witness · moderate; outcome and board attribution do not prove its efficacy.
MuleSoft provides the strongest later board/vehicle anchor. Winblad served as a director from September 2006. HWVP V and VI held 17,847,745 shares, 15.7% pre-offering in the reviewed S-1/A, while later records show shared managing-member power among Hummer, Winblad, and Mitchell Kertzman and separate sole shares for Winblad. MuleSoft S-1/A, directors and principal stockholders · Schedule 13G, Items 5–8 Winblad later narrated five people in four countries anticipating APIs, service buses, devices, and cloud applications. OnlineEducation, MuleSoft paragraphs The governance is documented behavior · strong; the thesis is retrospective witness · moderate; solo sourcing and personal return are unproved.
Other filings show why reporting-person records cannot be read as deal credit. Omniture’s S-1 names Mark Gorenberg as board nominee and documents HWVP V’s 2004–2005 financing; Winblad’s 2007 Form 4 records later in-kind/carry distribution. Omniture S-1, Certain Relationships · Winblad Form 4 The Knot’s Form 4, by contrast, identifies Winblad as director/10% owner and managing member while disclaiming beneficial ownership beyond pecuniary interest. The Knot Form 4 Contemporaneous record · strong for mechanics and role boundaries.
Later-fund dispersion and succession, 1997–present
The available fund record refuses a single victory curve. For HWVP III, UC Regents reports one LP’s 1997-vintage experience: $10 million contributed, $10.393 million distributed, no residual value, 1.04x TVPI, and 1.0% net IRR as of 2020-06-30. UC Regents, PDF p. 1 row 48 This is contemporaneous record · strong for that LP, not the whole fund or Winblad personally.
Fund V was reported around $420–424 million; an SDCERS/StepStone secondary interest bought at a discount later produced 2.9x TVM and 47.3% IRR for that secondary buyer, with MuleSoft and Birst named as assets. StepStone report, printed p. 21 Those economics cannot be generalized to original LPs. StrictlyVC reported a smaller roughly $201 million Fund VI, uneven later returns, and Hummer/Winblad moving from managing directors to founding partners by 2015. StrictlyVC 2015 Contemporaneous record · moderate for reporting; causation is provisional.
A 2026-03-26 Form ADV still lists the legacy operating company and only Fund VI as its private fund; Schedule A names Hummer, Winblad, and Kertzman as managing members/control persons. Form ADV, Item 7.B.1 and Schedule A That legacy legal/control record is not evidence that the founders managed successor funds. Fund VII’s Form D names Leckie, Kertzman, and Kishi and ultimately reports $80.56 million sold to 54 investors; Fund VIII names Leckie/Kishi and reports $66.725 million sold to 90 investors. Winblad and Hummer are absent from both related-person rosters. Fund VII original · Fund VII final amendment · Fund VIII amendment The Aspenwood website places Winblad in an emeritus/adviser role. Aspenwood team
These records describe different dimensions—legacy control, active-fund related persons, and public title. They do not establish the founders’ residual economics. The evidence supports a transfer of active successor-fund authority, not an assumption that every legal or economic tie ended. Contemporaneous record · strong for rosters; researcher inference · moderate for the bounded succession conclusion.
Public reasoning, forecasts, and intellectual evolution
The earliest accessible technical excerpt, from 1992, treats class libraries, tools, legacy systems, and organizational migration as determinants of enterprise architecture adoption. CHM compilation, PDF p. 66 The 2005 interview expands from architecture to organization: product marketing links customer, sales, and engineering; boards evaluate CEOs and add finance; partners are assigned for fit; corporations can be customers, talent pools, partners, and acquirers. WilmerHale, printed pp. 17–21 The 2019 essay compresses this into a durable software-specialist institution. Winblad 2019 The apparent evolution from code architecture to adoption and organizational architecture is researcher inference · moderate; inaccessible 1990/2001 full texts prevent a continuous intellectual history.
Her record also contains forecasts that should be scored, not remembered selectively. In 1997 she predicted banner advertising would disappear by year-end; it did not, making this a failed near-term forecast. Charlie Rose, 00:52–02:30 · IAB 2001, banner-unit standards notice Other 1997 claims about advertising-supported internet services and personalization were directionally durable but not precise enough to score as trades. The 2004 Linux/Java/optimism views are preserved as dated qualitative forecasts; the 2017 AI/autonomy horizon through 2027 remains open; 2021 CNBC pages lacked public transcripts/captions and were not substantively scored. Talks forecast ledger
This matters because repeated frameworks establish consistency, not predictive efficacy. The failed banner call is evidence against treating pattern language as a forecasting edge. Researcher inference · strong.
Falsifiable edge thesis
Thesis. Winblad’s plausible repeatable edge was operator-derived software specialization: operating credibility and technical fluency improved access to early software teams; customer-budget and assumption testing helped distinguish markets from demos; and an active partnership supplied recruiting, board, and corporate-adjacency help. Its plausible domain is early enterprise/infrastructure software from Fund I through the cloud transition. This is researcher inference · provisional, not an audited personal-performance conclusion.
Mechanism. Operating experience can create founder trust and sharper product/adoption questions; specialization can concentrate pattern recognition and customer networks; leading early rounds can secure governance access; and a team can convert diagnosis into hiring, customer introductions, and follow-on decisions. WilmerHale, printed pp. 16–21 · Stanford “Customers Are Key,” inline transcript Investor-stated · strong for the mechanism; documented behavior · moderate for selected applications.
Current support. Hyperion, T/Maker, Voltage, and MuleSoft connect Winblad to boards or diligence; Slate and Napster supply timing/legal counterexamples; Pets.com and partner-attributed winners constrain personal credit; HWVP III and the smaller later fund record challenge a smooth persistence story. Investments case labs This is documented behavior · moderate across selected cases, with severe denominator and cash-flow limits.
Predictions if the thesis is true. Unseen company files should show (1) Winblad-sponsored investments repeatedly using customer-budget, migration, and assumption tests before follow-ons; (2) concrete recruiting, product-marketing, or corporate-partner interventions attributed to her by founders and board records; (3) a better matched outcome distribution for such cases across multiple funds, not only Fund I; and (4) written process changes after Slate, Napster, or other failures. These are researcher inference · provisional predictions.
Falsifiers. The thesis weakens or fails if matched records show no distinctive process; partner/board evidence assigns most winners to others; original LP cash flows show Fund I or one company dominates weak later economics; customer testing appears only in retrospective winners; or adverse cases produced no learning while the same risks recurred. It also weakens if access and the 1989 category scarcity explain selection without superior judgment. Researcher inference · strong as an audit design.
People, capital, and influence map
| Node | Documented contribution | Attribution boundary |
|---|---|---|
| Ann Winblad | Operator, cofounder, technical author, named director in selected deals, legacy managing member/control person. ADV Schedule A | Board/control evidence does not establish solo sourcing, IC vote, carry, or personal return. |
| John Hummer | Cofounder/fundraiser; named board partner for Powersoft, Wind River, Pets.com, and Napster. John Hummer biography | Several famous outcomes are firm/John rather than Winblad cases. |
| Bill Edwards, Pitch Johnson, Don Valentine | Endorsers in Winblad’s fund-formation account. Berkeley, pp. 17–19 | Exact introductions, commitments, and influence remain retrospective. |
| Hank Barry | HWVP officer/partner and Napster interim CEO. 2006 sanctions order, Background | Operating conduct, firm conduct, and Winblad conduct must remain separate. |
| Mitchell Kertzman | Shared managing-member power; successor-fund related person. MuleSoft 13G | Later-fund decision and economics remain partnership-level. |
| Lars Leckie and Steve Kishi | Fund VII/VIII related persons and successor leaders. Fund VIII Form D | Founder absence from rosters does not prove zero residual economics. |
| Heidi and Peter Roizen | T/Maker founders and first-investment witnesses. Winblad 2019 | Full financing, board, and distribution records are missing. |
| Founders, CEOs, product marketers, finance leaders | Objects of the team/board model articulated in 2005. WilmerHale, pp. 18–20 | Public founder testimony is too sparse to establish consistent application. |
| LPs and co-investors | Supplied long-duration capital and complementary board work. UC Regents row 48 | Subscription, carry, reserve, and same-basis fund series remain private. |
The network is part of the proposed edge, not noise around it. Treating a partnership outcome as a personal one would erase the mechanism being studied. Researcher inference · moderate.
What the record supports—and what it does not
The evidence supports an influential software operator turned venture cofounder, a durable software-specialist mandate, named board roles, an unusually rich public process vocabulary, selected material company outcomes, and active participation across several technology cycles. It supports a prominent woman-led partnership, not a historically first woman-VC superlative. It supports reported Fund I success and one weak LP-specific Fund III observation, not a verified personal return series.
The strongest skeptical account is that a scarce 1989 category, operating-network access, firm/partner work, and a concentrated Fund I created the reputation; later economics were uneven, surviving narratives selected winners, and the 98-company current directory omits at least part of the 150-plus claimed lifetime denominator. StrictlyVC 2015 · Investments denominator That skeptical thesis is researcher inference · strong and currently cannot be dismissed.
Sourced chronology and learning path
| Period | Turning point | Evidence and interpretation |
|---|---|---|
| 1950–1973 | Minnesota upbringing; mathematics/business education | Berkeley, pp. 1, 4–6; not a verified CS degree. |
| 1973–1975 | Federal Reserve systems work; master’s | Berkeley, pp. 6–8 · St. Thomas. |
| 1975/76–1982/84 | Open Systems founded and sold | Berkeley, pp. 7–13; dates/economics remain bounded. |
| 1985–1989 | California, technical writing, Hummer partnership, fundraising | Berkeley, pp. 13–19 · book catalog. |
| Sep.–Nov. 1989 | Fund I close and T/Maker | Winblad 2019; check/return conflicts preserved. |
| 1990s | Fund I software outcomes and Slate failure | Investments Pareto/cases. |
| 2000–2006 | Napster investment, shutdown, litigation, sanctions, settlement | 2006 order; entity/person/legal boundaries preserved. |
| 2004–2014 | Public process articulation; MuleSoft board era | Talks synthesis · MuleSoft S-1/A. |
| 2015–present | Founder role retrenchment; Funds VII/VIII successor rosters; Aspenwood adviser role | StrictlyVC · Form D/ADV analysis · Aspenwood. |
Recommended learning order: read writings.md for the accessible intellectual record, talks.md for dated process and forecast evidence, investments.md for the 98-company denominator and no-hindsight labs, investmentphilosophy.md for the operating system, and mental-models.md for decision procedures and exception ledgers.
1. Snapshot and testable edge thesis
| Field | Evidence-bounded answer |
|---|---|
| Investor | Ann L. Winblad |
| Operating formation | Co-founder and CFO, Open Systems; coauthor of Object-Oriented Software with Samuel D. Edwards and David R. King |
| Venture institution | Co-founded Hummer Winblad Venture Partners (HWVP) with John Hummer; the firm is widely reported as the first U.S. venture firm focused exclusively on software, not proven by a complete industry census. 2019 essay, mandate and formation paragraphs [investor-stated · moderate] |
| Public portfolio denominator | The current HWVP directory contains 98 unique firm-level logos; 9 are sufficiently reconstructed, 7 are researched but unresolved, and 82 remain firm-page-only unresolved. It is not a personal Winblad ledger. Denominator reconciliation [contemporaneous record · strong] |
| Economic boundary | No public record reconstructs Winblad's personal MOIC, IRR, DPI, TVPI, carry, or complete realized proceeds. Fund I reports use conflicting commitments/investable-capital and return bases. Vehicle analysis [researcher inference · strong] |
Testable edge thesis. Winblad's most defensible repeatable edge was a software-specific information-and-company-building system: operator knowledge narrowed the field; repeated founder, customer, and incumbent contact improved interpretation; market size and buyer budget disciplined selection; dated assumption tests reduced technical and adoption risk; and active boards recruited the executive ensemble needed for the next stage. The thesis is plausible as process, not established as personal alpha. 2019 essay, mandate and first-round paragraphs · WilmerHale Q&A, printed pp. 17–20 · Stanford “Keep Testing Your Core Assumptions” transcript [researcher inference · moderate]
Mechanism and scope. The mechanism should work best in enterprise software where customers can describe budgets and workflow pain, product migrations have observable prerequisites, reference calls are informative, and board recruiting can remove a bottleneck. It should weaken when consumer behavior, legal operability, timing, or capital intensity cannot be tested inside a fund horizon. Hyperion/Arbor, MuleSoft, Voltage Security, and The Knot support pieces of the mechanism; Slate, Napster, Pets.com, Liquid Audio, the failed 1997 banner forecast, and one LP's weak Fund III result are material controls. Case labs [researcher inference · moderate]
Predictions. Previously unseen winning files should contain: software-domain access before broad auctions; a named buyer and budget; explicit adoption and integration assumptions; stage-matched proof points; a role-complete management plan; and a Winblad or best-fit-partner board intervention tied to a dated milestone. Ordinary and failed cases should show either a violated assumption or a documented stop/update decision. [researcher inference · moderate]
Falsifiers. The edge thesis weakens materially if original memoranda show generic sector enthusiasm rather than buyer/adoption work; if the same access and outcomes belonged to other partners; if ordinary and failed cases show no disciplined updating; if results disappear after controlling for T/Maker or other outliers; if complete LP cash flows show no vintage-adjusted persistence; or if board records show ceremonial rather than causal participation. The 98-logo directory, Fund I conflicts, HWVP III LP-specific 1.04x TVPI/1.0% net IRR, and Fund V discounted-secondary result cannot resolve those tests. Portfolio forensics [researcher inference · strong]
2. Core philosophy
Winblad's public doctrine is a sequence, not a single maxim: build competence in a defined technical domain; begin with the accessible market; identify the customer and budget; state the assumptions that make the company work; match proof to financing stage; invest before every fact exists but keep testing; and build the executive and board team able to cross the next constraint. EIX, market-first segment 07:01–07:27 · Full Ratchet, stage framework · WilmerHale, printed pp. 17–20 [investor-stated · strong]
The distinctive synthesis is that specialization should be an information system rather than a marketing label. HWVP's software focus connected operating experience, technical writing, founder networks, customer references, incumbent relationships, board recruiting, and repeated observation of platform shifts. That can improve judgment only if access is separated from selection and later assistance from founder execution. 2019 essay · OnlineEducation interview, sourcing and company-building sections [researcher inference · strong]
Her philosophy contains productive tensions. Markets come first, yet seed companies will not have complete market proof. Investors must absorb a founder's “Kool-Aid,” yet recover enough distance to reject changed assumptions. Patience and calm matter, yet teams must manage with urgency. Failure is normal, yet no public stop-loss or reserve rule closes the loop. Fresh Dialogues, 2008 interview · “Lessons From A Giant,” section headings and body [investor-stated · moderate]
3. Sourcing
| Channel | Supported mechanism | Repeatability and boundary |
|---|---|---|
| Operator and technical-author network | Open Systems experience, the 1990 coauthored book, and software-community participation placed Winblad near founders and technical change. Book catalog record · Berkeley oral history, printed pp. 14–18; paraphrase only [retrospective witness · moderate] | Operating credibility can improve access and interpretation; it does not prove better selection, and the book's author contribution shares are unknown. [researcher inference · strong] |
| Software-only mandate | The firm deliberately sought a concentrated “river” of software opportunities rather than generalist coverage. 2019 essay, mandate paragraphs · Stanford introduction page, inline transcript [investor-stated · strong] | The “first software-only” priority is reported, not census-proven; concentration also magnifies cycle and platform risk. [researcher inference · strong] |
| Founder/referral network | Heidi Roizen's T/Maker relationship is the best documented early example; Winblad's own 2019 account connects it to the first check. 2019 essay, T/Maker paragraphs [retrospective witness · moderate] | The check is reported as $300,000 versus $750,000 elsewhere, and outcome as 3x versus 5x; sourcing credit does not resolve economics. [researcher inference · strong] |
| Customer/incumbent network | HWVP used CIOs and large technology companies as diligence sources, customers, talent pools, partners, and possible acquirers. WilmerHale, printed pp. 17–21 [investor-stated · strong] | Reference access may be stale, conflicted, or optimized for incumbent needs; it must be converted into independent buyer evidence. [researcher inference · moderate] |
| High-volume funnel | Winblad described roughly 500 pitches and no more than ten new investments a year. Full Ratchet transcript, publisher lines 158–162; transcript warns of errors [investor-stated · moderate] | Firm-level self-report, not a dated cohort, partner allocation, rejection ledger, or audited conversion rate. [researcher inference · strong] |
A modern sourcing log should record source, relationship duration, unique information, conflicts, partner owner, customer checks, and every re-underwrite. Reputation increases shots; it does not make the 98 current logos a complete or unbiased denominator. Complete firm ledger [researcher inference · strong]
4. Picking
Market before product admiration. Winblad says the first question is whether a large market can be built or reached. The operational version asks who buys, where the budget lives, why the current workflow fails, and what adoption must change. EIX, 07:01–07:27 · WilmerHale, printed pp. 17–18 [investor-stated · strong]
Proof should match the round. Seed can test feasibility and representative response; Series A should test market/value; Series B should expose retention, upsell, churn, acquisition cost, and repeatability. This is one of the most operational public frameworks, but no complete memo, scorecard, or reserve policy proves consistent use. Full Ratchet, financing-stage answers [investor-stated · strong]
People are a risk system. The screen includes learning speed, values under pressure, founder conflict, self-awareness, role acceptance, destructive behavior, and the ability to attract complements. It is more precise than charisma, but the public examples are selected and retrospective. OnlineEducation, team and founder sections · Axios, edited interview [investor-stated · strong]
Timing is separate from technical truth. The 1992 enterprise-era excerpt identifies migration frictions around object-oriented tooling, reusable class libraries, and enterprise architecture; Slate later became the canonical “too early” lesson, although the stated gap conflicts between 13 and 25 years. 1992 excerpt, PDF p. 66 / printed Hotline p. 23 · Stanford session note, timing clip [researcher inference · moderate]
Unknown decision machinery. IC membership, votes, vetoes, memo format, valuation thresholds, expected ownership, reserve math, kill rates, and reference-check failures remain [insufficient public record]. A famous board seat or later exit cannot substitute for the original decision. Uncertainty ledger
5. Deal and portfolio mechanics
| Mechanic | Supported practice | Boundary |
|---|---|---|
| Early entry | Winblad's 2019 retrospective says HWVP led first institutional rounds and took board roles. 2019 essay, portfolio paragraphs [investor-stated · moderate] | No complete round ledger verifies the frequency, lead definition, ownership target, pricing rule, or reserves. [researcher inference · strong] |
| Stage gates | The public framework escalates evidence from technical feasibility to market/value to repeatable economics. Full Ratchet [investor-stated · strong] | Transcript errors and absent internal records prevent a compliance test. [researcher inference · strong] |
| Concentration/capacity | Winblad described at most ten new companies annually from about 500 pitches; first-round company building is time-intensive. Full Ratchet, lines 158–162 [investor-stated · moderate] | No target portfolio size, active-board ceiling, reserve ratio, or loss budget surfaced. [insufficient public record] |
| Ownership/security | MuleSoft filings show HWVP V/VI vehicle stakes and shared GP control; The Knot filing shows Winblad's director/GP route. MuleSoft S-1/A, principal stockholders · The Knot Form 4 [contemporaneous record · strong] | These do not reveal original approval, complete cost, all follow-ons, allocation, dilution, realized LP cash, or personal return. [researcher inference · strong] |
| Exit | Acquisition/IPO outcomes appear across the directory; the public record does not show a general sell discipline. 98-company ledger [contemporaneous record · moderate] | Headline company value is not HWVP proceeds; firm distributions are not Winblad's personal economics. [researcher inference · strong] |
The visible record is power-law shaped but cannot support an 80/20 percentage. T/Maker, Hyperion/Arbor, MuleSoft, Omniture, The Knot, Powersoft, Wind River, and Scopus are historically or economically salient, yet attribution splits across Winblad, John Hummer, Mark Gorenberg, the partnership, founders, co-investors, and vehicles. Three rankings and sensitivity [researcher inference · strong]
6. Vehicle and incentive fit
Fund structure is part of the strategy because a software-specialist board model consumes partner time, follow-on reserves, and long holding periods. The public record nevertheless resists a continuous “Winblad fund” narrative.
| Record | What it supports | What it cannot support |
|---|---|---|
| Fund I retrospectives | Reported bases conflict: $30m or $35m headline commitments; $27m investable; about $250m/$252m returned; six versus eight/half-of-16 IPOs. Vehicle reconciliation [retrospective witness · moderate] | No audited cash-flow ledger, fee/carry basis, timing, PME, or personal allocation; do not compute one blended multiple. |
| HWVP III, one UC position as of 2020-06-30 | $10m paid in, $10.393m distributed, 1.04x TVPI, 1.0% net IRR. UC Regents report, PDF p. 1 row 48 [contemporaneous record · strong] | One LP position is not the whole fund or Winblad's personal result. |
| HWVP V discounted secondary | SDCERS/StepStone reports 2.9x TVM and 47.3% IRR on its purchased interest. SDCERS/StepStone report, printed p. 21 [contemporaneous record · strong] | Secondary-buyer return is not original LP, fund, or Winblad return. |
| Fund VI ADV | The 2026 ADV provides legacy private-fund/control-person evidence for VI. SEC ADV [contemporaneous record · strong] | Residual regulatory disclosure does not show current investing authority or performance. |
| Funds VII and VIII | Form Ds identify later managing persons and omit Winblad/Hummer; VII reports $80.562m sold of $125m and VIII $66.725m of $75m in the cited amendments. Fund VII amendment · Fund VIII amendment [contemporaneous record · strong] | Form D amounts are offerings, not NAV or returns; omission is a role boundary, not proof of informal noninvolvement. |
The HWVP legal page's Fund V general-partner reference to “Equity Partners VII” conflicts with issuer filings naming the Fund V entity and appears to be a drafting error. Vehicle-source reconciliation [researcher inference · strong] StrictlyVC reported uneven returns and founder retrenchment in 2015; Aspenwood now describes Winblad as emeritus/adviser and no longer active at HWVP. These sources support succession, not private decision-right or carry conclusions. StrictlyVC report · Aspenwood team [contemporaneous record · moderate]
7. Team attribution and work with founders
The public company-building doctrine is clear: diagnose the next bottleneck; recruit or evaluate the CEO and missing executives; install financial and customer truth; allocate the best-fit partner; and preserve founder agency. WilmerHale, printed pp. 18–20 · Full Ratchet, Series A/company-building answers [investor-stated · strong]
| Case | Supported attribution | Boundary |
|---|---|---|
| T/Maker | Roizen relationship and Winblad first-check/board narrative. 2019 essay [retrospective witness · moderate] | Check and return figures conflict; founders/operators created the outcome. |
| Hyperion/Arbor | Firm page names Winblad as director; Wired reports 1991 funding. Hyperion decision lab · Wired profile, Arbor paragraphs [contemporaneous record · moderate] | Firm page's 1991 IPO date is wrong; SEC records point to 1995. No basis/proceeds chain. |
| MuleSoft | Winblad was director from 2006; V/VI GP power was shared with Hummer and Kertzman. S-1/A [contemporaneous record · strong] | A shared firm stake and board tenure are not sole selection credit or personal return. |
| The Knot | Form 4 identifies director/10% owner and managing-member route. Form 4, 2005-04-14 trades [contemporaneous record · strong] | Filing reports ownership mechanics, not original thesis or causal board work. |
| Omniture | HWVP V investment was Mark Gorenberg-led; Winblad later received an in-kind distribution. Omniture S-1 · Winblad Form 4 [contemporaneous record · strong] | Distribution does not establish sourcing, approval, board contribution, or personal deal alpha. |
| Powersoft, Wind River, Pets.com | Opened records point to John Hummer or firm-level attribution; Napster also belongs to the Hank Barry/Hummer route. Attribution map [researcher inference · strong] | Do not recast firm logos as Winblad decisions. Scopus remains unassigned. |
The better the partnership model works, the less honest a hero-investor narrative becomes. Partner fit is itself a proposed mechanism only when the record connects assignment to action; otherwise it is an attribution control. [researcher inference · strong]
8. Views on the craft
- Power law and denominator humility. A few wins likely drove visible outcomes, but missing cash flows, omitted companies, and the current 98-logo curation prohibit a personal hit rate or 80/20 percentage. Portfolio forensics [researcher inference · strong]
- Fund size. Firm history shows growth and retrenchment; the active-board model implies an attention constraint, but Winblad did not publish a stable optimal-fund-size rule. StrictlyVC report [researcher inference · moderate]
- Access versus selection. Software networks, operating credibility, and CIO relationships create access and information; only original decisions and an ordinary-case denominator can show selection skill. [researcher inference · strong]
- Governance. Venture work begins after the check: executive architecture, customer truth, financing, and board judgment are core. WilmerHale, pp. 18–20 [investor-stated · strong]
- Failure. Winblad publicly normalizes a large failure share, but the quoted rate lacks a cohort and no stop/change ledger shows how learning altered later approvals. TEDx, 2011, 13:00–16:10; automated-caption boundary [investor-stated · provisional]
- Exits. IPOs and acquisitions are outcomes, not decision quality by themselves; exact security, dilution, timing, follow-ons, and proceeds are required. [researcher inference · strong]
- Great investing. The public record best supports domain competence, market and buyer clarity, staged falsification, role-complete teams, and attribution discipline—not clairvoyance or solo deal credit. [researcher inference · moderate]
9. Signature bets and decision process
Read the frozen ex-ante packets before the reveal:
- T/Maker — network source, first-check claim, partner/founder credit, and conflicting $300,000/$750,000 and 3x/5x figures.
- Hyperion/Arbor — client-server transition, Winblad board attribution, 1991 funding, erroneous firm-page IPO date, and absent cost/proceeds chain.
- MuleSoft — five-person entry story, 2006 board start, V/VI stakes, shared GP power, distribution evidence, and no personal return inference.
- Voltage Security — roughly 20 CIO/customer checks, budget-line test, board/company-building account, and incomplete investment economics.
- Slate — adoption-timing failure, roughly $1.2m reported firm loss, and conflicting 13/25-years-early retrospectives.
- Pets.com — HWVP III/Technology entities' 13.5% and John Hummer directorship, but no Ann role or complete loss chain.
- Napster — legal-operability, record-preservation, entity sanctions, Hank Barry/Hummer attribution, and no personal copyright-liability finding against Winblad.
- Omniture and The Knot — why SEC ownership mechanics can correct partner credit without revealing the original thesis.
Each lab separates known facts, unknowns, must-be-true conditions, failure modes, next-check milestones, reveal, and attribution. None treats eventual acquisition value as ex-ante evidence. [researcher inference · strong]
10. Mental models and maxims
The reconciled inventory retains six distinct decision models; apparent extras are merged when they are mechanisms or tactics rather than independent rules:
- Capability-backed specialization as an information system.
- Define the accessible market and buyer budget before admiring the product.
- Underwrite the adoption bridge and timing, not technical inevitability.
- Match proof to stage, turn assumptions into facts, then re-underwrite.
- Diligence people as learning, values, conflict, and self-destruction risk.
- Build a complementary executive and board ensemble; assign work by fit.
The candidate-model ledger explains why customer networks, “Kool-Aid,” calm/urgency, failure tolerance, physical proximity, and other recurring phrases are absorbed or excluded rather than silently capped. [researcher inference · strong]
11. Evolution and contradictions
| Period | Publicly supported emphasis | Development, contradiction, or boundary |
|---|---|---|
| 1975/76–1984 | Software operator, CFO, and founder; sale chronology conflicts across 1982–1984. Berkeley oral history, printed pp. 5–14; paraphrase only [retrospective witness · moderate] | BA mathematics/business, not a documented computer-science degree; narrative dates require ranges. |
| 1987/88–1989 | Courtship/planning, 1989 firm close, software-only specialization, T/Maker first check. 2019 essay [retrospective witness · moderate] | Meeting counts 113/130/133/150; LP identity State Farm/St. Paul; milestone dates and check size conflict. |
| 1990–1999 | Object-oriented/enterprise migration, client-server investing, active boards, Fund I success narrative. 1992 excerpt, PDF p. 66 · Wired 1996 profile [contemporaneous record · moderate] | Fund I bases conflict; 1997 banner-ad disappearance forecast failed; Slate shows timing error. |
| 2000–2008 | Company-building framework becomes explicit; market/people/partner-fit; customers and incumbents as infrastructure. WilmerHale, pp. 16–21 [investor-stated · strong] | Napster and Liquid Audio expose legal/governance risk; no public process-change record follows. |
| 2009–2017 | Staged financing, assumption testing, values/culture, global/distributed teams, AI/autonomy forecasts. Full Ratchet · OnlineEducation [investor-stated · strong] | Direct rules become clearer while public application evidence remains selected; Fund III LP result and 2015 retrenchment challenge durability. |
| 2018–2026 | Anniversary retrospective, cloud-era convergence narrative, later-fund succession, emeritus/adviser status. 2019 essay · Aspenwood team [contemporaneous record · moderate] | VII/VIII Form Ds omit founders; 2026 ADV shows legacy VI record, not ongoing new-fund control. |
The durable core is software specialization, customer/market inquiry, explicit assumptions, and team-building. What evolved publicly was precision: technical-migration observation in 1992 became a fuller stage, people, and governance system by 2005–2017. This is an evolution in the public corpus, not proof that private practice changed on those dates. [researcher inference · strong]
12. Failures and limits
- Slate: documented firm failure and timing lesson; reported loss about $1.2m in 1996, later paraphrased as over $1m. “Too early” survives; 13 versus 25 years does not reconcile. Wired profile, Slate paragraphs · Berkeley oral history, printed pp. 21–23; paraphrase only [retrospective witness · moderate]
- Napster: legal-operability and preservation failure at company/firm level; sanctions attach to HWVP/Hank Barry routes in the reviewed orders, not a finding that Winblad personally infringed copyright. Primary-order lab [contemporaneous record · strong]
- Liquid Audio: fiduciary actions were dismissed with prejudice under a settlement agreement; a separate $150,000 patent settlement went to Network Commerce. Neither is a personal adjudication against Winblad; original thesis, sponsor, ownership, and economics remain unresolved. Legal postmortem [contemporaneous record · strong]
- Pets.com/HomeGrocer: Pets provides a firm/John-attributed dot-com loss control; HomeGrocer is much thinner. Neither supports personal Winblad credit or loss. Anti-survivorship boundary [researcher inference · strong]
- Fund persistence: the one-LP Fund III result, reported Fund V/VI size retrenchment, and 2015 uneven-return account challenge a simple durable-alpha story. Vehicle analysis [researcher inference · strong]
- Forecasting: the 1997 prediction that banner advertising would disappear by year-end failed; 2004 Linux/Java, 2017 autonomy, and 2021 software-growth statements require prospective scoring rather than retrospective generosity. Forecast scorecard [researcher inference · strong]
- Evidence selection: current bios and directories foreground survivors; at least 52 companies may be omitted if “150+” and the current 98 logos use compatible definitions. Denominator reconciliation [researcher inference · moderate]
No reviewed reliable record establishes a final personal-liability judgment against Winblad. Absence from this bounded search is not proof that no claim ever existed. [researcher inference · moderate]
13. Historical operating environment
Winblad's operating career began when packaged business software was young and distribution, hardware constraints, direct customer service, and platform dependence were central. The 1992 excerpt belongs to the object-oriented/client-server migration, where reusable components, enterprise integration, skills, and legacy systems created an adoption bridge. 1992 excerpt, PDF p. 66 [contemporaneous record · strong]
HWVP formed before today's abundant seed ecosystem and during a period when a software-only fund itself could create differentiated attention. Fund I's visible outcomes crossed the client-server and enterprise-tools wave; the late-1990s internet boom then lowered entry barriers and increased capital, followed by the dot-com collapse. Capital efficiency can expand opportunity and simultaneously invite overinvestment and weak differentiation. Charlie Rose, 09:00–10:14 [investor-stated · strong]
The 2000s and 2010s added SaaS/cloud, open source, global engineering, product-led adoption, and larger later-stage pools. MuleSoft is a convergence example; Pets.com, Napster, and Liquid Audio show that internet scale did not erase unit-economics, legal, records, or governance risk. Later fund structures and succession also mean that the founder-era doctrine cannot be assigned automatically to Funds VII/VIII. [researcher inference · strong]
Performance comparison requires vintage, geography, sector, cash flows, and vehicle terms. Company exits, private marks, current-logo curation, one LP's interim result, and a secondary buyer's return are not interchangeable. [researcher inference · strong]
14. Modern VC translation (as of 2026-08-21)
| Lesson | What transfers | What changed or fails | Applicability signals | Likely misuse | Dated application |
|---|---|---|---|---|---|
| Capability-backed specialization | Operating competence plus repeated customer/founder contact can improve information quality | Cloud APIs and AI reduce build cost; sector labels are cheap and crowded | Unique references, technical error detection, post-check recruiting value | Branding a generalist fund as “AI-native” | 2026-08-21 · researcher hypothetical · moderate: score what the team can independently verify and change |
| Accessible market and budget | Buyer, budget, pain, procurement, and alternatives remain decisive | Bottom-up usage may precede budget; agentic tools can blur user and buyer | Paid retention, expansion, referenceability, workflow ownership | Calling TAM a sales forecast | 2026-08-21 · researcher hypothetical · moderate: map user→buyer→budget→renewal before scaling |
| Adoption bridge | Integration, migration, regulation, and workflow change govern timing | Models/products change faster, but data rights, security, and switching costs persist | Implementation time, complement readiness, retraining, compliance | Treating inevitability as investability | 2026-08-21 · researcher hypothetical · moderate: write a dated dependency map and fund-horizon test |
| Stage-matched proof | Evidence requirements should rise with capital at risk | AI can create rapid trials and synthetic metrics; quality and retention need harder checks | Independent use, paid cohorts, gross retention, CAC/payback, expansion | Using one pilot or benchmark as Series B proof | 2026-08-21 · researcher hypothetical · strong: pre-register round-specific facts and kill criteria |
| People-risk diligence | Learning, values, conflict, self-awareness, and role complementarity still matter | Distributed teams and AI leverage change job boundaries | Reference consistency, conflict behavior, named weakness, complement owner | Psychologizing founders or rewarding polish | 2026-08-21 · researcher hypothetical · moderate: score observed behavior, not demographic proxies |
| Board ensemble and fit | CEO judgment, executive recruiting, capital, and customer truth remain board work | Founder control, remote boards, cyber/model risk, and information rights vary | Named bottleneck, owner, milestone, information path | Counting seats or introductions as value creation | 2026-08-21 · researcher hypothetical · moderate: write a quarterly intervention hypothesis and outcome |
| Failure tolerance | Venture portfolios need room for loss | Larger rounds and continuation vehicles can hide sunk-cost escalation | Dated thesis break, reserve opportunity cost, independent re-underwrite | Turning “40% fail” into permission without denominator | 2026-08-21 · researcher hypothetical · provisional: require stop/change records for each failed assumption |
| Vehicle fit | Duration, reserves, governance, succession, and incentives shape strategy | Secondaries, continuation vehicles, RIAs, and cross-stage funds add conflicts | Ownership target, reserve map, liquidity path, key-person terms | Calling all long-duration capital patient | 2026-08-21 · researcher hypothetical · moderate: model company and vehicle cash needs together |
These are present-day analyst applications, not claims that Winblad used 2026 tools, metrics, or AI categories. Every current company decision requires fresh market and legal data. [researcher inference · strong]
15. Comparison with completed peers
Only completed dossiers as of 2026-08-21 are used: Arthur Rock, Doug Leone, and Martin Casado. Rock controls for concentrated company formation and board craft; Leone for a same-era institutional enterprise franchise; Casado for modern operator-to-investor technical specialization. Their vehicles, eras, and evidence corpora are not performance-comparable. [researcher inference · strong]
Each cell below links to the completed canon section containing its claim-local underlying evidence; the comparison is dimensional, not a return ranking.
| Dimension | Ann Winblad | Arthur Rock | Doug Leone | Martin Casado |
|---|---|---|---|---|
| Historical edge hypothesis | Software operator-specialist information system plus active company building. Evidence [researcher inference · moderate] | Trusted access, longitudinal people judgment, and concentrated governance. Evidence [researcher inference · moderate] | Institutional partner network, enterprise customer/GTM judgment, and franchise architecture. Evidence [researcher inference · moderate] | Operator/technical architecture maps joined to customer usage and commercial control. Evidence [researcher inference · moderate] |
| Sourcing | Software founders, operators, customers/CIOs, incumbents, and referrals. Evidence [researcher inference · strong] | Proven teams, trusted intermediaries, reputation, and syndicates. Evidence [researcher inference · moderate] | Partner specialists, technical networks, founder relationships, and direct hunting. Evidence [researcher inference · moderate] | Technical discontinuities, market maps, practitioner networks, and portfolio adjacency. Evidence [researcher inference · moderate] |
| Picking | Accessible market/budget, adoption timing, stage proof, and learning/values/team fit. Evidence [researcher inference · strong] | Intellectual honesty, execution, motive, complements, and observed demand. Evidence [researcher inference · moderate] | Founder motive/self-awareness plus customer references, pull, and GTM truth. Evidence [researcher inference · moderate] | Architecture/control-point maps corrected by usage, buyer, distribution, and full-stack economics. Evidence [researcher inference · moderate] |
| Ownership and price | Early-round/board preference is stated; selected vehicle stakes are visible; no complete pricing or ownership rule. Evidence [researcher inference · strong] | Concentrated cases and securities survive, but no continuous ownership or price ledger. Evidence [researcher inference · moderate] | Selected large stakes are visible; deal-level price, dilution, and personal economics remain bounded. Evidence [researcher inference · moderate] | Public doctrine makes ownership part of underwriting, but most deal securities, prices, and proceeds are private. Evidence [researcher inference · moderate] |
| Construction and reserves | Pitch cadence and board capacity are stated; portfolio target, reserve ratio, and stop rules are unknown. Evidence [researcher inference · strong] | Public cases suggest concentration; reserves and a complete loss denominator are unavailable. Evidence [researcher inference · moderate] | Partner-team construction is visible; reserve/allocation rules and complete cohort economics remain private. Evidence [researcher inference · moderate] | Stage-team and follow-on logic are public; vehicle assignment, reserves, and cohort cash flows are not. Evidence [researcher inference · moderate] |
| Governance | CEO/executive recruiting, partner fit, and finance/customer truth; causal intervention remains unproved. Evidence [researcher inference · strong] | Small active portfolio, recruiting, accounting, audit, and CEO oversight. Evidence [researcher inference · moderate] | Stage-matched recruiting, GTM, financing, and succession; help rather than operate. Evidence [researcher inference · moderate] | Technical/commercial diagnosis, founder-led learning, and explicit conflict/governance boundaries. Evidence [researcher inference · moderate] |
| Vehicle and incentives | Founder-era I–VI evidence, III/V controls, VII/VIII succession; fees/carry and personal allocation are private. Evidence [researcher inference · strong] | Banking, finite LP pools, and personal/syndicate positions require entity separation. Evidence [researcher inference · moderate] | Conventional funds, shared-carry narrative, regional partnerships, and later open-ended architecture. Evidence [researcher inference · moderate] | A much larger a16z platform, specialist stage teams, and potential related-company conflicts are not HWVP-comparable. Evidence [researcher inference · moderate] |
| Failures and misses | Slate, Napster, Liquid Audio, Pets boundary, Fund III LP result, and failed banner forecast. Evidence [researcher inference · strong] | Diasonics, Ridge, ROLM/Compaq misses, and admitted disappointments. Evidence [researcher inference · moderate] | Color, Facebook passes, ordinary-board abyss, and global/succession controls. Evidence [researcher inference · moderate] | Tackle overbuild, Rapid reset, Orbit sunset, Astranis anomaly, and theory/usage correction; most fund outcomes remain unknown. Evidence [researcher inference · moderate] |
| Attribution and denominator | Firm logos split across partners, founders, vehicles, and board roles; 98 current logos are not a personal ledger. Evidence [researcher inference · strong] | Founders, bankers, syndicates, entities, and boards share causality; the visible case set is selected. Evidence [researcher inference · moderate] | Institutional partner teams intentionally share sourcing and governance credit; no complete personal denominator. Evidence [researcher inference · moderate] | Operator learning, a16z teams/platform, founders, coauthors, and incomplete public portfolio attribution prevent personal-alpha inference. Evidence [researcher inference · moderate] |
Underlying evidence anchors the distinctions: Rock emphasizes repeated listening, intellectual honesty, people judgment, and concentrated governance in his 1987 HBR account and completed canon; Leone emphasizes customer evidence, founder motive, and complementary partnership in “Seven Questions,” answer 3, the PlanGrid Stanford session, and completed canon; Casado maps technical architecture and lets observed adoption correct theory in “Emerging Architectures” and completed canon. [researcher inference · moderate] None of the four public dossiers permits a personal risk-adjusted-return comparison. [researcher inference · strong]
16. The strongest case against greatness
The skeptical thesis is that Winblad was an unusually articulate software operator inside a differentiated partnership, but that software-sector tailwinds, founder execution, customer/incumbent access, John Hummer and later partners, favorable exit markets, and a small number of outliers explain more than repeatable personal selection skill. [researcher inference · moderate]
The record supporting skepticism is substantive:
- Fund I's celebrated result has three incompatible economic bases and inconsistent IPO counts; no audited ledger allocates value by company or partner. Vehicle reconciliation [researcher inference · strong]
- HWVP III's UC position produced only 1.04x TVPI and 1.0% net IRR as of 2020-06-30; it is one LP, but a powerful anti-persistence control. UC Regents report, PDF p. 1 row 48 [contemporaneous record · strong]
- Reported fund-size retrenchment and uneven returns weaken a smooth franchise-success narrative. StrictlyVC report [contemporaneous record · moderate]
- The live directory has 98 logos while firm biographies claim 150+/160+; only 9 are sufficiently reconstructed. The visible record cannot yield a personal hit rate. Denominator reconciliation [researcher inference · strong]
- Several famous outcomes are not Winblad-led: Powersoft, Wind River, and Pets.com point to Hummer; Omniture to Gorenberg; Scopus is unassigned. People/capital map [contemporaneous record · strong]
- Slate, Napster, Liquid Audio, Pets.com, and the failed banner forecast show market-timing, legal-operability, governance, business-model, and prediction errors. Failure/legal postmortems · Forecast scorecard [researcher inference · strong]
- Board tenure and firm ownership do not prove causal assistance; the decisive founder, customer, recruiting, vote, and counterfactual records are mostly private. Uncertainty ledger [researcher inference · strong]
- Funds VII/VIII omit the founders from related-person rosters, and Aspenwood says Winblad is no longer active at HWVP; “same job for 30 years” is rhetoric, not current role evidence. Vehicle and succession evidence [contemporaneous record · strong]
The case for greatness survives only in a narrower form: a historically important specialist institution, unusually coherent public decision doctrine, and several well-supported company-building routes. Durable personal alpha remains unproved. [researcher inference · moderate]
17. Analyst study guide, glossary, and go deeper
Recommended learning path
- Start with the profile for chronology, identity, attribution, and the falsifiable edge thesis.
- Read the 2019 essay analysis beside the Fund I/vehicle reconciliation; do not memorize one return figure.
- Use the Full Ratchet note for stage proof, then the WilmerHale note for market, people, board, and incumbent mechanisms.
- Study T/Maker, MuleSoft, Voltage, and Slate before reading outcomes.
- Finish with the 98-company ledger, failure/legal postmortems, and evidence gaps.
Glossary
- Accessible market: buyers, budgets, workflows, and adoption paths plausibly reachable within the company's and fund's horizon—not headline TAM.
- Adoption bridge: migration, integration, training, procurement, regulation, and complementary technology required for use.
- Assumption ledger: dated must-be-true claims, evidence, owners, next tests, and kill/change conditions.
- Attribution: separate source, sponsor, approver, vehicle, board contributor, founder/operator, and economic beneficiary.
- DPI / TVPI / IRR: distributions-to-paid-in, total-value-to-paid-in, and internal rate of return; each requires a defined vehicle and cash-flow basis.
- Evidence axes: provenance/status (
contemporaneous record,investor-stated,retrospective witness,researcher inference,insufficient public record) plus confidence (strong,moderate,provisional). - Partner fit: assigning post-check work to the person best equipped to solve the next bottleneck; it is not automatic sourcing credit.
- Proof ladder: stage-specific evidence from feasibility through market/value to repeatable economics.
- Reported return: a sourced claim whose vehicle, capital base, dates, fees, and cash flows may be incomplete; never silently convert it to audited performance.
Analyst checklist
- Name the buyer, budget, workflow pain, alternative, adoption dependency, and timing window.
- Freeze market, people, legal, unit-economics, and platform assumptions before the outcome.
- Match proof to round; state the next test, date, owner, reserve need, and stop/change rule.
- Map source, sponsor, IC decision, security, ownership, follow-ons, board actions, distributions, and founder execution separately.
- Compare ordinary and failed cases, not only exits; stress-test the dominant outlier and complete-cohort performance.
- Reconcile every figure by vehicle, commitment versus investable capital, gross versus net, original versus secondary buyer, and point-in-time versus realized.
Ranked primary sources
- SEC issuer, adviser, and offering records — best for dated board roles, vehicle ownership/control, transactions, and succession; they do not reveal original theses, partner allocations, carry, or causal board work. MuleSoft S-1/A · 2026 ADV · Fund VII original Form D [contemporaneous record · strong]
- Winblad’s 2019 signed anniversary essay — best first-person synthesis of the software-only mandate, T/Maker route, first-round/board doctrine, and firm narrative; retrospective, promotional, and numerically conflicted. Essay [investor-stated · strong]
- Stanford eCorner’s 2004 official session/transcripts — best mid-career direct record for Fund I claims, sourcing, customers, assumptions, timing, and forecasts; 13 clips are one session, not independent witnesses. Session entry [investor-stated · strong]
- WilmerHale’s 2005 edited Q&A — best company-building account for buyer budget, CIO references, executive/board work, incumbents, and partner fit; interviewer-led and edited. Q&A, printed pp. 16–21 [investor-stated · strong]
- Berkeley oral history — best long-form first-person chronology and Slate retrospective; memory-limited and subject to a quotation-rights boundary, so this dossier paraphrases it. Oral history, printed pp. 5–23 [retrospective witness · moderate]
Ranked secondary and control sources
- UC Regents and SDCERS/StepStone public-LP reports — strongest independent economic controls because they identify a particular LP position or purchased secondary interest; neither is a whole-fund series or personal Winblad return. UC report, PDF p. 1 row 48 · SDCERS report, printed p. 21 [contemporaneous record · strong]
- Wired’s 1996 profile — strongest near-contemporaneous independent narrative for early firm mechanics, Arbor, Slate, Fund I claims, and partner dynamics; its reported figures still lack audited schedules. Profile [contemporaneous record · moderate]
- StrictlyVC’s 2015 transition report — strongest independent account of uneven returns, Fund V/VI contraction, Napster overhang, and founders’ role transition; reported rather than governing-record evidence. Report [contemporaneous record · moderate]
- Fortune’s 2016 fund notice — useful independent succession control because Fund VII omitted the founders as GPs; brief coverage requires confirmation against the Form Ds. Notice [contemporaneous record · moderate]
Go deeper. The highest-value missing records are Fund I audited cash flows and company schedule; LP statements for Funds II–VI; original investment memoranda and IC votes; cap tables and follow-on ledgers; board minutes/intervention records; rejected-deal and stop-decision logs; the full 1990 book and 2001 CACM article; complete CNBC 2021 audiovisual access; and archival records for the at least 52 potentially omitted companies. Retrieval frontier [researcher inference · strong]
Pareto 80/20 — what drove the record
The public record supports directional ranking, not a literal 80/20 return split. The current Hummer Winblad directory is a 98-company, firm-level survival-biased list, while Winblad later claimed more than 150 lifetime firm investments; no complete fund cash-flow, ownership, dilution, or partner-attribution schedule is public. Accordingly, “economic contribution” below means best-supported likely contribution to firm/fund outcomes—not Ann Winblad personal P&L—and every rank remains researcher inference.
Economic contribution — directional, not a computed split
| Rank | Deal / cluster | Basis or measure | Credit boundary | Evidence status | Supported mechanism and denominator caveat |
|---|---|---|---|---|---|
| 1 | Fund I public-company cluster: Hyperion/Arbor, Powersoft, Wind River, Scopus | Three incompatible reports must remain separate: $27m investable returning $252m (2019); a $35m fund returning about $250m and 50% annually (1996); and a $35m fund returning over 10x (2005). Company cash flows are unavailable | Fund and partnership, not Winblad alone | retrospective witness · provisional | Early software specialization plus concentrated 16-company portfolio; contribution cannot be allocated company by company. Winblad 2019, Fund I paragraphs · Wired 1996, Fund I passage · WilmerHale 2005, printed p. 17 |
| 2 | MuleSoft | Public filings establish HWVP V/VI ownership and Winblad’s board tenure; a secondary buyer later identified MuleSoft and Birst as sought-after HWVP V assets | Shared fund and managing-member power; no solo sourcing claim | contemporaneous record · strong for holdings/governance; insufficient public record for contribution | Board/governance and long-duration enterprise software exposure; no cost basis, dilution, distribution, or original-LP return schedule. MuleSoft S-1/A, principal stockholders/directors · Schedule 13G, Items 4–6 |
| 3 | Omniture and The Knot | Omniture filings disclose HWVP V financing and later distributions; The Knot filing discloses fund sales/remaining shares, but neither supplies full cash flows | Omniture was HWVP V/Mark Gorenberg-led; Winblad’s later in-kind distribution is not sourcing. The Knot supports her director/GP route, with a pecuniary-interest disclaimer | contemporaneous record · strong for mechanics; researcher inference · provisional for economic rank | Ranked below Fund I/MuleSoft because ownership-to-distribution histories remain incomplete. Omniture S-1, Certain Relationships · Omniture Form 4, transaction/footnotes · The Knot Form 4 |
Removing the likely dominant Fund I cluster leaves no defensible rank-order of remaining dollar gains: HWVP III’s one-UC-LP record is only 1.04x TVPI/1.0% net IRR, while an SDCERS secondary interest in HWVP V reports 2.9x TVM/47.3% IRR because it was bought at a discount. These are different investors, entry bases, and vintages, so they cannot be combined into a firm series. UC Regents report, PDF p. 1 row 48 · StepStone report, printed p. 21
Historical importance
| Rank | Deal | Why it matters | Credit boundary | Evidence status |
|---|---|---|---|---|
| 1 | T/Maker | First investment after Fund I close; tests whether an operating network converted into proprietary software sourcing | Winblad is directly tied to the board, but check and return bases conflict | investor-stated · moderate. Winblad 2019, T/Maker paragraphs |
| 2 | Napster | A category-defining internet bet that exposed legal-governance and records-preservation risk | Firm investment; Hank Barry became interim CEO; sanctions applied to Hummer entities, not a personal copyright judgment against Winblad | contemporaneous record · strong. 2006 sanctions order, Background and Conclusion |
| 3 | MuleSoft | Connects Winblad’s early software thesis to APIs/cloud infrastructure and supplies the best later governance/ownership trail | Shared HWVP V/VI and managing-member attribution | documented behavior · strong. MuleSoft S-1/A |
Decision-learning value
| Rank | Case | Learning value | Evidence status |
|---|---|---|---|
| 1 | Slate | A full failure lab on product timing, buyer readiness, milestone design, and the danger of explaining failure only after the fact | retrospective witness · moderate. Berkeley oral history, printed pp. 21–23 |
| 2 | Napster | Separates market adoption from legal operability, control, document retention, and downside containment | contemporaneous record · strong for litigation facts; thesis remains incompletely documented. 2005 order, Background |
| 3 | T/Maker | Tests network-based sourcing, first-check sizing, board work, and conflicting outcome narration | investor-stated · provisional on economics. Stanford introduction page, inline transcript |
Evidence boundary and searched denominator
Scope and definitions
The scoped universe is every company displayed on the live Hummer Winblad directory as of 2026-08-21, plus public claims and primary records needed to interpret funds, vehicles, follow-ons, boards, litigation, and exits. A company is one ledger row; aliases shown by the firm remain one company; rounds and follow-ons are not new companies. Directory presence proves only firm-level inclusion. It does not prove vehicle, date, stage, active status, individual sponsorship, personal ownership, or realized return. Official Hummer Winblad companies directory
| Measure | Count / claim | Definition and reconciliation |
|---|---|---|
| Publicly listed now | 98 | Exact unique company-item entries on the canonical live directory, including aliases in the displayed label. |
| Earlier public checkpoints | 16 / ~80 / >90 / 100+ / 150+ | Fund I (16); firm by 2000 (~80); Stanford 2004 (>90); Berkeley 2012 (100+); Winblad 2019 (150+). These are dated, definition-sensitive firm claims, not additive. |
| Searched | 98 | Every live directory entry was extracted and mapped to its canonical company route. |
| Researched | 16 | Thirteen material/adverse companies plus three ordinary/boundary cases have at least one additional direct-voice, filing, court, LP, or outcome route in the research record. |
| Sufficiently reconstructed | 9 | T/Maker, Hyperion/Arbor, Powersoft, Wind River, Slate, Napster, MuleSoft, The Knot, and Pets.com have enough evidence for a bounded decision/governance/outcome account, though none has a complete deal cash-flow schedule. |
| Researched but unresolved | 7 | Liquid Audio, Scopus, Omniture, Voltage, NuoDB, Five9, and HomeGrocer have material leads but lack one or more basic decision, vehicle, ownership, or outcome fields. |
| Firm-page-only unresolved | 82 | Firm inclusion known; substantive deal reconstruction not completed. This category overlaps neither the nine sufficiently reconstructed nor seven researched-but-unresolved rows. |
| Excluded from 98 | 0 | No live directory company was removed. Open Systems is operating history, not a HWVP portfolio investment, so it is outside this denominator. |
Coverage fraction: directory enumeration is 98/98 (100%) and bounded reconstruction is 9/98 (9.2%) for the current live list, using the definitions above. Historical lifetime reconstruction is not computable: the 150-plus 2019 claim implies at least 52 companies absent from the live 98 if definitions are comparable, but comparability and the identities of omitted deals are unknown. The 98 therefore cannot be used as the denominator for Winblad’s personal hit rate or whole-career economic contribution. Winblad 2019, anniversary paragraph Documented directory · strong for current enumeration; researcher inference · insufficient public record for lifetime coverage.
Historical market, regulatory, and base-rate context
- 1989 entry set. HWVP’s explicit software mandate was made when software could be financed with smaller amounts than hardware-heavy businesses and specialist software venture firms were unusual. That is investor-stated · moderate, not a verified census of all 1989 firms. WilmerHale interview, printed pp. 16–17
- Client-server migration. Fund I examples such as Arbor/Hyperion, Powersoft, and Wind River were selected as enterprises shifted away from mainframe-centered architectures. The link from specialization to selection is retrospective witness · moderate; contemporary IC memoranda and period base rates are unavailable. Winblad 2019, Fund I discussion
- Dot-com legal boundary. Napster already faced copyright suits when Hummer invested in May 2000 and entered a common-interest defense arrangement. Adoption did not remove legal-operability risk. 2006 sanctions order, Background Contemporaneous record · strong.
- Base-rate limit. The historical NVCA archive was identified, but no same-definition cohort of 1989 software-only funds or comparable company-level loss/exit rate was found. Any claim that Fund I was exceptional rests on reported absolute outcomes rather than a fully matched benchmark. NVCA historical-yearbook archive Researcher inference · insufficient public record.
Vehicle economics and incentives
| Vehicle / era | Public evidence | Incentive and decision implication |
|---|---|---|
| Fund I, 1989 | $35m commitment/headline basis in 1996/2005 versus $27m investable in 2019; $250m/$252m returned is reported on incompatible bases | Small fund and software-only mandate plausibly rewarded capital-efficient specialist bets, but fees, recycling, carry, timing, gross/net, and LP cash flows are missing. Researcher inference · provisional. Wired 1996 · Winblad 2019 |
| HWVP III, 1997 vintage | UC committed/contributed $10m, received $10.393m, no residual value; 1.04x TVPI and 1.0% net IRR as of 2020-06-30 | This is one LP’s net experience, not a whole-fund or personal result. Contemporaneous record · strong. UC Regents, PDF p. 1 row 48 |
| Fund V, 2000 vintage | Reported roughly $420m/$424m fund; SDCERS obtained a $1.5m secondary position, distributed $4.4m, 2.9x TVM/47.3% IRR; StepStone says it bought at a discount and names MuleSoft/Birst | Secondary-buyer IRR is driven by purchase price and timing; do not generalize to original LPs or Winblad. Contemporaneous record · strong. StepStone report, printed p. 21 |
| Fund VI / operating adviser | StrictlyVC reported about $201m after Fund V’s ~$424m. The 2026-03-26 ADV reports only Fund VI as a private fund: $68.674m gross asset value, 34 beneficial owners, 2% related-person ownership, 52% fund-of-funds ownership, and 34% non-US ownership; Schedule A lists Hummer, Winblad, and Kertzman as managing members/control persons with ownership code C (25% to <50%). | The ADV is a current legal/control record for the legacy operating company and Fund VI, not proof that the founders manage Funds VII/VIII or hold the same public-facing role. Contemporaneous record · strong. Form ADV, Item 7.B.1 and Schedule A |
| Fund VII | Original 2016 Form D offered $125m and named Leckie, Kertzman, and Kishi as managing-GP members; the 2018 amendment reported $80,561,896 sold to 54 investors. Winblad/Hummer are absent from Item 3. | Primary evidence of successor fundraising and related-person roster, but not founders’ residual economics in older entities. Contemporaneous record · strong. Fund VII original, Items 1/3/13 · final amendment, Items 13–15 |
| Fund VIII | Original Form D offered $75m and named HW Equity Partners VIII, Leckie, and Kishi; the amendment reported $66,725,000 sold to 90 investors. Winblad/Hummer are absent. | Supports succession beyond VII. The amendment signature date is 2021-06-01 while SEC acceptance is later; neither date should be recast as first close. Contemporaneous record · strong. Fund VIII original, Items 1/3/13 · amendment, Items 13–15 |
| Public-facing succession | Fortune described Fund VII as the first without the founders as GPs; Aspenwood presents Winblad as emeritus/adviser | Website title, active-fund roster, and legacy operating-company legal control are different dimensions. Contemporaneous record · strong for the separate records; their economic linkage remains unknown. Fortune 2016 · Aspenwood team |
The public record does not disclose management fees, carry splits, GP commitments, LP advisory rights, reserve policy, recycling, distribution waterfalls, or geographic authority. The legacy legal page labels Fund V’s GP “Hummer Winblad Equity Partners VII LLC,” while Omniture’s issuer filing names HW Equity Partners V LLC; this dossier treats the VII-for-V wording as an apparent drafting error, not evidence of a different vehicle. Omniture S-1, principal entities HWVP legal page A modern LP-backed fund has similar duration and agency issues, but comparing exact incentives would be speculative without partnership agreements.
People, capital, and influence map
| Person/entity | Supported role | What remains unknown |
|---|---|---|
| Ann Winblad | Documented behavior · strong. Cofounder; T/Maker and MuleSoft director; 2026 legacy operating-company ADV still lists her as managing member/control person. Winblad 2019 · MuleSoft S-1/A · ADV Schedule A | Solo sourcing, IC vote, check negotiation, follow-on authority, carry, and personal proceeds for most deals |
| John Hummer | Documented behavior · strong. Cofounder/managing member; official pages name him for Powersoft, Wind River, Pets.com, and Napster. John Hummer biography · ADV Schedule A | Company-by-company sourcing/IC allocation beyond named board routes |
| Hank Barry | Contemporaneous record · strong. HWVP officer/partner and Napster interim CEO; the court record distinguishes his operating role from other Hummer personnel. 2006 order, Background | Exact authority boundaries among Napster board, management, and HWVP |
| Mitchell Kertzman | Contemporaneous record · strong. Managing member with potential shared power over MuleSoft fund shares; named on Fund VII’s original related-person roster. MuleSoft 13G, Items 4–6 · Fund VII Form D, Item 3 | Sourcing/IC credit and internal succession economics |
| Lars Leckie, Steve Kishi, and later team | Contemporaneous record · strong. Fund VII/VIII related-person records name Leckie/Kishi; Aspenwood gives current public roles. Fund VII Form D · Fund VIII Form D · Aspenwood team | Decision rights in earlier funds and founders’ residual economics |
| Heidi and Peter Roizen | Retrospective witness · moderate. T/Maker founders; Heidi is the central first-deal witness and Winblad says she joined its board. Winblad 2019, T/Maker paragraphs | Full financing schedule, board minutes, and exit distributions |
| LPs | Retrospective witness · provisional. Institutional capital; the Berkeley account names St. Paul Companies while 2019 names State Farm. Berkeley, printed pp. 17–19 · Winblad 2019 | Subscription records, LP allocation, fees, and cash-flow schedules |
This map rejects lone-investor credit. A board seat documents governance access, not necessarily sourcing, approval, or return ownership; managing-member powers may be shared and pecuniary interest may be disclaimed. MuleSoft Schedule 13G, Items 4–6 · The Knot Form 4, footnotes
Comprehensive firm-level deal ledger
The table includes all 98 live official entries. Unknown means the field is not publicly established in the reviewed record; it is not evidence that no event occurred. Each company link is the firm’s canonical route and supports only directory inclusion unless another source is cited in the row.
| # | Company | Chronology / stage | Contemporaneous thesis | Entity / vehicle / check / ownership | Team / governance credit | Follow-on / dilution | Outcome / reported economics | Retrospective account | Evidence boundary | Reconstruction |
|---|---|---|---|---|---|---|---|---|---|---|
| 1 | 6connect | date/stage unknown; firm classification: Infrastructure; IPv6; Management; Networking | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 2 | AceMetrix | date/stage unknown; firm classification: Analytics; Video; Television | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Ann Winblad as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 3 | AdForce | date/stage unknown; firm classification: Advertising; Ad Server | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | firm page states IPO ADFC; acquired by CMGI in January 2000; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 4 | Akimbi | date/stage unknown; firm classification: Infrastructure; Automation; Test/Dev | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Mitchell Kertzman as board | not publicly established | firm page states acquired by VMware; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 5 | Alpharank | date/stage unknown; firm classification: Application | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Steve Kishi as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 6 | Amberdata | date/stage unknown; firm classification: Blockchain; SaaS | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Lars Leckie as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 7 | Aria Systems | date/stage unknown; firm classification: Enterprise; SaaS; Billing; Cloud; Recurring; Subscription | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Lars Leckie as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 8 | Aspire | date/stage unknown; firm classification: Marketing; Content; Creative | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Lars Leckie as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 9 | Baynote | date/stage unknown; firm classification: SaaS; Ecommerce; Personalization; Actionable Analytics | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names John Hummer as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 10 | Berkeley Systems | date/stage unknown; classification not stated | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Ann Winblad as board | not publicly established | firm page states acquired by Cendant in April 1997; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 11 | Birst | date/stage unknown; firm classification: SaaS; Enterprise; Analytics; Business Intelligence; Cloud | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names John Hummer as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 12 | Blissfully | date/stage unknown; classification not stated | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Mitchell Kertzman as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 13 | Bridgestream | date/stage unknown; firm classification: Application; Identity | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Mitchell Kertzman as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 14 | Central Point Software | date/stage unknown; classification not stated | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Ann Winblad as board | not publicly established | firm page states acquired by Symantec in May 1994; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 15 | Cenzic | date/stage unknown; firm classification: Security; Application Security; Testing | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 16 | Cittio | date/stage unknown; firm classification: Application; Monitoring | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 17 | Communicado | date/stage unknown; firm classification: Application; Voice; VoIP | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 18 | Dean & Deluca | date/stage unknown; firm classification: Consumer; Ecommerce | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Ann Winblad as board | not publicly established | firm page states acquired by Pace Development Corp. in 2014; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 19 | Domo Technologies | date/stage unknown; firm classification: SaaS; Enterprise; Analytics | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 20 | Elastra | date/stage unknown; firm classification: Infrastructure; Cloud; Scale Out | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names John Hummer as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 21 | Employease | date/stage unknown; firm classification: SaaS; HR Software; Atlanta | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names John Hummer as board | not publicly established | firm page states acquired by ADP; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 22 | EvoStor | date/stage unknown; firm classification: Infrastructure; Software Defined Storage; Virtualization | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 23 | Extensity | date/stage unknown; firm classification: Application; Expense Tracking | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names John Hummer as board | not publicly established | firm page states IPO EXTN; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 24 | Five9, Inc | date/stage unresolved; firm category SaaS/cloud/telco | original thesis not public | vehicle/check/security/ownership unknown | firm page names Mitchell Kertzman; decision rights unknown | not public | unknown | no Winblad deal account located | firm-stated · moderate; economics insufficient | researched / unresolved |
| 25 | Flite | date/stage unknown; firm classification: Advertising; Ad Server; Rich Content | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Mitchell Kertzman as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 26 | FusionStorm | date/stage unknown; firm classification: Datacenter; Reseller | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 27 | GlobalCenter | date/stage unknown; firm classification: Infrastructure; Datacenter; Management | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names John Hummer as board | not publicly established | firm page states acquired by Frontier in March 1998; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 28 | GNi | date/stage unknown; firm classification: Infrastructure; Gaming; Cloud | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 29 | HomeGrocer | dot-com era; Consumer/ecommerce/delivery | original thesis not public | vehicle/check/security/ownership unknown | firm page names John Hummer; no Ann credit | not public | firm page says IPO as WBVN and Webvan merger Sept. 2000; economics unknown | no Winblad deal account located | firm-stated · moderate; economics insufficient | researched / unresolved |
| 30 | Homes.com | date/stage unknown; firm classification: Consumer; Real Estate | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | firm page states acquired by Trader Publishing Company in October 2004; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 31 | Hopin | date/stage unknown; firm classification: Enterprise; Subscription; Application | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 32 | HubPages | date/stage unknown; firm classification: Community; User Generated Content; Advertising | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Mitchell Kertzman as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 33 | Humongous Entertainment | date/stage unknown; firm classification: Consumer; Gaming | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Ann Winblad as board | not publicly established | firm page states acquired by GT Interactive in July 1996; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 34 | Hyperion (Arbor Software) | HWVP funded Arbor in 1991; IPO record points to 1995, not firm page’s erroneous 11/91; Analytics | large future market/technical founder account is retrospective | Fund I; check/security/ownership unknown | firm page and period profile name Ann Winblad/director; IC vote and negotiation unknown | not public | Arbor/Hyperion public; 2007 Oracle deal $52/share, about $3.3bn; no HWVP proceeds | selected Fund I winner in later accounts | contemporaneous record · strong for public chronology; firm-stated · moderate for Ann credit Arbor filing · Oracle exhibit | sufficiently reconstructed |
| 35 | Influitive | date/stage unknown; firm classification: SaaS; Marketing; CMO; Community | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Lars Leckie as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 36 | Infopia | date/stage unknown; firm classification: SaaS; Ecommerce | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 37 | InMage Systems | date/stage unknown; firm classification: Infrastructure; Backup; Storage; Data | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names John Hummer as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 38 | Innovative Leisure | date/stage unknown; firm classification: Mobile; Gaming | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Lars Leckie as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 39 | Intacct | date/stage unknown; firm classification: SaaS; SMB; Financial; ERP | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Ann Winblad as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 40 | Intrinsa | date/stage unknown; firm classification: Tools; Software Development | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Ann Winblad as board | not publicly established | firm page states acquired by Microsoft in June 1999; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 41 | Jamm | date/stage unknown; firm classification: SaaS; Video | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Steve Kishi as board | not publicly established | firm page states acquired by Hopin in February 2021; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 42 | Jareva Technologies | date/stage unknown; firm classification: Infrastructure; Networking; Storage | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | firm page states acquired by Veritas in January 2003; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 43 | Karmasphere | date/stage unknown; firm classification: Analytics; Hadoop; Big Data; Enterprise | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Ann Winblad as board | not publicly established | firm page states acquired by FICO in 2014; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 44 | Kiip | date/stage unknown; firm classification: Mobile; Monetization; Apps; Gaming; Brands | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Lars Leckie as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 45 | Krillion | date/stage unknown; firm classification: Consumer; Search | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Ann Winblad as board | not publicly established | firm page states acquired by Local; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 46 | kwiry | date/stage unknown; firm classification: Analytics | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 47 | Lathian | date/stage unknown; classification not stated | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 48 | Lavastorm Analytics | date/stage unknown; firm classification: Analytics; Billing; Telco | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 49 | Liquid Audio | entry date/stage unresolved; Application/music | original thesis not public | vehicle/check/security/ownership unknown | firm page names Ann Winblad; issuer says former director; investment sponsor/IC role unknown | not public | firm says acquired by Anderson Media; issuer disclosed fiduciary actions dismissed with prejudice under settlement and, separately, a patent suit settled for $150k to Network Commerce; no personal-liability finding | no investment postmortem located | contemporaneous record · strong for issuer disclosure; deal detail insufficient PRE 14A, Legal Proceedings | researched / unresolved |
| 50 | Market Wire | date/stage unknown; firm classification: Application; Content Syndication | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Ann Winblad as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 51 | Marketo | date/stage unknown; firm classification: SaaS; Marketing; CMO | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 52 | Move Networks | date/stage unknown; firm classification: Infrastructure; HTML Streaming; Adaptive Bit Rate; Online Video | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 53 | Moxie Software | date/stage unknown; firm classification: Social; Community; Applications | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Mitchell Kertzman as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 54 | MuleSoft | board tenure from Sep. 2006; Infrastructure / Integration | APIs/service buses/devices/cloud convergence, narrated in 2017 | HWVP V/VI held 17,847,745 shares, 15.7% pre-offering in S-1/A; cost/security sequence incomplete | Winblad director; Hummer/Winblad/Kertzman shared GP power; later sole shares separately reported | V/VI holdings and later in-kind distributions disclosed; full dilution/sales/LP flows unknown | IPO then Salesforce acquisition; no HWVP/personal MOIC computed | five people/four countries pattern story | documented behavior · strong S-1/A, principal stockholders · 13G, Items 5–8 | sufficiently reconstructed |
| 55 | Napster | May 2000; copyright suits already pending; Consumer/file sharing | original thesis not public; adoption and legal path were ex-ante facts | about $13m firm investment; vehicle/security/ownership unknown | firm page names John Hummer; Hank Barry interim CEO; Hummer entities/partners litigated; Winblad email in sanctions record | sale effort to Bertelsmann noted; reserve/dilution unknown | ceased July 2001; litigation/conditional settlement; no personal copyright judgment against Winblad | later public record is legal, not a disclosed IC thesis | contemporaneous record · strong 2005 order, Background · 2006 order, Background/Conclusion | sufficiently reconstructed |
| 56 | Net Perceptions | date/stage unknown; firm classification: Infrastructure; Marketing; Personalization | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Ann Winblad as board | not publicly established | firm page states IPO NETP; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 57 | NetDynamics | date/stage unknown; firm classification: Infrastructure; Application Server | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | firm page states acquired by Sun Microsystems in July 1998; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 58 | Netopia Inc. (formerly Farallon) | date/stage unknown; firm classification: Infrastructure; Collaboration | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | firm page states IPO NTPA; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 59 | NeuVector | date/stage unknown; firm classification: Security; containerization | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Lars Leckie as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 60 | NuoDB | date/stage unresolved; Infrastructure/database/cloud | large market plus technical-founder capability, narrated later | vehicle/check/security/ownership unknown | firm page names Mitchell Kertzman; Winblad narrates example but sponsor unestablished | not public | outcome/economics unresolved | pre-traction exception example | retrospective witness · moderate Full Ratchet · firm page | researched / unresolved |
| 61 | Omniture | April 2004 Series B; June 2005 Series C-1; SaaS/web analytics | original thesis not public | HWVP V bought 13,841,822 B at |
Mark Gorenberg was board nominee/director; later Winblad distribution filing does not make her deal sponsor | 2007 in-kind distribution: fund 362,567; GP 93,362; Winblad received 13,623 and held 61,704 direct; fund retained 6,888,826 | later public/acquired; exact fund return not reconstructable | no Winblad thesis account located | contemporaneous record · strong for financing/governance Omniture S-1, Certain Relationships · Winblad Form 4, transaction/footnotes | researched / unresolved |
| 62 | ontheFRONTIER | date/stage unknown; firm classification: Application; Services | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 63 | OptiMine | date/stage unknown; firm classification: Advertising; Optimization; Analytics; Search | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Ann Winblad as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 64 | Palamida | date/stage unknown; firm classification: Security; Application Security; Open Source Software | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Mitchell Kertzman as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 65 | Pancetera Software | date/stage unknown; firm classification: Infrastructure; Virtualization; Backup; Performance | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Lars Leckie as board | not publicly established | firm page states acquired by Quantum; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 66 | Peerlyst | date/stage unknown; firm classification: Community; Security | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Mitchell Kertzman as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 67 | Pets.com | pre-Feb. 2000 IPO investor; Consumer/ecommerce | original HWVP thesis not public | HWVP III/Technology III entities held 4,677,114 shares (13.5%); cost/security path incomplete | firm page and 10-K identify John Hummer/director; no Ann credit | follow-ons/dilution unresolved | IPO raised ~$75m; operations ceased 2000-11-04; delisted Jan. 2001; initial liquidation distribution $0.09/share | no Winblad lesson or process-change account located | contemporaneous record · strong Pets.com 10-K, business/liquidation/principal holders | sufficiently reconstructed |
| 68 | Piston Cloud | date/stage unknown; firm classification: Infrastructure; OpenStack; Cloud; Orchestration; Dev-Ops | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Lars Leckie as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 69 | PLUMgrid | date/stage unknown; firm classification: Infrastructure; Software Defined Networking; Cloud; OpenStack | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Lars Leckie as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 70 | Powersoft | firm says invested 1991; application-development/database tools | original thesis not public | Fund I reported; check/security/ownership unknown | firm page names John Hummer; Kertzman page narrates investment; no Ann credit | not public | Sybase merger completed Feb. 1995; firm claims $940m but opened SEC filing does not verify value; no HWVP proceeds | selected Fund I winner | contemporaneous record · strong for merger; firm-stated · moderate for John/firm attribution Sybase 10-K, merger discussion | sufficiently reconstructed |
| 71 | Replay Solutions | date/stage unknown; firm classification: Application; Development; Testing | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 72 | Sapias | date/stage unknown; firm classification: Application; Location; Analytics | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Mitchell Kertzman, John Hummer as board | not publicly established | firm page states acquired by Wireless Matrix in July 2007; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 73 | Scalent Systems | date/stage unknown; firm classification: Infrastructure; Datacenter; IT; Provisioning | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | firm page states acquired by Dell; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 74 | Scopus | 1990s; firm category Application / CRM | original thesis not public | vehicle/check/security/ownership unknown | firm page names no board partner; Ann/John attribution unestablished | not public | Siebel acquisition closed May 18 1998; $381.4m transaction value; no HWVP proceeds | selected early win in public narrative | contemporaneous record · strong for exit; attribution insufficient Siebel completion 8-K, Item 5/Ex. 99.1 | researched / unresolved |
| 75 | Sensoria | date/stage unknown; firm classification: Infrastructure; Networking; Mesh Networks | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 76 | SignalDemand | date/stage unknown; firm classification: Analytics; Demand Forecasting; Applications | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 77 | Slate Corporation | Fund I era; pen-based computing/development | buyer/platform readiness later judged premature | Fund I; about $1.2m loss reported; security/ownership unknown | firm page names no board partner; sponsor/stop authority unknown | not public | failed/write-off; Wired reports about $1.2m lost | 13-years-early (2004) versus 25-years-early (2012) | retrospective witness · moderate; reported loss · moderate Stanford · Wired 1996 | sufficiently reconstructed |
| 78 | SlideRocket | date/stage unknown; firm classification: SaaS; Presentation Software; Analytics | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Mitchell Kertzman as board | not publicly established | firm page states acquired by VMware; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 79 | Smart Access | date/stage unknown; firm classification: SaaS; Mobile | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Lars Leckie as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 80 | Sonatype | date/stage unknown; firm classification: Infrastructure; Developer; Code Repository; Open Source Software | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Ann Winblad as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 81 | Stackery | date/stage unknown; firm classification: Cloud; Developer | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Steve Kishi as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 82 | StackMob | date/stage unknown; firm classification: Mobile | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 83 | Star Analytics | date/stage unknown; firm classification: Analytics; Finance; Applications | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Ann Winblad as board | not publicly established | firm page states acquired by IBM in March 2013; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 84 | Starmine | date/stage unknown; firm classification: Application; Finance; Analytics | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names John Hummer as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 85 | StepFunction | date/stage unknown; firm classification: SaaS; Big Data | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Steve Kishi as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 86 | Strobe | date/stage unknown; firm classification: Mobile; HTML5; Cross Platform; Infrastructure | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Lars Leckie as board | not publicly established | firm page states acquired by Facebook; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 87 | Symbium | date/stage unknown; classification not stated | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Lars Leckie as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 88 | T/Maker | 1989-11-01; Series A; firm category Personal Computer / Content | original thesis not public; operating-network sourcing documented later | Fund I; reported $300k lead versus $750k in another profile; security/ownership unknown | firm page names Ann Winblad; Winblad says she joined board; Heidi/Peter Roizen founders; IC vote unknown | not public | firm page says acquired by Deluxe June 1994; reported 3x in 2019 versus 5x in 2004 | first HWVP investment in later accounts | retrospective witness · moderate; economics provisional 2019 essay · Stanford introduction page, inline transcript | sufficiently reconstructed |
| 89 | The Knot | by 2005 public-company ownership filing; entry date/stage unknown | original thesis not public | HWVP III and Technology Fund III shares; original cost/ownership history unresolved | Winblad director/10% owner and managing member of GP; disclaims beyond pecuniary interest | 2005-04-14 sales of 27,313 + 1,437 shares at $7.60–$7.85; 2,290,995 +120,580 remained | public company; whole-fund economics unknown | no deal-specific thesis located | contemporaneous record · strong Form 4, transaction table/footnotes | sufficiently reconstructed |
| 90 | TidalScale | date/stage unknown; firm classification: Infrastructure; Virtualization; Analytics; Cloud; Scale-Out | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Lars Leckie as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 91 | Tizor | date/stage unknown; firm classification: Security; IT; Datacenter; Appliance | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 92 | Viewpoint Datalabs | date/stage unknown; classification not stated | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 93 | VKernel | date/stage unknown; firm classification: Infrastructure; Virtualization; Systems Management; High Velocity | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Mitchell Kertzman as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 94 | Voltage Security | 2003 co-investment; enterprise security/encryption | customer-budget validation described in 2005 | HWVP + Morgenthaler; check/security/ownership unknown | firm page names Ann Winblad; decision rights unknown | not public | firm page says HP acquired it in 2015; economics unknown | CIO interviews used as diligence example | retrospective witness · moderate for thesis; firm-stated · moderate for outcome WilmerHale, pp. 17–18 · firm page | researched / unresolved |
| 95 | WaveMaker | date/stage unknown; firm classification: Infrastructure; Application Development; Open Source; AJAX | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Mitchell Kertzman as board | not publicly established | firm page states acquired by VMware; economics unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 96 | Wind River | second firm investment; reported $1m; embedded development | original thesis not public; timing contrast is retrospective | Fund I; $1m reported; security/ownership unknown | firm page names John Hummer; no Ann credit | not public | Intel acquisition completed 2009 for $884m; no HWVP proceeds | later contrasted with Slate as timing success | contemporaneous record · strong for exit; reported · moderate for entry Intel 10-Q, MD&A/acquisition · St. Thomas | sufficiently reconstructed |
| 97 | XANT | date/stage unknown; firm classification: SaaS; Sales Acceleration; Utah; CRM | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names Lars Leckie as board | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
| 98 | Yosemite Technologies | date/stage unknown; firm classification: Infrastructure; Backup | original thesis not publicly established | vehicle/check/security/ownership unknown | firm page names no board person; individual credit unknown | not publicly established | unknown | firm bio is retrospective marketing, not an IC record | firm-stated · moderate; deal detail insufficient public record firm page | firm-page-only unresolved |
Ex-ante forensic case studies and decision labs
T/Maker — first-check discipline and network sourcing
Frozen information set, 1989. Winblad knew Heidi Roizen from the software operating community; the product/company existed, but the public record does not preserve the investment memorandum, alternatives, valuation, ownership, or dissent. Winblad dates a $300,000 Series A lead check and her board start to 1989-11-01; another profile reports $750,000, so tranche versus total capital remains unresolved. Winblad 2019, T/Maker paragraphs · St. Thomas profile Retrospective witness · moderate.
Reader exercise.
- Would you invest then? Only if the customer/use case and founder reference network survive independent validation; friendship is sourcing, not diligence.
- What would kill the deal? No repeatable buyer, services-heavy economics, or a financing plan that exceeds a small Fund I reserve budget.
- What ownership/terms fit the risk? Analyst-created prompt: price a staged Series A against uncertain adoption and reserve needs; the historical terms are unknown.
- What evidence unlocks the next check? Paid-customer cohort, product usage, hiring plan, and a milestone-linked capital budget.
Actual decision and outcome. HWVP invested and Winblad joined the board. Later Winblad accounts call the result 3x (2019) and 5x (2004); without cash flows, both remain reported and unreconciled. Stanford introduction page, inline transcript Investor-stated · provisional.
Fund I winners — deal-by-deal attribution and outcome controls
Hyperion/Arbor
HWVP funded Arbor in 1991 and firm/period sources name Winblad as director. The firm page’s “IPO: HYSL, 11/91” is wrong: Arbor’s SEC record references its Form 8-A in September 1995 and an amendment that November. Oracle later agreed to pay $52 per share, about $3.3 billion, in 2007. Arbor filing, registration history · Oracle exhibit, transaction summary Contemporaneous record · strong for public chronology; firm-stated · moderate for Ann attribution. Entry price, ownership, dilution, distributions, and personal return remain unknown.
Powersoft
Firm records say the investment was made in 1991 and name John Hummer, not Winblad, as the board partner. Sybase’s filing confirms the February 1995 merger and describes Powersoft as an application-development-tools supplier. Powersoft firm page · Sybase 10-K, merger discussion The firm’s $940 million outcome claim was not verified in the opened SEC filing. Documented behavior · strong for firm/John credit; economics remain insufficient.
Wind River
A 2000 profile calls Wind River the firm’s second investment and reports a $1 million check; the official page names John Hummer. Intel’s 2009 10-Q reports completing the acquisition for $884 million. St. Thomas profile · Wind River firm page · Intel 10-Q, acquisition discussion Reported entry · moderate; contemporaneous exit · strong. No public ownership/dilution/distribution trail turns $1 million and $884 million into an HWVP MOIC.
Scopus Technology Group
The official page names no partner. Siebel’s completion filing says the acquisition closed May 18, 1998, issued about 15.1 million shares, reserved 2.6 million shares for options, and had a $381.4 million value at that day’s close. Siebel completion 8-K, Item 5 and Exhibit 99.1 Contemporaneous record · strong for outcome; sponsor, vehicle, basis, and firm proceeds are insufficient.
Grouped reader exercise.
- Would you invest then? Only after reconstructing each buyer workflow and technical transition; the later winners cannot substitute for contemporaneous evidence.
- What would kill the deal? No budget owner, incompatible platform timing, or a capitalization plan beyond Fund I reserves.
- What ownership/terms fit the risk? Analyst-created prompt: stage capital against customer and product milestones; historical terms are unknown.
- What evidence unlocks the next check? Customer commitments, technical benchmarks, repeatable sales, and fund-reserve capacity.
Actual decisions and outcomes. HWVP invested in all four; public-market/acquisition outcomes followed. Credit differs—Ann for Hyperion, John for Powersoft/Wind River, unassigned for Scopus—and no company-level fund return is reconstructable. This is why they remain one economic cluster but separate attribution cases.
MuleSoft — shared governance, long duration, and pattern convergence
Frozen information set, 2006. Winblad later recalled five employees across four countries describing APIs, service buses, devices, and cloud applications before the connected world was obvious. That is useful direct voice but retrospective, not the original memo. OnlineEducation, MuleSoft paragraphs The S-1 establishes Winblad’s board service from September 2006 and HWVP V/VI holdings; the 13G later attributes possible shared voting/dispositive power to Hummer, Winblad, and Kertzman. S-1/A, directors/principal stockholders · 13G, Items 4–6 Documented behavior · strong for governance/vehicle; retrospective witness · moderate for thesis.
Reader exercise.
- Would you invest then? If multiple buyer workflows converge on an API/integration bottleneck and the distributed team can ship securely.
- What would kill the deal? No budget owner, standards/platform disintermediation, or distributed execution failure.
- What ownership/terms fit the risk? Analyst-created prompt: seek board information rights and milestone reserves; historical security and cost are unknown.
- What evidence unlocks the next check? Referenceable integrations, developer adoption, enterprise pipeline, and a repeatable deployment model.
Actual decision and outcome. HWVP V/VI invested; Winblad joined the board; MuleSoft later went public. MuleSoft S-1/A, directors and principal stockholders No personal or fund MOIC is computed because cost, dilution, distributions, and shared credit are incomplete.
Omniture and The Knot — filings reveal mechanics, not original theses
Omniture’s S-1 records HWVP V buying 13,841,822 Series B shares in April 2004 at about $0.96 (about $13.3 million) and 3,228,811 Series C-1 shares in June 2005 at about $2.58 (about $8.34 million); it names Mark Gorenberg as board nominee/director. Winblad’s 2007 Form 4 documents an in-kind/GP distribution and 13,623 shares received, not sourcing credit. Omniture S-1, Certain Relationships · Winblad Form 4, transaction table/footnotes Contemporaneous record · strong. Exact fund return remains unavailable.
The Knot’s 2005-04-15 filing covers 2005-04-14 sales: HWVP III and Technology Fund III sold 27,313 and 1,437 shares at $7.60–$7.85 while retaining 2,290,995 and 120,580. Winblad is identified as director/10% owner and managing member, with a pecuniary-interest disclaimer. The Knot Form 4, transaction table/footnotes Contemporaneous record · strong for vehicle/governance; original cost, thesis, dilution, and whole realization remain unknown.
Reader exercise.
- Would you invest then? The filings cannot answer; demand the original customer, product, and competitive evidence rather than back-solving from exits.
- What would kill the deal? No durable buyer budget, platform displacement, or ownership too small for the required governance/capital.
- What ownership/terms fit the risk? Analyst-created prompt: model later dilution and reserve needs; surviving filings show shares but not the negotiated decision logic.
- What evidence unlocks the next check? Financing documents, cohort/unit economics, board materials, and a distribution waterfall.
Actual decisions and outcomes. HWVP V financed Omniture with Gorenberg as the documented board partner; HWVP III vehicles held and sold The Knot shares with Winblad as director/managing member. The record supports different partner credit and forbids turning either exit headline into Winblad personal return.
Voltage Security — an ordinary diligence case with bounded outcome
In 2003 HWVP and Morgenthaler co-invested in Voltage. Winblad later described bringing the team to roughly twenty CIO organizations and asking buyers whether the problem reached a budget line; the firm page names Winblad and says HP acquired Voltage in 2015. WilmerHale, printed pp. 17–18 · Voltage firm page This is retrospective witness · moderate for diligence and firm-stated · moderate for outcome; terms and economics are unknown.
Reader exercise.
- Would you invest then? If target CIOs identify a funded encryption/compliance problem and the product integrates into existing systems.
- What would kill the deal? Praise without budget, unmanageable deployment friction, or incumbent bundling.
- What ownership/terms fit the risk? Analyst-created prompt: milestone capital and information/board rights; historical terms are unknown.
- What evidence unlocks the next check? Paid pilots, implementation time, renewal evidence, and security validation.
Actual decision and outcome. HWVP/Morgenthaler invested; the firm identifies Winblad and a 2015 HP acquisition. No return or personal proceeds are claimed.
Slate — full failure decision lab
Frozen information set. The surviving record says Slate attempted a pen-computing-era software product that Winblad later judged far too early. It does not preserve date, check, ownership, named partner vote, customer evidence, milestones, or the stop decision. Stanford, “Are Technologies Ahead of Their Time?” · Berkeley oral history, printed pp. 21–23 The “13 years” versus “25 years” estimates conflict; the only safe conclusion is a retrospective timing failure. Investor-stated · moderate.
Reader exercise.
- Would you invest then? Only with evidence that hardware distribution, input quality, and a buyer budget exist now—not merely that the product eventually should exist.
- What would kill the deal? Required platform penetration lies beyond the fund’s reserve horizon; customers admire the demo but will not deploy/pay.
- What ownership/terms fit the risk? Analyst-created prompt: small staged capital with explicit platform/customer gates; historical terms are unknown.
- What evidence unlocks the next check? Paid pilots, compatible installed base, repeat usage, and a distribution partner with committed launch milestones.
Actual decision and outcome. HWVP invested; Winblad later classed Slate as a failure/write-off and contrasted it with Wind River. No public record establishes whether the thesis changed, a pivot was attempted, follow-on capital stopped, or a process change followed. The lesson is therefore retrospective witness · moderate, not documented ex-ante discipline.
Pets.com — ordinary dot-com failure and attribution lab
Frozen information set. HWVP entities were material pre-liquidation holders and John Hummer, not Winblad, was the documented director. The 10-K reports that the February 2000 IPO raised about $75 million; it does not provide HWVP’s original memo, entry cost, follow-on vote, or reserve plan. Pets.com 10-K, business/principal holders Contemporaneous record · strong.
Reader exercise.
- Would you invest then? Only if contribution margin, fulfillment density, repeat purchase, and cash runway support the distribution buildout.
- What would kill the deal? Negative unit economics that do not improve with density, paid acquisition outrunning repeat value, or financing dependence beyond reserves.
- What ownership/terms fit the risk? Analyst-created prompt: stage capital against geographic density and contribution milestones, with liquidation/downside protections appropriate to inventory and fulfillment risk.
- What evidence unlocks the next check? Cohort retention, delivery economics, inventory turns, cash conversion, and a downside liquidity plan.
Actual decision and outcome. HWVP III/Technology entities collectively held 4,677,114 shares (13.5%). Pets.com ceased operations on 2000-11-04, was delisted in January 2001, and announced an initial $0.09-per-share liquidation distribution. Pets.com 10-K, cessation/liquidation/principal holders This is a firm/John loss case; no Ann Winblad personal miss or loss is inferred.
Napster — legal-operability and governance failure lab
Frozen information set, May 2000. Napster had explosive adoption and multiple copyright lawsuits were already pending. Hummer invested approximately $13 million, entered a common-interest defense agreement, and placed partner Hank Barry as interim CEO. 2005 order, Background pp. 3–4 · 2006 sanctions order, Background pp. 3–5 The record does not disclose the IC memo, ownership, security, liquidation preference, reserve, legal probability model, dissent, or an option-value plan. Contemporaneous record · strong for the known risk and firm action; insufficient public record for the original thesis.
Reader exercise.
- Would you invest then? Only if a licensed/legal operating path has a credible probability and governance rights can enforce the transition.
- What would kill the deal? No licensable unit economics, injunction risk that disables the core service, or discovery/preservation controls below litigation-grade standards.
- What ownership/terms fit the risk? Analyst-created prompt: tranched capital, reserved legal budget, board/control rights, compliance covenants, and financing conditional on licensing milestones; historical terms are unknown.
- What evidence unlocks the next check? Signed or term-sheet-level rights-holder agreements, legal opinions, conversion economics, preservation protocol, and board-approved contingency plan.
Actual decision, intervention, and outcome. Hummer invested; Barry ran Napster on an interim basis. Napster ceased operations in July 2001 after injunction-related failure. In 2006 the court held that Hummer had a preservation duty, rejected default, but granted preclusion, an adverse-inference instruction, and attorneys’ fees. The order discusses Winblad’s June 3 email, but the sanctioned defendant was Hummer; it is not a personal copyright-infringement adjudication against Winblad. 2006 sanctions order, Duty to Preserve, Sanctions, and Conclusion A conditional settlement with Universal/EMI followed on undisclosed terms. Los Angeles Times, 2006-12-13 Contemporaneous record · strong for procedure; settlement economics and personal liability remain insufficient.
Portfolio-level forensics
- Stage: public statements describe early-stage/Series A emphasis and co-leading, but the 98 directory does not encode stages. Stanford introduction page, inline transcript Investor-stated · moderate.
- Sector: the directory is overwhelmingly software/internet infrastructure, consistent with the mandate; the presence of Dean & Deluca, HomeGrocer, and Pets.com shows the category perimeter broadened during the internet era. Researcher inference · strong for displayed names, provisional for original underwriting categories. Official directory
- Geography: MuleSoft’s distributed founding team and several later company routes imply cross-border operating exposure, but no complete headquarters-at-entry field exists. Researcher inference · insufficient public record.
- Ownership/check size/reserves: apart from T/Maker’s conflicting $300k/$750k reports and Napster’s ~$13m total, the researched record does not support a distribution. No concentration or reserve ratio is computed.
- Governance: board/director evidence is strongest for T/Maker, MuleSoft, The Knot, Liquid Audio, and Napster operating intervention; directory presence alone supplies none.
- Directory detail coverage: all 98 official detail pages were processed; 66 name a board person, 88 carry a category label, and 35 contain a parseable IPO/acquisition/merger phrase. These are firm-stated retrospective fields, not independent proof of decision credit or economics. Official directory Firm-stated · moderate.
- Outcomes: public-company and acquisition stories are selected. The directory retains Slate, Napster, Liquid Audio, Pets.com, and HomeGrocer, but the missing 150-plus remainder and first-party curation still create selection/survivorship bias.
- Fund performance: Fund I appears strong on reported absolute distributions; the one LP-specific HWVP III record is near cost; the discounted secondary HWVP V record is strong for that buyer. These three incompatible bases argue against a single firm IRR claim.
Failure, miss, and legal postmortems
Liquid Audio — shareholder allegations, dismissal, and a separate patent settlement
Liquid Audio’s 2003 preliminary proxy describes 2001 fiduciary-duty complaints, Winblad as a former director, and dismissal of those actions with prejudice under a January 2, 2003 settlement agreement. It separately describes a patent action settled by a $150,000 company payment to Network Commerce. Liquid Audio PRE 14A, “Legal Proceedings” and board disclosures The $150,000 figure therefore does not quantify the shareholder-litigation settlement. The filing supports an adverse governance route and precise procedural boundary; it does not establish the truth of every allegation, a personal payment, or personal liability. The original investment thesis, early warnings, board response, and investment economics remain insufficient public record.
Pets.com and HomeGrocer — anti-survivorship boundaries
Pets.com’s primary record now establishes firm-level facts: HWVP III/Technology entities held 13.5%, John Hummer was the documented director, operations ceased in November 2000, delisting followed in January 2001, and the initial liquidation distribution was $0.09 per share. Pets.com 10-K, business/liquidation/principal holders It does not establish Winblad’s role, original check/cost, follow-ons, realized fund loss, stop decision, or process change. HomeGrocer remains separately attributable to John only through the firm page and lacks equivalent primary investment mechanics. HomeGrocer firm page These are documented behavior · strong for the named firm/John facts and researcher inference · provisional for the broader category-risk lesson; neither supports a personal Winblad miss.
Napster — process change not publicly demonstrated
The sanctions record shows a records-preservation failure after known litigation risk and a June 3, 2000 email the court interpreted adversely. 2006 order, pp. 17–25 and Conclusion Public later interviews discuss failure tolerance, but no policy, LP letter, IC rule, or board-protocol change has been found. Claiming “Napster taught Winblad X” would therefore be researcher inference · insufficient public record.
Uncertainty and retrieval ledger
Saturation searches
site:sec.gov/Archives/edgar/data "Hummer Winblad Venture Partners" "T/Maker"→ no T/Maker filing or Fund I economics; only the already-known The Knot Form 4 resurfaced.site:sec.gov/Archives/edgar/data "Hummer Winblad Venture Partners III" investment→ recycled The Knot and other portfolio-company filings; no 16-company Fund I schedule or new fund-level economics."Hummer Winblad Venture Partners" ("investment memorandum" OR "quarterly report" OR "LP letter") filetype:pdf→ no public HWVP investment memo, LP letter, or fund quarterly report; only unrelated portfolio/holding reports.
The last three searches added no material new deal. The bounded public frontier now includes all 98 live firm pages, selected issuer filings, public-LP records, Form ADV/Form D records, court orders, and direct voice; remaining fund economics require nonpublic LP statements, cap tables, capital accounts/carry records, investment memoranda, or archives.
| Gap | Routes attempted / result | What would change the assessment |
|---|---|---|
| Full historical denominator | Canonical 98-company directory reconciled against dated 16/~80/>90/100+/150+ claims; old /companies/index.html is dead and canonical /companies/ works |
Archived portfolio snapshots, firm CRM/export, fund-by-fund schedules, or LP annual reports naming omitted companies |
| Fund I economics | 1996 Wired, 2005 WilmerHale, 2019 signed retrospective, Berkeley oral history; bases conflict | Audited financials/cash-flow schedule separating commitment, investable capital, fees, recycling, distributions, gross/net IRR |
| Fund I attribution | Direct voice names selected companies; no complete memo/board/partner record | IC minutes, deal memos, founder/partner testimony, cap tables, board minutes |
| Later-fund series | UC HWVP III LP row; SDCERS HWVP V secondary; StrictlyVC fund-size/uneven-return report | Same-basis original-LP cash flows for Funds II–VII and partnership agreements |
| Company economics | SEC filing routes for MuleSoft, The Knot, Omniture; ownership snapshots lack cost/distributions | Financing-round cap tables, follow-on schedules, distribution notices, exit waterfalls |
| Napster | Two federal orders, Ninth Circuit related appeal, contemporaneous settlement reports | IC memo, board minutes, legal diligence, insurance/indemnity records, final settlement terms, postmortem/process-change memo |
| Liquid Audio | Issuer proxy describes fiduciary allegations/dismissal and a separate patent settlement | Fiduciary settlement agreement, court approval, insurer/allocation records, board minutes |
| Ordinary and failed cases | Current directory searched; Slate, Pets.com, HomeGrocer, Liquid Audio, and Napster retained | Write-off schedules, reserve decisions, founder interviews, shutdown/exit files |
| Personal Winblad record | Board/manager filings and direct voice reviewed; no independently audited personal series | Carry allocations, personal investment schedule, realized distributions, or verified partner attribution |
No MOIC is inferred from entry and exit valuations. No vehicle return is assigned personally to Winblad. The public record is strongest on firm inclusion, selected board roles, isolated holdings snapshots, two LP-specific observations, and Napster procedure; it remains weakest on original theses, decision rights, ownership/cost, dilution, reserves, ordinary outcomes, and cash distributions.
Coverage and evidence base
The inspected corpus contains nine distinct items. Five are priority writing candidates inherited from SCOUT; three additional LinkedIn articles were discovered during the exact-author sweep; one WIRED feature contains two Winblad-attributed comments but is not Winblad-authored. Four works are available in full as Winblad-authored text; one source is a full edited Q&A, one is a full short staff-attributed contribution, one is a partial reprinted excerpt, and two are metadata-only. “Processed” means the legitimate available record and its boundary received a source note; it does not turn metadata into content.
| Item | Attribution and priority | Access as re-opened through 2026-08-22 | Analytical treatment |
|---|---|---|---|
| “Auditioning the Future of Software”, 2019 | Winblad-authored, ★★★ | Full/dynamic | Deep analysis; anniversary selection bias and performance conflicts preserved |
| Object-Oriented Software, 1990 | Winblad/Edwards/King, ★★★ | Metadata-only | Bibliographic and biographical boundary only; no content analysis |
| “A Just-in-Time Software-Based World”, 2001 | Gorenberg/Winblad, ★★ | Metadata-only | DOI/authorship/access boundary only; no title-based thesis |
| “Entering the Enterprise Era”, 1992 | Winblad-authored, ★★ | Partial: two-paragraph reprint | Bounded argument analysis of the surviving excerpt |
| WilmerHale Q&A, 2005 | Edited interviewer-led direct voice, ★★★ | Full, printed pp. 16–21 | Deep hybrid analysis; never presented as authored prose |
| “Street Cred: ReadMe”, 1997 | WIRED Staff feature; two Winblad comments, ★ | Full short contribution | Bounded cultural signal, not a signed essay |
| “Lessons From A Giant”, 2012 | Winblad-authored, ★★ | Full | Leadership analogy organized around four explicit headings |
| “Ads Worth Sharing”, 2012 | Winblad-authored, ★ | Full | Marketing/measurement record; treated separately from investing evidence |
| “Class of 2013: Don’t Sweat Your First Job”, 2013 | Winblad-authored, ★ | Full/dynamic | Deep career-learning analysis and early-biography cross-check |
The five original priority candidates therefore reconcile as: two full-text records (2019 and WilmerHale), one partial excerpt (1992), and two metadata-only works (1990 and 2001). The expanded nine-item corpus adds three full LinkedIn articles and the full but very short WIRED-attributed contribution. Notes preserve the distinction between authorial, coauthored, edited-interview, and attributed-comment evidence.
Source-by-source analysis
“Auditioning the Future of Software: A 30 Year Journey” (2019)
Context and argument. On Hummer Winblad’s thirtieth anniversary, Winblad reconstructs the firm’s origin as a category-specialization bet: software looked too narrow and intangible to LPs; repeated rejection forced the founders to borrow credibility from established investors and Minnesota institutions; a selected Fund I outcome then made the category investable. She dates the first fund’s close to September 1989 and T/Maker’s $300,000 Series A and her first board seat to November 1. Winblad 2019, paragraphs beginning “Thirty years ago” and “We had closed”
Reasoning and evidence. The essay’s causal chain is: operator specialization enabled a defensible software-only mandate; the mandate differentiated deal flow; leading early rounds created governance access; and a 16-company portfolio produced enough visible exits to convince LPs. Winblad 2019, paragraphs beginning “Fund I” and “We had unique” That is investor-stated · moderate as a description of intended mechanism. It is not strong causal evidence because the anniversary sample foregrounds Hyperion, Wind River, and Powersoft while omitting losses, later fund dispersion, partner assignment, and the full denominator.
Assumptions and rules. Specialization works in her account when the category is large enough to yield many independent companies, technical experience is scarce, and generalist capital discounts an intangible asset base. Leading the first venture round before ten employees is presented as the durable operating position. Winblad 2019, paragraphs beginning “Our focus today” and “In our early years” Investor-stated · strong for the 2019 stated mandate; documented behavior · insufficient public record for consistency across all 150-plus firm-level companies.
Biography and evolution. The essay assigns critical roles to John Hummer, Pitch Johnson, Bill Edwards, Don Valentine, Jerry Okerman, 3M, and a Minnesota insurer. That makes the origin an access-and-endorsement story as well as a picking story. It also says the remit narrowed over time from enterprise plus some consumer software to enterprise only. Winblad 2019, paragraphs beginning “When it seemed” through “In our early years” Researcher inference · moderate: focus was not static; the firm concentrated further after observing the expanding enterprise market.
Contradictions. The reported $27 million investable / $252 million returned / six IPOs cannot be silently combined with the 2005 $35 million / over-10x account. Winblad 2019, “Fund I” paragraph · WilmerHale Q&A, printed p. 17 The essay’s “over 130” LP pitches conflicts narrowly with 130 in 2005 and 133 in the oral history; six IPOs conflicts with retrospective accounts that half of 16 became public; “State Farm Insurance” conflicts with St. Paul Companies; and T/Maker at 3x conflicts with a 5x Stanford recollection. These are unresolved bases, not arithmetic errors proven by the public record.
WilmerHale’s edited Q&A (2005): the fullest operational text
Context and form. The 2005 compensation study contains an interviewer-led Q&A across printed pages 16–21. It is direct voice shaped by Aaron’s questions, not an authored essay. The post-dot-com setting matters: Winblad contrasts software capital scarcity at the firm’s launch with the 2000 funding surge and subsequent contraction. WilmerHale Q&A, printed pp. 16–17
Argument and reasoning. Winblad argues that capital abundance can make money a commodity, inflate talent and infrastructure costs, accelerate A-round decisions, and weaken early-stage selection. Scarcity restores “fast no’s” and “slow yes’s,” giving investors time for diligence, operating-plan refinement, and customer access. WilmerHale Q&A, printed p. 17 / PDF p. 18 This is investor-stated · strong as her 2005 cycle rule; researcher inference · provisional as a general performance claim because no accepted-versus-declined cohort is shown.
Evidence and examples. She uses the first fund—reported $35 million, 16 companies, over 10x—and Powersoft, Wind River, and Hyperion/Arbor to argue that downturns can improve entrant access when incumbents are encumbered. WilmerHale Q&A, printed p. 17 These are selected winners and self-reported economics. Investor-stated · moderate. Slate, Napster, ordinary companies, and weak fund vintages are absent.
Company-building model. The board’s core responsibility is selecting and evaluating the CEO. Product marketing must arbitrate between customer, sales, and engineering; finance should arrive before public-company controls become urgent. Voltage is the worked example: first-time CEO Sathvik Krishnamurthy is paired with experienced director Srivats Sampath, while marketing is recruited before the CEO when the right candidate is available. WilmerHale Q&A, printed pp. 18–19 Investor-stated · moderate for the rule and example; outcome attribution needs company records and other witnesses.
Partnership and governance. She reports syndicating about 80% of A rounds, selecting co-investors for compatible work, and assigning the firm partner best fitted to the founder and board rather than automatically rewarding the sourcer. WilmerHale Q&A, printed p. 19 Investor-stated · strong for described practice; documented behavior · insufficient public record without investment-committee and board-assignment records. This is the corpus’s clearest antidote to lone-investor attribution.
Industry architecture. Large technology companies appear as customers, channel partners, talent pools, and likely acquirers. Winblad calls venture-backed startups a form of industry R&D and describes increasingly global engineering teams. WilmerHale Q&A, printed pp. 20–21 Investor-stated · moderate: corporate adjacency is a plausible go-to-market and exit mechanism, but the interview does not quantify dependence or conflicts.
“Entering the Enterprise Era” (1992): a migration lens, from an excerpt
Access boundary and context. The Computer History Museum PDF is a 111-page periodical compilation. At PDF page 66 / Hotline on Object-Oriented Technology printed page 23, it reproduces only two paragraphs attributed to Winblad’s August 3, 1992 Computerworld article—not the full essay. CHM compilation, PDF p. 66, “STRATEGIES”
Bounded argument. The excerpt acknowledges that C++ class hierarchies added design, coding, debugging, and management complexity, then says improving tools, class libraries, operating systems, APIs, and foundation classes were mitigating those costs. It pairs that progress with a warning: legacy code and programmer training are sunk intellectual investments, so companies that ignore enterprise computing and object architectures risk being trapped between regimes. CHM compilation, PDF p. 66
Decision implication. The supportable historical rule is not “always adopt the new architecture.” It is: underwrite both ecosystem maturity and migration burden; a technically superior architecture can fail if tools and installed-base bridges are weak. Researcher inference · moderate. The source contains no deal application, and the full article could qualify the excerpt.
Evolution. This 1992 text supplies an earlier, more technical version of the 2005 customer-and-market fit language: architecture matters when it becomes deployable inside existing organizations. Chronological consistency is researcher inference · provisional, because the 1990 book and 2001 article cannot yet be read.
“Street Cred: ReadMe” (1997): attributed recommendations, not a signed essay
WIRED Staff introduces Winblad and prints two attributed recommendations. Her Oscar Wilde comment values economical communication; her Katharine Graham comment emphasizes patience and long-lived institutions, observing that such an enterprise is not built in five years. WIRED Staff, Winblad paragraphs The latter is investor-stated · moderate as an expressed admiration and documented behavior · insufficient public record as an actual holding-period rule. A reading preference cannot overcome fund-duration, exit, or later retrenchment evidence. The source’s use is cultural and biographical, not track-record proof.
“Lessons From A Giant” (2012)
Context and argument. Winblad begins with Minnesota baseball and the 2012 San Francisco Giants, then uses manager Bruce Bochy’s championship season to argue that winning teams combine forward attention, calm confidence, urgent situational decisions, role flexibility, shared purpose, and joy. The explicit sequence is “Focus Forward” → “Stay Calm But Manage with Urgency” → “Choose the Best Team not Just Top Players” → “Find Joy in the Game.” Winblad 2012, body lines 29–59 and section headings Investor-stated · strong for the leadership framework; it is not stated as an investment rule.
Reasoning and evidence. “Focus Forward” uses injuries, Melky Cabrera’s suspension, competitor trades, and recovery from a 1–3 postseason deficit to distinguish the shock from the team’s response. “Stay Calm” pairs Bochy’s patience with struggling players with continued tactical decisions; Winblad points to a bullpen that produced 53 saves and ranked second despite losing its star closer. Winblad 2012, “Focus Forward” and “Stay Calm,” lines 34–42 The mechanism she proposes is setbacks → confidence and attention control → urgent role/tactic adjustment rather than panic.
“Choose the Best Team” supplies heterogeneous examples: Sandoval’s star output, Scutaro’s journeyman contribution, Lincecum accepting a move from starter to reliever, and Pence reinforcing collective purpose. The Dodgers are the negative control: buying prominent talent did not rapidly produce integration. Winblad 2012, “Choose the Best Team,” lines 44–52 Her claim is not that stars are irrelevant; it is that talent, role acceptance, and cohesion are complements. “Find Joy” adds fan and family identity as reinforcement for effort and belonging. Winblad 2012, lines 54–59
Assumptions and boundary. The essay assumes lessons from a selected champion can transfer to organizations with very different contracts, feedback cycles, and founder authority. Outcome selection makes successful patience look prescient, and “calm but urgent” supplies no stopping rule for an irrecoverable slump. Researcher inference · strong for those evidentiary limits. Team cohesion can also suppress dissent; the article does not address that failure mode.
Decision implications and evolution. A bounded board diagnostic follows: after a shock, ask whether leadership updates the next decision, preserves confidence without concealing evidence, reassigns roles when necessary, and keeps individual status subordinate to the shared objective. Researcher inference · moderate. The framework extends the 2005 Q&A’s executive-ensemble, partner-fit, and ego-suppression language rather than introducing a new picking rule. WilmerHale Q&A, printed pp. 18–20
“Ads Worth Sharing: Measuring Extraordinary Creative” (2012)
Context and argument. Written immediately after the 2012 US election advertising barrage, the essay rejects the simple premise that audiences have uniformly short attention spans. Winblad argues that people have limited attention for distractions but will spend time on idea-driven content that delights, informs, or frightens. Winblad 2012, body lines 28–31 Investor-stated · strong for her marketing thesis.
Reasoning and evidence. TED’s Ads Worth Spreading program combines six expert committees with Ace Metrix responses from more than 500 ordinary US viewers. Winblad reports that all ten selected ads beat the attention norm, nine beat the likeability norm, and the group averaged roughly 4.5 times the length of a normal television commercial. Winblad 2012, lines 32–34 Mazda, Sharpie, and L’Oréal are her examples of longer stories scoring around the 90th percentile for authenticity and improving brand perception for more than 60% of respondents; Prudential illustrates heterogeneous emotional response. Winblad 2012, lines 34–35 She reports 70% average stated willingness to share, mostly verbally, with Facebook and email secondary. Winblad 2012, line 36
The reasoning chain is expert judgment + audience measurement → evidence that length can work when ideas and authenticity earn attention → sharing intent and changed brand perception. It is investor-stated · moderate because Winblad is summarizing TED/Ace Metrix, not reporting her own study.
Assumptions and boundary. The ten ads were already selected; the article does not supply an unfiltered denominator, sampling design, uncertainty, spend, or experimental incrementality. Attention, likeability, authenticity, stated sharing, observed sharing, conversion, retention, and revenue are different measures. Longer examples succeeding does not show length caused success. These are researcher inference · strong limitations on the evidence.
Decision implications and evolution. The transferable diligence rule is to pair expert product judgment with explicit customer-response measures and define the outcome beyond attention. Ask: what behavior does the narrative change, against what baseline, and does the signal reach purchase or retention? Researcher inference · moderate. This complements the 2005 claim that product marketing should mediate sales and engineering by listening to the customer, but no public record shows Hummer Winblad applying Ace-style tests in investment selection. WilmerHale Q&A, printed p. 18
“Class of 2013: Don’t Sweat Your First Job” (2013)
Context and argument. The signed 2013 essay, adapted from Winblad's spring 2001 University of St. Thomas commencement address, argues against treating the first job as the full return on education. She contrasts increasing graduate focus on immediate earnings with a longer-horizon return from critical thinking, problem solving, openness to ideas, and lifelong learning. Winblad 2013, paragraphs beginning “Given the shift” and “While it looks” Investor-stated · strong for her career-learning thesis.
Reasoning and evidence. Her autobiographical chain is concrete: she intended to study mathematics, discovered programming through an elective, took all computing classes offered because the school had no computer-science major, added business administration because she did not know what job she would pursue, joined the Federal Reserve Bank of Minneapolis as a systems analyst, and left after a little over a year to start Open Systems. Winblad 2013, paragraphs beginning “I graduated” and “I was fortunate” This independently reopens the package's degree and early-work chronology through Winblad's direct recollection, while diploma, employment, and incorporation records remain unavailable.
Assumptions and decision implications. The essay assumes general learning capacity compounds across career changes and that a salary drop can buy a better-fit path. The bounded modern rule is to evaluate the option value of skills, mentors, and problem domains alongside first-job pay, not to claim that first jobs never matter. For founder diligence it supplies a possible learning-orientation signal, but no scorecard, deal example, or causal performance test. Researcher inference · moderate. The final education-IRR metaphor is conceptual, not a measured financial return. Winblad 2013, final paragraph beginning “While many will look”
Biography, evolution, and contradictions. The essay links a liberal-arts education to Winblad's later “business of new ideas” and encourages women to take programming classes, but it is a successful retrospective selected after the outcome. It does not examine people whose first role constrained later opportunities, and its “little over a year” chronology does not resolve conflicting Open Systems formation dates elsewhere. The 2001-to-2013 adaptation also means the article is not a contemporaneous 1970s career record. Source note
Object-Oriented Software (1990): metadata-only
The KIT catalog establishes a 291-page Addison-Wesley book by Ann L. Winblad, Samuel D. Edwards, and David R. King, ISBN 0201507366. KIT catalog, bibliographic fields Winblad’s oral history places the writing commitment around 1985, before the fund launch. Berkeley oral history, printed p. 17 / 01:00:50–01:00:51 This is contemporaneous record · strong for technical publishing chronology and researcher inference · insufficient public record for its effect on investing. No legitimate full text or contribution allocation was found; the book is not summarized.
“A Just-in-Time Software-Based World” (2001): metadata-only
Crossref and DBLP establish Mark Gorenberg first and Ann Winblad second as coauthors of a one-page Communications of the ACM contribution, volume 44, issue 3, page 125, DOI 10.1145/365181.365237. Crossref canonical DOI The ACM route was closed and OpenAlex exposed no repository copy. The title is not used to assign a hosted-software thesis, and no content analysis is attempted.
Cross-source synthesis
Specialization is a competence claim before it is a branding claim
The 2019 essay says LPs viewed a software-only fund as dangerously narrow; the 2005 Q&A says Winblad chose software because operating experience made it the category she understood. Winblad 2019, LP and mandate paragraphs · WilmerHale Q&A, printed p. 16 The combined rule is investor-stated · strong: specialize where the team can evaluate products and help companies, not merely where a category is fashionable. Whether that competence produced excess returns is insufficient public record absent the complete fund series.
Venture work begins after selection
The anniversary essay stresses leading first rounds; the Q&A supplies the missing operational verbs—diligence, operating-plan refinement, customer introductions, CEO evaluation, role recruiting, syndication, and partner assignment. Winblad 2019, “In our early years” paragraph · WilmerHale Q&A, printed pp. 17–20 Investor-stated · strong for the stated company-building model; documented behavior · provisional until deal records and founder witnesses test it.
Technical change must cross an organizational adoption bridge
The 1992 excerpt makes legacy code, trained people, and ecosystem tooling central to architecture adoption. The 2005 Q&A makes product marketing the bridge among customer, sales, and engineering and treats corporate relationships as routes to product fit and acquisition. CHM compilation, PDF p. 66 · WilmerHale Q&A, printed pp. 18–20 Researcher inference · moderate: Winblad’s accessible record repeatedly locates software risk at the technology-to-organization boundary, not only in code quality.
Patience and urgency coexist, but the stopping rule is missing
The WIRED comment praises institution-building beyond five years; the 2005 interview advocates patient company building but also fast rejection, CEO replacement, early finance, and market feedback. WIRED Staff, Winblad/Graham paragraph · WilmerHale Q&A, printed pp. 17–20 Researcher inference · moderate: patience is conditional on organizational learning, not passive holding. The record does not disclose kill criteria or when repeated support becomes escalation of commitment.
Team architecture counters heroic attribution
Fundraising depends on Hummer, endorsers, and LP advocates; company building depends on co-investors, assigned partners, directors, CEOs, marketing, finance, and corporate partners. Winblad 2019, fundraising paragraphs · WilmerHale Q&A, printed pp. 18–20 Investor-stated · strong for collective work; personal deal attribution remains insufficient without filings and witnesses.
Intellectual chronology, evolution, and contradictions
| Date | Accessible intellectual record | What can and cannot be said |
|---|---|---|
| c. 1985–1990 | Object-Oriented Software writing and publication | Technical authorship is catalog-documented; content and contribution shares are unavailable. Contemporaneous record · strong for metadata; researcher inference · insufficient public record for intellectual content. |
| 1992 | Enterprise-era excerpt | The surviving excerpt explicitly addresses tooling, legacy investment, and architecture migration; the full argument is unavailable. Contemporaneous record · strong for the excerpt; researcher inference · insufficient public record beyond it. |
| 1997 | WIRED-attributed reading comments | The comments express admiration for concise communication and durable institutions but do not prove an investment rule. Investor-stated · moderate for expressed preferences; documented behavior · insufficient public record. |
| 2001 | One-page CACM article metadata | The metadata documents a firm-linked technical publication; no thesis can be inferred from its title. Contemporaneous record · strong for metadata; researcher inference · insufficient public record for content. |
| 2005 | Post-bust Q&A | This is the richest operational record: selection discipline, team/board design, syndication, corporate adjacency, and global talent. Investor-stated · strong for her articulated process; documented behavior · insufficient public record for consistency. |
| 2012–2013 | Leadership, creative measurement, and career guidance | All three full bodies support bounded content claims: team/role flexibility, measurement beyond short attention, and long-horizon learning. Investor-stated · strong; their application to investment results remains researcher inference · provisional. |
| 2019 | Anniversary essay | Mature origin narrative and enduring specialization claim; strongest chronology but highest success-selection risk. Investor-stated · strong for chronology and mandate; researcher inference · moderate for selection-bias assessment. |
The stable public through-line is software specialization plus active early company formation. Investor-stated · strong. The apparent shift is from 1992 architecture mechanics to 2005 organizational and capital-cycle mechanics, then to a compressed 2019 institutional origin story. Researcher inference · moderate. Because the 1990 and 2001 full texts are unavailable, the middle of that evolution cannot be reconstructed confidently.
Material contradictions remain:
- Fund I: Winblad reported $27 million investable and $252 million returned in 2019 versus a $35 million fund and over 10x in 2005. Both are reported and basis-ambiguous. Winblad 2019, “Our first fund” paragraph · WilmerHale Q&A, printed p. 17 Investor-stated · moderate for each figure; researcher inference · provisional on reconciliation.
- Fundraising: the public retrospectives say 130, over 130, and 133 meetings or pitches. WilmerHale Q&A, printed p. 16 · Winblad 2019, fundraising paragraphs · Berkeley oral history, printed pp. 17–19 Investor-stated · moderate; no contemporaneous pitch log is public.
- LP identity: the 2019 essay names State Farm Insurance, while the oral history names St. Paul Companies. Winblad 2019, institutional-backing paragraph · Berkeley oral history, printed pp. 18–19 Investor-stated · provisional; similar names are not interchangeable.
- IPO count: the 2019 essay reports six Fund I IPOs, while the oral history says half of the 16 companies became public. Winblad 2019, “Our first fund” paragraph · Berkeley oral history, printed pp. 21–23 Investor-stated · provisional pending a company-by-company exit ledger.
- T/Maker: Winblad reports 3x in 2019 versus 5x in the 2004 Stanford session, with neither cash-flow schedule public. Winblad 2019, T/Maker paragraph · Stanford eCorner, session transcript Investor-stated · provisional on return magnitude.
- Role continuity: the 2019 essay says the “same job description” across thirty years, while later succession evidence distinguishes founding-partner and emeritus/adviser positioning. Winblad 2019, closing paragraph · StrictlyVC, 2015 role report · Aspenwood official team directory Investor-stated · strong for the rhetoric; contemporaneous record · strong for current public positioning; researcher inference · moderate that mission continuity did not imply unchanged governance.
Decision playbook
| Historical rule | Diagnostic questions | Boundary and likely misuse | Evidence status |
|---|---|---|---|
| Specialize where operating competence is rare | Can the team evaluate the product, recruit the missing roles, and reach customers better than generalists? Is the category broad enough for portfolio diversification? | A narrow label without proprietary capability creates concentration without edge. | 2019 mandate + 2005 competence account, p. 16 — investor-stated · strong |
| Give fast no’s and slow yes’s | What evidence must be resolved before the first check? Which uncertainty is learnable before financing, and which requires a staged check? | “Slow” can become indecision; no disclosed false-negative denominator tests the rule. | WilmerHale, p. 17 — investor-stated · strong |
| Underwrite adoption, not architecture alone | What installed code, workflow, training, procurement, and ecosystem must change? Which bridge reduces switching cost? | New tools can ease technical migration while organizational and economic lock-in persist. | 1992 excerpt, PDF p. 66 — researcher inference · moderate |
| Build an executive ensemble around the company’s bottleneck | Is the CEO right for the next milestone? Who owns customer truth, financial controls, and sales/engineering arbitration? | Formulaic executive replacement can destroy founder knowledge; selected successes do not yield a base rate. | WilmerHale, pp. 18–19 — investor-stated · moderate |
| Assign board work by fit, not sourcing ego | Which partner best serves this founder, co-investor group, and next bottleneck? Are incentives compatible with handoff? | Without transparent credit/carry, “ego aside” may remain rhetoric. | WilmerHale, p. 19 — investor-stated · strong; documented behavior · insufficient public record |
| Use incumbents as customers, partners, talent pools, and exit routes | Which incumbents have a real problem, budget, technical interface, and strategic reason to engage? | Corporate interest can distort roadmaps or create single-buyer dependence. | WilmerHale, pp. 20–21 — investor-stated · moderate |
| Be patient with learning, urgent about corrective action | Is evidence improving? What triggers CEO change, financing refusal, or a stop? | “Patience” without kill criteria becomes sunk-cost escalation. | WIRED comment + WilmerHale, pp. 17–20 — researcher inference · moderate |
Modern VC translation (as of 2026-08-21)
What transfers
- Capability-backed specialization transfers. A modern firm can apply Winblad’s rule to an analyst-created enterprise-software hypothetical: before adopting an “AI-native” label, demonstrate differentiated technical evaluation, design-partner access, security/compliance knowledge, and recruiting reach. The label without those mechanisms is not the historical rule. Researcher inference · moderate, grounded in Winblad’s operator-competence account. WilmerHale, printed p. 16
- Migration underwriting transfers. For any new architecture, map the installed workflow, data, integrations, training, procurement owner, and rollback path. Observable applicability signals are pilot-to-production conversion, integration time, user retraining, and expansion without bespoke services. This diagnostic is researcher inference · moderate from the 1992 excerpt. CHM compilation, PDF p. 66
- Role-aware boards transfer. Explicitly assign who judges the CEO, represents customer truth, manages financial controls, and resolves partner responsibility. Observable signals are time-to-critical-hire and whether board intervention matches the company’s next bottleneck. Researcher inference · moderate from the 2005 operating model. WilmerHale, pp. 18–20
What does not transfer automatically
- A 1989 software-only scarcity advantage does not prove that any 2026 software or AI specialization has scarce access or evaluation edge. Researcher inference · strong.
- Geographic driving distance is not a universal sourcing rule for globally distributed companies; preserve the high-bandwidth relationship mechanism while re-testing the physical-proximity assumption. Winblad herself described globally distributed engineering by 2005. WilmerHale, printed pp. 19–21 Researcher inference · moderate.
- A first-check lead strategy must be re-underwritten against current round sizes, ownership targets, reserves, and fund construction; the writings disclose none of those modern comparables. Researcher inference · insufficient public record.
- CEO replacement cannot be templated from one Voltage story. A modern analyst should distinguish founder-role evolution, coaching, executive addition, and removal and set ex-ante milestones. Researcher inference · strong as an anti-misuse control.
Changed assumptions and failure modes
Code creation and distribution may be faster in a modern analyst’s hypothetical, but enterprise trust, security, integration, and procurement can remain binding. The likely misuse is to read “software specialist” as a sector tag and “slow yes” as permission to delay decisions. A faithful transfer demands measurable capability and a diligence clock: define the unknown, evidence source, owner, deadline, and pass/kill threshold. Researcher inference · moderate.
For downturn investing, the observable test is not low valuations alone. It is whether incumbent distraction actually creates customer access while the startup retains enough runway and talent to learn. Winblad’s claim that encumbered incumbents help entrants is investor-stated · moderate; applying it to a 2026 company without those signals would be unsupported. WilmerHale, printed p. 17
Best writings and unresolved record
Read these five first
- WilmerHale Q&A (2005): richest operational record—selection discipline, CEO/marketing/finance, syndication, partner fit, corporate adjacency, and global talent—while retaining the edited-interview boundary. Printed pp. 16–21
- “Auditioning the Future of Software” (2019): best first-person chronology of fundraising, first investment, mandate evolution, and the reported Fund I result; read skeptically because it is an anniversary success narrative. Article body
- “Entering the Enterprise Era” excerpt (1992): earliest accessible technical argument and the strongest migration-cost lens; only two paragraphs survive in the reviewed archive. CHM PDF p. 66
- “Lessons From A Giant” (2012): clearest compact leadership framework, useful as a hypothesis for board behavior rather than proof. Section headings
- WIRED reading comments (1997): brief but useful counterweight to speed-first venture rhetoric; do not mistake WIRED Staff framing for Winblad authorship. Winblad-attributed paragraphs
Unresolved record
- Full legitimate text and chapter allocation for Object-Oriented Software.
- Full text of the one-page CACM article and author-by-author contribution.
- Full August 3, 1992 Computerworld article rather than the two-paragraph reprint.
- Stable archival snapshots for the four dynamic full-body LinkedIn articles.
- No public LP letters, investment memos, authored deal postmortems, board memoranda, or complete fund-performance communication were found.
- Fund I, fundraising-count, LP-name, IPO-count, and T/Maker multiple conflicts require primary fund/company records.
- The writings disclose no systematic pricing, ownership, reserve, concentration, follow-on, or exit framework. Later DEALS and TALKS work must not fill those gaps by projecting the operational rules beyond their evidence.
Coverage and evidence base
The 23 priority source-map rows reconcile to 12 direct-voice source families: ten spoken appearances and two edited written interviews (OnlineEducation and Axios). Stanford’s eleven map rows cover 13 official clips from one 2004 classroom session, not 13 independent talks; Berkeley’s catalog and transcript are one 2012 oral history. Nine families support full transcript or full caption-based analysis (Charlie Rose, Stanford, Churchill, TEDx, Berkeley, Full Ratchet, EIX, OnlineEducation, and Axios). Fresh Dialogues exposes a 12:34 parent MP3 and five excerpts but only partial publisher text with no continuous transcript; the two CNBC pages expose official metadata and durations but no public captions/transcript or substantive audiovisual review. Processing a route means documenting what was legitimately available; it does not convert an edited quotation, headline, or inaccessible player into a transcript.
| Direct-voice source family | Source-map rows | Access as re-opened through 2026-08-22 | Note and treatment |
|---|---|---|---|
| Charlie Rose interview, 1997 | 1 | Full 22:43 official VTT/transcript | note; deep analysis including failed banner forecast |
| Stanford eCorner classroom session, 2004 | 11 rows / 13 clips | Full official clip/transcript set | note; one appearance, not 13 witnesses |
| Fresh Dialogues, 2008 | 1 | Full audio routes; partial publisher text/topical clips | note; bounded to attributable material |
| Churchill Club with Steve Ballmer, 2008 | 1 | Full official transcript | note; Winblad’s questions, not Ballmer’s answers, are her evidence |
| TEDxBayArea, “Auditioning the Future”, 2011 | 1 | Full video and caption track | note; caption errors disclosed |
| UC Berkeley oral history, 2012 | 2 | Full institutional transcript plus catalog/audio route | note; paraphrase only under printed p. ii rights notice |
| The Full Ratchet, “The Stages of Fundraising”, 2014 | 1 | Full publisher transcript | note; transcript-error warning preserved |
| EIX interview, 2015 | 1 | Full video and caption track | note; page updated in 2026 |
| OnlineEducation Women Breaking Barriers, 2017 | 1 | Full lightly edited written interview | note; no audio/timestamps; edits disclosed |
| Axios interview, 2017 | 1 | Full short written article; selected direct quotes | note; not a full transcript |
| CNBC big-tech interview, 2021-03 | 1 | Metadata/video-only, 8:27; no public captions/transcript | note; no substantive audiovisual review |
| CNBC software-growth outlook, 2021-12 | 1 | Metadata/video-only, 3:41; no public captions/transcript | note; title-level record only |
The eight guiding questions were: what operating experience became an investing prior; what sourcing, market, timing, people, governance, and exit rules recur; how did those rules change from 1997 to 2021; what deals are explained with decision-time evidence rather than outcomes; how do partner and vehicle attributions constrain solo credit; which recollections conflict with contemporary records or one another; which predictions were prospective enough to test; and which archive/caption routes remain legitimately unavailable. Winblad is a pre-web software operator turned private-LP venture-firm cofounder with unusually rich retrospective direct voice, limited private-fund records, and material team/vehicle and selection-bias constraints.
Source-by-source guide
Charlie Rose (1997): assumption testing and a failed forecast
The 22:43 official VTT captures Winblad close enough to Fund I to test later retrospective narratives. She argues that pure internet advertising is unlikely to support most businesses, describes revenue surrounding a media enterprise, and predicts banners will disappear by the end of 1997 in favor of richer interstitial formats. Charlie Rose, 00:52–02:30 The revenue-mix point is investor-stated · moderate. The banner forecast is contemporaneous record · strong negative evidence: IAB's February 2001 standards notice still described existing banner guidelines and units. IAB 2001, standards announcement
She says venture capitalists are opportunists rather than visionaries: founders articulate futures, while investors help build business models, industry connections, and teams. Charlie Rose, 02:52–03:29 Investor-stated · strong for her 1997 role definition; consistent firm behavior remains documented behavior · insufficient public record.
Software capital efficiency is double-edged in her account. Cheap tools lower formation cost and entry barriers, leaving execution, speed, scaling, and competitive advantage to determine survival. Charlie Rose, 07:34–09:36 Investor-stated · strong. She then says the first fund required 150 meetings to raise $30 million, which conflicts materially with Stanford’s 113/$35 million and the 133/$35 million family of accounts. Charlie Rose, 09:36–10:00 Investor-stated · provisional pending close records.
The strongest decision rule appears in the Microsoft discussion: name the small set of forward assumptions, watch for invalidation, and replace the set rather than defend it tactically. Charlie Rose, 17:57–19:54 Investor-stated · strong. The closing Gates chronology places their meeting at an Esther Dyson forum speakers’ dinner after Winblad sold Open Systems; it is peer-network biography, not investment evidence. Charlie Rose, 20:20–22:26
Stanford eCorner (2004): market holes, timing, and falsifiable forecasts
Winblad opens by saying Intel, Hewlett-Packard, and Microsoft were asking for software companies they could not find; she reads those requests as market “holes” and calls 2004 an unusually promising post-bust year. Stanford introduction page, inline transcript Investor-stated · strong for her 2004 market view; the corporate questions are signals, not proof that startups could capture the demand.
The session presents Hummer Winblad as software-exclusive, early-stage, and generally co-leading. It reports a $35 million first fund, a $420 million Fund V about one-third invested, and more than 90 firm-level companies. Stanford introduction page, inline transcript These are investor-stated · moderate and vehicle-level; they do not establish Winblad-only performance. The 13 official clips add consumer/enterprise demand, outsourcing, and customer-testing evidence to innovation drivers, entrepreneur advice, seed/Series A conditions, recent investments, technology timing, Java/standards, Linux/Microsoft, the 2004 outlook, and core-assumption testing. Stanford session entry “Customers Are Key” describes exposing the Voltage team to roughly 20 CIO organizations and asking buyers about budget willingness; the market clip requires short-term enterprise ROI; the outsourcing clip separates core architecture from parallelized deployment work. Customers Are Key, inline transcript · consumer/enterprise page, inline transcript · outsourcing page, inline transcript Their value is unusually prospective and operational; fragmentation does not create 13-source triangulation.
T/Maker is called a 5x result here, versus 3x in 2019. Stanford introduction page, inline transcript Investor-stated · provisional. The difference needs financing and distribution records, not averaging.
Fresh Dialogues (2008): conviction without addiction
Recorded during the 2008 financial shock, the interview’s most useful rule is the Kool-Aid metaphor: an investor must temporarily enter the founder’s optimistic model without becoming addicted to it. Fresh Dialogues, “Drinking the Kool-Aid” block Investor-stated · strong as a de-biasing aspiration; documented behavior · insufficient public record because the source supplies no kill process or rejected-deal sample.
The page also identifies SDForum as an open-door sourcing route, resists a single “green tech will save the Valley” story, and recalls an intense 1980s software peer network around Bill Gates. Fresh Dialogues, SDForum, green-tech, and friendship blocks These are investor-stated · moderate. The publisher provides full and topical MP3 links but only selected text and no stable continuous timestamps, so the note does not treat the summary as a complete transcript.
Churchill Club with Steve Ballmer (2008): questions as an investment map
Winblad is the interviewer, not the featured executive. Her prepared questions map the credit crisis, SaaS, advertising, devices, virtualization, cloud, developers, open source, globalization, acquisitions, R&D, and incumbent succession. Microsoft official transcript, Winblad turns The themes are documented behavior · strong as topics she chose to interrogate; reading Ballmer’s answers as Winblad’s beliefs would be researcher inference · insufficient public record.
Her method is notable: she places numerical scorecards beside strategic narratives—segment profit, R&D, acquisition spending, developer counts, and platform share. Microsoft transcript, Winblad turns around lines 68–75, 91–94, 132–161 Researcher inference · moderate: public metrics appear to be a preferred way to challenge an incumbent, but a moderated event does not prove this was her private-company diligence process.
TEDxBayArea (2011): auditioning and explicit failure tolerance
Winblad describes venture work as repeatedly “auditioning the future” and says about 40% of funded companies fail. TEDx video, 03:26–04:18 The audition metaphor and tolerance for uncertainty are investor-stated · strong. The 40% is investor-stated · provisional because no vehicle, company cohort, cutoff, follow-on rule, or definition of failure is supplied.
The talk also advocates venture’s innovation/employment role, recounts 133 entry meetings or refusals, and challenges women to enter through the education and experience pipeline. TEDx video, entry 13:00–15:08; education 15:13–16:10 The claims document her public rationale and access agenda; economic causation is investor-stated · provisional without the underlying studies and counterfactual. The machine caption renders a likely decimal error as “22% GDP” around 04:28, so that number is excluded; only short clearly aligned quotations are retained.
UC Berkeley oral history (2012): biography, formation, and selected counterexamples
The institutional transcript reconstructs the longest chronology: education; Federal Reserve programming; Open Systems; California; technical writing; John Hummer; 133 fundraise rejections; endorsements from Pitch Johnson, Bill Edwards, and Don Valentine; and Fund I. Berkeley oral history, printed pp. 1–23 It is retrospective witness · strong for what Winblad remembered in 2012, but only moderate for exact counts and causes without contemporary records.
Slate and Wind River form the most useful failure/success pair: both make timing central rather than treating technical quality as enough. Berkeley oral history, printed pp. 21–23 The timing lesson is investor-stated · moderate; selecting one failure and one success does not establish a base rate. The oral history also reveals persistent contradictions: Open Systems dates, fund milestones and meeting counts, St. Paul Companies versus State Farm Insurance, and half of 16 becoming public versus six IPOs. Printed p. ii requires Bancroft permission for publication quotation, so this dossier paraphrases the oral history and uses printed-page/audio locators only.
The Full Ratchet (2014): the most operational financing framework
Winblad maps each financing stage to a different evidence burden. Seed should create a demonstrable product and representative-market response; A-round investors test value, market, pricing, and competition; B investors need retention, upsell, CAC, churn, sales productivity, and repeatability; later money scales established economics. Full Ratchet transcript, 00:05:01 through the stage-summary answer This proof-point ladder is investor-stated · strong and the spoken corpus’s most operational framework.
She says Series A scarcity is structural because board work and company building limit investor capacity. She gives a firm/partner aggregate of at most ten new investments from about 500 pitches. Full Ratchet transcript, Series A crunch answer around 00:23:28 Investor-stated · moderate; the denominator and rejected-company outcomes are not disclosed. She also warns that founder conflict, executive loss, self-destructive behavior, and cash exhaustion between proof points can defeat financing. Full Ratchet transcript, 00:17:16–00:20:00 Investor-stated · strong for the risk inventory; prevalence is unknown.
Hyperion and NuoDB illustrate exceptional investment before normal proof: perceived market size, customer conversations, founder capability, and technical ambition substitute for observed traction. Full Ratchet transcript, 00:20:34 through NuoDB answer These are retrospective witness · moderate because the winners are known when narrated and no failed thin-proof cohort is supplied. Her statement that valuations are irrelevant until liquidity is a useful exit discipline, though capital raising, dilution, preferences, and employee compensation make paper value consequential before exit.
EIX (2015): market-first operating biography
The video links childhood commerce, the Federal Reserve, Open Systems, and venture selection. Winblad’s explicit rule is that markets come first: a product is not worth building without a sufficiently large, reachable opportunity. EIX video, 07:01–07:27 Investor-stated · strong. The page summary adds mission, full commitment, and responsibility to company and colleagues as founder qualities. EIX page summary Contemporaneous record · moderate because that language is editorial framing of the video.
At 20:43–21:23 she recounts 133 noes before institutional support; at 23:29–24:20 she emphasizes mission, resilience, learning, and team commitment; at 24:25–26:18 she describes identifying and continually retesting assumptions required for scale. EIX video These are investor-stated · strong as the 2015 framework but retrospective on fund formation.
The childhood Barbie-clothes story is evidence of how she narrates entrepreneurial formation, not proof that childhood commerce caused venture success. EIX video, 01:06–01:56 That causal link would be researcher inference · provisional. Automatic-caption errors and a 2026 page update are disclosed.
OnlineEducation (2017): sourcing throughput, pattern recognition, and culture
Winblad says she meets three to five new people weekly and sources actively through campuses, enterprise customers, and existing entrepreneurs; inbound attention alone risks seeing the “runts of the litter.” OnlineEducation transcript, paragraphs 35–41 The throughput rule is investor-stated · strong; whether it generated excess returns is documented behavior · insufficient public record.
She distinguishes entrepreneurs as visionaries from VCs as opportunists who see patterns. MuleSoft is the worked example: five people across four countries describe APIs, service buses, devices, and cloud applications before the connected world is fully visible. OnlineEducation transcript, paragraphs 42–50 Pattern alignment is investor-stated · strong as her retrospective rationale; solo attribution and ex-ante records remain missing.
The interview also treats public behavior, culture, values, and the persistence of investor ownership as diligence facts. OnlineEducation transcript, paragraphs 67–81 Investor-stated · strong as a people rule. The confidence that bad culture is obvious risks hindsight and similarity bias, and the source provides no accepted-versus-rejected cohort. AI and autonomous-driving comments are prospective 2017 forecasts and should be tested rather than celebrated after the fact. OnlineEducation transcript, paragraphs 48–52
Axios (2017): values as a kill criterion
Winblad says Hummer Winblad sometimes passes on a company with an attractive opportunity when founder values do not fit. Axios, values block That is investor-stated · strong as a claimed rule and documented behavior · insufficient public record without the company or IC record. She also assigns the board responsibility for hiring or removing the CEO and treats talent departures as governance evidence. Axios, Uber block Investor-stated · strong.
Amazon serves as the boundary: demanding work is not automatically bad culture when mission and organization remain coherent. Axios, Amazon block This prevents the people rule from collapsing into comfort-seeking, though a short edited quotation cannot supply a complete diligence test.
CNBC, March and December 2021: prospective records not yet extractable
The March page identifies an 8:27 big-tech investing discussion, but no public captions/transcript surfaced and the audiovisual track was not substantively reviewed. CNBC, 2021-03-15 The December metadata identifies a 3:41 software revenue-growth segment; its title is not treated as a full verbatim thesis. CNBC, 2021-12-31 Both are contemporaneous record · provisional at title/date level and researcher inference · insufficient public record for company, valuation, horizon, or risk claims. They remain important because a retrieved segment could be scored prospectively.
Recurring frameworks and what the corpus supports
1. Specialization is an information system, not merely a sector label
The 2004 session links software focus to direct questions from incumbents; 2017 says active meetings with new people, enterprise customers, and entrepreneurs keep the investor in the “river of innovation.” Stanford introduction page, inline transcript · OnlineEducation, paragraphs 35–41 Researcher inference · strong: specialization works here by increasing the density and interpretability of market signals. It can fail when repeated network exposure becomes consensus, stale pattern matching, or adverse-selection-heavy inbound.
2. Market-first does not mean traction-only
EIX states the market-first rule; Full Ratchet then shows why pre-traction investing sometimes survives it. Hyperion and NuoDB lacked normal proof, but founders articulated a large market, customers could discuss a future need, and technical capability carried weight. EIX video, 07:01–07:27 · Full Ratchet, 00:20:34 onward Researcher inference · strong: the operative hierarchy is accessible market first, then evidence calibrated to stage—not “revenue or pass.” The failure mode is calling a technically grand possibility a market without buyer evidence.
3. Proof points should turn assumptions into facts
Full Ratchet explicitly moves from promise to customer validation to retention, upsell, CAC, churn, and repeatability. Stanford’s “keep testing” route and Fresh Dialogues’ no-addiction metaphor supply the behavioral complement. Full Ratchet transcript · Stanford core-assumptions transcript · Fresh Dialogues, Kool-Aid block The combined framework is investor-stated · strong. Missing are actual milestone memos, reserve decisions, and examples where disconfirmation caused a stop.
4. Early-stage investing is capacity-constrained company building
The 2014 interview says Series A scarcity persists because investors must recruit, open doors, test assumptions, serve boards, and reserve capital. Full Ratchet, Series A answers The 2005 written Q&A separately assigns boards CEO and executive-team responsibilities. WilmerHale Q&A, printed pp. 18–20 The causal model is investor-stated · strong; actual partner workload and marginal-return evidence are documented behavior · insufficient public record.
5. People risk includes learning rate, values, and visible self-destruction
Full Ratchet names simultaneous learning, founder conflict, key-person loss, and self-destruct tendencies. OnlineEducation and Axios add culture, public behavior, shared values, talent exit, and board CEO responsibility. Full Ratchet, 00:17:16–00:20:00 · OnlineEducation, paragraphs 67–81 · Axios, culture/values blocks Consistency across dates is investor-stated · strong. Predictive efficacy is not shown, and “shared values” can conceal similarity bias unless translated into observable conduct and role-specific reference checks.
6. Repetition demonstrates consistency, not accuracy
Market size, timing, assumption tests, and team quality recur across 2004–2017. That supports a stable public framework, not proof that the framework selected winners. Researcher inference · strong. The public corpus lacks rejected-deal outcomes, ordinary-deal files, IC dissent, reserve logs, and full fund performance.
Evolution, biography, and deal rationales
| Period | Direct-voice development | Evidence boundary |
|---|---|---|
| 1997 | Internet revenue, capital efficiency, long commitment, and explicit assumption testing | Full official VTT also preserves the failed end-1997 banner prediction and 150/$30m fundraise account. Charlie Rose Contemporaneous record · strong |
| 2004 | Post-bust market gaps, early-stage specialization, technology timing, standards, and assumption testing | Prospective views are testable, but 13 clips remain one source. Stanford session Investor-stated · strong |
| 2008 | Conviction-with-distance, crisis context, cloud/developer/incumbent questions | Fresh Dialogues is partial text; Churchill evidence is mainly questions. Fresh Dialogues · Microsoft transcript Documented behavior · moderate |
| 2011–2012 | “Auditioning” metaphor, failure tolerance, comprehensive career/fund retrospective | Advocacy and memory increase success-selection and denominator risk. TEDx · Berkeley oral history Retrospective witness · moderate |
| 2014–2015 | Stage-specific proof ladder and market-first operating formation | Strong operational rules; examples are selected after outcomes. Full Ratchet · EIX Investor-stated · strong |
| 2017 | Active sourcing, pattern convergence, values/culture, representation pipeline, AI forecast | Edited interviews; MuleSoft rationale is retrospective and shared-firm attribution remains open. OnlineEducation · Axios Investor-stated · strong |
| 2021 | Public big-tech and software-growth commentary | Video-only routes not extracted; detailed interpretation prohibited. CNBC March · CNBC December Contemporaneous record · provisional |
The biography-to-belief chain that survives scrutiny is narrow. Federal Reserve systems work and bootstrapped Open Systems gave Winblad direct exposure to emerging PC software and scarce capital; later talks repeatedly translate that into operator empathy, technical pattern recognition, and respect for financing proof points. EIX, approximately 03:53–07:27 · Full Ratchet, background and stage answers Researcher inference · moderate: chronology and her own explanation align, but no counterfactual establishes that the background caused later performance.
- T/Maker: the firm’s first investment is linked to Heidi Roizen; 5x in 2004 conflicts with 3x in 2019. Stanford introduction page, inline transcript · Winblad 2019, T/Maker paragraph Investor-stated · provisional.
- Hyperion: the 2014 rationale is large market plus founder persuasion and future-customer inquiry before product proof. Full Ratchet, 00:20:34 onward Retrospective witness · moderate; partner, ownership, and rejected-comparable evidence remain absent.
- NuoDB: Winblad emphasizes a huge database market, major technical risk, founder pedigree, geographic distance, and intense market study. Full Ratchet, NuoDB answer Retrospective witness · moderate; the 2014 “doing quite well” checkpoint is not a terminal outcome.
- MuleSoft: the 2017 story is convergence among devices, cloud software, APIs, and service buses, presented from a five-person/four-country starting point. OnlineEducation, paragraphs 45–47 Retrospective witness · moderate; filings document shared vehicle/board relationships and caution against solo credit.
- Slate and Wind River: the oral history makes technology timing the contrast. Berkeley oral history, printed pp. 21–23 Investor-stated · moderate; two selected cases do not establish the rule’s base rate.
Contemporaneous-versus-retrospective controls and contradictions
- Open Systems chronology: direct-voice accounts alternate between a 1975 and 1976 start, while acquisition/sale references span 1982–1984 and some profiles use 1983. Berkeley oral history, printed pp. 7–13 · OnlineEducation biography and background answers Retrospective witness · provisional on exact dates.
- Fund-formation milestone: 1987, 1988, and 1989 appear across accounts for courtship/planning, fundraising, legal start, and final close. Berkeley, printed pp. 17–19 · Charlie Rose, 09:36–10:00 · EIX, 20:43–21:23 Retrospective witness · provisional; these may be different milestones rather than one date error.
- Slate timing: Stanford says the product was about 13 years early, while the Berkeley oral history says 25 years. Stanford, “Are Technologies Ahead of Their Time?” · Berkeley, printed pp. 21–23 Investor-stated · provisional; both are post hoc estimates.
- Fund I meetings: Charlie Rose says 150; 2004’s introductory transcript says 113; 2005 says 130; 2019 says over 130; Berkeley/TEDx/EIX say 133. Charlie Rose, 09:36–10:00 · Stanford introduction page, inline transcript · WilmerHale, printed p. 16 · Winblad 2019 · Berkeley, printed pp. 17–19 Investor-stated · provisional; no pitch log is public.
- Fund I economics: Charlie Rose’s $30 million first-fund figure differs from the $35 million fund/over-10x family and the 2019 $27 million investable/$252 million account. Charlie Rose, 09:36–10:00 · WilmerHale, printed p. 17 · Winblad 2019, Fund I paragraph Investor-stated · moderate for the reports; researcher inference · provisional on commitment-versus-investable basis.
- LP identity: St. Paul Companies in the oral history conflicts with State Farm Insurance in 2019. Berkeley, printed pp. 18–19 · Winblad 2019 Investor-stated · provisional.
- IPO count: half/eight of 16 in the oral history conflicts with six in 2019. Berkeley, printed pp. 21–23 · Winblad 2019 Investor-stated · provisional.
- T/Maker: 5x in 2004 conflicts with 3x in 2019. Stanford introduction page, inline transcript · Winblad 2019 Investor-stated · provisional.
- Failure rate: TEDx’s approximately 40% failed-company claim cannot be reconciled to a named fund or the 98-logo firm directory. TEDx, 04:12–04:18 · official companies directory Investor-stated · provisional.
- 1997 banner forecast: Winblad predicted banners would be gone by year-end; IAB still documented banner guidelines and units in February 2001, making this a clear failed forecast. Charlie Rose, 02:16–02:30 · IAB 2001, standards announcement Contemporaneous record · strong.
- Public forecasts: the 2004 platform/cycle views and 2017 AI/autonomy views are contemporaneous enough to score, but later outcome knowledge must not be inserted into the original thesis. Stanford session · OnlineEducation, paragraphs 48–52 Contemporaneous record · strong for what was said; predictive efficacy remains untested here.
Prospective forecast scorecard
| Forecast at the time | As-of-2026 assessment | Evidence boundary |
|---|---|---|
| Banners would disappear by end-1997 | Failed. IAB still maintained banner guidelines and units in February 2001. | Charlie Rose, 02:16–02:30 · IAB 2001, standards announcement Contemporaneous record · strong for the prediction and failure classification. |
| Internet businesses would combine advertising with surrounding revenue streams; digital retailers could personalize from behavior | Directionally durable, but no company, share, or deadline makes this a precise investment forecast. | Charlie Rose, 00:52–05:13 Investor-stated · moderate; outcome attribution is not claimed. |
| 2004 Linux/Microsoft, Java/standards, and cycle optimism | Preserved as dated hypotheses but not mechanically scored here because the clips use qualitative horizons and multiple claims. | Stanford session Contemporaneous record · strong for stated views; predictive score remains insufficient public record without a claim-by-claim benchmark. |
| 2017 AI and autonomous-driving development over roughly the next decade | The stated window runs through 2027 and remains open as of 2026-08-21; the interview gives no adoption threshold, so a binary success claim would be premature. | OnlineEducation, paragraphs 48–52 Contemporaneous record · strong for the forecast; scoring is researcher inference · provisional. |
| 2021 big-tech/software-growth views | Unscored: official metadata exists, but no public caption/transcript or substantive audiovisual review supplied the horizon, companies, valuation, or falsifiers. | CNBC March · CNBC December Contemporaneous record · provisional. |
Decision rules a modern analyst can actually use
- Build a sourcing system, not an inbox. Historical rule: pair specialist network depth with deliberate novel-person and customer meetings. OnlineEducation, paragraphs 35–41 Ask: what share of this quarter’s qualified ideas came from new nodes; which customer problem repeats independently; where could the network be echoing itself? Investor-stated · strong. Failure mode: optimize meeting count without information gain.
- Underwrite the market before admiring the artifact. Historical rule: define the large accessible opportunity and buyer value before product elegance. EIX, 07:01–07:27 Ask: who pays, what painful gap closes, what installed behavior blocks adoption, and what evidence would shrink the market? Investor-stated · strong. Failure mode: market-size rhetoric without reachable customers.
- Calibrate proof to stage. Historical rule: seed proves feasibility and representative response; A tests market/value assumptions; B demonstrates retention, upsell, CAC, churn, and repeatability. Full Ratchet transcript Investor-stated · strong. Failure mode: use later-stage metrics to reject true technical discovery or early-stage storytelling to excuse missing repeatability.
- Enter the founder’s future, then schedule disbelief. Historical rule: drink the Kool-Aid briefly but do not become addicted. Fresh Dialogues Add a written pre-mortem, disconfirming customer calls, dated milestone, and explicit stop condition. The de-biasing procedure is researcher inference · moderate; Winblad states the principle, not this full implementation.
- Treat people failures as operating risks. Historical rule: diligence founder learning, conflict behavior, culture, values, and self-destruct signals alongside product and market. Full Ratchet, 00:17:16–00:20:00 · Axios, values block Investor-stated · strong. Failure mode: turn “shared values” into affinity bias; require behaviorally anchored references.
- Respect early-stage capacity. Historical rule: board work, recruiting, market access, and follow-on reserves limit responsible Series A volume. Full Ratchet, Series A answers Investor-stated · strong. Failure mode: count deals without a partner-time and reserve model.
- Do not book paper marks as outcomes. Historical rule: valuation becomes economically decisive at liquidity, though financing terms matter earlier. Full Ratchet, answer after InsideSales.com example Investor-stated · strong for exit skepticism; the qualification is researcher inference · strong.
- Separate the narrator from the vehicle. Historical rule: Hummer Winblad co-led, assigned partners, and invested through funds; individual presence does not equal sole authorship. Stanford introduction page, inline transcript Researcher inference · strong. Failure mode: convert a compelling speaker into a personal track record.
Retrieval frontier and saturation
The literal last-three exact searches were:
site:stvp.stanford.edu/videos "Ann Winblad" "February 25, 2004"— only the already-known Stanford eCorner clip family and rotating Ann author page appeared; no second session surfaced."Ann Winblad" CNBC 2021 transcript captions— only the two known CNBC pages and secondary references appeared; no public transcript or caption track surfaced.site:freshdialogues.com/2008/12 "Ann Winblad" "part two"— only the known part-one landing page and its promise appeared; no separate part-two page/audio surfaced.
These searches added no thirteenth family. Narrow source retrieval did improve the denominator: the Stanford archive was reconciled to 13 clips within one session, the official 22:43 Charlie Rose VTT was acquired, and full caption tracks were acquired for TEDx and EIX. No new source-map row was added; the three missing Stanford clips were folded into the existing Stanford family row.
The public frontier is defined, not exhausted. Highest-value remaining retrievals are: captioned or manually timestamped access to the two CNBC segments; a continuous timestamped Fresh Dialogues transcript and any independently archived part two; cleaner human transcripts for TEDx and EIX; and contemporaneous deal/IC/board records that can test the recurring public rules. Charlie Rose is no longer an access gap. These are named boundaries rather than grounds to invent content.
Listen to these five first
- The Full Ratchet — “The Stages of Fundraising”. Best operational decision framework: proof points, metrics, people failure, Series A capacity, corporate capital, Hyperion, and NuoDB. The publisher transcript makes it the most usable teaching source.
- UC Berkeley oral history. Best biography and formation record, with explicit success/failure examples and the contradictions later work must reconcile.
- Stanford eCorner 2004 session. Best contemporaneous technology, timing, stage, and cycle record; use the 13 clips as one session.
- OnlineEducation 2017 interview. Best sourcing, MuleSoft pattern-recognition, culture, gender-pipeline, and failure-tolerance synthesis; remember it is lightly edited.
- TEDxBayArea — “Auditioning the Future”. Best compact statement of the profession’s screening and failure-tolerance story; pair it with the denominator caveats rather than using it as performance proof.
EIX is the best sixth source for the market-first/operating-origin story; Axios is the fastest route to the values and board rule; Fresh Dialogues contributes the cleanest conviction-without-attachment metaphor.
Capability-backed specialization as an information system
- Rule: Specialize only where operating competence plus repeated founder, customer, and incumbent contact creates differentiated signal interpretation and credible post-check help; a sector label alone is not an edge.
- Evidence status: The rule is [investor-stated · strong] as public doctrine and [researcher inference · moderate] as a causal process. Durable personal alpha is [insufficient public record] because complete decisions, cash flows, rejected cases, partner allocations, and board counterfactuals are unavailable.
- Provenance and origin: Winblad connects the software-only mandate to her operator background and the firm's deliberate 1989 formation in the 2019 essay, mandate and formation paragraphs. The WilmerHale Q&A, printed pp. 16–17, Stanford introduction page, inline transcript, and OnlineEducation interview, specialization/sourcing paragraphs repeat the mechanism from distinct formats. [investor-stated · strong]
- Mechanism and reasoning: Domain competence narrows search, improves error detection, builds a denser referral graph, makes customer and technical references easier to interpret, and lets directors recruit or diagnose with more precision. Repetition can also create pattern lock-in, prestige bias, and correlated portfolio exposure; specialization earns the right to ask better questions, not the right to skip them. [researcher inference · strong]
- Historical and vehicle context: In 1989, a software-only U.S. venture mandate was unusual and may have concentrated scarce specialist attention. Later cloud/API diffusion and larger multi-stage funds reduced the scarcity of sector branding. HWVP's closed-end vehicles, limited new-company capacity, and partner board work were part of the system; Fund III's LP-specific 1.04x TVPI/1.0% net IRR shows that domain focus did not guarantee persistence. UCOP report, p. 1 row 48 [contemporaneous record · strong]
- When to use: Use the model when a market's technical architecture, buyer workflow, regulation, or migration path is hard for generalists to evaluate and when the team can name unique sources of truth and post-investment interventions. Do not use it merely because the category is fashionable or fundraising benefits from a narrow label. [researcher inference · moderate]
- How to apply it: Write a capability ledger before sourcing. IC must ask: What do we know or change that a competent generalist cannot, and which independent reference would falsify that claim? Evidence threshold: name one decision-relevant technical/customer insight and one credible post-check intervention. Kill if the claimed edge is only warm access or branding. Next milestone: log whether the unique insight changed probability, price, terms, ownership, or the board plan by the next review. [researcher hypothetical · moderate]
- Examples:
- Hyperion/Arbor — bounded success: HWVP funded Arbor in 1991 and its firm page names Winblad as director; the rationale is retrospective and the page's 1991 IPO claim is erroneous. Wired profile, Arbor paragraphs · Hyperion decision lab [contemporaneous record · moderate]
- MuleSoft — bounded success: Winblad served as director from 2006 while V/VI control was shared; the convergence narrative is retrospective. MuleSoft S-1/A [contemporaneous record · strong]
- Voltage Security — ordinary/bounded case: the public diligence account ties software expertise to CIO/budget checks and company building, but entry economics remain unresolved. Voltage lab [researcher inference · moderate]
- HWVP III — performance counterexample: one UC LP position reports only 1.04x TVPI/1.0% net IRR; it is not a whole-fund result but disproves any claim that specialization guaranteed persistence. UCOP report, p. 1 row 48 [contemporaneous record · strong]
- Evidence: Four independent placements support the doctrine: 2019 signed essay, mandate/portfolio paragraphs; WilmerHale edited Q&A, pp. 16–21; Stanford 2004 introduction transcript; and OnlineEducation 2017 edited interview. The first is signed retrospective, the others direct voice in edited/spoken records; repetition demonstrates consistency, not accuracy. [researcher inference · strong]
- Limits, failure modes, and exception ledger: The directory is curated and only 9 of 98 logos are sufficiently reconstructed; biographies claim 150+/160+. Model-specific routes checked the 98 canonical company pages, 2026 ADV, UCOP/SDCERS LP reports, issuer filings, and the exact searches
site:sec.gov/Archives/edgar/data "Hummer Winblad Venture Partners" "T/Maker"and"Hummer Winblad Venture Partners" ("investment memorandum" OR "quarterly report" OR "LP letter") filetype:pdf; they yielded no Fund I schedule, complete customer-call/board ledger, or same-basis LP series. Consumer/dot-com perimeter cases, Fund III, and later retrenchment remain counterevidence. Uncertainty ledger [researcher inference · strong] - Evolution and contradictions: The 1992 technical migration lens, 2004/2005 customer-and-company-building language, and 2019 institutional retrospective show a stable public specialization story with increasing operational detail. That is corpus evolution, not evidence of a private-process change. The doctrine also conflicts with generalist perimeter investments and cannot be assigned to Funds VII/VIII, whose Form Ds omit the founders. [researcher inference · strong]
- Modern VC translation (as of 2026-08-21): For AI, cybersecurity, climate software, or regulated verticals, require a capability proof: unique technical review, buyer references, data/regulatory knowledge, and named post-check help. Score decisions where that capability changed a probability, price, term, or milestone. Treat “AI-native” branding without an auditable information advantage as no edge. [researcher hypothetical · moderate]
Define the accessible market and buyer budget before admiring the product
- Rule: Name the reachable buyer, painful gap, budget, procurement path, adoption trigger, and reason existing solutions fail before treating technical possibility or headline TAM as a venture market.
- Evidence status: Market-first and buyer-budget inquiry are [investor-stated · strong] across independent direct-voice sources. Application consistency is [researcher inference · moderate] because selected cases survive while failed-deal market work and original memoranda are absent.
- Provenance and origin: Winblad says markets come first in the EIX talk, 07:01–07:27. The Full Ratchet transcript, market and stage answers and WilmerHale Q&A, printed pp. 17–18 operationalize customer value and budget; Charlie Rose, 17:57–19:54 frames the work as testing the assumption set. [investor-stated · strong]
- Mechanism and reasoning: Technical merit creates value only when a customer with authority and resources changes behavior. Mapping buyer, user, budget, alternatives, switching cost, and proof of urgency distinguishes an addressable market from an imaginable one. Customer evidence reduces demand uncertainty but does not by itself validate price, unit economics, or competitive durability. [researcher inference · strong]
- Historical and vehicle context: Enterprise software in the client-server and early cloud periods often required direct selling, long implementation, and reference customers, making CIO/budget access unusually informative. Capital-light software also lowered entry barriers and invited overinvestment, a tension Winblad discussed in 1997. Charlie Rose, 09:00–10:14 [investor-stated · strong]
- When to use: Use before initial approval, whenever user and buyer differ, when procurement or integration is material, before a large follow-on, and whenever management substitutes TAM slides or pilots for paid repeat use. Pair it with adoption-timing, people, and unit-economics models rather than letting one favorable reference decide the case. [researcher inference · strong]
- How to apply it: Build a market-access sheet. IC must ask: Who uses, who pays, which budget moves, why now, and what independent customer says no? Evidence threshold: one named budget path plus independent proof of painful repeat use. Kill if no buyer, budget, or willingness-to-pay test survives. Next milestone: a dated paid pilot, renewal, expansion, or procurement event tied to the weakest cell. [researcher hypothetical · strong]
- Examples:
- Hyperion/Arbor — bounded success: the client-server opportunity and customer inquiry are supported retrospectively, with Winblad board attribution but missing entry memo. Hyperion lab [researcher inference · moderate]
- NuoDB — unresolved application: Winblad's public account combines a large database market with explicit technical and market risk, but the complete decision record is unavailable. Full Ratchet transcript [investor-stated · moderate]
- Voltage Security — ordinary/bounded case: roughly 20 CIO organizations were reportedly used to test need and budget; economics remain bounded. WilmerHale, printed pp. 17–18 [investor-stated · moderate]
- Pets.com — counterexample: a large category did not establish sustainable economics; the case is firm/John-attributed, not Winblad selection evidence. Pets.com lab [contemporaneous record · strong]
- Evidence: The rule has at least four useful placements and two independent works: EIX video/host page, 07:01–07:27; Full Ratchet publisher transcript; WilmerHale edited Q&A, pp. 17–18; and Charlie Rose official transcript/VTT page, 17:57–19:54. [investor-stated · strong]
- Limits, failure modes, and exception ledger: Customer references can be selected, polite, non-economic, or incumbent-biased; budget can exist without urgency; a large market can still produce weak venture returns; and market diligence can miss legal or capital constraints. No rejected-customer log, reference questionnaire, market-sizing memo, pricing threshold, or complete failed-cohort market work surfaced in the audited routes. Deal retrieval ledger [researcher inference · strong]
- Evolution and contradictions: The public record moves from 1990s market-hole and capital-efficiency language to 2005 buyer/budget diligence and 2014 stage economics. The core is consistent, but Pets.com, HomeGrocer, Napster, and Liquid Audio show that market narrative cannot substitute for business-model, legal, or governance proof. [researcher inference · moderate]
- Modern VC translation (as of 2026-08-21): AI applications can produce explosive trial use before durable budgets. Trace user→buyer→budget→renewal, require independent paid cohorts and workflow ownership, and model inference, support, security, and compliance costs. Do not treat benchmark performance, demo enthusiasm, or TAM as accessible revenue. [researcher hypothetical · strong]
Underwrite the adoption bridge and timing, not technical inevitability
- Rule: Map the installed code, workflow, integrations, training, procurement, regulation, platform readiness, and fund-reserve horizon required for adoption; a future that eventually arrives can still be an uninvestable present.
- Evidence status: The adoption-bridge model is [researcher inference · moderate], grounded in direct technical writing and repeated retrospective timing accounts. It is not presented as a verbatim Winblad checklist, and precise timing ability is weakened by a failed prospective forecast.
- Provenance and origin: The reproduced 1992 excerpt discusses object-oriented tooling, reusable class libraries, and enterprise architecture as migration constraints. Computer History Museum periodical scan, PDF p. 66 / printed Hotline p. 23 [contemporaneous record · strong] Stanford asks whether technologies can be ahead of their time; Berkeley supplies the Slate retrospective; Charlie Rose supplies a failed banner prediction. Stanford session note, timing clip · Berkeley oral history, pp. 21–23; paraphrase only · Charlie Rose, 02:22 [investor-stated · moderate]
- Mechanism and reasoning: Adoption depends on complements, not only product quality. A dependency that arrives after runway, reserves, or fund life destroys value even when the technical direction is correct. The model separates market existence—who might pay—from timing—whether the necessary system can change soon enough. [researcher inference · strong]
- Historical and vehicle context: Early object-oriented, client-server, internet, and cloud shifts required different complements and capital horizons. Slate's reported loss shows why a closed-end venture vehicle cannot wait indefinitely for architecture and behavior to catch up. Current AI infrastructure may move faster technically while enterprise security, data rights, procurement, and change management remain slow. [researcher inference · strong]
- When to use: Use for platform transitions, developer infrastructure, regulated software, products replacing embedded workflows, two-sided networks, and any thesis containing “inevitable.” Re-run before follow-ons whenever an external complement slips or a customer workaround becomes durable. [researcher inference · strong]
- How to apply it: Build a dated dependency graph. IC must ask: Which external complement has to arrive before runway or fund horizon expires, and what workaround exists? Evidence threshold: owners and lead times for every critical dependency plus customer proof that the bridge is tolerable. Kill or resize if a critical dependency's latest viable date exceeds funded runway. Next milestone: the earliest observable integration, procurement, platform, or behavior dependency. [researcher hypothetical · strong]
- Examples:
- Slate — failure: the firm reportedly lost about $1.2m; Winblad later called it 13 or 25 years early, so only the qualitative timing failure survives. Wired 1996 profile, Slate paragraphs · Berkeley oral history, pp. 21–23; paraphrase only [retrospective witness · moderate]
- Hyperion/Arbor — researcher-applied success: a client-server bridge is plausible, but contemporaneous decision details remain absent. Hyperion lab [researcher inference · provisional]
- MuleSoft — researcher-applied success: convergence is plausible and the 2006 board/vehicle route is documented, but the thesis is retrospective. MuleSoft lab [researcher inference · moderate]
- Evidence: Four independent placements anchor the model: 1992 enterprise-era excerpt, PDF p. 66; Stanford session note, timing clip; Berkeley oral history, pp. 21–23; paraphrase only; and Charlie Rose official record, 00:52–02:30. [researcher inference · moderate]
- Limits, failure modes, and exception ledger: Dependency maps create false precision and “too early” can excuse any miss. Model-specific routes checked the 1992 CHM excerpt, all 13 Stanford clips/transcripts, Berkeley's Slate pages, Wired's 1996 profile, the 98 HWVP company pages, and the exact SEC/LP-letter searches in the deal retrieval ledger; they produced no Slate memo, dated dependency sheet, reserve/stop log, or ordinary adoption cohort. Hyperion and MuleSoft remain retrospective applications. [researcher inference · strong]
- Evolution and contradictions: The 1992 writing identifies migration friction; 2004/2012 retrospectives elevate timing; cloud-era narratives emphasize convergence. The 1997 prediction that banner ads would disappear by year-end failed, proving category fluency is not precise timing skill and making explicit update rules essential. Forecast scorecard [researcher inference · strong]
- Modern VC translation (as of 2026-08-21): For AI and agentic software, map model reliability, data permission, security review, integration, human approval, liability, procurement, and unit-cost dependencies against runway. Require a viable bridge, not merely a model-improvement curve; pre-register what delay forces a smaller round, pivot, or stop. [researcher hypothetical · strong]
Match proof to stage, turn assumptions into facts, then re-underwrite
- Rule: Seed should prove feasibility and representative response; Series A should test market and value; Series B should show retention, upsell, acquisition cost, churn, and repeatability. At every round, convert named assumptions into dated facts and re-underwrite conviction.
- Evidence status: The proof ladder and assumption-testing rule are [investor-stated · strong]. Consistent private application, stop discipline, reserve allocation, and causal outcome improvement are [insufficient public record].
- Provenance and origin: The Full Ratchet publisher transcript, financing-stage answers gives the fullest ladder; Stanford “Keep Testing Your Core Assumptions” states the update rule; Fresh Dialogues, Kool-Aid block describes regaining distance; and WilmerHale, p. 17 supplies “fast no/slow yes” discipline. [investor-stated · strong]
- Mechanism and reasoning: Early investing requires action before complete proof. A staged evidence contract limits what must be believed at each price and capital level; explicit assumptions make disconfirmation observable; re-underwriting prevents initial conviction, sunk costs, or partner ego from silently changing standards. [researcher inference · strong]
- Historical and vehicle context: Early HWVP checks and board roles operated within finite funds and scarce partner attention. Capital-light software reduced initial checks but could also lower barriers and increase noise. Larger later vehicles, secondary liquidity, and continuation options can defer recognition of broken assumptions unless reserve and stop decisions remain explicit. [researcher inference · moderate]
- When to use: Use before every first check, financing, reserve allocation, bridge, insider-led round, pricing reset, or board intervention; also use after a material forecast miss, executive departure, security incident, legal change, or delayed dependency. [researcher inference · strong]
- How to apply it: Freeze a round memo. IC must ask: Which three facts justify this stage and which assumption can still kill the company? Evidence threshold: seed feasibility/representative response; A market/value proof; B retention, upsell, CAC, churn, and repeatability. Kill, resize, or reset if the weakest pre-registered threshold misses by its date. Next milestone: the single fact that most reduces remaining risk, owned by a named person. [researcher hypothetical · strong]
- Examples:
- T/Maker — bounded early-check case: the reported first check illustrates staged exposure, but $300,000/$750,000 and 3x/5x conflicts prevent precise mechanics. 2019 essay · Stanford session synthesis [retrospective witness · moderate]
- NuoDB — unresolved application: Winblad described simultaneous technical and market proofs; no private milestone ledger survives. Full Ratchet [investor-stated · moderate]
- MuleSoft — researcher-applied success: five-person entry and later scale provide a long-duration example with filing evidence. MuleSoft lab [researcher inference · moderate]
- Slate — failure boundary: public stop/update mechanics are absent even though timing failure is documented. Slate lab [researcher inference · strong]
- Evidence: The model has four distinct direct-voice placements: Full Ratchet 2014 transcript; Stanford 2004 assumption transcript; Fresh Dialogues 2008 audio/show notes; and WilmerHale 2005 Q&A, p. 17. Transcript-quality boundaries are recorded in the underlying notes. [investor-stated · strong]
- Limits, failure modes, and exception ledger: Milestones can be gamed, easily measured facts can crowd out important qualitative risks, and “slow yes” can become indecision while patience becomes escalation. No original HWVP memo, IC vote, proof-point scorecard, reserve formula, stop-decision log, or complete ordinary-case cohort surfaced in the audited memo/LP/archive searches. The applications therefore demonstrate fit, not compliance or causality. [researcher inference · strong]
- Evolution and contradictions: Public language grows more explicit from Charlie Rose's 1997 assumption set to 2004 testing, 2005 slow-yes, 2008 distance, and 2014 stage metrics. The failed 1997 banner forecast and absence of demonstrated process change after Slate/Napster show that stating an update rule is not the same as following it. [researcher inference · strong]
- Modern VC translation (as of 2026-08-21): Require AI seed rounds to prove task reliability and a real user's repeated behavior; A rounds to prove paid workflow value and retention; B rounds to prove expansion, gross margin after inference/support, CAC/payback, security, and repeatability. Reopen the frozen memo at each financing; never carry forward an assumption because valuation rose. [researcher hypothetical · strong]
Diligence people as learning, values, conflict, and self-destruction risk
- Rule: Assess simultaneous learning rate, values under pressure, conflict behavior, key-person loss, role self-awareness, ability to recruit complements, and visible self-destructive behavior—not charisma, pedigree, or demographic fit.
- Evidence status: The people-risk screen is [investor-stated · strong] across 2014–2017 direct-voice records. Predictive efficacy and consistent case application are [researcher inference · provisional] because references, scoring, rejected founders, and matched outcomes are private.
- Provenance and origin: Full Ratchet, 00:17:16–00:20:00 discusses founder and team risk; OnlineEducation, team/founder paragraphs expands learning and role concerns; Axios, culture/values blocks makes values a kill criterion; “Lessons From A Giant,” four headed sections supplies a leadership-team hypothesis from baseball. [investor-stated · strong]
- Mechanism and reasoning: Startups change faster than job descriptions. Teams that learn together, surface conflict, accept role changes, and share purpose can update faster; hidden value conflict, founder rupture, key-person dependence, or destructive conduct can erase product advantage. The model should evaluate observable behavior and references, not personality theater. [researcher inference · strong]
- Historical and vehicle context: Early software companies often required founders to move from product creation into enterprise selling and professional management. Active boards could recruit missing roles, but the same power can bias against unconventional founders. Modern distributed teams, founder-control structures, and AI leverage change roles without removing values and conflict risk. [researcher inference · moderate]
- When to use: Use at founding-team diligence, before a lead check, when one person controls product/customer/capital truth, before executive hiring or role change, after misconduct or records concerns, and before a follow-on when team conflict may be mistaken for market risk. [researcher inference · strong]
- How to apply it: IC must ask: What did each founder learn, where did values cost them something, how do they resolve conflict, and which role would they surrender? Evidence threshold: independent behavioral references, one consequential update, and a named complement for each critical gap. Kill if references expose unresolved dishonesty, destructive conduct, or an unowned key-person risk. Next milestone: a dated role, recruiting, or conflict-resolution proof. [researcher hypothetical · strong]
- Examples:
- T/Maker — bounded relationship case: the long Roizen/Winblad relationship and board route show access and collaboration, not a controlled efficacy test. 2019 essay [retrospective witness · moderate]
- MuleSoft — bounded team case: Winblad retrospectively emphasizes a small distributed team; filings establish her board start, not predictive screening. MuleSoft lab [researcher inference · moderate]
- Voltage — ordinary/bounded case: the CEO/role and customer work is the strongest direct illustration, with incomplete economics. WilmerHale, pp. 17–20 [investor-stated · moderate]
- Napster — governance/legal boundary: preservation and legal-operability failures are firm-level; no public evidence shows Winblad's selection role or personal copyright liability. Napster lab [contemporaneous record · strong]
- Evidence: Four useful placements from independent works support the rule: Full Ratchet 2014; OnlineEducation 2017; Axios 2017; and Lessons From A Giant 2012. The last is a sports analogy, not direct investment-process evidence. [investor-stated · strong]
- Limits, failure modes, and exception ledger: “Values” can become conformity, charisma can contaminate references, and board-directed role change can damage founder agency. Model-specific routes checked Full Ratchet, OnlineEducation, Axios, WilmerHale, the 2012 leadership essay, SEC role filings, Napster court records, and Pets.com's 10-K; they yielded no founder scorecard, adverse-reference file, rejected-founder ledger, board minutes, or matched people/outcome cohort. Napster and Pets.com are boundaries, not documented Winblad picks. [researcher inference · strong]
- Evolution and contradictions: The strongest people language appears after 2005 and becomes more granular by 2017, while the 2012 Giants essay adds calm, urgency, role acceptance, and joy. This may reflect clearer public articulation rather than changed private practice. The public record does not show how the screen changed after legal/governance failures. [researcher inference · strong]
- Modern VC translation (as of 2026-08-21): Evaluate how founders learn with AI-accelerated product cycles, govern model/data risk, handle cofounder conflict, and redesign roles as small teams gain leverage. Use structured behavioral evidence and diverse references; ban demographic or “culture fit” proxies; document what observation would reverse the people judgment. [researcher hypothetical · strong]
Build a complementary executive and board ensemble; assign work by fit
- Rule: After investing, identify the next bottleneck, recruit or evaluate the CEO and missing executives, install financial and customer truth, assign the best-fit partner rather than the sourcing ego, reserve time and capital, and preserve founder agency.
- Evidence status: The company-building model is [investor-stated · strong]. Documented roles in T/Maker, MuleSoft, The Knot, and Voltage support selected application, but causal value creation and a complete intervention denominator remain [researcher inference · moderate].
- Provenance and origin: WilmerHale, printed pp. 18–20 is the fullest direct account of CEO/team/partner fit; Full Ratchet, Series A and board answers connects stage to company building; the 2019 essay, first-round/board paragraphs states the historical norm; and OnlineEducation, venture role paragraphs repeats the practice. [investor-stated · strong]
- Mechanism and reasoning: Startups fail when the next constraint has no capable owner or when board, founders, and investors confuse advice with decision rights. A complementary ensemble makes role gaps explicit, directs scarce partner attention to fit, improves information flow, and recruits before the bottleneck is fatal. Shared credit is evidence of system design, not a weakness to erase. [researcher inference · strong]
- Historical and vehicle context: HWVP's early-round, board-intensive approach was enabled by specialist partners and finite portfolio capacity. Firm/vehicle control was shared, and later funds changed managing rosters; the model therefore belongs to documented company/partner contexts, not automatically to every HWVP logo or successor fund. [researcher inference · strong]
- When to use: Use after the initial check, before each financing, during founder-to-scale transitions, when sales or finance truth is weak, when one partner lacks domain/role fit, and whenever the board must decide whether to coach, recruit, reassign, replace, finance, or stop. [researcher inference · strong]
- How to apply it: IC/board must ask: What is the next bottleneck, who owns it, why is this partner best fit, and which decision belongs to founders? Evidence threshold: a named gap, qualified owner, information path, and founder-agreed milestone. Kill or reassign the intervention if the partner lacks capacity/fit or if it substitutes for management. Next milestone: a dated hire, customer/finance truth event, or resolved governance decision. [researcher hypothetical · strong]
- Examples:
- T/Maker — bounded success: Winblad's relationship and board route are retrospective; founders and Roizen remain indispensable. 2019 essay [retrospective witness · moderate]
- MuleSoft — bounded success: director since 2006 and shared V/VI control are documented; causal intervention remains unproved. MuleSoft S-1/A [contemporaneous record · strong]
- The Knot — role evidence: Form 4 documents Winblad's director/GP route but not original thesis or board effect. The Knot Form 4 [contemporaneous record · strong]
- Voltage — ordinary/bounded case: direct Q&A describes customer and CEO/role work; economics are incomplete. WilmerHale, pp. 17–20 [investor-stated · moderate]
- Omniture — attribution counterexample: S-1 evidence points to Mark Gorenberg; Winblad's later in-kind distribution does not establish sourcing or board work. Omniture and The Knot lab [contemporaneous record · strong]
- Evidence: Four independent placements support the mechanism: WilmerHale 2005 edited Q&A, pp. 18–20; Full Ratchet 2014 transcript; Winblad 2019 signed essay; and OnlineEducation 2017 edited interview. SEC filings independently bound actual roles and shared power in MuleSoft and The Knot. [researcher inference · strong]
- Limits, failure modes, and exception ledger: Board tenure is not causation; recruiting can be founder displacement; “best fit” can conceal politics; partner capacity and reserves may prevent delivery. Omniture is Gorenberg-led; Powersoft, Wind River, Pets.com, and Napster point to Hummer/Barry/firm routes; Scopus is unassigned. No full board-minute set, intervention log, recruiting counterfactual, partner workload, or allocation/carry record surfaced. People/capital map [researcher inference · strong]
- Evolution and contradictions: The public record moves from early board narratives to an explicit 2005 partner-fit/CEO framework and later stage-capacity language. Successor-fund rosters and emeritus status bound continuity. A later in-kind distribution from Omniture does not retroactively establish sourcing or board work. [researcher inference · strong]
- Modern VC translation (as of 2026-08-21): Add model/data governance, cybersecurity, AI evaluation, and distributed-team design to the board bottleneck map. Track partner hours, intervention hypothesis, decision rights, founder consent, and outcome. Give credit separately to source, sponsor, approver, board contributor, recruiter, operator, and vehicle; do not convert firm ownership into a personal return claim. [researcher hypothetical · strong]
Evidence gaps and candidate models
| Candidate | Disposition | Why it is not a separate supported model | Evidence needed to promote it |
|---|---|---|---|
| High-cadence network/customer sourcing; “river of innovation” | Absorbed into capability-backed specialization | It is a channel and information mechanism, not a distinct decision rule. | Dated source-to-decision logs and rejected-deal cohort showing incremental selection quality. |
| Opportunist/pattern-convergence versus founder vision | Absorbed across specialization, market, and re-underwriting | Public language is descriptive and retrospective; no standalone procedure or three independent applications. | Original pattern maps, contemporaneous decisions, and false-positive/false-negative tests. |
| Incumbents as customers, partners, talent pools, and exits | Absorbed into market diligence and board ensemble | Useful tactics serve different decisions; exit access is not buyer validation and talent access is not sourcing alpha. | Three cases tying a specified incumbent tactic to a contemporaneous decision and counterfactual outcome. |
| Capital efficiency as advantage and low barrier | Context, not standalone model | The Charlie Rose record contains both effects but no portfolio rule, pricing threshold, or reserve response. | Stage-specific capital-efficiency screen, ordinary cases, and allocation evidence. |
| Slow yes / fast no | Absorbed into staged proof and re-underwriting | It describes cadence without a public stopping rule; “slow” can become indecision. | Decision-time distribution, rejection reasons, reversal rules, and later outcomes. |
| “Kool-Aid,” then regain distance | Absorbed into re-underwriting | One vivid metaphor specifies the psychological problem but not a distinct implementable process. | Independent applications showing who re-underwrote, what evidence changed, and the resulting action. |
| Patience for five-plus years | Absorbed into re-underwriting and vehicle context | Duration without reserve and stop rules can rationalize sunk-cost escalation. | Follow-on ledger, opportunity cost, kill criteria, and matched long-duration cohort. |
| Calm, urgency, role acceptance, and joy from Lessons From A Giant | Auxiliary people/governance hypothesis | One sports-analogy essay; transfer to investing is not demonstrated. | Independent investment cases with contemporaneous behavior and outcome controls. |
| Measure outcomes, not likability from “Ads Worth Sharing” | Auxiliary evidence-design hypothesis | The essay summarizes TED/Ace Metrix data, not Winblad's study, and has no direct investing-case application. | Investment cases where measured customer behavior reversed expert judgment. |
| Failure is acceptable / “40% fail” | Excluded as standalone rule | The stated rate lacks a defined cohort, basis, or documented process response; tolerance is not a decision procedure. | Complete vintage denominator, write-offs, stop decisions, reserves, and postmortem-to-rule changes. |
| Physical proximity / first ten employees | Contextual mechanic | Early geography and company-building capacity matter, but MuleSoft/global teams supply a later boundary. | Comparative remote/local cases and measured intervention effects. |
| Ask good questions | Observed style, not a model | Churchill moderator turns and interview questions reveal interests but no specified decision procedure. | Repeated question set tied to decisions, updates, and outcomes. |
| Same job description for 30 years | Rejected as literal continuity claim | Fund retrenchment, VII/VIII rosters, Aspenwood emeritus status, and 2026 ADV legacy-VI record establish role boundaries. | Governing documents showing continuous authority and economics, which did not surface. |
The inventory is not capped at six for convenience. Candidates were merged when they were mechanisms, channels, cadence labels, or context for a broader supported rule; they were excluded when they lacked a reusable procedure, independent placements, three grounded cases, or a falsifiable application. Promotion requires the evidence named above, not additional repetition of the same retrospective phrase. [researcher inference · strong]
What the evidence supports
The strongest defensible conclusion is narrower than a claim of proven personal investing alpha. The record supports Winblad as an important software operator who helped build an unusually early software-specialist venture institution and articulated a durable public method: use operating competence to improve information quality, start with an accessible buyer and budget, underwrite adoption dependencies, raise the proof threshold by financing stage, test people for learning and values, and use a complementary board team. The mechanism is plausible and unusually well documented in her direct voice, but complete decisions, rejected companies, partnership allocations, and same-basis fund cash flows are unavailable. The package therefore calls this a researcher inference · moderate, not a verified return premium. Profile, falsifiable edge thesis · WilmerHale Q&A, printed pp. 16–21 · 2019 signed retrospective, mandate and portfolio paragraphs
The biography supplies credible formation evidence without converting chronology into destiny. Winblad studied mathematics and business, worked in business systems, co-founded and operated Open Systems, and then co-founded Hummer Winblad in 1989. Those facts make later software specialization intelligible; they do not prove that the background caused superior selection. The acquisition year, Open Systems proceeds, Fund I fundraising count and LP identity, and the meaning of committed versus investable capital conflict across accounts and remain explicitly unresolved. Berkeley oral history, printed pp. 1, 4–13, 28–31 · St. Thomas profile, “Always a Coach”
The best investment evidence is company- and team-specific. T/Maker is well supported as the first investment and a Winblad board relationship, although both check and return figures conflict. Hyperion/Arbor has a credible Winblad board route. MuleSoft has primary evidence of Winblad's board service from September 2006, HWVP V/VI holdings, and shared voting/dispositive power among Hummer, Winblad, and Kertzman. Voltage preserves a useful, ordinary diligence account rather than only a celebrated outlier. Stanford introduction page, inline transcript · MuleSoft S-1/A, directors and principal stockholders · MuleSoft Schedule 13G, Items 4–6 · WilmerHale, printed pp. 17–18
The adverse record is substantive. Slate is a disclosed timing failure. Pets.com is a firm/John Hummer loss control, not a Winblad personal miss. Napster demonstrates known legal-operability risk, firm operating intervention, and a later records-preservation failure; the reviewed orders do not establish that Winblad personally infringed copyright. Liquid Audio's proxy records fiduciary-duty allegations naming Winblad and dismissal with prejudice under a 2003 agreement, but no personal adjudication. Pets.com 10-K, business, liquidation, and principal-holder sections · Napster 2006 sanctions order, Duty to Preserve, Sanctions, and Conclusion · Liquid Audio PRE 14A, “Legal Proceedings”
What could falsify the thesis
The favorable thesis predicts that original memoranda would identify buyer budgets, adoption constraints, stage-matched proof, and team gaps before outcomes; ordinary and losing deals would show the same gates; board records would connect a named intervention to a later milestone; and same-basis fund cash flows would retain strength after removing the largest outcome and controlling for vintage and vehicle. It also predicts that partner records would assign Winblad material sourcing, sponsorship, and governance responsibility rather than merely later narration.
The strongest alternative is simpler: the early software mandate created valuable access during a powerful sector wave, while founders, John Hummer and later partners, customer/incumbent networks, favorable exit markets, and a few outliers explain more than repeatable personal selection skill. That account fits the incompatible Fund I stories, a one-LP HWVP III result near cost, later reported fund retrenchment, major wins attributed to other partners, the thin ordinary-deal record, and the inability to calculate a personal denominator. UC Regents report, PDF p. 1 row 48 · StrictlyVC, “Hummer Winblad Reboots” · Denominator reconciliation
The favorable thesis would be materially weakened by memos showing that its public rules were absent at entry, write-off schedules showing inconsistent stop discipline, board minutes showing ceremonial rather than causal involvement, or same-basis fund returns explained by one company. It would be strengthened by contemporaneous IC records, rejected-company logs, ordinary-company board evidence, complete fund cash flows, and independent founder/partner testimony that preserve the claimed mechanism. No reviewed source demonstrates that Slate, Napster, Liquid Audio, Pets.com, or the failed 1997 banner forecast caused a documented change to HWVP's later process. Charlie Rose, 02:16–02:30 · IAB 2001, banner-unit standards notice · Failure postmortems
Attribution and denominator audit
The canonical HWVP directory displayed 98 unique company pages when accessed on 2026-08-21. All 98 are represented once in the ledger: nine sufficiently reconstructed, seven researched but unresolved, and 82 firm-page-only unresolved. This is complete coverage of the live directory, not a lifetime portfolio or personal denominator. Dated public claims range from 16 Fund I companies to roughly 80, more than 90, 100-plus, and 150-plus; absent historical schedules and alias reconciliation, lifetime coverage and a personal hit rate are not computable. Official directory · Source-map coverage assessment
The package preserves material team boundaries:
- T/Maker and Hyperion/Arbor have credible Winblad board routes, but their original IC allocations and complete economics are unavailable. T/Maker lab · Hyperion/Arbor lab
- Powersoft and Wind River are attributed by the firm pages to John Hummer; their exit values are not Winblad proceeds. Powersoft page · Wind River page
- MuleSoft is a Winblad board case with shared Hummer/Winblad/Kertzman vehicle control, not a solo ownership result. MuleSoft S-1/A · Schedule 13G
- Omniture's S-1 names Mark Gorenberg as the board partner; Winblad's Form 4 records later distribution mechanics, not sourcing. Omniture S-1, Certain Relationships · Winblad Form 4
- Pets.com's filing names John Hummer as director and HWVP entities as 13.5% holders. Pets.com 10-K
- Napster's operating intervention belongs principally to Hank Barry and the Hummer entities; the court's discussion of Winblad's email does not make the investment or adjudication personal. 2005 order, Background pp. 3–4 · 2006 order, Conclusion
Vehicle figures remain basis-specific. Fund I has three incompatible public bases. The UC HWVP III row is one LP's net result: $10 million paid in, $10.393 million total value/distributions, 1.04x TVPI, and 1.0% net IRR as of 2020-06-30. The SDCERS HWVP V interest is a discounted secondary bought by StepStone, reporting $1.529 million contributed, $4.405 million distributed, about 2.9x, and 47.3% IRR; it is not the original fund or LP experience. The 2026 ADV names only HWVP VI, reports $68.674 million gross asset value and 34 beneficial owners, and lists Hummer, Winblad, and Kertzman as code-C owners/managing members/control persons. Funds VII/VIII omit the founders from Form D related-person rosters, but that does not prove zero residual economics. UC Regents, PDF p. 1 row 48 · SDCERS/StepStone, printed p. 21 · SEC ADV, CRD 159709, 2026 annual amendment · Fund VII original Form D
Transfer limits for modern VCs
The portable core is procedural: prove a real capability edge; trace user to buyer, budget, and renewal; map adoption dependencies against runway; pre-register stage-specific evidence and kill conditions; evaluate observed learning and conflict behavior; and assign post-check work to named people. These practices create auditable decisions. The six mental models translate them into twelve-part field guides with applicability signals, misuse warnings, cases, failure controls, and dated 2026 hypotheticals. Mental-model field guide
The least portable elements are sector labels, relationship prestige, retrospective winner stories, and metaphors mistaken for laws. Modern AI products can exhibit fast trials without durable budget ownership, retention, data rights, reliable unit costs, security approval, or defensibility. The package properly treats current AI and agentic-software examples as researcher hypotheticals, not claims about Winblad's historical practice. Philosophy, modern translation
Vehicle and legal conditions also limit transfer. A company can be attractive while the ownership, reserve plan, duration, governance rights, or liquidity route makes the investment unattractive. Explosive adoption cannot substitute for legal operability or litigation-grade records, as Napster demonstrates. A secondary buyer's return cannot be used as evidence for original LP economics, and a 2026 legacy adviser filing cannot be applied automatically to successor Funds VII/VIII. These are constraints on using the doctrine, not footnotes to it. Vehicle analysis · Napster lab
Unresolved evidence
The decisive missing objects are original investment memoranda and IC votes; rejected-company logs; complete fund-by-fund cash flows, partnership agreements, reserve schedules, fee and carry allocations; financing cap tables and distribution waterfalls; board minutes and intervention outcomes; ordinary and losing company files; and independent founder, partner, executive, and LP testimony. Without them the package cannot estimate personal MOIC, IRR, hit rate, loss rate, or causal board value.
Important narrower gaps remain: Open Systems formation/acquisition records; the St. Paul Companies versus State Farm LP conflict; T/Maker's $300,000 versus $750,000 check and 3x versus 5x return; a complete Fund I schedule; original theses for Liquid Audio, Pets.com, and Napster; Napster's final settlement economics and any later process reform; Liquid Audio's January 2 agreement and allocation records; and the exact legal/economic transition from founder-era vehicles to Funds VII/VIII and Aspenwood. Uncertainty and retrieval ledger
Direct voice is rich but archival decision evidence is thin. The package processed nine priority writings and twelve priority talks, while preserving exact access boundaries for the 1992 excerpt, the metadata-only 1990 book and 2001 article, dynamic but full-body LinkedIn pages, paywalled press, and the absence of public LP letters, IC memos, or a dedicated Winblad/HWVP archive. Writings coverage · Talks retrieval frontier · Sources coverage assessment
Corrections made during review
| Claim before review | Primary-source reopen | Correction and affected documents |
|---|---|---|
| Liquid Audio's fiduciary/shareholder action had a proposed $150,000 company-funded settlement | The PRE 14A's “Legal Proceedings” section says the shareholder action was dismissed with prejudice under a January 2, 2003 agreement. The separately described $150,000 payment went to Network Commerce to settle a patent-infringement action. Liquid Audio PRE 14A, “Legal Proceedings” | Corrected. sources.md, _profile.md, investments.md, and investmentphilosophy.md now separate the two proceedings, state that no shareholder-action amount is disclosed, and preserve the no-personal-adjudication boundary. |
| Five Stanford transcript-PDF URLs were still treated as live pinpoint sources | All five PDF routes return 404; the official Stanford video/AV pages expose live inline transcripts for the same clips. Introduction · Customers · Assumptions | Corrected. All 33 URL occurrences now use the live official pages, and stale PDF-page locators were replaced with inline-transcript/clip locators. |
| “Class of 2013” was marked metadata-only/truncated | The canonical LinkedIn route now exposes the complete signed body, including education, early-work, career-learning, and 2001-commencement provenance. Winblad 2013 | Corrected. The source row, note, writings corpus accounting, source-by-source analysis, chronology, and retrieval boundary now treat it as full/dynamic. |
| The banner-ad forecast was called failed using only the prediction source | An official IAB notice still documented banner guidelines and units in February 2001. IAB 2001, standards notice | Corrected. One checked outcome-source row was added; _profile.md, talks.md, the Charlie Rose note, and this review now pair the 1997 prediction with dated outcome evidence. The final source-map baseline is 81 = 57 checked + 24 unchecked, with priorities 32/36/13. |
| The first ordinary-claim review mislabeled “Lessons From A Giant” as a Steve Jobs essay and linked a dead LinkedIn route | The complete signed article is about the 2012 San Francisco Giants and manager Bruce Bochy and uses four explicit leadership headings. Winblad 2012, complete article | Corrected. The ordinary-claim row now states the actual analogy and uses the canonical live article. |
| The first review draft cited the wrong adviser CRD | The Form ADV identifies Hummer Winblad Venture Partners as CRD 159709. 2026 Form ADV, cover and Item 1.E | Corrected. All review references now use CRD 159709 and the canonical filing PDF. |
Central-claim audit trail
The central audit re-opened the claims most capable of changing the thesis: causal biography, historical priority, edge/falsifiers, quotations, economics, Pareto ordering, deal rationales, team credit, vehicles, legal/failure lessons, denominator, peers, and modern premises.
| Central claim | Package location inspected | Source and locator control | Result |
|---|---|---|---|
| The edge is a software-specific information and company-building system, not verified personal alpha | profile, edge thesis; philosophy, snapshot | 2019 essay, mandate/portfolio paragraphs; WilmerHale, pp. 16–21 | Pass. Mechanism, domain, period, alternatives, predictions, and overturning evidence are explicit; alpha is not claimed. |
| Mathematics/business, operating experience, and entrepreneurship are formation evidence rather than proven causes | profile, opening | Berkeley oral history, pp. 1, 4–13 | Pass. The degree is not mislabeled computer science and causal language is inference-bounded. |
| HWVP's software-only historical priority is scoped and the unsafe earliest-woman superlative is rejected | profile, formation; sources, historical control | Charlie Rose, host introduction 00:07–00:36; 2019 essay; Science History Institute, Campbell-White/MedVenture finding aid | Pass. Software priority remains reported/firm-claimed rather than independently proved; Campbell-White's 1986 firm makes the unscoped gender superlative false. |
| All direct quotations are short, source-local, and not synthesized from inaccessible text | All 21 notes enumerated in the source map | 25 actual quote bullets checked against note locators, including Charlie Rose VTT timestamps, 2019 paragraph anchors, and the reprocessed 2013 essay note; five explicit no-quote bullets preserve the Berkeley, two CNBC, JIT, and book access boundaries | Pass. The longest retained quote is 19 words and none exceeds 25; restricted Berkeley text is paraphrased rather than quoted. |
| Fund I has three conflicting economic bases and no personal or audited return claim | investments, economic rank and vehicles | Wired 1996, Fund I passage; WilmerHale, p. 17; 2019 essay, Fund I paragraph | Pass. $27m→$252m, $35m→about $250m/50% annual, and $35m→over 10x are not collapsed. |
| Pareto analysis separates economic, historical, and learning ranks without inventing an 80/20 percentage | investments, opening | Filing, LP, direct-voice, and court anchors adjacent to each rank | Pass. Three directional rankings preserve confidence, attribution, and denominator limits. |
| T/Maker is the first-deal case, but check and return figures conflict | T/Maker lab | Stanford introduction, inline transcript, T/Maker paragraph; 2019 essay, T/Maker paragraph | Pass. $300k/$750k and 3x/5x remain unresolved; no preferred version is invented. |
| Hyperion is Winblad-associated; Powersoft and Wind River point to Hummer; Scopus is unassigned | Fund I attribution lab | official company pages; Oracle/Hyperion filing exhibit; Sybase/Powersoft 10-K; Intel/Wind River 10-Q | Pass. Exit values are not converted into Winblad credit or proceeds. |
| MuleSoft's board and holdings are documented but governance power is shared | MuleSoft lab | S-1/A, directors/principal holders; 13G, Items 4–6 | Pass. September 2006 board start, V/VI holdings, and shared control are separate from sourcing and return. |
| Omniture and The Knot filings reveal mechanics, not original theses or personal return | filing-mechanics lab | Omniture S-1; Omniture Form 4; The Knot Form 4 | Pass. Gorenberg board credit and vehicle/pecuniary-interest limits are preserved. |
| Voltage is an ordinary diligence case with about twenty CIO references and an HP outcome, not a reconstructed return | Voltage lab | WilmerHale, pp. 17–18; firm page | Pass. Diligence is retrospective witness evidence; terms/economics stay unknown. |
| Pets.com is a firm/John Hummer failure, not a personal Winblad miss | Pets.com lab | 10-K, business/liquidation/principal holders | Pass. 13.5%, John board role, cessation, delisting, and $0.09 initial distribution are filing-grounded. |
| Napster had known legal risk and firm intervention; sanctions do not establish Winblad personal copyright liability | Napster lab | 2005 order, Background pp. 3–4; 2006 order, Duty, Sanctions, Conclusion | Pass. ~$13m, pending suits, Barry's role, preservation duty, preclusion/adverse inference/fees, and denial of default are accurately bounded. |
| Liquid Audio's fiduciary action did not have a disclosed $150,000 settlement amount | profile, adverse record; legal postmortem | PRE 14A, “Legal Proceedings” | Pass after material correction. The $150,000 payment is now assigned only to the separate Network Commerce patent action. |
| UC III, SDCERS V, and ADV figures are vehicle-specific and not interchangeable | vehicle analysis | UC row 48; SDCERS p. 21; SEC ADV, CRD 159709 | Pass. Original-LP, secondary-buyer, and current-adviser bases are never combined. |
| Founder-era control and later succession are separated | profile, succession; vehicle analysis | Fund VII Form D; Fund VIII Form D; SEC ADV, CRD 159709 | Pass. Omission from VII/VIII rosters is not treated as proof of zero residual economics. |
| Failure lessons do not invent later process reform | philosophy, failures; postmortems | Slate, Pets, Napster, and Liquid Audio primary/direct routes above | Pass. Missing stop, reserve, and policy-change records are disclosed. |
| Peer comparison is dimensional, not a personal-return ranking | philosophy, peers | Arthur Rock HBR; Doug Leone, Seven Questions; Martin Casado, Emerging Architectures | Pass. Only completed peers are used and era/vehicle/evidence limits are explicit. |
| Modern examples are dated researcher applications, not retrospective Winblad claims | modern translation; six models | Contemporary premises are kept separate from historical source links in each model | Pass. All six state applicability signals, likely misuse, and a dated hypothetical. |
| The 98-logo denominator cannot yield a lifetime or personal hit rate | denominator | official directory, accessed 2026-08-21; dated count sources in coverage assessment | Pass. 9/98 reconstructed coverage is named; lifetime coverage is explicitly not computable. |
| The strongest skeptical case survives removal of the heroic narrative | philosophy, skeptical case; review, falsifiers | Fund conflicts, III/V controls, team attribution, adverse cases, and denominator evidence above | Pass. Institutional importance and public doctrine remain supportable; durable personal alpha remains unproved. |
Ordinary-claim audit trail
The reproducible spread takes two externally verifiable non-central claims from each of the seven pre-review root documents and two correction-trail claims from this review, for sixteen claims across all eight core documents. Central theses, Pareto ranks, and legal/economic conclusions audited above were excluded.
| # | Ordinary claim | Document | Source and locator | Result |
|---|---|---|---|---|
| 1 | Winblad combined mathematics and business rather than earning a computer-science degree | profile, opening | Berkeley oral history, printed pp. 1, 4–6 | Pass. |
| 2 | Public accounts disagree on the Open Systems start/sale date and proceeds | profile, opening | Berkeley, printed pp. 7–13; St. Thomas profile | Pass. The conflict is preserved. |
| 3 | The Object-Oriented Software catalog record names Winblad, Edwards, and King, Addison-Wesley, 1990, 291 pages, ISBN 0201507366 | sources, direct writings | Karlsruhe Institute of Technology catalog, bibliographic record | Pass. Re-opened catalog metadata supports the row. |
| 4 | The source map treats the 1992 enterprise-era article as an excerpt rather than a full article | sources, direct writings | CHM scan, PDF p. 66 / printed Hotline p. 23 | Pass. Only the reproduced passage is analyzed. |
| 5 | The 2012 lessons essay uses the San Francisco Giants and manager Bruce Bochy to organize four leadership lessons | writings, Lessons from a Giant | signed LinkedIn article, “Focus Forward” through “Find Joy in the Game” | Pass after correction. The four headings are Focus Forward; Stay Calm But Manage with Urgency; Choose the Best Team not Just Top Players; and Find Joy in the Game. |
| 6 | The 1992 excerpt focuses on business integration and migration, not object technology alone | writings, enterprise era | CHM scan, PDF p. 66 / printed p. 23 | Pass. The reproduced paragraphs support the bounded interpretation. |
| 7 | Winblad predicted banner ads would be gone by the end of 1997 | talks, Charlie Rose | official Charlie Rose VTT, 02:16–02:30; IAB 2001, banner-unit standards notice | Pass. The prediction and dated failure control are both reopened. |
| 8 | Winblad said HWVP would do at most ten new companies from about 500 pitches | talks, Full Ratchet | publisher transcript, answer beginning “At most, we'll do ten” | Pass. It is a stated cadence, not a verified historical acceptance rate. |
| 9 | All 98 company-detail pages were processed; 66 name a board person, 88 have a category, and 35 have an outcome phrase | investments, portfolio forensics | official directory and linked detail pages | Pass. Mechanical page-field counts reconcile; fields are firm-stated, not independent outcomes. |
| 10 | Voltage diligence reportedly included roughly twenty CIO organizations | investments, Voltage | WilmerHale, printed pp. 17–18 | Pass. Terms and economics remain unknown. |
| 11 | Stage economics are described as seed feasibility, A-round market proof, then later scaling evidence | philosophy, picking | Full Ratchet publisher transcript, stages answer | Pass. Current application is separately labeled. |
| 12 | Winblad warns that visible culture should affect whether a person joins a company | philosophy, people | OnlineEducation interview, culture paragraphs | Pass. The package does not convert the statement into demographic scoring. |
| 13 | The adoption model's technical anchor is the 1992 discussion of integration, reuse, and enterprise migration | models, adoption bridge | CHM scan, PDF p. 66 / printed p. 23 | Pass. The reconstructed model is inference-labeled. |
| 14 | The board-ensemble model treats recruiting and role complementarity as work, not proof of causal value | models, board ensemble | WilmerHale, printed pp. 18–20 | Pass. Board counterfactuals remain unavailable. |
| 15 | The 2013 career essay identifies itself as an adaptation of Winblad's spring 2001 St. Thomas commencement address | review, correction trail | signed LinkedIn article, final note | Pass. The provenance is explicit in the exposed full body. |
| 16 | The live Stanford introduction route exposes the session transcript after the old transcript-PDF route failed | review, correction trail | official Stanford AV page, inline transcript | Pass. The live official page and paragraph locator replace the dead PDF/page locator. |
Mechanical reconciliation
| Check | Observed result | Status |
|---|---|---|
| Core documents | 8/8 after adding this review | Pass |
| Pre-review root documents | 7/7 substantive; next nonblank after H1 is H2 | Pass |
| Source-map rows | 81 = 57 checked + 24 unchecked | Pass |
| Source priorities | 32 ★★★ + 36 ★★ + 13 ★ | Pass |
| Notes | 21 = 9 writing + 12 talk | Pass |
| Note schema | 21/21 contain all six required H2 sections | Pass |
| Investment ledger | 98 unique sequential rows, IDs 1–98 | Pass |
| Ledger states | 9 sufficiently reconstructed + 7 researched/unresolved + 82 firm-page-only unresolved | Pass |
| Decision exercises | 8 labs; each has invest/pass, kill, terms/ownership, and next-check prompts | Pass |
| Philosophy | 17/17 required numbered H2 sections | Pass |
| Mental models | 6 models × 12 labeled bullets | Pass |
| Grounded model cases | 24 total; each model has 3–5 including a boundary/counterexample | Pass |
| Liquid Audio drift search | Every current factual statement assigns $150,000/$150k only to Network Commerce's separate patent action; the sole contrary wording is preserved explicitly as the “claim before review” in the correction trail |
Pass after correction |
| Canonical HWVP directory | Zero live citations use /companies/index.html; one intentional retrieval-ledger mention records that dead old route |
Pass |
| Markdown whitespace | git diff --check clean |
Pass |
Twenty-point acceptance matrix
| # | Required improvement | Pass/fail | Document and section inspected | Correction or continuation required |
|---|---|---|---|---|
| 1 | Deep chronological investment biography | Pass | profile, full chronology | None. Formation, belief, action, outcome, conflicts, and causal limits connect without invented scenes. |
| 2 | Falsifiable thesis of the edge | Pass | profile, edge thesis; philosophy, snapshot | None. Mechanism, domain/period, predictions, alternatives, denominator, and overturning evidence are explicit. |
| 3 | Ex-ante deal reconstruction | Pass | eight forensic labs | None. Known/unknown information precedes outcomes; unavailable terms and dissent remain unknown. |
| 4 | Pareto economic, historical, and learning analysis | Pass | three ranked views | None. Ranks are directional, confidence-labeled, attribution-aware, and make no unsupported 80/20 calculation. |
| 5 | No premature completion or placeholders | Pass | All eight root documents and their openings | None. Each document is substantive; no status preamble, phase stub, or future placeholder remains. |
| 6 | Searched portfolio denominator and coverage | Pass | denominator; 98-row ledger | None. Live-directory coverage is 98/98; sufficiently reconstructed coverage is 9/98; lifetime coverage is not computable. |
| 7 | Comprehensive source-by-source writings | Pass | nine analyses; source map | None. Accessible priority items have notes and deep subsections; partial/metadata routes disclose exact limits. |
| 8 | Detailed, cited mental models | Pass | six-model field guide | None. Each model has 12 labels, 3–5 cases, multiple placements/sources, failure controls, and an attempted-route ledger. |
| 9 | Dated modern-VC translation | Pass | writings translation; philosophy translation; all models | None. Signals, changed assumptions, misuse, and dated hypothetical status are explicit. |
| 10 | Full failure postmortems | Pass | failure/legal postmortems; Slate, Pets, and Napster labs | None after Liquid Audio correction. Missing thesis, capital, stop, and process-change evidence is disclosed. |
| 11 | Partner, team, and decision-rights attribution | Pass | profile map; investments map | None. Winblad, Hummer, Barry, Kertzman, Gorenberg, founders, vehicles, and unknown IC roles remain separate. |
| 12 | Vehicle economics and incentive analysis | Pass | vehicle chapter; philosophy, vehicle | None. Fund I conflicts, III/V basis limits, ADV/Form D control, compensation gaps, succession, and modern comparison are covered. |
| 13 | Historical market, regulatory, and base-rate context | Pass | historical context; philosophy, environment | None. Later evidence is labeled and absent contemporaneous numerical base rates are not invented. |
| 14 | Direct voice and primary-archive exhaustion | Pass | source coverage; writings boundary; talks frontier | None. Nine writings and twelve talks are processed; archive, paywall, dynamic, metadata, and nonpublic-record boundaries are named. |
| 15 | Pinpoint citations | Pass | Central and ordinary audit trails; all root documents | None. Material claims use pages, printed pages, timestamps, filing sections/tables, paragraph openings, or dated snapshots. |
| 16 | Explicit attribution and evidence labels | Pass | writings; talks; investments; models | None. Investor statement, retrospective witness, firm statement, contemporaneous record, researcher inference, and insufficiency stay distinct. |
| 17 | Strongest case against greatness | Pass | philosophy, skeptical case; review, falsifiers | None. Outliers, access, team/vehicle attribution, denominator, survivorship, economics, era, and contradictions are tested. |
| 18 | Comparison with completed peers | Pass | Rock, Leone, Casado comparison | None. Three completed, dimension-matched peers are used; no personal-return ranking is attempted. |
| 19 | Investment-committee decision exercises | Pass | eight labs; study guide | None. Each lab has four no-hindsight prompts followed by actual decision/outcome; Slate, Pets, and Napster are adverse cases. |
| 20 | Reader learning architecture | Pass | profile chronology; study guide/glossary/checklists; people and capital maps | None. Relative links form a Markdown-native learning path without a bespoke site component. |
Direct writings and technical record
- ★★★ | Ann Winblad — “Auditioning the Future of Software: A 30-Year Journey” | https://www.linkedin.com/pulse/auditioning-future-software-30-year-journey-ann-winblad | 2019-11-01 | signed first-person essay | Fully processed anniversary account; self-reported Fund I, LP, IPO, and T/Maker figures remain explicitly unreconciled. Note: notes/w-auditioning-future-software.md. (A; full/dynamic; accessed 2026-08-21)
- ★★★ | Object-Oriented Software — library catalog record | https://katalog.bibliothek.kit.edu/bib/1102925 | 1990 | coauthored technical book/catalog | Processed to metadata boundary only: Ann L. Winblad, Samuel D. Edwards, David R. King; xviii + 291 pages; ISBN 0201507366; no legitimate full text or chapter allocation found. Note: notes/w-object-oriented-software.md. (A for metadata; metadata-only; accessed 2026-08-21)
- ★★ | “A Just-in-Time Software-Based World” | https://doi.org/10.1145/365181.365237 | 2001-03 | coauthored CACM article | Processed to exact metadata/access boundary: Mark Gorenberg then Ann Winblad, CACM 44(3), p. 125; ACM closed/403 and OpenAlex reported no repository full text. Note: notes/w-just-in-time-software-world.md. (A for metadata; metadata-only; accessed 2026-08-21)
- ★★ | “Entering the Enterprise Era” — archived excerpt | https://archive.computerhistory.org/resources/access/text/2024/06/102739322-05-0004-acc.pdf | 1992-08-03 | signed Computerworld essay/reprinted excerpt | Processed two-paragraph excerpt only at CHM compilation PDF p. 66 / Hotline printed p. 23; full article unavailable. Note: notes/w-entering-enterprise-era.md. (A for attributed excerpt; partial; accessed 2026-08-21)
- ★ | WIRED Staff — “Street Cred: ReadMe,” two Winblad-attributed comments | https://www.wired.com/1997/08/street-cred-readme-2/ | online 1997-08-28; September issue | staff feature/attributed reading comments | Processed only the two recommendations attributed to Winblad; the page is not signed or authored by her. Note: notes/w-wired-street-cred-readme.md. (A for attributed comments/B for framing; full short item; accessed 2026-08-21)
- ★★★ | WilmerHale — IT Compensation Study interview with Ann Winblad | https://www.wilmerhale.com/-/media/files/wilmerhale_shared_content/files/editorial/publication/2005compstudy_it_abridged.pdf | 2005 | edited interviewer-led Q&A in industry study | Processed printed pp. 16–21: fund/cycle claims, diligence, CEO/team, partner fit, corporate R&D, talent, and global teams; retained as direct-voice hybrid, not authored writing. Note: notes/w-wilmerhale-it-compensation-interview.md. (A for direct answers/B for edited study; full; accessed 2026-08-21)
- ★★ | Ann Winblad — “Lessons From A Giant” | https://www.linkedin.com/pulse/20121104233131-32875-lessons-from-a-giant | 2012-11-04 | signed LinkedIn essay | Processed leadership analogy under “Focus Forward,” “Stay Calm,” “Choose the Best Team,” and “Find Joy”; investment application remains inference. Note: notes/w-lessons-from-a-giant.md. (A; full/dynamic; accessed 2026-08-21)
- ★ | Ann Winblad — “Ads Worth Sharing: Measuring Extraordinary Creative” | https://www.linkedin.com/pulse/20121106193742-32875-ads-worth-sharing-measuring-extraordinary-creative | 2012-11-06 | signed LinkedIn essay | Inspected marketing/measurement writing; optional source note preserves the limited staff extraction and does not invent body examples. Note: notes/w-ads-worth-sharing.md. (A; full/dynamic route, bounded extraction; accessed 2026-08-21)
- ★ | Ann Winblad — “Class of 2013: Don’t Sweat Your First Job” | https://www.linkedin.com/pulse/20130521101113-32875-class-of-2013-don-t-sweat-your-first-job | 2013-05-21 | signed LinkedIn essay adapted from a 2001 commencement address | Processed the full body for education and early-career chronology, critical thinking/problem solving/lifelong learning, first-job optionality, and the education-IRR analogy. Note: notes/w-class-of-2013-first-job.md. (A; full/dynamic; accessed 2026-08-22)
Oral history, identity, firm, and archive records
- ★★★ | UC Berkeley — Ann Winblad oral history catalog | https://digicoll.lib.berkeley.edu/record/103613 | interview 2012-03-18 | institutional catalog/Audio 1–2 index | Processed with the transcript as one oral-history family; catalog supplies date/audio segmentation. Note: notes/t-berkeley-oral-history.md. (A; full catalog; accessed 2026-08-21)
- ★★★ | UC Berkeley — Ann Winblad oral history transcript | https://digicoll.lib.berkeley.edu/nanna/record/218713/files/winblad_ann.pdf?registerDownload=1&version=1&withMetadata=0&withWatermark=0 | interview 2012-03-18 | oral-history PDF, viii + 28 printed pages | Processed biography, formation, Fund I, Slate/Wind River, and contradiction evidence; printed p. ii requires permission to quote, so the dossier paraphrases only. Note: notes/t-berkeley-oral-history.md. (A; full; accessed 2026-08-21)
- ★★★ | Stanford eCorner — Ann Winblad biography | https://stvp.stanford.edu/people/ann-winblad | current archive page | institutional biography | Useful institutional cross-check for education, Open Systems, firm founding, and boards; biography repeats subject/firm claims. (A/B; full; accessed 2026-08-21)
- ★★★ | University of St. Thomas — “Always a Coach” | https://news.stthomas.edu/publication-article/always-a-coach/ | 2000 | alma-mater profile/interview | Detailed operating and venture chronology, 1983/$15m sale claim, T/Maker amount, and selected-portfolio/loss counts; reconcile against oral history and filings. (A/B; full; accessed 2026-08-21)
- ★★★ | Aspenwood Ventures — team directory | https://aspenwoodvc.com/team/ | current; accessed 2026-08-21 | official team page | Current primary route for Winblad’s emeritus/adviser status and succession positioning; legal/economic rights are not disclosed. (A; full; accessed 2026-08-21)
- ★★ | Hummer Winblad — legal page | https://hwvp.com/legal.html | current/archival | firm legal disclosure | Processed as an entity-numbering caution: the page labels Fund V’s GP “Hummer Winblad Equity Partners VII,” inconsistent with SEC records and treated as a drafting error, not legal evidence for Fund VII. (A; partial; accessed 2026-08-21)
- ★★ | Hummer Winblad — John Hummer biography | https://hwvp.com/team/john-hummer.html | archived/current site | firm biography | Processed for Powersoft, Wind River, Pets.com, and Napster firm/John attribution; first-party board claims are cross-checked against issuer/court records where available. (A/B; full; accessed 2026-08-21)
- ★★ | Hummer Winblad/Aspenwood — first-party company feed | https://www.linkedin.com/company/hummer-winblad-venture-partners | current/dynamic | company announcement feed | Rebrand, reported
$70mfinal close, and next-generation team announcement; dynamic access and self-description require archival capture. (A; partial/dynamic; accessed 2026-08-21) - ★★★ | Hummer Winblad — companies directory | https://hwvp.com/companies/ | canonical live directory; accessed 2026-08-21 | official portfolio directory | Processed the exact 98-entry directory and all 98 linked official detail pages into investments.md. Detail pages expose 66 named board attributions and 35 firm-stated outcome phrases, but remain first-party retrospective claims; aliases displayed by the firm stay one row, and no logo/board label is treated as personal return evidence. (A; full; accessed 2026-08-21)
- ★★★ | Hummer Winblad Venture Partners — Form ADV | https://reports.adviserinfo.sec.gov/reports/ADV/159709/PDF/159709.pdf | regulator filing; current report | SEC/IAPD adviser record | Processed 2026-03-26 annual amendment: Hummer Winblad Operating Company LLC; Fund VI private-fund record; Schedule A ownership/control; kept legal control distinct from Aspenwood website titles. Used Items 1 and 7.B.1 and Schedule A in investments.md. (A; full PDF; accessed 2026-08-21)
- ★★ | Science History Institute — Annette Campbell-White collection description | https://archives.sciencehistory.org/repositories/3/archival_objects/75870 | collection 1986–2014 | archival finding aid | Primary archival control that Campbell-White founded MedVenture in 1986; falsifies an unscoped “earliest woman VC founder” claim about Winblad. (A; full; accessed 2026-08-21)
- ★★ | Science History Institute — Annette Campbell-White oral history | https://digital.sciencehistory.org/works/4qlh3lg | oral history | archive/audio/transcript route | Independent historical-comparison route for earlier woman-led venture-firm chronology. (A; catalog/full varies; accessed 2026-08-21)
- ★★ | Computer History Museum — Patricia Cloherty oral history | https://archive.computerhistory.org/resources/access/text/2021/08/102792277-05-01-acc.pdf | 2021 | oral-history PDF | Records a venture career beginning in 1969; historical-control source, not a claim of identical founder status. (A; full; accessed 2026-08-21)
- ★★ | Mary Jane Elmore — angel-investing history | https://www.mjelmore.com/home-angel-investing | current | first-person professional history | Earlier West Coast woman VC-leadership route; self-published and should be paired with institutional archives later. (A/B; full; accessed 2026-08-21)
- ★ | Internet Archive — Hummer Winblad snapshot route | https://web.archive.org/web/*/http://www.humwin.com/ | 1990s–present | web archive | Route for removed team, portfolio, investment-criteria, and press pages; snapshot completeness and robots restrictions remain to be audited. (A/B; partial; accessed 2026-08-21)
- ★ | Computer History Museum oral-history catalog | https://www.computerhistory.org/collections/oralhistories/ | current catalog | archive search route | No dedicated Winblad oral history was found in the public catalog; relevant founder/partner witness interviews remain a next-phase lead. (A; catalog only; accessed 2026-08-21)
- ★ | Stanford Silicon Valley Archives | https://library.stanford.edu/libraries/silicon-valley-archives | current catalog | archive search route | No named Winblad/Hummer collection was identified in this run; useful for Don Valentine, software-industry, and venture context. (A; catalog only; accessed 2026-08-21)
Talks, interviews, and direct voice
- ★★★ | Stanford eCorner — introduction to Hummer Winblad and Mobius | https://stvp.stanford.edu/videos/introduction-to-hummer-winblad-and-mobius-venture-capital | 2004-02-25 | video/transcript | Processed as the entry point to one 46-minute classroom session; 13 official clips are consolidated in notes/t-stanford-ecorner-2004.md and never counted as independent witnesses. (A; full official clip/transcript set; accessed 2026-08-21)
- ★★★ | Stanford eCorner — introduction with inline transcript | https://stvp.stanford.edu/av/introduction-hummer-winblad-and-mobius-venture-capital | 2004-02-25 | official AV/transcript page | Processed biography, fund/vehicle figures, first-investment claim, and internal 113-meeting/5x conflicts; same session/note as every Stanford row. The former 2024 transcript-PDF route now returns 404, so this live inline-transcript route controls while the adjacent video row preserves the session entry. (A; full; accessed 2026-08-22)
- ★★★ | Stanford eCorner — Drivers for Software Innovation | https://stvp.stanford.edu/videos/drivers-for-software-innovation | 2004-02-25 | video/transcript clip | Processed innovation-driver framework inside the single 2004 session. Note: notes/t-stanford-ecorner-2004.md. (A; full; accessed 2026-08-21)
- ★★★ | Stanford eCorner — VC Words of Wisdom for Entrepreneurs | https://stvp.stanford.edu/videos/vc-words-of-wisdom-for-entrepreneurs | 2004-02-25 | video/transcript clip | Processed entrepreneur/fundraising advice inside the single 2004 session. Note: notes/t-stanford-ecorner-2004.md. (A; full; accessed 2026-08-21)
- ★★★ | Stanford eCorner — Trends in Seed and Series A Investing | https://stvp.stanford.edu/videos/trends-in-seed-and-series-a-investing | 2004-02-25 | video/transcript clip | Processed contemporaneous stage/market view; same-session dependence retained. Note: notes/t-stanford-ecorner-2004.md. (A; full; accessed 2026-08-21)
- ★★ | Stanford eCorner — Recent Investments | https://stvp.stanford.edu/videos/hummer-winblads-and-softbanks-recent-investments | 2004-02-25 | video/transcript clip | Processed candidate-deal/partner-comparison evidence with firm/team attribution boundary. Note: notes/t-stanford-ecorner-2004.md. (A; full; accessed 2026-08-21)
- ★★ | Stanford eCorner — Are Technologies Ahead of Their Time? | https://stvp.stanford.edu/videos/are-technologies-ahead-of-their-time | 2004-02-25 | video/transcript clip | Processed timing rule and Slate conflict inside the single session. Note: notes/t-stanford-ecorner-2004.md. (A; full; accessed 2026-08-21)
- ★★ | Stanford eCorner — Java and competing standards | https://stvp.stanford.edu/videos/the-java-standard-and-competing-technology-standards | 2004-02-25 | video/transcript clip | Processed as a dated, prospectively scoreable platform view. Note: notes/t-stanford-ecorner-2004.md. (A; full; accessed 2026-08-21)
- ★★ | Stanford eCorner — Linux and Microsoft | https://stvp.stanford.edu/videos/the-threat-of-linux-to-microsoft | 2004-02-25 | video/transcript clip | Processed as a dated, prospectively scoreable competitive forecast. Note: notes/t-stanford-ecorner-2004.md. (A; full; accessed 2026-08-21)
- ★★ | Stanford eCorner — 2004 optimism | https://stvp.stanford.edu/videos/2004-start-of-an-era-of-optimism | 2004-02-25 | video/transcript clip | Processed as a post-dot-com cycle forecast, not a timeless rule. Note: notes/t-stanford-ecorner-2004.md. (A; full; accessed 2026-08-21)
- ★★ | Stanford eCorner — assumption, customer, market, and offshore-development clip family | https://stvp.stanford.edu/av/keep-testing-your-core-assumptions | 2004-02-25 | four official clips/transcripts, consolidated row | Processed “Keep Testing Your Core Assumptions,” “How Consumer Markets and Enterprise Markets Drive the Software Industry,” “Outsourcing Software Development to Asia,” and “Customers Are Key,” including https://stvp.stanford.edu/videos/how-consumer-markets-and-enterprise-markets-drive-the-software-industry , https://stvp.stanford.edu/av/outsourcing-software-development-asia , and https://stvp.stanford.edu/av/customers-are-key . Note: notes/t-stanford-ecorner-2004.md. (A; full; accessed 2026-08-21)
- ★★★ | Charlie Rose — Ann Winblad interview | https://charlierose.com/videos/20230?autoplay=true | 1997 | broadcast interview/full VTT | Processed 22:43 official transcript/VTT: internet advertising, failed banner prediction, capital efficiency, 150/$30m fundraise account, assumption testing, and Gates chronology. Note: notes/t-charlie-rose-1997.md. (A for direct speech; full VTT; accessed 2026-08-21)
- ★★★ | TEDxBayArea — Ann Winblad | https://www.youtube.com/watch?v=HybHcXGvrGM | 2011 | official event video | Processed 18:40 video/captions for auditioning, failure tolerance, entry/fundraising, and education pipeline; machine-caption numbers were not trusted without validation. Note: notes/t-tedxbayarea-2011.md. (A for speech; full video/captions; accessed 2026-08-21)
- ★★★ | The Full Ratchet — “The Stages of Fundraising” | https://fullratchet.net/ep14-the-stages-of-fundraising-ann-winblad/ | 2014 | podcast/publisher transcript | Processed 40:50 full transcript for the stage proof ladder, Series A capacity, people/cash risks, corporate capital, Hyperion, and NuoDB; publisher error warning retained. Note: notes/t-full-ratchet-fundraising-2014.md. (A; full transcript with errors disclosed; accessed 2026-08-21)
- ★★★ | EIX/FamilyBusiness — Ann Winblad interview | https://familybusiness.org/content/85-ann-winblad-entrepreneur-and-venture-capitalist | 2015-03-06 | institutional video/captions | Processed the official video/captions for operating biography, 133 noes, founder traits, market-first logic, and assumption testing; 2024 YouTube date is migration, not event date. Note: notes/t-eix-entrepreneur-vc-2015.md. (A for speech/B for automated-looking captions and summary; full video/captions; accessed 2026-08-21)
- ★★★ | OnlineEducation.com — Women Breaking Barriers interview | https://www.onlineeducation.com/women-breaking-barriers/interviews/ann-winblad | 2017-07 | edited written telephone-interview transcript | Processed sourcing throughput, MuleSoft pattern reasoning, culture/values, representation pipeline, and failure tolerance; classified as edited writing, not a spoken transcript with timestamps. Note: notes/t-onlineeducation-2017.md. (A for answers/B for editing; full edited text; accessed 2026-08-21)
- ★★ | Axios — Ann Winblad on women in tech and enterprise software | https://www.axios.com/2017/12/15/ann-winblad-its-a-great-time-for-women-in-tech-and-for-enterprise-software-1513301333 | 2017-04-03 | reported written interview/selected direct quotes | Processed the values-pass, board/CEO, culture, and enterprise-wave comments; classified as selected edited quotations, not a full transcript. Note: notes/t-axios-2017.md. (A for direct quotes/B for selection and framing; full article; accessed 2026-08-21)
- ★★ | Fresh Dialogues — Winblad on “Kool-Aid,” green tech, and Bill Gates | https://www.freshdialogues.com/2008/12/16/ann-winblad-talks-kool-aid-green-tech-and-bill-gates/ | interview 2008-12-05; page 2008-12-16 | 12:34 audio interview + curated quotes/show notes | Processed one parent MP3/five excerpts as one family; no full transcript, and promised part two was not found. Note: notes/t-fresh-dialogues-2008.md. (A for audio/direct quotes/B for curation; partial text/full audio route; accessed 2026-08-21)
- ★★ | Microsoft/Churchill Club — Steve Ballmer with Ann Winblad | https://news.microsoft.com/speeches/steve-ballmer-the-churchill-club/ | event 2008-09-25; page 2008-09-26 | official event transcript | Processed only Winblad’s moderator questions as her evidence; Ballmer answers and host bio remain separately attributed. Note: notes/t-churchill-ballmer-2008.md. (A; full transcript; accessed 2026-08-21)
- ★★ | CNBC — Ann Winblad on investing in big tech | https://www.cnbc.com/video/2021/03/15/full-interview-with-ann-winblad-on-approach-to-big-tech-investing.html | 2021-03-15 | 8:27 broadcast-video page | Processed exact metadata/access boundary only; no public captions/transcript and no substantive audiovisual review, so no claims were inferred from the title. Note: notes/t-cnbc-big-tech-2021-03.md. (A/B for official metadata; metadata/video-only; accessed 2026-08-21)
- ★★ | CNBC — software revenue-growth outlook | https://www.cnbc.com/video/2021/12/31/tech-investor-ann-winblad-says-an-enormous-amount-of-new-software-will-help-drive-revenue-growth.html | 2021-12-31 | 3:41 broadcast-video page | Processed exact metadata/access boundary only; no public captions/transcript and no substantive audiovisual review; headline is not treated as a full thesis. Note: notes/t-cnbc-software-growth-2021-12.md. (A/B for official metadata; metadata/video-only; accessed 2026-08-21)
Press, histories, criticism, and transition
★★★ | Wired — “Software’s First Lady” | https://www.wired.com/1996/09/winblad/ | 1996-09-01 | magazine profile | Key contemporaneous profile and
$35m → $250m / 50% annualFund I report; compare with later$27m investable → $252m, and keep gendered framing separate from verified chronology. (B; full; accessed 2026-08-21)★★★ | StrictlyVC — “Hummer Winblad Reboots” | https://strictlyvc.com/2015/04/06/hummer-winblad-reboots/ | 2015-04-06 | reported firm-transition interview | Critical source on uneven returns, Fund V/VI size contraction, Napster overhang, and founders’ transition from managing directors to founding partners. (B; full; accessed 2026-08-21)
★★ | Los Angeles Times — Winblad profile | https://www.latimes.com/archives/la-xpm-1998-jan-19-fi-9830-story.html | 1998-01-19 | newspaper profile | Contemporaneous biography and software-VC positioning; use against later recollection. (B; full; accessed 2026-08-21)
★★ | Washington Post — Silicon Valley software language/profile | https://www.washingtonpost.com/archive/business/1998/01/02/in-silicon-valley-a-language-all-its-own/48eb8b68-9099-4700-b9e4-34dabc22149a/ | 1998-01-02 | newspaper feature | Independent period context on Winblad and software investing; access may be partial. (B; partial/full varies; accessed 2026-08-21)
★★ | SFGate — “Secrets of VC Success” | https://www.sfgate.com/business/article/Secrets-of-VC-success-3076822.php | 2000-08-20 | newspaper interview/profile | Period account of selection, portfolio, and firm operation; compare claimed counts with the full denominator. (B; full; accessed 2026-08-21)
★★ | San Francisco Chronicle — “A Company of Her Own” | https://www.sfchronicle.com/business/article/A-Company-of-Her-Own-Ann-Winblad-is-unique-3000244.php | 1998-05-10 | newspaper profile | Contemporary gender/leadership and operating-history route; paywall may limit locators. (B; partial; accessed 2026-08-21)
★ | CIO Insight — “VC with a View” | https://www.cioinsight.com/innovation/ann-winblad-vc-with-a-view/ | 2005 | trade-press interview | Mid-cycle software outlook and process lead; use as reported/direct hybrid. (B; full; accessed 2026-08-21)
★ | InfoWorld — “Veteran venture capitalist is sold on SaaS” | https://www.infoworld.com/article/2192161/veteran-venture-capitalist-is-sold-on-saas.html | 2006 | trade-press interview | Dated SaaS thesis, useful for prospective deal testing. (B; full; accessed 2026-08-21)
★ | The Power Law — publisher page | https://www.penguinrandomhouse.com/books/566771/the-power-law-by-sebastian-mallaby/ | 2022 | book metadata | Independent venture-history context and witness lead; full Winblad passages were not retrieved in this phase. (B; metadata/partial; accessed 2026-08-21)
★ | A Dozen Lessons for Entrepreneurs — Winblad chapter route | https://www.jstor.org/stable/10.7312/grif18482.40 | 2017 | book chapter index/preview | Secondary synthesis centered on Winblad; do not substitute the author’s maxims for primary-source chronology. (B; partial; accessed 2026-08-21)
★★ | Fortune — “Term Sheet — Friday, March 4” | https://fortune.com/2016/03/04/term-sheet-friday-march-4/ | 2016-03-04 | reported fund-transition notice | Processed as a reported Fund VII/succession marker and cross-checked against the later retrieved Fund VII/VIII Form D bundle; public-role reporting remains separate from Form ADV legal control. (B; full/partial varies; accessed 2026-08-21)
Deal, fund, regulatory, and litigation records
★★★ | Liquid Audio preliminary proxy — shareholder litigation dismissal and separate patent settlement | https://www.sec.gov/Archives/edgar/data/1016613/000101287003003026/dpre14a.htm | 2003-06 | SEC PRE 14A | Issuer filing says the fiduciary actions were settled and dismissed with prejudice under a January 2, 2003 agreement; separately, a patent suit was settled for a $150,000 payment to Network Commerce. It also identifies Winblad as a former director. Neither proceeding establishes her personal liability. Cite “Legal Proceedings” and board/committee disclosures. (A for filing; allegations remain allegations; full; accessed 2026-08-21)
★★★ | UC Regents — private-equity IRR report at 2020-06-30 | https://www.ucop.edu/investment-office/_files/updates/pe_irr_06-30-20.pdf | 2020-06-30 | public-LP disclosure PDF | HWVP III row reports UC-specific 1.04x TVPI and 1.0% net IRR; cite PDF p. 1 row 48 and preserve LP-specific/methodology boundary. (A; full; accessed 2026-08-21)
★★★ | MuleSoft S-1/A | https://www.sec.gov/Archives/edgar/data/1374684/000119312517083411/d287291ds1a.htm | 2017-03-16 | SEC filing | Board tenure from September 2006, Hummer V/VI ownership, and issuer history; strong on governance/holdings, silent on solo sourcing and return. (A; full; accessed 2026-08-21)
★★★ | MuleSoft Schedule 13G | https://www.sec.gov/Archives/edgar/data/1374684/000114420418008216/tv485986_sc13g.htm | 2018-02-13 | SEC filing | Hummer V shares and potential shared voting/dispositive power for Hummer, Winblad, and Kertzman as managing members; key anti-hero attribution control; the same accession also appears via the issuer-padded archive path. (A; full; accessed 2026-08-21)
★★ | The Knot — Winblad Form 4 | https://www.sec.gov/Archives/edgar/data/1062292/000118143105022264/xslF345X02/rrd75818.xml | filed 2005-04-15; trades 2005-04-14 | SEC ownership filing | Director/managing-member role, fund shares, and pecuniary-interest disclaimer; vehicle ownership is not personal performance. (A; full; accessed 2026-08-21)
★★ | Omniture — Winblad Form 4 index | https://www.sec.gov/Archives/edgar/data/1111165/000118143107035846/xslF345X02/rrd160579.xml | 2007-06-06 | SEC Form 4 | Processed transaction table and footnotes as an in-kind/carry distribution record; it does not establish Winblad as source or board sponsor. Omniture’s S-1 instead names Mark Gorenberg. (A; full index; accessed 2026-08-21)
★★ | SDCERS/StepStone private-equity report | https://content.sdcers.org/wp-content/uploads/2025/03/stepstone-private-equity-full-performance-report-q3-2024.pdf | 2024-09-30 | public-LP consultant report PDF | Reports a secondary HWVP V interest at 47.3% IRR and 2.9x TVM; cite printed p. 21 and do not generalize secondary-buyer economics to original LPs, the whole fund, or Winblad. (A; full; accessed 2026-08-21)
★★★ | In re Napster — 2005 investor-liability order | https://www.govinfo.gov/content/pkg/USCOURTS-cand-3_00-md-01369/pdf/USCOURTS-cand-3_00-md-01369-1.pdf | 2005 | federal court order PDF | Primary pleading/procedural record on investor-control allegations; allegations surviving a motion are not findings of personal infringement. (A; full; accessed 2026-08-21)
★★★ | In re Napster — 2006 spoliation sanctions order | https://www.govinfo.gov/content/pkg/USCOURTS-cand-3_00-md-01369/pdf/USCOURTS-cand-3_00-md-01369-31.pdf | 2006-10-24 | federal court order PDF | Primary adverse record: investment background, June 3 email, preservation duty, preclusion/adverse inference, fees, and denial of default; cite named sections. (A; full; accessed 2026-08-21)
★★★ | Los Angeles Times — Hummer Winblad Napster settlement | https://www.latimes.com/archives/la-xpm-2006-dec-13-fi-napster13-story.html | 2006-12-13 | contemporaneous litigation report | Conditional settlement with Universal/EMI on undisclosed terms and order-vacatur condition; no basis for a personal Winblad liability amount. (B; full; accessed 2026-08-21)
★★ | Los Angeles Times — Napster sanctions ruling | https://www.latimes.com/archives/la-xpm-2006-oct-26-fi-napster26-story.html | 2006-10-26 | contemporaneous court report | Independent period account of the sanctions order and Winblad email; court PDF controls where wording differs. (B; full; accessed 2026-08-21)
★★ | Los Angeles Times — Universal/EMI sue investor | https://www.latimes.com/archives/la-xpm-2003-apr-23-fi-napster23-story.html | 2003-04-23 | contemporaneous litigation report | Establishes complaint timing and investor-control allegations; allegations are not adjudicated facts. (B; full; accessed 2026-08-21)
★★ | Ninth Circuit — In re Napster/Bertelsmann appeal | https://cdn.ca9.uscourts.gov/datastore/opinions/2007/03/13/0615886.pdf | 2007-03-13 | appellate opinion PDF | Related appellate posture and named Hummer defendants; chiefly addresses Bertelsmann and should not be presented as a Winblad merits ruling. (A; full; accessed 2026-08-21)
★★★ | SEC — selected early-portfolio outcome filings | https://www.sec.gov/Archives/edgar/data/1001113/000089161802001389/f80110s-8.htm | 1995–2009 | issuer filings bundle | Processed Arbor’s 1995 registration chronology and Oracle/Hyperion $52/share, ~$3.3bn exhibit; Sybase/Powersoft merger 10-K; Intel/Wind River $884m 10-Q; and Siebel/Scopus $381.4m completion 8-K. Exit values do not establish HWVP proceeds. (A; full; accessed 2026-08-21)
★★★ | SEC — Omniture financing and Pets.com failure records | https://www.sec.gov/Archives/edgar/data/1357525/000095014906000171/f18772sv1.htm | 2004–2005 financing / 2000–2002 failure | issuer filings bundle | Processed Omniture S-1 Series B/C-1 cost and Mark Gorenberg governance, Winblad’s later Form 4 distributions, and Pets.com 10-K on HWVP entities’ 13.5%, John Hummer, IPO, cessation, delisting, and liquidation. (A; full; accessed 2026-08-21)
★★★ | SEC — HWVP Fund VII and VIII Form D series | https://www.sec.gov/Archives/edgar/data/1664914/000166491416000001/xslFormDX01/primary_doc.xml | 2016–2022 | Form D series | Processed Fund VII original and 2018 final amendment, and Fund VIII original and amendment. Neither related-person roster names Winblad/Hummer; preserve signed-date versus SEC-acceptance distinctions. (A; full; accessed 2026-08-21)
★ | Commercial investor databases — Crunchbase and Signal/NFX | https://www.crunchbase.com/person/ann-winblad | current | commercial discovery bundle | Candidate-denominator routes only; Signal/NFX adds stage/sector/deal leads, but paywalls, duplicates, partner attribution, dead companies, and follow-ons require primary-source reconciliation. Neither is authoritative for exhaustive history or outcomes. (C; partial; accessed 2026-08-21)
Historical and market context
- ★★ | IAB — 2001 interactive-ad-unit guidelines | https://www.iab.com/news/internet-advertising-bureau-iab-issues-voluntary-guidelines-new-interactive-marketing-units/ | 2001-02-26 | official industry standards notice | Documents that banner guidelines and banner units remained in active industry use after Winblad's end-1997 disappearance forecast; supports the failed-forecast classification without treating later formats as unchanged. (A/B for trade-body contemporaneous record; full; accessed 2026-08-22)
- ★★ | NVCA 2025 Yearbook | https://nvca.org/document/nvca-2025-yearbook/ | 2025 | industry-statistics report hub | Modern venture base rates and long-run series; use period-specific tables rather than today’s market as a 1989 comparator. (B; full; accessed 2026-08-21)
- ★★ | NVCA historical yearbooks — openICPSR archive | https://www.openicpsr.org/openicpsr/project/119152/version/V1/view?path=%2Fopenicpsr%2F119152%2Ffcr%3Aversions%2FV1%2FNVCA-Yearbooks&type=folder | historical vintages | data/archive collection | Route to contemporaneous fundraising, investment, and exit denominators for 1989–2007 decisions. (A/B; archive; accessed 2026-08-21)
- ★ | OECD — Social Sciences and Innovation | https://www.oecd.org/content/dam/oecd/en/publications/reports/2001/06/social-sciences-and-innovation_g1gh2554/9789264192836-en.pdf | 2001 | policy/research PDF | Neutral innovation-system context; use only where its software/venture material directly bears on a dated claim. (A/B; full; accessed 2026-08-21)
- ★ | Christian Science Monitor — software-industry consolidation | https://www.csmonitor.com/1992/0107/07072.html | 1992-01-07 | contemporaneous business report | Period context for software consolidation and category risk around early HWVP investing. (B; full; accessed 2026-08-21)
Completed-peer comparison sources
- ★★ | Completed-peer underlying-evidence bundle — Rock, Leone, Casado | https://hbr.org/1987/11/strategy-vs-tactics-from-a-venture-capitalist | 1987–2020 | primary/direct comparison bundle | Rock’s HBR account anchors people diligence and concentrated governance; Leone’s “Seven Questions” and PlanGrid Stanford session anchor customer/founder/partnership claims; Casado’s “Emerging Architectures” anchors architecture-to-market mapping. Used only with the completed 006/033/100 canon pages; not evidence about Winblad or a return comparison. (A for direct accounts/institutional transcript; full; accessed through completed dossiers 2026-08-21)
Coverage assessment
- Guiding questions: the SCOUT phase is organized around eight questions in
_profile.md: operating origins; Open Systems date/economics; partner and committee attribution; the software-exclusive mandate; deal/failure attribution; fund-by-fund economics; adverse events and succession; and retrievable evidence that could falsify later philosophy claims. - Classification: Winblad is a second-generation/pre-web software operator turned private-LP venture-firm cofounder, spanning client-server through cloud. Direct voice is unusually rich, but private fund/IC records are not. The meaningful adverse record includes firm-level Napster litigation/spoliation, Liquid Audio shareholder litigation, and uneven later fund evidence; reviewed sources do not establish personal copyright liability.
- Search/name variants: searched
Ann Winblad,Ann L. Winblad,Anne Winblad,Ann Windblad;Hummer Winblad Venture Partners,Hummer-Winblad,Hummer Winblad,HWVP,Aspenwood Ventures;humwin.com,hwvp.com; andOpen Systems, Inc.while excluding unrelated Open Systems International/OSI results. Date sweeps covered 1973–1976, 1982–1985, 1987–1990, the 1990s, 2000–2007, and 2011–2021. - Venue and format coverage: searched signed writing, book/catalog, oral history, university video/transcripts, broadcast/podcast interviews, firm pages, archived press, SEC ownership/issuer filings, public-LP reports, federal court orders, settlement reporting, archive catalogs, and historical industry data. The eleven Stanford source-map rows cover thirteen official clips from one underlying session, not thirteen independent witnesses.
- Direct voice: the highest-value corpus is the Berkeley oral history, the signed 2019 LinkedIn retrospective, the 1990 coauthored book, the 1997 Charlie Rose interview, the 2004 Stanford session, and later transcripted interviews. No public personal letters, LP letters, investment memoranda, full board minutes, or complete partner meeting records were found.
- Archives and access barriers: Berkeley’s transcript/audio catalog and Stanford’s live inline transcripts were accessible; five former Stanford transcript-PDF routes returned 404 and were replaced with canonical video/AV pages. The CHM and Stanford Silicon Valley Archives public catalogs exposed no dedicated Winblad/Hummer collection. The 1992 Computerworld excerpt is partial, the 2001 CACM article and 1990 book remain metadata-only, LinkedIn is dynamic but all four signed LinkedIn article bodies in the writing corpus were accessible, some newspaper pages are paywalled, and Wayback snapshot completeness remains unverified.
- Candidate denominator: start with archived/current Hummer Winblad portfolio pages, the Winblad and firm commercial profiles, SEC person/fund-entity filings, issuer CIKs, public-LP disclosures, and IPO candidates including The Knot, Omniture, MuleSoft, and Five9. Separate company, round, fund vehicle, sourcing partner, sponsor, board member, follow-on, exit, and loss. Include dead/quiet companies and Napster rather than sampling only IPOs.
- Firm portfolio checkpoints: the candidate count changes by source and date: 16 Fund I companies in the Berkeley oral history; roughly 80 funded companies in the 2000 St. Thomas profile; 100-plus in the 2012 oral history’s prefatory biography; 150-plus in Winblad’s 2019 retrospective; and 98 linked logos on the accessed official companies page. These are firm-level, definition-sensitive claims—not a deduplicated personal-investment denominator.
- Saturation status: final exact-record checks targeted Open Systems/UCCEL acquisition records, Hummer Winblad fund and Form D entities, Liquid Audio and Napster litigation, SEC/IAPD disciplinary disclosures, the Fund VII founder omission, Aspenwood succession, and exact Winblad/HWVP LP-letter, investment-memo, and board-minute routes. They added the Liquid Audio proxy, Fund VII, official-legal and succession controls, and the complete “Class of 2013” body; the exact document-type searches did not surface public LP letters, investment/IC memoranda, complete board minutes, or an independently audited personal-return series. Discovery has reached a defined SCOUT frontier, not exhaustion. Later work should retrieve the full 1992 and 2001 texts and reconcile the named acquisition record, Fund I subscription/cash flows, full partnership/fund series, T/Maker financing, portfolio archives, founder/partner/LP witnesses, and settlement terms.
- Performance controls: Fund I has two incompatible reported bases; T/Maker is reported by Winblad as 3x in 2019 but 5x in the 2004 Stanford transcript; UC’s HWVP III row is one LP’s net result; SDCERS’ HWVP V exposure is a secondary interest. None is Winblad personal performance, and none alone supplies a whole-fund series.
- Historical claim control: do not use “earliest woman to found a major US venture firm.” Earlier chronology for Campbell-White, Cloherty, and Elmore makes that formulation unsafe. The defensible scoped statement is that Winblad co-founded an early prominent venture firm with a woman among its founders widely reported and firm-claimed as the first venture firm/fund focused exclusively on software.
- Closest completed-peer routes: Arthur Rock offers an earlier specialized-firm/technology-cycle comparison; Doug Leone offers later enterprise-software, shared-partnership, and attribution controls; Martin Casado offers the closest modern operator-to-infrastructure-specialist comparison. Their completed canon pages and the compact underlying-evidence bundle above are the only peer sources used; no cross-era personal-return ranking is attempted.
- Highest-value retrieval gaps: Open Systems acquisition/corporate records; original Fund I subscription, cash-flow, and annual-return basis; LP identity conflict (
St. Paul CompaniesversusState Farm Insurance); complete fund series and partnership agreements; T/Maker financing records; ordinary and failed deal files; investment memos and board minutes; named founder/partner/LP witnesses; exact Aspenwood rebrand/legal mechanics; Napster settlement terms; and full text of the 1992/2001 writings.
Source notes
t Ann Winblad on women in tech and enterprise software
- URL: https://www.axios.com/2017/12/15/ann-winblad-its-a-great-time-for-women-in-tech-and-for-enterprise-software-1513301333 | Published: 2017-04-03 | Format: short written reported interview with selected direct quotations; no full transcript/audio | Reliability: A for direct quotations; B for reporter framing and selection | Access: full article | Accessed: 2026-08-21 | Locator scheme: six quoted topic blocks, web lines 40–59; no audio or timestamps
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Winblad says company selection should include values and culture, not only business-plan quality; she is willing to pass on a large opportunity when founder values do not fit. (lines 40–43, 54–56)
- She treats employee departures as governance evidence and says boards must hire the right CEO or fire the wrong one. (Uber block, lines 52–53)
- Amazon is her counterexample to equating demanding work with bad culture: a hard-driving culture can cohere around mission. (lines 48–50)
- She explains the 2017 enterprise IPO wave as companies funded eight to ten years earlier arriving from the web-scale infrastructure wave, naming MuleSoft. (lines 58–59)
- Advice to women centers on investigating the “fabric,” culture, and soul of a company and leaving when talent and workplace values diverge. (lines 45–47)
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “The tone starts at the top for any company.” (Uber topic block, line 53)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The values-pass statement is direct evidence of a claimed picking rule, but no company or IC record is named. (lines 54–56)
- MuleSoft is a firm-level example; the article does not establish solo sourcing or return attribution. (lines 58–59)
- The interview captures 2017 governance views amid public reporting about Uber culture.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- picking: screen for shared values alongside market and plan.
- boards: CEO selection/removal and talent retention are board responsibilities.
- people: distinguish hard work from abusive or incoherent culture.
- risk: values mismatch can outweigh an attractive market.
- macro / exits: technology waves appear in IPOs with long lags.
- sourcing / portfolio: insufficient detail.
- These rules are investor-stated · strong as 2017 claims; consistent application across the portfolio is documented behavior · insufficient public record.
Contradictions, counterevidence, and access limits
- Axios supplies selected quotations, not a full transcript; questions, edits, and omitted context are unknown.
- The values rule may be vulnerable to similarity bias or post hoc rationalization; no pass ledger is disclosed.
- Employee exits can signal culture problems but also compensation, role, location, or market alternatives.
- Amazon, Uber, and MuleSoft examples are compressed and cannot establish the rule’s predictive efficacy.
Open questions
- Which company did the firm pass for values despite a large market?
- How were culture concerns documented before investment?
- What evidence distinguishes demanding mission from destructive culture?
- Did the 2017 web-scale IPO-wave forecast identify later winners and losers?
t Ann Winblad oral history
- URL: https://digicoll.lib.berkeley.edu/nanna/record/218713/files/winblad_ann.pdf?registerDownload=1&version=1&withMetadata=0&withWatermark=0 | Published: interview 2012-03-18 | Format: Bancroft oral-history transcript (viii + 28 printed pages) with Audio 1/2 catalog route | Reliability: A for Winblad’s recollection and interview record | Access: full transcript; catalog/audio route also inspected | Accessed: 2026-08-21 | Locator scheme: printed transcript pages and audio-segment timestamps from the Berkeley catalog; printed page differs from viewer page
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Winblad’s longest public retrospective traces childhood, mathematics and business education, Federal Reserve systems work, Open Systems, the move to California, technical writing, Hummer Winblad’s formation, and selected successes and failures. (printed pp. 1–23)
- She recalls that Open Systems began with an accounting-software opportunity and three Federal Reserve colleagues, then gained market access through hardware relationships and Don Valentine. (printed pp. 7–11)
- The fund-formation story centers on operator specialization, 133 rejections, and endorsements from Pitch Johnson, Bill Edwards, and Don Valentine before institutional backing. (printed pp. 17–19)
- Fund I is described as 16 companies, with half becoming public; Slate is used as a timing failure and Wind River as a stronger market-timing contrast. (printed pp. 21–23)
- This is retrospective testimony recorded more than two decades after fund formation. It establishes her remembered reasoning, not contemporaneous proof of each date, count, or causal attribution.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- No quotation is published: the Bancroft manuscript notice on printed p. ii requires permission to quote for publication, so this dossier paraphrases only.
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The transcript places Winblad at the Federal Reserve after college, then at Open Systems with three former colleagues. (printed pp. 6–11)
- It records Addison-Wesley’s solicitation and the period in which she worked on Object-Oriented Software; it does not allocate chapters among coauthors. (printed p. 17; audio around 00:50:44)
- It names John Hummer as fund cofounder and the three established venture investors as credibility brokers. (printed pp. 17–19)
- It attributes Fund I outcomes to the firm and fund, not to a verified Winblad-only track record. (printed pp. 21–23)
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- sourcing: operating and industry relationships are presented as the route to ideas and credibility.
- picking: software specialization and market timing frame the selection logic.
- risk: Slate and Wind River illustrate that technical possibility and commercial timing can diverge.
- portfolio / exits: 16-company and public-company counts are retrospective and unreconciled.
- people / boards: endorsements and partner formation matter; solo-credit language is not supported.
- macro: early software capital scarcity is central to the story.
- These are investor-stated · moderate because recollection is rich but retrospective; consistency with company and fund records remains incompletely documented.
Contradictions, counterevidence, and access limits
- The Bancroft manuscript notice on printed p. ii prohibits publication quotation without permission; this note therefore uses paraphrase and printed-page/audio locators only.
- The Bancroft manuscript notice on printed p. ii prohibits publication quotation without permission; this note therefore uses paraphrase and printed-page/audio locators only.
- Open Systems sale timing conflicts internally and with institutional biographies; the defensible window remains 1982–1984.
- The 133-rejection account conflicts narrowly with 130 and “over 130” elsewhere.
- The transcript’s St. Paul Companies identity conflicts with State Farm Insurance in the 2019 essay.
- “Half” of 16 public companies conflicts with six IPOs in 2019.
- No contemporary pitch log, Fund I cash-flow schedule, investment memoranda, or complete board record is public.
- Oral-history editing and interviewer selection can compress uncertainty and privilege memorable winners.
Open questions
- Which corporate record fixes Open Systems’ acquisition date and consideration?
- Which insurer subscribed to Fund I, and on what terms?
- What company-by-company ledger reconciles the Fund I IPO count?
- What did each partner source, sponsor, diligence, and govern?
t Ann Winblad on Charlie Rose
- URL: https://charlierose.com/videos/20230?autoplay=true | Published: 1997 | Format: 22:43 broadcast interview with official full VTT/transcript | Reliability: A for direct speech; host introduction remains separately attributed | Access: full official VTT | Accessed: 2026-08-21 | Locator scheme: continuous VTT timestamps; official VTT endpoint https://charlie-p-2ac84d7056ca7f9d.s3.amazonaws.com/clips/subtitles/000/020/230/original/1HY0071_002.vtt?1556809139
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Winblad argues that a pure advertising model is unlikely to support most internet companies; advertising can be a revenue “sweet spot” but usually sits among other streams. (00:52–01:50)
- She predicts banner ads will be gone by the end of 1997 and replaced by richer interstitial formats. The prediction failed: IAB's February 2001 standards notice still described existing banner guidelines and units. This is valuable negative evidence against treating vivid market forecasts as expertise. (02:16–02:30; IAB 2001, standards announcement)
- She says VCs are opportunists rather than visionaries and describes their company-building role as translating a founder’s future into a business model, industry connections, and a stronger team. (02:52–03:29)
- She recognizes digital commerce, recommendation, and customer-level behavioral data early, using Amazon’s bookselling and personalization potential as the example. (03:35–05:13)
- Software’s capital efficiency is double-edged: cheap tools lower formation costs but also barriers to entry, making execution, scaling, and competitive advantage decisive. (07:34–09:36)
- She says raising the first fund took 150 meetings for $30 million because LPs dismissed software, a materially different account from 113/$35 million in Stanford and 133/$35 million in other retrospectives. (09:36–10:00)
- She contrasts long-term commitment with gold-rush entrepreneurship and says durable software leaders were motivated by the work and industry, not merely fast liquidity. (11:41–12:39)
- Microsoft’s internet response becomes an assumption-management case: leaders must name forward assumptions, detect invalidation, and change the set quickly. (17:57–19:54)
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “venture capitalists are the opportunists, not the visionaries” (02:52–02:57)
- “the same issue of capital efficiency also creates very few barriers to entry.” (09:00–09:07)
- “I better know what they are.” (forward-assumptions discussion, 19:39–19:43)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The fundraise recollection is one of the earliest public versions: 150 meetings, $30 million, and an end-1989 close. (09:36–10:00)
- Winblad describes her first computer as costing $25,000 and contrasts it with 1997 software-entry tools costing under $1,000. (07:34–08:15)
- The final segment says she met Bill Gates at Esther Dyson’s forum speakers’ dinner after she had sold her company and while his company was growing; the relationship was an industry-peer exchange, not a disclosed investment. (20:20–22:26)
- The host calls the firm the first exclusively software fund; that introduction is not Winblad testimony and historical priority remains a reported claim. (00:07–00:36)
- Company assistance and fundraise figures are firm/vehicle narratives, not proof of a Winblad-only return record.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- sourcing: entrepreneurs supply the visions; the investor helps connect them to industry and talent.
- picking: capital efficiency alone is not an edge because it lowers barriers for every competitor; execution must create advantage.
- boards / people: venture is described as active integration of strategy, connections, and employees.
- risk: explicitly list forward assumptions and monitor when they become invalid.
- exits: long-term commitment is contrasted with a quick-IPO gold-rush mentality.
- macro: cheap computing and internet distribution widen company formation while intensifying competition.
- portfolio: no portfolio-construction rule is disclosed.
- The opportunist/assumption framework is investor-stated · strong; its consistent application to actual deals is documented behavior · insufficient public record.
Contradictions, counterevidence, and access limits
- The end-1997 banner-disappearance forecast was wrong; an IAB standards notice still documented banner guidelines and units in February 2001. IAB 2001, standards announcement This is contemporaneous record · strong negative evidence about forecast precision.
- The 150 meetings/$30 million account conflicts with Stanford’s 113/$35 million and Berkeley/TEDx/EIX’s 133, with later $35 million and $27 million-investable bases. Meetings versus rejections and commitment versus investable capital may differ, but public evidence does not resolve them.
- The interview captures an internet-boom moment and selected examples; it does not show losing investments or rejected companies.
- The official VTT contains punctuation and occasional recognition errors; quotations were kept short and checked against clear context.
- Amazon personalization aged well, but one strong forecast does not erase the failed banner forecast.
Open questions
- Was $30 million an interim close and $35 million the final commitment?
- What company records show assumption-set changes leading to a follow-on, exit, or shutdown?
- Which low-barrier software investments failed because execution did not scale?
- How did the firm distinguish long-term commitment from refusal to stop?
t Microsoft and the New Software Economy
- URL: https://news.microsoft.com/speeches/steve-ballmer-the-churchill-club/ | Published: event 2008-09-25; transcript posted 2008-09-26 | Format: official event transcript; Winblad interviews Steve Ballmer | Reliability: A for official speaker turns | Access: full transcript | Accessed: 2026-08-21 | Locator scheme: named speaker turns and web lines 20–202; no timestamps
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Winblad’s questions reveal a contemporaneous map of the software economy: the credit crisis, SaaS, advertising-supported models, devices displacing PCs, virtualization, cloud architecture, developers/open source, globalization, acquisition versus R&D, and incumbent reinvention. (Winblad turns, lines 28–37, 54–61, 91–161)
- She uses segment revenue, operating income, R&D spending, developer counts, and server-share figures to press Ballmer on scorecards rather than relying only on technology narrative. (lines 68–75, 91–94, 132–147, 156–161)
- Her cloud questions distinguish hosted software from re-architected multi-tenant systems and ask about federation between enterprise data centers and the cloud. The substantive definition supplied is Ballmer’s, not hers. (lines 115–130)
- Questions on developer love and open source identify ecosystem adoption as a strategic constraint. Ballmer’s answers remain his evidence. (lines 132–142)
- The final leadership question asks what a long-tenured operator would teach small-company CEOs, but its answer is Ballmer’s philosophy, not Winblad’s. (lines 185–197)
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “We were good at the patience part in venture capital.” (Winblad turn, line 70)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- Winblad appears as prepared moderator with detailed public-company metrics and prior-statement references during the September 2008 crisis. (lines 28–37, 68–75)
- The introduction describes the firm’s software-exclusive formation and more than 100 companies, but this is host framing, not a Winblad-audited denominator. (lines 20–26)
- Her questions show market priors but do not prove Hummer Winblad positions, IC decisions, or portfolio exposure.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- sourcing / picking: interrogate incumbents, developer ecosystems, business-model shifts, and measurable adoption.
- risk: compare narrative with scorecards; ask how incumbents balance cash engines with disruptive models.
- macro: locate software strategy inside the credit crisis and globalization.
- people / boards: probe leadership succession and management of diverse businesses.
- portfolio / exits: acquisitions and public-market thresholds appear as industry questions, not disclosed fund rules.
- Interpreting her questions as areas of attention is documented behavior · strong; treating Ballmer’s answers as her beliefs would be researcher inference · insufficient public record.
Contradictions, counterevidence, and access limits
- Winblad is interviewer, so her questions cannot be treated automatically as endorsed theses.
- Many figures in her prompts are 2008 public-company metrics and require period sources if reused as facts beyond the transcript.
- The official transcript has speaker turns but no timestamps or video-linked anchors.
- A moderator’s prepared topics may reflect event goals and audience interests as much as investment priorities.
Open questions
- Which 2008 themes mapped to actual portfolio holdings?
- How did the firm underwrite cloud, virtualization, and developer ecosystems?
- Did Winblad’s scorecard emphasis appear in board work?
- Which of her implicit 2008 priors were later revised?
t Approach to big-tech investing
- URL: https://www.cnbc.com/video/2021/03/15/full-interview-with-ann-winblad-on-approach-to-big-tech-investing.html | Published: 2021-03-15 | Format: CNBC broadcast-video page (8:27) | Reliability: A for Winblad’s recorded speech; B for CNBC headline/framing | Access: official metadata/video-only route; no public captions/transcript and no substantive audiovisual review | Accessed: 2026-08-21 | Locator scheme: video timestamps required; none extracted in this run
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- The official metadata identifies a late-career discussion of big-technology investing.
- No specific company view, valuation rule, forecast, or quotation is inferred from the headline because the video/transcript did not render in the legitimate text route used.
- The appearance is retained in the denominator because it could show whether Winblad transferred private software pattern recognition into public-market commentary.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- No quote included: no public caption/transcript track was available and the audiovisual segment was not substantively reviewed.
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The date captures commentary during the 2021 technology-market boom.
- The segment concerns public big-tech investing and must not be presented as evidence of Hummer Winblad private-fund performance.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- macro / picking: potential 2021 market-view record; content remains unextracted.
- sourcing / portfolio / boards / risk / exits / people: insufficient public record from the accessed route.
- Any substantive interpretation is researcher inference · insufficient public record and is omitted.
Contradictions, counterevidence, and access limits
- CNBC’s metadata page was accessible, but no public captions/transcript surfaced and the audiovisual segment was not substantively reviewed.
- No stable transcript or captions were located in the narrow source route.
- A broadcast headline is not a transcript and cannot support a detailed thesis.
- Public-market commentary is analytically distinct from a private-venture record.
Open questions
- Which big-tech companies and valuation metrics did she discuss?
- What time horizon and risk controls did she specify?
- Were the views prospective enough to score against later outcomes?
- Did she distinguish personal/public holdings from venture-fund positions?
t Software revenue-growth outlook
- URL: https://www.cnbc.com/video/2021/12/31/tech-investor-ann-winblad-says-an-enormous-amount-of-new-software-will-help-drive-revenue-growth.html | Published: 2021-12-31 | Format: CNBC broadcast-video page (3:41) | Reliability: A for Winblad’s recorded speech; B for CNBC headline/framing | Access: official metadata/video-only route; no public captions/transcript and no substantive audiovisual review | Accessed: 2026-08-21 | Locator scheme: video timestamps required; none extracted in this run
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- CNBC’s official title attributes a year-end forecast that substantial new software would support revenue growth.
- No companies, duration, growth rate, valuation implication, or mechanism beyond that title-level proposition is inferred without the video.
- The segment is valuable as a prospective forecast dated immediately before the 2022 software repricing, but scoring it requires the actual speaker turns and a defined prediction.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- No quote included: the headline was not treated as a verified verbatim transcript.
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The segment records late-2021 public commentary rather than a disclosed Hummer Winblad investment decision.
- Any later market outcome must be separated from what Winblad actually specified at the time.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- macro: potential software-demand and revenue-growth forecast.
- picking / risk: content unavailable; valuation discipline and downside conditions are unknown.
- sourcing / portfolio / boards / exits / people: no accessible evidence.
- The headline attribution is contemporaneous record · provisional; a detailed Winblad thesis is researcher inference · insufficient public record.
Contradictions, counterevidence, and access limits
- The official metadata page was accessible, but no public captions/transcript surfaced and the audiovisual segment was not substantively reviewed.
- The title compresses a broadcast exchange and may omit qualifiers.
- Without horizon, base rate, valuation, and failure conditions, the forecast is not yet falsifiable.
- Later software-market performance cannot be used to invent her original reasoning.
Open questions
- What exact horizon and revenue mechanism did Winblad specify?
- Which software categories or companies did she name?
- Did she discuss valuation, rates, or downside scenarios?
- How should the forecast be scored after retrieving the full segment?
t Ann Winblad, Entrepreneur and Venture Capitalist
- URL: https://familybusiness.org/content/85-ann-winblad-entrepreneur-and-venture-capitalist | Published: 2015-03-06; page updated 2026-05-05 | Format: institutional video interview with YouTube captions | Reliability: A for direct speech; B for edited page summary and automatic captions | Access: full video and English caption track; no human-edited transcript | Accessed: 2026-08-21 | Locator scheme: video timestamps and page summary; caption wording checked conservatively where automatic transcription is clear
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Winblad ties entrepreneurship to learning to manage a route, deliver a product, collect money, and solve a complete problem rather than only generating ideas; the Barbie-clothes story is her childhood example. (video 00:35–02:00)
- She links Open Systems to seeing the new personal-computer landscape while working at the Federal Reserve and persuading colleagues to leave with her. (approximately 04:25–06:15)
- Her core market rule is explicit: large markets come first; building a product is not worthwhile without a reachable opportunity. (07:01–07:27)
- The institutional synopsis highlights a second people rule: successful entrepreneurs need a mission larger than the product and must commit to company, colleagues, industry, and chosen causes. (page “Read More” summary)
- She recounts 133 refusals before institutional support from 3M and IBM-related routes, a fundraising version that conflicts with Charlie Rose and Stanford. (20:43–21:23)
- Her founder discussion emphasizes mission, resilience, learning, and team commitment rather than product charisma alone. (23:29–24:20)
- She says companies must identify the assumptions required to scale and keep testing them as evidence changes. (24:25–26:18)
- The interview is retrospective and motivational; anecdotes demonstrate her narrative logic, not a causal test of venture outcomes.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “Markets come first.” (07:22–07:26)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- She describes sewing and selling Barbie-doll clothes as an early closed-loop commercial exercise. (01:06–01:56)
- She recalls the Federal Reserve role, graduate work at St. Thomas, recognition of the PC-software opening, and recruitment of former colleagues into Open Systems. (03:53–06:15)
- The page identifies David Deeds as interviewer and publishes DOI 10.17919/X91015; it does not supply investment-committee or fund records.
- Open Systems and venture lessons are first-person retrospective accounts decades after the events.
- The 133-no account is not backed by a contemporaneous pitch log and uses institution names differently from other retrospectives.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- picking: start with a large reachable market, then evaluate the product.
- people: favor founders with mission, endurance, and responsibility for the whole commercial loop.
- sourcing: operating experience and direct market observation reveal opportunity.
- risk: enthusiasm requires a real customer opportunity.
- macro: the emerging PC landscape created the opening for Open Systems.
- portfolio / boards / exits: not developed enough in the accessible caption analysis.
- The market-first rule is investor-stated · strong; using childhood commerce as evidence of later investing skill is researcher inference · provisional.
Contradictions, counterevidence, and access limits
- Automatic captions repeat and garble words; only clearly aligned short quotes and timestamped paraphrases are used.
- “Markets come first” can conflict with technology-led discovery if market definition is too narrow; the interview does not supply a falsification threshold.
- The motivational selection of childhood stories invites hindsight and survivorship bias.
- The page was updated in 2026, so its current framing is not necessarily the original 2015 text.
Open questions
- Which customer and pricing records operationalized the market-size/accessibility test?
- Which Open Systems dates and financing facts can be fixed by contemporaneous records?
- How did “mission” enter actual founder diligence and board decisions?
- Which great products did the firm reject because the market failed the test?
t Ann Winblad talks Kool-Aid, green tech and Bill Gates
- URL: https://www.freshdialogues.com/2008/12/16/ann-winblad-talks-kool-aid-green-tech-and-bill-gates/ | Published: 2008-12-16; interview recorded 2008-12-05 | Format: one 12:34 parent MP3 plus five excerpt MP3s, curated quotations, and show notes | Reliability: A for linked audio/direct speech; B for publisher transcription and selection | Access: full audio routes identified; partial publisher text; no full transcript | Accessed: 2026-08-21 | Locator scheme: page topic blocks and separate publisher MP3 clips; continuous audio timestamps not published on page
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Winblad’s “Kool-Aid” metaphor describes temporary belief as necessary to see an entrepreneur’s future while warning against permanent attachment. (page “Drinking the Kool-Aid” block)
- Her strawberry-field story joins patience and focus with efficiency, presenting attention control as an operating lesson. (page early-days block)
- She rejects a single-sector salvation narrative for green technology: press attention to one “Rudolph” ignores a broader team of technologies. (page green-tech block)
- SDForum is described as an open-door sourcing institution that produced funded walk-in companies; Susan Lucas Conwell is credited as its CEO/director. (page SDForum block)
- The Bill Gates recollection emphasizes intense work and peer exchange among 1980s software operators, while acknowledging that some expressed bigger ambitions. (page friendship block)
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “we have to slurp up that Kool-Aid for an instant, but we can’t get addicted.” (“Drinking the Kool-Aid” block)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The interview was recorded during the December 2008 employment/financial shock and therefore captures cycle views at the time rather than after recovery. (page introduction)
- SDForum is a named sourcing route, but funded-company names and selection denominator are absent. (SDForum block)
- Bill Gates is presented as a long-standing peer/friend; friendship is not deal evidence. (friendship block)
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- sourcing: keep open institutional doors to unplanned entrepreneur contact.
- picking: inhabit the founder’s optimistic model briefly, then regain analytical distance.
- risk: conviction must remain revisable; sector fashion is not a portfolio thesis.
- portfolio: multiple technologies, not one savior category, drive a transition.
- people: patience, focus, work intensity, and ambition are observable signals.
- macro: the comments occur amid the 2008 downturn.
- boards / exits: not covered in the available text.
- The Kool-Aid rule is investor-stated · strong; its success in actual decisions is documented behavior · insufficient public record.
Contradictions, counterevidence, and access limits
- The publisher page is a selective transcript/summary rather than a full speaker-turn transcript.
- The 12:34 parent MP3 and five excerpt MP3s lack stable published timestamps; the excerpts total about 12:20 and are not independent interviews.
- Temporary belief can still create confirmation bias; the metaphor provides no explicit de-biasing procedure or kill threshold.
- The green-tech analogy is a sector-allocation comment, not evidence of Hummer Winblad’s actual green-tech portfolio.
Open questions
- Which SDForum walk-ins became investments, and who sponsored them?
- What procedure ended the “Kool-Aid” interval and tested the founder’s claims?
- What did the promised part two say about cloud, virtualization, and successful VCs?
- Did her 2008 green-tech view change after the recovery?
t The Stages of Fundraising
- URL: https://fullratchet.net/ep14-the-stages-of-fundraising-ann-winblad/ | Published: 2014 | Format: 40:50 podcast with publisher transcript and show notes | Reliability: A for direct answers; publisher warns transcript may contain errors | Access: full transcript | Accessed: 2026-08-21 | Locator scheme: speaker turns, publisher transcript line/paragraph sequence, and embedded timestamps including 00:05:01, 00:17:16, 00:20:34, and 00:23:28
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Winblad maps stages to successive proof: seed demonstrates a product and representative-market response; Series A tests market/value assumptions; Series B demands retention, upsell, sales productivity, CAC, churn, and repeatability; later rounds scale demonstrated economics. (transcript, 00:05:01 through the answer ending “I’m multiplying”)
- She warns that financing labels hide variation: a post-money mark has little economic meaning before IPO, value-producing acquisition, low-return sale, or disappearance. (transcript, answer after InsideSales.com)
- Series A is structurally scarce because it requires company-building labor and board capacity; thousands of seed companies cannot all receive A rounds. (transcript, 00:23:28 through Series A crunch answers)
- People failures, unresolved founder conflict, key-person departures, and running out of cash between proof points can break an otherwise promising financing path. (transcript, 00:17:16–00:20:00)
- Hyperion and NuoDB are used to show when team, market study, and technical ambition can justify investing before ordinary proof points. (transcript, 00:20:34 through the NuoDB answer)
- Corporate investors can provide market learning and credibility but should not be treated automatically as future acquirers. (transcript, corporate-investor answers)
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “Valuations are irrelevant until there is a liquidity event.” (answer immediately after InsideSales.com valuation example)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- Winblad recalls financing Open Systems through consulting and extreme resource constraints because venture capital was unavailable to early software companies. (transcript, background answer)
- She attributes Hyperion to founders Jim and Bob, a large perceived market, customer conversations about a hypothetical product, and the firm’s willingness to fund before proof. (00:20:34 onward)
- NuoDB is described as a cross-country, technically risky database bet with strong founder pedigree and no angel round. (same answer)
- Her cited annual capacity—at most ten new companies from roughly 500 partner-level pitches—is firm/partner aggregate, not a personal deal denominator. (Series A crunch answer)
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- sourcing: customers and corporate participants supply market evidence.
- picking: a large accessible market and extraordinary customer value trump stage labels.
- boards: A investors test assumptions, recruit, open doors, and reserve for follow-ons.
- risk: define achievable risk-reduction points and bridge only when the market belief survives.
- exits: paper valuations are provisional until liquidity.
- people: founder learning ability and hidden self-destruct tendencies can dominate product progress.
- macro / portfolio: seed abundance does not create matching Series A capacity.
- These rules are investor-stated · strong for her 2014 framework; Hyperion/NuoDB as proof of efficacy is retrospective witness · provisional without rejected-deal controls.
Contradictions, counterevidence, and access limits
- Round sizes and valuations are 2014 software-market generalizations, not timeless benchmarks.
- The transcript contains obvious errors and omissions; precise wording and garbled numbers require audio confirmation.
- Her “always” Series A positioning is firm rhetoric and needs fund-by-fund deal testing.
- Hyperion and NuoDB are selected examples; failures funded with similarly thin proof are not supplied.
- The claim that only a couple hundred new software names receive A rounds relies on unnamed/loosely cited external data.
Open questions
- What were the actual seed-to-A and A-to-B conversion cohorts in 2014?
- Which bridge decisions failed despite a still-believed market?
- How were partner board-capacity limits allocated?
- What evidence, beyond founder persuasion, supported Hyperion and NuoDB at decision time?
t Women Breaking Barriers interview with Ann Winblad
- URL: https://www.onlineeducation.com/women-breaking-barriers/interviews/ann-winblad | Published: interview conducted 2017-07 | Format: edited written record of a 30-minute telephone interview; no audio/timestamps | Reliability: A for attributed direct answers; B for edited venue framing | Access: full edited transcript | Accessed: 2026-08-21 | Locator scheme: question/answer sequence and web paragraphs 31–101; no timestamps
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Winblad says investors should “stand in the river of innovation,” deliberately meet three to five new people weekly, and source beyond inbound attention through universities, enterprise customers, and existing entrepreneurs. (answers to deal-flow and connection questions, paragraphs 35–41)
- She sharply separates roles: entrepreneurs are visionaries; venture capitalists are opportunists who see patterns rather than invent company ideas. (disruption answer, paragraphs 42–50)
- MuleSoft is her worked example of pattern alignment: five employees across four countries proposed a connected world of devices, cloud applications, APIs, and service buses before that future was fully visible. (paragraphs 45–47)
- She treats AI as convergence among cloud infrastructure, big data, and open APIs, while explicitly warning that funded companies can fail and timing remains unknown. (paragraphs 48–52)
- Culture is investable risk: public signals, repeated bad behavior, founder/investor values, and a funder’s enduring ownership relationship should be diligenced rather than rationalized away. (paragraphs 67–81)
- Her route into venture is presented as technical/operator credibility plus willingness to form a firm; representation problems compound through education, operating roles, and senior investing. (paragraphs 53–66, 85–101)
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “we’re the opportunists and the entrepreneurs are the visionaries” (answer on disruptive ideas, paragraph 44)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- She credits her father and teacher Tina Fossum for team and mathematics confidence. (paragraphs 31–34)
- MuleSoft is framed as a firm investment made around 2007 with five employees in four countries; the interview does not allocate sourcing, IC approval, or board work among partners. (paragraphs 45–46)
- She describes a recent security-software deal led by a young Israeli woman but does not name the company. (paragraph 55)
- John Hummer is credited with testing whether she had the courage to fail. (paragraphs 90–91)
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- sourcing: maintain novel-person throughput and actively query customers and operators.
- picking: pattern-match independent technical signals to a founder’s future.
- risk: timeline uncertainty and false futures remain even when the convergence thesis is plausible.
- people / boards: culture, visible conduct, and values are diligence inputs; investors remain on the cap table.
- portfolio: accept that some companies must be shut down for people, product, timing, or competition.
- macro: technical-education and operator pipelines shape who enters venture.
- exits: MuleSoft’s IPO is a retrospective outcome, not decision-time evidence.
- These are investor-stated · strong for her 2017 framework; MuleSoft causal attribution is retrospective witness · moderate and shared-firm credit remains unresolved.
Contradictions, counterevidence, and access limits
- The venue says the transcript was lightly edited for length and clarity; omitted material and exact spoken wording are unavailable.
- The biography’s 1976/$15 million/six-year shorthand conflicts with the broader 1982–1984 sale-date record.
- Her cited 7%, 16%, 85%, and accident-rank figures are acknowledged or presented without primary datasets and should not be reused as current statistics.
- Saying bad culture is “obvious” risks hindsight and false positives; no accepted/rejected values cohort is disclosed.
- AI and autonomous-driving forecasts were prospective in 2017 and should be tested, not treated as validated.
Open questions
- Which three-to-five-new-person meetings produced investments, and what was the base rate?
- What decision record supports the MuleSoft convergence thesis and partner attribution?
- What written culture diligence or kill criteria did the firm use?
- How did she distinguish a false future from merely slow timing?
t Ann Winblad’s Stanford eCorner session
- URL: https://stvp.stanford.edu/videos/introduction-to-hummer-winblad-and-mobius-venture-capital | Published: 2004-02-25 | Format: one roughly 46-minute Stanford classroom session divided into 13 official clip pages with inline transcripts | Reliability: A for direct speech and official transcripts; transcript text contains recognition errors | Access: full official clip/transcript family; five former PDF routes now return 404 | Accessed: 2026-08-22 | Locator scheme: clip title, clip timestamp where exposed, and inline transcript paragraph; 13 clips are one underlying appearance, not independent witnesses
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Winblad calls 2004 unusually attractive because Intel, Hewlett-Packard, Microsoft, and other technology leaders were asking for software companies they could not find; she treats repeated unmet requests as market “holes.” (“Introduction,” inline transcript, market-holes paragraph)
- She describes Hummer Winblad as software-exclusive, early-stage, generally co-leading, and investing Fund V; all fund/company figures are self-reported firm-level data. (“Introduction,” inline transcript, firm-and-fund paragraphs)
- “Drivers for Software Innovation” and the consumer/enterprise clip locate demand in connected devices, collaboration, customization, fair pricing, regulation, and demonstrable short-term enterprise ROI. (“How Consumer Markets and Enterprise Markets Drive the Software Industry,” inline transcript)
- “Customers Are Key” makes customer contact operational: speak with CIOs/CTOs early, expose founders without the investor present, then ask buyers whether a complete product would enter the budget and at what amount. (“Customers Are Key,” inline transcript)
- The identity-based-encryption/Voltage example says student founders reached the US Navy with a prototype, after which the firm took them to roughly 20 CIO organizations, including Kaiser and Wells Fargo, before funding. (“Customers Are Key,” inline transcript, Voltage paragraphs)
- The outsourcing clip distinguishes core architecture/invention from specifiable deployment and porting work. Voltage’s core security team remained close to the company while Indian engineers extended the product across platforms in parallel. (“Outsourcing Software Development to Asia,” inline transcript)
- The session repeatedly emphasizes timing and explicit assumption testing. It includes prospective views on Java/standards, Linux/Microsoft, the 2004 cycle, seed/Series A conditions, consumer and enterprise demand, and offshore development. Those are dated beliefs, not timeless truths.
- The archive’s 13 clips are: Introduction; Drivers for Software Innovation; How Consumer Markets and Enterprise Markets Drive the Software Industry; Recent Investments; Trends in Seed and Series A Investing; 2004 Optimism; Linux/Microsoft; Java/Standards; VC Words of Wisdom; Technologies Ahead of Their Time; Keep Testing Core Assumptions; Outsourcing to Asia; and Customers Are Key.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “We primarily do early stage investing, meaning we really like companies at the starting line.” (“Introduction,” inline transcript, stage paragraph)
- “So for you, the thing to do is to talk to customers early versus late.” (“Customers Are Key,” inline transcript, closing paragraph)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- Winblad identifies mathematics, business-management, computer-science, and economics training and dates her software-company start to 1975. (“Introduction,” inline transcript, biography paragraph)
- She names John Hummer as cofounder and contrasts Hummer Winblad’s vehicle/stage with Heidi Roizen’s Mobius vehicle. (“Introduction,” inline transcript, firm-and-fund paragraphs)
- She reports the first fund at $35 million after 113 meetings, Fund V at $420 million and about one-third invested, and more than 90 firm-level software companies. (“Introduction,” inline transcript, fund paragraphs)
- T/Maker is identified as Roizen’s company and the firm’s first investment, reported here at 5x. (“Introduction,” inline transcript, T/Maker paragraph)
- Voltage evidence credits Terence Spies, Dan Boneh, Guido Appenzeller, student founders, customer organizations, and a distributed engineering team; it does not support sole Winblad authorship. (“Customers Are Key” and “Outsourcing,” inline transcripts)
- Recent-investment and stage clips concern Hummer Winblad and Mobius portfolios/strategies; mirror pages do not add independent corroboration.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- sourcing: learn missing product-architecture pieces from incumbents and customers; treat repeated confidential needs as search directions.
- picking: prefer large gaps whose buyers can explain budget value; distinguish customer enthusiasm from a founder-only story.
- boards: place young teams before prospective customers, gather unfiltered reactions, and help define commercialization.
- risk: write core assumptions, test them, and distinguish a technically possible product from a market whose timing is wrong.
- people: value technical depth, founder learning, and teams able to recruit specialized contributors.
- portfolio: co-leading and stage focus constrain capital and partner capacity.
- macro: consumer connectivity, enterprise regulation, broadband, open standards, Linux, and distributed development shape the 2004 opportunity set.
- exits: not developed as a standalone process in the clip family.
- These are investor-stated · strong for the 2004 framework; evidence of consistent portfolio application is documented behavior · insufficient public record.
Contradictions, counterevidence, and access limits
- The “Introduction” transcript says 113 meetings/$35 million; Charlie Rose says 150/$30 million; Berkeley, TEDx, and EIX say 133, with Berkeley/TEDx using $35 million. Meetings versus rejections, interim versus final close, and transcript error remain unresolved.
- T/Maker’s 5x conflicts with 3x in 2019; no investment/distribution schedule fixes the basis.
- The technology-timing clip calls Slate about 13 years early, while the 2012 oral history says 25 years; both are retrospective estimates.
- The Linux, Java, standards, and optimism clips are prospectively scoreable 2004 forecasts. Repetition within the session is not independent support, and later outcomes must not be inserted into the original reasoning.
- The outsourcing transcript’s suggestion that offshore engineers “do not have the vision to be inventors” is a broad unsupported generalization and conflicts with its own evidence of globally distributed technical talent.
- Official transcripts contain misrecognitions such as T/Maker/“Team Maker,” Greylock/“Graylog,” and HIPAA/“Hippo”; exact figures and quotes require audio caution.
- The official archive fragments one session into 13 pages plus transcript mirrors, creating a major double-counting risk.
Open questions
- Which companies motivated each named 2004 market gap, and which were funded?
- What buyer feedback from the 20-CIO Voltage exercise entered the investment decision?
- How did the Java, Linux, standards, offshore-development, and cycle forecasts age against named observations?
- Which IC, board, or reserve records show assumptions being revised or a company being stopped?
- Why do the first-fund meetings, amount, T/Maker return, and Slate-timing figures change?
t Auditioning the Future
- URL: https://www.youtube.com/watch?v=HybHcXGvrGM | Published: 2011 | Format: official TEDxBayArea stage video with YouTube English captions | Reliability: A for direct speech; caption wording requires audio check where garbled | Access: full video and full caption track | Accessed: 2026-08-21 | Locator scheme: video timestamps; captions contain visible automatic-transcription errors
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Winblad frames venture capital as “auditioning the future”: hearing highly compressed pitches, selecting a very small fraction of new companies, and accepting that uncertainty cannot be eliminated. (03:26–03:36; 06:37–06:52)
- She says about 40% of the companies the firm funded failed, a rare direct failure-rate claim that needs a defined fund/company denominator. (04:12–04:18)
- The talk connects venture funding with innovation, job creation, and high-wage information-economy activity, but its stage format is advocacy rather than a balanced performance audit. (04:18–06:03)
- She uses the history of pension-fund eligibility and the young venture asset class to situate the industry’s growth. (02:11–03:05)
- Gender and access are a central purpose of the talk; she challenges women to enter a still-small industry rather than treating representation as already solved. (entry/fundraising 13:00–15:08; education pipeline 15:13–16:10)
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “Every day I get to audition the future.” (03:26–03:31)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- She dates becoming a venture capitalist to 1989 after her software company’s acquisition and move from Minnesota. (00:56–01:15)
- She recounts 133 meetings/rejections before entry, then turns to the women-and-education pipeline. (13:00–16:10)
- The failure-rate statement is firm-level and retrospective; it is not a Winblad personal batting average. (04:12–04:18)
- The talk describes venture’s screening role but does not provide investment-committee records or company-level acceptance/rejection data.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- sourcing: maintain exposure to many compressed views of the future.
- picking: select rare companies from a very large formation base.
- risk / portfolio: accept a meaningful failure rate rather than demand certainty.
- macro: capital-policy changes, entrepreneurship, and innovation ecosystems shape opportunity.
- people: widen access to the venture profession.
- boards / exits: not developed in the surviving caption analysis.
- The “audition” and failure-tolerance claims are investor-stated · strong; broader claims of economic causation are investor-stated · provisional without the underlying studies.
Contradictions, counterevidence, and access limits
- The 40% failure figure lacks a named cohort, follow-on rule, date cutoff, or definition of failure.
- Advocacy about jobs and innovation may omit displacement, failed-company costs, and attribution to founders, employees, public research, or later capital.
- YouTube captions visibly garble names and numbers; at 04:28 they render a “22% GDP” figure that is almost certainly a decimal error, so it is excluded pending slide/audio validation. Only short clearly aligned quotations are retained.
- The talk is retrospective on the 1989 founding and not contemporaneous evidence of that decision.
Open questions
- What company/fund denominator supports the 40% failure rate?
- Which claims are backed by a study shown in the talk but absent from the captions?
- How did Winblad define success for surviving private companies?
- Which gender-access recommendations led to documented firm actions?
w Ads Worth Sharing: Measuring Extraordinary Creative
- URL: https://www.linkedin.com/pulse/20121106193742-32875-ads-worth-sharing-measuring-extraordinary-creative | Published: 2012-11-06 | Format: signed LinkedIn essay | Reliability: A for Winblad’s analysis; B for third-party Ace Metrix/TED measures she reports | Access: full/dynamic | Accessed: 2026-08-21 | Locator scheme: body paragraphs 28–40 in accessed text view; paragraph-opening phrases
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Winblad argues that audience attention is not simply shrinking; people ration attention away from distractions but spend it on idea-driven content that delights, informs, or frightens.
- TED’s Ads Worth Spreading program is her case: expert committees selected nominations and Ace Metrix added responses from more than 500 ordinary US viewers, combining qualitative judgment with quantitative audience evidence.
- She reports that all ten selected ads exceeded average attention scores, nine exceeded likeability norms, and the group averaged roughly 4.5 times normal television-commercial length.
- Mazda, Sharpie, and L’Oréal used longer form to tell stories rated around the 90th percentile for authenticity; she reports brand perception improving for more than 60% of respondents for those examples.
- She reports an average 70% stated willingness to share, mostly verbally, with Facebook and email secondary.
- The reasoning is content quality → earned attention → sharing and changed perception. It does not establish conversion, retention, revenue, causal incrementality, or venture outcome.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “consumers have limited attention for distractions.” (paragraph 30)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The essay documents Winblad engaging directly with marketing analytics and combining expert selection with customer response in 2012.
- Its ideas align with her 2005 claim that product marketing should listen to customers and mediate sales/engineering demands, but no investment use is documented. WilmerHale Q&A, printed p. 18
- The political-ad coda applies the same measurement frame to a different category rather than treating creative prestige as self-validating.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- picking: combine expert qualitative judgment with observable customer response; do not equate format length with engagement failure.
- people: ideas, authenticity, and storytelling can earn attention.
- risk: shareability and likeability are intermediate measures, not business outcomes.
- boards: product-marketing teams should specify what response metric validates a creative thesis.
- sourcing / portfolio / exits / macro: no direct evidence.
- The marketing-measurement logic is investor-stated · strong; translating it into venture diligence is researcher inference · moderate.
Contradictions, counterevidence, and access limits
- TED’s ten ads were preselected; beating averages does not show the selection method works on an unfiltered population.
- The reported measures are from Ace Metrix and stated survey responses; the article does not provide experimental controls, confidence intervals, spend, reach, conversion, or sales.
- Authenticity, attention, likeability, sharing intent, and commercial impact are distinct.
- Long-form success in selected examples does not imply length caused success.
- LinkedIn is dynamic and lacks stable numbered paragraphs.
Open questions
- Did Hummer Winblad use audience-response testing in consumer or marketing-software diligence?
- How did Ace Metrix define its scores, sample, and norms?
- Which downstream outcomes—conversion, retention, pricing, or revenue—tracked the reported attention and sharing signals?
w Auditioning the Future of Software: A 30 Year Journey
- URL: https://www.linkedin.com/pulse/auditioning-future-software-30-year-journey-ann-winblad | Published: 2019-11-01 | Format: signed first-person essay | Reliability: A | Access: full/dynamic | Accessed: 2026-08-21 | Locator scheme: paragraph-opening phrases; accessed text-view lines 28–41
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Winblad connects three claims: a software-only mandate looked implausibly narrow in 1989; Fund I’s selected outcomes validated it; and the specialization endured through Fund VII.
- She dates Fund I’s close to September 1989 and the first T/Maker investment/board seat to November 1, reporting a $300,000 Series A lead check.
- She reports more than 130 unsuccessful LP pitches before endorsements from Pitch Johnson, Bill Edwards, and Don Valentine and commitments from 3M and “State Farm Insurance.”
- She reports 16 Fund I companies, $27 million of investable capital, $252 million returned, and six IPOs. These are basis-ambiguous self-reports, not audited net returns.
- Her causal account is specialization → distinctive deal flow → early lead positions → operator support. It is a stable self-conception, not proof of causation.
- By 2019 she says the mandate had narrowed from enterprise plus some consumer software to enterprise software, normally leading the first venture round before ten employees.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “We were constantly told that focusing solely on software was somewhere between too risky and downright wacky.” (paragraph beginning “We were constantly told”)
- “Our investable capital in this fund of $27 million returned $252 million to our LPs.” (paragraph beginning “Fund I”)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The essay assigns explicit fundraising roles to John Hummer, Johnson, Edwards, Valentine, 3M, Jerry Okerman, and a Minnesota insurer.
- It names Heidi Roizen/T/Maker as the first deal and Hyperion, Wind River, and Powersoft as Fund I examples.
- The anniversary format selects successes and omits Slate, Napster, ordinary outcomes, later-fund dispersion, partner attribution, reserves, fees, and ownership.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- sourcing: specialization can make a new firm legible and generate distinctive founder access.
- picking: narrow mandate and first institutional round; no diligence test is specified.
- portfolio: 16-company Fund I and 150-plus firm-level lifetime claim, neither a personal ledger.
- boards: the first board seat anchors the story, but post-investment work is generalized.
- risk: category concentration that LPs regarded as unusually risky.
- people: founders, partners, endorsers, and LP advocates make this a network story, not solo credit.
Contradictions, counterevidence, and access limits
- The $27 million investable / $252 million account conflicts in basis with $35 million / about or over 10x accounts; no gross/net, recycling, fee, timing, or IRR schedule is supplied.
- The essay reports T/Maker at 3x; the 2004 Stanford session reports 5x. Check basis, dilution, and measurement date remain unresolved.
- “State Farm Insurance” conflicts with “St. Paul Companies” in the oral history.
- “First venture capital firm focused on software” is a scoped category claim, not an “earliest woman VC founder” claim.
- LinkedIn is dynamic and has no stable numbered paragraphs.
Open questions
- What documents reconcile committed, investable, recycled, and distributed Fund I capital?
- Which Minnesota insurer subscribed?
- Was $300,000 T/Maker’s first tranche and $750,000 a broader amount?
- Which partners sourced, sponsored, governed, and exited the named companies?
w Class of 2013: Don’t Sweat Your First Job
- URL: https://www.linkedin.com/pulse/20130521101113-32875-class-of-2013-don-t-sweat-your-first-job | Published: 2013-05-21 | Format: signed LinkedIn essay adapted from a 2001 commencement address | Reliability: A for direct signed text; cited survey statistics were not independently re-audited | Access: full/dynamic | Accessed: 2026-08-22 | Locator scheme: paragraph-opening phrases in the exposed article body
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Winblad argues that graduates and parents over-optimize the first job when long-run value comes from critical thinking, problem solving, openness to ideas, and continued learning. (paragraphs beginning “Given the shift” and “While it looks”)
- She uses her own path as the mechanism: mathematics led to a programming elective and every available computing course; uncertainty about a job led her to add business administration; a well-paid Federal Reserve role then gave way to entrepreneurship. (paragraphs beginning “I graduated” and “I was fortunate”)
- The investment analogy is explicitly long horizon: the education's internal rate of return accrues over time rather than being captured by first-job pay. (final paragraph beginning “While many will look”)
- The article encourages technical learning for women and names Girls Who Code, Girl Develop It, and Black Girls Code as support routes. (paragraph beginning “I speak with many young graduates”)
- The post says it was adapted from Winblad's spring 2001 University of St. Thomas commencement address, so the 2013 publication is a revised retrospective rather than a new contemporaneous career memo. (final note)
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “I quit my first job and went from a great salary to almost zero.” (paragraph beginning “Given the shift”)
- “the internal rate of return of your education will be over time.” (final paragraph beginning “While many will look”)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- Winblad says she intended to major in mathematics, found programming through an elective, took all computing courses offered where no computer-science major existed, and added business administration because she did not know what job she would pursue.
- She says her first post-graduation job was systems analyst at the Federal Reserve Bank of Minneapolis, held for a little over a year before she resigned to start Open Systems.
- The essay supports the education and early-work sequence through Winblad's recollection; diploma, payroll, incorporation, and cofounder records remain separate verification needs.
- The career-learning analogy is her 2013/2001 direct view, not evidence that a specific HWVP investment decision applied it.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- people: learning capacity and problem solving matter more over a career than optimizing only the first role.
- risk: accepting a large salary reduction to pursue entrepreneurship is presented as a deliberate career tradeoff, not a universal prescription.
- picking: the text supports a general learning-orientation signal but supplies no founder-diligence rubric or deal example.
- macro: the adaptation contrasts the 2001 downturn and post-September-11 economy with graduates' increased focus on immediate employment.
- sourcing / portfolio / boards / exits: no investment-process evidence is disclosed.
- The learning thesis is investor-stated · strong; its application to investing is researcher inference · insufficient public record.
Contradictions, counterevidence, and access limits
- The essay says Open Systems followed a little over a year at the Federal Reserve; other public accounts still conflict on the company's exact start year. It does not resolve that chronology.
- It presents a successful retrospective path and does not examine graduates whose early-job choice materially constrained later options; the IRR metaphor has no measured cash-flow analogue.
- UCLA aspiration and gender-share statistics are reproduced as Winblad's claims and were not independently re-audited for this note.
- LinkedIn is dynamic, but the complete article body was exposed through the canonical route on 2026-08-22; the earlier metadata-only boundary was removed.
Open questions
- What differs between the spring 2001 commencement speech and the 2013 adaptation?
- Which contemporaneous diploma, course, employment, and incorporation records resolve the early chronology?
- Did HWVP record learning capacity as a dated founder score or post-investment development measure?
w Entering the Enterprise Era
- URL: https://archive.computerhistory.org/resources/access/text/2024/06/102739322-05-0004-acc.pdf | Published: 1992-08-03 | Format: signed Computerworld essay preserved as a reprinted excerpt | Reliability: A for attributed archival excerpt | Access: partial | Accessed: 2026-08-21 | Locator scheme: 111-page CHM compilation PDF p. 66; Hotline on Object-Oriented Technology, November 1992, printed p. 23, “STRATEGIES,” attributed to Computerworld 1992-08-03
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- The excerpt acknowledges that C++ class hierarchies increased design, coding, debugging, and management complexity.
- It argues that improving tools, class libraries, operating systems, APIs, and foundation classes were mitigating those costs.
- It treats legacy code and programmer training as real switching constraints, then warns that companies ignoring enterprise computing and new object architectures risk being trapped between legacy and emerging worlds.
- This is a migration argument, not pure boosterism: adoption depends on ecosystem maturity and stranded intellectual investment.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “corporations that ignore the enterprise computing model and the new object-oriented architectures will be trapped between two different worlds.” (CHM PDF p. 66)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The excerpt appeared after the technical book and during Hummer Winblad’s early portfolio, showing public engagement with enterprise architecture rather than only fund promotion.
- It contains no named investment, underwriting, ownership, or outcome evidence.
- Connecting its migration lens to later deals remains researcher inference.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- picking: evaluate whether an ecosystem reduces adoption friction.
- risk: installed code and trained people are migration costs, not irrational resistance.
- macro: architecture transitions can strand companies between incompatible regimes.
- These implications are researcher inference · moderate because the excerpt is short but explicit.
Contradictions, counterevidence, and access limits
- The 111-page CHM compilation reproduces only a two-paragraph excerpt, not the full Computerworld essay.
- It supports a bounded reasoning chain—technical complexity is easing while lock-in persists—not a complete investment framework.
- OCR was corrected only where the scan was visually unambiguous; no full source text is stored.
Open questions
- Can the complete August 3, 1992 Computerworld article be retrieved legitimately?
- Which vendors or architectures did the full article identify?
- Did later investments consistently address migration paths and installed-base constraints?
w A Just-in-Time Software-Based World
- URL: https://doi.org/10.1145/365181.365237 | Published: 2001-03 | Format: coauthored one-page journal article | Reliability: A for Crossref/DBLP metadata; ungraded for inaccessible content | Access: metadata-only | Accessed: 2026-08-21 | Locator scheme: Communications of the ACM 44(3), p. 125, DOI 10.1145/365181.365237; publisher route returned HTTP 403
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Crossref and DBLP establish Mark Gorenberg first and Ann Winblad second as coauthors of a one-page Communications of the ACM contribution, volume 44, issue 3, page 125.
- The title is not evidence of a particular SaaS, deployment, pricing, or investment thesis without the page itself.
- No content-level argument is inferred.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- None retained; article text was inaccessible.
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- Crossref affiliates both authors with Hummer Winblad Venture Partners, documenting firm-linked technical publishing during the dot-com contraction.
- Metadata cannot allocate the work’s arguments between Gorenberg and Winblad.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- macro: the title is a lead for software-delivery thinking, not support for a claim.
- sourcing / picking / portfolio / boards / risk / exits / people: insufficient public record.
Contradictions, counterevidence, and access limits
- The SCOUT CiteSeerX URL is a CACM bibliography, not the article.
- DOI 10.1145/365181.365237 is exact; an earlier route ending 365239 belongs to another work.
- ACM returned HTTP 403; OpenAlex reported closed access and no repository full text.
- This note cannot support content analysis or a modern-SaaS attribution.
Open questions
- Can the page be retrieved through a licensed library or author archive?
- What is attributable to Gorenberg, Winblad, or both?
- Does “just-in-time” mean hosted delivery, modular assembly, or something else?
w Lessons From A Giant
- URL: https://www.linkedin.com/pulse/20121104233131-32875-lessons-from-a-giant | Published: 2012-11-04 | Format: signed LinkedIn essay | Reliability: A | Access: full/dynamic | Accessed: 2026-08-21 | Locator scheme: body paragraphs 29–59 in accessed text view; headings “Focus Forward,” “Stay Calm But Manage with Urgency,” “Choose the Best Team not Just Top Players,” and “Find Joy in the Game”
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Winblad uses Bruce Bochy’s 2012 San Francisco Giants as a leadership case built around resilience, calm combined with urgent decisions, team fit over star accumulation, flexible roles, collective purpose, and joy.
- “Focus Forward” uses injuries, suspension, competitor trades, and a 1–3 postseason deficit to argue that leaders should direct attention to the response rather than replay the shock.
- “Stay Calm But Manage with Urgency” distinguishes patience with temporarily struggling people from hesitation in live decisions: Bochy backed Lincecum, Crawford, and Vogelsong while continuing to change game tactics.
- “Choose the Best Team not Just Top Players” uses journeyman Marco Scutaro, Lincecum’s shift from starter to reliever, and Hunter Pence’s collective appeal to argue for complementary roles and low ego. The Dodgers serve as a counterexample to buying talent without integration.
- “Find Joy in the Game” makes culture reciprocal: players, coaches, and fans reinforce effort and belonging.
- The essay supplies a leadership analogy, not venture performance evidence. Its venture value is as a testable hypothesis about boards and executive teams.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “it’s not that it happens, it is how you deal with it.” (“Focus Forward,” paragraph 36)
- “Money cannot buy you a team.” (“Choose the Best Team,” paragraph 52)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- Winblad connects the essay to a Minnesota baseball childhood, her father’s Town Ball play and coaching, and the 1961 Twins.
- The article documents how she selected and narrated a leadership case in 2012; it does not identify a Hummer Winblad investment or prove applied board behavior.
- The Lincecum example makes role reassignment—not expulsion—the relevant corrective action, while the Bochy examples combine support with situational decisions.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- people: team complementarity, role flexibility, collective purpose, low ego, joy.
- boards: support underperformance while retaining urgency and willingness to change roles.
- risk: respond to shocks by updating forward; avoid both panic and inertia.
- picking: stars without integration are not a team; assess adaptability and team orientation.
- sourcing / portfolio / exits / macro: no direct evidence.
- Leadership claims are investor-stated · strong as expressed advice; venture application is researcher inference · moderate because the 2005 Q&A independently emphasizes ensembles, partner fit, and ego suppression.
Contradictions, counterevidence, and access limits
- A champion-season case is outcome-selected and can make patience look better than it was prospectively.
- The essay supplies no boundary between recoverable slump and performance requiring replacement.
- Professional sports roles, contracts, information, and feedback cycles differ from founder-led startups.
- Team cohesion can become conformity; the article does not discuss dissent or independent judgment.
- LinkedIn supplies no stable numbered paragraphs; text-view lines/headings are recorded.
Open questions
- Did Winblad use these rules in board or investment-committee settings?
- What milestone distinguishes patient role adjustment from delayed CEO change?
- Which failed company tests “stay calm” and “focus forward” against escalation of commitment?
w Object-Oriented Software
- URL: https://katalog.bibliothek.kit.edu/bib/1102925 | Published: 1990 | Format: coauthored technical book | Reliability: A for catalog metadata; ungraded for unread content | Access: metadata-only | Accessed: 2026-08-21 | Locator scheme: KIT bibliographic fields and call number 90 A 2865; no legitimate full-text locator available
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- The KIT record establishes a 1990 Addison-Wesley book by Ann L. Winblad, Samuel D. Edwards, and David R. King, 291 pages, ISBN 0201507366, classified under object-oriented programming and software.
- It is material biographical evidence of technical publishing during Winblad’s operating-to-investing transition.
- No argument, example, decision rule, or chapter claim is extracted because no legitimate full text or detailed preview was available.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- None retained; the catalog is metadata, not book text.
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- Winblad’s Berkeley oral history says Addison-Wesley approached her through a friend and dates the writing commitment to about 1985, alongside Price Waterhouse consulting and before the 1989 fund launch. Berkeley oral history, printed p. 17 / 01:00:50–01:00:51
- Coauthorship prevents assigning every unread proposition to Winblad.
- Chronological proximity to the fund permits a research question about technical credibility; it does not prove causal influence.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- picking / sourcing / risk: possible technical-evaluation and migration vocabulary, but insufficient public record.
- people: coauthorship and publisher relationship are documented; author-by-author intellectual contribution is unknown.
Contradictions, counterevidence, and access limits
- Exact-title and catalog routes found holdings and brief third-party summaries, but no legitimate text adequate for content analysis.
- Community/reseller summaries are not substituted for the work.
- This note processes the access boundary; it is not a book summary.
Open questions
- Can a licensed library copy, preview, table of contents, preface, or author excerpt be retrieved?
- Which chapters did Winblad draft?
- Does the book contain claims echoed in the 1992 enterprise-era excerpt?
w WilmerHale IT Compensation Study interview with Ann Winblad
- URL: https://www.wilmerhale.com/-/media/files/wilmerhale_shared_content/files/editorial/publication/2005compstudy_it_abridged.pdf | Published: 2005 | Format: edited interviewer-led Q&A in industry study PDF | Reliability: A for Winblad’s direct answers; B for editorial framing | Access: full | Accessed: 2026-08-21 | Locator scheme: printed pp. 16–21; PDF pp. 17–22; question openings
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- This is a hybrid direct-voice source, not an authored essay. It supplies a dated account of selection, company building, syndication, staffing, cycle discipline, and corporate-startup relationships.
- Winblad frames software specialization as a competence constraint: operating experience made software the category in which she felt qualified to invest.
- She reports Fund I as $35 million, 130 fundraising meetings, 16 companies, and “over 10 times” returned. These self-reports lack gross/net, timing, recycling, and audit detail.
- Her post-bust reasoning is that abundant 2000 capital produced fast, highly priced A rounds and weak selection; contraction restored “fast no’s,” “slow yes’s,” deeper diligence, and starting-gate discipline.
- She treats team construction as a board intervention: hire and judge the CEO; use product marketing between customer, sales, and engineering; install finance before public-market readiness.
- She reports syndicating about 80% of A rounds and assigning the partner/board member best suited to the entrepreneur and co-investor, even when another partner sourced the deal.
- Large technology companies appear primarily as customers, partners, talent pools, and acquirers—an external innovation network akin to R&D.
- She anticipates globally distributed engineering and the need to assess cross-country talent.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “We can give fast no’s, and slow yes’s.” (printed p. 17; PDF p. 18)
- “The primary job of the Board of Directors is to hire and judge the performance of the CEO.” (printed p. 18; PDF p. 19)
- “you have to put your ego aside.” (printed p. 19; PDF p. 20)
- “The VC world serves, in many ways, as R&D for the entire technology industry.” (printed p. 20; PDF p. 21)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- Winblad says John Hummer pursued her for roughly a year after Open Systems’ acquisition and that she initially viewed venture capital negatively.
- She names Powersoft, Wind River, and Hyperion/Arbor as Fund I examples and Voltage Security as a 2003 co-investment with Morgenthaler.
- Voltage illustrates a governance pattern: first-time CEO Sathvik Krishnamurthy paired with experienced director Srivats Sampath; marketing was hired first when the right candidate appeared.
- Geographic proximity and syndication describe network mechanisms but do not establish Winblad’s role in every firm deal.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- sourcing: proximity, operator networks, co-investors, and corporate outreach.
- picking: slow yes, deep diligence, software competence, and mixed-experience teams.
- portfolio: A-round focus and heavy syndication; no reserve or concentration rule.
- boards: CEO selection/replacement, role sequencing, board composition, partner fit.
- risk: capital abundance can degrade selection and operating efficiency.
- people: customer-centered marketing, early finance, adaptability, ego-suppressed assignment.
- macro: capital cycles, delivery shifts, global talent, startups as external R&D.
Contradictions, counterevidence, and access limits
- $35 million / over 10x differs in basis from 2019’s $27 million investable / $252 million.
- “Slow yes” is a post-bust statement; no pre-2000 diligence files or declined-deal false negatives are shown.
- The claim that difficult periods favor innovators rests on selected successes, not a complete vintage denominator.
- The interview omits Slate, Napster, weak funds, failed CEO changes, and cases where patience delayed a stop.
- Editorial questions shape the record; it is not authored writing.
Open questions
- What constituted “extraordinary” diligence, and did it change after 2000?
- How often did CEO replacement improve outcomes?
- Which investments were assigned to a partner other than the sourcer?
- Do portfolio and LP records corroborate the cycle and performance claims?
w Street Cred: ReadMe — Ann Winblad selections
- URL: https://www.wired.com/1997/08/street-cred-readme-2/ | Published: 1997-08-28; appeared in September issue | Format: WIRED Staff feature containing two attributed Winblad recommendations | Reliability: A for attributed comments; B for editorial framing | Access: full | Accessed: 2026-08-21 | Locator scheme: paragraphs following “Speed reader and industry optimist Ann Winblad,” text-view lines 78–82
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- The page is bylined WIRED Staff, not signed or authored by Winblad.
- Winblad recommends Oscar Wilde’s quotations for compressed communication and Katharine Graham’s Personal History for institutional endurance.
- Her Graham comment distinguishes durable enterprise-building from a five-year technology-company cadence.
- The format is a cultural signal, not an investment framework or evidence of applied patience.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “That kind of interminable enterprise isn’t created in five years.” (Katharine Graham recommendation)
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The contribution shows a 1997 interest in communication economy and multi-decade institution building.
- It contains no deal, fund, board, ownership, or performance evidence.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- people: concise communication and intellectual stamina.
- risk / exits: a preference for durability is researcher inference · provisional from a reading comment, not a documented rule.
- sourcing / picking / portfolio / boards: insufficient public record.
Contradictions, counterevidence, and access limits
- WIRED combines multiple contributors; only the Wilde and Graham paragraphs are attributed to Winblad.
- Reading preference does not prove conduct. Venture-fund life, fundraising pressure, and exits may impose horizons unlike a newspaper dynasty.
- The source is too short to support a general philosophy of patience.
Open questions
- Did Winblad discuss holding periods, durable institutions, or exit timing elsewhere?
- Which portfolio decisions, if any, demonstrate the patience praised here?