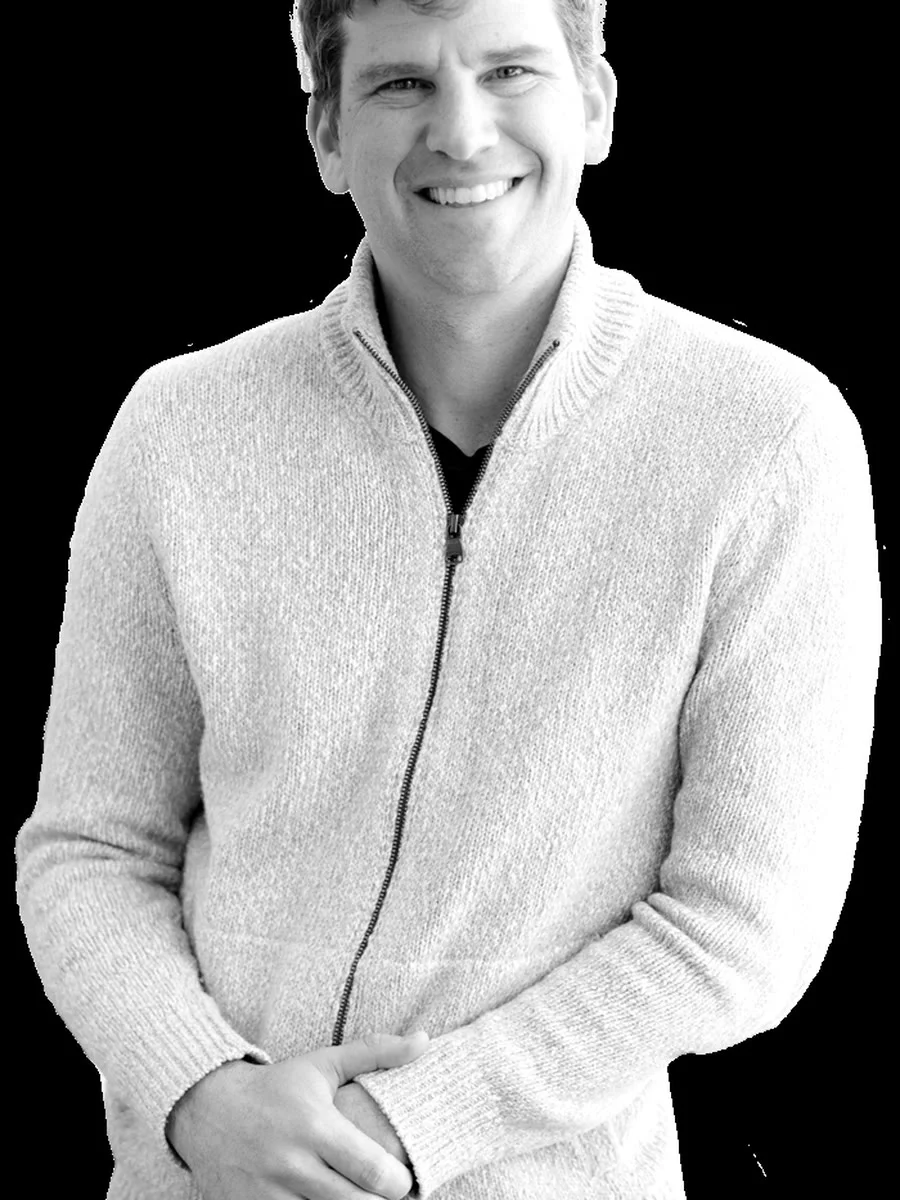
Michael Eisenberg
Three decades of Israeli venture; writes prolifically on values-driven company building.
Manhattan, Jerusalem, and a vocational turn (1971–1997)
Michael Eisenberg was born in Manhattan in 1971 and grew up in a religious Jewish family on New York's Upper West Side. He studied political science at Yeshiva College, edited The Commentator, and graduated in 1993. Those facts establish an unusual early combination—public argument, Jewish institutional life, and politics—but they do not by themselves explain an investing style. The Commentator, “path you took” question Globes profile box, 2025-05-01
The clearest first-person origin story comes from 1991, during the Gulf War, when Eisenberg was studying at Yeshivat Har Etzion. He recalls Rabbi Yehuda Amital challenging him to build an enterprise that could employ “10,000 people.” Eisenberg later presented the exchange as the reason he linked aliyah, dignified work, and economic development. It is strong evidence of how he narrates his purpose and only moderate evidence of the causal path taken three decades earlier. [retrospective witness | moderate] 18Forty, 17:20–20:58
After moving to Israel in 1993, Eisenberg worked in political consulting around the Oslo period, then moved toward technology finance. His 2017 account describes unemployment, a self-created merchant-banking activity, and PictureVision as his first investment. In a later interview he qualified the credit—he had “enabled or done” the investment, but the history was more complicated. Kodak filings verify that PictureVision was acquired in two steps, not who deserves investing credit or what Eisenberg earned. [retrospective witness | moderate] EconTalk, PictureVision passage Kodak 1998 filing Kodak 2000 filing
He worked with Shlomo Kalish at Jerusalem Global before joining Israel Seed Partners in 1997. That sequence matters more than a polished founder legend: the contemporary record says he joined an existing institution, while later biographies sometimes compress him into its founding story. [contemporaneous record | strong] Globes, 1999-10-12
Formative inference. The evidence supports a durable public purpose—use technology and enterprise to expand opportunity in Israel—and early experience translating between American capital networks and Israeli founders. It does not establish that religion, journalism, politics, or immigration caused superior selection. The more defensible causal claim is narrower: these experiences created access, a cross-border frame, and a tendency to judge companies inside a national system of skills, law, capital, and institutions. [researcher inference | moderate]
Israel Seed: company building through a violent cycle (1997–2005)
Israel Seed was a team and a set of LP-backed vehicles, not a Michael Eisenberg personal account. Jonathan Medved, Neil Cohen, Alan Feld, Eisenberg, and later managers supplied different functions; co-investors, founders, and boards did much of the company-building work. Contemporary descriptions emphasize early-stage company formation, rapid decisions, close board involvement, syndication, and helping Israeli companies reach US capital, customers, and management. [contemporaneous record | moderate] Israel Seed strategy profile, 1999 Israel Seed portfolio review, 2001
The vehicles scaled sharply. Public reporting reconstructs Fund I at an initial $2 million and a $7 million close, Fund II at $11 million, Fund III at $40 million, and Fund IV as a 2000-vintage Cayman vehicle reported at $226 million. A later firm-level figure of $262 million across four funds conflicts with the arithmetic sum of $284 million, so neither figure is a cash-flow ledger. Fund IV's general partner, adviser, economics, reserves, and partner allocations remain only partly visible. [contemporaneous record | moderate] 2005 transition report vehicle reconstruction and boundaries
This was the first era in which a recognizable method can be tested. The positive cases include DealTime/Shopping.com, GuruNet/Answers.com, Finjan, Cyota, Compugen, and Foxcom/MobileAccess; the ordinary and adverse record includes Mercado, Banter, Chiaro, MemLink, EarthNoise, Tradeum, Print Life, and other unresolved companies. The profile should not repeat Eisenberg's later claim that eight of eleven early companies reached public or acquired outcomes as an audited hit rate: the eleven are not fully identified, “backed” is undefined, the vehicles are mixed, and losses and cash realizations are missing. [retrospective witness | provisional] The Commentator, career-path answer 27-row Israel Seed ledger
Shopping.com is the strongest security-and-governance case from this period. DealTime launched in 1998; Eisenberg was a director, and later filings show Israel Seed II and IV with 1,932,158 ordinary equivalents before the 2004 IPO. The filing also shows shared Cohen/Medved/Eisenberg control and a small component held for Eisenberg's personal benefit. The company went public and was acquired by eBay, but the original checks, full dilution, distributions, fees, carry, and Eisenberg economics are not public. [documented behavior | strong] Shopping.com S-1/A, corporate history, related parties, and principal holders no-hindsight case
The period's failures are at least as revealing:
- Print Life, whose exact legal identity remains unverified, is Eisenberg's clearest admission of board error. He describes owning production capacity before demand was proven, pivoting too slowly when financing closed, and sharing responsibility with management for layoffs. [retrospective witness | moderate] Human Founder episode decision lab
- MemLink raised substantial capital for optical switching, then received a bridge that did not carry it through carrier trials or a new round. Contemporary accounts conflict over whether meaningful cash remained at shutdown. The supported lesson is milestone-to-financing mismatch, not a quantified Israel Seed loss. [contemporaneous record | moderate] January 2002 capital requirement shutdown evidence and lab
- Tradeum accepted VerticalNet stock announced at roughly $474 million before commercial product sales. The acquirer's value then collapsed. Israel Seed may still have realized an attractive return, but the shares, lockups, sale dates, and distributions are unavailable; announced value and realized cash cannot be merged. [contemporaneous record | provisional] March 2000 acquisition report realization-risk lab
- GuruNet was reportedly passed twice and funded on a third approach. Eisenberg connects the earlier passes to screening overload and interpersonal friction. The later IPO makes it a process-reversal case, not proof that the original passes were irrational. [retrospective witness | moderate] Globes, 1999-10-12 re-entry lab
- Foxcom/MobileAccess nearly closed, recovered, and was ultimately acquired by Corning. It is the necessary control against a simplistic “always stop distressed companies” lesson; the rescue actions and proceeds remain unknown. [documented behavior | moderate] Globes, January 2003 recovery lab
Fund IV keeps the biography from turning selected company exits into an institutional triumph. At year-end 2005, a CalPERS-derived record showed its $2.5 million commitment with $2.0 million contributed, $320,000 distributed, $1.2 million remaining, and a -15.8% interim IRR. Same-vintage Gemini, JVP, and Pitango funds were also negative, which supports a severe regime effect without absolving manager selection, pacing, reserves, or governance. Israel Seed abandoned preparations for Fund V in 2005 while continuing to manage active holdings. A 2011 reported mark remained sharply negative, but no final audited DPI or TVPI was found. [contemporaneous record | moderate] Fund V abandonment CalPERS snapshot and peers Fund IV decision lab
What this era changed. Later Eisenberg emphasizes durable company building, milestone finance, calm boards, and human consequences. The failures make those rules plausible learning, but no dated Israel Seed memo shows exactly when they became policy. The safe conclusion is that the period supplied the experiences later used to explain the method; a documented process change remains missing. [researcher inference | moderate]
Benchmark: scale, networks, and institutional apprenticeship (2005–2013)
Eisenberg joined Benchmark's Israel operation in 2005 as it deployed Benchmark Israel II, reported at $250 million. Arad Naveh and other local partners, the global Benchmark partnership, and legal GP entities constrain individual credit. By 2010 the dedicated local structure was being wound down after reporting insufficiently strong exits; Israeli investing could continue from the main platform. The change was neither a clean institutional failure nor proof that Israel investing ended. [contemporaneous record | moderate] 2005 transition Calcalist, 2010 wind-down
This era sharpened Eisenberg's distinction between startup activity and venture-scale value. His 2006 “DooHickeys” essay argues that cheap product creation also creates crowded me-too categories; a useful small business need not be able to return institutional capital. In 2009 he argued that weak trailing performance can improve the next opportunity set by driving capital and competition away. In the 2010–2012 Hummus essays and open letters, he shifted the Israeli ecosystem debate from startup count to scale talent, current technical stacks, global capital, anchor infrastructure, and enough ownership in large outcomes to return LP capital. [investor-stated | strong] DooHickeys, body paragraphs 1–11 Hummus Part 1 Eight Things, central test
The 32-name Benchmark-era association ledger contains pre-Eisenberg, local-fund, main-fund, and post-departure events, so it cannot be used as his personal denominator. Four companies have stronger person or filing evidence. [documented behavior | strong] Benchmark-era ledger
- Seeking Alpha is described by Eisenberg as his first Benchmark investment. It became a long-lived private company and a later patience story; check, ownership, cash flows, and liquidity remain unavailable. [retrospective witness | moderate] 2006 financing report case study
- Wix shows documented board service and selected investment fragments. Benchmark Capital Partners VI held 4,012,329 shares before the IPO; the filing explicitly says Eisenberg lacked voting and dispositive power over that block. [documented behavior | strong] A later report estimated an approximately $80 million full Benchmark disposition, a single-source gross figure rather than audited net distribution. [contemporaneous record | provisional] Wix F-1/A, financings and principal holders Wix case
- Finjan connects Israel Seed and Benchmark legal-holder histories and an Eisenberg board role. It illustrates institutional continuity, not a clean new Benchmark pick or a personal return. [documented behavior | strong] Finjan S-1/A, director and holder footnotes
- WeWork supplies unusually specific sourcing testimony: Benzi Ronen, Saul Singer, and others independently connected Eisenberg with Adam Neumann, and the founder's worldview held his attention. It does not disclose the Benchmark vehicle, IC vote, original terms, ownership, or Eisenberg's formal governance authority. [investor-stated | strong] The Commentator, “How did you end up sourcing WeWork?”
Benchmark also became the institutional model Eisenberg later said Aleph adapted. He credits equal economics with reducing internal bargaining and making bad news safer to surface, while acknowledging information asymmetry between the partner on a board and the wider partnership. This is retrospective testimony about organizational design, not a public partnership agreement. [retrospective witness | moderate] 20VC with Bill Gurley, 30:19–33:15
Ordinary-period reading. Benchmark offered platform access, experienced partners, follow-on capital, and brand. The local structure nevertheless did not continue into a third dedicated Israel fund. Wix became a visible public success and WeWork a visible governance failure, while most associations remain economically unresolved. The evidence therefore supports institutional apprenticeship and selected company contributions more strongly than personal performance. [researcher inference | strong]
Aleph: institutionalizing a relationship-and-scale method (2013–2018)
Aleph emerged from both opportunity and discontinuity. A 2013 report described a $120 million early-stage fund; Eden Shochat's official launch three days later announced $140 million, named Shochat and Eisenberg as equal founding partners, and identified Bruce Dunlevie as special partner. A separate Form D for Aleph-Aleph, L.P. offered $14 million and reported $11.125 million sold to 27 investors. These are different dated claims and vehicles, not three versions of one audited close. [contemporaneous record | strong] TechCrunch preliminary report Shochat-authored launch Aleph-Aleph Form D, Items 1–3, 7, and 13
The founding proposition was a small, equal partnership serving Israeli entrepreneurs who wanted to build large global companies. Its plausible organizational mechanism was less internal status competition, quicker decisions, and greater founder responsiveness. The legal voting rules, fee/carry allocation, reserve policy, key-person provisions, and exact company allocations are unavailable. Aaron Rosenson joined as an equal partner in 2016; later fund materials and filings also name Yael Elad and Tomer Diari in dated roles. [contemporaneous record | moderate] Forbes, Rosenson appointment people and vehicle map
Aleph's early visible cases show the method's range:
- Windward, the first announced financing, converted maritime data into security and commercial workflows, listed in London, and was acquired for cash in 2025. Aleph entities' holdings and take-private undertakings are public; cost, prior sales, distributions, fees, and carry are not. [documented behavior | strong] Windward admission document, capitalization and holders case study
- Freightos began as rate-data and quoting workflow before pursuing marketplace liquidity. It became public and grew transactions and gross booking value, while remaining loss-making in 2025. That makes it an ordinary public outcome and a useful test of software-to-network patience, not a completed return. [documented behavior | strong] 2025 results case study
- Lemonade joined relationship access, regulated full-stack execution, behavioral design, and data. At IPO filing, Aleph entities held 4,539,063 shares; the company subsequently scaled customers and premium but remained loss-making in 2025. It is a scaled operating company, not a completed Aleph realization. [documented behavior | strong] Lemonade S-1/A, holders, financials, and risks case study
- Healthy.io is the best surviving ex-ante memo. Eisenberg documented repeated learning about reimbursement, regulation, product constraints, and patient behavior before Aleph led the 2019 Series B. FDA clearances and later financing show progress; layoffs in 2023 and 2024 preserve the burn and commercialization test. [investor-stated | strong] Healthy.io essay, paragraphs 1–24 case study
The accompanying public doctrine is consistent but not yet economically validated. Eisenberg framed resilience and global ambition as Israeli founder advantages, warned that abundant capital can hide deteriorating adtech economics, and treated relationship duration as an information source. The risk is that national familiarity and founder closeness become favorable priors too difficult to reverse. [researcher inference | moderate] Optimistic About Israel 2016 Prediction
Long humanity meets governance (2018–2023)
In 2018 Eisenberg gave the method a moral vocabulary. “Long Humanity” argued that technology which restores connection, care, education, safety, dignity, and agency can create durable economic value, while attention extraction and dependency are less attractive. Empathy later applied the idea to bereavement; covenantal-capitalist writing would extend it into stakeholder obligation. [investor-stated | strong] Long Humanity, portfolio examples and closing Empathy, paragraphs 1–8
That thesis has a legitimate mechanism: trust-sensitive products can recruit mission-aligned people, reduce customer friction, and compound when business success increases customer capability rather than addiction. But mission is neither an audit nor a return. WeWork and Frank make that boundary unavoidable. [researcher inference | strong]
WeWork's 2017 bull case was not wholly imaginary. Enterprises were outsourcing workplace operations; brand, community, and scale could create a meaningful service. The contemporaneous bear case was equally visible: leases could last 15–20 years while customers rented by the month, and Regus supplied a prior cycle warning. The 2019 S-1 later disclosed large losses, lease obligations, related-party transactions, and founder control. Adam Neumann stepped down, and old equity was canceled without distribution in the 2023 restructuring. [contemporaneous record | strong] Wired, thesis and duration mismatch WeWork S-1, risk and governance sections Chapter 11 8-K, Item 1.03
Attribution matters. Eisenberg supports the sourcing/championing claim; official records identify Bruce Dunlevie as Benchmark's director from 2012. The company outcome does not establish Benchmark's lifetime cash result, and neither source supports assigning every board decision to Eisenberg. His later emphasis on steady boards, usable capital, and governance is a plausible update after WeWork, not proof of a specific contemporaneous rule change. [retrospective witness | moderate] WeWork 2023 proxy, director tenure WeWork decision lab
Frank is a sharper verification test. Aleph led a reported seed and participated in follow-ons. Before the JPMorgan sale, the FTC issued a warning that Frank may have misled consumers about fees and repayment; a warning was a governance signal, not an adjudication. The SEC later alleged customer-data fabrication; Charlie Javice and Olivier Amar were convicted, and Javice was sentenced to 85 months. Those findings concern founder/executive conduct, not Aleph knowledge or participation. JPMorgan's 2026 support-agreement claim against early holders including Aleph remained unresolved at the research cutoff. [documented behavior | strong] FTC warning letter DOJ sentencing CTech, complaint and Aleph response Frank decision lab
Frank is almost absent from the eleven-route spoken corpus. Silence is not an admission, but it prevents the public people/values/board doctrine from being treated as a tested control system. Missing evidence includes board composition, metric audits, response to the FTC warning, transaction representations, proceeds, escrow, and final civil disposition. [researcher inference | strong]
Alongside these adverse cases, Aleph expanded. Its jointly signed 2019 announcement reported a $200 million third fund. A 2021 Form D for Aleph IV offered $300 million but reported no sale at the filing date. Melio was acquired by Xero in 2025 for $2.5 billion up front plus employee-linked contingent consideration, yet the unavailable essay body and missing Aleph ownership prevent a fund-return claim. The record supports institutional continuity and company outcomes, not a personal track-record multiple. [contemporaneous record | strong] Aleph III announcement Aleph IV Form D, Items 1–3, 7, and 13 Melio case
War, AI, and a widening public role (2023–2026)
Eisenberg's public framework widened after October 7, 2023. In a December interview he described companies operating while an estimated 10–20% of employees were on reserve duty and said Aleph's LP base was overwhelmingly American and British. These are manager estimates, not audited portfolio or LP data. He linked wartime resilience to distributed civic capability: institutions should orchestrate citizens who can act at the network edge rather than manage every response centrally. [investor-stated | provisional] 18Forty, 20:58–35:51
The national commitment predates the war. Nevo Network, cofounded in 2020 to integrate immigrants into Israel's technology ecosystem, is a separate civic institution and must not be merged with Aleph's capital or outcomes. His 2024–2025 writing on Israeli domicile, covenantal capitalism, productivity, finance, infrastructure, and a “trillion-dollar economy” converts venture lessons into public-policy proposals. Those proposals are intellectually continuous with the Hummus essays, but advocacy is not evidence of fund advantage. [investor-stated | moderate] official biography and Nevo role Trillion-Dollar Economy, opening through fourth section
The AI thesis is another update of a longstanding platform model. Eisenberg argues that foundation models depreciate quickly and that durable value should move to legally controlled data, distribution, domain knowledge, workflows, network effects, or physical integration. Aleph's 2025 program proposed up to $3 million at pre-seed and a demanding revenue target for very small technical teams. The rule is young and internally tense: a fast revenue target can reward copyable wrappers before slow complements become moats. [investor-stated | moderate] Aleph AI Team, thesis and program terms 20VC solo, AI and ownership discussion
A 2026 Aleph V route verifies only the announcement title and URL; exact day, byline, legal entity, size, close, mandate, and portfolio are unavailable. “Long Israel” can be described as branding, not as a proven new vehicle strategy. [contemporaneous record | insufficient public record] Aleph V route
Eisenberg's public role also created a non-investment adverse record. In 2025 Ynet reported that Ehud Barak and Ehud Schneorson pursued a NIS 10 million defamation claim over his posts about Paragon. Plaintiffs alleged a competing commercial motive; Eisenberg denied that account and framed his remarks as public-interest scrutiny. These are contested positions with no located adjudicated disposition, and Paragon is not a portfolio-return case. [contemporaneous record | moderate] Ynet, pleadings and responses
People, capital, and influence
The investment record is better understood as a changing system than as a lone-investor story:
US and global LP capital
├── Israel Seed I–IV
│   └── Medved + Cohen + Eisenberg + other partners
│       └── founders, syndicates, boards, US managers and acquirers
├── Benchmark Israel I/II and Benchmark main funds
│   └── local partners + global Benchmark partnership
│       ├── Gurley: Shopping.com and cycle dialogue
│       └── Dunlevie: Benchmark model and documented WeWork board seat
└── Aleph / Aleph-Aleph / later vehicles
    └── Eisenberg + Shochat → Rosenson + Elad + Diari, by dated role
        ├── founders and executives create operating value
        ├── co-investors provide capital, dissent and governance
        ├── regulators, customers, platforms and public markets set constraints
        └── Nevo and civic work remain outside the fund boundary
| Person or institution | Supported influence | Boundary |
|---|---|---|
| Rabbi Yehuda Amital | Eisenberg's retrospective vocational catalyst: enterprise as dignified livelihood | No contemporaneous record proving the later career path followed from the exchange |
| Shlomo Kalish / Jerusalem Global | Early technology-finance apprenticeship and PictureVision setting | Title, capital source, security, decision rights, and economics unresolved |
| Jonathan Medved / Neil Cohen / Alan Feld | Israel Seed partnership, fundraising, boards, follow-ons, and triage | No wholesale transfer of fund outcomes or decisions to Eisenberg |
| Bill Gurley / Bruce Dunlevie / Benchmark partners | Institutional apprenticeship, co-investor and board lessons; Dunlevie documented on WeWork board | Help, board authority, fund ownership, and personal economics remain separate |
| Eden Shochat | Aleph equal cofounder; authored the launch statement; company and fund partner | Firm doctrine and deal outcomes are not solely Eisenberg's |
| Aaron Rosenson / Yael Elad / Tomer Diari | Dated Aleph partner, signatory, or GP-related roles | Carry, votes, succession, and company allocations are private |
| Daniel Schreiber / Shai Wininger / other founders | Lemonade formation and execution; Schreiber credited for New York licensing | Investor relationship and board presence do not transfer founder credit |
| Adam Neumann / Bruce Dunlevie / SoftBank / WeWork board | Distinct actors in sourcing, governance, capital, and company outcome | No evidence supports collapsing them into an “Eisenberg WeWork” result |
| Charlie Javice / Olivier Amar / JPMorgan / Aleph holders | Founder conduct, acquirer diligence, criminal findings, and unresolved contract claims | Founder convictions do not establish Aleph knowledge; complaint is not judgment |
| Kathryn Mayne / Horsley Bridge | Retrospectively credited with recognizing a fund gap and connecting Eisenberg with Shochat | No legal authority or economic allocation established |
| Founders, staff, customers and LPs | Supply company work, information, capital, and the ultimate return denominator | Company value, fund value, AUM, and personal wealth are different measures |
Function-level deal attribution—sourcing, approval, board work, recruiting, follow-on, exit, and later narration—is mapped in investments.md. Unknown is an evidence result, not an invitation to assign credit.
A falsifiable thesis of the edge
Proposed edge
[researcher inference | provisional] Eisenberg's most defensible proposed edge is relationship-led cross-border translation under a power-law discipline: within Israeli or Israel-connected seed and Series A investing, he and his partnerships use dense, repeated relationships to gain early access and behavioral information; translate Israeli technical or founder strengths into globally scaled products, management, customers, and capital; backcast from a large desired outcome to the required complements; and stay engaged through recruiting, boards, staged learning, and financing cycles.
The claimed mechanism has five links:
- Access: independent referrals and long relationships surface founders before or outside a fully priced auction. WeWork's referral convergence, Empathy's long relationship, and Healthy.io's repeated learning support the access mechanism. [investor-stated | moderate] Commentator, WeWork sourcing Empathy, founder history
- Selection: venture scale, founder learning, mission, non-consensus evidence, and a secular platform or cost curve filter the opportunity. [investor-stated | strong] DooHickeys Healthy.io
- Translation: small-market companies are built for global customers and institutions, using US capital and management without treating Israel merely as an R&D annex. [investor-stated | moderate] StrictlyVC, 2014 Q&A Hummus Part 1
- Institution: equal economics and a small partnership should reduce internal bargaining and help bad news travel, while ownership keeps outliers economically meaningful. [retrospective witness | moderate] 20VC with Gurley, 20:10–23:50 and 30:19–33:15
- Intervention: the board partner recruits, focuses attention, stages capital, and helps decide when to persist, pivot, sell, or stop. The public record shows selected acts, not a complete causal contribution ledger. [documented behavior | moderate] case-function map
Domain, period, and evidence
The thesis should apply most strongly to Israel-connected early-stage technology from roughly 1997 through 2025, particularly globally distributed software, data-rich workflows, marketplaces, and selected regulated categories where cross-border management, capital, and domain complements matter. It should apply less strongly to capital-intensive businesses whose duration exceeds the fund's reserves, local-only companies without a credible expansion mechanism, anonymous auction deals where relationship information is absent, and categories where the partnership lacks domain or regulatory competence. [researcher inference | moderate]
| Evidence class | Cases | What they support | What they do not prove |
|---|---|---|---|
| Wins / completed company outcomes | Shopping.com, Wix, Windward; Melio at company level | Cross-border company building, public or strategic liquidity, selected board/holding evidence | Comparable net fund contribution, sole Eisenberg credit, or a repeatable personal edge |
| Scaled but incomplete | Lemonade | Relationship, regulation, ownership at IPO, continuing scale | Profitability, full realization, or net Aleph return |
| Ordinary / unresolved | Seeking Alpha, Freightos, Healthy.io | Patience, workflow-to-platform logic, regulated learning, continuing operations | That patience created excess return rather than delayed resolution |
| Failures / adverse | Israel Seed IV, Print Life, MemLink, Tradeum, WeWork, Frank | Financing, security-form, governance, metric-verification, and abandonment limits | A quantified personal loss or proof that later rules existed ex ante |
| Reversal control | Foxcom/MobileAccess, GuruNet | Rescue and re-entry can be rational when evidence changes | A general rule to continue distressed companies or reverse every pass |
Denominator boundary
The searched union contains 123 institutional association rows across 121 unique corporate paths: 27 Israel Seed, 32 Benchmark-era, and 64 current Aleph-page associations. All 123 were researched to at least a dated association/status source; only 11 have partial security/governance reconstruction, 112 remain unresolved on that standard, and 14 in-ledger companies support full no-hindsight decision labs. Thirteen leads were excluded or collapsed. The actual career and fund denominator—including removals, failed companies, follow-ons, passes, write-offs, allocations, and cash realizations—is unknown, so coverage of the true portfolio and any hit rate are not computable. [documented behavior | strong] denominator reconciliation
No public cash-flow dataset supports a literal 80/20 split or identifies a dominant economic outlier. Removing Melio by headline transaction value, or Windward by completeness of security-to-exit evidence, still leaves contribution not computable. [researcher inference | strong] Pareto analysis
Predictions
If the edge thesis is real, unseen deal records should show:
- relationship-originated opportunities entering earlier, at better access or with more behaviorally useful information than auction-sourced deals;
- a higher rate of globally scaled outcomes among founders who demonstrate learning velocity and recruit cross-border management, after controlling for stage, vintage, price, sector, and partner;
- investment memos that explicitly map platform shifts and missing complements, not merely attach those explanations after success;
- initial ownership and follow-on choices consistent with power-law economics, with capital tied to dated learning milestones;
- board records showing recruiting, customer/capital introductions, governance escalation, and stop/exit decisions that affect outcomes rather than merely consume partner time; and
- relationship-led and values-aligned deals outperforming a matched denominator that includes ordinary companies, failures, and write-offs. [researcher inference | strong]
Evidence that would weaken or overturn it
The thesis would weaken if pass logs show no distinctive relationship access; if matched deals perform no better after price, ownership, stage, vintage, geography, and partner controls; if memos lack the later backcasting, governance, and abandonment rules; if portfolio returns are dominated by one unrelated outlier; if team or founder contributions explain the visible cases better than investor intervention; or if failures repeatedly receive follow-on capital without prewritten kill criteria. It would be overturned as an economic claim if complete vehicle cash flows show that the strategy did not return competitive net capital despite the coherent narrative. [researcher inference | strong]
Separating skill from favorable conditions
| Factor | Best supporting evidence | Alternative explanation / test |
|---|---|---|
| Skill | Repeated articulation of scale, platform complements, founder learning, ownership, and selected documented board roles | Doctrine may be post hoc; recover contemporaneous memos, passes, board decisions, and matched outcomes |
| Access | Cross-border networks, multiple WeWork referrals, long founder relationships, Benchmark and Yeshiva/Israel institutions | Privileged network may generate deal flow independent of selection skill; compare accessed deals with passes and auction deals |
| Team | Israel Seed partners, Benchmark global/local partners, Aleph's equal partnership, founders and co-investors | Visible outcomes may be team-led; allocate sourcing, vote, board, follow-on, and exit functions deal by deal |
| Vehicle | Increasing fund scale, Benchmark platform, Aleph early ownership and long-duration LP capital | Fundraising brand and reserves may create survival/access effects; compare legal vehicles, vintage, price, and reserve use |
| Regime | Post-Yozma Israeli growth, internet/cloud/mobile shifts, global capital, zero-rate growth, AI, and wartime policy | Sector and geography beta may explain outcomes; compare matched Israel and global cohorts using contemporaneous data |
| Luck | Platform timing, strategic acquirers, public-market windows, founder execution | Score forecasts and ex-ante dependency maps rather than outcome stories |
| Outliers | Shopping.com, Wix, Windward, Lemonade, Melio are economically plausible candidates | Costs and cash flows are missing, so neither contribution nor record excluding the top winner is measurable |
| Narrative | A large direct-voice archive creates a coherent philosophy | Writing volume and consistency do not prove implementation or returns; audit actual decisions and adverse silence |
The strongest case against greatness
The skeptical thesis is that Eisenberg is a gifted narrator, network builder, and Israeli ecosystem advocate whose public record is easier to admire than to measure. Dense American-Israeli institutional access could explain early opportunities; partners and founders could explain company execution; Yozma-era ecosystem growth, global software tailwinds, and abundant later capital could explain much of the opportunity set. Selected wins dominate his retrospective stories, while 112 of 123 association rows lack even partial security/governance reconstruction and the true portfolio denominator is unknown. [researcher inference | strong]
Israel Seed IV and the abandoned Fund V challenge a smooth learning narrative. Benchmark's dedicated Israel structure also ended without a third local fund. WeWork shows that compelling founder access and a real market can coexist with duration and governance failure. Frank shows that a mission-aligned product story and prominent acquirer do not establish metric integrity. Print Life and MemLink show that board attention does not guarantee capital staging or timely abandonment. None alone disproves investing skill; together they make a personal economic edge unproven. [documented behavior | strong] adverse postmortem map
The strongest answer is not a counter-story but discriminating evidence: audited vehicle cash flows; complete portfolio and pass denominators; original investment and follow-on memos; board minutes; individual function attribution; and vintage-, stage-, sector-, price-, ownership-, geography-, and partner-adjusted comparisons. If those records show repeatable access plus better selection and intervention across ordinary as well as famous deals, the edge thesis strengthens. If they show a few outliers, team credit, ordinary or weak net results, and rules written mainly after outcomes, the skeptical thesis wins. [researcher inference | strong]
Beliefs that changed, and those that did not
| Belief or practice | Earlier evidence | Later evidence | Best reading |
|---|---|---|---|
| Enterprise as national service | Amital story; aliyah; Israel Seed cross-border work | Nevo, wartime investing, trillion-dollar-economy advocacy | Stable purpose; causal effect on returns unproven [retrospective witness | moderate] |
| Startup count versus scale | 2006 internet and small-product essays | Hummus, Eight Things, Aleph scaleup mandate | Shift from enabling formation to insisting on global scale and ownership [investor-stated | strong] |
| Picking method | EconTalk says early work searched whitespace without a philosophy | Networks, people, backcasting, learning founders, complements | More explicit framework over time; implementation evidence incomplete [retrospective witness | moderate] |
| Capital cycles | 2009 scarcity can improve opportunity | 2016 adtech warning; 2021 tourist-capital and usable-capital distinctions | Stable regime awareness, richer security/ownership model; full forecast denominator absent [investor-stated | moderate] |
| Founder conviction | 2017 WeWork sourcing emphasizes an unusual worldview | Later board, capital, metric, and shutdown emphasis | Plausible governance update after adverse cases; no dated policy change [researcher inference | moderate] |
| Patience | Seeking Alpha and Healthy.io selected as long builds | Autonomous vehicles rejected for duration; Print Life shutdown lesson | Patience is bounded by fund horizon and learnable milestones in theory; public kill criteria missing [researcher inference | moderate] |
| Market versus state | Critiques diffuse subsidies | Advocates clusters, anchors, infrastructure, and national AI capacity | Stable boundary claim—fund shared capability, not weak firms—but capture risk remains [investor-stated | moderate] |
| Platform power | 2011 Amazon as capability anchor | 2021 Big Tech scattering; 2025 model commoditization | Platforms enable ecosystems and later extract rents; lifecycle view is coherent but retrospective [researcher inference | moderate] |
| Values | Family, Torah, service, long humanity | Covenantal capitalism and agency | Stable public identity; WeWork and Frank force values into measurable governance [investor-stated | strong] |
| Work and family | 2012 admits poor device boundaries | Later work intensity coexists with family-centered teaching | An unresolved personal operating tension, not an investment rule [researcher inference | moderate] |
Three contradictions remain productive rather than resolved. Optimism can become denial without stop rules. Relationship information can become familiarity bias without independent verification. National commitment can improve local knowledge and founder support while conflicting with the best unconstrained LP opportunity. [researcher inference | strong]
Remaining uncertainty
The public record remains weakest exactly where track-record claims become economic:
- final audited cash flows, DPI, TVPI, write-offs, and liquidation records for Israel Seed I–IV, Benchmark Israel vehicles, Benchmark main-fund Israel exposure, and each Aleph vehicle;
- a complete career denominator including passes, removed portfolio companies, failed and ordinary outcomes, follow-ons, securities, ownership, dilution, sales, distributions, fees, and carry;
- contemporaneous memos and IC records showing the stated relationship, backcasting, ownership, governance, and abandonment rules before outcomes;
- exact roles for PictureVision, Wix, WeWork, Lemonade, Healthy.io, Melio, Windward, Frank, and other prominent cases;
- board records for WeWork and Frank, including escalation, metric verification, response to the FTC warning, transaction representations, and eventual legal resolution;
- lawful full copies of seven partly accessible writings, two metadata-only writings, Aleph LP letters, original Six Kids pages, and the exact Aleph V filing/close record;
- verified English translations for the Hebrew works and publisher-certified transcripts for the auto-captioned or OpenAI-transcribed talks;
- the final disposition of the Frank holder litigation and Paragon defamation case; and
- an objective, dated scorecard for the 2009, 2012, 2016, 2021, and 2024–2026 forecasts.
Open-web discovery reached practical saturation: the last three source searches added no new material fact. The remaining gains depend mainly on lawful archive captures, LP/company records, board materials, and official court dockets. [documented behavior | strong] coverage and saturation ledger
Sourced chronology
| Date | Turning point | Evidence and boundary |
|---|---|---|
| 1971 | Born in Manhattan; raised on the Upper West Side | First-party/profile fact, not a vital record. Globes profile box |
| 1991 | Amital's enterprise-and-employment challenge during Gulf War | Retrospective motive evidence. 18Forty, 17:20–20:58 |
| 1993 | Yeshiva College graduation and aliyah | Political-science degree supported; alleged second field unresolved. YU event report |
| 1993–1997 | Political consulting, merchant banking, Jerusalem Global, PictureVision | Sequence is retrospective; transaction role/economics unresolved. Commentator career answer |
| 1997 | Joined Israel Seed | Contemporary transition evidence. Globes, 1999-10-12 |
| 1998–2005 | DealTime/Shopping.com board period, IPO, eBay sale | Security and board evidence strong; fund cash return absent. Shopping.com S-1/A |
| 2000 | Israel Seed IV vintage at technology/telecom peak | Fund size and structure reported; final fund economics absent. Fund IV lab |
| 2002 | MemLink bridge and shutdown period | Company failure documented; recovery conflict and fund loss unknown. MemLink lab |
| 2005 | Israel Seed abandoned Fund V; Eisenberg joined Benchmark Israel II | Vehicle/team transition, not personal performance proof. Globes transition report |
| 2006–2012 | Scale, power-law, capital-cycle, and national-substrate writings emerge | Direct doctrine; outcome denominator missing. writings chronology |
| 2010 | Dedicated Benchmark Israel structure began winding down | Israeli investing continued from global platform. Calcalist |
| 2012 | Benchmark-era TechCrunch interview | Earliest processed spoken checkpoint. Talk guide |
| 2012 / 2017 | Dunlevie's formal Benchmark directorship began in 2012; Eisenberg publicly recounted sourcing/championing in 2017 | The filed board date is contemporaneously anchored; the sourcing account is retrospective and does not supply an exact investment date. WeWork proxy Commentator sourcing Q&A |
| 2013 | Cofounded Aleph with Eden Shochat | $120m preliminary, $140m official, $14m parallel offering remain distinct. Shochat-authored launch |
| 2013–2014 | Windward and Freightos begin Aleph's visible company history | Company/vehicle evidence varies; no fund return. Windward lab Freightos lab |
| 2015 | Lemonade relationship and investment period | Aleph holdings later filed; thesis body partly inaccessible. Lemonade lab |
| 2016 | Rosenson joined Aleph as equal partner | Public structure claim, private economics. Forbes |
| 2018–2019 | Long Humanity and Healthy.io memo; Aleph III announced at $200m | Philosophy and fund intent, not audited return. Healthy.io essay Aleph III |
| 2019 | WeWork IPO collapse exposed governance and duration risks | Company filing does not allocate individual responsibility. WeWork S-1 |
| 2020 | Cofounded Nevo Network; Lemonade became Aleph's first IPO | Civic institution and fund outcome remain separate. official biography Lemonade filing |
| 2021 | Aleph IV Form D; JPMorgan acquired Frank | Offering notice and company acquisition do not establish fund return. Aleph IV Form D |
| 2023 | WeWork Chapter 11; October 7 shifted public/civic focus | Company equity outcome and national response evidence. WeWork 8-K |
| 2024 | 20VC and Human Founder interviews made AI, ownership, board, failure, and attribution rules explicit | Retrospective testimony; captions/transcription have stated limits. talks |
| 2025 | Windward acquisition completed; Javice sentenced; AI/national-policy writing expanded | Company/security, criminal, and policy records remain separate. Windward lab DOJ |
| 2025–2026 | Paragon defamation and Frank holder disputes remained unresolved | Allegations and defenses, not findings. Ynet CTech |
| 2026 | Agency Under Fire, later 18Forty interview, and Aleph V announcement route | Direct-voice endpoint; Aleph V body and vehicle details unavailable. talks |
Read this package as a curriculum
- Start with the writings synthesis, especially the cross-source themes and intellectual chronology. It shows what Eisenberg says and where access limits prevent stronger conclusions.
- Use the talks synthesis for the spoken evolution, then read the adverse retrospective audit. The earliest and richest checkpoints are ranked in Listen to these five first.
- Read the three Pareto views before any famous-deal story. Then inspect the denominator, people/function map, and all no-hindsight decision labs.
- For the hardest tests, use Israel Seed IV, WeWork, Frank, Print Life, and MemLink. Each asks invest/pass, kill criteria, ownership/terms, and next-check evidence before revealing the outcome.
- Continue to the investment philosophy for the operating system and modern transfer tests, then the mental-model field guide for reusable rules, mechanisms, examples, exceptions, and current checklists.
- Use the annotated source map and the 46 underlying note files linked from that map when a claim needs its access boundary, exact timestamp, printed page, heading, or source-family qualification.
The biography's bottom line is deliberately conditional: the record supports a thoughtful, persistent, cross-border company builder with an unusually explicit philosophy and several documented company outcomes. It does not yet support a measured personal return edge. The decisive future evidence is not another successful-company story; it is a complete, attributed, cash-flow and decision denominator. [researcher inference | strong]
1. Snapshot and testable edge thesis
| Dimension | Evidence-bounded answer |
|---|---|
| Investor, firms, era | Michael Eisenberg moved from Jerusalem Global to Israel Seed in 1997, joined Benchmark's Israel operation in 2005, and cofounded Aleph with Eden Shochat in 2013. The relevant record spans Israel's institutional-VC expansion, the dot-com and telecom collapse, global growth capital, and the applied-AI/war period. Globes, Israel Seed transition Globes, Benchmark move Aleph launch, body |
| Visible domain | Israeli or Israel-connected early-stage technology built for global markets: internet and telecom, software and marketplaces, regulated fintech/insurance/health, logistics/maritime data, and later applied AI and physical systems. The searched deal denominator contains 123 institution-association rows across 121 corporate paths, but is not the complete career portfolio. |
| Proposed edge | [researcher inference | provisional] Convert dense, long-duration Israel–US relationships into early access and resource connections; test unusual founders and secular change through learning, backcasting, and power-law scale; then use meaningful ownership, equal-partnership candor, and board work to help a small number of companies cross local capability gaps. EconTalk, people and backcasting, 1:06–14:51 Max Raskin, “Herzlean Task” 20VC, ownership and partnership, 21:47–33:15 |
| Scope | The thesis is most plausible for early-stage Israeli technology from the late 1990s through 2026 when global distribution, cross-border capital, management recruitment, or regulated-market navigation are binding. It is not a claim about public securities, frontier-model research, every Aleph partner, or personal returns. [researcher inference | moderate] 20VC AI, Israel/applied-AI scope, 09:17–12:08 |
| Evidence status | The intellectual and operating record is unusually rich; the economic test is not. Only 11 of 123 association rows have even partial security/governance reconstruction, and complete cost, dilution, distributions, fees, carry, passes, and write-offs are unavailable. [researcher inference | strong] denominator reconciliation |
Mechanism, predictions, and falsifiers
If the edge thesis is true, unseen contemporaneous records should show five recurring facts: logged referral convergence rather than one persuasive introduction; a written dependency map with evidence thresholds and kill criteria; company-specific proof that a local Israeli advantage can travel globally; meaningful initial ownership justified against price and reserves; and dated board, recruiting, customer, financing, or shutdown work that founders and partners independently attribute to Eisenberg. [researcher inference | strong] WeWork sourcing account, reporter question on sourcing Healthy.io decision essay, body paragraphs 1–23 20VC AI, ownership and board process, 42:35–53:48
The thesis weakens or fails if role-resolved records show that access came mainly from institutional privilege, selection and governance belonged chiefly to partners, founders, or co-investors, public rationales followed outcomes, the same rules were absent from ordinary and failed cases, or ownership- and vintage-adjusted cash results do not outperform after dominant winners are removed. WeWork, Frank, Israel Seed IV, Print Life, MemLink, and Tradeum are therefore tests of the thesis, not footnotes. [researcher inference | strong] Israel Seed IV interim-mark control WeWork S-1, risk factors and related-party sections DOJ, Frank adjudication
2. Core philosophy
Eisenberg's own words provide the shortest honest version of the system:
- “The core of my investment philosophy starts with people.” [investor-stated | strong] EconTalk, 1:06
- “You need to test the limits of the story.” [investor-stated | strong] EconTalk, 8:00
- “We consider a fresh perspective on a market to be feature and not a bug.” [investor-stated | strong] Healthy.io essay, body paragraph 3
- “Even if we have to pay more, we're optimizing for ownership.” [investor-stated | moderate] 20VC, OpenAI transcript verified to audio, 22:49–23:01
- “Don't fall in love with your own momentum, and board oversight remains critical.” [investor-stated | moderate] 20VC, OpenAI transcript verified to audio, 44:51–45:13
- “Companies take 10 years, but relationships are a lifetime.” [investor-stated | moderate] The Human Founder, OpenAI transcript, 05:09–05:13
Synthesis. [researcher inference | strong] The operating sequence is people and relationship → secular change and human response → backcast the dependency chain → seek non-consensus evidence → test venture scale and ownership → match capital to milestones → govern for truth → realize deliberately. The moral overlay—long humanity, agency, dignity, and productive prosperity—becomes investable only when it changes product incentives, metrics, and governance. This sequence is strongly evidenced as doctrine but only provisionally as an effective system because complete economics and matched decision records are unavailable. EconTalk, 1:06–14:51 and 33:39–54:29 Long Humanity, body paragraphs 7–25 20VC AI, mechanics, 35:37–53:48 denominator reconciliation
The system is deliberately conditional. People-first does not replace technical, regulatory, or integrity diligence; non-consensus does not mean contrary; power law does not erase price; patience does not mean indefinite support; and mission does not prove customer benefit. [researcher inference | strong] Healthy.io supplies a learning-centered positive example, while WeWork and Frank supply hard governance and metric-provenance controls. Healthy.io essay, paragraphs 1–23 WeWork Chapter 11 filing, Item 1.03 SEC Frank complaint announcement
3. Sourcing
Observed channels
| Channel | What the record supports | Repeatability and failure boundary |
|---|---|---|
| Referral convergence | Benzi Ronen, Saul Singer, and others independently connected Eisenberg with Adam Neumann. [investor-stated | strong] Commentator, WeWork sourcing question | Multiple independent referrals can reveal salience; they can also reflect network homogeneity. Log each referrer, conflict, evidence contribution, and rejected reference. |
| Long founder relationships | Daniel Schreiber's earlier company preceded Lemonade, and Eisenberg presents repeated founder contact as a lifetime relationship. [retrospective witness | moderate] Human Founder, opening relationship discussion | Familiarity provides behavioral history but can reduce skepticism, price discipline, and willingness to replace leadership. |
| Institutional network system | Eisenberg describes a personal associative map plus an Aleph CRM used for sourcing, recruiting, sales, business development, and financing connections. [investor-stated | moderate] Max Raskin, “Herzlean Task” | This is the clearest repeatable mechanism, but there is no privacy, data-quality, counterfactual, or deal-conversion audit. |
| Reputation and pre-round help | He treats durable conduct, relationships, and help before financing as non-price ways to win access. [investor-stated | strong] 20VC, 21:47–23:50 | Service is not evidence that the deal is good. Track the help separately from the IC score and disclose reciprocity. |
| Dense Israel–US institutions | Israel Seed, Benchmark, Aleph, US LPs/co-investors, Yeshiva/Israeli networks, and global founders form a cross-border access system. [documented behavior | moderate] Globes, Israel Seed network and model Aleph launch | Institutional privilege may explain access better than individual sourcing skill. It is hard for a new manager to reproduce and can exclude founders outside the graph. |
| Current inbound selectivity | In 2024 Eisenberg said he does little proactive sourcing after three decades and makes only two or three investments annually. [investor-stated | moderate] 20VC AI, 1:00:19–1:02:17 | This describes current senior-partner pull, not the historical funnel; it risks prestige selection and makes transfer to a new analyst especially weak. |
Sourcing operating rule
[researcher inference | strong] Record originator, referrers, relationship duration, observed behavior, independent evidence, conflicts, sponsor, why now, and rejection/re-entry condition before revealing relationship strength to the final product/market score. GuruNet shows why a pass needs a reversible evidence contract; WeWork shows why referral convergence cannot substitute for structural and governance diligence. GuruNet case WeWork case
4. Picking
Eisenberg's public doctrine weights people first, but not people alone:
- Learning and character. [investor-stated | strong] Test whether founders learn unfamiliar regulation, reimbursement, workflow, or technology and whether references show predictable conduct. Healthy.io is the clearest same-day decision document; it explicitly treats outsider perspective as an advantage while recording extensive learning. Healthy.io essay, paragraphs 1–23
- Secular change plus human response. [investor-stated | strong] Find a durable shift, ask how people will emotionally and behaviorally respond, then construct the business story. Do not invest in a category merely because it is fashionable. EconTalk, 1:06–14:51 Commentator, Israeli-trends question
- Backcast rather than extrapolate. [investor-stated | strong] State the desired future, list necessary dominoes, separate controllable from external dependencies, and identify blockers. The usable analyst addition is to add owners, deadlines, financing, and kill criteria. EconTalk, 8:00–14:51
- Venture-scale outcome. [investor-stated | strong] A useful product or good business is not automatically suitable for venture capital; the outcome must matter at fund scale after ownership and dilution. DooHickeys and MeTooHickeys, body paragraphs 1–11
- Scarcity and difference. [investor-stated | moderate] Crowded applications may be riskier than difficult domains where expertise, education, data, distribution, or physical integration protects economics. Scarcity is a hypothesis to test, not a moat label. 20VC AI, 12:12–17:52
- Complement system. [investor-stated | moderate] Diligence the talent, management, infrastructure, legal rights, regulation, energy, compute, capital, and global distribution that the company needs. Israel can supply some complements and lack others. Hummus Manifesto Part 1, body Misgav, 35:17–39:10
Red flags and decision rights
| Red flag | Diagnostic and stop condition |
|---|---|
| Founder story outruns evidence | Independently reproduce customers, users, revenue, aid, outcomes, and claims; stop or pause if management blocks validation. Frank is the required adverse control. FTC warning letter |
| Market demand hides balance-sheet mismatch | Stress fixed obligations, customer duration, related parties, governance, and a closed financing market; stop when survival depends on perpetual cheap capital. WeWork S-1, risk factors |
| Novelty without a learning engine | Name the domain experts, primary data, regulatory test, and first falsifier; downgrade if being an outsider is the only difference. [researcher inference | strong] |
| Local proof cannot travel | Separate Israeli technical/user evidence from foreign distribution, regulation, price, labor, and management requirements. Stop if the company has no financed route to global proof. [researcher inference | strong] |
| Category heat replaces company underwriting | Normalize model/provider access, logo overlap, subsidies, and copy time; reject category exposure without proprietary complements. 20VC AI, 01:18–14:09 |
| Patience has no dated gate | Require an uncertainty, evidence threshold, owner, date, cumulative-loss ceiling, and abandon/rewrite rule before each check. Golden Calf, body paragraphs 7–12 |
The public record rarely exposes Aleph's IC votes, vetoes, dissent, rejected references, or partner-specific decision rights. Picking is therefore well supported as articulated doctrine and selectively supported in cases, but not measured as a classifier. [researcher inference | strong] function-level responsibility map
5. Deal and portfolio mechanics
| Mechanic | Supported practice | Decision use and boundary |
|---|---|---|
| Ownership and price | Eisenberg says Aleph seeks meaningful ownership in the first round, rarely relies on pro rata, and may pay more for a rare company while optimizing ownership. [investor-stated | strong] 20VC AI, 42:35–44:44 20VC, 21:47–23:50 | Model ownership, dilution, reserves, and outcome size separately from price. Power law does not prove a company is the outlier; entry price still shapes middling outcomes. |
| Capital usability | Some finance, freight, banking, or payments companies may need balance-sheet credibility; excess cash in ordinary software/consumer companies may damage focus. [investor-stated | strong] 20VC, 17:49–18:59 | Require a customer or operating mechanism for the capital. A large round is not safety when it creates burn, overexpansion, or cap-table leverage. |
| Staging and follow-ons | Selected cases show bridges and repeated rounds, but the public record exposes no firm-wide reserve ratio or follow-on scorecard. MemLink, Foxcom, Healthy.io, Frank, Lemonade, and Wix show different continuation paths. [documented behavior | moderate] portfolio forensics | Every next check should name the milestone bought, syndicate capacity, cumulative exposure, and stop rule. Visible follow-ons are survivor- and news-selected. |
| Concentration | A power-law prior is explicit, and Eisenberg says he makes few new investments, but no complete position or cash-flow denominator supports a concentration rate. [investor-stated | moderate] TCTV, 08:29–09:29 20VC AI, 1:00:19–1:02:17 | Concentrate only when ownership, partner attention, reserves, and downside survivability fit; never infer a literal 80/20 split. |
| Boards | He describes data-rich pre-reads followed by one to three key questions, and says co-investor/board quality matters most in downturns. [investor-stated | strong] 20VC AI, 52:29–53:48 20VC, 30:19–33:15 | A concise meeting is useful only if independent controls, escalation rights, and truthful information exist. WeWork and Frank prevent a soft interpretation. |
| Liquidity and exits | Eisenberg favors an earlier public listing at an available price over waiting for a private headline, often prefers to hold winners, and regrets not selling some holdings during the zero-rate period. [investor-stated | moderate] 20VC AI, 35:37–42:34 | Listing, acquisition, current value, and investor realization are different events. Underwrite lockup, acquirer security, distribution, and sale policy as a second decision; Tradeum is the adverse control. |
The economic Pareto view is intentionally directional. Windward, Shopping.com, Wix, Melio, Lemonade, and Tradeum deserve verification priority, but no cost-basis and distribution ledger supports personal returns, fund contribution, hit rate, or a dominant-outlier calculation. [researcher inference | strong]
6. Vehicle and incentive fit
The strategy changed as its capital container changed; the vehicles cannot be collapsed into one personal fund.
| Vehicle era | Supported structure | How it may shape behavior | Missing control |
|---|---|---|---|
| Israel Seed I–III, 1995–1999 | The initial pool grew from a reported $2m to $7m; Fund II was reported at $11m; Fund III closed at $40m. Medved, Cohen, and Eisenberg were named around Fund III. Globes, Fund III [contemporaneous record | strong] | [researcher inference | moderate] Small pools favor early formation, syndication, partner attention, and outcomes that can matter at fund scale. | Legal agreements, LPs, fees, carry, reserves, allocations, and final cash flows. |
| Israel Seed IV and proposed V | Fund IV was a much larger 2000-vintage Cayman LP; CalPERS-derived reporting later showed an adverse interim mark. Fund V preparation was abandoned while the legacy portfolio continued. TASE vehicle disclosure Globes, Fund V [contemporaneous record | strong] | [researcher inference | moderate] A peak-vintage size step-up may increase deployment, reserve, board-load, and successor-fund pressure; peer losses show vintage also mattered. | Final DPI/TVPI/IRR, partner allocation, reserve policy, and formal fundraising cause. |
| Benchmark Israel II / main-fund period | Benchmark Israel II was reported at $250m; filed holdings show shared entity-level power. Eisenberg later said main-pool support continued after the dedicated local structure changed. Globes, 2005 Perion ownership chain [documented behavior | strong] | [researcher inference | moderate] A global platform can supply capital, pattern knowledge, syndicates, and brand while obscuring geographic authority and individual credit. | Portfolio boundary, partner votes, reserve allocation, carry, final fund results, and exact main-fund vehicles. |
| Aleph first fund and parallel vehicle | TechCrunch reported $120m before launch; Aleph's announcement said $140m. A separate Aleph-Aleph Form D offered $14m and recorded $11.125m sold to 27 investors. TechCrunch, 2013-06-30 Aleph launch Form D, Items 1–3, 7, 13 | [researcher inference | moderate] Small equal-partnership rhetoric can improve candor and founder responsiveness; centralized legal control and private agreements mean the actual mechanism is only partly visible. | Figure reconciliation, allocation agreement, LPs, fees/carry, votes, key-person terms, and reserves. |
| Aleph III–V / current firm | Aleph III announced $200m; Aleph IV's pre-sale Form D offered $300m; Aleph V is metadata-only in the processed record, while the current About page reported $850m AUM as accessed on 2026-08-22. Aleph III Aleph IV Form D Aleph About [contemporaneous record | moderate] | Larger successive pools may change check, ownership, reserves, stage, and partner load; no such policy should be inferred from AUM or metadata alone. [researcher inference | strong] | Aleph V legal vehicle, close, size, team, mandate, allocation, cash, succession, and performance. |
Equal economics are an incentive hypothesis, not a complete governance description. Eisenberg says Aleph adopted Benchmark's equal-partnership model to reduce internal bargaining and make bad news safer to surface, while acknowledging information asymmetry between the board partner and the rest of the firm. [investor-stated | strong] 20VC, 32:08–33:15 Exact compensation, carry, votes, conflicts, key-person clauses, and succession remain insufficient public record.
7. Team attribution and work with founders
LP and institutional capital
├── Israel Seed I–IV
│   └── Medved + Cohen + Eisenberg + other dated partners
├── Benchmark Israel / main funds
│   └── local partners + global Benchmark managing members
└── Aleph vehicles
    └── Eisenberg + Shochat → Rosenson + Elad + Diari, by date
        ├── founders and operators build the companies
        ├── co-investors provide capital, dissent, and governance
        └── customers, regulators, public markets, and acquirers constrain outcomes
| Work | Supported attribution | Boundary |
|---|---|---|
| Formation and institutional design | Medved/Cohen founded Israel Seed; Benchmark colleagues supplied institutional apprenticeship; Eisenberg and Shochat cofounded Aleph; Bruce Dunlevie and Kathryn Mayne appear in the retrospective Aleph-formation chain. [retrospective witness | moderate] Human Founder, 20:36–22:38 and Aleph-formation discussion | Do not turn an origin story into sole-founder credit or infer legal authority from advice. |
| Sourcing and sponsorship | WeWork referral convergence and Healthy.io repeated learning are Eisenberg-linked; many other companies have only firm association. [documented behavior | moderate] Commentator, WeWork question Healthy.io essay | Sponsor, IC vote, check allocation, and terms are usually unknown. |
| Board and recruiting | Filed/direct records support selected board roles at Shopping.com, Wix, Lemonade, Freightos, and others; Ciporin recruiting is reported; Eisenberg explicitly credits Schreiber for Lemonade's New York licensing. [documented behavior | moderate] Shopping.com S-1/A, management and holders 20VC AI, attribution correction, 55:47–56:30 | Board presence does not transfer founder execution; a fund block is not personal ownership. |
| Downturn governance | Eisenberg credits Bill Gurley, Bruce Dunlevie, Peter Fenton, and other Benchmark colleagues and says calm co-investors matter when bad news arrives. [retrospective witness | strong] 20VC, 30:19–33:15 and 46:06–47:23 | For WeWork, Dunlevie—not Eisenberg—is the official Benchmark director. WeWork proxy, director tenure |
| Founder relationship and intervention | Eisenberg calls the investor a stagehand, but also describes intense board work, priority intervention, executive recruiting, and recommending shutdown when founder time is the scarce asset. [investor-stated | moderate] Human Founder, role and shutdown discussion Max Raskin, “The Sacred and the Prosaic” | The coherent boundary is conditional intervention, not passivity; exact reserved matters and escalation rights are private. [researcher inference | strong] |
The attribution rule is simple: name the person who sourced, the vehicle that paid, the partnership that approved, the director who governed, the founder who executed, and the holder who realized. If one link is unknown, write unknown. [researcher inference | strong] function-level case map
8. Views on the craft
- Power law. [investor-stated | strong] A small number of companies can dominate value, so venture scale and ownership matter. This is a portfolio prior, not proof of any named winner or permission to overpay without limits. TCTV, 08:29–09:29 DooHickeys, body paragraphs 1–11
- Access versus selection. [researcher inference | strong] Reputation, relationships, and a network CRM may improve access; only contemporaneous evidence, price, ownership, and matched outcomes can establish selection. Max Raskin, “Herzlean Task”
- Fund size and usable capital. [investor-stated | moderate] More money helps only when the business has a real balance-sheet or milestone use; otherwise it can cause operational indigestion and cap-table pressure. 20VC, 14:53–18:59
- Cycles. [investor-stated | moderate] Innovation continues through cycles, but capital supply changes prices, talent allocation, financing risk, and realization. Cycle awareness should change preparation, not pretend to predict the turn. 20VC, 04:46–23:50 2016 Prediction, body
- Governance. [investor-stated | strong] Great venture work includes choosing truthful partners, surfacing bad news, asking the few questions that matter, and preserving the ability to act under stress. 20VC, 30:19–33:15 20VC AI, 52:29–53:48
- Exits. [researcher inference | strong] A company exit and a fund return are different. Tradeum shows stock-realization risk; Lemonade shows that listing, company performance, fund holdings, and direct personal sales must remain separate. Tradeum case Lemonade Form 4
- Great investor. [researcher inference | moderate] The supported ideal is a learn-it-all relationship builder who finds scarce change, buys enough ownership, builds a truth-seeking team, and remains accountable to capital and people. Whether Eisenberg repeatedly met that standard is not established by the public economics.
9. Signature bets and decision process
The 17 ex-ante decision labs freeze what was known before revealing the outcome. They should be used as IC exercises, not read as celebratory deal stories.
| Decision family | Cases | What to decide before outcome |
|---|---|---|
| Institutional origins and cross-border scaling | PictureVision, DealTime / Shopping.com, Wix, Seeking Alpha | Is the local capability a wedge into global demand, who does the missing management work, and which vehicle/person deserves attribution? |
| Aleph's applied-data and regulated bets | Windward, Lemonade, Healthy.io, Freightos, Melio | Which workflow, data, regulation, distribution, and ownership evidence makes the company venture-scale; what kills the thesis? |
| Fund and financing failures | Israel Seed IV / no Fund V, Print Life, MemLink | Does the next dollar buy a falsifying milestone, can the vehicle fund it, and when should a board stop? |
| Recovery, realization, and pass controls | Foxcom / MobileAccess, Tradeum, GuruNet | What distinguishes a rational rescue, how should stock consideration be realized, and what evidence makes a prior pass reversible? |
| Governance and integrity stress tests | WeWork, Frank | Can real demand survive duration, founder-control, related-party, data-provenance, compliance, and financing stress? |
Every lab asks the same four questions before the reveal: invest or continue; what kills the deal; what ownership and terms fit; and what evidence unlocks the next check. This is an analyst-created discipline grounded in the recovered record, not a claim that Eisenberg historically used a four-question form. [researcher inference | strong]
10. Mental models and maxims
The mental-model field guide reconciles the complete note and phase-document inventory into 17 distinct rules. The names and anchors below match that guide exactly; boundaries prevent related ideas from being merged into a cleaner but less faithful philosophy.
| # | Model | Earliest or strongest origin evidence | Essential boundary |
|---|---|---|---|
| 1 | Backcast the Dependency Chain | Eisenberg describes backcasting as working backward from a future through necessary dominoes. [investor-stated | strong] EconTalk, 8:00–14:51 | Procedural dependency mapping, not optimism; each domino needs evidence, owner, financing, and an abandonment date. |
| 2 | Compound Relationships into an Institutional Network | People-first investing, lifetime founder relationships, and the Aleph CRM reveal the progression from personal graph to firm system. [investor-stated | strong] EconTalk, 1:06–8:00 Max Raskin, “Herzlean Task” | Relationships create access and context, not proof; log conflicts, independent evidence, and counterfactual sources. |
| 3 | Pick Learn-It-All Outsiders and Complementary Teams | Healthy.io documents repeated learning in an unfashionable regulated category; later voice emphasizes execution and team credit. [investor-stated | strong] Healthy.io, paragraphs 1–23 20VC AI, 54:28–56:30 | People-first never substitutes for compliance, technical, scientific, or integrity diligence. |
| 4 | Match Venture Capital to Power-Law Scale and Buy Ownership Early | The 2006 scale filter and later ownership doctrine connect company potential with fund construction. [investor-stated | strong] DooHickeys, paragraphs 1–11 20VC, 21:47–23:50 | Power law does not mean price irrelevance; ownership, dilution, reserve burden, and ordinary outcomes still matter. |
| 5 | Seek Scarce Expressions of Secular Change | The 2024 AI discussion prefers difficult, specialist domains over crowded applications and ties scarcity to future importance. [investor-stated | moderate] 20VC AI, 12:12–17:52 | Scarcity without growth, gross profit, customer pull, or durability is merely obscurity. |
| 6 | Underwrite AI Complements, Not Model Access | Aleph's AI essay and interview distinguish foundation models from applied systems with data, distribution, knowledge, network, and workflow assets. [investor-stated | moderate] Aleph AI Team, closing and moat discussion 20VC AI, 01:18–14:09 | Model access and fast revenue are not moats; score revenue velocity and complement accumulation separately. |
| 7 | Practice Patient, Milestone-Gated Capital | The Golden Calf essay argues for patience under uncertainty; Healthy.io shows staged learning and external gates. [investor-stated | moderate] Golden Calf, paragraphs 7–12 Healthy.io | Patience is gated, not escalation of commitment; pre-register evidence and cumulative-loss ceilings. |
| 8 | Match Capital Intensity to Durable Financing and Customer Need | Eisenberg separates productive balance-sheet capital from indigestion; Print Life supplies the admitted financing failure. [retrospective witness | strong] 20VC, 17:49–18:59 Human Founder, 09:34–14:07 | Large markets and abundant cash do not cure duration mismatch or permanent fixed costs. |
| 9 | Design Boards and Partnerships for Truth under Stress | Board pre-reads/questions and equal-partnership candor are explicit operating claims. [investor-stated | strong] 20VC AI, 52:29–53:48 20VC, 30:19–33:15 | Governance rhetoric is challenged by WeWork and Frank; test information, independence, controls, and escalation rather than meeting style. |
| 10 | Treat Realization as a Second Investment Decision | The 2024 liquidity discussion separates IPO timing, holding winners, and missed zero-rate sales. [investor-stated | moderate] 20VC AI, 35:37–42:34 | A listing or acquisition is not DPI; model lockup, buyer security, distribution, taxes, and concentration. |
| 11 | Align Business Economics with Human Agency | Long Humanity connects business design to durable human needs and EconTalk applies the idea to named companies. [investor-stated | moderate] Long Humanity, paragraphs 7–25 EconTalk, 33:39–54:29 | Values cannot proxy product, compliance, harm, customer-outcome, or governance controls. |
| 12 | Build Portability and Power-to-the-Edge into Product Architecture | The platform-power critique and EconTalk discussion favor user agency and portable capability over lock-in. [investor-stated | moderate] Big Tech Tower of Babel, body EconTalk, 54:29–1:04:16 | Portability can weaken defensibility; state regulation can entrench incumbents or undermine security and privacy. |
| 13 | Go Global from Inception by Mapping Local Constraints | The Hummus essays diagnose Israel's management, scale, talent, platform, and global-market constraints. [investor-stated | strong] Hummus Part 1 EconTalk, 27:44–33:39 | Global ambition requires funded foreign distribution, regulation, management, and customer proof; domicile is not strategy. |
| 14 | Be Right and Non-Consensus, Not Merely Contrary | Eisenberg explicitly distinguishes a profitable non-consensus decision from consensus or simple opposition; Healthy.io is the ex-ante test case. [investor-stated | strong] Human Founder, 16:40–18:01 Healthy.io | Contrarian identity needs independent evidence, downside limits, and a falsifier. |
| 15 | Learn a Domain through Primary-Source Immersion | Eisenberg recommends learning core vocabulary, struggling through primary documents, and using that fluency to question experts; Healthy.io shows the applied version. [investor-stated | strong] Max Raskin, “Struggle With It” Healthy.io | Primary-source volume can still produce confirmation bias; require disconfirming experts and decision-relevant synthesis. |
| 16 | Invest through Cycles by Finding the Binding Scarce Input | The cycle doctrine distinguishes capital availability, talent scarcity, usable funding, and persistent innovation. [investor-stated | strong] 20VC, 05:02–23:50 2016 Prediction | Cycle timing never excuses company duration mismatch, weak unit economics, or an unfinanceable milestone. |
| 17 | Underwrite Countries as Productive-Capacity Systems | The Hummus sequence, demographic/economic writings, and civic talks treat skills, institutions, infrastructure, capital, and agency as a national system. [investor-stated | moderate] Hummus Part 1 Building Israel's Trillion-Dollar Economy 18Forty Civic, 20:58–31:52 | Firm-level global routing differs from country underwriting; civic spillovers, national mission, and LP return need separate ledgers. |
11. Evolution and contradictions
| Period | Development | Evidence and unresolved tension |
|---|---|---|
| 1997–2005: Israel Seed apprenticeship and failure | Seed formation, cross-border management, board work, the dot-com/telecom collapse, selected exits, and a failed successor-fund effort created the earliest recoverable operating laboratory. [researcher inference | moderate] | Later stories emphasize durable companies and boards, but no contemporaneous memo set proves that the mature rules governed Israel Seed IV. Globes, 2003 triage Globes, Fund V abandonment |
| 2005–2013: Benchmark and scale | Public voice by 2012 already contains power law, talent scarcity, platform shifts, and management-depth limits; Benchmark adds equal-partnership and co-investor doctrine. [researcher inference | strong] | It is unclear which ideas came from Eisenberg, which from Benchmark, and which were later articulated after outcomes. TCTV, 08:29–12:54 |
| 2013–2018: Aleph, relationships, and values | A small equal partnership, Israel-only mandate, long relationships, unusual founders, and long-humanity language become prominent. [investor-stated | moderate] | The 2017 WeWork account celebrates an unusual founder; the later governance record shows why narrative conviction needs counterweights. Commentator, WeWork question |
| 2019–2022: post-WeWork formalization | Ownership, capital usability, steady boards, backcasting, uncertainty, and cycle preparation become an integrated system. [researcher inference | strong] | The record does not show the date or content of a formal process change after WeWork, nor a public Frank postmortem. 20VC, 14:53–33:15 and 44:42–45:13 |
| 2023–2024: operating specificity | Wartime capital becomes accountability; the 2024 corpus adds AI filters, ownership, public liquidity, board format, financing failure, shutdown, and more careful team credit. [researcher inference | strong] | Public doctrine becomes richer while audited vehicle economics and pass logs remain absent. 20VC AI Human Founder |
| 2025–2026: infrastructure and statecraft | AI, energy, defense, atoms, regional complementarity, sovereignty, and productive national capacity broaden the frame beyond conventional software venture. [investor-stated | moderate] | The shift may require more capital, coordination, regulation, and patience than a small partnership can supply; no resolved outcome cohort yet tests it. Misgav, 20:36–39:10 Agency Under Fire, 04:35–10:38 |
Tensions to preserve
- Competition versus access. [researcher inference | moderate] Less capital competition could improve talent allocation in 2012, while paying more for a rare outlier could be rational in 2021. The tentative reconciliation is ownership-adjusted access to scarce talent, not cheapness alone. TCTV, 08:29–09:29 20VC, 21:47–23:50
- Founder hero versus board intervention. [researcher inference | strong] The investor is a stagehand, yet boards must protect solvency, integrity, and stakeholders. The public record does not publish the reserved-matter boundary. Human Founder, opening 20VC, 30:19–33:15
- Patience versus abandonment. [researcher inference | strong] Deep tech and atoms may need years; autonomous vehicles were rejected for excessive resolution time, and Print Life became a shutdown lesson. The reconciliation requires dated dependency and financing gates. EconTalk, autonomous-vehicle discussion Human Founder, Print Life
- Values versus verification. [documented behavior | strong] Long-humanity rhetoric can coexist with WeWork's governance failure and Frank's founder fraud. Values are a hypothesis until product, metric, compliance, and board controls work. Long Humanity WeWork 8-K DOJ Frank disposition
- Decentralized discovery versus state infrastructure. [researcher inference | moderate] Technology and civic action move power to the edge, while AI compute, energy, defense, and procurement may require coordinated national capacity. The unproven boundary is which bottleneck belongs to the state and which to firms. 18Forty Civic, 20:58–31:52 Misgav, 20:36–31:25
- Epistemic humility versus macro confidence. [researcher inference | strong] Eisenberg distinguishes knowledge from belief and prefers primary networks, yet makes national, demographic, and market forecasts without consistent baselines, horizons, or probabilities. 18Forty 2026, opening and macro questions
No surviving source shows that these tensions were resolved by a formal, dated operating-manual revision. The honest conclusion is an evolving doctrine with observable updates and unresolved implementation, not a frictionless timeless system. [researcher inference | strong]
12. Failures and limits
| Adverse case | What the record supports | Process lesson and limit |
|---|---|---|
| Israel Seed IV / no Fund V | Negative interim marks, comparable same-vintage peer pain, and abandonment of Fund V preparation; no final audited fund return. Globes, CalPERS snapshot [contemporaneous record | moderate] | Test pacing, reserves, public-stock realization, board load, and successor-fund feedback. Vintage shock is an alternative explanation, not an exemption. |
| Print Life | Eisenberg retrospectively assigns shared board/management responsibility for fixed-cost expansion, a slow pivot, and layoffs. [retrospective witness | moderate] Human Founder, Print Life discussion | Capital intensity needs a durable financing source, utilization gates, and an outsourcing alternative; company identity and loss remain unresolved. |
| MemLink and Foxcom | One bridge failed to unlock carrier validation and the company shut; the near-death control later recovered and was acquired. Globes, MemLink Corning, MobileAccess acquisition [documented behavior | moderate] | Do not learn “always stop” from a closure; compare milestone evidence, customer pull, required capital, and strategic alternatives. Economics remain unknown. |
| Tradeum | A reported $474m all-stock acquisition was followed by a buyer-price collapse; sources conflict on how much return survived. Globes, signing Globes, 2001 retrospective [contemporaneous record | provisional] | Underwrite acquirer risk, lockup, hedging, distribution, and sale plan. Neither headline value nor zero is supportable without cash records. |
| WeWork | A real demand thesis coexisted with visible long-lease/short-customer duration risk, later governance crisis, and Chapter 11. Dunlevie held the official Benchmark board seat. [documented behavior | strong] Wired, 2017 bull and bear WeWork proxy | Market truth does not rescue capital structure or governance. Benchmark's lifetime cash return and Eisenberg's authority remain unknown. |
| Frank | A 2020 FTC warning preceded a sale; founder/executive fraud was later adjudicated. A separate 2026 holder-contract suit against Aleph remains disputed. FTC letter DOJ CTech, Aleph dispute [documented behavior | strong] | Validate metric provenance, consumer claims, regulator remediation, and transaction data. Do not impute founder convictions to an investor or treat a complaint as adjudication. |
| GuruNet | Israel Seed passed twice and invested later after the model changed; the company reached an IPO. Globes, 1999 pass/re-entry [contemporaneous record | moderate] | A pass needs a falsifiable re-entry condition. Later success does not prove the early model was investable or the delayed entry uneconomic. |
The public record is structurally winner- and narration-selected. The 123-row discovered union is not the actual portfolio denominator; 112 rows lack the partial security/governance reconstruction standard, and no complete pass set or fund cash-flow ledger exists. The visible failures therefore improve the doctrine but cannot produce a hit rate, loss ratio, or personal alpha estimate. [researcher inference | strong] denominator reconciliation
13. Historical operating environment
| Era | What a contemporary IC could know | Interpretation boundary |
|---|---|---|
| 1993–1999: new institutional Israeli VC | Yozma committed $100m in 1993, created ten roughly $20m funds with government minority stakes and buyout rights, and was largely privatized by 2000. OECD, “original Yozma” [contemporaneous record | strong] | The policy opening, Israeli technical talent, immigration, and US capital routes were system advantages; they are not Eisenberg-specific skill or return. |
| 2000–2002: dot-com and telecom bust | Public B2B, internet, and optical-network values collapsed; Israel Seed paused new seed activity while triaging companies. Globes, January 2003 [contemporaneous record | strong] | Financing and public-stock risk were visible before final outcomes, but Foxcom shows that distress did not predetermine closure. |
| 2003–2005: selective reopening | IPO/M&A routes returned selectively; reported 2005 Israeli funding was $890m across 99 startups, while some managers raised successors and Israel Seed abandoned Fund V. Globes, 2006 market review [contemporaneous record | moderate] | Separate market recovery from manager selection and a company's own realization path. |
| 2005–2013: dedicated Israel funds and global pools | Benchmark Israel II brought larger institutional capacity; by 2010 reporting said no third dedicated local vehicle would be raised while Israel investing could continue globally. Calcalist, 2010 [contemporaneous record | moderate] | Platform access, local authority, specific vehicles, and partner economics must remain separate. |
| 2013–2021: scale-up and regulated software | Aleph launched into a deeper Israeli ecosystem with global capital and customers; many visible bets operated inside insurance, health, finance, freight, or maritime regulation. Aleph launch [contemporaneous record | moderate] | Software interfaces did not remove solvency, licensing, reimbursement, data, sanctions, or customer-protection requirements. |
| 2021–2026: repricing, war, AI, and atoms | Zero-rate abundance gave way to tighter funding; war stressed teams and capital; AI lowered application creation costs while increasing dependence on models, compute, energy, data rights, and regulation. Eisenberg increasingly emphasized usable capital, earlier liquidity, applied AI, and sovereignty. [investor-stated | moderate] 20VC AI Agency Under Fire | Current theses are young. Wartime anecdotes and AI category growth are not cohort returns; later views cannot be back-projected into earlier memos. |
Retrospective system controls are useful but cannot be smuggled into the ex-ante packet. The Bank of Israel later described early-stage financing as exposed to global cycles and asymmetric information; OECD later relayed an Israel Innovation Authority estimate that 20% of domestic funds generated 80% of profits. These explain why staging and power-law controls matter, not Eisenberg's performance. [researcher inference | strong] Bank of Israel, financing characteristics OECD country note
14. Modern VC translation (as of 2026-08-22)
Each major lesson below is a dated researcher transfer test, not an attribution of the added checklist to Eisenberg. Conditions can change after 2026-08-22.
| Lesson | What transfers now | What does not transfer / changed premise | Observable applicability signal | Most likely misuse |
|---|---|---|---|---|
| 1. Backcast the dependency chain | [researcher inference | strong] Backcasting remains useful when AI, regulation, procurement, hardware, or behavior must all change. EconTalk, 8:00–14:51 | Foundation-model capability and policy can move faster than a fixed five-year plan. | Each domino has an owner, dated threshold, dependency correlation, financing, and next decision. | Writing a persuasive future narrative without an abandonment schedule. |
| 2. Compound relationships institutionally | [researcher inference | moderate] Long trust, referrals, recruiting, customers, and financing remain scarce amid automated outreach. Max Raskin, “Herzlean Task” | A senior partner's three-decade graph cannot be copied by a new fund, and CRM scale raises privacy and bias risks. | Source paths are logged; independent references add nonredundant evidence; non-network founders enter the funnel. | Counting contacts, warmth, or testimonials as selection skill. |
| 3. Pick learn-it-all outsiders and complementary teams | [researcher inference | strong] Fast learners can cross regulated or domain-specific boundaries when paired with technical, commercial, and compliance experts. Healthy.io | Cheap AI prototyping makes outsider narratives common; it does not grant clinical, scientific, security, or legal truth. | The team changes its view after primary evidence, recruits missing expertise, and passes external tests. | Rewarding charisma, novelty, or hours worked while skipping integrity and domain controls. |
| 4. Match venture scale and buy ownership early | [researcher inference | strong] Model fund contribution from ownership, dilution, follow-ons, and plausible outcomes before committing partner time. DooHickeys | Low software creation cost can produce fast revenue without durable enterprise value; a small fund and large fund require different outcomes. | A security-level outcome table survives ordinary, downside, and outlier-excluded cases. | Invoking power law to ignore price, terms, reserves, or a weak base case. |
| 5. Seek scarce expressions of secular change | [researcher inference | moderate] Domain expertise, rights, distribution, physical integration, and customer education can protect economics in crowded categories. 20VC AI, 12:12–17:52 | Difficulty and small competition can also mean no market, slow adoption, or unattractive gross profit. | Named customers pay for the scarce capability; copy time and substitution are independently tested. | Confusing obscurity, complexity, or investor discomfort with non-consensus correctness. |
| 6. Underwrite AI complements, not model access | [researcher inference | strong] Test controlled data, domain knowledge, workflow insertion, distribution, network effects, physical assets, evaluation loops, and switching costs. Aleph AI Team | Model access, prompt craft, and an 18-month revenue target do not establish a moat; provider cost and bundling can change quickly. | Proprietary evidence improves with each customer and survives model/provider substitution and price shocks. | Calling purchased data, an API wrapper, or temporary model lead a compounding asset. |
| 7. Practice patient, milestone-gated capital | [researcher inference | strong] Regulated AI, health, climate, defense, and atoms may need staged technical, authorization, procurement, and economic proof. Agency Under Fire, 04:35–10:38 | Patience is not uniformly valuable for copyable software or a company whose bottleneck cannot change within the fund's horizon. | A tranche buys one named uncertainty reduction; a non-sponsor reviews exceptions. | Moving milestones, averaging down, or calling survival learning. |
| 8. Match capital intensity to durable financing and demand | [researcher inference | strong] Compute, energy, inventory, security, regulated balance sheets, and physical deployment require a financing map and customer reason for capital. 20VC, 17:49–18:59 | Abundant private capital and large TAM do not remove lease, hardware, or refinancing duration mismatch. | Customers value balance-sheet credibility; runway reaches the next external proof under downside pricing. | Treating a large round, capex, or strategic investor as moat or solvency. |
| 9. Design boards and partnerships for truth under stress | [researcher inference | strong] Pre-reads, few decisive questions, independent directors, audit rights, compliance logs, and escalation paths matter more as AI and regulation increase information asymmetry. 20VC AI, 52:29–53:48 | Equal economics and founder friendship do not by themselves surface fraud, related parties, safety issues, or customer harm. | Bad news reaches non-sponsor decision-makers; data are independently reproducible; reserved matters can be exercised. | Optimizing meeting elegance or “founder-friendly” posture instead of control effectiveness. |
| 10. Treat realization as a second decision | [researcher inference | strong] Compare IPO, tender, acquisition, distribution, holding, and hedging against dilution, liquidity, concentration, and vehicle life. 20VC AI, 35:37–42:34 | “Ride winners” is not a universal rule when lockups, acquirer stock, fund concentration, or LP liquidity bind. | The board/fund precommits decision ranges and records why information advantage justifies continued exposure. | Counting announced transaction value as return or narrating every unsold winner as conviction. |
| 11. Align economics with human agency | [researcher inference | strong] Convert dignity, agency, trust, and prosperity into product outcomes, complaint/harm measures, pricing, data-use rules, and compensation. Long Humanity | AI can scale persuasion, error, surveillance, and exclusion faster than a mission statement can correct them. | Customer benefit rises with revenue; harms trigger board action; vulnerable users have appeal and exit paths. | Giving a mission narrative underwriting credit without controls, as the Frank and WeWork stress tests warn. |
| 12. Build portability and power to the edge | [researcher inference | moderate] Data export, multi-model/provider architecture, customer control, and auditable permissions can reduce platform dependence. Big Tech Tower of Babel | Full portability may conflict with privacy, security, safety, network value, and legitimate switching costs. | Contractual data rights, tested migration, interoperability, and provider-stress results exist. | Sacrificing defensibility or security in the name of abstract decentralization. |
| 13. Go global from inception by mapping local constraints | [researcher inference | strong] Small-market companies should identify where product truth, customer truth, regulation, management, and capital must be obtained. Hummus Part 1 | Remote work and AI tools help execution but do not erase local procurement, trust, labor, language, tax, or licensing. | Paid foreign customers, local regulatory authority, repeatable sales, and a funded management plan appear before expansion. | Opening offices or reincorporating before evidence identifies the real constraint. |
| 14. Be right and non-consensus, not merely contrary | [researcher inference | strong] Map consensus, specify the differentiated claim, and pre-register evidence that would prove or disprove it. Human Founder, 16:40–18:01 | AI and geopolitical narratives make fashionable contrarianism easy; disagreement alone creates no payoff. | Independent customer/technical evidence improves while informed consensus remains skeptical for a stated reason. | Treating criticism as validation or adding “non-consensus” after the outcome. |
| 15. Learn through primary-source immersion | [researcher inference | strong] Read filings, contracts, technical papers, regulator records, and customer data; learn vocabulary before expert calls. Max Raskin, “Struggle With It” | AI summarization accelerates orientation but can omit qualifications, hallucinate, or reproduce source bias. | Analysts can trace each decision claim to an original record and articulate the strongest contrary expert view. | Measuring reading volume rather than changed probabilities or actionable evidence. |
| 16. Invest through cycles by finding the scarce input | [researcher inference | strong] Distinguish capital, talent, compute, energy, customers, authorization, and management; invest through cycles when innovation persists and the bottleneck is financeable. 20VC, 05:02–23:50 | Macro awareness does not make a manager a market timer or rescue a business with bad duration and unit economics. | The memo names the binding constraint, downside runway, financing terms, and evidence that new capital relaxes it. | Using a cycle narrative to justify permanent bullishness, defensiveness, or unlimited reserves. |
| 17. Underwrite countries as productive-capacity systems | [researcher inference | moderate] For defense, AI, energy, and infrastructure, map talent, institutions, capital, alliances, procurement, regulation, and physical capacity. Misgav, 20:36–39:10 | National resilience, civic value, ecosystem spillover, company economics, and LP return are different ledgers; mission does not collapse them. | Named projects, contracts, capacity, authorization, talent flows, revenue, and private-return paths exist. | Turning national optimism, subsidy, wartime selection, or political preference into a company-return thesis. |
The practical 2026 rule is to preserve the original insight while adding the control its adverse case exposes: network plus independent evidence; people plus verification; power law plus price; patience plus gates; agency plus governance; country mission plus separate LP economics. [researcher inference | strong]
15. Comparison with completed peers
The comparator set is limited to three completed canon rows and is dimension-matched rather than ranked. Bill Gurley is the closest same-institution, co-investor, board, ownership, and cycle comparator; Andy Rachleff is the closest Benchmark-origin and non-consensus/product-evidence control; Chemi Peres is the closest Israeli ecosystem, vehicle, and global-from-a-small-market control. [researcher inference | strong]
| Dimension | Michael Eisenberg | Bill Gurley | Andy Rachleff | Chemi Peres |
|---|---|---|---|---|
| Why valid | Focal investor across Israel Seed, Benchmark Israel, and Aleph. | Worked with Eisenberg at Benchmark and appears beside him in the strongest cycle/board discussion; same equal-economics institution, different US marketplace/public-economics specialization. 20VC joint episode, 30:19–47:23 [documented behavior | strong] | Benchmark cofounder whose earlier enterprise/infrastructure practice tests whether non-consensus, material ownership, and partnership behavior belong to the institution rather than Eisenberg. Forbes, Benchmark structure [researcher inference | strong] | Same Israeli venture buildout and global-market constraint, but Pitango's larger diversified platform and different vehicles provide a useful institutional contrast. Wharton, vehicle and founder doctrine [researcher inference | strong] |
| Sourcing | Long relationships, referral convergence, cross-border network, and CRM; conversion unmeasured. | Public analysis, founder/executive networks, and partner-led thematic search; his Uber account is the clearest hunted-substrate example. Gurley philosophy, sourcing | Inflection maps, trusted institutional networks, teaching/advising; source funnel remains incomplete. Rachleff philosophy, sourcing | Longitudinal contact, co-investor/referrer networks, and Israel–US/Asia institutional bridges; channel outcomes remain unknown. Peres philosophy, sourcing |
| Picking | People-first learning, secular change, backcasting, non-consensus, venture scale, and complement mapping. | Changed market equilibrium plus demand aggregation, revenue quality, unit economics, and founder learning. Gurley marketplace checklist | External change → proprietary non-consensus insight → narrow desperate customer → value before growth. Pattern Breakers transcript | Adaptable honest domain experts, global-market evidence, complementary teams, and market-specific authorization. Peres PMF essay |
| Ownership and portfolio | Meaningful first-round ownership and few deals are stated; reserves, concentration, and returns are unavailable. | Large filing-backed stakes and Uber outlier sensitivity; price/security economics are much more explicit, but complete returns remain absent. Gurley philosophy, mechanics | Filing-visible material positions, magnitude doctrine, and staged capital; one MPAE LP result is stronger fund evidence than Eisenberg's record but not personal return. Rachleff philosophy, mechanics | Sector/stage balance and platform support are stated; ownership, reserves, and complete economics are thinner. Peres philosophy, mechanics |
| Governance and founder work | Founder-as-hero plus intense questions, recruiting, shutdown, and equal-partnership candor; WeWork/Frank test control effectiveness. | Long board tenure and economic analysis, with Uber/Epinions showing information and stakeholder limits. Gurley philosophy, team | Candid context, staged financing, and board service; Ipsilon/Equinix/Opsware test productization, rescue, and founder/partner attribution. Rachleff philosophy, team | Founder agency, patient boards, team building, and debriefing; public intervention evidence is sparse and shared across multiple principals. Peres philosophy, team |
| Vehicle and incentives | Small seed funds → peak-vintage Fund IV → dedicated/global Benchmark pools → Aleph equal partnership; legal and economic detail is incomplete. | Benchmark IV–VIII pooled entities and equal economics provide the closest same-firm control; Gurley was not named in Fund X. Gurley philosophy, vehicle | MPAE, Benchmark, personal/family, and Wealthfront roles show how the same person changes with capital form; active Benchmark tenure ended in 2004. Rachleff philosophy, vehicle | Public Mofet → private partnerships → specialist/continuation entities; vehicle duration and public disclosure are more central. Peres philosophy, vehicle |
| Failures and learning | Israel Seed IV, Print Life, MemLink, Tradeum, WeWork, Frank, and GuruNet expose financing, realization, governance, integrity, and screening limits. | Google miss, Epinions, Uber governance, Good Eggs, Nanosolar, and Fanbase test public doctrine against real exceptions. Gurley failures | PointCast, Ipsilon, Equinix rescue, Loudcloud/Opsware, and Google test timing, productization, capital, and false negatives. Rachleff failures | GoRefer/Shopserve, Pitango III marks, and disputed deal credit test patience, diversification, and attribution. Peres failures |
What the comparison changes
- Gurley reduces personal attribution. [researcher inference | strong] Equal economics, steady-board language, ownership thinking, and co-investor lessons have a Benchmark institutional origin; Eisenberg himself credits those colleagues. The discriminating evidence is partner-specific sourcing, memos, votes, and board action—not similarity of rhetoric. 20VC joint episode, 30:19–47:23 Gurley vehicle analysis
- Rachleff narrows the claimed novelty. [researcher inference | strong] Non-consensus insight, market proof, material ownership, and a small partnership predate Eisenberg's Benchmark tenure. Eisenberg's more distinctive contribution may be combining that architecture with Israel–global networks, moral-economic writing, and country-level complement analysis. Forbes, Benchmark structure Rachleff philosophy
- Peres isolates geography from firm design. [researcher inference | strong] Both treat Israel as technical substrate plus management/market constraint, but Peres's diversified platform and specialist vehicles contrast with Aleph's cottage-partnership claim. Similar geography does not imply identical portfolio construction or return. Wharton, vehicle and founder doctrine Peres vehicle analysis
None of the three supplies a compatible personal-return benchmark. Differences in era, stage, geography, domain, vehicle, public evidence, and role duration prohibit a league table; the comparison is useful only for mechanism and attribution. [researcher inference | strong]
16. The strongest case against greatness
Skeptical thesis. [researcher inference | strong] Eisenberg's visible reputation may be explained by privileged cross-border access, three strong institutions, partner and founder execution, favorable Israeli technology/global-capital regimes, selected storytelling, and several famous company events—without evidence of repeatable Eisenberg-specific selection alpha or superior net fund returns.
- The denominator is missing. [researcher inference | strong] Processing 123 discovered association rows is not the same as observing the complete portfolio. Only 11 rows meet even the partial security/governance standard; passes, historical removals, costs, write-offs, distributions, fees, and carry remain incomplete. reconciliation
- Economic contribution is not computable. [researcher inference | strong] Windward, Shopping.com, Wix, Melio, Lemonade, and Tradeum are verification priorities, not a cash-return ranking. An acquisition value, IPO stake, current price, or direct personal sale cannot substitute for vehicle cash flows. economic view
- Institutional access can mimic sourcing skill. [researcher inference | strong] Israel Seed's US LP/co-investor graph, Benchmark's global brand and partners, and Aleph's accumulated CRM can produce warm deal flow that a new manager cannot reproduce. The record has no source-channel outcome cohort. Globes, Israel Seed model Max Raskin, “Herzlean Task”
- Team and founder misattribution is pervasive. [documented behavior | strong] Israel Seed and Benchmark holdings show shared control; Shochat cofounded Aleph; founders built the companies; Dunlevie held WeWork's official Benchmark board seat; Schreiber made Lemonade's licensing decision. people map WeWork proxy
- Public rationales are selected and often retrospective. [researcher inference | strong] Healthy.io is a rare same-day thesis; the strongest accounts of PictureVision, Print Life, WeWork lessons, and Aleph formation arrive years later. A coherent story after the outcome is not the original process. Healthy.io Human Founder
- The adverse record reaches core doctrine. [researcher inference | strong] Israel Seed IV challenges vehicle/pacing skill; Print Life and MemLink challenge financing gates; Tradeum challenges realization; WeWork challenges founder and governance judgment; Frank challenges mission, metrics, compliance, and control. adverse map
- Doctrine may be stronger than implementation. [researcher inference | strong] Equal partnership, board questions, values, relationships, backcasting, and patience are well articulated, but no public memo/board population shows that they preceded ordinary decisions, surfaced dissent, or changed outcomes. Frank is almost absent from the spoken philosophy. talks adverse audit
- Era and geography supplied real tailwinds. [researcher inference | strong] Yozma-era privatization, Israeli technical and military networks, US capital/management, internet/mobile/cloud distribution, and later global growth capital created opportunity no individual caused alone. OECD, Yozma
- National and moral visibility can blur fiduciary evaluation. [researcher inference | moderate] Writing on Israel, religion, prosperity, war, and humanity creates a distinctive public identity but does not prove company economics; civic spillovers and LP return must be separately measured. Covenantal Capitalism, full PDF 18Forty Civic
The favorable response is narrower. The direct record repeatedly shows a person who studies primary material, builds long networks, makes company-specific distinctions, credits partners and founders more carefully over time, and publicly confronts financing, governance, ownership, and realization risks. Healthy.io offers real ex-ante evidence; filings establish selected ownership and board roles; ordinary and failed cases extend beyond one visible winner. [researcher inference | provisional] That supports studying a serious operating doctrine, not claiming audited personal alpha.
Evidence that would decide the dispute
The favorable thesis should win only if the following independent records connect Eisenberg-specific work to repeatable ordinary and ex-outlier outcomes:
- a complete opportunity, pass, investment, follow-on, write-off, and exit denominator by legal vehicle;
- security-level cash flows, ownership, dilution, sales, distributions, fees, carry, and matched vintage benchmarks;
- contemporaneous sourcing logs, relationship conflicts, memos, rejected evidence, IC votes, dissent, and re-entry conditions;
- role-resolved founder, partner, co-investor, and executive testimony on sourcing, diligence, recruiting, board work, and stop/exit influence;
- board materials showing backcasting, bad-news escalation, regulatory remediation, metric verification, and abandonment gates before—not after—adverse outcomes;
- ex-Windward, ex-Shopping.com, ex-Wix, ex-Melio, and ex-Lemonade sensitivity rather than a famous-company sample; and
- a prospectively scored forecast ledger for cycle, AI, wartime, and national-capacity claims.
Until those records exist, “coherent, evolving Israel–global venture operating system with several important documented roles” is better supported than “demonstrated repeatable individual greatness.” [researcher inference | strong]
17. Analyst study guide, glossary, and go deeper
Recommended learning path
- Start with the verified biography to anchor institutions, dates, people, adverse events, and attribution boundaries before reading doctrine.
- Read the writings coverage, then the cross-source synthesis. Do not treat the nine limited writings as if their blocked or partial bodies were analyzed.
- Use the talks source guide to hear changes across 2012–2026; then read the adverse audit before accepting retrospective stories.
- Read the three separate Pareto views and the denominator before any famous deal.
- Run at least one positive, one ordinary, and two adverse decision labs without looking below each worksheet.
- Return to this operating system, then use the exact 17-model field guide for provenance, procedures, examples, exceptions, and dated transfer tests.
- End with the uncertainty ledger and the skeptical thesis above; write which missing record would most change your view.
Required no-hindsight exercises
- Positive/company-building: Windward tests domain data, customer transitions, ownership, and a completed corporate lifecycle.
- Ordinary/public: Freightos tests workflow value before network effects and prevents a fame-only sample.
- Fund failure: Israel Seed IV / no Fund V forces a December 2001 pacing, reserve, and realization decision before later marks.
- Capital-intensive failure: Print Life forces owned capacity versus outsourcing, milestones, and shutdown.
- Reversal pair: MemLink and Foxcom test whether the same distress label leads to opposite rational decisions.
- Realization failure: Tradeum separates company selection from stock-consideration disposition.
- Governance and integrity: WeWork and Frank require structural, related-party, metric, compliance, and board controls before later outcomes.
- Recoverable miss: GuruNet asks for a pass memo with a falsifiable re-entry condition.
Glossary
| Term | Meaning in this package |
|---|---|
| Aleph | The 2013 Israel-focused venture firm cofounded by Eisenberg and Eden Shochat; later partners and legal vehicles must be dated rather than collapsed. |
| Aleph-Aleph | A separate Cayman LP disclosed in a 2013 Form D; it is not a synonym for the flagship and its allocation relationship is unknown. Form D, Items 1–3 and 13 |
| BCPI | Benchmark Capital Partners Israel entities that appear in securities filings; entity voting power is not Eisenberg's personal ownership. |
| Israel Seed IV | The much larger 2000-vintage Israel Seed fund and the central adverse vehicle case; interim negative marks are not final audited performance. |
| Backcasting | Start with a desired future and work backward through necessary dominoes, blockers, owners, timing, and evidence. |
| Long humanity | Eisenberg's thesis that business economics can align with durable human needs and agency; treated here as a hypothesis requiring outcome and governance measures. |
| Creakonomics | His 2012 label for an economy shifting from a few large employers toward many smaller innovation firms; it is a macro model, not a deal score. TCTV, 04:04–07:42 |
| Indigestion | Excess capital that weakens focus, incentives, or survival rather than funding a customer-required asset or milestone. |
| Ownership optimization | Treat initial ownership and its fund-level consequence separately from headline price; never assume price is irrelevant. |
| Stagehand | Eisenberg's founder-first metaphor for the investor role; this package pairs it with explicit board duties under stress. |
| Complement system | The talent, management, data, infrastructure, law, regulation, energy, compute, distribution, capital, and institutions needed for a company to work. |
| Decision freeze | The dated evidence packet shown before an outcome in each lab; it blocks hindsight leakage. |
| Realization | The security-to-cash path through sale, distribution, listing, lockup, taxes, fees, and carry; distinct from a company event. |
Reusable sourcing checklist
These are analyst-created controls distilled from the relationship doctrine and its GuruNet/WeWork countertests, not a reported Aleph form. [researcher inference | strong] sourcing evidence GuruNet lab WeWork lab
- Record the originating person, channel, date, sponsor, and every independent referrer.
- State what each relationship contributes beyond warmth; disclose reciprocity, conflicts, and social/institutional overlap.
- Separate access quality from company quality and blind-score product/market evidence before revealing relationship strength.
- Add at least one reference outside the founder's and sponsor's graph and one rejected or adverse reference.
- Name the secular change, current consensus, differentiated claim, and why the opportunity is scarce rather than merely obscure.
- Preserve cold and underrepresented channels; audit whether the CRM reproduces homogeneity or excludes founders outside the network.
- For a pass, record the decisive uncertainty and an observable re-entry condition; review false negatives on a fixed cadence.
- Track conversion and outcome by source channel only after stage, price, ownership, vintage, partner, and selection are controlled.
Reusable diligence checklist
These are analyst-created controls joining the picking doctrine to the Frank, Healthy.io, and WeWork evidence; Eisenberg is not claimed to have used this exact checklist. [researcher inference | strong] picking evidence Frank lab Healthy.io lab
- Write the backcast: desired future, dominoes, blocker, owner, deadline, dependency correlation, and external gate.
- Test founder learning with a changed-belief example; verify character, integrity, recruiting, and complementary-team evidence independently.
- Read primary technical, customer, financial, regulatory, contractual, and security records before expert calls; recruit a disconfirming expert.
- Define the market as customer behavior and purchasing authority, not a top-down category; separate secular change from category heat.
- Reproduce customer, user, revenue, retention, loss, aid, safety, or impact metrics from raw or independently controlled records.
- Model venture scale at the security level: check, ownership, dilution, follow-ons, exit range, duration, and fund contribution.
- Identify capital intensity, fixed obligations, customer duration, next financing dependency, syndicate capacity, and downside runway.
- Map local and global complements: talent, management, sales, regulation, data rights, infrastructure, compute/energy, and later capital.
- For AI, test provider substitution, data/derived rights, evaluation loops, copy time, platform bundling, gross-margin repricing, and human appeal.
- For regulated or vulnerable-user products, inspect complaints, claims, disclosures, regulator correspondence, audit trails, privacy, and remediation.
- State the strongest alternative explanation and what evidence would reverse the relationship, founder, market, or mission prior.
Reusable IC checklist
This four-ledger, no-hindsight IC form is a researcher synthesis of the vehicle, ownership, attribution, and decision-lab record, not a recovered historical template. [researcher inference | strong] vehicle analysis decision labs
- Split the memo into dated facts, management claims, investor-stated thesis, and researcher inference.
- Name source, sponsor, diligence owner, terms lead, intended director, dissent, and the person with final authority; write unknown where necessary.
- Make the invest/pass/continue/stop choice before reading or discussing the later outcome.
- Specify what kills the deal across product, market, integrity, regulation, financing, governance, and realization.
- Tie the check and tranche to one next milestone; name the next decision date and cumulative reserve ceiling.
- Build ownership/price/security/downside tables; do not label the company an outlier in the base case.
- Ask why the company can use the capital and how excess funding changes founder, employee, co-investor, and board incentives.
- Underwrite co-investors, board independence, information rights, reserved matters, regulatory controls, and downturn behavior.
- Keep company economics, vehicle economics, ecosystem spillover, civic objective, and personal exposure in separate ledgers.
- Precommit the realization framework: listing, acquisition cash/stock, lockup, distribution, concentration, fund life, and information advantage.
- End with the next evidence request, the re-entry condition if passing, and the falsifier for the entire edge thesis.
Reusable governance checklist
These controls translate Eisenberg's stated board practice through the adverse WeWork, Frank, and Print Life record; they are recommendations, not evidence that every historical board used them. [researcher inference | strong] team and board evidence failure controls
- Require a decision-useful pre-read with raw KPI definitions, reconciliations, misses, risks, cash, hiring, compliance, and asks.
- Use one to three priority questions only after ensuring the information system is complete; brevity is not a control.
- Maintain independent access to auditors, regulators, counsel, key customers, whistleblower routes, and original metric records.
- Review related parties, founder transactions, secondary liquidity, fees, conflicts, and unusual contracts through independent directors.
- Stress cash runway, fixed obligations, customer duration, covenants, refinancing, sanctions, and downside capital availability.
- Put product claims, consumer harm, safety, privacy, data rights, model evaluations, and regulator remediation on the board calendar.
- Define founder/board reserved matters, escalation thresholds, succession, executive recruiting, and conditions for leadership change.
- Re-underwrite every follow-on prospectively; compare the milestone bought with stop, sale, recap, outsourcing, and shutdown alternatives.
- Protect employees and customers in a shutdown plan: severance, continuity, data disposition, creditor priority, and founder time.
- Treat an exit proposal as a new investment decision with security, lockup, representations, escrow, indemnity, distribution, and concentration analysis.
- After an adverse event, preserve the original memo and write a dated process change; do not rewrite the original thesis.
Go deeper — ranked source path
- Primary decision document: Bad Blood, Good Urine, Great People!, paragraphs 1–23 — the best ex-ante record of founder, learning, category, regulation, secular change, and explicit outcome uncertainty.
- Primary philosophy transcript: EconTalk, full transcript — people, backcasting, human response, Israel constraints, and long humanity with meaningful host pushback.
- Primary mechanics interview: 20VC AI, synchronized captions — AI filters, crowding, ownership, liquidity, boards, sourcing, and live attribution correction.
- Primary failure/team interview: The Human Founder, official episode — Print Life, capital intensity, founder relationships, team formation, shutdown, and empathy.
- Primary institutional/cycle interview: 20VC with Gurley, official episode — usable capital, price/ownership, partnership, boards, and cycle memory; keep Gurley's views separate.
- Primary issuer controls: Shopping.com S-1/A, Lemonade S-1/A, and Windward admission document — ownership, boards, risks, and company facts that discipline retrospective narration.
- Best adverse contemporary series: Globes, January 2003, Globes, July 2004, and Globes, Fund V abandonment — stressed companies, survivor reversals, realization ambiguity, and franchise discontinuity.
- Best system controls: OECD Israel country note and Bank of Israel financing analysis — Yozma, funding cycles, staging, and power-law context without converting ecosystem evidence into personal performance.
Final use rule
Use Eisenberg's system as a sequence of questions, never as a personality template: build the relationship, then challenge it; imagine the future, then map and kill its dependencies; buy ownership, then price the ordinary case; support founders, then govern independently; be patient, then enforce milestones; pursue human and national value, then keep customer, company, vehicle, and civic economics separate. [researcher inference | strong]
Pareto 80/20 — what drove the record
The public record does not support a literal 80/20 split, a career hit rate, or a ranking by net return. It contains company transaction values, public holdings, one reported Benchmark disposition, and dated interim fund marks, but not the complete costs, dilution, cash realizations, allocations, fees, carry, or fund cash flows needed to measure contribution. The three rankings below therefore answer three different questions and must not be merged. [researcher inference | strong]
Economic contribution — directional verification priority
This is a ranking of cases most likely to matter economically given the strength of the observable company/security evidence, not a return ranking. “Reported economics” means the stated number comes from the linked source and is not audited here. [researcher inference | strong]
| Rank | Case | Basis or measure | Proper attribution | Confidence | Supported mechanism | Denominator caveat | Case |
|---|---|---|---|---|---|---|---|
| 1 | Windward | Aleph entities' substantial pre-listing holdings, disclosed take-private undertakings, 215p cash offer, and completed 2025 acquisition | Aleph, L.P. and Aleph-Aleph, L.P.; team decision; no sole Eisenberg economics | [documented behavior | strong] | Domain data and maritime workflows reached government and commercial buyers, public liquidity, then cash acquisition | Full cost, earlier sales, allocation, distributions, fees, and carry absent | Case 1 |
| 2 | DealTime / Shopping.com | Israel Seed II/IV held 1,932,158 ordinary equivalents before the IPO; eBay completed a reported ~$685.3m acquisition | Israel Seed II and IV; shared Cohen/Medved/Eisenberg control; Eisenberg board role | [documented behavior | strong] | Structured product data, merchant referrals, management recruitment, and Epinions combination | Entry cost and fund cash-flow ledger absent; company purchase price is not fund proceeds | Case 2 |
| 3 | Wix | Benchmark Capital Partners VI held 4,012,329 shares pre-IPO; one press report later estimated an ~$80m full disposition | Benchmark vehicle and partnership; Eisenberg board member but explicitly not beneficial owner of the block | [documented behavior | moderate] | Product-led self-service web publishing and freemium distribution | Report is single-source; initial entry, all sales, fees, carry, and net distributions absent | Case 3 |
| 4 | Melio | Xero completed a $2.5bn upfront acquisition plus up to $500m employee-linked consideration | Melio founders/company; Aleph association; Eisenberg article metadata only | [contemporaneous record | provisional] | SMB accounts-payable and payment workflow | Primary Aleph ownership, cost, allocation, board role, and sale proceeds absent | Case 8 |
| 5 | Lemonade | Aleph entities held 4,539,063 shares at the IPO filing; company scaled materially but remained loss-making in 2025 | Aleph and Aleph-Aleph; Eisenberg held filing power and board roles; company execution belongs to founders/team | [documented behavior | moderate] | Full-stack insurance, automation, data, and incentive redesign | Ongoing holding/company; IPO value and direct personal Form 4 sales are not Aleph DPI | Case 4 |
| 6 | Tradeum | Announced all-stock sale was reported at $474m, followed by a >99% acquirer-price collapse | Israel Seed partnership; exact selling/distribution decisions unknown | [contemporaneous record | provisional] | B2B exchange software plus stock consideration at bubble prices | Sources conflict between “extraordinary return” and value evaporation; cash realized unknown | Case 14 |
Dominant-outlier test. No cash-flow dataset identifies a dominant economic outlier, so a genuine “record excluding the top winner” calculation is not possible. If one improperly ranked only by announced company transaction value, Melio's $2.5bn headline would dominate; removing it leaves Windward, Shopping.com, and Wix as documentable liquidity cases, but still does not yield fund contribution. If one instead ranks by completeness of vehicle-to-exit evidence, Windward ranks first; removing Windward leaves Shopping.com and Wix, again without comparable net cash flows. The result is robust only in the negative sense: economic concentration and contribution remain not computable with or without either proxy outlier. [researcher inference | strong] Xero acquisition announcement, transaction terms Windward recommended acquisition, offer and undertakings Shopping.com acquisition note
Historical importance — institution and strategy inflections
| Rank | Case | Basis | Proper attribution | Confidence | Why it changed the record | Denominator caveat | Case |
|---|---|---|---|---|---|---|---|
| 1 | PictureVision | Eisenberg's claimed first deal and bridge from merchant banking into technology investing; Kodak later acquired the company in two steps | Ambiguous personal/fee/merchant-bank arrangement; Kalish and other actors unresolved | [retrospective witness | moderate] | Establishes the analog-to-digital boundary-crossing origin story | Investor documents and economics absent | Case 9 |
| 2 | DealTime / Shopping.com | Best documented Israel Seed board and security case | Israel Seed team; Eisenberg director and small disclosed personal-benefit component | [documented behavior | strong] | Connects early Israeli seed investing to US management, public markets, and strategic sale | One selected survivor from an incomplete fund denominator | Case 2 |
| 3 | Israel Seed IV / no Fund V | Dated negative interim performance and abandonment of a successor fund | Fund/vintage/team, not Eisenberg personal result | [contemporaneous record | moderate] | Tests whether the early model survived the 2000 vintage and preserves the franchise discontinuity | Interim—not final—marks; team and vintage confounded | Case 10 |
| 4 | Wix | Filing-supported Benchmark position and Eisenberg board service | Benchmark Capital Partners VI and global/local team | [documented behavior | strong] | Illustrates the Benchmark-era shift from startup quantity to scaled Israeli internet company | Original memo and complete fund proceeds absent | Case 3 |
| 5 | Windward | First announced Aleph investment and a completed public-to-private path | Aleph founding team and vehicles | [contemporaneous record | strong] | Makes the 2013 applied-data/domain thesis testable over a full corporate lifecycle | Company lifecycle is not fund return | Case 1 |
| 6 | Lemonade | Aleph's first IPO and most visible long-humanity/applied-AI case | Aleph team, Eisenberg governance role, Schreiber/Wininger execution | [documented behavior | strong] | Connects relationships, mission, regulation, ownership, and public-market patience | Still operating and loss-making; no completed fund realization | Case 4 |
Decision-learning value — where a modern IC should spend time
| Rank | Case | Basis | Proper attribution | Confidence | Decision mechanism to test | Denominator caveat | Case |
|---|---|---|---|---|---|---|---|
| 1 | WeWork | Contemporaneous bull and bear cases plus later governance and bankruptcy evidence | Eisenberg sourced/championed; Dunlevie held Benchmark board seat; management/SoftBank/board distinct | [researcher inference | strong] | Separate real demand from duration mismatch, capital dependence, related parties, and founder control | Benchmark lifetime cash result unknown | Case 15 |
| 2 | Frank | Mission-led product, public FTC warning, adjudicated founder fraud, and unresolved holder litigation | Aleph investment; Javice/Amar criminal findings; no Aleph knowledge finding | [researcher inference | strong] | Validate metrics, regulatory claims, remediation, and M&A data provenance | Aleph board/diligence/economics absent; civil claim unresolved | Case 16 |
| 3 | Israel Seed IV | Negative interim marks beside same-vintage peer losses and failure to raise Fund V | Team/vintage/vehicle | [researcher inference | strong] | Reserve pacing, new-deal pace, public-stock liquidity, and franchise feedback | No final audited performance | Case 10 |
| 4 | Print Life | Eisenberg's candid account of a fixed-cost commitment and slow pivot | Board and management jointly; exact entity/vehicle unresolved | [retrospective witness | moderate] | Capital-source durability, outsourcing, utilization gates, and human cost | Company identity and loss amount unconfirmed | Case 11 |
| 5 | MemLink | Deep-tech milestone gap and bridge round that failed to unlock the next financing | Israel Seed and syndicate; no sole person credit | [contemporaneous record | moderate] | Size a round to a customer-validating milestone, not simply to time | Residual cash and recovery conflict unresolved | Case 12 |
| 6 | Tradeum | Company-selection and realization decisions can be scored separately | Israel Seed team | [researcher inference | strong] | Underwrite stock consideration, lockups, distribution, and acquirer risk | Cash realized unknown | Case 14 |
| 7 | Freightos | Long software-to-marketplace sequence with public ordinary outcome | Aleph/MoreVC team; Eisenberg director | [researcher inference | strong] | Require standalone workflow value before network effects and separate GBV from revenue | Public liquidity without profitability or DPI | Case 6 |
| 8 | Foxcom / MobileAccess | Near-death company later recovered and was acquired | Israel Seed team | [researcher inference | strong] | Compare rescue evidence with MemLink to avoid “always stop” hindsight | Rescue actions, purchase allocation, and proceeds absent | Case 13 |
Evidence boundary and searched denominator
Units, institutions, aliases, and inclusion rules
The scope is institution-association, not “Michael Eisenberg's personal portfolio.” It covers Israel Seed Partners from its 1995 formation through the active-portfolio transition after 2005; Benchmark Israel I/II and later Benchmark main-fund Israel activity through Eisenberg's 2012/2013 departure; and Aleph from its 2013 launch through the 2026-08-22 research cutoff. The legal entities and vintages are not interchangeable. [researcher inference | strong]
The search used contemporary Globes portfolio and fund reports; SEC/issuer ownership, governance, IPO, proxy, and transaction filings; CalPERS-derived reporting; the visible IVC Benchmark Israel II snapshot; Aleph's current 64-card company page; Aleph/Medium first-party writings; official company announcements; regulator and court records; and the processed writing/talk corpus. Search variants included Michael A. Eisenberg, Mike Eisenberg, מייקל אייזנברג, Israel Seed/Israel Ventures/Seed Management Associates, Benchmark Israel/BCPI, Aleph/Aleph-Aleph/Aleph Equity Partners, and company aliases below. [documented behavior | strong] source map, scope and verification
Inclusion rule: count a company once per institution when a dated public route associates it with that institution. Count the same corporate path twice across institutions because it represents separate vehicle exposure; collapse renames, bolt-ons, and outcome securities within an institution. Include adverse, ceased, ordinary, public, private, and acquired names. Exclude an event, host-introduced name, or global-fund deal if no scoped association is established. A financing total is not an investor check; an acquisition value is not proceeds; voting power is not personal ownership. [researcher inference | strong]
Reconciliation
| Required count | Israel Seed | Benchmark Israel / era | Aleph | Combined | Definition and boundary |
|---|---|---|---|---|---|
| Publicly claimed/known | 18 companies in Funds I–II by June 1999; no I–IV total | Fund I planned 15–18; visible IVC Fund II snapshot resolves to 23 unique paths; complete cross-vehicle total unknown | Current official page lists 64; older bio said >40 | Not additive | Claims concern different dates and scopes. Israel Seed 1999 report Benchmark IVC card Aleph companies |
| Searched associations | 27 | 32 | 64 | 123 | Every discovered scoped association was checked against at least one mapped route. |
| Researched associations | 27 | 32 | 64 | 123 | Every row below has a dated association/status source. |
| Security/governance sufficiently reconstructed | 4 | 4 | 3 | 11 | Shopping.com, Finjan, Commtouch, UltraShape; Finjan, Conduit, Wix, Vringo; Lemonade, Freightos, Windward. “Sufficient” is partial and excludes full cash economics. |
| Unresolved on that standard | 23 | 28 | 61 | 112 | Missing legal holder, security, governance, or dated event needed for the partial reconstruction standard. |
| Excluded/collapsed leads | 2 | 4 | 7 | 13 | Aliases, bolt-ons, global/host-only names, or outcome securities; not additional company entries. |
Cross-institution deduplication collapses the second Finjan and WeWork associations, producing 121 unique corporate paths from 123 association rows. Fourteen of the 123 association rows are represented in no-hindsight company labs at explicitly different evidence depths. PictureVision and Print Life are two additional company-like labs outside the ledger because investing-entity or corporate-identity evidence is incomplete; Israel Seed IV is a fund-vintage lab rather than a company. Those 14 in-ledger cases + 2 outside-ledger company-like cases + 1 fund-vintage case = 17 total cases. The 11-row security/governance count differs deliberately from the 14-row in-ledger case count: a failure may have rich contemporaneous financing evidence without a public cap table, while a public holding may have security evidence but no recoverable ex-ante thesis. [researcher inference | strong]
- Observed-source processing fraction: 123 researched association rows / 123 discovered association rows. This measures processing of the discovered union only.
- Partial security/governance reconstruction fraction: 11 / 123 association rows.
- Coverage fraction of the actual career or fund portfolios: not computable. The missing denominator is the complete historical company, write-off, follow-on, allocation, and disposition list for every vehicle. The true number of unobserved deals is unknown.
- Selection/survivorship warning: Israel Seed contemporary reporting overrepresents stressed companies and selected exits; IVC mixes current, ceased, and post-departure events; Aleph's current marketing page may omit removals and contains at least one date defect. None is a clean outcome census. [researcher inference | strong] Freightos 20-F, listing date control
Alias and exclusion map
| Lead | Treatment | Reason |
|---|---|---|
| Shopping.com | DealTime continuation | Rename, not a new Israel Seed entry. |
| ePinions | Inside DealTime/Shopping.com path | DealTime acquired it; no separate Israel Seed investment established. |
| Answers.com | GuruNet continuation | Rename. |
| Perion | Conduit/ClientConnect outcome security | Benchmark Israel II received shares through the transaction; no separate entry shown. |
| Wibya | Conduit bolt-on | Acquisition, not a distinct scoped Benchmark entry. |
| Lango | Zlango continuation | Relaunch/rename. |
| FTX Games | Funtactix asset path | Later asset disposition, not a new entry. |
| AutoLeadStar | Fullpath former name | Official company record. |
| JoyTunes | Simply former name | Official company record. |
| Yevvo / Meerkat | Houseparty predecessor lead | Legal/cap-table path unresolved; not separately counted. |
| CommonSense Robotics | Probable Fabric predecessor | Not asserted until registry/cap-table support is recovered. |
| Anodot | Probable Umbrella path | Page-copy clue only; legal equivalence unresolved. |
| Uber | Excluded | Host/collective phrasing did not establish an Eisenberg or Israel-vehicle association. |
Historical market, regulatory, and base-rate context
What a contemporary IC could have known
| Decision era | Available context | Proper use |
|---|---|---|
| 1995–1999 | Israel's new institutional venture market had recently been catalyzed by Yozma; Internet distribution and US capital/management connections were becoming investable, while local seed histories were short. The OECD later documented Yozma's 1993 $100m commitment, ten roughly $20m funds, 40% government stakes with buyout rights, and near-complete privatization by 2000. [contemporaneous record | strong] | Use Yozma to explain institutional opportunity, not to credit Eisenberg or forecast returns. OECD, “original Yozma” |
| 2000–2002 | Israel Seed IV was raised at the technology/telecom peak. By 2001 public comparables, B2B exchanges, and optical-network financing were collapsing; by 2002 Israel Seed temporarily stopped new seed activity while triaging companies. [contemporaneous record | strong] | A diligent board could see financing and public-stock risk before final outcomes; company-specific survival still varied. Israel Seed 2003 interview |
| 2003–2005 | IPO and M&A routes reopened selectively. In 2005, 99 Israeli startups raised a reported $890m versus 107/$855m in 2004, with communications still 38% of capital; some managers raised successors while Israel Seed abandoned Fund V. [contemporaneous record | moderate] | Separate market recovery from manager/franchise selection. Globes 2006 market review |
| 2005–2013 | Benchmark's dedicated local funds had access to a larger institutional platform, but 2010 reporting said the local structure had not produced sufficiently strong exits and no third dedicated fund would be raised; Israel investing could continue from the main pool. [contemporaneous record | moderate] | Treat platform, fund, and partner as separate units; do not force later investments into Israel II. Calcalist 2010 wind-down |
| 2013–2021 | Aleph launched into a maturing Israeli scale-up market with a small equal-partnership claim, global customers/capital, and increasing late-stage capital. Regulation was central in insurance, medical diagnostics, finance, freight, and maritime intelligence. [contemporaneous record | moderate] | Require sector-specific licensing, reimbursement, compliance, capital, and board controls; “software” does not remove regulated balance sheets. Aleph launch |
| 2021–2026 | Zero-rate capital, then tighter financing, war, AI acceleration, and public-market repricing changed the cost and availability of follow-on capital. Eisenberg's public doctrine became more explicit about usable capital, ownership, governance, and earlier liquidity. [investor-stated | moderate] | These later views cannot be back-projected into earlier memos without dated evidence. 20VC, capital/ownership/boards 20VC AI, liquidity and ownership |
Retrospective controls—not ex-ante facts
At year-end 2005, reported CalPERS marks for Israel Seed IV (-15.8%) were directionally similar to other 2000/2001-vintage Israeli vehicles: Gemini III -14.7%, JVP IV -13.5%, and Pitango III -18.25%. That makes vintage shock a serious alternative explanation, while the failed Fund V raise remains firm-specific adverse evidence. These were interim marks, not final returns. [contemporaneous record | moderate] Globes, CalPERS snapshot and peers
The Bank of Israel later described early-stage finance as unusually exposed to global funding cycles and explained staged capital/non-standard contracts as responses to uncertainty and asymmetric information. The OECD later reported seed investment of 0.02% of GDP for 2007–2021 with a database caveat, relayed an Israel Innovation Authority estimate of 13% average net IRR over a prior 10–15-year period, and relayed an estimate that 20% of domestic funds generated 80% of profits. These are retrospective system/base-rate controls only; they do not establish Eisenberg's performance or license a literal 80/20 claim here. [contemporaneous record | moderate] Bank of Israel, financing characteristics OECD, Israel country note
Vehicle economics and incentives
| Vehicle / entity | Capital, legal form, and duration evidence | Decision rights, incentives, and governance | Behavior it may have shaped | What remains unknown |
|---|---|---|---|---|
| Israel Seed I / initial pool | Began 1995 with $2m and closed/expanded at $7m; exact legal form not recovered. [contemporaneous record | moderate] | Medved and Cohen began the operation; Eisenberg joined in 1997. | A very small pool plausibly favored seed-stage formation and syndication. [researcher inference | moderate] | Partnership agreement, LPs, duration, fees, carry, reserves, allocations. |
| Israel Seed II | Reported $11m; legal name/jurisdiction unavailable. [contemporaneous record | moderate] | Team boundary only. | Same early-stage pressure; company allocation unavailable. | Complete portfolio and economics. |
| Israel Seed LP III | Closed in 1999 at $40m; Funds I–III totaled $58m. [contemporaneous record | strong] | Medved, Cohen, Eisenberg named; typical seed/first rounds reported at $1m–$2m. | Larger pool still emphasized seed, with greater follow-on/syndicate capacity. [researcher inference | moderate] | GP chain, votes, carry, final cash flows. Fund III report |
| Israel Seed IV, L.P. | Cayman LP, 2000 vintage, reported $226m managed and $160m called by YE2005; Israel Ventures Partners 2000 Ltd GP. [contemporaneous record | strong] | Neil Cohen later documented as GP controller/managing member; Eisenberg/Medved/Cohen were members. | Large step-up at a peak vintage plausibly increased follow-on, board-load, and deployment pressure; this is causal inference, not a documented policy. [researcher inference | moderate] | Final DPI/TVPI/IRR, term, carry, recycling, reserves, partner allocation. TASE disclosure Finjan S-1/A footnotes |
| Proposed Israel Seed V | Abandoned in 2005; no completed vehicle. [contemporaneous record | strong] | Cohen/Chinn/Widman continued active holdings after Medved/Eisenberg left. | Fundraising feedback ended new-vintage continuity but not legacy governance. | LP process and formal cause. Globes, Fund V abandonment |
| First Benchmark Israel fund | Contemporary close $220m in 2001; later $260m claim unresolved. BCPI I/Founders/Partners/Corporation entities appear in later filings. | Initial equal partners Kremer/Naveh/Shelef; a 2001 article reported 30% firm carry, not a governing agreement. Eisenberg joined in 2005. | Institutional scale and equal-partner rhetoric may reduce internal bargaining, but Eisenberg cannot receive entry credit for pre-2005 deals. [researcher inference | strong] | Exact legal equivalence, carry allocations, final performance. Globes 2001 fund structure |
| Benchmark Israel II, L.P. | Delaware LP, 2005 vintage, reported $250m close. [contemporaneous record | strong] | BCPI Partners II → BCPI Corporation II; filings name Eisenberg/Naveh with shared securities power, and one Vringo record also Wurtman. | Larger initial ownership and board governance were possible; shared power does not identify sourcing, IC vote, or carry. | Full portfolio, reserves, final DPI/TVPI, allocation, main-fund boundary. Perion ownership chain |
| Benchmark main-fund Israel activity | Retrospective 2009–2012/13 transition; exact vehicle(s) unavailable. | Eisenberg says he continued investing from the main pool with support from Dunlevie, Gurley, Fenton, Kagle, Harvey, and Lasky. | Removed a dedicated local-fund raise while retaining access to a larger pool; geographic authority and incentives are unproven. [retrospective witness | moderate] | Closing records, authority, allocation, economics. Human Founder, Aleph formation discussion |
| Aleph first flagship | TechCrunch reported $120m before launch; Shochat's official announcement said $140m. Aleph, L.P. appears in company filings. |
Eisenberg and Shochat cofounders; Dunlevie special partner; Shochat described an equal partnership in which the engaged partner could say yes and board. | Small-team/equal-economics rhetoric plausibly improves candor and founder responsiveness; legal votes/carry are not public. [researcher inference | moderate] | Final close reconciliation, LPs, fees/carry, reserves, key-person terms. Official launch |
| Aleph-Aleph, L.P. | Cayman parallel/side issuer: 2013 Form D offered $14m, sold $11.125m to 27 investors. [contemporaneous record | strong] | Eisenberg/Shochat related persons through GP-of-GP. | Parallel allocation may serve distinct LPs; purpose and economics unproven. | Allocation agreement and relation to flagship. Form D, Items 1–3, 7, 13 |
| Aleph GP chain | Aleph Equity Partners, L.P. is GP of Aleph and Aleph-Aleph; Aleph EP, Ltd. is GP of the GP. | Lemonade filing gives Eisenberg filing power; this is not personal ownership. | Centralized legal control can coexist with equal internal economics; agreement unavailable. | Votes, carry, succession, conflicts, co-invest. Lemonade proxy ownership footnote |
| Aleph III | Official 2019 announcement: $200m closed. [contemporaneous record | moderate] | Signed jointly by Rosenson, Shochat, Eisenberg, and Elad. | Team-signatory evidence defeats sole-Eisenberg fund attribution. | Form D/legal entity, close receipts, allocation/performance. Aleph III announcement |
| Aleph IV, L.P. | Cayman LP; 2021 Form D offered $300m, $0 sold and first sale not yet occurred on filing date. [contemporaneous record | strong] | Eisenberg, Shochat, Rosenson, Diari named directors of GP-of-GP. | Offered size is not committed capital; no deployment claim follows. | Final close, mandate, fees/carry, Elad role, portfolio allocation. Form D, Items 1–3, 7, 13 |
| Aleph V / current firm | 2026 announcement metadata only; current About page says $850m AUM and partners Eisenberg/Shochat/Elad/Diari. [contemporaneous record | provisional] | Exact legal vehicle and current succession not established. | No behavioral/economic inference is supportable from metadata/AUM marketing. | Exact day, size, close, team, mandate, cash. Aleph V route current About |
Modern-fund comparison (as of 2026-08-22). These vehicles share the broad LP-backed, closed-pool features of a contemporary venture fund where the legal records identify limited partnerships, but public evidence is insufficient on fund term, recycling, management fee, carry allocation, key-person clauses, reserve budget, co-invest rights, or continuation structures. Aleph's stated practice of buying meaningful ownership early and rarely relying on pro rata is a dated direct-voice operating claim, not a disclosed LPA rule. [investor-stated | moderate] 20VC AI, 42:35–44:44
People, capital, and influence map
LP / institutional capital
├── Israel Seed I–IV
│   └── Medved + Cohen + Eisenberg (+ Feld; later Chinn/Widman)
│       └── seed formation, boards, syndicates, follow-ons, exits and triage
├── Benchmark Israel I / II and Benchmark main funds
│   └── Kremer + Naveh + Shelef → Eisenberg + Naveh + Wurtman
│       └── global Benchmark partners and GP entities
│           └── board appointees, ownership, follow-ons and liquidity
└── Aleph / Aleph-Aleph / later Aleph vehicles
    └── Eisenberg + Shochat → Rosenson + Elad + Diari, by dated role
        ├── GP entities and fund capital
        ├── company founders and executives create operating value
        ├── co-investors supply capital, dissent and board participation
        └── regulators, customers, public markets and acquirers constrain outcomes
| Person / institution | Supported function | Boundary |
|---|---|---|
| Michael Eisenberg | Joined Israel Seed in 1997; GP/board work; joined Benchmark in 2005; BCPI director; Aleph cofounder/partner and GP-chain director; named company roles below | No blanket sole sourcing, IC control, beneficial ownership, carry, or personal return. |
| Jonathan Medved | Israel Seed founder/partner, spokesman, Fund IV GP member | No blanket equal economics or sole deal credit. |
| Neil Cohen | Israel Seed founder/managing partner; later Fund IV GP controller; legacy manager | Complete company votes and economics unknown. |
| Alan Feld; Daniel Chinn; Sigal Widman | Feld a later Israel Seed partner; Chinn/Widman legacy managers after 2005 | Entry credit and economics mostly unknown. |
| Arad Naveh; Mark Kremer; Nachman Shelef; Elie Wurtman | Benchmark Israel partners across vintages; Naveh/Wurtman appear in securities control records | Deal-level sourcing, votes, carry, and outcomes remain separate. |
| Bruce Dunlevie; Bill Gurley; Peter Fenton; Bob Kagle; Kevin Harvey; Mitch Lasky | Global Benchmark colleagues credited by Eisenberg; Dunlevie independently documented on WeWork board | Help, governance, and fund ownership cannot be redistributed to Eisenberg. |
| Eden Shochat | Aleph cofounder/equal founding partner, launch author, GP related person | Firm doctrine and deal outcomes are not solely Eisenberg's. |
| Aaron Rosenson; Yael Elad; Tomer Diari | Dated Aleph partner/signatory/GP-related roles | Current/historical allocations, votes, carry, and transitions unknown. |
| Kathryn Mayne / Horsley Bridge | Retrospectively credited with identifying a fund gap and Shochat as partner candidate | No legal fund authority established. |
| Founders/executives | Company formation and operating outcomes; Schreiber's Lemonade licensing and Ciporin's Shopping.com management are named examples | Investor board presence does not transfer founder credit. |
Function-level case responsibilities
Unknown means the public record is silent; it is not evidence that the function was absent.
| Case | Sourced / sponsored | Diligence / approval / terms | Board / recruiting / follow-on | Exit / stop influence | Later narration |
|---|---|---|---|---|---|
| PictureVision | Eisenberg says he originated a merchant-bank structure and invested a fee; Kalish/Montgomery roles unresolved | Unknown | Unknown | Kodak transactions documented; investor influence unknown | Eisenberg, with an explicit “history is complicated” qualification |
| Shopping.com | Israel Seed association; exact source unknown | Partner vote/entry terms unknown | Eisenberg director by 1998; reported Ciporin recruitment; Cohen/Medved shared later voting power; Gurley involved in Epinions transaction | No IPO sale by Israel Seed; eBay exit influence unknown | Eisenberg and Gurley retrospective board lesson |
| Wix | Benchmark sponsored; source unknown | 2010/2011 tranches filed; approval/negotiation unknown | Eisenberg board 2010–2015; Benchmark managing members—not Eisenberg—controlled fund shares | Benchmark disposition timing only secondarily reported | Eisenberg uses as scale/platform example |
| Seeking Alpha | Eisenberg calls it first Benchmark deal; 2006 announcement names board | Check/security/IC unknown | Eisenberg board; later follow-ons in IVC; company burn/model decisions private | No liquidity record | Eisenberg patience narrative |
| Windward | Aleph first announced financing; team credit | $5m round reported; partner vote/terms unknown | Aleph vehicles held shares; exact board work unknown | Aleph entities signed undertakings; exact individual influence unknown | Eisenberg and Aleph team use as applied-AI example |
| Lemonade | Long Eisenberg–Schreiber relationship; Aleph/Sequoia seed | Exact memo body inaccessible; filed securities/ownership later visible | Eisenberg board/lead independent director; Schreiber made NY licensing decision; follow-on allocations incomplete | Aleph did not sell at IPO; Eisenberg direct/personal Form 4 sales separate | Eisenberg and Shochat jointly recall firm thesis |
| Healthy.io | Eisenberg documents repeated learning/diligence; Aleph led | $18m round total; allocation/terms/IC unknown | Board role supported by biography; Aleph joined later rounds | No exit; layoff/governance decisions unknown | Eisenberg same-day thesis and later patience example |
| Freightos | Aleph/MoreVC co-led; Eisenberg quoted | $4.6m total round; allocation/terms unknown | Eisenberg director 2013–2025; Aleph in later rounds | Public listing; board resignation; sales unknown | Company and Eisenberg describe automation thesis |
| Melio | Aleph association; person sourcing unknown | Body/memo/check/terms unknown | Unknown | Xero transaction; Aleph sale allocation unknown | Eisenberg article metadata only |
| Print Life | Israel Seed-era attribution not independently fixed | Fixed-capacity board/management choice; exact vote/terms unknown | Eisenberg assigns board/management responsibility and mentions executive recruitment | Shutdown/layoffs; exact authority unknown | Eisenberg candid 2024 postmortem |
| MemLink | Israel Seed co-invested | Seed, 2000 round, and 2002 bridge totals public; votes/terms unknown | Syndicate funded bridge; several investors declined | Closure; cash/recovery unresolved | Contemporary reports; no Eisenberg-specific lesson |
| Tradeum | Israel Seed led first round | >$3m round and stock sale announced; allocation/lockup unknown | Unknown | Acquirer operations; Israel Seed stock-disposition plan unknown | Medved and later Globes accounts conflict on realization |
| WeWork | Eisenberg directly describes referral convergence and championing | Benchmark vehicle, vote, terms unknown | Dunlevie official Benchmark director; Eisenberg crisis participation only secondary reporting | Neumann removal and bankruptcy documented; exact Eisenberg influence unknown | Eisenberg's later governance/capital lesson |
| Frank | Aleph led seed and joined follow-ons; individual sponsor unknown | Metrics validation, board vote, terms unknown | Aleph role and FTC response unknown | JPMorgan acquisition/shutdown; seller litigation unresolved | Almost absent from Eisenberg spoken record |
| GuruNet | Israel Seed passed twice, then invested; Eisenberg narrates screen failure | Reported $2m third-round check; terms/approval unknown | Board/governance unknown | No IPO sale; later proceeds unknown | Eisenberg described capacity/interpersonal miss |
| Foxcom / MobileAccess | Israel Seed association | Rescue financing and thesis unknown | Near-closure intervention unknown | Corning acquired; investor influence/proceeds unknown | Contemporary team-level recovery account |
Comprehensive deal ledger — 123 association rows / 121 companies
Reading the ledger
Every discovered scoped association appears below, including ceased, weak, ordinary, continuing, public, and acquired companies. E0 means check/cost, full ownership history, dilution, disposition, cash proceeds, and vehicle return are not publicly established. E1 means a dated security/control snapshot exists, but complete cost, dilution, disposition, and cash proceeds still do not. “Unknown” is an evidence result. A page-reported year is an association year, not necessarily a closing date; an “acquired” label is a company event, not reported fund economics. [researcher inference | strong]
Israel Seed — 27 association rows
Unless a row says otherwise, contemporaneous thesis, check/security/ownership, individual sourcing/approval, board work, follow-on policy, retrospective account, and economics are not publicly established. The vehicle is unresolved among Funds I–IV. [researcher inference | strong]
| ID | Company / path | Date, stage, and vehicle | Thesis / check / ownership | Person, team, governance | Follow-on / status / outcome | Econ and evidence |
|---|---|---|---|---|---|---|
| IS-01 | Compugen | By 1996; seed/early; Fund I/II boundary | Unknown | Firm association only; predates Eisenberg's 1997 join unless later involvement shown | Public-company path; realization unknown | E0 [contemporaneous record | moderate] 1999 profile, company list |
| IS-02 | DealTime → Shopping.com; Epinions acquired | By Aug. 1998; seed; II/IV later holders | Structured comparison/referral logic reconstructable; 2003 IV warrant fragment $52,500; 1,932,158 ordinary equivalents at 2004 filing | Eisenberg director; Cohen/Medved/Eisenberg shared later power; small disclosed personal-benefit component | IPO 2004; eBay acquisition 2005 | E1 [documented behavior | strong] S-1/A, business, related-party transactions, principal holders |
| IS-03 | GuruNet → Answers.com | By 1999; later reported $2m third-round check | Passed twice; later business model accepted; ownership unknown | Israel Seed team; Eisenberg narrates screening/re-entry; board history later reported | IPO 2004; no IPO sale; lifetime proceeds unknown | E0 [retrospective witness | moderate] 1999 account IPO report |
| IS-04 | EarthNoise | By 1999; stage/fund unknown | Unknown | Team association; Eisenberg later describes employee redeployment | Closed; customer-list fragment reportedly sold to CastUP | E0 [retrospective witness | moderate] 2003 interview |
| IS-05 | Business Layers | By 1999; seed/early | Unknown | Firm association only | Acquired by Netegrity/Computer Associates per 2005 report | E0 [contemporaneous record | moderate] 2005 transition |
| IS-06 | iScraper | By 1999; stage/fund unknown | Unknown; no safe alias found | Firm association only | Outcome unresolved | E0 [contemporaneous record | moderate] 1999 profile |
| IS-07 | Tradeum | 1999; reported >$3m first round; Fund III/team | B2B exchange/XML thesis; stake/lockup unknown | Israel Seed led; no sole person allocation | Two million VerticalNet shares announced at $474m; price collapsed; cash realized unresolved | E0 [contemporaneous record | moderate] first round sale |
| IS-08 | Mercado Software | By 1999; seed/early | Unknown | Firm association only | Reported losing market in 2001; final outcome unresolved | E0 [contemporaneous record | moderate] 2001 portfolio review |
| IS-09 | CSafe | By 1999; stage/fund unknown | Unknown | Firm association only | Outcome unresolved | E0 [contemporaneous record | moderate] 1999 profile |
| IS-10 | Foxcom Wireless → MobileAccess | By June 1999; early; I/II | Original thesis/check unknown | Israel Seed team; rescue functions unknown | Near closure, reported ~$20m sales in 2004, acquired by Corning 2011 | E0 [contemporaneous record | moderate] 2003 recovery Corning completion |
| IS-11 | XACCT Technologies | By June 1999; early; I/II | Unknown | Firm association; later biographies associate Eisenberg with board | Reported troubled in 2001; final outcome unresolved | E0 [contemporaneous record | moderate] 1999 Fund III report 2001 review |
| IS-12 | PhoNet Communications | Before Oct. 1999 | Unknown | Firm association only | Sold to VCON for reported $5m in shares; proceeds unknown | E0 [contemporaneous record | moderate] 1999 profile |
| IS-13 | NomadIQ | By 2001 | Unknown | Firm association only | Sold to OmniSky; proceeds unknown | E0 [contemporaneous record | moderate] 2001 review |
| IS-14 | Chiaro Networks | By 2001; seed/early | Unknown | Firm association only | Market trouble noted; outcome unresolved | E0 [contemporaneous record | moderate] 2001 review |
| IS-15 | Banter | By 2001 | Unknown | Firm association only | Market trouble noted; outcome unresolved | E0 [contemporaneous record | moderate] 2001 review |
| IS-16 | MemLink | 1999 seed; 2000 round; 2002 bridge | MEMS optical-switch thesis; ISP in $3m seed, $21m round, and $6m syndicate bridge; allocation/ownership unknown | Israel Seed plus Lucent/Redwood/Oak; other investors declined bridge | Financing failed; shutdown; recovery/cash conflict unresolved | E0 [contemporaneous record | strong] 2000 round 2002 closure |
| IS-17 | ProActivity | By 2001 | Unknown | Firm association only | High prior valuation/financing risk noted; outcome unresolved | E0 [contemporaneous record | moderate] 2001 review |
| IS-18 | Lynx Photonic Networks | By 2001 | Unknown | Firm association only | High prior valuation/financing risk noted; outcome unresolved | E0 [contemporaneous record | moderate] 2001 review |
| IS-19 | Unicorn Solutions | 2001; explicitly seed | Check/ownership unknown; founder Zvi Schreiber named | Firm association only | Later acquisition lead; buyer/proceeds not captured | E0 [contemporaneous record | strong] 2001 review |
| IS-20 | Cyota | By Feb. 2002; security portfolio | Unknown | Firm association only | Later RSA acquisition is a retrieval lead; realization unknown | E0 [contemporaneous record | moderate] security portfolio report |
| IS-21 | Alchemedia | Before Finjan ISP investment | Security thesis; separate company, not Finjan alias | Firm association only | Merged into Finjan; exchange/recovery unknown | E0 [contemporaneous record | strong] Finjan/Alchemedia distinction |
| IS-22 | Finjan | ISP first millions; board by 2002; IV later holder | Security thesis; cost/ownership history incomplete | Eisenberg board; later Fund IV GP record gives Cohen voting authority | Public/reverse-merger path; offering snapshot, no proceeds | E1 [documented behavior | strong] 2002 report 2014 S-1/A footnotes |
| IS-23 | Native Networks | By 2005 | Unknown | Firm association only | Portfolio/transaction mention; exit/proceeds unresolved | E0 [contemporaneous record | moderate] 2005 transition |
| IS-24 | Aelis Photonics | By Jan. 2003; reported $2m total raised | Unknown | Eisenberg gave firm example; no board/closing record | Outcome unresolved | E0 [investor-stated | moderate] 2003 interview |
| IS-25 | Conduct → Qlusters path | 2003 EIR/formation; fund unknown | Unknown | Israel Seed backed Sharon Azulai as EIR; company/person allocation unresolved | Corporate path/outcome unresolved | E0 [contemporaneous record | moderate] Globes 2003 |
| IS-26 | UltraShape | Entry unknown; IV holder by 2007–2010 | IV reportedly ~63% after 2009 reverse merger; cost/proceeds unknown | Fund had board-nomination right at ≥8%; no Eisenberg-specific act | Later outcome/proceeds unresolved | E1 [documented behavior | moderate] investor-rights exhibit 2010 holding report |
| IS-27 | Commtouch → CYREN | IV held 19.75% at 2004 YE; 1.87% by 2006-03-31 | Vehicle holding; cost/cash receipts unknown | No Eisenberg entry/board proof | Sales/dilution reduced stake; final realization unknown | E1 [documented behavior | strong] 2005 Form 20-F, principal shareholder history |
Benchmark Israel / Benchmark-era — 32 association rows
Rows sourced only to the IVC snapshot are candidate-level and carry [contemporaneous record | provisional] support. The page contains post-Eisenberg follow-ons and does not establish individual credit or returns. Clarizen and Funtactix event duplicates are collapsed to one corporate path each.
| ID | Company / path | Date, stage, and vehicle | Thesis / check / ownership | Person, team, governance | Follow-on / status / outcome | Econ and evidence |
|---|---|---|---|---|---|---|
| BM-01 | Integra5 Communications | 2001 first round; first fund | Part of first reported $7m deployed; specifics unknown | Kremer/Naveh/Shelef; pre-Eisenberg | Outcome unresolved | E0 [contemporaneous record | strong] 2001 close |
| BM-02 | Lycium Networks | 2001 seed; first fund | Part of first reported $7m deployed; specifics unknown | Initial team; pre-Eisenberg | Outcome unresolved | E0 [contemporaneous record | strong] 2001 close |
| BM-03 | Oplus | Pre-2010; first fund | Unknown | Pre-Eisenberg entry | Reported acquired for $100m; fund proceeds unknown | E0 [contemporaneous record | moderate] 2010 wind-down |
| BM-04 | FilesX | Pre-2010; first fund | Unknown | Pre-Eisenberg entry | Reported acquired for $85m; fund proceeds unknown | E0 [contemporaneous record | moderate] 2010 wind-down |
| BM-05 | Finjan | Holding visible 2013–2018; BCPI I/Founders I nominees | Holding/control snapshot; original Benchmark entry unknown | Eisenberg/Naveh shared GP-chain power; Eisenberg board began via Israel Seed | Public/secondary path; incomplete cash flows | E1 [documented behavior | strong] Finjan S-1/A |
| BM-06 | CTERA | Seed 2008; II; follow-ons 2012–2018 | Unknown | Person role unknown; later rounds post-departure | IVC current | E0 [contemporaneous record | provisional] IVC Fund II, CTERA rows |
| BM-07 | GreenRoad | First round 2006; II; follow-ons through 2015 | Unknown | Person role unknown | IVC current | E0 [contemporaneous record | provisional] IVC Fund II, GreenRoad rows |
| BM-08 | Here Not There / Towns | First round 2023; legacy II association | Unknown | Post-Eisenberg; excluded from person credit | IVC current | E0 [contemporaneous record | provisional] IVC Fund II, company row |
| BM-09 | Seeking Alpha | Seed 2006; II; rounds 2007/2009 | Check/security/ownership unknown | Eisenberg calls it first Benchmark investment and served on board; approval/terms unknown | Long-lived private; no liquidity/economics | E0 [retrospective witness | moderate] 2006 announcement Golden Calf essay |
| BM-10 | BroadLight | By 2012; II | Unknown | Person role unknown | IVC acquired 2012; price/proceeds hidden | E0 [contemporaneous record | provisional] IVC Fund II, BroadLight row |
| BM-11 | Clarizen | Entry not exposed; II | Unknown | Third-party director association; primary record needed | 2018 MBO and 2021 event collapsed; proceeds unknown | E0 [contemporaneous record | provisional] IVC Fund II, Clarizen events |
| BM-12 | Cotendo | By 2011; II | Unknown | Person role unknown | IVC acquired 2011 | E0 [contemporaneous record | provisional] IVC Fund II, Cotendo row |
| BM-13 | Funtactix / FTX Games asset path | By 2016; II legacy | Unknown | Person role unknown | 2016 acquisition + 2020 asset sale; one path | E0 [contemporaneous record | provisional] IVC Fund II, Funtactix events |
| BM-14 | Gigya | Entry before 2017; II | Unknown | Issuer biography says Eisenberg invested/boarded; sole credit unsupported | SAP acquisition 2017 | E0 [contemporaneous record | moderate] Freightos 20-F, Eisenberg biography |
| BM-15 | Odysii | By 2015; II | Unknown | Person role unknown | IVC acquired 2015 | E0 [contemporaneous record | provisional] IVC Fund II, Odysii row |
| BM-16 | Sentrigo | By 2011; II | Unknown | Person role unknown | IVC acquired 2011 | E0 [contemporaneous record | provisional] IVC Fund II, Sentrigo row |
| BM-17 | Swifto | Exit 2025; II legacy | Unknown | Post-Eisenberg outcome; no person credit | IVC acquired 2025 | E0 [contemporaneous record | provisional] IVC Fund II, Swifto row |
| BM-18 | Wilocity | Entry before 2014; II | Unknown | Eisenberg writing calls Benchmark company; no deal-lead proof | IVC acquired 2014 | E0 [documented behavior | moderate] IVC Fund II, Wilocity row |
| BM-19 | Conduit / ClientConnect; Wibya bolt-on; Perion outcome shares | Second round 2008; II; IVC reported $8m / 18% | Large Perion holding later; complete cost/cash flows unknown | Eisenberg identifies as director; Eisenberg/Naveh shared GP-chain power | Conduit path ceased; 11.8% Perion 2019 snapshot | E1 [documented behavior | strong] Perion 2014 report, transaction 2019 ownership |
| BM-20 | Exaware | First round 2008; II; follow-ons through 2013 | Unknown | Person role unknown; last round post-departure | IVC historic/ceased | E0 [contemporaneous record | provisional] IVC Fund II, Exaware rows |
| BM-21 | Ghost Inc. | Seed 2006; first round 2008; II | Unknown | Person role unknown | IVC historic/ceased | E0 [contemporaneous record | provisional] IVC Fund II, Ghost rows |
| BM-22 | LucidEra | Seed 2006; first round 2007; II | Unknown | Person role unknown | IVC historic/ceased | E0 [contemporaneous record | provisional] IVC Fund II, LucidEra rows |
| BM-23 | MediAnd | First round 2008; II | Unknown | Person role unknown | IVC historic/ceased | E0 [contemporaneous record | provisional] IVC Fund II, MediAnd row |
| BM-24 | Power Challenge AB | First round 2007; II | Unknown | Person role unknown | IVC historic/ceased | E0 [contemporaneous record | provisional] IVC Fund II, Power Challenge row |
| BM-25 | Spotback | Seed 2006; II | Unknown | Person role unknown | IVC historic/ceased | E0 [contemporaneous record | provisional] IVC Fund II, Spotback row |
| BM-26 | TuneWiki | Seed 2008; first round 2010; II | Unknown | Person role unknown | IVC historic/ceased | E0 [contemporaneous record | provisional] IVC Fund II, TuneWiki rows |
| BM-27 | Vollee | First round 2006; second 2007; II | Unknown | Person role unknown | IVC historic/ceased; litigation merits/outcome not reconstructed | E0 [contemporaneous record | provisional] IVC Fund II, Vollee rows |
| BM-28 | Zlango / Lango | First round 2007; II; follow-ons 2009/2011 | Smartphone-transition mechanism narrated; check/ownership unknown | Eisenberg discusses timing; no sole decision proof | IVC historic/ceased | E0 [investor-stated | moderate] TCTV, 06:52–07:16 |
| BM-29 | Digital Fuel | Benchmark-era; vehicle/date unknown | Unknown | Issuer biography lead only | VMware acquisition lead; proceeds unknown | E0 [contemporaneous record | provisional] Freightos 20-F, Eisenberg biography |
| BM-30 | Wix | Board by Mar. 2010; BCP VI; exact Israel/main-fund allocation unresolved | 2010 Benchmark $7.009m and 2011 $1.004m disclosed fragments; 4,012,329 shares pre-IPO | Eisenberg board; filing denies his voting/dispositive power over block | IPO 2013; reported ~$80m full Benchmark exit in 2015 | E1 [documented behavior | strong] Wix F-1/A, financings and holders reported disposition |
| BM-31 | Vringo → XWELL | Convertible/holding by 2010–2012; II | Security snapshot; full cost/proceeds unknown | 13G mirror names Eisenberg/Naveh/Wurtman with shared GP power | Public/merger path; proceeds unknown | E1 [documented behavior | moderate] 2012 S-4 2010 13G mirror |
| BM-32 | WeWork | Initial 2012-era Benchmark investment; likely main/global pool | Enterprise-space thesis documented; exact check/security/ownership unknown | Eisenberg sourced/championed; Dunlevie official Benchmark director | Failed 2019 IPO; 2021 listing; 2023 Chapter 11 and old-equity cancellation | E0 [documented behavior | strong] 2017 sourcing Q&A 2023 8-K, Item 1.03 |
Aleph — 64 current-page association rows
Default for every row unless overridden: vehicle/fund allocation unknown; company card does not establish person-level sourcing, diligence, approval, terms, board work, follow-ons, ownership, realization, or retrospective rationale; thesis/check/security/ownership unknown; E0; [contemporaneous record | moderate]. Each year is the current page's displayed association year, not a verified close. “No controlled outcome” means no filing/transaction control was captured, not that the company failed or succeeded. The common source is the named card on the official Aleph companies page.
| ID | Company / alias | Page year / stage | Supported exception to defaults | Status / outcome and boundary | Econ / evidence |
|---|---|---|---|---|---|
| AL-01 | Agora | 2021; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Agora card |
| AL-02 | Anecdotes | 2020; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Anecdotes card |
| AL-03 | Approve | 2020; stage unknown | None | Page says acquired by Tipalti; proceeds unknown | E0 [contemporaneous record | moderate] Approve card |
| AL-04 | Brew | 2020; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Brew card |
| AL-05 | Bringg | 2017; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Bringg card |
| AL-06 | Centrical | 2019; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Centrical card |
| AL-07 | Colu | 2015; stage unknown | None | Page says acquired by HBSS Connect; proceeds unknown | E0 [contemporaneous record | moderate] Colu card |
| AL-08 | Compete | 2021; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Compete card |
| AL-09 | Coralogix | 2019; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Coralogix card |
| AL-10 | Daily.dev | 2022; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Daily.dev card |
| AL-11 | Daisy | 2019; stage unknown | Third-party profile links Eisenberg to board; primary record absent | No controlled outcome | E0 [contemporaneous record | provisional] Daisy card |
| AL-12 | Dream | 2023; stage unknown | Eisenberg self-reported unusually large initial fund exposure; vehicle/check denominator unverified | No controlled outcome | E0 [investor-stated | provisional] Dream card; 20VC AI, 42:35–43:37 |
| AL-13 | Embed | 2022; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Embed card |
| AL-14 | Empathy | 2020; stage unknown | Eisenberg-authored essay documents a long Gura relationship, not allocation or sole approval | No controlled outcome | E0 [investor-stated | moderate] Empathy card; deal essay, paragraphs 3–8 |
| AL-15 | Fabric; CommonSense Robotics unresolved predecessor lead | 2016; page says Seed/A/B | None | No controlled outcome; alias not legally reconciled | E0 [contemporaneous record | moderate] Fabric page |
| AL-16 | Finaloop | 2021; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Finaloop card |
| AL-17 | Floodlight | 2021; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Floodlight card |
| AL-18 | Frank | 2017; exact round on page unknown | Aleph led reported 2017 seed and joined follow-ons; no person-level decision/knowledge shown | Page says JPMorgan acquisition; Javice/Amar criminal findings; Aleph-holder suit unresolved | E0 [documented behavior | strong] DOJ sentencing |
| AL-19 | Freightos | Page 2013; contemporaneous Series B 2014 | Eisenberg director since 2013; Aleph legal holder; $4.6m round total, allocation unknown | Public Jan. 2023; page's Jan. 2022 label is erroneous; ongoing and loss-making 2025 | E1 [documented behavior | strong] 2022 20-F filed 2023, listing history |
| AL-20 | Fullpath / AutoLeadStar | 2019; stage unknown | Aaron Rosenson authored 2021 thesis; not Eisenberg credit | Page says Cox Automotive acquisition | E0 [contemporaneous record | moderate] Fullpath card; Rosenson essay |
| AL-21 | Geoquant | 2017; stage unknown | None | Page says Fitch Ratings acquisition | E0 [contemporaneous record | moderate] Geoquant card |
| AL-22 | Grain | 2022; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Grain card |
| AL-23 | Healthy.io | Page 2018; $18m Series B announced 2019 | Eisenberg same-day thesis/direct diligence; issuer biography supports board; exact check/ownership unknown | FDA clearances and follow-ons; private; layoffs reported 2023/2024 | E0 [investor-stated | strong] deal essay |
| AL-24 | HoneyBook | 2014; stage unknown | Issuer biography supports Eisenberg board | No controlled outcome | E0 [contemporaneous record | moderate] Freightos 20-F biography |
| AL-25 | Houseparty; Yevvo/Meerkat predecessor leads | 2016; stage unknown | Shochat—not Eisenberg—publicly owns the investor-failure/team-success narrative | Page says Epic Games acquisition; predecessor cap table unresolved | E0 [retrospective witness | moderate] Shochat account |
| AL-26 | Inevitable AI | Year not displayed; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Inevitable AI card |
| AL-27 | Jiga | 2020; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Jiga card |
| AL-28 | Lemonade | 2015; board from July 2015 | Aleph/Aleph-Aleph held 4,539,063 shares at IPO filing; Eisenberg filing power and lead independent-director role; not personal ownership | IPO 2020; ongoing public company; 2025 scale plus continued losses | E1 [documented behavior | strong] S-1/A, holders/board/financials |
| AL-29 | Luminate | 2016; stage unknown | None | Page says Symantec acquisition | E0 [contemporaneous record | moderate] Luminate card |
| AL-30 | Melio | 2018; stage unknown | Eisenberg essay body unavailable; no thesis/person credit | Xero completed acquisition; Aleph ownership/proceeds unverified | E0 [contemporaneous record | provisional] article metadata Xero terms |
| AL-31 | MyInterview | 2020; stage unknown | None | Page says Radancy acquisition | E0 [contemporaneous record | moderate] MyInterview card |
| AL-32 | Nexar | 2015; stage unknown | Issuer biography supports Eisenberg board | No controlled outcome | E0 [contemporaneous record | moderate] Freightos 20-F biography |
| AL-33 | NextSilicon | 2019; stage unknown | Eisenberg-hosted founder material supports relationship, not entry credit | No controlled outcome | E0 [contemporaneous record | moderate] NextSilicon card |
| AL-34 | Ohr | 2024; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Ohr card |
| AL-35 | OneStep | 2020; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] OneStep card |
| AL-36 | Panorays | 2017; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Panorays card |
| AL-37 | Placer.ai | 2019; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Placer.ai card |
| AL-38 | Ply | 2021; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Ply card |
| AL-39 | Q | 2022; stage unknown | None | Page says Apple acquisition | E0 [contemporaneous record | moderate] Q card |
| AL-40 | Raftt | 2021; stage unknown | None | Page says Wiz acquisition | E0 [contemporaneous record | moderate] Raftt card |
| AL-41 | Reeco | 2024; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Reeco card |
| AL-42 | RiseUp | 2017; stage unknown | Partial essay opening supports founder/ideation chronology only | No controlled outcome | E0 [investor-stated | provisional] opening paragraphs |
| AL-43 | SecuriThings | 2020; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] SecuriThings card |
| AL-44 | Sequence | 2023; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Sequence card |
| AL-45 | Sightful | 2022; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Sightful card |
| AL-46 | Simply / JoyTunes | 2014; page says A/B/C | Shochat authored the firm investment note; no sole Eisenberg credit | No controlled outcome | E0 [contemporaneous record | moderate] Simply page |
| AL-47 | SparkBeyond | 2018; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] SparkBeyond card |
| AL-48 | SphereX | 2022; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] SphereX card |
| AL-49 | Spines | 2023; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Spines card |
| AL-50 | Superlegal | 2018; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Superlegal card |
| AL-51 | Svix | 2022; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Svix card |
| AL-52 | TheGist | 2022; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] TheGist card |
| AL-53 | Thriver | 2018; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Thriver card |
| AL-54 | TinyTap | 2018; stage unknown | None | Page says Animoca Brands acquisition | E0 [contemporaneous record | moderate] TinyTap card |
| AL-55 | Travelier | 2019; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Travelier card |
| AL-56 | Trullion | 2020; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Trullion card |
| AL-57 | Umbrella; Anodot probable unresolved path | 2016; page says A/B | Page copy creates alias lead only | No controlled outcome; equivalence unresolved | E0 [contemporaneous record | provisional] Umbrella page |
| AL-58 | Uniper | 2020; page says early stage | None | No controlled outcome | E0 [contemporaneous record | moderate] Uniper page |
| AL-59 | Unit | 2020; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Unit card |
| AL-60 | Voltify | Year not displayed; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Voltify card |
| AL-61 | Waltz | 2024; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Waltz card |
| AL-62 | WeWork | Page says 2014; stage/vehicle unknown | Page does not establish an Aleph investment; original association is Benchmark-era | Failed IPO then Chapter 11; duplicate company path | E0 [contemporaneous record | moderate] WeWork card; 8-K, Item 1.03 |
| AL-63 | Windward | 2013; first reported $5m financing | Aleph/Aleph-Aleph holdings and current convertibles disclosed; team attribution | AIM 2021; FTV cash acquisition completed 2025 | E1 [documented behavior | strong] admission document, capitalization/holders |
| AL-64 | Workiz | 2018; stage unknown | None | No controlled outcome | E0 [contemporaneous record | moderate] Workiz card |
Ex-ante forensic cases and decision labs
Every case freezes the information set before disclosing later outcomes. The analyst-created prompts are not attributed to Eisenberg. Terms, dissent, milestones, governance, and alternatives are explicit where evidence permits and marked unknown otherwise. The actual decision/outcome follows the questions so the exercise can be run without hindsight.
Case 1: Windward
Freeze — November 2013. Windward's first reported institutional financing was $5m from Aleph. Founders Ami Daniel and Matan Peled brought Israeli naval experience; the company proposed to use satellite data and analytics to reveal hard-to-observe maritime behavior, initially for defense and homeland security. Domain expertise, new data feeds, and a paid security beachhead were visible. Commercial expansion, procurement duration, false-positive cost, data-provider dependency, sanctions change, model accountability, and customer concentration were unknown. [contemporaneous record | moderate] Globes, November 2013
Thesis and alternative. The investable mechanism was not generic “AI.” Messy vessel identity and movement could become proprietary labeled behavior embedded in analyst and compliance workflows. A security customer might finance product maturity before expansion into banking, insurance, commodities, and logistics. The alternative was a narrow government contractor with long sales cycles and fragile third-party data rights. [researcher inference | strong] admission document, “Business”
Terms, people, and governance known then. The $5m company financing is reported; check allocation, security, valuation, ownership, partner vote, board appointment, dissent, reserve plan, and kill criteria are unknown. It was Aleph's first announced investment. Eisenberg later used “we”; public firm accounts also support team participation, so sole attribution is unwarranted. [documented behavior | moderate]
Decision lab — stop before reading the outcome.
- Would you invest then? Is paid security demand enough to fund a long commercial transition?
- What would kill the deal? Which accuracy, renewal, procurement-delay, data-rights, or dual-use result ends support?
- What ownership/terms fit the risk? What initial ownership, board/audit rights, customer-use policy, and reserves compensate for a narrow market and long cycle?
- What evidence unlocks the next check? Which paid pilot, renewal, false-positive/negative result, commercial-revenue mix, and data-right proof must arrive?
Actual decision and outcome. Aleph invested. The 2021 admission document showed 12,960,596 shares held by Aleph L.P. and 1,289,246 by Aleph-Aleph, plus approximately $454,766/$45,234 of current convertibles; those are holdings and fragments, not cost basis. Windward listed on AIM at 155p, then FTV offered 215p in cash in 2024; Aleph entities gave irrevocable undertakings over 13,941,461 shares, 15.92% of issued capital. The acquisition completed March 18, 2025. This is a completed company and security event, but earlier sales, distributions, fees, carry, and net fund return remain unknown. [documented behavior | strong] admission document, capitalization and holders recommended acquisition, offer and undertakings FCA completion notice
Case 2: DealTime / Shopping.com
Freeze — August 1998. A later 2004 issuer filing records that the Israeli company was incorporated in March 1997, launched DealTime in 1998, and had Eisenberg as a director by August 1998. Online assortment made product/price/store comparison harder; merchants wanted measurable high-intent referrals. A free comparison tool supported by merchant referral fees and a structured catalog was a plausible new intermediary. Search-platform dependence, the dot-com crash, catalog defensibility, review liability, and the future Epinions combination were unknowable. These facts reconstruct the cutoff from a later filing; they are not a recovered 1998 investment packet. [documented behavior | strong] Shopping.com S-1/A, corporate information, business, management
Thesis, people, and terms. The mechanism was catalog/data breadth plus traffic and merchant participation; later scale validates that mechanism, not its entry probability. Eisenberg's board tenure is filed and later reporting credits him with recruiting Dan Ciporin, while later discussion credits Bill Gurley and other board actors around Epinions. The original check, security, valuation, partner vote, and reserve plan are absent. [documented behavior | moderate] Globes, CEO recruitment retrospective
By August 2004, Israel Seed II and IV jointly held 1,932,158 ordinary equivalents, 8.3% pre- and 6.8% post-offering. Israel Seed II's 991,440 included 20,417 held for Eisenberg's personal benefit; Israel Seed IV held 940,718. Cohen, Medved, and Eisenberg shared power, and Eisenberg disclaimed ownership beyond pecuniary interest. A 2003 IV warrant exercise for 75,000 Series B shares at $0.70 exposes only a $52,500 fragment, not full cost. [contemporaneous record | strong] S-1/A, principal shareholders and related-party transactions A December 2004 conference report says Eisenberg believed an Israeli Companies Law provision had almost blocked the IPO and that directors should be selected with global governance obligations in mind; it is an edited panel account, not a legal ruling. [contemporaneous record | moderate] Globes, corporate-law and director-selection account
Adverse packet. By June 2004 the company had a $157.5m accumulated deficit; Google supplied about 38% of 2003 revenue while also competing. Evolving search, intense competition, traffic dependence, fluctuating results, integration, and Epinions shareholder litigation were disclosed risks. [contemporaneous record | strong] S-1/A, risk factors
Decision lab — stop before reading the outcome.
- Would you invest then? Is the catalog/referral wedge a compounding asset or a directory feature?
- What would kill the deal? What traffic-concentration, merchant-renewal, catalog-freshness, or contribution-margin threshold ends support?
- What ownership/terms fit the risk? What board, leadership-replacement, staged-reserve, and distribution-concentration protections are required?
- What evidence unlocks the next check? Which repeat-use, direct-traffic, merchant ROI, conversion, and data-quality milestones matter?
Actual decision and outcome. Israel Seed invested and Eisenberg served on the board. DealTime acquired Epinions in 2003 for securities/options valued around $30.5m net of transaction costs. Shopping.com completed its October 2004 IPO at $18; Israel Seed registered no IPO sale. eBay completed an acquisition on August 30, 2005 for a reported purchase price of about $685.3m, including about $634.5m cash for common shares at $21 and $43.2m for assumed options. The company outcome is verified; Israel Seed II/IV proceeds, distributions, and Eisenberg economics are not. [documented behavior | strong] final prospectus eBay 10-K, acquisition note
Case 3: Wix
Freeze — no later than March 2010. A later 2013 issuer filing records that Wix offered browser-based self-service web publishing to non-coders through a freemium cloud model and that Eisenberg joined the board by March 2010. The opportunity was large and visible; durable free-to-paid conversion, acquisition payback, mobile/social displacement, churn, support cost, and the ability to serve professionals without becoming services-heavy were unresolved. These facts reconstruct the cutoff from a later filing; they are not a recovered 2010 investment packet. [documented behavior | strong] Wix F-1/A, business, history, board
Thesis and terms. The product-led-distribution thesis is reconstructed from the issuer's model, not recovered as Eisenberg's memo. In 2010 Benchmark invested $7.009m for 2,631,843 shares in a Series D; in 2011 it invested $1.004m for 147,105 shares in a Series E. Founders sold ordinary shares in both rounds. These are disclosed fragments, not complete cost. [researcher inference | moderate] F-1/A, share-capital and related-party financing notes
At IPO filing, Benchmark Capital Partners VI held 4,012,329 shares, 13.2% pre- and 11.0% post-offering. The filing says Eisenberg lacked voting/dispositive power and was not beneficial owner of that block; other Benchmark managing members controlled it. His supported function is board service, not personal fund ownership. [documented behavior | strong] F-1/A, principal shareholders
Decision lab — stop before reading the outcome.
- Would you invest then? Do publishing cohorts show a software engine or vanity traffic?
- What would kill the deal? Which churn, conversion, organic-acquisition, support-cost, or platform-shift result defeats it?
- What ownership/terms fit the risk? How should founder secondaries, board rights, leadership succession, and follow-ons be governed?
- What evidence unlocks the next check? Which activation-to-publish, free-to-paid, retention, mobile, app-ecosystem, and payback metrics qualify?
Actual decision and outcome. Benchmark invested; Eisenberg served on the board. Wix priced its November 2013 IPO at $16.50, with Benchmark not selling in the IPO. By early 2015 Benchmark was no longer a >5% holder and Eisenberg no longer appeared in the board table. [documented behavior | strong] Globes reported an approximately $80m full Benchmark disposition; that is a single-source reported gross estimate, not audited net distribution or Eisenberg profit. [contemporaneous record | provisional] Wix 2014 20-F, holders/board Globes, reported disposition
Case 4: Lemonade
Freeze — July–December 2015. The founder's dated announcement and a later 2020 issuer filing record that Daniel Schreiber and Shai Wininger proposed a technology-first insurance carrier with no legacy system, fixed fee, Giveback, reinsurance, rapid digital service, and behavioral design. A $13m seed from Aleph and Sequoia was later described; Eisenberg had joined the board by July. The visible bet was not merely an insurance app: a full-stack carrier would own workflow/data and align claims incentives, while also assuming licensing, pricing, fraud, reserve, catastrophe, reinsurance, regulatory-capital, and service risk. The filing-derived facts reconstruct the cutoff; they are not a recovered 2015 investment packet. [documented behavior | strong] founder announcement S-1/A, board/business/risk factors
Evidence and attribution. The stable 2015 Aleph article exposes only an opening power-law paragraph; absent Team/Mission/Moat/Market/Stage content cannot be inferred. Eisenberg's long relationship with Schreiber supports access, not company quality. He later corrected himself to credit Schreiber—not “we”—for the New York licensing decision. [investor-stated | strong] limited article 20VC AI, 55:47–56:30
At IPO filing, Aleph/Aleph-Aleph held 4,539,063 shares, 10.3% pre- and 8.3% post-offering, spanning Seed/A/B securities. The filing gave Eisenberg voting/investment power over entities; this is not personal ownership. Aleph did not sell at IPO. [documented behavior | strong] S-1/A, principal holders and financings
Adverse packet before public-market hindsight. Revenue rose $2m→$23m→$67m in 2017–2019, while net losses were ~$28m→$53m→$109m; gross loss ratio improved 161%→113%→79%. The 2019 Giveback was over $600k/about 1.5% of earned premium and discretionary. These show scale and operational improvement alongside severe loss/capital demands. [contemporaneous record | strong] S-1/A, selected financial data/business
Decision lab — stop before reading the outcome.
- Would you invest then? Is a regulated full-stack carrier the necessary way to own the data/incentive loop?
- What would kill the deal? Which licensing delay, loss ratio, retention, complaint, acquisition-payback, reinsurance, or solvency result ends support?
- What ownership/terms fit the risk? What board, reserve, regulatory, related-party, model-audit, and catastrophe controls are necessary?
- What evidence unlocks the next check? Which license, cohort loss, claims satisfaction, renewal, automation-quality, and capital stress test qualifies?
Actual decision and outcome. Aleph invested; Lemonade listed in 2020 at $26. A November 2020 Form 4 records direct/personal Eisenberg sales around $70–$72 while separately identifying fund holdings, so those sales cannot be called Aleph distributions. In 2025 Lemonade reported exactly 2,984,513 customers, $1.2365bn in-force premium, $737.9m revenue, $293.4m gross profit, a $165.5m net loss, and $118.1m adjusted-EBITDA loss. The company is scaled and ongoing, not a completed profitability or fund-realization case. [documented behavior | strong] Form 4 2025 10-K
Case 5: Healthy.io
Freeze — February 5, 2019. Aleph led an $18m Series B with Samsung NEXT/private investors. Healthy.io had FDA clearance for smartphone urinalysis, a Siemens partnership, Boots deployment, and a US kidney-disease testing ambition. Eisenberg's same-day essay documents his first medical investment and explicit filters: learning founders, large/emerging market, secular tailwind, mission, contrarian setting, and fresh perspective. Repeated meetings covered reimbursement, regulation, robotics, lighting, and patient behavior; rejected evidence and IC dissent remain unavailable. [investor-stated | strong] deal essay financing announcement
Mechanism and risk. Better phone cameras/computation plus calibration could turn standard dipsticks into home tests without proprietary electronic hardware; reusable computer vision/data might support multiple tests. Theranos stigma reduced competition but raised the need for independent clinical evidence. Device/lighting variability, invalid tests, payer reimbursement, completion/follow-up, privacy, FDA pathway, sales-cycle length, defensibility, and capital needs were open. [researcher inference | strong]
Check allocation, security, valuation, ownership, board right, reserve, partner vote, and kill criteria are unknown. The company later announced a $60m Series C, a previously unannounced $45m 2022 investment, and a $50m Series D, with Aleph among existing investors; issuer announcements do not allocate Aleph's follow-ons. FDA K210069 and K222921 establish clearance, not clinical-outcome superiority. [documented behavior | moderate] FDA K210069 decision summary FDA K222921 record
Decision lab — stop before reading the outcome.
- Would you invest then? Does clearance plus deployment justify a sector exception for an outsider founder?
- What would kill the deal? Which concordance, invalid-test, completion, follow-up, reimbursement, renewal, or gross-margin result ends it?
- What ownership/terms fit the risk? What clinical-validation, claim-control, adverse-event, data, board, and tranche protections are needed?
- What evidence unlocks the next check? Which independent lab comparison, paid contracted lives, payer renewal, regulatory milestone, and unit-economics result qualifies?
Actual decision and outcome. Aleph invested and participated in later financings. FDA records support continuing clearance, while Calcalist reported roughly 70 layoffs in 2023 and another 40—about one-third of then staff—in 2024. The company remained private and operating at the cutoff. Regulatory/product progress did not eliminate burn or go-to-market risk; revenue, profitability, ownership, liquidity, write-downs, and Aleph return remain unknown. [documented behavior | moderate] 2023 Series D announcement 2023 layoffs 2024 layoffs
Case 6: Freightos
Freeze — March 25, 2014. Aleph and MoreVC led a $4.6m Series B. Freight booking still depended on fragmented tariffs, email, and manual quoting; Freightos said an international quote could take about three days. The investment case was that structured rate data and workflow software could shorten quotes and eventually create marketplace liquidity. The contemporary announcement supports the problem and round, but does not disclose Aleph's allocation, security, valuation, ownership, board right, or partner vote. [contemporaneous record | moderate] Series B announcement
Mechanism and adverse packet. Normalizing carrier schedules and tariffs could produce a reusable data layer, then a transaction network. Risks included slow forwarder adoption, bad rates, incumbent resistance, two-sided liquidity, trade cyclicality, long integration, and a misleading gap between gross booking value and revenue. Later financing validates access to capital, not the entry thesis; the issuer reported a $14m round and then a $44.4m Series C, $94.4m cumulative funding. [researcher inference | moderate] Series C announcement
Decision lab — stop before reading the outcome.
- Would you invest then? Can workflow adoption precede and seed a defensible marketplace?
- What would kill the deal? Which quote-accuracy, repeat-booking, take-rate, concentration, or integration result defeats it?
- What ownership/terms fit the risk? What board/data rights, staged reserves, marketplace controls, and dilution protection fit a long liquidity build?
- What evidence unlocks the next check? Which forwarder retention, automated-quote share, repeat transaction, contribution margin, and balanced-side liquidity qualifies?
Actual decision and outcome. Aleph invested. Freightos later became public. Its February 2026 results said 2025 revenue was $29.46m, gross profit $19.68m, net loss $17.52m, transactions 1.643m, gross booking value $1.286bn, and year-end cash/deposits about $27.9m. A 2024 filing showed Aleph with 3,544,394 shares, about 7.08%; that is a holding, not cost or realized return. The company is an operating public outcome, not a completed fund return. [documented behavior | strong] 2024 Aleph holding, 20-F 2025 results
Case 7: Seeking Alpha
Freeze — September 2006. Seeking Alpha aggregated analysis from more than 200 contributors covering roughly 4,000 companies and had a Yahoo distribution agreement; TechCrunch reported Benchmark financing but no amount. The wedge was specialist analysis, low-cost contribution, syndication, and high-intent finance traffic. Quality control, contributor incentives, copyright, platform dependence, monetization, and editorial responsibility were unresolved. Eisenberg was reported on the board; the vehicle, check, ownership, and terms are unknown. [contemporaneous record | moderate] funding and Yahoo report
Learning boundary. Eisenberg later framed the company as a fourteen-year slow build before model/mobile acceleration. That retrospective supports patience and low burn as his lesson, but is vulnerable to survivorship and narrative compression. It does not supply the initial underwriting memo or fund economics. [investor-stated | moderate] Eisenberg, “The Golden Calf and Venture Capital Investments,” paragraphs 11–12
Decision lab — stop before reading the outcome.
- Would you invest then? Is distributed analysis a durable product or low-cost content arbitrage?
- What would kill the deal? Which contributor-quality, direct-traffic, retention, compliance, or monetization result ends support?
- What ownership/terms fit the risk? What board/editorial controls, staged capital, and founder vesting fit a slow, reputation-sensitive build?
- What evidence unlocks the next check? Which direct audience, repeat use, subscription conversion, contributor retention, and unit economics qualify?
Actual decision and outcome. Benchmark invested and Eisenberg served on the board. Seeking Alpha remained private and operating. A 2024 federal order dismissed an adviser's compensation complaint with leave to amend; that procedural ruling neither establishes an investor return nor makes the company a portfolio failure. Revenue, ownership history, secondary sales, distributions, and fund return remain unavailable. [documented behavior | moderate] Lingley procedural order
Case 8: Melio
Freeze — entry date and thesis unrecovered. Aleph's public portfolio establishes association, but the surviving writing route exposes metadata/opening material rather than a body that can support Eisenberg's underwriting. A generic hypothesis—small-business accounts-payable workflow plus embedded payments—would be researcher inference, not a recovered thesis. Initial date, vehicle, check, security, valuation, ownership, board rights, partner vote, and rejected evidence remain unknown. [documented behavior | moderate] Aleph portfolio
Decision boundary. The key ex-ante tests would have been whether software retention and payment monetization reinforced each other, whether customer-acquisition cost survived channel shifts, and whether fraud, bank dependencies, loss-sharing, take rate, working capital, and regulation were bounded. Later scale cannot be backfilled into entry underwriting. [researcher inference | moderate]
Decision lab — stop before reading the outcome.
- Would you invest then? Does bill-pay workflow create durable retention and an advantaged payment rail?
- What would kill the deal? Which churn, acquisition-payback, fraud-loss, bank concentration, take-rate, or compliance result defeats it?
- What ownership/terms fit the risk? What loss-allocation, data/audit, board, reserve, and regulatory covenants are required?
- What evidence unlocks the next check? Which retained cohort, payment frequency, gross-profit retention, fraud-adjusted margin, and bank redundancy qualifies?
Actual decision and outcome. Aleph invested; Xero announced the transaction in June 2025 and reported completion on October 15, 2025. [documented behavior | strong] Xero reported $2.5bn upfront consideration plus up to $500m of contingent employee-linked consideration, March annualized revenue of $187m, FY revenue of $153m, about 80,000 customers, and $30bn payment volume. [contemporaneous record | provisional] Those issuer-supplied operating figures and headline consideration do not reveal Aleph's ownership, proceeds, fund allocation, fees, carry, or net return; a press estimate of Aleph economics was excluded. Xero acquisition announcement Xero completion, 2025-10-15
Case 9: PictureVision
Freeze — mid-1990s. PictureVision digitized film and let consumers share photographs online, often by scanning negatives through processing partners. The bet joined an emerging consumer internet with existing film behavior, before broadband, camera phones, or clear online-photo economics. Merchant-banking/personal-fee descriptions do not establish that Israel Seed owned the investment; person, advisory firm, and fund remain separate. Original check, security, valuation, ownership, decision rights, and loss cases are unavailable. [retrospective witness | provisional] EconTalk transcript, “PictureVision” 20VC AI, 01:41–03:06
Mechanism and risk. Distribution through photo processors could overcome hardware adoption, while stored images and sharing might create retention. Scanning cost, slow connections, storage cost, privacy, weak payment willingness, processor dependence, and imminent digital-camera substitution were existential. The reconstruction is historically useful but insufficient for fund-return attribution. [researcher inference | moderate]
Decision lab — stop before reading the outcome.
- Would you invest then? Is processor distribution enough to bridge analog film into online sharing?
- What would kill the deal? Which scan cost, use frequency, storage cost, processor concentration, or digital-camera shift ends support?
- What ownership/terms fit the risk? What distribution exclusivity, data rights, staged capital, and strategic-sale protection are needed?
- What evidence unlocks the next check? Which active sharing, repeat rolls, partner rollout, per-image margin, and direct retention qualifies?
Actual decision and outcome. Kodak disclosed acquiring 51% of PictureVision in 1998 and the remaining interest in May 2000; its filings indicate aggregate consideration around $90m. This verifies a strategic company exit, not Eisenberg's or Israel Seed's proceeds. The exact investing entity and economics remain unresolved and the case stays outside the 123-row ledger. [contemporaneous record | strong] Kodak 1998 filing Kodak 2000 filing
Case 10: Israel Seed IV and no Fund V
Freeze — December 2001. Israel Seed IV was a 2000-vintage fund formed at the technology and telecom peak within a very-early-stage company-building strategy. The stated institutional advantages were rapid seed decisions, partner involvement, a connected LP network, syndication, and the ability to help Israeli companies reach U.S. capital and management. By the end of 2001, collapsing public technology comparables, Tradeum's stock-consideration decline, a concentrated communications/Internet portfolio, and the increasing financing needs of pre-revenue companies were visible. The future Fund IV write-offs, successor-fund decision, and later CalPERS marks must remain hidden at this cutoff. [contemporaneous record | moderate] Israel Seed 1999 strategy profile 2001 portfolio and market review
Mechanism, adverse packet, and terms. The fund mechanism was power-law seed ownership plus active company formation: back many young companies, reserve enough capital and board attention to reach U.S. markets, and use co-investors to carry winners. The adverse packet was a vintage and liquidity trap. Falling public and M&A comparables weakened stock exits; optical, communications, and Internet companies required large follow-ons just as syndicates withdrew; early-stage concentration extended duration; and a few partners could not actively govern an unlimited board load. Public reporting later described the partnership's four-fund platform, but the Fund IV LPA, exact final close, management fee, carry, reserves, pacing policy, concentration limits, recycling, key-person rights, company allocations, partner votes, dissent, and distribution policy remain unavailable. This is a fund/team/vintage case, not a personal Eisenberg security-selection result. [researcher inference | strong] Bank of Israel, financing uncertainty and staged-capital context
Decision lab — stop before reading the outcome.
- Would you continue the original pace then? Should the partnership keep seeding, slow new commitments, or concentrate reserves on existing milestones?
- What would kill the strategy? Which write-off, reserve-coverage, syndicate-withdrawal, board-load, public-stock, or LP-feedback threshold forces a change?
- What ownership/terms fit the risk? What company staging, syndicate, liquidation, distribution, concentration, and fund-reserve rules protect the vintage?
- What evidence unlocks the next commitment? Which customer validation, next-round coverage, cash realization, board-capacity, and portfolio runway metrics justify another seed or successor fund?
Actual decision and outcome. Globes later reported $14m, or 7%, of Fund IV written off by 2002. At year-end 2005, CalPERS data reported by Globes showed Fund IV at -15.8% IRR, $226m managed, $160m called, and $64m in paper write-offs; CalPERS had contributed $2m, received $320,000, and carried $1.2m of remaining value. Same-vintage Gemini, JVP, and Pitango funds were also negative, supporting a market-cohort explanation, while Israel Seed's inability to raise Fund V when stronger local franchises raised successors is firm-specific counterevidence. In June 2005 the partnership abandoned preparations for Fund V; active investments continued under remaining partners after Medved and Eisenberg left. A later report described roughly 60% paper write-off and negative 13% ROI at end-2011. These are dated interim reports, not a final audited liquidation, DPI, TVPI, or Eisenberg personal return. [contemporaneous record | moderate] Fund V abandonment CalPERS 2005 snapshot and peer comparison 2011 reported mark
Case 11: Print Life
Freeze — 1999, immediately before committing to owned printing capacity. Eisenberg retrospectively says he invested in a company, rendered as “Print Life” in the transcript, that pioneered online photo books. The demand hypothesis—turn digital photographs into physical albums—was plausible. The decisive operating choice was vertical integration into printing facilities, which created fixed capacity and financing needs. Demand utilization, print gross margin, equipment obsolescence, contract-manufacturing quality, working capital, acquisition cost, runway, and the durability of late-1990s venture financing were unknown. The company identity has not been independently confirmed, so the date and facts beyond Eisenberg's account remain provisional. [retrospective witness | moderate] Human Founder episode 149
Mechanism, adverse packet, and terms. Owning production could improve quality, turnaround, and margin if demand filled the plants; outsourcing or a milestone-gated pilot would preserve capital and flexibility at the cost of control. The adverse packet was the mismatch between fixed operating capacity and a financing source that could close suddenly. Bubble-era capital availability was not evidence that future rounds would fund underutilized plants. Eisenberg says board and management did not pivot quickly enough, but the source does not disclose the investment vehicle, check, security, valuation, ownership, facility cost, utilization plan, burn, board vote, dissent, outsourcing analysis, reserves, creditor seniority, or stop thresholds. Responsibility is explicitly shared between board and management rather than placed solely on the founder, market, or Eisenberg. [retrospective witness | moderate] official Podbean episode route
Decision lab — stop before reading the outcome.
- Would you approve owned capacity then? Does evidenced demand justify a plant, or should production remain outsourced or milestone-gated?
- What would kill the deal? Which utilization, gross-margin, quality, runway, financing, or customer-concentration threshold stops construction or support?
- What ownership/terms fit the risk? What capex tranche, equipment security, board approval, outsourcing fallback, reserve, and wind-down protections are required?
- What evidence unlocks the next check? Which paid order volume, repeat purchase, unit margin, SLA, utilization, and committed-financing result qualifies?
Actual decision and outcome. The board and management committed to capital-intensive printing as the financing environment reversed. Eisenberg says they pivoted too slowly; the company did not become the category standard, layoffs followed, and an executive he had recruited from a secure role was affected. He uses the case to argue that boards must know whether the business model depends on continually available capital and must account for the human cost of layoffs. No corporate filing, shutdown date, creditor recovery, severance ledger, total loss, vehicle attribution, or later formal process change was located. The case is strong evidence of an admitted decision error and empathy lesson, but weak evidence of investment economics. [retrospective witness | moderate] Human Founder canonical episode
Case 12: MemLink
Freeze — May 2002. MemLink, founded in 1999, was developing 3D MEMS optical switches. Israel Seed participated in a reported $3m seed and a $21m 2000 round at a $60m post-money valuation. By January 2002 management said engineering tests had worked, but carrier trials and commercialization would require another $30m–$40m after $18m had already been raised. Existing shareholders had supplied more than $5m in late 2001; in May 2002 Israel Seed, Lucent Venture Partners, Redwood, and Oak supplied a further $6m bridge, while Nisko, Aurum, and Southwestern Bell declined. The packet therefore contains technical progress and a potentially important telecom application, but no completed carrier validation, purchase commitments, commercial revenue, or funded path to the next milestone. [contemporaneous record | moderate] Globes, seed and 2000 financing Globes, January 2002 capital requirement
Mechanism, alternatives, and adverse packet. If the mirror architecture produced reliable high-capacity optical switching, patents, integration knowledge, and carrier qualification could create a defensible component position. The adverse mechanism was equally visible: long qualification cycles, telecom-customer concentration, expensive fabrication and testing, incumbent alternatives, and a funding environment already damaged by the telecom collapse. An additional bridge could preserve option value only if it bought a measurable carrier or strategic milestone; otherwise it could merely finance elapsed time. Selling the technology, narrowing the product, partnering with an equipment maker, or stopping before the bridge were live alternatives. [researcher inference | strong]
Terms, people, and governance known then. Israel Seed was one member of a multi-investor syndicate and joined the bridge. The public record does not expose Israel Seed's check allocation, security, ownership, board seat, liquidation preference, bridge seniority, voting record, milestone conditions, reserves, or the founders' and carriers' commitments. Lucent's participation was informative but not proof of purchase intent. Attribution belongs to the Israel Seed team and syndicate unless a source identifies an individual act. [documented behavior | moderate]
Decision lab — stop before reading the outcome.
- Would you invest or continue? Does the bridge buy a carrier-qualified inflection, or only another fundraising window?
- What kills the deal? Which carrier-test failure, financing shortfall, fabrication yield, cycle-time, or customer-concentration result requires stopping?
- What ownership/terms fit? What bridge seniority, milestone tranches, strategic rights, board control, downside sale process, and reserve limit compensate for the financing dependency?
- What evidence unlocks the next check? Which named carrier trial, paid commitment, test result, equipment-partner term sheet, burn reduction, and fully funded commercialization plan must arrive?
Actual decision and outcome — reveal only after locking the worksheet. The syndicate funded the bridge. By September 2002 a contemporary report said reserves were almost exhausted, most employees had been laid off, and the planned outside round had not closed; MemLink shut thereafter. A January 2003 Eisenberg interview described the company as closing while material cash remained. Those accounts conflict and may reflect timing, committed versus unrestricted cash, or a choice to preserve residual value; the record does not resolve the discrepancy. No wind-down ledger, asset-sale proceeds, creditor recovery, or Israel Seed distribution was located. The supported result is a company shutdown after failed financing, not a quantified fund loss. [contemporaneous record | moderate] Globes, September 2002 Globes, January 2003 retrospective
Case 13: Foxcom Wireless / MobileAccess
Freeze — January 2003. In a portfolio-triage interview, Eisenberg placed Foxcom among Israel Seed companies that had nearly closed but had unexpectedly recovered. At this cutoff the public packet supports distress and survival, not the reason for either. It contains no reliable current revenue, customer concentration, cash balance, bridge terms, product milestone, strategic offer, or management-change record. Treating the recovery itself as proof of a good continuation decision would import hindsight. [retrospective witness | provisional] Globes, January 2003
Mechanism, alternatives, and adverse packet. Foxcom/MobileAccess developed in-building wireless infrastructure. A plausible mechanism was that difficult deployment, radio-frequency integration, and carrier/enterprise acceptance could create a valuable installed-base position as indoor connectivity demand rose. The adverse case was capital-intensive hardware, long enterprise/carrier cycles, technology substitution, channel dependency, and the possibility that a rescue round would only defer closure. Alternatives included a narrow product focus, licensing or strategic partnership, a sale of technology, a controlled wind-down, or continued independent financing. The located record cannot establish which was considered. [researcher inference | moderate]
Terms, people, and governance known then. Israel Seed's portfolio association is supported; the investment vehicle, check size, ownership, board representation, follow-on amount, rescue participants, seniority, and partner vote are not. Later reporting identifies Foxcom Wireless as the corporate predecessor of MobileAccess, but does not reconstruct the recapitalization. This is a team/vehicle case, not evidence of Eisenberg's sole decision. [documented behavior | moderate] Techtime, corporate lineage
Decision lab — stop before reading the outcome.
- Would you invest or continue? Is there customer evidence that makes survival more valuable than conserving the remaining fund reserve?
- What kills the deal? Which bookings, gross-margin, deployment-time, cash-runway, technology-roadmap, or channel result ends support?
- What ownership/terms fit? What recap ownership, seniority, board rights, management conditions, sale rights, and syndicate commitments are required?
- What evidence unlocks the next check? Which signed deployments, renewal or expansion orders, strategic-partner support, unit economics, and fully funded operating plan must be verified?
Actual decision and outcome — reveal only after locking the worksheet. Foxcom survived and became MobileAccess. By July 2004 Globes reported approximately $20m of sales. Corning announced that it completed its acquisition of MobileAccess on March 2, 2011. Neither the official acquisition notice nor the located reporting discloses the consideration allocation, Israel Seed's retained ownership, interim dilution, sales, distributions, or net return. Foxcom is therefore a reversal control against outcome bias, not a documented loss and not a documented fund home run. [documented behavior | moderate] Globes, July 2004 portfolio retrospective Corning, completed acquisition
Case 14: Tradeum
Freeze — March 8, 2000, before accepting the acquisition consideration. Israel Seed had led a greater-than-$3m first round in 1999 in Tradeum, which offered XML-based software and services for business-to-business exchanges. The original packet emphasized standardization, first-mover advantage, strategic co-investors, and a large third-party forecast for B2B commerce. VerticalNet then agreed to acquire Tradeum for two million VerticalNet shares valued at approximately $474m on announcement. Tradeum had not yet begun commercial product sales. The proposed exit therefore converted private product and financing risk into concentrated public-company price, lockup, and realization risk. [contemporaneous record | moderate] Globes, August 1999 financing Globes, March 2000 acquisition
Mechanism, alternatives, and adverse packet. Shared data standards and exchange software could have become infrastructure for a large new market; strategic distribution through VerticalNet could accelerate that outcome. The adverse packet was the absence of product revenue, a consideration value driven by the buyer's extraordinary public multiple, integration risk, and unknown restrictions on selling or distributing the shares. Alternatives were cash or mixed consideration, hedging if permitted, prompt distribution after lockup, staged consideration, or remaining independent. The sources do not reveal bargaining power or whether these alternatives were available. [researcher inference | strong]
Terms, people, and governance known then. Israel Seed led the early financing, but the exact vehicle allocation, ownership at sale, exchange ratio by holder, lockup, registration rights, hedging limits, board approval, tax constraints, sale plan, and LP distribution policy are missing. The transaction and realization decisions belong to the fund/team; Eisenberg's individual vote and economics are not established. [documented behavior | moderate]
Decision lab — stop before reading the outcome.
- Would you accept the transaction? Does strategic acceleration justify exchanging a pre-revenue company for concentrated buyer stock at a bubble-era valuation?
- What kills the deal? Which buyer cash-burn, stock-volatility, integration, customer, lockup, or financing condition requires cash, protection, or rejection?
- What ownership/terms fit? What cash component, collar, registration right, escrow, earn-out, hedging permission, or mandatory distribution rule protects realization?
- What evidence unlocks the next check? Which buyer runway, audited backlog, integration plan, legal sale window, tax analysis, and board-approved disposition schedule must be known?
Actual decision and outcome — reveal only after locking the worksheet. VerticalNet completed the stock deal. By March 2001 its market value had fallen more than 99%; Jonathan Medved said Israel Seed had not exited optimally but still described the return on its early investment as extraordinary. VerticalNet cut about half the former Tradeum staff in April 2001 and shut the Jerusalem branch in October. A 2004 retrospective said the headline value had largely disappeared before realization. Both descriptions can coexist if only part of the position was monetized. Exact Israel Seed shares, lockups, sales, distributions, and cash proceeds remain absent, so neither the $474m headline nor a zero is an acceptable fund-return figure. [contemporaneous record | provisional] Globes, March 2001 Globes, April 2001 Globes, October 2001 Globes, July 2004
Case 15: WeWork
Freeze — continuation/re-underwriting checkpoint, September 18, 2017; initial 2012 investment packet unavailable. The bull packet held that large enterprises would outsource office operations as they had outsourced computing, allowing WeWork to gain scale and sell adjacent services. Eisenberg was publicly associated with sourcing or championing the opportunity for Benchmark; a 2017 profile described him as a board member or observer. The same-day adverse packet was already unusually explicit: WeWork assumed leases lasting up to 15–20 years while customers could rent monthly, and Regus supplied a prior downturn failure pattern. The packet did not disclose Benchmark's cost, current ownership, reserves, internal dissent, lease stress tests, related-party controls, or Eisenberg's formal voting authority. [contemporaneous record | moderate] Wired, thesis and structural risk The Commentator, reported involvement
Mechanism, alternatives, and adverse packet. Demand for flexible space and outsourced workplace services could be real while the enterprise remained financially fragile. The central mechanism was a duration transformation funded by repeated equity and debt: long fixed lease obligations supported short, cyclical customer commitments. Scale might improve purchasing and brand economics, but it could also multiply correlated lease exposure faster than contribution profit. Alternatives included slower city expansion, management contracts, landlord risk sharing, longer customer commitments, franchise structures, lower leverage, or a staged capital plan. [researcher inference | strong]
Terms, people, and governance known then. Benchmark was an early investor, but official records identify Benchmark founder Bruce Dunlevie as its director from 2012. Eisenberg's reported observer or participant role must not be upgraded into the fund's formal board seat. Benchmark's follow-ons, liquidation rights, sales, distributions, and lifetime cash result are unknown. Governance is a team and board question; sourcing does not establish unilateral control. [documented behavior | strong] WeWork 2023 proxy, board tenure
Decision lab — stop before reading the outcome.
- Would you invest or continue? Is enterprise demand sufficient when a recession can widen the lease/customer duration gap faster than scale lowers costs?
- What kills the deal? Which occupancy, location contribution, lease-adjusted cash burn, covenant, related-party, founder-control, or recession-stress result ends support?
- What ownership/terms fit? What board independence, founder-vote limits, related-party approval, lease-duration caps, tranche gates, and capital-reserve rights are required?
- What evidence unlocks the next check? Which mature-city cash flow, cohort occupancy, enterprise retention, lease stress test, audited related-party schedule, and downside financing plan must be verified?
Actual decision and outcome — reveal only after locking the worksheet. The 2019 S-1 disclosed mounting losses, long lease obligations, related-party transactions, and founder-control risks. Adam Neumann stepped down as CEO in September 2019; the company's announcement again identified Dunlevie as the Benchmark director. WeWork filed Chapter 11 on November 6, 2023, with pre-existing equity slated for cancellation without a distribution. That establishes severe company and old-equity impairment, not Benchmark's lifetime return or Eisenberg's personal loss. [documented behavior | strong] In 2021 Eisenberg said the market opportunity had been real but that valuation and momentum could not replace board oversight; that is a retrospective lesson, not evidence of a specific control adopted or an intervention that would have succeeded. [retrospective witness | moderate] SEC S-1 WeWork leadership announcement SEC Chapter 11 8-K 20VC episode
Case 16: Frank
Freeze — follow-on/governance/M&A-readiness checkpoint, November 10, 2020; initial 2017 seed packet unavailable. Aleph led Frank's reported $5.5m 2017 seed, participated in a $10m 2018 Series A, and was reported among early investors joining a further $5m financing in April 2020. Frank promised to simplify FAFSA and help students obtain more aid; Eisenberg included it in an Aleph portfolio argument about expanding education access. The decision-time evidence located publicly consists largely of company-reported user and aid claims, not an independently audited metric definition. By November 2020 the FTC had issued a warning letter saying Frank may have misled consumers about CARES Act relief and a cash-advance product, including fee and repayment representations. A warning letter is a regulatory signal, not an adjudication. [contemporaneous record | strong] TechCrunch, 2018 financing Crunchbase News, 2018 Series A TechCrunch, 2020 financing FTC warning letter
Mechanism, alternatives, and adverse packet. A simpler financial-aid workflow could reduce administrative friction, build trusted student distribution, and enable adjacent services. The adverse mechanism was mission-driven marketing outrunning substantiated claims in a regulated consumer-finance setting. User definitions, aid attribution, complaint rates, disclosure quality, fee economics, data provenance, and regulatory issue tracking were decision variables, not back-office details. After the warning, alternatives included pausing claims and growth, independent data and compliance audits, board-supervised remediation, management changes, or refusing further support or a sale until controls were verified. [researcher inference | strong] FTC explanation
Terms, people, and governance known then. The public record supports Aleph financings and a portfolio association; it does not establish Aleph's ownership, board seat at each date, reserve decisions, audit access, internal response to the FTC letter, metric-verification work, or any individual's knowledge. Founder and executive conduct must not be imputed to an investor without evidence. [documented behavior | moderate] Aleph, portfolio framing
Decision lab — stop before reading the outcome.
- Would you continue after the warning? Is the issue remediable marketing/compliance weakness, or evidence that reported traction cannot yet be trusted?
- What kills the deal? Which unreproducible user count, aid attribution, complaint, regulatory nonresponse, fee disclosure, or management-integrity finding requires a stop?
- What ownership/terms fit? What audit right, board compliance committee, representation, escrow, indemnity, data-room certification, and holdback is necessary before follow-on or sale?
- What evidence unlocks the next check? Which independently reproduced user table, raw-record sample, regulator correspondence, corrected disclosures, complaint analysis, and signed remediation attestation must be obtained?
Actual decision and outcome — reveal only after locking the worksheet. JPMorgan acquired Frank in 2021 for a reported $175m and later shut it after discovering fabricated customer data. In 2023 the SEC alleged that founder Charlie Javice had represented approximately 4.25m users when the company had fewer than 300,000. The status later advanced from allegation: after trial, Javice and Olivier Amar were convicted of conspiracy, wire fraud, bank fraud, and securities fraud; in September 2025 Javice was sentenced to 85 months. [contemporaneous record | strong] Those adjudications concern founder/executive conduct and do not establish Aleph or Eisenberg knowledge or participation. In April 2026 JPMorgan separately sued early holders including Aleph entities under a support-agreement theory; Aleph disputes the contractual claim, which remained unresolved at the cutoff. [contemporaneous record | moderate] Acquisition proceeds, escrow, distributions, current exposure, and net Aleph return are unknown. SEC, 2023 complaint announcement DOJ, conviction and sentence CTech, April 2026 dispute redacted complaint mirror
Case 17: GuruNet
Freeze — October 12, 1999, at the third-round decision. Eisenberg said Israel Seed had passed on GuruNet twice, attributing the misses partly to deal-flow overload and a tendency to look for reasons to reject when founders challenged the fund. The firm was now considering or making a reported $2m third-round investment because it believed the business model had become right. At this cutoff the packet supports a changed investor judgment; it does not supply the first two plans, the revised model, revenue, usage, unit economics, valuation, ownership, or the precise falsifying evidence that caused the reversal. [contemporaneous record | moderate] Globes, October 1999
Mechanism, alternatives, and adverse packet. GuruNet sought to answer users' questions through software and online reference content, a path later associated with Answers Corporation. A reusable query/content system could compound through product use and distribution. The adverse packet was more fundamental: the earlier model had twice failed the fund's test, the revised evidence is not preserved, and screening overload or interpersonal friction may have distorted judgment in either direction. Alternatives were invest, pass permanently, run a small evidence-gated check, or issue a dated pass memo with explicit re-entry conditions. [researcher inference | moderate]
Terms, people, and governance known then. The reported $2m belongs to Israel Seed; vehicle, allocation, security, valuation, ownership, board rights, reserves, and partner vote are not reported. Eisenberg's description supports involvement in the screening history, not sole authority over the investment or later outcome. [documented behavior | moderate]
Decision lab — stop before reading the outcome.
- Would you invest now? Does the third version resolve a falsified business-model problem, or is the reversal driven by fear of missing out?
- What kills the deal? Which repeat-use, answer-quality, acquisition-cost, content-rights, monetization, founder-cooperation, or runway result ends support?
- What ownership/terms fit? What evidence-gated tranche, board information right, ownership target, reserve cap, and founder/investor working agreement fits a twice-passed opportunity?
- What evidence unlocks the next check? Which documented model change, cohort usage, monetization test, distribution proof, and prewritten re-entry condition must be satisfied?
Actual decision and outcome — reveal only after locking the worksheet. Israel Seed entered in the third round. GuruNet raised $11.75m in its October 2004 IPO; reporting put Israel Seed at 11.4% before and 4.4% after the offering, with no shares sold in the IPO. The company later became Answers Corporation; its SEC filing confirms the IPO and business evolution. The record does not disclose the earlier round terms, subsequent sales, distributions, or lifetime fund proceeds. This is a recoverable miss and process-reversal case, not a clean anti-portfolio win. [documented behavior | moderate] Globes, October 2004 IPO Answers 2007 10-K
Portfolio forensics — compact tail findings
The association ledger is a map of companies, vehicles, and public events, not a return series. A financing, IPO, acquisition, shutdown, or current valuation cannot by itself establish cost basis, dilution, sale timing, distributions, fees, carry, or net LP return. [researcher inference | strong]
Cross-vehicle structure and observed patterns
These are patterns in the discovered public union, not measured career frequencies. Missing checks, failed companies, private marks, and historical portfolio removals prevent rate calculations. [researcher inference | strong]
| Dimension | What the 123-row union supports | What remains unknown / prohibited inference |
|---|---|---|
| Stage | Israel Seed and the dedicated Benchmark vehicles were described as seed/early-stage; Aleph publicly presents an early-investment model. Selected rows show seed through Series B entry and later follow-ons. | No complete stage-coded census, initial-versus-follow-on split, or stage hit rate. |
| Sector | The observed sequence shifts from Internet/security/telecom and optical components toward software, marketplaces, fintech/insurance, health, logistics, and applied data/AI. | Page labels are inconsistent; no sector allocation or return contribution is computable. |
| Geography | The repeat pattern is Israeli or Israel-connected formation with US/global customers, capital, management, listings, and acquirers. | Domicile, founder nationality, operating center, and fund mandate are not interchangeable. |
| Check / ownership | Public filings expose only selected round totals, security fragments, and eleven partial governance/security reconstructions. Eisenberg later said Aleph seeks meaningful early ownership and rarely relies on pro rata. | A round total does not establish any investor-specific check; a fund holding is not personal ownership; no median check or ownership statistic is supportable. |
| Follow-on / reserves | Shopping.com, Wix, Lemonade, Freightos, Healthy.io, Frank, MemLink, and other selected cases show follow-ons or bridges. Israel Seed IV makes reserve sufficiency central. | Publicly visible follow-ons are survivor- and news-biased; no reserve ratio or follow-on success rate is supportable. |
| Governance | Filed/direct evidence establishes selected director, observer, voting-power, recruiting, and transaction roles; the function matrix above assigns only named acts. | Sourcing does not imply IC control; observer status differs from the formal WeWork board seat held by Dunlevie; board presence does not transfer founder execution. |
| Outcome / realization | The union deliberately retains private, public, acquired, ceased, shutdown, distressed, and disputed paths. Windward, Shopping.com, Wix, WeWork, Frank, Tradeum, and Israel Seed IV show why status and security form matter. | IPO/acquisition value is not DPI; shutdown is not quantified loss; current valuation is not realization; no win/loss rate or career multiple is computable. |
The adverse tail sharpens six reusable controls:
| Control | Cases | Supported use | Prohibited shortcut |
|---|---|---|---|
| Financing-to-milestone survival | MemLink; Foxcom | Compare what a bridge actually buys and use a recovery case as the shutdown control | Calling all distressed bridges irrational after seeing which company survived |
| Company selection versus realization | Tradeum | Underwrite stock consideration, lockups, and disposition as a second investment decision | Treating announcement value as cash returned, or later collapse as proof of zero proceeds |
| Demand versus balance-sheet structure | WeWork | Stress fixed obligations, customer duration, governance, and capital availability separately from market demand | Inferring Benchmark's loss from WeWork's bankruptcy or assigning Dunlevie's board authority to Eisenberg |
| Mission versus metric provenance | Frank | Require independently reproducible metrics and regulator-issue controls before follow-on or sale | Imputing adjudicated founder fraud to Aleph, or treating an FTC warning as a final finding |
| Pass quality and reversibility | GuruNet | Record falsifiable re-entry conditions and distinguish model change from fear of missing out | Scoring an early pass as wrong merely because the later company went public |
| Vehicle/team attribution | All six | Credit a named individual only for sourced acts; retain fund and syndicate boundaries | Converting portfolio association, sourcing, or observer status into sole decision or personal economics |
Cross-case inference. [researcher inference | strong] The common failure surface is not simply picking the wrong market. It is a mismatch between the next operational milestone and the capital, governance, duration, data integrity, or realization mechanism available to reach it. That claim is a transfer test to run on other cases, not a statement of Eisenberg's formal playbook.
Adverse and miss postmortems — compact map
| Case or lead | Supported status | Best no-hindsight cutoff | Principal unresolved boundary |
|---|---|---|---|
| Israel Seed IV / no Fund V | Negative dated marks and abandoned Fund V preparation; active portfolio management continued | December 2001 reserve/pacing decision | Final audited DPI/TVPI, liquidation, partner attribution, and vintage-versus-manager decomposition |
| Print Life | Eisenberg's retrospective admission of board/management error around capital-intensive photo printing | Before committing to owned printing capacity | Corporate identity, check, runway, board record, and recovery |
| MemLink | Shutdown after repeated financing and failed outside round | May 2002 bridge | Milestone gates, bridge terms, wind-down cash conflict, and recovery |
| Foxcom/MobileAccess | Near-closure followed by revenue and completed strategic acquisition | January 2003 continuation | Rescue trigger, recap table, sale consideration, and fund proceeds |
| Tradeum | Stock exit followed by buyer-price collapse and operational shutdown | March 2000 consideration choice | Lockup, sales, distributions, and realized fund value |
| WeWork | Real demand thesis plus visible duration risk; later governance crisis and Chapter 11 | September 2017 | Benchmark cost, follow-ons, distributions, Eisenberg authority, and causal effect of possible interventions |
| Frank | Public pre-sale compliance signal; later adjudicated founder fraud; unresolved holder contract dispute | November 2020 after FTC warning | Aleph board role, metric audit, regulator response, proceeds, escrow, and 2026 case disposition |
| GuruNet | Two passes followed by a third-round investment and IPO | October 1999 re-entry | Early memos, model changes, terms, and proceeds |
| Earthnoise / Alchemedia | Shutdown/customer-list sale and salvage merger fragments | Not yet lab-ready | Original thesis, capital, role, consideration, and recovery |
| Unnamed post-2023 shutdown | Eisenberg's philosophy account of recommending closure | Not case-ready | Company identity, capital, decision record, and outcome |
| Paragon dispute | Unresolved defamation/communications proceeding; not a portfolio failure | Not yet investment-lab eligible | Pleadings, rulings, commercial-conflict facts, and final disposition |
The adverse map keeps four legal/economic states distinct: a public warning is not adjudication; a complaint is an allegation until resolved; a founder's conviction does not establish investor participation; and a company event does not establish a fund's cash return. Paragon should remain a communications/conflict-control lead outside the investment-case sequence unless a verified portfolio link and final procedural record emerge. [researcher inference | strong] Ynet, latest located Paragon procedure
Uncertainty and retrieval ledger
| Priority | Missing record | Best legitimate retrieval route | What it would resolve | Current use boundary |
|---|---|---|---|---|
| 1 | Israel Seed IV final audited statements, capital account, liquidation and LP distributions | CalPERS private-equity records; fund administrator or LP archive; Israeli partnership filings | Final DPI/TVPI and whether interim negative marks recovered | Use dated marks only; never call them final return |
| 2 | MemLink bridge documents, board minutes, carrier trials, and wind-down ledger | Israeli corporate file; insolvency/liquidator record; former directors/investors; surviving patent assignments | What the bridge bought, why financing failed, and whether cash remained | Call a shutdown, not a quantified fund loss |
| 3 | Foxcom/MobileAccess recap and Corning merger consideration table | Israeli corporate filings; Corning purchase accounting; merger materials; former CFO/investor records | Rescue mechanism, dilution, holder consideration, and Israel Seed proceeds | Use only as recovery/reversal control |
| 4 | Tradeum exchange, lockup, registration, sale, and LP-distribution records | VerticalNet merger filings and exhibits; Israel Seed LP reports; transfer-agent records | Paper value versus monetized value and timing | Preserve the conflict between exceptional return and evaporated headline |
| 5 | Benchmark WeWork memo, follow-on schedule, observer rights, board materials, sales and distributions | Benchmark/LP records; WeWork financing and board documents; bankruptcy claims and security ledgers | Eisenberg's actual authority, governance actions, and vehicle economics | Company bankruptcy cannot establish Benchmark lifetime return |
| 6 | Frank cap table, Aleph board role, data-audit files, FTC response, support agreement, escrow and current docket | Delaware and New York court dockets; FTC correspondence; JPMorgan acquisition exhibits; board and fund records | Control response, proceeds, contractual exposure, and final disposition | Separate Javice/Amar adjudication from unresolved Aleph contract allegations |
| 7 | GuruNet first two plans/pass memos, third-round term sheet, ownership history and distributions | Israel Seed archive; founder/board files; GuruNet/Answers registration statements and holder records | Whether the model truly changed and the economics of delayed entry | Call it a recoverable miss, not a clean anti-portfolio win |
| 8 | Print Life legal identity and corporate file | Original episode producer/guest confirmation; Israel company registry; 1999 photo-printing trade press | Entity, team, financing, facilities, shutdown and recovery | Use only as a retrospective philosophy/postmortem account |
| 9 | Earthnoise and Alchemedia transaction documents | Israeli registry; CastUP and Finjan filings; former investor/company records | Customer-list and merger consideration, governance and recovery | Keep as salvage leads, not losses or exits |
| 10 | Paragon pleadings, interim rulings, conflict disclosures and final judgment/settlement | Israeli court file and party-authenticated pleadings | Procedural status, truth/privilege findings, motive and damages | Describe party contentions only; exclude from investment performance |
Retrieval stop rule. A new source changes a case only if it improves one of four fields: decision-time evidence, mechanism and kill criteria, contractual/governance attribution, or cash realization. Additional copies of the same financing or acquisition announcement do not increase confidence. [researcher inference | strong]
Coverage and evidence base
This corpus contains 35 priority written routes and 35 source notes. The access denominator below follows what was actually retrievable on 2026-08-22, not the more optimistic discovery status recorded during SCOUT.
| Status | Count | Treatment |
|---|---|---|
| Fully readable | 26 | Full bodies were processed with the source’s available headings, paragraphs, printed pages, or PDF pages. |
| Partially readable and substantively analyzed | 7 | Only the publisher-visible paragraph(s), opening fragment, or book preview were analyzed; unavailable material was not reconstructed. |
| Entirely inaccessible/unrepresented | 0 | Every route has at least verified publisher metadata. |
| Substantively analyzed | 33 | Twenty-six full works plus seven partial works with meaningful body or preview text. |
| Metadata only; no body analysis | 2 | Melio and Announcing Aleph V are inventoried solely to their verified publication metadata. |
The seven partial but substantively analyzed items are:
- A Look Back at Our Letters to Our LPs and Capital Exuberance: only the byline/date and one opening paragraph are stable. They establish Eisenberg's annual-letter responsibility and named inspirations, not any excerpt, cycle warning, portfolio action, chart, or result. Canonical route
- Invest in Relationships, Not Transactions: only the byline/date and one introductory paragraph are stable. They establish an annual-LP-meeting setting and a concern with commoditized capital, not the absent relationship mechanism, examples, checklist, or endnotes. Canonical route
- Why We Decided to Drink the Lemonade: only the byline/date and one opening paragraph are stable. It supports a power-law premise and selected outlier examples, not the unavailable Team, Mission, Moats, Market, or Stage sections. Canonical route
- LMND — Aleph’s First IPO: only the title, byline/date, and one opening paragraph are stable. They support the firm-level first-IPO label and Eisenberg/Shochat's recalled 2013 global-brand and technology pitch, not later product, values, or return claims. Canonical route
- Empowering Others to RiseUp!: only two opening paragraphs are stable. They support the founder chronology and the anticipated objections about a nine-million-person market and lower-income subscriptions, not the unavailable investment decision, product, price, impact, expansion, or financing. Canonical route
- The Tree of Life and Prosperity: only the contents, preface excerpt, and the beginning of the “anchor and seven satellites” framework were available; chapters and the remainder of the framework were not analyzed. Publisher preview
- Be Long Israel. We Are.: first-party index metadata plus an opening fragment support only the byline/date, wartime timing, and firm-level statement that Aleph had been investing since October 7. No quote, deployment total, sector, vehicle, decision rule, or result is used. Canonical route
The two metadata-only items are Melio: Investing in Great People (verified title, byline, date, and URL; no stable body and no quotation) and Announcing Aleph V: Long Israel (verified 2026 title and URL; exact day, byline, body, fund size, close status, mandate, team, and portfolio unavailable). They are processed access records, not content analyses. Melio route Aleph V route
[researcher inference | strong] The accessible writings are rich in direct reasoning but weak as an economic record. Direct voice establishes what Eisenberg says he values; it does not establish audited outcomes, personal attribution, or causal effectiveness. The 35 routes are distinct works but are concentrated in Eisenberg/Aleph/Medium source families, so repeated claims across those routes increase corpus coverage, not independent corroboration. Search-index body text was discarded wherever a stable lawful publisher capture was unavailable. Israel Seed, Benchmark, and Aleph are separate institutions and vehicles. Meet Aleph is by Eden Shochat and remains Shochat-authored official firm evidence; Aleph III is signed by Aaron Rosenson, Eden Shochat, Michael Eisenberg, and Yael Elad. Full Healthy.io and Empathy essays are investor-authored narratives, while the limited Lemonade and RiseUp pages reveal only their openings and Melio reveals metadata only. WeWork's later bankruptcy and Frank's founder fraud show that a compelling humanity or values story cannot substitute for governance, unit economics, verification, or a portfolio denominator. Meet Aleph, byline and body WeWork Chapter 11 Form 8-K, Item 1.03 DOJ, Javice sentencing
Source-by-source analysis
1. Wake Up and Smell the Java: Israel Needs the Internet (2006)
- Argument and reasoning — [investor-stated | moderate]: Eisenberg treats bandwidth, tax law, corporate law, and internet skills as venture infrastructure. Asset-light internet firms could reach global markets with less fixed capital than subsidized industrial projects, but founders and headquarters would leave if Israel’s rules and connectivity lagged. The assumptions are that internet distribution materially lowers capital needs and that headquarters location transmits jobs, services, and tax revenue. Body paragraphs 1–9
- Evidence and decision rule — [investor-stated | provisional]: the essay uses contemporary rankings, asserted company migration, and comparisons with Tower Semiconductor and ECI rather than a complete dataset. The operational rule is to diligence the jurisdictional substrate and prefer capital-efficient digital businesses when distribution costs are falling; policy should remove bottlenecks before subsidizing yesterday’s architecture. Body paragraphs 2–9
- Biography, evolution, and limits — [investor-stated | moderate]: Eisenberg says he made the case to Prime Minister Ehud Olmert, showing early policy engagement. This 2006 substrate thesis becomes the cloud/talent argument of the Hummus series and the platform-complements logic of the 2025 AI essay. It supplies no deal, adoption scorecard, or cost-benefit analysis. Opening and closing
2. DooHickeys and MeTooHickeys (2006)
- Argument and reasoning — [investor-stated | strong]: cheap product creation expands entrepreneurship but also produces crowded “me-too” categories. A useful niche product may support a founder without being large enough to return a venture fund; favorable trend language is not differentiation. Body paragraphs 1–9
- Evidence and decision rule — [investor-stated | moderate]: Web 2.0 widgets and mobile applications are examples, not a cohort. Match financing type and pressure to plausible outcome scale: bootstrap a small utility and reserve institutional capital for a differentiated opportunity capable of a very large outcome. Test market size, barrier to entry, category crowding, and whether capital changes the attainable scale. Body paragraphs 4–11
- Biography, evolution, and limits — [researcher inference | moderate]: this Benchmark-era scale filter recurs in the full 2012 venture-industry checklist. The accessible RiseUp opening shows that founders anticipated a small-market objection but does not show that Aleph accepted an exception; Melio has no body evidence. The missing rule is how to preserve optionality when an apparently small tool may compound into a platform. Full essay Eight Things
3. Sarah Lacy, David Li and the Wrong Side of Historical Performance (2009)
- Argument and reasoning — [investor-stated | moderate]: trailing returns can invert the next opportunity because capital supply responds endogenously. Strong vintages attract LP money, competition, and valuations; weak vintages drive money away, potentially improving entry conditions for persistent founders and remaining investors. Body paragraphs 1–13
- Evidence and decision rule — [investor-stated | provisional]: David Li’s Gaussian-copula failure and Sarah Lacy’s Israel statistics are analogies and historical inputs, not proof of subsequent venture performance. The usable rule is to ask what the last return period did to current competition, price, founder quality, and capital availability before extrapolating it. Body paragraphs 1–22
- Biography, evolution, and limits — [contemporaneous record | moderate]: the 2009 bullishness is contemporaneous and identifies no commitment or company placed because of the call. The analogy can become unfalsifiable unless the next vintage is scored against a predeclared benchmark; the blocked 2022 retrospective cannot supply that score. Closing paragraphs
4. The Hummus Manifesto — Part 1 (2010)
- Argument and reasoning — [investor-stated | moderate]: Israel’s constraint was not startup quantity but scale capacity. Tiny teams dispersed scarce engineering talent, while government and military reliance on older stacks limited web-scale, cloud, open-source, and mobile experience; growing companies then struggled to recruit people who had built large systems. “We have a dearth of talent” and surrounding sections
- Evidence and decision rule — [investor-stated | provisional]: Conduit, Wix, a Google anecdote, the Lavi program, and Yozma are practitioner examples rather than a labor-market census. For diligence, map stack currency, senior scale experience, recruiting competition, and the ability to aggregate talent; do not infer ecosystem strength from seed-company counts. Full essay
- Biography, evolution, and limits — [contemporaneous record | moderate]: the essay converts portfolio-company hiring pain into national policy and anticipates Aleph’s later startup-to-scaleup service claim. Concentrating people in scaleups may improve execution but can suppress experimentation; no boundary tells an engineer when founding is socially inferior to joining. Full essay
5. The Hummus Manifesto — Part 2 (2010)
- Argument and reasoning — [investor-stated | moderate]: public capital should create new shared capability, not preserve firms or jobs that private investors rejected. Diffuse grants can mute market signals, impose bureaucracy, and hold talent in weaker activity; concentrated infrastructure and imported late-stage expertise can expand the opportunity set. Government-funding and late-stage sections
- Evidence and decision rule — [investor-stated | provisional]: Eisenberg says he advised portfolio CEOs to avoid Chief Scientist funding, with a capital-intensive exception, and cites the absence of newer multinational anchors and dedicated late-stage skill. Evaluate public money by additional capability, spillovers, and counterfactual private financing—not by dollars or jobs preserved. Full essay
- Biography, evolution, and limits — [contemporaneous record | moderate]: he includes his own firm among managers questioning dedicated Israel funds, a tension with the Israel-focused Aleph launch three years later. The policy critique also contains an investor conflict: subsidized capital can compete with private capital. No recipient/nonrecipient outcome comparison is supplied. Full essay
6. The Hummus Manifesto — Part 3 (2010)
- Argument and reasoning — [investor-stated | moderate]: Eisenberg proposes a long-tenure public investment function that concentrates Israel on a few distinctive capabilities while leaving company selection to entrepreneurs and private investors. Clusters in clean energy, cloud, agriculture, food, and water would attract anchors, suppliers, researchers, founders, and skilled labor. “Vision and Decision” and sector proposals
- Evidence and decision rule — [investor-stated | provisional]: Better Place, proposed demonstration infrastructure, cloud migration, and a large agriculture commitment are prospective examples. Define limited measurable capability goals, assign accountable long-horizon leadership, fund shared infrastructure, and separate national spillover from any one company’s survival. Full essay
- Biography, evolution, and limits — [investor-stated | moderate]: Eisenberg identifies himself as a New York immigrant and embeds economic strategy in civic and Jewish purpose. The proposed CIO concentrates authority while the essay also fears corruption and technical incompetence; continuity and capture are unresolved opposing risks. Full essay
7. An Open Letter to Zeev Holtzman (2011)
- Argument and reasoning — [investor-stated | moderate]: domestic fund formation is not the ecosystem health metric when global firms invest from main funds. Israel could shift from startup quantity to scale through international capital, experienced operators, acquisitions of small teams, and talent consolidation into companies capable of large outcomes. Scale-up and capital sections
- Evidence and decision rule — [investor-stated | provisional]: named investors, financings, Conduit/Wibya, Wix, PrimeSense, and a hiring anecdote form a contemporaneous inventory, not a census. Judge a fund or ecosystem by its ability to finance and staff large companies through scale and return meaningful capital to LPs, not by acquisition count or local fund closings. Full letter
- Biography, evolution, and limits — [contemporaneous record | moderate]: Eisenberg identifies Benchmark as his employer and himself as a Wix and Conduit director; firm and board association do not establish sole sourcing or economics. The optimism changes emphasis from Hummus Part 2’s pessimism without a documented causal update. Full letter
8. Hummus Manifesto Part 4 — It’s Amazon Stupid! (2011)
- Argument and reasoning — [investor-stated | moderate]: industrial incentives should be ranked by adjacent capability, not immediate capital expenditure or jobs. Amazon’s cloud, device, media, marketplace, and logistics platform could train engineers and enable many downstream businesses; Eisenberg argues this was more forward-looking than another incumbent semiconductor subsidy. Amazon-platform argument
- Evidence and decision rule — [investor-stated | provisional]: the ARM/mobile threat to Intel and prospective cloud/logistics spillovers are forecasts without quantified subsidy, tax, employment, supplier, or bargaining effects. Score an anchor by breadth, durability, strategic direction, dependency risk, and locally retained learning. Full essay
- Biography, evolution, and limits — [researcher inference | moderate]: the piece extends the cluster framework but conflicts with Part 3’s resistance to a national champion and, later, with the Big Tech scattering thesis. The reconciliation is platform-as-infrastructure rather than protected champion, yet dependence on one foreign platform remains real. Full essay
9. The Only 8 Things That Matter for Israel’s Venture Capital Industry (2012)
- Argument and reasoning — [investor-stated | strong]: mature venture should be judged by a small number of very large companies and exits, because ordinary acquisitions cannot return institutional funds. Ecosystem importance, company scale, and fund returns are distinct and require venture ownership. Central test and company lists
- Evidence and decision rule — [investor-stated | moderate]: an explicitly unscientific revenue screen produces eight names and later four additions; healthcare is excluded for lack of expertise. Start with credible scale and ownership, then model entry price, dilution, follow-ons, preferences, and realized cash before calling an outcome fund-returning. Lists, additions, and disclosure
- Biography, evolution, and limits — [contemporaneous record | moderate]: asterisks associate several companies with Benchmark, not Eisenberg personally. Expansion from eight to twelve reveals a changing watchlist; the omitted failures, early companies, healthcare, and ordinary outcomes make it unusable as a hit-rate denominator. Full essay
10. Connected Economics — The Threat — Part 1 (2013)
- Argument and reasoning — [investor-stated | moderate]: the internet is treated as a connected deflationary system: global labor, flexible staffing, software productivity, direct transactions, mobile work, global capital, and slow-moving government jointly weaken undifferentiated labor and physical intermediaries. “Five Premises” and subsequent sections
- Evidence and decision rule — [investor-stated | provisional]: US charts, platforms, and anecdotes are applied to Israel without causal isolation. Diligence differentiated skill, substitution/augmentation, property and lender exposure, jurisdictional mobility, and second-order tax effects; do not assume headcount is value creation. Full essay
- Biography, evolution, and limits — [investor-stated | moderate]: Eisenberg says the framework reached Prime Minister Benjamin Netanyahu and that he advised the Finance Ministry for 18–24 months; this is self-reported policy proximity. The platform/regime thinking later appears in adtech, Big Tech, and AI, but the essay overweights technological causality and under-models distribution. Opening and full essay
11. Meet Aleph: Our New $140 Million Venture Capital Fund (2013)
- Argument and reasoning — [contemporaneous record | strong]: Eden Shochat—not Eisenberg—announces Aleph as an equal partnership and service business for Israeli entrepreneurs building very large, scalable companies, initially at Series A. The title states $140 million; the body names Eisenberg and Shochat as founders and Bruce Dunlevie as special partner. Byline, title, and body
- Evidence and decision rule — [contemporaneous record | moderate]: this is an official launch statement, not audited commitments or a fund-construction document. Its operational proposition is service beyond capital; it contains no check range, ownership target, reserves, company count, voting rights, or performance test. Body paragraph
- Biography, evolution, and limits — [contemporaneous record | strong]: the page supports co-founding and an equal-partnership principle, not equal contribution to every deal or sole Eisenberg authorship. Later writings increasingly use Eisenberg’s personal voice, but firm doctrine and partner economics must not be inferred from them. Byline and body
12. Why We Are So Optimistic About Israel (2014)
- Argument and reasoning — [investor-stated | moderate]: optimism and resilience are presented as the entrepreneurial traits that let Israeli founders imagine better systems, improvise under constraint, and attack large global problems. National threat, solidarity, immigration, military/academic skill, and social trust are proposed as cultural inputs. Opening and founder examples
- Evidence and decision rule — [investor-stated | provisional]: MobileOCT, JoyTunes, OwnHealth, Freightos, and reported survey statistics are selected examples. Ask whether the founder can articulate a consequential future, persist through a named setback, assemble missing resources, and learn; national identity cannot replace product, market, or execution evidence. Named-founder examples
- Biography, evolution, and limits — [investor-stated | moderate]: Eisenberg describes roughly 20 years of investing and direct founder relationships. The essay shifts the earlier bottleneck story from skills and scale to temperament without reconciling their weights; resilience can be overconfidence unless paired with disconfirming milestones. Full essay
13. Why We Decided to Drink the Lemonade (2015)
- Argument and reasoning — [investor-stated | moderate]: the one stable opening paragraph frames venture capital as an outlier business in which a few companies and firms drive most returns. Facebook, Google, and Twitter are examples; the claim that one company can account for 30% of annual venture returns has no visible calculation, year, or dataset. Opening paragraph
- Evidence and decision rule — [investor-stated | provisional]: the recoverable rule is only to recognize outcome concentration; it does not explain the Lemonade decision. The title confirms a collective Aleph decision frame, but founder selection, matchmaking, mission, moat, market, stage, check, ownership, or results are not recoverable. Title and opening paragraph
- Biography, evolution, and limits — [contemporaneous record | moderate]: the signed 2015 page is ex-ante as to the later IPO, but its unavailable body prevents a deal-thesis scorecard. The separate S-1/A is an IPO-stage company control, not evidence for claims hidden behind the blocked Medium body. Lemonade S-1/A, Prospectus Summary
14. 2016 Prediction
- Argument and reasoning — [investor-stated | strong]: Eisenberg predicts impairment of at least one leading Israeli venture-backed adtech company because local funding remained exuberant while US financing, consumer acceptance, platform economics, and public comparables weakened. Aggressive private valuations and preferences could leave ordinary holders with little even after a sale. Prediction and evidence paragraphs
- Evidence and decision rule — [investor-stated | moderate]: Zirra estimates, press counts, and sector observations are approximate. Triangulate local financing against the leading market, platform control, customer behavior, public comparables, and the liquidation waterfall; rising capital can be a late-cycle warning rather than validation. Evidence and conclusion
- Biography, evolution, and limits — [contemporaneous record | moderate]: the dated call is scoreable, but the corpus lacks the objective year-end adjudication and complete forecast denominator. Read with the full 2009 scarcity essay, it shows Eisenberg treating capital supply as contextual rather than uniformly bullish or bearish; the blocked 2022 retrospective contributes no cycle claim. Full essay Sarah Lacy/David Li
15. Long Humanity (2018)
- Argument and reasoning — [investor-stated | moderate]: Eisenberg argues that social media and adtech made genuine connection, care, education, healing, and physical community scarcer; technology that restores those human needs could create the next investment cycle. Digital transactions remain valid, but attention extraction and manipulative advertising are disfavored. Body paragraphs 1–28
- Evidence and decision rule — [investor-stated | provisional]: WeWork, Nexar, JoyTunes, Lemonade, health, financial safety, and Frank illustrate the theme but do not prove causality or return. Prefer products whose repeated customer benefit builds agency/community and can support durable economics; reject models permanently dependent on manipulation, while measuring governance and unit economics separately. Portfolio examples and closing
- Biography, evolution, and limits — [documented behavior | strong]: WeWork’s 2023 bankruptcy shows that a valid human need does not validate leases, financing, governance, or company design. Frank’s later fraud outcome challenges values-based selection without implying Aleph knowledge. These are not footnotes: they materially reduce support for “humanity” as an investing edge. WeWork 8-K, Item 1.03 DOJ, Javice sentencing
16. Bad Blood, Good Urine, Great People! (2019)
- Argument and reasoning — [investor-stated | strong]: Healthy.io expands the criteria: learning-oriented, mission-driven outsiders can enter a regulated sector when a secular smartphone cost curve, software/data reuse, automation, standard components, and detailed regulatory learning support the fresh perspective. Body paragraphs 1–20
- Evidence and decision rule — [investor-stated | moderate]: Eisenberg cites regular visits, reimbursement/FDA learning, country/test counts, use cases, and approval, while Theranos-driven aversion reduced funding competition. Treat contrarian stigma as potential mispricing only after independent clinical, regulatory, product, and founder evidence survives; unfamiliarity is not itself an edge. Body paragraphs 7–23
- Biography, evolution, and limits — [investor-stated | strong]: he identifies this as his first digital-health investment and explicitly says the outcome was not yet knowable. The essay omits failed validation, false-positive/negative data, reimbursement outcomes, ownership, and rejected evidence; company claims about lives and savings remain unverified. Body paragraphs 5–24
17. Aleph III (2019)
- Argument and reasoning — [contemporaneous record | strong]: the announcement states a $200 million fund continuing to back ambitious Israeli founders building large global companies, with customer, follow-on-capital, talent, technology, and data support intended to accelerate startups into scaleups. Body paragraphs 1–3
- Evidence and decision rule — [investor-stated | provisional]: the four-paragraph fundraising statement provides no operating cases, check sizes, stage bands, reserves, ownership, portfolio count, fees, or performance. Treat the mandate as stated intent and require legal/offering records and outcomes before inferring continuity. Full announcement
- Biography, evolution, and limits — [contemporaneous record | strong]: Aaron, Eden, Michael, and Yael sign the announcement and credit the full team. It is direct evidence against sole-Eisenberg fund attribution. “Exactly the same” sits beside new technology/data support, leaving mandate continuity and operational evolution unresolved. Signatory block
18. LMND — Aleph’s First IPO (2020)
- Argument and reasoning — [investor-stated | moderate]: the opening recalls Eisenberg and Eden Shochat telling prospective LPs in 2013 that Aleph sought remarkable entrepreneurs building large, meaningful global brands and businesses, with machine learning, machine vision, and data as industry-change drivers. This is a 2020 recollection, not the original pitch. Opening paragraph
- Evidence and decision rule — [contemporaneous record | moderate]: the title labels Lemonade Aleph’s first IPO; the separate S-1/A provides an independent company snapshot. Treat an IPO as a checkpoint rather than proof of moat or fund return, and distinguish the recalled firm mandate from product claims unavailable in the article body. S-1/A, printed pp. 1–8
- Biography, evolution, and limits — [contemporaneous record | strong]: the opening jointly attributes the original pitch to Eisenberg and Shochat. It supplies no partner allocation, board role, cost basis, ownership, dilution, lockup, sale, or realized proceeds; company IPO value is not Aleph fund profit. Title and opening paragraph
19. Melio: Investing in Great People (2020)
- Access record — [contemporaneous record | insufficient public record]: a first-party publisher index verifies the title, Michael A. Eisenberg byline, 2020-09-14 date, and canonical URL. No stable lawful article-body capture or paragraph locator was available. Canonical route
- What can and cannot be learned — [researcher inference | insufficient public record]: “Investing in Great People” is verified title language, not an evidenced people-selection rule. Founder chronology, sourcing, financing, market, team formation, product-market fit, board role, ownership, and performance cannot be inferred, and no quotation is used. Canonical route
- Attribution and retrieval need — [researcher inference | insufficient public record]: metadata establishes Eisenberg’s authorship of a Melio-related essay, not that he personally sourced or led an Aleph investment. A lawful publisher export and contemporaneous vehicle records are required before any body, deal, or economics claim is restored. Canonical route
20. We All Need More Empathy in Our Lives and Deaths (2021)
- Argument and reasoning — [investor-stated | moderate]: Empathy applies Long Humanity to bereavement: software should reduce forms, bureaucracy, financial strain, and isolation while amplifying human care. Mission-product-founder alignment is treated as part of product quality in a trust-sensitive category. Body paragraphs 1–8
- Evidence and decision rule — [investor-stated | moderate]: Eisenberg’s decade-long relationship with Ron Gura, Gura’s prior company/eBay/WeWork/Aleph EIR experience, and familiarity with Yon Bergman support founder selection. In vulnerable markets, test whether conduct, privacy, pricing, support, and product design embody the stated mission—not merely whether the founders speak its language. Body paragraphs 3–8
- Biography, evolution, and limits — [investor-stated | provisional]: the idea matured through years of discussion, reinforcing relationship-led sourcing. The launch essay gives no market size, buyer, outcomes, economics, governance, or falsification test; long familiarity can supply behavioral evidence and familiarity bias simultaneously. Full essay
21. Children Are Growth (2021)
- Argument and reasoning — [investor-stated | moderate]: Eisenberg treats population as a source of labor, demand, specialization, invention, and long-horizon national confidence rather than only a resource burden. Fewer researchers can slow innovation; technology can let output outgrow population, while aging can weaken housing, tax, labor, and pension systems. Hebrew body and “On Optimism and Innovation”
- Evidence and decision rule — [investor-stated | provisional]: Jones’s model, aggregate output/population charts, Japan, Germany, Haredi integration, and immigration are selected comparisons. Underwrite change-oriented ventures and infrastructure for a growing society, but scenario-test housing, water, transport, education, labor participation, migration, and per-capita welfare. Full Hebrew essay
- Biography, evolution, and limits — [investor-stated | moderate]: Eisenberg identifies himself as a father of eight and an investor, making the thesis personally situated. Aggregate correlation does not isolate institutions or productivity, and optimism about children does not settle household autonomy or unequal public-service burdens. English summaries remain researcher translations. Full Hebrew essay
22. Big Tech Is a Modern Tower of Babel That Must Be Scattered (2021)
- Argument and reasoning — [investor-stated | moderate]: large platforms created connection and economic value but accumulated control over speech, identity, behavior, and cultural difference. Eisenberg’s “scatter” remedy is portable identity, keys, and social graphs that make exit credible and enable competing communities—not only corporate breakup. Body paragraphs 1–12
- Evidence and decision rule — [investor-stated | provisional]: Balaji Srinivasan’s crypto networks and Ben Thompson’s interoperability argument are proposals, not welfare evidence. Look for user custody and interoperable primitives while explicitly diligencing moderation, privacy leakage, spam, key recovery, child safety, and whether portability can overcome network effects. Body paragraphs 6–12
- Biography, evolution, and limits — [researcher inference | moderate]: the essay shows willingness to challenge incumbents despite their value creation. It also complicates the 2011 Amazon-anchor advocacy: an enabling platform can create national capability and later become a concentration risk. Architecture, competition, and moral legitimacy must be assessed over time. Full op-ed
23. The Tree of Life and Prosperity (2021)
- Argument and reasoning — [investor-stated | moderate]: the accessible preface treats ethics as an economic input that can create trust, reputation, identity, and durable value. Eisenberg explicitly says his specialization is people rather than technology or market prediction and admits that passion may have been retrospectively narrated as strategy. Preface excerpt
- Evidence and decision rule — [investor-stated | provisional]: visible material introduces an anchor of religious/humanist principle and the first portion of seven satellites for principled products, willingness to pay, and confidential trust. Treat founder character and value alignment as hypotheses to test through product behavior and stakeholder outcomes; do not infer unseen satellites or chapters. Preview headings and excerpt
- Biography, evolution, and limits — [investor-stated | strong]: Eisenberg links Rabbi Yehuda Amital, Torah study, political science, newspaper editing, and early investing uncertainty to his people-first lens. The preview is partial and cannot stand for the book; the self-critique is important counterevidence against portraying his process as fully systematic. Preface excerpt
24. Invest in Relationships, Not Transactions (2021)
- Argument and reasoning — [investor-stated | provisional]: the one stable introduction places Eisenberg at Aleph’s 2021 annual LP meeting and frames the period as one of “weaponized” or commoditized capital. The title signals a relationship preference, but the body needed to establish its mechanism is unavailable. Opening paragraph
- Evidence and decision rule — [investor-stated | insufficient public record]: the opening names Sam Lessin as a friend and influence but does not expose Lessin’s quotation or Eisenberg’s application. No early-stage/growth distinction, company example, founder checklist, board rule, or return evidence is recoverable. Opening paragraph
- Biography, evolution, and limits — [contemporaneous record | moderate]: the page supports an LP-strategy-writing role and topic, not a measured relationship edge. A lawful full body plus deal and pass denominators are needed before operational claims or performance implications can be attributed to this essay. Canonical page
25. Parashat Ki Tisa: The Golden Calf and Venture Capital Investments (2022)
- Argument and reasoning — [investor-stated | moderate]: uncertainty tempts founders and investors to demand premature, visible results. Early venture lacks mature sales, margin, and growth histories, so technology, regulation, markets, and leaders may need time; Healthy.io and Seeking Alpha illustrate persistence through external timing and slow model development. Body paragraphs 1–12
- Evidence and decision rule — [investor-stated | provisional]: Eisenberg says smartphone cameras/regulation delayed Healthy.io and that Seeking Alpha accelerated long after a 2006 investment through model change and mobile adoption. Stage capital against thesis milestones, preserve runway for learning, and do not equate slow progress with failure before testing whether the external gate is actually moving. Company examples
- Biography, evolution, and limits — [investor-stated | moderate]: he calls Seeking Alpha his first Benchmark investment, direct person-level testimony without economics. Both cases are survivor-selected and retrospective; patience without kill criteria can become escalation of commitment. Company examples and close
26. Empowering Others to RiseUp! (2022)
- Argument and reasoning — [investor-stated | moderate]: two visible opening paragraphs describe Yuval Samet brainstorming a company with Eisenberg, returning about a year later with Tamara Harel-Cohen and Iftach Bar, and expecting Aleph to reject a nine-million-person initial market and a subscription aimed at lower-income customers. Opening paragraphs
- Evidence and decision rule — [investor-stated | provisional]: the opening supplies relationship-led ideation and two presumed filters—market size and customer segment. It does not reveal Aleph’s answer, the investment decision, price, customer research, impact, expansion, financing, or return, so no accepted “local wedge” rule is inferred. Opening paragraphs
- Biography, evolution, and limits — [contemporaneous record | moderate]: Eisenberg names all three founders and recounts a multi-year chronology, but the retrospective does not show sole approval, deal leadership, vehicle, ownership, board role, or outcome. Canonical page
27. A Look Back at Our Letters to Our LPs and Capital Exuberance (2022)
- Argument and reasoning — [investor-stated | provisional]: the one stable opening paragraph says Eisenberg took responsibility for Aleph’s annual LP letter at the firm’s formation and names Warren Buffett and Jeff Bezos as inspirations. The cycle argument promised by the title is not visible. Opening paragraph
- Evidence and decision rule — [investor-stated | insufficient public record]: no selected letter excerpt, cycle warning, runway or revenue rule, financing policy, secondary rule, chart, company action, or return is recoverable. Neither the title nor unstable search-index text can supply them. Canonical page
- Biography, evolution, and limits — [contemporaneous record | moderate]: the opening supports Eisenberg’s recurring communication responsibility, not sole investment authority. Even a complete retrospective would be selected evidence; the full dated letters, omitted forecasts, contrary passages, actions, and fund results are required for a forecast or performance denominator. Opening paragraph
28. Milk, Honey and Uncertainty (2022)
- Argument and reasoning — [investor-stated | moderate]: the Hebrew book distinguishes calculable risk from unknowable futures. Under uncertainty, one acts through staged commitments aligned with mission and positive asymmetry: loss is bounded while a complete success can be enormous. PDF p. 47–49 / printed p. 48–50
- Evidence and decision rule — [investor-stated | provisional]: Bruce Dunlevie’s staircase analogy, biblical movement, family experience, and later rehabilitation discussion provide intellectual examples, not calibrated portfolio math. Decompose a large uncertain outcome into milestones, define the loss at each, preserve the option to continue, and do not require false probabilities before acting. PDF p. 47–49 and p. 269
- Biography, evolution, and limits — [investor-stated | moderate]: Eisenberg integrates family, faith, Benchmark mentorship, and venture practice. Positive asymmetry can obscure correlated bets, follow-ons, opportunity cost, dilution, and repeated small losses; the full Hebrew text is available, but English renderings require fluent review. Full PDF
29. Abraham, Wealth and Economic Fraternity (2022)
- Argument and reasoning — [investor-stated | moderate]: wealth is not separate from moral agency: Abraham’s resources enable teaching, protection, alliances, and nation building. Eisenberg prefers “fraternity”—networks, choice, capability, and ownership—to paternalistic transfer because another person’s economic agency can expand the whole system. “Economy of Fraternity”
- Evidence and decision rule — [investor-stated | provisional]: Abraham/Lot and Carnegie are normative contrasts, not controlled economic evidence. Ask whether capital leaves the recipient with skill, network, choice, ownership, and a route to independence; measure mobility rather than only money transferred. Full Hebrew op-ed
- Biography, evolution, and limits — [researcher inference | moderate]: the op-ed is a compact precursor to the later full covenantal-capitalism essay. Fraternity can exclude outsiders and hide investor power unless stakeholder scope, rights, and conflicts are explicit; no RiseUp or Wix mechanism is inferred from this op-ed. English descriptions are researcher translations. Full Hebrew op-ed
30. Be Long Israel. We Are. (2024)
- Access boundary — [contemporaneous record | insufficient public record]: verified publisher metadata supplies title, Eisenberg byline, 2024-02-14 date, three-minute label, and an opening fragment that attributes post-October-7 investment activity to Aleph. The body was unavailable and no quote, amount, sector, vehicle, pace, or causal claim is used. Canonical route
- What can and cannot be learned — [researcher inference | insufficient public record]: timing and firm-level wartime advocacy are supported; an Eisenberg personal allocation, “Long Israel” decision rule, or performance claim is not. Neighboring fund announcements and later essays cannot be substituted for the missing source. Canonical route
- Evolution and retrieval need — [researcher inference | insufficient public record]: the title appears consistent with long-running national optimism, but that semantic continuity is not content evidence. A lawful publisher export or archive capture must establish actual stage, sectors, deployment categories, and exceptions. Canonical route
31. Incorporate in Israel or Delaware? (2024)
- Argument and reasoning — [investor-stated | moderate]: Israeli incorporation is Eisenberg’s default because operating simplicity, employee options, legal treatment, tax/IP location, and national spillovers can align company and ecosystem interests; a concrete regulatory need can justify a US entity. Opening through final advice
- Evidence and decision rule — [investor-stated | provisional]: the Musk compensation ruling and a proposed state matching program are illustrations, not comparative domicile evidence. Ask counsel to name the exact commercial/regulatory reason for Delaware; if none survives, default to Israel, and condition public support on locally retained benefit. Body paragraphs
- Biography, evolution, and limits — [investor-stated | moderate]: Eisenberg claims more than 25 years of consistent preference but supplies no domicile denominator. He opposes state matching as anti-Darwinian, then proposes a local-incorporation condition if adopted—a coherent second-best position and a live tension between market selection and industrial policy. Full essay
32. Spreading Wealth Through Covenantal Capitalism (2024)
- Argument and reasoning — [investor-stated | strong]: prosperity belongs inside a moral project, but covenant obliges wealth to increase other people’s capability, ownership, mobility, and dignity. Private property and enterprise are retained while extractive debt and permanent dependency are rejected. PDF pp. 2–20 / printed pp. 54–72
- Evidence and decision rule — [investor-stated | moderate]: Abraham, Jonathan Sacks, Wix training, RiseUp, debt law, mentorship, and upward-income mobility form the argument. Diligence whether company revenue rises when customers become more capable; instrument board reporting around mobility, trust, ownership, and conflict rather than accepting a mission statement. “Contract or Covenant,” Wix/RiseUp, and “We Need New Thinking”
- Biography, evolution, and limits — [researcher inference | moderate]: this is the mature formal synthesis of the values/humanity line, but the favorable company examples are selected and no counterfactual treatment effects or returns are presented. Subscription alignment does not eliminate privacy, exclusion, retention, or pricing risk. Full essay
33. Introducing the Aleph AI Team (2025)
- Argument and reasoning — [investor-stated | moderate]: as foundation models commoditize, durable AI value must move to domain expertise, proprietary data, distribution, network effects, or integrated physical workflows. Fast growth without defensibility is an “AI meteor,” while capital may be necessary to construct hard complements. Author cross-post and canonical essay
- Evidence and decision rule — [investor-stated | provisional]: Aleph advertises up to $3 million at pre-seed for two- or three-person technical teams and a $10 million revenue objective within 18 months, while mentioning three unnamed marketplace investments. Identify the non-model advantage, its legal ownership, compounding loop, and why capital accelerates it; reject generic features despite early revenue. Canonical essay
- Biography, evolution, and limits — [researcher inference | moderate]: the thesis updates the 2006 internet and 2011 cloud platform logic: value shifts to complements when a layer commoditizes. Speed and moat building may conflict, “standard SAFE” is unspecified, and no cohort or mature outcome tests the program. Canonical essay
34. Building Israel’s Trillion-Dollar Economy (2025)
- Argument and reasoning — [investor-stated | moderate]: prior startup-nation engines will not by themselves double Israel’s nominal GDP. Debt service, war costs, productivity gaps, infrastructure delay, uneven participation, and bureaucracy require state operating discipline; finance, AI, infrastructure, and regional integration are proposed growth engines. Opening through fourth section
- Evidence and decision rule — [investor-stated | provisional]: market, defense, financing, GDP, and policy facts are cited, but the $1 trillion bridge is not modeled in real terms. Apply service levels, ROI, KPIs, deadlines, accountable owners, and selective rather than uniform cuts; scenario-test fiscal cost, distribution, regulation, geopolitical dependence, exchange rates, and real productivity. Second through fourth sections
- Biography, evolution, and limits — [investor-stated | moderate]: Eisenberg reports policy discussions and extends venture language to state management. The essay synthesizes two decades of scale/national-capability writing, but crypto, tax, welfare, and regional proposals are value-laden and uncosted; future Aleph investments cannot be inferred from policy advocacy. Full essay
35. Announcing Aleph V: Long Israel (2026)
- Access boundary — [contemporaneous record | insufficient public record]: a first-party publication index verifies the 2026 title and canonical URL. Exact day, byline, body, legal vehicle, fund size, target/final close, mandate, stage, geography, team, and portfolio were unavailable. Canonical route
- What can and cannot be learned — [researcher inference | insufficient public record]: the title permits only the existence of an Aleph V announcement with “Long Israel” branding. It does not support individual Eisenberg economics, a new strategy, continuity, deployment, or performance. Canonical route
- Evolution and retrieval need — [researcher inference | insufficient public record]: apparent continuity with Aleph III and wartime-national writing is a retrieval hypothesis, not a finding. A lawful body plus the relevant filing must distinguish offered amount, commitments, close status, AUM, and legal entities. Canonical route
Cross-source synthesis
Relationships are the claimed sourcing edge, but evidence must graduate
[investor-stated | moderate] Full Healthy.io and Empathy essays describe pre-investment learning, repeated contact, and an entrepreneur-in-residence relationship; RiseUp's two stable opening paragraphs add a multi-year founder-ideation chronology. The limited Relationships opening establishes only the 2021 annual-LP-meeting setting and Eisenberg's concern with commoditized capital. It does not expose the article's mechanism or examples, and the Lemonade and Melio bodies cannot be used. Healthy.io Empathy RiseUp opening
[researcher inference | moderate] The best operational reading is not “invest in friends.” A relationship is an information prior that must graduate into learning speed, recruiting pull, customer evidence, domain mastery, and ethical conduct. Otherwise the same closeness creates familiarity bias, insider access, price indiscipline, and reluctance to change leadership. The corpus supplies no pass denominator, founder-reference study, or comparison of relationship-led and auction-sourced outcomes.
Venture scale, power laws, and exceptions
[investor-stated | strong] From 2006 through 2012, Eisenberg repeatedly distinguishes a good small business from a venture-returning one and separates company importance from fund economics. The relevant outcome is not funding or acquisition count but enough company value, owned at a defensible basis, to return meaningful capital. DooHickeys Eight Things
[researcher inference | insufficient public record] The accessible record does not establish a later exception rule. Lemonade's stable opening supports only a power-law premise; RiseUp's opening shows founders anticipated a small-market objection, not why Aleph invested; Melio supplies metadata only. A defensible exception framework would require the missing memos or article bodies, including the violated rule, compensating evidence, scale milestones, and kill criteria. Lemonade opening RiseUp opening Melio metadata
Values and humanity are product theses, not proof of goodness or return
[investor-stated | strong] Long Humanity, the full Empathy essay, Abraham, and covenantal capitalism make a coherent claim: products can create economic value by increasing trust, dignity, agency, and customer capability. Alignment should appear in business-model and product behavior, not merely philanthropy. The partial Tree preview supports an ethics-and-trust premise but not the unseen framework; the RiseUp opening supports no product-impact claim. Long Humanity Empathy Covenantal Capitalism, printed pp. 54-72
[documented behavior | strong] WeWork and Frank make the necessary adverse pairing. WeWork satisfied a community narrative yet later entered bankruptcy; Frank appeared in the human-centered portfolio list, while its founder was later convicted and sentenced for fraud. Neither outcome proves that Eisenberg or Aleph knew of misconduct, and the Frank support-agreement dispute remains unresolved. They do prove that values language cannot replace verification, governance, capital structure, stakeholder protection, or downside control. WeWork 8-K, Item 1.03 DOJ sentencing release JPMorgan complaint mirror, allegations only
Cycle awareness is preparation, not timing
[investor-stated | moderate] The full 2009 scarcity essay and 2016 adtech prediction show capital supply changing opportunity in opposite directions depending on competition, entry price, platform economics, public comparables, and security terms. The 2022 LP-retrospective opening establishes Eisenberg's letter-writing responsibility and named inspirations only; it contributes no recoverable cycle policy. Sarah Lacy/David Li 2016 Prediction LP-retrospective opening
[researcher inference | moderate] A modern rule suggested by the two full essays is to treat financing conditions as an input, not a stop/go signal: model price, terms, underlying industry economics, and the cost of losing the next round. Runway, consumption, revenue-variance, secondary, or company-action rules remain unproven until the retrospective body and original letters are recovered.
Patience and uncertainty require explicit abandonment rules
[investor-stated | moderate] The Golden Calf essay and Milk, Honey and Uncertainty defend staged action when probabilities and mature metrics do not exist. External technology, regulation, and customer behavior may need time; one bounded step preserves the option to learn and a power-law winner can repay many failures. Golden Calf Milk, Honey and Uncertainty, printed pp. 48–50
[researcher inference | moderate] Patience is not evidence of correctness. Survivor-selected Healthy.io and Seeking Alpha examples do not reveal companies that consumed follow-on capital and failed. A usable version needs a milestone, budget, next learning event, external-gate evidence, and thesis-kill condition at each step.
National substrate and company selection are intertwined—but not identical
[investor-stated | strong] The 2006 internet essay, Hummus series, Holtzman letter, Connected Economics, Aleph launch, demographic/domicile essays, and trillion-dollar plan treat bandwidth, skills, immigration, global capital, law, taxation, defense/university knowledge, infrastructure, and state capacity as upstream venture inputs. Wake Up Java Hummus Part 1 Trillion-Dollar Economy
[researcher inference | moderate] This is a distinctive strength of the corpus: it notices complement systems before reducing opportunity to a company. It is also a risk. National advocacy can bias domicile, sector, founder, and holding decisions away from the best risk-adjusted LP choice; platform attraction can later become concentration; state coordination can become capture. Each investment memo should separate company return, fund return, ecosystem spillover, and national objective.
Platform shifts move value to scarce complements
[investor-stated | moderate] Internet distribution, cloud platforms, mobile cameras, direct customer interfaces, interoperable identity, and commoditizing AI models are one intellectual line. When the core layer becomes cheap, value moves to scarce talent, data, distribution, domain knowledge, workflows, physical integration, trust, or network effects. Connected Economics Healthy.io Aleph AI Team
[researcher inference | provisional] The moat categories are hypotheses, not permanent facts. Platform owners can appropriate complements; data rights can be weak; distribution can vanish; network effects can be local; fast revenue can come from a copyable feature. Diligence must identify the legal/technical compounding loop and simulate platform repricing or replication.
Intellectual chronology, evolution, and contradictions
- 2006 — substrate plus scale — [researcher inference | moderate]: Wake Up Java argues that digital infrastructure and rules shape opportunity; DooHickeys insists that lower creation cost does not make every product venture-scale. The durable tension—more experimentation versus scarce talent/capital—is already present. Java DooHickeys
- 2009 — capital-cycle contrarianism — [researcher inference | moderate]: weak trailing returns and capital withdrawal are reframed as potential forward opportunity. The later full 2016 adtech prediction shows the converse risk: abundant local funding can persist while platform economics and public comparables weaken. Sarah Lacy/David Li 2016 Prediction
- 2010–2013 — scale-up nation and intervention tension — [researcher inference | moderate]: Hummus diagnoses fragmented talent and obsolete capability, attacks diffuse subsidies, then proposes concentrated public coordination and foreign anchors. The Holtzman letter grows more optimistic about global capital; Connected Economics expands the view to labor, property, finance, and state lag. Market selection and industrial policy remain unresolved partners. Hummus series Connected Economics
- 2013 — institutionalization at Aleph — [contemporaneous record | strong]: Shochat’s launch announcement formalizes an equal partnership, Series A, and service-to-scaleups model. Later first-person essays should not erase that co-founded institutional design. Meet Aleph
- 2014–2016 — founder character and category avoidance — [researcher inference | moderate]: the full optimism essay turns national resilience into a founder-selection hypothesis, while the full adtech prediction shows category-level avoidance and cap-table concern. Lemonade's stable opening adds only a power-law premise, not a five-part thesis or rule exception. Optimistic About Israel Lemonade opening 2016 Prediction
- 2018–2020 — humanity, sector exception, and institutional attribution — [researcher inference | moderate]: Long Humanity adds a moral/product thesis; Healthy.io documents outsider learning and secular cost curves; the collectively signed Aleph III announcement restates firm continuity; the LMND title/opening records Aleph's first IPO and jointly recalls a 2013 Eisenberg-Shochat pitch. Melio supplies metadata only. WeWork's later bankruptcy exposes the gap between a resonant theme and company/governance quality. Long Humanity Healthy.io WeWork 8-K
- 2021–2022 — broader moral and uncertainty framework — [researcher inference | moderate]: the full Empathy, demographics, platform-power, patience, uncertainty, and biblical-economics works broaden the worldview. The partial Tree preface supplies the crucial self-critique that passion may be re-narrated as strategy. The Relationships and LP-retrospective openings do not establish the unavailable mechanisms, cycle rules, or a general systematization claim. Tree preview Empathy Milk, Honey and Uncertainty
- 2024–2026 — national commitment and AI complements — [researcher inference | provisional]: covenantal capitalism formalizes stakeholder agency; domicile and trillion-dollar essays turn fund principles into state prescriptions; AI shifts the moat from models to complements. Be Long Israel and Aleph V cannot yet support body-level conclusions, so apparent wartime/fund continuity stays open. Covenantal Capitalism Aleph AI Team
The important contradictions are not editorial defects; they are decision boundaries:
- Venture scale versus a local-market objection — [researcher inference | insufficient public record]: the full 2006/2012 writings reject subscale outcomes, while the RiseUp opening shows that founders expected an objection to an Israel-first market. It does not show Aleph's answer, so neither an accepted wedge rule nor a quantitative threshold is established.
- Capital-cycle insight versus missing action record — [researcher inference | insufficient public record]: the full 2009 and 2016 essays support regime-sensitive skepticism, but the blocked LP-retrospective body cannot establish fundraising, spending, runway, or secondary policies. The intellectual view is visible; portfolio implementation is not. Sarah Lacy/David Li 2016 Prediction
- Market Darwinism versus state coordination — [investor-stated | moderate]: diffuse grants and pension matching are criticized while national clusters, anchors, and conditions are proposed. The stated boundary is shared capability rather than company rescue; capture risk remains.
- Amazon anchor versus platform scattering — [researcher inference | moderate]: a platform can create ecosystem capability and later become a lock-in threat. Policy should price both lifecycle phases.
- Optimism/patience versus denial — [researcher inference | moderate]: resilience and waiting are praised, but no public stop-loss denominator distinguishes them from stubbornness.
- People/values versus verification/governance — [documented behavior | strong]: WeWork and Frank show that narrative congruence and long relationships do not secure ethical conduct, capital discipline, or stakeholder outcomes.
- Fast AI growth versus slow moat construction — [investor-stated | provisional]: the 18-month revenue aspiration can reward the same copyable applications the essay rejects unless separate moat milestones control the program.
Decision playbook and modern translation
Lesson 1 — Source through relationships, underwrite through evidence
- Historical rule — [investor-stated | moderate]: the full Healthy.io and Empathy essays, plus the stable RiseUp opening, document selected cases in which learning, repeated contact, or ideation preceded investment. They do not prove a corpus-wide relationship mechanism; the Relationships and Lemonade bodies remain unavailable. Healthy.io Empathy RiseUp opening
- Diagnostic questions: What behavior was observed before the pitch? Who independently confirms it? What did the founder learn or change? Can the team recruit someone excellent? Which evidence would reverse the relationship prior?
- Boundary and failure modes — [researcher inference | moderate]: familiarity, reciprocal networks, homogeneity, weak price discipline, founder entrenchment, and confused personal/firm attribution. Require independent references, conflict disclosure, a written counter-thesis, and post-investment governance triggers.
- Modern VC translation (as of 2026-08-22) — [researcher inference | moderate]: AI-assisted outreach and crowded auctions make authentic long-duration relationships scarcer, but also make network privilege easier to mistake for judgment. Track access source separately from IC score; blind-score product/market evidence before revealing relationship strength; measure founder-help claims through dated introductions, hires, customers, and decisions rather than testimonials.
Lesson 2 — Match venture capital to a credible power-law path
- Historical rule — [investor-stated | strong]: a useful product or important company is not automatically a venture-returning investment. Model plausible company scale, ownership, dilution, and exit proceeds; bootstrap where institutional pressure exceeds the attainable outcome. DooHickeys Eight Things
- Diagnostic questions: What outcome returns the fund at target ownership? Is the initial market a ceiling or a wedge? What expands the market? What capital is necessary before proof? Which security terms change ordinary-holder proceeds?
- Boundary and failure modes — [researcher inference | moderate]: premature TAM inflation, rejecting compounding niches, confusing company value with fund cash, and using power laws to excuse any price or check. Write an ownership-sensitive outcome table and update it after each round.
- Modern VC translation (as of 2026-08-22) — [researcher inference | moderate]: software and AI lower creation cost but increase feature crowding and platform dependence. A small team can reach revenue quickly without building durable enterprise value. Demand proof of retention, expansion, proprietary complement, and distribution independence before treating speed as scale.
Lesson 3 — Prefer “different,” but require a learning engine
- Historical rule — [investor-stated | moderate]: Healthy.io shows an outsider entering an unfashionable regulated category by learning reimbursement, regulation, workflow, and technical constraints while building on a secular cost curve. One selected case supports a testable pattern, not a general hit-rate claim. Healthy.io
- Diagnostic questions: What incumbent assumption is being discarded? What must the outsider learn? Which evidence shows learning velocity? Is consensus aversion rational? What is the first regulatory, technical, or customer falsifier?
- Boundary and failure modes — [researcher inference | moderate]: novelty theater, disdain for domain knowledge, fraud/science risk after a scandal, and “contrarian” as a substitute for being right. Pair outsider insight with named experts, primary data, and validation gates.
- Modern VC translation (as of 2026-08-22) — [researcher inference | moderate]: generative AI makes a fresh interface cheap; difference must live in workflow, rights, trust, distribution, hardware, or data accumulation. Simulate what happens if the leading model copies the feature or changes price/API access.
Lesson 4 — Turn values into observable product and governance design
- Historical rule — [investor-stated | moderate]: prefer business models that prosper when customers gain agency, safety, skill, ownership, or trust; treat mission as a recruiting and product input, not a charitable add-on. Long Humanity Covenantal Capitalism
- Diagnostic questions: Who pays and who benefits? Does revenue rise when the customer improves? What data would expose harm? What happens under growth pressure? Which board metric tests dignity/agency rather than engagement?
- Boundary and failure modes — [documented behavior | strong]: circular values claims, vulnerable-user exploitation, mission branding, privacy conflict, founder exceptionalism, and governance blind spots. WeWork and Frank require direct fraud checks, related-party review, whistleblower channels, financing discipline, and independent directors. WeWork S-1, related-party and governance sections SEC Frank release
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong]: AI systems can scale persuasion, profiling, and error faster than human review. Convert values into data-use limits, evaluation sets, appeal paths, pricing rules, harm thresholds, and executive compensation. A mission score without governance evidence receives no underwriting credit.
Lesson 5 — Prepare for cycles without pretending to time them
- Historical rule — [investor-stated | moderate]: capital supply changes competition, entry price, and security risk. The full 2009 essay argues that scarcity can improve a forward opportunity set; the full 2016 essay warns that abundant local financing can lag deteriorating platform economics and public comparables. Neither supplies a complete fund-action policy. Sarah Lacy/David Li 2016 Prediction
- Diagnostic questions: What regime are we in? Which public/private comparables diverge? How many months to cash-out under plan and downside? Which terms become toxic in a flat/down round? What evidence justifies spending ahead?
- Boundary and failure modes — [researcher inference | moderate]: permanent bearishness, defensive over-dilution, false precision, and retrospective selection of warnings. Maintain a dated forecast ledger with conditions, portfolio action, and outcome.
- Modern VC translation (as of 2026-08-22) — [researcher inference | moderate]: compute runway against vendor/model costs, security/compliance spend, revenue concentration, and financing availability. Separate “capital available” from “capital consumable”; require board-approved triggers for hiring, secondaries, and growth spend.
Lesson 6 — Stage uncertainty; do not sanctify patience
- Historical rule — [investor-stated | moderate]: when probabilities are unknowable, fund the next learning step, keep downside bounded, and allow technology/regulation/market timing to mature. Milk, Honey and Uncertainty Golden Calf
- Diagnostic questions: What uncertainty will this tranche resolve? Is the external gate measurably moving? What is the maximum cumulative loss? What result kills the thesis? When is the next irreversible decision?
- Boundary and failure modes — [researcher inference | strong]: escalation of commitment, moving milestones, correlated bets, founder charisma, and survival bias. Write stop conditions before the check and have a non-sponsor partner adjudicate exceptions.
- Modern VC translation (as of 2026-08-22) — [researcher inference | moderate]: AI and regulated deep tech can have rapid technical change but slow procurement, safety, or reimbursement. Separate technical, regulatory, distribution, and economic milestones; fund the bottleneck that can actually change, not a generic promise to wait.
Lesson 7 — Underwrite the complement system, not only the company
- Historical rule — [investor-stated | strong]: talent, infrastructure, law, taxes, global capital, universities, defense knowledge, and anchor platforms shape company outcomes. A venture thesis should identify which complements must exist and who controls them. Hummus Part 1 Incorporate in Israel or Delaware
- Diagnostic questions: Which skills, data, infrastructure, legal rights, and downstream capital are required? Are they local, portable, subsidized, or controlled by a platform/state? What happens if policy or provider changes?
- Boundary and failure modes — [researcher inference | moderate]: national advocacy overriding LP duty, subsidy dependence, anchor capture, local-incorporation friction, and mistaking ecosystem spillover for company return. Keep four ledgers: company economics, vehicle economics, ecosystem spillover, and civic objective.
- Modern VC translation (as of 2026-08-22) — [researcher inference | moderate]: diligence compute/energy, model/provider concentration, data residency, export controls, talent visas, regulation, and follow-on capital. Price portability and multi-provider architecture; do not count public subsidy as durable unit economics.
Lesson 8 — Put scarce complements behind AI speed
- Historical rule — [investor-stated | moderate]: foundation-model access is not a moat; proprietary domain knowledge, legally controlled data, distribution, network effects, and physical/workflow integration can compound. Aleph AI Team
- Diagnostic questions: What asset improves with each customer? Who owns the data and derived rights? How long to copy? What distribution survives platform bundling? Why does capital deepen rather than merely subsidize growth?
- Boundary and failure modes — [researcher inference | moderate]: fake data moats, purchased distribution, model dependence, adverse gross-margin repricing, and an 18-month revenue target that rewards copyable features. Score revenue velocity and moat construction separately.
- Modern VC translation (as of 2026-08-22) — [researcher inference | moderate]: require a model-provider stress test, data-rights opinion, evaluation/feedback loop, switching-cost evidence, and gross-margin scenario. A fast-growing wrapper can qualify only if a dated complement-building plan is already producing proprietary evidence.
Best writings and unresolved record
Ranked five
- Bad Blood, Good Urine, Great People! — [researcher inference | strong]: the best full ex-ante decision document in the corpus because it exposes founder, category, secular-cost-curve, regulation, product, and contrarian reasoning while saying the outcome was not yet known. Full essay
- DooHickeys and MeTooHickeys — [researcher inference | strong]: the clearest full early-stage economic filter, separating useful products and small businesses from opportunities that can plausibly support venture economics. Full essay
- Long Humanity — [researcher inference | moderate]: the clearest full statement of the human-needs thesis and the most important to read adversarially beside WeWork's bankruptcy and Frank's founder-fraud outcome. Full essay WeWork 8-K DOJ sentencing
- The Hummus Manifesto — Part 1 — [researcher inference | moderate]: the strongest ecosystem diagnosis. It shows Eisenberg thinking in complements—skills, stacks, scale experience, talent allocation—and provides the foundation for later scaleup and national-capability work. Canonical essay
- Spreading Wealth Through Covenantal Capitalism — [researcher inference | moderate]: the most formal mature statement of values as economic architecture. It is valuable precisely when read beside WeWork and Frank, which force the analyst to translate principle into verification and governance rather than accept rhetoric. Full PDF
Unresolved record
- Obtain lawful complete captures for all nine limited items: the seven partially readable, substantively analyzed works are Why We Decided to Drink the Lemonade, LMND - Aleph's First IPO, A Look Back at Our Letters to Our LPs and Capital Exuberance, Invest in Relationships, Not Transactions, Empowering Others to RiseUp!, The Tree of Life and Prosperity, and Be Long Israel. We Are.; the two metadata-only works are Melio: Investing in Great People and Announcing Aleph V: Long Israel. The exact publication day, byline, fund entities, and close language of Aleph V remain unknown.
- Obtain the complete English Tree of Life and Prosperity and verify all Hebrew translations in Milk, Honey and Uncertainty, Children Are Growth, and Abraham, Wealth and Economic Fraternity with a fluent editor.
- Obtain the full body of the 2022 LP retrospective and the complete 2018-2021 and current Aleph LP letters. The stable public opening establishes Eisenberg's letter-writing responsibility and named inspirations only; it cannot yield a forecast denominator, company-action ledger, or fund-performance attribution.
- Reconstruct the complete Israel Seed, Benchmark, and Aleph portfolios by legal vehicle, including passes, failures, ordinary outcomes, follow-ons, write-offs, renames, ownership, dilution, realized cash, DPI, TVPI, and IRR. Until then, no writing-derived philosophy can be called an economic edge.
- Retrieve original investment memos, closing/allocation records, and board minutes for Lemonade, Healthy.io, Melio, Empathy, RiseUp, WeWork, and Frank. Separate Eisenberg’s role from Shochat, other partners, directors, founders, and the legal vehicle.
- Score the 2016 adtech prediction and build a complete dated forecast ledger. A single highlighted call and selected LP warnings do not establish forecasting skill.
- Resolve the WeWork governance record and the Frank support-agreement litigation without overreach. Javice’s conviction is a founder finding, not a finding of Aleph knowledge; the 2026 complaint is an allegation until adjudicated.
- Preserve the central falsifier: if relationship-led, values-aligned, scale-oriented investments do not outperform an ownership- and vintage-adjusted denominator after ordinary failures and dominant outliers are included, the corpus describes a coherent worldview rather than a demonstrated investing edge.
Coverage and evidence base
This guide reconciles 11 of 11 priority talk/interview routes, all available in sufficient form for substantive analysis. The dated record runs from the TechCrunch TV interview recorded on 2012-07-16 through the 18Forty interview published 2026-04-18; the Max Raskin Q&A says “Jan 15” but exposes no year, so it is deliberately left outside the chronology rather than silently dated. “Full” below means the complete publisher text or the complete relevant audio/video was lawfully available and processed; it does not mean that every route has an official verbatim transcript. [documented behavior | strong]
| Evidence path | Count | Routes | What “full” means and what can still fail |
|---|---|---|---|
| Publisher text, transcript, or Q&A | 5 | YU Commentator (2017); EconTalk (2022); Max Raskin (year unknown); Agency Under Fire (2026); 18Forty Iran/USA/Israel (2026) | Commentator and Raskin are edited Q&As without timestamps. EconTalk supplies a full publisher transcript with timestamps. Agency supplies a first-party Aleph transcript plus topic timestamps. The 2026 18Forty page supplies a Sofer.ai transcript lightly edited by the publisher, with only the 6:13 interview-start time. Editing, machine error, and publisher framing remain possible. [documented behavior | strong] |
| Official automatic captions | 2 | TechCrunch TV (2012); 20VC AI (2024) | English en-orig captions were retrieved from the official YouTube uploads and cue positions were checked against their synchronized tracks. They are machine captions, not publisher-certified transcripts; unusual names and compressed phrases remain vulnerable to error. [documented behavior | strong] |
| OpenAI transcription of official RSS audio | 4 | 20VC Gurley/Eisenberg (2021); 18Forty Civic Revolution (2023); Human Founder (2024); Misgav (2025) | Complete official RSS audio was processed. The 20VC joint episode used gpt-4o-transcribe-diarize in three duration-safe chunks with offsets reconciled; the other three used whisper-1. Speaker assignment relied on diarization plus host addressee cues for 20VC, and on explicit turns/questions for non-diarized files. Ambiguous cross-talk was excluded. [documented behavior | strong] |
Three timebase qualifications matter. First, the 2023 18Forty RSS file retrieved for this research was 1:14:27 and placed the guest conversation at 07:24–59:51; publisher-page/show-note timing that begins around 4:35 appears to refer to a different, likely pre-dynamic-ad cut. Second, the 2025 Misgav source was 1:08:46 while the compressed transcription copy decoded at 1:08:56; locators after the guest entrance at 20:36 are conservative ranges and need audio checking before quotation. Third, 20VC's 50:01 joint interview was chunked at roughly 1,000 seconds because of transcription-duration limits; offsets were reconciled to the official episode, but unclear overlap was not used. [documented behavior | strong] The 11 priority works come from nine venue families: 20VC contributes two appearances and 18Forty contributes two. Repetition within those families is evidence of consistency or evolution, not independent corroboration; first-party Aleph media is direct voice but not independent outcome evidence. [researcher inference | strong]
The classification rule is intentionally strict. A clearly attributed answer establishes what Eisenberg said on a date, not that the factual claim, causal story, forecast, deal credit, or fund result is true. A host introduction, question, show note, or biography is not converted into an Eisenberg answer. “We” may mean a firm, partnership, board, or portfolio company and is not individual credit without a transaction or governance record. Israel Seed, Benchmark, Aleph, their separate funds, co-investors, founders, and Eisenberg personally remain separate units. [researcher inference | strong]
Each substantive statement below carries two labels: an attribution axis—investor-stated, contemporaneous record, documented behavior, retrospective witness, or researcher inference—and a support axis—strong, moderate, provisional, or insufficient public record. “Strong” can mean strong evidence that a statement was made; it does not certify the statement's underlying economics.
Dated source-by-source guide
2012-07-16 — TechCrunch TV: talent scarcity, power laws, and an early cycle view
Access and speaker evidence. The 13:30 official video was processed from its synchronized English automatic captions. The recording date is 2012-07-16; the current YouTube upload is dated 2023-06-05, so the interview context—not the upload date—anchors the evidence. Only Eisenberg's visible answers are used; the host's company and role introduction is secondary framing. [contemporaneous record | strong] TechCrunch canonical page official YouTube video/caption route
Central claim and mechanism. Eisenberg treats software as a paired productivity and labor-allocation shock: it removes some low-skill work while increasing demand for engineering, technical management, and scalable-system talent. His proposed response is reskilling rather than shifting workers into another vulnerable low-skill category, though he concedes that education is slow and the policy answer is incomplete. [investor-stated | strong] 00:59–03:40
His “Creakonomics” model moves from large industrial employers toward smaller, faster innovation businesses. Geographic and sector diversity should make an economy less fragile than a local monoculture; mobile, local, social, and internet platform shifts are the enabling layer. Zlango is the contemporaneous illustration of a product revived when smartphones supplied a missing platform, not evidence of Benchmark's return. [investor-stated | moderate] 04:04–07:42
Decision evidence. He already articulates a power-law prior: a small number of companies create disproportionate opportunity. He also interprets a quarterly Israeli funding contraction as potentially healthy because excess capital competes for scarce scaling talent. This is an early scarcity thesis; it supplies no fund denominator and the remark that less competition helps is conditional on that local capital-and-talent setting. [investor-stated | moderate] 08:29–09:29
Biography, boundary, and later tension. Eisenberg connects Israeli military technical service with early responsibility and creative problem-solving, then names broad management capacity as an Israeli weakness relative to the United States. He also rejects a static work-life balance and admits mobile work can take attention from children. These are contemporaneous temperament and ecosystem claims, not proof that any named team scaled well. The capital-scarcity preference later sits beside his 2021 willingness to pay for rare outliers; the consistent variable is not cheapness but scarce talent and differentiated access. [investor-stated | moderate] 10:00–12:54
2017-11-12 — The Commentator: career reconstruction, independent trends, and WeWork sourcing
Access and speaker evidence. This is a complete edited student-newspaper Q&A. Exact interviewer questions and article sections are the locators; there are no timestamps or stable paragraph numbers. Clearly attributed answers are direct-voice evidence, while the introduction's board list and assets-under-management figures remain reporter-written snapshots. [documented behavior | strong] The Commentator, full Q&A
Biography. In a 2017 reconstruction, Eisenberg moves from Yeshiva University newspaper editing to political consulting, unemployment, a self-created technology merchant bank, PictureVision, Israel Seed, DealTime/Shopping.com and ePinions, Benchmark, and finally Aleph. He says eleven early companies produced eight public or acquired outcomes, but does not name the denominator, define “backed,” identify vehicles, include losses, or disclose cash returns. The sequence is useful; the claimed hit rate is not audited. [retrospective witness | provisional] Commentator, “path you took” question
Decision evidence. WeWork is unusually specific sourcing testimony: Benzi Ronen, Saul Singer, and others independently connected Eisenberg and Adam Neumann, and Neumann's unusual worldview held Eisenberg's attention. That shows a relationship-convergence and founder-narrative mechanism. It does not show the Benchmark vehicle, IC vote, valuation, ownership, unit-economic test, governance protections, or individual board authority. [investor-stated | strong] Commentator, “How did you end up sourcing WeWork?”
Asked about Israeli trends, he names larger companies and “Scale Up Nation,” then says he tries not to invest in trends. Read together, the rule is to recognize a secular substrate without outsourcing underwriting to category consensus. The short answer does not define a trend-vs-fashion test. [investor-stated | moderate] Commentator, Israeli startup trends question
Values and adverse control. He puts people, purpose, family, Torah, service, and ethics ahead of money and companies. That is a public operating identity, not an outcome audit. The contemporaneous enthusiasm for a compelling WeWork founder supplies a hard counterweight: later governance concerns and Chapter 11 show why founder difference needs independent governance, economics, and abandonment criteria. Bankruptcy does not establish that Eisenberg's 2017 attention decision was irrational or that he controlled later decisions. [researcher inference | strong] Commentator, student-advice and WeWork questions WeWork 2023 Form 8-K, Item 1.03
2021-12-05/06 — 20VC with Bill Gurley: cycles, ownership, boards, and capital as a weapon
Access and speaker evidence. The publisher page is dated 2021-12-05 while the official RSS record is dated 2021-12-06; both are retained rather than silently collapsed. The official 50:01 RSS audio was transcribed with gpt-4o-transcribe-diarize in three serial duration-safe chunks. Chunk offsets were reconciled to episode time; automatic speaker labels were checked against Harry Stebbings's explicit addressee cues, and uncertain cross-talk was excluded. Gurley's arguments remain Gurley's even when Eisenberg agrees. [documented behavior | strong] 20VC, official episode
Cycle model. Eisenberg remembers recognizing dot-com irrationality yet thinking it might continue, using his younger self as evidence that investors can see excess and still underweight a turn. In 2021 he distinguishes the period by tourist capital and globally distributed venture markets. More capital can coexist with scarcer returns because funding grows faster than the set of companies able to produce venture-scale outcomes. [retrospective witness | moderate] 20VC, 04:46–11:21
Capital and ownership. A large late-stage war chest may become a cap-table weapon in a downturn: a well-funded holder can support a company while compressing weaker holders. He separates companies that need balance-sheet credibility—some finance, freight, banking, or payments businesses—from ordinary software and consumer companies, where unusable cash may damage focus. Access to a rare outlier can justify a higher price, but ownership is a separate optimization and investor reputation or pre-financing help should reduce reliance on being the top bidder. [investor-stated | strong] 20VC, 14:53–23:50
Board and partnership mechanics. Shopping.com/DealTime and ePinions are retrospective lessons in choosing calm co-investors and board members for a downturn. Eisenberg also says Aleph adopted Benchmark's equal-economics partnership model because it reduces internal bargaining and makes bad news safer to surface, while admitting information asymmetry between the board partner and the wider partnership. Neither account allocates exact historical votes or returns. [retrospective witness | moderate] 20VC, 30:19–33:15
Evolution and WeWork boundary. The episode converts the 2012 scarcity intuition into a fuller cycle policy: invest across cycles, secure differentiated access, preserve ownership, and ask whether capital is operationally usable. WeWork is discussed as proof that a large market and momentum do not substitute for governance. That is a retrospective process lesson after the failed IPO, not evidence that Eisenberg personally held the original Benchmark board seat or changed a specific vote. Independent reporting attributes that initial seat to Bruce Dunlevie. [retrospective witness | moderate] 20VC, board/cycle discussion Vanity Fair, independent reconstruction WeWork S-1, governance and related-party sections
2022-02-14 — EconTalk: backcasting, networks, and long humanity
Access and speaker evidence. EconTalk supplies a full publisher transcript with timestamps for a conversation recorded 2022-01-25. Host Russ Roberts's challenges are preserved as challenges, not attributed answers; this matters especially when he questions insurance incentives and broad technological claims. [documented behavior | strong] EconTalk, official transcript
Central framework. Eisenberg describes early venture work as searching whitespace without a philosophy, followed by a learned focus on networks and people. The investment pattern combines a secular trend, a human emotional response, and a story about how the two become a business. His most portable tool is backcasting: describe the desired future, identify necessary dominoes, separate controllable from uncontrollable dependencies, and test blockers. He credits Bruce Dunlevie with the complementary question of what can go right. [retrospective witness | strong] EconTalk, career and backcasting discussion
Decision evidence. Autonomous vehicles are a stated rejection because the time-to-resolution was too long relative to fund and execution horizons. PictureVision is a positive but qualified origin example: Eisenberg says he enabled or made the investment, then concedes the history is more complicated. This careful qualification is stronger attribution behavior than a blanket sole-credit claim, but the transaction still requires closing and vehicle records. [retrospective witness | moderate] EconTalk, autonomous-vehicle and PictureVision passages
Institution and geography. He contrasts a small equal partnership at Benchmark/Aleph with a superfund hierarchy, and describes Israel's small market as forcing global ambition while limiting the management bench. Dense networks can accelerate matching and help; they can also encode access bias, a limitation the interview does not test. [investor-stated | moderate] EconTalk, Aleph model and Israel discussion
Values and contradiction. “Long humanity” means aligning the business model and incentives with durable human needs rather than monetizing dependency or isolation. Lemonade is the promotional example, but Roberts pushes on whether the insurance incentive claim generalizes. The exchange is valuable precisely because the host exposes a missing control: a humane narrative must be translated into measurable customer, loss-ratio, governance, and return evidence. [investor-stated | moderate] EconTalk, Lemonade and incentives discussion Lemonade S-1/A
2023-12-12 — 18Forty: civic revolution, crisis resilience, and capital as accountability
Access and speaker evidence. The official Spreaker RSS MP3 retrieved for this run was 1:14:27 and transcribed with whisper-1. Eisenberg's guest conversation occupies 07:24–59:51; host framing, dynamic advertisements, and closing commentary outside that band are excluded. The page's shorter apparent timebase should not be used interchangeably with these locators. [documented behavior | strong] 18Forty, official episode
Biography and purpose. Eisenberg traces his technology career to Rabbi Yehuda Amital's 1991 instruction to create dignified livelihoods for ten thousand people, then reframes high-tech companies as twenty-first-century factories. It is unusually direct motive evidence but a selected memory recounted more than three decades later. He says Aleph invests only in Israeli startups and ties that mandate to a stronger national economy; it is a dated fund-position statement, not a claim about every vehicle or personal investment. [retrospective witness | moderate] 18Forty, 17:20–20:58
Civic framework. Technology moves capability toward individuals at the network edge, and Eisenberg expects government to shift from management toward orchestration. He argues that military responsibility and tools formed during the judicial-reform conflict supplied infrastructure citizens repurposed after October 7. The mechanism connects pre-crisis capability to wartime agency; the examples are speaker-selected and lack a comparative denominator. [investor-stated | moderate] 18Forty, 20:58–31:52
Portfolio and capital evidence. He estimates that roughly 10–20% of Aleph-company employees were on reserve duty while companies continued delivering, and says every Aleph investor contacted the firm after October 7. He also estimates over 95% of fund capital came from the United States and United Kingdom, with a very small Emirati share. These are contemporaneous manager observations, not company-level performance or audited LP-composition data. [investor-stated | provisional] 18Forty, 35:05–35:51 and 51:43–54:08
Investment translation and boundary. In contrasting investment with charity, he argues ownership creates monitoring, repeat engagement, and accountability. That supports a governance-and-commitment rationale for capital, not a return claim. His dismissal of peer review as creativity-dampening reveals a nonconformist preference, but it is not permission to relax external verification. [investor-stated | moderate] 18Forty, 46:16–48:15 and 55:28–57:47
2024-06-19 — 20VC solo: AI underwriting, ownership, exits, and board craft
Access and speaker evidence. The 1:02:17 official YouTube interview was processed from its synchronized English automatic captions. Wording and cue positions were checked against the track, but names and compressed language remain machine-caption risk. Host assertions are not treated as Eisenberg evidence. [documented behavior | strong] 20VC canonical episode page official YouTube video/caption route
AI thesis. Eisenberg holds that AI can be transformational while an AI investment gold rush destroys capital. His dot-com analogy separates durable infrastructure from investable company economics. He names overlapping LP exposure, logo chasing, geographic-copy assumptions, model depreciation, and key-person loss as failure modes. The rule is to underwrite the exceptional company, not buy category exposure. [investor-stated | strong] 01:18–09:09
Aleph's stated scope is Israel-only, applied AI, and full-stack workflow transformation rather than foundation models. Eisenberg attributes that to Israeli application talent and insufficient local academic/large-company talent density for frontier models. Windward and Lemonade are retrospective applied-AI examples; “we invested” does not allocate sourcing, IC, board work, ownership, or returns across Aleph partners and funds. [investor-stated | moderate] 09:17–12:08
Competition and risk. He avoids obvious crowded AI applications and prefers domains requiring expertise and market education. A difficult synthetic-biology or hard-tech company may be less risky than crowded SaaS because uniqueness can preserve price and channel economics. His 2005 sell-side-analyst study yields a public-market heuristic: scarce exposure to an important future can earn a premium, conditional on growth and gross profit. These are qualitative rules without matched base rates. [investor-stated | moderate] 12:12–17:52
Capital, liquidity, and boards. Eisenberg prefers an earlier public listing at the available price over waiting for a private headline valuation; he favors holding winners when information and conviction justify it, yet regrets not selling one or two holdings during zero-rate conditions. He emphasizes meaningful initial ownership, says he rarely relies on pro rata, and describes board preparation as a data-rich letter followed by one to three questions in about 45 minutes. The self-reported unnamed approximately 11x complete exit and Dream Security fund-percentage claim remain unverified. [investor-stated | moderate] 35:37–52:33
Operating style and boundary. He says he does not invest over Zoom, may rattle founders through intensity, sources little proactively after thirty years, and makes only two or three deals a year. He rates Israel's network above average and management below average. He also corrects himself to credit Daniel Schreiber—not “we”—for Lemonade's New York licensing decision, a useful live attribution repair. None of these self-assessments supplies pass, loss, or return denominators. [investor-stated | moderate] 52:33–1:02:17
2024-09-30 — The Human Founder: failure, relationship duration, and Aleph's formation
Access and speaker evidence. The official 54:06 RSS audio was transcribed with whisper-1 verbose-json segment timestamps. There was no speaker diarization; attribution follows explicit interview turns and questions, and ambiguous cross-talk is excluded. [documented behavior | strong] Apple Podcasts metadata route official Podbean episode/RSS route
Role philosophy. Eisenberg casts the founder as the hero and the investor as a stagehand whose relationship can last a lifetime. Daniel Schreiber's earlier company and later Lemonade illustrate a long founder relationship, not proof that Eisenberg caused either outcome. Reputation is predictable conduct over time; empathy can coexist with closing a company when returning the founder's time is the better choice. [investor-stated | moderate] Human Founder, opening relationship and shutdown discussion
Failure case. Print Life, his 1999 example, combined vertical integration with capital-intensive printing just as financing tightened. He describes a slow pivot, layoffs, a recruited executive, and shared board/management responsibility. The resulting rule is to test whether the business depends on continually available financing and to stop when the financing source or model breaks. This is candid retrospective process evidence, not a contemporaneous memo or complete creditor/shareholder account. [retrospective witness | moderate] Human Founder, Print Life discussion
Career and team formation. Eisenberg describes an improvised entry—political-consulting layoff, technology merchant bank, wealthy backers, his fee invested into a digital-photo company, Montgomery Securities, and a complementary partnership with Shlomo Kalish. He credits Kalish's Israeli relationships and experience separately from his own business model. [retrospective witness | moderate] Human Founder, 20:36–22:38
For Aleph, he dates a 2009 Benchmark arrangement, an end-2012 departure, a Bruce Dunlevie deck, Dunlevie's suggestion of Eden Shochat, Kathryn Mayne of Horsley Bridge catalyzing the fundraise and partner search, a nine-week process, and a July 3 close. It is the best spoken team-formation map in this set precisely because it credits Shochat as cofounder and names institutional helpers. It remains a 2024 recollection requiring fund documents for exact dates, commitments, and decision rights. [retrospective witness | moderate] Human Founder, Aleph formation discussion
Publication year unknown — Max Raskin: learning loops, a network operating system, and priority
Access and speaker evidence. The live page is a complete edited text Q&A dated “Jan 15,” but the year is not exposed. Section headings and exact questions are the stable locators. The answers are direct attributed voice with editorial uncertainty; the missing year prevents chronological claims. [documented behavior | strong] Max Raskin, full Q&A
Learning method. Eisenberg recommends repeated exposure before comprehension: learn a field's five-to-ten key terms, struggle through primary documents, then use the vocabulary to ask experts better questions. He says he taught himself finance by reading S-1s, balance sheets, and profit-and-loss statements. The page refers to K-1 “annual reports,” which may be an editing or terminology error; it should not be silently corrected into a 10-K claim. [investor-stated | strong] Raskin, “Struggle With It”
Network and sourcing mechanics. He describes an associative mental map of people plus an Aleph CRM annotated manually and automatically. The system is meant to produce sourcing, recruiting, business development, sales, and funding connections. This turns the corpus's vague relationship advantage into an institutional operating mechanism, but the interview supplies no privacy, access-control, data-quality, matched-outcome, or counterfactual audit. [investor-stated | moderate] Raskin, “Herzlean Task”
Priority and decision evidence. Only one item can be first at a time; presence requires removing phone distraction. Healthy.io is the example of a portfolio need temporarily taking priority. That establishes concentrated attention, not intervention quality or company outcome. His topic-driven information diet and expert network may improve synthesis while increasing selection and confirmation risk. [investor-stated | moderate] Raskin, “The Sacred and the Prosaic” and “Hot Topics”
Biography and boundary. Eisenberg calls himself nontechnical and dates his last coding to seventh or eighth grade, making translation, questioning, people networks, and pattern acquisition his claimed edge. He also says fundraising rewards authenticity and hard work and rejects reduced work intensity. That is a people-selection belief, not evidence that hours cause returns; it also continues the unresolved family/attention tension visible in 2012. [investor-stated | moderate] Raskin, “Coding The City of David” and fundraising question
2025-08-13 — Misgav: AI as national infrastructure and regional complementarity
Access and speaker evidence. The official 1:08:46 RSS MP3 was processed with whisper-1. The compressed copy decoded at 1:08:56; after Eisenberg enters at 20:36, locators are rounded conservative ranges and require official-audio checking before quotation. There was no diarization; explicit question/answer turns support attribution. [documented behavior | strong] Misgav, official episode
Central framework. Eisenberg says civilian innovation is normally superior to state planning, using soldiers' bottom-up defense tools as an example, but treats AI as an exception because energy, compute, and scarce talent make it national infrastructure. The tension is substantive: decentralization is the discovery engine, while concentrated state capacity supplies the substrate. The interview does not specify the boundary where coordination becomes crowding out. [investor-stated | moderate] Misgav, 20:36–31:25
Regional thesis. He assigns the UAE and Saudi Arabia energy, capital, and infrastructure capacity, and Israel innovation talent, chips, and US access. The proposed combination could serve markets south and east. This is a strategic proposal with no named joint venture, commitments, economics, or execution evidence. [investor-stated | provisional] Misgav, 35:17–39:10
Investment and operating translation. A small home market forces global sales but cannot solve the talent bottleneck; Israeli companies may need offices in deeper overseas labor pools and AI-enabled services beyond cyber and defense. The transferable underwriting questions are whether scarce labor is available, whether distributed teams preserve execution, and whether the global market is entered from inception. The interview does not connect these conditions to a named Aleph pass or outcome. [researcher inference | moderate] Misgav, 59:17–61:55
Biography and attribution. He credits partners across family, Aleph, nonprofit activity, editing, and Bat Shlomo rather than claiming individual control. Wartime resilience is a personally situated selection judgment, not evidence that service traits predict startup outcomes. A “first investor in Lemonade” phrase requires company/closing records and must not erase Shochat, other partners, the vehicle, or founders. [retrospective witness | moderate] Misgav, 21:11–25:48 and 1:02:54–1:05:02
2026-03-09 — Agency Under Fire: wartime agency, atoms, and an ex-ante keep-investing rule
Access and speaker evidence. This is a first-party Aleph solo episode with a publisher transcript and key-topic timestamps from 00:00 to 10:38. The page oddly displays “No transcript found” immediately before the transcript; the visible transcript itself is the evidence. As a solo first-party item, speaker attribution is clear, while military, market, and causal claims still require external controls. [documented behavior | strong] Aleph, Agency Under Fire
Agency thesis. Eisenberg uses a shelter dating app, wartime weddings, pre-army youth building protected delivery rooms, and a granddaughter story to argue that agency scales under pressure. These vivid selected cases support his philosophy of decentralized action, not a representative measure of national behavior. [investor-stated | moderate] Agency Under Fire, 00:00–04:35
Investment rule. He describes an unnamed Aleph company growing during war and states that Aleph kept investing rather than waiting for calm. This is useful ex-ante posture evidence: crisis may reveal mission, adaptability, and demand, while a no-investment default can miss them. Without the company, check, cohort, pass set, or subsequent result, it is not proof that wartime deployment outperformed. [investor-stated | moderate] Agency Under Fire, company and keep-investing passages
Atoms and sovereignty. Eisenberg expects a decade of technology sovereignty, defense, AI, energy, and physical systems, where military error carries real cost and atoms require five-to-seven-year patience. He says countries are seeking Israeli technology. This extends the 2024 preference for difficult, domain-specific systems, but unnamed demand and a thematic horizon are not deal economics. [investor-stated | moderate] Agency Under Fire, 04:35–10:38
Forecast boundary. His claims that the Tel Aviv market was up almost 10%, that the US/China/Israel are the top three technology powers, and that venture investment will surge after war lack index, period, baseline, or forecast window in the transcript. They belong in a forecast ledger, not a performance conclusion. The cited annual letter was not located publicly. [investor-stated | provisional] Agency Under Fire, market and outlook passages
2026-04-18 — 18Forty: preemption, statecraft, prosperity, and epistemic tension
Access and speaker evidence. The publisher supplies a full Sofer.ai transcript lightly edited by 18Forty. The interview begins at 6:13, but later timestamps are absent; exact host-question and answer-topic anchors are used. Direct answers are A/B voice evidence because machine transcription and editing are acknowledged. Host biography, numbers, and summaries are not converted into answers. [documented behavior | strong] 18Forty, Iran, USA, Israel
Decision analogy. Eisenberg begins by distinguishing what he thinks from what he knows, then analogizes state preemption to non-consensus investing: do not allow a problem to compound until response becomes existential, and tolerate ridicule when early evidence supports action. Howard Marks's consensus/non-consensus matrix is the explicit intellectual bridge. The analogy offers a timing preference, not evidence that Aleph applied it successfully. [investor-stated | moderate] 18Forty, opening and “was the Iran response worth it?” question
Information method. He says errors in reporting about him reduced his trust in general media, so he does his own research and urges direct calls to people in Israel. First-person networks can improve context but do not remove secrecy, selection, motivated reasoning, or confirmation bias. This method is consistent with the Raskin network system and needs independent contradiction-seeking. [investor-stated | moderate] 18Forty, US–Israel sentiment and rapid-fire news questions
Macro and national doctrine. Eisenberg describes four interacting revolutions—democratic stress, a failing welfare-state model, renewed war, and AI plus energy/physical infrastructure—and reports involvement in Pact Silico. He advocates “prosper and make others prosperous”: productive innovation, exports, energy, trade, and institutions should expand capability for Israel and its neighbors. These are macro and civic theses with almost no company-level underwriting evidence. [investor-stated | moderate] 18Forty, horseshoe-theory, US–Israel, and next-national-project questions
Biography, evolution, and contradiction. He again recounts Amital's 1991 ten-thousand-livelihood instruction and says he decided on the spot to pursue it. The story is now roughly thirty-five years old and was already told publicly in the 2023 18Forty episode; a 2026 suggestion that he had never discussed it should therefore mean an exact variant or setting, or else conflicts with the surviving record. His closing preference for mutual responsibility without false consensus coheres with equal partnership, while his bold forecasts for American Jewish decline and Israeli growth sit uneasily beside his repeated epistemic humility. [researcher inference | strong] 18Forty, “why aren't you a rabbi?” and American-Jewry exchanges 2023 18Forty, 17:20–20:09
Cross-source frameworks
1. Relationship advantage must become institutional evidence
The sequence is unusually coherent: 2017 WeWork sourcing shows independent referrals converging on a founder; 2021 says reputation, help before a round, and relationships are non-price access advantages; 2022 makes networks and people central to learned philosophy; Raskin exposes the Aleph CRM that converts a personal mental map into sourcing, hiring, sales, and funding; Human Founder adds predictable long-duration conduct. [researcher inference | strong] Commentator, WeWork question 20VC, 21:47–23:50 Raskin, “Herzlean Task”
The missing test is whether network-sourced deals outperform comparable non-network opportunities after stage, price, ownership, vintage, partner, and selection are controlled. Relationship density may generate trust and proprietary context; it may also produce homophily, unrecorded conflicts, and persuasive-founder bias. The operating rule is therefore: log referral paths, competing evidence, relationship conflicts, rejected references, and counterfactual deal access—not merely contact count. [researcher inference | moderate]
2. Power law does not eliminate price, ownership, or financing risk
The 2012 power-law prior matures in 2021 into separate controls for access, price, ownership, and usable capital. The 2024 version adds meaningful initial ownership, rare reliance on pro rata, selective winner-holding, earlier liquidity, and regret about failing to sell during a cheap-money period. Print Life adds a financing-source failure mode, while WeWork demonstrates how abundant capital and narrative momentum can coexist with governance failure. [researcher inference | strong] TCTV, 08:29–09:29 20VC, 14:53–23:50 20VC AI, 35:37–52:33
The resulting decision rule is conditional: pay enough to secure a rare outlier only when the company can use the capital, the ownership can matter at fund scale, the next financing dependency is explicit, and governance survives a downturn. Entry price matters most for middling cases, which is exactly why underwriting cannot assume the company is already the outlier. [researcher inference | moderate]
3. Backcasting converts optimism into a dependency map
Eisenberg's strongest analytic tool is the 2022 backcast: describe the future, list necessary dominoes, distinguish controllable and external dependencies, and identify blockers. The 2024 AI interview adds asset durability, specialist knowledge, customer acquisition, and public-market scarcity. The 2026 preemption analogy adds timing: act before a compounding blocker becomes existential. [researcher inference | strong] EconTalk, backcasting discussion 20VC AI, 04:31–17:52 18Forty 2026, Iran-response question
The missing discipline is an explicit abandonment schedule. A useful memo should name each domino, evidence threshold, owner, deadline, dependency correlation, financing runway, and kill criterion. Otherwise “what can go right” becomes narrative permission and contrarianism becomes identity rather than a falsifiable decision. [researcher inference | moderate]
4. Founder agency needs board-level counterweights
Human Founder calls the founder the hero and investor the stagehand; 2017 values founders who see differently; 2023 and 2026 elevate decentralized civic agency. Yet 2021 says steady boards matter most in downturns, 2024 describes concentrated board questions, and Print Life pairs empathy with shutdown. These are complements only if role boundaries are explicit: founders lead, while boards protect solvency, integrity, stakeholder obligations, and learning under stress. [researcher inference | strong] Human Founder, role and Print Life discussions 20VC, 30:19–33:15
The WeWork and Frank records prevent a soft interpretation of “stagehand.” Values and relationship duration do not replace independent verification, related-party review, customer-data authentication, audit rights, whistleblower channels, or escalation rules. Conversely, neither adverse case proves Eisenberg knowledge or individual control. [researcher inference | strong]
5. Israel is a substrate and constraint, not a return explanation
Across 2012–2026, Eisenberg consistently names early responsibility, technical creativity, dense networks, global-from-day-one pressure, and wartime agency as Israeli advantages; he repeatedly names management depth, scarce specialized talent, small local demand, and political/fiscal capacity as constraints. The 2025 regional proposal tries to match Israeli talent with Gulf capital, energy, and infrastructure. [investor-stated | moderate] TCTV, 10:00–11:08 EconTalk, Israel discussion Misgav, 35:17–39:10
The investment translation is to test whether a company turns substrate into a specific advantage while funding the missing management, sales, regulatory, and labor capabilities. National mission cannot substitute for LP fiduciary discipline, and Israeli resilience cannot be inferred to every founder or vehicle. [researcher inference | strong]
6. “Long humanity” requires product and governance measurements
The spoken corpus repeatedly links dignity, community, prosperity, service, and human agency to technology. Lemonade, civic investment, and the Amital origin story make the narrative concrete. But a company can market community while extracting rents, or claim empathy while using weak controls. The framework becomes investable only when the memo states who benefits, who pays, which behavior the business model rewards, what harms are externalized, and how governance detects divergence. [researcher inference | strong] EconTalk, long-humanity discussion 18Forty Civic, 17:20–22:39
The required controls depend on the product: customer outcomes and loss ratios for insurance, occupancy and related-party economics for workspace, data authenticity and consent for financial platforms, and procurement/accountability for defense. Values are a hypothesis about incentive alignment until those measures and adverse cases are reviewed. [researcher inference | strong]
7. Decentralized discovery and concentrated infrastructure form a live tension
The early corpus favors small innovative firms, networks at the edge, civic movements, and founder agency. By 2025–2026, AI compute, energy, defense, and physical systems lead Eisenberg toward state coordination, technology sovereignty, and five-to-seven-year atoms investments. This is a genuine evolution from software-era diffusion to infrastructure realism, not necessarily a reversal. [researcher inference | strong] TCTV, 04:04–06:32 Misgav, 20:36–31:25 Agency Under Fire, sovereignty discussion
The boundary test is who must coordinate which bottleneck. Energy grids, compute, procurement, and national security may require state capacity; product discovery and company formation may still work best bottom-up. A deal thesis should identify regulatory capture, subsidy dependence, procurement cycles, dual-use risk, and whether private returns survive if policy support changes. [researcher inference | moderate]
Chronological evolution and contradictions
| Period | What changes | What remains stable |
|---|---|---|
| 2012: Benchmark-era public voice | Software is a labor shock; capital contraction may improve talent allocation; power-law outcomes and management scarcity are already explicit. [investor-stated | moderate] | Scarce people, platform shifts, global opportunity, and candid work-family trade-offs. |
| 2017: Aleph and WeWork confidence | Relationships and unusual founders become visible sourcing mechanisms; values and independent thinking are foregrounded. [investor-stated | strong] | Status-quo skepticism and Israel-to-global ambition. |
| 2021–2022: post-WeWork, late-cycle formalization | Cycle memory, ownership, usable capital, steady boards, equal partnership, backcasting, and long-humanity incentives become an integrated framework. [researcher inference | strong] | Outlier access and relationships remain central, but governance becomes more explicit. |
| 2023: war and civic mission | Investment is recast as accountability; edge capability and crisis response are elevated to a political-economic model. [investor-stated | moderate] | Agency, networks, Israel-only firm identity, and dignified employment. |
| 2024: mechanics and self-critique | Applied-AI filters, scarcity premiums, ownership, IPO timing, board format, financing failure, shutdown, and team credit are unusually operational. [researcher inference | strong] | Rare people, nonconsensus, and long relationships. |
| 2025–2026: infrastructure and statecraft | AI, energy, atoms, defense, regional alliances, and state capacity broaden the frame beyond conventional venture. [investor-stated | moderate] | Early action, agency, Israeli globalism, and productive prosperity. |
The corpus also contains unresolved tensions:
- Competition versus access. In 2012 reduced investor competition appears healthy; in 2021 paying more for a rare outlier can be rational. These reconcile if scarce talent and ownership-adjusted access—not low price alone—are the target, but no matched outcomes test the reconciliation. [researcher inference | moderate]
- Founder narrative versus governance. The 2017 WeWork sourcing story celebrates a compelling unusual founder; 2021 stresses steady boards and later governance lessons. The record does not show when or how Eisenberg's diligence or escalation rules changed. [researcher inference | strong]
- Stagehand versus intervention. Founders are heroes, yet Eisenberg describes priority portfolio intervention, intense boards, recruiting executives, and shutdown advice. The practical role is conditional intervention, not passivity; decision-right boundaries remain undescribed. [researcher inference | strong]
- Patience versus abandonment. Difficult businesses and atoms require long horizons, but autonomous vehicles can be rejected for excessive duration and Print Life can be shut after financing breaks. Patience is coherent only with dated dependency milestones and financing limits. [researcher inference | strong]
- Cottage partnership versus national-scale infrastructure. A small equal firm is presented as an advantage, while AI/defense/energy require coordinated scale. The corpus does not explain portfolio concentration, conflicts, or reserve policy when a cottage investor enters capital-intensive systems. [researcher inference | moderate]
- Diffusion versus centralization. Technology pushes power to the edge in 2023; AI is national infrastructure in 2025. The likely distinction is application discovery versus compute/energy substrate, but Eisenberg does not explicitly state that boundary. [researcher inference | moderate]
- Epistemic humility versus macro confidence. He repeatedly says he does not know, distrusts weak reporting, and prefers primary calls, yet makes assertive demographic, market, and geopolitical forecasts without probabilities or baselines. [researcher inference | strong]
- Amital story novelty. The 2026 implication that the origin story had not been publicly told conflicts with the surviving 2023 18Forty telling unless the claim meant that particular variant or setting. [documented behavior | strong]
- Work and family. The 2012 admission of poor device boundaries and the Raskin defense of work intensity coexist with a family- and covenant-centered identity. No later source supplies a resolved operating boundary. [researcher inference | moderate]
Deal rationales and required filing controls
Spoken deal stories are starting hypotheses, not credit or return records. The minimum control is company identity, date, vehicle, security, sourcing, IC action, board role, ownership, dilution, follow-ons, distributions, and loss denominator. [researcher inference | strong]
| Company or decision | What the talks actually support | Control required before stronger use |
|---|---|---|
| PictureVision | Eisenberg remembers creating a merchant-bank model, investing his fee, and “enabling or doing” a digital-photo investment, while conceding the history is more complicated. [retrospective witness | moderate] | Closing documents, co-investors, security, vehicle/personal capital, Kodak acquisition proceeds, and allocation of Kalish/Montgomery roles. |
| Print Life | A 1999 capital-intensive vertical-integration failure taught financing-dependency, pivot-speed, and shutdown lessons. [retrospective witness | moderate] | Company/vehicle records, financing history, board minutes, creditor outcome, contemporaneous decision chronology, and total loss. |
| DealTime / Shopping.com / ePinions | He describes Shopping.com and ePinions as network, co-investor, executive-recruitment, and downturn-board lessons; Gurley and other partners appear in the story. [retrospective witness | moderate] | Use the Shopping.com S-1/A for company history, capitalization, losses, and risks; add Israel Seed security/cash-flow records and board minutes before personal credit or return. |
| Zlango, Wix, and other Benchmark associations | Zlango illustrates platform timing; Wix and other names appear as ecosystem/portfolio examples. The talks do not reconstruct individual decisions. [investor-stated | provisional] | The Wix Form 20-F supports board/company facts, not Benchmark fund cash flows; obtain deal allocation, ownership, votes, and realized proceeds. |
| WeWork | 2017 supplies person-level network sourcing and founder conviction; 2021 supplies a post-collapse governance/capital lesson. [retrospective witness | strong] | Pair the 2019 S-1 and 2023 Chapter 11 8-K with the actual Benchmark vehicle, Dunlevie/Eisenberg board roles, IC record, votes, sales, and cash outcomes. |
| Lemonade | It illustrates relationship duration, applied AI, public listing, founder agency, business-model values, and a correction crediting Daniel Schreiber for licensing. [investor-stated | moderate] | The Lemonade S-1/A establishes company risks, losses, and Aleph ownership at IPO; later Forms 4, fund allocations, board minutes, and cash distributions are needed for investor outcome. |
| Healthy.io | Raskin supplies concentrated portfolio attention; written/deal material elsewhere supplies a diligence narrative. The talk alone does not establish intervention content or return. [investor-stated | moderate] | Deal memo, vehicle, board record, regulatory evidence, follow-on decisions, ownership, and outcome; distinguish urgency from successful help. |
| Windward | Eisenberg retrospectively classifies it as pre-LLM applied AI. [investor-stated | moderate] | The Windward admission document can establish issuer-stated holdings and financing; it cannot assign sourcing, IC, board value, or Aleph cash return. |
| Dream Security | A 2024 interview describes an unusually large initial exposure as evidence of ownership conviction. The exact percentage, vehicle denominator, allocation, and later result are not verified. [investor-stated | provisional] | Subscription/closing documents, specific fund commitment denominator, partner allocation, conflicts, dilution, valuation, and subsequent cash flows. |
| Unnamed complete exit and unnamed wartime companies | The approximately 11x exit, post-October shutdown advice, and wartime growth story demonstrate claimed decision types but are intentionally unidentifiable. [investor-stated | provisional] | No return, lesson, or credit should be promoted until company, security, date, cash flows, board role, and downside set are disclosed. |
| Frank | These eleven talks provide no substantive Frank underwriting, diligence, board, or exit rationale. Absence is not evidence of absence or knowledge. [documented behavior | strong] | Company/deal/board records, customer-data diligence, the SEC release, DOJ disposition, and unresolved support-agreement complaint mirror, with criminal and contract issues kept separate. |
Adverse and retrospective audit
Israel Seed: a career story without a complete vehicle outcome
The talks repeatedly select PictureVision, DealTime/Shopping.com, ePinions, and an early claimed hit rate to explain learning. They do not supply Israel Seed I–IV cash flows, the full company denominator, personal decision rights, losses, or final net returns. Contemporaneous reporting says Israel Seed abandoned a fifth-fund raise in 2005; a later CalPERS-based report showed Israel Seed IV at -15.8% at year-end 2005, with $1.2 million remaining value and $320,000 distributed on $2 million contributed. Those are dated interim LP/vehicle observations, not Eisenberg's personal return or necessarily final fund performance. [contemporaneous record | moderate] Globes, 2005 transition report Globes, CalPERS year-end 2005 report
The falsifiable retrospective question is whether the later emphasis on durable companies, steady boards, financing dependence, and patient pivots appears in dated Israel Seed records before or during the weak period, or only in later selected memories. [researcher inference | strong]
WeWork: unusually good voice evidence, incomplete governance evidence
The record has three useful dates. In 2012 WeWork is only a Second Street ecosystem observation, not an articulated investment case. In 2017 Eisenberg gives a favorable, contemporaneous sourcing story centered on referral convergence and an unusual founder. In 2021 he discusses boards, capital, and WeWork after the attempted IPO collapse. The company filed Chapter 11 in November 2023. [documented behavior | strong]
That chronology supports a real update—from founder/narrative conviction toward explicit governance and capital warnings—but not proof of causal learning or individual responsibility. Independent reporting attributes the initial Benchmark board seat to Bruce Dunlevie; exact Eisenberg sourcing, IC, voting, later crisis role, share sales, and vehicle result remain unassembled. Peak private valuation, company bankruptcy, and personal/fund return are different measures. [researcher inference | strong] 2017 Commentator Q&A Vanity Fair, independent reconstruction WeWork S-1 WeWork 8-K
Frank: a major adverse record almost absent from spoken philosophy
Frank does not receive a substantive investment rationale in the 11-route talk corpus. Founder Charlie Javice was convicted and sentenced in 2025 for the fraud described by DOJ; that adjudicated disposition concerns Javice. JPMorgan's 2026 pleading separately asserts support-agreement obligations against Aleph-related holders; it is unresolved, and the public report states the complaint does not allege that Aleph knew of or participated in the fraud. [documented behavior | strong] DOJ sentencing release redacted complaint mirror CTech report and Aleph response
The silence matters as a research gap, not an admission. It prevents the spoken claims about values, people, relationships, board craft, and long humanity from being treated as tested process. The next evidence must be contemporaneous diligence, customer-data validation, board escalation, transaction representations, support-agreement language, and eventual court disposition. [researcher inference | strong]
Forecast ledger
| Date and source | Forecast or forward claim | Observable test and present boundary |
|---|---|---|
| 2012 TCTV | Lower Israeli funding could improve investor competition and return talent to stronger companies. [investor-stated | provisional] | Define the quarter, funding series, talent flows, company cohort, ownership, and subsequent returns. No matched test appears in the talks. |
| 2021 20VC | Abundant venture capital can make returns scarcer; tourist capital and global diffusion may change the next correction. [investor-stated | moderate] | Compare 2021 vintage net DPI/TVPI and loss ratios across manager quality, geography, entry stage, tourist exposure, and ownership. No dataset is supplied. |
| 2022 EconTalk | Durable “long humanity” companies can capture very large markets when incentives align with human needs. [investor-stated | provisional] | Pre-register customer benefit, retention, unit economics, governance, harm measures, exit/cash return, and a comparable non-values cohort. Named examples alone cannot test it. |
| 2023 18Forty Civic | Government will move from managing citizens to orchestrating distributed civic capability; wartime portfolio resilience may persist. [investor-stated | provisional] | Track institutional adoption, budgets, service delivery, company retention/revenue/runway during and after reserve-duty shocks, and failures omitted from the interview. |
| 2024 20VC AI | AI is transformative but the gold rush will destroy capital; few foundation-model companies will deliver major investor returns, while applied full-stack AI can create durable value. [investor-stated | moderate] | Define model/app cohorts, capital invested, gross margins, model-cost decay, retention, exits, and net fund returns through a full cycle. The thesis is too young for a resolved score. |
| 2024 20VC AI | Earlier IPO liquidity at the available price can be preferable to waiting for a higher private valuation; scarcity can earn a premium when growth and gross profit persist. [investor-stated | moderate] | Compare dilution, capital access, post-listing performance, realized fund cash flows, and matched delayed-IPO companies. Lemonade alone is selected evidence. |
| 2025 Misgav | AI becomes national infrastructure; Gulf energy/capital/infrastructure plus Israeli talent/chips/US access can form a regional growth platform. [investor-stated | provisional] | Require named projects, contracts, compute and energy capacity, governance, US export/security approvals, talent flows, revenue, and private returns. None is supplied in the episode. |
| 2026 Agency Under Fire | Postwar venture investment will surge and Israel will remain a leading technology power. [investor-stated | provisional] | Fix a prewar and wartime baseline, index, currency, period, stage, real-vs-nominal measure, foreign share, and follow-on window. “Almost 10%” without an index or period is not scoreable. |
| 2026 18Forty | Democratic stress, welfare-state limits, war, AI, and energy will interact; American Jewish population/influence will shrink while Israel grows and becomes more culturally generative. [investor-stated | provisional] | Specify demographic series, migration, affiliation/influence metrics, horizon, confidence band, institutional outputs, and disconfirming thresholds. The transcript gives none. |
The ledger should be updated with dated observations, not rewritten after outcomes. A forecast without a baseline, horizon, metric, and falsifier remains a worldview statement. [researcher inference | strong]
Listen to these five first
- 20VC solo, 2024 — the richest single operating source: AI filters, crowding, asset durability, ownership, public liquidity, board format, sourcing, and live attribution correction. Use the synchronized caption track for exact wording. [researcher inference | strong]
- The Human Founder, 2024 — best for failure, empathy, shutdown, financing dependence, career entry, partner complementarity, and Aleph formation; unusually useful for separating Shochat, Dunlevie, Mayne, and Eisenberg. [researcher inference | strong]
- EconTalk, 2022 — clearest coherent investment philosophy: trend plus human response, backcasting, collaboration, Israel constraints, equal partnership, and long humanity, with Roberts supplying valuable pushback. [researcher inference | strong]
- 20VC with Bill Gurley, 2021 — strongest cycle/ownership/capital/board discussion and a useful paired-speaker test. Listen carefully because Gurley's views cannot be merged into Eisenberg's. [researcher inference | strong]
- TechCrunch TV, 2012 — the shortest and earliest checkpoint. It reveals which ideas predate Aleph and later outcomes: talent scarcity, power laws, platform shifts, management limits, capital correction, and work-family trade-offs. [researcher inference | strong]
The two 18Forty wartime episodes are essential for civic and national philosophy, but the five above offer the best first-pass coverage of investment mechanics and intellectual evolution. The Raskin item is a high-value read rather than a listen, and its year remains unknown. [researcher inference | strong]
Unresolved record and falsifier
- Obtain publisher-certified transcripts, or perform a second audio verification, for all four OpenAI-transcribed and two auto-caption routes before using disputed names or exact quotations. Preserve both 18Forty timebases and resolve the Misgav ten-second decode difference. [documented behavior | strong]
- Recover the Max Raskin publication year from page metadata, an archive capture, sitemap, feed, or publisher confirmation; do not infer it from topics. [documented behavior | strong]
- Obtain the original 2018–2021 and later Aleph annual letters, deal memos, pass logs, board minutes, portfolio-support records, and versioned investment policies. The public talks describe process but rarely show the contemporaneous artifact. [researcher inference | strong]
- Build security- and vehicle-level ledgers for Israel Seed, Benchmark, and Aleph: company, date, vehicle, partner, sourcing, IC, board seat, cost, ownership, follow-on, dilution, disposition, gross proceeds, and net fund cash flows. Ordinary failures and write-offs must stay in the denominator. [researcher inference | strong]
- Reconstruct WeWork and Frank governance from primary records. For WeWork, separate Dunlevie, Eisenberg, Benchmark, SoftBank, management, and the board. For Frank, separate Javice's criminal disposition from the unresolved holder contract dispute and from any still-unknown diligence or knowledge evidence. [researcher inference | strong]
- Score the forecast ledger prospectively and preserve the original wording, horizon gaps, and baselines rather than converting thematic claims into successes after the fact. [researcher inference | strong]
- Resolve person/team/vehicle attribution for PictureVision, Shopping.com, Wix, WeWork, Lemonade, Healthy.io, Windward, Dream Security, and unnamed examples before assigning a “greatest investment,” mistake, or return to Eisenberg. [researcher inference | strong]
Central falsifier. If relationship-led, values-aligned, scale-oriented investments do not outperform a stage-, vintage-, price-, ownership-, geography-, and partner-adjusted denominator that includes ordinary failures, write-offs, governance breakdowns, and adverse outcomes—not only selected winners—then the talks establish a coherent and evolving worldview, not a demonstrated investment edge. Evidence that the stated backcasting, governance, ownership, and abandonment rules were absent from contemporaneous decisions would further falsify the claim that later explanations describe the process actually used. [researcher inference | strong]
Model 1: Backcast the Dependency Chain
- Rule — [investor-stated | strong] Start with a concrete successful future, work backward through every necessary domino, separate controllable work from external dependencies, and decline the investment when an indispensable blocker cannot resolve within the fund, financing, or execution horizon. Eisenberg credits Bruce Dunlevie with the companion prompt, “what can go right?”; that is bounded upside analysis, not generic optimism. EconTalk, 8:00–14:51
- Evidence status — [researcher inference | strong] The rule is directly stated in a complete official transcript and recurs in several decisions; its causal contribution to returns is unproven because no contemporaneous memo/pass denominator or ownership-adjusted result set is public.
- Provenance and origin — [retrospective witness | strong] Eisenberg locates the method in Benchmark-era teaching from Dunlevie and in his own early PictureVision learning; Milk, Honey and Uncertainty later gives Dunlevie’s related staircase model of sequential low-probability steps. EconTalk, career/backcasting passages Milk, Honey and Uncertainty, PDF pp. 47–49
- Mechanism and reasoning — [researcher inference | strong] Backcasting exposes hidden conjunction risk: a large outcome may require technology, regulation, distribution, financing, and behavior all to succeed. Naming the chain converts a story into milestones and prevents one exciting premise from masking an impossible timing dependency.
- Historical and vehicle context — [documented behavior | moderate] The method spans Eisenberg’s recollections of pre–Israel Seed PictureVision, Benchmark mentorship, and later Aleph investing. Those institutions, Eisenberg’s personal fee investment, and the legal deal vehicle must remain separate; Kodak’s acquisition verifies PictureVision’s company outcome, not his return. Kodak 2000 filing
- When to use — [researcher inference | strong] Use it for regulated, physical, marketplace, platform-dependent, or behavior-change businesses. Do not use it to manufacture precision where evidence is absent, or when a single external dependency—such as an unbounded autonomous-vehicle deployment timetable—dominates all company learning.
- How to apply it — [researcher inference | strong] Write the terminal customer behavior and economics; list each domino, owner, evidence threshold, correlation, cost, and deadline; identify the next irreversible step. Kill when a necessary domino has no credible owner, the time-to-proof exceeds cash plus reserve capacity, the blocker is outside company influence without a hedge, or two consecutive gates move without new evidence.
- Examples — [documented behavior | strong]
- PictureVision — [retrospective witness | moderate]: analog-processing distribution was a bridge to online sharing before broadband; Eisenberg qualifies his credit, and Kodak later acquired the company. EconTalk, PictureVision passages Kodak 2000 filing
- Healthy.io — [documented behavior | moderate]: camera, calibration, regulation, reimbursement, and patient behavior formed the dependency chain; FDA clearance advanced some gates, while layoffs show commercial and burn risk remained. Healthy.io essay, body ¶¶5–24 FDA K210069
- Autonomous vehicles — [investor-stated | strong]: Eisenberg says he rejected the category because indispensable dependencies took longer to resolve than the investment horizon. EconTalk, backcasting/rejection passage
- Evidence — [investor-stated | strong] Independent underlying routes are the official EconTalk transcript, the complete Hebrew book, Kodak filings, the contemporaneous Healthy.io essay, and FDA records. The method is strongly evidenced as Eisenberg’s framework; it is only moderately supported as behavior and insufficiently supported as an economic edge. Local evidence map: EconTalk note, PictureVision case, and Healthy.io case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] Narrative owners can make every domino sound tractable; correlated dependencies break naïve multiplication; a future can be desirable but unfinanceable. Frank is the compliance/metric-verification warning: a mission story did not substitute for independently reproducing customer data, and later adjudication concerns founder conduct, not proven investor knowledge. DOJ sentencing release
- Evolution and contradictions — [researcher inference | moderate] The early “what can go right” posture becomes explicit dependency mapping in 2022 and preemption language in 2026. The unresolved contradiction is macro confidence without predeclared probabilities: the model is rigorous only when its falsifiers are dated before outcomes. 18Forty 2026, opening/Iran-response questions
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] For AI, add model access, compute/energy, data rights, evaluation, security, distribution, gross-margin repricing, and regulatory approval as separate dominoes. Stress a leading model copying the feature and a provider changing price or access. Transfer succeeds when gates generate proprietary evidence; it fails when a generic AI story is relabeled a roadmap. Grounded current example: Healthy.io shows why FDA gate progress and later layoffs must coexist in one dependency map. FDA K222921 2024 layoffs
Model 2: Compound Relationships into an Institutional Network
- Rule — [investor-stated | strong] Treat long relationships as an information and access advantage, then institutionalize them so the network can source, recruit, sell, finance, and test claims for the whole partnership; relationship strength is a prior, never a substitute for underwriting. EconTalk, 1:06–8:00 Max Raskin, “Herzlean Task”
- Evidence status — [researcher inference | strong] Multiple direct interviews and company narratives establish the practice, but there is no network-sourced versus non-network denominator, price control, conflict audit, or causal return study.
- Provenance and origin — [retrospective witness | strong] Eisenberg says his early philosophy evolved toward networks and people; the Max Raskin Q&A describes an associative people map and Aleph CRM, while the official EconTalk transcript describes collaboration as core. EconTalk, 1:06–8:00 Max Raskin, “Herzlean Task”
- Mechanism and reasoning — [researcher inference | strong] Repeated interaction reveals conduct under changing conditions; independent referral convergence increases discovery probability; structured memory lets contacts serve multiple portfolio needs. The edge compounds only if observations, conflicts, and outcomes are logged rather than remaining founder folklore.
- Historical and vehicle context — [documented behavior | strong] WeWork referrals occurred in the Benchmark context; Empathy and RiseUp relationship narratives are Aleph-era; Lemonade’s history is jointly institutional and must not erase Eden Shochat, Aleph vehicles, or Daniel Schreiber’s decisions. The Commentator, WeWork sourcing question RiseUp opening
- When to use — [researcher inference | strong] Use when character, recruiting, sensitive customers, or long board work matter and when several independent nodes provide distinct evidence. Do not use closeness as proof, pay an unmodeled familiarity premium, or let a personal relationship determine firm credit or governance rights.
- How to apply it — [researcher inference | strong] Record every referral path, observed behavior, conflict, rejected reference, help delivered, and counterfactual source; blind-score product and market evidence before exposing relationship strength. Kill the relationship premium when references are circular, negative evidence is suppressed, the founder resists independent checks, or price/terms require assuming friendship changes economics.
- Examples — [documented behavior | strong]
- WeWork — [retrospective witness | strong]: independent referrals converged on Neumann, a genuine sourcing signal that did not prevent later governance and balance-sheet failure. Commentator, sourcing question WeWork Chapter 11 8-K
- Empathy — [investor-stated | moderate]: Ron Gura’s decade-long relationship and Aleph EIR period supplied behavioral context, but the launch essay gives no outcome denominator. Empathy, body ¶¶3–8
- RiseUp — [investor-stated | provisional]: Yuval Samet brainstormed with Eisenberg and returned with two cofounders; the stable text ends before the investment rationale or outcome. RiseUp opening
- Evidence — [documented behavior | strong] The EconTalk transcript, Raskin Q&A, Commentator Q&A, Empathy essay, RiseUp opening, and WeWork filing are distinct underlying routes. The inaccessible body of Invest in Relationships, Not Transactions contributes only title/context, not the mechanism. Relationships opening Local evidence map: Raskin note, EconTalk note, and WeWork case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] Dense networks create homophily, privilege, reciprocity, stale information, privacy risk, founder entrenchment, and reluctance to stop. WeWork is the strongest adverse control; a compelling founder and convergent referrals did not validate lease duration, related parties, or control structure. WeWork S-1, risk/governance sections
- Evolution and contradictions — [researcher inference | strong] Personal memory evolves into an Aleph operating system and a public relationships doctrine. After WeWork, the talks foreground steady boards and predictable conduct, but the record does not show when a new escalation rule entered actual policy.
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] AI-assisted outreach makes contact volume cheap and trusted context scarcer. Maintain a consented relationship graph with provenance, access controls, freshness, and outcome tags; separate access source from IC score. Transfer fails when CRM density becomes an unexamined social graph or when synthetic personalization masquerades as trust. No additional 2026 company example is publicly supported; a labeled hypothetical is to test whether a network-sourced deal retains its blind IC score after the relationship prior is revealed.
Model 3: Pick Learn-It-All Outsiders and Complementary Teams
- Rule — [investor-stated | strong] Prefer founders who see the world differently, learn an unfamiliar domain faster than incumbents, and recruit complementary strengths; “people first” means testing learning behavior and team construction, not betting on charisma. Tree preview, Preface ¶¶13–15 20VC AI, 54:28–56:30
- Evidence status — [researcher inference | strong] Eisenberg states people as his claimed specialization and provides several selected cases. There is no pass denominator or comparison with technology-first selection, and Melio: Investing in Great People has no accessible body.
- Provenance and origin — [investor-stated | strong] The Tree of Life and Prosperity preview says he focuses on people because he lacks deep technology/market expertise, while conceding that passion may be retrospectively narrated as strategy. Tree preview, Preface ¶¶13–15
- Mechanism and reasoning — [researcher inference | strong] Outsiders can discard incumbent assumptions; rapid vocabulary, expert, and evidence acquisition closes their knowledge gap. Complementary partners reduce correlated blind spots and broaden networks, but only if disagreement is safe and responsibilities are explicit.
- Historical and vehicle context — [retrospective witness | strong] Eisenberg credits Shlomo Kalish’s Israeli relationships and experience as complementary to his own business model at Israel Seed, and credits Eden Shochat plus institutional helpers in Aleph’s formation. This is team evidence, not sole-founder mythology. Human Founder, 20:36–22:38 and Aleph-formation discussion
- When to use — [researcher inference | strong] Use in categories where an entrenched model is breaking and the founder demonstrates learning velocity, recruiting pull, humility, and mission. Do not equate inexperience with originality, hours with quality, or an unusual worldview with ethics, regulatory competence, or truthfulness.
- How to apply it — [researcher inference | strong] Ask for the founder’s last three changed beliefs, primary evidence that changed them, missing executive roles, reference dissent, and a domain-expert challenge. Kill when the founder cannot name falsifiers, repeatedly ignores disconfirming data, cannot recruit the missing skill, centralizes all decisions, or treats controls as incumbent obstruction.
- Examples — [researcher inference | strong]
- Healthy.io — [investor-stated | strong]: Yonatan Adiri entered diagnostics as an outsider but repeatedly learned reimbursement, regulation, optics, robotics, and patient workflow before Aleph’s Series B. Healthy.io, body ¶¶5–24
- Firm formation — [retrospective witness | moderate]: Eisenberg explicitly credits Kalish’s complementary experience and Shochat’s distinct partnership role; no source supports a lone-founder account. Human Founder, 20:36–22:38 and Aleph formation
- WeWork — [researcher inference | strong]: Neumann’s distinctive worldview attracted attention but did not protect the company from founder-control, related-party, and financing risk. WeWork S-1
- Evidence — [investor-stated | strong] Independent sources include the partial Tree preview, full Healthy.io essay, Human Founder audio, official 20VC captions, and WeWork filings. In the 20VC interview Eisenberg explicitly prefers a net-new, naïve founder for a new market and then corrects himself to credit Schreiber for Lemonade licensing. 20VC AI, 54:28–56:30 Local evidence map: Healthy.io writing note, Human Founder note, and WeWork case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] Founder selection is vulnerable to halo effects, pedigree/network access, survivorship, and post hoc character stories. Frank shows why values and ambition cannot replace raw-data reproduction and compliance; Javice’s conviction does not establish Eisenberg or Aleph knowledge. SEC Frank release
- Evolution and contradictions — [researcher inference | moderate] The corpus progresses from informal people intuition to learn-it-all and team-complementarity language, while Tree’s self-critique resists a falsely systematic history. Management scarcity in Israel also means founder quality must include the ability to import or grow scale leadership.
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] Model-assisted founders can learn vocabulary quickly, so distinguish fluent synthesis from changed behavior: inspect experiments, source provenance, expert corrections, security/compliance decisions, and recruited operators. Transfer fails when polished AI-generated answers are mistaken for earned domain judgment. Grounded current example: Healthy.io combines outsider learning with regulatory progress, while its layoffs keep commercial execution as the countertest. 2024 layoffs
Model 4: Match Venture Capital to Power-Law Scale and Buy Ownership Early
- Rule — [investor-stated | strong] A useful product, good company, or important ecosystem outcome is not automatically venture-returning. Institutional capital requires a credible path to fund-scale proceeds and enough early ownership for an outlier to matter; price is a conditional input, not irrelevant. DooHickeys, ¶¶1–11 20VC joint, 21:47–23:50
- Evidence status — [researcher inference | strong] The rule recurs from 2006 through 2024 and is supported by public holding fragments, but audited gross/net cash flows and a complete loss denominator are missing across Israel Seed, Benchmark, and Aleph.
- Provenance and origin — [investor-stated | strong] DooHickeys separates bootstrappable utilities from venture opportunities; Eight Things separates ecosystem importance, company scale, and LP return. Later 20VC remarks add meaningful initial ownership and rare reliance on pro rata. DooHickeys, ¶¶1–11 Eight Things, central test
- Mechanism and reasoning — [researcher inference | strong] Venture returns are power-law distributed; small checks without retained ownership can produce visible wins that do not return a fund. Early conviction can buy ownership before proof, while reserves and later dilution determine whether that ownership survives.
- Historical and vehicle context — [documented behavior | strong] Israel Seed’s seed strategy, Benchmark’s Wix block, and Aleph’s Lemonade/Windward holdings are different vehicle records. Company value, fund gross proceeds, net LP return, and Eisenberg’s personal economics cannot be interchanged. Wix F-1/A, principal shareholders
- When to use — [researcher inference | strong] Use before every institutional check and follow-on. Do not force venture money into a capped market, reject a small initial wedge without testing expansion, or justify any valuation by declaring the company an outlier in advance.
- How to apply it — [researcher inference | strong] Build an ownership-sensitive proceeds table across ordinary, strong, and outlier outcomes; include entry price, security, dilution, reserves, follow-ons, preferences, taxes, fees, and time. Kill when no plausible outcome returns meaningful fund capital, ownership cannot survive the financing plan, the initial market is a ceiling without an expansion proof, or required terms destroy common-holder alignment.
- Examples — [researcher inference | strong]
- Wix — [researcher inference | strong]: Benchmark held 13.2% pre-IPO and did not sell in the offering; the later reported disposition is not audited net return. Wix F-1/A, principal holders
- Lemonade — [researcher inference | strong]: Aleph held 10.3% pre-IPO, yet the company remains loss-making and fund realization is incomplete. Lemonade S-1/A, holders/financings
- Israel Seed IV — [researcher inference | moderate]: seed ownership plus power-law strategy did not prevent a weak vintage or failed successor-fund raise. CalPERS snapshot Fund V abandonment
- Evidence — [documented behavior | strong] Independent support comes from two full Eisenberg essays, 2012 and 2024 interviews, SEC issuer filings, and contemporary fund reporting. The stable Lemonade investment essay exposes only its opening power-law premise, not the absent Team/Mission/Moat/Market/Stage analysis. Lemonade opening Local evidence map: DooHickeys note, Wix case, Lemonade case, and Israel Seed IV case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] TAM inflation, excessive entry price, reserve starvation, preference stacks, pro-rata complacency, and fund-size drift can erase the model. A rare company may warrant a premium, but middling outcomes—more common ex ante—remain highly price-sensitive. 20VC joint, 21:47–23:50
- Evolution and contradictions — [researcher inference | strong] The early scale filter becomes a four-variable discipline—access, price, ownership, usable capital. RiseUp’s opening reveals a local-market objection but not the exception rule; it cannot be used to claim that small wedges were systematically accepted.
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] AI lowers creation cost and raises feature crowding. Require retained cohorts, expansion, proprietary complements, distribution independence, and a capitalization path before calling rapid revenue venture scale. A small durable cash business may be excellent; the model says finance it appropriately rather than force it into a fund-return narrative. Grounded current example: Freightos has public transaction scale and continuing losses, exactly why scale and fund-return economics must remain separate. 2025 results
Model 5: Seek Scarce Expressions of Secular Change
- Rule — [investor-stated | strong] Invest in a differentiated company that expresses an important secular shift; avoid buying crowded category exposure. Scarcity can earn a valuation premium only when durable growth and gross profit accompany it. 20VC AI, 12:12–17:52
- Evidence status — [researcher inference | strong] The model is directly stated across interviews and essays and has multiple company illustrations, but no matched study distinguishes scarcity from novelty or shows excess returns after price.
- Provenance and origin — [retrospective witness | strong] Eisenberg says a 2005 study of sell-side analysts taught him that scarce public exposure to an important future can command a premium; the 2006 DooHickeys essay already warns that cheap creation produces me-too categories. 20VC AI, 12:12–17:52 DooHickeys
- Mechanism and reasoning — [researcher inference | strong] A secular shift expands demand, while true scarcity protects customer acquisition, pricing, talent, and investor attention. Crowding reverses those benefits: imitation raises acquisition cost, compresses differentiation, and allows platform owners to appropriate value.
- Historical and vehicle context — [investor-stated | moderate] Platform shifts appear in the Benchmark-era Zlango, Wix, and adtech commentary and the Aleph-era Healthy.io, Windward, Lemonade, and AI thesis. “We invested” still denotes a firm/vehicle unless closing records allocate individual action.
- When to use — [researcher inference | strong] Use when a durable substrate—mobile cameras, cloud, global logistics data, AI, regulation, or behavior—changes the cost curve and few companies own the needed complement. Do not use when “different” means no demand, when category scarcity comes from an impossible market, or when a platform can bundle the feature cheaply.
- How to apply it — [researcher inference | strong] Define the secular variable, date the evidence, map competitors and substitutes, identify the scarce asset and its legal control, then test growth, gross profit, retention, and copy time. Kill when differentiation is merely interface, the asset does not compound, the market must be educated beyond financing capacity, or platform replication destroys unit economics.
- Examples — [documented behavior | strong]
- Zlango — [investor-stated | provisional]: smartphones supplied a missing platform and revived the proposition, but the talk gives no ownership or return evidence. TCTV, 04:04–07:42
- Healthy.io — [documented behavior | moderate]: improving phone cameras supported regulated home diagnostics; later layoffs keep commercial risk live. Healthy.io essay 2024 layoffs
- Adtech avoidance — [investor-stated | moderate]: worsening platform economics, public comparables, and crowded local funding triggered avoidance rather than a blanket internet rejection. 2016 Prediction
- Evidence — [investor-stated | strong] Independent routes include official 20VC captions, TCTV captions, the full 2016 essay, Healthy.io’s contemporaneous investment essay, and FDA records. They establish the heuristic and selected application, not a complete cohort. Local evidence map: 20VC AI note, TCTV note, and Healthy.io case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] Uniqueness can mask thin demand, regulation, long sales, or technical fragility. WeWork appeared category-defining and had a large market, yet duration mismatch and governance overwhelmed scarcity. Healthy.io shows a less terminal boundary: product/regulatory progress can coexist with layoffs and unknown economics. Healthy.io 2024 layoffs
- Evolution and contradictions — [researcher inference | moderate] The model moves from internet/platform transitions to “different, not better” and then to scarce AI complements. The tension is market education: obscurity can protect entry price while extending time and capital to adoption.
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] Score revenue velocity and complement construction separately. Current signals are proprietary workflow data, licensed rights, distribution, network density, physical integration, regulated trust, and switching evidence. Misuse is paying a scarcity premium for a wrapper whose model provider can erase it in one release. Grounded current example: Healthy.io retains regulated product evidence but unresolved private economics and recent layoffs, so scarcity is not treated as outcome proof. 2024 layoffs
Model 6: Underwrite AI Complements, Not Model Access
- Rule — [investor-stated | strong] Treat foundation-model access as a commoditizing input; durable applied-AI value must accumulate in domain knowledge, proprietary and lawful data, distribution, networks, physical integration, or full-stack workflow control. Aleph AI Team, moat and program sections
- Evidence status — [researcher inference | moderate] The model is explicit and current but young: the Aleph AI program has no mature cohort, unnamed marketplace examples cannot be audited, and prior Windward/Lemonade success does not prove the 2025 program.
- Provenance and origin — [investor-stated | strong] The 2024 20VC interview distinguishes transformational AI from a capital-destroying gold rush and limits Aleph to applied AI; the 2025 essay formalizes complements and “AI meteor” failure. 20VC AI, 01:18–14:09 Aleph AI Team
- Mechanism and reasoning — [researcher inference | strong] Model capability diffuses and depreciates; complements compound through customer-specific feedback, rights, integration, and repeated use. Full-stack applications can own the economic loop while foundation-model investors bear enormous capital, talent, and key-person concentration.
- Historical and vehicle context — [investor-stated | moderate] Eisenberg retrospectively classifies Windward and Lemonade as pre-LLM applied AI; the Aleph AI Team offers up to $3 million at pre-seed with an 18-month revenue ambition. These are Aleph-level claims, not personal allocations or guaranteed terms. Aleph AI Team, program terms
- When to use — [researcher inference | strong] Use for AI-native diligence and for legacy companies adding AI. Do not assume a data moat without rights and feedback, reject foundation infrastructure categorically outside Aleph’s Israel-specific constraint, or treat rapid revenue as evidence of durability.
- How to apply it — [researcher inference | strong] Map model/provider dependence, data provenance and derived rights, evaluation loop, workflow ownership, distribution, switching cost, gross margin, security, and human override. Kill when the feature is reproducible with public APIs, data cannot lawfully train/improve the system, customer learning does not accumulate, provider repricing breaks margin, or evaluations cannot bound material harm.
- Examples — [researcher inference | moderate]
- Windward — [retrospective witness | moderate]: domain expertise, maritime data, and analyst/compliance workflow form complements; its completed acquisition is a company event, not a disclosed fund return. 20VC AI, 09:17–10:42 Windward admission document
- Lemonade — [retrospective witness | moderate]: a regulated carrier owns more workflow than an AI feature, while losses, capital, reinsurance, and model risk remain material. 20VC AI, 09:17–10:42 Lemonade 2025 10-K
- Frank — [researcher inference | strong]: this non-AI control shows why user/data provenance must be reproduced whenever distribution rests on claimed scale. SEC Frank release
- Evidence — [investor-stated | moderate] Two direct first-party sources support the rule; issuer filings independently ground the older company examples. No disclosed Aleph AI Team portfolio, terms schedule, failure set, or realized outcome yet tests the program. Local evidence map: AI Team note, 20VC AI note, and Windward case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] “Proprietary data” may be nonexclusive, biased, or unlawful; distribution can be rented; workflows can resist automation; networks may stay local; model/API changes can erase gross margin. The 18-month revenue target may select exactly the copyable applications the essay rejects unless moat gates remain separate.
- Evolution and contradictions — [researcher inference | moderate] This is the latest version of the 2006 internet and 2011 cloud insight that value moves when a layer commoditizes. A live tension remains between decentralized application discovery and the 2025 claim that compute/energy make AI national infrastructure. Misgav, 20:36–31:25
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] Require a model-provider stress test, data-rights opinion, versioned evals, unit-cost sensitivity, customer feedback loop, switching evidence, and a dated complement roadmap. The rule transfers to robotics and defense only with physical-safety, export-control, procurement, and human-command gates; otherwise “full stack” becomes an excuse for unbounded capital. Grounded current example: Windward paired domain data/workflow with a completed 2025 acquisition, though fund economics remain undisclosed. FCA completion
Model 7: Practice Patient, Milestone-Gated Capital
- Rule — [investor-stated | strong] Give uncertain technologies and markets time, but purchase learning in bounded stages; patience is warranted only while a named external or company-controlled gate is moving and the next check preserves positive asymmetry. The Golden Calf, ¶¶7–12 Milk, Honey and Uncertainty, PDF pp. 47–49
- Evidence status — [researcher inference | strong] Two full writings state the logic and several deal histories supply survivor and failure controls. Public evidence still lacks the original tranche terms, reserve policy, abandonment schedule, and full set of patient investments that failed.
- Provenance and origin — [investor-stated | strong] Milk, Honey and Uncertainty distinguishes unknowable futures from calculable risk and recommends sequential action; The Golden Calf warns against demanding premature visible results. Milk, Honey and Uncertainty, PDF pp. 47–49 The Golden Calf, ¶¶7–12
- Mechanism and reasoning — [researcher inference | strong] A small committed step buys information and preserves the option to continue; low burn extends the observation window; a power-law payoff can repay many bounded failures. Stage gates prevent uncertain probability from becoming unlimited duration or capital.
- Historical and vehicle context — [retrospective witness | moderate] Healthy.io and Seeking Alpha are Aleph- and Benchmark-era survivor narratives; MemLink and Print Life are Israel Seed-era failure/decision narratives. None exposes complete security-level follow-ons, so “patient” cannot be mapped to a verified fund return.
- When to use — [researcher inference | strong] Use when technical, regulatory, procurement, or behavior evidence is directionally measurable and a tranche reaches the next inflection. Do not use when the next round—not the product milestone—is the only plan, the gate is static, or the fund lacks reserves and horizon for the claimed wait.
- How to apply it — [researcher inference | strong] Before funding, specify the uncertainty, next evidence event, budget, deadline, external-gate indicator, financing coverage, and cumulative loss cap. Kill when two gates move without new evidence, a required external condition worsens, the fully funded path disappears, a milestone is rewritten after failure, or the opportunity cost exceeds the predeclared cap.
- Examples — [researcher inference | strong]
- Healthy.io — [documented behavior | moderate]: smartphone-camera and regulatory readiness advanced; FDA clearance supports product progress while private economics remain unknown. FDA K222921
- Seeking Alpha — [retrospective witness | moderate]: Eisenberg describes a fourteen-year, low-burn build before business-model and mobile acceleration; the survivor narrative supplies no fund return. Golden Calf, company example
- MemLink — [researcher inference | moderate]: a bridge without a fully funded commercialization path preceded shutdown. MemLink shutdown report
- Print Life — [retrospective witness | moderate]: a slow pivot and financing dependence turned patience into costly delay and layoffs. Human Founder
- Evidence — [documented behavior | strong] Independent underlying sources are two full investor writings, FDA records, contemporary Globes financing/shutdown reports, and the Human Founder interview. Together they support the distinction between staged learning and financing dependence, not a quantified optimal hold period. Local evidence map: Golden Calf note, Healthy.io case, Seeking Alpha case, and MemLink case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] Survivorship, moving milestones, sunk-cost bias, correlated bets, dilution, bridge seniority, and board attachment can make delay look principled. Foxcom/MobileAccess is the reversal control: a near-death company later survived and sold, so a stop rule should be evidence-based, not outcome-fitted. Corning acquisition notice
- Evolution and contradictions — [researcher inference | strong] Patience broadens from software and diagnostics to five-to-seven-year “atoms” in 2026, while autonomous vehicles are rejected for excessive duration and Print Life is closed. The coherent boundary is financeable, dated dependency progress—not technology difficulty itself. Agency Under Fire, 04:35–10:38
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] Separate technical, safety, regulatory, procurement, distribution, and economic gates for AI, defense, climate, and biotech. Fund the bottleneck that can change; require a fully funded downside plan and non-sponsor review of exceptions. The model fails when “patient capital” becomes a brand for bridge rounds that buy only time. Grounded current example: Healthy.io shows regulatory progress plus continuing financing and distribution risk rather than a simple patience success. Series D announcement 2024 layoffs
Model 8: Match Capital Intensity to Durable Financing and Customer Need
- Rule — [investor-stated | strong] Ask whether capital is intrinsically required to create customer trust or product capability, or merely available. Finance the former with duration-matched reserves and controls; treat excess unusable cash and fixed capacity as strategic risk. 20VC joint, 14:53–18:59 Human Founder, 09:34–14:07
- Evidence status — [researcher inference | strong] The rule is directly articulated in 2021 and candidly illustrated by Print Life. Its application is not fully observable because facility, reserve, security, and syndicate terms are mostly absent.
- Provenance and origin — [retrospective witness | strong] Print Life taught Eisenberg that vertical integration can make the business dependent on an always-open financing source; the joint 20VC interview distinguishes balance-sheet credibility businesses from ordinary software that can suffer capital “indigestion.” Human Founder, Print Life discussion 20VC joint, 14:53–18:59
- Mechanism and reasoning — [researcher inference | strong] Fixed assets, regulatory capital, inventory, leases, and long procurement cycles create duration and refinancing risk. Capital can also be productive when the balance sheet itself wins customer trust or unlocks a compounding physical/data asset; the key is evidence that dollars deepen the mechanism rather than conceal weak demand.
- Historical and vehicle context — [documented behavior | moderate] The cases span Israel Seed-era hardware/facilities, Benchmark-era WeWork, and Aleph-era Freightos, Lemonade, and hard-tech ambitions. Each vehicle’s reserves, ownership, and follow-on obligations differ and are not reconstructed from company financing totals.
- When to use — [researcher inference | strong] Use for fintech/insurance, hardware, manufacturing, defense, biotech, marketplaces with working capital, and any lease-heavy model. Do not assume all software is capital-light, treat a large round as validation, or count customer funds/regulatory capital as freely spendable growth capital.
- How to apply it — [researcher inference | strong] Build a source-and-use map by restricted/unrestricted cash, fixed obligations, milestone, customer benefit, and refinancing date; stress zero new equity and a demand shock. Kill when the business cannot reach the next value inflection with committed funds, capacity precedes evidenced utilization, duration is structurally mismatched, or new money only repays old risk without changing customer economics.
- Examples — [researcher inference | strong]
- Print Life — [retrospective witness | moderate]: owned printing capacity preceded proven demand and financing durability; the company pivoted too slowly. Human Founder, Print Life discussion
- WeWork — [researcher inference | strong]: long leases funded short customer commitments, multiplying correlated exposure before Chapter 11 impaired old equity. WeWork S-1, lease/liquidity risks Chapter 11 8-K
- MemLink — [researcher inference | moderate]: commercialization required another $30–$40 million after $18 million raised; a bridge did not secure the outside round. MemLink capital requirement
- Evidence — [documented behavior | strong] Independent sources include the 20VC interview, Human Founder account, WeWork filings, and contemporaneous MemLink reports. Freightos and Lemonade filings add ongoing examples where gross booking value or premium scale must not be confused with free cash or profitability. Freightos 2025 results Local evidence map: 20VC joint note, Print Life case, and MemLink case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] An overly capital-light rule can miss regulated carriers, physical infrastructure, and data networks; undercapitalization can be as fatal as excess. Foxcom/MobileAccess survived a near-death period and later sold, so rescue financing may be rational when signed customer evidence and a fully funded plan exist—not merely because survival later occurred.
- Evolution and contradictions — [researcher inference | moderate] The 2006 preference for asset-light internet models becomes a conditional 2021 capital test and then a 2026 interest in atoms, defense, and energy. This is an evolution from “avoid capital intensity” to “finance only necessary, governed intensity.” Wake Up Java, ¶¶4–9
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] Add compute reservations, model-inference commitments, energy, chip inventory, security certification, and sovereign procurement to the sources-and-uses map. Current signal: a dollar buys a measurable capability, customer contract, or margin improvement. Misuse: calling hyperscaler bills or subsidized pilots a moat. Grounded current example: Lemonade ended 2025 with scale, cash-consuming losses, and regulated insurance obligations, making capital purpose measurable. 2025 10-K
Model 9: Design Boards and Partnerships for Truth under Stress
- Rule — [investor-stated | strong] Build small, equal, predictable partnerships and data-rich boards that make bad news safe to surface, concentrate discussion on one to three consequential questions, and protect integrity, solvency, and stakeholder obligations when momentum breaks. 20VC AI, 52:29–53:48 20VC joint, 30:19–33:15
- Evidence status — [researcher inference | strong] Multiple direct sources state partnership and board mechanics, with Shopping.com, Print Life, WeWork, and Frank as adverse controls. The record rarely reveals contemporaneous votes, minutes, dissent, or causal effect.
- Provenance and origin — [retrospective witness | strong] Eisenberg attributes Aleph’s equal-economics partnership to Benchmark’s model and recalls DealTime/Shopping.com and ePinions as lessons in choosing calm co-investors. In 2024 he describes a data-rich board letter, preparation calls, and a 45-minute discussion. 20VC joint, 30:19–33:15 20VC AI, 52:29–53:48
- Mechanism and reasoning — [researcher inference | strong] Equal economics reduces internal deal bargaining; predictable conduct lowers information withholding; pre-read data protects scarce meeting time; focused questions reveal decisions rather than reward presentation. Independent controls keep “founder as hero” from becoming founder impunity.
- Historical and vehicle context — [contemporaneous record | strong] Meet Aleph is Eden Shochat-authored and calls Aleph an equal partnership; Aleph III is collectively signed. These firm statements cannot be assigned solely to Eisenberg, while individual board seats and fund voting power require issuer/vehicle records. Meet Aleph Aleph III
- When to use — [researcher inference | strong] Use from partnership formation through every board, especially before rapid hiring, related-party deals, regulated claims, capital raises, or shutdown. Do not let brevity eliminate dissent, use “stagehand” to evade fiduciary duties, or interpret equal economics as equal contribution to every deal.
- How to apply it — [researcher inference | strong] Send verified operating, cash, compliance, and stakeholder data before the meeting; solicit non-sponsor dissent; assign each decision, owner, trigger, and escalation path. Kill or suspend support when raw metrics cannot be reproduced, related parties evade independent approval, runway/solvency triggers breach, whistleblowers lack a route, or management repeatedly withholds material variance.
- Examples — [researcher inference | strong]
- Shopping.com — [researcher inference | moderate]: the filing documents Eisenberg’s board tenure and material traffic concentration; later narratives credit multiple board actors. Shopping.com S-1/A
- Print Life — [retrospective witness | moderate]: Eisenberg describes a shared board/management failure to pivot and finance responsibly, followed by layoffs. Human Founder
- WeWork — [researcher inference | strong]: founder control and related parties show the failure of passive “stagehand” governance. WeWork S-1
- Frank — [researcher inference | strong]: the FTC warning and later founder adjudication show why claims and data need board-level authentication; they do not establish investor knowledge. FTC warning DOJ disposition
- Evidence — [documented behavior | strong] Independent routes include two interviews, official firm announcements, SEC filings, the FTC warning, and later DOJ adjudication. They support the need for controls; they do not establish which controls Aleph had, what anyone knew, or whether JPMorgan’s 2026 support-agreement allegations will prevail. Local evidence map: 20VC AI note, Print Life case, WeWork case, and Frank case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] Equal partnerships can deadlock; compact boards can become homogeneous; sponsor-prepared data can frame out bad news; intensity can silence founders. WeWork’s formal Benchmark seat belonged to Bruce Dunlevie, not Eisenberg, and Frank’s founder conviction must not be imputed to investors. WeWork 2023 proxy, board tenure DOJ Javice disposition
- Evolution and contradictions — [researcher inference | strong] The public voice moves from founder fascination in the 2017 WeWork story to explicit steady-board and data-discipline lessons after the failed IPO. The unresolved question is whether this was a changed operating system or retrospective articulation.
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] Board packs should include model/version evals, security incidents, data provenance, regulatory claims, human overrides, concentration, unit-cost drift, and scenario runway. AI may summarize the pack but cannot authenticate source data or replace accountable dissent. A mission score earns no credit without reproducible controls. Grounded current example: the Frank record makes reproducible customer data and regulator correspondence mandatory while preserving the boundary that founder adjudication is not investor knowledge. DOJ disposition
Model 10: Treat Realization as a Second Investment Decision
- Rule — [investor-stated | strong] When liquidity appears, re-underwrite the security you are about to own or keep. Hold only when information advantage and forward value justify concentration; otherwise realize or distribute rather than let a headline valuation substitute for cash. 20VC AI, 35:37–42:34
- Evidence status — [researcher inference | moderate] The current rule is directly stated in one rich interview and several filings reveal outcome fragments. Exact fund sales, lockups, distributions, taxes, hedges, fees, and carry are too incomplete to score skill.
- Provenance and origin — [investor-stated | strong] In 2024 Eisenberg favors listing at an available public price, holding winners selectively, and admits regret at not selling one or two positions during zero-rate conditions. 20VC AI, 35:37–42:34
- Mechanism and reasoning — [researcher inference | strong] A merger, IPO, or tender changes the risk object: private execution risk becomes liquid price, buyer credit, lockup, concentration, and tax risk. Re-underwriting prevents paper marks from being mistaken for DPI and preserves the option to redeploy.
- Historical and vehicle context — [documented behavior | strong] Tradeum’s stock sale belongs to Israel Seed; Wix’s block belonged to Benchmark funds; Windward and Lemonade involve Aleph entities plus distinct direct/personal holdings. Company exit value, fund proceeds, and Eisenberg personal sales are separate ledgers. Lemonade Form 4
- When to use — [researcher inference | strong] Use at acquisition consideration, IPO lockup expiry, tender, secondary, follow-on, distribution-in-kind, and every material public-price change. Do not automate selling solely because liquidity exists or hold solely to avoid regret, signal confidence, or protect a private mark.
- How to apply it — [researcher inference | strong] Compare after-tax/liquidity-adjusted expected value across cash, stock, hold, hedge, and distribute; test buyer runway, public comparables, lockup, correlation, ownership, information edge, fund duration, and downside. Sell or hedge when the original thesis is broken, concentration exceeds mandate, buyer security cannot be underwritten, or continued holding depends on a higher multiple rather than company evidence.
- Examples — [researcher inference | strong]
- Tradeum — [researcher inference | moderate]: a pre-revenue company became VerticalNet shares valued near $474 million; the buyer fell over 99% before full realization and exact proceeds remain unknown. Acquisition report 2001 realization report
- Wix — [researcher inference | moderate]: its IPO and later reported Benchmark disposition show company liquidity without audited fund cash. Wix 2014 20-F
- Windward — [researcher inference | strong]: the 2025 cash acquisition and Aleph holdings are documented, yet prior sales and net fund return remain unknown. Windward offer/undertakings FCA completion
- Evidence — [documented behavior | strong] Independent sources include official 20VC captions, contemporary Tradeum reporting, SEC issuer filings, FCA completion evidence, and a direct Lemonade Form 4. They establish decisions and fragments, not a complete realization record. Local evidence map: 20VC AI note, Tradeum case, Wix case, and Windward case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] Early sale can destroy power-law upside; taxes, signaling, information restrictions, and distribution rights constrain action. Reported headline consideration may overstate cash; a later collapse does not prove a feasible hedge or sale existed at the relevant time.
- Evolution and contradictions — [researcher inference | moderate] Tradeum is the historical adverse case; the 2024 rule makes liquidity explicit and admits regret. The tension between riding winners and preferring earlier IPO liquidity is coherent only when information edge, concentration, and price are written separately.
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] Maintain a security-level disposition memo for token, tender, continuation-vehicle, public-stock, and M&A consideration. Include lockups, collars, vesting, market depth, sanctions/export exposure, and LP distribution mechanics. Misuse is citing the peak mark or acquisition headline as “return” without cash-flow and ownership evidence. Grounded current example: Windward completed a cash acquisition in 2025, yet absent security-level distributions still prevent a net-return claim. FCA completion
Model 11: Align Business Economics with Human Agency
- Rule — [investor-stated | strong] Prefer products whose revenue grows when customers gain capability, trust, dignity, safety, learning, ownership, or meaningful connection; translate values into business-model and governance design rather than treating mission as philanthropy or founder branding. Long Humanity, ¶¶1–28 EconTalk, 33:39–54:29
- Evidence status — [researcher inference | strong] Long Humanity, Empathy, covenantal capitalism, and EconTalk form a coherent direct-voice line. The causal claim that alignment improves returns is untested, and WeWork/Frank are material adverse controls.
- Provenance and origin — [investor-stated | strong] Long Humanity says the social damage of a prior platform cycle creates the next market opening; Covenantal Capitalism formalizes agency, ownership, trust, and stakeholder prosperity as economic architecture. Long Humanity, ¶¶1–28 Covenantal Capitalism, printed pp. 54–72
- Mechanism and reasoning — [researcher inference | strong] When customer benefit, payment, retention, reputation, and employee mission reinforce one another, values can lower distrust and deepen durable demand. Misaligned advertising, manipulation, or hidden fees can monetize dependency while externalizing harm.
- Historical and vehicle context — [investor-stated | moderate] The thesis spans Benchmark-era WeWork advocacy and Aleph-era Lemonade, Empathy, Frank, and RiseUp framing. These selected portfolio examples are institutional/promotional and do not assign sole credit or demonstrate a values-factor return.
- When to use — [researcher inference | strong] Use for products affecting vulnerable users, money, insurance, education, health, work, identity, grief, or community. Do not reject all advertising categorically, assume a subscription is aligned, or allow national/religious purpose to override LP duties and individual rights.
- How to apply it — [researcher inference | strong] Identify payer, beneficiary, externalized party, revenue-triggering behavior, data rights, pricing, appeals, harm metric, and board owner. Kill when revenue rises as customer welfare falls, claims cannot be independently measured, consent/exit is not credible, vulnerable users bear hidden downside, or growth pressure repeatedly overrides stated protections.
- Examples — [researcher inference | strong]
- Lemonade — [documented behavior | strong]: fixed-fee/Giveback design sought claims alignment, while filings show severe early loss ratios and ongoing losses. Lemonade S-1/A
- Empathy — [investor-stated | provisional]: software is meant to reduce bereavement administration, but the launch essay lacks an outcome/economics denominator. Empathy essay
- WeWork — [researcher inference | strong]: real community demand coexisted with unsustainable leases and governance. WeWork Chapter 11 8-K
- Frank — [researcher inference | strong]: education-access framing did not substitute for verified data and controls; founder adjudication is not an investor-knowledge finding. DOJ disposition
- Evidence — [documented behavior | strong] Independent routes include full first-party essays, an academic PDF, official EconTalk transcript, SEC filings, and DOJ adjudication. The RiseUp page has only two opening paragraphs and cannot support product-impact claims. RiseUp opening Local evidence map: Long Humanity note, Empathy note, WeWork case, and Frank case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] Values can be circular, exclusionary, privacy-invasive, paternalistic, or expensive; stakeholder objectives can conflict. Frank’s criminal disposition concerns Javice, not proven investor knowledge; JPMorgan’s 2026 contractual claim against early holders remains unresolved and separate. JPMorgan complaint mirror, allegations only
- Evolution and contradictions — [researcher inference | strong] The line develops from community/humanity into fraternity, covenant, and national prosperity. Tree’s admission that passion may be re-narrated as strategy and WeWork/Frank prevent the mature framework from being read as demonstrated edge.
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] For AI, convert values into collection limits, consent, evaluation sets, appeal paths, pricing rules, human override, red-team harms, and compensation metrics. Current grounded test: revenue retention should coexist with better verified customer outcomes. Misuse: a “responsible AI” page without product constraints, board ownership, or raw evidence. Grounded current example: Lemonade reports substantial 2025 scale and continuing losses, allowing customer, loss, capital, and mission claims to be tested together. 2025 10-K
Model 12: Build Portability and Power-to-the-Edge into Product Architecture
- Rule — [investor-stated | moderate] Design systems so users and local actors can carry identity, relationships, data, and decision power across providers; credible exit and edge capability discipline centralized platforms and institutions. Tower of Babel, ¶¶6–12 18Forty Civic, 20:58–31:52
- Evidence status — [researcher inference | provisional] The architecture is directly advocated in a full op-ed and two interviews, but no disclosed investment application or company outcome connects it to Eisenberg’s venture decisions.
- Provenance and origin — [investor-stated | strong] Big Tech Is a Modern Tower of Babel proposes portable identity, keys, and social graphs as a “scattering” remedy; the 2023 18Forty interview generalizes technology’s movement of capability to the network edge. Tower of Babel, ¶¶1–12 18Forty Civic, 20:58–31:52
- Mechanism and reasoning — [researcher inference | strong] Portability lowers switching cost and platform coercion; local tools let users and civic groups discover and respond faster than central planners. Credible exit promotes competition, while common infrastructure preserves interoperability.
- Historical and vehicle context — [researcher inference | moderate] The model is a political/product extension of Eisenberg’s earlier network and internet work, not a disclosed Aleph portfolio screen. Crypto-network and civic examples should not be converted into firm investments or returns.
- When to use — [researcher inference | strong] Use for identity, social, data, finance, marketplaces, public services, and AI agents where platform lock-in or state latency matters. Do not decentralize safety-critical command, assume users can custody keys, or confuse nominal export with usable interoperability.
- How to apply it — [researcher inference | strong] Test data/identity export, semantic compatibility, switching time, key recovery, moderation, privacy leakage, spam/fraud, child safety, and governance of the shared layer. Kill when exit is technically available but economically unusable, portability increases harm without recourse, or the protocol remains controlled by one vendor.
- Examples — [investor-stated | moderate]
- Big Tech — [investor-stated | provisional]: accumulated control is the adverse case; portable identity/social graphs are a proposed remedy, not validated welfare evidence. Tower of Babel, ¶¶1–12
- Civic reuse — [investor-stated | provisional]: tools built before October 7 were reportedly repurposed after the attack, illustrating edge capability without a comparative denominator. 18Forty Civic, 20:58–31:52
- Crypto/Web3 — [investor-stated | provisional]: ownership and exit are the aspiration, while host pushback exposes incentive and generalization gaps. EconTalk, 54:29–1:04:16
- Evidence — [researcher inference | provisional] Independent routes are the full op-ed, official EconTalk transcript, and OpenAI-transcribed 18Forty audio; they establish a product/policy doctrine, not a disclosed venture screen. Model-specific attempted-route ledger: the complete op-ed yielded architecture but no company; EconTalk yielded crypto aspiration but no named portfolio application; 18Forty Civic yielded civic reuse but no investable company or outcome; the official Aleph company page and 123-association deal ledger yielded no cited portability screen. Missing proof is three named product or investment decisions with contemporaneous criteria and outcomes. Aleph companies, current page Local evidence map: Tower of Babel note, 18Forty Civic note, and the talks synthesis.
- Limits, failure modes, and exception ledger — [researcher inference | strong] Portability can propagate abuse, fragment moderation, expose private graphs, shift security burden to users, and fail against network effects. The 2011 Amazon-anchor advocacy is the lifecycle boundary: a platform may create capability before later becoming a concentration risk. Hummus Part 4
- Evolution and contradictions — [researcher inference | strong] Early internet writing seeks enabling anchors; 2021 seeks to scatter accumulated platform power; 2025 treats AI compute/energy as centralized national infrastructure. The likely reconciliation is decentralized application discovery over coordinated substrate, but Eisenberg does not state the precise boundary.
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] Require machine-readable export, agent/data portability, multi-provider routing, key recovery, audit logs, moderation and liability design, and a real switching exercise. Transfer fails in defense, health, or finance when decentralized control removes accountable command or legally required oversight. No documented Eisenberg portfolio application clears this full checklist; labeled hypothetical: require an AI agent to export data, permissions, and history into a competing provider before crediting portability.
Model 13: Go Global from Inception by Mapping Local Constraints
- Rule — [investor-stated | strong] Use a small home market as pressure to build for global demand from inception, while explicitly importing or developing the sales, management, regulatory, and labor capacity the home ecosystem lacks. Wake Up Java, ¶¶1–9 Hummus Part 1
- Evidence status — [researcher inference | strong] The global-from-Israel thesis is consistent across two decades and several companies have public operating evidence. Its causal effect on returns and the full set of globally ambitious failures remain unknown.
- Provenance and origin — [investor-stated | strong] Wake Up Java argues that internet infrastructure and rules let Israeli firms reach global markets; the Hummus series then reframes startup quantity as a scale-talent constraint. Wake Up Java, ¶¶1–9 Hummus Part 1
- Mechanism and reasoning — [researcher inference | strong] Limited domestic demand discourages local optimization; global distribution expands TAM and exposes the company to stronger customers and capital. The same distance raises acquisition, management, time-zone, localization, regulatory, and hiring costs, so globalization works only when missing complements are financed and owned.
- Historical and vehicle context — [contemporaneous record | strong] Shochat’s 2013 Aleph launch announcement sets an Israel-to-large-global-company mandate, while Aleph III is a collective firm statement. Benchmark associations and Aleph companies cannot be merged into one vehicle or attributed only to Eisenberg. Meet Aleph Aleph III
- When to use — [researcher inference | strong] Use when the problem and product travel, digital or partner distribution can cross borders, and management can be distributed without breaking learning. Do not treat an English website as global proof, ignore a valid domestic wedge, or enter many countries before one repeatable channel and compliance model exist.
- How to apply it — [researcher inference | strong] Map home advantage, missing complement, target customer, beachhead, localization, regulation, data residency, sales leadership, support, working capital, and follow-on funding by geography. Kill a market when acquisition/payback, renewal, compliance, localization burden, or management span fails its predeclared gate; kill the global thesis when no market produces repeatable pull.
- Examples — [researcher inference | strong]
- Wix — [researcher inference | strong]: a self-service cloud product sold beyond Israel; the IPO verifies company scale, not Eisenberg’s personal economics. Wix F-1/A
- Freightos — [researcher inference | strong]: a cross-border workflow/marketplace reached 1.643 million 2025 transactions while remaining loss-making. Freightos 2025 results
- Healthy.io — [researcher inference | moderate]: US kidney-testing expansion followed regulatory progress; layoffs show global regulated distribution remained costly. FDA K210069 2024 layoffs
- Evidence — [documented behavior | strong] Independent sources include full essays, firm announcements, EconTalk/TCTV/Misgav interviews, and issuer filings. The stable RiseUp opening only records founders anticipating a nine-million-person objection; it does not disclose Aleph’s answer or a local-wedge exception. RiseUp opening Local evidence map: Wake Up Java note, Wix case, Freightos case, and Healthy.io case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] Global ambition can hide weak local fit, remote-customer distance, foreign key-person risk, regulatory fragmentation, and expensive premature offices. The TCTV/EconTalk record repeatedly identifies Israeli management depth as a constraint, not a patriotic advantage. TCTV, 10:00–11:08
- Evolution and contradictions — [researcher inference | moderate] The thesis progresses from internet export to scale-up talent and, by 2025, to regional complementarity with Gulf capital/energy/infrastructure. It remains distinct from Model 17: this is a company route-to-market rule; country underwriting is a macro allocation/context rule.
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] AI reduces translation and service cost but does not remove procurement, trust, sovereignty, export controls, local data law, or management depth. Current signal: retained customers in a second geography with locally compliant, supportable unit economics. Misuse: counting global sign-ups while revenue, infrastructure, and decision-making remain concentrated in one fragile channel. Grounded current example: Freightos sells a cross-border network from an Israeli base, but public losses keep global reach from becoming return proof. 2025 results
Model 14: Be Right and Non-Consensus, Not Merely Contrary
- Rule — [investor-stated | strong] Act before consensus when independent evidence supports a mispriced future and delay compounds the blocker; opposition or ridicule is not evidence of correctness, so every contrarian position needs a falsifier and price discipline. 18Forty 2026, Iran-response question Healthy.io essay
- Evidence status — [researcher inference | strong] The distinction is explicit in direct writings and interviews and appears in several decisions. No complete pass/forecast ledger demonstrates that non-consensus calls outperformed, and some macro claims lack baseline or horizon.
- Provenance and origin — [investor-stated | strong] The 2009 essay says trailing poor performance can improve the next vintage as capital withdraws; the 2026 18Forty interview explicitly invokes Howard Marks’s consensus/non-consensus matrix and preemption. Sarah Lacy/David Li, ¶¶8–22 18Forty 2026, Iran-response question
- Mechanism and reasoning — [researcher inference | strong] Consensus determines competition, price, and available talent; an independently correct minority view can buy better access before proof. Preemption matters when risk compounds nonlinearly, but error costs rise when action is irreversible.
- Historical and vehicle context — [contemporaneous record | moderate] The 2009 Israel call was Benchmark-era public commentary without an identified check; Healthy.io is a disclosed Aleph decision; later statecraft analogies are personal policy views, not Aleph mandates.
- When to use — [researcher inference | strong] Use when primary evidence diverges from market belief, the variant view is causal and testable, and the payoff is asymmetric. Do not use contrarian identity to dismiss regulation, science, governance, or liquidity; do not confuse “few competitors” with customer demand.
- How to apply it — [researcher inference | strong] Write consensus, variant view, why consensus persists, evidence, price, timing advantage, action cost, and three falsifiers; appoint a challenger and date the update. Kill when the variant evidence fails replication, the advantage is fully priced, the supposed consensus was misdescribed, or adverse facts are explained away solely as proof of being early.
- Examples — [researcher inference | strong]
- Healthy.io — [investor-stated | strong]: the team entered diagnostics after Theranos made it unfashionable, while demanding camera, regulatory, reimbursement, and workflow learning. Healthy.io essay
- Adtech — [investor-stated | moderate]: a locally crowded sector was avoided as platform and public-market evidence deteriorated. 2016 Prediction
- GuruNet — [researcher inference | moderate]: Israel Seed passed twice and later entered after a changed model, but the evidence justifying reversal remains absent. GuruNet 1999 report
- Evidence — [documented behavior | strong] Independent routes include the full 2009 and 2016 essays, official 2026 transcript, contemporaneous Healthy.io essay, and GuruNet reporting. They support the reasoning pattern, not a base-rate-adjusted hit rate. 2016 Prediction Local evidence map: Healthy.io note, 18Forty 2026 note, and GuruNet case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] Contrarianism can become ego, motivated reasoning, permanent bearishness, or an unfalsifiable “too early” defense. WeWork is a useful inverse control: popularity and a compelling nonstandard founder neither validated nor invalidated the lease/governance thesis; direct evidence had to decide.
- Evolution and contradictions — [researcher inference | moderate] The model broadens from capital cycles and sector avoidance to geopolitical preemption. Eisenberg’s stated epistemic humility conflicts with bold demographic/geopolitical forecasts that lack probabilities and thresholds; those remain forecast-ledger items, not validated models.
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] In AI, consensus forms within weeks. Archive the contemporaneous variant memo, benchmark model/provider releases, and require a customer or technical test before action. Transfer succeeds where regulation, workflow, or atoms create misunderstood constraints; it fails when social-media novelty or “everyone is wrong” rhetoric replaces evidence. Grounded current example: Healthy.io remains the best disclosed non-consensus case, with regulatory progress and layoffs preventing a one-sided winner narrative. FDA K222921 2024 layoffs
Model 15: Learn a Domain through Primary-Source Immersion
- Rule — [investor-stated | strong] Learn a field’s five to ten key terms, struggle through primary documents, and use the acquired language to ask experts sharper questions; keep direct evidence and secondhand narrative visibly separate. Max Raskin, “Struggle With It”
- Evidence status — [researcher inference | moderate] The learning method is explicit in one complete Q&A and behaviorally consistent with Healthy.io and filing-heavy deal work. No time log, memo history, decision comparison, or complete error set measures whether it improves outcomes.
- Provenance and origin — [investor-stated | strong] Eisenberg says he taught himself finance through S-1s, balance sheets, and profit-and-loss statements and recommends repeated exposure before comprehension. The Q&A’s “K-1 annual reports” wording may be an editing error and is not silently converted to 10-K. Max Raskin, “Struggle With It”
- Mechanism and reasoning — [researcher inference | strong] Vocabulary compresses expert communication; primary records expose definitions, incentives, risks, and changes that summaries omit; iterative questions convert reading into an evidence map. Direct calls add context but require contradiction because networks can select what the researcher hears.
- Historical and vehicle context — [investor-stated | moderate] Eisenberg describes himself as nontechnical, making translation, questions, people, and pattern acquisition his claimed edge across Israel Seed, Benchmark, and Aleph. That self-description is not proof that every relevant memo used this process.
- When to use — [researcher inference | strong] Use before entering a new industry, interpreting a regulated metric, evaluating a public comparable, or making a macro claim. Do not substitute terminology for competence, use only friendly experts, or bypass qualified legal, clinical, security, or scientific review.
- How to apply it — [researcher inference | strong] Build a source hierarchy; define ten terms and disputed metrics; read filings/regulatory records; ask independent operators the same questions; log contradictions and confidence changes. Stop or defer when a core metric cannot be reproduced, experts disagree on safety without a resolving test, primary rights/records are unavailable, or the team cannot explain the mechanism without jargon.
- Examples — [researcher inference | strong]
- Healthy.io — [investor-stated | strong]: diligence repeatedly addressed reimbursement, regulation, optics, robotics, lighting, and patient behavior before the Series B. Healthy.io, body ¶¶5–24
- Shopping.com — [researcher inference | strong]: its S-1 exposes traffic concentration, losses, litigation, and ownership that retrospective success stories omit. Shopping.com S-1/A, risks/holders
- Frank — [researcher inference | strong]: reported user/aid claims required raw-record reproduction and regulatory follow-up, not narrative familiarity. FTC warning SEC release
- Evidence — [documented behavior | strong] Independent underlying sources are the Raskin Q&A, full Healthy.io essay, SEC filings, FTC warning, and DOJ resolution. Eisenberg’s 2026 preference for direct calls over general media adds consistency, not independent correctness. 18Forty 2026, US–Israel/news questions Local evidence map: Raskin note, Healthy.io case, Shopping.com case, and Frank case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] Primary documents can be issuer-framed, incomplete, delayed, technically misunderstood, or fraudulent; friendly expert networks create confirmation bias. Frank’s later adjudication concerns founders and executives and does not prove which investor diligence occurred. FTC explanation
- Evolution and contradictions — [researcher inference | moderate] The approach grows from self-taught financial literacy to cross-domain diligence and distrust of weak reporting. Eisenberg’s reported dismissal of peer review as creativity-dampening is a real boundary: independent verification may be slow, but novelty does not lower the evidentiary bar.
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] Use AI to index and compare primary records, never to create absent evidence. Preserve source snippets, dates, version/model IDs, calculations, and human expert corrections; reproduce user, revenue, eval, and safety metrics from raw samples. Misuse is treating fluent synthesis or citation volume as verification. Grounded current example: the Frank sequence requires raw metric reproduction, regulator records, and adjudicated outcome to remain separate evidence layers. FTC warning DOJ disposition
Model 16: Invest through Cycles by Finding the Binding Scarce Input
- Rule — [investor-stated | strong] Do not treat a cycle as a binary risk-on/risk-off signal. Identify the binding scarce input—venture-scale companies, talent, ownership, credible follow-on capital, public liquidity, customer budget, or infrastructure—and invest or conserve according to how the cycle changes its price and availability. Sarah Lacy/David Li, ¶¶8–22 20VC joint, 05:02–23:50
- Evidence status — [researcher inference | strong] The model appears contemporaneously in 2009, 2012, and 2016 and retrospectively in 2021. It lacks a dated fund-action ledger, full vintage cash flows, and the inaccessible LP-letter body needed to test implementation.
- Provenance and origin — [investor-stated | strong] The 2009 David Li analogy warns that a model fitted to benign history can fail after regime change; weak trailing venture returns can improve forward entry conditions if capital and competition withdraw. Sarah Lacy/David Li, ¶¶1–22
- Mechanism and reasoning — [researcher inference | strong] Capital supply changes entry price, terms, syndicate durability, and founder behavior; talent supply changes execution; public comparables and platform economics change exit value. The apparent scarce resource can switch during a cycle, so yesterday’s bottleneck should not be extrapolated.
- Historical and vehicle context — [contemporaneous record | moderate] The 2009 and 2012 comments are Benchmark-era market views; the 2016 adtech call and 2021 joint interview are Aleph-era. Israel Seed IV’s weak vintage and abandoned Fund V are separate team/fund evidence, not Eisenberg’s personal return.
- When to use — [researcher inference | strong] Use in annual pacing, reserves, follow-ons, pricing, syndicate selection, and category allocation. Do not wait for a perfect macro turn, infer structural health from funding totals, or call every downturn attractive when customers, talent, or next-round capital remain structurally broken.
- How to apply it — [researcher inference | strong] Maintain a dated dashboard of entry prices/terms, public/private divergence, capital by stage, talent availability, customer budgets, runway, reserve coverage, and syndicate reliability; prewrite what each regime changes. Stop new exposure when the required next-round market and customer demand both deteriorate, reserve coverage breaches, public economics falsify the private model, or no identified scarce input improves the payoff.
- Examples — [researcher inference | strong]
- 2009 Israel call — [investor-stated | moderate]: Eisenberg argued that capital scarcity could improve conditions for persistent founders; no matched vintage result is supplied. Sarah Lacy/David Li
- 2012 contraction — [investor-stated | provisional]: he viewed lower funding as potentially healthy because capital competed for scarce scaling talent. TCTV, 08:29–09:29
- 2016 adtech — [investor-stated | moderate]: abundant local financing lagged worsening platform and public-market economics. 2016 Prediction
- Israel Seed IV — [researcher inference | moderate]: a bad vintage, capital needs, and weak outcomes were not cured by power-law strategy. CalPERS snapshot
- Evidence — [documented behavior | strong] Independent underlying routes include two full essays, official captions, a two-investor 20VC interview, and contemporaneous CalPERS/fund reporting. The 2022 LP retrospective establishes only Eisenberg’s letter-writing role and inspirations, not any runway, pacing, or secondary policy. LP retrospective opening Local evidence map: 2009 essay note, 20VC joint note, and Israel Seed IV case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] The model can become unfalsifiable cycle storytelling, permanent contrarianism, or false precision. Weak trailing returns may reveal durable ecosystem failure, not opportunity; abundant capital may be rational when customer demand and productive capacity expand. Israel Seed Fund V abandonment
- Evolution and contradictions — [researcher inference | strong] “Less competition is healthy” evolves into “access to a rare outlier can justify price,” with ownership and usable capital as reconciling variables. The tension remains untested because no stage-, price-, ownership-, and vintage-adjusted denominator is public. 20VC joint, 04:46–23:50
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] In AI, track compute/energy, frontier talent, lawful data, enterprise change budgets, model-cost decay, security/compliance spend, and growth capital separately. Current signal is a scarce complement whose economics improve as generic capability cheapens. Misuse is buying “AI exposure” because funding volume or model benchmarks rose. The Aleph AI Team is a current documented program but not an outcome; a labeled hypothetical is to test whether its cohort builds owned complements before the 18-month revenue target. Aleph AI Team
Model 17: Underwrite Countries as Productive-Capacity Systems
- Rule — [investor-stated | strong] Evaluate a venture ecosystem as a system of people, skills, infrastructure, law, capital, demography, institutions, security, and global connections; favor interventions that create durable productive capability rather than preserve particular firms, and keep national objectives separate from fund returns. Wake Up Java, ¶¶1–9 Hummus Part 2
- Evidence status — [researcher inference | moderate] This is the broadest and most persistent worldview in the corpus, but its use as a venture allocation model is supported mainly by advocacy and forecasts; “Long Israel” performance, ex-ante country screens, and complete cross-country controls are unavailable.
- Provenance and origin — [investor-stated | strong] The 2006 internet essay treats bandwidth, tax, corporate law, and skills as national venture infrastructure; the Hummus series develops talent concentration, anchors, late-stage expertise, and focused public capability. Wake Up Java, ¶¶1–9 Hummus Part 2
- Mechanism and reasoning — [researcher inference | strong] Skills, research, connectivity, law, management, and follow-on capital are complements: a missing one caps company scale. Anchor institutions and shared infrastructure can train people and spawn downstream firms, while diffuse subsidy can preserve weak activity and mute selection.
- Historical and vehicle context — [investor-stated | strong] The model is personally tied to Eisenberg’s immigration, religious/civic purpose, and Israel-focused Aleph identity, but policy advocacy is not an Aleph investment and firm mandates are collectively governed. The metadata-only Aleph V announcement cannot prove fund size, close, deployment, or performance. Aleph V canonical route
- When to use — [researcher inference | strong] Use for geographic allocation, domicile, talent strategy, public/private complement mapping, and geopolitical scenario work. Do not treat national resilience as a company metric, let patriotism override LP duty, assume public spending creates private return, or collapse ecosystem spillover into fund economics.
- How to apply it — [researcher inference | strong] Keep four ledgers—company economics, vehicle economics, ecosystem capability, and civic objective. Map skilled labor, management, customers, infrastructure, energy/compute, regulation, tax/IP, security, foreign capital, and exit depth; assign metrics, owners, horizons, and counterfactuals. Kill a geographic thesis when talent/capital flight, legal instability, infrastructure failure, customer access, or exit restrictions breach thresholds and no company-level hedge exists.
- Examples — [investor-stated | moderate]
- Focused capability — [investor-stated | moderate]: the Hummus essays prefer concentrated cloud/agriculture/energy capability to diffuse firm subsidy and allow one company to fail while spillovers persist. Hummus Part 3
- Anchor lifecycle — [investor-stated | provisional]: the 2011 Amazon-versus-Intel proposal scores spillover breadth; the later Tower of Babel critique supplies platform-capture risk. Hummus Part 4 Tower of Babel
- AI/regional capacity — [investor-stated | provisional]: the 2025 trillion-dollar plan and Misgav interview join AI, energy, infrastructure, finance, and regional complementarity without a costed return bridge. Trillion-Dollar Economy Misgav, 20:36–39:10
- Evidence — [researcher inference | moderate] Independent routes include full Medium essays, Sapir and Hashiloach essays, official and OpenAI-transcribed interviews, Bank of Israel/OECD context, and company/fund controls. They strongly establish Eisenberg’s systems worldview but not three named country-allocation decisions or superior fund returns. Model-specific attempted-route ledger: the Hummus series, Children Are Growth, the trillion-dollar essay, Misgav, and both 18Forty appearances yielded prescriptions; Bank of Israel and OECD yielded context/base rates; the Aleph V route yielded metadata only; the firm portfolio and deal ledger yielded no country-screen memo or vehicle outcome. Missing proof is three ex-ante geographic-allocation decisions with thresholds, vehicle attribution, and outcomes. Children Are Growth Bank of Israel, financing characteristics OECD, Israel country note Local evidence map: Hummus Part 2 note, Misgav note, and Israel Seed IV case.
- Limits, failure modes, and exception ledger — [researcher inference | strong] Industrial policy risks capture, corruption, dependency, distributional harm, and national-champion bargaining power; market Darwinism can underfund public goods. Eisenberg criticizes diffuse grants and pension matching while proposing concentrated state coordination. Israel Seed IV’s weak record shows that a country thesis cannot rescue a vehicle. Israel Seed IV 2011 reported mark
- Evolution and contradictions — [researcher inference | strong] The model moves from internet substrate to scale-up capacity, demography, domicile, wartime agency, AI sovereignty, and regional prosperity. Its enduring contradiction is decentralized entrepreneurial discovery versus concentrated state infrastructure; the stated boundary is shared capability rather than company rescue, but capture controls remain underspecified. Misgav, 20:36–39:10
- Modern VC translation (as of 2026-08-22) — [researcher inference | strong] Underwrite energy/compute, export controls, dual-use regulation, cyber/physical security, talent visas, reserve duty, data residency, university pipelines, sovereign procurement, downstream capital, and regional partners. Transfer succeeds when a company owns a portable advantage and has hedges for missing complements. Misuse is attaching “national resilience” to a deal without stage-, price-, ownership-, and risk-adjusted economics. Current documented application: the Misgav regional AI-complement proposal remains provisional until named projects, contracts, capacity, and returns exist. Misgav, 35:17–39:10
Evidence gaps and candidate models
- Inventory reconciliation. [researcher inference | strong] The 17 models above reconcile all 46 source notes, the 35-route writings synthesis, 11-route talks synthesis, and 123-association/121-company investment ledger. Synonyms were merged by decision mechanism: “different is better” is split across Models 3, 5, and 14; “relationships, reputation, and service” are Models 2 and 9; “patience and uncertainty” are Model 7; “long humanity, fraternity, and covenant” are Model 11; “Scale-Up Nation/global from day one” is Model 13; “Long Israel” is Model 17.
- Candidate — Singular Priority. [investor-stated | insufficient public record] The Raskin Q&A says only one item can be first and names Healthy.io as a temporary priority; 20VC’s concentrated board questions are adjacent but do not establish portfolio triage. Attempted routes: Raskin “Sacred and Prosaic,” Healthy.io essay, 20VC board segment, Human Founder stagehand discussion, and Aleph service announcements. Missing proof: three distinct dated priority-allocation cases, displaced work, escalation/exit criteria, and outcome comparison. Raskin, “The Sacred and the Prosaic”
- Candidate — Investor as Stagehand. [investor-stated | provisional] Human Founder supplies the reusable metaphor, but the corpus also shows executive recruitment, intense boards, shutdown advice, and governance duties. It is therefore folded into Models 2 and 9 rather than promoted as a standalone nonintervention rule. Attempted routes: Human Founder, 20VC board segments, Empathy/Healthy.io, Aleph launch, Shopping.com filings. Missing proof: explicit decision-right boundaries across at least three boards. Human Founder, opening role discussion
- Candidate — Reputation as Predictable Conduct. [investor-stated | provisional] The Human Founder interview and 20VC access discussion support reputation as a relationship mechanism, not a distinct underwriting model. Attempted routes: Human Founder, 20VC joint, Relationships opening, Empathy, WeWork sourcing. Missing proof: an observable reputation score, independent counterpart evidence, rejected deals, and controlled access/price outcomes.
- Candidate — Default to Israeli Incorporation. [investor-stated | provisional] The 2024 essay gives a clear conditional rule—use Delaware only for a concrete regulatory reason—but it is a legal/policy application of Model 17, not a cross-corpus model. Attempted routes: the full domicile essay, SEC issuer domiciles, Aleph company list, public matching-program commentary. Missing proof: the portfolio domicile denominator, actual exceptions, counsel memoranda, comparative financing/exit cost, and updated law. Incorporate in Israel or Delaware
- Candidate — Keep Investing during Crisis. [investor-stated | insufficient public record] Agency Under Fire states that Aleph kept investing during war and gives an unnamed growing company; Be Long Israel and Aleph V expose fragments/metadata only. It remains an application of Models 16 and 17. Attempted routes: Agency transcript, 18Forty Civic, Be Long Israel, Aleph V, wartime company announcements. Missing proof: named checks, date, vehicle, comparable passes, portfolio cohort, and subsequent outcomes. Agency Under Fire
- Excluded slogans. [researcher inference | strong] “Optimism and resilience,” “founder as hero,” “values create value,” “be long Israel,” and “what can go right” are not separate models without a reusable mechanism, decision procedure, boundary, and falsifier. Their operational content is preserved in Models 1, 3, 7, 9, 11, 14, 16, and 17.
- Priority evidence gaps. [researcher inference | strong] Recover original investment/pass memos, complete LP letters, partnership/board minutes, full legal-vehicle cash flows, security-level sales/distributions, and the inaccessible Lemonade, Melio, Relationships, RiseUp, Be Long Israel, and Aleph V bodies. Verify all Hebrew translations and ambiguous audio/caption locators before publication quotations.
- Model-level falsifier. [researcher inference | strong] If relationship-led, people-first, non-consensus, values-aligned, scale-oriented investments do not outperform a stage-, vintage-, price-, ownership-, geography-, partner-, and liquidity-adjusted denominator that includes ordinary losses, governance failures, and unrealized positions, this field guide describes a coherent worldview—not a demonstrated investment edge. Evidence that the rules were absent from contemporaneous decisions would further falsify claims of process continuity.
Strongest skeptical result
The public record does not establish a comparable, audited cash-return series for Michael Eisenberg, Israel Seed, the Benchmark vehicles, or Aleph. The searched union contains 123 vehicle-company associations covering 121 companies, but only 11 association rows are sufficiently reconstructed even at the partial E1–E3 level; 112 remain E0 and 13 investigated candidates were excluded. No entry-to-exit cash flow, fee, carry, dilution, or final audited DPI/TVPI series supports a career multiple, hit rate, attribution share, or valid dominant-winner removal. [researcher inference | strong] Denominator reconciliation
This is not a small technical caveat. The observable record overweights companies that raised, listed, sold, survived, or attracted controversy. Israel Seed IV supplies material counterevidence: the 2000-vintage vehicle carried a reported negative interim return, material paper write-offs, and no successor Fund V, while same-vintage peers were also negative. That weakens a simple selection-skill narrative without proving personal underperformance or a final fund result. [contemporaneous record | moderate] Israel Seed IV case CalPERS-derived 2005 report
The strongest defensible conclusion is therefore narrower: the corpus documents a durable method—relationship-led access, cross-border company building, power-law scale, complement mapping, and active governance—but leaves its economic edge provisional. [researcher inference | provisional] Profile edge thesis Philosophy edge thesis
What the evidence supports
The package supports five findings.
- Eisenberg had continuous operating exposure across Israel Seed, Benchmark, and Aleph, but the legal vehicles and partner teams differ by era. [documented behavior | strong] Career and vehicle chronology
- Relationships are a repeatable sourcing and information mechanism in his own accounts; filings and third-party reports are still required before upgrading access into decision credit or return. [investor-stated | strong] Talk framework
- Cross-border translation—product, management, customers, regulation, and capital—is visible in Shopping.com, Wix, Lemonade, Windward, Freightos, and other cases, though founder, co-investor, and vehicle contributions remain material. [researcher inference | moderate] People and function map
- His later philosophy contains more explicit governance, financing-dependency, and abandonment controls than the earlier public voice. WeWork, Print Life, and Israel Seed IV make that change plausible, not causally proven. [researcher inference | moderate] Evolution and contradictions
- The best reusable artifact is a falsifiable operating framework, not a return ranking: date the packet, separate initial investment from continuation, map dependencies, define kill criteria, and reveal the outcome only after the worksheet. [researcher inference | strong] Seventeen decision labs
What could falsify the thesis
The thesis predicts that previously unseen contemporaneous records should repeatedly show relationship-sourced access converting into differentiated evidence, explicit dependency maps, ownership discipline, and dated interventions across ordinary as well as famous deals. It would be weakened if those practices appear mainly in later narration, if partner- or institution-level work explains the decisions, or if relationship-sourced companies do not outperform comparable non-network opportunities after vintage, sector, price, and ownership controls. [researcher inference | strong] Profile predictions Profile overturning evidence
It would be overturned economically by a complete, attribution-resolved ledger showing no matched-vintage net advantage after fees, no repeatable ownership or realization benefit, or results dominated by a few inaccessible outliers. Repeated governance and metric-integrity failures after the stated learning dates would also falsify the claim that later doctrine became enforceable process. [researcher inference | strong] Philosophy falsifiers Denominator and failures
What the evidence does not support
- It does not support attributing firm, fund, partner-team, founder, or board outcomes to Eisenberg personally without a named act or right. [researcher inference | strong] Function-level responsibilities
- It does not support turning financing totals, valuations, IPO prices, acquisition consideration, or issuer ownership tables into personal or net-fund returns. [researcher inference | strong] Economic evidence boundary
- It does not support treating WeWork's bankruptcy as a quantified Benchmark loss, Frank founder fraud as investor knowledge, or the unresolved JPMorgan holder complaint as adjudicated liability. [documented behavior | strong] WeWork case Frank case
- It does not support recovering missing bodies. The Melio essay is metadata/opening-fragment-only; the Lemonade investment article is partial; seven other writing routes stop at their legitimate access boundary. [documented behavior | strong] Writing coverage
- It does not support a causal claim that Israel itself explains returns. War, immigration, technical talent, U.S. market access, capital cycles, and regulation are regime variables that can help or hurt. [researcher inference | strong] Historical context
Scope and method
The acceptance review reopened the six core synthesis documents, all 35 writing notes, all 11 talk notes, the source map, and the deal ledger. It tested claim-local citations, exact source locators, source-family independence, two-axis labels, quote length, access honesty, person/team/vehicle separation, adjudication status, no-hindsight ordering, tables, links, fragments, and renderability. [documented behavior | strong] Source-map scope
Coverage is explicit rather than implied: 75 source rows comprise 57 priority-three, 17 priority-two, and one unchecked event-metadata row; 74 were processed. The writing denominator is 35 of 35 routes—26 full, seven partial but substantively analyzed, and two metadata/opening-fragment-only. The talk denominator is 11 of 11 routes—five publisher text/Q&A/transcript, two official auto-caption, and four OpenAI transcriptions. [documented behavior | strong] Writing coverage Talk coverage
The review cutoff is 2026-08-22. Later filings may be used to reconstruct earlier facts only when their later source date is stated; they are not relabeled as contemporaneous investment packets. [documented behavior | strong] Retrospective controls
Central-claim and ordinary-claim audit
The following reproducible spread tests 31 claims: 10 central claims and 21 ordinary claims, with at least one ordinary claim from each of the seven pre-review core documents. Ordinary rows 27–31 use the first non-headline, independently checkable factual proposition encountered after each previously uncovered document’s opening section; this prevents selecting only favorable or spectacular claims. “Supported” means support to the stated boundary, not proof of economic causation.
| # | Type | Claim tested | Adjacent control and locator | Result |
|---|---|---|---|---|
| 1 | Central | Relationship-led cross-border translation is the proposed edge. | _profile, proposed edge; no cash-return proof. | Supported as [researcher inference | provisional] |
| 2 | Central | The same edge grade governs the philosophy. | Philosophy §1. | Aligned: [researcher inference | provisional] |
| 3 | Central | Relationships are an information channel, not outcome evidence. | Writings, relationships. | Supported: [researcher inference | strong] |
| 4 | Central | Power-law selection requires ownership and financing discipline. | Talk framework §2. | Supported as stated method: [researcher inference | strong] |
| 5 | Central | Backcasting is a recurring dependency-mapping method. | Model 1. | Supported: [investor-stated | strong] |
| 6 | Central | Governance became more explicit after earlier-cycle failures. | Profile, changed beliefs. | Plausible, not causal: [researcher inference | moderate] |
| 7 | Central | Israel Seed, Benchmark vehicles, and Aleph require separate attribution. | Vehicle economics. | Supported: [documented behavior | strong] |
| 8 | Central | Economic contribution and top-outlier removal are not computable. | Pareto view. | Supported negative finding: [researcher inference | strong] |
| 9 | Central | Modern transfer requires prewritten milestones and falsifiers. | Modern VC translation. | Supported recommendation: [researcher inference | strong] |
| 10 | Central | The 17 models are hypotheses with anchors, not proven alpha. | Evidence gaps. | Supported boundary: [researcher inference | strong] |
| 11 | Ordinary | Israel Seed IV had a weak reported interim record and no Fund V. | Case 10; final audited result absent. | Supported: [contemporaneous record | moderate] |
| 12 | Ordinary | Same-vintage Israeli funds were also negative in the 2005 snapshot. | Case 10 outcome. | Supported regime control: [contemporaneous record | moderate] |
| 13 | Ordinary | Windward is the best partially reconstructed security path. | Case 1; earlier sales and distributions absent. | Supported: [documented behavior | strong] |
| 14 | Ordinary | Shopping.com filings establish vehicle holdings and shared control. | Case 2; original check absent. | Supported: [documented behavior | strong] |
| 15 | Ordinary | Wix filings do not assign Benchmark's block to Eisenberg personally. | Case 3, principal-shareholder locator. | Supported: [documented behavior | strong] |
| 16 | Ordinary | Lemonade reported exactly 2,984,513 customers for 2025. | Case 4, 2025 Form 10-K. | Supported: [documented behavior | strong] |
| 17 | Ordinary | Healthy.io provides a recoverable same-day diligence essay, not a return. | Case 5. | Supported: [investor-stated | strong] |
| 18 | Ordinary | Freightos exposes selected security and governance evidence, not net proceeds. | Case 6. | Supported: [documented behavior | strong] |
| 19 | Ordinary | Xero completed Melio on 2025-10-15; Aleph economics remain unknown. | Case 8, issuer completion release. | Supported: [documented behavior | strong] |
| 20 | Ordinary | PictureVision is outside the 123-row ledger because the investing entity is unresolved. | Case 9. | Supported exclusion: [retrospective witness | provisional] |
| 21 | Ordinary | Print Life is a retrospective failure narrative without original company records. | Case 11. | Bounded: [retrospective witness | provisional] |
| 22 | Ordinary | WeWork's 2017 packet is a continuation checkpoint, not the missing 2012 initial memo. | Case 15. | Corrected boundary: [contemporaneous record | moderate] |
| 23 | Ordinary | Frank's 2020 packet is a follow-on/governance checkpoint, not the missing 2017 seed memo. | Case 16. | Corrected boundary: [contemporaneous record | strong] |
| 24 | Ordinary | Javice's criminal disposition is adjudicated; the holder-contract dispute is not. | Frank outcome. | Separated: [documented behavior | strong] |
| 25 | Ordinary | “Meet Aleph” is Eden Shochat-bylined and cannot evidence Eisenberg authorship. | Writing 11. | Attribution preserved: [contemporaneous record | strong] |
| 26 | Ordinary | The Melio writing body is unavailable and no body quote is used. | Writing 19. | Access boundary preserved: [documented behavior | strong] |
| 27 | Ordinary | The current Aleph About page names Eisenberg, Eden Shochat, Yael Elad, and Tomer Diari while claiming 850 million dollars under management. | Profile people map and Aleph About, accessed 2026-08-22. | Verified as a dated first-party current claim, not an audit: [contemporaneous record | provisional] |
| 28 | Ordinary | sources.md records the EconTalk route as published 2022-02-14 from a 2022-01-25 recording and exposes a complete publisher transcript. | Source-map talk row and EconTalk transcript header. | Verified: [contemporaneous record | strong] |
| 29 | Ordinary | The Max Raskin page displays Jan 15 without a year, so talks.md excludes it from the dated chronology. | Talk source section and publisher page. | Verified access boundary: [documented behavior | strong] |
| 30 | Ordinary | The philosophy uses Bank of Israel financing research as system context, not as proof of Eisenberg-specific edge. | Historical environment and Bank of Israel analysis. | Verified boundary: [researcher inference | strong] |
| 31 | Ordinary | Model 15 treats repeated primary-source reading and domain vocabulary as a learnable diligence practice. | Model 15 and Raskin, “Struggle With It”. | Verified as stated practice, not alpha proof: [investor-stated | strong] |
Attribution and denominator audit
This audit begins with the legal vehicle and named function, then tests whether the source supports person-level action, team-level action, or only a company outcome. Unknown allocation, ownership, voting, cash flow, and intervention remain unknown rather than being assigned from proximity. [researcher inference | strong] Function-level responsibilities
Independent deal and team cross-checks
| Claim | Independent control | Accepted boundary |
|---|---|---|
| Israel Seed IV vehicle performance | CalPERS-derived report plus Fund V report | Interim vehicle observations only; not personal or final performance. [contemporaneous record | moderate] |
| Shopping.com holdings and board role | SEC S-1/A | Shared Israel Seed control and filed director role; no complete proceeds. [documented behavior | strong] |
| Wix holdings and person boundary | SEC F-1/A | Benchmark block was not Eisenberg beneficial ownership. [documented behavior | strong] |
| Lemonade holdings and operating outcome | SEC S-1/A and 2025 10-K | Filed entity holdings and company metrics; no Aleph DPI. [documented behavior | strong] |
| WeWork governance and downside | SEC 2023 proxy and Chapter 11 8-K | Dunlevie held the Benchmark seat; bankruptcy does not quantify lifetime fund return. [documented behavior | strong] |
| Frank founder fraud and holder dispute | DOJ sentencing and redacted complaint | Founder disposition adjudicated; investor knowledge not found; contract claim unresolved. [documented behavior | strong] |
| Melio acquisition completion | Xero completion, 2025-10-15 | Company transaction complete; Aleph ownership and proceeds unverified. [documented behavior | strong] |
Allegation, adjudication, and company-outcome states
| Matter | What is established | What remains prohibited or unresolved |
|---|---|---|
| WeWork | The issuer filed Chapter 11 and the old-equity treatment is documented. SEC 8-K | Company impairment does not establish Benchmark lifetime cash return or personal responsibility. [documented behavior | strong] |
| Frank | Javice and Amar were convicted; Javice was sentenced. DOJ disposition | The separate holder support-agreement claim against Aleph entities is disputed and unresolved; no source establishes Eisenberg or Aleph knowledge of the fraud. [documented behavior | strong] |
| Paragon | Plaintiffs and Eisenberg have opposing reported positions. Ynet report | No adjudicated disposition was located; allegations and denial remain claims, not findings. [contemporaneous record | moderate] |
Denominator and outlier test
The denominator ladder is: three institution eras; multiple legal vehicles; 123 association rows; 121 company paths; 11 partial reconstructions; 112 unresolved rows; 13 exclusions; 17 teaching cases, of which 14 are in-ledger and three are vehicle or outside-ledger reconstructions. A coverage fraction exists only for partial reconstruction—11/123 association rows—not for economic success. [documented behavior | strong] Reconciliation
No dominant-outlier test is valid because no comparable cash-flow column exists. Melio dominates announced transaction value; Windward dominates reconstruction completeness. Removing either proxy changes the narrative ranking but still cannot produce economic contribution, return concentration, or a career multiple. [researcher inference | strong] Dominant-outlier test
The ordinary and adverse tail must remain in the record: Israel Seed IV, Print Life, MemLink, Tradeum, WeWork, Frank, GuruNet's two passes, and unresolved/private portfolio rows prevent a wins-only synthesis. [researcher inference | strong] Adverse map
No-hindsight and retrospective-bias audit
All 17 forensic cases place four decision questions before the sourced outcome. Cases 2–4 now state when a later issuer filing reconstructs cutoff facts. Case 15 is a 2017 continuation/re-underwriting checkpoint because the 2012 initial packet is absent; Case 16 is a 2020 follow-on/governance/M&A-readiness checkpoint because the 2017 seed packet is absent. [documented behavior | strong] Case sequence
Retrospective voice remains weakest where it selects memorable lessons without contemporaneous memos: PictureVision, Print Life, Israel Seed hit-rate claims, and post-collapse WeWork lessons. Such accounts support what Eisenberg later said, not the original probability, rejected evidence, partner dissent, or causal credit. [researcher inference | strong] Talk adverse audit
What a reader should test personally
- Rebuild one deal from the dated packet only, answer the four questions, and then reveal the outcome. Windward, Shopping.com, Healthy.io, WeWork, and Frank provide the widest evidence range. Decision labs
- For every “we,” write the legal vehicle, named actor, decision right, board role, and missing cash-flow fields. People and function map
- Compare relationship-sourced companies with a matched non-relationship cohort on entry access, ownership, survival, and realization; the current record cannot do this. Falsifiers
- Treat values and national narratives as product hypotheses. Pre-register retention, unit economics, regulatory harm, governance, and financing-dependency tests. Long-humanity control
- Audit realization separately from selection. IPO, acquisition, and valuation are events, not distributions. Model 10
Transfer limits for modern VCs
The transferable elements as of 2026-08-22 are process disciplines: compound trusted networks without substituting them for diligence; backcast every scarce complement; prewrite milestones and abandonment rules; align capital intensity with durable financing; separate sourcing, IC, board, and founder credit; and maintain a realized-cash ledger. [researcher inference | strong] Modern translation
The nonportable elements are era- and access-dependent: Israel's 1990s immigration and U.S.-capital bridge, early web scarcity, Benchmark's brand and network, Aleph's accumulated founder relationships, unusually low early ownership prices, and specific regulatory openings. A 2026 investor cannot infer that copying the narrative or sector list recreates the economics. [researcher inference | strong] Historical environment
AI, defense, energy, and regulated-finance translations need stronger controls than software-era analogies: compute and energy dependence, government procurement, export controls, model commoditization, data rights, compliance, and correlated capital needs must be dated and stress-tested. [researcher inference | strong] Model 6 Model 8
The three completed-peer comparisons—Bill Gurley, Andy Rachleff, and Chemi Peres—are dimensional controls for Benchmark lineage, partnership mechanics, cycles, and Israeli cross-border context; they are not a return league table and transfer no claim without Eisenberg-specific evidence. [researcher inference | strong] Peer-comparison audit
Learning path and render audit
Recommended order: read this review; study the profile; freeze and solve five investment cases; compare the writing chronology with the talk chronology; then use the 17 models and the four checklists. This order separates biography, method, decision evidence, and reusable tools.
The render audit checks H1/H2 order, Markdown-table widths, local paths and fragments, labels, quotes, and the site build. Links point to repository-relative files so the package remains navigable outside the generated site. [documented behavior | strong]
Corrections made in controlled review
- Normalized 51 non-enum evidence labels across five talk notes while preserving the underlying claim boundaries.
- Replaced five non-enum Reliability metadata values with the permitted A/B/C enum.
- Corrected two quote-count annotations: Human Founder to 9 words and TechCrunch TV to 12 words.
- Escaped evidence-label pipes in four malformed talk tables covering 29 rows.
- Added the three exact official acquisition-media URLs needed to reconcile talk-note metadata with canonical publisher rows.
- Aligned the economic edge grade in profile and philosophy to provisional.
- Replaced the rounded Lemonade customer count with 2,984,513 from the 2025 filing.
- Replaced the stale Melio completion citation with Xero's 2025-10-15 issuer release.
- Removed an unsupported Israel Seed IV adviser attribution while preserving the supported GP/controller evidence.
- Relabeled later-filed Shopping.com, Wix, and Lemonade freeze facts as documented behavior and stated the source-date boundary.
- Recast WeWork 2017 and Frank 2020 as continuation/follow-on checkpoints because their initial packets are unavailable.
Unresolved evidence
What to reopen next
Priority one is audited vehicle cash flow: LP statements, capital-account records, final liquidation accounts, distribution dates, fees, carry, write-offs, and company-by-company allocation for Israel Seed I–IV, the relevant Benchmark vehicles, and Aleph funds. Without them, the economic edge remains provisional. [researcher inference | strong] Uncertainty ledger
Priority two is contemporaneous decision process: original memos, partner votes, dissent, reserve decisions, board minutes, founder references, and dated kill criteria for WeWork, Frank, Lemonade, Shopping.com, Wix, Healthy.io, Melio, and ordinary losses. Priority three is adjudicative closure on the unresolved Frank support-agreement dispute. [researcher inference | strong] Evidence that would decide the dispute
Access instability remains a substantive limit. Seven writings are partial-but-analyzed, two are metadata/opening-fragment-only, auto-captions and OpenAI transcripts are not publisher-certified, and first-party Aleph pages can change. The notes preserve acquisition method, locator, and legitimate access boundary; no unavailable body is silently reconstructed. [documented behavior | strong] Writings unresolved record Talk unresolved record
Twenty-point acceptance matrix
| # | Requirement | Document/section inspected | Evidence/result | Correction or continuation | Verdict |
|---|---|---|---|---|---|
| 1 | Deep chronological investment biography | _profile chronology and chapters | Formative experience, three institutional eras, ordinary periods, changes, setbacks, actions, and outcomes are sourced; causal interpretation is labeled. | None. | PASS |
| 2 | Falsifiable thesis of the edge | _profile edge; philosophy §1; review falsifier | Mechanism, domain/period, cases, denominator, predictions, alternative explanation, and overturning evidence are explicit; economic grade is provisional. | Continue only if attribution-resolved cash flows or matched cohorts appear. | PASS |
| 3 | Ex-ante deal reconstruction | Seventeen cases | Each freezes evidence and uncertainty, covers mechanism/risks/terms boundaries, asks four questions, and reveals outcome afterward; later-filing and continuation boundaries are explicit. | WeWork and Frank initial packets remain named retrieval gaps. | PASS |
| 4 | Pareto economic, historical, and learning analysis | Investments first H2 | Economic-verification, historical-importance, and learning ranks state basis, attribution, confidence, denominator, and links; a true outlier test is declined without cash flows. | Continue only with comparable realized cash flows; no proxy percentage. | PASS |
| 5 | No premature completion or placeholders | Eight core files; review opening | Every file is substantive and has H1 plus substantive first H2; empty/status-only and media-artifact scans are clear. | Governance completion is a separate post-acceptance action outside this pass. | PASS |
| 6 | Searched portfolio denominator and coverage | Evidence boundary | 123 association rows / 121 companies reconcile to 11 partial reconstructions, 112 unresolved, and 13 exclusions with aliases, duplicates, bias, and a defensible 11/123 reconstruction fraction; economics remain not computable. | Retrieve full rosters, passes, allocations, and cash flows before any hit-rate claim. | PASS |
| 7 | Comprehensive source-by-source writings | Writing coverage; 35 notes | All 35 priority routes are processed: 26 full, seven partial/substantive, and two metadata-only, each with a note and synthesis subsection at its legitimate boundary. | Continue only if lawful stable bodies for the nine limited routes surface. | PASS |
| 8 | Detailed, cited mental models | Seventeen models; gap ledger | Seventeen distinct models contain all 12 required bullets and 55 grounded cases, including failures, limits, citations, provenance, and dated transfer tests. | Named model-level gaps remain; no padding or unsupported model is admitted. | PASS |
| 9 | Dated modern-VC translation | Philosophy §14; models | Major lessons and every model carry 2026-08-22 boundaries, changed assumptions, signals, misuse risks, and grounded examples or labeled hypotheticals. | Refresh when regulatory, AI, defense, energy, or vehicle premises change. | PASS |
| 10 | Full failure postmortems | Adverse map; Cases 10–17 | Israel Seed IV, Print Life, MemLink, Tradeum, WeWork, Frank, GuruNet, and ordinary outcomes cover thesis, warnings, capital, governance, response, outcome, lessons, attribution, and counterfactual uncertainty where evidence permits. | Original memos, board minutes, and quantified loss ledgers remain gaps. | PASS |
| 11 | Partner, team, and decision-rights attribution | People map; function table; review audit | Sourcing, board, recruiting, narration, holdings, vehicle control, founders, and co-investors are separated; absent approvals, votes, allocations, and economics remain unknown. | Preserve unknowns until primary allocation, IC, or governance records appear. | PASS |
| 12 | Vehicle economics and incentive analysis | Vehicle chapter; philosophy §6 | Israel Seed, Benchmark, and Aleph are separated across capital, duration, fundraising, rights, geography, liquidity, reserves, succession, regulation, and missing fee/carry evidence. | LPAs, fee/carry schedules, reserve policy, and audited distributions remain priorities. | PASS |
| 13 | Historical market, regulatory, and base-rate context | Investments context; philosophy §13 | Contemporary financing, technology, regulation, and market evidence is separated from later filings and retrospective data; system base rates are not person-level performance. | Preserve source-date labels when adding later controls. | PASS |
| 14 | Direct voice and primary-archive exhaustion | Sources coverage/saturation; writings; talks | 75 routes include 35 writings and 12 talk/event rows; 74 are processed. Eleven priority talks reconcile 5 publisher + 2 captions + 4 OpenAI; the unchecked event has no transcript and archive/letter barriers are exact. | Continue only through lawful archives, public LP material, official dockets, or a recovered transcript. | PASS |
| 15 | Pinpoint citations | 46 notes; claim audit | Every note declares canonical/acquisition URL, date, format, A/B/C, access, accessed date, and locator scheme; claims use timestamps, headings, filing items, pages, or disclosed limits; quotes are at most 25 words. | Recheck unstable routes before future quotation. | PASS |
| 16 | Explicit attribution and evidence labels | Eight core files and 46 notes; legal-state table | Enum audit finds zero invalid two-axis labels; statement, behavior, witness, inference, allegation, adjudication, person, team, and vehicle remain distinct. | None. | PASS |
| 17 | Strongest case against greatness | _profile skeptical case; philosophy §16; review opening | Missing economics, survivorship, outliers, access, attribution, era effects, Israel Seed IV, WeWork, Frank, and retrospective doctrine are tested with discriminating evidence. | Economic verdict remains provisional pending cash-flow and matched-decision evidence. | PASS |
| 18 | Comparison with completed peers | Philosophy §15 | Gurley, Rachleff, and Peres are completed, dimension-matched controls across sourcing, ownership, governance, partnership, incentives, cycles, geography, and failures; no return league table is inferred. | None; conclusions remain dimensional. | PASS |
| 19 | Investment-committee decision exercises | Decision labs; study guide | All 17 cases ask invest/pass, kill criteria, ownership/terms, and next-check milestones before outcome; failures, misses, fund-vintage, continuation, and ordinary cases are linked. | None. | PASS |
| 20 | Reader learning architecture | _profile curriculum; study guide/glossary/checklists; review path | Chronology, cross-links, ranked path, glossary, four checklists, 17 models, cases, and Markdown people/capital maps form a coherent path without bespoke components. | Re-run links/rendering after future heading changes. | PASS |
Final verdict
PASS, with a material economic-evidence reservation. The package is acceptable as a deeply sourced investment biography, philosophy reconstruction, decision-lab corpus, and skeptical research map. It is not acceptable as proof of a personal or fund-level return record. The decisive adverse fact is not one failed company; it is the absence of comparable cash-flow evidence across a survivorship-biased public denominator, reinforced by Israel Seed IV's weak interim record and the noncomputability of an outlier-removal test. [researcher inference | strong]
The edge thesis remains useful precisely because it is falsifiable: comparable company-level allocations and realized cash flows, attribution records, dated memos, and matched relationship/non-relationship cohorts could strengthen it; weak ownership, ordinary outcomes, inconsistent governance, or no advantage after regime and team controls would overturn it. [researcher inference | provisional]
Scope, identity, and evidence boundaries
This map treats Michael Eisenberg, Michael A. Eisenberg, Mike Eisenberg, מייקל אייזנברג, mieisenberg, @mikeeisenberg, Six Kids and a Full Time Job, Israel Seed Partners, Benchmark Israel and Aleph as search variants. Stars rank retrieval priority, not truth. Reliability is A for Eisenberg's direct voice, signed firm material, filings, courts and official records; B for strong named-source journalism or institutional interviews; and C for discovery leads requiring corroboration. Personal views, Aleph firm positions, Israel Seed or Benchmark vehicle activity, board service and company outcomes remain distinct. No check size, multiple, fund return, ownership or deal leadership is treated as audited without vehicle, cash-flow, allocation, dilution and realization evidence.
- ★★★ | Michael Eisenberg — official biography and portfolio | https://michaeleisenberg.vc/ | current page; accessed 2026-08-22 | first-party biography and portfolio page; reliability A for self-description | Verification: full page with biography and portfolio-logo blocks. Why: identity, Nevo Network, stated career duration and a first-party Aleph portfolio-total claim. Limit: undated and stale versus Aleph's current team/AUM page; self-reported attribution is not a return ledger.
Direct writings, books, op-eds, and archive survivors
- ★★★ | A Look Back at Our Letters to Our LPs and Capital Exuberance | https://www.aleph.vc/content/a-look-back-at-our-letters-to-our-lps-and-capital-exuberance | 2022-09-13 | essay; reliability A | Verification: partial; one stable publisher-visible opening paragraph with byline/date. Why: establishes Eisenberg's Aleph annual-letter responsibility and names Buffett and Bezos as inspirations. Limit: no letter excerpt, cycle rule, runway policy, company action or return is recoverable from the stable route.
- ★★★ | Invest in Relationships, Not Transactions | https://www.aleph.vc/content/invest-in-relationships-not-transactions | 2021-10-20 | investment-strategy essay; reliability A | Verification: partial; byline/date and one stable opening paragraph. Why: establishes the annual-LP-meeting setting and concern with weaponized or commoditized capital. Limit: the relationship mechanism, examples, checklist and outcomes are unavailable and unquoted.
- ★★★ | Why We Decided to Drink the Lemonade | https://www.aleph.vc/content/why-we-decided-to-drink-the-lemonade | 2015-12-09 | deal essay; reliability A | Verification: partial; byline/date and one stable opening paragraph. Why: supports only an explicit power-law premise and selected outlier examples. Limit: the Lemonade team, mission, moat, market, stage, investment decision and economics are unavailable.
- ★★★ | Bad Blood, Good Urine, Great People! | https://medium.com/aleph-vc/bad-blood-good-urine-great-people-8ca6ac125bc2 | 2019-02-05 | ex-ante Healthy.io deal essay; reliability A | Verification: full, paragraph locator. Why: unusually explicit Aleph criteria and diligence narrative. Limit: investor-authored and omits rejected evidence and ownership economics.
- ★★★ | Melio: Investing in Great People | https://medium.com/aleph-vc/melio-investing-in-great-people-cfe145a418d2 | 2020-09-14 | deal essay; reliability A | Verification: metadata only; first-party index verifies title, Michael A. Eisenberg byline, date and canonical URL, while the body returns 403. Why: preserves the publication record. Limit: no body, quotation, people-selection rule, sourcing, financing, market, team, board, ownership or performance claim is used.
- ★★★ | LMND — Aleph's First IPO | https://www.aleph.vc/content/lmnd----alephs-first-ipo | 2020-07-02 | IPO retrospective; reliability A | Verification: partial; title/byline/date and one stable opening paragraph. Why: records Aleph's first-IPO label and Eisenberg's joint recollection with Eden Shochat of the 2013 firm pitch. Limit: no company-thesis, product, moat, ownership or return claim is recoverable from the body.
- ★★★ | Long Humanity | https://medium.com/aleph-vc/long-humanity-32b9dad0d54d | 2018-11-21 | philosophy essay; reliability A | Verification: full, paragraph locator. Why: central link among community, WeWork, adtech abstention and long-duration human needs. Limit: broad normative thesis and portfolio examples do not prove causality or returns.
- ★★★ | We All Need More Empathy in Our Lives — and Deaths | https://medium.com/aleph-vc/we-all-need-more-empathy-in-our-lives-and-deaths-c4ffc2b8888f | 2021-04-07 | ex-ante Empathy deal essay; reliability A | Verification: full, headings and paragraphs. Why: direct statement of the values-create-value thesis. Limit: investment announcement without independent outcome evidence.
- ★★★ | Empowering Others to RiseUp! | https://www.aleph.vc/content/empowering-others-to-riseup | 2022-04-13 | deal essay; reliability A | Verification: partial; byline/date and two stable opening paragraphs. Why: supports a founder/ideation chronology and anticipated objections about an Israel-only nine-million-person market and lower-income subscription customers. Limit: Aleph's answer, investment decision, product, price, impact, expansion, financing and return are unavailable.
- ★★★ | Aleph III | https://www.aleph.vc/content/aleph-iii | 2019-12-17 | fund announcement; reliability A | Verification: full, headings and paragraphs. Why: primary statement of fund size, stage, geography and claimed strategy continuity. Limit: fundraising communication, not audited fund documentation.
- ★★★ | Introducing the Aleph AI Team | https://medium.com/aleph-vc/introducing-the-aleph-ai-team-building-the-next-wave-of-ai-companies-26a8df04320c | 2025-03-26 | sector thesis and program announcement; reliability A | Verification: full, headings and lists. Why: current AI thesis places moats in data, distribution and domain depth rather than foundation models. Limit: very early thesis with no mature outcome set.
- ★★★ | Announcing Aleph V: Long Israel | https://medium.com/aleph-vc/announcing-aleph-v-long-israel-2d810e6e48ca | 2026; exact publication day unverified | fund announcement; reliability A | Verification: metadata only; first-party index verifies the 2026 title and canonical URL, while the body returns 403. Why: preserves the existence of the announcement. Limit: exact day, byline, legal vehicle, fund size, close status, mandate, stage, geography, team, portfolio, deployment and performance are unavailable.
- ★★★ | Incorporate in Israel or Delaware? | https://www.aleph.vc/content/incorporate-in-israel-or-delaware | 2024-03-05 | policy and founder-advice essay; reliability A | Verification: full, headings and paragraphs. Why: modern tax, governance and national-interest tradeoffs. Limit: policy advocacy, not legal or tax advice; rules can change.
- ★★★ | Be Long Israel. We Are. | https://medium.com/aleph-vc/be-long-israel-we-are-c4197869cd16 | 2024-02-14 | wartime firm essay; reliability A | Verification: partial; first-party index verifies title, Michael A. Eisenberg byline, date and an opening fragment that Aleph had been investing since October 7. Why: supports timing and a firm-level wartime statement only. Limit: no quotation, amount, sector, vehicle, pace, decision rule or result is used.
- ★★★ | Why We Are So Optimistic About Israel | https://www.aleph.vc/content/why-we-are-so-optimistic-about-israel | 2014-09-08 | ecosystem thesis; reliability A | Verification: full, headings and paragraphs. Why: early Aleph-era scale-up and resilience argument. Limit: advocacy predating later political, capital and war shocks.
- ★★★ | 2016 Prediction | https://www.aleph.vc/content/2016-prediction | 2016-01-13 | market prediction; reliability A | Verification: full, paragraphs. Why: falsifiable get-out-of-adtech call for a forecast scorecard. Limit: one selected prediction is not a complete prediction denominator.
- ★★★ | The Hummus Manifesto — Part 1 | https://medium.com/%40mikeeisenberg/the-hummus-manifesto-part-1-a95bce2803be | original 2010-07-12; Medium repost 2015-05-05 | policy manifesto; reliability A | Verification: full, headings, paragraphs and original-date footer. Why: diagnoses talent fragmentation and an obsolete technology stack. Limit: surviving repost; original Blogspot route is dead.
- ★★★ | The Hummus Manifesto — Part 2 | https://medium.com/%40mikeeisenberg/the-hummus-manifesto-part-2-b936e697c7ad | original 2010-07-14; Medium repost 2015-05-05 | policy manifesto; reliability A | Verification: full with original-date footer. Why: critiques indiscriminate state R&D and argues for focused disruptive bets. Limit: polemical policy essay, not a program evaluation.
- ★★★ | The Hummus Manifesto — Part 3 | https://medium.com/%40mikeeisenberg/the-hummus-manifesto-part-3-36715d526f57 | original 2010-09-06; Medium repost 2015-05-05 | policy manifesto; reliability A | Verification: full with framework bullets and original-date footer. Why: institutional prescriptions behind the scale-up-nation thesis. Limit: surviving repost and author-selected evidence.
- ★★ | Hummus Manifesto Part 4 — It's Amazon Stupid! | https://medium.com/%40mikeeisenberg/hummus-manifesto-part-4-it-s-amazon-stupid-e20763aad70 | original 2011-10-04; Medium repost 2015-05-11 | policy manifesto; reliability A | Verification: full with original-date footer. Why: concrete infrastructure bet on Amazon, AWS, cloud and logistics. Limit: must be scored against subsequent timing and policy, not read as prescience by default.
- ★★★ | An Open Letter to Zeev Holtzman: The Sky Is Not Falling | https://medium.com/%40mikeeisenberg/an-open-letter-to-zeev-holtzman-the-sky-is-not-falling-in-israel-it-is-getting-brighter-45a9ddeb39d | original 2011-05-31; later Medium repost | open letter; reliability A | Verification: full with original-date footer. Why: early scale-up-nation formulation and debate over Israel's fund landscape. Limit: response to a named peer, not a market census.
- ★★★ | The Only 8 Things That Matter for Israel's Venture Capital Industry | https://medium.com/%40mikeeisenberg/the-only-8-things-that-matter-for-israel-s-venture-capital-industry-e88a1f09b97e | original 2012-07-19; Medium repost 2015-05-13 | investment-policy essay; reliability A | Verification: full, numbered sections and original-date footer. Why: explicit venture-scale filters, market math and exclusions. Limit: normative checklist without complete pass or outcome denominator.
- ★★ | Connected Economics — The Threat — Part 1 | https://medium.com/%40mikeeisenberg/connected-economics-the-threat-part-1-d57ada01682f | original 2013-01-18; later Medium repost | macroeconomic essay; reliability A | Verification: full with original-date footer. Why: internet deflation, global labor and capital, and state-policy lag. Limit: broad macro claims require official-data controls.
- ★★ | Wake Up and Smell the Java: Israel Needs the Internet | https://medium.com/%40mikeeisenberg/wake-up-and-smell-the-java-israel-needs-the-internet-18238f2dd31d | original 2006-04-27; Medium repost 2015 | early blog essay; reliability A | Verification: full with original-date footer. Why: early internet-infrastructure and digital-economy thesis. Limit: repost may not preserve all original links or comments.
- ★★★ | Doohickeys and Metoohickeys | https://medium.com/%40mikeeisenberg/doohickeys-and-metoohickeys-e58e8cd89247 | original 2006-09-18; Medium repost 2015 | investment essay; reliability A | Verification: full with original-date footer. Why: early distinction between a viable small business and a venture-scale opportunity. Limit: heuristic, not a complete investment-selection record.
- ★★★ | Sarah Lacy, David Li and the Wrong Side of Historical Performance | https://medium.com/%40mikeeisenberg/sarah-lacy-david-li-and-the-wrong-side-of-historical-performance-b74f4851cf32 | original 2009-03-26; Medium repost 2015 | investment essay; reliability A | Verification: full with original-date footer. Why: contrarianism, scarce capital and rear-view-mirror selection. Limit: argumentative response with no audited performance data.
- ★★★ | Parashat Ki Tisa: The Golden Calf and Venture Capital Investments | https://medium.com/%40mikeeisenberg/parashat-ki-tisa-the-golden-calf-and-venture-capital-investments-ae846aaf83f9 | 2022-02-17 | Torah and investment essay; reliability A | Verification: full, heading and paragraphs. Why: patience framework tied to Healthy.io and Seeking Alpha. Limit: illustrative cases are selected retrospectively.
- ★★ | The Tree of Life and Prosperity | https://www.everand.com/book/512764969/The-Tree-of-Life-and-Prosperity-21st-Century-Business-Principles-from-the-Book-of-Genesis | 2021-08-24 | English book preview; reliability A | Verification: partial but substantively analyzed; publisher preview exposes contents, preface, and only the beginning of the anchor-and-seven-satellites framework. Why: supports the people-first self-description, ethics/trust premise and visible framework portion. Limit: chapters and the remainder of the framework were not available or inferred.
- ★★ | Milk, Honey and Uncertainty — Hebrew edition | https://media.alhatorah.org/Books/Bemidbar_Hebrew_-_Michael_Eisenberg.pdf | 2022; exact day not exposed | Hebrew book PDF; reliability A | Verification: full PDF with stable page locators. Why: extended treatment of uncertainty, leadership, national purpose and economics. Limit: Hebrew-language claims require careful translation and the edition date is year-only.
- ★★★ | Spreading Wealth Through Covenantal Capitalism | https://www.etzion.org.il/sites/default/files/2025-01/Eisenberg0053-00721.pdf | 2024 | journal essay; reliability A | Verification: full PDF, printed pages and DOI 10.54469/3728GBSH2. Why: most formal synthesis of covenant, wealth creation and stakeholder obligation. Limit: normative essay rather than an empirical investment study.
- ★★★ | Building Israel's Trillion-Dollar Economy | https://sapirjournal.org/money/2025/building-israels-trillion-dollar-economy/ | 2025-11-11 | long-form policy essay; reliability A | Verification: full, headings and paragraphs. Why: current scale, finance, productivity and institutional-reform thesis. Limit: advocacy and forecasts require later outcome testing.
- ★★ | Big Tech Is a Modern Tower of Babel That Must Be Scattered | https://www.washingtonexaminer.com/opinion/436279/big-tech-is-a-modern-tower-of-babel-that-must-be-scattered/ | 2021-08-08 | op-ed; reliability A | Verification: full, paragraph locator. Why: platform concentration, speech and technology-governance position. Limit: opinion outlet and short format; policy effects are untested.
- ★★ | Children Are Growth | https://hashiloach.org.il/issue-25-kkrz-me/ | 2021-06, issue 25; exact day not exposed | Hebrew essay; reliability A | Verification: full, headings and paragraphs. Why: connects demographics, uncertainty, innovation and growth. Limit: Hebrew text and normative demographic claims require external data.
- ★★ | Abraham, Wealth and Economic Fraternity | https://www.globes.co.il/news/article.aspx?did=1001428811&fid=2 | 2022-11-04 | Hebrew op-ed; reliability A | Verification: full/indexed, paragraph locator. Why: applies Abrahamic economics to wealth and social responsibility. Limit: op-ed is direct voice but not investment-outcome evidence.
- ★★ | Meet Aleph: Our New $140 Million Venture Capital Fund | https://www.aleph.vc/content/meet-aleph-our-new-140-million-venture-capital-fund | 2013-07-03 | official firm announcement; reliability A with attribution qualification | Verification: full, headings and bullets. Why: founding principles and equal-partnership design. Limit: bylined Eden Shochat; do not attribute every sentence solely to Eisenberg.
Talks, interviews, podcasts, and event routes
- ★★★ | Michael Eisenberg on the Start-Up Nation, Storytelling, and the Power of Technology | https://www.econtalk.org/michael-eisenberg-on-the-start-up-nation-storytelling-and-the-power-of-technology/ | 2022-02-14; recorded 2022-01-25 | official EconTalk audio and full publisher transcript; reliability A for attributed voice | Verification: complete publisher transcript with timestamps; processed to a source note and synthesis section. Why: investing principles, PictureVision attribution boundary, backcasting, values, competition and long-humanity thesis. Limit: retrospective interview and book-tour context; host challenges remain separate evidence.
- ★★★ | Executive Profile: Michael Eisenberg, Partner at Aleph VC and Investor in WeWork | https://yucommentator.org/2017/11/executive-profile-michael-eisenberg-partner-aleph-vc-investor-wework/ | 2017-11-12 | complete edited Q&A; reliability A/B | Verification: full publisher text processed by exact interviewer-question anchors; PDF issue mirror also exists. Why: career path, YU writing formation, status-quo skepticism and contemporaneous WeWork sourcing rationale. Limit: student-newspaper editing; introduction, board list and AUM are reporter framing rather than Eisenberg answers.
- ★ | The Silicon Valley of the Middle East | https://www.yu.edu/news/the-silicon-valley-of-the-middle-east | 2013-09-30 | official event report/announcement; reliability A/B | Verification: full event metadata. Why: contemporaneous Aleph launch-era biography and stated $140 million fund context. Limit: not a transcript of the October 9 presentation.
- ★★ | Michael Eisenberg of Benchmark Capital — TCTV | https://techcrunch.com/video/michael-eisenberg-of-benchmark-capital/ | recorded 2012-07-16; current publisher upload 2023-06-05 | 13:30 video interview; reliability A for visible attributed answers/A-B for publisher metadata | Verification: complete official YouTube video processed from synchronized English en-orig automatic captions, with cue positions checked against the track; acquisition media: https://www.youtube.com/watch?v=mBX3C3Pf7w8. Why: contemporaneous Benchmark-era voice before Aleph. Limit: later upload and machine captions; the publisher description's role label is secondary framing.
- ★★★ | Bill Gurley and Michael Eisenberg on an Impending Bust | https://www.thetwentyminutevc.com/bill-gurley-michael-eisenberg | publisher page 2021-12-05; official RSS record 2021-12-06 | joint 20VC interview; reliability A for attributed audio/A-B for show notes | Verification: complete 50:01 official RSS audio processed with OpenAI gpt-4o-transcribe-diarize in three duration-safe chunks; offsets and speaker handoffs were reconciled. Why: cycle comparison, price, ownership, capital use, boards and temporal diversification. Limit: no publisher transcript; show notes are not answers, Gurley's views stay separate, and ambiguous cross-talk was excluded.
- ★★★ | Foundation Models Are the Fastest Depreciating Asset in History | https://www.thetwentyminutevc.com/michael-eisenberg-2 | 2024-06-19 | solo 20VC interview; reliability A for attributed video/A-B for show notes | Verification: complete 1:02:17 official YouTube video processed from synchronized English en-orig automatic captions and checked by cue; acquisition media: https://www.youtube.com/watch?v=dgiwcus79I8. Why: AI filters, ownership, exits, board craft, sourcing and portfolio mechanics. Limit: provocative publisher framing and machine-caption risk; no publisher-certified transcript.
- ★★★ | Interview with Michael Eisenberg | https://www.maxraskin.com/interviews/michael-eisenberg | page displays Jan 15 without year; accessed 2026-08-22 | complete edited text Q&A; reliability A/B | Verification: full publisher text processed by section heading and exact question anchor. Why: learning process, S-1/K-1 wording, diligence vocabulary, time allocation, CRM and work ethic. Limit: publication year, audio and editing record are unavailable; the K-1 wording may be a speaker or editorial error.
- ★★ | The Human Founder, Episode 149 | https://podcasts.apple.com/il/podcast/episode-149-with-michael-eisenberg-general-partner-at/id1559540616?i=1000671324444 | 2024-09-30 | 54:06 podcast; reliability A for attributed audio/A-B for host metadata | Verification: complete official Podbean RSS audio at https://thehumanfounder.podbean.com/e/episode-149-with-michael-eisenberg-general-partner-at-%D7%B4aleph%D7%B4/ processed with OpenAI whisper-1 verbose-json segment timestamps; explicit turns support attribution and ambiguous cross-talk was excluded. Why: Print Life failure, financing dependence, relationships, shutdown judgment, partner credit and Aleph formation. Limit: no publisher transcript; Apple/Podbean summary and host introduction are not answers.
- ★★★ | Agency Under Fire | https://www.aleph.vc/content/agency-under-fire | 2026-03-09 | Invested solo episode with first-party full transcript; reliability A for direct dated voice | Verification: complete publisher transcript and key-topic timestamps processed. Why: current agency-at-scale, wartime investing, defense technology, sovereignty, atoms and capital-flow forecasts. Limit: first-party wartime advocacy; market and military claims are unverified, and the cited Aleph annual letter is not public in full.
- ★★ | What's Next: The Civic Revolution in Israel | https://18forty.org/podcast/michael-eisenberg-whats-next-the-civic-revolution-in-israel/ | 2023-12-12 in the official RSS record; publisher YouTube dated 2023-12-13 | 18Forty interview; reliability A for attributed audio/A-B for show notes | Verification: complete 1:14:27 official Spreaker RSS MP3 processed with OpenAI whisper-1; guest conversation is 07:24-59:51. Why: civic agency, capital as accountability, Aleph's stated geography and post-October 7 mission. Limit: no publisher transcript; dynamic-ad audio has a different timebase from page/show-note timing, and host framing outside the guest band is excluded.
- ★★★ | Iran, USA, Israel: What Comes Next | https://18forty.org/podcast/michael-eisenberg/ | 2026-04-18 | 18Forty interview with full Sofer.ai transcript lightly edited by the publisher; reliability A/B | Verification: complete publisher text processed; interview begins 6:13 and later claims use exact question/topic anchors because no later timestamps are exposed. Why: latest long-form direct voice on war, Israel-diaspora relations, religion, statecraft and public work. Limit: machine transcription/light editing and thin venture mechanics; host biography and figures are secondary.
- ★★ | Michael Eisenberg on AI, Abraham Accords and Why He's Bullish About Israel's Future | https://www.misgavins.org/en/ep-8-michael-eisenberg-on-ai-abraham-accords-and-why-hes-bullish-about-israels-future/ | 2025-08-13 | 1:08:46 Misgav podcast; reliability A for attributed audio/A-B for synopsis | Verification: complete official RSS audio processed with OpenAI whisper-1. Why: AI, national infrastructure, talent constraints, economy and regional integration. Limit: no publisher transcript; the transcription copy decoded 10 seconds longer, so post-20:36 locators are conservative ranges requiring official-audio checking before quotation.
Historical Israel Seed and transition reporting
- ★★★ | Seed Investing: Sowing in a Cemetery | https://www.globes.co.il/news/article.aspx?did=534032 | 2001 | contemporaneous Hebrew industry report; reliability B | Verification: full/indexed quotes from Eisenberg and Alan Feld. Why: early-stage persistence, long-duration fund design and power-law rationale during the bust. Limit: reported claims, translation risk and no underlying LP research.
- ★★ | Israel Seed Backs Sharon Azulai's EIR | https://www.globes.co.il/news/article.aspx?did=687151 | 2003-05-11 | contemporaneous Hebrew deal report; reliability B | Verification: full/indexed direct quotations. Why: people-before-idea EIR model and Qlusters/Conduct case context. Limit: journalistic summary; duplicate variant did=687243 is excluded.
- ★★★ | The Microwave-Company Era Is Over | https://www.globes.co.il/news/article.aspx?did=813837 | 2004-07-12 | Hebrew fund profile; reliability B | Verification: full/indexed direct quotations. Why: company-building duration, pivots and pre-Shopping.com fund posture. Limit: reported profile and expected-exit framing.
- ★★ | Israeli Companies Law Almost Blocked the Shopping.com IPO | https://www.globes.co.il/news/article.aspx?did=861325 | 2004-12-06 | Hebrew conference report; reliability B | Verification: full/indexed panel remarks; duplicate did=861211 excluded. Why: governance, director-selection and regulatory position tied to a realized company. Limit: edited panel account, not legal analysis.
- ★★★ | I Understood I Would Never Be Considered Israeli | https://www.globes.co.il/news/article.aspx?did=899795 | 2005-03-31 | long Hebrew profile/interview; reliability B | Verification: substantial indexed text; alternate did=899747 is the same work family. Why: fullest Israel Seed-era biography plus explicit criticism, failed-company examples and 2004 outcomes. Limit: some access can be subscriber-gated and anonymous talkback criticism is not verified evidence.
- ★★ | Shopping Last | https://www.globes.co.il/news/article.aspx?did=922590 | 2005 | Hebrew Shopping.com retrospective; reliability B | Verification: full/indexed account of the 1999 CEO recruitment. Why: traces Eisenberg's role in recruiting Dan Ciporin and the pre-IPO company-building story. Limit: published six years after the 1999 event and lacks closing documents.
- ★★★ | Israel Seed Stops Raising Fund V; Eisenberg Joins Benchmark | https://www.globes.co.il/news/article.aspx?did=922658 | 2005-06-09 | contemporaneous Hebrew transition report; reliability B | Verification: full, named quotes and fund figures. Why: precise Israel Seed closure/new-investment boundary, vehicle totals and Benchmark move. Limit: reported fund amounts and success claims are not audited cash flows.
Funds, filings, board roles, and company outcome controls
- ★★★ | Aleph-Aleph, L.P. Form D | https://www.sec.gov/Archives/edgar/data/1588089/000158944413000002/xslFormDX01/primary_doc.xml | 2013-10-30 | SEC exempt-offering notice; reliability A | Verification: full XML, signed by Eisenberg, with issuer and related-person fields. Why: primary Aleph launch vehicle and legal-role evidence. Limit: Form D is unaudited, omits portfolio, LPs, cash flows and performance.
- ★★★ | Aleph IV, L.P. Form D | https://www.sec.gov/Archives/edgar/data/1899105/000189910521000001/xslFormDX01/primary_doc.xml | 2021-12-15 | SEC exempt-offering notice; reliability A | Verification: full XML signed by Eisenberg. Why: later vehicle, address and related-person continuity. Limit: no offering-performance or portfolio disclosure.
- ★★★ | Shopping.com S-1/A | https://www.sec.gov/Archives/edgar/data/1108482/000119312504161119/ds1a.htm | 2004-09-24 | SEC registration statement; reliability A | Verification: full filing with page and section locators. Why: company history, ownership, accumulated losses, risks and IPO capitalization for the canonical Israel Seed outcome. Limit: offering snapshot; does not yield Eisenberg's personal economics or a full Israel Seed return.
- ★★★ | Finjan S-1/A | https://www.sec.gov/Archives/edgar/data/1366340/000119380514000080/e611753_s1a-finjan.htm | 2014-01-15 | SEC registration statement; reliability A | Verification: full filing with Eisenberg's director history and Aleph/Benchmark chronology. Why: board-role duration and a complex operating-company/IP outcome. Limit: reorganized company and resale registration; not proof that Eisenberg sourced every Finjan transaction.
- ★★★ | Wix 2013 Form 20-F | https://www.sec.gov/Archives/edgar/data/1576789/000104746914002723/a2219037z20-f.htm | 2014-03-20 for FY2013 | SEC annual report; reliability A | Verification: full filing with page/Item locators and Eisenberg biography. Why: board tenure, Benchmark-era attribution, company economics and post-IPO ownership context. Limit: company-level filing, not Benchmark fund cash flows.
- ★★★ | WeWork S-1 | https://www.sec.gov/Archives/edgar/data/1533523/000119312519220499/d781982ds1.htm | 2019-08-14 | withdrawn SEC registration statement; reliability A | Verification: full filing with governance, related-party, loss and capitalization sections. Why: primary adverse control for the WeWork thesis and board oversight. Limit: offering was withdrawn and the filing does not allocate individual-board responsibility.
- ★★★ | Lemonade S-1/A | https://www.sec.gov/Archives/edgar/data/1691421/000104746920003846/a2241899zs-1a.htm | 2020-06-18 | SEC registration statement; reliability A | Verification: full filing with Aleph ownership and voting-power footnotes. Why: tests the 2015 deal essay against capitalization, losses, risks and governance. Limit: IPO snapshot; later sales and returns require subsequent Forms 4 and cash-flow data.
- ★★★ | Freightos 2022 Form 20-F | https://www.sec.gov/Archives/edgar/data/1927719/000141057823000461/crgo-20221231x20f.htm | 2023-03-31 for FY2022 | SEC annual report; reliability A | Verification: full filing with Eisenberg board tenure and Aleph holdings footnotes. Why: board, vehicle ownership and public-company outcome control. Limit: de-SPAC/public snapshot and no Aleph cost/realization ledger.
- ★★★ | Windward Admission Document | https://investors.windward.ai/wp-content/uploads/2021/10/Windward-Ltd-Admission-Document.pdf | 2021 | London admission document; reliability A | Verification: full PDF with pages, Aleph holdings and financing amounts. Why: strongest public ownership/capitalization route for Windward. Limit: issuer-prepared offering document, not Aleph fund performance; UK listing conventions differ from SEC filings.
- ★★★ | Aleph Companies | https://www.aleph.vc/companies | current page; accessed 2026-08-22 | official dynamic portfolio page; reliability A for firm-listed associations | Verification: full dynamic page with company cards and exit labels. Why: best current institutional Aleph portfolio denominator and status map. Limit: dynamic/current presentation can omit failed, renamed, written-off or older realized companies and does not allocate partner credit.
Adverse, legal, skeptical, and institutional controls
- ★★ | Why WeWork Thinks It's Worth $20 Billion | https://www.wired.com/story/this-is-why-wework-thinks-its-worth-20-billion/ | 2017-09-06 | contemporaneous reported profile; reliability B | Verification: full article and attributable Eisenberg thesis at paragraphs around the valuation discussion. Why: pre-collapse WeWork rationale based on enterprise real-estate services and scale. Limit: journalist-selected quotation and no board documents.
- ★★★ | Inside the Fall of WeWork | https://www.vanityfair.com/news/2019/11/inside-the-fall-of-wework | 2019-11-21 | investigative feature; reliability B | Verification: full/metered article with named reporting. Why: governance and outcome counterweight, including Eisenberg's role during the Neumann crisis. Limit: secondary reconstruction with anonymous sources; not an adjudicated record.
- ★★★ | WeWork Chapter 11 Form 8-K | https://www.sec.gov/Archives/edgar/data/1813756/000119312523271902/d522028d8k.htm | 2023-11-07; petitions filed 2023-11-06 | SEC current report; reliability A | Verification: full filing, Item 1.03 and Restructuring Support Agreement section. Why: primary company-level bankruptcy outcome control for the earlier WeWork thesis. Limit: does not calculate Benchmark's realized loss or assign personal responsibility for each governance decision.
- ★★★ | JPMorgan Sues Aleph Over Frank Fraud Fallout | https://www.calcalistech.com/ctechnews/article/ry2dgpthzg | 2026-04-12 | legal/business report; reliability B | Verification: full article and Aleph response. Why: current contractual dispute and Frank diligence/outcome context. Limit: allegations remain unresolved; report explicitly says the complaint does not allege Aleph knew of or participated in fraud.
- ★★★ | Ehud Barak and Former Cyber Chief Sue Eisenberg over Paragon Posts | https://www.ynetnews.com/business/article/h1aabs4ggl | 2025-05-28 | legal report; reliability B | Verification: full article summarizes both pleadings and Eisenberg's defense. Why: material reputational/legal dispute and possible conflict allegations. Limit: pending allegations, not findings; underlying Hebrew pleadings remain a retrieval lead.
- ★★★ | SEC Charges Founder of Frank with Fraud | https://www.sec.gov/newsroom/press-releases/2023-74 | 2023-04-04 | SEC enforcement release; reliability A | Verification: full official release linked to the complaint. Why: primary regulator chronology and alleged customer-data fabrication. Limit: action is against Charlie Javice, not Eisenberg or Aleph; allegations at filing were not yet findings.
- ★★★ | Startup CEO Charlie Javice Sentenced to 85 Months | https://www.justice.gov/usao-sdny/pr/startup-ceo-charlie-javice-sentenced-85-months-prison-175-million-fraud | 2025-09-29 | DOJ sentencing release; reliability A | Verification: full official disposition, sentence, forfeiture and restitution. Why: adjudicated criminal outcome for the Frank fraud. Limit: does not adjudicate Aleph's diligence, knowledge or separate support-agreement liability.
- ★★★ | JPMorgan v. Frank Holders — redacted complaint mirror | https://assets.bwbx.io/documents/users/iqjWHBFdfxIU/rkgqKTKU8u.Q/v0 | 2026-03-11 draft/redacted complaint | Bloomberg-hosted pleading mirror; reliability A for allegations/B for mirror provenance | Verification: full 58-page PDF names Aleph entities and pleads support-agreement claims. Why: primary allegation set for the 2026 contractual case. Limit: complaint is not a ruling; mirror label says draft and should be replaced by the official docket copy when available.
- ★★★ | Benchmarking Government Support for Venture Capital: Israel | https://www.oecd.org/en/publications/benchmarking-government-support-for-venture-capital_82cd3fe1-en/israel_b5c8cc2e-en.html | 2025 | OECD country note; reliability A/B | Verification: full institutional note with downloadable PDF and data notes. Why: independent denominator for foreign-capital dependence, public programs and sector concentration. Limit: country-level aggregates do not measure Aleph or Eisenberg performance.
- ★★★ | Financing Characteristics of High-Tech Companies in Israel | https://www.boi.org.il/en/communication-and-publications/press-releases/analysis-by-the-bank-of-israel-s-research-departmentfinancing-characteristics-of-high-tech-companies-in-israel/ | 2020 | Bank of Israel research summary; reliability A | Verification: full official analysis and linked study. Why: financing structure and global-VC-share control for Eisenberg's macro claims. Limit: sector-level data and publication-period definitions may not match individual deals.
Coverage assessment, search ledger, and open gaps
Inventory. This map contains 75 deduplicated annotated routes: 1 first-party identity/portfolio route, 35 direct writings/books/op-eds and official firm statements, 12 talks/interviews/podcast routes, 7 historical Israel Seed or transition reports, 10 fund/company filing or official-portfolio controls, and 10 adverse/legal/skeptical/institutional controls. The 35 written routes reconcile to 26 fully readable, 7 partially readable and substantively analyzed, and 2 metadata-only, for 33 substantively analyzed works. The seven partial works are Why We Decided to Drink the Lemonade, LMND - Aleph's First IPO, A Look Back at Our Letters to Our LPs and Capital Exuberance, Invest in Relationships, Not Transactions, Empowering Others to RiseUp!, The Tree of Life and Prosperity, and Be Long Israel. We Are. The metadata-only works are Melio: Investing in Great People and Announcing Aleph V: Long Israel. The spoken denominator is 11 of 11 priority routes processed plus one unprocessed ★ event-metadata route that has no transcript. Acquisition reconciles exactly to 5 publisher texts/Q&As/transcripts, 2 official automatic-caption tracks, and 4 OpenAI transcriptions of official RSS audio; every priority route has a note and a substantive synthesis section. The 11 works come from nine venue families: the two 20VC works and two 18Forty works are separate appearances but not independent publisher families. The map has nine full filing/admission documents plus the official Aleph portfolio page. Direct voice establishes dated statements, not source-family-independent corroboration, economic truth, or individual deal credit.
Variants and time sweeps. Searches used Michael Eisenberg, Michael A. Eisenberg, Mike Eisenberg, מייקל אייזנברג, mieisenberg, @mikeeisenberg, Six Kids and a Full Time Job, Israel Seed, Benchmark Israel, Aleph, LP letter, annual letter, shareholder letter, memo, writings, books, op-ed, newsletter, transcript, PDF, board, resignation, failure, write-off, lawsuit, litigation, defamation, fraud, SEC, Frank, WeWork and Paragon. Sweeps covered 1995–2005 Israel Seed, 2005–2013 Benchmark, the 2013 Aleph launch, 2014–2019 early portfolio/fund formation, 2020–2022 IPO/exuberance/capital-cycle writing, and 2023–2026 war, AI, public-policy, litigation and Aleph V material.
Direct-voice/archive boundary. The Aleph content archive and the two Medium author/publication routes were searched title-by-title; the surviving Medium imports are preferred over dead Six Kids Blogspot originals because they retain author identity and original-date footers. The Aleph website often duplicates article and podcast chrome, so only publisher-visible article text is evidence. The stable 2022 LP-retrospective route exposes one opening paragraph: it establishes Eisenberg's annual-letter responsibility and named inspirations but no letter excerpt or cycle policy. No complete public LP letter, shareholder letter, annual letter or internal-memo corpus was found. Eisenberg told Max Raskin that he writes a weekly Globes piece and a WhatsApp-distributed piece; the latter is not a public, auditable archive. Canonical firm routes use aleph.vc and medium.com/aleph-vc; look-alike Aleph domains were excluded. The legacy israelseed.com domain now resolves to unrelated/hijacked gambling-style content and is excluded rather than treated as an archival Israel Seed source.
Access and attribution gaps. Nine works have limited access. Seven are partially readable and substantively analyzed: Why We Decided to Drink the Lemonade (one opening paragraph), LMND - Aleph's First IPO (one opening paragraph), A Look Back at Our Letters to Our LPs and Capital Exuberance (one opening paragraph), Invest in Relationships, Not Transactions (one opening paragraph), Empowering Others to RiseUp! (two opening paragraphs), The Tree of Life and Prosperity (contents, preface and partial framework preview), and Be Long Israel. We Are. (metadata plus opening fragment). Two are metadata-only: Melio: Investing in Great People and Announcing Aleph V: Long Israel. Obtain lawful stable captures before adding unavailable body claims or quotations. Hashiloach and Globes access can vary by locale/subscription; no paywall was bypassed. Original Six Kids comments, link context and several Blogspot pages remain unavailable. Meet Aleph is bylined to Eden Shochat and is an official co-founding statement, not sole Eisenberg authorship; Aleph III is jointly signed by Aaron Rosenson, Eden Shochat, Michael Eisenberg and Yael Elad. Interview show notes are not transcripts. A board seat, related-person listing, signature or beneficial-ownership power does not prove individual sourcing, approval, ownership or economics.
Vehicle and outcome denominator. Israel Seed, Benchmark Israel and Aleph must remain separate; personal capital must not be inferred from a vehicle holding. A union of the mapped contemporary Israel Seed sources produces a working institutional minimum of about 20 distinct companies after treating DealTime/Shopping.com and Alchemedia/Finjan as corporate paths rather than duplicate investments; only DealTime/Shopping.com currently has strong direct person-level sourcing testimony. The provisional Benchmark person-candidate set is 10 names—Conduit, Digital Fuel, Finjan, Clarizen, Wix, Gigya, Seeking Alpha, TuneWiki, Zlango and WeWork—but only Wix, WeWork, Seeking Alpha and Finjan currently have stronger board, filing or direct-testimony support, so no hit rate is computed. Eisenberg's first-party biography says Aleph has invested in more than 40 companies; the dynamic official companies page is the current institutional base, while older sources add omitted or historical names including Frank, Bringg, JoyTunes, Healthy.io, Nexar, Colu, Anodot and Yevvo. Exact Aleph and career-wide denominators remain uncomputable until those routes are exported, deduplicated and reconciled with failed, renamed, written-off, follow-on and personal investments. The public record supplies Form D notices and selected-company filings but no complete cap-table, pass, ordinary-outcome, cash-flow, DPI, TVPI or final IRR denominator. Company IPO value is not fund profit. Frank criminal findings establish founder fraud, not Aleph knowledge; the 2026 support-agreement complaint is unresolved. Paragon allegations are pending.
Completed-peer controls. Bill Gurley's source map is the closest completed Benchmark-partner and cycle-discipline control; Andy Rachleff's source map controls Benchmark's founding equal-partnership model and attribution; Chemi Peres's source map and Neil Rimer's source map provide Israeli and European venture comparisons. These are comparison routes only; no peer claim transfers to Eisenberg without its own source.
Identity controls. Avraham Eisenberg's SEC, Mango Markets and criminal matters are unrelated and excluded. Archaeologist and academic Michael Eisenberg, Michael Isenberg, Michael Ellsberg and similarly named executives were excluded. Wikipedia, ranking listicles, unsourced databases and generic speaker biographies were used only as discovery leads and are not bibliography evidence.
Last-three-search saturation. (1) The exact search "Michael A. Eisenberg" "annual letter" Aleph PDF returned only the already-mapped annual-LP-meeting reflection and no public letter/PDF. (2) site:aleph.vc/content "Michael A. Eisenberg" (memo OR letter OR shareholders) returned already-mapped fund and strategy essays with no new memo corpus. (3) ("Six Kids and a Full Time Job" OR sixkidsandafulltimejob) "Michael Eisenberg" archive returned biographies, the known Medium archive and dead Blogspot references, but no new canonical originals. These last searches added no material source or fact; open-web discovery is saturated, with remaining gains dependent on lawful archive captures, private LP access or official court-docket retrieval.
Highest-value retrieval leads. Obtain the full 2018–2021 and current Aleph annual letters, archived Six Kids pages and comments, public copies of Eisenberg's early Commentator editorials, complete Israel Seed and Benchmark Israel fund/portfolio records, Aleph LP cash flows and portfolio denominator, deal memos, closing/allocation records, board minutes for WeWork and Frank, the official Delaware docket complaint and future disposition in JPMorgan's holder case, and the underlying pleadings/disposition in the Paragon defamation matter. Until then, reported returns, sourcing, governance judgments and current role boundaries stay qualified rather than guessed.
Source notes
t 18Forty: What's Next? The Civic Revolution in Israel
- URL: https://18forty.org/podcast/michael-eisenberg-whats-next-the-civic-revolution-in-israel/ | Published: 2023-12-12 | Format: podcast | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: OpenAI
whisper-1segment timestamps checked against the official Spreaker RSS MP3; dynamically retrieved audio duration 1:14:27, with the guest conversation at 07:24-59:51 and host framing, advertisements, and commentary outside that range.
Takeaways
- His venture career is presented as an economic-development vocation. Eisenberg traces it to Rabbi Yehuda Amital's Gulf War-era instruction to build a factory that would support 10,000 dignified livelihoods. He says he left an initial 18-month political-consulting career after deciding politics could not achieve that goal and recast high-tech companies as the modern factory. This is unusually direct motive evidence, but it is a retrospective origin story rather than a contemporaneous career record. [retrospective witness | moderate] [17:20-20:09]
- Aleph's stated mandate was geographically narrow and socially expansive. He says Aleph invested only in Israeli startups, then connects that choice to a stronger Israeli economy and “honest and decent” employment. The interview supports Eisenberg's public framing of Aleph, not the mandate of every fund or proof of realized social outcomes. [investor-stated | moderate] [20:41-20:58]
- Diffusion is his bridge from technology to politics. He argues that technology moves capability toward individuals at the network edge and that social organization follows. His resulting forecast is a shift from government management to government orchestration of citizen action. This is a macro philosophy; the episode does not show it operating as an Aleph screening rule. [researcher inference | moderate] [20:58-22:39; 31:29-31:52]
- He interprets Israel's civic response as a capability formed before the crisis. Military responsibility and technology tools developed during the judicial-reform conflict are offered as pre-existing infrastructure that citizens repurposed after October 7. The crisis examples are speaker-selected and do not establish comparative performance across societies. [retrospective witness | moderate] [22:39-24:38; 26:46-31:52]
- The portfolio observation is resilience, not immunity. He says Aleph companies had roughly 10-20% of staff in reserve duty yet were still delivering, while expressing more concern about government budgeting. No company-level data or counterexamples are supplied, so this remains a contemporaneous manager observation. [investor-stated | provisional] [35:05-35:51]
- Capital is valuable partly because it creates accountability. In contrasting investment with charity, he says owners monitor, return, and form a deeper partnership; he immediately disclaims investment-adviser status. His farm examples concern civic attachment, not a recommendation or venture return claim. [investor-stated | moderate] [46:16-48:15]
- LP support is framed as relationship durability. Eisenberg says every Aleph investor contacted the firm after October 7 and estimates that more than 95% of capital was from the United States and United Kingdom, with a very small Emirati share. These private fund-composition claims require LP or fund-primary corroboration. [investor-stated | provisional] [51:43-54:08]
- His intellectual method prizes agency and nonconformity. He names the Torah, Range, Red Notice, and Halakhic Man as influences, then rejects a hypothetical PhD on the ground that peer review dampens creativity. The latter is evidence of temperament, not a warrant to lower research standards. [retrospective witness | moderate] [55:28-57:47]
Quotes
- “Factories in the 21st century are high-tech companies.” [19:21-19:26]
- “We only invest in Israeli companies.” [20:47-20:51]
- “The law of technology is diffusion.” [20:58-21:05]
- “The world is going to move from management to orchestration.” [31:29-31:45]
- “We need to focus on doing, not talking.” [48:30-48:37]
- “Everything in life is personal and personal relationships matter.” [53:39-53:46]
- “Peer review dampens creativity.” [57:24-57:31]
Biography and decision evidence
- Eisenberg says he grew up on Manhattan's West Side, attended Manhattan Day School and MTA, and came from a Zionist family long established in the United States. [retrospective witness | moderate] [17:20-17:33]
- After his freshman year of college he studied at Yeshivat Har Etzion (“the Gush”); one year became two, placing him there during the Gulf War. He names Rabbi Michael Hecht, Rabbi Aharon Lichtenstein, and Rabbi Yehuda Amital as formative teachers or interlocutors. [retrospective witness | moderate] [17:33-18:16]
- He recalls Amital redirecting a question about settling Israel toward creating dignified employment, which Eisenberg says became a life goal. His later interpretation is that high-tech companies are the twenty-first-century factories he can enable as an investor. [retrospective witness | moderate] [18:16-20:09]
- He says his first career was political consulting for about a year and a half. The interview does not name the employer, dates, or clients, so those need an independent chronology source. [retrospective witness | moderate] [19:26-19:36]
- He says he chairs Hashomer HaChadash, describes its agricultural volunteer work, and connects that role to civic self-efficacy. The role and claimed 4,000 daily wartime volunteers were not independently verified here. [investor-stated | moderate] [20:09-20:37]
- He describes five children or sons-in-law then called into military service, four in Gaza, and later discusses the deaths of two cousins. This family context materially shapes the episode's crisis judgments and should accompany, not be stripped from, those claims. [investor-stated | moderate] [13:35-14:02; 29:14-31:07]
- He says his books are written in Hebrew partly because writing masks his American accent, and reports waking near 5:20 a.m. without an alarm. These are low-stakes autobiographical details rather than investment evidence. [investor-stated | moderate] [49:37-49:45; 58:05-58:39]
Philosophy signals
- Dignified livelihoods as the objective function: he connects company formation, national prosperity, personal dignity, family stability, and social contribution. [retrospective witness | moderate] [18:16-20:58]
- Power to the edge: technology's recurring direction is diffusion, making individuals more capable and enabling bottom-up organization. [researcher inference | moderate] [20:58-22:39]
- Government as orchestrator: public institutions should coordinate capable civic networks rather than attempt to manage all delivery directly. [investor-stated | moderate] [31:29-31:52]
- Shared action before shared opinion: trust comes from undertaking difficult work together; ideological agreement is not the necessary starting condition. [investor-stated | moderate] [27:47-28:31; 45:31-45:47]
- Ownership creates engagement: invested capital produces monitoring, recurring contact, and a sense of partnership that donations alone may not. [investor-stated | moderate] [46:16-48:15]
- Relationships are institutional resilience: his account of post-October 7 LP behavior treats durable personal ties as a protective asset for a country-specific fund. [investor-stated | moderate] [51:43-54:08]
Contradictions, counterevidence, and access limits
- Eisenberg calls technology a decentralizing force while comparing concentrated control of AI, infrastructure, and platforms to nation-state power. The episode recognizes both trajectories but does not resolve when diffusion beats concentration. [researcher inference | moderate] [09:53-11:01; 20:58-22:39]
- His preferred government role is orchestration rather than management, yet crisis orchestration itself needs authority, accountability, funding, and failure handling. Those institutional mechanics are largely absent. [researcher inference | moderate] [31:29-31:52]
- Evidence for civic and portfolio resilience comes from an extraordinary wartime sample selected by an advocate-investor. Reserve-duty percentages, company delivery, civic rescue outcomes, LP composition, and LP unanimity were not independently verified. [investor-stated | provisional]
- He defended Elon Musk against allegations of antisemitism based on a meeting and reports from mutual friends. That is Eisenberg's dated 2023 assessment, not an adjudicated finding; later evidence is outside this source and requires separate control research. [investor-stated | moderate] [08:33-11:51]
- His skepticism of peer review fits a nonconformist identity but conflicts with the dossier's need for reproducibility and adversarial verification. It should not be imported as a research rule. [researcher inference | moderate] [57:11-57:47]
- The 18Forty page provides show notes and a summary, not a verbatim transcript. This note used an OpenAI transcript of the complete official RSS audio. Quotes were checked against segment context; source audio should be consulted before final publication. The retrieved MP3 was 1:14:27 because it included ads and host material; only the guest conversation at 07:24-59:51 was attributed to Eisenberg.
Open questions
- Which dated career records identify Eisenberg's political-consulting employer, clients, and transition into venture capital?
- Was Amital's “10,000 livelihoods” exchange recorded closer to the event, and how consistently has Eisenberg told it over time?
- Is “only Israeli companies” a binding mandate for every Aleph vehicle, and how does the firm define an Israeli company?
- Can Aleph or portfolio-primary data substantiate the wartime staffing and delivery claims, including failures and delays?
- What are the audited geographic and institutional boundaries of the LP base described here?
- Which investment memos show that dignified employment, diffusion, civic agency, or founder responsibility affected an actual selection or follow-on decision?
- When does Eisenberg favor centralized infrastructure over edge diffusion, especially for AI and defense technology?
- How have his 2023 assessments of Musk, corporate power, and Israel's civic-government balance evolved in later interviews?
t Michael Eisenberg: Iran, USA, Israel: What Comes Next
- URL: https://18forty.org/podcast/michael-eisenberg/ | Published: 2026-04-18 | Format: 18Forty podcast with full Sofer.ai transcript, lightly edited by publisher | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: interview begins 6:13; exact host-question and answer-topic anchors because the transcript supplies no later timestamps
Takeaways
- [investor-stated | strong] Eisenberg opens with epistemic uncertainty—he calls the ceasefire tense and repeatedly distinguishes what he thinks from what he knows—yet makes forceful moral and strategic claims about Iran. The note treats those as wartime direct voice, not verified intelligence. 18Forty, interview begins 6:13, opening “general pulse” question
- [investor-stated | strong] A portable decision rule connects investing and statecraft: do not let a problem compound until response becomes existential; preemption is often unpopular, while a valuable contrarian decision may require enduring ridicule. He invokes Howard Marks's consensus/non-consensus matrix. The analogy expresses a preference for early non-consensus action but does not show that Aleph used it successfully in a deal. 18Forty, question on whether the Iran response was worth it
- [investor-stated | moderate] Eisenberg says he stopped trusting general reporting after seeing errors in coverage about himself and instead does his own research. His later advice is to call friends and family in Israel for authentic ground-level information. Direct networks can improve context, but neither personal access nor primary calls eliminate selection, secrecy, or confirmation bias. 18Forty, US–Israel sentiment answer and rapid-fire news question
- [investor-stated | provisional] He identifies four simultaneous revolutions: stressed democratic government, a failing welfare-state model, renewed war, and rapid AI disruption alongside energy/physical-infrastructure needs. This is a macro framework, not a sourced forecast, and the transcript gives no probabilities, timing bands, portfolio weights, or disconfirming indicators. 18Forty, answer after the “horseshoe theory” question
- [investor-stated | provisional] Eisenberg reports involvement in establishing Pact Silico and describes Israel–US military, intelligence, investment, and technology ties as exceptionally robust. He also cites an unnamed private-equity buyer considering further Israeli investment. The role, transaction, and flow claims remain self-reported and unnamed. 18Forty, question on whether the US–Israel relationship is irreparably different
- [investor-stated | strong] His national economic doctrine is “prosper and make others prosperous”: Israel should build an innovative, productive society whose exports, energy, trade, and institutions create material capability for citizens and neighbors. Prosperity is paired with obligation, not treated as an end state. 18Forty, question on Israel's next project after security
- [investor-stated | moderate] The implied venture translation is to prefer productive innovation that expands agency and exports a real capability, not merely rents or symbolism. The interview, however, contains almost no company-level underwriting evidence; it moves from theology and statecraft to economic aspiration without defining a venture screen. 18Forty, answer on prosperity, innovation, and a model society
- [investor-stated | provisional] Eisenberg predicts a smaller, less politically influential American Jewish community and a growing, more culturally generative Israel. These demographic and institutional forecasts are assertive but unsourced in the transcript; the stated percentages and population trajectory should not be reused without demographic controls. 18Forty, exchange on American Jewish continuity
- [investor-stated | moderate] Culture is “upstream” of politics and resilience in his framework. He argues that real-life national challenges generate religious and institutional creativity, and that calendars, language, service, and shared events shape identity. The mechanism resembles his venture preference for experience-tested knowledge, but the analogy is interpretive rather than a stated investment rule. 18Forty, exchange on American versus Israeli religious production
- [retrospective witness | moderate] The most important career-origin story is disclosed as a memory from 1991: after the Gulf War, Rav Yehuda Amital told Eisenberg to make aliyah and create employment that lets ten thousand people earn honestly. Eisenberg says he decided on the spot to pursue that purpose and later received a public reminder from Amital to keep working. It is powerful first-person biography recorded about thirty-five years later, with no contemporaneous document in the source. 18Forty, question “why aren't you a rabbi”
- [investor-stated | strong] The closing principle distinguishes mutual responsibility from cosmetic unity. Eisenberg argues that a dispersed people need a shared multi-decade project and reciprocal obligation even when they disagree. The organizational analogue is coordinated commitment without forced consensus; that application is researcher interpretation, not explicitly about Aleph. 18Forty, closing exchange “arvut not achdut”
- [investor-stated | moderate] Current biography in the transcript includes work with government that disrupts his sleep, ongoing Torah/economics/statecraft books, and morning-oriented work. These are self-reported April 2026 activities and should not be generalized beyond the date. 18Forty, rapid-fire book and sleep questions
Quotes
- “If you don’t rock the boat, your boat gets rocked.” — Michael Eisenberg, question on whether the Iran response was worth it
- “Being preemptive is generally right, not wrong.” — Michael Eisenberg, same answer
- “We have a commandment to be a prosperous society.” — Michael Eisenberg, question on Israel's next project
- “Comfort is not a benefit.” — Michael Eisenberg, Rav Amital career-origin answer
- “The key thing is arvut is mutual responsibility.” — Michael Eisenberg, closing exchange
Biography and decision evidence
- The publisher introduction describes Eisenberg as Aleph co-founder/general partner, reports $850 million under management, says Aleph has invested in more than fifty startups since 2013, lists example companies, and identifies boards, writing, lectures, family, and books. These are host-authored current-page claims, not Eisenberg's testimony or audited fund data. 18Forty, publisher summary before transcript
- [retrospective witness | moderate] Eisenberg says his father studied in Israel in 1967 and recounts a study partner's challenge that aliyah depended on personal action. The story frames agency as inherited family language but does not establish a causal investment mechanism. 18Forty, opening exchange after 6:13
- [retrospective witness | moderate] Eisenberg says he received teaching offers in Houston and Atlanta, had done Yachad and outreach work, studied at Yeshivat Har Etzion, and chose an Israel/employment path after Amital's 1991 instruction. The interview is the stated origin of purpose; education, offers, and timing remain uncorroborated here. 18Forty, question “why aren't you a rabbi”
- [investor-stated | provisional] He says he is “in the room,” has done government work, was involved in Pact Silico, and has access to military and policy figures. The interview provides no title, mandate, dates, minutes, decision authority, compensation, or conflict-management boundary. 18Forty, US–Israel relationship, news-source, and sleep answers
- [retrospective witness | provisional] Eisenberg says his children have served extensive reserve duty and that this experience changed their generation. Family experience informs the worldview but should not be converted into firm or portfolio evidence. 18Forty, answer on national aspiration and American Jewry
- [investor-stated | strong] He reports two active Hebrew book projects, one collecting several years of Genesis writing and one finishing a Torah series through Deuteronomy, with limited English translation. This is dated intellectual-output evidence rather than investing performance. 18Forty, rapid-fire book question
- Retrospective versus contemporaneous boundary: the Rav Amital, Gulf War, childhood, father, and early aliyah stories are retrospective. The ceasefire view, government work, US–Israel relationship, AI/macro framework, current books, and calls for mutual responsibility are contemporaneous April 2026 statements. Predictions about the next decades remain ex-ante and testable, not established outcomes.
Philosophy signals
- Tags: picking / risk — [investor-stated | moderate]: address compounding threats early, seek correct non-consensus positions, and tolerate reputational discomfort. The source supplies no price, sizing, evidence threshold, or kill criterion. 18Forty, Iran-response answer
- Tags: sourcing — [investor-stated | moderate]: prefer direct calls, personal research, and people close to events over generic feeds. The method needs deliberate disconfirmation because access can become an echo chamber. 18Forty, media and rapid-fire news answers
- Tags: people — [investor-stated | strong]: agency means accepting responsibility, creating productive work, helping others prosper, and acting without waiting for institutional permission. 18Forty, prosperity and Rav Amital answers
- Tags: macro — [investor-stated | provisional]: underwrite institutional capacity, welfare-state finance, conflict, AI, energy, demographics, trade corridors, and cultural identity as interacting long-cycle forces. The framework is broad enough to invite unfalsifiable storytelling unless tied to company milestones. 18Forty, four-revolutions and next-project answers
- Tags: portfolio / boards — [researcher inference | insufficient public record]: the interview offers no company decision, ownership, follow-on, reserve, governance, or exit detail.
- Tags: values — [investor-stated | moderate]: prosperity must carry mutual obligation; social strength is measured by responsibility rather than unanimous belief. 18Forty, prosperity and closing answers
Contradictions, counterevidence, and access limits
- [researcher inference | strong] Eisenberg says “I don't know” about the future US–Israel relationship and warns against prophecy, then makes confident demographic, institutional, geopolitical, and cultural forecasts. The tension is useful: his uncertainty language should be applied to the forecasts, not only to the opening question. 18Forty, US–Israel and next-project exchanges
- [researcher inference | moderate] Comfort is described as ossifying, yet the social project seeks security and prosperity. The likely boundary is productive tension without existential insecurity, but the interview does not state a measurable optimum. 18Forty, next-project and Rav Amital answers
- [researcher inference | strong] Statecraft preemption is analogized to contrarian investing. The analogy can obscure asymmetric moral, legal, liquidity, and human consequences; a good investment matrix is not evidence for military strategy, or vice versa. 18Forty, Iran-response answer
- [researcher inference | moderate] Personal access is presented as superior to media, while the interview itself contains multiple unsourced real-time claims, unnamed transactions, and exact-sounding demographic assertions. Proximity can improve information and still require independent verification. 18Forty, media, relationship, demographic, and news-source answers
- The publisher states that Sofer.ai produced the transcript and it was lightly edited. It contains likely imperfections, so quotes are short and anchored by question rather than invented timestamps.
- The interview begins at 6:13, but the page supplies no subsequent timestamps. Question/topic anchors are the most precise stable locators available.
- The source is a religious/civic interview conducted during active conflict. It is rich for biography, values, public-policy worldview, and current intellectual evolution but thin for venture mechanics.
- Claims about Iran, US policy, military capability, trade, demographics, investment flows, and government involvement were not independently adjudicated in this note. Reliability A/B records direct voice, not objective truth.
- No media was downloaded or transcribed.
Open questions
- What formal government role, authority, dates, and conflict disclosures underlie Eisenberg's “in the room” and Pact Silico statements?
- Is there contemporaneous documentation of Rav Amital's 1991 instruction or Eisenberg's immediate career decision?
- Which Aleph decisions demonstrate preemption/contrarianism ex ante, including losing or passed cases?
- What data supports the American Jewish population forecasts, Israeli belief rates, and US investment-flow claims?
- How would “prosper and make others prosperous” change a term sheet, board decision, pricing test, or exit choice?
- Which observations would falsify the four-revolutions framework over the next decade?
t 20VC: Michael Eisenberg on AI, venture portfolios, and market structure
- URL: https://www.youtube.com/watch?v=dgiwcus79I8 | Published: 2024-06-19 | Format: video | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: YouTube timestamps (1:02:17); English automatic captions (en-orig; caption model not exposed) retrieved with yt-dlp; quote wording and cue positions checked against the official video's synchronized caption track
Takeaways
- [investor-stated | strong] Eisenberg's starting AI thesis holds two claims together: AI is the most transformational technology he expects to see, and an investment gold rush around it will destroy capital. His historical analogy is the dot-com and fiber buildout, where a bubble financed lasting infrastructure while many companies failed (01:18–03:15).
- [investor-stated | moderate] He names three loss patterns: LPs who think fund count creates diversification despite overlapping company and theme exposure; VCs “logo chasing” fashionable companies; and investors who pay for a geographic copy without testing whether the local market can support the same scale (03:25–04:27).
- [investor-stated | moderate] Foundation-model economics are assessed as talent and asset durability problems. He agrees that models depreciate quickly and asks what persists if key people can leave, while allowing that a team capable of integrating models may itself be valuable. The source does not supply retention data, model-cost curves, or realized returns (04:31–06:29).
- [investor-stated | strong] He rejects “foundation models” as a venture asset class: only a very small number of companies may make investors substantial money, so underwriting must identify the exceptional company rather than rely on category exposure (07:42–09:09).
- [investor-stated | strong] Aleph's stated geographic and technical scope is Israel-only, applied AI, and full-stack workflow transformation—not foundation models. Eisenberg's rationale is a perceived Israeli advantage in military-derived application talent but insufficient academic and large-company talent density for frontier foundation models (09:17–10:42).
- [investor-stated | moderate] Windward (2013) and Lemonade (2015) are offered as evidence that Aleph invested in applied AI before the LLM wave. These are retrospective “we/I invested” statements; the interview does not allocate sourcing, approval, board work, ownership, or returns among Aleph's partners and vehicles (09:29–09:57).
- [investor-stated | moderate] His applied-AI wedge is that AI-native companies may be structurally harder for incumbents to copy than internet-era businesses were. A legacy company's fragmented or inaccessible data can prevent it from using AI effectively; he cites this as a reason to hold Lemonade longer (11:13–12:08).
- [investor-stated | strong] Eisenberg avoids crowded, obvious AI applications and prefers domains requiring specialized knowledge and market education. He says competition itself does not usually kill companies—poor execution does—but crowded markets worsen customer acquisition, retention, and channel economics (12:12–14:09).
- [investor-stated | moderate] He challenges the idea that a technically novel synthetic-biology or hard-tech company is inherently riskier than SaaS. In his framing, competitive SaaS faces price erosion and an easily replicated operating model, while a difficult company can be unique. This is a qualitative risk comparison without base rates (13:35–15:19).
- [retrospective witness | moderate] Eisenberg says that after joining Benchmark in 2005 he interviewed public-market sell-side analysts to study premium multiples. His conclusion: a company can receive a scarcity premium when it is the only public way to express a future trend, conditional on growth and gross profit (15:19–16:30).
- [investor-stated | provisional] A recent Aleph portfolio review, he says, found only one horizontal SaaS company among its last 17 investments. He immediately corrects a verbal reversal in the interview; the count is self-reported, undefined by date/vehicle, and not reconciled to a portfolio ledger (17:32–17:52).
- [investor-stated | moderate] On defense, he opposes treating war as a fashionable margin opportunity but also regards AI-enabled defense as necessary. His commercial warning is concrete: government procurement, regulation, and domain selling are a profession, so software investors chasing the theme without those capabilities may lose money (27:24–30:41).
- [investor-stated | strong] He favors public-market liquidity earlier and at the price available rather than waiting for a private headline valuation. Lemonade is his example; he says companies can raise public capital and build under public scrutiny instead of assuming the IPO market is “closed” (35:37–37:37).
- [investor-stated | strong] His exit rule is intentionally binary: ride winners when the board investor has a differentiated information advantage and conviction; otherwise take a good realized return rather than mechanically average out. He calls failure to sell all of one or two positions at zero-rate-era prices one of his mistakes (40:09–42:34).
- [investor-stated | provisional] He reports selling Aleph's entire position in an unnamed company for “11x or so” because the fund differed from management and other investors on the outlook. Because the company, cash flows, vehicle, dates, and audited return are undisclosed, the figure is self-reported and unusable as verified track-record evidence (40:09–40:31).
- [investor-stated | strong] Aleph rarely exercises pro rata, expecting to buy meaningful ownership in seed and Series A. Dream Security is his example of paying for ownership up front; he says the initial check was roughly 6.5% of the fund, but the single-source number lacks the fund denominator and independent confirmation (42:35–43:37).
- [investor-stated | moderate] He rejects the simple strategy of many initial bets followed by heavy concentration into visible winners: the best companies may be unavailable for follow-ons. He does, however, retain a narrower exception—some apparently middling companies warrant selective follow-ons when the investor sees underappreciated progress (43:38–44:44).
- [investor-stated | strong] His board-process prescription is a data-rich letter instead of a presentation, one to three explicit strategic questions, preparation calls, and a concentrated discussion. He says most well-prepared meetings can finish in 45 minutes while preserving real governance work (52:29–53:48).
- [investor-stated | strong] Eisenberg says he did not invest over Zoom during the pandemic and tries to meet founders and boards in person. He also identifies a failure mode in his own intensity: getting too deep can rattle first-time founders when the investor should remain at a 10,000-foot perspective (53:49–55:01).
- [investor-stated | strong] By 2024 he says he no longer sources proactively: referrals accumulated over 30 years provide enough opportunities for his target of two or three investments annually. He rates global networking as above average and management help as below average (1:00:05–1:01:08).
Quotes
- “One of the hardest things to do in the venture business is to hold two truths in your head.” (Eisenberg, auto-caption, 01:18–01:27; 19 words).
- “Bad execution undoes companies.” (Eisenberg, auto-caption, 13:17–13:25; 4 words).
- “The IPO window is wide open. The question is: what's the price you're willing to take?” (Eisenberg, auto-caption, 36:10–36:18; 16 words).
- “I'm actually in the opposite camp generally, which is: ride your winners.” (Eisenberg, auto-caption, 41:30–41:47; 12 words).
- “We have to buy our ownership in the first round.” (Eisenberg, auto-caption, 42:35–42:57; 10 words).
- “I don't do proactive sourcing anymore.” (Eisenberg, auto-caption, 1:00:19–1:00:39; 6 words).
Biography and decision evidence
- [retrospective witness | moderate] Eisenberg dates the start of his venture career to 1995 and calls PictureVision, an online photo-sharing business dependent on scanning film negatives, his first deal. The account does not identify his employer, vehicle, decision rights, ownership, or outcome (01:41–02:09).
- [retrospective witness | strong] He says he joined Benchmark in 2005 and used the pre-portfolio period to interview sell-side analysts about public multiples, supporting a specific origin for his “only way to play a trend” thesis (15:19–16:30).
- [investor-stated | moderate] Eisenberg says he invested in Seeking Alpha at Benchmark roughly 19 years earlier and remained on its board. The claim establishes his narrated continuity but not the investment date, board appointment record, ownership, or vehicle (04:38–04:48).
- [retrospective witness | moderate] In discussing unfamiliar science investments, he says he recruited an Israeli chemistry PhD from the United States, placed him in the adjacent office for a year, learned chemistry, and built a company with him. The automatic captions do not reproduce the company and technical details reliably enough to name it here (32:54–33:53).
- [investor-stated | moderate] During Israel's pandemic shutdown, Eisenberg says his role chairing the country's largest volunteer organization gave him a travel pass. He used it to meet a first-time founder face-to-face at his home while developing an unlaunched LLM-monetization company; the organization and company are not named reliably in the caption track (55:03–55:45).
- [retrospective witness | strong] He corrects himself while recounting Lemonade's New York licensing decision: after initially saying “we,” he says Daniel Schreiber—not Eisenberg—made the decision. That correction is useful evidence against investor-credit inflation (55:47–56:30).
- [investor-stated | moderate] At age 53, Eisenberg calls himself “old” for venture and acknowledges evidence that investing performance can decline with age. He hopes Aleph will keep him around rather than asserting a succession timetable (59:41–1:00:05).
- [investor-stated | strong] He separates his current role into referral-based access, global networking, and limited management capability. A claimed recent introduction to a Fortune 10 CEO through two hops illustrates network reach but is not independently documented (1:00:05–1:01:08).
- [investor-stated | strong] He says people close to him may judge that he allocates insufficient time to them across venture work, community work, and family. This complicates his long-running rejection of “work-life balance” by shifting the question from his own allocation to its effects on others (1:01:11–1:02:03).
Philosophy signals
- Tags: AI / cycles / picking / sourcing / ownership / follow-ons / exits / boards / people / network / geography / defense / regulation / risk.
- [investor-stated | strong] Separate a transformative technology from its investable companies; avoid category exposure, duplicated LP exposure, fashionable logos, and untailored geographic copies (01:18–04:27).
- [investor-stated | strong] Fit the AI layer to local advantage: Aleph avoids foundation models and seeks applied, full-stack workflow businesses built from Israel's application and military technology base (09:17–10:42).
- [investor-stated | strong] Prefer underexplored domains with difficult market education and specific knowledge; do not confuse a familiar spreadsheet model with lower risk (12:12–15:19).
- [investor-stated | moderate] Test whether a company can become the scarce public expression of a durable trend, while still requiring growth and gross profit; uniqueness is not a waiver for business quality (15:19–16:30).
- [investor-stated | strong] For exits, compare the board investor's information advantage and conviction with the available realized return; do not preserve optionality mechanically when the internal view is negative (40:09–42:34).
- [investor-stated | strong] Buy intended ownership early rather than assume pro-rata access to winners. Reserve selective follow-ons for cases where the investor can see progress that later investors do not (42:35–44:44).
- [investor-stated | strong] Use boards for governance and a few high-leverage strategic decisions, not product-manager commentary or slide review; do the reading and bilateral preparation before the meeting (52:29–53:48).
- [investor-stated | moderate] Prefer direct, in-person relationships and referral-driven sourcing, but monitor whether intensity, bluntness, or accumulated network privilege disadvantages first-time founders or narrows new access (51:40–55:45; 1:00:05–1:01:08).
- [researcher inference | moderate] His “net-new naïve” founder preference should be implemented as a falsifiable challenge to inherited assumptions, not a blanket rejection of expertise; the interview provides the Lemonade anecdote but no denominator of expert versus outsider founders (55:47–56:30).
Contradictions, counterevidence, and access limits
- [contemporaneous record | moderate] The source is a complete official video, but the text route is YouTube's English automatic caption track, not a creator transcript. Names and technical terms are sometimes badly rendered; unclear entities are omitted, and linked timestamps provide the direct replay route.
- [researcher inference | strong] The 20VC page outline and promotional clips are show notes, not transcript. Host claims, questions, valuations, and examples are not assigned to Eisenberg unless he expressly adopts them.
- [researcher inference | strong] Eisenberg praises “riding winners” yet reports fully selling an unnamed position and regrets not fully selling others. His stated resolution is information advantage plus conviction, but the interview supplies no repeatable valuation threshold, probability update, or decision memo (40:09–42:34).
- [researcher inference | strong] Avoiding pro rata while emphasizing ownership can work only if initial ownership is large enough and dilution tolerable. The source does not disclose Aleph's target ownership, reserves, fund size, follow-on rate, or ownership at exit (42:35–44:44).
- [researcher inference | strong] Dream Security's reported check as about 6.5% of a fund and the unnamed exit at “11x or so” are single-source, self-reported figures. They require the vehicle denominator, cash-flow dates, and independent records before synthesis as track-record facts.
- [researcher inference | strong] The foundation-model, European-regulation, China, defense-market, SaaS, IPO, and venture-return claims are forecasts or participant assertions, not verified contemporary statistics in this note. Several country and cohort rankings lack defined measures.
- [researcher inference | moderate] Eisenberg favors first-time, non-expert founders but says his own intensity can delay or rattle them. That is a material implementation tension, not evidence that either practice always produces better outcomes (54:28–56:30).
- [researcher inference | moderate] He says in-person contact matters and did not invest over Zoom during the pandemic, yet also describes a network accumulated over three decades as replacing proactive sourcing. This could improve trust while narrowing the reachable founder set; the source provides no sourcing funnel or demographic comparison.
- [researcher inference | strong] Windward, Lemonade, Seeking Alpha, Dream Security, and unnamed-company statements use “I” and “we” inconsistently. No claim here assigns sole deal credit, and later company outcomes are not back-projected into the original decision.
- [investor-stated | moderate] The age-performance concern, delivery bluntness, board impatience, over-intensity, and time-allocation costs are Eisenberg's own criticisms. The source documents awareness, not subsequent behavioral change.
Open questions
- Which fund, role, and decision record correspond to PictureVision, and what happened to the investment?
- What measurable talent-density, compute, data, or research thresholds would cause Aleph to revisit its “no Israeli foundation models” position?
- How does Aleph define applied AI and distinguish durable data/workflow advantage from a thin wrapper around a depreciating model?
- Which unnamed position was sold fully for the reported “11x or so,” and what ex-ante evidence supported the exit?
- What are Aleph's target initial ownership, reserve ratio, pro-rata exceptions, and realized dilution by fund?
- Which Aleph fund made the Dream Security investment, what was the actual check-to-commitment ratio, and who sourced and approved it?
- What portfolio ledger supports the “one horizontal SaaS among the last 17” claim, and what were the inclusion dates and categories?
- Did Eisenberg alter founder communication, board cadence, or intervention intensity after the first-time-founder delay he describes?
- What sourcing opportunities are lost when a mature investor relies almost entirely on referrals, and how does Aleph audit network bias?
- Which board letters or templates demonstrate the proposed 45-minute governance process in practice?
t 20VC with Bill Gurley and Michael Eisenberg
- URL: https://www.thetwentyminutevc.com/bill-gurley-michael-eisenberg | Published: 2021-12-06 | Format: podcast | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: official RSS audio timestamps (50:01); OpenAI transcription with gpt-4o-transcribe-diarize in three serial duration-safe chunks, offsets reconciled to episode time; automatic speaker labels checked against Harry Stebbings's explicit addressee cues
Takeaways
- [retrospective witness | moderate] Eisenberg recalls entering venture early in his career with a few exits and one small public company before the dot-com collapse. He says he knew conditions were irrational but still felt they might continue, using the memory to explain why young investors can underestimate cycle turns (04:46–06:18).
- [investor-stated | moderate] He sees two important differences between 1999 and 2021: many more “tourist” investors and a venture-financing model distributed across hundreds of global markets. Diffusion creates competing possibilities—a synchronized global reversal or differentiated local outcomes—rather than an easy replay of Silicon Valley's 2000 path (05:02–06:18).
- [investor-stated | moderate] Capital can remain abundant while returns become scarce. His mechanism is that more funding chases a limited number of companies capable of sustaining very high outcomes, although large newly addressable industries could enlarge that set (10:07–11:21).
- [investor-stated | moderate] A large late-stage war chest can become a cap-table weapon in a downturn: a capital-rich investor can finance a company when others cannot and thereby compress weaker holders. Founder secondary liquidity further changes incentives, but Eisenberg says the behavioral effect in hard times is unknowable ex ante (14:53–15:39).
- [investor-stated | strong] He separates businesses that require balance-sheet credibility—such as some financial-services, freight, banking, or payments companies—from ordinary software and consumer companies. Large rounds may support customer trust in the former; in the latter, unusable capital can weaken focus and operating discipline (17:49–18:59).
- [investor-stated | strong] Price discipline is subordinate to access to rare outliers, but entry price still changes middling outcomes. His proposed control is to invest through cycles, stretch for exceptional people when necessary, preserve ownership, and avoid becoming the highest bidder merely because the investor failed to build a valuable founder relationship (21:47–23:50).
- [investor-stated | strong] He describes ownership as a separate optimization from nominal price: Aleph may pay more while optimizing for ownership because the few exceptional outcomes drive the fund. Reputation, relationships, network help, and support before the financing are his proposed non-price sources of advantage (22:55–23:50).
- [retrospective witness | moderate] Eisenberg treats co-investor and board quality as a risk-control problem revealed in downturns. His Shopping.com/Dealtime and Epinions board experience taught him that founders need calm, experienced “steady hands,” while fearful investors can transmit partnership pressure into company governance (30:19–31:48).
- [investor-stated | strong] Equal partnerships are presented as both incentive design and decision process: shared economics reduce internal bargaining and can create a safer place to surface bad news. He says Aleph adopted Benchmark's equal-partnership model, while acknowledging unavoidable information asymmetry between the board partner and the rest of the partnership (32:08–33:15).
- [investor-stated | moderate] He views technical talent—not office space—as the scarce 2021 input. A bust might reallocate people toward better uses without reducing their cost; at the same time, boom-era compensation could pull more people from banking and consulting into engineering and product roles (38:48–40:41).
- [investor-stated | provisional] His LP view is explicitly a forecast: venture remains lopsided; despite a larger population of profitable funds, he expects much of the index not to beat public markets and the top quartile to remain far better. The interview supplies no fund-return dataset or Aleph performance disclosure to validate that projection (41:45–42:35).
- [investor-stated | strong] On WeWork, Eisenberg preserves both sides of the lesson: the large commercial-real-estate market mattered, but headline valuation and company momentum should not displace board oversight. This is a short retrospective lesson, not a full decision-time postmortem (44:42–45:13).
- [retrospective witness | moderate] Asked whether success or failure taught him more, he instead credits people: Benchmark partners Bill Gurley, Bruce Dunlevie, and Peter Fenton; current colleagues; and entrepreneurs. That response resists a lone-genius reading of his process (46:06–46:37).
Quotes
- “More companies die of indigestion than die of starvation.” (Eisenberg, OpenAI transcript, 17:49–17:56; 9 words).
- “Innovation is constant. And so that's why you got to invest across the cycles.” (Eisenberg, OpenAI transcript, 21:50–21:55; 14 words).
- “Even if we have to pay more, we're optimizing for ownership.” (Eisenberg, OpenAI transcript, 22:49–23:01; 11 words).
- “I prefer to optimize long-term on reputation rather than optimizing on dollars now.” (Eisenberg, OpenAI transcript, 23:33–23:50; 13 words).
- “Don't fall in love with your own momentum, and board oversight remains critical.” (Eisenberg, OpenAI transcript, 44:51–45:13; 13 words).
- “Who you invest with actually really matters.” (Eisenberg, OpenAI transcript, 47:05–47:23; 7 words).
Biography and decision evidence
- [contemporaneous record | moderate] Stebbings introduces Eisenberg as Gurley's former Benchmark partner, says Eisenberg spent 15 years in the Benchmark partnership, and says he then co-founded Aleph. This is host biography, not employment documentation (00:34–00:50).
- [retrospective witness | moderate] Eisenberg's first-dot-com-cycle memory includes early exits and a small public company but does not name the companies, vehicles, entry dates, ownership, or realized economics (04:46–06:18).
- [retrospective witness | moderate] He says the advice that companies die from “indigestion” came from Benchmark, preserving institutional provenance rather than claiming authorship (17:49–17:56).
- [retrospective witness | strong] Eisenberg attributes the ownership lesson to Benchmark and says it guides Aleph. The statement supports transmission of a principle, not proof that every Aleph deal maximized ownership or that he alone set the rule (22:55–23:01).
- [retrospective witness | strong] He connects his Shopping.com/Dealtime–Epinions board experience with Gurley to the later judgment that co-investor and board composition matter in downturns (30:19–31:48). The transcript's automatic rendering of the historical company names is imperfect; the note preserves the claimed lesson without reconstructing merger terms.
- [investor-stated | strong] He says the equal-partnership structure used at Benchmark was adopted at Aleph and treats it as “religion” there. The claim describes internal culture and economics at a high level; it does not disclose the partnership agreement, voting thresholds, carry allocation, or exceptions (32:08–32:49).
- [investor-stated | moderate] Eisenberg refers to cases where “we” raised large rounds for balance-sheet-dependent opportunities. He names financial-services categories and a possible company example, but the transcription is not sufficiently clear to assign the decision, company, or round to a specific Aleph partner or vehicle (17:56–18:59).
- [investor-stated | moderate] In the WeWork quick-fire response he identifies a real market opportunity alongside governance and momentum failures. He does not state in this segment who sourced Benchmark's investment, his personal voting or board role, ownership, follow-on decisions, or losses (44:42–45:13).
- [retrospective witness | strong] Eisenberg explicitly credits learning to Benchmark colleagues, present partners, and entrepreneurs. The automatic transcript renders some current-partner names uncertain, so only the clearly identified Benchmark participants are retained by name (46:06–46:37).
Philosophy signals
- Tags: cycles / picking / price / ownership / sourcing / relationships / reputation / capital intensity / boards / partnership / risk / talent / LP returns.
- [investor-stated | strong] Invest across cycles because innovation persists and the cost of missing a rare outlier can dominate the benefit of avoiding expensive but mediocre deals (21:47–22:55).
- [investor-stated | strong] Distinguish productive capital intensity from “indigestion”: require a concrete mechanism—such as customer demand for balance-sheet durability—before treating a large financing as an operating advantage (17:49–18:59).
- [investor-stated | strong] Optimize ownership separately from price, but do not treat money as the sole product. If winning requires the highest bid, diagnose whether the investor failed to build trust, contribute before funding, or make the network useful (22:55–23:50).
- [investor-stated | strong] Underwrite the board and co-investor syndicate for downside behavior: prior downturn experience, ability to carry bad news into partnership meetings, calm governance, and aligned economics are part of company risk (30:19–33:15).
- [investor-stated | moderate] Treat founder secondary sales and large late-stage war chests as changes in incentive and bargaining structure, not just financing volume (14:53–15:39).
- [researcher inference | moderate] His scarcity analysis yields a two-resource IC check: identify whether capital or talent is the binding constraint, then ask whether more funding relaxes the constraint or merely bids up the scarcer input (10:07–11:21; 38:48–40:41).
- [investor-stated | strong] A large market can support an exceptional company, but headline valuation and self-reinforcing momentum are not governance evidence (44:42–45:13).
Contradictions, counterevidence, and access limits
- [contemporaneous record | moderate] This note uses a complete official RSS MP3. No official verbatim transcript was found. OpenAI's gpt-4o-transcribe-diarize rejected the 3,000-second upload because the model's maximum was 1,400 seconds; the same temporary audio was divided into three sequential approximately 1,000-second chunks, transcribed successfully, and timestamp offsets were reconciled.
- [contemporaneous record | moderate] The diarization labels occasionally fail at speaker handoffs. Speaker attribution therefore follows Stebbings's explicit “Bill” and “Michael” prompts plus conversational continuity; unclear names and ambiguous cross-talk are excluded. Minor punctuation is supplied for readability.
- [researcher inference | strong] The 20VC page outline and episode description are show notes, not transcript. Host-read sponsor statistics and Stebbings's biography/portfolio framing are not attributed to Eisenberg.
- [researcher inference | strong] Claims about market declines, Tel Aviv rent, historical acquisition prices, fund-index returns, top-quartile persistence, and portfolio examples remain participant statements unless independently sourced elsewhere. This note does not elevate them to verified market data.
- [researcher inference | strong] “Invest across cycles” and “optimize for ownership” can conflict with the warning that excess capital creates indigestion and compresses mediocre outcomes. Eisenberg resolves the tension only conditionally: stretch for rare people and outliers, retain ownership, and require a use case for capital. The source offers no numerical kill criteria.
- [researcher inference | moderate] Equal economics may encourage candid collaboration, but the interview supplies no counterexample, partnership minutes, compensation documents, or evidence separating structure from partner selection and culture.
- [researcher inference | strong] The episode pairs Eisenberg with Gurley. Gurley's views—including asymmetric-risk examples, Google and Square misses, direct listings, and the “what could go right?” maxim—are not assigned to Eisenberg even when he agrees.
- [researcher inference | strong] The WeWork segment is retrospective and compressed. “Board oversight remains critical” is a claimed lesson, not evidence that a particular board intervention was available, attempted, or would have changed the outcome.
Open questions
- Which early exits and small public company was Eisenberg referring to, and which firm or vehicle made each investment?
- What ownership range does Aleph target by stage, and when will it trade ownership for price, syndicate quality, or reserve capacity?
- Which balance-sheet-dependent Aleph companies raised large rounds, and what customer evidence justified the capital before each financing?
- How are equal-partnership economics, voting, board accountability, and conflict resolution specified at Aleph?
- Which co-investors or board configurations produced strong versus poor behavior in actual downturns?
- What was Eisenberg's exact role in Benchmark's WeWork sourcing, approval, governance, follow-ons, and later postmortem?
- Did the 2022–2023 reset validate his 2021 predictions about talent reallocation, return scarcity, and venture-index underperformance?
- What denominator and vintage data would distinguish enduring top-quartile persistence from selection, access, and survivorship effects?
t Agency Under Fire
- URL: https://www.aleph.vc/content/agency-under-fire | Published: 2026-03-09 | Format: Aleph Invested solo podcast episode with first-party full transcript | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: publisher key-topic timestamps from 00:00 to 10:38 plus corresponding transcript paragraphs
Takeaways
- [investor-stated | strong] Eisenberg defines “agency at scale” through civilians acting without central instruction during wartime: an app for singles in shelters, weddings continuing underground, and pre-army young adults constructing protected delivery rooms. The examples demonstrate the concept he wants readers to see, but they are selected anecdotes rather than a population measure. Agency Under Fire, 00:35–03:28
- [retrospective witness | moderate] A newly born granddaughter in an underground hospital area makes the resilience thesis personal. Eisenberg connects family continuity, mutual aid, and improvisation to a national culture that keeps building during attack. The experience is contemporaneous to the recording; the inference from one event to national comparative advantage is broader than the evidence. Agency Under Fire, 02:14–03:28
- [investor-stated | provisional] He extends civic agency to company execution, describing an unnamed Aleph company growing rapidly and serving customers while employees manage shelters, closed schools, and family duties. Because the company, metrics, baseline, and observation period are withheld, the example cannot verify “unabated” growth or portfolio-wide resilience. Agency Under Fire, 03:28–04:31
- [investor-stated | provisional] The macro thesis is that technology, sovereignty, geopolitics, and national resilience will be entangled for at least a decade. Eisenberg predicts countries with cohesive identity and scalable citizen agency will outperform passive states. This is wartime advocacy and forecast, not demonstrated venture performance. Agency Under Fire, 04:31–06:14
- [investor-stated | provisional] He calls the United States, China, and Israel the three most advantaged technological states in the next global phase. The episode supplies no comparative index, denominator, weighting, or counterexample; the ranking is an assertion and should not be used as a country-allocation score. Agency Under Fire, 06:14
- [investor-stated | moderate] Modern conflict is presented as an extreme validation environment for intelligence sharing, AI coordination, defense systems, and the consequences of engineering error. The investable implication is that technologies tested under life-and-death constraints may expose reliability faster than lab projects. The failure mode is obvious selection bias: deployment proves use, not safety, transferability, margins, procurement durability, or investability. Agency Under Fire, 06:43–08:08
- [investor-stated | provisional] Eisenberg contrasts Israeli military engineers' price of error with academic project grading and says the difference can be either a feature or a bug. The caveat matters: mission discipline may improve reliability while also encouraging secrecy, narrow requirements, risk aversion, or poor civilian-product fit. He does not specify how Aleph evaluates that translation. Agency Under Fire, 07:10
- [investor-stated | moderate] He dates the move from SaaS toward “atoms” to roughly five-to-seven years earlier and says early investors are benefiting. Countries seeking Israeli defense technology and startups already deployed in the conflict are offered as demand evidence. No companies, entry dates, valuations, ownership, revenues, or returns are given. Agency Under Fire, 08:08–09:12
- [investor-stated | insufficient public record] Eisenberg says the Tel Aviv Stock Exchange rose almost 10% after the war began, attributes it partly to reduced Iran risk, and predicts a postwar surge in venture investment. The transcript does not define the index, start/end time, currency, benchmark, or source, and the future flow forecast is not yet an outcome. Agency Under Fire, 09:12–09:51
- [investor-stated | strong] The episode ends with an explicit call to continue investing and building. As evidence, this is clear ex-ante advocacy during conflict; it does not reveal whether Aleph changed pace, price, sector mix, reserves, or exposure. Agency Under Fire, 09:51–10:38
Quotes
- “The machine, the high-tech machine, the innovation machine, the agency machine, is working here.” — Michael Eisenberg, 03:28–04:31
- “The price of being wrong or incorrect or failing in the Israeli military is life and death.” — Michael Eisenberg, 07:10
- “Sometimes that's a feature, sometimes that's a bug.” — Michael Eisenberg, 07:10
- “Keep investing.” — Michael Eisenberg, 09:51–10:38
- “The AI era demands it.” — Michael Eisenberg, 09:51–10:38
Biography and decision evidence
- [contemporaneous record | strong] Eisenberg records alone because a guest's UK flight was canceled and says the studio had just left a shelter after a Tel Aviv siren. This is first-person recording context, not independent war reporting. Agency Under Fire, 00:00
- [investor-stated | strong] He says Aleph held its first partner meeting in roughly a week and heard from one unnamed company. This supplies a dated operational glimpse but no agenda, decision, attendance, metrics, or partner attribution. Agency Under Fire, 03:28–04:31
- [investor-stated | provisional] Eisenberg says some defense-tech and AI startups were deployed while also serving customers. He does not name Aleph as investor in those companies or allocate sourcing, board, or economic credit. Agency Under Fire, 08:27–09:12
- [investor-stated | provisional] He frames five-to-seven-year-old atoms investments as now benefiting. Without names or records, this cannot become a deal claim, return claim, or proof of his personal foresight. Agency Under Fire, 08:08–08:27
- Retrospective versus contemporaneous boundary: the app, hospital, family, shelter, partner-meeting, and market observations are presented as current during the episode. The post-October-7 market comparison and five-to-seven-year investment history are retrospective. The postwar investment surge and decade-long techno-geopolitical regime are forecasts.
- The episode repeatedly cites “our annual letter” on agency and geopolitics. The complete letter is not publicly available in the mapped corpus, so the podcast cannot validate what the original letter said, when LPs received it, or whether its forecast preceded the observed events.
Philosophy signals
- Tags: people — [investor-stated | moderate]: prefer people who act under uncertainty, improvise, serve others, and continue building under pressure. Anecdotes do not distinguish durable agency from crisis adrenaline. Agency Under Fire, 00:35–04:31
- Tags: picking — [investor-stated | provisional]: seek technologies linked to defense, physical systems, AI coordination, sovereignty, and national resilience; require evidence that a military advantage transfers to a scalable civilian or allied-market product. The second clause is the note's boundary, not an Eisenberg-stated screen. Agency Under Fire, 04:31–09:12
- Tags: risk — [investor-stated | moderate]: observe technology where the price of failure is severe, while acknowledging that such pressure can be a bug. No safety, ethics, procurement, export-control, or dual-use diligence checklist is supplied. Agency Under Fire, 06:43–08:08
- Tags: macro — [investor-stated | provisional]: underwrite conflict, industrial capacity, sovereign technology, alliance structure, capital flows, and country resilience as linked variables over a decade. Agency Under Fire, 04:31–10:38
- Tags: portfolio / exits — [researcher inference | insufficient public record]: the call to keep investing has no pace, ownership, reserve, follow-on, exit, or liquidity rule.
Contradictions, counterevidence, and access limits
- [researcher inference | strong] The episode moves quickly from vivid civilian anecdotes to national, market, and investment conclusions. The stories support a concept of agency; they do not establish comparative national productivity, venture returns, or causal stock-market effects. Agency Under Fire, 00:35–10:38
- [researcher inference | moderate] Life-and-death testing can reveal reliability, but it can also suppress disclosure and create requirements unlike civilian markets. Eisenberg calls the difference a possible bug yet supplies only upside examples. Agency Under Fire, 06:43–08:27
- [researcher inference | strong] The nearly 10% TASE move is attributed to a clearing Iran overhang without an event study or competing explanations. Treating price movement as confirmation of a geopolitical thesis would be post hoc. Agency Under Fire, 09:12–09:51
- The transcript's statements about military targets, state conduct, diplomatic outreach, exchange performance, and investment flows were not independently verified for this note. They are preserved as Eisenberg's claims.
- The publisher page paradoxically displays “No transcript found” immediately before the full transcript. The full body is nonetheless visible and was processed; the key-topic timestamps provide stable topic locators.
- The source is first-party Aleph media, recorded during war, with explicit advocacy and promotion. Reliability A means direct dated voice, not neutral war reporting or validated investment results.
- No media was downloaded or transcribed.
Open questions
- What annual-letter text and delivery date preceded the conflict, and what falsifiable predictions did it contain?
- Which atoms or defense investments were made five-to-seven years earlier, by which vehicle and partner, at what price and ownership?
- What TASE index, currency, start date, and comparator support the “almost 10%” and best-performing claims?
- How does Aleph diligence export control, procurement concentration, civilian transfer, classification, safety, and ethics in dual-use companies?
- Did Aleph actually change deployment pace after October 7 or the Iran war, and what denominator supports a claimed boom?
t Michael Eisenberg on the Start-Up Nation, Storytelling, and the Power of Technology
- URL: https://www.econtalk.org/michael-eisenberg-on-the-start-up-nation-storytelling-and-the-power-of-technology/ | Published: 2022-02-14; recorded 2022-01-25 | Format: EconTalk podcast with official full transcript | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: publisher-supplied timestamps in the transcript
Takeaways
- [investor-stated | strong] Eisenberg divides his career into an initially opportunistic phase and a learned philosophy. In 1995 he followed open internet “whitespace” without a settled framework; by 2022 he describes trusted relationships with founders, investors, corporations, and technologists as the mechanism for deal flow, recruiting, and company development. This is a retrospective account of evolution, not a contemporaneous 1995 memo. EconTalk, 1:06
- [investor-stated | moderate] His “long humanity” thesis is narrower than generic optimism: he wants economic empowerment and incentive realignment embedded in the business model, not appended as ESG or philanthropy. The source demonstrates a stated filter, but it supplies no searched denominator of investments accepted or rejected under it. EconTalk, 1:06 and 33:39
- [retrospective witness | moderate] Eisenberg recalls PictureVision as the first investment he “enabled or did,” immediately qualifying that the attribution was more complicated. He derives three lessons from the 1995 encounter: a secular technology curve can overcome present constraints; products with positive emotional resonance can accelerate adoption; and early-market storytelling helps mobilize attention. The qualification prevents treating this interview as sole-sourcing proof. EconTalk, 4:07
- [investor-stated | strong] Storytelling is necessary but dangerous. Eisenberg says committing capital requires testing a story's physical, regulatory, and coordination constraints. His backcasting method starts with the desired future, enumerates what must go right, separates controllable from uncontrollable steps, and searches for immovable blockers or timelines longer than the financing path can bear. EconTalk, 8:00–14:51
- [investor-stated | moderate] The decision rule is asymmetric rather than base-case forecasting: ask what can go right, then test whether the chain of low-probability conditions has a feasible path. His refusal to invest in autonomous vehicles at that time is a live boundary—large vision alone does not overcome a dependency chain he expects to take too long. The transcript does not disclose what evidence would reverse that view. EconTalk, 8:00–14:51
- [investor-stated | moderate] He treats collaboration as a structural advantage: multidisciplinary technology demands complementary skills, execution converts an idea into a company, and the small Israeli network can enable fast references and company support. The broad claim that multi-founder companies outperform solo-founded ones is asserted without a dataset or definition in the transcript. EconTalk, 23:53–33:39
- [investor-stated | strong] Eisenberg distinguishes Aleph and Benchmark-style “cottage” venture firms from capital-heavy superfunds. He characterizes the former as small, local, focused, equal partnerships. For Israeli venture, he identifies four underwriting constraints: insufficiently large outcome imagination, a shallower scale-management bench, export-market execution from day one, and dense networks that improve references while reducing secrecy and proprietary access. EconTalk, 27:44
- [investor-stated | provisional] The “long humanity” mechanism rests on a stage-of-technology claim: after a disruptive platform arrives, products that restore agency, health, economic output, and human fit become the next opportunity set. It is a thesis about where demand and talent will move, not demonstrated predictive efficacy. EconTalk, 33:39–37:13
- [investor-stated | moderate] Lemonade is offered as a portfolio illustration of incentive redesign: direct distribution may improve data capture; a flat fee is meant to reduce the carrier's incentive to reject claims; and charitable giveback is intended to reduce fraudulent claiming. This is an investor's promotional explanation of a company he helped form, not independent proof that the incentives or unit economics work as described. EconTalk, 37:13–46:49
- [contemporaneous record | strong] Host Russ Roberts directly challenges the insurance generalization and asks whether competition, regulation, and rent seeking complicate the alignment story. Eisenberg concedes that free-market logic is impaired in heavily licensed markets, then argues that internet/mobile direct distribution can partially restore competition. The exchange preserves dissent rather than presenting the portfolio narrative as settled fact. EconTalk, 46:49–54:29
- [investor-stated | provisional] Eisenberg advocates measuring household resilience and long-term empowerment rather than relying only on GDP or quarterly financial incentives. He says he was working on new metrics but supplies neither their definitions nor validation in the interview. The operational implication is to specify the behavioral metric before claiming values alignment. EconTalk, 54:29
- [investor-stated | moderate] On platform power, his preferred intervention is user agency and portability: let a customer move a social graph or data to a competing product. He also acknowledges that Web3's ownership promise may fail when a centralized platform can still deplatform assets. The contradiction is productive: architectural rhetoric must be tested against actual control points. EconTalk, 54:29–1:04:16
- [investor-stated | strong] The closing book discussion links biblical narratives to recurring economic problems—wealth, family enterprise, transition, incentives, and institutions. Eisenberg presents ancient texts as a durable case library requiring translation rather than literal copying, and says his later work was moving toward a third model of capitalism after prolonged easy money. EconTalk, 1:04:16
Quotes
- “The core of my investment philosophy starts with people.” — Michael Eisenberg, 1:06
- “You need to test the limits of the story.” — Michael Eisenberg, 8:00
- “Part of what I try to do in this is, is what I call backcasting, which is the inverse of forecasting.” — Michael Eisenberg, 8:00
- “Execution is so under-appreciated in the world because we think a world of geniuses.” — Michael Eisenberg, 23:53
- “Business is the best purveyor of positive change in the world.” — Michael Eisenberg, 37:13
Biography and decision evidence
- [retrospective witness | moderate] Eisenberg says he made aliyah from New York in 1993 and encountered PictureVision two years later through a weak-tie introduction. He remembers being a new father with family abroad, which made remote photo sharing emotionally legible to him. The source is recorded roughly twenty-seven years after the event and does not establish vehicle, allocation, ownership, or sole credit. EconTalk, 4:07
- [investor-stated | moderate] He credits Bruce Dunlevie at Benchmark with the “what can go right?” question and identifies his Aleph/Benchmark organizational preference as equal, small, focused, and local. These are explicit influence and vehicle-attribution statements, not proof that every partner or decision followed one method. EconTalk, 8:00 and 27:44
- [investor-stated | strong] Eisenberg says his Tel Aviv office remained primary while he had just taken a Jerusalem office for roughly one to one-and-a-half days weekly to hold uninterrupted meetings. This is dated operational context, not a durable current-role claim. EconTalk, 27:44
- [investor-stated | moderate] The Lemonade discussion distinguishes Eisenberg's claimed role—introducing the founders and being present around company formation—from sole founder, team, or fund credit. No return or personal-economics claim is available. EconTalk, 37:13–46:49
- Retrospective boundary: career origins, PictureVision lessons, and long-run Israeli ecosystem claims are memories interpreted in 2022. The contemporaneous evidence is the dated interview itself: it reliably shows what Eisenberg said in January 2022, not what he documented in 1995.
Philosophy signals
- Tags: sourcing / people — [investor-stated | strong]: build trust across founders, investors, technologists, and corporations; use the network for deal discovery, reference checks, recruiting, customers, and financing. EconTalk, 1:06 and 27:44
- Tags: picking / risk — [investor-stated | strong]: backcast from the future state, identify necessary dominoes, test physical and regulatory constraints, and reject visions whose blocker or duration outruns the investable path. EconTalk, 8:00–14:51
- Tags: people / boards — [investor-stated | moderate]: prefer complementary teams and relentless executors; use the investor network to build management, but do not infer board intervention or outcome causality absent company-level evidence. EconTalk, 23:53
- Tags: portfolio / exits — [investor-stated | moderate]: the cottage-firm model still requires grand-slam outcomes; Israel's small-market mental model can undershoot the scale a venture fund needs. No ownership, reserve, follow-on, or exit discipline is specified. EconTalk, 27:44
- Tags: macro — [investor-stated | moderate]: military networks, immigration, export orientation, management depth, regulation, and technology cycles are treated as upstream inputs to venture outcomes. Several national claims are broad and unquantified. EconTalk, 14:51–33:39
- Tags: picking / values — [investor-stated | provisional]: seek business models whose customer economics and social effect reinforce one another; require a measurable mechanism rather than a corporate-responsibility add-on. EconTalk, 33:39–54:29
Contradictions, counterevidence, and access limits
- [researcher inference | strong] Storytelling is simultaneously an adoption edge and a diligence hazard. Eisenberg's own solution is capital-at-risk backcasting, but the transcript does not show a false-positive ledger or a case where his story test failed. EconTalk, 4:07–14:51
- [researcher inference | moderate] “Long humanity” coexists with acceptance of platform concentration and rapid technological disruption. Portability is a proposed boundary, yet Eisenberg concedes that nominal decentralization can retain centralized chokepoints. EconTalk, 33:39–1:04:16
- [contemporaneous record | strong] Roberts contests the claim that insurers make money by rejecting claims and asks whether Lemonade's framing neglects competition and regulation. The transcript offers no independent loss-ratio, customer, fraud, or profitability evidence, so the example remains a rationale rather than an outcome test. EconTalk, 46:49–54:29
- [researcher inference | moderate] Eisenberg praises rule-challenging military culture but criticizes weak civilian enforcement that enables people to evade rules. The distinction appears to be productive dissent versus opportunistic noncompliance; he does not supply an operational test for separating them in founders. EconTalk, 14:51
- The publisher supplies a full timestamped transcript, but it contains editorial uncertainty markers and transcription artifacts. Quotes above avoid uncertain passages. No audio was downloaded or independently retranscribed.
- Reliability is A for what the dated transcript records Eisenberg saying. It is not A for the truth, causal force, or economic success of the claims he makes, and the book-tour context increases retrospective narrative risk.
Open questions
- What full set of Aleph investments and passes was evaluated under “long humanity,” and what were the false positives?
- What milestones, probabilities, and time limits make a backcast investable rather than merely imaginable?
- Which PictureVision entity and vehicle held the original investment, who decided it, and what was Eisenberg's exact role?
- How were Aleph's proposed empowerment or resilience metrics defined, audited, and linked to underwriting?
- What ownership and reserve rules preserve cottage-firm economics when Israeli companies require global scale capital?
t The Human Founder episode 149 with Michael Eisenberg
- URL: https://thehumanfounder.podbean.com/e/episode-149-with-michael-eisenberg-general-partner-at-%D7%B4aleph%D7%B4/ | Published: 2024-09-30 | Format: podcast | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: official RSS audio timestamps (54:06); OpenAI whisper-1 verbose_json transcription with segment timestamps; speaker attribution follows interview turns and explicit questions, with ambiguous cross-talk excluded
Takeaways
- [investor-stated | strong] Eisenberg calls investors “stagehands” and founders the heroes. This is both an attribution boundary and a service philosophy: he credits entrepreneurs for company building while describing the investor as behind-the-scenes support (03:56–05:29).
- [retrospective witness | moderate] Daniel Schreiber illustrates relationship compounding: Eisenberg says he invested in Schreiber's first startup in the mid-to-late 1990s, stayed in touch after a moderate outcome, and was later invited into Lemonade. The source does not identify the first vehicle, original ownership, or alternative reasons Schreiber returned (04:23–05:13).
- [investor-stated | strong] Eisenberg prioritizes long-term relationships over transaction cycles: companies may take a decade, but the founder relationship can persist beyond a single outcome. He says curiosity and enjoyment of people motivate the work (04:23–06:20).
- [retrospective witness | provisional] He attributes some ability to read people to his mother and grandmother and an inclination to like people to his father and paternal grandfather. This is family memory, not evidence that inherited judgment predicts venture outcomes (08:11–08:50).
- [retrospective witness | strong] Print Life is a detailed failure account. Eisenberg says a 1999 investment pioneered photo books, then the board and management vertically integrated into capital-intensive printing facilities during the bubble. When capital tightened, the company failed to pivot quickly enough and lost a chance to become an industry standard (09:34–12:33).
- [retrospective witness | strong] He assigns Print Life responsibility to both board and management rather than treating the market turn as the sole cause. The decision rule he extracts is to know the funding source and durability before choosing a capital-intensive model (11:29–12:33).
- [retrospective witness | strong] The human cost matters in his postmortem: layoffs hit print-shop workers, and he still thinks about an executive recruited from a well-paid role. His proposed response combines severance, empathy, and a test of whether he behaves differently in a similar future decision (12:14–14:07).
- [investor-stated | moderate] Reputation is framed as repeatable, anticipatable conduct rather than marketing: do the right thing far more often than not, take action rather than rely on good intent, and recognize that complex failures cannot be mechanically mapped onto the next case (13:47–15:00).
- [investor-stated | moderate] He borrows Howard Marks's consensus/non-consensus axes to explain investor loneliness: a correct consensus view may already be priced, so exceptional returns require being right and non-consensus while tolerating being wrong before being right. This is stated philosophy, not a measured Aleph attribution study (16:40–18:01).
- [retrospective witness | strong] Eisenberg describes recommending that an unnamed founder shut down a company after the October 2023 war began. His reasoning centered on returning the founder's time and focus, not recovering the fund's money; he presents empathy and a hard business decision as compatible (18:29–20:33).
- [investor-stated | strong] He distinguishes personal empathy from business continuation. A long relationship does not justify keeping a weak company alive; the investor should be candid when the idea, timing, mental state, or market no longer supports the venture (18:29–20:33).
- [retrospective witness | strong] His entry into investing was improvised rather than planned: political consulting, a layoff he learned about slowly before the internet, inability to find work, and a self-created technology merchant-bank model. With no capital, he called wealthy people, raised money, and invested his fee in an early digital-photography company (20:36–21:50).
- [retrospective witness | strong] Eisenberg says the first such company succeeded, enabling the next step. He then persuaded Montgomery Securities to make him its Israel representative and partnered with Shlomo Kalish, explicitly dividing their inputs: Kalish supplied Israeli relationships and experience; Eisenberg supplied the business model (21:35–22:38).
- [investor-stated | moderate] Parenting and venture support share a self-efficacy principle for him: point out capabilities and obstacles, but do not solve every problem for the founder. Directness is his chosen mode, although the interview does not establish how founders experience it (27:00–29:10).
- [retrospective witness | strong] Aleph's formation began within an unusually supportive Benchmark transition. Eisenberg says a 2009 handshake let him manage out the Israel portfolio while continuing to invest from Benchmark's main fund; at the end of 2012 he judged the portfolio ready and left with partner and LP support (40:00–41:10).
- [retrospective witness | strong] He specifically credits Benchmark partners Bruce Dunlevie, Bill Gurley, Peter Fenton, Bob Kagle, Kevin Harvey, and Mitch Lasky. Dunlevie helped with the deck and conceptualization and pushed him toward Eden Shochat as co-founder, preserving institutional and partner contribution (40:09–41:24).
- [retrospective witness | moderate] Eisenberg says he and Shochat traveled for nine consecutive weeks to raise Aleph's first fund, returning to Israel each Shabbat so Eisenberg could be with his family, and closed on July 3 before a family baseball trip. These are vivid retrospective details without contemporaneous travel or closing documents (42:23–42:50).
- [retrospective witness | moderate] The 2009 “Hummus Manifesto” and an open-source conference are his possible first connections with Shochat. At the end of 2012, Kathryn Mayne of Horsley Bridge reportedly identified an Israeli early-stage fund gap and encouraged Eisenberg to act; Eisenberg and Mayne independently wrote down Shochat's name as a partner candidate (44:01–45:33).
- [investor-stated | moderate] “Different is better than better” describes the Eisenberg–Shochat pairing: religious New York upbringing and immigration to Israel versus Shochat's Israeli kibbutz and secular background. Eisenberg says affection and trust emerged by working through shared experience, not by finding an initially similar partner (41:15–43:41).
- [investor-stated | moderate] The Aleph name encoded the founders' aspirations: explicitly Israeli identity, first-place global entrepreneur service and LP performance, “alpha” above-market returns, and a generational firm. These are formation ambitions, not proof of later rankings or returns (45:40–47:18).
Quotes
- “Investors are stagehands. We're behind the scenes. The heroes of the journey are the entrepreneurs.” (Eisenberg, OpenAI transcript, 04:00–04:15; 15 words).
- “Companies take 10 years, but relationships are a lifetime.” (Eisenberg, OpenAI transcript, 05:09–05:13; 9 words).
- “You better damn well know where you're getting capital from if you're running a capital-intensive model.” (Eisenberg, OpenAI transcript, 11:51–12:01; 16 words).
- “The only way to make money as an investor is to be right and be non-consensus.” (Eisenberg, OpenAI transcript, 17:31–17:44; 16 words).
- “We never signed a document, as best I can tell.” (Eisenberg, OpenAI transcript, 40:20–40:30; 10 words).
- “You work together and you develop affection.” (Eisenberg, OpenAI transcript, 43:11–43:15; 7 words).
Biography and decision evidence
- [contemporaneous record | provisional] Gali Bloch-Liran's introduction describes Eisenberg as an Aleph general partner, spouse of Yaffa, father of eight, grandfather, author, and leader or board member of several nonprofits. It also gives Aleph AUM and portfolio counts. These are host-read show notes, not Eisenberg's testimony or independently verified records (01:22–02:10).
- [retrospective witness | moderate] Eisenberg says he was about 28 when he invested in Print Life around 1999. The date and age are approximate in his telling, but they align with an early-career first-bubble learning episode (09:34–10:10).
- [retrospective witness | strong] Print Life identifies a concrete team: four Rehovot founders from Indigo and recruited CEO Meg Weston, formerly of Konica America. Eisenberg uses “we” for the board/management decision to vertically integrate, leaving individual votes and the investment vehicle unknown (10:10–12:33).
- [retrospective witness | strong] His pre-venture sequence is political consulting → layoff/unemployment → self-created technology merchant banking → digital-photography financing → Montgomery Securities Israel representative → partnership with Shlomo Kalish (20:36–22:38). Exact employers, dates, fees, and securities structure remain unverified here.
- [retrospective witness | moderate] He says he had lived in Israel for only four years when Montgomery selected him, and admits he then knew little about investment banking, technology, or Israel. His decision to recruit Kalish is presented as an early complementarity move (21:58–22:38).
- [retrospective witness | strong] The Benchmark separation is narrated as a four-year transition after the firm stopped investing internationally, anchored by a 2009 handshake and an end-2012 departure decision. Eisenberg says he continued investing from Benchmark's main fund while managing the Israel portfolio, a useful vehicle boundary that still requires fund documents (40:00–41:10).
- [retrospective witness | strong] The Aleph founding account credits Shochat as co-founder, Dunlevie as a deck/model adviser, Mayne as a market-gap catalyst and partner-match influence, and Benchmark LPs as references or investors. It does not support sole-founder credit for Eisenberg (40:00–45:33).
- [retrospective witness | moderate] The nine-week first-fund raise is tied to recurring Shabbat returns and a July 3 close. The interview does not state the year in that passage; the surrounding end-2012 and Aleph chronology suggests 2013, but that inference is not promoted to a direct claim (42:23–42:50).
- [investor-stated | moderate] Eisenberg says his religious New York background and immigration differed from Shochat's Israeli, kibbutz, secular, and partly Nigerian childhood. This is Eisenberg's description of Shochat, not Shochat's own testimony (41:15–42:20).
- [retrospective witness | moderate] He says the “Hummus Manifesto” may have led to meeting Shochat through open-source work and the Reversim conference, but repeatedly signals uncertain memory about the exact introduction. The uncertainty is part of the record (44:01–44:37).
Philosophy signals
- Tags: people / relationships / sourcing / founders / boards / capital intensity / cycles / risk / reputation / non-consensus / partnership / vehicle transition.
- [investor-stated | strong] Attribute company creation to founders; evaluate the investor by durable relationships, predictable conduct, and useful behind-the-scenes support rather than public credit (03:56–05:29; 13:47–15:00).
- [retrospective witness | strong] For capital-intensive strategies, map financing sources across a downturn before adding fixed operating assets. Print Life is a documented application and failure rather than a generic maxim (09:34–12:33).
- [investor-stated | moderate] Review mistakes by asking whether the same decision context would produce different conduct, while resisting a one-variable lesson from a multivariable outcome (12:48–15:00).
- [investor-stated | strong] Combine conviction with explicit stop decisions: being non-consensus requires an iron stomach, but loyalty to a founder does not justify wasting that founder's time on a company the investor believes will fail (16:40–20:33).
- [retrospective witness | strong] Fill known capability gaps with a complementary partner: Kalish supplied local network and experience early; Shochat later supplied a deliberately different perspective at Aleph (21:58–22:38; 41:15–43:41).
- [investor-stated | moderate] Treat partnership quality as something built through shared work and experience, not inferred from superficial similarity or immediate rapport (42:50–43:41).
- [researcher inference | moderate] The career story suggests a resourcefulness model—convert fees, networks, and service work into investment access when personal capital is absent—but the legal, regulatory, and historical financing context must be reconstructed before treating it as a modern playbook (20:36–22:38).
Contradictions, counterevidence, and access limits
- [contemporaneous record | moderate] This note uses the complete official RSS MP3. No official transcript was available. OpenAI whisper-1 produced a full English verbose_json transcript with segment timestamps; the model has no speaker diarization, so attribution follows interview turns and explicit questions. Cross-talk and uncertain passages are excluded.
- [researcher inference | strong] The Podbean description and Bloch-Liran's introduction are show notes/host framing, not verbatim Eisenberg evidence. Fund AUM, company counts, family facts, book totals, nonprofit roles, and praise from unnamed peers are not treated as verified merely because the host reads them.
- [contemporaneous record | moderate] Whisper repeatedly renders “Aleph” as “Olive/Oliph,” “Eden” inconsistently, and some proper names phonetically. Obvious names are normalized; any entity that could not be resolved confidently is omitted.
- [researcher inference | strong] The stagehand metaphor limits investor credit, yet Eisenberg also says “we” made the Print Life business-model error and describes recruiting, shutdown, and fund-formation decisions. The evidence supports a consequential supporting role, not either total modesty or lone-investor causation.
- [researcher inference | strong] The Schreiber–Lemonade sequence shows a durable relationship but does not prove that relationship caused Lemonade's investment or outcome. Deal economics, co-investors, partner votes, and founder reasons remain absent.
- [researcher inference | moderate] “Right and non-consensus” is Eisenberg's rendering of a Howard Marks framework. It does not show that Aleph consistently held non-consensus positions, that those positions were right, or that price was not already incorporating the view.
- [researcher inference | strong] The shutdown story is narrated only by Eisenberg; the founder and company are unnamed, no board decision is documented, and no later outcome is available. It demonstrates his claimed reasoning, not that shutdown was objectively optimal.
- [researcher inference | strong] The Benchmark handshake, continued main-fund investing, Israel-portfolio management, LP support, nine-week raise, and July 3 close are retrospective self-report. Partnership, fund, LP, and closing records are the required controls.
- [researcher inference | moderate] The Aleph name's performance ambitions and “generational firm” framing are aspirations. The interview gives no net returns, benchmark, loss ratio, or denominator capable of validating them.
- [researcher inference | moderate] Eisenberg values anticipatable behavior but also emphasizes non-consensus decisions and blunt shutdown advice. Predictability here means values and process, not predictable agreement or investment outcomes.
Open questions
- What firm and vehicle funded Print Life, what capital was deployed, who approved vertical integration, and what recovery followed?
- Which first digital-photography financing converted Eisenberg's fee into equity, and what legal and economic structure did it use?
- What are the exact dates and roles for political consulting, Montgomery Securities, and the partnership with Shlomo Kalish?
- Which Benchmark main fund supported Eisenberg's post-2009 Israel investments, and what authority and economics governed that transition?
- Do contemporaneous Benchmark, Aleph, or LP records corroborate the handshake, end-2012 notice, first-fund travel dates, and July 3 close?
- How did Kathryn Mayne, Bruce Dunlevie, Eden Shochat, and Eisenberg each shape Aleph's original thesis, economics, and fundraising?
- Which unnamed company did Eisenberg recommend closing after October 2023, and what evidence, alternatives, and decision rights were present?
- How often did long-term founder relationships produce later investments compared with new relationships, and what were the respective outcomes?
t Interview with Michael Eisenberg
- URL: https://www.maxraskin.com/interviews/michael-eisenberg | Published: Jan 15; year not exposed on the live page | Format: full edited text Q&A | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: publisher section headings and exact interviewer-question anchors; no timestamps or stable paragraph numbers
Takeaways
- [investor-stated | strong] Eisenberg's learning method is repeated exposure before comprehension: struggle through unfamiliar material until patterns form, learn a field's five-to-ten key words, then use that vocabulary to earn substantive conversations with experts. The mechanism is not pretending expertise; it is reducing the cost of asking informed questions. Raskin, “Struggle With It,” questions on Hebrew and crypto
- [retrospective witness | moderate] He says he studied political science rather than investing and learned finance by repeatedly reading S-1s, balance sheets, and profit-and-loss statements without initially understanding them. This explains a self-taught pattern-recognition style but does not establish accounting competence or investment efficacy. Raskin, “Struggle With It,” question on investing study
- [investor-stated | strong] His priority rule is singular: only one item can occupy the top of the list at a time, and presence means removing phone distraction. He illustrates dynamic reprioritization with health and a Healthy.io portfolio company requiring concentrated attention. The source does not describe how Aleph allocates partner time or resolves competing portfolio emergencies. Raskin, “The Sacred and the Prosaic,” questions on productivity and priorities
- [investor-stated | strong] Eisenberg describes two parallel networking systems: an associative mental map of people he finds interesting and an Aleph CRM that is heavily annotated and updated automatically and manually. He names three outputs—deal sourcing, talent recruiting, and business/corporate development including sales and funding. This is one of the corpus's clearest descriptions of a firm-level network operating system. Raskin, “Herzlean Task,” questions on collecting people and the database
- [investor-stated | moderate] The human system is deliberately imperfect: Eisenberg calls his own relationship maintenance disorganized and jokes that he competes with the database. The implied operating design pairs high-context individual recall with institutional memory rather than assuming either is sufficient. The transcript provides no access-control, consent, data-quality, or outcome audit. Raskin, “Herzlean Task,” questions on staying in touch and database output
- [investor-stated | moderate] He says capital providers prefer earnest, authentic, hardworking counterparts and rejects fashionable arguments for reduced work intensity. This is a fundraising and people-selection belief, not evidence that work hours cause returns; it risks confusing visible intensity with judgment, health, or durable team performance. Raskin, “Herzlean Task,” question on raising money
- [investor-stated | moderate] Eisenberg distinguishes politicians from policy and says he prefers civic movements. He views civil society as the likely mechanism for institutional change and reports involvement in Israeli policy initiatives. No initiative, authority, result, or conflict boundary is specified. Raskin, “Herzlean Task,” questions on politics and civic movements
- [investor-stated | strong] The interview documents a topic-driven information diet: no newspaper subscription, articles gathered from multiple outlets, then deep “rabbit holes” around current problems. At the time of the page he names civic movements, Lebanon, and ethical frameworks for new technologies. The process favors focused synthesis but may increase selection and network-confirmation bias. Raskin, “Hot Topics,” questions on newspapers and current topics
- [investor-stated | moderate] His morning writing practice integrates Torah, economics, and technology. He says he writes two weekly pieces, one for Globes and one for a WhatsApp list, while researching books on Deuteronomy and capitalism. The WhatsApp distribution is not a public, stable corpus and cannot be treated as audited writing evidence. Raskin, “Struggle With It,” questions on morning reading and study routine
- [investor-stated | moderate] Eisenberg describes himself as not technical, says his last coding was in seventh or eighth grade, and remembers an early program calculating Jewish prayer times. That makes his stated edge translation, questioning, pattern acquisition, and people networks rather than hands-on engineering. Raskin, “Coding The City of David,” question “Do you code?”
Quotes
- “Every topic has its own language.” — Michael Eisenberg, “Struggle With It,” crypto-learning question
- “You can only have one thing at the top of your priority list at any given point in time.” — Michael Eisenberg, “The Sacred and the Prosaic,” productivity question
- “I collect people I like, and I find interesting.” — Michael Eisenberg, “Herzlean Task,” collecting question
- “There's no substitute for hard work.” — Michael Eisenberg, “Herzlean Task,” fundraising question
- “I just try not to waste it.” — Michael Eisenberg, “Hot Topics,” time-management question
Biography and decision evidence
- The publisher introduction identifies Eisenberg as Aleph co-founder and general partner in Tel Aviv. Because the page exposes no year, this is an undated publisher snapshot rather than confirmed-current role evidence. Raskin, introduction
- [retrospective witness | moderate] Eisenberg says yeshiva immersion with an Israeli study partner built his Hebrew and that college combined political science, daily Torah study, and newspaper editing. The chronology is direct recollection without dates beyond school stage. Raskin, “Struggle With It,” opening questions
- [investor-stated | strong] Healthy.io is the only named portfolio-work example: Eisenberg says it then required many hours daily and his fullest attention. The passage demonstrates claimed post-investment involvement but not the problem, intervention, board authority, result, or whether the work was personal or institutional. Raskin, “The Sacred and the Prosaic,” daily-priority question
- [investor-stated | strong] Aleph's CRM is explicitly firm-level infrastructure. Its stated outputs include sourcing, recruiting, sales/business development, and funding; this supports institutional capability, not exclusive Eisenberg credit for each resulting deal or hire. Raskin, “Herzlean Task,” database questions
- [investor-stated | moderate] Eisenberg describes dual US-Israeli citizenship, permanent family commitment to Israel, and a formative connection to his grandfather's US Navy service. These are self-described identity facts, not investment mechanisms. Raskin, “Washington and Jerusalem,” citizenship questions
- [investor-stated | moderate] He reports partner meetings on Sundays and says he looks at data throughout them. The type of data, decision rights, dissent process, and investment-committee rules remain unavailable. Raskin, “Hot Topics,” screen-time questions
- Retrospective boundary: school, early-finance learning, coding, and family stories are retrospective. The priority examples, CRM description, reading topics, portfolio attention, and weekly writing cadence are contemporaneous only to an unknown publication year.
Philosophy signals
- Tags: sourcing — [investor-stated | strong]: build field vocabulary, reach experts, maintain an annotated connection graph, and convert it into deal flow. Raskin, “Struggle With It” and “Herzlean Task”
- Tags: people — [investor-stated | moderate]: value earnestness, authenticity, work intensity, interesting people, and long-lived relationships. No structured reference rubric or false-positive evidence is provided. Raskin, “Herzlean Task,” people and fundraising questions
- Tags: picking / risk — [investor-stated | moderate]: read primary financial documents before full fluency, acquire the language of a domain, and use recurring patterns to form better questions. Pattern familiarity must not be confused with validated causal knowledge. Raskin, “Struggle With It,” investing-study question
- Tags: portfolio / boards — [investor-stated | moderate]: concentrate time where a company requires it and use institutional network data for recruiting, customers, and later funders. Triage criteria and outcome evidence are absent. Raskin, priority and CRM questions
- Tags: macro — [investor-stated | provisional]: civil society and civic movements are preferred change mechanisms; Lebanon and technology ethics are research areas. The interview offers interests rather than investable theses. Raskin, “Herzlean Task” and “Hot Topics”
- Tags: exits — [researcher inference | insufficient public record]: the Q&A contains no exit timing, realization, reserve, ownership, or distribution rule.
Contradictions, counterevidence, and access limits
- [contemporaneous record | moderate] The page transcribes Eisenberg saying “K-1’s” are annual reports. That terminology is nonstandard: the public-company annual filing discussed alongside S-1s is generally a 10-K, while Schedule K-1 reports pass-through tax items. Because no audio or correction record was used, the note preserves the published wording and treats it as a possible speaker or editing error rather than silently repairing it. Raskin, “Struggle With It,” investing-study question
- [researcher inference | moderate] Singular prioritization can create focus but also key-person risk and portfolio neglect when multiple companies need help. The source provides no delegation or escalation mechanism. Raskin, “The Sacred and the Prosaic,” priority questions
- [researcher inference | moderate] A richly annotated CRM can compound network advantage while also encoding stale judgments, consent risks, homophily, and biased access. No governance or outcome denominator is disclosed. Raskin, “Herzlean Task,” database questions
- [researcher inference | moderate] Eisenberg's disdain for work-life-balance rhetoric sits beside the same interview's account of back pain forcing reprioritization and a marriage practice that often misses its weekly target. Intensity may be a value; the source also displays its capacity constraints. Raskin, “The Sacred and the Prosaic” and fundraising question
- The live page displays “Jan 15” but no year. No publication year is inferred from design, surrounding interviews, or mutable site metadata.
- The Q&A has headings but no timestamps, stable paragraph numbering, recording, or editorial-change log. It is full as published, not necessarily verbatim.
- Reliability is A/B for attributed direct answers. Claims about firm systems, policy involvement, books, and personal routines are self-reported and uncorroborated within this source.
Open questions
- What is the missing publication year, and does a feed or archived snapshot preserve it?
- Did the recording say K-1 or 10-K, and how much editing occurred?
- What fields, refresh rules, access controls, and measurable conversion rates govern Aleph's CRM?
- What specific Healthy.io problem required Eisenberg's concentrated time, what action did he take, and what changed?
- How does the singular-priority rule operate when two portfolio crises or fiduciary duties collide?
- Which weekly WhatsApp pieces have a lawful, stable public archive?
t Misgav: AI, Abraham Accords, and Israel's Future
- URL: https://www.misgavins.org/en/ep-8-michael-eisenberg-on-ai-abraham-accords-and-why-hes-bullish-about-israels-future/ | Published: 2025-08-13 | Format: podcast | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: OpenAI
whisper-1segment timestamps against the official RSS MP3; source duration 1:08:46, while the compressed transcription copy decoded as 1:08:56, so locators after 20:36 are rounded to conservative ranges and should be checked against the official audio before publication.
Takeaways
- Civilian invention is the default; AI is the exception. Eisenberg says defense-tech initiatives emerged from soldiers' observed needs rather than a state plan, but treats AI as national infrastructure because it combines energy, compute, and scarce technical labor. This is a state-capacity thesis, not evidence that Aleph applies the same rule to company selection. [retrospective witness | moderate] [20:36-25:48; 30:21-31:25]
- His regional AI case is built on complementary constraints. He assigns the UAE and Saudi Arabia energy, capital, and infrastructure-building capacity, and Israel innovation talent, chip design, and U.S. access. He proposes that the combination serve markets south and east. The interview supplies a strategic proposal, not proof of execution or returns. [investor-stated | provisional] [35:17-39:10]
- A small home market is an advantage only if paired with external capacity. He argues that Israeli companies learn to sell internationally from inception, then says AI-enabled services and offices in larger overseas talent pools are needed to broaden growth beyond cyber and defense. [investor-stated | moderate] [59:17-61:55]
- Talent is the repeated bottleneck. The same constraint appears at nation and company level: attract highly trained people into or back to Israel, while companies recruit through global offices. This is a useful transfer test for investments whose model assumes abundant specialized labor. [investor-stated | moderate] [31:01-31:28; 1:01:00-1:01:55]
- His optimism rests partly on wartime selection evidence. He links young Israelis' service, improvised military tools, and resilience to future innovation. That is a personally situated judgment during an ongoing war; it does not establish that the observed traits persist in civilian companies or predict venture outcomes. [researcher inference | moderate] [22:46-25:48]
- Political will and capital allocation are his limiting conditions. He argues that debt-financed war spending makes prioritization of security and growth infrastructure more urgent. Fiscal figures and institutional claims in the conversation were not independently verified here. [investor-stated | moderate] [25:59-29:48]
- Partnership is his operating answer to limited personal capacity. In family, Aleph, nonprofit work, editing, and the Bat Shlomo project, he credits capable partners rather than individual control. This is biographical evidence of a stated delegation principle, not proof of team performance. [retrospective witness | moderate] [21:11-22:22; 1:02:54-1:05:02]
Quotes
- “Generally, in technology, civilian innovation wins.” [30:21-30:28]
- “AI is infrastructure for the future nation-state, like nuclear power, like nuclear weapons.” [30:45-30:59]
- “What they all lack is talent.” [36:28-36:34]
- “Great Israeli companies don't necessarily service the local market.” [59:17-59:26]
- “We don't have enough talent here.” [1:00:58-1:01:03]
- “I actually don't believe in work-life balance.” [1:05:13-1:05:26]
Biography and decision evidence
- Eisenberg says he bought land at Bat Shlomo and has a farm there; he and Eli Wurtman started Bat Shlomo Winery, which Wurtman now runs and owns. This is direct autobiographical testimony, but the ownership history was not independently checked. [retrospective witness | moderate] [21:11-22:22]
- He says two of his children were then in the army, describes extensive service by children and sons-in-law, and says he lost two cousins after October 7. These facts explain the interview's unusually personal link between wartime experience and the innovation thesis. [investor-stated | moderate] [23:14-24:36]
- He describes himself as Lemonade's first investor while using it as an example of an AI-native service company. That attribution and the accompanying growth claim require a portfolio or company-primary check before reuse as track-record evidence. [retrospective witness | moderate] [1:00:30-1:00:54]
- He says he chairs Hashomer HaChadash and participates in Nevo, then names operating partners at both organizations. Treat the roles as self-reported pending organization-primary verification. [investor-stated | moderate] [1:02:54-1:03:42]
- The hosts, not Eisenberg, introduce him as a New York native who moved to Israel in 1993, an Israel Seed and Benchmark alumnus, Aleph's 2013 co-founder, and a father of eight. Those show-note/host claims are leads only; the guest later confirms that the “six kids” blog title predates two more children. [contemporaneous record | moderate] [19:13-20:31; 1:02:02-1:02:21]
Philosophy signals
- Different coordination rules for different technologies: bottom-up experimentation should lead ordinary technology and defense-tech formation, whereas capital- and resource-intensive AI demands state coordination. [investor-stated | moderate] [30:21-33:15]
- Constraint-first regional strategy: map each country's scarce and abundant inputs, then build a coalition whose combined resources exceed what any member can assemble. [investor-stated | provisional] [35:17-39:10]
- Global from inception: limited local demand can train founders to seek international customers early, but access to global labor must expand with the market. [investor-stated | moderate] [59:17-1:01:55]
- Partnership over heroic individualism: his account of family, investing, civic work, and writing consistently assigns leverage to chosen collaborators. [retrospective witness | moderate] [1:02:54-1:05:02]
- Trade-offs over balance: he rejects a stable work-life equilibrium and frames resilience as accepting finite time and unavoidable trade-offs. This is a personal philosophy, not an investable rule without further evidence. [investor-stated | moderate] [1:05:13-1:07:58]
Contradictions, counterevidence, and access limits
- Eisenberg favors bottom-up civilian innovation for defense technology yet centralized authority, budget, and hiring flexibility for AI. The distinction is internally reasoned by AI's resource intensity, but it needs testing against technologies that mix infrastructure and startup experimentation. [researcher inference | moderate] [30:21-34:09]
- He says Israel's domestic-market constraint fosters global ambition while also calling insufficient local talent a binding limit. The first mechanism can improve market orientation; the second can still impede execution, so neither claim cancels the other. [researcher inference | moderate] [59:17-1:01:55]
- His regional framework depends on Gulf-Israel cooperation, U.S. alignment, access to compute, and political implementation that he says is not yet happening. It is a scenario with explicit dependencies, not a completed operating system. [investor-stated | provisional] [35:17-39:10]
- Market-performance, debt, government-budget, foreign-fund-entry, company-growth, and military-effectiveness statements remain unverified speaker claims and should not be lifted as facts from this note. [investor-stated | provisional]
- The first 20:36 is a hosts-only geopolitical discussion and introduction. It was not attributed to Eisenberg. The note analyzes the complete guest interview from 20:36 onward, using an OpenAI transcript of the official RSS audio; there is no official verbatim transcript. Compression introduced an approximately ten-second decode-time difference, and speaker diarization was not supplied, so every quote was checked by conversational context and should be rechecked against audio for final publication.
Open questions
- Has the proposed Israeli AI unit, budget, or authority been adopted, and what role—if any—did Eisenberg formally have in the commission?
- Which Aleph investments most clearly demonstrate the “AI-enabled services” thesis, and what evidence predates their outcomes?
- Does Aleph underwrite foreign recruiting and distributed offices explicitly when evaluating Israeli companies?
- What portfolio evidence supports or contradicts the claim that selling globally from inception offsets a small home market?
- Do contemporaneous records confirm Eisenberg's original role and economics in Bat Shlomo Winery and his “first investor” description of Lemonade?
- How should analysts separate his public-policy advocacy from Aleph's vehicle-level investment decisions?
t TechCrunch TV interview with Michael Eisenberg
- URL: https://www.youtube.com/watch?v=mBX3C3Pf7w8 | Published: 2012-07-16 | Format: video | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: YouTube timestamps (13:30); English auto-captions (en-orig) retrieved with yt-dlp; quote wording and cue positions checked against the official video's synchronized caption track
Takeaways
- [investor-stated | strong] Eisenberg frames software as both a productivity shock and a talent-allocation constraint: software replaces some lower-skill work while increasing demand for engineers, technical managers, and people who can build scalable systems (00:59–03:01).
- [investor-stated | moderate] His proposed labor response is reskilling rather than retraining people for another vulnerable low-skill job. He suggests vouchers for unemployed or underemployed people to acquire higher-level skills, while admitting education is slow and that he is better at questions than answers (03:13–03:40).
- [investor-stated | moderate] “Creakonomics” is his label for the transition from twentieth-century industrial corporations toward smaller, faster, innovation-based businesses. He treats a geographically diversified technology economy as less exposed to a single employer or industry than a local monoculture (04:04–06:32).
- [investor-stated | moderate] His 2012 trend map emphasizes mobile, local, social, and internet-led transformation across apparently unrelated industries. Zlango's revival after smartphones is his contemporaneous example of a product whose enabling platform arrived after the company (06:39–07:42).
- [investor-stated | strong] He presents venture outcomes as highly skewed: few companies break out, but those that do can create unusually large opportunities. This is a stated power-law intuition, not a disclosed Benchmark portfolio-return distribution (08:29–08:45).
- [investor-stated | moderate] In the Israeli market, he interprets a reported quarterly funding contraction as both reduced competition for investors and a possible correction toward an appropriate capital supply. His mechanism is that excess funding competes away scarce scaling talent from the strongest companies (08:46–09:29).
- [investor-stated | moderate] He connects Israeli military technical units to early responsibility, budget ownership, determination, and creative problem-solving, but also names a scaling limitation: he says Israeli teams may be weaker than US counterparts at broad management (10:00–11:08).
- [investor-stated | strong] His personal operating philosophy rejects a static work-life “balance” in favor of explicit trade-offs. Mobile tools can increase efficiency, he says, but can also take attention from children; he acknowledges he does not manage that boundary particularly well (11:34–12:54).
Quotes
- “There are very few companies that really break out and create very meaningful opportunities.” (Eisenberg, auto-caption, 08:32–08:38; 14 words).
- “Less competition is always good.” (Eisenberg, auto-caption, 09:05–09:11; 5 words).
- “The determination to work the long nights, the long hours, the weekends” (Eisenberg, auto-caption, 10:48–10:54; 12 words).
- “We all live a life of trade-offs.” (Eisenberg, auto-caption, 12:06–12:10; 7 words).
Biography and decision evidence
- [contemporaneous record | moderate] Colleen Taylor introduces Eisenberg as a Benchmark Capital general partner overseeing Israel operations and says he is usually based in Israel; this establishes the public role represented in the interview, not the firm's legal decision-rights structure (00:06–00:24).
- [contemporaneous record | moderate] Taylor notes that his blog was still called “Six Kids and a Blog” although he then had eight children. Eisenberg later credits his wife with managing the family and him; neither remark independently documents family history (00:27–00:43; 11:34–11:44).
- [investor-stated | moderate] He identifies Uber, Wix, and Zlango as portfolio companies or companies “of ours” and says Benchmark invested in Wix. The interview does not specify which partner sourced, sponsored, approved, priced, or governed any investment (01:26–02:13; 06:52–07:16).
- [investor-stated | moderate] His Zlango account supplies a decision-relevant timing observation—founded for feature phones, languishing, then growing after smartphones—but does not establish what Benchmark believed at entry, invested, owned, reserved, or returned (06:52–07:16).
- [investor-stated | moderate] Eisenberg names WeWork's Second Street coworking location as one example of an environment that could incubate small companies. This is a 2012 ecosystem observation, not evidence of an investment thesis, underwriting decision, board role, or later view of WeWork (06:02–06:26).
Philosophy signals
- Tags: picking / power law / capital supply / geography / talent / people / platform shifts / macro / work.
- [investor-stated | strong] Seek industries being reorganized by software, but underwrite whether the supply of high-skill builders and scaling managers can support the opportunity (00:59–03:01).
- [investor-stated | moderate] A platform transition can unlock a previously stalled company; Zlango is stated evidence for watching the enabling substrate rather than judging demand in a static technology environment (06:52–07:16).
- [investor-stated | moderate] Treat capital abundance as a possible operating liability in a talent-constrained ecosystem, not automatically as ecosystem health (08:46–09:29).
- [researcher inference | moderate] His “single points of failure” macro analogy suggests a portfolio question: does a company or ecosystem depend on one employer, platform, funding source, or scarce labor pool? The interview applies the principle to regional economies, not explicitly to portfolio construction (04:44–06:32).
- [investor-stated | moderate] Founder determination and creative technical problem-solving are positive signals; management at scale is a separate capability rather than an automatic consequence of technical intensity (10:00–11:08).
Contradictions, counterevidence, and access limits
- [contemporaneous record | moderate] The source is a complete official video, but the text route is YouTube's English automatic caption track, not a creator-provided transcript. Punctuation and names are normalized only where the audio context is unambiguous; readers should use the linked video moments for replay.
- [researcher inference | strong] Taylor's questions and introductions are interviewer framing, not Eisenberg's claims. The TechCrunch landing page and YouTube description are metadata/show notes, not verbatim transcript evidence.
- [researcher inference | strong] “Less competition is always good” is rhetorically categorical but context-bound: Eisenberg immediately qualifies it with a claim about Israel's capital-to-talent balance. It should not be transferred into a general rule that less financing competition always improves venture outcomes (09:05–09:29).
- [researcher inference | strong] The reported 10% quarterly decline in Israeli venture deployment, Nokia pension exposure, and Facebook valuation are uncorroborated speaker statements in this note. They are not treated as verified market statistics or return evidence (05:29–05:43; 08:17–09:05).
- [researcher inference | moderate] His military-service generalizations risk selection and cultural stereotyping; the interview offers no cohort denominator, counterexamples, or evidence separating training effects from selection, networks, education, or immigration.
- [contemporaneous record | strong] The video's TechCrunch recording date is 2012-07-16, while this YouTube copy was uploaded on 2023-06-05. The metadata line uses the original recording/publication context; the upload date should not be mistaken for the interview date.
- [researcher inference | strong] The interview predates later outcomes for WeWork and other named companies. It cannot establish later knowledge, causal responsibility, or whether Eisenberg's view changed.
Open questions
- What evidence did Benchmark have at the time it invested in Zlango, and did the smartphone transition precede or follow the investment decision?
- Who sourced, sponsored, approved, and governed Benchmark's Wix, Zlango, and Uber positions, and which vehicle held each?
- Did Eisenberg adopt a repeatable talent-density or capital-supply test in later Aleph investment decisions?
- How did he distinguish an ecosystem with productive micro-entrepreneurship from one with undercapitalized firms unable to scale?
- Did his view that Israeli technical teams lagged US teams in broad management change as Israel produced more globally scaled companies?
- Which later interviews or writings revisit the tension between personal attention, family commitments, and always-on mobile work?
t Executive Profile: Michael Eisenberg, Partner at Aleph VC and Investor in WeWork
- URL: https://yucommentator.org/2017/11/executive-profile-michael-eisenberg-partner-aleph-vc-investor-wework/ | Published: 2017-11-12 | Format: edited student-newspaper Q&A | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: interviewer-question anchors and article paragraphs; no timestamps or stable paragraph numbers
Takeaways
- [retrospective witness | moderate] Eisenberg traces venture entry to an indirect path: Commentator editing led to political consulting, unemployment exposed the cost of lacking an Israeli military network, and he formed a technology merchant bank despite little technical knowledge. This is a 2017 reconstruction of a 1990s career transition, not a contemporaneous employment record. Commentator, question “path you took”
- [retrospective witness | provisional] He says the merchant bank backed eleven companies in three years and that eight later went public or were acquired. The article does not name the complete eleven, define “backed,” identify vehicles, show losses, or supply cash returns; the result must remain self-reported rather than a verified hit rate. Commentator, question “path you took”
- [retrospective witness | moderate] The career sequence he gives is PictureVision, recruitment to Israel Seed, DealTime/Shopping.com, collaboration with Bill Gurley on the ePinions acquisition, nearly a decade at Benchmark, then Aleph after Benchmark focused on Silicon Valley. The sequence is useful biography, while transaction credit and outcomes require company and fund records. Commentator, question “path you took”
- [investor-stated | strong] Eisenberg describes WeWork sourcing as network convergence: Benzi Ronen, Saul Singer, and others independently pushed him and Adam Neumann toward one another. He stayed on an initial phone call because Neumann was compelling and concluded that unusual founders see the world differently. This is rare person-level sourcing testimony recorded before WeWork's later collapse. Commentator, question “How did you end up sourcing WeWork”
- [researcher inference | strong] The WeWork answer is simultaneously decision evidence and an adverse control: the source documents how persuasive founder narrative influenced attention, but gives no discussion of governance, related parties, unit economics, valuation discipline, ownership, or kill criteria. The company later filed Chapter 11; that outcome does not prove the 2017 sourcing judgment irrational, but it falsifies any inference that compelling difference alone establishes durable company quality. Commentator, WeWork question WeWork Form 8-K, Item 1.03
- [investor-stated | moderate] Asked what trend was moving Israeli VC, he answers “bigger companies” and “Scale Up Nation,” then says he tries not to invest in trends and does not care where others invest. The implied rule is to underwrite an independent company path inside a secular ecosystem shift, not follow sector popularity. The short answer does not specify how he distinguishes a durable trend line from consensus. Commentator, question “trends in the Israeli startup ecosystem”
- [investor-stated | strong] Career advice centers people, ethics, purpose, optimism, service, hard work, family, and daily Torah study. He explicitly subordinates money and companies to values and people. This is a normative operating identity; it is not evidence that every portfolio decision or board action met those values. Commentator, two student-advice questions
- [retrospective witness | moderate] Eisenberg says college newspaper writing clarified contested issues during the Revel crisis, gave change agents a platform, exposed him to rebuke, and trained him to challenge entrenched claims while questioning his own decisions. That account supplies a plausible formation story for his later public writing and status-quo skepticism, but causation is remembered twenty-plus years later. Commentator, question “Editor in Chief”
Quotes
- “Founders make companies because they see the world differently.” — Michael Eisenberg, WeWork sourcing question
- “I try not to invest in trends.” — Michael Eisenberg, Israeli startup trends question
- “The basis of your career is values and people. Not money and companies.” — Michael Eisenberg, student career-advice question
- “We cannot stay stagnant.” — Michael Eisenberg, Editor-in-Chief question
Biography and decision evidence
- The reporter identifies Eisenberg as Yeshiva College class of 1993, a former Commentator editor-in-chief, an Aleph equal partner, and a former Benchmark general partner. The same introduction reports over $300 million of Aleph AUM and lists eight boards or observer roles. Those are 2017 editorial assertions and a dated snapshot, not direct Eisenberg testimony or current status. Commentator, introduction
- [retrospective witness | moderate] Eisenberg names Neil Cohen and Jon Medved as Israel Seed founders who recruited him after rejecting an earlier job request. He credits Gurley as an existing friend and co-lead Shopping.com director in the ePinions transaction. These are person-attribution leads, not closing-document proof. Commentator, question “path you took”
- [investor-stated | strong] The WeWork answer names introducers, describes the setting and duration pressure of the first call, and attributes sourcing to Eisenberg. It does not establish that he alone approved the Benchmark investment, governed the company, or received personal economics. Commentator, WeWork sourcing question
- [retrospective witness | moderate] Eisenberg says Benchmark's international retrenchment and his purpose of creating Israeli jobs motivated Aleph's formation. This is a founder's later motive statement; it should not be substituted for partner, LP, or vehicle records. Commentator, question “path you took”
- Retrospective boundary: most career claims cover events from the early 1990s through 2013 and are narrated in 2017. The WeWork enthusiasm, current board snapshot, Aleph AUM statement, and Scale Up Nation answer are contemporaneous to the 2017 publication, making them especially valuable for later outcome comparison.
Philosophy signals
- Tags: sourcing / people — [investor-stated | strong]: cultivate overlapping trusted channels; take repeated founder referrals seriously; use the first interaction to test whether the founder's worldview is distinctive. Commentator, WeWork sourcing question
- Tags: picking — [investor-stated | moderate]: seek companies capable of scaling beyond Israel while resisting crowd-following. The interview supplies no market-size threshold, valuation test, or falsification criterion. Commentator, Israeli startup trends question
- Tags: people / risk — [investor-stated | moderate]: surround oneself with ethical people, maintain an external conscience, question one's own decisions, and challenge received beliefs. The operationalization inside diligence or boards is unstated. Commentator, student-advice and Editor-in-Chief questions
- Tags: macro — [investor-stated | provisional]: “Israel” is the favored long-term trend line, but the answer is advocacy without country-risk, sector, price, currency, or capital-cycle conditions. Commentator, industry-interest question
- Tags: boards / exits — [retrospective witness | provisional]: Shopping.com's ePinions acquisition is presented as collaborative company-building; the note cannot derive governance method or investment return from the anecdote. Commentator, question “path you took”
Contradictions, counterevidence, and access limits
- [researcher inference | strong] The advice to remain around ethical people sits uneasily beside the source's unqualified 2017 celebration of Neumann's compelling founder quality. The relevant lesson is not guilt by later outcome; it is that charisma and worldview require separate governance, verification, and incentive tests. Commentator, WeWork and student-advice questions WeWork Form 8-K, Item 1.03
- [researcher inference | moderate] “I try not to invest in trends” coexists with “the Israel trend line is up and to the right.” A coherent reading is company-specific independence within a national secular thesis, but Eisenberg does not state that reconciliation here. Commentator, trends and industry-interest questions
- The edited Q&A has no timestamps, stable paragraph numbers, recording, or editorial-change log. Exact question text is therefore the most precise available locator.
- The introduction's AUM and board roster are reporter-written and time-bound. “Currently” means the 2017 publication date and must not be carried into 2026.
- The eleven-company/eight-outcome claim is self-reported, survivor-selected, and lacks a company denominator, write-offs, ownership, invested capital, realization dates, or cash-return evidence.
- Reliability is A/B: strong for the fact that the article attributes the quoted answers to Eisenberg; weaker for the completeness, editing, retrospective accuracy, and unsourced introductory metrics.
Open questions
- What were the eleven merchant-bank companies, investment vehicles, losses, ownership stakes, and realized cash returns?
- Which Benchmark partners approved WeWork, what were the original price and ownership, and what governance risks were documented ex ante?
- What did Eisenberg's 2017 “ethical people” test require beyond founder charisma and network references?
- Which specific Commentator editorials survive in the YU archive, and what did they say contemporaneously?
- What objective scale threshold distinguished a Scale Up Nation candidate from a merely larger Israeli company?
w 2016 Prediction
- URL: https://www.aleph.vc/content/2016-prediction | Published: 2016-01-13 | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: prediction paragraph followed by evidence and conclusion paragraphs
Takeaways
- Eisenberg makes one falsifiable sector call: by the end of 2016, at least one leading Israeli venture-backed adtech company would have been sold, shut down, or sharply reduced. He deliberately frames the prediction around company impairment rather than a general funding slowdown.
- The argument combines a crowded local supply of adtech companies, rising Israeli funding even as US sector funding fell, consumer and platform pressure on mobile advertising, and valuation ceilings imposed by weaker public comparables. Israel is treated as lagging the US cycle, so exuberant financing is a late signal rather than reassurance.
- He adds a capital-structure mechanism: if private rounds were raised at aggressive valuations with liquidation preferences or other investor protections, a disappointing exit could still leave founders, employees, and junior holders with little even when the company headline value appears substantial.
- The quantitative evidence is explicitly approximate: a Zirra analysis estimated four Israeli companies among the global top ten, aggregate current value around $2.25 billion, possible exit value above $3 billion, and about $450 million raised; a cited press report counted roughly 600 companies and 16,000 workers. These are source-reported estimates, not audited figures.
- He allows countercases: one or two companies might survive, and stronger operators could benefit from consolidation. The thesis is therefore about sector structure and distribution of outcomes, not the impossibility of any adtech winner.
- The actionable rule is to triangulate private financing against public comparables, platform control, consumer behavior, and cap-table terms. Sector funding growth can be a danger signal when upstream economics are deteriorating.
Quotes
- “At least one of Israel’s leading VC-backed adtech companies will be at best a shadow of its former self.” — canonical essay, prediction paragraph.
Biography and decision evidence
- The prediction is dated and ex ante, making it unusually useful for scoring Eisenberg's forecasting process. It is not a complete denominator of his annual forecasts, investments, exits, or avoided deals.
- The essay expresses a sector view but identifies no Aleph short, divestiture, pass, reserve decision, or portfolio action caused by it.
- References to cap tables and terms are framed as unknowns; they show what he believed mattered, not possession of confidential company economics.
Philosophy signals
- Macro: compare local financing momentum with the leading market's cycle and with platform-level shifts.
- Risk: test platform capture, consumer rejection, public-comparable compression, liquidation preferences, and employee payout waterfalls.
- Picking: allow exceptional operators but demand company-specific evidence against a structurally weakening category.
- Exits: headline sale value is not stakeholder return; model the preference stack and ownership by security class.
Contradictions, counterevidence, and access limits
- The note does not score the prediction because the essay alone cannot establish which company outcome occurred by year-end. A later, independent outcome source and a predeclared success criterion are required.
- The estimates come from Zirra and press reporting rather than filings or a complete market census. The author also says he does not know the relevant cap tables and terms.
- A single selected prediction is vulnerable to publication bias. Without all contemporaneous predictions, there is no forecasting hit rate.
- The closing appeal for mission-driven alternatives is normative and does not prove that socially purposeful sectors offer better venture returns.
Open questions
- Which company or companies met the stated 2016 condition, on what date, and under which objective measure?
- What were the actual preference stacks and employee payouts in the relevant exits or shutdowns?
- Did Aleph pass on, sell, or reserve differently for adtech because of this analysis?
- What is the complete set of Eisenberg's dated predictions, including misses and ambiguous outcomes?
w לא רק חיפוש רוחני: אברהם אבינו כבד במקנה, בכסף ובזהב, וטוב שכך (Abraham, Wealth and Economic Fraternity)
- URL: https://www.globes.co.il/news/article.aspx?did=1001428811&fid=2 | Published: 2022-11-04 | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: Hebrew subheading + body paragraph counted within subheading; English renderings in this note are researcher translations
Takeaways
- Eisenberg argues that Abraham’s wealth is not an embarrassing detail beside his spiritual mission. Genesis repeatedly records livestock, silver, gold, dependents, and movement of resources because material capacity enables agency, teaching, protection, alliance, and nation building (opening section, ¶¶1–6).
- He rejects an ideal that religious life should withdraw from the “real economy.” In his account, sustained abstention from productive economic life is dangerous for a community and a sovereign state because it weakens responsibility and capacity (opening section, later paragraphs).
- The essay contrasts Andrew Carnegie’s “Gospel of Wealth” stewardship with Abraham’s conduct. Carnegie’s wealthy trustee acts on behalf of poorer people; Abraham instead backs Lot, teaches him to earn, connects him to an Egyptian network, and lets him choose his own field of development (“כלכלת אחווה” / “Economy of Fraternity,” ¶¶1–4).
- The resulting “economy of fraternity” combines private property, ownership rights, and the human drive to create and prosper with mutual responsibility, faith in another person’s potential, and investment in that person’s economic success (“כלכלת אחווה,” closing ¶¶1–3).
- Sacrifice for another is framed as investment rather than zero-sum charity: empowering a brother can improve both individual and aggregate growth. This is the compact op-ed version of the later “covenantal capitalism” framework.
Quotes
- “אברהם היה הראשון לאמץ את המודל הכלכלי של התורה: כלכלת אחווה.” (“כלכלת אחווה,” closing; researcher translation: Abraham first adopted the Torah’s economic model, an economy of fraternity.)
- “כלכלת אחווה דורשת ויתורים למענו של האח.” (“כלכלת אחווה,” closing; researcher translation: an economy of fraternity requires concessions for one’s brother.)
Biography and decision evidence
- The article shows Eisenberg using Torah exegesis to define an operating model of capital: do not only transfer resources; supply agency, networks, choice, and a path to ownership.
- It provides strong direct evidence for his declared people-empowerment philosophy but no evidence that a named company, board action, or fund cash flow met that standard.
- The comparison with Carnegie indicates an aversion to paternalistic philanthropy and a preference for investee self-efficacy.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- people: Backs another person’s capacity to earn and choose rather than making them a permanent beneficiary.
- picking: Suggests preference for products and founders that expand capability, ownership, networks, and upward mobility.
- macro: Private property and wealth creation require reciprocal responsibility to sustain a flourishing polity.
- risk: Treats economic withdrawal and paternalistic dependence as social risks.
- portfolio / boards / exits: No sizing, governance, or return evidence appears.
Contradictions, counterevidence, and access limits
- The Abraham and Carnegie contrast simplifies both. Carnegie funded broad public institutions, while a biblical family narrative is not a controlled economic-policy case.
- “Fraternity” can become exclusionary unless the relevant community and rights of outsiders are specified. The op-ed does not fully address power imbalances between investor and recipient.
- The synthesis is normative and theological. It provides neither mobility metrics nor comparison against cash transfers, public services, worker protections, or redistribution.
- The Globes webpage text was indexed and readable at access, but its chrome says the print article is available to subscribers. No paywall was bypassed. Hebrew-to-English descriptions here are researcher translations.
Open questions
- Who counts as the “brother” in portfolio, workplace, national, and cross-border settings?
- How are agency and economic mobility measured after an investment?
- What governance duties follow when empowering the investee conflicts with investor control or return maximization?
w Introducing the Aleph AI Team: Building the Next Wave of AI Companies
- URL: https://medium.com/aleph-vc/introducing-the-aleph-ai-team-building-the-next-wave-of-ai-companies-26a8df04320c | Published: 2025-03-26 | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: author cross-post paragraph sequence and named program terms
Takeaways
- Eisenberg announces Aleph AI-TEAM for two- or three-person technical founding teams and offers up to $3 million at pre-seed on what he calls a standard capped SAFE. The program target combines speed—zero to $10 million of revenue within 18 months—with defensibility, rather than treating early revenue alone as success.
- The investment thesis is that foundation models and AI engines are commoditizing, so durable value must be built from domain expertise, unique data, and distribution. Fast-growing but undefended “AI meteors” are the explicit anti-pattern.
- His causal reasoning is: generic model access makes features easy to reproduce; ephemeral distribution can produce quick revenue; proprietary data, network effects, or hardware/workflow integration take capital and repeated use; those compounding assets create the moat. This is why he rejects the claim that AI startups are necessarily easier to bootstrap.
- Preferred search spaces include AI-enabled marketplaces with non-SaaS economics, workflows in which AI reduces communication and coordination overhead, and robotics, laboratories, chemicals, or semiconductor manufacturing where continuous operation might accelerate learning cycles.
- Evidence is programmatic, not outcome-tested: he says Aleph had already invested in three AI-enabled marketplace businesses, but does not name them, present their economics, or show that the proposed moats persisted. The $10 million/18-month objective is an underwriting aspiration, not a reported result.
- Operationally, the essay implies a diligence sequence: identify the non-model advantage; show how use compounds data or distribution; explain why capital accelerates that asset; and reject a generic AI feature even if its initial growth is fast.
Quotes
- “Do not bring us run-of-the-mill AI features.” — canonical essay, author cross-post, closing paragraph.
Biography and decision evidence
- This is a dated 2025 Aleph program announcement authored by Eisenberg and therefore direct evidence of his current sector language and the firm's stated offer. It does not establish that he alone set the terms or approved every investment made under the program.
- The announced amount, SAFE structure, target team size, and revenue objective belong to Aleph AI-TEAM. They are not evidence of Eisenberg's personal check, ownership, or realized performance.
- His statement that Aleph had made three relevant marketplace investments is a firm-level assertion without names or vehicle allocation; it should not be converted into a person-level deal list.
Philosophy signals
- Picking: require a differentiated, compounding advantage in data, distribution, domain knowledge, network effects, or integrated physical workflows; model access by itself is insufficient.
- Risk: treat very fast AI growth without defensibility as a warning, and test whether distribution and revenue disappear when the feature is copied.
- Portfolio: the offer is concentrated enough to fund moat-building at pre-seed, but the essay supplies neither portfolio construction nor reserve policy.
- People: the target is a very small, ambitious technical team capable of moving rapidly; the essay does not specify a repeatable founder-scoring rubric.
- Macro: model commoditization is the premise behind moving value toward proprietary complements.
Contradictions, counterevidence, and access limits
- The canonical Medium page was intermittently blocked during retrieval. Full text was available in Eisenberg's same-day author cross-post; analysis is limited to that signed text and the canonical publication metadata.
- Speed and defensibility can conflict: an 18-month revenue target may reward easily distributed applications while the essay also insists on slower, capital-intensive moat creation. No evidence here resolves how Aleph weights those objectives when they diverge.
- Proprietary data and marketplaces can themselves be competed away, regulated, or weakened by model/platform owners. The essay asserts the moat categories but does not provide cohort retention, unit economics, data rights, or counterexamples.
- “Standard capped SAFE” is not sufficiently specific to compare price or control; the cap, discount, pro-rata rights, governance, and selection process are undisclosed.
Open questions
- Which three AI-enabled marketplace investments supplied the empirical basis, and what vehicle, partner, date, and outcome belongs to each?
- What cap and rights applied to the advertised SAFE, and did all accepted teams receive the same terms?
- How does Aleph measure a data or distribution moat before product-market fit, and what evidence causes it to reject a fast-growing “meteor”?
- How many teams entered the program, reached the 18-month revenue target, or failed, and what is the complete denominator?
w Aleph III
- URL: https://www.aleph.vc/content/aleph-iii | Published: 2019-12-17 | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: four body paragraphs and signatory block; no stable paragraph numbers
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Central announcement — [investor-stated | strong]: Aleph III closed at a stated $200 million and would continue investing in ambitious Israeli entrepreneurs building large, meaningful companies and global brands from Israel. The amount is a firm announcement, not audited fund documentation. Body paragraph 1
- Strategy continuity — [investor-stated | moderate]: “exactly the same thing” means continuity of geography, founder ambition, and company-building mission across Aleph funds. The text does not define check sizes, stage bands, ownership targets, reserves, sector exposure, or portfolio count, so operational continuity cannot be tested here. Body paragraph 1
- Value-add mechanism — [investor-stated | moderate]: Aleph says it uses customer, follow-on-funder, and talent relationships plus proprietary technology and data to help startups become scaleups. This names the claimed operating system but supplies no cases, usage metrics, or incremental outcome evidence. Body paragraph 3
- Founder mindset — [investor-stated | provisional]: the partnership claims to approach support with a founder mindset and to work tirelessly for entrepreneurs and investors. These are positioning statements; a governance or service standard is not specified. Body paragraphs 2–4
- Team attribution — [contemporaneous record | strong]: the announcement is signed Aaron, Eden, Michael, and Yael and thanks the full Aleph team. It is direct evidence against treating the fund or strategy as a sole-Eisenberg product. Signatory block
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “A $200 million fund that will do exactly the same thing as previous Aleph funds.” — collective Aleph signatories; body paragraph 1. Source
- “Our focus is devoted to accelerating startups to scaleups.” — collective Aleph signatories; body paragraph 3. Source
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The December 2019 announcement documents Eisenberg as one of four named signatories alongside Aaron Rosenson, Eden Shochat, and Yael Elad, with the full team explicitly credited. Closing and signatory block
- The statement credits LP support, portfolio entrepreneurs, and the Israeli technology ecosystem. It confirms the institutional setting of the strategy but discloses no LP identities or commitments. Body paragraph 2
- Aleph III is a distinct vehicle from the 2013 Aleph-Aleph vehicle and later Aleph IV. The source does not support carrying portfolio companies, performance, or individual economics across vehicles.
- The announcement contains no investment decisions or company examples; it is evidence of intended mandate and team composition, not a track-record ledger.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- sourcing / picking — [investor-stated | moderate]: focus on Israeli founders with global-company and brand ambition rather than a narrow local outcome. Body paragraph 1
- portfolio / people — [investor-stated | provisional]: use firm relationships to recruit talent, reach customers, and obtain later financing; use internal tools/data to make support repeatable. Body paragraph 3
- boards / risk — [insufficient public record]: the announcement says nothing about governance, reserves, concentration, loss tolerance, ownership, or follow-on rules; later synthesis must not infer these from “service.”
- exits — [insufficient public record]: global-brand ambition does not specify IPO, M&A, holding-period, or liquidity preferences.
Contradictions, counterevidence, and access limits
- The claim of doing “exactly the same thing” sits beside an emphasis on scaling, proprietary technology, and data. These may be capability refinements within a stable mandate, but the announcement is too short to distinguish continuity from evolution.
- The $200 million close is self-announced. No Aleph III Form D, audited financial statement, LP report, or cash receipt record was retrieved in this batch.
- Firm tools and relationships are described as value-add, but there is no counterfactual showing company outcomes were better because of them.
- Fundraising communication naturally foregrounds continuity, gratitude, and service and omits failures, fees, carry, key-person terms, recycling, reserves, concentration, and performance.
- The full body contains only four substantive paragraphs. A short announcement cannot support detailed portfolio-policy or return conclusions.
Open questions
- Can an official Aleph III Form D or equivalent filing independently confirm offered/sold amount, legal issuer, dates, and related persons?
- What changed from Aleph I/II to III in check size, stage, team, platform spend, reserves, and ownership despite the continuity claim?
- Which proprietary tools/data existed by December 2019, how were they used, and what outcome evidence distinguishes them from marketing?
- What are Aleph III’s complete company, write-off, follow-on, exit, DPI, TVPI, and IRR denominators?
w Announcing Aleph V: Long Israel
- URL: https://medium.com/aleph-vc/announcing-aleph-v-long-israel-2d810e6e48ca | Published: 2026 (exact day unverified) | Format: essay | Reliability: A | Access: partial | Accessed: 2026-08-22 | Locator scheme: canonical URL and publication-index metadata; no article-body locator available
Takeaways
- The first-party Aleph/Medium index establishes that an announcement titled “Announcing Aleph V: Long Israel” exists at the canonical URL in 2026. The exact publication day and article body were not lawfully retrievable in this pass.
- No fund size, close status, strategy, stage, geography, team attribution, deployment pace, or portfolio claim is extracted here. The title alone is not a sufficient basis to reconstruct any of those propositions.
- This note is an access-control record, not a source analysis. It prevents an indexed title from being mistaken for reviewed primary evidence.
Quotes
- No quotation used: no publisher capture with verifiable body text and stable locator was available.
Biography and decision evidence
- The indexed item is firm-level evidence that Aleph publicly named a fifth vehicle or announcement “Aleph V”; it is not evidence of Eisenberg's individual economics, role in every decision, or personal capital commitment.
- Eisenberg's name, byline, and exact relationship to the unavailable body must be verified from a lawful capture before person-level claims are made from it.
Philosophy signals
- Portfolio: not analyzable from the accessible metadata.
- Macro: the words “Long Israel” are part of the verified title, but their intended meaning and supporting reasoning are unavailable and therefore not inferred.
Contradictions, counterevidence, and access limits
- The live canonical route returned HTTP 403 and the available index did not expose a stable publication day or article body.
- Search snippets, title semantics, neighboring Aleph announcements, Form D notices, or press summaries cannot substitute for this source. No indexed fragment is treated as a quotation or thesis.
- Any later note that supplies fund figures must preserve whether they refer to target size, first close, final close, commitments, or assets under management and must identify the legal vehicle.
Open questions
- What is the exact publication timestamp and byline?
- What legal entities and fund size or close figures does the announcement actually name?
- Which stages, geographies, reserves, and team members does Aleph V cover?
- Is a lawful publisher export, RSS body, archived capture, or corresponding filing available for line-by-line verification?
w Bad Blood, Good Urine, Great People!
- URL: https://medium.com/aleph-vc/bad-blood-good-urine-great-people-8ca6ac125bc2 | Published: 2019-02-05 | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: Medium body paragraphs 1–24 as counted from the first paragraph after Share; no publisher-stable paragraph numbers
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- General criteria — [investor-stated | strong]: Eisenberg’s model combines remarkable, learning-oriented founders; a large/emerging market; a secular tailwind; mission and values; a contrarian angle; and a fresh perspective. Relevant prior experience can help, but the Healthy.io case explicitly permits an outsider who learns quickly. Body paragraphs 1–7
- Exception logic — [investor-stated | strong]: Aleph had not planned to invest in medicine and Eisenberg had not previously invested in digital health, yet a mission-driven founder with deep learning and customer value justified crossing the sector boundary. This repeats his rule-breaking pattern: an exception must satisfy multiple core theses rather than depend on enthusiasm alone. Body paragraphs 5–8
- Technology thesis — [investor-stated | moderate]: Healthy.io bet that improving smartphone cameras and computation would allow software plus standard dipsticks to perform home diagnostics. Avoiding proprietary hardware reduced manufacturing and some regulatory risk while creating reusable software/data assets and potential multi-product scope. Body paragraphs 9–20
- Diligence evidence — [investor-stated | moderate]: Eisenberg describes learning in reimbursement, robotics, lighting, patient behavior, and FDA processes; regular pre-investment visits; more than 100,000 home tests in four countries; use cases in Israel and the UK; and FDA approval. These are detailed claims but remain investor/company supplied in this note. Body paragraphs 7–15
- Contrarian mechanism — [investor-stated | provisional]: Theranos had made diagnostics unattractive to funders; Eisenberg saw less competition and greater resolve to invest. Being outside consensus is treated as economically useful only because the company also matched Aleph’s machine vision, data, automation, mission, and software theses. Body paragraphs 16–20
- Outcome boundary — [investor-stated | strong]: Eisenberg explicitly says it was too early to know whether the investment would be great. The durable evidence in the essay is the pre-IPO decision logic, not a return claim. Body paragraph 23
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “We consider a fresh perspective on a market to be feature and not a bug.” — body paragraph 3. Source
- “It is too early to say whether Healthy.io will be a great venture investment.” — body paragraph 23. Source
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- Eisenberg says this was his first investment in digital health/medicine and that Aleph’s original scope did not anticipate medical businesses. Healthy.io therefore documents a sector-expansion decision. Body paragraph 5
- Yonatan Adiri is described as a former Getaround founder and CTO to Israeli President Shimon Peres; Eisenberg says he had known Adiri for years and visited the company regularly before investing. Ron Zohar and the broader team are credited alongside Adiri. Body paragraphs 6–9
- The essay identifies a “seat at the table” but does not specify whether that means Eisenberg personally, another Aleph representative, an observer, or a formal board seat. It also gives no check size or ownership. Body paragraph 6
- Diligence included Silicon Valley friends warning that the Theranos scandal could make diagnostics difficult to finance. This is retrospective reporting of pre-investment feedback, not a dated memo or named witness. Body paragraphs 16–18
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- people / picking — [investor-stated | strong]: prefer mission-driven “learn-it-alls” with enough humility and speed to master a regulated system, even when they begin outside it. Body paragraphs 1–8
- sourcing — [investor-stated | moderate]: repeated contact over years can make a sector exception investable, but relationship is evidence to examine rather than a substitute for domain diligence. Body paragraphs 5–9
- risk — [investor-stated | moderate]: reduce hardware and regulatory exposure through standard components; back a secular cost curve; seek data/software reuse across multiple pathways. Body paragraphs 10–21
- macro / picking — [investor-stated | provisional]: use post-scandal aversion as a potential entry advantage only when independent product, regulatory, and founder evidence survives diligence. Body paragraphs 16–20
Contradictions, counterevidence, and access limits
- Being unpopular because of Theranos can lower financing competition, but it can also be a rational signal of scientific, regulatory, and fraud risk. The essay does not disclose failed validation, false positives/negatives, clinical study design, reimbursement outcomes, or rejected evidence.
- The claim that smartphone software was already saving lives and hundreds of millions of dollars is not independently substantiated in the essay and should remain company/investor-stated.
- “No hardware” is qualified by the use of a standard dipstick and controlled imaging workflow; the investment is less hardware-dependent, not literally hardware-free.
- The essay’s examples—Lemonade, WeWork, Uber, Check Point—are selected successes or high-profile companies and do not establish a base rate for the criteria.
- Access was full, but Medium supplies no stable paragraph IDs. Locators in this note count visible body paragraphs and must be rechecked if the publisher edits the page.
Open questions
- What clinical, regulatory, and reimbursement documents did Aleph review, and which findings were investment kill criteria?
- How were individual and team deal roles divided among Eisenberg, the Aleph partnership, Adiri, and external scientific advisers?
- Did the anticipated data moat materialize across multiple products, and was it legally/clinically transferable across markets?
- What later results would show that post-Theranos aversion created mispricing rather than correctly priced risk?
w Be Long Israel. We Are.
- URL: https://medium.com/aleph-vc/be-long-israel-we-are-c4197869cd16 | Published: 2024-02-14 | Format: essay | Reliability: A | Access: partial | Accessed: 2026-08-22 | Locator scheme: Aleph publication-index card; no verified article-body locator available
Takeaways
- Aleph's first-party Medium index verifies the title, Michael A. Eisenberg byline, publication date, three-minute reading label, and an opening fragment stating that Aleph had been investing since October 7. The remaining body was not available in a stable publisher capture.
- That fragment is not enough to establish deployment totals, portfolio names, sectors, fund vehicles, causal reasoning, or a general wartime investment doctrine. None is reconstructed here from the title, index, or source-map summary.
- This note records provenance and the access failure so later synthesis cannot silently promote discovery metadata into full-text evidence.
Quotes
- No quotation used: the index fragment was not verified against a lawful full-body capture with a stable paragraph anchor.
Biography and decision evidence
- The accessible card supports authorship and timing in the Aleph era. It does not establish Eisenberg's sole responsibility for any firm investment after October 7.
- “Aleph” in the indexed fragment is a firm attribution; without the body and vehicle records, it cannot be translated into Eisenberg's personal capital, check size, deal leadership, or performance.
Philosophy signals
- Macro: not analyzable beyond the verified wartime timing signaled by the title and opening fragment.
- Portfolio: no body-level evidence was accessible for stage, sector, sizing, reserves, or pace.
Contradictions, counterevidence, and access limits
- The canonical Medium route returned HTTP 403 during this pass. Publication-index text is discovery evidence, not a substitute for the article.
- The patriotic title may tempt a reader to infer an investment rule; that would exceed the evidence. Any synthesis must wait for a lawful capture or cite a different, fully accessible signed source.
- No claims about results can be made without vehicle allocation, complete investment denominator, cost, dilution, realization, and cash-flow evidence.
Open questions
- What exact investments, dates, vehicles, and amounts did the article identify after October 7?
- Did Eisenberg distinguish new checks, follow-ons, reserves, bridge financing, and public advocacy?
- What sectors or company-selection criteria, if any, were stated in the unavailable body?
- Can Aleph provide a publisher export or lawful archive capture with stable paragraph locators?
w Big Tech Is a Modern Tower of Babel That Must Be Scattered
- URL: https://www.washingtonexaminer.com/opinion/436279/big-tech-is-a-modern-tower-of-babel-that-must-be-scattered/ | Published: 2021-08-08 | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: body paragraph counted from first paragraph after byline
Takeaways
- Eisenberg maps the Tower of Babel story onto concentrated digital platforms. The original services created genuine connection, knowledge access, and economic value, but he argues scale and uniformity later enabled control over speech, behavior, and cultural difference (body ¶¶1–5).
- “Scatter” is a product and architecture prescription, not simply a corporate breakup. Users should be able to take identities, account keys, and social graphs across services, making exit credible and allowing startups to build alternative communities (¶¶6–9).
- He cites Balaji Srinivasan’s proposal for user-controlled crypto social networks and Ben Thompson’s interoperability argument. The common mechanism is portability: reduce platform lock-in without assuming the state can centrally design every successor network (¶¶8–9).
- The policy lens is simultaneously competitive and moral. Technology embeds human priorities and bias; therefore technical standards, governance rules, and disclosure must be debated publicly against durable social principles rather than treated as neutral engineering (¶¶10–12).
- For venture analysis, the essay identifies an opportunity in identity, interoperability, user custody, and new social networks, but it does not disclose an investment, market-size model, or outcome.
Quotes
- “Technology is hardly ever ‘objective,’ ‘impartial,’ or ‘neutral.’” (body ¶10)
- “God’s solution to the tower was not to break it up into smaller parts, but rather to scatter it.” (body ¶9)
Biography and decision evidence
- The op-ed shows Eisenberg publicly supporting structural limits on platforms that had created substantial value. It is evidence that he does not equate incumbent scale with permanent social legitimacy.
- His solution preference—portable primitives that enable new entrants—aligns with venture creation rather than only antitrust litigation. No person-level deal or Aleph allocation is identified.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- picking: Looks for protocols and products that give users custody, portability, and credible exit.
- risk: Treats platform lock-in, speech control, cultural homogenization, and embedded designer bias as systemic risks.
- macro: Competition policy and moral legitimacy shape the technology opportunity set.
- people: Human agency and plural communities matter more than frictionless uniformity.
- portfolio / boards / exits: No construction, governance, or realization evidence is given.
Contradictions, counterevidence, and access limits
- The Tower of Babel metaphor compresses distinct problems—content moderation, antitrust, privacy, interoperability, and market power—into one moral narrative.
- Account and graph portability can also increase spam, fraud, harassment, privacy leakage, and security burdens. The article does not specify standards, liability, or moderation across federated services.
- User-held cryptographic keys create recovery and usability problems; portability does not by itself create viable competitors or solve network effects.
- This is a short opinion essay in an advocacy-oriented outlet. It provides Eisenberg’s position, not measured evidence that scattering would improve welfare.
Open questions
- Which portability layer—identity, content, graph, messaging, payments, or reputation—should be standardized first?
- How would a scattered network preserve moderation, privacy, account recovery, and child safety?
- Did this thesis lead to specific investments, passes, or board positions?
w ילדים זה צמיחה (Children Are Growth)
- URL: https://hashiloach.org.il/issue-25-kkrz-me/ | Published: 2021-06 (issue 25; exact day not exposed) | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: Hebrew webpage paragraph counted from standfirst + footnote roman numeral; English renderings in this note are researcher translations
Takeaways
- Eisenberg responds to proposals that Israel should restrain fertility because population growth strains land and infrastructure. He argues Israel’s high birth rate signals optimism and continuity and should be analyzed as an economic asset rather than only a per-capita denominator (standfirst and body ¶¶1–3).
- His central economic mechanism is more people producing more ideas. Drawing on Charles I. Jones’s declining-population model, he argues that fewer researchers and inventors can eventually slow or stop technological progress; population growth expands labor, demand, specialization, and the pool of innovators (¶¶4–7; footnote iii).
- He contrasts post-1950 population growth of less than fourfold with output growth of more than tenfold and attributes the difference to technological improvement. The claim is that innovation can outpace resource pressure, not that crowding costs never exist (¶¶7–9).
- Japan and Germany are presented as warnings: aging or declining populations weaken housing transactions, baby-related industries, tax receipts, labor supply, output, and innovation while increasing pension pressure and immigration needs (¶¶10–13).
- He explicitly acknowledges Malthusian and Keynesian concerns that population can reduce living standards, but reads the historical charts as showing technology “defeating” the predicted curve (¶13). That is an author inference from aggregate history, not causal identification.
- The policy implication is to build infrastructure and improve productivity for a growing population rather than reduce children to improve per-capita ratios. Family growth is tied to national confidence, investment, and a long-term orientation.
- Under “On Optimism and Innovation,” he turns the demographic argument into a selection rule. Assets labeled safe can conceal the risk that historical patterns will not survive technological change; investors seek breakpoints, acceleration, and levers not yet reflected in prices, so he says he invests in change-oriented ventures (§“על אופטימיות וחדשנות,” ¶¶1–4).
- He treats low Haredi workforce participation and educational gaps as a human-capital problem rather than a fertility problem, pointing to rising internet adoption and comparing potential integration to China’s urban transition and Soviet immigration to Israel. He closes by offering to invest “real cash money” in solutions (§“התשואה החרדית,” ¶¶1–7). The comparisons and prospective return are advocacy, not measured forecasts.
Quotes
- “ילדים הם צמיחה.” (body thesis; researcher translation: children are growth.)
- “שיפורים טכנולוגיים ‘מנצחים’ את שיפוע העקומה החזוי.” (body ¶13; researcher translation: technological improvements beat the projected curve’s slope.)
- “למדתי שיש להשקיע במיזמים מוטי שינוי.” (§“על אופטימיות וחדשנות,” ¶4; researcher translation: I learned to invest in change-oriented ventures.)
Biography and decision evidence
- The essay links Eisenberg’s well-known pro-family and national-development values to his macro view. It is direct philosophical evidence, not a record of a venture decision.
- Its use of a formal growth paper, contemporary journalism, and historical comparisons shows a framework-building habit across economics and culture. The evidence set is selected to defend the thesis and should not be mistaken for a systematic literature review.
- Eisenberg discloses that he is a father of eight and explicitly contrasts an investor’s forward-looking perspective with an academic economist’s analysis (opening ¶2; §“על אופטימיות וחדשנות”). This clarifies standpoint and possible personal bias.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- macro: Demography is treated as an upstream driver of demand, labor supply, invention, fiscal capacity, and national resilience.
- people: Human beings are productive agents and potential innovators, not merely consumption burdens.
- risk: Depopulation creates slow-moving demand, pension, tax-base, and innovation risks; overcrowding and ecological constraints receive less weight.
- picking / portfolio: Supports long-duration bets on infrastructure and services for a growing Israel, but names no investment rule or holding.
- boards / exits: No evidence.
Contradictions, counterevidence, and access limits
- Aggregate GDP can rise while housing affordability, congestion, education quality, emissions, water stress, and GDP per capita worsen. The essay does not model these constraints.
- Correlation between population growth and output does not isolate institutions, capital deepening, trade, women’s labor participation, education, or selection effects. Japan and Germany are not clean counterfactuals for Israel.
- The essay frames births as optimism but does not fully address household income, parental autonomy, childcare burden, or unequal public-service capacity.
- The source is full Hebrew text; English formulations here are researcher translations and should be checked by a fluent editor before quotation.
Open questions
- What fertility path maximizes long-run per-capita welfare under Israel’s housing, water, transport, and education constraints?
- How sensitive is the Jones model to automation, migration, and research productivity rather than headcount?
- Which portfolio sectors did Eisenberg favor because of this demographic thesis?
w Connected Economics — The Threat — Part 1
- URL: https://medium.com/%40mikeeisenberg/connected-economics-the-threat-part-1-d57ada01682f | Published: 2013-01-18 (original; later Medium repost displayed 2015-05-13) | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: section heading + body paragraph counted from first prose paragraph
Takeaways
- Eisenberg presents a five-part macro thesis: the internet is deflationary; labor and employment have become global; connectivity, mobility, and productivity substitute for some labor and commercial real estate; capital is global; and government adjusts too slowly. These are investor-stated premises, not results established by the essay (opening and “Five Premises” list).
- Price comparison, ecommerce, global labor platforms, flexible staffing, mechanization, and software-driven coordination are treated as one connected system. His key investment implication is that scarce, differentiated skills retain pricing power while undifferentiated labor and incumbent intermediaries lose it (“The Internet Is Deflationary,” ¶¶1–7).
- He expects businesses to disaggregate: permanent payroll becomes variable cost, consumers transact directly, and fewer employees coordinate a given amount of output. The suggested beneficiaries are adaptable specialists and global “go-getters”; the suggested losers are middle-management ladders, malls, office landlords, banks exposed to property, and tax authorities dependent on physical activity (“Employment Is Global” and “Connectivity, Mobility and Productivity,” ¶¶1–8).
- Capital is described as jurisdiction-shopping for opportunity, skilled labor, predictable courts, moderate taxes, and light-impact regulation. Israel is therefore framed as a small, unusually changeable state that can compete by moving faster (“Capital Is Global,” ¶¶1–4; closing paragraph).
- The essay records direct policy proximity: Eisenberg says an earlier slide deck was shown to Prime Minister Benjamin Netanyahu and other economic leaders, informed the 2010 Hummus Manifesto, and that he had advised the Ministry of Finance during the preceding 18–24 months (opening ¶¶1–4). That is useful biographical evidence but self-reported, not an official appointment record.
Quotes
- “The internet is massively deflationary.” (“Five Premises,” item 1)
- “If you do not have a unique skill, then you have zero pricing leverage.” (“The Internet Is Deflationary,” ¶5)
- “Capital seeks large opportunity, low impact regulations, moderate tax rates, stable and predictable judicial systems and highly skilled workforces.” (“Capital Is Global,” ¶1)
Biography and decision evidence
- Eisenberg explicitly says he is not an economist and holds a political-science degree. He nevertheless applies US productivity/employment charts to Israel and connects them to policy advice (opening ¶¶3–4). This is evidence of his interdisciplinary, thesis-led process, not an economics credential.
- The essay links his early Israel technology policy work to fears about old-technology layoffs, dependence on Microsoft-era platforms, engineering shortages, and state R&D allocation. It supports a long-running macro-to-venture orientation, but not any specific deal attribution or fund return.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- macro: Treats networked technology as a structural regime change affecting prices, labor, capital, property, banking, and the state together.
- picking / people: Implies preference for globally saleable, differentiated skill and adaptable founders rather than employment-scale narratives.
- risk: Flags second-order balance-sheet risks: ecommerce can impair retail property and consequently lenders and municipal tax bases.
- portfolio / exits: No portfolio construction, position sizing, ownership, exit, or return evidence is supplied.
Contradictions, counterevidence, and access limits
- The essay often infers causality from coincident US chart trends. Productivity/employment decoupling can have multiple drivers, and job destruction in one activity does not establish economy-wide net job loss. No sensitivity analysis or country comparison is provided.
- Applying US data to Israel is an admitted assumption. The effects of immigration, defense spending, education, labor-force participation, local regulation, and the shekel are not isolated.
- The capital-mobility prescription is normative. Low taxes and lighter regulation may attract investment but can trade off against public revenue, worker protection, financial stability, and distribution; those costs are not modeled.
- Surviving access is a later Medium repost. The original blog layout, comments, outbound-link state, and any intervening edits are unavailable.
Open questions
- Which Ministry of Finance advice was adopted, and what measurable outcomes followed?
- How did Eisenberg distinguish labor-replacing from labor-augmenting companies in actual investment memos?
- Did the forecasted commercial-property and bank stress appear in Israel on the timing and scale implied?
w Spreading Wealth Through Covenantal Capitalism
- URL: https://www.etzion.org.il/sites/default/files/2025-01/Eisenberg0053-00721.pdf | Published: 2024 | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: PDF page (1-based) + printed page 53–72 + section heading; DOI 10.54469/3728GBSH2
Takeaways
- Eisenberg rejects the premise that material prosperity is spiritually suspect. He reads biblical abundance as blessing (berakha) and Abraham’s repeated association with property (rekhush) as evidence that wealth creation belongs inside the national moral project (“Wealth is Inherent to Blessing,” PDF pp.2–3 / printed pp.54–55).
- The constraint is covenant. Drawing on Jonathan Sacks, he contrasts a contract’s exchange of interests with a covenant’s loyalty, shared identity, and responsibility for people who may not be signatories. He extends that logic to an economy in which prosperity must build other people’s capability rather than merely transfer consumption (“Contract or Covenant,” PDF pp.4–7 / printed pp.56–59).
- Abraham is the model of “affluence as influence”: his resources support Lot and allies, build cross-group relationships, and propagate values. Modern Israel’s technology, agriculture, health innovation, and Abraham Accords are offered as analogous channels (“Abraham Rises Up in Israel,” PDF pp.8–9 / printed pp.60–61).
- Wix’s training of people from Israel’s socioeconomic periphery is presented as modern pe’ah: trainees gain skills and income, society gains mobility and role models, and Wix gains a long evaluation period and talent pipeline (PDF p.8 / printed p.60). This is an author-selected company example, not an independent program evaluation.
- RiseUp represents a product-level version of covenantal capitalism. Rather than profit when users overdraft, a subscription model and a single cash-remaining signal are designed to align company economics with household financial progress (PDF pp.9–10 / printed pp.61–62).
- He argues for shifting from charity and debt dependence toward investment, ownership, mentorship, and liquidity that increase the recipient’s skills, network, confidence, and asset base. Proposed metrics include year-over-year upward income mobility rather than only a poverty index (PDF pp.14–16 / printed pp.66–68, “We Need New Thinking”).
- The formal synthesis is capitalism with private property, enterprise, and wealth creation, covenanted by duties to empower others and avoid extractive debt. National autonomy makes the model more powerful because Israel can shape policy, not just philanthropy (“Summary and Synopsis,” PDF pp.19–20 / printed pp.71–72).
Quotes
- “Prosperity is power for purpose. His affluence is global influence.” (PDF p.9 / printed p.61)
- “A wealthy nation with prosperous citizens is one that enables other people to gain wealth.” (PDF p.7 / printed p.59)
- “We need more wealthy and self-efficacious people.” (PDF p.15 / printed p.67)
Biography and decision evidence
- Eisenberg says that when he invests he asks for the founder’s and startup’s “genesis story” because it reveals foundational character and idea (PDF p.3 / printed p.55). This is direct process evidence, though it does not show a scoring rubric or decision denominator.
- He describes drafting an alternative prozbul after the shemitta year to take debt cancellation more seriously, receiving mixed public reaction, and working with two religious-court judges (PDF pp.16–17 / printed pp.68–69). It illustrates a willingness to challenge rote institutional practice, but it is self-reported.
- Wix and RiseUp are used as examples of the worldview. Their appearance does not by itself establish Eisenberg’s personal sourcing, board contribution, investment vehicle, or financial result.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- picking: Prefers business models whose revenue grows when customers become more capable, prosperous, or trusted.
- people: Founder origin stories, dignity, mentorship, and self-efficacy are core underwriting lenses.
- macro: Wants mobility, credit, training, tax incentives, and innovation measured as national covenantal infrastructure.
- risk: Treats extractive consumer credit and prosperity without obligation as moral and systemic risks.
- portfolio / boards / exits: Provides mission filters, not fund construction, governance attribution, or return evidence.
Contradictions, counterevidence, and access limits
- This is a formal but normative journal essay, not an empirical study. The Wix and RiseUp cases are favorable selections, and no counterexamples or measured treatment effects are presented.
- Aligning a subscription business with user welfare reduces one conflict but does not eliminate pricing, privacy, efficacy, exclusion, or retention risks.
- The essay’s critique of existing religious/legal practice, consumer credit, and diaspora paradigms is broad. Specialists may dispute both textual interpretation and policy feasibility.
- Claims about Israeli military ethics and international economic influence are contested political assertions beyond the investment evidence and require independent controls.
Open questions
- How would covenantal alignment be measured in diligence, board reporting, and executive compensation?
- What happens when customer empowerment lowers near-term revenue or conflicts with LP return duties?
- Are Wix training and RiseUp outcomes independently measured, and what are their counterfactuals?
w DooHickeys and MeTooHickeys
- URL: https://medium.com/%40mikeeisenberg/doohickeys-and-metoohickeys-e58e8cd89247 | Published: 2006-09-18 (original; Medium repost 2015-04-24) | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: body paragraph counted from opening Kevin Maney reference + original-date footer
Takeaways
- Using Kevin Maney’s description of the Web 2.0 widget glut, Eisenberg separates a good small business from a venture-scale investment. Cheap software creation can enable a founder to earn a good living without making the company capable of returning a venture fund (body ¶¶1–8).
- He sees the same “me-too” pattern in mobile apps: founders cite rising adoption acronyms and vast populations, yet offerings blur together. Trend participation is therefore not differentiation (¶¶4–5).
- Lower startup cost is double-edged. It expands entrepreneurship and makes bootstrapped niche businesses viable, but it also lowers entry barriers and produces a crowded field in which indiscriminate VC financing can put “a lot of money in the ground” (¶¶6–9).
- His prescription is explicit fund-fit discipline: use savings for a small web utility, reserve venture capital and its pressure for opportunities capable of becoming large public companies, and avoid a weak IPO rush that could recreate the Pets.com-era market washout (¶¶9–11).
- This is a selection heuristic, not a result set. The essay names no complete cohort of funded and rejected companies and supplies no subsequent outcome test.
Quotes
- “The web doohickey world is the corner grocery of this century.” (body ¶9)
- “We should keep the venture capital focused on the really big opportunities.” (body ¶9)
- “Take $17 from your savings account. Don’t raise $17,000,000!” (body ¶9)
Biography and decision evidence
- The essay is contemporaneous Benchmark-era direct voice. Eisenberg identifies Benchmark companies Second Life and eBay as platforms on which small entrepreneurs could build, but this does not attribute either underlying investment to him personally.
- The distinction anticipates his later focus on market size and venture-scale outcomes. It is evidence of stated screening logic, not evidence that every portfolio decision followed it.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- picking: Requires differentiation and a plausible public-company-scale outcome; a viable product and favorable trend are insufficient.
- portfolio / exits: Connects check size and financing pressure to the exit scale the company must support.
- risk: Treats cheap creation, category imitation, and an overheated funding market as correlated crowding risk.
- people: Offers founders a fit test: bootstrapping may be better than accepting institutional capital.
- boards: No governance practice appears.
Contradictions, counterevidence, and access limits
- “Public-company scale” is asserted rather than quantified. Some initially small utilities can compound or become strategic acquisitions; the essay does not describe how to detect that optionality.
- The argument can encourage false precision about eventual scale at a stage when markets are emergent. It does not address portfolio learning, staged financing, or capital-efficient venture outcomes below IPO scale.
- References to Second Life and eBay are labeled as Benchmark companies on the repost, but firm association must not be converted into personal sourcing or economics.
- The Medium page is a later repost. Original outbound links, comments, and possible formatting are not preserved.
Open questions
- Which 2006 mobile and Web 2.0 proposals did Eisenberg pass on under this rule, and how did they fare?
- What market-size or return threshold converted “small business” into “venture scale” for his fund at the time?
- Did later investments in platform-dependent products change this view?
w Why We Decided to Drink the Lemonade
- URL: https://www.aleph.vc/content/why-we-decided-to-drink-the-lemonade | Published: 2015-12-09 | Format: essay | Reliability: A | Access: partial | Accessed: 2026-08-22 | Locator scheme: byline/date block and one publisher-visible opening paragraph
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- The stable Aleph page verifies Michael A. Eisenberg as author, the December 9, 2015 date, and one opening paragraph. It does not expose the later Team, Mission, Moats, Market, or Stage sections.
- The recoverable argument is a power-law premise: venture capital is an outlier business in which a small number of companies and firms return most of the capital. This explains why one exceptional outcome can dominate a fund, but it does not by itself explain the Lemonade decision. Opening paragraph
- Facebook, Google, and Twitter are used as examples, followed by a claim that one company can account for 30% of annual venture returns. The page supplies no calculation, year, or underlying dataset, so the percentage is investor-stated rather than verified.
- The title confirms that the essay concerns an Aleph investment decision. The stable text does not support claims about founder selection, mission, moat, market, check size, stage exception, ownership, or results.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “Venture Capital is an aberration business.” — canonical page, opening sentence.
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The signed page places Eisenberg at Aleph in 2015 and shows him publicly framing a firm investment through power-law venture economics.
- The title uses a collective decision frame. Without the unavailable body or closing records, it does not allocate the decision among Eisenberg, Eden Shochat, other Aleph partners, or a legal vehicle.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- portfolio: venture outcomes are expected to be highly concentrated in a few outliers.
- risk / exits: a headline power law does not replace company-level underwriting, ownership, dilution, or realization evidence.
- sourcing / picking / people / boards / macro: not analyzable from the recoverable paragraph.
Contradictions, counterevidence, and access limits
- The canonical Aleph page exposes only the opening paragraph and a Read full article link; the linked Medium body returned 403. Earlier search-index text was not treated as a stable full source, and its article-wide claims and quotations were removed.
- The 30% annual-return claim is unsourced on the visible page and must not be reused as a verified statistic. The named platform examples are selected winners, not a denominator.
- No investment amount, ownership, return, board role, product evidence, or adverse case is available in the recoverable text.
Open questions
- Can Aleph or Medium provide a lawful full publisher capture with the named sections and stable locators?
- What contemporaneous memo, terms, ownership, and decision record support the Lemonade investment?
- What dataset supports the claimed annual return concentration?
w The ONLY 8 Things That Matter for Israel's Venture Capital Industry
- URL: https://medium.com/%40mikeeisenberg/the-only-8-things-that-matter-for-israel-s-venture-capital-industry-e88a1f09b97e | Published: 2012-07-19 (Medium repost 2015-05-13) | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: article-body paragraphs, alphabetical company list, dated additions, disclosure, and original-date footer
Takeaways
- Eisenberg rejects debate over quarterly capital supply and investor-founder rhetoric as secondary. His outcome test is whether Israel's mature venture industry can build large companies and large exits; small acquisitions generally cannot satisfy venture-fund return math.
- He does not advocate a single Nokia-like national champion. He wants multiple companies comparable in scale to Check Point, Mellanox, Galileo, and Shopping.com, so ecosystem and fund performance are not dependent on one employer.
- The initial “unscientific” screen requires venture backing and revenue believed or known to be in the tens of millions of dollars. It yields Conduit, FiftyOne, InstallCore, Kenshoo, LiveU, Outbrain, Panaya, and Wix; later dated additions add CyberArk, Forescout, SolarEdge, and Lumus.
- He separately lists large non-venture-backed companies because they matter to the ecosystem but not to venture-fund returns. That distinction is an important attribution boundary: company scale is not the same thing as venture performance.
- Healthcare is excluded because Eisenberg says he lacks sector knowledge. The admission narrows the domain, but it also means the list cannot serve as a complete denominator for Israeli venture-scale companies.
- The usable decision rule is to start with revenue scale and plausible exit magnitude, then trace venture ownership and fund math. A company can be important nationally while irrelevant to venture returns if venture funds did not own it.
Quotes
- “Israel’s now mature venture industry and funds will be judged by only one thing: Can it/we build large companies and exits?” — canonical essay, central test paragraph.
Biography and decision evidence
- Eisenberg discloses that he was a Benchmark partner. Asterisks associate Benchmark with Conduit, Panaya, and Wix; the list does not state that he personally sourced, led, owned, or realized each investment.
- Ronen Shilo is cited as supporting the large-outcome criterion, but the article remains Eisenberg's unscientific list rather than a joint Benchmark memo.
- The piece is contemporaneous Benchmark-era evidence of his scale filter. It is not a portfolio denominator because it intentionally omits healthcare, early companies, failures, nonrevenue candidates, and firms outside the author's knowledge.
Philosophy signals
- Exits: require an outcome large enough to work in venture-fund math; national visibility or M&A count is not enough.
- Picking: use meaningful revenue and venture backing as an initial scale screen, while recognizing that revenue alone does not establish margins, growth, ownership, or exit value.
- Portfolio: seek several independent large-company candidates rather than one national champion.
- Risk: separate ecosystem importance, company success, and fund return; each has a different denominator and ownership requirement.
Contradictions, counterevidence, and access limits
- Despite the title, later additions expand the eight-company list to twelve. That makes the article a changing watchlist rather than a fixed prediction set.
- The author says he “assume[s] or know[s]” companies have tens of millions in revenue. Assumption and knowledge are not separated company by company, and none of the revenue figures is documented here.
- A large exit does not automatically generate a large fund return; entry price, ownership, follow-ons, dilution, preferences, fees, recycling, and realization timing are absent.
- Several company and investor labels can change through merger, rename, or later financing. The list is a July 2012 snapshot with later July additions, not a current status table.
Open questions
- For each of the twelve named companies, what revenue evidence was available by the relevant July 2012 date?
- Which firms produced realized cash returns large enough to meet the stated venture-fund test, by legal vehicle?
- Why were the four additions absent initially, and does the change reflect new evidence or an unstable selection process?
- What companies would enter the denominator if healthcare, failures, and ordinary outcomes were included?
w We All Need More Empathy in Our Lives and Deaths
- URL: https://medium.com/aleph-vc/we-all-need-more-empathy-in-our-lives-and-deaths-c4ffc2b8888f | Published: 2021-04-07 | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: subtitle and Medium body paragraphs counted from the founder-image caption; no publisher-stable paragraph numbers
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Central argument — [investor-stated | strong]: technology should reduce the administrative and emotional burden on bereaved families; a company embodying empathy can create customer value and a large brand while advancing Eisenberg’s broader “values create value” and “Long Humanity” theses. Body paragraphs 1–8
- Problem definition — [investor-stated | moderate]: end-of-life conversations are difficult, bereaved families can be isolated, and forms, bureaucracy, painful encounters, and financial stress arrive at their most vulnerable moment. The article diagnoses a service gap but provides no prevalence, willingness-to-pay, or market-size evidence. Body paragraphs 3–4
- Solution mechanism — [investor-stated | provisional]: software can organize burdensome tasks and amplify, rather than replace, human care. The thesis depends on the product expressing the same values promised by the founders; no outcome or customer evidence appears in this launch essay. Body paragraphs 4–7
- Founder selection — [investor-stated | strong]: Eisenberg had known Ron Gura for more than a decade and Yon Bergman for years; Gura’s Gifts Project/eBay/WeWork experience and time as an Aleph EIR were evidence of scaling and human-problem orientation. The desire to work together predated the company. Body paragraphs 5–7
- Decision rule — [investor-stated | moderate]: in emotionally sensitive markets, founder conduct and mission-product congruence are part of product risk, not decorative culture. This is a clear selection rule, though the essay does not describe diligence that could falsify claimed empathy. Body paragraphs 6–8
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “In the 21st century, values create value.” — body paragraph 1. Source
- “Loss shouldn’t be as complicated as it is.” — body paragraph 6. Source
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- Gura had discussed end-of-life technology with Eisenberg over the preceding couple of years, showing idea development before the 2021 announcement. Body paragraph 3
- The source identifies Gura as a former Aleph EIR, founder of The Gifts Project, eBay leader after its acquisition, and WeWork scaler; those are Eisenberg’s descriptions and should be independently checked in the final biography. Body paragraph 5
- Yon Bergman is a cofounder whom Eisenberg says he had known and admired for years, but the essay provides less biographical or diligence detail for Bergman than for Gura. Body paragraph 7
- “We are thrilled to partner” establishes Aleph participation but gives no check size, stage, allocation, ownership, board role, or partner decision rights. Body paragraph 7
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- sourcing / people — [investor-stated | strong]: maintain relationships with prior founders/EIRs and let important problems mature through repeated discussion before company formation. Body paragraphs 3–7
- picking — [investor-stated | moderate]: require mission-product-founder alignment where trust and vulnerability are central to adoption. Body paragraphs 5–8
- risk — [researcher inference | provisional]: because values claims are hard to observe ex ante, diligence should test privacy, pricing, service failures, claims handling, and treatment of vulnerable users; none is described in the essay.
- portfolio — [investor-stated | provisional]: extend the Long Humanity theme from community and care into death administration; thesis continuity is documented, economic contribution is not. Opening and closing
Contradictions, counterevidence, and access limits
- “Values create value” can be circular when founder values are inferred from a product marketed around those values. Independent customer outcomes and conduct under stress are needed.
- Long personal relationships provide behavioral evidence but create familiarity and attribution risk. The note exposes no rejected concerns, market tests, or competing teams.
- The company is described as both relieving grief and building a large business/brand; the essay does not address the pricing, data, or sales practices required to keep those aims aligned.
- This is an ex-ante investment announcement with no customer metrics, financials, regulatory analysis, portfolio economics, or later outcome control.
- Medium was fully readable, but it offers no stable paragraph IDs; paragraph-count locators should be rechecked after publisher edits.
Open questions
- What product, privacy, and customer-service evidence did Aleph require before investing in a bereavement platform?
- How did Empathy validate willingness to pay without exploiting crisis-driven urgency, and who is the economic buyer?
- What later evidence would show that empathy is an operating moat rather than positioning?
- How were deal credit and governance responsibility divided among Eisenberg, Aleph partners, Gura, Bergman, and later investors?
w Parashat Ki Tisa — The Golden Calf and Venture Capital Investments
- URL: https://medium.com/%40mikeeisenberg/parashat-ki-tisa-the-golden-calf-and-venture-capital-investments-ae846aaf83f9 | Published: 2022-02-17 | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: body paragraph counted from first paragraph after title
Takeaways
- Eisenberg interprets the placement of Shabbat immediately before the golden-calf episode as a lesson in patience. The Israelites pay with jewelry for an immediate, tangible answer because they cannot tolerate Moses’s delay and uncertainty; Shabbat requires stopping and letting processes mature (body ¶¶1–6).
- He maps this to early-stage venture, where sales, gross margin, and growth histories are too immature for later-stage modeling. Investors must allow technology, regulation, markets, and leaders to develop while still adjusting strategy toward long-term objectives (¶¶7–8).
- Healthy.io is the technology-and-regulation case. Eisenberg says early product iterations failed partly because smartphone cameras lacked sufficient resolution; the company persisted until cameras and regulatory acceptance caught up (¶¶9–10).
- Seeking Alpha is the capital-discipline case. He calls it his first Benchmark investment, says growth stayed slow after the 2006 investment and accelerated roughly fourteen years later after business-model changes and greater mobile use; founder David Jackson is credited with steady focus and careful capital management rather than “spray and pray” spending (¶¶11–12).
- These two selected retrospectives show what Eisenberg means by patience, but they do not establish a base rate. The essay gives no comparison with patient companies that failed or impatient companies that succeeded.
Quotes
- “We cannot microwave everything.” (body ¶6)
- “Venture capital lacks such inputs.” (body ¶7)
- “Play the long game.” (closing paragraph)
Biography and decision evidence
- Eisenberg directly attributes the 2006 Seeking Alpha investment to himself while at Benchmark and describes it as his first investment there (body ¶11). This is person-level testimony, although check size, vehicle, ownership, and returns remain undisclosed.
- He also says he invested in Healthy.io, but the essay does not specify whether this was through Aleph, another vehicle, or personal capital. Vehicle attribution must remain open absent the closing record.
- The cases reveal a willingness to wait through non-working iterations and slow growth when the core thesis and founder discipline persist.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- picking / people: Selects for founder conviction, persistence, and capital stewardship under uncertainty.
- risk: Distinguishes uncertainty from measurable later-stage risk; seeks thesis durability rather than premature certainty.
- portfolio: Implies patient reserves and long holding periods but supplies no follow-on or concentration policy.
- macro: Technology and regulatory readiness can be external timing gates.
- boards / exits: No board intervention or realized-return evidence is supplied.
Contradictions, counterevidence, and access limits
- The golden-calf analogy moralizes impatience and may obscure legitimate stop-loss decisions. Waiting can preserve a breakthrough or prolong a weak thesis; the essay gives no disconfirming thresholds.
- Healthy.io’s claim that the long wait “now saves lives” is promotional and not supported here by clinical-outcome evidence.
- Seeking Alpha’s acceleration is attributed to patience, business-model change, and mobile adoption without disentangling their effects. Subscriber and return figures are absent.
- Both examples are survivorship-selected and retrospective. The full essay is readable, but linked supporting records are not part of the note.
Open questions
- What milestones, budgets, and kill criteria governed follow-on decisions in each company?
- Which patient investments failed, and how did Eisenberg distinguish persistence from escalation of commitment?
- What were the vehicles, ownership stakes, cash flows, and realized or unrealized outcomes?
w The Hummus Manifesto — Part 1
- URL: https://medium.com/%40mikeeisenberg/the-hummus-manifesto-part-1-a95bce2803be | Published: 2010-07-12 (Medium repost 2015-05-05) | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: named headings, article-body paragraphs, and original-date footer
Takeaways
- Part 1 argues that Israel's innovation bottleneck is not simply a shortage of startups or liquidity. Too many tiny companies scatter scarce engineering and product talent, while older institutional technology choices train workers on stacks that are losing relevance to open-source, web-scale, cloud, and mobile systems.
- The causal chain is explicit: two-person startup formation and equity expectations pull engineers away from scaling firms; successful firms cannot hire people who have built large systems; government and military reliance on Microsoft/.NET reinforces yesterday's skills; Israel then lacks the architecture and operations experience required for internet-scale companies.
- Eisenberg supports the argument with observations from Conduit and Wix, comments attributed to a Wix executive and former partner Sigal Widman, and an anecdote involving a Google engineer. These are practitioner signals, not a representative labor-market dataset.
- The Lavi fighter program and Yozma are used as historical examples of focused national projects that created technical talent and an investing ecosystem. The historical examples motivate intervention but do not by themselves prove that a new program would reproduce the spillovers.
- He distinguishes startup quantity from scale capacity. The operating metric should be the concentration of current technical skills inside companies capable of becoming large, not the number of seed projects launched.
- A usable diligence rule follows: map the target company's stack, senior scale experience, recruiting competition, and ability to retain talent; do not infer ecosystem strength from formation or funding counts alone.
Quotes
- “This is scattering our talent and preventing our more successful and growing startups from finding and hiring the talent they need.” — canonical essay, “We have a dearth of talent,” paragraph 3.
Biography and decision evidence
- The essay comes from Eisenberg's Benchmark period and identifies Conduit and Wix as portfolio companies. That phrasing establishes a portfolio relationship in his working context, not sole sourcing, ownership, or the responsible legal vehicle for every round.
- Sigal Widman is described as a former partner; her observation is evidence cited by Eisenberg, not necessarily his independent measurement.
- The article shows an investor using portfolio-company hiring problems to construct a national policy thesis. It does not show which investment, pass, or reserve decision changed as a result.
Philosophy signals
- People: scarce senior engineers with web-scale experience are a strategic asset; founder abundance can impose a talent-allocation cost.
- Picking: test whether a company can aggregate exceptional talent and build on current infrastructure rather than merely launch a feature.
- Risk: obsolete stacks, missing scale experience, and fragmented teams can dominate financing availability.
- Macro: military procurement, government systems, immigration, and national projects shape the venture labor pool.
Contradictions, counterevidence, and access limits
- The broad claims about .NET, open source, and national skill deficits rest on selected examples and the author's observations. No comparative hiring, wage, stack-adoption, or company-survival data are presented.
- Encouraging talented engineers to join scaling companies may improve scale outcomes while reducing experimentation and new-company option value; the essay does not model that tradeoff.
- Later Israeli successes using varied stacks could weaken the technology-specific diagnosis without disproving the broader complement/talent argument.
- This is a surviving Medium repost. The original Blogspot route and comments are unavailable, so contemporaneous edits and audience counterarguments cannot be checked.
Open questions
- What contemporaneous hiring data would confirm the claimed shortage and its causes?
- Which Conduit and Wix roles remained unfilled, for how long, and with what operating consequence?
- How did Eisenberg decide when an engineer should found a company versus join a scaling one?
- Which later portfolio outcomes support or falsify the stack and talent-concentration thesis?
w The Hummus Manifesto — Part 2
- URL: https://medium.com/%40mikeeisenberg/the-hummus-manifesto-part-2-b936e697c7ad | Published: 2010-07-14 (Medium repost 2015-05-05) | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: named headings, article-body paragraphs, and original-date footer
Takeaways
- Part 2 distinguishes strategic public investment that creates capabilities from diffuse grants that preserve existing firms or jobs. Eisenberg favors a few large, disruptive national bets and rejects spreading money across projects already rejected by private capital or across incumbents protecting employment.
- His market-signal reasoning is that indiscriminate Office of the Chief Scientist support can select against quality: entrepreneurs accept strings and bureaucracy; private investors' rejection signal is muted; resources remain in weaker activities; and job preservation displaces new-company formation and capability building.
- He says he and colleagues advised portfolio CEOs not to take Chief Scientist money, with one exception involving a company before he joined its board. He also acknowledges that capital-intensive technologies can justify public support, so the rule is not “no state funding” but “fund shared disruptive capability, not routine operating survival.”
- The second mechanism is anchor-company skill formation. Earlier multinationals such as National Semiconductor, Microsoft, Intel, and Motorola trained workers, but Israel had not attracted the newer Facebook, Amazon, Google, Salesforce, and Chinese technology companies he saw as the next training grounds.
- A third mechanism concerns venture structure: dedicated Israel funds were drying up because managers doubted the number of venture-scale opportunities, while Israel lacked enough late-stage capital and expertise. He proposes a Yozma-like effort to import foreign late-stage investors and company-scaling knowledge.
- The decision rule is to evaluate public capital by additional capability created, not dollars or jobs preserved; evaluate foreign investment by learning spillovers; and distinguish early capital supply from the late-stage expertise needed to build large companies.
Quotes
- “It is a job preservation strategy rather than a job creation strategy.” — canonical essay, government-funding discussion.
Biography and decision evidence
- The source provides a direct, contemporaneous account of advice to CEOs about Chief Scientist funding. It does not name the companies, state whether the boards adopted the advice, or quantify the resulting financing and outcomes.
- Eisenberg includes his own firm among venture organizations reconsidering dedicated Israel funds. At the time this is a Benchmark-context statement; it must not be attributed to later Aleph vehicles.
- The essay documents his 2010 view that Israel faced a venture-scale opportunity and late-stage expertise gap. It is not an audited description of Benchmark's fund returns or allocation.
Philosophy signals
- Macro: prefer concentrated public investment in shared capabilities and modern anchor institutions over diffuse firm subsidy.
- Picking: take private-market rejection seriously, while making explicit exceptions for capital-intensive technologies and public-good spillovers.
- Risk: government strings, adverse selection, employment preservation, and missing late-stage skill can suppress venture-scale outcomes.
- Portfolio: early-stage capital and late-stage scale capital solve different problems and should not be counted as interchangeable supply.
Contradictions, counterevidence, and access limits
- Eisenberg argues for substantial state coordination while warning that officials lack technical judgment and that grants distort selection. Part 3 proposes an institution intended to resolve that tension, but its effectiveness is assumed rather than demonstrated.
- The advice against Chief Scientist funding comes from a venture investor whose preferred financing may compete with subsidized capital. The essay discloses the position but provides no counterfactual cohort of recipients and nonrecipients.
- Claims about annual venture-scale opportunity of roughly $250–$500 million and capital drying up are author estimates, not a full deal census or LP cash-flow record.
- The multinational-company list treats local presence as a training mechanism without measuring retention, spillovers, or displacement.
Open questions
- Which portfolio companies rejected Chief Scientist support on this advice, and what happened relative to comparable recipients?
- What program design would preserve useful capital-intensive exceptions without creating the adverse selection he describes?
- Which foreign late-stage investors entered Israel, and did they transfer the predicted expertise?
- How did the dedicated-fund pessimism evolve into Aleph's 2013 Israel-focused formation thesis?
w The Hummus Manifesto — Part 3
- URL: https://medium.com/%40mikeeisenberg/the-hummus-manifesto-part-3-36715d526f57 | Published: 2010-09-06 (Medium repost 2015-05-05) | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: named headings, numbered principles, article-body paragraphs, and original-date footer
Takeaways
- Part 3 turns the first two essays' diagnosis into an institutional proposal. Israel should choose a few sectors in which it can be globally distinctive, build decision machinery insulated from short political cycles, and connect economic growth to employment, social cohesion, Jewish purpose, and broadly shared benefit.
- Eisenberg proposes a cabinet-level Chief Investment Officer coordinating the Chief Scientist, military technology, science, and university budgets over a six-to-ten-year term. Government would create infrastructure and focused capability; entrepreneurs and private investors would choose and scale the companies.
- The sector cases are clean energy, cloud computing, and agriculture. For clean energy he proposes a national demonstration city and research/manufacturing cluster; for cloud he proposes attracting Amazon or Google infrastructure and retraining government/army systems toward cloud and open source; for agriculture he proposes a roughly $500 million commitment around food and water technology.
- The mechanism is clustering: a visible national challenge attracts foreign anchors, suppliers, researchers, workers, and founders; repeated collaboration creates expertise; private companies capture opportunities while the public gains employment and strategic capability.
- He expressly separates national benefit from the success of any one company when discussing Better Place. The company might fail, yet the supporting talent and infrastructure could still produce spillovers. That is a testable portfolio/ecosystem distinction, not proof that spillovers occurred.
- The operating rule is to define a limited number of measurable national capability goals, assign long-tenure accountable leadership, fund shared infrastructure, and leave company selection to competitive private actors.
Quotes
- “We need to focus on a scant few areas and place some bets with massive budgets.” — canonical essay, “Vision and Decision,” framework paragraph.
Biography and decision evidence
- Eisenberg identifies himself as an immigrant from New York when discussing Israel's appeal to global talent. That is direct autobiographical evidence, though it gives no date for his move.
- The essay shows his investment thinking embedded in a civic and Jewish moral framework: economic policy should bind society and enable people to do well while doing good. It does not show a portfolio-screening score or return tradeoff derived from that value.
- References to specific sectors and companies are policy examples, not proof of a personal investment or board role.
Philosophy signals
- Macro: build clusters through focused infrastructure, foreign anchors, universities, defense technology, and accountable long-horizon coordination.
- Picking: let private actors select companies inside publicly enabled capabilities rather than have government pick individual firms.
- Risk: policy diffusion, election-cycle turnover, capture, corruption, and missing technical accountability can dissipate public capital.
- People: attract immigrants and foreign expertise, retrain existing workers, and use scale projects as talent factories.
Contradictions, counterevidence, and access limits
- The proposed CIO concentrates power even as the essay acknowledges that state intervention has few clear successes and creates corruption risk. Long tenure may improve continuity while weakening democratic correction or increasing capture.
- Part 3 warns against dependence on a single Nokia-style national champion, yet its cluster proposals rely heavily on a few anchor firms. The intended distinction is platform spillover rather than champion protection, but execution could collapse that boundary.
- Sector budgets, timelines, employment benefits, and spillover mechanisms are proposals. The article provides no cost-benefit model, governance controls, baseline, or later scorecard.
- Better Place is used prospectively and with explicit uncertainty. Its later outcome cannot be treated as evidence from this 2010 text without a separate dated source.
Open questions
- Was any CIO-like institution created, and what authority, tenure, budget, and audit regime did it receive?
- Which proposed clean-energy, cloud, or agriculture projects were funded, and against what measurable baseline?
- Did foreign anchors generate enduring local IP and talent spillovers or primarily consume subsidy?
- How does Eisenberg reconcile long-horizon technocratic authority with corruption, capture, and democratic accountability?
w Hummus Manifesto Part 4 — It's Amazon Stupid!
- URL: https://medium.com/%40mikeeisenberg/hummus-manifesto-part-4-it-s-amazon-stupid-e20763aad70 | Published: 2011-10-04 (Medium repost 2015-05-11) | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: article-body paragraph sequence and original-date footer
Takeaways
- Part 4 converts the cloud-cluster proposal into a company-specific policy preference: if Israel is debating a large incentive for Intel, it should compare that opportunity with attracting Amazon's cloud, device, media, marketplace, and logistics platform.
- Eisenberg's reasoning is based on adjacent capability. Amazon would not only operate infrastructure; it could train cloud engineers, stimulate digital media and applications, improve logistics and food distribution, and expose local firms to a growing platform. The policy unit is therefore the spillover network, not the facility alone.
- The Intel comparison is technological and forward-looking: he argues that ARM and mobile architectures threaten incumbent processor economics, whereas Amazon sits at the center of cloud, distribution, and digital consumption. The essay does not quantify either company's expected subsidy, employment, tax, or supplier effects.
- The proposal mixes national capability and cost-of-living policy. Better distribution is expected to lower food costs, while cloud infrastructure is expected to improve startup formation and engineering skills.
- The actionable rule is to rank anchor-company incentives by the breadth, durability, and strategic direction of local spillovers rather than by capital expenditure or immediate jobs alone.
Quotes
- “Bringing Amazon to Israel would immediately make us a player in cloud computing.” — canonical essay, Amazon-platform argument.
Biography and decision evidence
- This 2011 essay is public policy advocacy from Eisenberg's Benchmark period. It is not evidence that Benchmark invested in Amazon, Intel, or an Israeli infrastructure project.
- The piece shows how he evaluates platform adjacencies and opportunity cost at an ecosystem level. It does not identify a private-company diligence process or realized venture result.
Philosophy signals
- Macro: compare industrial-policy options by platform spillovers, future technology direction, talent formation, logistics, and consumer benefits.
- Picking: favor platforms that enable many downstream businesses over facilities whose local learning effects may be narrower.
- Risk: incumbent capital expenditure can look safe while the architecture shifts elsewhere; policy evaluation should be forward-looking.
- People: engineer training and repeated exposure to a modern platform are treated as durable assets.
Contradictions, counterevidence, and access limits
- Part 3 resists a one-company national champion, while Part 4 centers Amazon. The plausible reconciliation is that Amazon is an enabling platform rather than a protected champion, but reliance on one foreign firm still creates bargaining and concentration risk.
- “Immediately” overstates how quickly data centers, training, supplier formation, or marketplace access translate into national capability. No implementation timeline or counterfactual is provided.
- Claims about Intel's architectural threat and Amazon's prospective food-distribution effects are author forecasts, not a comparative economic study.
- This is a surviving repost; the original Blogspot discussion and any contemporaneous rebuttals are not available.
Open questions
- What incentives did Israel ultimately offer Amazon and Intel, and what local capabilities resulted?
- Did AWS presence measurably change Israeli startup costs, talent, or cloud adoption relative to comparable ecosystems?
- How should government price dependency and bargaining risk when the desired anchor is a dominant foreign platform?
- Which forecast was more accurate: declining strategic spillover from incumbent semiconductor manufacturing or broad spillover from Amazon?
w Incorporate in Israel or Delaware?
- URL: https://www.aleph.vc/content/incorporate-in-israel-or-delaware | Published: 2024-03-05 | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: article-body paragraph sequence by opening words
Takeaways
- Eisenberg's default advice is Israeli incorporation. His reasoning combines operating simplicity, Israel's Section 102 employee-option regime, an assertedly founder-friendly legal environment, access to regional trade, and the national benefit of retaining tax base and intellectual property.
- The recommendation is conditional rather than absolute: a company with a concrete regulatory reason may still need a US entity. He frames domicile as a strategic choice with operating, governance, financing, employee, and national-externality consequences—not merely a tax optimization.
- He invokes the Delaware Chancery Court ruling on Elon Musk's compensation as evidence that Delaware governance may need reform. That is an illustrative case, not a comparative study of Delaware and Israeli corporate law.
- He also discusses a proposed Israeli government program to match roughly $1 billion of institutional investment in Israeli high tech. Although he opposes the intervention as potentially anti-Darwinian and risky for pension capital, he argues that, if adopted, 90% should go to Israeli-incorporated companies so the public captures tax and IP benefits.
- The reasoning chain is: domicile affects where legal rights, payroll, tax, and IP reside; public support should buy domestic spillovers; therefore state-backed capital should not subsidize foreign-incorporated structures absent a regulatory necessity.
- The operating rule is to ask counsel for a specific regulatory or commercial reason to use Delaware. If none survives scrutiny, default to Israel. The article is advocacy, not individualized legal, tax, or fiduciary advice.
Quotes
- “Unless you have a regulatory reason to incorporate in the US, I highly recommend you incorporate your company here in Israel.” — canonical essay, final paragraph.
Biography and decision evidence
- Eisenberg says he had invested in Israeli startups for more than 25 years and had consistently favored Israeli incorporation. This is a self-reported policy preference, not a reconstructed denominator of portfolio domiciles or exceptions.
- The essay is an Aleph-era founder-advice document. “We” statements about investment and advocacy should remain attributable to the author/firm context rather than to every Aleph partner or vehicle.
- His opposition to the matching program, followed by a proposed condition if government proceeds, shows a pragmatic distinction between preferred policy and implementation under a policy he does not control.
Philosophy signals
- Picking: treat legal domicile as part of the company design and test whether a claimed Delaware need is concrete rather than customary.
- Risk: include governance forum, employee options, tax/IP location, regulation, and political durability in structural diligence.
- People: the advice asks founders to resist reflexive advisor convention and own the incorporation tradeoff.
- Macro: domestic incorporation is presented as a channel through which venture activity can strengthen Israeli institutions and public finances.
Contradictions, counterevidence, and access limits
- The author is both a venture investor and a national-policy advocate; the national-interest recommendation may not match every founder's financing, tax, exit, or fiduciary constraints.
- He criticizes state matching as distorting market selection but then proposes a strong domicile condition on that same capital. This is internally coherent as second-best policy design, yet it remains a material tension between market selection and industrial policy.
- The Musk ruling, Section 102 advantages, regional-market access, and proposed matching-program terms are presented by the author and were not independently re-litigated or updated in this source note. Corporate, tax, and funding rules can change after publication.
- The article gives no outcome comparison between otherwise similar Israeli and Delaware companies and no denominator for his claimed historical preference.
Open questions
- How many Eisenberg-backed companies incorporated in Israel versus Delaware, and what stated exception applied in each Delaware case?
- Did the matching program take effect on the terms described, and was any 90% Israeli-domicile condition adopted?
- Which specific regulatory regimes would qualify as a sufficient US-incorporation reason?
- How did counsel, founders, and LP obligations alter this advice in actual Aleph investment decisions?
w LMND — Aleph’s First IPO
- URL: https://www.aleph.vc/content/lmnd----alephs-first-ipo | Published: 2020-07-02 | Format: essay | Reliability: A | Access: partial | Accessed: 2026-08-22 | Locator scheme: byline/date block, title, and one publisher-visible opening paragraph
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- The stable page verifies Eisenberg’s byline, the July 2, 2020 date, and the title’s description of Lemonade as Aleph’s first IPO. The article body beyond its opening paragraph is not recoverable from the canonical shell.
- In the visible paragraph, Eisenberg recalls that he and Eden Shochat told prospective LPs seven years earlier that Aleph wanted remarkable entrepreneurs capable of building large, meaningful global brands and businesses. Opening paragraph
- The same paragraph says their original pitch anticipated meaningful industry change driven by machine learning, machine vision, and big data. This is a 2020 retrospective account of a 2013 pitch, not the original LP document.
- The visible text does not establish that Lemonade validated the thesis, explain the company’s product or economics, or prove a realized Aleph return. The IPO description in the title is a firm milestone, not a cash-flow ledger.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “We wanted to invest in remarkable entrepreneurs.” — canonical page, opening paragraph.
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- Eisenberg explicitly joins Eden Shochat in the recalled Aleph I fundraising pitch. That supports co-founder attribution and argues against treating the original mandate as Eisenberg’s sole design.
- Aleph’s first IPO is a firm/vehicle-level label. The page does not disclose partner allocation, board role, cost basis, ownership, dilution, lockup, sales, or realized proceeds.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- people / picking: seek remarkable founders with ambition to build large, meaningful global businesses.
- macro: machine learning, machine vision, and data were presented as broad industry-change drivers.
- exits: an IPO is visible in the title, but no liquidity or return rule is recoverable from the opening.
- portfolio / boards / risk: not analyzable from the stable text.
Contradictions, counterevidence, and access limits
- The canonical shell exposes one opening paragraph and links a Medium original that returned 403. Earlier search-index text was not treated as a lawful stable full capture; unsupported later-body analysis and the ambiguous paraphrased quotation were removed.
- A 2020 recollection can preserve a genuine 2013 thesis while selecting the parts that fit the IPO narrative. The original LP materials are needed to establish ex-ante wording.
- IPO status does not establish fund return quality. Capitalization, financial risks, and later outcomes require the separate SEC and cash-flow record.
Open questions
- Can the full publisher original and 2013 LP pitch be lawfully retrieved with stable locators?
- What were Aleph’s cost basis, fully diluted ownership, sale history, and realized/unrealized contribution?
- Which 2013 technology claims were documented contemporaneously rather than reconstructed at IPO?
w Long Humanity
- URL: https://medium.com/aleph-vc/long-humanity-32b9dad0d54d | Published: 2018-11-21 | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: Medium body paragraphs counted from the Rothschild opening; no publisher-stable paragraph numbers
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Central argument — [investor-stated | strong]: after two decades of social-media investment, Eisenberg proposes “humanity” as the next venture theme: technology that enables talking, care, education, healing, physical community, and mutual success rather than isolating users or monetizing reflexes. Body paragraphs 1–8
- Contrarian timing — [investor-stated | moderate]: he adapts the “blood in the streets” maxim to perceived damage in human interaction: invest where screens, echo chambers, and social-media incentives have made genuine connection scarce. This is normative market framing, not a demand or valuation study. Body paragraphs 1–8
- WeWork case — [investor-stated | provisional]: Eisenberg says his earlier investment was not a real-estate trade but a bet that people wanted physical, helpful community rather than online antagonism. The essay uses WeWork as thesis evidence before its failed 2019 offering and 2023 bankruptcy, so later outcomes materially challenge efficacy even if they do not negate customer demand. Body paragraphs 8–10 WeWork Chapter 11 Form 8-K, Item 1.03
- Adtech exclusion — [investor-stated | moderate]: Eisenberg says he stopped investing in adtech because targeting and engagement systems exploit weak impulses and finance social-media harms. He admits ads can help human-centered startups acquire early users but argues they cannot sustain durable growth. Body paragraphs 13–20
- Portfolio examples — [investor-stated | provisional]: Nexar, JoyTunes, Lemonade, diagnostic health, financial safety nets, and education/Frank are grouped as services that save, teach, protect, or bring people together. They illustrate a thesis family; the essay does not show that humanity caused adoption or returns. Body paragraphs 21–24
- Technology boundary — [investor-stated | moderate]: digital transactions and productivity tools remain acceptable; the test is whether technology enhances agency and human interaction rather than enclosing people in manipulative feedback. Body paragraphs 18–28
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “The next technological revolution and investment trend is humanity.” — body paragraph 7. Source
- “Technology can be a positive force.” — body paragraph 25. Source
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- Eisenberg says he had presented the “invest in humanity” thesis repeatedly to college audiences for two years before publication, placing its development around 2016–2018. No recordings or text of those speeches are linked. Body paragraph 7
- He dates the WeWork investment to roughly six years earlier and frames it as a community thesis. The essay does not identify vehicle, check, price, ownership, board process, or how later governance risk entered the decision. Body paragraphs 8–10
- The adtech abstention is described as an earlier decision and tied to a separate post, but this essay provides no complete prior adtech portfolio or decision date. Body paragraph 13
- The listed companies span disclosed and then-stealth investments; portfolio attribution is institutional and promotional. No company-level outcome or individual-credit ledger is supplied.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- macro / picking — [investor-stated | moderate]: look for durable human needs made scarcer by the prior platform cycle; treat the social consequence of incumbent technology as the next market opening. Opening through WeWork discussion
- picking / people — [investor-stated | provisional]: favor products that build community, care, competence, safety, or agency and can charge for repeated customer benefit rather than attention extraction. Portfolio examples and closing
- risk — [investor-stated | moderate]: exclude or scrutinize models whose economics depend on manipulation, echo chambers, or a permanent advertising subsidy. Adtech paragraphs
- portfolio — [researcher inference | provisional]: thesis fit must remain separate from governance, capitalization, unit economics, and return; WeWork is the strongest warning that a resonant human need does not validate a company structure.
Contradictions, counterevidence, and access limits
- WeWork entered Chapter 11 in November 2023. The failure does not show that community demand was false, but it does show that thesis-level demand can coexist with unsustainable financing, governance, leases, and execution. WeWork 8-K, Item 1.03
- Frank, named as an education-access example, later became an adverse outcome: founder Charlie Javice was sentenced to 85 months for fraud. That challenges the sufficiency of values rhetoric; it does not establish Eisenberg or Aleph knowledge. DOJ sentencing release
- The essay condemns ad-driven growth while acknowledging ads help portfolio companies start. It offers no measurable threshold for when acquisition support becomes manipulation or dependency.
- The causal leap from customer preference for “humanity” to superior LP returns is asserted, not demonstrated. Selected portfolio examples and personal Facebook abstention do not create a return denominator.
- Several social claims rely on linked press/surveys without methodological analysis. Philosophical quotations from Rothschild, Plato, and Hobbes function rhetorically rather than as investment evidence.
Open questions
- What measurable product signals distinguish genuine community/agency from branding that merely claims those values?
- How did the humanity thesis affect WeWork governance, financing, or exit decisions when the company’s operating risks became clear?
- What is the full hit/miss denominator for Aleph investments classified under “Long Humanity,” and did they outperform other themes?
- What revenue models can fund human-centered services without the advertising dependence the thesis rejects?
w A Look Back at Our Letters to Our LPs and Capital Exuberance
- URL: https://www.aleph.vc/content/a-look-back-at-our-letters-to-our-lps-and-capital-exuberance | Published: 2022-09-13 | Format: essay | Reliability: A | Access: partial | Accessed: 2026-08-22 | Locator scheme: byline/date block, title, and one publisher-visible opening paragraph
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- The stable Aleph page verifies Eisenberg’s byline and September 13, 2022 publication date but exposes only one opening paragraph, not the selected LP-letter excerpts signaled by the title.
- Eisenberg says that at Aleph’s formation he took responsibility for writing the annual letter to the firm’s limited partners. This is direct authorship evidence for the letters, though no complete letter is public on the recoverable page. Opening paragraph
- He names Warren Buffett and Jeff Bezos as inspirations and says producing a unique, insightful letter every year is difficult. This supplies an intellectual reference point and communication challenge, not evidence of matching their records.
- No cycle warning, runway rule, financing policy, secondary-liquidity rule, dated excerpt, company action, or return result is recoverable from the stable paragraph. The title alone cannot supply those arguments.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “I decided to take on the responsibility of writing the annual letter to our Limited Partners.” — canonical page, opening paragraph.
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The signed 2022 page directly attributes Aleph’s annual-LP-letter responsibility to Eisenberg from the firm’s start.
- The letters are communications to Aleph LPs. Their statements and any actions discussed would still require vehicle, team, company, and date attribution rather than automatic personal-decision credit.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- people / portfolio: Eisenberg treats recurring written communication with LPs as a personal responsibility.
- macro / risk / boards / exits / sourcing / picking: not analyzable because the letter excerpts and article body are unavailable.
Contradictions, counterevidence, and access limits
- The canonical Aleph page exposes only the opening paragraph and a Read full article link; the linked Medium body returned 403. Earlier search-index text and quotations were removed because they are not a stable reproducible capture.
- The title promises a retrospective selection. Even a full article would not substitute for the complete letters, omitted forecasts, contrary passages, company actions, or performance denominator.
- The visible page provides no audited fund result, portfolio company list, financing terms, DPI, TVPI, IRR, ownership, or cash flows.
Open questions
- Can Aleph release the complete dated annual letters or a lawful full publisher capture?
- Which warnings were contemporaneous, which actions followed, and what contrary forecasts were omitted?
- How did any resulting company decisions affect survival, dilution, and fund returns?
w Meet Aleph: Our New $140 Million Venture Capital Fund
- URL: https://www.aleph.vc/content/meet-aleph-our-new-140-million-venture-capital-fund | Published: 2013-07-03 | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: byline/date block + single announcement body paragraph
Takeaways
- This concise launch announcement is by Eden Shochat, not Michael Eisenberg. It names Shochat and Eisenberg as Aleph’s founders and describes the firm as an equal partnership; its statements are official firm/founder-position evidence, not sole Eisenberg authorship (byline/date and body paragraph).
- Aleph’s stated goal is to help Israeli entrepreneurs build very large, scalable companies. The service-business language puts founder support, not capital alone, at the center of the offering (body paragraph).
- The initial stage focus is Series A. The page announces a $140 million fund in its title, while the body describes best-in-class limited partners and Bruce Dunlevie as a special partner (title and body paragraph).
- The launch design supports institutional attribution to Aleph and co-founder attribution to Eisenberg. It does not allocate individual deal credit, ownership, carry, authority, or economic contribution between the partners.
Quotes
- “Aleph is an equal partnership.” — Eden Shochat, official Aleph launch announcement, body paragraph.
- “Aleph is a service business.” — Eden Shochat, official Aleph launch announcement, body paragraph.
Biography and decision evidence
- The page is contemporaneous primary evidence that Michael Eisenberg and Eden Shochat founded Aleph together in 2013 and that Bruce Dunlevie joined as special partner.
- It establishes a public Series A and Israel-to-global scale mandate at formation. It does not say which founder originated the model or each sentence; the byline requires Shochat-first authorship attribution.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- people: Positions the fund as a service organization for Israeli entrepreneurs.
- picking: Targets Series A companies with the potential to become very large and scalable.
- portfolio: Supplies fund size and stage, but no company count, check range, reserves, ownership target, or diversification model.
- boards / risk / exits / macro: Not developed in the short announcement.
Contradictions, counterevidence, and access limits
- Fundraising language is promotional and does not constitute audited capital commitments, deployment, fees, carry, or performance. SEC Form D is the better legal control for the offering.
- “Equal partnership” is a governance principle, not evidence of equal contribution to every decision or equal economics.
- “Best-in-class LPs” is an untestable descriptor because no LP list or criteria are given.
- The current Aleph page wraps the historical announcement in newer site/podcast chrome, but the dated byline and short article body are fully readable. The visible spelling “scaleable” is preserved on the source; this note standardizes it as “scalable” outside quotations.
Open questions
- What did equal partnership mean legally for voting, carry, and deadlock resolution?
- What were Fund I’s target check size, ownership, reserves, and company-count plan?
- Which initial decisions were attributable to Shochat, Eisenberg, Dunlevie, or the partnership collectively?
w Melio: Investing in Great People
- URL: https://medium.com/aleph-vc/melio-investing-in-great-people-cfe145a418d2 | Published: 2020-09-14 | Format: essay | Reliability: A | Access: partial | Accessed: 2026-08-22 | Locator scheme: publisher-index title, byline, date, and canonical URL; no verified article-body locator available
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Medium’s publisher index verifies the title, Michael A. Eisenberg byline, September 14, 2020 date, and canonical URL. The live article returned 403/internal error, and no stable body capture was available.
- The words Investing in Great People are part of the verified title. They do not, without body text, establish a people-first investment process, Melio sourcing chronology, market-size filter, financing role, team construction, or product-market-fit thesis.
- Previously surfaced search-index text appeared continuous but is not a stable reproducible publisher route. It is treated only as a retrieval lead and is not analyzed or quoted here.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- No quotation used: no lawful stable article-body capture with a reproducible locator was available.
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The index establishes Eisenberg’s authorship in the Aleph era and the existence of a Melio-related essay.
- It does not establish that Eisenberg personally sourced or led an Aleph investment, nor does it disclose vehicle, check size, ownership, board role, syndicate, follow-ons, or outcome.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- people: the title signals a topic, not an analyzable rule or evidenced method.
- sourcing / picking / portfolio / boards / risk / exits / macro: not analyzable from publisher metadata.
Contradictions, counterevidence, and access limits
- The canonical Medium route returned 403/internal error. Search-index body text, images, outbound links, comments, and revision history are not treated as full access.
- Earlier quotations, the reported $144 million financing figure, founder chronology, and article-wide argument were removed because none is reproducible from a stable lawful body route in this pass.
- Title language can be promotional and cannot demonstrate that people selection caused product-market fit or returns.
Open questions
- Can Medium or Aleph provide a lawful full publisher capture with stable paragraph locators?
- What contemporaneous memo documents founder selection, market evidence, allocation, ownership, and governance?
- Which claimed financing and operating facts can be independently verified from filings or company announcements?
w חלב, דבש ואי־ודאות (Milk, Honey and Uncertainty)
- URL: https://media.alhatorah.org/Books/Bemidbar_Hebrew_-_Michael_Eisenberg.pdf | Published: 2022 (exact day not exposed) | Format: book-chapter | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: PDF page (1-based) + printed page + Hebrew section heading; English renderings in this note are researcher translations
Takeaways
- Eisenberg reads Numbers/Bemidbar as a book about a people assigned a mission while moving into the unknown. He emphasizes that pekudim are not merely people counted but people charged with a task; the wilderness journey is an enduring prototype for action amid radical uncertainty (PDF p.15 / printed p.16, introduction).
- The autobiographical opening links uncertainty to faith and family formation. He recounts his parents’ response to difficult medical advice and presents belief not as prediction certainty but as one way to find courage and choose under uncertainty (PDF pp.11–12 / printed pp.12–13, dedication/introduction). This is family testimony and theological interpretation, not medical evidence.
- A core distinction is between risk management and uncertainty. Under uncertainty, one cannot wait for full probabilities; one “plants a stake” and advances, choosing among competing values while accepting that not all legitimate values can be maximized at once (PDF p.47 / printed p.48, paragraphs before §יא).
- Section יא, “אי־ודאות כאסטרטגיה” (“Uncertainty as Strategy”), contains the clearest investment evidence. Eisenberg attributes to Benchmark partner Bruce Dunlevie a staircase analogy: each required success may have low probability, so the compounded chance is very small, yet a complete success can be enormous. The operating answer is staged progress from one uncertain point to the next (PDF p.47 / printed p.48, §יא, opening ¶¶1–2).
- He generalizes asymmetric payoff logic: try multiple actions aligned with plausible trends or deliberately against consensus when the present loss is bounded and a success could create large change or return. In venture, an investment can be lost once while a world-changing winner may return tens or hundreds of times the investment (PDF p.48 / printed p.49, §יא, ¶¶4–6). These are author-stated payoff claims, not audited portfolio economics.
- He frames technological entrepreneurship as progress through failures and unknowns, anchored by tradition and directed toward high-impact purposes rather than novelty alone (PDF pp.48–49 / printed pp.49–50, §יא, closing paragraphs).
- Elsewhere, he applies the same action-under-uncertainty concept to rehabilitation and the biblical city of refuge: ambiguity about the past should not freeze action, and institutions should create future stability and recovery (PDF p.269 / printed p.270, §ד “מעגלי שיקום”). This broadens the framework beyond investing.
Quotes
- “בתנאים של אי־ודאות צריך לעשות, לנעוץ יתד ולהתקדם קדימה.” (PDF p.39 / printed p.40; researcher translation: under uncertainty one must act, plant a stake, and move forward.)
- “תחום ההון־סיכון הוא דהירה אל הלא־נודע.” (PDF p.48 / printed p.49; researcher translation: venture capital is a gallop into the unknown.)
Biography and decision evidence
- Eisenberg explicitly names Bruce Dunlevie as his valued Benchmark partner and preserves a piece of partnership teaching about compounded startup uncertainty (PDF p.47 / printed p.48). This supports intellectual influence, not joint attribution for a specific investment.
- The book connects his family history, religious formation, and venture practice. That direct synthesis helps explain his comfort with probabilistic failure and his insistence on purpose, but it remains retrospective self-narration.
- The mathematical example in the PDF’s text extraction appears as a 5% chance for each step and less than 1% overall; without the original oral context or an explicit number of steps, it should be treated as illustrative rather than a calibrated model.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- risk: Separates calculable risk from unknowable futures; favors staged commitments and positive asymmetry.
- picking: Seeks experiments whose failure is bounded and whose success could produce disproportionate change, while aligning with a directional thesis or principled contrarian view.
- portfolio: Multiple attempts and power-law payoff language imply a portfolio logic, but no exact diversification or reserve rule is provided.
- people: Courage, mission, active choice, and willingness to bear tradeoffs are treated as leadership qualities.
- macro / exits / boards: The framework is extended to society and technology, but board process and actual realization data are absent.
Contradictions, counterevidence, and access limits
- The source is a complete 361-page Hebrew PDF. This note sampled the introduction, “Uncertainty as Strategy,” and a later rehabilitation passage; it is not a chapter-by-chapter digest of the entire book.
- All English glosses are researcher translations. Hebrew nuance, rabbinic citations, and page typography should be checked by a fluent reviewer before publication-level quotation.
- “Bounded loss, vast upside” can obscure follow-on capital, opportunity cost, correlated bets, dilution, and the possibility of repeated small losses overwhelming a portfolio. The mask analogy in §יא has much lower downside than a VC check and is explicitly imperfect.
- Religious narrative can discipline action but does not by itself validate probability estimates or business-market fit.
Open questions
- How does Eisenberg set stage gates, loss budgets, and abandonment criteria when probabilities are unknowable?
- Which portfolio decisions show the difference between productive uncertainty and insufficient diligence?
- Is Dunlevie’s staircase example documented elsewhere with its precise assumptions and intended math?
w An Open Letter to Zeev Holtzman: The Sky Is Not Falling in Israel. It Is Getting Brighter
- URL: https://medium.com/%40mikeeisenberg/an-open-letter-to-zeev-holtzman-the-sky-is-not-falling-in-israel-it-is-getting-brighter-45a9ddeb39d | Published: 2011-05-31 (later Medium repost) | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: article-body paragraph sequence and original-date footer
Takeaways
- Eisenberg answers Zeev Holtzman's reported warning of collapse by arguing that domestic fund-raising is the wrong health metric. Global firms were investing from main funds, large rounds were entering Israel, and new-company activity was shifting toward mobile, cloud, SaaS, agriculture, and global markets.
- The central venture-return claim is not that more capital is always good. Israel needs a small number of large companies because power-law “home runs” drive LP returns; weak funds and marginal startups can exit while talent consolidates into companies with a credible chance to scale.
- The transformation mechanism has four parts: long-duration international capital replaces some local dedicated funds; failed founders join scaling companies; larger Israeli companies acquire small teams/products; and experienced operators return from Silicon Valley. Together these inputs move “Start-Up Nation” toward “Scale-Up Nation.”
- Evidence includes named investors and rounds—Battery, Bessemer, Benchmark, Sequoia, Greylock, Accel, Index; Wix, Kayma, and PrimeSense—plus a three-engineer hiring anecdote, Conduit's acquisition of Wibya, microfund estimates, and a Gigya founder quotation. It is a rich contemporaneous inventory but not a census.
- Eisenberg still identifies gaps: advanced-research investment, executive sales/marketing recruitment, and focused late-stage funds. Optimism is conditional on scale capability, not a claim that every ecosystem input was healthy.
- The decision rule is to judge an ecosystem or fund by its ability to aggregate talent, finance companies through scale, and produce large outcomes—not by the count of domestic fund closes or startups.
Quotes
- “The challenge has been that Israeli VCs have not grown big companies needed to generate venture returns for LPs.” — canonical essay, scale discussion.
Biography and decision evidence
- Eisenberg identifies Benchmark as his employer and says it invested from its main fund. That distinction matters: the essay does not describe a dedicated Benchmark Israel vehicle for the activity discussed.
- He identifies himself as a Wix and Conduit board member and identifies Gigya and Wilocity as Benchmark companies. Board or firm association does not by itself prove sole sourcing, deal leadership, allocation, ownership, or return.
- The exchange with Zeev Holtzman documents a live disagreement between two Israeli venture practitioners. Holtzman's position is represented through Eisenberg's response and the linked report, not a full transcript of Holtzman's reasoning.
Philosophy signals
- Macro: distinguish local fund formation from total global capital and expertise available to companies.
- Portfolio: power-law outcomes require concentrating talent and follow-on capacity in firms capable of becoming large.
- People: returning scale operators and founders willing to join larger teams are ecosystem assets.
- Exits: small acquisitions can consolidate talent, but the fund-level objective remains large outcomes that return meaningful capital to LPs.
Contradictions, counterevidence, and access limits
- Hummus Part 2, published less than a year earlier, said many venture firms including his had questioned dedicated Israel economics and identified too few venture-scale opportunities. This letter reframes fund contraction as productive consolidation amid stronger deal flow. The sources show a changed emphasis but not a documented causal update.
- The claim that a fund shakeout enabled larger companies may confuse correlation with causation; global technology cycles, foreign capital, and company maturity could also explain the observations.
- Named rounds are financing events, not proof of durable company value or LP return. The roughly $100 million microfund estimate is explicitly observational.
- The surviving Medium repost preserves the body and original date but not the original Blogspot comments or all contemporaneous context.
Open questions
- Did the named 2011 companies generate the large outcomes and LP returns anticipated, after dilution and realization?
- Which incoming global funds supplied true late-stage operating expertise rather than capital alone?
- What evidence separates beneficial talent consolidation from a contraction that reduced experimentation?
- How did Holtzman respond, and which side's measurable predictions were more accurate over the next fund cycle?
w Why We Are So Optimistic About Israel
- URL: https://www.aleph.vc/content/why-we-are-so-optimistic-about-israel | Published: 2014-09-08 | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: article-body paragraph sequence and named-founder examples
Takeaways
- Eisenberg reduces the entrepreneurial temperament to optimism—the capacity to imagine a better state—and resilience—the drive to keep acting against doubt and adversity. He then maps those traits from founders to Israeli society and treats the country as unusually fertile ground for ambitious company formation.
- The mechanism he proposes is cultural and experiential: recurring national threats, social solidarity, immigration, military and academic training, and limited tolerance for being “coddled” produce persistence and improvisation. That temperament then attracts additional immigrant talent and supports companies aimed at global problems.
- His evidence mixes national survey claims—happiness, optimism, and having someone to rely on—with selected founder cases: Ariel Beery/MobileOCT, Yuval and Yigal Kaminka/JoyTunes, Yonatan Adiri/OwnHealth, and Zvi Schreiber/Freightos. The examples show the pattern he admires but do not establish national causality or a founder-performance denominator.
- The founder pattern is mission plus resourcefulness: use image analysis, mobile devices, military or academic technology, and inexpensive components to lower the cost of cancer screening, music education, diagnostics, or freight. “World-class” is linked to global problem size and impact, not merely a domestic technology credential.
- The practical selection rule is to test whether a founder can articulate a better future, persist through skepticism, assemble missing tools, and attack a consequential global problem from Israel. National optimism is context, not a replacement for product, market, and execution diligence.
- The essay's evidence is contemporaneous advocacy during and after war. It gives a clear people thesis but no comparative failure cases, portfolio returns, or test that separates resilience from overconfidence.
Quotes
- “It comes down to two: Optimism and Resilience.” — canonical essay, opening discussion of entrepreneurial traits.
Biography and decision evidence
- Eisenberg says he had spent much of the preceding 20 years investing in entrepreneurs. This supplies a 2014 self-description of career duration, not an independently verified start date or complete investment record.
- JoyTunes is explicitly identified as an Aleph portfolio company; that is firm-level association, not proof of sole sourcing, personal ownership, or realized return.
- The essay records direct familiarity with the named founders, including a same-day meeting with Zvi Schreiber and his prior skepticism of Ariel Beery. These are relationship and judgment signals, not board or deal-lead records.
- His references to his children and to prospective immigrants show that the national thesis is personal and civic as well as financial; the source does not quantify how that value preference changed an investment decision.
Philosophy signals
- People: favor optimism, resilience, curiosity, determination, and the ability to improvise under constraint.
- Picking: seek founders applying Israeli technical capabilities to large, global, socially consequential problems.
- Risk: doubt and hardship are treated as tests of agency, but the source lacks a rule for distinguishing resilience from stubbornness.
- Macro: social trust, immigrant inflows, military/academic skill formation, and national optimism are proposed as entrepreneurial inputs.
Contradictions, counterevidence, and access limits
- Selected successful or promising founders cannot show that national adversity causes better venture outcomes. War can also destroy human capital, depress investment, and drive migration; those countervailing channels are not tested.
- The Hummus Manifesto had emphasized talent fragmentation, obsolete stacks, and missing scale experience. This essay does not retract those constraints; it shifts from ecosystem bottlenecks to founder temperament, leaving the relative weights unresolved.
- Happiness and optimism percentages are reported without a fully preserved methodological citation in the canonical text reviewed here. They should be independently checked before quantitative reuse.
- Several named companies were early-stage in 2014, so the examples are ex-ante aspirations rather than validated outcomes.
Open questions
- Which founder decisions did Eisenberg change after observing resilience under a specific setback?
- What evidence would distinguish useful optimism from denial or escalation of commitment?
- Did the named 2014 companies ultimately produce the global impact and venture-scale outcomes the essay anticipated?
- How did the thesis change after later wars, political conflict, and cycles in Israeli talent migration?
w Invest in Relationships, Not Transactions
- URL: https://www.aleph.vc/content/invest-in-relationships-not-transactions | Published: 2021-10-20 | Format: essay | Reliability: A | Access: partial | Accessed: 2026-08-22 | Locator scheme: byline/date block and one publisher-visible opening paragraph
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- The stable Aleph page verifies Eisenberg’s byline, the October 20, 2021 date, and one introductory paragraph written while he prepared for Aleph’s annual LP meeting.
- The visible framing contrasts investment strategy with an era Eisenberg calls weaponized capital or capital as a commodity. It establishes the market context he wanted to address, but not his full early-stage-versus-growth argument or relationship mechanism. Opening paragraph
- Eisenberg says a recent article by his friend Sam Lessin supplied a quotation that stood out. The quotation and subsequent application are not visible, so Lessin’s view and Eisenberg’s interpretation cannot be reconstructed.
- The title signals a preference for relationships over transactions, but title semantics alone do not establish sourcing rules, founder diligence, board behavior, portfolio construction, or outcomes.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “Capital as a commodity.” — canonical page, opening paragraph.
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The opening places Eisenberg in a strategy-writing role for Aleph’s 2021 annual LP meeting and identifies Sam Lessin as a friend and cited influence.
- No named investment, allocation, board action, ownership, or result is recoverable from the stable paragraph.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- macro / portfolio: abundant, commoditized capital is the explicit setting for the strategy reflection.
- sourcing / people: the title suggests a relationship orientation, but its mechanism and decision rule are not analyzable without the body.
- picking / boards / risk / exits: not supported by the recoverable text.
Contradictions, counterevidence, and access limits
- The canonical Aleph page exposes only the introductory paragraph and links a Medium original that returned 403. Earlier search-index body analysis and quotations were removed rather than treated as a stable full source.
- The phrase weaponized capital is rhetorical and the stable paragraph supplies no market data, comparative fund evidence, or counterexample.
- Neither the title nor the introduction demonstrates that relationships improve access, judgment, governance, or returns.
Open questions
- Can the full publisher original, Sam Lessin quotation, and named sections be lawfully retrieved with stable locators?
- What observable behavior distinguishes a useful long-term relationship from familiarity bias?
- Which investments, passes, or board decisions document the strategy in practice?
w Empowering Others to RiseUp!
- URL: https://www.aleph.vc/content/empowering-others-to-riseup | Published: 2022-04-13 | Format: essay | Reliability: A | Access: partial | Accessed: 2026-08-22 | Locator scheme: byline/date block and two publisher-visible opening paragraphs
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- The stable Aleph page verifies Eisenberg’s byline, the April 13, 2022 date, and two opening paragraphs describing RiseUp’s pre-investment setup. The later product, community, impact, and financing narrative is unavailable.
- Eisenberg says Yuval Samet came to brainstorm a next company about six years before publication, then returned one year later with Tamara Harel-Cohen and Iftach Bar seeking investors. This is direct retrospective evidence of relationship-led company ideation. Opening paragraphs
- According to Eisenberg, the founders expected Aleph to reject a company initially limited to Israel’s nine-million-person market and a subscription product for lower socioeconomic customers. The setup exposes two presumed filters—market size and customer segment—but the visible text does not reveal Aleph’s final reasoning.
- The second paragraph states a conventional belief that financial services should target the top 20%. The essay’s visible framing challenges that belief, but no customer research, price, retention, outcome, or addressable-market evidence is recoverable.
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “Who would want to initially target a market of only nine million people?” — canonical page, opening paragraph 2.
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- Eisenberg describes a multi-year relationship with Samet before the financing request and names Harel-Cohen and Bar as cofounders.
- The recoverable text says the founders sought investors and anticipated an Aleph rejection; it does not show that Eisenberg alone approved, led, owned, or governed an investment.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- sourcing / people: brainstorm with a known founder before company formation and observe how the team changes over time.
- picking / macro: small domestic markets and lower-income subscription customers appear as priors to test, not yet as proven exceptions.
- portfolio / boards / risk / exits: not analyzable from the two visible paragraphs.
Contradictions, counterevidence, and access limits
- The canonical Aleph page exposes two opening paragraphs and links a Medium original that returned 403. Earlier search-index claims about price, seed leadership, community, financial outcomes, and expansion were removed because they are not reproducible from the stable text.
- The six-year and one-year chronology is a 2022 recollection, not a contemporaneous memo. The page provides no date for the eventual investment.
- Nine million and top 20% are rhetorical market anchors, not a quantified venture-return case.
Open questions
- Can a lawful full capture establish the investment decision, product evidence, financing, and outcome claims?
- What contemporaneous evidence changed Aleph’s views on domestic-market size and customer ability to pay?
- What were vehicle, allocation, ownership, board rights, and complete customer-outcome denominator?
w Sarah Lacy, David Li and the Wrong Side of Historical Performance
- URL: https://medium.com/%40mikeeisenberg/sarah-lacy-david-li-and-the-wrong-side-of-historical-performance-b74f4851cf32 | Published: 2009-03-26 (original; later Medium repost) | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: body paragraph counted from opening Felix Salmon/Wired reference + original-date footer
Takeaways
- Eisenberg uses Felix Salmon’s account of David Li’s Gaussian-copula model as an analogy for venture allocation based on trailing returns. A model calibrated to a short, benign history can look precise while embedding regime assumptions that fail when conditions change (body ¶¶1–7).
- He maps the feedback loop onto VC: strong 1990s returns attracted LP capital, greater capital increased competition and valuations, and subsequent returns fell. After poor 2000s performance, withdrawals should reduce competition and create a better forward opportunity set (¶¶8–12).
- The practical rule is contrarian and supply-sensitive. Past fund or geography returns may be negatively related to future vintage conditions because capital availability, founder selection, and entry price respond endogenously (¶¶10–13).
- Sarah Lacy’s reported 2001–2009 Israeli venture statistics are accepted as possibly accurate historical description, but Eisenberg disputes the forward inference that Israel had lost its “mojo.” Scarce capital and persistent entrepreneurs are, in his framing, precisely the reasons to invest (¶¶14–22).
- The essay contains no audited Benchmark or personal performance data. It is an argument about cycles, not proof that the 2009 Israeli vintage subsequently outperformed.
Quotes
- “Investing is a contrarian business, not a herd business.” (body ¶12)
- “Scarcity of capital is a plus for investors; hardy innovators drive venture capital.” (body ¶22)
- “Past performance is no indication of future returns.” (closing paragraph)
Biography and decision evidence
- This is direct, contemporaneous evidence that Eisenberg was publicly bullish on Israeli VC in March 2009 despite weak trailing returns and reduced LP appetite.
- He engages both a quantitative-model failure and a named journalist’s market critique, showing a process that challenges extrapolation and asks how capital supply changes the next vintage. The essay does not identify a particular 2009 deal placed because of that view.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- macro / risk: Treats capital cycles and model-regime error as primary underwriting context.
- picking: Sees capital scarcity as a filter that may leave more committed founders and lower competitive entry conditions.
- portfolio: Implies vintage diversification and countercyclical allocation, though no pacing rule or allocation percentage is given.
- exits: Warns that recent exit droughts are backward-looking; no forecast horizon is specified.
- people / boards: “Hardy” founders matter; governance practice is absent.
Contradictions, counterevidence, and access limits
- The CDO analogy is illuminating but imperfect: venture returns, illiquidity, dispersion, follow-on needs, and power-law outcomes differ materially from correlation-model failure in structured credit.
- Poor trailing returns can reflect durable ecosystem weaknesses rather than a temporary capital-cycle trough. The essay does not test Lacy’s claims about sector fit, geography, or comparative opportunity.
- Lacy’s figures are reproduced from Dow Jones VentureSource but not independently audited here; capital raised and disclosed acquisitions/IPOs may not form a complete cash-return measure.
- The argument risks becoming unfalsifiable if any weak period is labeled attractive. A forward vintage scorecard is needed. The source is a later Medium repost.
Open questions
- What did the 2009–2012 Israeli venture vintages return net of fees relative to US and European peers?
- Which fund commitments or company investments express this specific contrarian call?
- What observable conditions would have made Eisenberg conclude the weakness was structural rather than cyclical?
w The Tree of Life and Prosperity: 21st Century Business Principles from the Book of Genesis
- URL: https://www.everand.com/book/512764969/The-Tree-of-Life-and-Prosperity-21st-Century-Business-Principles-from-the-Book-of-Genesis | Published: 2021-08-24 | Format: book-chapter | Reliability: A | Access: partial | Accessed: 2026-08-22 | Locator scheme: preview heading + table-of-contents entry + preview paragraph counted within heading (platform exposes no stable printed pages)
Takeaways
- The accessible preview establishes the book’s method rather than its full chapter arguments: read Genesis as a source of economic and business reasoning, and use modern economic experience to reread the biblical narratives (“Preface,” ¶¶1–7). Only the contents and a preface excerpt are visible; no claim is made about inaccessible chapters.
- Eisenberg treats ethics as an economic input, not a charitable constraint added after profit. Principles build trust, reputation, identity, market institutions, and long-duration value (“Preface,” paragraphs around “Principles are part…”).
- He gives unusually candid strategy evidence. Venture investors can specialize in technological change, market evolution, or people; he says he lacks deep technology and market expertise and therefore focuses on people. He also concedes that this may be “passion re-narrated as strategy” (“Preface,” ¶¶13–15).
- Torah study, especially adversarial paired study (chavruta), is described as formative to his process. He connects it to treating ancient people as economically real: Abraham faces wealth and hardship, Isaac reinvents a livelihood, Jacob manages family-business tension, and Joseph develops crisis policy with unpredictable results (“Preface,” ¶¶15–19).
- The preview introduces an “anchor and seven satellites” investment framework. The anchor combines fear of God, Torah, and humanism; the satellites evaluate principled products that become enabling infrastructure. The visible portion includes willingness to pay a principled premium and trust sufficient for users to share confidential information, but the preview cuts off during item five (“An Anchor and Seven Satellites,” items 1–5).
- The contents show twelve Genesis-parashah chapters spanning innovation, wealth, game theory, business reinvention, land, urbanization, and policy. Titles alone are navigation evidence, not evidence for unseen conclusions (Table of Contents).
Quotes
- “I do not know much about technology and markets, so I focus on people.” (“Preface,” ¶13)
- “Perhaps this is passion re-narrated as strategy.” (“Preface,” ¶15)
- “Principles, as a component of business, are a competitive advantage.” (“Preface,” paragraph before “An Anchor and Seven Satellites”)
Biography and decision evidence
- Eisenberg recalls Rabbi Yehuda Amital urging him at age nineteen to move to Israel and create dignified employment for 10,000 people. He says the challenge still informs how he links Torah, company creation, and social purpose (“Preface,” ¶¶3–5). This is autobiographical testimony, not independently verified contemporaneous evidence.
- He describes a political-science degree, college newspaper editing, extensive Torah study, and an early investing period driven by curiosity and a desire to prove himself, without an explainable formal strategy (“Preface,” ¶¶13–15).
- The people-first statement is strong direct evidence of his self-understood edge. It does not show how the criterion was scored, how team decisions were allocated, or whether it outperformed technology- or market-led selection.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- people: People selection is the claimed specialization; moral character, practical judgment, and growth potential are integral to underwriting.
- picking: Looks for principled products that become trusted infrastructure and whose ethics are part of customer value.
- risk: Treats identity and trust as economic assets, but offers no visible quantitative loss framework in the preview.
- macro: Connects institutions, family, land, urbanization, innovation, and public policy to economic behavior.
- portfolio / boards / exits: The accessible excerpt supplies no sizing, reserves, board practice, or return record.
Contradictions, counterevidence, and access limits
- Access stops during satellite five on a page labeled “Page 1 of 1.” Chapters listed in the contents were not available, so this note must not stand in for the complete book.
- The publisher/platform page advertises subscription access and pagination may drift. It does not expose stable printed-page numbers for the preview; headings and locally counted paragraphs are the most reproducible locators.
- Claims that principles create competitive advantage are plausible but normative and selectively illustrated. Values can also impose costs, conflict, or be used as post hoc narrative; no comparative portfolio analysis is visible.
- Eisenberg’s admission that passion may be retold as strategy is useful counterevidence to an overly systematic portrait of his process.
Open questions
- What are satellites five through seven, and how are all seven applied in an actual investment memo?
- Which investments failed despite passing the values framework, and which profitable opportunities were rejected on principle?
- Does the full book distinguish firm doctrine from Eisenberg’s personal religious and economic interpretation?
w Building Israel’s Trillion-Dollar Economy
- URL: https://sapirjournal.org/money/2025/building-israels-trillion-dollar-economy/ | Published: 2025-11-11 | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: article section break + body paragraph counted within section
Takeaways
- Eisenberg opens with a resilience case: strong market performance, defense exports, technology financing, major acquisition and infrastructure announcements during war, against a five-decade rise from roughly $11.3 billion GDP in 1973 (in today’s dollars) to about $580 billion. These figures are attributed in the article to the IMF, Defense Ministry, and cited commentators but were not independently recomputed here (opening section, ¶¶1–6).
- He argues those historical growth drivers are insufficient to double GDP above $1 trillion within ten years. War cost, rising debt service, productivity gaps, infrastructure delay, concentrated burdens of work/service/tax, and bureaucracy are the binding constraints (second section, ¶¶1–10).
- Government should be managed more like an internet-era operating system: explicit service-level agreements, ROI measures, KPIs, public targets, deadlines, and accountable officials. Spending should shift from consumption toward productive infrastructure and people who perform national service, work, and pay taxes (second and third sections).
- The budget prescription is deliberately selective rather than across-the-board austerity. Eisenberg argues uniform ministry cuts protect political inputs while harming the sectors most capable of increasing output; public spending should be evaluated as investment (third section, ¶¶1–6).
- Housing and infrastructure approvals should be radically compressed, including an 80% timetable reduction, and postwar rebuilding should use air rights and rapid infrastructure to expand supply (third section, later paragraphs). The feasibility claim is advocacy, not a demonstrated implementation plan.
- Three proposed growth engines are finance, AI, and regional integration. Tel Aviv should compete as a financial center through US-competitive hedge-fund regulation, crypto-friendly rules, and lower capital-gains taxation; the state should fund AI infrastructure and implementation; the Abraham Accords and IMEC could connect Israel to Gulf, Indian, and—conditional on regime change—Iranian markets (fourth section).
Quotes
- “The growth drivers that produced the start-up nation over the past three decades will not suffice.” (opening section, ¶6)
- “What is required is selective and judicious spending cuts, prioritizing investment-oriented spending.” (third section, ¶4)
- “Tel Aviv has an opportunity to become the second capital for finance, after New York.” (fourth section, ¶4)
Biography and decision evidence
- Eisenberg says he has criticized broad uniform budget cuts for nearly two decades and reports discussions with Israel’s finance minister after Iranian missile attacks (third section). This is direct evidence of policy engagement, not an official record of authority or policy adoption.
- He says he joined Shervin Pishevar in establishing an Israel-Iranian alliance in January 2024 (fourth section). The essay does not specify legal form, membership, activity, or results, so the claim should remain self-reported.
- The article extends his venture lens—investment versus consumption, KPIs, regulatory competition, technology leverage—to national economic management.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- macro: Growth, productivity, debt service, state capacity, demographics, regional trade, and security are one investment environment.
- picking: Favors finance, AI, infrastructure, and cross-regional platforms as scalable engines.
- risk: Highlights war finance, regulatory delay, debt compounding, and participation imbalance.
- people: Rewards contribution and national service; calls for accountable leaders and operators.
- portfolio / boards / exits: Uses portfolio/ROI language at state scale but gives no fund-level evidence.
Contradictions, counterevidence, and access limits
- The $1 trillion goal is nominal and sensitive to inflation, exchange rates, population growth, and starting-year choice. The essay does not show a real-GDP bridge or scenario model.
- Conditioning welfare priority on national service, taxes, and work is a political value judgment with distributional, disability, caregiving, minority, and legal implications not fully addressed.
- Crypto-friendly regulation and lower hedge-fund taxes can attract capital but may increase enforcement, money-laundering, volatility, and fiscal risks. Benefits and foregone revenue are not quantified.
- Predictions about Iranian regime change and regional integration are highly uncertain and geopolitically contingent. Wartime statistics and current-policy claims require ongoing verification.
Open questions
- What annual real productivity, labor participation, investment, and exchange-rate assumptions produce the $1 trillion target?
- What are the costed fiscal effects and distributional impacts of the proposed spending and tax changes?
- Which investable themes, if any, did Aleph adopt from this national thesis, and under what vehicle?
w Wake Up and Smell the Java: Israel Needs the Internet
- URL: https://medium.com/%40mikeeisenberg/wake-up-and-smell-the-java-israel-needs-the-internet-18238f2dd31d | Published: 2006-04-27 (original; Medium repost 2015-04-21) | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: body paragraph counted from first prose paragraph + original-date footer
Takeaways
- Eisenberg argues that Israel should treat internet infrastructure and internet-company formation as a national development strategy, not a niche technology policy. The claim was early: he contrasts the coming internet economy with the previous IBM/Intel/Microsoft investment cycle and says the next generation will not be built on the same model (body ¶¶1–7).
- The proposed bottlenecks are tax treatment, company law, bandwidth, subsea connectivity, and insufficient internet skills. He claims entrepreneurs and headquarters were moving to Gibraltar, Hungary, Cyprus, and tax shelters, taking jobs, services, and tax revenue with them (¶¶2–4). Those examples are assertions in an advocacy essay, not a complete migration dataset.
- He contrasts already-profitable, asset-light internet companies with subsidized capital-intensive companies such as Tower Semiconductor and ECI. His prescription is targeted tax incentives for internet headquarters and subsidiaries, fast home connections, network investment, and a deliberate skills cluster (¶¶4–9).
- The deeper selection principle is capital efficiency: falling development and distribution costs should let internet businesses reach markets and profitability with less fixed capital than “wrought iron” projects. The essay does not show a deal denominator or test whether that preference produced superior returns.
Quotes
- “The internet is the future.” (body ¶7)
- “This is a national emergency like building railroads.” (closing paragraph)
Biography and decision evidence
- Eisenberg says he made this case to Prime Minister Ehud Olmert and other officials (opening ¶1). It supports direct-voice evidence of policy engagement in 2006 but is not independently verified lobbying or advisory-service documentation.
- The article locates his early investment worldview at the intersection of national infrastructure, regulation, and venture capital: improve the substrate first, then attract and retain globally oriented firms.
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- macro: Reads bandwidth, tax law, and corporate law as inputs to the venture opportunity set.
- picking: Favors internet-native, capital-efficient businesses over fixed-asset projects dependent on subsidy.
- people: Calls for training and clustering internet skills; talent density is treated as infrastructure.
- risk: Identifies jurisdictional flight and inadequate connectivity as ecosystem risks.
- portfolio / boards / exits: Contains no position-sizing, governance, exit, or realized-performance evidence.
Contradictions, counterevidence, and access limits
- The essay offers no company-by-company evidence for the claimed headquarters flight, and some cited activity involved online gambling, whose regulatory and social costs are not discussed.
- Tax incentives and very high bandwidth are asserted to attract activity, but fiscal cost, deadweight subsidy, market concentration, and implementation sequencing are not quantified.
- The comparison with Tower Semiconductor and ECI compresses different industrial strategies and time horizons into a rhetorical contrast. Capital intensity alone does not establish poor social or financial return.
- The e-readiness ranking and linked contemporary statistics need period-specific external verification. The surviving source is a 2015 Medium repost, so original comments and some link context may be lost.
Open questions
- Which named companies moved or declined to locate in Israel because of the cited rules?
- What were the original bandwidth targets, costs, and adoption outcomes?
- Did this thesis directly source or exclude identifiable Israel Seed or Benchmark investments?