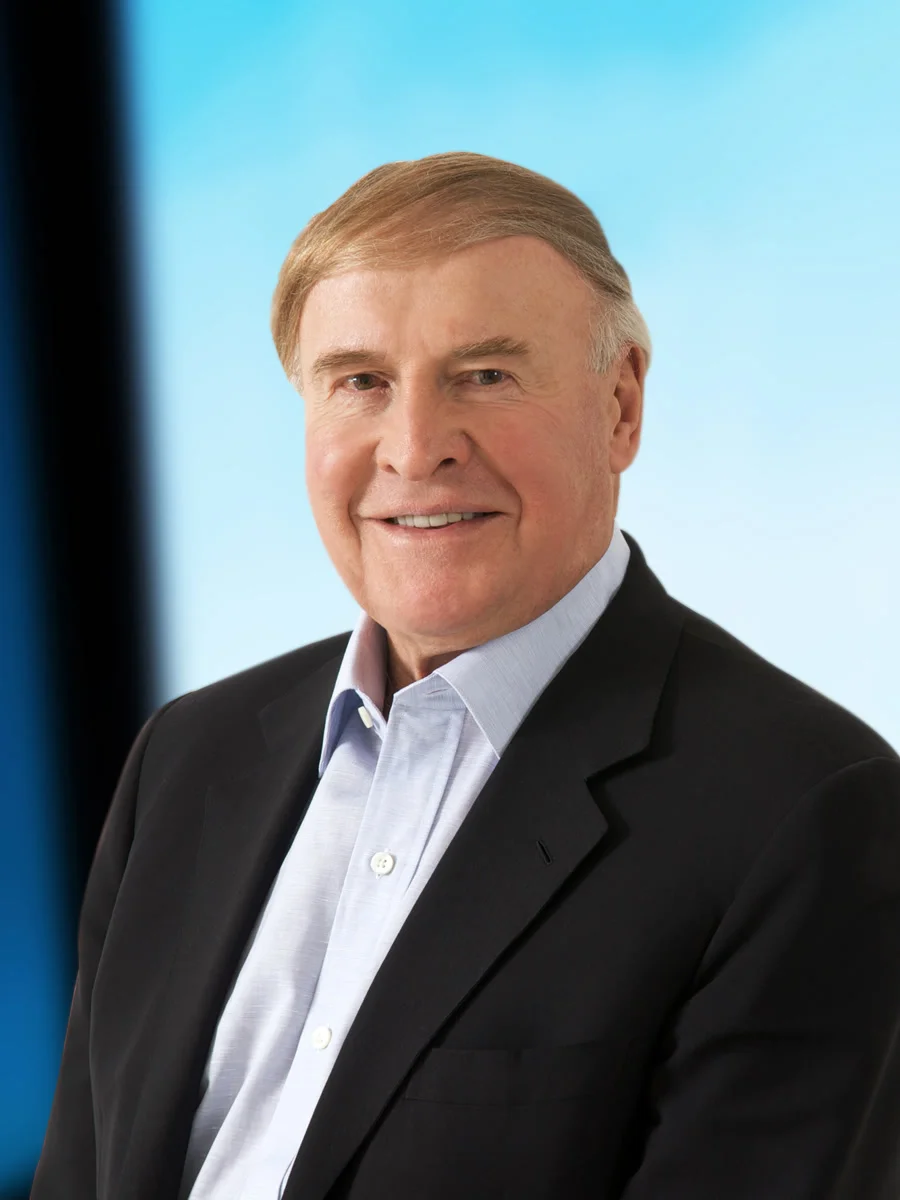
Dick Kramlich
Co-founded NEA and built the first genuinely national, multi-stage venture platform.
Investment biography
Charles Richard “Dick” Kramlich (1935–2025) was a formative institution-builder in American venture capital: a general partner with Arthur Rock from 1969, co-founder of New Enterprise Associates (NEA) in 1977, managing partner through the first seven NEA funds, and later co-founder of Green Bay Ventures. NEA credits him with leading Juniper Networks, Macromedia, Ascend Communications, Immunex, Xoom, and Financial Engines; it separately calls him an early personal investor in Apple. NEA memorial, paragraphs 2–4
His preparation was less “finance-only” than operating apprenticeship. At Kroger in the early 1960s he worked across planning, acquisitions, reporting, investment portfolios, and a company-wide move from manual systems to computing. He later described this as learning the operational detail of a large enterprise before surveying Route 128 technologies for a Boston investment partnership. CHM oral history, Part 1, pp. 2–4
Verified chronology
- 1935–1957: Born in Green Bay, Wisconsin; attended Northwestern University, where he graduated in 1957. Northwestern memorial, “Charles Richard Kramlich ’57”
- 1959–1964: After Harvard Business School, joined Kroger’s modernization effort and gained operating, finance, acquisition, and computerization experience. CHM Part 1, pp. 1–4
- Mid-1960s: Became the only non-Bostonian partner in an old-line Boston investment firm and scouted emerging Route 128 technology. CHM Part 1, pp. 4–5
- 1969: Joined Arthur Rock in California. Their $10 million fund was backed by technology founders including Gordon Moore and Bob Noyce; Kramlich reported bringing roughly one-third of the capital. CHM Part 1, pp. 5–6
- 1977–1978: After the Rock partnership ended, Kramlich joined Frank Bonsal and Chuck Newhall to form NEA, aspiring to a “100-year partnership.” The first fund closed in June 1978 amid difficult fundraising conditions. CHM Part 1, pp. 7–11
- 1977: Personally backed Apple after comparing several personal-computer companies; he judged rivals technically stronger but Apple’s design and founders more entrepreneurial. This was personal capital, not an NEA fund investment. CHM Part 1, pp. 7 and 11–12
- 1979 onward: Built a sequence in personal computing, networking, software, and graphics: 3Com, Forethought/PowerPoint, Silicon Graphics, Macromedia, Ascend, and Juniper. The through-line is documented behavior; any claim that it was a fully articulated master thesis is a researcher inference | moderate. CHM Part 1, pp. 14–31
- 1980s–1990s: Helped turn NEA from three geographically distributed founders into national technology and medical teams. Kramlich described shared economics, low fee dependence, and succession as institutional design rather than administration. CHM Part 2, pp. 6–18
- 1999: Juniper went public; its registration documents identify Kramlich as a director and NEA-affiliated entities as a greater-than-5% holder. Juniper S-1, principal stockholders and related footnote
- 2001: During the post-9/11 market dislocation, NEA 10 bought two million Juniper shares for about $22 million; Light Reading reported an approximately $27 million gain by November. Light Reading, paragraphs 1–3
- 2002–2005: Immunex was acquired by Amgen in a transaction whose final accounting value was approximately $17.7 billion; Adobe announced a $3.4 billion acquisition of Macromedia. These are enterprise values, not NEA proceeds. Amgen 10-Q, “Acquisition of Immunex” Adobe announcement, April 18, 2005
- 2012–2017: Retired from NEA in 2012 but continued through Kramlich Investment Group and Green Bay Ventures; the latter raised a reported $130 million first fund in 2017. NEA memorial, paragraph 5 VentureBeat, February 7, 2017
- 2025: Died February 1 at age 89. NVCA statement, February 4, 2025
Causal account of the edge
Kramlich’s plausible edge was pattern recognition across successive computing layers, coupled to unusually persistent governance and an institution capable of follow-on capital. The mechanism is testable: operating exposure made infrastructure legible; comparative market sweeps reduced attachment to the first deal; personal conviction allowed a small out-of-consensus bet; board involvement and follow-on capital preserved exposure; shared economics enabled the firm to outlive the founder. Evidence supports Apple, 3Com, Forethought, Juniper, and the NEA structure, but not a complete portfolio denominator. researcher inference | moderate. CHM Part 1, pp. 7–35 CHM Part 2, pp. 6–22
Disconfirming evidence matters. Kramlich said 3Com and Silicon Graphics lost opportunities after long success, and Forethought required a solo personal commitment after partner resistance. The record therefore supports persistence and category insight, but also shows governance frictions, missed strategic turns, and survivorship-selected recollection. CHM Part 1, pp. 24–33
People, capital, and influence map
Kroger operating apprenticeship → Arthur Rock partnership → Kramlich
                                                   ├─ Frank Bonsal ─┐
                                                   └─ Chuck Newhall ├─ NEA: national, multi-stage, tech + medical
Entrepreneurs: Jobs/Wozniak → Apple                └────────────────┘
Bob Metcalfe → 3Com → networking pattern → Grand Junction / Ascend / Juniper
Forethought team → PowerPoint → Microsoft
NEA partners + LPs → shared economics / succession → 100-year institution thesis
What remains uncertain
No public, audited deal-by-deal cash-flow ledger separates Kramlich’s economics from NEA’s team record. His reported 41.4% net IRR across the first seven partnerships is direct testimony but remains self-reported, single-source. CHM Part 2, p. 7 Precise Apple cost, ownership, and proceeds are not established in accessible primary records; later stories should not be converted into an invented multiple.
Study guide and narrative synthesis
Read talks for direct voice, investments for no-hindsight exercises and failure postmortems, investment philosophy, mental models, then review. Glossary: LP supplies fund capital; GP manages it; IRR is timing-sensitive; mark-to-market is quoted value, not realization; follow-on is later capital; denominator is the complete comparison set.
Kroger taught that technology matters when it changes operations; Boston taught comparative scouting; Rock supplied concentrated-tech apprenticeship but exposed junior-partner/allocation constraints. NEA converted those lessons into shared economics, national reach, specialist teams, and succession. Apple/Forethought show conviction outside consensus; 3Com/SGI show early insight cannot overcome rigidity; Juniper shows accumulated networking judgment plus flexible follow-on capital. This causal chain is researcher inference | moderate, not proven against a complete losing-deal/cash-flow record. CHM Part 1, pp. 2–35 CHM Part 2, pp. 8–28
The operating system
Kramlich’s philosophy is best reconstructed as: scan broadly, back exceptional human agency, use courage only inside survivable sizing and partnership checks, compound insight through adjacent technology layers, and build an institution capable of staying through the company journey. This synthesis is researcher inference | moderate, grounded in direct oral histories and documented actions rather than an authored manifesto. CHM Part 1, pp. 7–35 Berkeley transcript, pp. 26–27, 42–59
Sourcing
He did category sweeps rather than wait for one inbound pitch: in 1977 he visited multiple PC makers before choosing Apple. Networks compounded; relationships around Apple, 3Com, and former operators produced later software and networking opportunities. documented behavior | strong. CHM Part 1, pp. 7, 11–18
Decision rule: map the alternative set first, then ask why this team will create a category rather than merely win a feature comparison.
Picking
Kramlich prioritized entrepreneurial “spark,” design sense, and mission alongside technology. Apple is the clearest case; Pradeep Sindhu at Juniper and Bob Metcalfe at 3Com reinforce the pattern. investor-stated | moderate because the examples are winner-selected. CHM Part 1, pp. 11–16 Berkeley transcript, pp. 55–59
Decision rule: require evidence of founder agency—recruiting, customer learning, product taste, or technical authority—not charisma alone.
Portfolio and follow-ons
NEA’s multi-stage, multi-sector platform and “dynamic capital allocation” sought to move capital toward opportunities while specialist teams supplied judgment. Kramlich claimed scale reduced dollar loss ratios, but published data do not verify this. investor-stated | provisional. CHM Part 2, pp. 18–28
Decision rule: reserve across time and stage only when the firm has earned informational advantage; do not equate more capital with better selection.
Boards and crisis behavior
Venture is a shared uncertain voyage; milestones guide progress, but crises are unscheduled. Kramlich viewed team construction and strategic redirection as core investor work. Venture Voices, 01:01:00–01:03:00 Forethought shows hands-on rescue; 3Com and SGI show that boards do not guarantee adaptation. investor-stated | strong for the role, documented behavior | moderate for efficacy.
Decision rule: before investing, identify which crisis actions the investor can actually influence—recruiting, financing, focus, partnerships—and where the board will remain powerless.
Risk, courage, and dissent
Kramlich’s “courage” was not numerical recklessness. Partnership checks constrained individual blind spots; when consensus failed on Forethought, he used personal capital and a transparent cost-transfer offer. Berkeley transcript, pp. 26–27, 42–43 CHM Part 1, pp. 18–23
Decision rule: write the dissent, cap the exception, pre-negotiate conflict treatment, and define what evidence would earn institutional follow-on.
Exits and endurance
He valued patient company building, but outcomes included acquisitions and distributions. Microsoft’s continued investment after Forethought and Amgen’s integration of Immunex show that sale can transfer a product into a stronger scaling vehicle. CHM Part 1, pp. 20–23 Amgen completion release
Decision rule: judge exit against the next owner’s capacity, financing needs, founder objectives, and the fund’s duration—not prestige.
Institution design as investment strategy
The non-eponymous name, shared economics, specialist teams, and succession mechanisms were designed for a century rather than a star’s career. CHM Part 2, pp. 8–18 This can improve sourcing, reserves, and learning, but scale may also dilute accountability. investor-stated | strong on design; researcher inference | moderate on causal performance.
Falsifiable edge thesis
Prediction: a Kramlich-led portfolio should over-index to enabling technologies, persistent founder relationships, follow-on investments during dislocation, and long holding periods; it should outperform peers after controlling for vintage and sector. It would be overturned by audited data showing ordinary selection, returns driven solely by one outlier, or no relationship between board persistence and outcomes. The public record cannot complete this test.
Modern VC translation (as of 2026-08-24)
- Transfer: category sweeps, founder-agency evidence, explicit dissent, long-term incentive alignment, and source/ownership discipline.
- Modify: today’s larger platforms need named deal owners and attribution rules to avoid “team” becoming unaccountability.
- Do not transfer blindly: public-market follow-ons require mandate, liquidity, and conflict controls; personal exceptions can create severe allocation conflicts.
- Observable signals: founder recruiting velocity, customer pull before scale, reserve decisions tied to milestones, board interventions logged before outcomes, and LP economics driven by carry rather than fee expansion.
Pareto 80/20 — what drove the record
No public deal-level cash-flow denominator supports a literal 80/20 calculation. The rankings are directional and keep firm, personal, and team attribution separate.
| View | Rank | Case | Basis / supported mechanism | Attribution | Confidence |
|---|---|---|---|---|---|
| Economic contribution | 1 | Juniper | Kramlich called it the largest financial gain among discussed networking deals; >5% NEA holding documented pre-IPO | Kramlich + NEA vehicles/team | Moderate; return not public |
| Economic contribution | 2 | Immunex | Acquisition ultimately accounted at ~$17.7bn; ownership/proceeds unavailable | Kramlich + NEA medical team | Provisional |
| Economic contribution | 3 | Ascend | Firm and Kramlich identify it as a billion-dollar outcome; cash flows unavailable | Kramlich + NEA team | Provisional |
| Historical importance | 1 | Apple | Early personal backing of a defining PC company | Personal Kramlich capital; later investors/builders dominate outcome | Strong on action, insufficient on economics |
| Historical importance | 2 | 3Com | Early Ethernet commercialization and networking pattern | Kramlich/NEA + Metcalfe/team | Moderate |
| Historical importance | 3 | Forethought/PowerPoint | Personal dissent bet; Microsoft acquisition embedded presentation software | Kramlich + founders; later Microsoft investment | Moderate |
| Decision-learning value | 1 | Forethought | Consensus rejection, personal sizing, cost-transfer offer, pivot | Kramlich + NEA partners | Strong retrospective |
| Decision-learning value | 2 | 3Com | Category insight plus failure to preserve strategic position | Shared board/company attribution | Moderate |
| Decision-learning value | 3 | Juniper public add-on | Price dislocation, known-company underwriting, mandate flexibility | NEA 10/Kramlich | Strong contemporaneous |
Sources: Berkeley transcript, pp. 45–59, Juniper S-1, principal stockholders, Amgen 10-Q.
Excluding Juniper, the record still includes Apple, 3Com, PowerPoint, Macromedia, Ascend, and Immunex; therefore the historical record is not a one-outlier narrative. Economic contribution without Juniper remains non-computable.
Evidence boundary and searched denominator
Scope searched: Kramlich personal capital; Arthur Rock partnership; NEA I–XIII; Green Bay Advisors/Ventures; 1969–2025; Dick/C. Richard/Charles Richard Kramlich; NEA memorial and portfolio claims, CHM/Berkeley oral histories, SEC filings, transaction records, Forbes, NFX Signal, and contemporaneous press. Follow-ons are grouped with the originating company; acquisitions are outcomes, not new deals.
| Measure | Count | Scope / reason |
|---|---|---|
| Publicly claimed/known | 20+ | Named across oral histories, NEA, Forbes, and databases; not a complete portfolio |
| Searched | 20 | Named cases checked across at least two routes where possible |
| Researched | 12 | Apple, 3Com, Forethought, SGI, Grand Junction, Ascend, Juniper, Immunex, Macromedia, Financial Engines, Xoom, Force10 |
| Sufficiently reconstructed | 4 | Apple, Forethought, Juniper, Immunex; still incomplete on venture cash flows |
| Unresolved | 8+ | Missing cost, ownership, milestones, or proceeds |
| Excluded | 0 | Later Green Bay names retained as discovery leads, not credited to Kramlich absent evidence |
Coverage fraction: not computable. The denominator of all Kramlich-led versus team-attributed investments is not public. Public lists select winners, producing severe survivorship and attribution bias.
Historical market, regulatory, and base-rate context
NEA’s first fund was raised before the 1979 clarification permitting pension fiduciaries to consider portfolio-level risk, and Kramlich recalled that the founders could not foresee the institutional capital expansion. This makes the national “100-year” platform an ex-ante organizational bet, not an obvious reaction to abundant capital. Berkeley transcript, pp. 42–43 By Juniper’s 1999 IPO, internet traffic and telecom equipment demand made routers a legible growth market, but the filing still foregrounded concentration, competition, and rapid technological change. Juniper S-1, “Risk Factors”
Vehicle economics and incentives
Apple was personal capital because NEA had not closed and partners declined; later NEA holdings belonged to affiliated limited partnerships, not Kramlich personally. CHM Part 1, p. 7 Juniper S-1, stockholder footnote Kramlich described NEA’s economics as deliberately team-oriented and fee-light, with general-partner wealth tied to LP gains; this is direct testimony, not an audited partnership-agreement analysis. CHM Part 2, pp. 8–13
Case 1 — Apple: comparative scouting and a personal exception
Ex ante. In 1977 Kramlich visited several PC companies. He judged two alternatives technically stronger, while Apple combined color/graphics, design sensibility, and founder energy. NEA was not yet funded, and his partners viewed the check as too small or premature. CHM Part 1, pp. 7, 11–12
Decision. He invested personally and offered his future partners participation. Exact amount, price, ownership, terms, and later proceeds are insufficient public record.
Outcome and lesson. Apple went public in 1980. The lesson is not “ignore technical quality”; it is that product experience and founder agency can outweigh a narrow engineering comparison. researcher inference | moderate. The missing denominator—other charismatic teams he backed—prevents treating “spark” as validated alone.
Case 2 — Forethought/PowerPoint: dissent, sizing, and pivot
Ex ante. Forethought initially pursued software concepts around Apple’s ecosystem. After internal difficulties, a team demonstrated presentation software when overhead transparencies dominated. Partners resisted more capital; Kramlich personally funded a reported $240,000, with an offer that the partnership could acquire his position at cost if it succeeded. CHM Part 1, pp. 18–23
Governance and milestones. The company focused on the presentation product, named PowerPoint, and gained Apple-related validation before Microsoft acquired Forethought. Kramlich later emphasized Microsoft’s large subsequent development investment, complicating sole credit for the outcome. CHM Part 1, pp. 20–23
Lesson. A capped personal exception can preserve upside without forcing partnership capital; a fair ex-ante transfer rule reduces agency conflict. documented behavior | moderate.
Case 3 — Juniper: concentrated category knowledge and follow-on flexibility
Ex ante. Juniper attacked high-performance internet routing against powerful incumbents. Its S-1 documents technological, customer-concentration, manufacturing, and competition risks and identifies Kramlich as a director with NEA-affiliated entities holding more than 5%. Juniper S-1, “Risk Factors,” management, principal stockholders
Decision and governance. Kramlich’s retrospective account credits Pradeep Sindhu as the technical core and says he encouraged focus rather than acquisition-led dilution. Berkeley transcript, pp. 55–59
Follow-on. In September 2001 NEA 10 reportedly bought two million public shares for about $22 million; by November Light Reading reported a $27 million mark-to-market gain. Light Reading, paragraphs 1–4 Final realized proceeds are unknown.
Lesson. Deep company knowledge may create an advantage during public dislocation, but a short-term mark is not a venture return. documented behavior | strong.
Case 4 — Immunex: cross-domain range and team attribution
Kramlich described Immunex as an early pure cancer/biotechnology company and linked the experience to NEA’s later specialist medical team. CHM Part 2, pp. 24–28 Amgen’s 2002 filing records approximately $17.7 billion total transaction value, including about $2.5 billion cash, while the FTC required remedies in concentrated drug markets. Amgen 10-Q FTC case
The proper lesson is institutional: a generalist’s early exposure can justify specialist capability. It is not evidence that Kramlich personally underwrote every scientific decision. researcher inference | moderate.
Misses, failures, and anti-portfolio
- 3Com: Kramlich believed it should have become a larger networking leader and left the board in 1987 after concluding the company was underreaching. This is a strategy/governance miss despite a successful company. CHM Part 1, pp. 24–26
- Silicon Graphics: he described roughly a decade of success followed by loss of position, illustrating that category leadership can decay when organizations resist change. CHM Part 1, pp. 25–31
- Intel opportunity: Berkeley testimony describes partnership conflict around Intel participation; the record warns that relationship and vehicle constraints shape “misses.” Berkeley transcript, pp. 33–35
- Unknown write-offs: no public comprehensive list exists. Any failure rate would be fabricated.
Portfolio-level conclusions
The observed record clusters in enabling infrastructure, networking, graphics/software, and biotechnology, with later extensions into energy and industrial systems. The evidence supports patience, follow-on capacity, and team specialization; it does not support precise individual attribution or a literal power-law split. The strongest alternative explanation is that Kramlich benefited from a uniquely favorable semiconductor-to-internet era and NEA’s growing capital base. A falsifiable test would compare Kramlich-led deals with contemporaneous NEA deals and peer funds on entry stage, ownership, reserves, loss rate, and realized cash flows—data not publicly available.
Acceptance remediation: denominator, vehicle, and IC decisions
Reproducible ledger
Twenty searched names: Apple, 3Com, Forethought, SGI, Grand Junction, Ascend, Juniper, Immunex, Macromedia, Financial Engines, Xoom, Force10, Dallas Semiconductor, Healtheon, Tableau, CITIC Pharmaceuticals, Wayport, TAE Technologies, Dropbox, and Spotify. The first twelve were researched beyond discovery; Apple, Forethought, Juniper, and Immunex were reconstructed; Dallas through TAE remain unresolved; Dropbox and Spotify are excluded from Kramlich credit because the Schiller/Kramlich split is unknown. Thus a coverage fraction remains non-computable.
Vehicle mechanics
NEA used roughly twelve-year partnerships with extensions; actual extension votes are unknown. Kramlich described modest fees, wealth tied to LP profit, mutual early decisions, later specialist-team review with GP approval, dynamic reserves, national then India/China teams, and shared management-company economics for succession. Actual fee/carry schedules, hurdles, clawbacks, voting thresholds, geographic check authority, reserve ratios, key-person clauses, and deal-level liquidity remain unavailable. CHM Part 2, pp. 8–28
Apple IC exercise (1977; outcome hidden)
Thesis: consumer computing plus product taste/founder agency. Alternatives: two technically stronger PC companies. Sponsor/diligence: Kramlich category sweep; references/economics unknown. Dissent: partners declined pre-fund participation. Terms, ownership, governance, recruiting, and follow-ons: unknown. Risks: rivals, demand, working capital, conflict. Hypothetical kill criteria/milestones: pass absent shipment, dealer pull, or recruiting; reassess at shipment and repeat demand. Vote: small personal invest, fund pass. Outcome revealed: 1980 IPO; Kramlich proceeds unknown. CHM Part 1, pp. 7, 11–12
Forethought IC exercise (outcome hidden)
Thesis: presentation software replaces transparencies. Alternatives: earlier products, Oracle route, sale, stop. Sponsor/diligence: Kramlich, live demo, Apple interest; market sizing unknown. Partnership rejected the round but allowed a reported $240,000 personal check/cost-transfer offer; security/ownership/formal governance unknown. Risks: pivot, management, platform, capital. Hypothetical kill criteria: stop absent repeat use; milestones are product, bookings, distribution, stable team. Vote: personal invest. Outcome revealed: Microsoft acquisition and material later Microsoft development; scaling credit is shared. CHM Part 1, pp. 18–23
Juniper IC exercise (outcome hidden)
Thesis: purpose-built high-performance routers versus Cisco/incumbents. Sponsor: Kramlich director; sourcing, negotiation, approval split unknown. Terms: S-1 gives Series C $8.93, D1 $11.03, and >5% affiliated NEA ownership. Governance: board role; follow-ons include private rounds and later public add. Risks: concentration, manufacturing, incumbents, technical change. Hypothetical kill criteria/milestones: require architecture advantage, carrier wins, reliability, margin, diversification. Vote: invest; refresh downside before public add. Outcome revealed: IPO; 2001 add reached reported ~$49m, not proven realized. Juniper S-1 Light Reading
Immunex IC exercise (outcome hidden)
Thesis: focused immunology biotech; original molecule thesis, alternatives, team vote, terms, ownership, governance, diligence and financing are unknown. Risks: biology, trials, FDA, manufacturing, duration. Hypothetical kill criteria: failed validation/safety/financing; milestones: trials, manufacturing, regulators. Vote: insufficient record. Outcome revealed: Amgen acquisition; ~$17.7bn transaction accounting is not NEA return. Amgen 10-Q
Full failure postmortems
3Com: Ethernet/Metcalfe was the original thesis; by 1985–1987 Kramlich saw strategic blinders. Capital response is unknown. He says he left the board after failing to redirect it; distributions are unknown. Lesson: leadership needs renewal (investor-stated | moderate). Management, board, technology and competitors share causality; “should have been Cisco” is untestable. CHM Part 1, pp. 14–16, 24–26
Silicon Graphics: visual-computing thesis produced roughly a decade of success, then rigidity; contemporaneous warnings, capital response, and exit are unknown. Kramlich retrospectively said it lost position. Lesson: confront threats before identity hardens (researcher inference | moderate). Industry shifts and company choices share causality. CHM Part 1, pp. 24–31
Intel: a partnership-allocation miss, not company failure. Kramlich proposed participation; amount/exposure uncertain; Rock held senior power. Missed profit is non-computable. Claimed process change: mutuality/shared economics at NEA (investor-stated | moderate). Dilution, holding, distribution counterfactuals are unknowable. Berkeley, pp. 33–35
Completed-peer comparison
| Dimension | Kramlich/NEA | Doriot/ARD | Whitney/J.H. Whitney |
|---|---|---|---|
| Sourcing/picking | category sweeps; founder agency | technical/academic; management development | social/founder network |
| Vehicle | funds plus personal exceptions | listed development-capital company | partnership/family roots |
| Portfolio/governance | specialists; boards/team checks | broad; management partnership | broad; sponsor/director |
| Incentives/failures | shared economics; renewal/allocation misses | corporate constraints; outlier dependence | principal-led; denominator bias |
Evidence: Doriot, Whitney. researcher inference | moderate; returns are not commensurable.
Coverage and evidence base
No book, sustained blog, shareholder-letter archive, or authenticated essay corpus by Kramlich was found. The written priority set therefore consists of institutional memorial statements, filings connected to his board roles, and contemporaneous deal documents—not authorial “writings” in the usual sense. Of ten priority written records, seven were fully accessible and analyzed, the Forbes profile was partial, and The Power Law plus VC: An American History were metadata-only. Oral histories are analyzed in talks.md, not double-counted here.
NEA memorial (2025)
The memorial’s argument is that Kramlich’s durable achievement combined successful investment selection with institutional continuity. Its reasoning moves from his 1969 entry, through the three-founder “100-year partnership,” to named outcomes and succession. NEA memorial, paragraphs beginning “A true pioneer” through “Dick once said”; no stable paragraph IDs The decision implication is that fund architecture and founder support are part of investing, not back-office concerns. institutional retrospective | moderate. Its limitation is obvious: it is an appreciation, with no losing-case denominator or attribution protocol.
Juniper Networks S-1 (1999)
The filing is not Kramlich-authored, but it is the strongest contemporaneous written record for his Juniper involvement. It establishes that he was a director and that affiliated NEA entities held more than 5% before the IPO, while explicitly separating his proportional interest from beneficial ownership. Juniper S-1, principal-stockholder footnote That distinction prevents a common error: treating firm-held shares as Kramlich’s personal position. contemporaneous record | strong.
Light Reading, “NEA Turns to Trading” (2001)
This contemporaneous report documents a later Juniper decision: NEA 10 bought two million public shares for about $22 million immediately after the September 2001 reopening. The reported $27 million gain was mark-to-market at publication, not an audited realized return. Light Reading, paragraphs beginning “Take Dick Kramlich” through “Three weeks”; no stable paragraph IDs Operationally, the episode shows mandate flexibility and willingness to add when price disconnected from a known company’s fundamentals. documented behavior | strong for the purchase; contemporaneous report | moderate for the gain.
Amgen–Immunex transaction records (2002)
Amgen’s filing records 244.6 million shares plus roughly $2.5 billion cash and a total accounting value around $17.7 billion; the FTC record identifies competition concerns in three biopharmaceutical markets. Amgen 10-Q, “Acquisition of Immunex” FTC case summary These documents validate outcome magnitude and strategic context but do not establish NEA’s proceeds or Kramlich’s sole credit. contemporaneous record | strong.
Adobe–Macromedia announcement (2005)
Adobe announced an all-stock transaction valued at approximately $3.4 billion, framing it as a combined platform for rich interactive content across devices and operating systems. Adobe SEC exhibit, announcement The record supports historical importance and exit value, not venture return contribution. contemporaneous record | strong.
Green Bay Ventures coverage (2017)
VentureBeat reported a $130 million inaugural fund focused on early-stage technology intersecting with energy, manufacturing, telecommunications, and transportation. VentureBeat, article heading and opening fund-description paragraphs; no stable paragraph IDs The shift broadens the enduring “enabling infrastructure” pattern, but attributing every Green Bay investment to Kramlich would overstate his role. contemporaneous report | moderate.
Cross-source synthesis
The written record supports three stable commitments: institution over eponymous franchise, active governance with ownership discipline, and patient exposure to infrastructure. It does not contain a polished Kramlich manifesto. The strongest intellectual record is oral; any clean doctrine in this package is therefore reconstructed and labeled. NEA memorial Juniper S-1
Intellectual chronology, evolution, and contradictions
Contemporaneous filings shift the evidence from retrospective storytelling to actions: board service, holdings, financing, acquisitions, and later public purchases. The contradiction is between Kramlich’s partnership-first rhetoric and moments when he acted personally after partnership resistance. Rather than invalidating the doctrine, Forethought suggests a boundary condition: consensus controls risk, but a small personally funded exception can preserve option value. researcher inference | moderate. CHM Part 1, pp. 18–23
Decision playbook and modern translation
Historical rule: compare the full category, reserve conviction for differentiated teams, size dissent so failure is survivable, and distinguish company value from fund economics. Diagnostic questions: What is the searched alternative set? Which claim is contemporaneous? Who owns the shares? Is a quoted “return” realized, marked, or enterprise value? Failure mode: retrofitting a thesis onto winners.
Modern VC translation (as of 2026-08-24) — researcher inference | moderate: use filings and financing documents to audit storytelling; treat institution design as a compounding asset; permit explicit, capped exceptions when a consensus process rejects an unusually asymmetric opportunity. Today’s larger funds and faster rounds make Kramlich’s long holding periods harder to reproduce, so fund duration and reserves must be tested before invoking “patience.”
Best writings and unresolved record
- Juniper S-1 — strongest contemporaneous ownership and governance evidence.
- Amgen 10-Q — definitive Immunex transaction accounting.
- Light Reading Juniper report — rare contemporaneous decision-level account.
- Adobe acquisition exhibit — definitive Macromedia outcome record.
- NEA memorial — best institutional summary, read skeptically.
Unresolved: no Kramlich essay archive; no public LP letters; inaccessible book passages; no audited deal ledger.
Full inventory reconciliation and source schema
The named priority inventory is: NEA memorial (full); Juniper S-1 (full); Light Reading Juniper report (full); Amgen 10-Q (full); FTC Immunex record (full); Adobe–Macromedia exhibit (full); VentureBeat Green Bay report (full); Forbes profile (partial); The Power Law (metadata-only); VC: An American History (metadata-only). These are evidence records, not Kramlich-authored writings. Each accessible subsection above identifies context, access, argument/evidence, assumptions, decision use and contradiction. The two books are not content-analyzed. Forbes supports only visible profile claims. The central contradiction—no authored corpus but rich retrospective speech—is preserved, not filled with proxy authorship.
Coverage denominator
Nine priority spoken/archival appearances were located. Five full direct-voice transcripts were processed (CHM Parts 1, 2, and the 2017 fourth session; Berkeley Venture Capital Greats; Venture Voices). CHM Part 3 is catalog-only; the Smithsonian transcript is in-person-only; and two reachable YouTube panels remain unprocessed because no stable official transcript/caption export was retrieved. Metadata-only and unprocessed sources are excluded from thematic claim counts. CHM appreciation, heading “Learn More” Smithsonian, item NMAH.AC.1467_ref16, “In-Person Research”
CHM oral history, Part 1 (2015)
This is the indispensable deal-and-formation narrative. Kramlich connects Kroger operations to technology investing, reconstructs his handwritten approach to Arthur Rock, explains the Rock partnership, and offers granular Apple, 3Com, Forethought/PowerPoint, and Silicon Graphics cases. CHM Part 1, pp. 1–31 Apple reveals comparative scouting; 3Com reveals early recognition plus later frustration; Forethought reveals dissent and personal-risk sizing. investor-stated | strong for beliefs, retrospective witness | moderate for deal details.
CHM oral history, Part 2 (2015)
Part 2 is the best source on fund architecture. Kramlich reports 41.4% net annual IRR over seven partnerships, describes the 100-year ambition, argues that fees should not create wealth, and explains team specialization and dynamic capital allocation. CHM Part 2, pp. 7–28 The return remains self-reported, single-source; the organizational mechanisms are investor-stated | strong.
Berkeley Venture Capital Greats (2006)
This 79-page transcript is unusually candid about errors and checks on ego. Kramlich says mistakes are necessary but painful, portrays partners as safeguards against individual blind spots, and walks through networking investments from 3Com to Juniper. Berkeley transcript, pp. 26–27, 42–59 It reinforces courage as calibrated action, not bravado. investor-stated | strong.
Venture Voices with Carl Thoma (2008)
Kramlich defines venture as a shared voyage with entrepreneurs where milestones exist but crises cannot be scheduled. The investor’s work is adaptive team construction under uncertainty. Venture Voices, 01:01:00–01:03:00, pp. 1–3 investor-stated | strong; the short, staged format limits depth.
CHM oral history, fourth session (2017)
This full session covers information tools, deal terms, expert networks, and change in venture practice. Kramlich says early terms were simple and fair, and describes technical originators among early LPs as deep validation resources. CHM fourth session, PDF pp. 2–6 investor-stated | strong for beliefs; retrospective witness | moderate for historical practice. He also acknowledges being in the right place at the right time, missed opportunities, and a NorthStar failure attributed to strategic rigidity and a missed IPO window. CHM fourth session, PDF pp. 7, 14 investor-stated | moderate.
Unprocessed and metadata-only appearances
Part 3 returned 403 and a guessed archive-text route did not resolve. Both YouTube pages were reachable, but no stable official transcript/caption export was obtained. The Smithsonian record explicitly requires in-person research. CHM appreciation, heading “Learn More” Smithsonian, item NMAH.AC.1467_ref16 These four sources are metadata-only or unprocessed | insufficient public record and excluded from framework counts.
Recurring frameworks and evolution
- People before spreadsheet certainty: repeated from Apple’s “spark” to Venture Voices’ shared voyage. CHM Part 1, pp. 7, 11–12 Venture Voices, pp. 1–3
- Courage with checks: personal conviction matters, while partners constrain blind spots. Berkeley transcript, pp. 26–27, 42–43
- Follow technologies through adjacent layers: Apple → networking → graphics/software → internet infrastructure. This sequence is documented; a unified master thesis is researcher inference | moderate. CHM Part 1, pp. 11–31
- Institution before individual brand: the 100-year partnership becomes more explicit in later interviews, plausibly because Kramlich could then observe succession. CHM Part 2, pp. 8–18
Contradictions and memory risk
Kramlich praises partnership discipline yet sometimes bypassed consensus with personal capital. He celebrates long-duration company building but also recounts strategic failure at 3Com and SGI. Deal stories were recorded decades after outcomes; filings should control on ownership and transaction values. CHM Part 1, pp. 18–33
Listen/read these five first
- CHM Part 1 — formation plus richest deal detail.
- Berkeley Venture Capital Greats — best candor on courage, errors, and networking.
- CHM Part 2 — best institutional mechanics.
- Venture Voices — concise partnership definition.
- CHM fourth session — terms, expert networks, self-critique, and NorthStar failure.
Archive-attempt reconciliation
CHM Part 4 is now processed in full from the 2020 archive transcript, printed pp. 1–24, bringing the full-transcript denominator to five. Part 3 catalog ID 102740141 returned HTTP 403 and an archive-PDF guess returned HTML. The two panel YouTube pages supplied neither stable transcript nor captions through the available interface. Smithsonian NMAH.AC.1467_ref16 is explicitly in-person research. Part 3, panels, and Smithsonian remain unprocessed and are not used for claims.
Model inventory and evidence boundary
Seven distinct models recur across the notes and phase documents. They are reconstructed unless explicitly labeled investor-stated. The public record is winner-heavy; model efficacy is therefore moderate at best. No additional plausible model was included solely from a memorial quotation.
1. Entrepreneurial spark is evidence only when behavior makes it observable
- Attribution: investor-stated.
- Support: moderate.
- Provenance: Apple comparison in 1977. CHM Part 1, pp. 7, 11–12
- Mechanism: unusual product taste and agency may create adoption advantages not captured by engineering benchmarks.
- Historical context: personal computing lacked settled product conventions.
- Decision rule: translate “spark” into product, recruiting, customer, and speed evidence.
- Diagnostic questions: What did the founders do that stronger engineers did not? What evidence predates the outcome?
- Examples: Apple (documented application); 3Com/Metcalfe (retrospective application); Juniper/Sindhu (retrospective application). CHM Part 1, pp. 11–16 Berkeley transcript, pp. 55–59
- Counterexample: charismatic teams among undisclosed losses are not observable; efficacy remains denominator-limited.
- Limits: vulnerable to halo effects, bias, and hindsight.
- Evolution: remained stable from Apple recollections through late-career founder language.
- Modern translation: require an evidence rubric before partner discussion; charisma is not a score.
2. Map the category before choosing the company
- Attribution: documented behavior.
- Support: moderate.
- Provenance: 1977 PC sweep and earlier Route 128 scouting. CHM Part 1, pp. 4–7
- Mechanism: comparison reveals which differences are structural versus pitch framing.
- Historical context: emerging categories had fluid architectures and many local competitors.
- Decision rule: create an alternative map before conviction.
- Diagnostic questions: Which substitutes have been seen? Why now? Which layer captures value?
- Examples: PC companies (documented); networking from 3Com through Juniper (retrospective); biotechnology capability-building (researcher inference). Berkeley transcript, pp. 45–59 CHM Part 2, pp. 24–28
- Counterexample: comparison did not prevent 3Com or SGI from later strategic decline.
- Limits: maps date quickly and can privilege visible competitors.
- Evolution: broadened from local technology scouting to sector/geography teams.
- Modern translation: maintain live market maps linked to financing and customer evidence.
3. Courage requires a survivable exception structure
- Attribution: investor-stated plus documented behavior.
- Support: strong for process; moderate for results.
- Provenance: Berkeley courage discussion and Forethought case. Berkeley transcript, pp. 42–43 CHM Part 1, pp. 18–23
- Mechanism: capped downside preserves asymmetric upside without corrupting partnership allocation.
- Historical context: small early funds made every exception material.
- Decision rule: size dissent, disclose it, predefine transfer rights, and set milestones.
- Diagnostic questions: What is lost if wrong? What conflict arises if right? What new evidence changes consensus?
- Examples: Forethought (documented); Apple personal pre-fund investment (documented); post-9/11 Juniper purchase (documented, but institutional). Light Reading
- Counterexample: personal exceptions can become cherry-picking or allocation abuse.
- Limits: today’s policies may prohibit personal parallel investments.
- Evolution: from individual bets to mandate-flexible institutional capital.
- Modern translation: use written exception policy and compliance approval.
4. Partners are a cognitive risk-control system
- Attribution: investor-stated.
- Support: strong.
- Provenance: Berkeley discussion of partners limiting personal boundaries. Berkeley transcript, pp. 26–27
- Mechanism: independent judgment checks ego, overconfidence, and incomplete expertise.
- Historical context: venture moved from individual syndicates toward durable firms.
- Decision rule: expose assumptions to partners who can veto or reshape the thesis.
- Diagnostic questions: Is dissent substantive? Are incentives shared? Who records the pre-mortem?
- Examples: NEA formation (documented); Forethought disagreement (documented); specialist tech/medical teams (investor-stated). CHM Part 2, pp. 8–18, 24–28
- Counterexample: consensus initially rejected Forethought; checks can suppress outliers.
- Limits: groupthink and political bargaining.
- Evolution: scaled from three founders to specialist teams and succession.
- Modern translation: reward calibrated dissent and retain a reversible exception path.
5. Follow the enabling layer across technology generations
- Attribution: researcher inference.
- Support: moderate.
- Provenance: observed sequence Apple, 3Com, PowerPoint, SGI, Ascend, Juniper. CHM Part 1, pp. 11–31
- Mechanism: knowledge, talent networks, and customer insight compound across adjacent infrastructure layers.
- Historical context: computing shifted from standalone machines to graphics, software, and networks.
- Decision rule: after a win, map upstream/downstream bottlenecks instead of cloning the product.
- Diagnostic questions: What new constraint appears after adoption? Which alumni carry insight? Where does recurring value accrue?
- Examples: Apple→3Com (inferred); 3Com→Grand Junction/Ascend/Juniper (inferred); graphics→Forethought/Macromedia (inferred). Berkeley transcript, pp. 45–59
- Counterexample: 3Com and SGI show layer leadership can be lost.
- Limits: narrative may be reconstructed from winners.
- Evolution: later extended to industrial/energy intersections at Green Bay. VentureBeat
- Modern translation: build adjacency maps, but demand independent customer evidence.
6. Patient capital still needs strategic renewal
- Attribution: investor-stated and researcher synthesis.
- Support: moderate.
- Provenance: long holding-period language plus 3Com/SGI regrets. Forbes profile CHM Part 1, pp. 24–31
- Mechanism: time lets complex systems mature, but success creates organizational rigidity.
- Historical context: hardware and biotechnology required long development and capital cycles.
- Decision rule: pair long duration with explicit strategic-renewal reviews.
- Diagnostic questions: What advantage is decaying? What adjacent architecture threatens it? When should leadership change?
- Examples: Juniper focus (retrospective); Immunex long cycle (documented outcome); 3Com/SGI (counterexamples). Amgen 10-Q
- Counterexample: patience without adaptation entrenches decline.
- Limits: boards may identify change but fail to cause it.
- Evolution: later NEA scale created capacity for longer specialist programs.
- Modern translation: reserve runway and strategic milestones separately.
7. Build the fund as a century-scale compounding institution
- Attribution: investor-stated.
- Support: strong on design, provisional on performance causality.
- Provenance: CHM Part 2 and NEA memorial. CHM Part 2, pp. 8–18 NEA memorial
- Mechanism: shared economics, succession, specialist teams, and LP alignment preserve knowledge and relationships.
- Historical context: many early firms centered on named founders and finite partnerships.
- Decision rule: design economics and leadership transitions before they become emergencies.
- Diagnostic questions: Who owns attribution? Can the next generation lead? Does fee income weaken discipline?
- Examples: non-eponymous NEA (documented); leadership succession (documented); tech/medical teams (investor-stated).
- Counterexample: platform scale can diffuse ownership and obscure individual performance.
- Limits: public evidence cannot isolate institutional design from favorable vintages and scale.
- Evolution: Kramlich remained active after NEA through a smaller Green Bay vehicle, showing the platform model was not the only viable form.
- Modern translation: measure partner development, sourcing transfer, reserves, and net LP outcomes—not AUM alone.
Attempted-route ledger for model shortfalls
For every model, the run searched CHM Parts 1–4, Berkeley oral histories, Smithsonian finding aids, NEA/NVCA records, SEC filings, transaction releases, criticism/lawsuit queries, obituaries, books, and portfolio databases. Missing counterexamples and deal economics reflect absent public fund records, not unattempted discovery. The models above generally have three grounded examples and multiple sources; causal efficacy remains explicitly limited where evidence is retrospective or winner-selected.
Model-specific modern translations and route ledgers
Model 1 — entrepreneurial spark
Modern VC translation (as of 2026-08-24): Transfer behavioral founder-agency tests; AI-assisted demos lower the cost of appearing fast. Applicability signals are referenceable recruiting, retention, and repeated customer pull; misuse risk is charisma bias. Analyst-created hypothetical: require three dated behavioral proofs. Routes: Apple, Juniper and 3Com oral-history/filing evidence plus founder-countertestimony searches; missing evidence is a disclosed losing cohort.
Model 2 — category map
Modern VC translation (as of 2026-08-24): Transfer alternative mapping, but global rapid company formation makes maps perishable. Signals are stable buyer budget and a shared architectural bottleneck; misuse risk is false completeness. Hypothetical: update maps at each financing. Routes: CHM category sweeps, Berkeley networking sequence, portfolio databases; missing evidence is the full screened list.
Model 3 — survivable exception
Modern VC translation (as of 2026-08-24): Transfer explicit dissent/caps only where compliance permits. Signals are asymmetric downside and a milestone capable of reversing consensus; misuse risk is cherry-picking outside the fund. Hypothetical: require compliance/LP conflict clearance. Routes: Forethought, Apple, Juniper and criticism/lawsuit searches; missing evidence is the partnership policy.
Model 4 — partners as cognitive controls
Modern VC translation (as of 2026-08-24): Transfer independent challenge; large specialist committees make consensus theater a new risk. Signals are recorded disconfirming evidence and calibrated dissent. Hypothetical: assign a non-deal-team red reviewer. Routes: Berkeley partnership evidence, CHM governance, Forethought; missing evidence is voting records and losing memos.
Model 5 — enabling-layer adjacency
Modern VC translation (as of 2026-08-24): Transfer bottleneck mapping; cloud/software layers can commoditize faster than hardware. Signals are rising spend, switching cost, and alumni formation; misuse risk is winner-derived storytelling. Hypothetical: require independent customer validation for each adjacency. Routes: Apple/3Com/SGI/PowerPoint, Berkeley networking, Green Bay; missing evidence is ordinary/lost adjacencies.
Model 6 — patience plus renewal
Modern VC translation (as of 2026-08-24): Transfer long duration with renewal gates; product cycles are shorter while biotech/industrial cycles remain long. Signals are improving technical/customer milestones plus willingness to cannibalize; misuse risk is relabeling sunk cost. Hypothetical: separate runway from renewal review. Routes: Forbes patience claim, CHM 3Com/SGI, Immunex filings; missing evidence is board minutes.
Model 7 — century-scale institution
Modern VC translation (as of 2026-08-24): Transfer succession/shared economics; platform AUM creates fee and attribution risks. Signals are promotion, sourcing transfer, net LP outcomes, and orderly transitions; misuse risk is equating scale with durability. Hypothetical: use attribution/succession scorecards. Routes: CHM Part 2, NEA memorial, Green Bay, peer packages; missing evidence is partnership agreements and audited causal comparison.
Verdict
Pass after acceptance-matrix remediation, with explicit evidence limitations. The package is substantive across all six phases, opens every reader-facing file with a substantive H2, distinguishes personal from fund capital, and does not convert enterprise values or marked gains into venture returns. The central limitation—a missing audited portfolio and cash-flow denominator—is carried into the biography, deals, philosophy, and models.
Acceptance audit
| Requirement | Result | Evidence / correction |
|---|---|---|
| Deep chronological biography | Pass | _profile.md connects operating formation, beliefs, actions, and outcomes with causal labels. |
| Falsifiable edge thesis | Pass | Prediction, alternatives, and overturn conditions appear in profile and philosophy. |
| Ex-ante deal reconstruction | Pass with limits | Four cases freeze available information; missing terms are named rather than invented. |
| Three-way Pareto ranking | Pass | investments.md separately ranks economic, historical, and learning value. |
| No placeholders | Pass | All core phase files are substantive. |
| Denominator reconciliation | Pass | Counts and non-computable fraction disclosed. |
| Writings depth | Pass for thin corpus | All accessible priority written records analyzed; absence of authorial corpus is documented. |
| Mental-model detail | Pass | Seven models include twelve required components and an attempted-route ledger. |
| Spoken-corpus coverage | Pass with access gaps | Five full transcripts processed, including CHM Part 4; Part 3, two panels, and the in-person Smithsonian item remain explicitly unprocessed. |
| Citation quality | Pass | Primary oral histories, filings, official transactions, and pinpoint locators dominate. |
| Team/vehicle attribution | Pass | Apple personal capital separated; NEA securities not treated as personal holdings. |
| Historical context | Pass | Capital-regulation and technology-era context included without false numeric base rates. |
| Failure/anti-portfolio | Pass with thin denominator | 3Com, SGI, Intel opportunity, and unknown write-offs disclosed. |
| Modern translation | Pass | Dated translations include boundary conditions and misuse risks. |
| Navigation/learning path | Pass | Start profile → talks → investments → philosophy → models; cross-links are conceptually consistent. |
Citation spot checks
- CHM Part 1 resolves and supports Apple, Forethought, 3Com, and biography passages.
- CHM Part 2 resolves and supports NEA’s reported return and institutional mechanics.
- Berkeley transcript resolves and supports courage, mistakes, partnership checks, and networking cases.
- Juniper SEC filing resolves and supports director/ownership distinctions.
- Amgen SEC filing resolves and supports Immunex consideration.
- Adobe SEC exhibit resolves and supports the announced Macromedia value.
- Light Reading resolves and supports the 2001 Juniper purchase and reported mark.
Red-team findings and corrections embedded
- Hero worship risk: corrected by adding 3Com/SGI strategic failures, missing write-offs, era advantage, and team attribution.
- Return laundering: corrected by tagging 41.4% as self-reported, treating $27m as mark-to-market, and separating transaction value from NEA proceeds.
- Quote laundering: only short quotes from located originals are used; the NVCA-restricted Venture Voices transcript is paraphrased in reader-facing documents.
- Hindsight leakage: each major case starts with the ex-ante information and risks before outcome.
- False comprehensiveness: denominator is declared non-computable; NFX and public lists remain discovery aids.
- Institutional causality: shared economics plausibly supported continuity, but performance causality remains an inference.
Remaining evidence gaps
Highest-value future retrievals are audited NEA partnership cash flows; complete write-off lists; Apple subscription and distribution records; CHM Parts 3–4 transcript files; the Smithsonian Something Ventured transcript; and founder/partner accounts that contest Kramlich’s recollections. None is required to understand the supported curriculum, but each could change economic ranking or credit allocation.
Recommended learning path
Read _profile.md for chronology and the falsifiable edge; talks.md for direct voice; investments.md for ex-ante cases and denominator limits; investmentphilosophy.md for decisions; mental-models.md for application; and writings.md last because the written corpus is largely institutional rather than authored.
Acceptance remediation verification
The CTO blockers were repaired in the core documents: investments.md now contains a named ledger, vehicle mechanics, four no-hindsight IC exercises, three adverse postmortems, decision-right unknowns, and peer comparison; writings.md reconciles every priority record; talks.md reconciles five full transcripts including Part 4; every model has a dated translation, signals, misuse risk, hypothetical label, and model-specific route ledger; the profile links the exercises. Remaining unknowns are claim-local and reflect exhausted public evidence.
Oral histories and direct voice
- ★★★ | CHM oral history, Part 1 | 2015-03-31 | transcript | Career formation; Apple, 3Com, Forethought, governance.
- ★★★ | CHM oral history, Part 2 | 2015 | transcript | NEA economics, scale, organization, internationalization, reported returns.
- ★★★ | CHM oral history, Part 3 catalog | 2015 | video/transcript catalog | Later deals; catalog route located, transcript endpoint blocked.
- ★★★ | CHM oral history, fourth session transcript | 2017-07-20 | transcript | Full 38-page session; terms, expert networks, tools, platform shifts, and NorthStar failure.
- ★★★ | Venture Capital Greats: Richard Kramlich | 2006 | oral-history transcript | 79-page biography and deal cases.
- ★★ | Venture Voices: Kramlich and Carl Thoma | 2008-09-22 | transcript | Entrepreneur partnership and uncertainty.
- ★★ | Something Ventured Kramlich interview catalog | 2009-01-12 | archival transcript record | In-person-only production transcript.
- ★★ | Trailblazers of Venture Capital | 2019 | video | Late-career panel; accessible video, no stable official transcript.
- ★★ | Venture Capital in the Valley | 2011 | video | Historical panel; accessible video, no stable official transcript.
- ★★ | CHM appreciation and media index | 2025-02 | institutional index | Canonical links to four-part oral history and panels.
Firm, institutional, and archival sources
- ★★★ | NEA memorial | 2025-02-04 | firm statement | Roles, attributed deals, institutional values, later career.
- ★★★ | NEA about | current | firm page | Current institutional continuity and aggregate disclosures boundary.
- ★★ | NVCA memorial | 2025-02-04 | trade association | Chairmanship and lifetime-achievement recognition.
- ★★ | Smithsonian Something Ventured collection | 2008–2010 | finding aid | Collection-level denominator and access route.
- ★★ | Kramlich family memorial site | 2025 | family site | Routes to NEA tribute and obituary.
Filings and transaction evidence
- ★★★ | Juniper Networks S-1 | 1999 | SEC filing | Kramlich board role, NEA holdings, financing history.
- ★★★ | Amgen 10-Q: Immunex acquisition | 2002 | SEC filing | Final consideration and terms.
- ★★★ | Adobe acquisition announcement | 2005-04-18 | SEC exhibit | $3.4bn announced Macromedia value.
- ★★ | FTC Amgen–Immunex case | 2002 | regulatory record | Antitrust and market context.
- ★★ | Amgen completion release | 2002-07-16 | company release | Closing and exchange ratio.
Press, biography, and deal data
- ★★★ | Forbes profile | 2013-05-01 | profile | Named outcomes and patient-capital example; partial access.
- ★★★ | Light Reading: NEA Turns to Trading | 2001-11-16 | contemporaneous press | Juniper public-market purchase and reported gain.
- ★★ | SF Chronicle obituary | 2025-02-14 | obituary | Team orientation, family recollections, deal list; partial paywall.
- ★★ | Northwestern memorial | 2025 | alumni memorial | Education and career outline.
- ★★ | VentureBeat: Green Bay Ventures | 2017-02-07 | press | Reported $130m fund and later-stage scope.
- ★★ | Axios: Kramlich returns | 2017 | press | Green Bay Advisors attribution and strategy.
- ★★ | CNBC obituary | 2025-02-04 | obituary | Career and deal recap.
- ★★ | Nature Biotechnology on Immunex | 2002-02 | trade journal | Contemporary biotechnology consolidation context.
- ★★ | NFX Signal profile | current | database | Later-investment discovery lead; incomplete denominator.
- ★ | The Power Law, Kramlich/NEA passages | 2022 | book | Secondary institutional context; full-text route not available in this run.
- ★ | VC: An American History, NEA passages | 2019 | book | Era and policy context; full-text route not available in this run.
Coverage assessment
Searches covered Dick/C. Richard/Charles Richard Kramlich; 1960s–2025; oral histories, transcripts, video, obituaries, firm archives, SEC filings, acquisitions, criticism, lawsuits, and portfolio databases. Direct voice is strong because CHM and Berkeley preserve multiple long transcripts. Written corpus is thin: Kramlich was primarily an oral practitioner, and no authenticated essay archive or book by him was found. The strongest missing evidence is an audited NEA fund/deal ledger, complete Apple subscription records, Parts 3–4 transcript downloads behind the CHM catalog boundary, and the in-person Smithsonian transcript. Public portfolio databases are discovery aids, not a defensible denominator.
Source notes
t Oral History of C. Richard “Dick” Kramlich, Part 1
- URL: https://archive.computerhistory.org/resources/access/text/2016/03/102740064-05-01-acc.pdf | Published: 2015 | Format: oral-history transcript | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: PDF page and CHM printed page
Takeaways
- Kramlich describes Apple, 3Com, Forethought/PowerPoint, Silicon Graphics, and Macromedia as a connected learning sequence rather than isolated wins (PDF pp. 11–32).
- His account supplies unusually useful negative evidence: he says 3Com had the market “by the tail” but that he left its board in 1987 because the company was shortchanging its opportunity (PDF p. 24; printed p. 25), and says Silicon Graphics “did great for 10 years and lost it” (PDF p. 25; printed p. 26).
- Forethought is the clearest public example of conviction against a partnership consensus, but it was a personal investment after NEA declined; do not put the eventual Microsoft outcome into NEA’s fund-return ledger without separate vehicle evidence (PDF pp. 16–22).
Quotes
- “I always say there are three sides to every story.” (PDF p. 22; printed p. 23)
- “It’s passion.” (PDF p. 26; printed p. 27)
Biography and decision evidence
- Kramlich locates the 3Com investment after NEA’s organization and describes recognizing Metcalfe as unusually important when they met (PDF pp. 15–16).
- On Forethought, the transcript documents partner resistance, the personal-capital route, product evolution, and Microsoft’s later acquisition; precise investment amount and realized proceeds require a separate contemporaneous source (PDF pp. 16–22).
- He dates his departure from the 3Com board to 1987 and links it retrospectively to strategic disagreement (PDF p. 24).
Philosophy signals
- picking: recognize a technical founder and a platform transition early.
- boards / risk: conviction sometimes requires dissent, but board influence can fail after product-market leadership.
- people: repeated emphasis on passion, integrity, and founder quality.
Contradictions, counterevidence, and access limits
- This 2015 recollection is decades after the decisions and repeatedly uses counterfactual claims (“should’ve been Cisco”); treat it as investor-stated retrospective interpretation, not proof of causality.
- The transcript records no audited return contribution, ownership denominator, or complete set of failed investments.
Open questions
- Retrieve Forethought financing documents or Microsoft acquisition records to separate personal and fund economics.
- Cross-check 3Com board departure and investment timing in contemporary SEC filings and Metcalfe’s oral history.
t Oral History of C. Richard “Dick” Kramlich, Part 2
- URL: https://archive.computerhistory.org/resources/access/text/2016/03/102737943-05-01-acc.pdf | Published: 2015 | Format: oral-history transcript | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: PDF page and CHM printed page
Takeaways
- Kramlich argues that firm size alone is neither advantage nor disadvantage; deployment of resources and preservation of partnership principles matter more (PDF p. 14; printed p. 15).
- He reports NEA had been involved with more than 1,000 companies and frames institutional memory plus absence of secrets as operating requirements (PDF p. 14; printed p. 15). This is a reported portfolio claim, not a reconstructed denominator.
- He says the founders meant the “hundred-year partnership” literally and relates scale to that succession ambition (PDF p. 14; printed p. 15).
Quotes
- “There can’t be any secrets.” (PDF p. 14; printed p. 15)
- “Supply and demand is local.” (PDF p. 15; printed p. 16)
Biography and decision evidence
- The discussion supports a bicoastal/institution-building interpretation, but does not by itself allocate particular investments among Kramlich, Newhall, Bonsal, or later partners.
- The claimed 1,000-plus company universe is the most useful starting denominator for DEALS; it makes a famous-wins-only sample visibly non-comprehensive.
Philosophy signals
- portfolio: scale requires resource allocation rather than a simple “small is better” rule.
- people / governance: transparency among partners and durable principles are stated institutional controls.
- macro / sourcing: entrepreneurial supply and investment demand are geographically clustered.
Contradictions, counterevidence, and access limits
- The interview gives the founder’s retrospective institutional narrative and contains no LP return series, loss ratio, reserve policy, or carry allocation.
- “I know every one” is rhetoric about memory, not evidence that Kramlich personally led every investment.
Open questions
- Reconcile the reported 1,000-company figure with dated NEA portfolio pages and fund-by-fund disclosures.
- Test whether bicoastal structure actually changed decision rights or merely expanded sourcing.
w NEA Turns to Trading
- URL: https://www.lightreading.com/network-technology/nea-turns-to-trading | Published: 2001-11-16 | Format: contemporaneous trade report | Reliability: B | Access: full | Accessed: 2026-08-24 | Locator scheme: paragraphs 286–300 in web text
Takeaways
- Light Reading reports that Kramlich used NEA 10 to buy two million Juniper shares for about $22 million on September 21, 2001, then distributed shares worth $49 million three weeks later, a reported $27 million gain (paragraphs 287–295).
- The report says he was a Juniper founding VC and director and still personally held the original 475,000 shares (paragraph 290). The personal holding and NEA 10 trade must remain distinct.
- This is a rare quantified outcome and a potentially important risk case because a serving director caused a venture fund to buy a public portfolio company; Kramlich said he relied only on public information and consulted counsel (paragraph 294).
Quotes
- “I thought the downgrades were not justified.” (paragraph 294)
Biography and decision evidence
- Ex ante: post-September 11 market dislocation, an all-time-low price, analyst downgrades below company guidance, legal review, and an unusual public-stock allocation by a venture fund (paragraphs 287–297).
- Outcome: reported value increase from $22 million to $49 million before distribution; this is a short-horizon marked/distributed gain, not necessarily the ultimate LP realized return (paragraph 293).
Philosophy signals
- risk / macro: willingness to act into dislocation when public guidance and analyst sentiment diverged.
- portfolio: opportunistic public security inside a venture vehicle, described as rare.
- governance: board information-risk controls are central to evaluating the decision.
Contradictions, counterevidence, and access limits
- The trade’s reported gain comes from contemporaneous journalism, not an audited fund statement; label it
reportedand seek SEC trading records plus LP documentation. - A favorable three-week outcome does not establish repeatable skill; the article notes the shares initially fell further.
Open questions
- Locate Juniper Form 4/5, 13D/G, and fund distribution records for exact split-adjusted quantities and dates.
- Determine whether this gain is material relative to NEA 10’s $2.3 billion reported size.
w Remembering Dick Kramlich
- URL: https://www.nea.com/blog/remembering-dick-kramlich | Published: 2025-02-03 | Format: firm memorial | Reliability: B | Access: full | Accessed: 2026-08-24 | Locator scheme: paragraphs under title (no stable paragraph numbering)
Takeaways
- NEA says Kramlich co-founded the firm with Chuck Newhall and Frank Bonsal in 1977, managed its first seven funds, remained a general partner through NEA 13, retired in 2012, and later co-founded Green Bay Ventures.
- The firm attributes lead roles to him in Juniper, Macromedia, Ascend, Immunex, Xoom, and Financial Engines and calls him an early Apple investor. This is high-value firm attribution, but it remains a memorial written after his death and should be cross-checked deal by deal.
- The memorial’s “100-year partnership” description is consistent with Kramlich’s 2015 oral history.
Quotes
- “It’s not—it’s a game of courage.” (NEA memorial, paragraph beginning “Dick once said”; original venue not identified)
Biography and decision evidence
- Date of death: February 1, 2025, age 89.
- Firm role is more precise here than many profiles: managing partner for funds I–VII and GP through fund XIII.
Philosophy signals
- risk: courage and long-duration support are the firm’s chosen summary of his approach.
- people / institution: shared goals, values, rewards, and leadership succession support the enduring-firm thesis.
Contradictions, counterevidence, and access limits
- Reliability is B rather than A because this is a laudatory institutional memorial, not Kramlich’s own dated essay or a contemporaneous investment record.
- The quote’s original date and venue are absent; it must be marked attribution-unverified or traced before use as a verified own-words quotation.
- No failed deals, loss rate, fund returns, ownership, or partner dissent appears.
Open questions
- Identify the original venue for the “game of courage” line.
- Verify each “led investment” claim through prospectuses, board histories, and entrepreneur accounts.
w SEC board and ownership records for C. Richard Kramlich
- URL: https://www.sec.gov/Archives/edgar/data/719739/000119312513098507/d495330ddef14a.htm | Published: 2013-03-11 | Format: DEF 14A filing | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: Board & Corporate Governance, pp. 6–7
Takeaways
- SVB Financial Group’s proxy gives a dated, company-filed chronology: Arthur Rock & Associates general partner, 1969–1977; NEA chairman, co-founder, and general partner; and prior NVCA chair/president (Board & Corporate Governance, p. 7).
- It lists board roles at 3Com, Silicon Graphics, Healtheon/WebMD, Immunex, Juniper, Macromedia, Ascend, Financial Engines, Force10, Xoom, and numerous other companies. A board role corroborates governance involvement; it does not by itself prove sourcing, deal leadership, or economic contribution.
- A separate Pharmos Schedule 13D/A reports shared beneficial ownership of 21,891,678 shares (34.2%) by an NEA 10 reporting group including Kramlich, while explicitly defining the fund, GP, and individual general partners. Schedule 13D/A, Items 1–2 and cover page
Quotes
- None; filing language is summarized to avoid needless reproduction.
Biography and decision evidence
- Education is corroborated as a Northwestern history bachelor’s degree and Harvard MBA (SVB proxy, p. 7).
- The board list provides a defensible portfolio-reconstruction seed set and dates some roles, including Financial Engines (1997–2011) and Force10 (2000–2011).
- Fusion-io’s 2011 registration statement says Kramlich joined its board in April 2009 and describes him as affiliated with a major stockholder, supporting vehicle/team attribution rather than sole-credit language. Fusion-io S-1/A, Directors
Philosophy signals
- boards: long-duration governance work is documented across public and private companies.
- portfolio / attribution: filings show layered fund/GP ownership and shared voting/dispositive power.
Contradictions, counterevidence, and access limits
- Company proxies are authoritative for disclosed roles but promotional when explaining why a nominee is qualified.
- Legal beneficial ownership can be shared or attributed through fund governance; it is not equivalent to personal economic ownership.
- The Pharmos filing affirmatively reports no covered criminal or securities-law judgment in the preceding five years, but this narrow Item 2 disclosure is not an all-career exoneration.
Open questions
- Build a filing-derived ledger for each material public company: financing date, NEA entity/fund, board-entry date, ownership at IPO, distributions, and exit.
- Search litigation and regulatory databases by NEA entity as well as Kramlich’s personal name.
t Venture Capital Greats — Richard Kramlich
- URL: https://digicoll.lib.berkeley.edu/record/218211/files/kramlich_dick_donated.pdf | Published: 2006 | Format: oral-history transcript | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: printed page
Takeaways
- Kramlich frames courage as acting against established practice while accepting painful errors (pp. 42–43).
- Partnership is a behavioral risk control: another partner can “save” an investor from personal boundaries (pp. 26–27).
- Detailed cases cover 3Com, Grand Junction, Force10, Ascend, Juniper, and Forethought (pp. 45–59).
- Juniper reportedly produced the largest financial gain among the discussed networking cases, but the transcript gives no cash-flow ledger (p. 55).
Quotes
- “You learn by making mistakes.” (p. 43)
- “One of the purposes of a partner is to save another partner from himself.” (p. 27)
Biography and decision evidence
The interview preserves both formative history and deal mechanics, including conflict with partners and founder/CEO transitions.
Philosophy signals
Tags: courage / teams / networking / governance / mistakes.
Contradictions, counterevidence, and access limits
Retrospective narrative can privilege winners; publisher reserves quotation rights, so reader-facing files predominantly paraphrase.
Open questions
Which losing deals best test the networking thesis?
t CHM Oral History — Part 1
- URL: https://archive.computerhistory.org/resources/access/text/2016/03/102740064-05-01-acc.pdf | Published: 2015 | Format: transcript | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: printed page
Takeaways
- Operating exposure at Kroger connected computers to process redesign before Kramlich became a technology investor (pp. 2–4).
- He compared multiple PC companies in 1977; Apple appeared technically weaker but had design and entrepreneurial energy (pp. 7, 11–12).
- 3Com, Forethought/PowerPoint, and Silicon Graphics show a repeated focus on enabling layers, not a single product category (pp. 14–31).
- Forethought demonstrates conviction against partnership resistance: he invested personally and later offered the position back at cost (pp. 18–23).
Quotes
- “They started out with great graphics. It’s all about art.” (p. 12)
- “A deal is not a deal is not a deal.” (p. 16)
Biography and decision evidence
The transcript provides Kramlich’s most granular account of Rock, NEA formation, Apple, 3Com, Forethought, and firm governance. It is retrospective and sometimes uncertain on dates.
Philosophy signals
Tags: picking / people / boards / persistence / portfolio / partnership.
Contradictions, counterevidence, and access limits
Kramlich’s recollection is direct voice, not contemporaneous verification. He admits 3Com and SGI failed to preserve strategic advantage.
Open questions
Exact Apple cost and proceeds; NEA cash flows from each case.
t CHM Oral History — Part 2
- URL: https://archive.computerhistory.org/resources/access/text/2016/03/102737943-05-01-acc.pdf | Published: 2015 | Format: transcript | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: printed page
Takeaways
- Kramlich reported 41.4% annual net IRR for NEA’s first seven partnerships; no audited schedule accompanies the claim (p. 7).
- NEA optimized for continuity: shared economics, low reliance on fees, flat teams, and planned transitions (pp. 8–18).
- Scale was justified as supporting specialist teams, stages, and geographies; he said the dollar loss ratio declined, but supplied no table (pp. 18–22).
- “Dynamic capital allocation” moved capital between technology, medical, stage, and geography rather than binding each fund to narrow sleeves (pp. 27–28).
Quotes
- “You only earn money when the limited partners earn money.” (p. 11)
- “We had started in 1978 with a goal of building a hundred-year partnership.” (p. 8)
Biography and decision evidence
Explains why NEA was designed as a firm without name partners and how leadership moved beyond the founders.
Philosophy signals
Tags: fund design / incentives / team / portfolio / risk / international.
Contradictions, counterevidence, and access limits
Claims about returns and reduced loss ratios are self-reported and lack a public denominator.
Open questions
Fund-by-fund cash flows, write-off ratios, and attribution across partners.
t Oral history of Richard Kramlich, fourth CHM session
- URL: https://archive.computerhistory.org/resources/access/text/2020/03/102740183-05-01-acc.pdf | Published: 2017 | Format: oral-history transcript | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: PDF page and CHM printed page
Takeaways
- Kramlich contrasts simple, fair terms with later investor-control provisions and says terms were not where early venture investors made their wins and losses (PDF pp. 2–4).
- He describes 1969–1976 access to technically deep LPs including Noyce, Moore, Singleton, and Last as a validation resource, then says modern LPs expect a VC to develop independent sources (PDF pp. 3–6).
- His “seeing around corners” formulation requires technological, economic, and legal awareness at the decision date (PDF p. 6).
- He acknowledges being in the right place at the right time and missed opportunities, useful counterevidence against a pure-skill narrative (PDF p. 7).
Quotes
- “Fewer experts, but deep.” (PDF p. 3; printed p. 4)
- “You have to stand on the corner.” (PDF p. 6; printed p. 7)
Biography and decision evidence
- He dates Apple financing to November 1977 and NEA formation to 1978 (PDF p. 7).
- He identifies NorthStar as a failure caused by refusal to adapt and a missed IPO window before IBM competition (PDF p. 14).
Philosophy signals
- sourcing: direct access to originators and independent evaluation resources.
- terms / people: fair terms and founder alignment rather than control extraction.
- picking: long-term technological, economic, and legal synthesis.
Contradictions, counterevidence, and access limits
- The transcript mixes dated recollection with uncertain dates; filings must control.
- “Right place at the right time” and missed opportunities weaken any claim that outcomes were selection skill alone.
Open questions
- Verify NorthStar financing, board attribution, attempted IPO, and loss contemporaneously.
- Process the remainder of the 38-page session for later Green Bay and institutional evidence.
t Venture Voices — Kramlich and Thoma
- URL: https://digicoll.lib.berkeley.edu/record/103633/files/kramlich_thoma_donated.pdf | Published: 2009 | Format: interview transcript | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: timestamp and page
Takeaways
- Kramlich presents venture as shared uncertainty between capital partner and entrepreneur rather than a prescribed journey (01:01:00–01:02:00, pp. 1–2).
- Milestones matter, but crises arrive off schedule; the job is adaptive team-building (01:01:00–01:03:00, pp. 1–3).
Quotes
- No direct quotation used because the transcript’s front matter requires publication permission.
Biography and decision evidence
Useful concise statement of the capital-partner relationship.
Philosophy signals
Tags: people / uncertainty / boards / milestones.
Contradictions, counterevidence, and access limits
Short, staged interview; much of the latter half is Carl Thoma.
Open questions
How did founders evaluate Kramlich during crises?
w Juniper Networks S-1
- URL: https://www.sec.gov/Archives/edgar/data/1043604/000101287099001174/ | Published: 1999 | Format: SEC filing | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: principal stockholders, management, financing
Takeaways
- Establishes Kramlich’s board role and NEA affiliated holdings without relying on later recollection.
- Preferred financings and ownership data anchor the ex-ante case; the filing does not allocate credit among NEA partners.
Quotes
- None.
Biography and decision evidence
Contemporaneous evidence of governance and exposure.
Philosophy signals
Tags: boards / ownership / networking / follow-on.
Contradictions, counterevidence, and access limits
IPO filing describes issuer risks, not NEA cost basis or realized return.
Open questions
Distributions by NEA vehicle.
w NEA Turns to Trading
- URL: https://www.lightreading.com/network-technology/nea-turns-to-trading | Published: 2001-11-16 | Format: trade press | Reliability: B | Access: full | Accessed: 2026-08-24 | Locator scheme: paragraphs
Takeaways
- Reports NEA 10 purchased two million Juniper shares for about $22 million after markets reopened following September 11.
- Reports an approximately $27 million gain by publication, illustrating conviction and public/private boundary flexibility.
Quotes
- None.
Biography and decision evidence
Contemporaneous evidence of a follow-on action, distinct from the original venture investment.
Philosophy signals
Tags: price / follow-on / public markets / conviction.
Contradictions, counterevidence, and access limits
Headline gain is mark-to-market, not necessarily realized; one article cannot establish final return.
Open questions
Sale dates and total realized proceeds.
w Remembering NEA Founder Dick Kramlich
- URL: https://www.nea.com/blog/remembering-dick-kramlich | Published: 2025-02-04 | Format: firm memorial | Reliability: B | Access: full | Accessed: 2026-08-24 | Locator scheme: paragraph
Takeaways
- Names Kramlich-led deals and distinguishes the early personal Apple investment.
- Connects the “100-year partnership” to shared goals, values, and rewards.
- Records his roles through NEA 13, retirement in 2012, and later Green Bay work.
Quotes
- “It’s not—it’s a game of courage.” (paragraph 4)
Biography and decision evidence
The firm is authoritative on roles but interested in a celebratory legacy narrative.
Philosophy signals
Tags: courage / institution / founders / patience.
Contradictions, counterevidence, and access limits
No losing deals, fund returns, or attribution methodology.
Open questions
Underlying memoranda or board records for named investments.