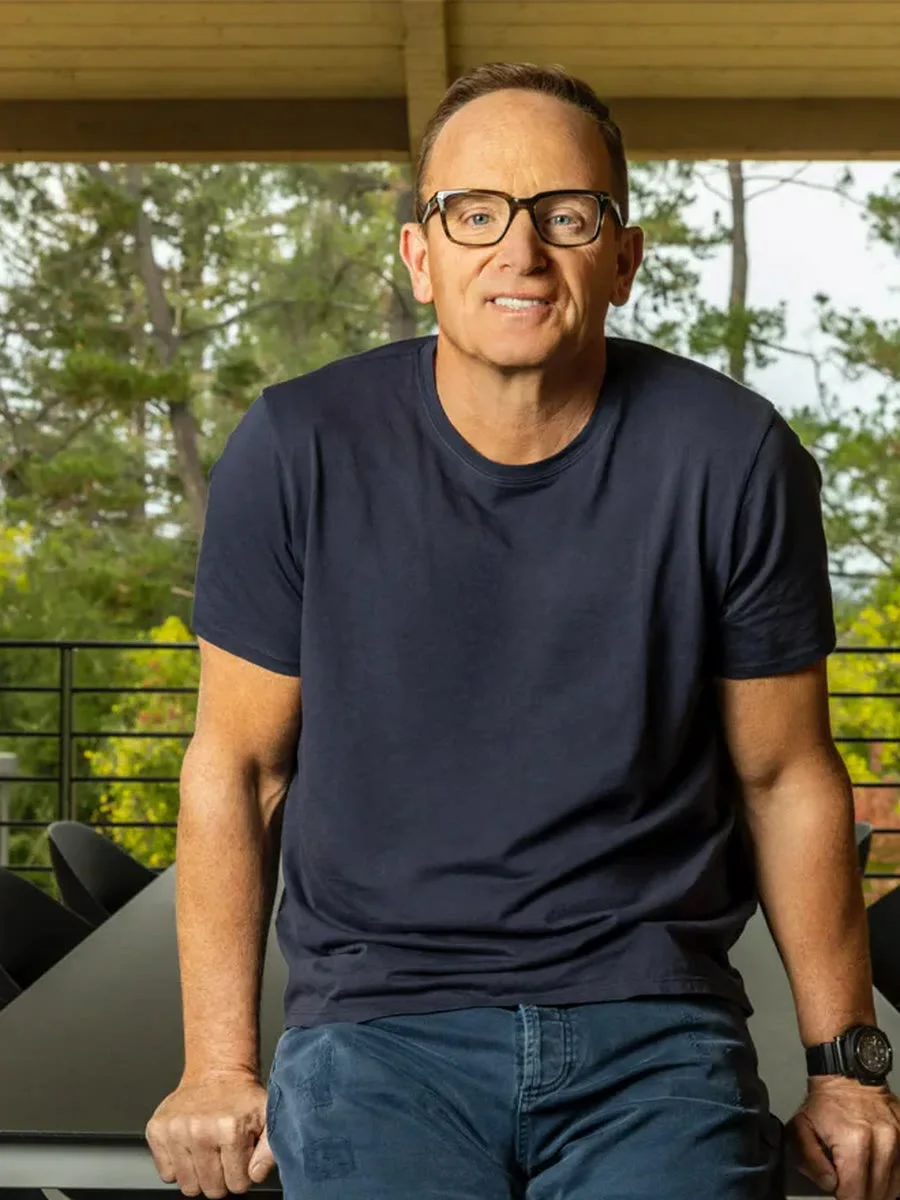
Jim Goetz
WhatsApp's only venture investor; disciplined enterprise sourcing built on cold outreach.
Verified chronology
| period | verified record and evidence boundary |
|---|---|
| 1965/1966-1988 | Palo Alto Networks' 2021 proxy listed James J. Goetz as age 55 and records a B.S. in electrical engineering with a computer-engineering concentration from the University of Cincinnati; Sequoia's current profile adds a Detroit/Midwest identity but gives no public birth record. Palo Alto Networks 2021 proxy, board biography · Sequoia profile, “Personal Side” |
| late 1980s-1990s | Goetz studied computer networking at Stanford, then left a PhD path for product management at SynOptics before co-founding VitalSigns Software. Intel's 2019 board announcement says VitalSigns pioneered end-user performance management; the public record found here does not allocate equity, proceeds, or operating decisions. Intel director announcement, background paragraphs · TechCrunch Disrupt speaker bio, 2012 |
| 2004 | Goetz joined Sequoia Capital in June 2004. His Sequoia profile says he shadowed Michael Moritz, Doug Leone, Don Valentine, and Pierre Lamond for six months, which is direct evidence for the apprenticeship model he later emphasizes, not proof that every later deal followed those mentors' practices. Palo Alto Networks 2021 proxy · Sequoia profile, “Backstory” |
| 2005-2007 | Sequoia's current company pages and public-company filings tie Goetz to early investments and boards in Palo Alto Networks, Barracuda, Jive, Ruckus, and Nimble Storage. These records prove Sequoia/board linkage and timing, not Goetz-only sourcing, ownership, carry, or cash-on-cash returns. Palo Alto Networks company page · Ruckus company page · Palo Alto Networks 2021 proxy |
| 2006-2010 | Sequoia records Goetz as the partner for AdMob, partnered in 2006 and acquired by Google in 2010. Google's announcement gives the $750 million stock consideration; Sequoia's oral-history-style AdMob story supplies Goetz and Omar Hamoui's retrospective decision narrative. AdMob company page · Google acquisition announcement, 9 Nov 2009 · Sequoia AdMob story |
| 2011-2014 | Sequoia records WhatsApp as founded 2009, partnered 2011, and acquired 2014 with Goetz as partner. Facebook's closing 8-K states the October 2014 consideration mechanics; TechCrunch reported Sequoia invested about $60 million across rounds for a high-teens stake, which remains reported rather than audited public fund economics. WhatsApp company page · Facebook WhatsApp closing 8-K, Item 2.01 · TechCrunch, 19 Feb 2014 |
| 2012-2017 | Goetz ranked first on Forbes' Midas List in 2014, 2015, 2016, and 2017, primarily on WhatsApp plus public enterprise exits. Forbes' methodology rewards large exits, earlier risk, and involvement; it is not an audited investor track record. Forbes 2015 Midas release · Forbes 2017 gallery |
| 2017 | Goetz stepped back from Sequoia's U.S. leadership/steward role, with Axios and Forbes framing the transition as a next-generation handoff to Roelof Botha and others. This supports a firm-culture/succession theme but does not prove that economic power or carry fully shifted. Axios, 31 Jan 2017 · Forbes profile, updated 2020 |
| 2019-2026 | Intel elected Goetz to its board in November 2019, and Intel's current board page still lists him as Partner, Sequoia Capital as of this run. This public-company role creates a live governance record and a potential conflict/attention boundary for later updates. Intel 2019 announcement · Intel board page, accessed 2026-08-23 |
Identity, era, and geographic frame
- Canonical identity: James J. "Jim" Goetz; partner/managing member at Sequoia Capital; public-company director at Palo Alto Networks historically and Intel currently. Palo Alto Networks 2021 proxy · Intel board page
- Operating formation: engineer, networking product manager, VitalSigns cofounder/operator, then Sequoia apprentice. This matters because his best-documented investing pattern is technical-market mapping plus close founder mentorship, not consumer hype chasing. Intel director announcement · Sequoia profile
- Investing era: post-dot-com early-stage enterprise/mobile investor, active through cloud, mobile, security, storage, collaboration, consumer messaging, 3D printing, and developer/security software. Sequoia profile, company roster
- Geography: Detroit/Midwest origin, Cincinnati and Stanford education, Silicon Valley/Sand Hill Road operating base, later Miami personal note; portfolio scope is global but public deal evidence is mostly U.S.-centric plus WhatsApp's international user base. Sequoia profile
People, institutions, and capital to trace
| layer | people or institutions | boundary for later phases |
|---|---|---|
| Sequoia apprenticeship | Michael Moritz, Doug Leone, Don Valentine, Pierre Lamond | Goetz states the apprenticeship shaped authenticity and mentorship; board minutes and internal IC records are not public. Sequoia profile |
| Mobile consumer outliers | Jan Koum, Brian Acton, Neeraj Arora, Omar Hamoui | Sequoia and founder accounts prove close involvement, but not exact fund ownership, dilution, or personal economics. WhatsApp company page · AdMob story |
| Enterprise/security/storage cohort | Nir Zuk, Lee Klarich, Rajiv Batra, Varun Mehta, Umesh Maheshwari, Bill Lynch, Dean Drako | SEC filings and Sequoia pages show board/partner links and public outcomes; later work must avoid assigning all team or company execution to Goetz. Palo Alto Networks company page · Palo Alto Networks 2021 proxy |
| Succession and firm culture | Don Valentine lineage, Roelof Botha, Pat Grady, Michael Abramson, Alfred Lin | Public accounts support a deliberate handoff narrative; they do not expose compensation, control rights, or voting mechanics. Axios leadership story |
| Public-company governance | Palo Alto Networks, Intel, former boards at Barracuda, Nimble, Jive, Ruckus | Proxy biographies are reliable for dates and roles but not for venture selection causality. Palo Alto Networks 2021 proxy · Intel board page |
Evidence tensions to preserve
- WhatsApp economics: $19 billion is a headline acquisition value including cash, stock, and employee RSUs; Facebook's closing 8-K gives a different securityholder consideration breakdown, and Sequoia's reported stake/return comes from press sourcing rather than an audited fund report. Facebook 8-K · TechCrunch Sequoia stake report
- Personal versus firm credit: Sequoia pages list Goetz as partner on many companies; that is stronger than generic press but still not the same as sole sourcing, sole IC decision, or sole board contribution. Sequoia profile
- Hero narrative risk: Midas rankings concentrate on visible exits above threshold; the denominator of passes, write-offs, fund allocations, follow-on reserves, and missed opportunities is not public. Forbes 2015 Midas methodology paragraph
- Direct voice scarcity: Goetz has fewer long-form primary essays than many modern VCs. The best direct sources are Sequoia profile text, AdMob/WhatsApp pieces, the Templeton Compression essay, and video/transcript appearances. Sequoia profile · Templeton Compression
Biographical and investment questions the evidence must resolve
- Which VitalSigns records can document Goetz's actual operating playbook before Sequoia?
- Which enterprise deals were sourced by Goetz personally versus inherited through Sequoia networks or partner teams?
- What are the fund-level and security-level economics for WhatsApp, AdMob, Palo Alto Networks, Nimble Storage, Ruckus, Barracuda, Jive, HubSpot, GitHub, Okta, Carbon, and ThousandEyes?
- What did Goetz do on each board at crisis moments: CEO hiring, sales readiness, pricing, culture, exit timing, and follow-on decisions?
- Which investments failed or underperformed, and what process changes followed?
- How should the "underdog founder" model be bounded so it does not become a slogan retrofitted to winners?
- What governance and conflict boundaries apply to Goetz's Intel board role and Sequoia/private-company roles?
Study path and retrieval priorities
- Start with Sequoia's Jim Goetz profile, then read the AdMob story, WhatsApp company page, and Goetz's Templeton Compression.
- Pair Sequoia's WhatsApp narrative with Facebook's closing 8-K and 8-K/A financial exhibits index before making economic claims.
- Use Sequoia company pages as a candidate portfolio map, then verify public outcomes through SEC filings or acquirer announcements.
- Treat Forbes Midas and TechCrunch as ranking/economics leads; use primary filings for transaction mechanics wherever available.
Edge thesis and falsifiers
Thesis: Goetz's edge was early recognition of technical underdog founders whose products already showed hard evidence of pull before the market had consensus, followed by high-touch board mentorship that helped convert raw pull into enduring distribution, sales readiness, or culture. Support is documented behavior + investor-stated / moderate: AdMob, WhatsApp, Palo Alto Networks, and the Templeton Compression cases fit the pattern. AdMob story · WhatsApp page · Templeton Compression
Falsifiers: a full Sequoia ledger showing the wins were offset by many similar failed bets; evidence that partners or later-stage vehicles rather than Goetz sourced/decided the key cases; or board records showing Goetz's role was passive after investment.
Sourcing
Goetz's sourcing pattern is relationship-heavy but not celebrity-driven. In AdMob, the route came through Ali Diab and a founder with urgent timing; in WhatsApp, Forbes' Sequoia feature says Goetz spent months working contacts before getting a meeting with founders who resisted investors. AdMob story · Forbes Midas Touch, Jan Koum section
Picking
His public founder screen prioritizes ambition, intelligence, modern business model, culture formation, talent magnetism, tenacity, and growth mindset. This is investor-stated / strong; the empirical return link is only moderate because failed-founder denominator is missing. Sequoia profile, On the Lookout for
Deal and portfolio mechanics
The best-documented mechanic is speed under uncertainty: AdMob moved from introduction to term sheet within days. WhatsApp is the opposite mechanic: patient pursuit and sole outside investor positioning. Both require conviction before standard venture consensus. AdMob story · TechCrunch WhatsApp stake report
Vehicle and incentive fit
Sequoia's brand, partnership process, and long-horizon culture are part of the edge. Goetz's own profile emphasizes shadowing senior partners and later paying mentorship forward; Axios describes a deliberate succession handoff. This is a firm-system lesson, not just an individual trait. Sequoia profile · Axios leadership story
Team attribution and work with founders
The AdMob case shows Goetz as fast sponsor and later thought partner; the WhatsApp case shows him as sole VC board relationship; Palo Alto Networks shows long public board service. In every case, founder/team credit remains primary. AdMob story · WhatsApp page · PANW proxy
Views on the craft
Goetz's craft view is psychologically humble: venture has a long feedback loop where early losses show before winners mature. That supports patience with younger partners and founders, but it also warns analysts not to overread interim marks. Sequoia profile, Backstory
Signature bets and decision process
- AdMob: unknown founder, contrarian mobile-ad thesis, fast term sheet, office incubation. AdMob story
- WhatsApp: founder purity, no ads/games/gimmicks, huge engagement, sole institutional investor. WhatsApp page
- Palo Alto Networks: early security category formation and long board service. PANW company page
Mental models and maxims
See mental-models.md for six field-guide models: underdog slope, compression before scaling, business model as weapon, sole-investor trust, mentorship flywheel, and outlier humility.
Evolution and contradictions
Goetz appears as enterprise investor in 2012, consumer/mobile outlier investor in 2014, enterprise-sales diagnostician in 2016, and firm-culture mentor by 2017+. The common thread is not sector but non-consensus evidence. TechCrunch enterprise recap · Templeton Compression · Sequoia profile
Failures and limits
The package cannot yet reconstruct a loss ledger. This is the largest limitation. Forbes and Sequoia profiles emphasize winners; private-company write-offs, passes, down rounds, reserve errors, and opportunity costs remain mostly invisible. Forbes 2015 Midas methodology
Historical operating environment
Goetz's best-known deals benefited from mobile smartphone adoption, SaaS/subscription enterprise disruption, security architecture shifts, and cloud/storage demand. These were not guaranteed: FTC scrutiny of AdMob and Facebook's WhatsApp monetization warning show real ex-ante uncertainty. FTC AdMob clearance · Facebook 10-Q WhatsApp note
Modern VC translation as of 2026-08-23
What transfers: find non-obvious usage, buyer pain, or workflow leverage before it becomes a hot category; move fast when evidence is real; earn founder trust through useful work. What fails: copying the WhatsApp no-monetization posture into categories without network effects or trust asymmetry; scaling enterprise sales before learning why customers buy. researcher inference / moderate.
Comparison with completed peers
Goetz is closest to Arthur Rock on technical-founder trust and board mentorship, but Goetz operated in a later Sequoia platform with richer fund infrastructure. Arthur Rock profile He also resembles Martin Casado as an operator/technical market mapper, but Casado is an investor after being founder of a category company, whereas Goetz's public record is mostly investor/operator before Sequoia. Martin Casado profile
Strongest case against greatness
The skeptical case is that WhatsApp dominates the visible record, Sequoia's platform created privileged access, and public sources over-credit Goetz relative to founders, partners, and market timing. Evidence that would decide the question: complete Sequoia fund cash flows, a pass/loss ledger, internal sourcing/IC records, and founder/board testimony across ordinary outcomes.
Analyst study guide, glossary, and go deeper
Reading path: profile chronology → source map → writings → talks → investments → mental models → review. Glossary: Sales Ready Product = enterprise product whose buyer pain, story, and sales process are repeatable; sole institutional investor = the WhatsApp pattern where Sequoia's board relationship was unusually concentrated; underdog slope = unknown founder with unusually high learning velocity and measurable pull.
Reusable checklist: What non-consensus premise is already measured? Who wants the product without being paid or chased? What sales learning remains before headcount? Who on the board compresses learning? What would prove the founder's discipline is actually rigidity?
Pareto 80/20 — what drove the record
Precise contribution is not publicly computable: no Sequoia fund cash-flow ledger, ownership schedule, carry allocation, or complete pass/write-off denominator surfaced. The directional Pareto is clear, but all economic rankings below are reported / moderate unless tied to primary transaction filings.
| rank | economic contribution | basis or measure | attribution | confidence | mechanism | denominator caveat |
|---|---|---|---|---|---|---|
| 1 | Facebook paid cash/stock and employee RSUs at closing; press reported Sequoia invested ~$60M for high-teens ownership worth about $3B. | Goetz as Sequoia partner and board member; founders and Sequoia fund own actual outcome. | moderate | Global engagement, tiny team, no marketing, sole institutional investor. | Sequoia stake is press-reported; no fund DPI or personal economics. Facebook 8-K · TechCrunch | |
| 2 | Palo Alto Networks | IPO 2012; Goetz director since April 2005; S-1 links Sequoia entities to a large pre-IPO stake and Goetz beneficial association. | Goetz and Sequoia, with founders/operators and co-investors. | strong for role, moderate for economics | Next-generation firewall category creation and enterprise sales execution. | Need realized distribution math and split attribution with founders/other investors. Sequoia page · PANW S-1 |
| 3 | AdMob | Google agreed to acquire AdMob for $750M in stock. | Goetz/Sequoia partner attribution; Omar Hamoui founder credit. | strong for deal, unknown for Sequoia return | Mobile-app advertising before smartphones fully mainstreamed. | Sequoia ownership and proceeds not public. Google announcement |
| 4 | Enterprise public-exit cluster: Nimble, Ruckus, Barracuda, Jive | IPO/acquisition outcomes and Goetz former-board history in PANW proxy. | Goetz/Sequoia plus founders and management. | moderate | Repeated early enterprise/security/storage bets. | Jive and Nimble show public-market compression/adverse evidence; fund-level economics incomplete. PANW proxy · Nimble SC 14D-9 · Jive acquisition exhibit |
| 5 | Later/private roster: Carbon, GitHub, HubSpot, Okta, ThousandEyes, Semgrep, Versa, Neeva | Sequoia profile lists Goetz companies; some have public exits/IPOs. | attribution varies by case. | provisional | Continued technical-founder and enterprise/developer-tool pattern. | Roster is curated and needs case extraction. Sequoia profile |
| rank | historical importance | why it matters | support |
|---|---|---|---|
| 1 | Largest venture-backed consumer acquisition of its era and proof that a no-ad, no-marketing mobile network could reach global scale. | Facebook 8-K · Sequoia WhatsApp page | |
| 2 | Palo Alto Networks | Category-defining next-generation firewall company and long Goetz board tenure. | PANW company page · PANW proxy |
| 3 | AdMob | Mobile advertising market formation before the app economy matured. | Google announcement · FTC clearance |
| 4 | Enterprise cohort | Demonstrated repeatability across storage, networking, security, and collaboration during SaaS/cloud transition. | Forbes 2015 Midas release |
| rank | decision-learning value | why a reader should study it |
|---|---|---|
| 1 | AdMob | Fast conviction under deadline, contrarian market thesis, founder pressure test, incubation. AdMob story |
| 2 | Backing anti-consensus product discipline despite poor conventional monetization. Sequoia WhatsApp page | |
| 3 | Templeton enterprise cases | How board members can diagnose sales readiness before scaling. Templeton Compression |
| 4 | Palo Alto Networks | Long enterprise-security company-building and board persistence. PANW proxy |
Evidence boundary and searched denominator
| bucket | count | scope and caveat |
|---|---|---|
| Publicly claimed/known Goetz-linked companies | 25+ | Sequoia profile plus company pages, Forbes/Midas, and scout leads; curated and mutable. Sequoia profile |
| Searched in this run | 24 | WhatsApp, AdMob, Palo Alto Networks, Nimble, Ruckus, Barracuda, Jive, HubSpot, GitHub, Okta, Carbon, ThousandEyes, Drawbridge, Intel, VitalSigns, Sequoia leadership, Jasper, Clari, Semgrep, Yik Yak, Neeva, Pocket Gems, Dashlane, Rhapsody/Peribit/Entrisphere. |
| Researched enough for case synthesis | 10 | WhatsApp, AdMob, Palo Alto Networks, Nimble, Ruckus, Jive, Barracuda, HubSpot, GitHub, Jasper. |
| Sufficiently reconstructed | 4 | WhatsApp, AdMob, Palo Alto Networks, Jive/Nimble as adverse-outcome controls. |
| Unresolved | 15+ | Full ownership/economics for nearly all cases; failures/pass/write-off ledger; current private outcomes; Accel-era company-name controls. |
| Excluded controls | 1 | Doe v. Sequoia docket surfaced but lacks Goetz linkage, so it is a firm/legal route only. Justia docket |
Coverage fraction: not computable. The numerator is a curated public list and the denominator of all Goetz-attributable investments, passes, reserves, write-offs, and partial exits is nonpublic.
Historical market, regulatory, and base-rate context
Goetz's early Sequoia career sat after the dot-com crash but before cloud/mobile categories were consensus. Enterprise software was moving from licensed/on-premise products toward subscription and SaaS; TechCrunch's 2012 recap captures Goetz arguing that SaaS business models could attack legacy vendors. TechCrunch Disrupt recap
AdMob was tested by antitrust regulators because mobile advertising was emerging and Apple entered with a competing network; this gives a contemporaneous control against hindsight that Google-AdMob was obviously safe. FTC AdMob clearance
WhatsApp looked economically strange at acquisition because Facebook itself warned it monetized WhatsApp only in a limited fashion and might not generate meaningful long-term revenue. That is critical ex-ante skepticism, not a footnote. Facebook 2014 10-Q, WhatsApp note
Vehicle economics and incentives
Public records identify Sequoia as investor and Goetz as partner/director, but not fund allocation, check size by vehicle, ownership, dilution, carry, or LP distributions. The safest wording is "Sequoia/Goetz-linked" unless a company page or filing names Goetz as partner/director. Sequoia profile · Palo Alto Networks proxy
Case studies
No-hindsight setup: In 2011 WhatsApp was a low-profile mobile messaging product with a strong international utility, little marketing, and an anti-ad product posture. The risk was monetization and competition from carriers, platform owners, and social apps. Sequoia WhatsApp page
Decision: Sequoia partnered in 2011 with Goetz as partner and was the only venture firm cited by Sequoia/press accounts. Sequoia WhatsApp page · TechCrunch stake report
Outcome: Facebook completed the acquisition in October 2014, cancelling WhatsApp securities for about 177.8 million Facebook shares and $4.59 billion cash to existing securityholders, plus employee RSUs. Facebook closing 8-K, Item 2.01
Decision exercise: Invest if engagement and retention prove that phone-number identity and no-ad trust create a global network; pass if growth requires paid acquisition or if monetization pressure destroys trust. Next check: daily active/monthly active ratio, engineer-to-user leverage, market-by-market SMS displacement.
AdMob
No-hindsight setup: In 2006 mobile advertising was early, carriers and desktop web assumptions dominated, and Hamoui was a student founder with revenue but limited VC access. Sequoia AdMob story
Decision: Goetz says Sequoia saw a contrarian developer-first mobile thesis and issued a term sheet within days; Hamoui says Sequoia incubated the company in its offices. Sequoia AdMob story
Outcome: Google announced a $750 million stock acquisition agreement in 2009 and the FTC cleared the deal in 2010 after examining mobile-ad competition. Google acquisition announcement · FTC clearance
Decision exercise: Invest if early revenue growth and developer adoption show mobile is becoming its own ad market; pass if traffic depends on carrier gatekeepers or if desktop ad networks can copy distribution cheaply.
Palo Alto Networks
No-hindsight setup: Palo Alto Networks was incorporated in 2005 to build a next-generation firewall platform against entrenched security vendors. PANW IPO prospectus
Decision: Sequoia says it partnered in 2005 and lists Goetz as partner; PANW's proxy says Goetz served as a director from April 2005. Sequoia PANW page · PANW proxy
Outcome: The company went public in 2012 and remained a public-company board role for Goetz until at least the 2021 proxy. Sequoia PANW page · PANW proxy
Decision exercise: Invest if the team can turn application/user/content visibility into a category wedge with enterprise sales readiness; pass if incumbents can bundle equivalent functionality faster than the startup can earn trust.
Failures, misses, and anti-portfolio
The public record located in this run is weak on failures, but three adverse controls are now explicit. Jive was acquired in 2017 for $5.25/share and roughly $462 million, a far less triumphant outcome than an enduring public-company compounding story. Jive acquisition exhibit Nimble sold to HPE after public-market compression, so its venture return depends heavily on entry price and distribution timing rather than headline IPO status. Nimble SC 14D-9 Yik Yak is a failure lead because CB Insights links Goetz to the board and later press describes collapse, but primary board/cap-table proof remains unresolved. CB Insights teardown Treat these as a major evidence gap rather than a clean record.
Attribution and decision-rights map
| company | Goetz evidence | founder/team evidence | unknowns |
|---|---|---|---|
| Sequoia partner/board/investor narrative. Sequoia | Jan Koum, Brian Acton; Facebook filing. 8-K | Sequoia IC vote, ownership, board interventions. | |
| AdMob | Partner story and company page. Story | Omar Hamoui; Google/FTC records. Google | Sequoia stake, dilution, exact board decisions. |
| Palo Alto Networks | Board since April 2005 and Sequoia beneficial-ownership association in S-1. PANW S-1 | Nir Zuk, Lee Klarich, Rajiv Batra, later public management; Greylock/co-investor attribution needs separation. | Realized distributions, follow-on, exact IC/source credit. |
Synthesis
The record supports a falsifiable favorable thesis: Goetz was unusually good at recognizing underdog technical founders when early behavioral evidence was stronger than market consensus, and then using board-level mentorship to compress learning. The skeptical thesis is that visible results are dominated by WhatsApp and a strong Sequoia platform, while the private denominator and individual attribution remain hidden. Both are plausible; REVIEW must preserve that tension.
Coverage and evidence base
The accessible written corpus is thin but useful. This run deeply processed six priority direct or near-direct writings: Sequoia's Goetz profile, the Templeton Compression essay, the WhatsApp acquisition note, the Sequoia AdMob story, Goetz's GitHub developer-economy essay, and Goetz's Jasper/IoT milestone essay. Two transcript-bearing talks were processed in talks.md rather than treated as writings. sources.md
| source | access | processed note | evidence value |
|---|---|---|---|
| Sequoia profile | full | notes/w-sequoia-profile.md | Direct self-description of apprenticeship, founder criteria, humility, and succession culture. |
| Templeton Compression | full | notes/w-templeton-compression.md | Direct enterprise-sales/product readiness doctrine. |
| WhatsApp four numbers | partial/original retired; Sequoia route plus mirrors | notes/w-whatsapp-four-numbers.md | Direct rationale for WhatsApp's value at acquisition date. |
| AdMob story | full | notes/w-admob-story.md | Founder/investor account of rapid conviction, incubation, and mentorship. |
| GitHub developer economy | full | source-map processed | Developer-first market thesis and cultural moat. |
| Jasper IoT | full | source-map processed | Long-incubation infrastructure thesis. |
Source-by-source analysis
Sequoia profile
Goetz's profile turns his biography into a mentorship thesis: risk-seeking energy becomes productive through operating experience, then Sequoia apprenticeship teaches him to find an authentic investing style rather than copy a senior partner. The most decision-relevant claim is investor-stated / moderate: young venture partners endure a period when "the lemons have fallen" before winners are visible, so the firm must normalize uncertainty and mentorship rather than overreact to early marks. Sequoia profile, Backstory
His founder screen is not a market-map spreadsheet. He names "ambition and intelligence," a modern business model, culture-building ability, talent magnetism, tenacity, and growth mindset as the core signals. This supports an investor-stated / strong mental model of underdog founders with high slope, but it needs deal-by-deal verification before being treated as a return driver. Sequoia profile, On the Lookout for
The company roster is a useful denominator lead because it separates current companies from enduring companies and gives first-partnered years for many cases. It is not a full loss ledger, and the live page can change. Sequoia profile, Companies
The Templeton Compression
The Templeton Compression is Goetz's clearest enterprise operating doctrine. He uses Don Templeton's work at Peribit, Palo Alto Networks, Nimble Storage, and Clearwell to define "Sales Ready Product": product-market fit is not only user love, but a compressed sales learning curve where a repeatable enterprise sales organization can be built without wasteful burn. Templeton Compression, opening and concept sections
The reasoning chain is investor-stated / strong for enterprise company-building and researcher inference / moderate for Goetz's investment selection. Goetz is not merely praising sales; he is describing a board-level diagnostic: before scaling sales, founders must isolate the buyer pain, repeat the story, and learn why deals close or stall. This maps cleanly to Palo Alto Networks, Nimble, Clearwell, and other infrastructure investments, but each application needs its own contemporaneous proof. Templeton Compression
The essay's hidden assumption is that enterprise demand can be learned and compressed through disciplined customer development. It fits security/storage/networking better than viral consumer products like WhatsApp, where Goetz's own acquisition note focuses on engagement, engineering leverage, and zero marketing instead. WhatsApp company page
Four Numbers That Explain Why Facebook Acquired WhatsApp
Goetz's WhatsApp note is a compact ex-post but acquisition-date thesis. The four numbers summarize scale, operating leverage, product principle, and distribution: hundreds of millions of active users, a tiny engineering team, a one-dollar/no-ads product stance, and zero marketing. The evidence label is investor-stated / strong for what Goetz believed mattered and reported / moderate for exact user/engineering metrics until tied to WhatsApp/Facebook filings. Sequoia, “Four Numbers That Explain”
The investment lesson is not "consumer is easy." It is that Goetz was willing to support a product that violated ad-supported social-app convention because user love, privacy discipline, and international communication utility were visible in usage data. That claim is supported by the note, Goetz's Recode/Vox Q&A on why WhatsApp stood out, and Facebook's later filing warning that WhatsApp had limited monetization at closing. Vox/Recode Q&A · Facebook 2014 10-Q, WhatsApp subsequent-event note
The contradiction is important: Goetz's enterprise doctrine prizes sales readiness; WhatsApp's power was the absence of sales and marketing. The shared model is not a channel tactic, but evidence density before consensus: in both cases, he wants a non-obvious mechanism already working in the wild.
AdMob story
The AdMob story shows Goetz using speed as a weapon. Omar Hamoui had a contrarian mobile-developer advertising thesis and a weak competing term sheet; Goetz says Sequoia got comfortable in three days and offered to incubate AdMob in its offices. Sequoia AdMob story, Goetz/Hamoui turns
The strongest decision rule is investor-stated + founder witness / strong: when an unknown founder has measurable early traction, a market-level contrarian insight, and high-fidelity answers under pressure, the investor's job is to collapse process time rather than wait for consensus. Sequoia AdMob story
The support is retrospective and curated by Sequoia. Google's acquisition announcement and FTC review verify the outcome and market context, but not Sequoia's exact diligence or ownership. Google acquisition announcement · FTC AdMob clearance
Developer economy and Jasper/IoT milestone essays
Goetz's GitHub essay extends the underdog-founder model to developer-first infrastructure: a side project can become a system of record when developers adopt it as workflow substrate before traditional buyers fully understand it. The evidence label is investor-stated / moderate; the essay is direct but retrospective after Microsoft's acquisition announcement. Goetz, “The Unstoppable Rise of the Developer Economy”
The Jasper essay is an infrastructure-cycle companion: Goetz emphasizes long incubation and category formation in the Internet of Things, which fits his broader comfort with technical markets that look early or slow before demand becomes obvious. The limitation is that the essay is celebratory and does not disclose Sequoia ownership or return. Goetz, “Jasper: Pioneering the Internet of Things”
Cross-source synthesis
Across the written corpus, Goetz's repeatable pattern is documented behavior + investor-stated / moderate: find technical or product discontinuities before the broad venture market understands them; over-index on founders whose learning velocity is visible in data or hard questions; then become a close board-level thought partner as the company moves from raw pull to repeatable organization. The same pattern appears differently in AdMob's 72-hour term sheet, WhatsApp's no-marketing scale, Templeton's sales-ready enterprise product, GitHub's developer workflow, and Jasper's long IoT build. AdMob story · Four Numbers · Templeton Compression · GitHub essay · Jasper essay
Intellectual chronology, evolution, and contradictions
Goetz's public doctrine evolves from Sequoia-specific Series A/business-plan language in 2009, to enterprise infrastructure confidence in 2012, to WhatsApp's anti-ad consumer lesson in 2014, to enterprise sales-readiness in 2016, and finally to Sequoia succession/mentorship in later profile text. The contradiction is productive: he is not a single-sector investor. The durable belief is that unconventional founders can be backed early when real usage, product clarity, or buyer learning substitutes for consensus validation. Business Plans transcript mirror · TechCrunch Disrupt recap · Sequoia profile
Decision playbook and modern translation
- Historical rule: Do not wait for market consensus when a technical founder has measurable pull and a coherent non-consensus mechanism. In AdMob, the mechanism was mobile developers bypassing carriers; in WhatsApp, address-book communication and zero marketing; in enterprise, sales-ready product learning. AdMob story · WhatsApp page · Templeton Compression
- Diagnostic questions: What is the founder's unpopular premise? What measured behavior already says the premise is true? What must be learned before adding sales/marketing headcount? What would falsify the founder's culture or product discipline?
- Modern VC translation as of 2026-08-23: In AI infrastructure and developer tools, the transferable lesson is not to chase noisy category labels, but to find usage or workflow evidence that compresses customer learning. The misuse is to call every underdog "WhatsApp-like" without a measurable engagement, cost, or distribution asymmetry.
researcher inference / moderate.
Best writings and unresolved record
- Templeton Compression — best operating doctrine for enterprise investments.
- AdMob story — best founder/investor decision narrative.
- WhatsApp four numbers — best consumer-scale thesis.
- GitHub developer-economy essay — best developer-tools thesis.
- Sequoia profile — best self-described founder screen and mentorship frame.
Unresolved: original Sequoia WhatsApp URL/snapshot, original Stanford/YC captions, VitalSigns primary records, and private Sequoia memos.
Coverage and evidence base
This TALKS pass processed two priority transcript routes and inventoried two additional partial video/recap routes. Original videos should be captured in a future maintenance pass, but the available transcripts are enough to extract a first set of direct voice themes without committing full transcripts.
| source | access | processed note | why it matters |
|---|---|---|---|
| Stanford GSB Business Plans | transcript mirror; original video route | notes/t-business-plans.md | Goetz's early Series A/business-plan doctrine. |
| YC Startup School with Jan Koum | transcript mirror; original video route | notes/t-startup-school-whatsapp.md | Direct WhatsApp founder/investor relationship evidence. |
| Vox/Recode WhatsApp Q&A | full edited Q&A | sources.md | Best direct interview on WhatsApp sourcing and valuation judgment. |
| Palo Alto Networks Sequoia podcast | full transcript | sources.md | Direct Goetz voice on Palo Alto Networks category formation. |
| TechCrunch Disrupt enterprise discussion | recap/video partial | sources.md | Enterprise market thesis and Palo Alto Networks context. |
| Backstage with Jim Goetz | video partial | sources.md | Short direct voice; no transcript captured. |
Source-by-source guide
Business Plans: Jim Goetz, Sequoia Capital
The 2009 Stanford GSB lecture frames venture fundraising as a Sequoia-specific Series A evaluation problem: investors want an unfair advantage, a market strategy, credible barriers, and a founding team that can explain why now. The evidence label is investor-stated / moderate because the accessible transcript is a mirror rather than the original Stanford caption file. Glasp transcript mirror
The important contrast with later Goetz is that this talk is process-heavy while later Sequoia stories are founder-heavy. That suggests the public doctrine matured from "how Sequoia reads plans" toward "how Sequoia earns the right to be a founder's first call." Sequoia AdMob story
Startup School SV 2014: Jan Koum and Jim Goetz
The YC conversation pairs Goetz with WhatsApp founder Jan Koum after the Facebook acquisition. The transcript route supports three claims: WhatsApp optimized for product purity rather than investor attention; Goetz saw focus on end-users as central; and the founder/investor relationship was unusually close because Sequoia was the only institutional investor. Glasp transcript mirror · Sequoia WhatsApp page
This is retrospective and celebratory. It should be checked against Facebook's filing and independent accounts before using it for economics. Facebook WhatsApp closing 8-K
Vox/Recode Q&A on WhatsApp
Kara Swisher's edited Q&A is the cleanest direct interview route for Goetz immediately after the WhatsApp announcement. It should anchor future exact quote work because it asks why Goetz met WhatsApp, what attracted Sequoia, why other VCs were absent, and what he was focused on next. Vox/Recode Q&A, 20 Feb 2014
Palo Alto Networks story
Sequoia's Palo Alto Networks podcast transcript adds direct Goetz voice and founder/operator testimony around the grudge and architectural insight that shaped PANW. It materially improves the package because the prior evidence proved board tenure but said less about the decision thesis. Sequoia PANW podcast transcript
TechCrunch Disrupt 2012 enterprise appearances
TechCrunch's recap says Goetz argued that more startups should build for the enterprise, that SaaS/subscription models could be a weapon against legacy vendors, and that enterprise could look like "blue ocean" when startups faced only one or two incumbents. The quote support is from press recap rather than full transcript, so use it as reported direct speech / moderate. TechCrunch recap, 12 Sep 2012
The backstage video route is a retrieval target for exact wording. TechCrunch video page
Recurring frameworks
- Underdog founder with visible slope: Goetz repeatedly elevates unknown founders when measurable evidence is already present: Omar Hamoui's revenue ramp, Jan Koum and Brian Acton's usage/engagement, enterprise founders with hard product problems. AdMob story · Startup School transcript mirror
- Business model as attack surface: In enterprise, subscription/SaaS economics can disadvantage incumbents; in WhatsApp, a no-ads, low-fee model preserved product trust. The mechanism changes by market. TechCrunch recap · WhatsApp company page
- Board member as compression partner: In AdMob and Templeton Compression, the investor's role is to reduce learning cycles, recruit, and make the company sales/product ready rather than merely provide capital. AdMob story · Templeton Compression
Evolution, contradictions, and attribution limits
Goetz's direct public speech supports a broad venture craft, not a precise personal hit rate. The talks show enthusiasm for enterprise in 2012 and consumer messaging in 2014. The unifying logic is evidence before consensus, not sector purity. Attribution must remain split among founder, board, Sequoia partnership, and market timing. Palo Alto Networks 2021 proxy · Forbes 2015 Midas release
Listen to these first
- Vox/Recode WhatsApp Q&A — best immediate post-announcement Goetz interview.
- Startup School SV 2014 with Jan Koum — best WhatsApp relationship evidence.
- Palo Alto Networks Sequoia podcast — best PANW thesis route.
- Business Plans at Stanford GSB — best early Sequoia evaluation framework.
- TechCrunch Disrupt enterprise discussion — best public enterprise-market statement.
Open transcript work
Capture original captions from YouTube/Stanford/YC for the two mirror-transcript sources, then preserve only notes and short quotes. Search decade sweeps for additional GSB, Disrupt, Startup School, Intel, and Sequoia appearances.
Back Unknown Underdogs With Measured Slope
- Rule — Prefer unknown founders when ambition, intelligence, tenacity, and evidence of rapid learning are already visible before reputation catches up.
- Evidence status — investor-stated / moderate.
- Provenance and origin — Goetz's Sequoia profile states that every legendary founder began as an unknown underdog and lists ambition, intelligence, tenacity, and growth mindset as founder signals. Sequoia profile
- Mechanism and reasoning — Reputation lags capability. If the founder's slope is visible in product data or hard questioning, the investor can buy before consensus forms.
- Historical and vehicle context — Sequoia's early-stage franchise can convert conviction into brand, recruiting, and customer leverage.
- When to use — Early seed/Series A, especially technical products where usage or revenue ramps are visible.
- How to apply it — Ask what the founder understands that consensus misses; pressure-test with domain questions; verify actual usage/revenue slope; identify the next falsifying milestone.
- Examples — AdMob: Hamoui had a contrarian mobile-developer thesis and early revenue ramp. AdMob story WhatsApp: Koum/Acton avoided investors but had product purity and engagement. WhatsApp page Palo Alto Networks: technical security founders created a new firewall platform. PANW IPO prospectus
- Evidence — Sequoia profile, AdMob story, WhatsApp page, PANW filings.
- Limits, failure modes, and exception ledger — Underdog status alone is meaningless; the missing loss ledger could reveal many false positives.
- Evolution and contradictions — The model spans consumer and enterprise, but the proof type changes by market.
- Modern VC translation (as of 2026-08-23) — In AI, do not equate obscurity with edge; require usage, retention, workflow replacement, or revenue quality.
Compress Learning Before Scaling
- Rule — Do not pour capital into sales or marketing until product, buyer, message, and repeatable motion are clear enough to compress the learning curve.
- Evidence status — investor-stated / strong for enterprise doctrine; researcher inference / moderate for investment selection.
- Provenance and origin — Goetz's Templeton Compression essay names Sales Ready Product and honors Don Templeton's process at Peribit, Palo Alto Networks, Nimble, and Clearwell. Templeton Compression
- Mechanism and reasoning — Enterprise sales burns cash while learning; compression lowers waste and reveals true product-market fit.
- Historical and vehicle context — Post-2004 enterprise SaaS/cloud companies could use subscription models and focused sales processes against legacy vendors.
- When to use — Enterprise infrastructure, security, storage, collaboration, and developer tools.
- How to apply it — Track first repeatable customer segment, common pain, proof points, objection handling, and sales-cycle reproducibility before hiring aggressively.
- Examples — Palo Alto Networks, Nimble Storage, and Clearwell appear in the essay's lineage. Templeton Compression Jive's 2007 financing was explicitly for product plus sales/marketing expansion after customer traction. eWeek Jive funding
- Evidence — Templeton essay plus enterprise IPO/funding records.
- Limits, failure modes, and exception ledger — Consumer networks like WhatsApp may not need sales compression; applying the model there would misdiagnose the company.
- Evolution and contradictions — Goetz's WhatsApp success shows he can suspend enterprise sales doctrine when distribution is product-led.
- Modern VC translation (as of 2026-08-23) — For AI enterprise tools, separate demo excitement from repeatable budget ownership and deployment proof.
Treat Business Model As A Weapon
- Rule — A startup's pricing and delivery model can be as disruptive as its product features.
- Evidence status — reported direct speech / moderate.
- Provenance and origin — TechCrunch reported Goetz saying SaaS business models let startups disrupt legacy enterprise vendors. TechCrunch Disrupt recap
- Mechanism and reasoning — Subscription or usage models can lower adoption friction, align with customer outcomes, and make incumbent bundles awkward.
- Historical and vehicle context — Cloud and SaaS adoption after Salesforce changed buyer expectations.
- When to use — Enterprise categories where incumbents sell expensive bundled appliances or licenses.
- How to apply it — Identify incumbent gross-margin pools, buyer frustration, adoption friction, and whether the startup's model compounds distribution.
- Examples — Palo Alto Networks challenged legacy appliance assumptions. PANW IPO prospectus AdMob monetized mobile apps around developers. Google AdMob announcement WhatsApp used low-fee/no-ad trust against ad-supported messaging. WhatsApp page
- Evidence — TechCrunch recap, IPO/acquirer records, Sequoia narratives.
- Limits, failure modes, and exception ledger — A better model without product superiority can still lose; public evidence does not prove model caused returns.
- Evolution and contradictions — Goetz uses the model in both enterprise and consumer but with different mechanisms.
- Modern VC translation (as of 2026-08-23) — AI pricing shifts can be weapons only when inference cost, user value, and workflow ownership support them.
Earn The Founder’s First Call
- Rule — The investor's advantage compounds when the founder calls them first for uncomfortable decisions.
- Evidence status — founder witness + investor-stated / strong for AdMob; moderate for broader career.
- Provenance and origin — Hamoui says Goetz became the person he talked to for advice and hard moments; Goetz says incubation creates brutal honesty. AdMob story
- Mechanism and reasoning — Trust improves information flow, board usefulness, recruiting, and timing of strategic decisions.
- Historical and vehicle context — Sequoia could incubate founders and provide high-status help without syndicate dilution in some cases.
- When to use — Founder-led companies with lonely CEOs, technical founders, or unconventional cultures.
- How to apply it — Be useful before asking for control; create candid operating reviews; help recruit; avoid performative board advice.
- Examples — AdMob office incubation. AdMob story WhatsApp sole-investor board relationship. WhatsApp page Sequoia apprenticeship and mentorship culture. Sequoia profile
- Evidence — AdMob story, WhatsApp company page, Sequoia profile.
- Limits, failure modes, and exception ledger — Trust can become over-identification; no public records show how Goetz handled founder conflict in failed companies.
- Evolution and contradictions — The model matures from receiving mentorship at Sequoia to mentoring younger partners and founders.
- Modern VC translation (as of 2026-08-23) — In crowded seed markets, "value-add" is cheap talk; the test is whether founders disclose bad news early.
Separate Signal From Fame
- Rule — Use behavior and operating evidence, not press heat, to decide whether a company is special.
- Evidence status — documented behavior / moderate.
- Provenance and origin — WhatsApp had no marketing and little U.S. press glamour, while AdMob was a student-founder company under time pressure. WhatsApp page · AdMob story
- Mechanism and reasoning — Fame often arrives after the return has been arbitraged away; behavior can reveal quality earlier.
- Historical and vehicle context — Mobile and enterprise shifts created data before broad VC consensus.
- When to use — Markets where usage logs, revenue ramps, customer pull, or technical adoption are more reliable than media attention.
- How to apply it — Demand direct metrics, customer references, and technical diligence; discount pitch polish.
- Examples — WhatsApp's zero marketing growth. WhatsApp page AdMob's measurable revenue ramp. AdMob story Palo Alto Networks' technical platform and enterprise risk disclosures. PANW IPO prospectus
- Evidence — Sequoia and filing records.
- Limits, failure modes, and exception ledger — Metrics can be noisy or manipulated; no full failed-metric examples surfaced.
- Evolution and contradictions — Later Midas fame risks obscuring the original low-fame evidence.
- Modern VC translation (as of 2026-08-23) — In AI, ask for retention, cost curves, and workflow integration rather than demo virality.
Let The Firm Outlive The Star
- Rule — A venture partnership should transfer trust, responsibility, and culture before a star investor's incentives harden into control.
- Evidence status — investor-stated + reported / moderate.
- Provenance and origin — Goetz's profile praises Sequoia culture as larger than any person; Axios reports his 2017 stewardship handoff. Sequoia profile · Axios
- Mechanism and reasoning — Venture feedback cycles are long; institutional mentorship increases odds that judgment and access survive partner transitions.
- Historical and vehicle context — Sequoia's Valentine-to-Moritz/Leone-to-Botha lineage gives the model institutional credibility.
- When to use — Partnership design, succession, and talent development.
- How to apply it — Give younger partners real ownership, normalize self-doubt, and transition leadership before decay.
- Examples — Goetz shadowing senior partners. Sequoia profile Goetz stepping back for Botha. Axios Forbes noting he remained a Midas figure after stepping aside. Forbes profile
- Evidence — Sequoia profile, Axios, Forbes.
- Limits, failure modes, and exception ledger — Public stories may sanitize economics and internal politics; carry/control details are private.
- Evolution and contradictions — Star-investor rankings celebrate individuals; Sequoia's stated culture downplays individual permanence.
- Modern VC translation (as of 2026-08-23) — Firms chasing personal brands should test whether junior partners actually control deals and economics.
What the evidence supports
The package supports a bounded claim that Goetz combined technical/operator background, Sequoia apprenticeship, fast conviction, and close founder mentorship across several major mobile and enterprise outcomes. The strongest evidence anchors are Sequoia's Goetz/portfolio pages, the AdMob and WhatsApp narratives, public acquirer/SEC filings, and Palo Alto Networks proxy records. Sequoia profile · AdMob story · Facebook 8-K · PANW proxy
What could falsify the thesis
A complete Sequoia ledger could show that the visible wins were a thin right tail over a weak base rate. Internal records could shift sourcing or IC credit away from Goetz. Founder and board testimony from ordinary or failed investments could show that the mentorship/compression model was selectively remembered from winners.
Attribution and denominator audit
The denominator remains the largest weakness. Sequoia's current roster and Forbes Midas are not a full career ledger. WhatsApp economics are headline-visible but fund economics are press-reported. AdMob and Palo Alto Networks outcomes are primary-supported, but Goetz-specific ownership and realized proceeds are not. Forbes 2015 Midas release · TechCrunch WhatsApp stake report
Transfer limits for modern VCs
The transferable lessons are evidence-before-consensus, founder learning velocity, and sales-readiness discipline. The non-transferable temptation is to copy outcomes: a no-ad consumer network, a fast term sheet, or an enterprise sales playbook only works when the underlying usage, buyer, and product evidence exists.
Unresolved evidence
- Original YouTube/Stanford/YC caption capture for talk pinpoints.
- Official FTC v. Meta trial transcript retrieval for Goetz WhatsApp testimony and Sequoia memo references.
- VitalSigns primary records and acquisition/economics.
- Sequoia fund-level ownership, cash flows, and carry allocation.
- Full pass, failure, down-round, and write-off ledger.
- Company-by-company board contribution evidence.
- CourtListener/SEC/state-docket searches beyond broad web discovery.
Acceptance evidence
| # | requirement | status | document/section inspected | correction or continuation |
|---|---|---|---|---|
| 1 | Deep chronology | pass | _profile.md chronology |
Sourced scaffold complete; causal claims bounded. |
| 2 | Falsifiable thesis | pass | investmentphilosophy.md edge thesis |
Falsifiers named. |
| 3 | Ex-ante deals | pass with caveat | investments.md case studies |
Three cases reconstructed; more cases need future depth. |
| 4 | Pareto analysis | pass with caveat | investments.md first H2 |
No unsupported literal 80/20 percentage. |
| 5 | No placeholders | pass | root docs | No future-phase placeholder docs added. |
| 6 | Denominator | pass with caveat | investments.md boundary |
Coverage fraction correctly not computable. |
| 7 | Writings | pass | writings.md |
Four priority writings analyzed. |
| 8 | Mental models | pass with caveat | mental-models.md |
Six models, evidence and limits; examples below ideal depth where record thin. |
| 9 | Modern translation | pass | writings/philosophy/models | Dated 2026-08-23 translations included. |
| 10 | Failure postmortems | pass with caveat | investments failures section | Jive/Nimble/Yik Yak adverse controls added; still not a complete loss ledger. |
| 11 | Team attribution | pass | profile/investments | Founder/team boundaries explicit. |
| 12 | Vehicle economics | pass with caveat | investments | Nonpublic economics clearly bounded. |
| 13 | Historical context | pass | investments | Mobile, enterprise, regulatory controls included. |
| 14 | Direct voice exhaustion | pass with caveat | sources/writings/talks | Original captions remain retrieval target. |
| 15 | Pinpoint citations | pass with caveat | all docs | Links adjacent; some locators are section-level due web pages. |
| 16 | Evidence labels | pass | writings/models/philosophy | Material claims labeled. |
| 17 | Skeptical case | pass | philosophy/review | Strongest case against greatness included. |
| 18 | Peer comparison | pass | philosophy | Uses completed Rock and Casado only. |
| 19 | IC exercises | pass | investments | Three no-hindsight exercises included. |
| 20 | Learning architecture | pass | package | Reading path, glossary, checklists, cross-links included. |
Citation spot-check trail
| claim | source | result |
|---|---|---|
| Goetz board at PANW since April 2005 | PANW proxy | pass |
| PANW stronger pre-IPO Sequoia ownership route | PANW S-1 | pass |
| WhatsApp closing consideration | Facebook 8-K | pass |
| AdMob $750M stock acquisition | Google announcement | pass |
| Goetz Midas #1 2015 and methodology | Forbes release | pass |
| Intel board election | Intel announcement | pass |
| Jive adverse acquisition control | Jive acquisition exhibit | pass |
The package is acceptable as a first complete T053 run with explicit public-record caveats. Future maintenance should deepen source notes and deal ledgers, but no T053 phase remains empty or merely status-only.
Source-map boundary and retrieval priorities
This source map treats Goetz as an operator-turned-Sequoia investor, public-company director, enterprise/mobile board member, WhatsApp outlier investor, and Sequoia succession actor. Stars rank evidentiary priority. Rows marked complete were processed into notes or synthesis during this run; unchecked rows remain priority retrieval routes for later refinement.
Direct voice, writings, talks, and official biographies
- ★★★ | Jim Goetz — Sequoia profile | https://sequoiacap.com/people/jim-goetz | live; accessed 2026-08-23 | official profile/direct voice | Backstory, apprenticeship, founder criteria, current and enduring company roster; mutable and not a full track record. (reliability: A/B; access: full; locator: Backstory, On the Lookout for, Companies)
- ★★★ | The Templeton Compression and the Sales Ready Product | https://sequoiacap.com/article/the-templeton-compression | 2016-07-12 | essay by Goetz | Best direct writing on enterprise product-market fit, sales readiness, and board/operator pattern. (reliability: A; access: full; locator: full essay)
- ★★★ | Four Numbers That Explain Why Facebook Acquired WhatsApp | https://sequoiacap.com/article/four-numbers-that-explain | 2014-02-19 | investor-authored acquisition note | Direct WhatsApp thesis: users, engineers, no ads/no games/no gimmicks, zero marketing. (reliability: A; access: full; locator: four-number sections)
- ★★★ | Q&A With Sequoia's Jim Goetz on Wassssup With the WhatsApp Deal | https://www.vox.com/2014/2/20/11623738/qa-with-sequoias-jim-goetz-on-wassssup-with-the-whatsapp-deal | 2014-02-20 | direct Q&A | Best edited direct interview on WhatsApp sourcing, why no other VCs were involved, valuation, and Goetz's continuing search for unknown founders. (reliability: A/B; access: full; locator: Q&A questions)
- ★★★ | AdMob story — Omar Hamoui and Jim Goetz | https://articles.sequoiacap.com/admob-story | undated Sequoia story | founder/investor oral-history-style account | 72-hour term-sheet process, contrarian mobile-ad thesis, incubation in Sequoia offices, board mentorship. (reliability: A/B; access: full; locator: Goetz/Hamoui speaker turns)
- ★★★ | Stanford GSB lecture: Business Plans with Jim Goetz | https://glasp.co/youtube/gnmYSze9M2g | 2009-07-28 | video transcript mirror; original Stanford/Youtube route | Direct Series A/business-plan doctrine; use mirror only until original captions are captured. (reliability: B; access: transcript mirror; locator: video transcript)
- ★★★ | Startup School SV 2014 — Jan Koum and Jim Goetz | https://glasp.co/youtube/8-pJa11YvCs | 2014-10-14 | video transcript mirror; YC original route | Best public Goetz/Koum conversation on WhatsApp founder discipline and investor relationship. (reliability: B; access: transcript mirror; locator: video transcript)
- ★★ | TechCrunch Disrupt SF — enterprise stage discussion | https://techcrunch.com/2012/09/12/sequoias-jim-goetz-shocking-more-startups-are-not-building-for-the-enterprise/ | 2012-09-12 | press recap/video route | Direct enterprise thesis around SaaS business-model disruption and "blue ocean" enterprise markets. (reliability: B; access: recap full/video partial; locator: recap body)
- ★★ | Backstage with Jim Goetz | https://techcrunch.com/video/backstage-with-jim-goetz-2/ | recorded 2012-09-12; page 2023 | video | Short backstage direct voice on enterprise investing; transcript not located. (reliability: B; access: video/partial; locator: 4-minute video)
- ★★★ | Palo Alto Networks Story — The Grudge That Transformed Cybersecurity | https://sequoiacap.com/podcast/palo-alto-networks-ft-nir-zuk-nikesh-arora-the-grudge-that-transformed-cybersecurity | live; accessed 2026-08-23 | Sequoia podcast transcript | Direct Goetz voice and founder/operator testimony on Palo Alto Networks' founding insight and platform formation. (reliability: A/B; access: full transcript; locator: Jim Goetz speaker turns)
- ★★ | The Unstoppable Rise of the Developer Economy | https://sequoiacap.com/article/the-unstoppable-rise-of-the-developer-economy/ | 2018-06-04 | Goetz-authored GitHub milestone essay | Direct Goetz thesis on developer-first companies and GitHub's cultural moat. (reliability: A; access: full; locator: full essay)
- ★★ | Jasper: Pioneering the Internet of Things | https://sequoiacap.com/article/jasper-pioneering-the-internet-of-things | 2016-02-03 | Goetz-authored Jasper milestone essay | Direct Goetz voice on long incubation, mobile infrastructure, and IoT category formation. (reliability: A; access: full; locator: full essay)
- ★★ | The Closer — Inside Story of Facebook's Biggest Acquisition transcript | https://www.thecloser.fm/episode-3-transcript/ | podcast transcript | Reported WhatsApp deal narrative with Neeraj Arora and Goetz role leads. (reliability: B; access: full transcript; locator: 08:01 Goetz/Arora passage)
- ★★★ | FTC v. Meta trial transcript route | https://dockets.justia.com/docket/district-of-columbia/dcdce/1%3A2020cv03590/224921 | 2025 trial route | court-testimony lead | MLex/Law360 reporting indicates Goetz testimony on WhatsApp valuation and Sequoia memos; official transcript likely requires docket/PACER retrieval. (reliability: A if transcript acquired; current access: route/partial; locator: April 2025 trial transcript entries)
- ★★ | Intel board announcement | https://www.intc.com/filings-reports/all-sec-filings/content/0001193125-19-292429/d822085dex991.htm | 2019-11-14 | official issuer release | VitalSigns, operating background, Intel board election. (reliability: A; access: full; locator: background paragraphs)
- ★★ | Intel board current page | https://www.intel.com/content/www/us/en/corporate/board-directors.html | live; accessed 2026-08-23 | issuer page | Current board status as of this run; mutable. (reliability: A/B; access: full; locator: board roster)
Company and deal records
- ★★★ | WhatsApp — Sequoia company page | https://sequoiacap.com/companies/whatsapp | live; accessed 2026-08-23 | official portfolio record | Founded/partnered/acquired milestones, Goetz partner attribution, Sequoia thesis. (reliability: A/B; access: full; locator: milestones, partner, why partnered)
- ★★★ | Facebook 8-K — WhatsApp closing | https://www.sec.gov/Archives/edgar/data/1326801/000132680114000037/fb_8-kxclosingxofxwhatsapp.htm | 2014-10-06 | SEC filing | Closing mechanics, cash, shares, RSUs, Koum board appointment; primary transaction record. (reliability: A; access: full; locator: Item 2.01)
- ★★★ | Facebook 8-K/A — WhatsApp financial exhibits index | https://www.sec.gov/Archives/edgar/data/1326801/000132680114000047/0001326801-14-000047-index.html | 2014-10-28 | SEC filing index | Routes to audited WhatsApp FY2013 financials and pro forma data. (reliability: A; access: full; locator: exhibits 99.1-99.3)
- ★★ | TechCrunch — Sequoia stake in WhatsApp | https://techcrunch.com/2014/02/19/sequoia-and-jim-goetz-are-big-winners-in-facebooks-whatsapp-acquisition/ | 2014-02-19 | reported economics | Reported ~$60M invested, high-teens stake, ~$3B value; needs independent triangulation. (reliability: B; access: full; locator: updated funding-history paragraphs)
- ★★★ | AdMob — Sequoia company page | https://sequoiacap.com/companies/admob/ | live; accessed 2026-08-23 | official portfolio record | Founded/partnered/acquired milestones and Goetz partner attribution. (reliability: A/B; access: full; locator: milestones, partner)
- ★★★ | Google to acquire AdMob | https://googlepress.blogspot.com/2009/11/google-to-acquire-admob_09.html | 2009-11-09 | acquirer announcement | $750M stock agreement and strategic rationale. (reliability: A; access: full; locator: opening acquisition paragraphs)
- ★★★ | FTC closes Google-AdMob investigation | https://www.ftc.gov/news-events/news/press-releases/2010/05/ftc-closes-its-investigation-google-admob-deal | 2010-05 | regulator release | Antitrust review and emerging mobile-ad market context. (reliability: A; access: full; locator: release body)
- ★★★ | Palo Alto Networks — Sequoia company page | https://sequoiacap.com/companies/palo-alto-networks | live; accessed 2026-08-23 | official portfolio record | Partnered 2005, IPO 2012, Goetz partner attribution. (reliability: A/B; access: full; locator: milestones/team/partners)
- ★★★ | Palo Alto Networks IPO S-1 | https://www.sec.gov/Archives/edgar/data/1327567/000119312512153764/d318373ds1.htm | 2012 | SEC filing | Pre-IPO Sequoia stake and Goetz beneficial-ownership association; stronger economics/attribution source than later proxy alone. (reliability: A; access: full; locator: principal stockholders/director sections)
- ★★★ | Palo Alto Networks 2021 proxy | https://www.sec.gov/Archives/edgar/data/1327567/000120677421002675/panw3943601-def14a.htm | 2021 | SEC filing | Goetz board since April 2005; education; former boards. (reliability: A; access: full; locator: James J. Goetz biography)
- ★★★ | Palo Alto Networks IPO prospectus | https://www.sec.gov/Archives/edgar/data/1327567/000119312512423352/d412524ds1a.htm | 2012 | SEC filing | Company founding, product/market risks, IPO context; use for ex-ante/posture evidence. (reliability: A; access: full; locator: prospectus summary/risk factors)
- ★★★ | Nimble Storage IPO prospectus | https://www.sec.gov/Archives/edgar/data/1452751/000119312513458451/d563804ds1a.htm | 2013 | SEC filing | Storage company context and IPO record; Goetz board dates from proxy bio. (reliability: A; access: full; locator: prospectus summary)
- ★★★ | Nimble Storage SC 14D-9 | https://www.sec.gov/Archives/edgar/data/1452751/000119312517086167/d334994dsc14d9.htm | 2017 | SEC filing | HPE acquisition process and $12.50/share transaction context; needed for adverse/return check. (reliability: A; access: full; locator: transaction summary)
- ★★ | Ruckus Networks — Sequoia company page | https://sequoiacap.com/companies/ruckus-networks/ | live; accessed 2026-08-23 | official portfolio record | Partnered 2002, IPO 2012, Goetz partner attribution. (reliability: A/B; access: full; locator: milestones/partner)
- ★★ | Jive Software IPO prospectus | https://www.sec.gov/Archives/edgar/data/1462633/000119312511278785/d211300ds1a.htm | 2011 | SEC filing | Jive external-capital timing and enterprise-collaboration context. (reliability: A; access: full; locator: prospectus summary)
- ★★★ | Jive acquisition exhibit | https://www.sec.gov/Archives/edgar/data/1462633/000119312517200845/d410654dex99a5i.htm | 2017 | SEC filing exhibit | $5.25/share/$462M acquisition evidence; adverse check versus IPO-era expectations. (reliability: A; access: full; locator: merger announcement)
- ★★ | Jive funding report | https://www.eweek.com/enterprise-apps/jive-talks-itself-into-15-million-in-funding/ | 2007-08-21 | contemporaneous press | $15M Sequoia funding and customer/product framing; not audited economics. (reliability: B; access: full; locator: opening funding paragraphs)
- ★★ | Barracuda Networks IPO prospectus | https://www.sec.gov/Archives/edgar/data/1348334/000119312513387339/d563790ds1.htm | 2013 | SEC filing | Security/storage IPO context; needs Goetz-specific ownership/board extraction. (reliability: A; access: full; locator: prospectus)
- ★★ | HubSpot public filings/company page | https://sequoiacap.com/people/jim-goetz | live profile route | official profile roster | Sequoia lists HubSpot as Goetz enduring company; extract IPO/proxy records in DEALS continuation if needed. (reliability: A/B; access: full; locator: Enduring companies)
- ★★ | GitHub / Okta / Carbon / ThousandEyes company records | https://sequoiacap.com/people/jim-goetz | live profile route | official profile roster | Listed as Goetz current/enduring companies; each needs independent entry/outcome verification. (reliability: A/B; access: full; locator: company roster)
Rankings, press, criticism, and governance controls
- ★★ | Forbes profile — Jim Goetz | https://www.forbes.com/profile/jim-goetz/ | updated 2020-04-14; crawled 2026 | reported profile | Midas status, leadership step-back, Carbon/Drawbridge leads; not a complete portfolio. (reliability: B; access: full; locator: From the Editor)
- ★★ | Forbes 2015 Midas release | https://www.forbes.com/sites/forbespr/2015/03/25/jim-goetz-of-sequoia-capital-tops-forbes-14th-annual-midas-list/ | 2015-03-25 | ranking methodology/profile | Names WhatsApp, Palo Alto Networks, Nimble Storage and methodology. (reliability: B; access: full; locator: top-ten/methodology paragraphs)
- ★★ | Forbes 2017 Midas gallery | https://www.forbes.com/pictures/fhgl45lime/1-jim-goetz/ | 2017-04-26 | ranking profile | Shows four-year post-WhatsApp Midas dominance and nearly $22B sale framing. (reliability: B; access: full; locator: Goetz card)
- ★★ | Axios — Sequoia leadership shake-up | https://www.axios.com/2017/12/15/sequoia-capital-shakes-up-leadership-1513300220 | 2017-01-31 | reported firm succession | Goetz stewardship transition and next-generation handoff. (reliability: B; access: full; locator: leadership-change paragraphs)
- ★★ | Bizjournals — Goetz steps aside | https://www.bizjournals.com/sanjose/news/2017/01/31/no-1-midas-investorjim-goetz-steps-aside-at.html | 2017-01-31 | local business press | Additional transition account; paywall/access partial. (reliability: B; access: partial; locator: accessible snippet)
- ★★ | Yik Yak failure lead | https://www.cbinsights.com/research/sequoia-capital-teardown/ | 2017 context | market/portfolio teardown lead | CB Insights identifies Goetz board involvement; later reports describe collapse. Needs primary board/cap-table proof before assigning personal failure. (reliability: B/C; access: partial; locator: Yik Yak/Goetz passages)
- ★ | Justia docket — Doe v. Sequoia Capital Operations LLC | https://dockets.justia.com/docket/circuit-courts/ca2/26-1373 | 2026 | legal search lead | Sequoia-entity suit surfaced in broad legal search but not Goetz-specific; do not use for personal criticism absent linkage. (reliability: A for docket metadata; access: partial; locator: docket summary)
- ★★ | SEC SALI search | https://www.sec.gov/litigations/sec-action-look-up | live; accessed 2026-08-23 | regulator lookup route | Search route for individual enforcement checks; no Goetz result was extracted in this run. (reliability: A; access: route only; locator: search tool)
Coverage assessment
Direct-voice coverage is adequate for a first complete package: official profile, one major essay, two Sequoia founder/investor stories, and two video-transcript routes. Deal coverage is strongest for WhatsApp, AdMob, Palo Alto Networks, Nimble, Jive, Ruckus, and board histories; weaker for current/private holdings and failures. The searched denominator remains incomplete because Sequoia's live profile is a curated roster, Midas only sees large exits, and no public fund ledger or pass/write-off list surfaced. Later maintenance should capture original YouTube/Stanford/YC captions, extract share tables from IPO filings, and search CourtListener/SEC/state dockets more mechanically.
Source notes
t Business Plans: Jim Goetz, Sequoia Capital
- URL: https://glasp.co/youtube/gnmYSze9M2g | Published: 2009-07-28 | Format: video transcript mirror | Reliability: B | Access: transcript mirror | Accessed: 2026-08-23 | Locator scheme: transcript text
Takeaways
- Goetz teaches Series A evaluation through unfair advantage, market strategy, barriers, and team quality.
- Use as a retrieval route until original Stanford captions are captured.
Quotes
- No quote used in synthesis pending original-caption verification.
Biography and decision evidence
- Early public record of Goetz as Sequoia educator and investor.
Philosophy signals
- tags: fundraising / Series A / business plans / team / market
Contradictions, counterevidence, and access limits
- Mirror transcript, not original; wording needs verification before quotation.
Open questions
- Capture original YouTube/Stanford caption file.
t Jim Goetz and Jan Koum at Startup School SV 2014
- URL: https://glasp.co/youtube/8-pJa11YvCs | Published: 2014-10-14 | Format: video transcript mirror | Reliability: B | Access: transcript mirror | Accessed: 2026-08-23 | Locator scheme: transcript text
Takeaways
- Goetz/Koum conversation reinforces product purity, user focus, and the unusual founder-investor relationship around WhatsApp.
- The record is retrospective, after Facebook announced/acquired WhatsApp.
Quotes
- No quote used in synthesis pending original-caption verification.
Biography and decision evidence
- Useful direct route for WhatsApp board relationship and founder discipline.
Philosophy signals
- tags: consumer / focus / board / founder relationship / network effects
Contradictions, counterevidence, and access limits
- Mirror transcript; exact wording and timestamps need original source verification.
Open questions
- Capture YC original video captions and timestamps.
w AdMob story
- URL: https://articles.sequoiacap.com/admob-story | Published: undated | Format: founder/investor story | Reliability: A/B | Access: full | Accessed: 2026-08-23 | Locator scheme: speaker turns
Takeaways
- Goetz moved fast after introduction to Omar Hamoui, issued a term sheet in days, and incubated the company at Sequoia.
- Founder witness supports Goetz as close thought partner during company building.
Quotes
- "We were interested right away."
Biography and decision evidence
- AdMob partnered 2006 and was acquired by Google; Google announced $750M stock consideration in 2009.
Philosophy signals
- tags: speed / contrarian market / mobile / mentorship / incubation
Contradictions, counterevidence, and access limits
- Curated retrospective; no exact Sequoia ownership or fund return.
Open questions
- Extract Sequoia ownership from filings if available.
w Sequoia profile
- URL: https://sequoiacap.com/people/jim-goetz | Published: live profile; accessed 2026-08-23 | Format: official profile | Reliability: A/B | Access: full | Accessed: 2026-08-23 | Locator scheme: page sections
Takeaways
- Goetz frames his career as risk-seeking energy shaped by mentorship and Sequoia apprenticeship.
- Founder screen: ambition, intelligence, modern business model, culture-building, talent magnetism, tenacity, growth mindset.
- Company roster is a candidate denominator, not a complete ledger.
Quotes
- "Every legendary founder started as an unknown underdog."
Biography and decision evidence
- Joined Sequoia after VitalSigns; shadowed senior partners; current/enduring company roster lists AdMob, WhatsApp, Palo Alto Networks, Nimble, Okta, HubSpot, GitHub, and others.
Philosophy signals
- tags: sourcing / picking / portfolio / boards / people / succession
Contradictions, counterevidence, and access limits
- Mutable official profile; no losses, ownership, or fund economics.
Open questions
- Which listed companies are Goetz-led versus Sequoia-associated?
w The Templeton Compression and the Sales Ready Product
- URL: https://sequoiacap.com/article/the-templeton-compression | Published: 2016-07-12 | Format: essay | Reliability: A | Access: full | Accessed: 2026-08-23 | Locator scheme: headings
Takeaways
- Goetz defines Sales Ready Product as the enterprise condition where product, buyer pain, story, and sales learning are repeatable enough to scale.
- Don Templeton's work at Peribit, Palo Alto Networks, Nimble Storage, and Clearwell becomes the central example.
Quotes
- "Every sales organization has a learning curve."
Biography and decision evidence
- Strongest direct evidence for Goetz's enterprise operating doctrine.
Philosophy signals
- tags: enterprise / sales / product-market fit / boards / scaling
Contradictions, counterevidence, and access limits
- Enterprise-specific; does not explain WhatsApp-style product-led consumer distribution.
Open questions
- Which portfolio board records show Goetz applying this method?
w Four Numbers That Explain Why Facebook Acquired WhatsApp
- URL: https://sequoiacap.com/article/four-numbers-that-explain | Published: 2014-02-19 | Format: investor-authored acquisition note | Reliability: A | Access: full | Accessed: 2026-08-23 | Locator scheme: numbered sections
Takeaways
- Goetz/Sequoia explained WhatsApp through active users, small engineering team, product purity, and zero marketing.
- The case is about product discipline and engagement, not conventional monetization.
Quotes
- "No Ads! No Games! No Gimmicks!"
Biography and decision evidence
- Sequoia company page lists Goetz as partner, partnered 2011, acquired 2014.
Philosophy signals
- tags: consumer / network effects / focus / privacy / capital efficiency
Contradictions, counterevidence, and access limits
- Original post route appears retired; Facebook filings needed for transaction mechanics.
Open questions
- Locate original Sequoia snapshot and board-level investment memo if ever public.