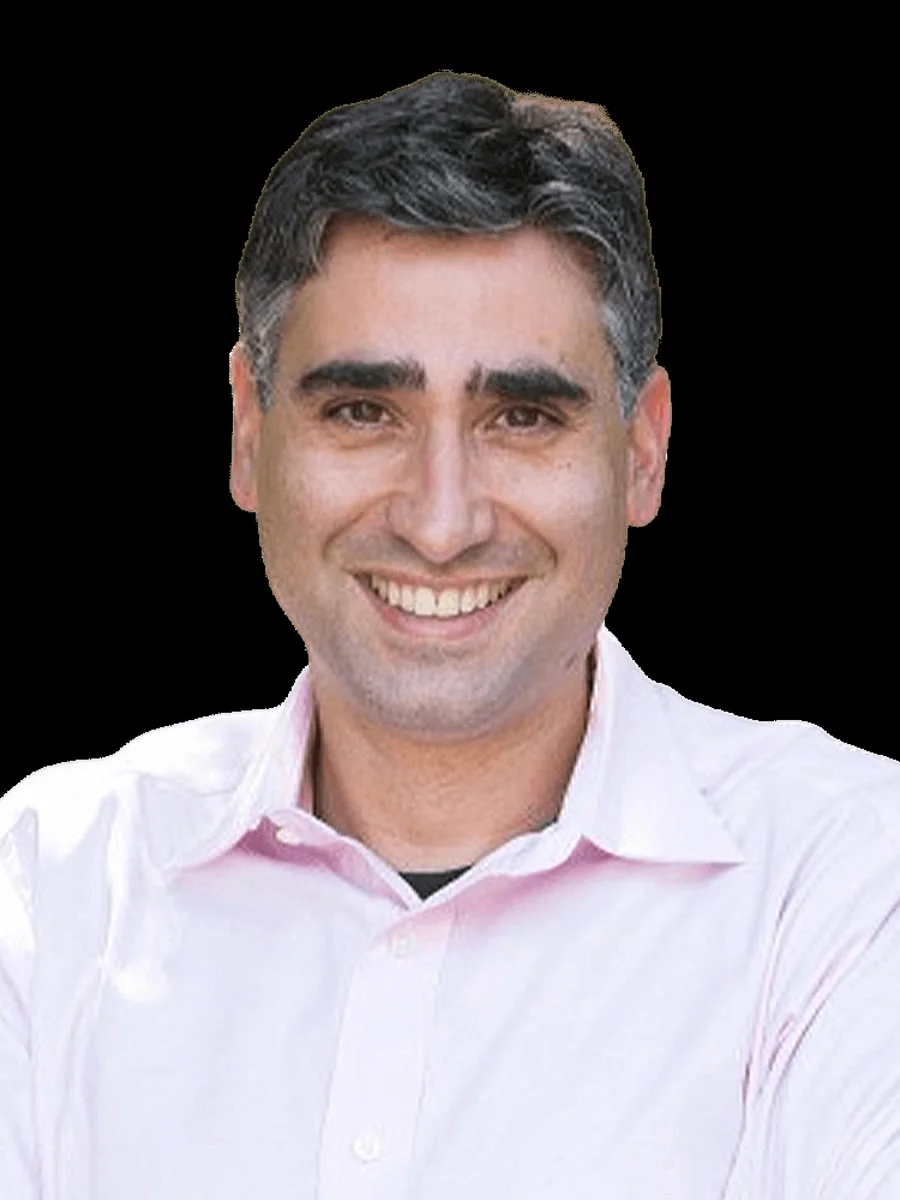
Martin Casado
Networking founder turned a16z's infrastructure theorist; prolific writer on AI economics.
Security, systems, and the habit of changing the control point (c. 1976/1977–2003)
Casado's useful formation is not a tidy founder myth. LLNL's 2015 direct-interview profile says he was 38, which supports an approximate 1976/1977 birth year; it places his birth near Seville and his childhood across Colorado, Montana, and Flagstaff, while a 2012 Fortune profile says Cartagena. No civil record located in this project resolves the discrepancy. [retrospective witness · moderate] LLNL, opening biography · Fortune, biography paragraphs
At Northern Arizona University he studied computer science and engineering, then worked at Lawrence Livermore National Laboratory from 1998 to 2003, first on atmospheric and large-scale simulations and later on a classified network-security assessment after September 11. LLNL's dates control over a later NEC attachment's 2000–2006 range, but the often-repeated causal bridge from that security work to his later architecture remains his and LLNL's retrospective account, not a decision-date diary. [retrospective witness · moderate] Stanford personal page, “Education” · LLNL, LLNL and post-9/11 passages
The durable lesson was a systems question: security failures could be properties of architecture and administration, not merely individual devices. [researcher inference · moderate] That framing predicts Casado's later preference for moving intelligence into a new control layer, but chronology alone does not prove that the lab caused the investment method. LLNL, post-9/11 passage · Ethane, abstract
Stanford, collaborative invention, and the first commercialization boundary (2003–2007)
At Stanford, Casado completed an MS—his own page and a contemporaneous teaching case say 2005, while Stanford Magazine styles it MS ’07—and a 2007 PhD. His dissertation, Architectural Support for Security Management in Enterprise Networks, and the SANE and Ethane papers moved from security policy toward logically centralized network control. These were team records: Nick McKeown, Scott Shenker, Dan Boneh, Michael Freedman, Justin Pettit, Jianying Luo, Natasha Gude, Nick McKeown's group, and other collaborators appear across the papers and institutions. [contemporaneous record · strong] Stanford personal page, “Education” · dissertation, title and approval pages · SANE, abstract and author list · Ethane, abstract and author list
Casado also co-founded Illuminics Systems, an IP-analytics company later acquired by Quova. The current record does not establish its entity history, complete founder team, financing, transaction value, ownership, or proceeds. [contemporaneous record · insufficient public record] a16z profile, biography paragraphs · NAU commencement program, p. 6
The later “inventor of software-defined networking” shorthand is too broad. Casado materially coauthored SANE, Ethane, NOX, Open vSwitch, and Onix work, but he is not an author of the canonical 2008 OpenFlow paper, and independent history traces SDN through multiple earlier programs and teams. [contemporaneous record · strong] Stanford publication index · OpenFlow, title and author list · Feamster, Rexford, and Zegura, pp. 9–10
This period formed the first candidate edge: deep technical work can expose a misplaced control point before the commercial market has a settled category. [researcher inference · moderate] It is a sourcing hypothesis, not proof of superior selection. dissertation, title and approval pages · Ethane, abstract
Nicira: from research architecture to product, governance, and a measured exit (2007–2016)
Casado, McKeown, and Shenker founded Nicira in 2007. Later institutional and founder accounts say vendors showed little interest in directly adopting the research, so the team shifted toward network virtualization. Casado distinguishes his own full-time founder role from his academic co-founders' roles; the distinction is relevant but retrospective. [retrospective witness · moderate] ICSI, “A Revolution with ICSI Roots” · Casado, “The technical founder maze”
NOX, Open vSwitch, Onix, and the broader Nicira team made the architecture operational. Teemu Koponen, Justin Pettit, Ben Pfaff, and many others belong in the technical record; Steve Mullaney and later VMware teams belong in commercialization and scale. [contemporaneous record · strong] Open vSwitch research index · Stanford publication index
Casado's 2020 account of Nicira's three-CEO sequence is unusually valuable because it admits repeated founder/CEO mismatch and the eventual need for role clarity. It is still a retrospective founder narrative without board minutes, votes, compensation records, or the other executives' complete accounts. [retrospective witness · moderate] Casado, “Bringing in an External CEO,” full essay
Before the sale, contemporaneous sources showed a shipping Network Virtualization Platform, early customers, more than $50 million of financing, incumbent response, and adoption risk. In August 2012 VMware completed the acquisition. The announced transaction was approximately $1.26 billion; VMware later reported $1.0996 billion of aggregate consideration net of acquired cash and $152.4 million of assumed equity attributed to post-combination service. None of those measures reveals Casado's personal proceeds or a16z's fund return. [contemporaneous record · strong] Fortune, financing/customers/risks · VMware 2012 Form 10-K, Note B
Casado stayed through VMware's integration, ultimately leading networking and security. A 2014 interview cited a $100 million run rate; a16z's 2016 appointment announcement later cited $600 million at 2015 year-end. These are annualized operating measures, not audited standalone revenue or investment returns. [contemporaneous record · moderate] Network World, opening role and run-rate questions · a16z appointment, VMware paragraphs
The most transferable operating formation is therefore narrower than “successful founder”: identify a control abstraction, survive a market with no agreed category, translate the architecture into a reusable product, recruit complementary management, and use distribution to scale. [researcher inference · moderate] Nicira supports the mechanism; it does not establish that Casado could repeatedly select external companies. Casado, “Bringing in an External CEO” · Fortune, product/customers/risks
The operator becomes an infrastructure investor (2016–2020)
In February 2016 Casado announced that he would leave VMware's operating role, remain a strategic adviser, and join a16z on 1 April. The firm appointed him a general partner focused on enterprise and infrastructure as Fund V supplied a $1.5 billion multi-stage platform. [contemporaneous record · strong] Casado, “And So…,” full post · a16z appointment · Fund V, allocation paragraphs
The early public deal record moved through optimization, APIs, microservices, customer-data systems, space infrastructure, analytics, hardware security, data pipelines, and open-source commercialization. SigOpt described deepening a prior seed position; RapidAPI and Kong turned API structure into a market thesis; Yubico connected a product used inside a16z to practitioner reference checks; Tecton linked an operating team to a production feature-store problem. [investor-stated · strong] SigOpt, opening and closing · RapidAPI, full body · Yubico, diligence and closing · Tecton, final two paragraphs
The pattern is not “only invest in one's circle of competence.” Astranis explicitly began outside Casado's domain and required learning a new technical, regulatory, and capital system. [investor-stated · strong] Astranis, unfamiliarity, architecture, and closing board passages The stronger rule is to convert unfamiliarity into falsifiable architecture, customer, supplier, financing, and regulatory questions. [researcher inference · moderate]
Public service broadened in parallel. Casado had testified to House science subcommittees on cybersecurity before joining a16z; he and Brian Shih founded MuralNet in 2017, and later public records document tribal-network work and a 2021 Jefferson Award. These facts show policy and institution-building exposure, not neutral policy expertise or measured community impact. [contemporaneous record · strong] House hearing and witness record · Triggs testimony, pp. 1–3
Cloud economics, market formation, and operating doctrine (2020–2023)
The written corpus made the investment map explicit. Casado and coauthors argued that accumulated data is rarely a durable moat without continuing marginal learning; AI products should be measured per successful task, not only by traditional software gross margin; enterprise go-to-market must connect user pull to a budget owner; cloud economics can shift at scale; and early markets “anneal” through repeated product, customer, and category interaction. [investor-stated · strong] writings synthesis, core written philosophy
The spoken corpus adds an operating boundary. Developers and open source can create distribution, but commercial conversion, pricing, support, and enterprise controls remain necessary. Category creation is a process of matching product, language, buyer, and budget—not merely declaring a new label. [investor-stated · strong] talks, 2016–2022 source guide
This period also exposes contradiction. “Infrastructure is everything” sits beside “the cloud killed infrastructure”; the sustainable interpretation is that hyperscalers commoditize broad layers while creating new specialized control points. [researcher inference · strong] writings, evolution matrix
Tackle is the best public adverse case. The Series B thesis cited customer pull and low burn, the later round was described as preemptive, and the CEO subsequently said the company had overbuilt in 2021–22 and separated 75 people. No public record identifies Casado's board vote, an investor stop rule, a process change, or the investment outcome. [documented behavior · strong] Tackle lab
AI infrastructure, concentrated capital, and policy advocacy (2023–2026)
The AI-era work extends the same architecture-to-economics method: map model, compute, tooling, and application layers; identify bargaining power and supplier concentration; measure inference-adjusted contribution; and distinguish workflow ownership from model ownership. Casado and coauthors repeatedly expect falling cost and expanding demand, while acknowledging capital intensity and unsettled value capture. [investor-stated · strong] writings, generative-AI sources 9–11 · talks, 2024–2026 guide Whether this doctrine improves selection or returns remains unproved. [researcher inference · provisional]
The vehicle changed with the thesis. a16z announced a $1.25 billion Infrastructure pool in 2024 and a $1.7 billion successor allocation in 2026. Form D and ADV records name the legal pools and Andreessen/Horowitz control chain but do not establish Casado's vote, carry, allocation, ownership, reserves, or returns. [contemporaneous record · strong] vehicle analysis
Cursor is the largest visible company outcome in the public Casado-linked record: a four-person a16z Series A thesis preceded a completed all-stock SpaceX transaction assigning Cursor a $60 billion implied equity value. It is team-attributed company value, not a Casado return. [contemporaneous record · strong] Removing Cursor leaves only $1.132729 billion of disclosed visible company-event value across Yubico and Parsec; both are required to cross 80 percent. [researcher inference · strong] investments, economic rank and outlier test
World Labs' $1 billion 2026 financing is capital raised, not a disclosed valuation or return. AI's 88.8 percent share of US VC deal value in Q1 2026 is material base-rate context: scale may reflect company quality and regime concentration together. [contemporaneous record · strong] World Labs, opening funding paragraph · Q1 2026 Venture Monitor, Executive Summary
Casado's policy arguments favor evidence-based, capability-specific regulation, open development, and “little tech.” [investor-stated · strong] They are financially interested advocacy from an investor in AI infrastructure and applications. The FTC's partnership work, enacted and proposed legislation, safety research, and concentration evidence must remain independent tests. [researcher inference · strong] policy writing · FTC AI partnership report release
A falsifiable account of the edge
Proposed edge. [researcher inference · moderate] In enterprise infrastructure and AI from 2016 through 2026, Casado's plausible repeatable advantage is architecture-to-market translation: technical depth and operator access help him identify a new control point; practitioner and portfolio networks test whether it solves production pain; operating doctrine translates it into product, pricing, buyer, and market-formation milestones; the a16z platform supplies capital, research, recruiting, and governance reach. written-corpus synthesis · spoken-corpus evolution · sourcing forensics
| causal arrow | surviving evidence | boundary |
|---|---|---|
| systems/security formation → architectural search | SANE/Ethane/Nicira and later API, data, cloud, and AI stack maps repeatedly reorganize a system around a control layer. [researcher inference · moderate] technical source map | Technical continuity is visible; causal transfer into selection performance is not audited. |
| operator history → production and founder judgment | Yubico product use, Parsec multi-year observation, Tecton founder-domain history, and portfolio-customer references show concrete information channels. [documented behavior · moderate] sourcing forensics | Channels may be privileged access, circular validation, or team work; efficacy is unproved. |
| market map → sourced company/category | Forty-three authored/coauthored announcements repeatedly tie a company to an architectural discontinuity. [contemporaneous record · strong] announcement corpus | Announcements are selected positive narratives; passes and losses are missing. |
| operating toolkit → milestone-based underwriting | Writings specify task economics, buyer/budget paths, annealing, pricing, and cloud/compute bridges. [investor-stated · strong] written decision playbook | Original IC memos, thresholds, votes, and post-investment causality are absent. |
| selection → outcome | Cursor, Yubico, Parsec, unpriced acquisitions, ordinary private companies, and Tackle provide mixed company outcomes. [contemporaneous record · moderate] outcome forensics | Company outcomes do not supply cost, ownership, proceeds, or a matched denominator. |
Predictions. [researcher inference · moderate] In unseen Casado-linked cases, the favorable thesis predicts: an explicit architectural discontinuity or control point before market consensus; named production users or practitioner references; a founder/team with direct system knowledge; a measurable user-to-budget and unit-economics bridge; milestone changes before repeat capital; and evidence that the rule appeared before the outcome. mental models
Falsifiers. [researcher inference · strong] The thesis would weaken materially if a complete deal/pass ledger showed no better selection or ownership-adjusted outcome than comparable a16z deals; if successful cases lacked pre-decision architecture/customer evidence; if performance concentrated entirely in Cursor after team and vehicle allocation; if negative cases received follow-ons without changed evidence; or if the public rules were applied inconsistently once original memos and votes became available. denominator and coverage · outlier test
People, capital, and role boundaries
| layer | documented people/institutions | what may be credited | what remains unknown |
|---|---|---|---|
| research and invention | Casado, McKeown, Shenker, Stanford/ICSI/LLNL teams, paper coauthors | paper-specific technical contribution and collaborative architecture [contemporaneous record · strong] technical source map | lone-inventor credit, fractional contribution, and economic allocation |
| Nicira/VMware | Casado, McKeown, Shenker, Mullaney, engineering and commercial teams, VMware | founder/operator leadership and company outcomes [contemporaneous record · strong] Nicira/VMware records | board votes, founder ownership, personal proceeds, and individual causal share |
| a16z control and capital | Marc Andreessen and Ben Horowitz appear in the reviewed GP/control chain; Fund V, VII, IX Infrastructure, and X Infrastructure provide dated capital context | legal vehicle and platform context [contemporaneous record · strong] vehicle analysis | Casado's vote, carry, geographic authority, check allocation, reserves, and LP cash flows |
| investment team | Sarah Wang, Matt Bornstein, Jennifer Li, Yoko Li, Guido Appenzeller, Marco Mascorro, Rajko Radovanovic, Justine Moore, Ben Horowitz, and others recur as coauthors | shared public thesis and research [contemporaneous record · strong] people map | sole sourcing, sponsorship, diligence, negotiation, approval, and fractional credit |
| founders, boards, and customers | founders own company claims; as of 2026-08-20, Casado's profile lists 17 current and eight former boards | explicit board service and identified information channels [contemporaneous record · strong] board roster audit | interventions, recusals, conflicts, board votes, follow-on and exit influence |
| LPs and counterparties | 154 Fund VII investors; 223/255 beneficial owners in Fund IX/X snapshots; issuers and acquirers | supply capital or execute company transactions [contemporaneous record · strong] vehicle filings | capital accounts, net returns, seller waterfalls, distributions, and Casado economics |
Skill, access, team, vehicle, era, and luck
- Skill. [researcher inference · moderate] The strongest evidence is repeated architecture/economics decomposition, founder-domain pattern recognition, and an unusually operational public toolkit. It remains an explanatory candidate, not an audited return cause. written philosophy · spoken evolution
- Access. [documented behavior · strong] a16z portfolio companies, internal product use, Stanford/Nicira networks, boards, and the firm's brand create privileged information channels. Access can improve diligence or simply improve deal entry; the record cannot separate them. sourcing forensics
- Team. [contemporaneous record · strong] Joint bylines, firm governance, technical collaborators, founders, and company teams make lone-investor attribution untenable. people map
- Vehicle. [contemporaneous record · strong] Large multi-stage and dedicated Infrastructure pools enable repeat and capital-intensive investing, but can create deployment, valuation, overlap, and liquidity pressure. Person-level authority and economics are not public. vehicle analysis
- Era. [researcher inference · strong] The 2021 financing boom, 2022 exit reset, 2025 LP cash-flow pressure, and 2026 AI concentration change the meaning of rounds, marks, and follow-ons. historical context
- Luck and outliers. [researcher inference · strong] Cursor dominates visible company-event value. The public record cannot show whether that reflects foresight, access, team execution, price/ownership, or an exceptional tail event. outlier test
Failure, change, and unresolved contradiction
The record contains operating setbacks but few documented investor-process changes. Tackle admitted overbuilding; RapidAPI had a major workforce reset; Astranis documented a mission-impacting component failure; Orbit and new.email were sunset or absorbed; several acquisitions have undisclosed terms. [documented behavior · strong] failure matrix
Casado's public doctrine did change in breadth—from infrastructure primitives to cloud economics, market formation, AI stacks, physical AI, and policy—but the change is more visible in topics than in disclosed IC governance. [researcher inference · moderate] No public record shows a general postmortem protocol, reserve rule, recusal framework, portfolio-conflict process, or stop rule added after a named failure. evolution matrix · evidence gaps
The central tensions should remain unresolved rather than rhetorically harmonized:
- falling AI cost can expand demand while capital intensity and supplier concentration still capture value; AI economics synthesis
- open source can distribute and legitimate a category while weakening commercial capture; written contradiction matrix
- product pull can coexist with a missing buyer, weak margin, or services-heavy delivery; written decision playbook
- cloud can commoditize broad infrastructure while creating new specialized control points; cloud contradiction
- non-consensus search can be useful while consensus companies and strong access still dominate outcomes; non-consensus note
- founder empathy can coexist with the need for complementary executives and clear authority; founder/CEO account
- “little tech” policy advocacy can promote entry while also serving the portfolio's economic interests. policy writing · firm disclosures
The strongest case against greatness
Skeptical thesis. [researcher inference · strong] Casado may be an exceptional technical explainer operating inside a premier platform rather than a publicly demonstrated exceptional investor. The deal corpus is selected by the investor and firm; the actual deal/pass/write-off denominator is unavailable; 43 reconstructed cases contain no complete fund cash-flow chain; Cursor dominates visible value; board and byline evidence overstate individual decision rights; private rounds and issuer metrics are not returns; and the favorable record is conditioned on a16z access, capital, recruiting, and brand. denominator · people map · outlier test
The public evidence also cannot show whether architecture maps arrive before deals or are written afterward, whether follow-ons improved prospective fund returns, whether board service changed outcomes, whether open-source/control-point companies outperformed a matched cohort, or whether AI policy positions improve social outcomes. [researcher inference · strong] coverage assessment · evidence gaps
Favorable reply. [researcher inference · moderate] The record does show a coherent, decade-long technical-to-commercial language, multiple ex-ante decision records, a mix of strong/ordinary/adverse cases, and repeatable diagnostics that are more specific than generic founder quality. That is enough to study the method; it is not enough to certify investment greatness. seven decision labs · mental models
Decisive evidence. [researcher inference · strong] Original dated market maps, complete sourced/pass/loss cohorts, IC memos and votes, role allocation, security/price/ownership, reserve decisions, board actions, seller proceeds, and LP cash flows would discriminate skill from access, team, vehicle, era, and luck. attempted routes and missing proof
Bottom line
Casado's most defensible contribution is a way of seeing: treat a technology market as a changing system of control points, then force the architecture through product, user, buyer, pricing, margin, and category tests. [researcher inference · moderate] The method is operationally rich and historically grounded. Its repeatable selection efficacy and economics remain unproved. written philosophy · talk evolution · return boundary
The analyst should therefore borrow the questions, not the reputation: map the layer, identify who gains bargaining power, validate production pull, reconstruct the buyer and budget, normalize per-successful-outcome economics, write the next milestone, and keep team/vehicle/company/return credit separate. reusable mental models
Sourced chronology and learning path
| period | turning point | what to read next |
|---|---|---|
| c. 1976/77–2003 | Arizona education and LLNL systems/security work; exact birth details remain bounded. | LLNL profile, biography and lab passages |
| 2003–2007 | Stanford security/control research, Illuminics, and collaborative SANE/Ethane work. | technical source map |
| 2007–2012 | Nicira forms; research architecture becomes a network-virtualization product and company. | Casado founder account · 2012 decision context |
| 2012–2016 | VMware acquisition/integration and transition to a16z. | VMware 10-K, Note B · a16z appointment |
| 2016–2020 | API, security, data, open-source, and market-creation investing. | writings · early talks |
| 2020–2023 | Cloud economics, pricing, market annealing, and repeat-capital tests; Tackle supplies an adverse case. | written decision playbook · Tackle lab |
| 2023–2026 | AI stack economics, policy advocacy, dedicated Infrastructure pools, and Cursor's outlier outcome. | AI talks · vehicle analysis · Cursor lab |
Recommended path: read the 16-writing synthesis, then the 31-talk chronology, freeze the decision dates in the seven labs, study the operating rules in investment philosophy, and use the procedures and exception ledgers in mental models. The unresolved source and economics routes remain in sources.md.
1. Snapshot and testable edge thesis
| question | evidence-bound answer |
|---|---|
| Who and where | Martin Casado moved from LLNL network-security work and Stanford systems research to co-founding Nicira, operating VMware's networking business, and becoming an a16z general partner in 2016; the firm currently says he leads a16z Infrastructure. Nicira is an operator outcome and is excluded from the venture-selection and investor-return denominator. LLNL, “The accidental entrepreneur,” LLNL and post-9/11 passages · VMware, transition post · a16z profile, opening biography |
| Public investing era and denominator | The bounded record runs from the 2016 SigOpt announcement through 2026-08-20. It contains 68 included public claims across 46 companies: 43 Casado-authored/coauthored announcements plus 25 current/former board claims, less 22 overlaps; 43 companies are sufficiently reconstructed and three board-only lineages remain incomplete. This is a public-attribution universe, not the actual portfolio. a16z author/profile archive · counted denominator |
| Proposed edge | [researcher inference · moderate] Casado's plausible repeatable advantage is translating a technical discontinuity into a market map, then correcting that map with product use, practitioner/customer evidence, buyer-and-budget mechanics, and full-stack economics before using an a16z specialist team, portfolio network, capital, and board access to support the company. written-corpus synthesis · spoken-corpus synthesis |
| Mechanism | [researcher inference · strong] The causal chain proposed by the corpus is: architecture changes → a new workflow or control point appears → research and portfolio/customer loops surface companies → usage challenges the theory → diligence separates insertion from monetization and reversible from irreversible costs → stage-appropriate capital and governance preserve the option. This is a supported operating system, not proven alpha. Software Chasms, Takeaways · 20VC, Takeaways · Past, Present, and Future of Digital Infrastructure, 06:49–34:18 |
| Scope in which it should work | [researcher inference · moderate] The thesis should be strongest in early-stage enterprise, developer, cloud, data, security, and AI infrastructure where architecture, workflow, and economic control points are still unsettled and technical diligence is decision-relevant. It should weaken in domains where regulatory authority, physical production, distribution, brand, or specialized operating knowledge dominates systems insight; Casado's reported robotics/space learning is a boundary test, not proof the edge generalizes. Entering Uncharted AI Territory, 23:13–30:31 and 42:28–58:41 · Astranis lab |
| Evidence for | [researcher inference · moderate] SigOpt, RapidAPI/Kong, Yubico, Tecton, and Cursor preserve a recurring public sequence of architecture thesis, practitioner or product evidence, and later company development. Cursor is an exceptional team-attributed company outcome; Yubico and Parsec add differently structured priced events; Tackle and Astranis add adverse evidence. historical-importance ranking · decision-learning ranking |
| Evidence against or not yet shown | [researcher inference · strong] No public record supplies the actual opportunity/pass/loss denominator, contemporaneous scorecards, partner votes, compatible checks and ownership, reserves, person- or fund-specific proceeds, or LP cash flows. Recent AI announcements are often team-authored. The public record therefore cannot show that the proposed mechanism caused superior selection or net returns. return non-computability proof · people map |
Predictions. [researcher inference · strong] If the edge thesis is true, unseen dated market maps, memos, customer-reference files, IC records, and board materials should show the same questions before outcomes: the unstable technical boundary; user, buyer, and budget; alternative architectures; paid control point; contribution margin; platform/supplier power; reversible versus sunk cost; founder competency gaps; scenario probabilities; and explicit kill/next-check milestones. The pattern should recur in ordinary and failed cases, not only selected winners, and should predict stronger outcomes after controlling for access, team, stage, price, ownership, sector, vehicle, and vintage. deal sourcing forensics · missing-record ledger
Falsifiers. [researcher inference · strong] The thesis weakens materially if the missing cohort shows that (1) sourcing came mainly from generic warm access without a distinctive technical map; (2) usage/customer evidence did not change rankings, prices, or passes; (3) successful cases were partner-led while Casado-attributed ordinary cases did no better than a matched baseline; (4) category boundaries were redrawn after outcomes; (5) follow-ons ignored the published unit-economics and no-new-capital tests; or (6) complete net ex-Cursor cash flows do not outperform appropriate vintage/stage benchmarks. dominant-outlier test
2. Core philosophy
What Casado actually says
- Architecture creates the search space. [investor-stated · strong] Across infrastructure talks and essays, Casado treats changes in abstraction—programmable networks, APIs, microservices, cloud specialization, data stacks, foundation models, and agents—as openings for new control points and companies. Infrastructure… Is Everything, Takeaways · Emerging Architectures, opening through “Blueprints” · Who Owns the Generative AI Platform?, stack map
- Usage can overturn a beautiful theory. [documented behavior · moderate] Casado recounts that Hugging Face usage challenged an internally reasoned view. The account supports a correction loop, but no dated memo, opportunity, terms, or vote proves that the correction produced an investment result. Past, Present, and Future of Digital Infrastructure, 06:49–34:18
- Product adoption and economic ownership are separate gates. [investor-stated · strong] Developer or user love can insert a product, while a buyer, budget, procurement path, commercial control point, margin, and ultimately fund ownership determine whether adoption can become a venture outcome. Growth+Sales, “New buyer, new motion” and Failure Modes #1–#6 · Monopolies vs. Oligopolies in AI, 53:38–57:09
- Uncertainty should be preserved long enough to learn. [investor-stated · strong] The written corpus favors simple early packaging, flexible cloud/API capacity, founder-led market discovery, and deliberate specialization only after workload, buyer, and repetition become clearer. Bottom Up Pricing & Packaging, user-journey framework · Market Annealing, operating stages · The Cost of Cloud, repatriation framework
- Non-consensus is conditional, not ceremonial. [investor-stated · strong] Casado distinguishes product/customer evidence that contradicts current investor belief from ignoring informed objections or the financing audience a company will soon need. His stated Series A and total-exposure framework makes the rule stage- and vehicle-dependent. Is Non-Consensus Investing Overrated?, 00:00:54–00:11:04, 00:28:20–00:32:46, 00:52:10–00:53:06
- Models must be revised when economics change. [investor-stated · strong] The 2020 warning that AI companies can carry compute, data, review, and deployment burdens becomes a 2023 conditional discontinuity and a 2025 margin-bridge argument using routing, tiering, enterprise mix, and product feedback. The durable rule is full-cost measurement, not permanent AI pessimism or optimism. 2020 AI essay, “Gross Margins” and “Scaling AI systems” · 2023 economic case · 2025 margins essay
Synthesis
[researcher inference · strong] Casado's operating system is best understood as disciplined translation: turn a technical change into falsifiable company economics, then allow customer evidence to change the map. Its strength is that it connects architecture, product, go-to-market, cost, and capital rather than stopping at technical novelty. Its weakness is that almost every public example comes from an interested, positively selected record; coherence is not causal proof. written core · spoken evolution · denominator boundary
The method has five gates:
- Map the discontinuity. [researcher inference · strong] Identify which abstraction is moving, what becomes newly possible, and which incumbents or platforms gain or lose bargaining power. written synthesis
- Locate the indispensable workflow. [researcher inference · strong] Test whether the product reaches value, is retained, spreads, and controls a meaningful part of the user's work. Growth+Sales
- Trace user to budget. [researcher inference · strong] Name the economic buyer, paid trigger, procurement/security bridge, pricing metric, and expansion mechanism. Bottom Up Pricing & Packaging
- Underwrite the whole stack. [researcher inference · strong] Include cloud, inference, data, evaluation, support, services, supplier power, migration, and capital needs rather than assuming software economics. 2020 AI essay · AI compute essay
- Match evidence to capital and governance. [researcher inference · moderate] Set the next check, ownership aspiration, leadership needs, conflicts, and board role to the remaining uncertainty. The public doctrine supports this gate; deal-specific rights and effects are mostly unknown. Tecton lab · vehicle boundary
3. Sourcing
How opportunities appear
| sourcing channel | documented evidence | repeatability and risk |
|---|---|---|
| Architecture and market maps | [investor-stated · strong] Casado describes research before live deal cycles, specialist market coverage, and mapping technology layers and submarkets. 20VC, 18:47–19:22 and 33:35–36:17 · Emerging Architectures, research process and blueprints | [researcher inference · moderate] Repeatable as a search process; not proven as a return edge. Dated maps, ranking changes, empty categories, and passes are needed to prevent retrospective relabeling. |
| Portfolio and customer loops | [investor-stated · strong] SigOpt surfaced through a portfolio executive briefing; Tackle through another portfolio company's board meeting; Fivetran through portfolio and public-company encounters; Distributional through SigOpt and 25+ AI-leader interviews. SigOpt, sourcing and closing paragraphs · Tackle, discovery paragraph · Distributional, diligence/relationship paragraphs | [researcher inference · strong] This is a real institutional access advantage and a selection confounder. Record who introduced the company, whether the reference was economically related, and which independent references challenged the thesis. |
| Direct product use | [documented behavior · moderate] a16z/Casado used Braintrust and Yubico; Convex records earlier Casado angel/adviser involvement. Braintrust, lead/user sentence · Yubico, internal-use and diligence paragraphs · Convex issuer Series A | [researcher inference · strong] Product truth improves problem understanding but can create confirmation bias, information asymmetry, and related-role conflicts. Usage is not an ownership, conversion, or return signal. |
| Technical and operating network | [investor-stated · moderate] Casado-authored a16z posts connect Isovalent to the Nicira/Stanford network, ActionIQ to a prior Stanford relationship, and Tecton to experienced Uber ML-infrastructure founders. Isovalent, team passages · ActionIQ, relationship/interview passages · Tecton, Michelangelo and closing paragraphs | [researcher inference · moderate] Domain reputation can increase access and reference quality. A warm network is not independent proof of selection skill; the funnel needs cold-source and declined-opportunity comparators. |
| Coauthored specialist team | [contemporaneous record · strong] Recent infrastructure/AI posts frequently include Matt Bornstein, Sarah Wang, Yoko Li, Guido Appenzeller, Jennifer Li, Justine Moore, Marco Mascorro, or Rajko Radovanovic. Cursor's thesis names four authors. a16z Casado archive, bylines · Cursor announcement, byline | [researcher inference · strong] Broader expertise may make the system more scalable while reducing personal attribution. Each opportunity needs a role ledger rather than equal or solo credit assumptions. |
Sourcing rule. [researcher inference · strong] For every opportunity, record the first-contact source, date, economic relationship, information rights, sponsor, independent disconfirming references, and whether the market map existed before the company appeared. Kill the “sourcing edge” claim if the map was reconstructed after the winner or if related portfolio references supplied all decisive evidence. sourcing forensics · source coverage
4. Picking
Selection and underwriting hierarchy
[researcher inference · strong] The public record supports a hierarchy, not a weighted formula. written decision playbook · spoken decision evidence
- Technical discontinuity and control point. Can the product own an indispensable workflow, interface, standard, data path, or economic bottleneck as architecture shifts? RapidAPI · Isovalent · Cursor
- Customer truth. Can users reach value, return, spread, and produce references without a sales organization manufacturing the signal? Growth+Sales, Failure Modes · Tackle lab
- Buyer and budget. Who owns the budget, which trigger justifies paid conversion, and what procurement, compliance, security, or integration path stands between usage and revenue? Bottom-up pricing, framework
- Whole-product economics. What is contribution margin per successful outcome after inference, human review, implementation, support, failure/retry, cloud, and supplier costs? The New Business of AI, cost taxonomy
- Founder and leadership fit. Does the team have the technical depth, commercial learning speed, recruiting power, and domain competence for the current bottleneck? Casado's own CEO-transition account and robotics-domain admission argue against a universal technical-founder rule. On Fear and Leadership, Takeaways · Entering Uncharted AI Territory, Takeaways
- Financing survival and consensus. Can the company reach the next independently valuable milestone within a no-new-capital scenario, and will the next financing audience understand the evidence? Non-Consensus, Takeaways · Tackle company update, overbuilt/runway paragraphs
Diligence questions
- Market. [researcher inference · strong] What exact submarket is being underwritten; what alternative definitions would reverse the conclusion; and what customer budget is forming or disappearing? architecture-map evidence
- Product. [researcher inference · strong] What independent value moment, retained cohort, within-logo spread, reliability threshold, and switching behavior demonstrate workflow control? Growth+Sales, failure modes
- Economics. [researcher inference · strong] What is quality-adjusted contribution margin; which costs are variable, delayed, subsidized, supplier-set, or hidden in services; and what must improve by the next check? New Business of AI, cost taxonomy
- Moat. [researcher inference · strong] Does the company own scarce data, integration, distribution, brand, marketplace liquidity, open-standard governance, or cost advantage after model/platform parity? Raw data volume and open-source stars are insufficient. Empty Promise of Data Moats, “A practical framework” · Software Chasms, Takeaways
- People. [researcher inference · moderate] Which job must the founder remain uniquely responsible for, what leadership role must change, and what evidence would support that transition? The public corpus supplies self-reported Nicira learning, not a general causal cohort. Bringing in an External CEO, “The technical founder maze”
- Decision. [researcher inference · strong] Name sponsor, coauthors, objector, alternatives, vote/veto, conflicts, vehicle, check, security, ownership, reserves, board right, kill criteria, and next-check milestones. Public bylines and board rosters do not fill these fields. attribution rule
Picking boundary. [researcher inference · insufficient public record] No original IC memos, scoring thresholds, votes, price walk-aways, rejected companies, or matched outcome cohort establishes the actual weighting of these gates or Casado's legal decision rights. denominator boundary · missing-record ledger
5. Deal and portfolio mechanics
Price, ownership, securities, reserves, and concentration
| mechanic | supported public doctrine or behavior | hard boundary |
|---|---|---|
| Price | [investor-stated · strong] Casado says price is market-set while early-stage ownership must be large enough for a median outcome to matter to the fund. Monopolies vs. Oligopolies, 53:38–57:09 | [researcher inference · insufficient public record] No company-specific price ceiling, valuation method, price walk-away, or price-versus-quality trade is disclosed. Round size is not the a16z check. |
| Ownership | [investor-stated · strong] Ownership is treated as a binding early-stage fund constraint; Casado has also described a Series A preference and a roughly $30–40M total-exposure framework in general discussion. Non-Consensus, 00:52:10–00:53:06 | [researcher inference · insufficient public record] No deal supplies verified initial and fully diluted ownership, dilution, preferences, and later proceeds together. A general framework is not a company stake. |
| Security and terms | [researcher inference · insufficient public record] The corpus sometimes identifies a financing stage or company transaction form, but not compatible a16z securities, liquidation preferences, anti-dilution, information, veto, pro rata, or exit rights. comprehensive ledger | Do not infer preferred economics from “led,” a board seat, or total round size. |
| Reserves and follow-ons | [contemporaneous record · strong] SigOpt, Tecton, Coactive, and Ideogram announcements disclose multiple checks; Metronome's issuer post says seed plus Series A. portfolio forensics | [researcher inference · insufficient public record] No reserve policy, ownership-maintenance target, decline case, cross-vehicle transfer, or follow-on counterfactual is public. Repeat capital is informative only when tied to changed evidence. |
| Concentration | [researcher inference · moderate] The public 46-company universe clusters in developer/cloud/API infrastructure (17), data/analytics/ML infrastructure (12), AI models/apps (9), security (6), and hard tech/autonomy (2). category exposure | This is a mutually exclusive research taxonomy, not invested-capital exposure. Checks, marks, reserves, and geography are incompatible or missing. |
| Exits | [researcher inference · strong] The bounded record contains three priced company events, ten unpriced company events affecting eleven lineages, and one asset/R&D-unit event; 31 lineages lack a qualifying primary corporate-outcome record. outcome forensics | Company consideration, an IPO/listing, a private financing mark, tender/secondary, investor proceeds, and LP distributions are different states. No repeatable Casado exit discipline or person/fund realization schedule is public. |
Portfolio rule. [researcher inference · strong] Do not construct a portfolio from an architecture diagram. For each control-point thesis, cap correlated exposure to the same hyperscaler, model vendor, data source, buyer, regulation, or financing regime; map “mortal enemy” conflicts before investment; and re-underwrite every follow-on against the best new opportunity and a no-new-capital case. The need for this rule is strong; evidence that Casado/a16z actually applies it company by company is insufficient. conflict convention
Return proof boundary. [researcher inference · strong] Gross MOIC needs invested cost plus realized and residual value. DPI/TVPI need LP paid-in capital, distributions, and NAV after fees, expenses, and carry. IRR also needs dated calls and distributions. Apart from Yubico's proposed 6.1% combined-company closing snapshot, the record lacks complete ownership histories; it also lacks deal-to-vehicle mapping, securities, dilution paths, tenders, residual NAV, fee/carry allocation, recycling, subscription-line effects, and dated cash flows. Holding Cursor's $60B merger-implied company value constant, both an immaterial high-cost diluted stake never distributed and a material low-cost stake promptly distributed fit the evidence. Therefore no unique MOIC, DPI, TVPI, or IRR is publicly computable. Yubico/ACQ Bure release, “Ownership structure” table · SpaceX 8-K, Item 1.01 · formal non-computability proof
6. Vehicle and incentive fit
| vehicle / institutional fact | strategy-enabling interpretation | constraint and non-attribution boundary |
|---|---|---|
| Fund V, 2016: $1.5B across seed, early, and mid-stage growth a16z, allocation paragraphs | [researcher inference · moderate] Casado entered a broad multi-stage platform with enough scope to back early infrastructure and continue into later rounds. | It was not a disclosed Casado vehicle; no public record assigns him a dedicated budget, vote, carry, or return. |
| Fund VII, 2020: $1.25B sold to 154 investors; Growth Fund II: separately announced $3.2B SEC Form D, Items 3, 5, 12–14 · a16z announcement, separate-team passage | [investor-stated · moderate] Separate early and growth teams can let an early board sponsor support the company while another team evaluates a later round. | Separation is a stated design, not audited proof of independence, conflict resolution, allocation fairness, or early-sponsor control. |
| Fund IX AI Infrastructure, 2024: announced $1.25B; 2026 ADV shows $1.801B GAV, 223 beneficial owners, 0% valued by a non-related person fund announcement · Fund IX Form D · ADV, Schedule D §7.B.(1), fund 805-7322153653 | [researcher inference · moderate] A named pool makes specialist research, ownership, and reserves more institutionally plausible. | GAV is not NAV, proceeds, or LP distributions; related-party valuation is a process caution, not proof of misvaluation. No deal in the package is publicly mapped to this vehicle. |
| Fund X AI Infrastructure, 2026: announced $1.7B; ADV shows $1.624B GAV and 255 beneficial owners announcement, allocation paragraph · Form D · ADV, fund 805-8284876334 | [researcher inference · moderate] Successor capital can extend the strategy across a long AI/infrastructure build cycle. | Final close, deployment, ownership, valuation correctness, reserves, and performance remain unknown. |
Authority, compensation, stakeholders, and continuity
- Practice leadership. [contemporaneous record · strong] The current profile says Casado leads Infrastructure. a16z profile, opening role
- Rounded oral authority claim. [investor-stated · moderate] Casado describes running an approximately $1.2B pool; this is a rounded self-description, not legal-control evidence. Monopolies vs. Oligopolies, 54:51–57:09
- Legal control boundary. [contemporaneous record · strong] Fund VII and IX/X filings and the ADV name Marc Andreessen and Ben Horowitz in the GP/control chain. ADV, Schedules A/B [researcher inference · strong] “Leads” does not prove unilateral allocation, legal vote, veto, ownership, or carry; absence from ownership schedules does not prove Casado lacks an IC vote, delegated budget, informal influence, or economics.
- Fees and carry. [contemporaneous record · strong] Fund IX/X Forms D say a GP or affiliate is entitled to a management fee under governing documents. They do not provide a usable rate, base, duration, offsets, hurdle, or carry split. Any Casado carry or compensation claim is therefore insufficient public record. Fund IX, Item 15 · Fund X, Item 15
- LP incentive. [researcher inference · strong] LPs supply pooled capital and bear vehicle-level fees, valuation, duration, and liquidity risk. Industry cumulative negative LP cash flow of $196.9B from 2022 through 2025-06-30 raises the value of realized-cash evidence; it does not reveal any a16z vehicle's DPI. Q4 2025 Venture Monitor, Executive Summary and liquidity sections
- Founder incentive and conflicts. [investor-stated · strong] Casado describes a “one mortal enemy” convention and acknowledges that pivots can create later conflicts. This may protect founder candor while restricting the fund's future search set. No general recusal, information-barrier, valuation, cross-vehicle allocation, or LPAC exception record is public. Monopolies vs. Oligopolies, 57:09–59:35
- Geography and regulation. [researcher inference · insufficient public record] The public corpus does not establish decision-date domicile, geographic authority, cross-border allocation, or company-specific regulatory restrictions consistently enough to infer a geographic mandate. The ADV and Form Ds establish U.S. adviser/vehicle facts, not deal-level authority. ADV, Item 5.F and Schedules A/B · vehicle boundary
- Duration and liquidity. [researcher inference · moderate] Large successor pools can finance longer company-building and follow-ons, while private marks, cross-vehicle allocations, and weak exit markets can delay LP cash. Without governing documents and cash flows, “patient capital” is an untested label. vehicle analysis · historical context
- Succession and key person. [researcher inference · insufficient public record] The package supplies no key-person clause, succession plan, replacement rule, or test of whether the Infrastructure process persists without Casado, Andreessen, Horowitz, or the current specialist team. formal-authority boundary · missing-record ledger
7. Team attribution and work with founders
People, capital, and influence
| actor | supported role | unsupported upgrade |
|---|---|---|
| Casado | [contemporaneous record · strong] As of 2026-08-20: general partner, Infrastructure lead, named author/coauthor, and 17 current/eight former board claims. a16z profile, biography and board lists | Sole source, sponsor, IC vote, allocation, check, ownership, follow-on, exit vote, proceeds, or causal board impact. |
| Andreessen and Horowitz | [contemporaneous record · strong] Named in GP/control chains reviewed for Funds VII/IX/X and the adviser. Fund IX Form D, Item 3 · ADV, Schedules A/B | Deal-by-deal vote, sponsor, allocation, or operating contribution. |
| Bornstein, Mascorro, Radovanovic | [contemporaneous record · strong] Shared the public Cursor thesis with Casado. Cursor byline | Equal contribution, source, board designation, terms, or individual economics. |
| Li, Appenzeller, Wang, Moore, and other recurring coauthors | [contemporaneous record · strong] Joint research and public selection narratives across newer infrastructure/AI deals. Casado archive, bylines | A byline is not legal decision authority; Casado cannot absorb their credit. |
| Founders and operators | [contemporaneous record · strong] Own product, recruiting, sales, operating, financing, and transaction execution; issuer metrics belong to the issuer unless independently filed. people and role map | A board member or investor does not become the causal author of company execution or outcome. |
| Boards | [contemporaneous record · strong] A board seat proves governance service. Eleven announcements contain board language, three collectively without a named designee. board forensics [researcher inference · moderate] A seat likely supplies company information, but the public record does not disclose its scope. | Attendance, recruiting, intervention, management replacement, follow-on authorization, conflict handling, or exit influence without a specific record. |
| LPs and vehicles | [contemporaneous record · strong] Supply legal capital and bear fund-level economics. vehicle table | Their capital is not Casado's personal capital; company outcomes are not LP distributions. |
Working with founders
- Board posture. [investor-stated · moderate] Casado describes a board member's role as bringing market maps and scarce functions rather than issuing operating commands. That is a stated boundary, not a board-effect study. 20VC, 31:10–33:20
- Leadership fit. [retrospective witness · moderate] His Nicira account of declining the CEO role, regretting an interim choice, and hiring Steve Mullaney supports the principle that the required leader changes with company phase. It lacks board, employee, customer, and Mullaney corroboration and cannot establish the counterfactual. On Fear and Leadership, biography evidence
- Founder-led sales. [retrospective witness · provisional] Casado says founders should remain involved in strategic early sales and category learning. Public evidence does not identify the deals, bookings, counterfactual close rate, or board actions that caused later operating results. On Fear and Leadership, Takeaways · Market Annealing
- Recruiting and intervention. [researcher inference · insufficient public record] The 25 board claims create plausible access to recruitment and intervention, but no company-by-company record establishes who recruited, evaluated, backed, replaced, or constrained management. people map
- Ethical governance. [researcher inference · strong] Product use, customer relationships, board information, competitor mapping, co-investment, valuation, and public advocacy can improve diligence and bias it. Each deal should disclose related roles, permissible information use, recusals, competitor lanes, affected stakeholders, and who owns the decision. No public record proves that a16z's stated conflict conventions achieved those outcomes. allocation and conflict evidence · policy evidence boundary
8. Views on the craft
| craft question | best-supported view | evidence limit |
|---|---|---|
| What is venture investing? | [investor-stated · strong] Specialist research should precede the compressed deal process; the investor maps a market, tests companies against customer evidence, and helps supply scarce functions without running the company. 20VC, 18:47–19:22, 31:10–33:20, and 33:35–36:17 | The account advocates for the scaled a16z model and does not compare its net outcomes with boutiques or generalists. |
| Power law | [investor-stated · strong] Early-stage ownership must allow a meaningful outcome to matter to the fund; the rule is connected to median outcomes and fund size rather than a claim that every winner should absorb unlimited capital. Monopolies vs. Oligopolies, 53:38–57:09 | No Casado/fund ownership or cash-flow ledger tests the doctrine. Cursor dominates visible company-event value but not a provable return series. |
| Fund size and stage | [investor-stated · moderate] Casado favors a barbell of scaled multi-product platforms and focused boutiques, with distinct teams for different risk/stage buckets. 20VC, Takeaways | Large platforms gain research, service, reserve, and signaling capacity while adding fees, allocation, conflict, governance, and succession problems. Comparative performance is absent. |
| Access versus selection | [researcher inference · strong] Portfolio customers, product use, technical reputation, and specialist colleagues create better access and information; only ex-ante scores, passes, cold-source cases, and matched outcomes can show selection rather than access. sourcing forensics | No such complete cohort is public. |
| Governance | [investor-stated · moderate] A board should add maps, recruiting, and scarce resources while respecting founder agency. 20VC note | No minutes, votes, attendance, intervention, conflict, or counterfactual outcome record supports a personal governance edge. |
| Exits | [researcher inference · insufficient public record] No direct corpus establishes a repeatable sell, hold, tender, distribution, or exit-timing discipline. The public deal record documents corporate events, not security-level realization. outcome and realization forensics | A $60B all-stock merger, $800M public transaction, $332.729M cash acquisition, unpriced acquisition, and listing are not economically interchangeable. |
| What makes a great investor? | [researcher inference · moderate] The corpus implies preparedness before the deal, willingness to let usage falsify theory, stage/ownership awareness, explicit opposite scenarios, and role humility outside competence. spoken evolution | Greatness additionally requires attributable, risk-adjusted, net ex-outlier results and responsible stakeholder outcomes; those are not public here. |
Craft maxim. [researcher inference · strong] A good venture narrative says what could be true; a good investment process specifies what would make it false, who owns the decision, what capital is at risk, and which evidence earns the next check. Non-Consensus note, takeaways · uncertainty ledger
9. Signature bets and decision process
These are cross-links to the no-hindsight labs, not outcome-based reconstructions of private IC logic. Every proposed alternative, kill test, and next-check rule is a researcher inference unless the cited decision-date source states it; support is graded claim by claim below.
| case and decision freeze | contemporaneous thesis | decision tension / kill test | later reveal and disciplined lesson |
|---|---|---|---|
| Cursor, 2024-08-22 | [investor-stated · strong] Workflow-first AI coding product, rapid user pull, external-model flexibility; four-person a16z thesis, later Casado board claim. a16z announcement, byline through founders/model-choice | [researcher inference · moderate] Kill on paid-cohort reversion, uneconomic model cost, platform bundling, enterprise security failure, or fork-maintenance burden. | [contemporaneous record · strong] SpaceX's filed all-stock agreement used a $60B implied Cursor equity value and Cursor reported close. Lesson: workflow retention can precede model ownership, but preserve team, supplier, security, ownership, and return boundaries. SpaceX 8-K, Item 1.01 · Cursor, opening two paragraphs |
| Parsec, 2020-12-15 | [investor-stated · strong] Multi-year observation of a demanding consumer product plus enterprise use in media/design/engineering. a16z Parsec, 2017-demo/customer and Series B/board paragraphs | [researcher inference · moderate] Kill if latency advantage, post-pandemic enterprise cohorts, security, egress-adjusted margin, or focus fail. | [contemporaneous record · strong] Unity recorded $332.729M gross cash consideration nine months later. Lesson: long observation is replayable; an early acquisition does not validate the standalone thesis or establish fund proceeds. Unity 10-K, Note 6 |
| Tackle, 2021 B and C | [investor-stated · strong] Portfolio-customer discovery, 200+ customers, low burn, references, then a preemptive follow-on and faster scaling. a16z thesis · issuer Series C | [researcher inference · strong] Re-underwrite software/services mix, expansion, burn multiple, concentration, bookings-to-cash, and no-new-capital runway before preemptive capital. | [documented behavior · strong] The CEO later said the company had overbuilt and separated 75 people; it was later acquired on undisclosed terms. Lesson: customer truth does not excuse financing-cycle overbuild; this is an operating miss and unknown investment outcome. company update |
| Isovalent, 2020-11-10 | [investor-stated · strong] eBPF/Cilium as a cloud-native networking, observability, and security control point with production adoption and a known team. a16z Isovalent | [researcher inference · moderate] Kill on platform absorption, weak commercial attach, failed community neutrality, or kernel-security risk. | [contemporaneous record · strong] Cisco completed an unpriced acquisition. Lesson: community adoption is incomplete without paid conversion, neutrality, and platform bargaining power; strategic fit is not investor-return proof. Cisco completion |
| Yubico, 2018-05-31 | [investor-stated · strong] Internal product use, practitioner references, profitability, limited outside capital, and Casado board seat. a16z Yubico | [researcher inference · moderate] Kill on platform displacement, standards fragmentation, supply-chain constraint, or weak expansion. | [contemporaneous record · strong] The issuer completed an approximately $800M equity-value transaction/listing. Lesson: product truth, board governance, security-level liquidity, and LP distribution are separate gates. Yubico transaction overview |
| Astranis, 2018-03-01 | [investor-stated · strong] Casado disclosed initial context limits, learned a lower-cost GEO architecture, and joined the board. a16z Astranis | [researcher inference · moderate] Gate launch, on-orbit performance, regulation, contracts, supplier redundancy, debt capacity, and capital per deployed capacity. | [documented behavior · strong] Astranis reported a mission-impacting supplier-component failure, a fix, and later financing. Lesson: outside-domain curiosity must become milestones; financing can indicate progress or dependence and is not return. Arcturus anomaly |
| Tecton, 2018 seed / 2020 A | [investor-stated · strong] Experienced production-ML founders, a feature-store problem, customer research, and repeat capital. a16z Tecton | [researcher inference · moderate] Release follow-on only on production deployment, renewal/expansion, commercial attach, time-to-value, and platform neutrality. | [contemporaneous record · strong] Tecton later raised a $100M C and Databricks announced it would join; completion/terms are not established here. Lesson: repeat capital matters only if the changed evidence and independent alternative are recorded. Databricks announcement |
Shared decision-rights boundary. [researcher inference · strong] None of the seven cases discloses the complete alternative set, dissent, IC vote, deal-specific vehicle, check, security, ownership, reserves, board conduct, exit decision, or documented post-outcome process change. Calendar year must not be used to guess the vehicle. seven decision labs · missing-record ledger
10. Mental models and maxims
This is the reconciled navigable inventory for the companion field guide. Seven combined rules survive the evidence bar; eight attractive candidates are explicitly absorbed or excluded in the field guide rather than promoted from slogans, forecasts, or too-few applications. [researcher inference · strong] candidate-model ledger
| model | rule and provenance | key boundary | field-guide link |
|---|---|---|---|
| Map, then falsify with use and relative diligence | [investor-stated · strong] Architecture maps define the search space; retained use, budget, and company-relative evidence must be allowed to overturn it. Architecture essay, opening through “Blueprints” · Digital Infrastructure, 00:29:03–00:31:48 | A map is a sourcing instrument, not proof of company quality, ownership, or return. | Model 1 |
| Trace user → buyer → budget → expansion | [investor-stated · strong] Link independent value and retention to buyer authority, procurement, paid triggers, value-aligned pricing, and economic expansion. Growth+Sales, failure modes · Bottom-up pricing, sections 1–9 | Free use and top-line growth can conceal weak conversion, services burden, or bill shock. | Model 2 |
| Anneal before scaling | [investor-stated · strong] Keep founders and a small generalist team close to product, category, buyer, pricing, and deployment until the variables converge. Market Annealing, operating sequence | Historical ARR/staffing ranges are observations, not universal thresholds; custom work can masquerade as learning. | Model 3 |
| Underwrite the monetizable control point | [researcher inference · strong] Treat open source and technical layers as adoption inputs; test workflow ownership, paid attach, governance, supplier power, switching, and bundling. Selling to Developers, 11:35–24:58 · GenAI platform map | Technical importance, community adoption, or present bottleneck status need not produce durable capture. | Model 4 |
| Buy option value; specialize on stable workload economics | [researcher inference · strong] Rent flexibility while demand is uncertain; specialize or internalize only after workload, migration, utilization, staffing, reliability, supplier, and capital tests. Cost of Cloud, repatriation framework · AI compute, decision framework | “Cloud bad” and “own GPUs” are category errors; decide by workload and scenario. | Model 5 |
| Measure contribution per completed task | [researcher inference · strong] Include failures, retries, inference, evaluation, human review, implementation, support, and capacity allocation in the outcome denominator. New Business of AI, cost taxonomy · Questioning Margins, margin bridge | Falling nominal model cost cannot excuse services drift, low completion quality, or indefinite negative unit economics. | Model 6 |
| Make financing, ownership, and downside part of the thesis | [researcher inference · moderate] Tie every tranche to changed evidence, milestones, ownership, structure, reserves, governance, and a no-new-capital case. Tackle lab · Monopolies vs. Oligopolies, 53:38–57:09 | A round or mark is not progress; without security, stake, dilution, proceeds, and distributions it is not a return. | Model 7 |
11. Evolution and contradictions
Dated evolution
| era | observed emphasis | supported interpretation |
|---|---|---|
| 2016–2018 | Technical discontinuities, APIs, microservices, developer insertion, pricing, founder-led category creation. spoken chronology | [researcher inference · strong] Architecture becomes a company-search map, but user, buyer, price, sales motion, and commercial control are already separate gates. |
| 2019–2021 | Software chasms, data-moat skepticism, AI/cloud costs, integration/services burden, leadership transitions, enterprise selling. written evolution | [researcher inference · strong] The doctrine becomes less architecture-deterministic: irreversible COGS, services, leadership, and distribution can dominate technical elegance. |
| 2022–2023 | Usage corrects theory; market maps and separate stage teams are explicit; GenAI is an economic discontinuity; market annealing formalizes founder-led discovery. 20VC · Digital Infrastructure | [researcher inference · strong] The system becomes more institutional and reflexive, while fund-platform advocacy becomes a larger confounder. |
| 2024 | AI opportunity is paired with correctness, memory/state, domain expertise, tail risk, public research capacity, and application-level regulation. Hard Limits · Uncharted | [researcher inference · strong] Technical enthusiasm broadens into explicit boundary conditions and public policy, but welfare claims remain interested and incomplete. |
| 2025–2026 | Market-first search, ownership, conflict lanes, conventional moat after AI bootstrap, labor/output pricing, capital flywheel, vertical expansion, and alternative market structures. spoken chronology | [researcher inference · strong] Capital, ownership, concentration, and conflicts become more explicit just as AI financing concentration and LP liquidity make those questions most material. |
Contradictions to preserve
| tension | disciplined reconciliation | evidence that would resolve it |
|---|---|---|
| Data moats vs. robotics deployment flywheel | [researcher inference · strong] The flywheel is consistent only if field data are scarce, lawful, representative, hard to simulate, and still create material marginal lift. 2019 data-moat framework · 2025 robotics essay | Learning curves, rights, decay, simulator substitution, and competitor catch-up. |
| AI services burden vs. margin repair | [researcher inference · strong] New capability and routing can improve economics, but the 2020 full-cost taxonomy remains the test. 2020 AI · 2025 margins | Named cohorts through cost, quality, support, conversion, and retention changes. |
| Bottom-up pull vs. founder-led market annealing | [researcher inference · moderate] Annealing discovers the value moment and buyer; product-led growth scales only after the independent value moment exists. Growth+Sales, failure modes · Market Annealing, operating sequence | Failed-category denominator and causal comparison with top-down/services-led entrants. |
| Open source/openness vs. platform concentration | [researcher inference · strong] Open artifacts can reduce one barrier while compute, distribution, contracts, data, and paid control remain concentrated. open-code position · FTC report, §§4–5 | Portability tests, ownership/control terms, supplier alternatives, and value capture over time. |
| Technical-founder preference vs. leadership/domain needs | [researcher inference · strong] Technical depth matters when architecture is the bottleneck; sales, operations, regulation, or domain expertise may dominate later. leadership note, biography evidence · Uncharted, competence boundary | Decision-date role specifications, board decisions, and matched transition outcomes. |
| Non-consensus vs. financing consensus | [researcher inference · strong] Customer truth can be non-consensus; survival still requires sufficient runway and future financing or self-funding. Non-Consensus note, takeaways | Dated objections, cash plan, next-round result, and pass cohort. |
| Scaled specialist platform vs. conflicts | [researcher inference · strong] Specialist teams can improve diligence and stage fit while increasing related-company information, competitor, signaling, valuation, and allocation conflicts. 20VC vehicle/team note · Monopolies conflict evidence | Conflict map, recusals, founder elections, exceptions, LPAC records, and founder experience. |
| AI capital flywheel vs. circular finance | [researcher inference · strong] GPU use and financing show activity, not independent end demand or investor return. Capital Flywheel, contradictions | End-customer cash, supplier credits, strategic recycling, training-adjusted margin, and next-round dependence. |
| Evidence-based policy vs. interested advocacy | [researcher inference · strong] Marginal-risk analysis is useful only with company exposure, lobbying, affected-party evidence, cumulative harms, enforcement, and a position-change rule. Base AI Policy | Company-by-company conflict map, policy incidence, harm thresholds, and documented revisions. |
Evolution boundary. [researcher inference · strong] Public changes in rhetoric do not establish changed IC or board behavior. The only defensible claim is that Casado's expressed framework widened from technical architecture toward customer evidence, full-stack economics, ownership, conflicts, capital intensity, and policy. Process-change claims require dated internal records. written evolution · spoken evolution
12. Failures and limits
Named adverse evidence
| case | what failed or came under stress | response | valid lesson and limit |
|---|---|---|---|
| Tackle | CEO said the company overbuilt in 2021–22 and separated 75 people after a preemptive financing/scaling period. company update | Cost reduction, model broadening, stated long runway, later undisclosed acquisition. Tackle company status | [researcher inference · strong] Re-underwrite every preemptive round against no-new-capital runway. It is an operating miss, not a proven investment loss or write-off. |
| RapidAPI/Rapid | Company-confirmed roughly 50% workforce reduction and CEO change; Nokia later acquired technology assets and an R&D unit rather than a clearly documented whole-company acquisition. TechCrunch, company-confirmation paragraphs · Nokia, acquired-assets paragraph | Major operating reset and bounded asset transfer. | [researcher inference · strong] Do not turn startup narrative, prior mark, or asset sale into success/loss without security-level economics or Casado governance attribution. |
| Orbit | Standalone product sunset within 90 days after Postman acquisition. Postman, acquisition and sunset paragraphs | Product folded into acquirer. | [researcher inference · strong] A product endpoint and a company/fund outcome are different units. |
| Astranis | Mission-impacting satellite anomaly traced to a supplier component. Astranis, anomaly/fix paragraphs | Reproduced failure, design fix, later financing. | [researcher inference · moderate] Hard-tech underwriting needs supplier and in-field milestones; financing does not decide technical or fund success. |
| Resend/new.email | Separate brand and stack created maintenance burden; experiment was sunset. Resend, “Why” paragraphs | Capabilities integrated into parent. | [researcher inference · strong] Preserve cheap product experiments and distinguish product-level failure from parent-company failure. |
| Fly.io | Founder comments document a 2024 workforce adjustment; the disclosed Casado board role came later. founder comments · issuer financing/board post | Later Series D and Casado board appointment. | [researcher inference · strong] Chronology forbids attributing an earlier adverse event to later board governance. |
| Hugging Face | Casado recalls that the firm sometimes over-intellectualized despite strong usage. Colossus, 00:29:03–00:31:48 | Public record does not establish an investable opportunity, allocation, term sheet, or decision. | [researcher inference · moderate] Treat it as a warning to let usage challenge theory, not a priced anti-portfolio return. |
Failure handling protocol
- Name the unit that failed. [researcher inference · strong] Product experiment, operating plan, technical milestone, whole company, security, fund position, and LP outcome are different. failure forensics
- Reopen the decision-date thesis. [researcher inference · strong] Compare original signals, unknowns, alternatives, dissent, price, ownership, and kill criteria with the reveal; do not use later information to rewrite the entry rationale. failure forensics
- Separate response from result. [researcher inference · strong] Cost cuts, management changes, product integration, design fixes, follow-ons, and acquisitions are actions, not proof they restored value. failure forensics
- Record capital and governance decisions. [researcher inference · strong] Identify who authorized bridge, reserve, hiring reset, leadership change, sale, shutdown, or refusal—and what stakeholder obligations remained. failure forensics
- Change the process only when documented. [researcher inference · strong] No public case establishes a Casado/a16z postmortem that changed an IC, reserve, or board rule. The downside re-underwrite and other process changes here are analyst rules, not investor-stated reforms. failure forensics
Failure boundary. [researcher inference · strong] The actual loss, write-off, pass, reserve-refusal, and below-cost-exit denominator is absent. “No adverse event surfaced” for a private company is unknown, not clean. The positive announcement corpus cannot support a personal hit rate, failure rate, or claim of superior learning. failure forensics · denominator boundary
13. Historical operating environment
| regime | decision-relevant context | interpretation boundary |
|---|---|---|
| 2016 platform expansion | a16z announced Fund V at $1.5B across seed, early, and mid-stage growth as Casado joined. Fund V, allocation paragraphs | [researcher inference · moderate] Early infrastructure theses came from a broad institutional platform, not a disclosed standalone Casado pool. |
| 2021 financing/exit boom | NVCA/PitchBook reported $329.6B invested across 17,054 U.S. VC deals and $774.1B of exit value. Q4 2021 Venture Monitor, Executive Summary | [researcher inference · strong] Tackle's B and preemptive C occurred under unusually permissive capital; this reduces uniqueness and makes downside re-underwriting more important, not less. |
| 2022 liquidity reset | Q1 exits fell to $33.6B after three quarters above $192B. NVCA Q1 2022, exit-market paragraph | [researcher inference · strong] Runway, burn, and financing resilience changed sharply; later cuts should not be judged against 2021 conditions alone. |
| 2025 LP pressure | Q4 2025 monitor reported $66.1B U.S. fundraising, a 24.6% close ratio, and $196.9B cumulative negative LP cash flow since 2022 through 2025-06-30. Q4 2025 Venture Monitor, Executive Summary/liquidity | [researcher inference · strong] Private marks and fund announcements are weaker substitutes for DPI when industry liquidity is stressed. This is not a16z performance evidence. |
| 2026 AI concentration | AI represented 88.8% of U.S. VC deal value and 42.5% of deal count in Q1. Q1 2026 Venture Monitor, Executive Summary | [researcher inference · moderate] Cursor and World Labs sit within a historically concentrated funding regime; large rounds and values can reflect company quality, platform competition, and market-wide capital concentration. |
Base-rate boundary. [researcher inference · strong] These industry observations are not matched to the Casado-linked companies by vintage, stage, geography, ownership, risk, or cash-flow timing. They explain alternative causes and changed constraints; they do not establish alpha. Contemporaneous decision analysis must use the data available then, while later statistics remain explicitly retrospective.
14. Modern VC translation — as of 2026-08-20
Each row carries a claim-local two-axis label. “Grounded example” means a current fact in the completed package, not a claim that Casado applied the rule or earned a return.
| major lesson | what transfers now | what does not / changed assumptions | observable applicability signals | likely misuse | grounded current example |
|---|---|---|---|---|---|
| Architecture → workflow → economics [researcher inference · strong] | Map technical change, then require retained workflow, buyer, budget, and paid control. | A 2016 API or 2020 data-stack category map is not today's market; agents and foundation models shift boundaries faster and enable platform bundling. | Retained cohorts, workflow share, buyer-approved expansion, attach, switching, and margin. | Investing in every box on a stack diagram. | Cursor's 2024 thesis emphasized workflow despite external models; its later merger is a company outcome, not proof the whole category map or investor return. a16z Cursor |
| Usage falsifies theory [researcher inference · strong] | Treat surprising retained use as a reason to reopen the model and gather independent evidence. | Virality, free users, prompt volume, or portfolio-company adoption do not establish paid durability. AI products can acquire users through model novelty before retention/moat exists. | Paid retention, repeat task completion, expansion, referenceability, model-parity persistence, and independent references. | Calling any growth spike a moat or a missed winner. | The Hugging Face recollection is a process correction, not an investable-opportunity record. Colossus, 00:29:03–00:31:48 |
| Marginal data value [researcher inference · strong] | Gate “data moat” claims on lawful access, scarcity, representativeness, marginal lift, cost, decay, and replication. | Raw corpus size and historical supervised-learning assumptions do not transfer cleanly amid synthetic data, simulation, foundation priors, and multimodal collection. | Lift by tranche, cost per useful datum, rights, decay, error-segment improvement, and competitor catch-up. | Labeling any proprietary dataset a moat. | The robotics deployment-data flywheel is a source-stated application that still requires the 2019 marginal-value test. robotics essay |
| Contribution margin per successful outcome [researcher inference · strong] | Include attempts, retries, evaluation, human review, support, implementation, and training allocation; permit low early margin only with a dated bridge. | 2020 model prices and a fixed software-margin target do not transfer; routing and outcome pricing can improve or obscure economics. | Quality-adjusted cost, human-review share, support load, routing savings, conversion, retention, and breakeven date. | Assuming model deflation will repair indefinite negative unit economics. | World Labs' issuer-reported $1B financing establishes capital raised, not valuation, margin, realization, or a16z return. World Labs, opening funding paragraph |
| Discovery before scale [researcher inference · strong] | Require convergence in repeated use case, buyer, deployment, and salesperson productivity before scaling functions. | The 2023 essay's ARR/timing ranges and selected examples are not universal gates; AI-assisted building/selling may speed iteration without creating a budget. | Declining customization, stable cycle time, references, rep ramp, payback, and fully loaded quota contribution. | Calling permanent bespoke services “market annealing.” | Tackle's admitted overbuilding after preemptive capital is the strongest grounded warning. Tackle update |
| Flexible infrastructure, then deliberate specialization [researcher inference · strong] | Compare hosted, reserved, specialized, and owned paths per workload and preserve portability until demand is predictable. | “Repatriate” and “own compute” are not general rules; GPU scarcity, supplier contracts, egress, data gravity, depreciation, and reliability differ from 2021. | Utilization, workload unit cost, migration capex, staffing, downtime, discounts, supplier share, and portability tests. | Treating cloud gross margin as free or owned capacity as automatically cheaper. | Astranis' capital and supplier milestone record shows why physical infrastructure needs different gates from software. Astranis anomaly |
| Open source plus paid control [researcher inference · strong] | Measure community production use, governance, commercial attach, neutrality, services burden, and platform capture. | Repository activity does not establish revenue or durable independence; cloud vendors and open-model distributors can absorb value. | Production use, paid conversion, retention, multi-vendor support, contributor concentration, and switching. | Equating open-source popularity with ownership or exit value. | Isovalent's Cisco acquisition is strategically consistent but unpriced and does not reveal fund economics. Cisco completion |
| Two-scenario market underwriting [researcher inference · strong] | Keep fragmentation and concentration cases live with probabilities, thresholds, and dates. | Generic “AI will be an oligopoly” or “models commoditize” claims are too broad; submarket and vertical scope matter. | Share, switching, distillation gap, subsidy, distribution, contract exclusivity, vertical expansion, and loss tolerance. | Preserving both narratives so no outcome can falsify the thesis. | The FTC's AI-partnership report supplies current contract/concentration concerns; it does not decide every submarket. FTC report, §§4–5 |
| Ownership and financing survival [researcher inference · strong] | Model check, security, dilution, pro rata, reserve, next-round need, and fund-return contribution under downside and upside scenarios. | Large rounds, lead labels, private valuations, or GAV do not identify ownership or return; 2026 AI concentration makes price/financing alternatives unusually regime-sensitive. | Fully diluted stake, preference waterfall, cash runway, milestone financing need, reserve opportunity cost, and likely next investor. | Treating a company valuation or financing as a fund mark or LP distribution. | Cursor's $60B implied company equity value and Yubico's listing mechanics are distinct from a16z proceeds. SpaceX 8-K · Yubico transaction |
| Conflict-aware specialist platform [researcher inference · strong] | Map related customer/portfolio/board roles, competitor lanes, information rights, recusals, allocation, valuation, and signaling before first contact. | A “one mortal enemy” convention and separate teams are controls claimed by the investor, not audited outcomes; pivots and model convergence create new conflicts. | Signed conflict map, founder election, independent references, recusal, information barriers, LPAC/board approvals, and logged exceptions. | Treating portfolio access as unbiased diligence or specialist density as personal alpha. | The recent coauthored AI portfolio expands expertise and shared credit while increasing possible category overlap. a16z Casado archive |
| Evidence-based policy and ethics [researcher inference · strong] | Translate claims into affected parties, harm, authority, marginal cause, existing-law gap, enforcement, audit, conflicts, and revision triggers. | “Permissionless,” national competition, and application-level regulation cannot by themselves resolve labor, safety, security, concentration, export, liability, or cumulative harms. | Incident rates, affected-party evidence, concentration, liability, auditability, remedy, refusal thresholds, and disclosed economic interests. | Using technological progress or portfolio interest as a welfare conclusion. | Casado/a16z's AI policy advocacy is an interested record that should be tested alongside regulator evidence. Base AI Policy · FTC release |
15. Comparison with completed peers
Comparator boundary. [researcher inference · strong] Only three completed repository peers are defensible. Trae Stephens is the closest current operator/founder-investor comparison for technical access, conflicts, private marks, and missing returns. Georges Doriot and Reid Dennis supply long-duration vehicle, active-governance, technical-translation, and outlier tests, but are not technology-era or modern private-fund matches. Marc Andreessen, Ben Horowitz, and Peter Thiel are not completed canon peers and are excluded from comparison.
| dimension | Casado | Trae Stephens | Georges Doriot | Reid Dennis | discriminating lesson |
|---|---|---|---|---|---|
| Sourcing | [researcher inference · moderate] Architecture maps, portfolio/customer loops, product use, Stanford/Nicira networks, specialist coauthors. sourcing | [researcher inference · moderate] Government/Palantir/Anduril networks, market maps, portfolio customers; related-role access is especially material. Stephens sourcing | [researcher inference · moderate] Advisers, brokerages, and institutional referrals supplied material ARD flow, with source unknown for much of the record. Hsu and Kenney, p. 594 | [researcher inference · moderate] Personal/trust referrals, broker flow, The Group syndication, and geography. Dennis, printed pp. 13–15/PDF pp. 19–21 | [researcher inference · strong] Network access is an institutional asset and performance confounder. Track source, sponsor, independence, and cold-source cases. |
| Picking / underwriting | [researcher inference · moderate] Technical boundary → workflow → buyer/budget → full-stack economics → financing and leadership. Casado picking | [researcher inference · moderate] Founder/mission, non-consensus, funded authority, reusable product, and technical-commercial complement. Stephens core philosophy | [researcher inference · moderate] People, technical defensibility, commercial practicability, and whole-company development. HBS, Financing New Ideas | [researcher inference · moderate] Technical possibility → present customer → company → security economics, with role-relevant people evidence. Dennis transcript 2, pp. 37–42 | [researcher inference · strong] Casado is strongest on architecture/economics translation; peers warn that technical insight and mission still need whole-company, authority, and security-level economics. |
| Ownership / capital | [researcher inference · strong] General ownership doctrine; one proposed Yubico combined-company stake and lockup; most deal checks, securities, stakes, reserves, cash flows, and distributions absent. Casado deal and portfolio mechanics · Yubico boundary | [researcher inference · strong] Target ownership/terms largely unknown; separate venture/growth pools support concentration. Stephens vehicle boundary | [researcher inference · moderate] ARD mixed equity/debt and staged DEC capital against milestones. Hsu and Kenney, Table 3 · Nicholas, p. 234 | [researcher inference · moderate] Personal/trust, syndicate, corporate, IVA, and IVP vehicles changed capacity, duration, and rights. Dennis, pp. 13–28/PDF pp. 19–34 | [researcher inference · strong] Patient/concentrated capital is not a personality trait; legal form, ownership, authority, duration, fees, and cash flow are causal. |
| Portfolio / outlier | [researcher inference · strong] Cursor dominates visible company-event value; excluding it leaves $1.132729B across Yubico and Parsec, still not investor returns. outlier test | [researcher inference · strong] Anduril dominates visible personal ownership/mark evidence; ex-Anduril elite returns are unproved. Stephens outlier test | [researcher inference · strong] ARD's reported 14.7% CAGR fell to 7.4% without DEC versus cited 12.8% DJIA. Hsu and Kenney, p. 599 | [researcher inference · moderate] Dennis rejected a one-or-two-of-ten philosophy in his remembered Group record; later net vintage evidence is dispersed. Dennis, pp. 27–28/PDF pp. 33–34 | [researcher inference · strong] Test every reputation ex-outlier, by vintage, on ownership and net realized cash—not company values alone. |
| Governance / conflicts | [researcher inference · moderate] Board as map/resource provider; 25 roster claims; one-mortal-enemy convention; intervention and recusal records missing. Casado team and governance | [researcher inference · moderate] Founder/operator/investor/policy overlap makes conflict and independent controls especially material. Stephens governance | [researcher inference · moderate] Demanding mentorship and centralized Boston authority show the boundary between active support and paternal control. Aulikki Olsen, transcript p. 9 | [researcher inference · moderate] Active boards, sponsor roles, plan revision, recusals, and liquidity conflicts vary by case. McMurtry, printed pp. 30–32/PDF pp. 40–42 | [researcher inference · strong] Board access must be matched by role, conflict, independence, dissent, and outcome records; “helpful” is not a causal category. |
| Vehicles / incentives | [researcher inference · strong] Broad Fund V, separate Fund VII/Growth II, named IX/X Infrastructure pools; legal control and Casado compensation/carry unresolved. Casado vehicle analysis | [researcher inference · strong] LP-backed flagship/growth entities with sparse personal authority evidence. Stephens vehicle boundary | [researcher inference · moderate] ARD's public closed-end form broadened access but constrained affiliate transactions and employee incentives. House hearing, pp. 339–340 | [researcher inference · moderate] Vehicle evolution changed capital capacity and succession. Dennis, pp. 35–48/PDF pp. 41–54 | [researcher inference · strong] No form is automatically aligned. Compare authority, duration, fees, liquidity, regulation, conflicts, and succession dimension by dimension. |
| Failure learning | [researcher inference · strong] Tackle is the clearest operating miss; Rapid, Astranis, Orbit, and product-level resets add bounded adverse evidence; no named investment-loss/process-change ledger. Casado failures | [researcher inference · strong] Named operating setbacks and conflicts exist, but loss/writeoff attribution is thin. Stephens failures | [researcher inference · strong] Island Packers and the DEC ex-outlier test challenge company-building romance. Nicholas, p. 232 · Hsu and Kenney, p. 599 | [researcher inference · moderate] Reference was too early, Apple was passed on price, and held-to-zero securities test intuition. Dennis transcript 2, pp. 17–18, 39–40 | [researcher inference · strong] Casado's thinnest evidence is where historical peers teach most: name the error, capital response, governance choice, and process change. |
16. The strongest case against greatness
Skeptical thesis. [researcher inference · provisional] Casado's visible reputation may be the product of exceptional technical and institutional access, a16z's team/platform/capital, a favorable infrastructure-and-AI regime, selected public narratives, and one dominant company event—without enough personal roles, ownership, failures, or net cash flows to establish repeatable personal outperformance. denominator · people map · dominant-outlier test
- One dominant visible company event. [researcher inference · strong] Cursor is the only priced person-linked company outcome above $1B and dwarfs the other disclosed values. Ex-Cursor visible company-event value is $1.132729B across Yubico and Parsec; unpriced events cannot enter the arithmetic. This says nothing about stake, cost, or return. dominant-outlier test
- Access may precede selection. [researcher inference · strong] Stanford/Nicira credibility, a16z's brand, portfolio customers, board rooms, internal product use, and specialist colleagues can supply opportunities and information unavailable to an ordinary investor. No matched cold-source or access-controlled cohort exists. sourcing forensics
- Team and vehicle misattribution. [researcher inference · strong] Cursor has four named thesis authors; newer AI deals are frequently coauthored; Andreessen and Horowitz appear in legal control records; founders and boards do the operating work. A Casado byline or practice-lead title does not prove sole sponsorship, vote, ownership, or outcome causality. people map
- Missing actual denominator. [researcher inference · strong] Forty-six public-attribution companies, 43 reconstructed, and 31 without qualifying primary outcomes do not reveal the actual investments, passes, losses, write-offs, reserve refusals, or private positions. Career-wide coverage and hit rate are not computable. denominator
- No compatible economics. [researcher inference · strong] Company consideration, listing, private financing, operating metrics, investor proceeds, and LP distributions remain distinct. No case supplies cost, security, ownership, dilution, dated proceeds, and distributions together; MOIC, DPI, TVPI, and IRR are unidentified. non-computability proof
- Survivorship and narration. [researcher inference · strong] Investment announcements explain why the firm invested; failed theses, losing categories, passes, diluted winners, and reserve refusals are less publishable. Flexible categories can make later winners look inevitable. official announcement corpus · denominator boundary
- Doctrine may exceed behavior evidence. [researcher inference · strong] The public corpus coherently teaches customer truth, full-stack economics, market maps, and no-new-capital thinking, yet supplies no IC cohort showing that these tests actually controlled decisions, prices, or follow-ons. Tackle's overbuilding is direct counterevidence to easy claims that the doctrine always governed capital. written core · Tackle adverse lab
- Era effects. [researcher inference · strong] Cloud programmability, open source, cheap 2021 capital, 2022 reset, AI capability jumps, platform competition, and 2026 AI funding concentration can create both opportunity and extreme marks independent of personal skill. historical environment
- Conflicts and interested advocacy. [researcher inference · strong] Portfolio/customer/board access, competitor lanes, related valuations, public AI advocacy, and regulation positions can sharpen information and bias diligence or narration. Stated separate teams and the “one mortal enemy” convention are not audited controls. allocation and conflict evidence · policy evidence boundary
- Ordinary and adverse cases remain economically unresolved. [researcher inference · strong] Tackle, Rapid, Orbit, Astranis, Resend, and Fly.io add real operating/technical evidence but not fund losses, recovery, governance causality, or returns. “No adverse event found” for the rest is not success. failure and adverse record
- Generalization beyond core competence is unproved. [researcher inference · moderate] Space, robotics, physical AI, policy, and model-market claims may benefit from systems thinking but require domain, manufacturing, regulatory, safety, and affected-party evidence not supplied by infrastructure experience alone. Astranis competence-boundary lab · Uncharted note
- Succession and transferability are unknown. [researcher inference · strong] The proposed edge may depend on Casado, a16z's current coauthors, the portfolio network, and Andreessen/Horowitz-controlled structures. No public key-person or post-Casado continuity test exists. vehicle and authority boundary · current institutional identity
What would decide between favorable and skeptical theses
[researcher inference · strong] The favorable case strengthens if signed role ledgers, dated maps/memos, pass logs, votes, independent references, company-by-company conflict controls, board records, reserve decisions, and full fund cash flows repeatedly connect Casado-specific actions to superior ordinary-case and net ex-Cursor outcomes after controlling for access, coauthors, stage, price, ownership, sector, vehicle, and vintage. The skeptical case strengthens if those records show mainly warm-network sourcing, generic post hoc categories, partner-heavy decision/execution, customer references without independence, doctrine-inconsistent follow-ons, weak ex-outlier net economics, or stakeholder/conflict costs hidden by private marks. uncertainty and retrieval ledger
17. Analyst study guide, glossary, and go deeper
Recommended reading path
- Formation and attribution: read the sourced chronology and learning path, then the Stanford/LLNL/Nicira sources before using operator experience as an investing cause.
- Core operating system: read Software Chasms, 20VC — Venture Model, and Past, Present, and Future of Digital Infrastructure.
- Written economics: read Data Moats, The New Business of AI, Growth+Sales, Cost of Cloud, and Market Annealing.
- Replay decisions without hindsight: do Tackle first as the failure/miss lab, then Cursor, Astranis, and the remaining four labs. Answer invest/pass, kill criteria, ownership/terms, and next-check milestones before reading each reveal.
- Audit economics and credit: read the denominator, vehicle boundary, people map, and outcome forensics.
- Stress the modern doctrine: read Entering Uncharted AI Territory, Non-Consensus, Monopolies vs. Oligopolies, and Capital Flywheel alongside the skeptical case above.
- Compare, do not canonize: compare only the completed Trae Stephens, Georges Doriot, and Reid Dennis packages.
Investor-specific glossary
| term | disciplined meaning |
|---|---|
| Technical discontinuity | A change in architecture, capability, cost, or abstraction that may create a company search; not itself a market or moat. |
| Control point | A workflow, interface, standard, integration, data path, distribution channel, or economic bottleneck that can support bargaining power; must be tested against platform capture. |
| Customer truth | Retained use and referenceable evidence capable of challenging a theory; does not substitute for buyer, budget, margin, or return. |
| Market map | A dated hypothesis about layers, dependencies, companies, and scenarios; not a portfolio, denominator, or proof of foresight. |
| Market annealing | Founder-led iteration that seeks convergence in product, use case, buyer, category, and sales motion before specialization; not permission for permanent services work. |
| Growth+sales | Linked self-serve/user-adoption and enterprise-conversion funnels; neither funnel proves the other. |
| Contribution margin per successful outcome | Revenue less the costs of attempts, failures, inference, evaluation, human review, implementation, support, and other delivery work. |
| Mortal enemy | Casado's stated convention allowing a founder to identify one rival the investor will not back; not a complete conflict policy. |
| Infrastructure pool | A legally distinct a16z vehicle publicly branded for AI Infrastructure; title does not map any specific deal, vote, stake, or return to Casado. |
| Company consideration | Gross transaction value paid for the company or securities; not automatically seller proceeds to a16z. |
| Listing / IPO venue | A public-trading event or venue; not proof a holder sold or an LP received cash. |
| Private mark | A financing-derived or other private-company valuation reference; not cash realization. |
| Tender / secondary | A holder-level liquidity transaction; absent from the reviewed primary Casado record and distinct from primary financing. |
| Investor proceeds | Cash or securities actually allocated to an investor after transaction mechanics; not publicly established here. |
| LP distribution / DPI | Cash or securities distributed by the fund to LPs, divided by paid-in capital for DPI; not inferable from company outcomes or GAV. |
Reusable sourcing and diligence checklist
Provenance. [researcher inference · strong] These fields consolidate the supported sourcing, picking, model, role, and vehicle boundaries; they are analyst procedures, not a recovered a16z checklist. sourcing · picking · mental models · people and vehicle map
- Source — [researcher inference · strong]: first-contact person/date; map predating company; related portfolio/customer/board/angel role; permissible information; independent references; cold-source comparison.
- Problem/workflow — [researcher inference · strong]: user, job, frequency, severity, incumbent, independent value moment, retention, spread, switching, failure tolerance.
- Buyer/budget — [researcher inference · strong]: buyer, budget source, paid trigger, security/procurement/integration path, pricing metric, expansion, churn after repricing.
- Architecture/moat — [researcher inference · strong]: control point, alternatives, open/proprietary boundary, data marginal lift/rights, platform capture, supplier dependence, portability.
- Economics — [researcher inference · strong]: quality-adjusted contribution margin, services, review, inference/training, cloud/egress, CAC/payback, working capital, depreciation, no-new-capital runway.
- Team — [researcher inference · strong]: technical, commercial, operational, regulatory, and domain evidence; missing competency; recruiting; succession; role-change trigger.
- Decision — [researcher inference · strong]: sponsor, coauthors, objector, alternatives, vote/veto, prediction log, kill date, stakeholder impacts, conflicts/recusal.
- Terms — [researcher inference · strong]: vehicle, check, security, price, fully diluted ownership, preferences, dilution, pro rata, reserves, board/observer rights, information, downside, exit rights.
Reusable IC, follow-on, governance, and exit checklist
Provenance. [researcher inference · strong] These steps consolidate the seven no-hindsight labs, vehicle/return boundaries, failure handling, and model exception ledgers; they are analyst procedures, not documented Casado process changes. decision labs · vehicle boundary · return proof · model exception ledgers
- Freeze the information set. [researcher inference · strong] Record what was known, unknown, believed, disputed, and available at the decision date; do not import later market or company facts.
- Write both cases. [researcher inference · strong] Probability-weight at least two market structures and the strongest pass; name evidence and dates that invalidate each.
- State invest/pass and kill tests. [researcher inference · strong] Include product, buyer, economics, technical, financing, regulatory, conflict, and ethical thresholds.
- Price the security, not the story. [researcher inference · strong] Model ownership, dilution, preferences, reserves, follow-ons, downside, tender, and distribution; a company valuation is not fund return.
- Release the next check on changed evidence. [researcher inference · strong] Compare against the best new opportunity, same-date market conditions, and a no-new-capital plan; do not use sunk cost or current mark as proof.
- Govern legibly. [researcher inference · strong] Predefine board purpose, independent voice, recruiting/leadership triggers, information barriers, conflicts, recusal, incident escalation, stakeholder remedy, key-person continuity, and stop conditions.
- Separate exit layers. [researcher inference · strong] Company agreement/consideration → holder allocation → lockup/escrow/tax → sale or in-kind security → fund proceeds → LP distribution. Do not collapse the chain.
- Run the postmortem. [researcher inference · strong] Distinguish thesis error, execution, timing, financing, governance, and luck; record capital response, stakeholder cost, counterfactual, and actual process change.
Best sources, ranked for learning value
- Software Chasms, full transcript note — densest bridge from technical architecture to product, open source, delivery, integration, and enterprise sales.
- 20VC — Venture Model, full note — strongest direct account of maps, debate, stage/vehicle design, board boundary, and scaled-platform advocacy.
- Past, Present, and Future of Digital Infrastructure, full note — clearest usage-over-theory correction and workload/cloud/open-standard analysis.
- The New Business of AI — foundational full-cost taxonomy and the best baseline for testing later AI optimism.
- Market Annealing — strongest founder-led discovery/scale mechanism, with historical-threshold caveats.
- Is Non-Consensus Investing Overrated?, direct interview — most falsifiable account of informed objections, financing consensus, stage, ownership, and promised cohort testing.
- Monopolies vs. Oligopolies in AI, direct podcast — strongest current ownership, conflict, vehicle, and alternative-market-structure source.
- Complete deal forensics — the essential denominator, vehicle/role/economics boundaries, seven no-hindsight labs, outlier test, and adverse record.
- VMware 2012 Form 10-K, Note B — best demonstration that announced value, net consideration, post-combination compensation, and personal proceeds are different measures; Nicira remains operator history only.
- A16Z ADV, Schedules A/B and Schedule D §7.B.(1) — strongest public control/vehicle/GAV/valuation-process boundary; not performance evidence.
Highest-value unresolved evidence
| missing record | why it matters | conclusion until recovered |
|---|---|---|
| Signed deal/role ledger, IC charters, memos, votes, and objections | Separates source, sponsor, selection, legal authority, team credit, and changed belief. | Bylines and board rosters remain bounded public participation/service evidence. |
| Actual investments, passes, losses, write-offs, and reserve refusals | Tests selection, survivorship, false positives/negatives, and ex-outlier repeatability. | Career-wide coverage, hit rate, and alpha remain not computable. |
| Deal-to-vehicle mapping, checks, securities, cap tables, dilution, preferences, tenders, NAV, proceeds, and LP cash flows | Determines ownership, realization, MOIC, DPI/TVPI, IRR, and vehicle incentives. | Company outcomes and marks cannot become investor or LP returns. |
| Conflict, recusal, information-barrier, valuation, allocation, and LPAC records | Tests the specialist-platform and “mortal enemy” governance claims. | Stated controls remain unaudited; absence is not misconduct proof. |
| Board minutes, consents, recruiting, follow-on, leadership, incident, and exit records | Tests whether board access produced beneficial governance and who acted. | Board service proves no specific intervention or causal outcome. |
| Dated market-map archive and prediction log | Distinguishes prepared search from post hoc category expansion. | Coherent public doctrine remains a plausible mechanism, not demonstrated foresight. |
| Independent company cohorts for data lift, AI unit economics, cloud crossover, open-source conversion, and market annealing | Tests whether published operating frameworks predict outcomes beyond selected examples. | Frameworks remain useful diagnostics with unproved comparative efficacy. |
| Company-by-company AI/policy exposure, lobbying, affected-party evidence, harms, thresholds, and revision rules | Tests ethical incidence and interested advocacy. | Public policy views are investor-stated positions, not established welfare results. |
Bottom line. [researcher inference · moderate] The record supports a teachable, falsifiable operating system: map technical discontinuities, let customer use correct theory, translate workflow into buyer/budget and full-stack economics, preserve option value, and match capital/governance to the remaining uncertainty. It does not yet support the stronger claim that Casado personally generated superior net returns. The decisive evidence is not another selected-winner story; it is the dated role/pass/loss/ownership/cash-flow/conflict record, tested on ordinary cases and ex-Cursor. written core · spoken evolution · return boundary
Pareto 80/20 — what drove the record
[researcher inference · strong] No literal 80/20 split, personal hit rate, DPI, TVPI, MOIC, IRR, or Casado-generated dollar total can be calculated from the public record. The searchable record combines 43 investor-authored or coauthored deal announcements, 25 current/former board claims, four Casado-announcement repeat-financing histories plus one issuer-reported seed-and-Series-A history, company acquisition consideration, an all-stock public-company transaction, private financing marks, and issuer-reported operating metrics. It does not disclose compatible a16z cost, security, ownership, dilution, seller allocation, dated proceeds, or LP distributions. The rankings below therefore answer three different questions and never add those measures together. a16z author page, current/former board paragraphs · a16z portfolio disclosure, disclosure below portfolio table · searched denominator
Economic contribution — observable company-outcome rank, not investor returns
Ranking rule. [researcher inference · strong] The eligible universe is the sufficiently reconstructed person-linked venture ledger, excluding Nicira and Illuminics because they are founder/operator outcomes. No eligible case supplies verified Casado- or a16z-specific proceeds, cost, ownership, dilution, and dated cash flows together. The ranking therefore uses a reproducible proxy: (1) a completed, priced company transaction outranks an unpriced exit or private financing; (2) cash consideration is identified separately from stock consideration but does not automatically outrank a much larger priced all-stock transaction; (3) stronger public Casado/team attribution breaks ties inside an outcome class; and (4) capital raised, revenue, and an unclosed mark are not substitutes for company value. This ranks observable company evidence, not MOIC, DPI, IRR, or dollar contribution. ledger · vehicle boundary
| rank | case | observable proxy and basis | attribution / supported mechanism | return boundary | case |
|---|---|---|---|---|---|
| 1 | Cursor | SpaceX's SEC-filed agreement assigned Cursor a $60 billion implied equity value in an all-stock merger, and Cursor said the acquisition closed on 2026-08-14. SpaceX 8-K, Item 1.01 and “Merger Consideration” · Cursor, opening two paragraphs | The 2024 a16z Series A thesis has four named authors—Matt Bornstein, Marco Mascorro, Rajko Radovanovic, and Casado—and the current profile, board paragraph places Casado on the board. [contemporaneous record · strong] for team attribution and company transaction; [researcher inference · provisional] for any individual contribution | a16z's check, security, ownership at close, stock received, lockup, transfer, tax, distribution, and Casado economics are unknown. | lab |
| 2 | Yubico | The issuer announced an approximately $800 million equity-value public transaction through ACQ Bure and later traded publicly; the measure is transaction equity value, not cash proceeds. Yubico/ACQ Bure release, transaction overview and consideration lines | Casado wrote the 2018 investment thesis, described diligence, and joined the board; the company named a16z as a principal investor in the public transaction. [contemporaneous record · strong] | The proposal anticipated a16z holding 6.1% of the combined company and a 180-day lockup. It does not disclose entry cost, the full dilution path, actual closing shares, later sales, fund allocation, distributions, or returns. Public listing is not realization. Yubico/ACQ Bure release, “Ownership structure” table and 180-day lockup paragraph | lab |
| 3 | Parsec | Unity's 2021 Form 10-K records $332.729 million gross cash consideration and separately records $23.402 million of acquired cash as an acquired asset. Unity 10-K, Note 6 “Acquisitions,” Parsec table | Casado said a16z led the 2020 Series B and that he joined the board after tracking the company from 2017. [investor-stated · strong] for sponsorship; [contemporaneous record · strong] for company consideration | Gross acquisition consideration is not a16z proceeds; the preference stack, seller allocation, escrow, taxes, distributions, and holding-period cash flows are unknown. | lab |
Dominant-outlier test. [researcher inference · strong] Cursor is the only publicly priced person-linked company outcome above $1 billion in the searched record and is roughly two orders of magnitude larger than the two other disclosed transaction measures. Removing Cursor leaves $1.132729 billion of disclosed visible company-event value: Yubico is 70.626% and Parsec 29.374%, so both are required to cross 80%. Unpriced acquisitions, the Fivetran–dbt all-stock merger with undisclosed exchange economics, and private companies cannot enter that arithmetic. This is a share of visible company-event value only, not a return series or a calculated share of Casado's or a16z's economic contribution. Yubico transaction · Parsec consideration
Historical importance — separate from economics
Ranking rule. [researcher inference · strong] Eligible cases require a direct Casado-authored/coauthored investment record. Rank lexicographically by (1) evidence that the case introduced a new public practice or doctrine, (2) persistence of that practice in later cases, (3) later institutional/company significance, and (4) stronger Casado-specific attribution; earlier direct records break remaining ties. This is a chronology-and-doctrine rank, not economics.
| rank / case | historical basis | attribution / support | supported mechanism | caveat / link |
|---|---|---|---|---|
| 1. SigOpt | First surviving Casado-authored venture announcement after he joined a16z; it explicitly describes an existing seed position and a decision to deepen the investment. SigOpt, opening and closing paragraphs | [investor-stated · strong] for the published follow-on rationale | [researcher inference · moderate] operator-to-investor transition using portfolio-customer access and vertical breadth | original seed sponsor, check, vehicle, ownership, and approval remain unknown; ledger |
| 2. RapidAPI / Kong | The 2016 RapidAPI and 2017 Mashape/Kong announcements are the earliest public expression of the API-as-business-interface and microservices theses that recur across Casado's later portfolio. RapidAPI, full body and closing · Mashape, full body and closing | [investor-stated · strong] for contemporaneous thesis; team/approval mechanics unknown | [researcher inference · moderate] technical architecture becomes a sourcing map for infrastructure control points | consistency is not proof of selection efficacy; ledger |
| 3. Yubico | Earliest public case connecting Casado's security history, product use inside a16z, formal diligence, and a board seat; later became a public-company outcome. Yubico, diligence and closing board paragraphs | [investor-stated · strong] for decision rationale; [contemporaneous record · strong] for transaction | [researcher inference · moderate] direct product truth plus referenceable security practice | no security-level realization record; lab |
| 4. Tecton | Clearest early public repeat-capital sequence: a16z invested at seed in 2018 and again at Series A after tracking production demand. Tecton, final two paragraphs | [investor-stated · strong] for the repeat-financing account | [researcher inference · moderate] release reserves after customer engagement confirms infrastructure pull | check, ownership, internal gates, and later acquisition economics are unknown; lab |
| 5. Cursor | Largest visible company outcome and strongest current test of the thesis that workflow ownership can matter even when models are supplied by others. 2024 deal thesis | [contemporaneous record · strong] for four-person thesis and transaction | [researcher inference · moderate] product workflow and retention can precede proprietary-model investment | later scale cannot be leaked into the 2024 decision; lab |
Decision-learning value — ranked for replayability
Ranking rule. [researcher inference · strong] Eligible cases require both a decision-date record and a later reveal. Rank lexicographically by (1) clarity and severity of the decision tension—including documented error before extreme positive-outcome or technical-adverse cases—(2) strength of the later reveal, (3) transferability across deals, and (4) attribution quality. Thus Tackle's admitted operating error ranks ahead of Cursor's extreme outcome, which ranks ahead of Astranis's narrower technical failure-and-response record. This ranks learning value, not success.
| rank / case | replayable tension | support | decision rule to test | case |
|---|---|---|---|---|
| 1. Tackle | Strong customer pull, low burn, a preemptive 2021 follow-on, later admitted overbuilding, 75 separations, and an acquisition with undisclosed terms. Series B thesis · company update, opening and “overbuilt” paragraphs | [contemporaneous record · strong] for operating evidence; investment economics unknown | re-underwrite cohort quality, services content, burn multiple, and no-new-capital runway at every preemptive round | lab |
| 2. Cursor | Extraordinary company outcome alongside dependence on external models, compute, platform distribution, and a four-person a16z team. a16z Series A · SpaceX agreement | [contemporaneous record · strong] | distinguish workflow retention from model-supplier risk; preserve team and ownership attribution | lab |
| 3. Astranis | Casado explicitly began outside his expertise, learned space/regulatory constraints, and backed a capital-intensive hardware company. Astranis, “When we first heard” and closing board paragraphs | [investor-stated · strong] for learning path; later operational causality unproved | convert an unfamiliar-sector pitch into falsifiable technical, regulatory, launch, debt, and customer milestones | lab |
| 4. Parsec | A consumer/community product became enterprise infrastructure, then sold nine months after the Series B. Parsec thesis · Unity 10-K | [investor-stated · strong] for the thesis; [contemporaneous record · strong] for acquisition | use multi-year product observation, but do not let an early sale validate the full standalone thesis | lab |
| 5. Yubico | a16z used the product before investing, found broad professional adoption in diligence, then navigated a public transaction rather than a simple cash exit. Yubico deal post · transaction release, overview and consideration lines | [contemporaneous record · strong] | treat product truth, governance, security-level liquidity, and public-market realization as separate gates | lab |
Evidence boundary and searched denominator
Unit of analysis. [researcher inference · strong] The reproducible unit is a public deal-linked claim record, then a company lineage. The search found 70 candidate claim records across 48 candidate companies. Two company candidates were excluded from the venture denominator: Nicira is Casado's founder/operator outcome, and Illuminics lacks a reconstructed a16z investment record. The included universe is therefore 68 deal-linked public claims across 46 companies: 43 Casado-authored or coauthored a16z investment announcements plus 25 current/former board claims, with 22 companies appearing in both sets and three board-only companies. Multiple financings disclosed inside one announcement remain subfacts rather than new denominator units. a16z author archive, announcement index · a16z profile, current and former board paragraphs
| audit state | claim records / companies | rule and boundary |
|---|---|---|
| publicly claimed / known | 68 / 46 | At least one official Casado/coauthor investment announcement or current/former a16z profile-board claim exists. This is a public-attribution universe, not a complete career portfolio. |
| candidate records searched | 70 / 48 | Every live Casado-byline announcement, every live profile-board name, and two founder/operator candidates were enumerated through 2026-08-20. A search record is not proof of a personal deal. |
| candidate records researched | 70 / 48 | Each candidate was opened against the best available announcement, profile, issuer/acquirer, regulatory, and adverse route; research depth varies with public access. |
| sufficiently reconstructed companies | 43 | Public person/team link, entry or material financing context, a decision-date thesis or role boundary, and a current outcome/status boundary are all recoverable. |
| included but incomplete companies | 3 | A public board claim exists, but no claim-local Casado investment announcement or adequate entry/thesis reconstruction was located: DeepMap, Netlify, and Pindrop. |
| excluded candidates | 2 | Nicira and Illuminics are retained in the historical/operator record but excluded from venture selection and return denominators. |
| unresolved | 3 included records, plus economics for all 46 | The three board-only lineages remain reconstruction gaps; no company supplies the complete person/fund cash-flow evidence needed for a return calculation. |
| public-record reconstruction coverage | 43 / 46 = 93.5% | This measures the included public-attribution universe only. Career-wide coverage fraction: not computable because the actual-deal, pass, write-off, and private-position denominator is not public. |
Attribution rule. [researcher inference · strong] A Casado byline proves public participation in the published thesis; a joint byline remains team work. A board roster proves board service, not sourcing, sponsorship, diligence, IC approval, check allocation, ownership, follow-on authority, exit approval, or proceeds. Company and SEC records can establish financing or transaction facts but not silently fill person-level roles. Where the record is silent, the ledger says unknown; it never upgrades a firm lead to a Casado lead. a16z portfolio disclosure, disclosure below portfolio table · current author/profile record
Economics rule. [researcher inference · strong] A financing amount is capital raised; a post-money valuation is a private-company mark; revenue and annualized revenue are operating measures; acquisition consideration is company-level transaction value; a listing is a liquidity venue. None is a16z or Casado proceeds. Publicly observed person- or fund-specific proceeds are unknown, not zero. The record cannot support a hit rate because public claims are selective, losses and passes are underdisclosed, follow-on depth varies, and the underlying actual-deal denominator is unavailable.
Historical and base-rate context
| regime | period evidence | implication for the Casado-linked record |
|---|---|---|
| Platform expansion | Casado joined a16z as Fund V was announced at $1.5 billion across seed, early, and mid-stage growth. a16z, “Fund V,” announcement/allocation paragraphs | [researcher inference · moderate] Early public deal theses should be read as products of a broad multi-stage platform, not a disclosed standalone Casado vehicle. |
| 2021 financing and exit boom | NVCA/PitchBook reported $329.6 billion invested across 17,054 U.S. VC deals and $774.1 billion of exit value. 2021 Venture Monitor, Executive Summary | [researcher inference · strong] Tackle's Series B and preemptive Series C occurred in an unusually permissive regime. The context reduces uniqueness but does not excuse company-level overbuilding. |
| 2022 liquidity reset | NVCA's first-quarter update said quarterly exits had nearly halted at $33.6 billion after three consecutive quarters above $192 billion. NVCA Q1 2022 update, exit-market paragraph | [researcher inference · strong] Runway, burn, and down-round resilience became more important; later operating cuts cannot be judged against 2021 financing conditions alone. |
| 2025 LP pressure | The Q4 2025 Venture Monitor reported $66.1 billion of U.S. VC fundraising, a 24.6% fund-close ratio, and cumulative negative LP cash flow of $196.9 billion since 2022 through 2025-06-30. Q4 2025 Venture Monitor, Executive Summary and liquidity sections | [researcher inference · strong] Large fund announcements amid weak industry liquidity make DPI and realized-cash evidence more important, not less. |
| 2026 AI concentration | AI accounted for 88.8% of U.S. VC deal value and 42.5% of deal count in Q1. Q1 2026 Venture Monitor, Executive Summary | [researcher inference · moderate] Cursor and World Labs sit inside an exceptional capital-concentration regime; large rounds and prices can reflect both company quality and market-wide concentration. |
Base-rate boundary. [researcher inference · strong] These statistics contextualize selection, price, fundraising, exits, and liquidity. They are not matched by vintage, stage, geography, ownership, risk, or cash-flow timing and cannot establish alpha. The public Casado record is positively selected: investor announcements explain why a16z invested, while passes, write-offs, reserve refusals, and ordinary private outcomes are far less likely to be published.
Vehicle economics, incentives, and decision rights
| date | vehicle / structure | public fact | supported conclusion | unsupported conclusion |
|---|---|---|---|---|
| 2016-06-10 | Andreessen Horowitz Fund V | a16z announced $1.5B across seed, early, and mid-stage growth. Fund V, allocation paragraphs | [contemporaneous record · strong] Casado entered a broad multi-stage platform. | Dedicated Casado capital, legal authority, carry, or returns. |
| 2020-11-20 | Fund VII | a16z announced $1.3B; Form D records exactly $1.25B sold to 154 investors and names Marc Andreessen and Ben Horowitz in the GP chain. a16z Fund VII/Growth II, announcement and team paragraphs · SEC Form D, Items 3, 5, 12–14 | [contemporaneous record · strong] Early-stage capital and a distinct legal vehicle are observable. | Portfolio returns, Casado's vote, or a person-specific allocation. |
| 2020-11-20 | Growth Fund II | a16z separately announced $3.2B and distinct early/growth teams. announcement, separate-team passage | [investor-stated · strong] The platform describes stage specialization and separation. | That separation eliminated conflicts or gave the early sponsor control of follow-ons. |
| 2024-04-16 | Fund IX — AI Infrastructure | a16z announced $1.25B. The initial Form D names the vehicle and managing chain; the 2026 ADV reports $1.801B gross assets, 223 beneficial owners, and 0% of assets valued by a non-related person. a16z “New Funds, New Era,” allocation paragraph · Fund IX Form D, Items 1, 3, 13, 15 · A16Z ADV, Item 5.F and Schedule D §7.B.(1), fund ID 805-7322153653 | [contemporaneous record · strong] A legally distinct named pool and later regulatory snapshot exist. | Commitments paid in, NAV, independent value, DPI, performance, or Casado's economics. |
| 2026-01-09 | Fund X — AI Infrastructure | a16z announced $1.7B; the ADV reports $1.624B gross assets and 255 beneficial owners. a16z “Why Did We Raise $15B?”, allocation paragraph · Fund X Form D, Items 1, 3, 13, 15 · A16Z ADV, Schedule D §7.B.(1), fund ID 805-8284876334 | [contemporaneous record · strong] A successor Infrastructure pool is observable. | Final closes, deployed capital, valuation correctness, ownership, or return. |
Formal authority and compensation boundary
- Practice leadership. [contemporaneous record · strong] The firm profile says Casado leads a16z Infrastructure; in a direct interview he describes running an approximately $1.2B Infrastructure fund, consistent with a rounded account of the announced $1.25B pool. a16z profile, opening biography · “Monopolies vs. Oligopolies in AI,” 53:38–57:09
- Legal control record. [contemporaneous record · strong] Fund VII and Funds IX/X filings name Andreessen and Horowitz in the GP managing chain. The current ADV identifies A16Z Holdings as a 75%+ direct owner/control person and Andreessen and Horowitz as indirect owners/control persons; Casado was not located in those ownership/control schedules. A16Z ADV, Schedules A/B
- Inference boundary. [researcher inference · strong] Absence from those schedules does not prove Casado lacks an IC vote, delegated budget, informal influence, or economics. Conversely, “leads” or “runs” does not prove a legal vote, veto, unilateral allocation, carry, or ownership. Partnership agreements, IC charters and minutes, delegation schedules, and compensation records would be needed.
- Fee evidence. [contemporaneous record · strong] Fund IX/X Forms D state that a GP or affiliate is entitled to a management fee under governing documents. They do not supply a usable rate, base, duration, offsets, hurdle, or carried-interest split. Fund IX, Item 15 · Fund X, Item 15
- Valuation and RAUM caution. [contemporaneous record · strong] The ADV reports 0% of Fund IX/X assets valued by a non-related person and warns that multiplexer RAUM double-counts uncontributed commitments and component-fund assets. That supports a valuation-process caution, not an allegation of misvaluation. GAV and RAUM are not NAV, proceeds, or LP distributions. A16Z ADV, Schedule D §7.B.(1) and Miscellaneous explanation
Allocation, ownership, and conflict incentives
- Ownership incentive. [investor-stated · strong] Casado says early-stage ownership is binding because a median outcome must return a meaningful share of a fund; price is market-set, while large markets and growth-stage checks alter the constraint. This is a general framework, not evidence of a company-specific stake. “Monopolies vs. Oligopolies in AI,” 53:38–57:09
- Conflict convention. [investor-stated · strong] He describes a “one mortal enemy” convention under which a founder may identify one rival the investor will not back and acknowledges that pivots can create later conflicts. same interview, 57:09–59:35
- Stage-team separation. [investor-stated · moderate] Casado says seed, venture, and growth teams are separated partly so founders can speak candidly to a board sponsor while another group assesses a later round. 20VC, 14:15–15:33
- Conflict implication. [researcher inference · moderate] Mapping a market and reserving a competitor lane can focus diligence and support a portfolio company, but it can also reduce later learning and optionality. The record does not disclose a general recusal, information-barrier, valuation, or cross-vehicle allocation protocol.
Why returns remain non-computable
[researcher inference · strong] Gross MOIC requires realized proceeds, residual value, and invested cost. Net TVPI/DPI require LP distributions, ending NAV, and paid-in capital after fees, expenses, and carry. IRR additionally requires every dated capital call and distribution. Apart from Yubico's proposed 6.1% combined-company closing snapshot, the public record lacks complete ownership histories; it also lacks company-to-fund mapping, initial and follow-on cost, security and preference terms, reserves, tender or secondary sales, residual NAV, fee/carry allocation, recycling, subscription-line effects, and dated LP cash flows. Yubico/ACQ Bure release, “Ownership structure” table
Hold every observed fact constant, including Cursor's $60B merger-implied value. One compatible scenario gives a relevant fund an immaterial diluted stake bought at high cost and never distributed; another gives it a material low-cost stake whose SpaceX shares are promptly distributed. Both fit the public record, yet their MOIC, DPI, and IRR differ by orders of magnitude. Therefore the record does not identify a unique answer. Report not publicly computable, never zero and never a point estimate.
People, capital, and influence map
| node | public role / evidence | capital or influence edge | hard boundary |
|---|---|---|---|
| Martin Casado | a16z general partner; Infrastructure lead; named author/coauthor; current/former director. profile, biography and board lists | Technical thesis, published selection rationale, customer/portfolio access, and company governance where a board role is explicit. | No inferred sole source, sponsor, IC vote, allocation, ownership, follow-on, exit vote, or proceeds. |
| Marc Andreessen and Ben Horowitz | GP-chain managing persons in the reviewed Form D filings; indirect control persons in ADV. Fund IX Form D, Item 3 · ADV, Schedules A/B | Formal firm/GP control record. | Does not reveal deal-by-deal votes or allocation. |
| Matt Bornstein, Marco Mascorro, Rajko Radovanovic | Coauthors with Casado on Cursor. announcement byline | Shared public underwriting thesis. | Source, terms, board delegation, and fractional credit unknown. |
| Yoko Li, Guido Appenzeller, Jennifer Li, Justine Moore, Sarah Wang | Recurring coauthors across newer infrastructure/AI investments. Casado archive, bylines | Team research, selection, and published thesis. | Joint authorship is not proof that Casado led or that contribution was equal. |
| Company founders and executives | Product, operating, and financing claim owners. | Customer evidence, metrics, hiring, product and transaction execution. | Issuer-reported metrics remain unaudited unless filed; company value is not investor return. |
| Company boards | Casado is listed on 17 current and eight former boards in the live profile. profile, board paragraphs | Governance, information access, recruiting, follow-on and exit discussion may occur. | A board seat alone proves none of those specific actions, nor fund authority or economics. |
| Follow-on syndicates and acquirers | Named company financing participants; SpaceX, Unity, Cisco, Databricks, Stripe, Postman, and others as transaction counterparties. | Price discovery, capital, strategic distribution, and transaction execution. | Holder allocations, seller waterfalls, taxes, and a16z distributions remain generally unknown; Yubico is the bounded exception with an anticipated 6.1% combined-company stake and 180-day lockup. Yubico/ACQ Bure release, “Ownership structure” table and lockup paragraph |
| LPs and fund vehicles | 154 Fund VII investors; 223/255 beneficial owners in Fund IX/X ADV snapshots. | Supply pooled capital and bear vehicle-level fees, valuations, and liquidity; any carried-interest economics depend on governing documents not established here. | Names, capital accounts, cash flows, net returns, and Casado-specific economics are not public. |
Comprehensive public person-linked deal ledger
Key. [researcher inference · strong] A is an official Casado-authored/coauthored a16z deal announcement; BC/BF is a current/former board claim in the live a16z profile, current/former board paragraphs; R/I is sufficiently reconstructed/incomplete. Roles are S source, P public sponsor/narrator, D diligence, Ap formal approval, B board, F follow-on, and X exit; ? means unknown. An R record reconstructs the public claim—not the security, economics, or return. Unless stated otherwise, the capital entity is an a16z-managed vehicle whose exact fund, check, ownership, reserves, fee, and carry are unknown.
| # | company; record | entry / thesis | public role chain | status and economics boundary | support |
|---|---|---|---|---|---|
| 1 | ActionIQ; A; R | 2017-10-23; stage unknown; customer-data platform. | S=prior Stanford relationship; P=Casado; D=dozen enterprise interviews; Ap/B/F/X?. | Acquired by Uniphore; terms/economics unknown. | [investor-stated · strong] relationship, diligence, closing · [documented behavior · strong] Uniphore acquisition overview |
| 2 | Ambient.ai; A+BC; R | 2022-01-19; stage unknown; camera-based security AI. | P=Casado; D=demo/customer evidence; B=current; S/Ap/F/X?. | Private/operating; economics unknown. | [investor-stated · strong] thesis and closing |
| 3 | Anyscale; A; R | 2019-12-17; A led; Ray/distributed computing. | P=Casado+Horowitz; collective board seat unassigned; other roles?. | Private/operating; economics unknown. | [investor-stated · strong] byline and A/board closing |
| 4 | Astranis; A+BC; R | 2018-03-01; stage unknown; MicroGEO broadband. | P=Casado; D=technical/founder learning; B=Casado/current; other roles?. | Private; financing/backlog are not value. | [investor-stated · strong] GEO thesis and board |
| 5 | Braintrust; A+BC; R | 2024-10-08; A led; LLM evaluation/observability. | P=Casado; D=product use; B=current; other roles?. | Private/operating. | [investor-stated · strong] lead/user sentence |
| 6 | Coactive; A+BC; R | 2023-03-21; seed+A; queryable visual data. | P=Casado+Bornstein; B=current; F=seed+A; other roles?. | Private; check/vehicle unknown. | [investor-stated · strong] byline and seed/A closing |
| 7 | Convex; A+BC; R | 2022-04-27; $26M A led; reactive backend. | S/D=prior angel/adviser; P=Casado; B=current; F=personal then firm. | Personal/firm channels distinct; economics unknown. | [documented behavior · strong] A/board closing · company angel/adviser account |
| 8 | Cursor; A+BC; R | 2024-08-22; A; AI-native editor. | P=Bornstein+Mascorro+Radovanovic+Casado; B=current; other roles?. | $60B merger-implied value; proceeds unknown. | [contemporaneous record · strong] four-person byline and A · SpaceX 8-K, Item 1.01 “Merger Consideration” |
| 9 | dbt/Fishtown; A+BF; R | 2020-04-22; stage unknown; analytics engineering. | P=Casado; B=former; other roles?. | Fivetran all-stock merger; economics unknown. | [investor-stated · strong] identity/thesis and closing · [documented behavior · strong] issuer merger completion |
| 10 | DeepMap.ai; BF; I | Date/stage/vehicle/thesis unknown. | B=former; all investment roles?. | NVIDIA acquisition; terms unknown. | [documented behavior · strong] profile former-board sentence · NVIDIA post, “DeepMap Delivers Mapping Advances” |
| 11 | Deeptune; A; R | 2026-03-19; A led; RL environments. | P=Mascorro+Casado; D=lab work stated; other roles?. | Acquisition reported secondarily; terms/primary confirmation absent. | [investor-stated · strong] byline and A · [contemporaneous record · provisional] Fortune report, opening and undisclosed-terms paragraphs |
| 12 | Distributional; A+BC; R | 2023-12-14; seed; AI testing. | S=SigOpt relationship; P=Casado+Bornstein; D=25+ AI leaders; B=current. | Private/operating. | [investor-stated · strong] diligence and closing |
| 13 | Eclypsium; A; R | 2018-12-04; seed led; firmware security. | P=Casado; D=technical/market evidence; other roles?. | Private/operating. | [investor-stated · strong] thesis and seed closing |
| 14 | EngFlow; A; R | 2021-10-12; seed led; remote builds. | P=Casado; D=customer evidence; other roles?. | Private/operating. | [investor-stated · strong] customer and seed paragraphs |
| 15 | Fivetran; A+BC; R | 2019-09-24; $44M B led; automated connectors. | S/D=portfolio/customer encounters; P=Casado; B=current. | Completed all-stock dbt merger; exchange economics unknown. | [investor-stated · strong] references and B/board closing · [documented behavior · strong] issuer merger completion |
| 16 | Fly.io; A; R | 2022-07-28; B led; edge compute. | P=Casado; 2026 issuer says board; other roles?. | 2024 cuts preceded disclosed board role; private. | [investor-stated · strong] thesis and B closing · [contemporaneous record · moderate] founder comments · issuer 2026 financing/board paragraph |
| 17 | Ideogram; A+BC; R | seed+A; 2024-02-28 A led; generative media. | P=Casado+Jennifer Li; B=current; F=seed+A. | Private/operating. | [investor-stated · strong] byline and seed/A closing |
| 18 | Imply; A+BC; R | 2018-03-13; A led; real-time OLAP. | P=Casado; D=technical/community evidence; B=current. | Private/operating. | [investor-stated · strong] thesis and A closing |
| 19 | Instabase; A; R | first invested ~2017; workflow automation. | S/D=founder/product/customer work; P=Casado; other roles?. | Continued partnership; second check not proven. | [investor-stated · strong] first-invested/diligence paragraphs |
| 20 | Isovalent; A+BF; R | 2020-11-10; stage unknown; eBPF/Cilium. | S=domain relationship; P=Casado; D=technical/open-source; B=former. | Cisco acquisition; price unknown. | [investor-stated · strong] eBPF/Cilium and closing · [documented behavior · strong] Cisco completion, opening paragraphs |
| 21 | Kong/Mashape; A+BC; R | 2017-03-23; stage unknown; API gateway. | S/D=prior use/community; P=Casado; B=current. | Private; one renamed lineage. | [investor-stated · strong] identity/use and closing |
| 22 | Material Security; A+BC; R | 2020-06-30; stage unknown; email security. | P=Casado; B=current; other roles?. | Private/operating. | [investor-stated · strong] threat thesis and partnership |
| 23 | Metronome; A+BF; R | 2022-02-01; $30M A led; usage billing. | S/D=portfolio references; P=Casado; B=former; company says seed+A. | Stripe acquisition; terms unknown. | [investor-stated · strong] references and A/board · [documented behavior · strong] Stripe completion, opening paragraphs |
| 24 | MotherDuck; A; R | 2022-11-15; A led; DuckDB analytics. | P=Casado+Jennifer Li; other roles?. | Private; financing is not value. | [investor-stated · strong] byline and A closing |
| 25 | Netlify; BC; I | Date/stage/vehicle/thesis unknown. | B=current; all investment roles?. | Private/operating. | [documented behavior · strong] profile current-board sentence |
| 26 | Orbit; A+BF; R | 2020-12-02; stage unknown; community system of record. | P=Casado; B=former; other roles?. | Postman acquisition; product sunset; terms unknown. | [investor-stated · strong] thesis and investment · [documented behavior · strong] Postman acquisition and sunset paragraphs |
| 27 | Parsec; A+BF; R | 2020-12-15; B led; remote graphics. | S/D=2017 demo/multi-year watch; P=Casado; B=former. | Unity $332.729M gross company cash consideration; proceeds unknown. | [investor-stated · strong] demo/customers and B/board · [contemporaneous record · strong] Unity 10-K, Note 6 Parsec table |
| 28 | Phota Labs; A; R | 2025-09-16; $5.6M seed led; photo generation. | P=Yoko Li+Casado+Jennifer Li; other roles?. | Private; too recent for outcome. | [investor-stated · strong] byline and seed |
| 29 | Pindrop; BC; I | Date/stage/vehicle/thesis unknown. | B=current; all investment roles?. | Private/operating. | [documented behavior · strong] profile current-board sentence |
| 30 | Preset; A+BC; R | 2019-10-10; stage unknown; Superset commercialization. | P=Casado; D=open-source/founder evidence; B=current. | Private; later financing is not proof of down round. | [investor-stated · strong] Superset and closing · [contemporaneous record · strong] issuer Series C opening |
| 31 | QuiverAI; A; R | 2026-02-25; seed led; editable SVG model. | P=Yoko Li+Appenzeller+Casado; D=research evidence. | Private; too recent for outcome. | [investor-stated · strong] byline and seed |
| 32 | RapidAPI/Rapid; A; R | 2016-11-21; stage unknown; API marketplace. | P=Casado; D=developer/app/call traction; other roles?. | Nokia acquired assets/R&D, not clearly whole company; terms unknown. | [investor-stated · strong] thesis and closing · [documented behavior · strong] Nokia release, opening and acquired-assets paragraph |
| 33 | Rasa; A; R | 2020-06-23; B led; open-source conversational AI. | P=Casado; historical board statement; other roles?. | Private; present board tenure unknown. | [investor-stated · strong] thesis and B/board |
| 34 | Relace; A; R | 2025-10-08; $23M A led; coding-agent layer. | P=Yoko Li+Appenzeller+Casado; board seat unassigned. | Private; too recent for outcome. | [investor-stated · strong] byline and A/board |
| 35 | Resend; A; R | 2024-12-04; A led; developer email. | P=Yoko Li+Jennifer Li+Casado; board seat unassigned. | Parent private; new.email sunset is not company failure. | [investor-stated · strong] byline and A/board |
| 36 | Runta; A; R | 2026-07-16; seed led; agent compute. | S/D=decade founder relationship; P=Casado+Yoko Li+Appenzeller. | Private; too recent for outcome. | [investor-stated · strong] relationship and seed |
| 37 | Shizuku AI; A; R | 2026-02-09; seed led; AI companions. | P=Justine Moore+Mascorro+Casado; D=founder evidence. | Private; too recent for outcome. | [investor-stated · strong] byline and seed |
| 38 | SigOpt; A; R | existing seed; 2016-08-24 deepening; optimization. | S=portfolio EBC; P=Casado; D=founder/customers; F=deepen; seed sponsor unknown. | Intel acquisition; terms unknown. | [investor-stated · strong] seed and deepening · [documented behavior · strong] Intel employee post, opening acquired-status paragraph |
| 39 | Tabular; A+BF; R | 2021-08-31; A led; Iceberg/open tables. | P=Casado; D=technical/open source; B=former. | Databricks announced an acquisition; price unknown. | [investor-stated · strong] thesis and A · [documented behavior · strong] transaction announcement, opening |
| 40 | Tackle; A; R | 2021-03-09; B led; cloud-marketplace GTM. | S=portfolio board meeting; P=Casado; D=references; B=historical. | Overbuilt/cut 75; later acquired by AppDirect; terms unknown. | [investor-stated · strong] source, traction, B/board · [documented behavior · strong] overbuilding/update · issuer status, acquired by AppDirect |
| 41 | Tecton; A; R | 2018 seed+2020 A; feature store. | S/D=Michelangelo/ML teams; P=Casado; F=seed+A. | Databricks announced Tecton would join; completion and terms unknown. | [investor-stated · strong] thesis and seed/A closing · [documented behavior · strong] Databricks announcement, summary/opening |
| 42 | Tigris; A; R | 2024-02-20; stage unknown; S3 storage. | P=Casado; other roles?. | Private/operating. | [investor-stated · strong] storage thesis and closing |
| 43 | Truffle Security; A+BC; R | 2021-12-08; A led; secret discovery. | P=Casado; D=project/founder evidence; B=current. | Private/operating. | [investor-stated · strong] thesis and A closing |
| 44 | WaveForms; A; R | 2024-12-09; stage unknown; audio models. | P=Justine Moore+Mascorro+Casado; D=founder evidence. | Meta acquisition reported; no primary confirmation/terms. | [investor-stated · strong] byline and investment · [contemporaneous record · provisional] TechCrunch report, opening and terms paragraphs |
| 45 | World Labs; A+BC; R | 2024-09-13; stage unknown; world models. | S=company approached a16z; P=Casado+Sarah Wang; B=current. | Company later announced $1B of new financing; it is not valuation or a16z return. | [investor-stated · strong] byline and partnership · [contemporaneous record · strong] company funding announcement, opening paragraph |
| 46 | Yubico; A+BF; R | 2018-05-31; stage unknown; hardware authentication. | P=Casado; D=product/security references; B=former. | ~$800M merger/listing value; realization unknown. | [investor-stated · strong] diligence and board · [contemporaneous record · strong] transaction overview and consideration · first trading day |
Ledger arithmetic and observable patterns
- Stage partition. [contemporaneous record · strong] The 43 announcement records divide into 7 seed-only, 12 Series-A-only, 5 Series-B-only, 4 explicit multi-check/multi-round, and 15 stage-unknown pages: 7 + 12 + 5 + 4 + 15 = 43.
- Follow-ons. [contemporaneous record · strong] SigOpt, Tecton, Coactive, and Ideogram explicitly disclose multiple checks; Metronome's company post separately says seed+A. No complete reserve schedule exists.
- Governance. [contemporaneous record · strong] The profile supplies 25 board claims: 17 current and eight former. Eleven announcements contain board-seat language, but three coauthored posts leave the designee unassigned. Historical Rasa/Tackle seats are absent from today's roster, so present tenure is unknown.
- Outcomes. [researcher inference · strong] Fourteen distinct primary-record corporate events affect 15 of 46 lineages: three priced transactions/listing events, ten unpriced acquisitions/combinations (the Fivetran–dbt event affects two lineages), and one bounded Rapid asset/R&D-unit sale. The remaining 31 lineages have no qualifying primary corporate-outcome record in this sweep; that is a search status, not a solvency or return conclusion.
Ex-ante decision labs
Each lab freezes the public information set before revealing the later record. The proposed kill tests and modern decision rules are researcher inference unless a source expressly states them; they are not reconstructed IC memos. Shared record limit. [researcher inference · strong] None of the seven cases discloses a complete alternative set, formal dissent, IC vote, deal-specific vehicle allocation, or post-outcome board/IC process change. Every alternative below is therefore a researcher-generated decision branch, and silence means unknown. The 2018 cases sit inside the public Fund V platform context; the 2020 cases precede or closely bracket the Fund VII announcement; the 2021 Tackle decisions must not import later full-year boom statistics; and the 2024 Cursor freeze follows the Fund IX Infrastructure announcement but is not publicly mapped to that vehicle. Fund V, allocation paragraphs · Fund VII, opening/team paragraphs · Fund IX, allocation paragraph
Decision lab 1: Cursor — workflow pull, model dependence, and an outlier exit
Freeze: 2024-08-22. [contemporaneous record · strong] The four-person a16z Series A post described an AI-native VS Code fork, thousands of paying developers, adoption at named sophisticated companies, and users who rarely switched back. Cursor did not train a foundation model. Known: product, paid pull, technical team, familiar editor base. Unknown: ARR, retention cohorts, inference-adjusted margin, enterprise security, customer concentration, model-supplier power, terms, ownership, and individual a16z roles. Fund IX Infrastructure had been announced four months earlier, but no public source maps this deal to that vehicle. a16z Cursor, byline through founders/model-choice paragraphs · Fund IX announcement, allocation paragraph
Underwriting reconstruction. [researcher inference · moderate] The thesis was that high-frequency workflow ownership and context could matter more than owning the model. Kill if paid cohorts reverted, model cost made usage uneconomic, vendors or GitHub bundled the interface, security blocked enterprise use, or the fork became a maintenance trap. Next-check evidence: retained paid seats, expansion, cost per useful task, latency, security conversion, and supplier concentration. No public terms justify a specific ownership answer.
Alternatives, dissent, and governance. [researcher inference · insufficient public record] Plausible branches were to wait for retention/margin proof, back a model-owning competitor, build a thinner extension thesis, or pass. No public record identifies the alternatives actually considered, dissent, the board designee's intervention, a stop decision, or a changed a16z process after the outcome.
- Would you invest then?
- What would kill the deal?
- What ownership/terms fit the risk?
- What evidence unlocks the next check?
Reveal. [contemporaneous record · strong] Cursor later reported $900M C/$9.9B and $2.3B D/$29.3B with rapidly rising annualized revenue; those are issuer-reported financings/metrics. SpaceX's filed agreement used a $60B implied Cursor equity value in an all-stock merger, and Cursor said it joined SpaceX on 2026-08-14. Cursor C, opening financing/ARR paragraphs · Cursor D, opening financing/revenue paragraphs · SpaceX 8-K, Item 1.01
Interpretation. [researcher inference · moderate] Later model/infrastructure investment is consistent with responding to external-model dependence, but the causal motivation and any a16z intervention are not established. The company event is directionally exceptional as visible company-value evidence; a16z cost, stake, stock received, lockup, tax, distribution, MOIC, and IRR remain unknown.
Lesson/counterfactual. [researcher inference · moderate] Workflow pull and retention were the strongest early signals. A standalone Cursor might have compounded or faced platform commoditization; the merger prevents the public record from resolving that counterfactual. Preserve the four-person team attribution.
Decision lab 2: Parsec — consumer product to enterprise infrastructure
Freeze: 2020-12-15. [investor-stated · strong] Casado said he saw a demo in 2017, tracked Parsec for years, and observed a loyal gaming community plus enterprise customers in media, architecture, engineering, and game development. The $25M Series B was led by a16z during pandemic remote work, 25 days after the public Fund VII announcement; no source maps the check to that vehicle. Known: difficult low-latency technology, product community, named enterprise demand. Unknown: post-pandemic durability, margin/egress cost, security, concentration, sales cycle, terms, ownership, and competitive bundling. Parsec, 2017-demo/customer and Series B/board paragraphs · issuer Series B, opening financing paragraph · Fund VII announcement, opening
Underwriting reconstruction. [researcher inference · moderate] A demanding consumer use case could prove a horizontal enterprise primitive. Kill if latency advantage disappeared, enterprise cohorts did not expand after reopening, cloud cost blocked margin, security failed, or consumer/enterprise focus fractured. Next evidence: renewals, expansion, reliability, security, mix shift, and egress-adjusted contribution margin.
Alternatives, dissent, and governance. [researcher inference · insufficient public record] Plausible branches were to wait for post-pandemic enterprise cohorts, back a native enterprise remote-work product, license the technology, or pass. No public record identifies actual alternatives, dissent, acquisition-vote conduct, stop rules, or a process change after the sale.
- Would you invest then?
- What would kill the deal?
- What ownership/terms fit the risk?
- What evidence unlocks the next check?
Reveal. [contemporaneous record · strong] Unity acquired Parsec about nine months later. Its 10-K records $332.729M gross cash consideration, separately records $23.402M of acquired cash as an asset, and says the transaction was not material enough for separate pro-forma results. The company cash price is not fund proceeds; entry valuation, allocation, preference stack, dilution, waterfall, escrow, and distributions are absent. Unity 10-K, Note 6 Parsec table
Lesson/counterfactual. [researcher inference · moderate] Multi-year observation before investment is more replayable than the quick sale. Independence could have created more value or exposed pandemic normalization and bundling risk; the early acquisition cannot validate the whole standalone thesis.
Decision lab 3: Tackle — customer truth, preemptive capital, and overbuilding
Freeze 1: 2021-03-09; freeze 2: 2021-12. [investor-stated · strong] Casado found Tackle because another portfolio company used it, cited 200+ customers, references, growth and low burn, led the $35M B, and joined the board. The issuer later called its C preemptive and planned more aggressive scaling. Known: customer pull, marketplace volume, founder references. Unknown: NRR, software/services mix, take rate, gross margin, cloud concentration, policy risk, implementation labor, CAC payback, terms, ownership, board votes, and downside runway. The decision-date posts contain no matched market-financing baseline; later full-year 2021 boom statistics are context for review, not facts available at either decision. Tackle thesis, discovery/traction and B/board paragraphs · Series B, financing/metrics paragraphs · Series C, preemptive/scaling paragraphs
Underwriting reconstruction. [researcher inference · strong] Kill if marketplace volume failed to create durable software revenue, services were required to deploy, a hyperscaler internalized the layer, payback stretched, or costs assumed an unsupported curve. Before the C, re-underwrite cohort expansion, services content, bookings-to-cash, burn multiple, concentration, and a no-new-capital scenario.
Alternatives, dissent, and governance. [researcher inference · insufficient public record] Plausible branches were a smaller or delayed C, milestone-gated hiring, services partnerships, or no follow-on. No public record identifies actual dissent, Casado's board vote, reserve decision, stop rule, or an investor process change after the operating reset.
- Would you invest then?
- What would kill the deal?
- What ownership/terms fit the risk?
- What evidence unlocks the next check?
Reveal. [contemporaneous record · strong] In 2023 CEO John Jahnke said 75 employees would leave, the company had “overbuilt in 2021 and 2022,” and it was broadening toward services/sales-led work while retaining more than five years of runway. AppDirect announced an acquisition agreement in 2025, and Tackle's current company page identifies it as acquired; terms were not disclosed. Tackle update, overbuilt/runway/model paragraphs · AppDirect, opening transaction paragraphs · Tackle company page, acquired status
Interpretation. [researcher inference · strong] The public warning pattern is a preemptive round followed by headcount acceleration and admitted overbuilding; the company response was cost reduction, runway extension, and model change. The rule that every preemptive round needs a downside re-underwrite is researcher-generated. No documented investor process change, Casado board action, reserve vote, ownership, or acquisition waterfall was found.
Lesson/counterfactual. [researcher inference · strong] Tackle is a documented operating miss and unknown investment outcome—not a zero or proven loss. Slower hiring or a smaller C might have preserved focus and ownership, or ceded a forming category. Every preemptive round needs a downside re-underwrite.
Decision lab 4: Isovalent — open-source control point and an unpriced exit
Freeze: 2020-11-10. [investor-stated · strong] The thesis was that eBPF/Cilium could become a cloud-native networking, observability, and security layer, supported by open-source production adoption and a team Casado knew through Nicira/Stanford. Terms, stage, board role, conversion metrics, concentration, and governance were unknown. Isovalent, eBPF/Cilium adoption/team passages
Underwriting reconstruction. [researcher inference · moderate] Kill if cloud vendors absorbed the control point, community neutrality failed, kernel security risk emerged, or open source did not convert into paid expansion. Next evidence: production adoption, commercial attach, retention, and ecosystem neutrality.
Alternatives, dissent, and governance. [researcher inference · insufficient public record] Plausible branches were to wait for paid conversion, back a closed commercial layer, rely on a cloud-vendor implementation, or pass. The public record does not identify actual alternatives, dissent, board designation, acquisition-vote conduct, a stop rule, or an investor process change.
- Would you invest then?
- What would kill the deal?
- What ownership/terms fit the risk?
- What evidence unlocks the next check?
Reveal. [contemporaneous record · strong] Cisco completed the acquisition in 2024 without disclosing consideration. Cisco completion, opening paragraphs
Interpretation. [researcher inference · moderate] The strategic fit is consistent with the technical thesis but does not validate it causally or identify a16z's return, board response, acquisition alternatives, or the value of remaining independent.
Lesson/counterfactual. [researcher inference · moderate] Open-source adoption is incomplete evidence until commercial attach, neutrality, and platform bargaining power are tested. Remaining independent could have preserved upside or exposed cloud-vendor capture; undisclosed consideration cannot resolve the branch.
Decision lab 5: Yubico — product truth to public transaction
Freeze: 2018-05-31. [investor-stated · strong] a16z used YubiKeys internally; Casado described reference checks among security teams, broad adoption, profitability, limited outside capital, and his board seat. Known: working hardware, open standards, practitioner use, capital efficiency. Unknown: check, price, ownership, hardware concentration, enterprise sales efficiency, consumer adoption, standards/platform risk, and exit rights. The public context is Fund V's broad multi-stage platform; the deal-to-vehicle mapping is unknown. Yubico, root-of-trust, diligence, capital-efficiency and board paragraphs · Fund V, allocation paragraphs
Underwriting reconstruction. [researcher inference · moderate] Kill if platform authenticators displaced keys without coexistence, standards fragmented, supply chain constrained growth, or enterprise use failed to expand. Next evidence: deployments, replacement/renewal, standards adoption, margins, and platform dependence.
Alternatives, dissent, and governance. [researcher inference · insufficient public record] Plausible branches were software-only authentication, waiting for platform-standard adoption, a smaller non-board position, or passing. Actual alternatives, dissent, transaction-election conduct, stop rules, and post-listing process changes are unknown.
- Would you invest then?
- What would kill the deal?
- What ownership/terms fit the risk?
- What evidence unlocks the next check?
Reveal. [contemporaneous record · strong] Yubico combined with ACQ Bure and listed in 2023 at an approximately $800M company equity value through mixed cash/stock mechanics. Before closing, the issuer expected a16z to own 6.1% of the combined company and disclosed a conditional 180-day lockup. The completion record does not establish a16z's actual closing shares, later compliance or sales, entry basis, fund allocation, distributions, or return. Listing is a venue, not realization. Yubico/ACQ Bure release, “Ownership structure” table and lockup paragraph · first trading day, opening completion paragraph
Lesson/counterfactual. [researcher inference · moderate] Direct product truth and practitioner references are strong early evidence, but company transaction, holder liquidity, and LP distribution remain three separate gates.
Decision lab 6: Astranis — outside-competence learning and capital intensity
Freeze: 2018-03-01. [investor-stated · strong] Casado said a16z had not invested in space, described his own initial context gap, and backed a lower-cost geostationary architecture after technical/founder work; he joined the board. Known: prototype path, differentiated architecture, founders, first-space-deal status. Unknown: launch reliability, supplier risk, customer contracts, regulatory timing, debt capacity, constellation economics, check, ownership, and team decision allocation. The public platform context is Fund V; no deal-level vehicle is identified. Astranis, unfamiliarity/architecture and board paragraphs · Forbes, opening financing/board and prototype passages · Fund V, allocation paragraphs
Underwriting reconstruction. [researcher inference · moderate] Kill if launch/on-orbit milestones failed without credible correction, contracts lacked financing value, unit economics required uneconomic scale, or debt/equity needs outran milestones. Next evidence: tests, launch, customer deposits, regulatory approvals, supplier redundancy, on-orbit performance, and capital per deployed capacity.
Alternatives, dissent, and governance. [researcher inference · insufficient public record] Plausible branches were to wait for flight proof, back a different orbit/architecture, syndicate a smaller option position, or pass. Actual alternatives, dissent, board responses to the anomaly, stop rules, and process changes are not public.
- Would you invest then?
- What would kill the deal?
- What ownership/terms fit the risk?
- What evidence unlocks the next check?
Reveal. [contemporaneous record · strong] Astranis reported a mission-impacting Arcturus solar-array-drive anomaly, reproduced a supplier-component failure, and proposed a fix. It later raised substantial equity/debt and reported five satellites/backlog. These are operating and financing facts, not valuation or return. No public source allocates a16z's governance response. Arcturus update, anomaly/reproduced-failure paragraphs · Series E, opening capital and operating paragraphs
Lesson/counterfactual. [researcher inference · moderate] An outside-domain deal should translate curiosity into technical, regulatory, customer, financing, and supplier milestones. Continued financing can reflect progress or capital dependence; without unit economics and ownership, it does not answer the return question.
Decision lab 7: Tecton — repeat capital and open-source commercialization
Freeze: 2018 seed and 2020-04-28 Series A. [investor-stated · strong] The post connected the founders' Uber Michelangelo experience to a production feature store, said a16z engaged top ML teams, and disclosed seed then A investment. Known: domain team, production problem, market conversations, repeat decision. Unknown: seed/A checks and vehicles, ownership, open-source/commercial conversion, retention, cloud competition, internal approval, and acquisition rights. The seed falls within the public Fund V era; the A predates the Fund VII announcement, and neither check is mapped to a vehicle. Tecton, Michelangelo/feature-store and seed/A closing · Fund V · Fund VII announcement
Underwriting reconstruction. [researcher inference · moderate] Kill if feature stores became a cloud-native commodity, data gravity favored platforms, deployment remained services-heavy, or paid use did not expand. Next evidence: production deployments, renewal/expansion, attach to ML workloads, time-to-value, and platform neutrality.
Alternatives, dissent, and governance. [researcher inference · insufficient public record] Plausible branches were seed-only observation, a cloud-native competitor, a broader MLOps platform, or passing on the A. Actual alternatives, dissent, the repeat-check approval, board role, acquisition conduct, stop rules, and process changes are unknown.
- Would you invest then?
- What would kill the deal?
- What ownership/terms fit the risk?
- What evidence unlocks the next check?
Reveal. [contemporaneous record · strong] Tecton later raised a $100M C, and Databricks announced the strategic acquisition without disclosing consideration. Series C, round/syndicate section · Databricks, summary and “Tecton + Databricks”
Interpretation. [researcher inference · moderate] A follow-on investor becoming acquirer is consistent with strategic fit but does not validate the original selection causally or reveal price, seller allocation, fund proceeds, governance response, or alternative standalone value.
Lesson/counterfactual. [researcher inference · moderate] Repeat capital is most informative when tied to a changed evidence set. The public post says seed then A, but not the internal gate. Platform acquisition may be the best path or evidence that standalone independence narrowed; public data cannot choose.
Portfolio forensics
Category exposure
[researcher inference · moderate] This mutually exclusive taxonomy is a research convenience, not an a16z classification. It shows that the public record is overwhelmingly software/infrastructure and that later AI additions extend rather than replace the earlier control-point thesis.
| category | count | included companies | underwriting implication |
|---|---|---|---|
| Developer, cloud, API, and commercial infrastructure | 17 | Anyscale, Braintrust, Convex, EngFlow, Fly.io, Isovalent, Kong, Metronome, Netlify, Orbit, Parsec, RapidAPI, Relace, Resend, Runta, Tackle, Tigris | Highest visible concentration; product pull and control-point arguments recur, but cloud/platform dependence and services content differ materially. |
| Data, analytics, and ML infrastructure | 12 | ActionIQ, Coactive, dbt, Distributional, Fivetran, Imply, Instabase, MotherDuck, Preset, SigOpt, Tabular, Tecton | Open formats, data gravity, developer usability, and system-of-record economics recur; several strategic combinations remain unpriced. |
| AI models and applications | 9 | Cursor, Deeptune, Ideogram, Phota Labs, QuiverAI, Rasa, Shizuku AI, WaveForms AI, World Labs | Most are young and team-attributed; financing size and model claims are especially poor outcome proxies. |
| Security | 6 | Ambient.ai, Eclypsium, Material Security, Pindrop, Truffle Security, Yubico | Direct product/technical evidence is strongest in Yubico; public person-level economics are absent across the group. |
| Hard tech / autonomy | 2 | Astranis, DeepMap | Capital, supplier, regulation, and milestone risk require different gates from software; DeepMap is board-only/incomplete. |
| Total | 46 | 17 + 12 + 9 + 6 + 2 = 46. |
Geography, check size, and invested-capital boundary
- Geography. [researcher inference · insufficient public record] The announcement and mutable board/profile corpus does not consistently state incorporation, headquarters at investment date, operating footprint, or customer geography. A reproducible geographic partition was therefore not constructed; domain examples and current websites cannot be substituted for decision-date domicile.
- Check size and invested capital. [researcher inference · insufficient public record] Public posts often disclose total round size and sometimes that a16z led, but they rarely disclose the a16z check, vehicle, security, reserves, or follow-on allocation. No compatible invested-capital total exists across the 46 lineages, so round totals are not summed as firm or Casado capital. vehicle and economics boundary · source-map denominator boundary
Sourcing, diligence, and follow-on patterns
- Portfolio and customer loops. [investor-stated · strong] SigOpt surfaced through a portfolio executive briefing; Tackle through a portfolio-company board meeting; Fivetran through portfolio and public-company encounters; Distributional through SigOpt and interviews with 25+ AI leaders; ActionIQ through a prior Stanford relationship and a dozen marketer interviews. SigOpt, opening sourcing and closing follow-on · Tackle, discovery paragraph · Distributional, diligence/relationship paragraphs
- Product truth. [documented behavior · moderate] Braintrust and Yubico record direct a16z/Casado product use; Convex records earlier personal angel/adviser involvement. This improves access to product evidence but can also create confirmation, information-asymmetry, and conflict risks. Braintrust, lead/user sentence · Yubico, internal-use/diligence paragraphs · Convex company Series A, angel/adviser paragraphs
- Repeat-capital evidence. [contemporaneous record · strong] Only four Casado announcement pages explicitly disclose multiple checks—SigOpt, Tecton, Coactive, and Ideogram—while Metronome's issuer post separately says seed+A. Public reserve decisions, decline cases, and ownership maintenance are missing.
- Board coverage. [contemporaneous record · strong] Twenty-five of 46 lineages appear on the current profile's board roster, but only 11 deal announcements contain board-seat language and three of those are collective/unassigned. Board service increases access; it does not prove the initial investment role or later intervention.
- Attribution concentration. [researcher inference · strong] Early posts are more often Casado-only bylines; later AI/application posts more often name two to four a16z authors. Cursor's outcome should not be retroactively converted into solo Casado evidence, and coauthored recent deals are not independent proof that a personal edge scaled.
Outcome and realization forensics
| observed state | count / examples | what may be said | what may not be said |
|---|---|---|---|
| Priced company transactions/listing | 3 events / 3 lineages: Cursor, Yubico, Parsec. SpaceX 8-K, Item 1.01 · Yubico transaction overview · Unity 10-K, Note 6 | Comparable company-level event values exist. | Investor proceeds, ownership, realized gain, DPI, MOIC, or IRR. |
| Unpriced acquisitions/combinations | 10 events / 11 lineages: ActionIQ, dbt/Fivetran, DeepMap, Isovalent, Metronome, Orbit, SigOpt, Tabular, Tackle, Tecton. Uniphore · Fivetran/dbt · NVIDIA acquired-status post · Cisco · Stripe · Postman · Intel acquired-status post · Tabular announcement · Tackle status · Tecton announcement | A completed or announced corporate outcome and, sometimes, strategic rationale exist; Tabular and Tecton remain bounded as announced agreements. | Terms-undisclosed events are not zero and cannot be ranked economically. |
| Bounded asset/R&D-unit sale | 1 event / 1 lineage: Rapid. Nokia release, opening and acquired-assets paragraph | A technology-asset and R&D-unit transfer occurred. | Do not call it a whole-company exit or infer holder proceeds. |
| No qualifying primary corporate-outcome record | 31 lineages in the bounded sweep. source-map coverage assessment | No qualifying primary event was located by the cutoff. | “Clean,” “successful,” solvent, current mark, or return. |
| Financing/operating figures | World Labs $1B financing; Astranis capital/backlog; Cursor private rounds. World Labs funding announcement, opening paragraph · Astranis Series E · Cursor Series D | Capital needs, issuer-reported scale, or financing terms may be described with source labels. | Financing raised, backlog, revenue, or private valuation as investor realization. |
Outcome reconciliation. [researcher inference · strong] The table contains 14 distinct corporate events affecting 15 lineages: 3 priced events + 10 unpriced company events + 1 asset event. Therefore 15 affected + 31 without a qualifying primary record = 46 included lineages. WaveForms and Deeptune remain secondary/provisional reports and do not enter the primary-event count.
Tender/secondary boundary. [researcher inference · insufficient public record] No reviewed primary source identifies an a16z tender or secondary sale in these 46 companies. The conclusion is “not observed in the bounded record,” not “no sale occurred.”
Failures, misses, and adverse evidence
| case | adverse or limiting evidence | response / terminal state | disciplined conclusion |
|---|---|---|---|
| Tackle | CEO said the company overbuilt in 2021–22 and separated 75 people. company update, overbuilt and runway paragraphs | Cost reduction, services/sales-led expansion, long stated runway; AppDirect acquisition terms undisclosed. | [documented behavior · strong] Best public operating-miss case; investment outcome unknown. |
| RapidAPI/Rapid | Company-confirmed roughly 50% workforce reduction and CEO change were reported in 2023. TechCrunch, opening/company-confirmation paragraphs | Nokia later acquired technology assets and an R&D unit, not clearly the whole company. Nokia, opening and acquired-assets paragraph | [contemporaneous record · moderate] Major operating reset; no Casado board attribution, write-off, or return evidence. |
| Orbit | Postman said the standalone Orbit product would sunset within 90 days of acquisition. Postman, acquisition and final sunset paragraphs | Product folded into acquirer. | [documented behavior · strong] Product sunset is not proof of company-level investor loss. |
| Astranis | Issuer reported a mission-impacting Arcturus solar-array-drive anomaly and reproduced a supplier component failure. Astranis, anomaly/fix paragraphs | Design fix and later equity/debt financing; issuer metrics unaudited. | [documented behavior · strong] Real technical adverse event and response; no fund-return inference. |
| Resend / new.email | Separate brand/stack created maintenance cost; experiment was sunset and capabilities moved into Resend. Resend, “Why” and separate-stack paragraphs | Integration into parent product. | [documented behavior · strong] Product-level failed experiment, not parent-company failure. |
| Fly.io | Founder comments document a 2024 workforce adjustment. founder comments in thread | Issuer announced a 2026 Series D and Casado board role. issuer financing/board paragraph | [contemporaneous record · moderate] The adverse event predates the disclosed Casado board role; do not misattribute governance. |
| Preset | Issuer announced a $7.27M C in 2026. Preset, opening financing paragraph | Continued operation/financing. | [researcher inference · strong] Round size alone cannot establish a down round without prior price/security data. |
| WaveForms / Deeptune | Quality reporting says each was acquired; terms undisclosed, and primary transaction confirmation remained missing in this pass. WaveForms report, opening/terms paragraphs · Deeptune report, opening/terms paragraphs | Short-duration reported transactions. | [contemporaneous record · provisional] Do not promote to verified outcomes or gains without issuer/acquirer records. |
No-result discipline. [researcher inference · strong] Searches also covered Fivetran/dbt, DeepMap, Metronome, Preset, WaveForms, Resend, Phota, Relace, Shizuku, QuiverAI, Deeptune, Runta, Fly.io, EngFlow, ActionIQ, Eclypsium, and the remaining ledger. “No adverse event surfaced” is unknown, not clean, because private-company disclosures are selective and identity/role coverage is uneven.
Misses and anti-portfolio
- Hugging Face recollection. [retrospective witness · moderate] Casado says the firm sometimes talked itself out of companies despite strong usage and uses Hugging Face in a discussion of open-source traction. The record supplies no dated opportunity, allocation, term sheet, IC vote, or proof the firm could have invested. Treat it as a process warning against over-intellectualizing—not a priced miss or counterfactual return. Colossus, 00:29:03–00:31:48
- “Nearly 200” is not a denominator. [investor-stated · strong] Casado's direct interview mixes investments he made with funds/teams he helped run; his Series A preference, $30–40M total-exposure framework, standalone-outcome preference, and informed-objection test are general process claims. a16z News, 00:00:54–00:11:04, 00:28:20–00:32:46, 00:52:10–00:53:06
- Missing anti-portfolio. [researcher inference · insufficient public record] No complete passes, rejected-deal chronology, allocation losses, write-offs, reserve refusals, or public/private-market opportunity-cost ledger was found. Therefore public announcements cannot yield a personal selection hit rate.
Uncertainty, missing records, and continuation routes
| unanswered question | exact missing evidence | next retrieval route | conclusion if absent |
|---|---|---|---|
| Deal economics | Initial/follow-on cost, security, fully diluted ownership, preferences, dilution, tenders, proceeds, distributions by company and vehicle | Company cap tables; fund investment schedules; audited statements; distribution notices | MOIC/IRR/DPI/TVPI and economic hit rate remain non-computable. |
| Decision authority | Sourcing logs, IC charters/minutes/votes, delegated budgets, partner approvals and objections | Partnership/IC records; named-participant interviews; board packages | Bylines remain public narration; legal control filings do not allocate deal decisions. |
| Vehicle allocation | Deal-to-fund/SPV mapping, reserve transfers, growth-team allocation and ownership | Fund financials; allocation/conflict logs; Form ADV supplements/LP reports | Calendar year must not be used to guess a vehicle. |
| Conflicts | Portfolio conflict lists, mortal-enemy elections, recusals, information barriers, cross-vehicle valuation/allocation protocol | Conflict/recusal policies; board consents; LPAC records; founder interviews | Stated conventions remain untested in the public corpus. |
| Board behavior | Meeting attendance, recruiting, follow-on/exit votes, interventions, dissent | Board minutes/consents; director interviews; transaction proxy materials | Board roster proves service only. |
| Losses/passes | Complete actual-deal denominator, passes, write-offs, mark history, reserves, rejected follow-ons | Internal ledger; audited valuation schedules; complete anti-portfolio | Public announcement denominator remains positively selected. |
| Yubico realization | Actual closing shares versus the proposed 6.1% stake; applicability and compliance with the disclosed 180-day lockup; entry basis, later sales, fund allocation, distributions, and taxes | Post-completion shareholder tables; securities filings; fund reports | The proposal establishes an anticipated stake and lockup, not actual realization or return. |
| WaveForms/Deeptune | Primary issuer/acquirer confirmation and transaction terms | Meta/Mercor/company releases or filings | Outcomes remain secondary/provisional. |
| Private operating status | Audited revenue, margin, burn, runway, financing, solvency for 31 lineages without a qualifying primary outcome record | Company filings/data rooms; creditor records; audited financials | Search silence remains unknown. |
Bottom line
[researcher inference · strong] Casado's public record is most consistent with a technical-control-point and customer-truth investing practice amplified by a16z's portfolio, team, capital, and board access. Cursor is the dominant visible company-value event; Parsec is the cleanest cash-priced ordinary exit; Tackle is the strongest adverse operating lesson. Yet no public case identifies a person- or fund-specific return, and recent joint bylines weaken any solo-repeatability claim. The defensible conclusion is about observable decision evidence and company outcomes—not personal alpha, realized returns, or a complete hit rate.
Coverage and evidence base
Literal priority-source reconciliation
The WRITINGS inventory contains 16 priority works: 9 ★★★ and 7 ★★. Every work is processed here and has one source note. Fourteen canonical or authorized copies exposed the complete article body; two publisher routes exposed only an authenticated headline, deck or opening plus the a16z author-index attribution. The denominator therefore reconciles as 14 full + 2 partial + 0 metadata-only = 16, and analysis of the two gated essays stops at the visible boundary.
| access state | count | exact records |
|---|---|---|
| full | 14 | The Empty Promise of Data Moats; The New Business of AI; Growth+Sales; Emerging Architectures for Modern Data Infrastructure; Bottom Up Pricing & Packaging; The Cost of Cloud; The Cloud Killed Infrastructure; Market Annealing; Who Owns the Generative AI Platform?; Navigating the High Cost of AI Compute; The Economic Case for Generative AI and Foundation Models; Base AI Policy on Evidence; Questioning Margins Is a Boring Cliché; America Cannot Lose the Robotics Race |
| partial | 2 | AI Talks Leave “Little Tech” Out — WSJ headline-level record plus a16z authorship/index record; Keep the Code Behind AI Open — Economist headline and publisher excerpt/attribution plus a16z index record |
| inaccessible / metadata-only | 0 | none |
| deeply analyzed to the available boundary | 16/16 | full texts receive argument, mechanism, evidence, assumption, decision, contradiction, and translation analysis; partial texts receive bounded access analysis without reconstructing a hidden body |
Evidence boundary — researcher inference | strong. The corpus is unusually useful for reconstructing a dated infrastructure-investing vocabulary: marginal data value, AI contribution margin, hybrid go-to-market, workload specialization, market creation, stack bargaining power, compute procurement, open-weight policy, and physical-AI industrial capacity. It is not a performance record. Coauthored essays are joint positions; unnamed portfolio observations lack a denominator; examples can be success-selected; and no writing supplies complete passes, checks, ownership, reserves, fund cash flows, or realized returns. a16z itself warns that mentioned investments are not representative and that some third-party information is not independently verified. a16z article disclosure · source map, candidate-deal boundary
Source-by-source analysis
1. “The Empty Promise of Data Moats” (2019, with Peter Lauten)
Context, argument, and reasoning. Casado and Lauten distinguish a true network effect—each additional node directly makes participation more valuable—from a data scale effect, where a larger corpus may improve a model without connecting users. Their anti-moat mechanism is two-sided: the next useful observation often becomes harder and costlier to acquire, clean, label, secure, and refresh, while overlapping or long-tail observations add less product value. A permission-shared Eloquent Labs customer-support distribution illustrates diminishing coverage, but it is one domain rather than a representative enterprise-AI base rate. investor-stated | strong for the framework; investor-stated | moderate for its empirical generalization. Essay, “Data + network effects ≠ data network effects” through “A practical framework”
Decision implications, boundary conditions, and evolution. The usable underwriting rule is to measure minimum viable corpus, marginal acquisition cost, incremental model lift, decay, rights, portability, error tolerance, and competitor catch-up—then test ordinary moats such as workflow, distribution, vertical knowledge, trust, brand, and account control. The authors preserve important exceptions: scarce or exclusive sources, regulated access, trust-mediated custody, material accuracy thresholds, and hard-to-reproduce domain learning can be defensible. The later robotics essay’s deployment-data flywheel and the 2025 margins essay’s product-feedback thesis therefore do not simply reverse 2019; they must prove the exact scarce-data and incremental-value conditions this article specifies. researcher inference | strong for the continuity test; no public deal record shows that Casado used it to approve or reject a named investment. Essay, “When IS data defensible?” · robotics essay, deployment-data discussion · 2025 margins essay, product-specific data discussion · source note
2. “The New Business of AI (and How It’s Different From Traditional Software)” (2020, with Matt Bornstein)
Context, argument, and reasoning. Before the generative-AI boom, Casado and Bornstein argue that many AI companies combine repeatable software with service-like production: inference and retraining consume infrastructure, changing customer distributions create deployment work, humans review or catch failures, and edge cases can require customer-specific handling. Their private-company observations put many gross margins around 50–60%, cloud at 25% or more of revenue, and ongoing manual data work at 10–15%, while warning that five to ten early customers can conceal a growing ML backlog. The source states that these estimates come from founder interviews and publishes no sampling frame, so they are dated hypotheses rather than base rates. investor-stated | strong for the cost taxonomy; investor-stated | provisional for the numeric generalization. Essay, opening list, both “Gross Margins” sections, “Scaling AI systems,” and “Sources”
Decision implications, boundaries, and later tension. The direct operating advice is to narrow the domain, minimize per-customer model forks, allocate compute and human failover to cost of revenue, expose edge-case backlog, preserve stack optionality, and accept a coherent services model when the task truly requires it. For investment analysis, recurring revenue is insufficient: contribution margin must include inference, evaluation, implementation, support, and successful-task completion. The 2023 economic essay argues that foundation models and more error-tolerant creative/copilot work can escape this “mediocrity spiral,” while the 2025 margins essay adds routing, tiering, and enterprise mix as repair mechanisms. Those are testable updates, not permission to ignore the 2020 accounting discipline. researcher inference | strong for this reconciliation; the corpus provides no matched cohort showing which companies crossed from services-heavy delivery to scalable product. 2020 essay, “Building, scaling, and defending great AI companies” · 2023 economic case · 2025 margins essay · source note
3. “Growth+Sales: The New Era of Enterprise Go-to-Market” (2020, with Peter Lauten)
Context, argument, and reasoning. Lauten and Casado describe “growth+sales” as two linked funnels: a self-serve product first creates end-user adoption, retention, word of mouth, and within-logo spread; enterprise sales then converts that pull into security review, procurement, broad rollout, premium features, and expansion. Their six failure modes make the thesis falsifiable: a product may not reach value unaided; paid acquisition may buy transient users; company-level revenue can hide weak engagement; sales can arrive before customer pull; free use may lack a buyer or premium bridge; and a successful sales motion can cause product neglect. The examples are selected winners, so they establish plausibility rather than comparative superiority. investor-stated | strong for the operating sequence; investor-stated | moderate for the market generalization. Essay, “New buyer, new motion” and Failure Modes #1–#6
Decision implications, boundaries, and evolution. The diligence rule is to reconstruct the full user-to-budget path: independent time-to-value, cohort engagement, persona, organic retention, within-account propagation, buyer identity, security/procurement bridge, premium conversion, CAC by motion, and product velocity after sales hiring. Customer requests for wider rollout—not management’s desire for faster revenue—are the timing signal. The model does not fit centralized systems of record, regulated deployments, or integration-heavy products whose users cannot bypass authorization. It also complements rather than replaces 2023 market annealing: bottom-up pull can reveal a market, while founder-led sales still has to shape product, buyer, and category when no stable market exists. researcher inference | moderate for this cross-source reconciliation; no public decision record shows which Casado deal passed because of the dual-funnel test. Essay, Failure Modes #1, #3–#6 · Market Annealing · source note
4. “Emerging Architectures for Modern Data Infrastructure” (2020, with Matt Bornstein and Jennifer Li)
Context, argument, and reasoning. The original October 2020 version—not the later update now foregrounded by the shorter landing route—maps a data-infrastructure layer whose spending, tooling, and operating complexity were rising. Bornstein, Casado, and Li report a two-year research process involving hundreds of founder and expert conversations plus more than 20 practitioner interviews. Their core mechanism is architectural: warehouses and lakes were acquiring overlapping storage, transaction, semi-structured-data, scale, and SQL capabilities, while analytics and operational/ML workloads still differed enough to support parallel systems. Three blueprints then match control and complexity to customer maturity: modern BI, multimodal processing, and a full AI/ML stack. investor-stated | strong for the blueprint trade-offs; investor-stated | provisional for the market totals and category breadth, which rely on selected third-party data and an undisclosed practitioner sample. Original essay, opening, “Analytics, AI/ML, and the Great Convergence?” and “Blueprints”
Decision implications, boundaries, and evolution. The investable rule is to locate an unstable but necessary control point: identify the customer blueprint, indispensable workload, expertise burden, integration cost, and whether convergence strengthens or erases the vendor. This is a sourcing taxonomy, not a portfolio or return model. The essay simultaneously celebrates tool proliferation and predicts convergence; an investor must therefore distinguish temporary exploration from a durable independent market. By 2026, the right use is to rebuild the architecture from observed deployments and ask whether a product reduces total system complexity after people, integration, and egress—not to carry forward 2020 vendor boxes or market estimates. researcher inference | moderate. Original essay, unified architecture, blueprint limitations, and “Looking ahead” · version-bound source note
5. “Bottom Up Pricing & Packaging” (2021, with Jennifer Li)
Context, argument, and reasoning. Li and Casado derive a pricing system from the user journey rather than a copied SaaS page. A casual user can become a professional, team, and enterprise buyer; each transition changes the value delivered, buying authority, packaging, and service burden. Their four-tier pattern—free, prosumer, team, enterprise—comes from a 50-company map, while nine operating rules cover simple starting plans, journey continuity, monetization timing, qualification, price metrics, unit price, and experimentation. The mechanism is strongest where product usage can precede central authorization: organic value reveals demand, qualified accounts emerge, and sales completes security, procurement, administration, or broader rollout without severing the adoption path. investor-stated | strong for the decision sequence; investor-stated | moderate for generalization from selected companies. Essay, sections #1–#9 and four-tier framework
Decision implications, boundaries, and evolution. The IC test is a literal map of user, team, buyer, budget, trigger, tier, sales handoff, conversion, expansion, churn, support cost, and margin. Usage pricing should scale with value rather than punish expansion; free use should remain only while it creates measurable learning or qualified demand. The framework does not fit every regulated system of record, mandated deployment, or integration-heavy product, and waiting to monetize can conceal weak willingness to pay. It joins the earlier growth+sales model and later AI-margin argument: product pull is a distribution asset, but compute-intensive free use must earn its way into positive contribution margin. researcher inference | strong for the combined test; no named board decision or deal outcome validates it. Essay, sections #4–#9 · 2025 margins essay, conclusion · source note
6. “The Cost of Cloud, a Trillion Dollar Paradox” (2021, with Sarah Wang)
Context, argument, and reasoning. Wang and Casado argue that public cloud has high option value early—fast provisioning, flexible capacity, lower initial operating burden—but can become a structurally expensive cost of revenue at scale. Their mechanism is not “cloud bad”: once workloads stabilize and utilization becomes predictable, a company may capture part of the provider margin through owned or contracted infrastructure, while migration difficulty and engineering distraction create a lock-in tax. The essay’s market-cap and aggregate-value estimates are scenario arithmetic, not observed recoverable value, and its Dropbox example bundles several operational changes rather than proving repatriation alone caused the reported margin improvement. investor-stated | strong for the lifecycle framework; investor-stated | provisional for the $100 billion / $500 billion aggregate extrapolations. Essay, “The paradox,” “The cloud cost equation,” Dropbox case, and market-value estimate
Decision implications, boundaries, and evolution. Underwrite portability before scale: workload unit cost, utilization volatility, data gravity, egress, reserved pricing, migration capital, required reliability staff, depreciation, facilities, and fallback capacity. The choice is workload-specific and staged, not a company-wide ideological switch. Dropbox’s FY2025 filing is useful counterevidence to any frozen “owned means cheap” rule: it reports gross margin declining from 83% to 80% amid infrastructure-refresh and facilities costs. By 2026, compare realistic hybrid scenarios and preserve bargaining power through architecture and contracts. researcher inference | strong. Essay, repatriation decision and objections · Dropbox FY2025 10-K, MD&A, pp. 57–59 · source note
7. “The Cloud Killed Infrastructure. Long Live Infrastructure.” (2022)
Context, argument, and reasoning. Casado argues that hyperscalers did not eliminate infrastructure companies; they abstracted general-purpose primitives and thereby made specialized workload layers easier to build. The opportunity exists where a slice is large enough and sufficiently different in performance, data, security, or operating requirements that a verticalized cloud or service can outperform a generic platform. His examples establish that specialization is possible, not that every named vertical is a durable venture market. Meanwhile, hyperscalers continue to extend upward, bundle adjacent capabilities, subsidize strategic products, and improve price/performance. investor-stated | strong for the enabling logic; investor-stated | provisional for broad investability across the selected categories. Essay, cloud abstraction, specialized infrastructure, and examples
Decision implications, boundaries, and evolution. A vertical-cloud thesis must identify the exact workload discontinuity, absolute market, utilization advantage, customer switching cost, distribution path, capital requirement, and credible hyperscaler response. Loose coupling to the lower stack and a large specialized slice are enabling conditions; dependence on one cloud, weak differentiation, or a bundlable feature can destroy the thesis. This complements rather than reverses the cost-of-cloud essay: public infrastructure can enable a new vendor while remaining its largest cost and bargaining-power risk. researcher inference | strong. Essay, conditions and closing framework · source note
8. “Market Annealing: Getting to $10M ARR in Very Early Markets” (2023, with Peter Levine)
Context, argument, and reasoning. Casado and Levine describe company and market as co-adapting before product, buyer, price, positioning, and sales motion have stabilized. Founder-led sales carries product and category information across early customers; two or three “renaissance reps” can generalize that learning; specialized functions arrive only after repeatable patterns emerge. The authors give rough ranges for founder involvement, sales-leader timing, rep economics, and elapsed time, but the observations come from unnamed company experience and lack a failed-company denominator. investor-stated | strong for the learning sequence; investor-stated | provisional for numeric thresholds such as founder involvement through roughly $4–10 million ARR, hiring a leader around $2–4 million, or quota/load heuristics. Essay, byline, market-annealing model, founder-led selling, renaissance reps, and scaling sequence
Decision implications, boundaries, and evolution. The operating question is whether early commercial work is reducing uncertainty: common painful use case, repeatable user, economic buyer, deployment path, price, and shorter cycle. Bespoke revenue that grows without convergence is not annealing; it is services drift. A modern milestone plan should time-box experiments and define kill conditions for stagnant retention, falling reuse, rising customization, no common buyer, and no referenceable wins. The essay itself supplies the learning mechanism but not those stop rules. Bottom-up adoption can accelerate annealing when users self-discover value, but it cannot replace founder interpretation in an undefined market. researcher inference | strong. Essay, early customers through transition to scale · source note
9. “Who Owns the Generative AI Platform?” (2023, with Matt Bornstein and Guido Appenzeller)
Context, argument, and reasoning. In January 2023, Bornstein, Appenzeller, and Casado divide generative AI into infrastructure, foundation-model, and application layers. They observe infrastructure receiving much of the early dollar flow, model providers bearing training and serving costs, and applications showing rapid experimentation but uncertain retention, margins, and differentiation. The point is diagnostic rather than a settled winner forecast: no layer yet had an obvious systemic moat, and bargaining power could move as models commoditized, cloud providers integrated, or applications accumulated workflow and distribution. Their flow-of-funds and margin ranges are rough early-market estimates with incomplete samples. investor-stated | strong for the three-layer framework; investor-stated | provisional for 20–40%, 10–20%, 80–90%, and related quantitative generalizations. Essay, market map, value-flow, moat, and “What next?” sections
Decision implications, boundaries, and evolution. Diligence each layer’s gross profit after compute, supplier concentration, switching cost, portability, distribution, data rights, and ability to move up or down the stack. The 2023 “no systemic moats” conclusion was an information-set boundary, not a timeless fact. The FTC’s 2025 cloud/AI partnership study documents equity, revenue-sharing, control, exclusivity, information access, cloud commitments, and switching-cost mechanisms that can concentrate power; it expressly does not decide their legality or market effect. By 2026, a stack thesis must model contractual control as well as technical architecture. researcher inference | strong. Essay, defensibility and integration discussion · FTC Office of Technology report, executive summary and §§4–5, pp. 1–3 and 16–37 · source note
10. “Navigating the High Cost of AI Compute” (2023, with Guido Appenzeller and Matt Bornstein)
Context, argument, and reasoning. Appenzeller, Bornstein, and Casado convert AI-compute anxiety into a workload model. Cost depends on training versus inference, model size, request volume, latency, utilization, hardware availability, engineering capacity, provider discounts, and how frequently the workload changes. Public cloud or hosted APIs maximize early option value; reserved capacity, specialized providers, model optimization, and owned infrastructure can become economical as utilization stabilizes. Their prices and the rough annual-spend threshold discussed in the article describe April 2023 market conditions, not enduring procurement laws. investor-stated | strong for the variable set; investor-stated | provisional for price points and the roughly $50 million scale heuristic. Essay, byline, workload matrix, build-versus-buy, provider, and cost sections
Decision implications, boundaries, and evolution. Require a per-successful-task cost tree, not “GPU spend”: model choice, tokens or runtime, batching, utilization, latency SLA, retry/evaluation, human review, failure rate, peak capacity, depreciation, networking, and portability. Stress at least hosted, reserved/multicloud, specialized-cloud, and owned scenarios with transition capital and service reliability. The rule evolves the cost-of-cloud thesis into AI, but model architectures, hardware, prices, and supply have changed too much to reuse the 2023 dollar thresholds. researcher inference | strong. Essay, optimization and decision sections · source note
11. “The Economic Case for Generative AI and Foundation Models” (2023, with Sarah Wang)
Context, argument, and reasoning. Casado and Wang revisit the 2020 warning that capability is not economics. Their discontinuity claim has three parts: foundation models broaden task coverage; many creative and copilot tasks tolerate probabilistic output and invite user feedback; and falling generation cost can expand consumption and new product behavior. This can escape the “mediocrity spiral” in which edge cases require ever more services work. The essay openly labels its calculations rough and non-scientific; illustrative output-cost comparisons do not establish equal quality, complete workflow substitution, or durable margins. investor-stated | strong for the conditional mechanism; investor-stated | provisional for adoption, revenue, cost, and labor-substitution examples. Essay, “Capability != economics,” “How generative AI…,” “Let’s run the numbers,” and defensibility
Decision implications, boundaries, and evolution. Underwrite reliable completion rather than nominal generation: task tolerance, evaluation, human review, integration, liability, full workflow cost, retention, willingness to pay, and who captures falling-cost surplus. “Marginal creation cost toward zero” is directional rhetoric, not accounting; training, serving, distribution, supervision, and capital remain nonzero. Snowflake’s FY2025 filing is a useful current boundary: product gross margin fell from 74% to 71% as cloud infrastructure and AI-related investment rose and newer features lacked scale. Falling unit prices do not guarantee company margin expansion. researcher inference | strong. Essay, numbers and caveats · Snowflake FY2025 10-K, MD&A, pp. 70–71 · source note
12. “AI Talks Leave ‘Little Tech’ Out” (2024, with Katherine Boyle)
Access-bounded analysis. The Wall Street Journal route exposes an authenticated headline-level record but not a complete article body in the retrieved record; the a16z author archive preserves Casado’s and Katherine Boyle’s joint attribution. The title supplies a bounded joint position that AI-policy conversations omit “Little Tech,” but the accessible record does not define the constituency, identify the conversations, or expose the article’s reasoning, evidence, prescriptions, or examples. investor-stated | insufficient public record. No sentence below treats a headline, index record, or later commentary as the full text. WSJ canonical route, headline-level access · a16z author archive, attributed entry
Decision implication and boundary. A present-day diligence translation is to model compliance fixed cost, licensing or compute thresholds, incumbent exceptions, access to standard-setting, and whether rules change entrant survival without improving measured safety. That is researcher inference | moderate, not a recovered Boyle/Casado checklist. The article’s gated body, examples, citations, and precise definition of “Little Tech” remain unresolved, so it cannot bear a stronger regulatory or investment conclusion. source note
13. “Keep the Code Behind AI Open” (2024, with Ion Stoica)
Access-bounded analysis. The Economist route exposes a headline-level record but not a complete article body; The Economist's public post identifies Martin Casado and Ion Stoica as the guest-essay writers and attributes a bounded claim that open source will power AI innovation and remain the most secure software-development path. The accessible record does not define “open,” distinguish weights from code or data, expose evidence, or show exceptions and safety boundaries. investor-stated | moderate for the excerpted joint position; investor-stated | insufficient public record for the hidden reasoning chain. The Economist publisher post, body sentence above the linked card · Economist canonical route, headline-level access
Decision implication and boundary. The NTIA’s July 2024 open-weights report offers the strongest contemporary boundary: open models can diffuse innovation, research, and access while also carrying misuse and distribution risks; the evidence did not support immediate restrictions, but monitoring, evaluation, transparency, and the option for future action remained necessary. A 2026 investment test should specify which artifact is open, who can modify or deploy it, what complements retain value, what misuse and provenance controls exist, and whether openness creates adoption without eliminating capture. researcher inference | moderate. NTIA report, executive summary and recommendations · source note
14. “Base AI Policy on Evidence, Not Existential Angst” (2024)
Context, argument, and reasoning. Casado argues that AI-specific regulation should target demonstrated marginal risk—incremental harm relative to existing computer systems—rather than fear attached to a technology category. The useful mechanism is a baseline test: define the existing risk, isolate new capability and exposure, identify the gap in current law, then choose an intervention proportional to the added harm. Yet the essay’s broad claims that feared events did not materialize and AI appears very safe do not publish a search method, denominator, or common outcome measure. investor-stated | strong for the marginal-risk framework; investor-stated | provisional for the safety generalization. Essay, “Avoiding spurious AI regulations” and “AI policy based on reality”
Decision implications, counterevidence, and self-interest. Investors should model both over-regulation and under-regulation: use case, jurisdiction, affected population, severity, probability, exposure growth, irreversibility, existing authority, and a measurable revision trigger. Newsom’s SB 1047 veto criticizes a compute proxy while still calling for proactive guardrails; the international safety report documents current harms, uncertain severe risks, and limited assurance. Evidence-based policy is therefore an adaptive measurement regime, not “wait for catastrophe.” Casado’s role leading an AI/infrastructure practice creates an institutional interest in lower compliance burdens and should raise the burden for independent evidence. researcher inference | strong. Newsom veto message, pp. 1–2 · International AI Safety Report, executive summary and §5 · source note
15. “Questioning Margins Is a Boring Cliché” (2025, with Sarah Wang)
Context, argument, and reasoning. Wang and Casado reject a static gross-margin veto for AI applications. A low-margin launch cohort can improve through tiering, rate limits, routing to cheaper models, inference-price declines, enterprise mix, and expansion into higher-value workflow. The conclusion still says persistently low or negative margins can be fatal and should affect valuation; the real disagreement is whether a current margin is destiny. Historical winners show possibility, not a base rate, and the authors’ private observations omit company identities, cohort tables, periods, and audited margin bridges. investor-stated | strong for the repair mechanisms; investor-stated | provisional for 10–100x cost decline, 80/20 revenue concentration, and broad application-economics claims. Essay, all five claim headings and conclusion
Decision implications, boundaries, and evolution. Underwrite a dated margin bridge: inference per successful task, support, rate-limit sensitivity, routing quality loss, conversion by plan, enterprise expansion, churn after repricing, supplier concentration, and time to positive contribution margin. This is an evolution of—not permission to discard—the 2020 AI-cost framework. Snowflake’s reported margin compression provides a counterexample to automatic improvement, while model competition and packaging remain genuine repair options. The authors are financially interested a16z general partners making the investability case and publish no failed-startup denominator. researcher inference | strong. 2025 essay, conclusion · 2020 AI essay, gross-margin taxonomy · Snowflake FY2025 10-K, MD&A, pp. 70–71 · source note
16. “America Cannot Lose the Robotics Race” (2025, with Anne Neuberger)
Context, argument, and reasoning. Casado and Neuberger describe a physical-AI flywheel: manufacturing clusters colocate component suppliers, integrators, and customers; proximity improves iteration and tacit process knowledge; deployment produces real-world data; better policies increase useful deployment. Harmonic reducers illustrate why precision parts and integration—not foundation models alone—can be system bottlenecks. The essay’s robot-density, component-share, price, automation, and productivity figures have different dates and denominators and were not reconciled into a causal estimate. investor-stated | strong for the stack mechanism; investor-stated | provisional for the comparative industrial and deregulatory claims. Op-ed, “The impossible,” “Micron tolerance,” “How the West lost…,” and “What we need to do”
Decision implications, contradictions, and self-interest. Diligence the complete learning system: bill of materials, country/supplier concentration, yield, failure rate, integration cycle, customer-site permission, utilization, teleoperation, repair, data rights, and regulatory milestones. The data flywheel does not contradict the 2019 anti-moat essay unless deployment data are scarce, reusable, representative, and incrementally valuable; simulation, shared models, customer ownership, or hardware reliability may break it. The call for both low-friction Chinese supply and resilient allied capacity also needs an explicit dependency boundary. The article names World Labs while Casado’s a16z biography lists him on its board, making the company example financially interested. researcher inference | strong. Op-ed, component and policy sections · a16z profile, current board list · source note
Cross-source synthesis
Core written philosophy
Casado’s written record is most coherent when treated as a sequence of mechanism maps, not slogans:
- Identify the changing boundary. Data infrastructure, cloud specialization, model/application layers, and robotics clusters become interesting where a technical or institutional abstraction moves. researcher inference | strong. Data architecture · vertical cloud · GenAI platform
- Translate the boundary into an economic mechanism. Data volume must create marginal learning; model capability must create reliable completion; cloud flexibility must beat lifecycle cost; product use must lead to a buyer and budget. researcher inference | strong. Data moats · AI economics · growth+sales
- Preserve option value while uncertainty is high. Start with simple packaging and flexible infrastructure; learn through founder/customer contact; internalize, specialize, or add sales only after demand and workloads stabilize. researcher inference | strong. Bottom-up pricing · cost of cloud · market annealing
- Re-test instead of canonizing the first model. The 2020 low-margin warning becomes a 2023 conditional discontinuity and a 2025 margin-bridge argument; the invariant is full-cost measurement, not a permanent bearish or bullish position. researcher inference | strong. 2020 AI · 2023 economic case · 2025 margins
This supports a plausible architecture-to-economics translation skill. It does not establish superior security selection or returns. The public writings omit complete opportunities, passes, failed theses, checks, ownership, reserves, cash flows, and realized proceeds. researcher inference | insufficient public record. Candidate-deal boundary
Evolution and contradiction matrix
| tension | earlier position | later position | sustainable reconciliation | missing proof |
|---|---|---|---|---|
| Data scale versus deployment flywheel | Data volume usually lacks network-effect economics; test marginal value and scarcity (2019). 2019 note | Robotics deployment data can compound model quality and adoption (2025). 2025 note | The later claim passes only if data are exclusive or hard to reproduce, legally reusable, representative, and still yield material lift. **researcher inference | strong.** |
| Cloud cost versus cloud opportunity | Mature predictable workloads may justify repatriation (2021). Cost note | Cloud abstraction creates new specialized infrastructure vendors (2022). Opportunity note | Cloud can be both enabling substrate and supplier-cost risk; decide per workload and preserve portability. **researcher inference | strong.** |
| AI services economics versus margin repair | AI often carries compute, data, human-review, and edge-case burdens (2020). 2020 note | New tasks/models can escape services drift (2023); packaging/routing can repair margins (2025). 2023 note · 2025 note | Underwrite a falsifiable contribution-margin bridge; capability or falling unit cost alone is insufficient. **researcher inference | strong.** |
| Bottom-up growth versus founder-led annealing | Product pull should precede and qualify enterprise sales (2020–21). GTM note · pricing note | Undefined markets require hands-on founder sales and category shaping (2023). Annealing note | Product-led distribution applies after an independent value moment exists; annealing creates or discovers that moment and buyer. **researcher inference | moderate.** |
| GenAI openness versus stack concentration | Open code/weights and competition support entry (2024 access-bounded position). Open-code note | Infrastructure captures early value; contractual partnerships can create control and switching costs (2023–25 record). Stack note · FTC report, §§4–5 | Openness at one artifact does not remove compute, distribution, data, or contract bottlenecks. **researcher inference | strong.** |
| Proliferation versus convergence | New architecture produces many tooling categories (2020). | Warehouses/lakes and cloud platforms can absorb adjacent functions (2020 onward). | Proliferation is an exploration phase unless a vendor owns a durable workload/control point that platforms cannot cheaply bundle. **researcher inference | moderate.** Architecture note |
| Evidence-based policy versus interested advocacy | Marginal harm and existing-law gaps should determine new rules (2024). Policy note | The same essay makes broad safety claims; robotics essay urges “permissionless” deployment (2025). Robotics note | Treat the baseline test as useful while independently measuring cumulative, asymmetric, labor, safety, and security risks. **researcher inference | strong.** |
| Digital abstraction versus physical capacity | Software abstractions and specialized clouds reorganize infrastructure (2020–23). Architecture note · cloud note | Robotics advantage depends on precision parts, factories, clusters, and national policy (2025). Robotics note | Physical AI adds capital, supply-chain, integration, and policy constraints; it is a completion of the stack, not proof software is irrelevant. **researcher inference | strong.** |
What the writings do and do not establish by decision dimension
| decision dimension | strongest public evidence | support boundary |
|---|---|---|
| Sourcing | Architecture maps, workload discontinuities, market-creation loops, and practitioner interviews can generate categories and founder conversations. Architecture note · annealing note | **researcher inference |
| Picking | Marginal data value, per-successful-task economics, stack power, product-to-budget path, and market-annealing convergence are falsifiable tests. Data note · AI note · stack note | **researcher inference |
| Pricing / GTM | Growth+sales, user-journey packaging, qualification, founder selling, routing, and margin bridges form a coherent operating toolkit. GTM note · pricing note · margins note | **researcher inference |
| Ownership / reserves | Cloud internalization and compute procurement show sensitivity to capital and supplier economics. Cloud note · compute note | **researcher inference |
| Portfolio construction | Stack maps identify interdependence and concentration risks. Stack note | **researcher inference |
| Boards / governance | Li and Casado cite board experience and several essays translate into operating metrics. Pricing note | **researcher inference |
| Policy / risk | Marginal-risk and open-model arguments offer testable regulatory questions. Policy note · open-code note | **researcher inference |
| Exits / returns | None of the 16 writings supplies a repeatable exit rule or investor cash-flow evidence. Evidence boundary | **researcher inference |
Reusable decision playbook
The following translations are dated 2026-08-19 and are researcher inference, unless a source explicitly states the underlying historical rule.
1. Measure marginal learning, not accumulated data
- Historical rule. [researcher inference | moderate] Ask whether the next observation is costly, scarce, legal to use, and materially improves the product. Data-moat framework
- Diagnostics. [researcher inference | moderate] Learning curve by corpus size; incremental acquisition/label cost; decay; rights; error-segment lift; competitor catch-up; simulator or synthetic-data substitution. Data-moat note
- Kill test. [researcher inference | moderate] If incremental data produce negligible customer or model value, “more data” is not a moat. Data-moat note
- Modern boundary. [researcher inference | strong] Robotics deployment data qualify only when they satisfy the same scarcity, reuse, representativeness, and lift tests. Robotics flywheel
- Modern VC translation (as of 2026-08-19). [researcher inference | moderate] Transfers: gate a claimed data moat on measured marginal product lift and lawful reusable access; does not transfer: raw corpus size, the 2019 category examples, or an assumption that proprietary data are automatically scarce; changed assumptions: synthetic data, simulation, foundation-model priors, and multimodal collection can lower replication cost; observable signals: lift by added-data tranche, acquisition/label cost, rights, decay, and competitor catch-up; likely misuse: calling any private dataset a moat; current example: the 2025 robotics flywheel is a source-stated application of the test, not an independently demonstrated outcome. Data-moat note · robotics note
2. Underwrite contribution margin per successful outcome
- Historical rule. [researcher inference | moderate] Allocate inference, training, human review, implementation, support, and edge-case work to the delivered product. 2020 AI cost taxonomy
- Diagnostics. [researcher inference | moderate] Cost per attempted and successful task; failure/retry/evaluation; customer-specific work; gross profit after support; task tolerance and liability. 2020 AI note
- Kill test. [researcher inference | moderate] If scale increases exception labor or model forks faster than gross profit, growth is services drift. 2020 AI note
- Modern boundary. [researcher inference | strong] Permit low initial margins only with measured routing, tiering, conversion, retention, and time-bound improvement. 2025 margin bridge
- Modern VC translation (as of 2026-08-19). [researcher inference | moderate] Transfers: underwrite quality-adjusted contribution margin per completed task; does not transfer: 2020 model prices, workload mix, or a fixed software-margin benchmark; changed assumptions: model routing, agent retries, multimodal workloads, and vendor price competition alter both cost and completion; observable signals: cost per attempt/success, human-review share, support load, routing quality, conversion, retention, and a dated breakeven path; likely misuse: treating future model deflation as permission for indefinite negative unit economics; current example: Snowflake's FY2025 gross-margin compression is a grounded company counterexample to automatic margin improvement, not a matched AI-startup cohort. 2025 margin note · Snowflake FY2025 10-K, MD&A, pp. 70–71
3. Reconstruct the user-to-budget system
- Historical rule. [researcher inference | moderate] Product use must connect continuously to a buyer, budget, enterprise trigger, and pricing metric. Growth+sales · Bottom-up pricing
- Diagnostics. [researcher inference | moderate] Time-to-value, cohort retention, within-logo spread, buyer identity, premium trigger, security/procurement path, CAC and payback by motion, churn after price changes. GTM note
- Kill test. [researcher inference | moderate] Free usage without a credible buyer/premium bridge, or sales growth disconnected from retained users, fails. Pricing note
- Modern boundary. [researcher inference | moderate] Usage billing must track customer value and include AI cost volatility; avoid bill shock masquerading as expansion. Pricing note
- Modern VC translation (as of 2026-08-19). [researcher inference | moderate] Transfers: trace user value to the economic buyer, premium trigger, procurement path, and value-aligned metric; does not transfer: historical price points, named-winner examples, or a presumption that bottom-up use converts; changed assumptions: variable AI costs, security review, outcome pricing, and agent autonomy can separate usage from value; observable signals: retained activation, within-logo spread, free-to-paid conversion, buyer-approved expansion, payback, and churn after repricing; likely misuse: presenting free-user growth or token consumption as enterprise demand; hypothetical: an AI assistant with high daily use but no budget owner fails until a paid workflow and quality-adjusted margin are demonstrated. GTM note · pricing note
4. Separate discovery from scale in early markets
- Historical rule. [researcher inference | moderate] Founders carry product, buyer, pricing, and category information until patterns repeat; renaissance reps generalize before specialized teams scale. Market Annealing
- Diagnostics. [researcher inference | moderate] Common use case, reusable product, repeated buyer, cycle time, referenceability, implementation variance, salesperson ramp, quota contribution after full load. Annealing note
- Kill test. [researcher inference | moderate] Revenue rises while reuse falls, customization grows, and no common buyer or deployment emerges. Annealing note
- Modern boundary. [researcher inference | moderate] Treat the essay’s ARR and timing ranges as historical observations; set company-specific experiments and stop dates. Annealing note
- Modern VC translation (as of 2026-08-19). [researcher inference | moderate] Transfers: separate founder-led discovery from repeatable sales and require convergence in product, buyer, and deployment; does not transfer: the essay's $10M/$30M/$100M markers, timing ranges, or selected-company outcomes; changed assumptions: AI-assisted building and selling can accelerate iteration without creating a budget or reusable product; observable signals: repeated use case/buyer, declining customization, stable cycle time, references, rep ramp, and fully loaded quota contribution; likely misuse: excusing permanent bespoke services as category creation; hypothetical: an industrial-AI vendor may keep founders in discovery until three repeat deployments share a product and buyer, then stop or scale on a dated test. Annealing note
5. Preserve infrastructure option value, then specialize deliberately
- Historical rule. [researcher inference | moderate] Flexible cloud/API capacity is valuable under uncertainty; predictable scaled workloads can justify reservation, specialization, or internalization. Cost of Cloud · AI compute
- Diagnostics. [researcher inference | moderate] Unit workload cost, utilization, egress, data gravity, provider discount, migration cost, reliability staff, depreciation, supplier leverage, multicloud portability. Cloud note
- Kill test. [researcher inference | moderate] An internalization plan whose savings disappear after migration capital, idle capacity, staffing, or reliability is rejected. Cloud note
- Modern boundary. [researcher inference | moderate] Compare hosted, reserved, specialized, and owned scenarios per workload; do not migrate an entire company on slogan economics. Compute note
- Modern VC translation (as of 2026-08-19). [researcher inference | moderate] Transfers: preserve flexibility under demand uncertainty and compare lifecycle economics per stable workload before specializing; does not transfer: the 2021 multiplier, historical cloud discounts, or a company-wide repatriation prescription; changed assumptions: accelerator scarcity, specialized clouds, egress terms, sovereign requirements, and bursty AI demand reshape the frontier; observable signals: utilization, reserved-price capture, egress, reliability labor, migration capital, payback, and portability; likely misuse: turning repatriation or multicloud into ideology; current example: Dropbox's FY2025 filing grounds the continuing materiality of infrastructure cost but does not establish a universal owned-versus-cloud answer. Cloud note · Dropbox FY2025 10-K, cost-of-revenue and infrastructure discussion
6. Treat a stack map as a bargaining-power map
- Historical rule. [researcher inference | moderate] Identify the indispensable workload and which layer owns distribution, switching cost, compute, data, and customer relationship. Data architecture · GenAI platform
- Diagnostics. [researcher inference | moderate] Supplier/customer concentration, exclusivity, revenue share, control rights, information flow, cloud commitments, portability, platform-bundling response. Stack note
- Kill test. [researcher inference | moderate] A startup that is a replaceable feature with one dominant supplier and no workflow/distribution control lacks a venture-scale control point. Stack note
- Modern boundary. [researcher inference | strong] Include contractual power documented by the FTC, not only technical diagrams. FTC report, §§4–5
- Modern VC translation (as of 2026-08-19). [researcher inference | strong] Transfers: map technical dependencies together with distribution, contract, control, information, and switching rights; does not transfer: 2023 layer shares, vendor rankings, or the prediction that one layer will capture value; changed assumptions: model-provider partnerships, exclusivity, cloud credits, open weights, and platform bundling can move power without moving the diagram; observable signals: concentration, control rights, revenue share, portability tests, renewal leverage, and alternative suppliers; likely misuse: equating a visible stack position with durable economics; current example: the FTC's 2025 report documents contractual control mechanisms but does not establish final value capture or startup returns. Stack note · FTC report, §§4–5
7. Use architecture maps as hypotheses, not portfolio construction
- Historical rule. [researcher inference | moderate] Match products to customer maturity and the simplest adequate blueprint; more control is not automatically better. 2020 data blueprints
- Diagnostics. [researcher inference | moderate] Durable workload, operational necessity, integration burden, buyer, platform substitution, category survival, total system complexity. Architecture note
- Kill test. [researcher inference | moderate] If convergence or bundling removes the independent budget/control point, the mapped category is not a company. Architecture note
- Modern boundary. [researcher inference | strong] Rebuild maps from current deployments; do not infer position size, diversification, or return from sector coverage. Architecture note
- Modern VC translation (as of 2026-08-19). [researcher inference | moderate] Transfers: use an architecture map to generate falsifiable workload and control-point hypotheses; does not transfer: the 2020 boxes, category boundaries, or any portfolio weight/return conclusion; changed assumptions: platform convergence, agents, open standards, and bundling can erase independent categories; observable signals: standalone budget, operational necessity, retention, integration burden, platform substitution, and category survival; likely misuse: funding every box or treating map coverage as diversification; hypothetical: a new data-observability vendor qualifies only if it retains an independent budget and workflow after the warehouse bundles adjacent features. Architecture note
8. Govern open models through an evidence-and-monitoring loop
- Historical rule. [researcher inference | moderate] Openness can diffuse innovation and competition; new restrictions should respond to measured marginal risk and gaps in existing law. Base AI Policy
- Diagnostics. [researcher inference | moderate] Artifact opened, licenses, capability, misuse exposure, provenance, evaluation, distribution reach, affected population, legal gap, severity, reversibility, monitoring trigger. Policy note
- Kill test. [researcher inference | moderate] “Open” without a definition or “safe” without a denominator does not support a policy or investment conclusion. Open-code note
- Modern boundary. [researcher inference | strong] Preserve the ability to tighten controls when monitored evidence changes; NTIA’s 2024 recommendation was continued evidence-building, not permanent nonregulation. NTIA report, recommendations
- Modern VC translation (as of 2026-08-19). [researcher inference | strong] Transfers: define the opened artifact, compare marginal risk with alternatives, identify legal gaps, and precommit monitoring/escalation triggers; does not transfer: a permanent presumption that openness is safe or that 2024 evidence settles later capabilities; changed assumptions: better distillation, tool use, distribution, and incident evidence can alter both benefit and misuse exposure; observable signals: evaluation deltas, exploit/misuse incidents, reach, severity, reversibility, affected populations, and enforcement gaps; likely misuse: treating portfolio interest or open status as societal-outcome evidence; current example: NTIA's 2024 evidence-building recommendation is a grounded policy process example, not proof that 2026 controls should remain unchanged. Policy note · NTIA report, recommendations
9. Diligence physical AI as an industrial system
- Historical rule. [researcher inference | moderate] Robotics performance depends on component precision, supplier proximity, integration, deployment access, and learning data—not models alone. Robotics essay
- Diagnostics. [researcher inference | moderate] Bill of materials, country/supplier concentration, yield, lead time, field failures, repair, teleoperation, utilization, customer-site approvals, data rights, working capital, policy milestones. Robotics note
- Kill test. [researcher inference | moderate] A demo whose production yield, component access, field reliability, or customer deployment loop cannot meet milestones is not validated by model capability. Robotics note
- Modern boundary. [researcher inference | moderate] Treat allied capacity and deregulation as scenarios; model cost, schedule, safety, labor, and security rather than assuming policy delivery. Robotics note
- Modern VC translation (as of 2026-08-19). [researcher inference | moderate] Transfers: diligence the full component-to-deployment learning system and finance its working-capital path; does not transfer: the essay's country statistics, component shares, price examples, or deregulatory outcome assumptions; changed assumptions: export controls, tariffs, automation, supplier localization, insurance, and customer-site rules affect scale; observable signals: qualified suppliers, yield, lead time, field reliability, repair, utilization, deployment permission, data rights, and cash conversion; likely misuse: treating a software benchmark or demo as manufacturing readiness; current example: the essay's World Labs reference is a financially interested illustration and supplies no independent production, deployment, or outcome record. Robotics note · a16z profile, current board list
Best five writings for reconstructing the method
- [researcher inference | strong] “The New Business of AI” (2020) — clearest example of translating technical failure modes into a cost taxonomy and falsifiable operating economics. Note
- [researcher inference | strong] “The Cost of Cloud” (2021) — strongest lifecycle and option-value framework, with enough assumptions to challenge rather than merely repeat. Note
- [researcher inference | strong] “Market Annealing” (2023) — most explicit account of founder learning, sequencing, and the transition from discovery to repeatable go-to-market. Note
- [researcher inference | strong] “The Empty Promise of Data Moats” (2019) — durable anti-slogan test that also supplies the boundary under which later data-flywheel claims can be true. Note
- [researcher inference | strong] “Who Owns the Generative AI Platform?” (2023) — most useful stack-level bargaining-power map and a clean historical information set for testing later concentration. Note
The five are selected for decision transparency and cross-corpus leverage, not because public evidence shows they produced the best investments. researcher inference | strong.
Missing evidence and continuation routes
- [researcher inference | insufficient public record] Full licensed bodies or authorized archives for the WSJ and Economist essays; until then, their source notes and analysis remain partial. WSJ note · Economist note
- [researcher inference | insufficient public record] Original IC memos, deal calendars, sourcing records, passes, sponsor/approval roles, checks, security terms, ownership, reserves, and follow-on decisions tied to these frameworks. Source-map retrieval ledger
- [researcher inference | insufficient public record] A complete opportunity and outcome denominator, including companies that followed similar maps but failed, plus realized fund cash flows. Candidate-deal boundary
- [researcher inference | insufficient public record] Named company-level evidence for the 2020 AI cost sample, 2023 annealing benchmarks, 2023 platform economics, and 2025 margin bridge. AI note · annealing note · platform note · margin note
- [researcher inference | insufficient public record] Longitudinal tests of the 2020 data-infrastructure categories and predictions against acquisitions, bundling, shutdowns, and durable independent vendors. Architecture note
- [researcher inference | insufficient public record] Workload-level cloud/owned cost studies including engineering, utilization, reliability, migration, facilities, and capital—not gross-margin anecdotes alone. Cloud note
- [researcher inference | insufficient public record] Casado/a16z lobbying, policy, portfolio-exposure, and conflict-management records for AI openness, regulation, and robotics advocacy. Policy note · robotics note
- [researcher inference | insufficient public record] Robotics production evidence: yield, unit cost, field reliability, supplier concentration, deployment utilization, data rights, and working-capital/exit-duration fit. Robotics note
Until those records are public, the written corpus supports a testable analytical vocabulary and a plausible architecture-to-economics translation skill. It does not support a personal hit rate, causal portfolio advantage, audited governance regime, or realized-return claim. researcher inference | insufficient public record.
Coverage and evidence base
The TALKS corpus reconciles 31 priority appearance families: 11 ★★★, 19 ★★, and one ★. Every family has one notes/t-*.md record, and all 31 are substantively processed from a complete exact recording, transcript, or captions. [contemporaneous record | strong] for inventory/access; [researcher inference | strong] for family boundaries. Source map, priority talks and supporting routes
| processed state | count | boundary |
|---|---|---|
| ★★★ represented by a source note and this synthesis | 11/11 | all priority-three appearances |
| ★★ represented by a source note and this synthesis | 19/19 | all priority-two appearances |
| ★ represented by a source note and this synthesis | 1/1 | short 2017 graduation talk |
| substantively analyzed | 31 | complete exact recording and usable claim-level locator |
| full creator transcript or captions | 10 | official/publisher text with direct claim locators |
| full official media, no full creator transcript | 21 | bounded secondary text used only for navigation and manual audio/video checking |
| source notes | 31/31 | one note per deduplicated family |
Several publisher versions are not independent talks. Turpentine E70 replays the June 2024 Cognitive Revolution interview; the December 2025 a16z “AI Boom” episode replays the October Generalist interview; the February 2026 capital-flywheel episode replays the Latent Space original; the March 2026 monopolies wrapper is the July 2025 20VC interview distributed by a16z in August; and the September 2023 generative-AI presentation is a spoken adaptation of the August Casado–Sarah Wang essay. Repetition establishes emphasis or a medium/version boundary, not independent confirmation. [researcher inference | strong]. E70 note, Contradictions · AI Boom note, Contradictions · Capital Flywheel note, Contradictions · Monopolies note, Contradictions · presentation note, Contradictions
Where no creator transcript existed, the exact publisher asset was bound by URL, GUID or platform ID, runtime, and clock. Third-party captions or ASR were navigation aids; uncertain speech was paraphrased, speaker turns were preserved, and no machine-only wording was promoted as a quotation. No raw audio, video, captions, or transcript artifact is stored in the investor directory. [contemporaneous record | strong]. Coverage map, coverage assessment · 20VC access note, Contradictions · Future Software note, Contradictions
The corpus is unusually good at mechanisms and self-correction: Casado explains how technical discontinuities become company searches, why usage can overturn a theory, why founder roles change across company phases, and why stage and vehicle shape an investment rule. It remains an interested record produced largely by a16z, its portfolio, or friendly interviewers. Repetition does not prove selection alpha, portfolio returns, AI market structure, policy welfare, or that an example caused an outcome. [researcher inference | strong]. Non-Consensus note, Contradictions · Future VC note, Contradictions
Source-by-source guide
Infrastructure… Is Everything (2016-02-25)
Casado connects LLNL simulation, post-9/11 intelligence work, Stanford networking, and Nicira to a search lens: newly programmable technical layers can create companies, but only when a concrete application, user, buyer, and delivery path exist. This is formation evidence, not proof that technical depth predicts returns. [retrospective witness | moderate]. Note, 01:19–10:07 and 32:13–34:38
Selling to Developers & Open Source Business Models (2016-04-13)
Developer adoption lowers discovery and insertion friction but does not identify the economic buyer or paid control point. [investor-stated | strong]. Casado's strongest direct behavior is an organizational choice at Nicira—separate open and proprietary teams with a senior arbiter—while Peter Levine supplies much of the broader sales and Red Hat argument. [documented behavior | moderate]. Note, 06:47–16:27 and 21:21–24:58
Pricing, Pricing, Pricing (2016-08-13)
Pricing is treated as market discovery: require paid trials, connect price to the sales motion, and learn whether a founder can move from early hunters to repeatable selling. Mark Cranney owns much of the packaging and contracting playbook; Casado's evidence is retrospective Nicira practice. [investor-stated | moderate]. Note, Takeaways
Trends in—and the Future of—Infrastructure (2016-08-21)
The initial sector map joins three shifts—hardware to software, installed product to service, and operator procurement to developer influence. The investable mechanism is removal of incumbent advantages; developer attention remains top-of-funnel, not revenue or defensibility. [investor-stated | strong]. Note, 00:45–20:38
All About Microservices (2016-09-01)
Microservices create richer application semantics and new security, observability, routing, and operational gaps, but a technical function is not automatically a company. Adrian Cockcroft owns the Netflix operating history; Casado owns the infrastructure-market interpretation and its TAM boundary. [investor-stated | moderate]. Note, Takeaways
Software Secures the World (2017-02-12)
Casado reframes security from a simple arms race to a workflow-misalignment problem: point tools create alerts faster than human teams can process them, so automation and integrated response may become the new product layer. Company examples and inbound figures are selected illustrations without a losing-company denominator. [investor-stated | moderate]. Note, 01:20–18:27
Going to Market When No Market Exists (2017-06-09)
A new market lacks a settled budget, comparison set, buyer, price, and repeatable process. Casado prescribes founder-led discovery, explicit narrative, high initial anchoring, and later sales repeatability; the talk is a direct precursor to “market annealing,” not evidence that category declaration causes adoption. [investor-stated | strong]. Note, 00:52–25:22
Navigating Uncertainty (2017-07-02)
The graduation talk adds a personal judgment rule: preserve optionality, act before uncertainty disappears, and update after failure. Its genre and survivor perspective make it useful biography but weak investment-efficacy evidence; the separate closing speaker is excluded from Casado attribution. [investor-stated | moderate]. Note, Casado 00:04–06:56
Creating a Category, from Pricing to Positioning (2018-02-24)
Casado separates category creation from proof of market: map the buyer's existing budget and mental model, delay price until technical value is established, then require production use, repeated use cases, and non-founder selling before calling founder-generated interest product-market fit. [investor-stated | strong]. Feaster's early-customer, product-marketing, and competitive-playbook claims remain separately attributed. [contemporaneous record | strong]. Note, Casado 02:06–07:38 and 13:41–22:30
The World Through an API (2018-03-09)
Casado generalizes disaggregation: as a technical ecosystem matures, smaller functions can support products, infrastructure vendors, and aggregators. Kong/Mashape, RapidAPI, and SigOpt are interested company illustrations, not evidence of Casado's sponsorship, check, ownership, or return. [investor-stated | strong]. Note, 01:01–16:28
Software Chasms (2019-01-28)
The most complete early operating framework is that technical companies cross repeated chasms—problem definition, product, delivery, integration, and enterprise sales. Founder-led sales is diagnostic; open source and services are tools with costs, not shortcuts. [investor-stated | strong]. Note, publisher transcript
Gross Margins, Early to Late (2020-06-26)
Gross margin is a phase- and architecture-dependent diagnostic rather than an early universal cutoff. Casado focuses on technical COGS, cloud reversibility, implementation, and AI/ML costs; later-stage benchmarks belong partly to co-speakers. [investor-stated | strong]. Note, Takeaways
On Fear and Leadership (2020-12-04)
Casado supplies rare decision evidence: he declined Nicira's CEO role, later regretted an interim arrangement, hired Steve Mullaney permanently, and describes the hire as probably his best company decision. [retrospective witness | strong]. The broader rule is to match product, sales, and operations leadership to the current bottleneck without making fear the decision criterion. [investor-stated | strong]. Note, 09:07–29:30
Cloud Cost (2021-06-25)
Cloud economics move from reversible startup tradeoff to potential COGS and strategic constraint as usage scales. The source supports scenario modeling, workload segmentation, negotiated-price and migration boundaries—not a universal repatriation threshold. [investor-stated | strong]. Note, transcript pp. 3–20
Past, Present, and Future of Digital Infrastructure (2022-06-07)
Casado combines cloud cost, workload specialization, fine-grained consumption, and open-standard boundaries with a valuable correction loop: reported Hugging Face usage challenged the team's theory. The case is process testimony; the episode supplies no investment memo, sponsor, price, ownership, or return. [documented behavior | moderate]. Note, 06:49–34:18
Cloud Wars, Company Wars, and Innovating Through Change (2022-09-07; recorded 2021)
The second cloud war moves infrastructure inside software COGS, while company transitions require deliberate cannibalization and organization change. The recording predates publication and includes Michael Dell and Steven Sinofsky; their operating claims must remain separate. [investor-stated | moderate]. Note, Takeaways
20VC — whether the venture model is broken (2022-12-05)
Casado argues for a barbell of scaled multi-product platforms and focused boutiques, with research performed before a fast deal and separate teams across risk buckets. He also defines a board boundary—supply market maps and scarce functions, not operating commands. [investor-stated | strong]. His admission of early overfitting is retrospective evidence about his own practice. [retrospective witness | moderate]. Note, 09:30–39:30
The Economic Case for Generative AI — presentation (2023-09-25)
The talk explains why earlier AI startups struggled with tail accuracy, human exception handling, narrow markets, hardware, and cheap human substitutes, then argues foundation models change cost and market breadth. It is a solo adaptation of the August Casado–Wang essay and therefore a processed spoken version, not independent corroboration. [investor-stated | moderate]. Note, 00:00–14:39
Why America Must Lead in AI Investment (2024-03-05)
Casado's questions favor investment, talent, and application-level regulation; Senator Todd Young supplies many of the specific policy prescriptions and acknowledges low-probability, high-cost risks. The useful boundary is cautious enablement, not a no-regulation position or Casado-only authorship. [investor-stated | moderate]. Note, Takeaways
Cognitive Revolution / Turpentine E70 — AI Innovation and AGI (original 2024-06-28; replay 2024-12-24)
Casado emphasizes heavy-tail reliability, a moving AGI definition, application-level regulation, and a falsifiable prediction of model-market fragmentation; Nathan Labenz supplies material counterarguments on abstraction, scaling, and unknown capability. E70 is one shortened replay, not a later forecast. [investor-stated | moderate]. Note, original clock
Entering Uncharted AI Territory (2024-07-09)
The interview combines model economics, market structure, overbuild risk, and technical-founder bias. [investor-stated | strong]. Casado's admission that drone/robotics boards revealed his lack of vertical expertise is retrospective evidence of a domain boundary changing the firm's specialist coverage. [retrospective witness | moderate]. Note, 23:13–30:31 and 42:28–58:41
AI's Hard Limits and Open Problems (2024-09-02)
Casado treats machine learning as a third programming primitive while stressing correctness, memory, state, information, and human-control limits for agents. He simultaneously favors public research compute, application-level rules, and M&A availability; the policy-incidence claims remain untested here. [investor-stated | strong]. Note, 20:12–42:42
Where Value Will Accrue in AI (2025-05-27)
Casado disaggregates AI into many markets and says model capability solves a bootstrap problem, not retention or moat. Sarah Wang—not Casado—supplies the sharpest warning about oversized pre-traction rounds and category conflicts. [investor-stated | strong]. Note, 02:45–20:55
AI Is Upending SaaS Pricing (2025-07-18)
Seat pricing breaks when AI reduces users while increasing work, so the metric must move toward output or value. The practical playbook is jointly shaped by Metronome CEO Scott Woody and is financially interested; the episode provides no matched retention, margin, or valuation cohort. [investor-stated | strong]. Note, Takeaways
The Future of Software Development (2025-07-21)
Casado calls models a new programming/infrastructure layer but rejects a simple replacement story: probabilistic logic adds verification, data, networking, latency, and guarantee requirements. Co-speakers own distinct product and workflow claims, and external productivity evidence is mixed. [investor-stated | strong]. Note, Takeaways
20VC / Monopolies vs. Oligopolies in AI (original 2025-07-28; later wrappers)
Casado starts from observed users, revenue, and value creation, then underwrites both monopoly and oligopoly paths by submarket. The same interview gives the clearest current ownership rule, conflict admission, approximately $1.2 billion infrastructure-fund reference, and a bounded 2×—not 10×—coding-productivity intuition. [investor-stated | strong]. Note, a16z feed-drop clock
State of American AI Policy: From Pause AI to Build (2025-08-15)
Casado characterizes a policy shift from precaution toward national building, while co-speakers supply distinct legal and political claims. The note tests the rhetoric against primary policy documents; “build” remains advocacy by an investor with AI exposure, not a welfare result. [investor-stated | moderate]. Note, Takeaways
Is Non-Consensus Investing Overrated? (2025-09-04)
Casado narrows his viral claim: products should often be non-consensus to customers, but investors must understand informed objections and future financing consensus. He invites a cohort test, admits it is unfinished, and makes stage/check size part of the rule. [investor-stated | strong]. Note, 00:00:30–11:04 and 43:06–53:06
Jack Altman and Martin Casado on the Future of VC (original 2025-09-03; a16z republication 2025-09-04)
The Uncapped feed drop describes specialist market coverage, media/distribution, conflict lanes, staying power, and a16z's multi-product design. It is valuable firm-process testimony but also explicit advocacy for the platform Casado helps lead. [investor-stated | strong]. Note, Takeaways
“This Feels Like 1996” (original 2025-10-07; a16z replay 2025-12-30)
Casado argues that enterprise adoption lags individual capability, AI has no inherent moat, and the boom is still early rather than late-dot-com overbuilt. “Markets in” is his current sequence—map structural demand, then select the team. [investor-stated | strong]. No failed-map cohort tests the claimed edge. [researcher inference | insufficient public record]. Note, Takeaways
AI's Capital Flywheel (2026-02-19)
Casado and Sarah Wang describe a capital→compute→capability→demand→revenue loop, vertical expansion risk, and two market futures: fragmented applications or model oligopoly. [investor-stated | strong]. GPU utilization is not independent customer cash, and current revenue may borrow against the next training run. [researcher inference | strong]. Note, Takeaways
Evolution, contradictions, and present translation
The dated evolution judgments in this table are [researcher inference | strong]; each row links the direct spoken records from which the comparison is reconstructed.
| era | dominant spoken evidence | evolution |
|---|---|---|
| 2016–2018 | Infrastructure, Takeaways, Selling, Takeaways, GTM, Takeaways, API, Takeaways | Technical discontinuity becomes a company-search map, but user, buyer, price, sales motion, and monetizable control point are already separate gates. |
| 2019–2021 | Software Chasms, Takeaways, Gross Margins, Takeaways, Fear/Leadership, Takeaways, Cloud Cost, Takeaways | The doctrine becomes less triumphalist: services, integration, COGS, leadership transitions, enterprise selling, and irreversibility can dominate elegant product architecture. |
| 2022–2023 | Digital Infrastructure, Takeaways, 20VC, Takeaways, GenAI presentation, Takeaways | Usage is allowed to falsify theory; venture becomes a specialist, multi-stage institutional design; generative AI is framed as an economic discontinuity rather than only a capability jump. |
| 2024 | America/AI, Takeaways, Uncharted, Takeaways, Hard Limits, Takeaways, E70/original, Takeaways | AI enthusiasm is paired with tail-risk, correctness, domain expertise, application-level regulation, public research investment, and explicit willingness to be wrong on agents and market concentration. |
| 2025–2026 | Value Accrual, Takeaways, Monopolies, Takeaways, Non-Consensus, Takeaways, AI Boom, Takeaways, Flywheel, Takeaways | Market-first search, ownership, conflict, conventional moat, labor/output pricing, capital intensity, vertical expansion, and two-scenario underwriting dominate. The public performance denominator remains absent. |
The main tensions and usable reconciliations are [researcher inference | strong] unless a row states otherwise:
- Developer adoption versus the economic buyer. Developer love can discover and insert a product, while budget authority, procurement, security, and enterprise sales decide monetization. Treat usage as a falsification/learning signal, not revenue proof. Selling note, Contradictions · Digital Infrastructure note, Contradictions
- Open source versus control and scale. Open source can create trust and distribution, but services burden, governance, cloud capture, and the paid control point determine venture economics. Separate community health from ownership and margin. Selling note, Contradictions · Software Chasms note, Contradictions
- Infrastructure transformation versus cloud consolidation. Casado first predicts startup opportunity as layers become programmable, then documents hyperscaler leverage and cloud COGS, and later reopens specialized workloads. Underwrite the workload-specific cost/performance curve and portability rather than a universal rebundling cycle. Trends note, Contradictions · Cloud Cost note, Contradictions
- Category creation versus trend alignment. Founder will and narrative can create a market, but a shrinking trend or absent financing path can turn the exercise into a decade-long death march. Require named buyers, budget formation, sales repetition, and runway. GTM note, Contradictions · 20VC note, Contradictions
- Software margins versus irreversible COGS. Early software rhetoric coexists with later cloud, inference, implementation, supervision, and next-model-training costs. Gross margin is an architecture and phase diagnostic, not a categorical software entitlement. Gross Margins note, Contradictions · Flywheel note, Contradictions
- Technical-founder preference versus commercial and domain leadership. Casado's systems formation sharpens technical diligence, while his own Nicira CEO decision and robotics-board admission show where sales, operations, or vertical expertise dominate. Record the missing competency and decision right rather than universalize founder type. Fear/Leadership note, Contradictions · Uncharted note, Contradictions
- Market-first search versus retrospective category selection. Space mapping can improve preparedness, but flexible market definitions make winners look inevitable after the fact. Preserve dated maps, passes, ranking changes, and losing categories. 20VC note, Contradictions · AI Boom note, Contradictions
- Contrarian product versus financing consensus. Non-consensus customer behavior can create the product opportunity; informed investor objections and the next financing audience are survival constraints. The rule is stage- and vehicle-specific and may favor a large networked firm. Non-Consensus note, Contradictions
- Model fragmentation versus oligopoly. Distillation, diminishing returns, and specialized tasks support fragmentation; capital intensity, subsidy, platform distribution, and vertical expansion support concentration. Define submarket, share, switching, and loss thresholds ex ante. E70 note, Contradictions · Monopolies note, Contradictions
- AI bootstrap versus durable moat. Model capability can create magical acquisition, but workflow, integration, data, marketplace, distribution, brand, or cost advantage must retain the user after model parity. Value Accrual note, Contradictions · AI Boom note, Contradictions
- Agent productivity versus systems limits. Code generation can remove accidental complexity, while correctness, memory, state, verification, and human review limit autonomous deployment. Measure end-to-end release quality and intervention, not generated tokens. Future Software note, Contradictions · Hard Limits note, Contradictions · Monopolies note, Contradictions
- Build policy versus harm and regulatory incidence. Casado favors investment and application-level rules; that does not establish which applications, liability regimes, market-power controls, export rules, or low-probability risks warrant intervention. America/AI note, Contradictions · Policy note, Contradictions
- Scaled specialist platform versus conflicts. Specialist coverage and multiple capital products can improve access and stage fit; they also enlarge category conflicts, signaling power, fees, and internal allocation questions. Separate teams are a control claim, not an audited conflict outcome. 20VC note, Contradictions · Future VC note, Contradictions · Monopolies note, Contradictions
- Capital flywheel versus circular financing. Used GPUs and rising model revenue show activity, not independent demand or return. Track end-customer cash, strategic recycling, training-adjusted margin, next-round dependence, and supplier credits. Flywheel note, Contradictions
- “1996” supercycle versus overbuild. Enterprise adoption lag may extend the cycle, while calendar analogy and utilization cannot rule out subsidized capacity or weak ROI. Define demand quality, capacity utilization, retention, and financing dependence before using the analogy. AI Boom note, Contradictions
Biography, decisions, vehicles, and attribution leads
The disciplined use of each lead is [researcher inference | strong] unless otherwise labeled.
| lead | spoken evidence | disciplined use |
|---|---|---|
| LLNL, intelligence, Stanford | Infrastructure, Biography and decision evidence; Hard Limits, Biography and decision evidence | Formation explains a systems lens; verify dates, programs, role scope, and team contribution independently. |
| Nicira problem discovery and survival | Infrastructure, Biography and decision evidence; Fear/Leadership, Biography and decision evidence | Retrospective account supports repeated customer/problem search during the 2008 downturn, not a contemporary decision log. |
| Open/proprietary organization | Selling, Biography and decision evidence | Named behavior is useful, but engineer identity, repository, decision date, and causal outcome are missing. |
| CEO transition | Fear/Leadership, Biography and decision evidence | Declining CEO, interim regret, and Mullaney hire show changed judgment; board, employee, customer, and Mullaney evidence is absent. |
| Founder-led strategic sales | Fear/Leadership, Biography and decision evidence | Large-deal participation is self-reported; recover deal identities, bookings, recognition, and counterfactual close rates. |
| Cloud-cost board practice | Gross Margins, Biography and decision evidence; Cloud Cost, Biography and decision evidence | Casado says boards tracked cost/reversibility; no company list, minutes, intervention, or outcome is public here. |
| Hugging Face usage correction | Digital Infrastructure, Biography and decision evidence | Rare learning evidence; retrieve the dated memo, ranking, sponsor, vote, price, and whether the update changed an investment. |
| Robotics/drone domain limit | Uncharted, Biography and decision evidence | Board exposure reportedly changed specialist coverage; identify companies, organization decision, and resulting selection record. |
| Almost 200 investments | Non-Consensus, Biography and decision evidence | Mixed direct/fund activity is not a person-level deal denominator, hit rate, or return series. |
| Infrastructure vehicle | Monopolies, Biography and decision evidence | Spoken ~$1.2B is rounded relative to the announced $1.25B; recover stage, ownership targets, reserves, checks, and realized cash flows. |
| Conflict rule | Future VC, Biography and decision evidence; Monopolies, Biography and decision evidence | “One mortal enemy,” map exclusions, and separate teams are stated controls; audit exceptions, pivots, recusals, declines, and founder experience. |
| Portfolio examples | Value Accrual, Biography and decision evidence; AI Boom, Biography and decision evidence | Cursor, World Labs, Hugging Face, and others demonstrate thesis exposure, not Casado-only source/sponsor/vote/ownership/return. |
The spoken corpus also contains unreconciled Nicira/VMware operating figures—approximately $600 million in some accounts and approximately $1 billion in the 2017 go-to-market talk. They may refer to different dates, measures, or business scopes; none is an audited Casado-specific outcome. [retrospective witness | provisional]. GTM note, Biography and decision evidence · 20VC note, Biography and decision evidence
Five sources to study first
The ranking is [researcher inference | strong], based on source completeness, mechanism density, self-correction, and direct decision evidence—not prestige.
- Software Chasms (2019), Takeaways — best bridge from technical-founder experience to repeated product, delivery, integration, open-source, and enterprise-sales tests; full publisher transcript.
- 20VC — Venture Model (2022), Takeaways — best direct account of space mapping, team debate, stage-specific vehicles, board-role limits, scenario planning, and scaled-firm advocacy.
- Past, Present, and Future of Digital Infrastructure (2022), Takeaways — best investor correction loop: usage over theory, workload specialization, consumption pricing, cloud cost, and open-standard boundaries.
- Entering Uncharted AI Territory (2024), Takeaways — best AI-era combination of economics, technical moat, category risk, domain-limit admission, and explicit willingness to be wrong.
- Is Non-Consensus Investing Overrated? (2025), Takeaways — best falsifiable decision-process discussion, with informed objections, financing consensus, stage/check-size boundary, and an unfinished promised cohort test.
On Fear and Leadership, Takeaways is the best biography-to-decision supplement; Monopolies vs. Oligopolies, Takeaways the best current ownership/conflict/AI-market supplement; and Capital Flywheel, Takeaways the best current capital/compute dependency supplement.
Evidence still missing
- No complete personal deal ledger, opportunity/pass denominator, dated market-map archive, IC memorandum set, partner vote/veto record, check/security/ownership schedule, reserve history, fund cash flow, loss series, or realized person-level attribution record surfaced. “Almost 200 investments” cannot support hit rate, MOIC, IRR, DPI, or alpha. [researcher inference | strong]. Non-Consensus note, Open questions · Source map, vehicle and deal-attribution records
- The corpus cannot show that specialization, technical formation, market mapping, usage sensitivity, consensus awareness, or a16z services caused better selection or returns. Needed evidence is an ex-ante scored cohort including passes, write-offs, missed winners, stage, access, price, ownership, and matched baselines. [researcher inference | strong]. 20VC note, Open questions · Future VC note, Open questions
- Developer adoption, open-source popularity, category narrative, and fast AI usage remain upstream signals. Buyer authority, paid control point, retention, direct-sales burden, conflict, gross margin, and capital intensity can break the conversion to venture outcomes. [researcher inference | strong]. Selling note, Open questions · Value Accrual note, Open questions
- No public cloud-repatriation crossover rule or AI gross-margin cohort supplies workload costs, discounts, staffing, depreciation, egress, migration, inference, retries, supervision, training allocation, or later outcome. [researcher inference | strong]. Cloud Cost note, Open questions · AI Pricing note, Open questions
- The model market can fragment, monopolize, or oligopolize depending on submarket definition, capital, subsidy, distillation, distribution, proprietary data, and switching. The talks supply competing mechanisms, not a settled outcome. [researcher inference | strong]. E70 note, Open questions · Monopolies note, Open questions
- “1996,” “no dark GPUs,” and AI capital-flywheel claims still need independent utilization, end-customer cash, revenue quality, strategic-credit, training-adjusted margin, and financing-dependence evidence. Private financing and infrastructure use are not investor proceeds. [researcher inference | strong]. AI Boom note, Open questions · Flywheel note, Open questions
- AI developer productivity needs task-level evidence across greenfield and mature codebases, time, defects, review, maintainability, deployment, and intervention. Casado's hands-on use and company anecdotes do not establish general productivity or labor displacement. [researcher inference | strong]. Future Software note, Open questions · Monopolies note, Open questions
- Policy advocacy lacks a complete application-risk taxonomy, causal incidence analysis, company-by-company financial-interest map, public-cost accounting, and triggers for changing position. Public investment and regulatory restraint are compatible only after objectives, externalities, authority, and accountability are specified. [researcher inference | strong]. America/AI note, Open questions · Policy note, Open questions
- The spoken record cannot establish that Nicira's permanent CEO hire, founder-led selling, open/proprietary split, cloud-cost monitoring, or a16z platform services caused success. Decision participants, contemporaneous documents, customers, employees, and counterfactuals remain thin. [researcher inference | strong]. Fear/Leadership note, Open questions
- The category-creation heuristics still lack a failed-category denominator, named portfolio outcome cohort, and evidence that delayed price, the $200,000–$300,000 direct-sales hurdle, or the three product-market-fit signals predict retention or returns. [researcher inference | insufficient public record]. Creating Category note, Open questions
[researcher inference | strong] The defensible spoken-corpus through-line is diagnostic rather than predictive: identify a technical discontinuity; map the workflow, user, buyer, and budget; let usage challenge the map; separate insertion from monetization; match leadership and sales motion to the bottleneck; document irreversible costs; and underwrite financing, ownership, conflicts, and supplier dependencies. The record supports that coherent operating system. It does not prove personal returns, complete attribution, policy welfare, or a settled AI market structure. Software Chasms, Takeaways · 20VC, Takeaways · Non-Consensus, Takeaways · Monopolies, Takeaways
Model 1: Map the market, then let observed use and relative diligence falsify the map
- Rule: A technical shift can reveal necessary workloads before the winning product is legible. A map narrows where to look; it cannot tell the investor which box becomes a durable company. Real deployments, retained use, budget, and relative company evidence must be allowed to overturn the taxonomy.
- Evidence status: [investor-stated · strong] for Casado's stated market-first search, “usage graph over theory” correction, and architecture-mapping practice; [researcher inference · moderate] for the combined procedure and any claim that it improved selection. No public comparative performance test exists.
- Provenance and origin: The intellectual root is Casado's network-systems work: begin with a technical discontinuity and the functions it makes possible, rather than a company name. In investing, the 2020 data-infrastructure essay turned that habit into explicit architecture blueprints after two years of research; the 2022 Past, Present and Future of Digital Infrastructure interview then supplied the important correction that Hugging Face's usage contradicted the team's theory; the 2022 venture-model and 2025 non-consensus interviews made market-first research and company-relative diligence explicit. 2020 architecture essay, opening through “Blueprints” · 2022 infrastructure interview, Casado at 00:29:03–00:31:48 · 2022 venture-model interview, 18:47–19:22 and 33:35–36:17
- Mechanism and reasoning: Mapping concentrates search and builds a common language for workload, buyer, incumbent response, and control point. Usage supplies a reality check. Comparing companies inside the same problem space makes team, product, go-to-market, and architecture differences more legible than a one-off “is this good?” judgment. Informed dissent reduces the risk that a senior partner's elegant map becomes the answer. Architecture essay, “Blueprints” and “Looking ahead” · Digital Infrastructure, Hugging Face correction at 00:29:03–00:31:48 · Venture-model interview, research/debate at 18:47–19:22 and 33:35–36:17 Assumptions: The discontinuity is real; the mapped workload is operationally necessary; public or diligence usage is not purely subsidized; comparable alternatives exist; the team can observe disconfirming evidence; and incentives allow the thesis to be revised rather than defended.
- Historical and vehicle context: This model spans Casado's operator formation in network systems, the 2020 architecture-mapping work, the 2022 Hugging Face correction, and 2025 investing-process interviews. 2020 architecture essay, opening and blueprints · 2022 correction, 00:29:03–00:31:48 · 2025 non-consensus debate, 00:06:38–00:11:04 Distributional, ActionIQ, and Astranis are public a16z thesis records, but none is mapped publicly to a specific fund, check, security, ownership target, reserve decision, or IC vote. Distributional · ActionIQ · Astranis Hugging Face is process testimony, not a disclosed deal or return.
- When to use: Use the model when its core uncertainty is decision-relevant and these signals can be observed: production use rather than pilots; repeated workload across customers; retained or expanding usage; a named buyer and budget; referenceability; lower total system complexity; a product surviving adjacent-platform bundling; an outlier whose use persists despite contradicting the initial theory. Do not use it as a selection or sizing rule when no independent workload/budget exists, usage is subsidy-driven, or consumer taste and regulation dominate technical topology.
- How to apply it: (1) Draw the current workflow and stack from actual deployments. (2) Mark necessary but unstable functions, independent budgets, incumbents, and likely bundling paths. (3) Build a same-problem comparison set, including a pass/do-nothing alternative. (4) gather retained-use, production, reference, and willingness-to-pay evidence. (5) Write the evidence that would erase a box or elevate an outlier. (6) Debate the strongest disconfirming case before discussing valuation and ownership. (7) Rebuild the map at each follow-on; never use sector coverage as portfolio construction.
- Examples:
- Documented process correction — Hugging Face. [documented behavior · moderate] Casado said the usage graph conflicted with the team's theory and taught them to trust observed adoption more. The account does not say whether a16z invested at that moment, who changed the decision, or what return followed. Casado at 00:29:03–00:31:48
- Documented diligence — Distributional. [investor-stated · strong] The announcement connects an existing SigOpt relationship with more than 25 customer interviews; that is market- and company-level triangulation, not proof the process selected the best company. Distributional announcement, founder relationship and interview paragraphs
- Documented diligence — ActionIQ. [investor-stated · strong] Casado tied prior Stanford knowledge of the founder to interviews with roughly a dozen enterprises about the customer-data problem. No alternative set, pass record, or deal economics is public. ActionIQ announcement, founder and enterprise-interview paragraphs
- Documented learning boundary — Astranis. [investor-stated · strong] Casado said he began outside his expertise and learned the satellite, regulatory, and market system before investing. A later supplier-caused mission anomaly tests the map but does not establish that the map caused the decision. Astranis announcement, “When we first heard” through board paragraph · Astranis anomaly, reproduced-failure paragraphs
- Evidence: The architecture essay establishes the map; the digital-infrastructure interview documents the usage-over-theory correction; the venture-model interview documents pre-deal research and internal debate; and the company posts establish only the named diligence facts. Architecture essay · Digital Infrastructure, 00:29:03–00:31:48 · Venture-model interview, 18:47–19:22 and 33:35–36:17 They do not prove causal selection skill or investor return. Exact evidence gaps: No original category maps used in a named IC; no company-comparison scorecards; no list of alternatives or passes; no vote/dissent record; no pre/post-Hugging Face process document; no matched mapped-versus-unmapped investment outcomes; and no ownership or return data showing economic value from the method.
- Limits, failure modes, and exception ledger: Limits and exceptions: Strong early use can be free, curiosity-driven, or concentrated; architecture maps can be self-fulfilling firm marketing; same-space comparison may miss an orthogonal entrant; and the public record contains no complete passes or category cohorts. Hugging Face is evidence of one correction, not a measured correction rate. Architecture mapping is least useful where consumer taste or regulation, rather than technical topology, determines the market. Failure modes: funding every box; confusing category salience with a company; privileging a partner's theory over deployment data; mistaking subsidized or free usage for demand; allowing a map to freeze while platform boundaries move; or using “market-first” to hide that no comparative company work was documented. Falsifiers: the workload disappears into a platform bundle; customers will not allocate a standalone budget; retained use collapses after subsidy or fashion; total integration burden rises; or repeated company comparisons show the mapped variable has no relationship to adoption, economics, or outcomes.
- Evolution and contradictions: The method moves from a founder-engineer's system map, to a 2020 category taxonomy, to a 2022 admission that adoption can defeat theory, to a 2025 emphasis on non-consensus relative judgment. The update is meaningful: maps become falsifiable search instruments rather than predictions. Architecture essay · Digital Infrastructure, 00:29:03–00:31:48 · Non-consensus debate, 00:06:38–00:11:04 · Relative diligence, 01:00:32–01:05:27 The live contradictions are preserved by the limits, adverse examples, and falsifiers above; later evidence does not retroactively enter an earlier decision.
- Modern VC translation (as of 2026-08-20): [researcher inference · strong] Transfers: map workflows and contract power, then require a dated map-change memo. Does not transfer: static taxonomies or architecture-as-capture. Changed assumptions: concentrated model/cloud suppliers, faster bundling, regulation, and physical-system dependencies. Observable signals: retained production use, an accountable buyer/budget, independent references, and survival after bundling. Likely misuse: financing every attractive box. Current grounded example: the 2026 Runta thesis makes agent-compute architecture investable only as a public thesis; it does not establish capture or return. Runta, relationship and agent-compute thesis
Model 2: Trace a continuous user-to-buyer-to-budget-to-expansion chain
- Rule: Product use proves that somebody can obtain value; it does not prove a company has a budget owner, procurement path, premium trigger, or profitable sales motion. An investable bottom-up business needs a continuous causal path from activation to retained use, within-account spread, buyer-approved purchase, and economic expansion.
- Evidence status: [investor-stated · strong] for Casado's repeated distinction between technical adoption and the buying center, plus the coauthored growth+sales and bottom-up-pricing frameworks; [researcher inference · moderate] for deal-level application and portfolio efficacy.
- Provenance and origin: The 2016 developer-selling discussion treated open source as a technical trust and insertion mechanism, not a complete business model. The 2019 Software Chasms interview sharpened bottom-up entry plus enterprise conversion. The 2020 Growth+Sales essay supplied six failure modes, and the 2021 pricing essay mapped the user journey through free, professional, team, and enterprise tiers. 2016 podcast, 06:47–16:27 · 2019 interview, 00:26:48–00:30:39 · Growth+Sales, “New buyer, new motion” and Failure Modes #1–#6 · Bottom Up Pricing, sections #1–#9
- Mechanism and reasoning: Low-friction use bypasses incumbent distribution and creates qualified accounts. Product telemetry identifies where value concentrates. Enterprise sales converts security, administration, compliance, support, and broader rollout into paid expansion. Pricing and packaging preserve continuity between the user's value and the buyer's economic reason to pay. Selling to Developers, 06:47–16:27 · Growth+Sales, “New buyer, new motion” and Failure Modes #1–#6 · Bottom Up Pricing, sections #1–#9 Assumptions: Users can adopt or influence adoption; product value is experienced before a full centralized purchase; retained activity predicts organizational value; a premium boundary exists; the paid metric scales with customer value; and sales/support cost fits deal size.
- Historical and vehicle context: The doctrine predates and crosses several a16z fund eras. Yubico's 2018 decision sits in the Fund V platform period. Yubico thesis · Fund V, allocation paragraphs Parsec's 2020 Series B closely follows the Fund VII announcement. Parsec thesis · Fund VII, opening Tackle's 2021 rounds occurred in a permissive financing regime, while Fivetran is another portfolio-customer sourcing example. Tackle Series B · Tackle Series C · 2021 Venture Monitor, Executive Summary · Fivetran No public source maps these checks to a vehicle or supplies compatible ownership and return data.
- When to use: Use the model when its core uncertainty is decision-relevant and these signals can be observed: retained activation; organic account penetration; users asking for administration/security/enterprise deployment; repeatable buyer identity; paid conversion without engagement collapse; expansion and referenceability; declining implementation per account; sales productivity after full ramp; value-aligned usage rather than bill shock. Do not use it as a mandatory bottom-up template for centralized systems of record, regulated or safety-critical deployments that require prior authorization, or any product with no credible premium/budget bridge.
- How to apply it: (1) Name user, champion, administrator, economic buyer, and procurement authority. (2) Measure independent time-to-value, cohort retention, and within-logo spread. (3) identify the event that creates enterprise value and the feature/control that can be charged for. (4) trace security, procurement, implementation, and contract steps. (5) segment CAC, payback, support, churn, and gross margin by self-serve and sales-assisted motions. (6) Test price and packaging with real buyers. (7) Hire sales because customers request wider deployment, not because free growth needs a revenue story.
- Examples:
- Documented application — Yubico. [investor-stated · strong] a16z used YubiKeys before investing, and Casado described broad practitioner references plus profitability/capital efficiency. This is unusually direct product truth, but public records omit conversion cohorts, price, and a16z economics. Yubico announcement, product-use, diligence, and board paragraphs
- Documented application — Parsec. [investor-stated · strong] Casado tracked the product from a 2017 demo and cited a loyal gaming community plus enterprise customers in several professional verticals before a16z led the 2020 Series B. The consumer-to-enterprise bridge was part of the public thesis; post-pandemic cohort and margin data were not. Parsec announcement, demo/customer and Series B paragraphs
- Documented application and adverse test — Tackle. [investor-stated · strong] A portfolio customer sourced the company, and the decision record cited 200-plus customers, references, growth, and low burn. Later company testimony that it overbuilt and separated 75 employees shows that customer pull did not by itself validate scalable economics. Tackle Series B thesis · Tackle company update, opening and “overbuilt” paragraphs
- Documented application — Fivetran. [investor-stated · strong] The announcement says repeated encounters with the product through portfolio companies helped establish demand. That supports portfolio-customer sourcing, not a complete user-to-budget cohort. Fivetran announcement, portfolio encounter and investment paragraphs
- Evidence: The developer-selling discussion establishes the user/buyer split; Growth+Sales and Bottom Up Pricing supply the funnel, failure modes, and packaging procedure; the four announcement records establish only their named sourcing and diligence facts. Selling to Developers, 06:47–16:27 · Growth+Sales · Bottom Up Pricing They do not prove causal selection skill or investor return. Exact evidence gaps: No deal-level funnel dashboards; no cohort retention, conversion, CAC/payback, expansion, or churn for the four cases; no record of rejected high-usage companies; no causal board actions; no matched bottom-up versus top-down outcomes; and no investment ownership/return record.
- Limits, failure modes, and exception ledger: Limits and exceptions: Centralized systems of record, safety-critical deployments, and regulated infrastructure may require top-down authorization before use. High-touch enterprise products can be sound businesses without bottom-up entry. Conversely, Yubico's hardware/security path and Parsec's acquisition do not prove the framework generalizes. The public examples are selected and understate products that achieved use but never monetized. Failure modes: free users without a budget owner; sales masking weak engagement; a paid pilot buying access to expertise rather than product; open-source popularity without a paid control point; services-heavy integration; pricing units disconnected from value; premature field sales; or product neglect after sales succeeds. Falsifiers: no common buyer after repeated deployments; paid cohorts retain no better than free cohorts; within-logo use does not expand; enterprise requirements force customer-specific product forks; gross profit cannot cover the required sales/support motion; or repricing destroys use because consumption was never economic value.
- Evolution and contradictions: The model develops from “developers are an adoption wedge” (2016), through a barbell enterprise-buying model (2019), into explicit funnel and packaging diagnostics (2020–2021), and then into 2025 AI pricing concerns where a unit of usage must include variable cost and outcome quality. Selling to Developers, 06:47–16:27 · Software Chasms, 00:26:48–00:30:39 · Growth+Sales · Bottom Up Pricing · AI pricing, Takeaways The live contradictions are preserved by the limits, adverse examples, and falsifiers above; later evidence does not retroactively enter an earlier decision.
- Modern VC translation (as of 2026-08-20): [researcher inference · strong] Transfers: trace active user → workflow owner → economic buyer → procurement → price → contribution. Does not transfer: seats, tokens, or raw task counts as value. Changed assumptions: agents add retries, human review, security approval, liability, and variable inference cost. Observable signals: paid expansion, budget transfer, stable completion quality, and declining intervention. Likely misuse: calling daily use a business. Current grounded example: the 2025 AI-pricing discussion treats seat-to-usage change as a live operating problem, not proof that a particular pricing unit works. AI Is Upending SaaS Pricing, 00:10–20:12 and 21:42–31:44
Model 3: Anneal product, buyer, and category before scaling the organization
- Rule: In a new market, product, user, buyer, budget, deployment, price, and category language are all uncertain and coupled. Scaling specialized functions before those variables converge amplifies noise. Founder-led customer work carries the most product context; a small number of generalists can then turn repeated patterns into a playbook.
- Evidence status: [investor-stated · strong] for the founder-led learning sequence and services-drift boundary; [investor-stated · provisional] for published ARR, timing, and staffing ranges; [researcher inference · moderate] for deal and outcome applications.
- Provenance and origin: Nicira supplied the operating lesson: OEM/partnership routes failed, and roughly two years of direct founder selling were required to learn a new category. The 2017 no-market and pricing talks converted that history into a discovery discipline. The 2019 Software Chasms interview separated execution failure from absent/premature product-market fit. The 2023 Market Annealing essay named the model and sequenced founders, a few generalist “renaissance reps,” and later specialization; the 2024 interview limited it explicitly to category creation. Software Chasms, 00:08:10–00:11:36 · Pricing podcast, 07:20–13:51 · Market Annealing, founder-led selling through scaling sequence · Uncharted, 00:42:28–00:45:45
- Mechanism and reasoning: Each live sale tests product and market hypotheses at once. Repeated use cases reduce the search space; reusable implementation and a common buyer shorten cycles; references lower education cost. Specialization becomes productive only after the information being handed off is stable enough to replicate. Software Chasms, 00:08:10–00:11:36 · Market Annealing, founder-led selling through scaling sequence Assumptions: The company is truly creating a category rather than entering a mature one; founders can sell and update product; customer work can converge on reusable functionality; early salespeople report bad news; and financing runway is long enough to learn without making endless exploration costless.
- Historical and vehicle context: Nicira is the founder/operator origin and must remain outside Casado's venture-selection denominator. Software Chasms, 00:08:10–00:13:19 The illustrations span Tecton's 2018 seed and 2020 Series A, Parsec's 2020 Series B, and Tackle's 2021 Series B and preemptive Series C. Tecton, customer and seed/Series A paragraphs · Parsec, Series B/board paragraph · Tackle Series B · Tackle Series C The Tackle follow-on occurred inside the 2021 financing boom. 2021 Venture Monitor, Executive Summary No public record assigns deal-specific vehicles, internal alternatives, reserve gates, or board votes.
- When to use: Use the model when its core uncertainty is decision-relevant and these signals can be observed: three or more repeat deployments sharing a use case and buyer; declining customer-specific engineering; shorter and less founder-dependent cycles; repeatable price/value language; references; successful generalist-rep ramp; stable implementation; and fully loaded quota contribution after the playbook exists. Do not use it to excuse indefinite bespoke work, to delay ordinary execution in a mature category with known buyers, or after dated convergence tests repeatedly fail.
- How to apply it: (1) Freeze the unknowns: painful use case, user, buyer, budget, deployment, price, and category language. (2) Set a dated experiment for each. (3) Keep founders in sales/product feedback until repeated evidence emerges. (4) Add a small number of generalists who can create, not merely execute, the playbook. (5) Measure reuse, customization, referenceability, cycle time, implementation, and rep ramp. (6) Add specialized sales/marketing/customer-success capacity only after convergence. (7) Stop or change model if revenue grows while reuse falls.
- Examples:
- Documented origin case — Nicira. [retrospective witness · strong] Casado says OEM and partner distribution failed and founder-led direct selling resolved the causal question. This is founder/operator learning, not a venture-selection success. Software Chasms, 00:08:10–00:13:19
- Researcher-applied illustration — Tecton. [researcher inference · moderate] The 2020 announcement says a16z invested at seed in 2018 and again at Series A after engagement with ML teams and production feature-store demand. It is consistent with staged evidence release, but no public milestone memo or reserve gate exists. Tecton announcement, customer and seed/Series A paragraphs
- Researcher-applied illustration — Parsec. [researcher inference · moderate] Casado's multi-year observation from 2017 to the 2020 Series B fits learning before commitment, but the public record does not show product/buyer convergence measures. The acquisition nine months later leaves the standalone scaling thesis unresolved. Parsec announcement · Unity 10-K, Note 6
- Adverse illustration — Tackle. [researcher inference · strong] Strong early customer evidence and a preemptive Series C preceded admitted overbuilding. The case demonstrates why a new round must re-test repeatability, services content, and no-new-capital runway rather than simply extrapolate growth. Acquisition terms remain unknown, so this is an operating miss, not a proven investor loss. Tackle Series C, preemptive/scaling paragraphs · company update
- Evidence: The Nicira interview establishes the founder-led discovery origin; Market Annealing supplies the explicit sequence; the Tecton, Parsec, and Tackle records are labeled applications or adverse illustrations rather than proof of the model. Software Chasms, 00:08:10–00:13:19 · Market Annealing · Tackle update They do not prove causal selection skill or investor return. Exact evidence gaps: No named company cohort behind the 2023 thresholds; no failed-company denominator; no actual board staffing decisions tied to the model; no customer-level longitudinal data; no proof Tecton/Parsec used this process; no Tackle board vote or intervention record; and no outcome/return comparison for companies that scaled before versus after convergence.
- Limits, failure modes, and exception ledger: Limits and exceptions: Bottom-up products can reach repeatability without prolonged founder selling; regulated or complex categories may require domain sellers early; a rapid demand shock can make slow learning costly; and the essay's selected-company observations lack a failure denominator. Nicira is retrospective and success-selected. Tackle shows that early fit can coexist with later organizational error. Failure modes: treating bespoke services as discovery forever; using paid pilots as proof of demand; hiring route sellers for a nonexistent route; scaling marketing before category language works; founder charisma hiding nonrepeatability; survivalist underinvestment after the inflection; or applying category-creation patience to an ordinary market with clear comparables. Falsifiers: no convergence in product/buyer/deployment by the precommitted date; each customer needs a core fork; non-founder reps cannot reproduce wins; sales cycle and implementation do not improve; references do not create follow-on demand; or a mature incumbent category already supplies the buyer and budget, making “annealing” an excuse for weak execution.
- Evolution and contradictions: The early lesson was direct selling to discover demand. By 2019 it became a diagnostic separating execution from PMF. In 2023 it became an organizational sequence. In 2024 Casado added a boundary: use annealing for category creation, not as a universal company-building ritual. Software Chasms, 00:08:10–00:11:36 · Market Annealing · Uncharted, 00:42:28–00:45:45 The live contradictions are preserved by the limits, adverse examples, and falsifiers above; later evidence does not retroactively enter an earlier decision.
- Modern VC translation (as of 2026-08-20): [researcher inference · strong] Transfers: founder-led learning, convergence dashboards, and dated stop tests. Does not transfer: the essay's historical ARR/staffing ranges as universal gates. Changed assumptions: AI accelerates demos, code, and outbound activity while models and categories change faster. Future of Software Development, Takeaways Observable signals: reusable deployment, buyer recurrence, shorter cycles, declining review burden, and fully loaded rep productivity. Likely misuse: endless exploration disguised as speed. Current hypothetical: an agent startup should not scale field sales until three repeat deployments share workflow, buyer, and implementation; this is an analyst test, not a documented Casado deal.
Model 4: Underwrite the monetizable control point, not the technical layer or open-source adoption alone
- Rule: A technically important layer can be economically weak. Open source or a model API can create adoption while clouds, model suppliers, distributors, or customers capture the value. A venture-scale company needs a defensible point where operational necessity, customer relationship, switching cost, and the right to charge coincide.
- Evidence status: [investor-stated · strong] for the distinction among developer adoption, open-source insertion, operated service, and paid boundary; [researcher inference · strong] for converting architecture and GenAI stack maps into a bargaining-power test; [researcher inference · moderate] for case outcomes.
- Provenance and origin: At Nicira, Casado dealt directly with open/proprietary roadmap conflict and put strong engineering talent on the open project while separating teams under a senior arbiter. The 2016 developer/open-source and microservices discussions framed open source as distribution and technical trust rather than monetization. The 2020 data-stack essay looked for necessary unstable control points; the 2023 GenAI platform essay extended the map to compute, models, and applications; the 2024 interview said durable AI moats would migrate toward workflow, integration, community, distribution, and brand rather than model access alone. Selling to Developers, 11:35–24:58 · 2020 architecture essay · GenAI platform essay · Uncharted, 00:26:00–00:30:31
- Mechanism and reasoning: Technical insertion creates trust and lowers adoption friction. Workflow depth, operation, integration, security, proprietary control, community, distribution, and contracts can then create switching cost and pricing power. Supplier and platform concentration can reverse that power even when the product remains technically central. Selling to Developers, 11:35–24:58 · Data architecture, control-point framework · GenAI platform, stack economics Assumptions: The workload remains independently necessary; customers value the operated/integrated product; the paid boundary does not destroy community trust; contracts permit multi-supplier or migration options; and an incumbent cannot cheaply bundle the function or appropriate demand information.
- Historical and vehicle context: The operating origin is Nicira's open/proprietary product organization, not an investment. Selling to Developers, 20:42–24:58 Isovalent and Tecton are 2020 public thesis records; Cursor is a four-person 2024 a16z thesis and current board claim. Isovalent thesis · Tecton thesis · Cursor thesis, byline and model-choice paragraphs Cisco completed Isovalent's acquisition; Databricks had announced, but not completed at the cutoff, Tecton's transaction; and Cursor later entered an all-stock merger. Cisco completion, opening paragraphs · Databricks announcement, opening · SpaceX 8-K, Item 1.01 These are company events, not fund-return evidence; vehicle, ownership, and proceeds remain unknown.
- When to use: Use the model when its core uncertainty is decision-relevant and these signals can be observed: production-critical operation; durable independent budget; broad integrations but low customer migration; user trust converting to paid administration/security/service; falling supplier concentration; contractual portability; expansion around workflow; and survival after adjacent bundling. Do not use it when the layer has no independent budget, remains a replaceable feature, cannot preserve a paid boundary, or is economically controlled by one supplier or bundling platform.
- How to apply it: (1) Draw technical and contractual stack maps. (2) For every layer, identify supplier, user, buyer, budget, operator, data access, distribution, and switching rights. (3) Distinguish free/open insertion from the thing customers pay to operate or control. (4) Test dependence on a dominant cloud/model/distributor and the platform's ability to observe and bundle. (5) Model replacement and portability. (6) Assign milestones for workflow depth, enterprise control, gross margin, and supplier diversification. (7) Kill the deal if the company remains a replaceable feature with no independent budget.
- Examples:
- Documented operating application — Nicira's open/proprietary organization. [investor-stated · strong] Casado described separate teams and a senior arbiter to protect the adoption and paid roadmaps. The source omits the project, economics, and comparative outcome. Selling to Developers, 20:42–24:58
- Documented thesis — Isovalent. [investor-stated · strong] The a16z post identifies eBPF/Cilium as an open, operational control point in networking, observability, and security; Cisco later completed an acquisition with terms undisclosed. That outcome is consistent with strategic control-point value, not proof of a16z return. Isovalent thesis · Cisco completion
- Documented thesis — Tecton. [investor-stated · strong] The post frames feature stores and production ML data as a necessary control point and records seed plus Series A support. Databricks later announced that Tecton would join it, but completion and terms were not public at the cutoff; strategic fit is not realized-return evidence. Tecton announcement · Databricks announcement
- Researcher-applied illustration — Cursor. [researcher inference · moderate] The 2024 thesis relied on high-frequency coding workflow and retained use despite externally supplied models. The later all-stock SpaceX transaction is an exceptional company event but does not reveal whether workflow power overcame supplier economics as a standalone business. Cursor thesis · SpaceX 8-K, Item 1.01
- Evidence: The developer/open-source discussion establishes insertion and organizational conflict; the architecture and GenAI essays establish the control-point and bargaining-power maps; the company and acquirer records establish only the named theses and events. Selling to Developers, 11:35–24:58 · Data architecture · GenAI platform · Cisco completion They do not prove causal selection skill or investor return. Exact evidence gaps: No project-level Nicira economics; no public supplier/customer contracts; no switching-test data; no independent-budget cohorts; no Isovalent/Tecton/Cursor entry ownership or proceeds; no comparison against mapped control points that were bundled or failed; and no evidence that Casado's abstract stack model caused those selections.
- Limits, failure modes, and exception ledger: Limits and exceptions: Some commodity layers produce excellent cash flows through scale; some open-source projects monetize through services without venture economics; strategic acquisitions can reward a weak standalone control point; and contractual power can move without any visible architecture change. The portfolio examples are success-selected, while Orbit's acquired-and-sunset product shows that acquisition does not preserve an independent control point. Postman, acquisition and 90-day sunset paragraphs Failure modes: equating GitHub stars with economics; open-source/proprietary roadmap conflict; services-heavy monetization; moving up-stack into fragmented demand; single-model or single-cloud dependence; platform copying; customer multi-homing; or confusing an acquisition by an incumbent with proof of standalone value capture. Falsifiers: the platform bundles the function and customers churn; no paid premium survives; switching tests are easy and common; one supplier can change price/terms enough to erase margin; integration work scales linearly with customers; or the independent budget disappears.
- Evolution and contradictions: The model advances from internal open-source governance to market insertion, then to architecture control points, and finally to a combined technical/contractual bargaining-power view in AI. Casado's 2024 moat migration claim narrows earlier enthusiasm for model-layer novelty. Selling to Developers, 11:35–24:58 · Data architecture · GenAI platform · Uncharted, moat migration at 00:26:00–00:30:31 The live contradictions are preserved by the limits, adverse examples, and falsifiers above; later evidence does not retroactively enter an earlier decision.
- Modern VC translation (as of 2026-08-20): [researcher inference · strong] Transfers: map technical and contractual control, commercial attach, and failover. Does not transfer: open-source adoption or present model scarcity as automatic capture. Changed assumptions: cloud credits, model-routing rights, exclusivity, revenue share, and platform vertical expansion. Observable signals: independent budget, paid attach, neutral governance, real failover, and durable workflow ownership. Likely misuse: calling GitHub stars or a bottleneck a moat. Current grounded example: Cursor's 2026 transaction is an exceptional workflow-level company event, but it still does not disclose standalone supplier economics or a16z return. SpaceX 8-K, Item 1.01
Model 5: Buy option value under uncertainty; specialize or internalize only when workload economics stabilize
- Rule: Flexible external infrastructure is valuable when demand, product, and hardware needs are uncertain. Once a workload is predictable, the provider's margin, egress, and control can outweigh flexibility. The right answer is not “cloud” or “owned”; it is a staged comparison for each workload after counting migration, idle capacity, staff, capital, facilities, and reliability.
- Evidence status: [investor-stated · strong] for the lifecycle and workload-specific rule; [investor-stated · provisional] for the original aggregate cloud-value estimates; [researcher inference · strong] for the 2026 hybrid decision procedure; [researcher inference · moderate] for portfolio applications.
- Provenance and origin: The 2021 Cost of Cloud essay argued that public cloud has high early option value but can become a material cost of revenue at scale. The 2022 infrastructure essay argued that hyperscaler abstractions also enable specialized vertical infrastructure. The 2022 interview described an unpublished cloud-versus-self-host counterfactual model. The 2023 compute essay expanded choices to hosted, reserved, specialized, and owned capacity, while the 2024 interview added the fiber-glut warning: secular demand can be real and supply investment badly timed. Cost of Cloud, “The paradox” through repatriation decision · Cloud Killed Infrastructure, conditions and conclusion · 2022 interview, 00:06:49–00:19:42 · High Cost of AI Compute · Uncharted, 00:03:33–00:04:43
- Mechanism and reasoning: Renting converts fixed capital and provisioning risk into variable expense and accelerates learning. Reservation/specialization/internalization can capture utilization and hardware advantages after variance falls. Portability and contracts preserve bargaining power while the firm learns. Timing error creates stranded capacity or permanent lock-in. Cost of Cloud, lifecycle and objections · Cloud Killed Infrastructure, specialization conditions · High Cost of AI Compute, decision framework Assumptions: Workloads can be measured independently; demand eventually becomes forecastable; the company can negotiate or migrate; specialized hardware/software creates real unit-cost advantage; reliability and staffing costs are observable; and financing duration matches the payback period.
- Historical and vehicle context: The written rule developed from the 2021 cloud-cost framework through the AI-capacity cycle. Cost of Cloud · High Cost of AI Compute Dropbox is an external public-company example rather than a Casado deal. Dropbox FY2025 10-K, MD&A pp. 57–59 Parsec, Cursor, and Astranis are researcher-applied portfolio illustrations with different workload and capital profiles. Parsec · Cursor · Astranis Their public records do not identify the responsible vehicle, negotiated infrastructure terms, ownership, reserves, or realized proceeds.
- When to use: Use the model when its core uncertainty is decision-relevant and these signals can be observed: stable utilization; predictable workload mix; large provider margin; short modeled payback after all costs; successful portability test; multiple suppliers; improving reserved-price capture; high data gravity with long duration; and financing runway through deployment. Do not use it to justify internalization while demand is volatile, when all-in savings vanish after migration/reliability/capital costs, or when payback exceeds the product and financing horizon.
- How to apply it: (1) Segment workloads by latency, variability, data gravity, hardware, security, and sovereignty. (2) Calculate current all-in unit cost, including egress and labor. (3) Model hosted/on-demand, reserved, specialized-cloud, contracted, and owned cases with utilization ranges. (4) Include migration capital, reliability staff, depreciation, facilities, fallback capacity, and opportunity cost. (5) Run supplier-failure and demand-downside cases. (6) Preserve portability until savings exceed the migration hurdle with margin of safety. (7) Re-test before every large capacity commitment.
- Examples:
- Documented external case and counterexample — Dropbox. [contemporaneous record · strong] The 2021 essay used Dropbox as a repatriation illustration. Dropbox's FY2025 filing later reported gross margin declining from 83% to 80% amid infrastructure-refresh and facilities costs, falsifying any simple “owned is permanently cheaper” rule. It does not invalidate workload-specific internalization. 2021 essay, Dropbox case · Dropbox FY2025 10-K, MD&A pp. 57–59
- Researcher-applied illustration — Parsec. [researcher inference · moderate] Low-latency remote graphics makes egress, GPU utilization, reliability, and cloud concentration decision-critical. The public decision record does not disclose them, and Unity's later cash acquisition cannot validate the missing workload economics. Parsec thesis · Unity 10-K, Note 6
- Researcher-applied illustration — Cursor. [researcher inference · moderate] External models and compute gave the 2024 product speed and optionality, while creating supplier and per-task cost exposure. The public record does not establish whether infrastructure strategy later changed or whether workload economics improved. Cursor Series A thesis
- Researcher-applied illustration — Astranis. [researcher inference · moderate] Dedicated satellite manufacture, launch, supplier, and debt commitments are the physical extreme of an option-versus-specialization decision. A mission anomaly and replacement response provide operational evidence, not proof that capital was sized correctly. Astranis investment thesis · Astranis anomaly, failure and fix
- Evidence: The cloud-cost, specialization, and AI-compute essays establish the staged workload framework; Dropbox's filing and the claim-local deal records provide examples and counterevidence rather than a matched outcome cohort. Cost of Cloud · Cloud Killed Infrastructure · High Cost of AI Compute · Dropbox FY2025 10-K, MD&A pp. 57–59 They do not prove causal selection skill or investor return. Exact evidence gaps: The unpublished company-level counterfactual model; actual negotiated cloud/compute terms; named workload cost studies; engineering and reliability allocations; migration outcomes; specialist-provider failure data; deal-specific capacity covenants; and any evidence tying the model to venture returns.
- Limits, failure modes, and exception ledger: Limits and exceptions: Stable workloads may still favor cloud because negotiated discounts, reliability, and opportunity cost dominate. Owned systems can suffer refresh cycles, idle capacity, and facilities expense. Hardware-heavy companies cannot always preserve cheap options. The 2021 aggregate estimates and unpublished 2022 counterfactual model are not reproducible; Dropbox is one bundled operational case. Failure modes: ideological repatriation; company-wide decisions instead of workload segmentation; excluding labor/reliability/capital; forecasting peak demand; cloud commitments that destroy optionality; specialist providers with thin balance sheets; or financing a secular-demand thesis at a cyclical overbuild peak. Falsifiers: savings vanish under realistic utilization; migration payback exceeds product/financing horizon; reliability falls; supplier concentration rises; the workload changes faster than dedicated capacity can adapt; or customer/sovereignty constraints prevent the proposed architecture.
- Evolution and contradictions: The argument starts as cloud lifecycle economics, expands to specialized infrastructure opportunity, then to AI accelerator procurement and macro overbuild timing. The more mature version is a portfolio of workload options, not a repatriation slogan. Cost of Cloud · Cloud Killed Infrastructure · High Cost of AI Compute · Uncharted, overbuild at 00:03:33–00:04:43 The live contradictions are preserved by the limits, adverse examples, and falsifiers above; later evidence does not retroactively enter an earlier decision.
- Modern VC translation (as of 2026-08-20): [researcher inference · strong] Transfers: price flexibility as an option and stage specialization behind measured workload economics. Does not transfer: “cloud bad,” permanent repatriation savings, or average utilization. Changed assumptions: accelerator obsolescence, power/interconnect, sovereignty, model routing, and provider solvency. Observable signals: utilization distributions, portability tests, short all-in payback, supplier alternatives, and funded duration. Likely misuse: financing peak capacity from a secular-demand story. Current grounded example: Astranis' 2026 equity/debt financing funds a physical capacity system but does not prove capital sizing or return. Astranis Series E/debt, opening capital paragraphs
Model 6: Underwrite quality-adjusted contribution margin per completed task
- Rule: Revenue per attempt, seat, or token can obscure whether the product completes economically valuable work. Retries, model cascades, human review, support, implementation, and failures belong in the denominator. Gross margin can improve, but expected deflation is not a substitute for a measurable path.
- Evidence status: [investor-stated · strong] for the AI cost taxonomy and margin-bridge mechanisms; [investor-stated · provisional] for the 2020 private-company percentage ranges; [researcher inference · moderate] for the exact metric and named deal applications because no public portfolio dashboard exists.
- Provenance and origin: The 2020 New Business of AI essay argued that inference, retraining, human review, implementation, and customer-specific edge cases make many AI companies economically unlike classic software. The 2023 economic essay added a task-tolerance test: capability is not useful economics when failure, evaluation, and workflow adaptation remain costly. The 2023 compute essay made procurement part of cost of revenue. The 2025 margin essay argued that low early margins can improve through routing, tiering, repricing, and enterprise mix—but only with an explicit bridge. New Business of AI, gross-margin and scaling sections · Economic Case for GenAI · High Cost of AI Compute · Questioning Margins
- Mechanism and reasoning: Narrower tasks and better evaluation reduce errors and review; routing sends simple work to cheaper models; caching/batching and negotiated compute reduce inference cost; reusable deployment reduces services; pricing/tiering aligns revenue with delivered value. Each change should improve contribution per accepted completed task, not merely reported utilization. New Business of AI, cost taxonomy and scaling · Economic Case for GenAI, task-tolerance framework · Questioning Margins, operating levers Assumptions: Completed-task quality can be defined; failed attempts and review can be measured; customers value the output enough to pay; cost declines are not fully passed through; workflow integration is reusable; and the company retains some pricing or routing control.
- Historical and vehicle context: The 2020 framework came from an unnamed private-company interview sample before foundation-model economics changed the workload; the 2023 and 2025 updates respond to those changes rather than erase the earlier accounting rule. New Business of AI, “Gross Margins” and “Scaling AI systems” · Economic Case for GenAI · Questioning Margins Cursor, Tackle, and Parsec are deal illustrations; Snowflake is an external counterexample. Cursor · Tackle · Parsec · Snowflake FY2025 10-K, MD&A pp. 70–71 None supplies a Casado/a16z cost basis, portfolio margin dashboard, vehicle allocation, or realized return.
- When to use: Use the model when its core uncertainty is decision-relevant and these signals can be observed: lower retry and intervention rates; stable accepted-output quality; decreasing compute and support per success; reusable deployment; positive cohort contribution; value-aligned price; better enterprise mix without hidden services; and observed, not assumed, routing savings. Do not use it as a single margin veto where the task inherently requires a coherent services component, or when accepted output cannot be defined; in those cases use a broader customer-value and cash-contribution test.
- How to apply it: (1) Define the accepted output and customer value. (2) Count attempts, retries, latency, review, escalation, support, implementation, inference/training, storage, and third-party fees. (3) Compute revenue and contribution per accepted completed task by use case/customer. (4) stress model price, error rate, and usage mix. (5) Specify a dated margin bridge with owner and milestone for routing, tiering, automation, pricing, or mix. (6) re-underwrite negative-margin customers and customer-specific forks. (7) Stop if scale worsens quality-adjusted economics without a validated repair.
- Examples:
- Researcher-applied illustration — Cursor. [researcher inference · moderate] Paid developer pull is strong evidence, but the 2024 freeze omitted inference-adjusted margin, retries, useful-task completion, and supplier concentration. The later company outcome cannot retroactively fill those unit economics. Cursor thesis · SpaceX 8-K, Item 1.01
- Adverse illustration — Tackle. [researcher inference · moderate] Marketplace volume and customer count did not disclose software/services mix, take rate, gross margin, implementation labor, or CAC payback. The later overbuilding admission makes those omissions decision-relevant, while completed-acquisition terms leave investor outcome unknown. Tackle thesis · Tackle company update · Tackle issuer status
- Researcher-applied illustration — Parsec. [researcher inference · moderate] Low-latency graphics creates an obvious quality/cost denominator: successful session quality after GPU, bandwidth, egress, support, and enterprise security. None of those figures is public in the deal record. Parsec announcement
- Grounded external counterexample — Snowflake. [contemporaneous record · strong] Snowflake's FY2025 filing documented gross-margin compression; it is a useful warning against automatic margin expansion, not a matched AI-startup application or a Casado investment outcome. Snowflake FY2025 10-K, MD&A pp. 70–71
- Evidence: The 2020 AI-business essay establishes the cost taxonomy; the 2023 economic and compute work updates task economics; the 2025 margin essay supplies possible repair levers; the examples remain illustrations without a portfolio cohort. New Business of AI · Economic Case for GenAI · High Cost of AI Compute · Questioning Margins They do not prove causal selection skill or investor return. Exact evidence gaps: Names and denominator of the 2020 sample; company-level cost allocation; accepted-task definitions; retry/review/implementation cohorts; actual margin bridges and board milestones; price elasticity; failed AI investments behind Casado's “bloodbath” remark; and matched returns by quality-adjusted margin.
- Limits, failure modes, and exception ledger: Limits and exceptions: Low-margin products can be valuable when the market is enormous, capital is patient, or services create a defensible compound system. High gross margin can hide weak retention or customer value. “Completed task” may be ambiguous in creative/interactive products. The original 50–60%, 25%+, and 10–15% observations come from an unnamed early-company sample and must not be treated as 2026 base rates. Failure modes: counting tokens/tasks as value; excluding review or implementation from cost of revenue; assuming model prices always fall; customer-specific ML backlogs; using revenue growth to hide gross loss; per-seat pricing when agents do the work; outcome pricing without reliable attribution; or preserving usage by subsidizing uneconomic heavy users. Falsifiers: cost per accepted result does not fall with scale; review/escalation remains structurally high; customers reject output or will not pay; price competition captures all cost deflation; deployment/support grows linearly; or margin improvement depends only on an uncontracted future supplier price.
- Evolution and contradictions: Casado's early view emphasized structural AI cost and services drift. The foundation-model update allowed more tasks to become economical. The 2025 view became less categorical about current margin but more demanding about the bridge. The durable element is accounting discipline, not a fixed software-margin threshold. New Business of AI · Economic Case for GenAI · Questioning Margins The live contradictions are preserved by the limits, adverse examples, and falsifiers above; later evidence does not retroactively enter an earlier decision.
- Modern VC translation (as of 2026-08-20): [researcher inference · strong] Transfers: measure revenue and every variable/semi-variable cost per accepted customer outcome. Does not transfer: fixed classic-SaaS margin thresholds or assumed model-cost deflation. Changed assumptions: agents add retries, tool calls, runtime, human escalation, and warranty/error cost. Observable signals: stable accepted quality, falling intervention and cost per success, reusable deployment, and contracted pricing. Likely misuse: counting tokens or attempts as value. Current grounded example: the 2025 margins essay offers routing/tiering/repricing mechanisms, but no named company bridge proves them. Questioning Margins, “The margin question” through operating levers
Model 7: Treat financing timing, ownership, and downside scenarios as part of the product thesis
- Rule: Venture outcomes depend not only on product truth but also on how much capital is raised, at what price and seniority, what ownership is preserved, which milestones it buys, and whether reserves survive the downside. Too little capital can kill a correct thesis before the market forms; too much or too easy capital can accelerate hiring/capacity ahead of repeatability and reduce future flexibility.
- Evidence status: [investor-stated · strong] for ownership as a binding venture variable, scenario debate, and the danger of both under- and over-capitalization; [researcher inference · moderate] for the integrated model; [researcher inference · insufficient public record] for Casado's actual deal ownership, reserve, and governance practice.
- Provenance and origin: Nicira's 2008 survival at roughly twelve people and later difficulty reversing austerity supplied the two-sided operating lesson. The 2022 venture-model interview described stage-specific teams, scenario planning, and vigorous debate rather than precision forecasting. The 2024 overbuild warning separated secular demand from investment timing. The 2025 monopoly/oligopoly interview made ownership and fund math explicit. The 2026 AI capital-flywheel discussion made financing, compute, capability, demand, and revenue interdependent while warning that deployed GPUs alone do not prove durable demand. Software Chasms, 00:59:12–01:01:27 · 2022 venture-model interview, 14:15–15:33 and 23:00–29:23 · Uncharted, 00:03:33–00:04:43 and 00:50:34–00:52:34 · 2025 ownership/fund math, 53:38–57:09 · 2026 Latent Space capital flywheel, 03:19–11:24
- Mechanism and reasoning: Scenario-based financing connects a tranche to technical, customer, regulatory, or economic uncertainty reduction. Ownership determines whether even a successful company matters to a fund. Reserves provide option value when evidence improves. Downside runway and covenant/structure analysis prevent a financing mark from being confused with value creation. Software Chasms, 00:59:12–01:01:27 · Venture-model interview, 14:15–15:33 and 23:00–29:23 · Ownership/fund math, 53:38–57:09 Assumptions: Milestones can be defined and verified; capital actually retires named risks; the investor can obtain terms commensurate with uncertainty; financing markets may close; follow-on rights are usable; and governance can change spend when evidence disappoints.
- Historical and vehicle context: Nicira supplies operator evidence about survival and reinvestment. Software Chasms, 00:59:12–01:01:27 The 2022 venture-model interview describes stage-specific teams and scenario planning; the 2025 monopoly/oligopoly interview ties ownership to fund math and refers to an approximately $1.2 billion infrastructure fund, versus the announced $1.25 billion Fund IX Infrastructure vehicle. Venture-model interview, 14:15–15:33 and 23:00–29:23 · Ownership/fund math, 53:38–57:09 · Fund IX, allocation paragraph Tackle, Astranis, Tecton, and World Labs supply financing or operating illustrations, but no source maps them to that vehicle or discloses check, security, ownership, reserves, preference stack, or proceeds. Tackle Series C · Astranis financing · Tecton · World Labs financing
- When to use: Use the model when its core uncertainty is decision-relevant and these signals can be observed: milestone delivery per dollar; longer runway without slower learning; stable/improving burn multiple; validated technical/regulatory gates; repeatable customer cohorts; financing alternatives; preserved pro rata/ownership; management willing to cut before liquidity forces it. Do not use it as a rigid ownership or tranching formula when milestones cannot be measured, when strict staging would destroy exploration value, or when the ownership target would force a pass on an exceptional company without improving fund downside.
- How to apply it: (1) Write base, upside, and survival cases using only decision-date information. (2) Define what the round buys and the risk retired per dollar. (3) model post-money ownership, dilution, preference/seniority, pro rata, reserves, time to next evidence, and no-new-capital runway. (4) Tie hiring/capacity to repeatability or technical milestones. (5) Define board-level spend triggers, pauses, and stop criteria. (6) Re-underwrite a preemptive round as a new deal. (7) Keep financing amount, valuation, company event, fund proceeds, and realized distributions separate.
- Examples:
- Documented origin tension — Nicira. [retrospective witness · moderate] Casado credits austerity with survival through 2008 and says it later made reinvestment difficult. The case supports two-sided capital timing, not a venture return calculation. Software Chasms, 00:59:12–01:01:27
- Adverse application — Tackle. [documented behavior · strong] The issuer described its 2021 Series C as preemptive and planned aggressive scaling; it later admitted overbuilding and separated 75 employees. This is direct operating evidence for re-underwriting easy capital. The completed acquisition has undisclosed terms, so loss, return, and recovery cannot be inferred. Tackle Series C · Tackle update · Tackle issuer status
- Researcher-applied illustration — Astranis. [researcher inference · moderate] Satellite manufacture, launch, regulation, suppliers, customers, debt, and replacement missions create explicit capital milestones. Public financing and mission records show activity, not ownership quality or return. Astranis thesis · Astranis anomaly · Astranis Series E/debt
- Documented repeat-financing record — Tecton. [investor-stated · strong] The announcement records a16z seed support in 2018 and a Series A after further customer/production evidence. It does not disclose checks, valuations, reserve policy, or whether evidence formally unlocked the second check. Tecton announcement, final two paragraphs
- Researcher-applied illustration — World Labs. [researcher inference · provisional] The company later announced $1 billion of new financing. That is capital raised, not valuation, company value, or a16z return, and the public record does not expose capacity milestones or ownership. World Labs financing announcement, opening paragraph
- Evidence: The Nicira account establishes the capital-timing tension; the venture-model and monopoly/oligopoly interviews establish scenario, vehicle, ownership, and fund-math claims; the company records establish only named financing or operating facts. Software Chasms, 00:59:12–01:01:27 · Venture-model interview, 14:15–15:33 and 23:00–29:23 · Ownership/fund math, 53:38–57:09 They do not prove causal selection skill or investor return. Exact evidence gaps: No fund/check/security/price/ownership/reserve ledger for any Casado deal; no IC scenario sheets or votes; no board budgets or stop decisions; no Tackle preference stack or acquisition consideration; no Astranis debt/covenant allocation; no World Labs ownership; and no realized cash-flow series linking capital discipline to fund performance.
- Limits, failure modes, and exception ledger: Limits and exceptions: Some category winners require aggressive preemption before metrics mature; strict milestone tranching can starve exploration; ownership targets may cause an investor to miss exceptional companies; and cutting early can destroy the very option the capital was meant to buy. Nicira and Tackle are two anecdotes in different regimes. The capital-flywheel thesis can become circular when financing demand funds suppliers and masks end demand. Failure modes: treating a large round or valuation as an outcome; financing secular demand at a cyclical peak; preemptive capital without a revised downside case; overbuilding teams or capacity; austerity becoming identity after the inflection; hidden debt/covenants; or good company outcomes producing weak fund returns because ownership/dilution/structure were poor. Falsifiers: the next tranche retires no named risk; burn grows faster than repeatability; no-new-capital runway falls; milestone dates slip without learning; downside proceeds would not clear senior claims; follow-on ownership cannot be defended; or the expected company value does not produce an acceptable fund outcome under realistic dilution.
- Evolution and contradictions: The founder lesson was survival versus timely reinvestment. The investor articulation adds ownership, stage teams, and debate. The AI-era update adds capital-intensity, supplier finance, and overbuild timing. The invariant is to price uncertainty through capital and terms rather than narrate it away. Software Chasms, 00:59:12–01:01:27 · Venture-model interview, 14:15–15:33 and 23:00–29:23 · Ownership/fund math, 53:38–57:09 · Capital flywheel, 03:19–11:24 The live contradictions are preserved by the limits, adverse examples, and falsifiers above; later evidence does not retroactively enter an earlier decision.
- Modern VC translation (as of 2026-08-20): [researcher inference · strong] Transfers: tie each financing to changed evidence, milestones, ownership, structure, reserves, governance, and a no-new-capital case. Does not transfer: capital raised, valuation, or deployed GPUs as product/return evidence. Changed assumptions: concentrated AI suppliers, cloud credits, strategic/circular financing, power commitments, and long private duration. Observable signals: risk retired per dollar, independent customer cash, stable burn multiple, defensible ownership, and milestone delivery. Likely misuse: financing a secular truth at a cyclical peak. Current grounded example: World Labs' 2026 $1B financing is capital raised only; capacity milestones, ownership, and return remain unknown. World Labs, opening funding paragraph
Evidence gaps and candidate models
Evidence contract
Information cutoff: 2026-08-20. This is a reconstruction from the frozen Casado package, not an account of private a16z investment-committee practice. The public record supports a set of testable decision tools; it does not show that any model caused a named investment, establishes no personal hit rate, and exposes no complete check/price/ownership/reserve/return history. A deal post proves only the named author's participation in a public thesis; a board roster proves service, not sourcing or economics. Applications below are therefore called documented applications only when a source connects the rule to the action. Everything else is explicitly a researcher-applied illustration.
Inventory reconciliation and retention rule
The corpus produced fifteen plausible model families across the complete writing, talk, biography, and deal-note inventories. Seven clear the working bar below; eight are excluded or absorbed rather than promoted as standalone models. Retention required: a repeatable procedure, observable signals, a falsifier, at least three distinct grounded applications, and useful support from at least two independent underlying sources. Selected-winner examples establish plausibility, not efficacy. The retained set is not an arbitrary “top seven”; it is every candidate that survived those tests.
Across all seven models, the decisive missing layer is private process and economics: original IC memoranda, dated alternatives and passes, partner votes, check/security/price, ownership and dilution, reserve decisions, board interventions, realized proceeds, and complete opportunity/outcome denominators. Model-specific gaps remain in each model's Evidence component; absence is unknown, never clean or zero.
Excluded or absorbed candidates — attractive, but not standalone evidence-backed models
The exclusion test was applied after reviewing the complete priority writing/talk notes, the 43 announcement records, the current/former board roster, seven decision labs, and the primary adverse/outcome sweep. “No result” is an evidence state, not proof of a clean outcome.
- Marginal-data-value / “data moat” test — absorbed into Models 4 and 6; standalone support insufficient. The 2019 essay supplies an excellent rule—measure marginal observation value, acquisition/labeling cost, decay, rights, exclusivity, and competitor catch-up—and preserves scarce, regulated, or trust-mediated exceptions. But the frozen record does not connect it to three distinct named investment decisions or outcomes. Eloquent Labs is one domain illustration; robotics deployment data and Cursor context are later hypotheses, not documented applications. Attempted routes: essay, later margin/robotics writings, all announcements, board roster, and outcome sweep. Missing: deal memos, data-rights diligence, longitudinal model-lift cohorts, and passes. Data-moats essay
- Evidence-and-monitoring governance for open models — excluded from the investment-model set. The 2024 policy essay and NTIA record support a policy procedure—define the artifact, compare marginal risk, identify legal gaps, monitor, and precommit escalation—but not three investment applications, portfolio-governance cases, or conflict-management outcomes. Attempted routes: full policy note, partial open-code essay, announcements, profile, and adverse sweep. Missing: investment decisions changed by evaluation evidence, incident thresholds, lobbying/conflict records, and monitoring actions. Policy essay · NTIA report
- Physical AI as an industrial system — excluded as too new and financially interested. The 2025 robotics essay offers a useful component→integration→deployment-data chain and can inform Astranis/DeepMap diligence, but it is one current sector thesis with no three-case production/outcome record. World Labs is a financially interested illustration and not manufacturing evidence. Attempted routes: robotics essay, Uncharted board-learning discussion, Astranis/DeepMap/World Labs records, and adverse sweep. Missing: bill-of-materials, yield, field failures, utilization, repair, supplier concentration, data rights, working-capital, and realized outcomes. Robotics essay
- Bounded autonomy / tail-and-correction-loop test — excluded as a prospective technical thesis. Casado's agent skepticism is direct and falsifiable—long-horizon correctness, state, memory, planning, and correction must improve—but the corpus supplies no three-company decision/outcome set. Cursor coding, autonomous vehicles/DeepMap, and support agents are cross-domain illustrations only; Casado explicitly notes internal dissent. Attempted routes: 2024 hard-limits and innovation talks, 2025 software-development talk, Cursor/DeepMap records, and adverse sweep. Missing: task-horizon cohorts, intervention rates, state-consistency tests, economic reliability, named passes, and investment changes. Uncharted, 00:56:32–00:58:41
- Technical-founder prior / match leadership to the bottleneck — excluded as an admitted bias, not a validated model. Nicira's founder selling, sales-team retention, open/proprietary team structure, and a16z's later physical-domain specialization show useful behaviors, but only the first company has detailed operating testimony and no comparison demonstrates technical founders outperform commercial/domain founders. Attempted routes: pricing/developer/chasms talks, Uncharted, profile, and all deal-team descriptions. Missing: selection denominator, false positives/negatives, CEO-change cases, role scorecards, board interventions, and outcomes. Uncharted, 00:42:28–00:43:41
- “One mortal enemy” conflict rule — excluded for lack of cases. The 2025 monopoly/oligopoly interview supplies a memorable direct statement about portfolio conflict, but no public conflict decision, recusal, consent, information barrier, or harmed company is disclosed. Attempted routes: interview, current portfolio, board roster, vehicle analysis, and overlapping category map. Missing: policy text, actual exceptions, company consent, enforcement, and outcome evidence. Monopolies vs. Oligopolies, 57:09–59:35
- AI capital flywheel / 1996 supercycle / model fragmentation — retained as scenarios inside Models 1, 5, and 7, not standalone models. These are competing forecasts: financing can create compute/capability/demand feedback; genuine demand can coexist with overbuild; model markets may fragment or consolidate. They generate scenarios and falsifiers but do not yet have three independent decision/outcome applications. Attempted routes: 2024 Uncharted; 2025 generalist and monopoly/oligopoly talks; the 2026 capital-flywheel talk; current AI announcements, financings, and adverse sweep. Missing: audited end-demand versus circular financing, workload utilization, supplier/customer contracts, market-share transitions, passes, and returns. Uncharted · Latent Space capital-flywheel discussion
- Update-through-failure / navigation under uncertainty — absorbed, not retained alone. It is a valuable epistemic stance but is not sufficiently discriminating to select or govern an investment without the concrete map, annealing, cost, or capital procedure above. The record gives Hugging Face, Nicira, and Tackle as different kinds of learning, yet no common ex-ante rule or process-change ledger binds them. Attempted routes: uncertainty talk, labs, biographies, and adverse sweep. Missing: precommitted update triggers, recorded belief changes, decisions reversed, and comparative results.
Critical tensions the reader should keep live
- Maps versus graphs: architecture reasoning is Casado's comparative advantage, but his clearest process correction says observed use can beat theory. The procedure must specify when the map yields.
- Adoption versus capture: developer/open-source pull is a sourcing and insertion signal; it can coexist with no buyer, no paid control point, supplier dependence, or services-heavy economics.
- Discovery versus discipline: annealing justifies patient learning only while product, buyer, and deployment converge. Tackle shows that strong customer truth does not excuse re-underwriting capital and organizational scale.
- Flexibility versus cost: rented infrastructure preserves option value, while stable scale can justify specialization. Both cloud lock-in and premature internalization are live failure modes.
- Capability versus completed-work economics: better models and falling nominal prices do not automatically lower cost per accepted outcome once retries, review, support, and integration are counted.
- Secular truth versus entry timing: AI or infrastructure demand can be enormous while capacity, valuation, or financing is mistimed. A correct technical thesis is not a sufficient investment thesis.
- Company outcome versus fund outcome: Cursor, Yubico, Parsec, and other events can be economically important company records, but without cost, ownership, dilution, proceeds, and dates they cannot validate these models as return-generating skill.
What the evidence supports
[researcher inference · moderate] The defensible thesis is narrower than “great investor.” From 2016 through 2026, Casado repeatedly translated changes in infrastructure architecture into testable questions about workflow, user, buyer, budget, control point, contribution margin, and financing. The dated writing and spoken records make that method unusually legible; the public deal record supplies several ex-ante illustrations and one clear adverse capital-scaling case. The record does not establish that Casado personally sourced or approved every attributed deal, that the method caused any outcome, or that it produced superior ownership-adjusted or net returns. _profile.md, “A falsifiable account of the edge” · writings.md, “Core written philosophy” · talks.md, “Evolution, contradictions, and present translation”
The formation sequence is real but collaborative. [retrospective witness · moderate] LLNL's 2015 institutional profile records Casado's 1998–2003 systems/security work and post-9/11 network-security assignment. LLNL, career and post-9/11 paragraphs [contemporaneous record · strong] Stanford and the technical papers record SANE/Ethane-era research with coauthors, while VMware records the Nicira corporate transaction. technical-record map, SANE/Ethane entries · VMware 2012 Form 10-K, Note B, “Acquisition of Nicira, Inc.” [researcher inference · moderate] That sequence supports a plausible systems lens, not a causal proof that operator experience created later investing performance.
[researcher inference · strong] The package's most useful learning result is therefore procedural: freeze the market map and alternatives; demand a user-to-buyer-to-budget chain; normalize economics per accepted outcome; tie capital to risk retirement; preserve team, vehicle, company, investor-proceeds, and LP-distribution boundaries; then reveal the outcome. The seven decision labs and seven retained models operationalize those rules without claiming private IC provenance. investments.md, “Ex-ante decision labs” · mental-models.md, inventory reconciliation
Central-claim audit trail
The audit below re-opened the highest-risk claims against the linked underlying record and recalculated the arithmetic. Pass means the bounded claim is supported; it does not upgrade company evidence into personal performance evidence.
| ID | central claim tested | source and exact locator re-opened | result and warranted boundary |
|---|---|---|---|
| C1 | Architecture-to-market translation is the proposed 2016–2026 edge. | Data Moats, “Incremental Data Value” and “When IS data defensible?” · talk evolution, dated 2016–2026 rows · profile causal-arrow table | Pass — [researcher inference · moderate]. Repetition and specificity support a testable method; no matched cohort supports alpha or causation. |
| C2 | LLNL/security work plausibly shaped the later systems lens. | LLNL, career 1998–2003 and post-9/11 assignment paragraphs · profile, first two chronology sections | Pass — [researcher inference · moderate]. Dates and work are direct; the later investing effect remains an explicitly labeled causal inference. |
| C3 | Nicira is an operator outcome, not an investment selected by Casado; transaction measures must be separated. | VMware 2012 Form 10-K, Note B, Nicira consideration and assumed-equity paragraphs · denominator exclusions | Pass — [contemporaneous record · strong]. $1,099.6M net-of-cash consideration includes $1,083.0M cash and $16.6M pre-combination-service equity; $152.4M post-combination-service awards were excluded from consideration. The record supplies no Casado proceeds. |
| C4 | The economic, historical, and decision-learning Pareto ranks answer different questions. | economic ranking rule · historical ranking rule · learning ranking rule | Pass — [researcher inference · strong]. Each universe, lexicographic rule, attribution rule, and return boundary is stated; no rank is presented as realized performance. |
| C5 | Cursor is the dominant visible company event at a $60B implied equity value. | SpaceX Form 8-K, Item 1.01, “Merger Consideration” · Cursor, opening completion paragraphs · a16z Series A, four-person byline | Pass — [contemporaneous record · strong] for company value, completion, and team byline; [researcher inference · insufficient public record] for Casado-specific contribution, stake, proceeds, or distribution. |
| C6 | Yubico is an approximately $800M mixed-consideration public transaction and the issuer disclosed firm-level ownership constraints. | Yubico/ACQ release, “Key figures,” transaction highlights, “Ownership structure” table, and 180-day undertaking | Pass after REVIEW correction — [contemporaneous record · strong]. The release expected 6.1% post-combination Andreessen Horowitz ownership and named it in a 180-day lockup. Entry cost, exact closing stake, later sales, investor proceeds, and LP distributions remain unknown. |
| C7 | Parsec's disclosed acquisition measure is $332.729M gross cash consideration, not investor proceeds. | Unity 2021 Form 10-K, Note 6, Parsec paragraph and consideration table · a16z Parsec, opening history and closing board paragraph | Pass — [contemporaneous record · strong] for company consideration and [investor-stated · strong] for Casado's public sponsorship account; seller allocation and a16z economics are absent. |
| C8 | Removing Cursor leaves $1.132729B of visible priced company-event value; Yubico and Parsec are both needed to cross 80%. | Yubico, $800M equity transaction value · Unity Note 6, $332.729M | Pass — [researcher inference · strong]. Recalculation: $800M + $332.729M = $1,132.729M; shares are 70.626% and 29.374%. It is an outlier test on visible company-event measures, not returns. |
| C9 | The public-attribution denominator is 68 claims / 46 included companies, researched from 70 candidate claims / 48 candidate companies. | denominator table and rules · source-map reconciliation | Pass — [researcher inference · strong]. 43 announcement claims + 25 board claims = 68 claim records; 43 + 25 − 22 overlaps = 46 companies; adding Nicira and Illuminics yields 70 / 48. Forty-three of 46 are sufficiently reconstructed, or 93.5%. This is not the career-wide actual-deal denominator. |
| C10 | Fourteen primary corporate events affect 15 of 46 lineages, leaving 31 without a qualifying primary event. | outcome reconciliation | Pass — [researcher inference · strong]. Three priced + ten unpriced company events + one Rapid asset/R&D-unit event = 14; the Fivetran–dbt event spans two lineages; 15 + 31 = 46. Announced-but-uncompleted and secondary-only reports stay bounded. |
| C11 | MOIC, DPI, TVPI, and IRR are not publicly computable. | non-computability proof · source-map economic boundary | Pass — [researcher inference · strong]. The record lacks a compatible company-to-fund map, cost, security, ownership/dilution, residual value, seller proceeds, LP paid-in capital/distributions, fees/carry, and dated cash flows. Multiple incompatible return paths fit every observed company fact. |
| C12 | Fund V, VII, Growth II, IX Infrastructure, and X Infrastructure are platform/vehicle context; Casado's authority and economics are not established. | Fund VII Form D, Items 3, 5, 12–14 · Fund IX Form D, Items 1, 3, 13, 15 · Fund X Form D, Items 1, 3, 13, 15 · A16Z ADV, Schedules A/B and Schedule D §7.B.(1) | Pass — [contemporaneous record · strong]. Filings establish legal pools, GP/control chain, gross assets and owner counts; they do not establish Casado's vote, veto, carry, allocation, reserves, stake, or returns. GAV/RAUM are not NAV, proceeds, or LP distributions. |
| C13 | Tackle is the strongest public adverse decision-learning case, not a proven fund loss. | Tackle Series C, preemptive financing and expansion plan · Tackle update, 75 separations and “overbuilt” paragraph · Tackle company page, acquisition status | Pass — [documented behavior · strong]. The operating miss and later acquisition are public; check, preferences, governance causation, acquisition consideration, recovery, and return are not. |
| C14 | Historical financing and liquidity conditions constrain causal interpretation. | 2021 Venture Monitor, Executive Summary · Q1 2022 NVCA update, exit-market paragraph · Q4 2025 Venture Monitor, Executive Summary and liquidity sections · Q1 2026 Venture Monitor, Executive Summary | Pass — [researcher inference · strong]. Dated base rates contextualize rounds, exits, LP pressure, and AI concentration; they are not matched alpha controls and are never leaked into an earlier decision worksheet. |
| C15 | Seven models, three completed peers, and selected direct phrases are bounded rather than padded. | model retention and eight-candidate exception ledger · completed-peer controls · “one mortal enemy,” 57:09–59:35 | Pass — [researcher inference · strong]. Seven of fifteen candidates meet the procedure/example/source bar; Trae Stephens, Georges Doriot, and Reid Dennis are the only completed comparators; short direct phrases are tied to timestamps or headings and not treated as independent proof. |
What could falsify the thesis
[researcher inference · strong] The favorable account is falsifiable only if future private evidence can separate method from access, team, vehicle, era, and luck. The following tests are decisive rather than rhetorical:
- Selection test. A complete sourced/pass/loss ledger, frozen at each decision, would weaken the thesis if architecture/customer evidence did not predict selection or ordinary-case outcomes better than stage-, sector-, and vintage-matched a16z opportunities. denominator and continuation routes
- Behavior test. Original market maps, memos, dissent, votes, and follow-on records would weaken it if the published rules were retrospective explanations, if milestones did not change capital decisions, or if negative evidence was ignored. profile falsifiers
- Attribution test. Signed role ledgers would weaken a personal-edge claim if sourcing, diligence, approval, governance, and exit work were principally performed by coauthors, other partners, founders, or platform teams. people and influence map
- Economics test. Security-level cash flows would weaken the thesis if ownership-adjusted, net, and ex-Cursor results were no better than matched funds or deals despite strong company outcomes. non-computability proof
- Failure test. Board and reserve records would weaken it if Tackle-like overbuilding recurred without precommitted stop rules, revised downside cases, governance response, or a documented process change. failure matrix
- Conflict test. Company-by-company records would weaken the institutional explanation if competitor lanes, cross-vehicle allocation, portfolio references, related valuation, or policy advocacy were not governed by disclosed consent, recusal, information barriers, and independent checks. allocation and conflict incentives
[researcher inference · strong] The strongest skeptical explanation currently survives: Casado may be an exceptional technical explainer with privileged operator and a16z access, participating in team decisions during favorable infrastructure and AI regimes, while one extreme company event dominates visible value. The public record cannot distinguish that explanation from repeatable personal selection skill. The ex-Cursor test prevents the skeptical case from collapsing into “only one outcome”—Yubico and Parsec remain visible—but neither supplies fund economics. profile, “The strongest case against greatness” · philosophy, decision evidence that would discriminate
Attribution and denominator audit
[researcher inference · strong] The mechanical ledger reconciles, but its unit must remain explicit. It is a public claim-record/company-lineage universe, not a complete portfolio: 43 announcement claims plus 25 board claims produce 68 records; removing 22 company overlaps produces 46 included lineages. Adding two excluded founder/operator candidates produces 70 candidate records across 48 companies. Of the 46 included lineages, 43 are sufficiently reconstructed and three—DeepMap, Netlify, and Pindrop—remain board-only incomplete. Thus 43/46 = 93.5% public-record reconstruction coverage, while career-wide coverage, hit rate, loss rate, and returns are not computable. denominator table · source reconciliation
[researcher inference · strong] The economic vocabulary also reconciles: corporate consideration, listing, private mark, tender/secondary, investor proceeds, and LP distributions are distinct. Yubico is the one visible case in which the issuer disclosed an expected firm-level post-combination stake and lockup; even there the record does not identify entry cost, exact close/dilution path, sales, proceeds, fund mapping, or distributions. An unknown is not zero. Yubico, ownership table and lockup paragraph · glossary
Material deal and team cross-checks
| case | public attribution re-opened | independent company/outcome record | audit result |
|---|---|---|---|
| Cursor | Four named 2024 thesis authors; profile names Casado as director. a16z announcement, byline and closing · profile, current-board paragraph | SpaceX 8-K, Item 1.01 · Cursor, completion opening | Pass — [contemporaneous record · strong]. Team thesis and company transaction; no fractional credit or investor-return inference. |
| Yubico | Casado published the 2018 diligence rationale and board role. a16z Yubico, diligence and closing paragraphs | Yubico/ACQ, $800M value; expected 6.1% a16z ownership; 180-day lockup | Pass after correction — [contemporaneous record · strong]. Firm-level stake evidence is retained; Casado economics, realized proceeds, and LP cash remain unknown. |
| Parsec | Casado said a16z led the Series B after tracking the company and that he joined the board. a16z Parsec, opening and closing | Unity 10-K, Note 6, Parsec | Pass — [investor-stated · strong] for sponsorship; [contemporaneous record · strong] for $332.729M company consideration. |
| Tackle | The 2019/2021 public theses describe portfolio discovery, customer evidence, and a preemptive follow-on. a16z Tackle, discovery and decision paragraphs · issuer Series C, preemptive round and hiring plan | issuer update, 75 separations and overbuild · issuer company status | Pass — [documented behavior · strong]. Strongest adverse learning case; no personal governance action, loss, or return claimed. |
| Tecton | Casado's post records a16z seed support in 2018 and Series A participation after later customer evidence. a16z Tecton, final two paragraphs | Databricks, “Tecton + Databricks” announcement | Pass — [investor-stated · strong] for financing history; [contemporaneous record · strong] for an announced, not proved-completed, corporate event. Checks, reserve rule, terms, and proceeds are unknown. |
| Astranis | Casado's thesis explicitly records an unfamiliar-domain learning path and board role. a16z Astranis, opening and closing board paragraphs | Astranis, Arcturus anomaly and response | Pass — [investor-stated · strong] for the decision narrative and [documented behavior · strong] for the technical adverse event; no causal board or return conclusion. |
[researcher inference · strong] A byline proves participation in a public thesis; a board roster proves service. Neither proves sole sourcing, sponsorship, diligence, negotiation, IC approval, check allocation, reserves, follow-on authority, exit vote, ownership, or proceeds. The filing record establishes Andreessen/Horowitz legal control, not deal-by-deal votes; Casado's practice-lead title establishes operational prominence, not legal authority or carry. a16z portfolio disclosure, disclosure below table · A16Z ADV, Schedules A/B
Transfer limits for modern VCs
Information cutoff: 2026-08-20. [researcher inference · strong] The transferable object is the question set, not Casado's reputation, network, fund size, or visible marks.
| lesson | what transfers now | what does not transfer / likely misuse | observable 2026 test |
|---|---|---|---|
| Map before selecting | Freeze layers, dependencies, control points, substitutes, and competing scenarios before meeting the company. | A flexible post-deal category map that makes the winner inevitable. | Dated map, ranked alternatives, pass log, and explicit evidence that changes the rank. Model 1 |
| Follow the complete adoption chain | Trace user value → retained use → buyer → budget → procurement → paid expansion. | Developer love, open-source stars, pilots, or usage presented as revenue or defensibility. | Cohort retention, paid conversion, budget owner, sales cycle, expansion and churn. Model 2 |
| Anneal before scaling | Let founders iterate product, use case, buyer, and category until a repeatable pattern appears. | Permanent services work or a 2021-style hiring plan justified by enthusiasm alone. | Converging implementation time, repeatable cohorts, declining customization, burn multiple, and a no-new-capital runway. Model 3 |
| Underwrite capture, not only adoption | Identify the monetizable workflow/control point and test platform bundling, open-source governance, and supplier power. | Treating technical importance or community adoption as a moat. | Paid control, switching cost, distribution independence, portability, and marginal data value. Model 4 |
| Preserve option value | Rent and stay portable while demand/workload is uncertain; internalize or specialize after stable evidence. | Universal “cloud is cheap” or “repatriate” rules. | Workload stability, lifecycle cost, utilization, reversibility, lock-in, and migration cost. Model 5 |
| Measure completed-work economics | Include retries, evaluation, human review, implementation, support, inference, and training in contribution margin. | Nominal model-price decline, software gross-margin analogy, or generated tokens as outcome evidence. | Cost per accepted task at required quality, intervention rate, support burden, and customer willingness to pay. Model 6 |
| Make capital part of the thesis | Tie each round to risk retired, terms, ownership, reserves, downside, and stop/go triggers. | Capital raised, private valuation, GPUs deployed, or GAV treated as performance. | Milestone delivery per dollar, defensible ownership, stable burn, independent demand, and distribution evidence. Model 7 |
[researcher inference · strong] Important assumptions have changed: AI capital and supplier concentration are exceptional; strategic/circular financing can mimic end demand; model capability and price move quickly; long private duration raises liquidity and valuation-process risk; policy positions can be economically interested. The current package handles those changes with dated transfer tests, the 2026 AI base rate, fund-vehicle cautions, and independent policy controls. It does not show that an emerging manager without a16z's brand, portfolio references, check size, stage teams, or access can reproduce the sourcing advantage. historical environment · modern translation
Unresolved evidence
[researcher inference · strong] Acceptance is for a bounded public-record curriculum, not for a completed economic proof. The highest-value missing records remain: a complete opportunity/pass/loss ledger; historical a16z roster snapshots; original market maps and IC memoranda; partner votes and dissent; company-by-company source/sponsor/diligence/negotiation roles; conflict consent, recusal, and information barriers; security, price, ownership, dilution and reserve schedules; board interventions and stop decisions; tenders/secondaries; seller waterfalls; residual NAV; fees/carry; and dated LP calls and distributions. source-map access boundaries · investment continuation routes
[researcher inference · strong] Three included companies—DeepMap, Netlify, and Pindrop—still lack adequate entry/thesis reconstruction; Illuminics lacks a reconstructed a16z investment record and remains excluded; no original Illuminics–Quova transaction record or complete Nicira cap table was found. Two gated essays remain analyzed only to authenticated visible boundaries. Audio-only talks are bound to exact media/time locators but lack creator transcripts. These are disclosed limitations after mapped legitimate routes, not permission to reconstruct hidden bodies or infer a clean record. writings coverage · talks coverage · source-map archival gaps
Ordinary-claim reopenings
Selection rule: two ordinary claims were chosen from each of the seven pre-REVIEW core documents, alternating mechanical/inventory claims with factual or interpretive claims. This yields 14 reopenings across every root rather than a convenient cluster.
| ID | root and ordinary claim | source / locator re-opened | result |
|---|---|---|---|
| O1 | _profile.md: LLNL career ran 1998–2003 and included a post-9/11 secure-network assignment. |
LLNL, “Livermore roots,” career and post-9/11 paragraphs | Pass — [retrospective witness · moderate]. The 2015 institutional profile directly records the dates and account but is retrospective and celebratory. |
| O2 | _profile.md: a16z's live profile lists 17 current and eight former boards as of the cutoff. |
a16z profile, “About,” current and former board paragraphs | Pass — [contemporaneous record · strong]. Roster proves service only. |
| O3 | sources.md: 220 priority rows + 16 supporting route groups = 236 annotated rows and 274 unique URLs. |
coverage, “Corpus, categories, and search variants” plus mechanical row/URL recount | Pass — [researcher inference · strong]. Direct corpus remains separately 60 routes. |
| O4 | sources.md: only completed Trae Stephens, Georges Doriot, and Reid Dennis packages are comparators. |
completed-peer boundary · eight underlying peer works and locators | Pass — [contemporaneous record · strong] for repository completion; [researcher inference · strong] for comparability boundary. |
| O5 | writings.md: 16 priority works reconcile as 9 ★★★ + 7 ★★ and 14 full + 2 partial. |
literal priority-source reconciliation and the 16 notes/w-* records |
Pass — [contemporaneous record · strong]. No gated body is reconstructed. |
| O6 | writings.md: the data-moat rule requires marginal-value, freshness, distribution, scarcity, and catch-up tests. |
Data Moats, “Incremental Data Value,” “Data Freshness,” and “When IS data defensible?” | Pass — [investor-stated · strong] for the rule; named-deal use remains unproved. |
| O7 | talks.md: 31 appearance families reconcile as 11 ★★★ + 19 ★★ + 1 ★, with 10 creator-text and 21 official-media routes. |
talks coverage table and the 31 notes/t-* records |
Pass — [contemporaneous record · strong]. Replay/wrapper families are not double-counted. |
| O8 | talks.md: the Hugging Face account is evidence of theory yielding to observed use, not proof of a changed investment. |
Digital Infrastructure note, “Biography and decision evidence”, underlying media 00:29:03–00:31:48 | Pass — [retrospective witness · moderate]. Memo, vote, price, and causal investment change remain missing. |
| O9 | investments.md: 43/46 included companies are sufficiently reconstructed, or 93.5%. |
denominator table | Pass — [researcher inference · strong]. Recalculation is 93.478%, rounded to 93.5%; career-wide coverage is not computable. |
| O10 | investments.md: Tecton is an announced transaction, not a proved completed acquisition. |
Databricks, “Tecton + Databricks” announcement · outcome table | Pass — [contemporaneous record · strong]. It remains in the unpriced/announced boundary. |
| O11 | investmentphilosophy.md: synthesis contains the required 17 sections in literal order. |
snapshot through study guide, mechanical H2 recount | Pass — [contemporaneous record · strong]. |
| O12 | investmentphilosophy.md: 2026 transfer warns that World Labs' $1B is financing, not valuation or return. |
World Labs, opening funding paragraph · modern translation | Pass — [contemporaneous record · strong] for financing; [researcher inference · strong] for the economic boundary. |
| O13 | mental-models.md: seven of fifteen candidate families are retained and eight are excluded or absorbed under an explicit bar. |
inventory reconciliation and candidate ledger | Pass — [researcher inference · strong]. No below-target candidate is promoted by citation padding. |
| O14 | mental-models.md: Tackle is an adverse capital-discipline application but cannot establish loss or recovery. |
Model 7, adverse Tackle example · Tackle update, 75 separations/overbuilt | Pass — [documented behavior · strong]. Acquisition consideration and fund economics are absent. |
Twenty-point acceptance matrix
| # | §11.1 requirement | pass / fail | documents and sections inspected | correction or continuation required |
|---|---|---|---|---|
| 1 | Deep chronological investment biography | Pass | _profile chronology · formation narrative | Preserve date discrepancies and retrospective labels; continue only if original Illuminics/Nicira records surface. |
| 2 | Falsifiable thesis of the edge | Pass | _profile edge and falsifiers · philosophy snapshot · skeptical case | Obtain matched deal/pass and role/economic records to decide skill versus access/team/era/luck. |
| 3 | Ex-ante deal reconstruction | Pass | seven decision labs | Preserve freeze/worksheet/reveal order; private terms, dissent, votes, and stop decisions remain named gaps. |
| 4 | Pareto economic, historical, and learning analysis | Pass | first H2 and three ranking rules | Recompute if a new priced primary outcome appears; never add incompatible measures. |
| 5 | No premature completion or placeholders | Pass | All eight core documents; substantive first H2s; 16 writing notes; 31 talk notes | No placeholder found. Acceptance remains bounded by the unresolved-evidence section, not by invented closure. |
| 6 | Searched portfolio denominator and coverage | Pass | denominator · source reconciliation · 46-row ledger | Reconstruct DeepMap, Netlify, and Pindrop if a claim-local entry record becomes available; archive roster drift. |
| 7 | Comprehensive source-by-source writings | Pass | 16-work coverage · source-by-source analysis | Legitimately retrieve the two gated essay bodies; do not infer them meanwhile. |
| 8 | Detailed, cited mental models | Pass | seven models · retention and eight-candidate ledger | Obtain private decision applications before upgrading any model from teachable procedure to demonstrated investing process. |
| 9 | Dated modern-VC translation | Pass | philosophy translation as of 2026-08-20 · each model's “Modern VC translation” bullet | Refresh contemporary premises after the cutoff; preserve inference/hypothetical labels. |
| 10 | Full failure postmortems | Pass | failure matrix · Tackle failure lab · philosophy limits | Seek capital response, board action, loss/recovery, and process-change records; do not turn search silence into success. |
| 11 | Partner, team, and decision-rights attribution | Pass | people map · philosophy team section · six deal cross-checks above | Keep all silent source/sponsor/vote/negotiation/follow-on/exit roles unknown. |
| 12 | Vehicle economics and incentive analysis | Pass | vehicle chapter · philosophy vehicle fit | Partnership agreements, IC charter, delegation, geography, compensation/carry, reserves, succession, and LP cash flows remain unavailable. |
| 13 | Historical market, regulatory, and base-rate context | Pass | historical/base-rate table · philosophy historical environment | Add only dated, decision-available evidence or clearly labeled retrospective comparison; no unmatched alpha inference. |
| 14 | Direct voice and primary-archive exhaustion | Pass | source-map direct routes and barriers · writings coverage · talks coverage | Continue the exact archive/paywall/transcript routes named in highest-value retrieval leads. |
| 15 | Pinpoint citations | Pass | Central audit, 14 ordinary reopenings, all root documents and notes | Maintain heading/paragraph/timestamp/filing-item pinpoints; bind mutable pages to the 2026-08-20 access date. |
| 16 | Explicit attribution and evidence labels | Pass | All synthesis/economic documents plus this review | Canonical axes remain separate: source relationship and support grade; do not upgrade investor narration to behavior. |
| 17 | Strongest case against greatness | Pass | _profile skeptical case · philosophy skeptical case · falsification section above | Ex-Cursor matched net economics and signed role records are the decisive continuation. |
| 18 | Comparison with completed peers | Pass | philosophy peer matrix · eight underlying peer works | Compare only completed Stephens, Doriot, and Dennis; preserve era/vehicle comparability limits. |
| 19 | Investment-committee decision exercises | Pass | seven ex-ante labs · study-guide sequence | Keep Tackle first as the failure/miss exercise; acquire original terms, votes, and milestones if possible. |
| 20 | Reader learning architecture | Pass | chronology · reading path · glossary · checklists · people map | Relative-link path is Markdown-native and usable; no bespoke component is required. |
Acceptance judgment. [researcher inference · strong] All twenty requirements pass as a public-record learning package after correcting the Yubico firm-ownership/lockup boundary. The curriculum supports study of a falsifiable method and its limits; it does not support a personal return, alpha, sole-credit, or clean-conflict conclusion. Any later completion bookkeeping should preserve that distinction.
Source-map boundary and retrieval priorities
This source map treats Casado as a researcher, founder/operator, venture investor, board member, nonprofit cofounder, and policy advocate. It separates Casado's direct voice from coauthored work, team research, a16z firm claims, company outcomes, regulatory records, and independent criticism. Stars rank evidentiary priority, not truth. Every current roster, private valuation, run-rate figure, acquisition amount, and policy claim retains its own measurement and attribution boundary.
Discovery archives and current institutional identity
- ★★★ | Andreessen Horowitz — Martin Casado author and team archive | https://a16z.com/author/martin-casado/ | live; accessed 2026-08-20 | official mutable profile and content index | Current role, 17 current/eight former boards, biography, writings, and spoken-corpus discovery route; not proof of complete deal attribution or economics. (reliability: A for current firm record; access: full; accessed: 2026-08-20; locator: “About,” current/former board paragraphs, chronological content index)
- ★★★ | Martin Casado — Stanford personal archive | https://yuba.stanford.edu/~casado/ | live/undated; accessed 2026-08-19 | first-person academic homepage | Education, affiliations, projects, teaching, publications, awards, and archived research routes; mutable and partly stale. (reliability: A/B; access: full; accessed: 2026-08-19; locator: “Selected Projects and Research,” “Teaching,” “Education”)
- ★★★ | Martin Casado — Stanford publication index | https://yuba.stanford.edu/~casado/publications.html | live/undated; accessed 2026-08-19 | first-person publication bibliography | Primary discovery denominator for the technical corpus; individual author lists and dates still control. (reliability: A/B; access: full; accessed: 2026-08-19; locator: chronological publication list)
- ★★ | Open vSwitch — research-paper index | https://www.openvswitch.org/support/papers/ | live; accessed 2026-08-19 | project bibliography | Routes to primary technical papers and preserves team authorship; not a Casado-only archive. (reliability: A; access: full; accessed: 2026-08-19; locator: paper list)
Biography, education, operating chronology, public service, and awards
- ★★★ | Lawrence Livermore National Laboratory — The accidental entrepreneur | https://www.llnl.gov/article/41011/accidental-entrepreneur | 2015-04-28 | official direct-interview profile | Richest record of family moves, LLNL internship/employment, simulation work, post-9/11 security assignment, Stanford transition, and later origin narrative; retrospective and celebratory. (reliability: B; access: full; accessed: 2026-08-19; locator: opening biography and LLNL/post-9/11 passages)
- ★ | LLNL — Martin Casado Entrepreneurs' Hall of Fame profile, retired route | https://ipo.llnl.gov/success/hall-of-fame/martin-casado | 2015/current archive record | institutional biography lead | The canonical route returned HTTP 404 on 2026-08-19; no claim extraction relies on it, and the two working LLNL pages carry the chronology. (reliability: A/B for institutional provenance; access: inaccessible/404; accessed: 2026-08-19; locator: retired canonical route, no live body)
- ★★ | LLNL — Four researchers to be inducted into Entrepreneurs' Hall of Fame | https://www.llnl.gov/article/40721/four-researchers-be-inducted-lawrence-livermore-entrepreneurs-hall-fame | 2015-01-15 | official award announcement | Confirms induction date, LLNL tenure, and institutional framing; use primary papers for invention credit. (reliability: A/B; access: full; accessed: 2026-08-19; locator: Casado paragraphs)
- ★★★ | Martin Casado — Stanford PhD dissertation, Architectural Support for Security Management in Enterprise Networks | https://yuba.stanford.edu/~nickm/papers/martin-casado-thesis.pdf | 2007-12 | primary academic PDF | Decision-date account of SANE/Ethane, centralized control, advisers, and research problem; decisive for technical chronology. (reliability: A; access: full; accessed: 2026-08-19; locator: title/approval pp. 0–2, abstract pp. 4–5)
- ★★★ | Stanford EE204 — Nicira Networks company case | https://web.stanford.edu/class/ee204/2012/Nicira%20Networks.pdf | 2012 | university teaching case PDF | Near-contemporaneous management, founder, education, board, and financing scaffold; not an audited filing. (reliability: B; access: full; accessed: 2026-08-19; locator: Exhibit 7, pp. 29–31)
- ★★ | Northern Arizona University — honorary doctorate recipients | https://in.nau.edu/commencement/new-page/honorary-doctorate-recipients/ | live; accessed 2026-08-19 | institutional roster | Confirms 2016–17 honorary doctorate; supplies no operating or investment evidence. (reliability: A; access: full; accessed: 2026-08-19; locator: 2016–2017 roster)
- ★★ | Northern Arizona University — commencement program | https://archive.library.nau.edu/digital/api/collection/nauarch/id/46661/download | 2017 | institutional PDF | Retrospective biography and Illuminics/Quova lead; verify transaction mechanics elsewhere. (reliability: B; access: full; accessed: 2026-08-19; locator: p. 6)
- ★★★ | Martin Casado — And So… | https://blogs.vmware.com/networkvirtualization/2016/02/martin-casado.html/ | 2016-02-24 | first-person contemporaneous transition post | Exact April 1 a16z start, VMware adviser transition, and succession framing. (reliability: A; access: full; accessed: 2026-08-19; locator: closing transition paragraphs)
- ★★★ | Marc Andreessen — Martin Casado joins a16z | https://a16z.com/martin-casado/ | 2016-02-24 | official sponsor/firm announcement | a16z appointment, 2009 Nicira relationship, named people, and firm-reported NSX growth; retrospective sponsor account, not independent financing or audited revenue. (reliability: A/B; access: full; accessed: 2026-08-19; locator: opening, investment, and VMware paragraphs)
- ★★★ | U.S. House Science Committee — Cyber Security: What the Federal Government Can Learn from the Private Sector | https://science.house.gov/2016/1/research-and-technology-subcommittee-and-oversight-subcommittee-hearing-cyber | 2016-01-08 | congressional hearing record | Establishes pre-a16z public testimony, witness role, and contemporaneous VMware title; link through to Casado's written statement. (reliability: A; access: full; accessed: 2026-08-19; locator: witness list and statement link)
- ★★ | Martin Casado — House cybersecurity written statement | https://science.house.gov/sites/republicans.science.house.gov/files/documents/HHRG-114-SY15-WState-MCasado-20160108.pdf | 2016-01-08 | first-person congressional statement PDF | Direct policy and operating record before venture tenure; distinguish recommendations from measured outcomes. (reliability: A; access: full; accessed: 2026-08-19; locator: pp. 1–8)
- ★★★ | MuralNet — About | https://www.muralnet.org/about/ | live; accessed 2026-08-19 | official nonprofit profile | Records 2017 cofounding with Brian Shih and current Casado/Mariel Triggs roles; mutable and insufficient alone for impact totals. (reliability: A/B; access: full; accessed: 2026-08-19; locator: history and team sections)
- ★★★ | Mariel Triggs — House testimony on tribal broadband | https://docs.house.gov/meetings/IF/IF16/20190716/109797/HHRG-116-IF16-Wstate-TriggsM-20190716.pdf | 2019-07-16 | primary congressional testimony PDF | Gives February 2017 MuralNet founding, Casado/Shih roles, motivation, and operating model through the CEO's account. (reliability: A; access: full; accessed: 2026-08-19; locator: pp. 1–3)
- ★★ | Stanford Magazine — Tackling the Tribal Digital Divide | https://stanfordmag.org/contents/tackling-the-tribal-digital-divide | 2020-03 | reported university feature | Named-participant history of MuralNet and Flagstaff formation; conflicts with stronger sources on the MS year. (reliability: B; access: full; accessed: 2026-08-19; locator: biography and MuralNet operating paragraphs)
- ★★ | Multiplying Good — 49th Annual Jefferson Awards | https://www.globenewswire.com/news-release/2021/10/01/2307177/0/en/JOAN-GANZ-COONEY-DR-ANTHONY-FAUCI-AND-JUST-GOODS-AMONG-THIS-YEAR-S-JEFFERSON-AWARD-RECIPIENTS.html | 2021-10-01 | award-giver release | Confirms Casado and Triggs received the 2021 Onassis public-service award; does not independently audit impact. (reliability: A/B; access: full; accessed: 2026-08-19; locator: recipient paragraphs)
- ★★★ | U.S. Senate — eighth bipartisan AI Insight Forum | https://www.schumer.senate.gov/newsroom/press-releases/statements-from-the-eighth-bipartisan-senate-forum-on-artificial-intelligence | 2023-12-06 | Senate event record | Establishes participant roster and routes to Casado's statement; policy participation is not neutral authority. (reliability: A; access: full; accessed: 2026-08-19; locator: Casado entry and statement link)
- ★★★ | Martin Casado — Senate AI Insight Forum statement | https://www.schumer.senate.gov/imo/media/doc/Martin%20Casado%20-%20Statement.pdf | 2023-12-06 | first-person policy PDF | Direct dated position on AI risk, open source, cybersecurity, data, and regulatory capture; disclose AI-investor interest. (reliability: A; access: full; accessed: 2026-08-19; locator: pp. 1–4)
- ★★ | ACM — 2012 technical awards | https://awards.acm.org/binaries/content/assets/press_releases/tech_awards_2012.pdf | 2013 award cycle | award-giver PDF | Officially labels the Grace Murray Hopper Award as 2012 and records then-current roles. (reliability: A; access: full; accessed: 2026-08-19; locator: Casado award paragraph)
- ★★ | NEC C&C Foundation — 2015 C&C Prize | https://sg.nec.com/en_AP/press/201510/ap_20151016_02.html | 2015-10-16 | award-giver announcement | Confirms 2015 team prize with McKeown and Shenker, contradicting current personal/firm 2014 labels. (reliability: A; access: full; accessed: 2026-08-19; locator: Group B recipient section)
- ★★ | Stanford SystemX — SDN and OpenFlow originators receive NEC C&C award | https://systemx.stanford.edu/news/sdn-and-openflow-originators-receive-nec-cc-award | 2015 | institutional award announcement | Corroborates the 2015 award and team attribution; not a source for sole invention. (reliability: A/B; access: full; accessed: 2026-08-19; locator: award and recipient paragraphs)
- ★★ | NEC C&C Foundation — recipient roster | https://www.candc.or.jp/kensyo/recipient_cc.html | live; accessed 2026-08-19 | award-giver index | Independent official year check placing Casado, McKeown, and Shenker in the 2015 roster. (reliability: A; access: full; accessed: 2026-08-19; locator: 2015 Group B entry)
- ★★ | USENIX — Test of Time Awards | https://www.usenix.org/conferences/test-of-time-awards | live through 2026 | award-giver index | Confirms 2025 Open vSwitch and 2026 network-virtualization team awards; durable technical influence is not venture performance. (reliability: A; access: full; accessed: 2026-08-19; locator: 2025 and 2026 NSDI entries)
Primary technical record and independent intellectual history
- ★★★ | Casado et al. — SANE: A Protection Architecture for Enterprise Networks | https://yuba.stanford.edu/~casado/sane/paper.html | 2006 | primary peer-reviewed paper | Earliest priority architecture in the direct technical sequence; preserve full author team and enterprise-security problem. (reliability: A; access: full; accessed: 2026-08-19; locator: abstract and author list)
- ★★★ | Casado et al. — Ethane: Taking Control of the Enterprise | https://yuba.stanford.edu/~casado/ethane_ton_08.pdf | 2007/2009 | primary peer-reviewed PDF | Central logical-control architecture, deployment evidence, and contemporaneous author biography including LLNL, Illuminics, and Nicira. (reliability: A; access: full; accessed: 2026-08-19; locator: abstract; author biography p. 13)
- ★★★ | McKeown et al. — OpenFlow: Enabling Innovation in Campus Networks | https://web.stanford.edu/class/archive/cs/cs244/cs244.1156/papers/openflow.pdf | 2008-04 | primary peer-reviewed PDF | Canonical OpenFlow artifact and essential authorship boundary: Casado is not in the author list. (reliability: A; access: full; accessed: 2026-08-19; locator: title/authors and abstract, pp. 1–2)
- ★★★ | Gude et al. — NOX: Towards an Operating System for Networks | https://yuba.stanford.edu/~casado/nox-ccr-final.pdf | 2008-07 | primary peer-reviewed PDF | Documents Casado's coauthorship inside a broad Stanford/Nicira team and the network-operating-system concept. (reliability: A; access: full; accessed: 2026-08-19; locator: title, author block, abstract)
- ★★★ | Koponen et al. — Onix: A Distributed Control Platform for Large-scale Production Networks | https://www.usenix.org/events/osdi10/tech/full_papers/Koponen.pdf | 2010-10-06 | primary conference PDF | Production-scale control-platform evidence with Nicira, Google, NEC, ICSI, and Berkeley collaborators; no individual engineering allocation. (reliability: A; access: full; accessed: 2026-08-19; locator: title, authors, abstract)
- ★★ | Pettit et al. — Virtual Switching in an Era of Advanced Edges | https://www.openvswitch.org/support/papers/dccaves2010.pdf | 2010 | primary technical PDF | Places Casado in the Nicira/Open vSwitch technical team before acquisition. (reliability: A; access: full; accessed: 2026-08-19; locator: title and author block, p. 1)
- ★★★ | Pfaff et al. — The Design and Implementation of Open vSwitch | https://www.usenix.org/system/files/conference/nsdi15/nsdi15-paper-pfaff.pdf | 2015 | primary NSDI paper PDF | Mature implementation record and later test-of-time source; team outcome rather than proof of Casado primacy. (reliability: A; access: full; accessed: 2026-08-19; locator: title, authors, abstract)
- ★★★ | Koponen et al. — Network Virtualization in Multi-tenant Datacenters | https://www.usenix.org/conference/nsdi14/technical-sessions/presentation/koponen | 2014-04 | primary NSDI paper, slides, video, and audio | Full 25-author production-network-virtualization record and later test-of-time source; collective authorship remains explicit. (reliability: A; access: full; accessed: 2026-08-19; locator: proceedings pp. 203–216; canonical session page)
- ★★★ | Martín Casado, Nate Foster, and Arjun Guha — Abstractions for Software-Defined Networks | https://doi.org/10.1145/2661061.2661063 | 2014-09 online; 2014-10 issue | CACM journal article | Conceptual synthesis of SDN abstractions; canonical DOI may be gated, while the full author PDF is public. (reliability: A; access: full via author PDF/partial canonical; accessed: 2026-08-19; locator: CACM 57(10), pp. 86–95)
- ★★★ | Martín Casado, Nick McKeown, and Scott Shenker — From Ethane to SDN and Beyond | https://web.stanford.edu/class/cs244/papers/ethane_to_sdn_and_beyond.pdf | 2019-10 | ACM SIGCOMM CCR editorial note PDF | Three-author retrospective on the technical lineage; explicitly non-peer-reviewed and unsuitable as sole decision-date evidence. (reliability: A for author recollection; access: full; accessed: 2026-08-19; locator: CCR 49(5), four-page PDF)
- ★★★ | Patil et al. — GoEX: Perspectives and Designs Towards a Runtime for Autonomous LLM Applications | https://arxiv.org/abs/2404.06921 | 2024-04-10 | arXiv preprint | Ten-author agent-runtime paper on delegation, undo, and damage confinement; primary research record, not investment-performance evidence. (reliability: A; access: full abstract/PDF/source; accessed: 2026-08-19; locator: v1 title/authors, abstract, system sections)
- ★★★ | Yang et al. — Cloud Infrastructure Management in the Age of AI Agents | https://arxiv.org/abs/2506.12270 | 2025-06-13 preprint; 2025-08 journal | ACM SIGOPS OSR article/preprint | Nine-author current technical work on AI-agent cloud management; useful for doctrine evolution while preserving research-team credit. (reliability: A; access: full; accessed: 2026-08-19; locator: eight-page article; OSR 59(1))
- ★★★ | Feamster, Rexford, and Zegura — The Road to SDN: An Intellectual History of Programmable Networks | https://www.cs.princeton.edu/courses/archive/fall13/cos597E/papers/sdnhistory.pdf | 2014-04 | independent peer-reviewed history PDF | Strongest check on lone-inventor narratives and map of active networking, control/data-plane separation, OpenFlow, operating systems, and virtualization. (reliability: B; access: full; accessed: 2026-08-19; locator: historical synthesis and conclusion, pp. 9–10)
- ★★ | Stanford Engineering — Open networking summit to explore SDN | https://engineering.stanford.edu/news/open-networking-summit-explore-software-defined-networking | 2011 | near-contemporaneous institutional history | NSF/Clean Slate, Stanford/Berkeley collaboration, OpenFlow, GENI, and industry-adoption context. (reliability: B; access: full; accessed: 2026-08-19; locator: research-origin paragraphs)
- ★★ | ICSI — A Revolution with ICSI Roots | https://icsi.berkeley.edu/stories/a-revolution-with-icsi-roots/ | retrospective institutional history | named-collaborator account of Nicira formation and the shift from vendor indifference toward network virtualization; requires contemporaneous control. (reliability: B; access: full; accessed: 2026-08-19; locator: Nicira formation and research-to-company passages)
- ★★ | ACM SIGCOMM — Test of Time Paper Award roster | https://www.sigcomm.org/awards/acm-sigcomm-test-of-time-paper-award | live | award-giver index | Confirms Ethane's 2017 recognition; use only for award fact and collective technical longevity. (reliability: A; access: full; accessed: 2026-08-19; locator: 2017 entry)
- ★★ | ACM SIGOPS — Hall of Fame history | https://sigops.hosting.acm.org/about/history/ | live | award-giver history | Confirms Onix's 2021 Hall of Fame entry; not venture-performance evidence. (reliability: A; access: full; accessed: 2026-08-19; locator: 2021 entries)
Nicira, VMware, financing, transaction, and operating records
- ★★★ | Virtualization Review — Nicira interview with Martin Casado | https://virtualizationreview.com/articles/2012/07/09/interview-nicira-martin-casado-nicira-network-virtualization.aspx | 2012-07-09 | contemporaneous founder interview | Direct pre-exit account of product, customers, competitors, pricing, and adoption; valuable decision-date record. (reliability: A/B; access: full; accessed: 2026-08-19; locator: background, customers, and competitors questions)
- ★★★ | Fortune — Nicira wants to reinvent routing | https://fortune.com/2012/05/01/nicira-wants-to-reinvent-routing/ | 2012-05-01 | contemporaneous reported profile | Financing, founders, customers, competitive risks, and biographical claims before the sale; contains Cartagena birthplace conflict. (reliability: B; access: full; accessed: 2026-08-19; locator: financing, customers, risks, and biography paragraphs)
- ★★★ | VMware Form 8-K — Nicira acquisition completion | https://www.sec.gov/Archives/edgar/data/1124610/000112461012000026/form8-k.htm | 2012-08-24 | SEC-filed transaction record | Close date, wholly owned status, approximately $1.095B cash, $168M assumed unvested awards, and escrow; do not equate with personal proceeds. (reliability: A; access: full; accessed: 2026-08-19; locator: Item 2.01)
- ★★★ | VMware Form 10-Q — Nicira acquisition accounting | https://www.sec.gov/Archives/edgar/data/1124610/000112461012000030/vmw-9302012x10q.htm | 2012 | SEC-filed financial record | $1.0996B consideration net of acquired cash and the pre-/post-combination equity distinction; accounting measure differs from headline price. (reliability: A; access: full; accessed: 2026-08-19; locator: Note B, “Acquisition of Nicira, Inc.”)
- ★★★ | VMware Form 10-K — Nicira acquisition note | https://www.sec.gov/Archives/edgar/data/1124610/000112461013000009/vmw-12312012x10k.htm | 2013 | audited annual filing | Final annual acquisition accounting and business rationale; no founder-level ownership or proceeds. (reliability: A; access: full; accessed: 2026-08-19; locator: Note B, “Acquisition of Nicira, Inc.”)
- ★★ | VMware — Introducing VMware NSX | https://blogs.vmware.com/networkvirtualization/2013/08/vmware-nsx.html/ | 2013-08-26 | official product announcement | Shows the platform combined Nicira and VMware technologies; prevents attribution of the entire outcome to one founder. (reliability: A; access: full; accessed: 2026-08-19; locator: opening and architecture passages)
- ★★ | Network World — VMware's Casado talks about evolving SDN use cases | https://www.networkworld.com/article/930386/vmwares-casado-talks-about-evolving-sdn-use-cases-including-a-prominent-role-for-security.html | 2014-10-06 | operating interview | Direct role, security thesis, and $100M run-rate claim; annualized metric needs audited-company context. (reliability: A/B; access: full; accessed: 2026-08-19; locator: opening role and run-rate questions)
- ★★ | VMware — Rajiv Ramaswami appointed to lead Networking and Security | https://www.globenewswire.com/news-release/2016/02/24/1325965/0/en/VMware-Appoints-Former-Broadcom-and-Cisco-Executive-Dr-Rajiv-Ramaswami-to-Lead-Networking-and-Security-Business.html | 2016-02-24 | official company release | Succession and role boundary as Casado moved to a16z; company-authored. (reliability: A; access: full; accessed: 2026-08-19; locator: appointment and Casado-transition paragraphs)
- ★★★ | Martin Casado — Bringing in an External CEO | https://a16z.com/bringing-in-an-external-ceo/ | 2020-03-06 | first-person retrospective essay | Direct account of Nicira's three-CEO sequence, founder authority, and formal-title choices; demands contemporaneous governance checks. (reliability: A; access: full; accessed: 2026-08-19; locator: opening and three-CEO/Steve Mullaney passages)
Independent market, policy, conflict, and skeptical context
- ★★★ | FTC — staff report on AI partnerships and investments | https://www.ftc.gov/news-events/news/press-releases/2025/01/ftc-issues-staff-report-ai-partnerships-investments-study | 2025-01 | regulator report release | Independent concentration, cloud-partnership, lock-in, access, and governance questions for an AI-infrastructure investor's claims. (reliability: A; access: full; accessed: 2026-08-19; locator: findings and report link)
- ★★★ | FTC Office of Technology — Partnerships Between Cloud Service Providers and AI Developers | https://www.ftc.gov/system/files/ftc_gov/pdf/p246201_aipartnerships6breport_redacted_0.pdf | 2025-01 | regulator staff report PDF | Primary 6(b)-study counterevidence on cloud commitments, equity and revenue-sharing, control and exclusivity, information transfer, compute access, and switching costs; the report disclaims a complete legal or economic market analysis. (reliability: A; access: full; accessed: 2026-08-19; locator: executive summary pp. 1–3; §§4–5, printed pp. 16–37)
- ★★★ | NTIA — Dual-Use Foundation Models with Widely Available Model Weights | https://www.ntia.gov/sites/default/files/publications/ntia-ai-open-model-report.pdf | 2024-07 | U.S. Commerce Department report PDF | Independent policy baseline recognizing competition, research, privacy, safety, misuse, and accountability tradeoffs; found insufficient evidence for immediate restrictions while recommending monitoring, audits, transparency, and future action if risks change. (reliability: A; access: full; accessed: 2026-08-19; locator: executive summary and policy recommendations)
- ★★★ | Snowflake — FY2025 Form 10-K | https://www.sec.gov/Archives/edgar/data/1640147/000164014725000052/snow-20250131.htm | filed 2025-03-26 | SEC-filed issuer financial record | Current test of compute and margin claims: product gross margin fell from 74% to 71%, third-party cloud infrastructure cost rose, and the filing identifies workload mix, pricing, new products, AI investment, efficiency, and stock compensation as drivers. (reliability: A; access: full; accessed: 2026-08-19; locator: MD&A, printed pp. 70–71)
- ★★★ | Dropbox — FY2025 Form 10-K | https://www.sec.gov/Archives/edgar/data/1467623/000146762326000008/dbx-20251231.htm | filed 2026-02-20 | SEC-filed issuer financial record | Current boundary on the 2021 repatriation case: Dropbox still operates owned/colocated infrastructure, while 2025 gross margin fell from 83% to 80% as infrastructure refresh and facilities costs rose; architecture changes cost levels but does not freeze them. (reliability: A; access: full; accessed: 2026-08-19; locator: MD&A, printed pp. 57–59)
- ★★★ | California Governor — SB 1047 veto message | https://www.gov.ca.gov/wp-content/uploads/2024/09/SB-1047-Veto-Message.pdf | 2024-09-29 | official executive-action PDF | Primary counterevidence to a simple regulation/no-regulation frame: rejects a compute proxy while calling for empirical analysis, proactive safeguards, and risk-sensitive guardrails. (reliability: A; access: full; accessed: 2026-08-19; locator: pp. 1–2)
- ★★★ | International AI Safety Report — interim report | https://www.gov.uk/government/publications/international-scientific-report-on-the-safety-of-advanced-ai/international-scientific-report-on-the-safety-of-advanced-ai-interim-report | 2024 | international scientific synthesis | Independent boundary on the “safe” claim: records present harms, disputed severe risks, evidence gaps, and limited assurance methods without collapsing uncertainty into either catastrophe or no-risk advocacy. (reliability: B; access: full; accessed: 2026-08-19; locator: executive summary, malicious-use sections, and §5)
- ★★ | A Path for Science- and Evidence-based AI Policy — expert statement | https://understanding-ai-safety.org/ | 2024 | multi-signatory policy statement cited by Casado | Supports marginal-risk study while calling for research across discrimination, scams, misinformation, sexual-abuse material, cybersecurity, environment, biosecurity, and extreme risks; endorsement is not outcome evidence. (reliability: B; access: full; accessed: 2026-08-19; locator: recommendation and risk-domain list)
- ★★ | a16z — Katherine Boyle profile | https://a16z.com/author/katherine-boyle/ | live; accessed 2026-08-19 | official mutable contributor profile | Establishes Boyle's a16z role and American Dynamism affiliation for the joint WSJ policy-essay interest boundary; not evidence of the gated article body. (reliability: A for current firm identity; access: full; accessed: 2026-08-19; locator: profile description)
- ★★ | a16z — Emerging Architectures for Modern Data Infrastructure, updated landing page | https://a16z.com/emerging-architectures-for-modern-data-infrastructure/ | live update route; accessed 2026-08-19 | official version-navigation page | Points to the original 2020 article and later architecture updates; used only to preserve version boundaries, not as evidence known in October 2020. (reliability: A for version record; access: full; accessed: 2026-08-19; locator: updated-reference-architecture notice and original-version link)
- ★★★ | California Legislature — SB 1047 status and bill history | https://leginfo.legislature.ca.gov/faces/billStatusClient.xhtml?bill_id=202320240SB1047 | 2024 | enacted-process record | Primary legislative baseline for Casado/a16z AI-safety advocacy; bill text, votes, veto, and commentary must remain distinct. (reliability: A; access: full; accessed: 2026-08-19; locator: status, votes, and bill-text tabs)
- ★★★ | Washington Post — AI spending and revenue-gap analysis | https://www.washingtonpost.com/technology/2024/07/24/ai-bubble-big-tech-stocks-goldman-sachs/ | 2024-07-24 | reported market analysis | Capital-intensity and monetization counterweight to falling-cost and expanding-demand narratives; access may vary. (reliability: B; access: full on access date; accessed: 2026-08-19; locator: spending, revenue-gap, and analyst-argument paragraphs)
- ★★ | Fortune — Base AI Policy on Evidence, Not Existential Angst | https://fortune.com/2024/12/14/ai-regulation-policy/ | 2024-12-14 | first-person guest commentary | Original publication route for Casado's policy argument; compare with the a16z republication and preserve access/version boundaries. (reliability: A for authored view; access: full at mapping date; accessed: 2026-08-19; locator: full commentary paragraphs)
- ★★ | TechCrunch — a16z lobbying spending | https://techcrunch.com/2025/08/25/a16z-spends-1-49m-in-washington-lobbying-while-rivals-mostly-sit-out/ | 2025-08-25 | reported policy/conflict record | Quantifies firm policy engagement and supplies economic-interest context; does not establish Casado's individual direction or benefit. (reliability: B; access: full; accessed: 2026-08-19; locator: spending and firm-policy paragraphs)
- ★★ | PitchBook-NVCA — Venture Monitor hub | https://nvca.org/pitchbook-nvca-venture-monitor/ | current archive; accessed 2026-08-19 | industry dataset/report hub | Routes to vintage-correct financing, fundraising, concentration, and exit context; methodology and later revision must be disclosed. (reliability: B; access: full; accessed: 2026-08-19; locator: quarterly report archive)
- ★★ | Cambridge Associates — US PE/VC Benchmark Commentary, Calendar Year 2024 | https://www.cambridgeassociates.com/insight/us-pe-vc-benchmark-commentary-calendar-year-2024/ | 2025 | benchmark commentary | Net-return and vintage comparison boundary; private marks, company exit values, and LP performance remain different measures. (reliability: B; access: full; accessed: 2026-08-19; locator: methodology and US VC results sections)
Priority direct writings and presentations
- ★★★ | Martin Casado and Matt Bornstein — The New Business of AI (and How It's Different From Traditional Software) | https://a16z.com/the-new-business-of-ai-and-how-its-different-from-traditional-software/ | 2020-02-16 | coauthored essay | Early falsifiable account of AI cost structures, services, defensibility, data, and margins; preserve joint authorship and publication-date information set. (reliability: A; access: full; accessed: 2026-08-19; locator: section headings and charts)
- ★★★ | Sarah Wang and Martin Casado — The Cost of Cloud, a Trillion Dollar Paradox | https://a16z.com/the-cost-of-cloud-a-trillion-dollar-paradox/ | 2021-05-27 | coauthored essay | Central cloud-economics and repatriation argument with public-company examples; forecast and accounting assumptions require dated outcome checks. (reliability: A; access: full; accessed: 2026-08-19; locator: cost/paradox framework and case tables)
- ★★★ | Martin Casado — The Cloud Killed Infrastructure. Long Live Infrastructure! | https://a16z.com/the-cloud-killed-infrastructure-long-live-infrastructure/ | 2022-06-09 | first-person essay | Investment-era thesis on cloud abstraction, developer control, and a renewed infrastructure layer; connect to deals without assuming performance. (reliability: A; access: full; accessed: 2026-08-19; locator: section headings)
- ★★★ | Martin Casado and Peter Levine — Market Annealing: Getting to $10M ARR in Very Early Markets | https://a16z.com/market-annealing-getting-to-10m-arr-in-very-early-markets/ | 2023-01-11 | coauthored operating essay | Explicit early-market creation mechanism and $10M-ARR milestone; later work must separate advice, observed examples, and causal efficacy. (reliability: A; access: full; accessed: 2026-08-19; locator: “Market annealing” framework and stages)
- ★★★ | Matt Bornstein, Guido Appenzeller, and Martin Casado — Who Owns the Generative AI Platform? | https://a16z.com/who-owns-the-generative-ai-platform/ | 2023-01-19 | coauthored market map | Dated stack, value-accrual, moat, and market-structure predictions; three-author evidence, not a sole Casado doctrine. (reliability: A; access: full; accessed: 2026-08-19; locator: stack diagram and conclusion)
- ★★★ | Guido Appenzeller, Matt Bornstein, and Martin Casado — Navigating the High Cost of AI Compute | https://a16z.com/navigating-the-high-cost-of-ai-compute/ | 2023-04-27 | coauthored essay | Concrete cost, capacity, procurement, and infrastructure constraints for AI companies; assumptions should be checked against later prices and architectures. (reliability: A; access: full; accessed: 2026-08-19; locator: cost drivers and mitigation sections)
- ★★★ | Martin Casado and Sarah Wang — The Economic Case for Generative AI and Foundation Models | https://a16z.com/the-economic-case-for-generative-ai-and-foundation-models/ | 2023-08-03 | coauthored essay/presentation | Core demand, cost-curve, surplus, and business-model argument; publication-date forecasts permit later falsification. (reliability: A; access: full; accessed: 2026-08-19; locator: presentation sections and figures)
- ★★★ | Martin Casado — Base AI Policy on Evidence, Not Existential Angst | https://a16z.com/base-ai-policy-on-evidence-not-existential-angst/ | 2024-12-16 | first-person policy essay | Current deregulatory/open-source thesis from a financially interested investor; pair with bill text, regulator evidence, and credible opposing cases. (reliability: A; access: full; accessed: 2026-08-19; locator: evidence, risk, and policy-recommendation sections)
- ★★ | Sarah Wang and Martin Casado — Questioning Margins Is a Boring Cliché | https://a16z.com/questioning-margins-is-a-boring-cliche/ | 2025-08-21 | coauthored essay | Challenges static margin screens and reframes value/cost dynamics; needs matched company outcomes and cash economics. (reliability: A; access: full; accessed: 2026-08-19; locator: opening thesis and examples)
- ★★★ | Martin Casado and Peter Lauten — The Empty Promise of Data Moats | https://a16z.com/the-empty-promise-of-data-moats/ | 2019-05-09 | coauthored essay | Early direct statement on data-network effects and defensibility; valuable precursor to later generative-AI moat claims. (reliability: A; access: full; accessed: 2026-08-19; locator: data-moat argument and conditions)
- ★★ | Peter Lauten and Martin Casado — Growth+Sales: The New Era of Enterprise Go-to-Market | https://a16z.com/growthsales-the-new-era-of-enterprise-go-to-market/ | 2020-07-29 | coauthored essay | Product-led growth, enterprise sales, and route-to-market evidence; verify each named example and preserve joint authorship. (reliability: A; access: full; accessed: 2026-08-19; locator: section headings)
- ★★ | Matt Bornstein, Martin Casado, and Jennifer Li — Emerging Architectures for Modern Data Infrastructure | https://a16z.com/emerging-architectures-for-modern-data-infrastructure-2020/ | 2020-10-15 | coauthored technical essay | Original dated data-stack map and market forecast connecting technical architecture to investment search; later landing-page updates are excluded from this information set. (reliability: A; access: full; accessed: 2026-08-19; locator: architecture diagrams, blueprint sections, and version boundary)
- ★★ | Jennifer Li and Martin Casado — Bottom Up Pricing & Packaging: Let the User Journey Be Your Guide | https://a16z.com/bottom-up-pricing-packaging-let-the-user-journey-be-your-guide/ | 2021-03-11 | coauthored essay | Pricing and adoption doctrine for developer-led companies; analysis must separate examples from demonstrated causal efficacy. (reliability: A; access: full; accessed: 2026-08-19; locator: user-journey and pricing sections)
- ★★ | Martin Casado and Katherine Boyle — AI Talks Leave “Little Tech” Out | https://www.wsj.com/articles/ai-talks-leave-little-tech-out-homeland-security-adversaries-open-source-board-46e3232d | 2024-05-15 | coauthored opinion essay | Headline-level policy signal only; no hidden reasoning, examples, or prescriptions are reconstructed without legitimate full access. (reliability: A for authored view; access: partial/paywalled; accessed: 2026-08-19; locator: headline-level record and a16z archive attribution; no full body)
- ★★ | Martin Casado and Ion Stoica — Keep the Code Behind AI Open, Say Two Entrepreneurs | https://www.economist.com/by-invitation/2024/07/29/keep-the-code-behind-ai-open-say-two-entrepreneurs | 2024-07-29 | coauthored guest essay | The Economist's public post identifies both writers and preserves one bounded joint excerpt; the article body, evidence, exceptions, and internal contribution allocation remain unresolved. (reliability: A for publisher attribution and excerpt; access: partial/paywalled; accessed: 2026-08-19; locator: canonical headline plus The Economist public-post attribution; no full body)
- Supporting publisher route | The Economist — public attribution for Keep the Code Behind AI Open | https://www.linkedin.com/posts/the-economist_keep-the-code-behind-ai-open-say-two-entrepreneurs-activity-7224300277560946688-jvPw | 2024-07 | primary publisher social post | Names Martin Casado and Ion Stoica as the guest-essay writers and supplies one short attributed excerpt; does not substitute for the gated body. (reliability: A for publisher attribution; access: full; accessed: 2026-08-19; locator: post body, sentence immediately above linked By Invitation card)
- ★★ | Martin Casado and Anne Neuberger — America Cannot Lose the Robotics Race | https://www.a16z.news/p/america-cannot-lose-the-robotics | 2025-09-26 | coauthored newsletter/op-ed reproduction | Industrial-policy and robotics-capital thesis; use the full publisher copy while preserving joint authorship and advocacy interest. (reliability: A; access: full; accessed: 2026-08-19; locator: section headings)
Priority talks, podcasts, and transcript routes
- ★★★ | Invest Like the Best — Martin Casado: The Past, Present, and Future of Digital Infrastructure | https://joincolossus.com/episode/casado-the-past-present-and-future-of-digital-infrastructure/ | 2022-06-07 | long-form podcast | Full 56:44 publisher audio; current publisher text is only partial, with a secondary archival excerpt used as a locator and selected wording checked against audio. (reliability: A for direct voice, B for secondary text; access: full audio / partial current publisher transcript; accessed: 2026-08-20; locator: official enclosure timestamps, with approximately four-second page-clock drift)
- ★★★ | Invest Like the Best — Martin Casado: Entering Uncharted AI Territory | https://joincolossus.com/episode/casado-entering-uncharted-ai-territory/ | 2024-07-09 | long-form podcast | Full 1:08:03 publisher audio; current publisher text is partial and third-party ASR is navigation-only. (reliability: A for direct voice, B for navigation text; access: full audio / partial current publisher transcript; accessed: 2026-08-20; locator: official enclosure timestamps, with approximately one-minute page-clock drift)
- ★★★ | From the New World — Martin Casado: AI's Hard Limits | https://www.fromthenew.world/p/martin-casado-ai-hard-limits | 2024-09-02 | long-form podcast/post | Direct AI capability, constraint, policy, and market argument; preserve host framing and exact audio/transcript version. (reliability: A for direct voice, B for publisher framing; access: full; accessed: 2026-08-20; locator: chapter/timestamp scheme on publisher page)
- ★★ | Turpentine VC E70 — Martin Casado on AI Innovation and AGI | https://metacast.app/podcast/turpentine-vc-venture-capital-and-investing/LUJoKypp/e70-martin-casado-of-a16z-on-ai-innovation-and-agi/zb2A3RvL | 2024-12-24 | replay podcast | E70 is a 1:43:40 replay of the 2024-06-28 Cognitive Revolution original, whose 1:48:20 publisher audio/video and speaker-labelled transcript supply the evidence; count once. (reliability: A for original direct record, B for replay metadata; access: full original transcript/audio and full replay audio; accessed: 2026-08-20; locator: original publisher timestamps)
- ★★★ | a16z Podcast — Where Value Will Accrue in AI, with Martin Casado and Sarah Wang | https://a16z.com/podcast/where-value-will-accrue-in-ai-martin-casado-sarah-wang/ | 2025-05-27 | firm LP Summit panel | Full 21:41 official audio, no publisher transcript; third-party ASR was navigation-only and Casado/Wang turns remain separate. (reliability: A for direct voice, B for navigation text; access: full audio / partial text; accessed: 2026-08-20; locator: official-audio timestamps)
- ★★ | a16z Podcast — AI Is Upending SaaS Pricing | https://a16z.com/podcast/ai-is-upending-saas-pricing/ | 2025-07-18 | firm podcast | Full 42:52 official audio with partial public transcript and bounded speaker-checked navigation ASR; preserve Scott Woody's separate operating claims and Metronome interest. (reliability: A for direct voice, B for navigation text; access: full audio / partial text; accessed: 2026-08-20; locator: official-audio timestamps)
- ★★★ | a16z Podcast — Why a16z's Martin Casado Believes the AI Boom Still Has Years to Run | https://a16z.com/podcast/why-a16zs-martin-casado-believes-the-ai-boom-still-has-years-to-run/ | 2025-12-30 | replay of Generalist interview | Underlying Generalist interview published 2025-10-07 (1:24:44); a16z replay is 1:22:20. Count once and date claims to the original. (reliability: A for original audio, B for chapter map/third-party transcript; access: full original and replay audio / partial text; accessed: 2026-08-20; locator: Generalist original chapter times)
- ★★★ | a16z Podcast — AI's Capital Flywheel: Models, Money, and the Future of Power | https://a16z.com/podcast/ais-capital-flywheel-models-money-and-the-future-of-power/ | 2026-02-19 | replay of Latent Space interview | Original Latent Space audio/transcript is 55:18; a16z replay is 57:52 with inserted material. Count once and preserve Casado/Wang attribution. (reliability: A for original direct record; access: full original transcript/audio and replay audio; accessed: 2026-08-20; locator: original Latent Space timestamps)
- ★★★ | 20VC — Martin Casado on whether the venture model is broken | https://www.tapesearch.com/episode/20vc-a16z-s-martin-casado-on-how-the-venture-model-is-broken-why-vcs-should-be-running-wall-st-who-wins-and-who-loses-in-the-next-generation-of-venture-investing-lessons-from-marc-andreesen-ben-horowitz-and-chris-dixon/BbFqixXybsSEEV8iJT3CuE | 2022-12-05 | long-form podcast | Complete 51:52 official RSS audio; public transcript routes are incomplete/gated, so bounded ASR supported timestamped paraphrase and no verbatim quote. (reliability: A for direct official audio, B for navigation text; access: full audio / partial text; accessed: 2026-08-20; locator: official Libsyn audio timestamps)
- ★★★ | a16z Podcast — Is Non-Consensus Investing Overrated? | https://a16z.com/podcast/is-non-consensus-investing-overrated/ | 2025-09-04 | firm podcast | Direct current debate on contrarianism, consensus, selection, and venture process; preserve participant attribution and firm-production bias. (reliability: A for direct voice; access: full transcript/audio; accessed: 2026-08-20; locator: publisher transcript timecodes)
- ★★ | a16z Podcast — Infrastructure… Is Everything | https://a16z.com/podcast/a16z-podcast-infrastructure-is-everything/ | 2016-02-25 | firm podcast | Earliest transition-era direct discussion of infrastructure and operating formation; complete official audio was reviewed with bounded navigation text and no machine-only quote. (reliability: A for direct voice; access: partial text/full audio; accessed: 2026-08-20; locator: audio timestamps; show notes)
- ★★ | a16z Podcast — Selling to Developers & Open Source Business Models | https://a16z.com/podcast/a16z-podcast-selling-to-developers/ | 2016-04-13 | firm podcast | Early developer-first go-to-market and open-source business-model evidence. (reliability: A for direct voice; access: partial text/full audio; accessed: 2026-08-20; locator: audio timestamps; show notes)
- ★★ | a16z — Trends in—and the Future of—Infrastructure | https://a16z.com/trends-in-and-the-future-of-infrastructure/ | 2016-08-21 | 23-minute talk/video | Early a16z infrastructure map close to investment-career entry; full video permits timestamped analysis. (reliability: A for direct voice; access: full video; accessed: 2026-08-20; locator: video timestamps)
- ★★ | a16z Podcast — Pricing, Pricing, Pricing | https://a16z.com/podcast/a16z-podcast-pricing-pricing-pricing/ | 2016-08-13 | firm podcast with transcript | Early pricing doctrine and examples; preserve speaker turns. (reliability: A for direct voice; access: full transcript/audio; accessed: 2026-08-20; locator: timestamped transcript)
- ★★ | a16z Podcast — All About Microservices | https://a16z.com/podcast/a16z-podcast-all-about-microservices/ | 2016-09-01 | firm podcast with transcript | Technical and market-architecture evidence from the first investing year. (reliability: A for direct voice; access: full transcript/audio; accessed: 2026-08-20; locator: timestamped transcript)
- ★★ | a16z — Software Secures the World | https://a16z.com/software-secures-the-world/ | 2017-02-12 | 20-minute talk/video | Security thesis linking technical formation to market search; claim-level outcome tests remain later work. (reliability: A for direct voice; access: full video; accessed: 2026-08-20; locator: video timestamps)
- ★★ | a16z — Going to Market When No Market Exists | https://a16z.com/going-to-market-when-no-market-exists/ | 2017-06-09 | talk/video and deck | Early precursor to market annealing and category formation, with a full audiovisual route. (reliability: A for direct voice; access: full video/page; accessed: 2026-08-20; locator: video timestamps and deck sections)
- ★ | a16z — Navigating Uncertainty: Advice for Graduates (and Others Changing Course) | https://a16z.com/navigating-uncertainty-advice-for-graduates-and-others-changing-course/ | 2017-07-02 | eight-minute talk/video | Biographical judgment and career advice; lower direct investment value but useful for formation/evolution. (reliability: A for direct voice; access: full video; accessed: 2026-08-20; locator: video timestamps)
- ★★ | a16z Podcast — Creating a Category, from Pricing to Positioning | https://a16z.com/podcast/a16z-podcast-creating-a-category-from-pricing-to-positioning/ | 2018-02-24 | three-speaker firm podcast | Complete 31:50 official audio was reviewed with strict Casado/Feaster/Chokshi separation; local ASR was navigation-only, material passages and handoffs were manually checked, and no verbatim quote was promoted. (reliability: A for direct audio, B for navigation text; access: full audio / partial text; accessed: 2026-08-20; locator: exact official-audio timestamps)
- ★★ | a16z — The World Through an API | https://a16z.com/the-world-through-an-api/ | 2018-03-09 | 18-minute talk/video | API-economy thesis close to Kong/Mashape-era investments; requires deal-attribution separation. (reliability: A for direct voice; access: full video; accessed: 2026-08-20; locator: video timestamps)
- ★★★ | Software Engineering Daily — Software Chasms with Martin Casado | https://softwareengineeringdaily.com/2019/01/28/software-chasms-with-martin-casado/ | 2019-01-28 | long-form podcast with publisher transcript | Detailed technical-to-market transition and infrastructure history; strong early spoken route. (reliability: A for direct voice; access: full transcript/audio; accessed: 2026-08-20; locator: transcript/timestamps)
- ★★ | a16z Podcast — Gross Margins: Early to Late, What They Do (and Don't) Tell You | https://a16z.com/podcast/a16z-podcast-gross-margins-early-to-late-what-they-do-and-dont-tell-you/ | 2020-06-26 | firm podcast | Margin-screen evidence to compare with 2025 writing; complete official audio was speaker-checked with secondary text used only for navigation. (reliability: A for direct voice; access: partial text/full audio; accessed: 2026-08-20; locator: audio timestamps; show notes)
- ★★ | a16z Podcast — On Fear and Leadership: Product to Sales, CTOs to CEOs | https://a16z.com/podcast/a16z-podcast-on-fear-and-leadership-product-to-sales-ctos-ceos/ | 2020-12-04 | firm podcast | Founder-role and leadership-transition evidence relevant to Nicira's CEO sequence and board practice. (reliability: A for direct voice; access: partial text/full audio; accessed: 2026-08-20; locator: audio timestamps; show notes)
- ★★ | Software Engineering Daily — Cloud Cost with Martin Casado | https://softwareengineeringdaily.com/2021/06/25/cloud-cost-with-martin-casado/ | 2021-06-25 | podcast with publisher transcript route | Direct elaboration of the cloud-cost thesis; pair with the coauthored essay and later outcomes. (reliability: A for direct voice; access: full transcript/audio; accessed: 2026-08-20; locator: transcript/timestamps)
- ★★ | a16z Podcast — Cloud Wars, Company Wars, and Innovating Through Change | https://a16z.com/podcast/cloud-wars-company-wars-and-innovating-through-change/ | 2022-09-07 | multi-speaker firm podcast | Competitive transition and operator history; separate Casado's turns from co-speakers. (reliability: A for direct voice; access: partial text/full audio; accessed: 2026-08-20; locator: audio timestamps; show notes)
- ★★ | a16z — The Economic Case for Generative AI | https://a16z.com/the-economic-case-for-generative-ai/ | 2023-09-25 | presentation with transcript | Publisher transcript spans 00:00–14:39; 13:35 is the final chapter start, not a verified duration. Solo restatement of the 2023-08-03 Casado/Wang essay, so not independent thesis corroboration. (reliability: A for direct voice; access: full video/transcript; accessed: 2026-08-20; locator: publisher transcript timestamps)
- ★★★ | a16z — Why America Must Lead in AI Investment | https://a16z.com/why-america-must-lead-in-ai-investment/ | 2024-03-05 | policy interview/podcast with transcript | Direct policy and investment argument with full transcript; advocacy interest and co-speaker attribution remain explicit. (reliability: A for direct voice; access: full transcript/audio; accessed: 2026-08-20; locator: timestamped transcript)
- ★★ | a16z Podcast — The Future of Software Development: Vibe Coding, Prompt Engineering, AI Assistants | https://a16z.com/podcast/the-future-of-software-development-vibe-coding-prompt-engineering-ai-assistants/ | 2025-07-21 | multi-speaker firm podcast | Full 44:23 official audio and official YouTube; no publisher transcript, with third-party ASR navigation-only and all speaker turns preserved. (reliability: A for direct voice, B for navigation text; access: full audio/video / partial text; accessed: 2026-08-20; locator: official video/audio timestamps)
- ★★ | a16z Podcast — The State of American AI Policy: From Pause AI to Build | https://a16z.com/podcast/the-state-of-american-ai-policy-from-pause-ai-to-build/ | 2025-08-15 | multi-speaker firm podcast | Full 42:01 official audio and official YouTube; no publisher transcript, with third-party ASR navigation-only and independent policy sources used for comparison. (reliability: A for direct voice, B for navigation text; access: full audio/video / partial text; accessed: 2026-08-20; locator: official video/audio timestamps)
- ★★★ | a16z Podcast — Jack Altman and Martin Casado on the Future of VC | https://a16z.com/podcast/jack-altman-martin-casado-on-the-future-of-vc/ | 2025-09-03 original; 2025-09-04 a16z republication | Uncapped interview and a16z feed-drop edit | Original Uncapped GUID
df6fdb44-887f-11f0-94e9-b3e2a6697529is 52:10; a16z Simplecast editac6fc175-2685-49b6-b64b-1d66e87b4ae4is 53:28. Complete official audio plus a full third-party timestamped navigation transcript; publisher identifies Jack Altman as host. (reliability: A for direct voice, B for navigation text; access: full audio / partial publisher text; accessed: 2026-08-20; locator: a16z edit timestamps) - ★★ | a16z Podcast — Monopolies vs. Oligopolies in AI | https://a16z.com/podcast/monopolies-vs-oligopolies-in-ai/ | 2026-03-20 | wrapper around 2025 interview | One underlying 20VC interview: original 2025-07-28 (1:10:37), a16z feed drop 2025-08-28 (1:17:25), web wrapper 2026-03-20. Count once; no publisher transcript. (reliability: A for official audio/identity, B for navigation ASR; access: full original and a16z-distributed audio / partial text; accessed: 2026-08-20; locator: a16z feed-drop audio timestamps)
Supporting recording, transcript, and counterevidence routes used in T100.3
These are version, navigation, or independent-comparison routes for the 31 priority families above. They do not add to the priority denominator.
- Official Simplecast players for the 2016 a16z episodes: Infrastructure, Selling to Developers, Pricing, and Microservices. Exact publisher audio clocks used where creator transcripts were absent. (reliability: A for direct audio; access: full; accessed: 2026-08-20; locator: elapsed player timestamps)
- Official Simplecast players for Creating a Category, Gross Margins, and Fear and Leadership, plus the Creating a Category API/player record. Complete publisher audio; no creator transcript for these versions. (reliability: A for direct audio and publisher metadata; access: full audio / partial text; accessed: 2026-08-20; locator: elapsed player timestamps and API metadata)
- Official a16z/AI player for AI Is Upending SaaS Pricing. Complete 42:52 audio with partial public text. (reliability: A for direct audio; access: full audio / partial text; accessed: 2026-08-20; locator: episode player timestamps)
- Official a16z player records for Future of Software Development, State of American AI Policy, and Monopolies vs. Oligopolies. Exact IDs, durations, and a16z feed versions. (reliability: A for publisher metadata/audio; access: full audio; accessed: 2026-08-20; locator: player metadata and elapsed time)
- Current Colossus routes for Digital Infrastructure and Uncharted AI. Current publisher audio is full while page transcript text is partial. (reliability: A for direct audio; access: full audio / partial text; accessed: 2026-08-20; locator: chapters and enclosure timestamps)
- Software Engineering Daily publisher transcripts: SED756 — Software Chasms and SED1287 — Cloud Cost. (reliability: A; access: full; accessed: 2026-08-20; locator: PDF pages and printed timestamps)
- Official a16z YouTube recordings: Trends/Future Infrastructure, Software Secures the World, Going to Market, Navigating Uncertainty, World Through an API, Economic Case presentation, Future Software, and State of American AI Policy. (reliability: A for direct voice; access: full video/captions where noted; accessed: 2026-08-20; locator: video timestamps)
- Official 20VC episode pages for the 2022 venture-model interview and the 2025 market-structure interview. Full official RSS audio and publisher framing; no publisher transcript. (reliability: A for direct audio, B for show-note framing; access: full audio / partial text; accessed: 2026-08-20; locator: official audio clocks)
- Original Uncapped #23 routes: Spotify for Creators episode, official RSS, and Apple episode. These identify the 2025-09-03 original, GUID
df6fdb44-887f-11f0-94e9-b3e2a6697529, and 52:10 runtime; the separate a16z edit is 53:28. (reliability: A for publisher feed/audio, B for directory metadata; access: full audio / partial text; accessed: 2026-08-20; locator: RSS item and player clocks) - Original publisher routes behind later replays: Cognitive Revolution, Generalist, and Latent Space. Used to bind the original interviews, speakers, and clocks rather than treat later a16z/Turpentine versions as new talks. (reliability: A for original direct records, B where transcript is machine-generated; access: full media, full text for Cognitive Revolution/Latent and chapter map for Generalist; accessed: 2026-08-20; locator: original timestamps/chapters)
- Full publisher transcript for Is Non-Consensus Investing Overrated?. (reliability: A; access: full transcript/audio; accessed: 2026-08-20; locator: transcript timecodes)
- Secondary navigation text: Digital Infrastructure archival excerpt, Uncharted AI, Value Accrual, AI Pricing, Future Software, State Policy, Future VC, Monopolies, and AI Boom replay transcript. Used only for navigation/wording checks against exact media, not as independent evidence. (reliability: B/C; access: full or partial as disclosed in notes; accessed: 2026-08-20; locator: third-party timestamps)
- Firm disclosure route: a16z disclosures. Identifies interested-investor context; it does not enumerate all company-specific positions. (reliability: A for firm disclosure; access: full; accessed: 2026-08-20; locator: disclosure page)
- AI coding counterevidence: METR randomized experienced-developer study (2025-07-10). Relevant to mature-repository productivity, not every coding task. (reliability: A for research report; access: full; accessed: 2026-08-20; locator: results/method sections)
- Cloud-market counterevidence: FTC cloud-computing RFI synthesis and NBER cloud concentration paper. Used for switching, concentration, and platform-power comparisons rather than Casado attribution. (reliability: A for government/working-paper records; access: full; accessed: 2026-08-20; locator: findings/abstract and body)
- Open-model and AI-policy controls: NTIA open-model-weights report, California SB 1047 decision, and 2025 U.S. AI Action Plan. Primary policy records used to test episode characterizations. (reliability: A; access: full; accessed: 2026-08-20; locator: executive summary/decision text and named policy pillars)
Vehicle, deal-attribution, exit, and failure records
- ★★★ | Andreessen Horowitz — portfolio directory and disclosure | https://a16z.com/portfolio/ | live; accessed 2026-08-20 | official firm database | Firm candidate universe and warning that the list is incomplete and “exited” does not imply profit; no Casado hit-rate inference. (reliability: A; access: full; accessed: 2026-08-20; locator: disclosure below portfolio table)
- ★★★ | Andreessen Horowitz — canonical investment list | https://a16z.com/investment-list/ | live; accessed 2026-08-20 | dynamic firm database | Denominator/control route; dynamic output is not a stable complete person-linked export and firm disclosure says some positions are omitted. (reliability: A; access: partial/dynamic; accessed: 2026-08-20; locator: dynamic table and disclosure)
- ★★ | Forbes — Martin Casado profile | https://www.forbes.com/profile/martin-casado/ | updated 2026-05-27 | reported investor profile | Additional investment/recognition leads; neither complete denominator nor audited economics. (reliability: B; access: full; accessed: 2026-08-20; locator: “From the Editor” and investment-summary paragraphs)
- ★★★ | SEC — Andreessen Horowitz Fund VII Form D | https://www.sec.gov/Archives/edgar/data/1829358/000182935820000001/xslFormDX08/primary_doc.xml | 2020-12-02 | SEC filing | Vehicle identity/related-person record; no Casado allocation, carry, or performance. (reliability: A; access: full historically/automated 403 on 2026-08-20; accessed: 2026-08-20; locator: Items 2, 3, 13–15)
- ★★★ | Andreessen Horowitz — New Funds, New Era | https://a16z.com/new-funds-new-era/ | 2024-04-16 | firm fundraising announcement | $1.25B Infrastructure pool inside $7.2B; size is not deployment or performance. (reliability: A for firm claim; access: full; accessed: 2026-08-20; locator: allocation paragraph and disclosure block)
- ★★★ | Andreessen Horowitz — Why Did We Raise $15B? | https://a16z.com/why-did-we-raise-15b/ | 2026-01-09 | firm fundraising announcement | $1.7B Infrastructure allocation; no decision-right, carry, reserve, or return disclosure. (reliability: A for firm claim; access: full; accessed: 2026-08-20; locator: allocation list)
Official Casado-linked deal-announcement corpus — 43 records
Every row below is a primary record of what its named author(s) publicly wrote, not proof of sole decision rights, audited company metrics, ownership, or return.
- ★★★ | Martin Casado — SigOpt | https://a16z.com/announcement/sigopt/ | 2016-08-24 | investor-authored announcement | Optimization thesis and explicit deepening of a pre-existing seed position. (reliability: A; access: full; accessed: 2026-08-20; locator: header/byline/date, opening and closing investment paragraphs)
- ★★★ | Martin Casado — RapidAPI | https://a16z.com/announcement/rapidapi/ | 2016-11-21 | investor-authored announcement | API-market thesis and investment record. (reliability: A; access: full; accessed: 2026-08-20; locator: header/byline/date, thesis body, closing)
- ★★★ | Martin Casado — Mashape/Kong | https://a16z.com/announcement/mashape/ | 2017-03-23 | investor-authored announcement | Binds Mashape to Kong and prevents false double counting. (reliability: A; access: full; accessed: 2026-08-20; locator: identity/use and closing paragraphs)
- ★★★ | Martin Casado — ActionIQ | https://a16z.com/announcement/actioniq/ | 2017-10-23 | investor-authored announcement | Customer-data thesis, prior relationship, and disclosed enterprise diligence. (reliability: A; access: full; accessed: 2026-08-20; locator: relationship/diligence and closing paragraphs)
- ★★★ | Martin Casado — Astranis | https://a16z.com/announcement/astranis/ | 2018-03-01 | investor-authored announcement | MicroGEO thesis, outside-domain learning, investment and board. (reliability: A; access: full; accessed: 2026-08-20; locator: architecture and closing board paragraphs)
- ★★★ | Martin Casado — Imply | https://a16z.com/announcement/imply/ | 2018-03-13 | investor-authored announcement | Druid/analytics thesis and a16z-led Series A. (reliability: A; access: full; accessed: 2026-08-20; locator: opening Druid context and closing A paragraph)
- ★★★ | Martin Casado — Yubico | https://a16z.com/announcement/yubico/ | 2018-05-31 | investor-authored announcement | Root-of-trust thesis, product/reference diligence, capital-efficiency claim and board. (reliability: A; access: full; accessed: 2026-08-20; locator: opening, diligence and closing board paragraphs)
- ★★★ | Martin Casado — Eclypsium | https://a16z.com/announcement/eclypsium/ | 2018-12-04 | investor-authored announcement | Firmware-security thesis and seed lead. (reliability: A; access: full; accessed: 2026-08-20; locator: security thesis and closing seed paragraph)
- ★★★ | Martin Casado — Fivetran | https://a16z.com/announcement/fivetran/ | 2019-09-24 | investor-authored announcement | Automated-pipeline thesis, customer encounters, B lead and board. (reliability: A; access: full; accessed: 2026-08-20; locator: thesis/references and closing)
- ★★★ | Martin Casado — Preset | https://a16z.com/announcement/preset/ | 2019-10-10 | investor-authored announcement | Superset commercialization thesis. (reliability: A; access: full; accessed: 2026-08-20; locator: Superset/company distinction and closing)
- ★★★ | Martin Casado — Instabase | https://a16z.com/announcement/instabase/ | 2019-10-21 | investor-authored announcement | Prior-investment chronology, diligence, and workflow-platform thesis. (reliability: A; access: full; accessed: 2026-08-20; locator: “first invested,” diligence, and closing)
- ★★★ | Martin Casado and Ben Horowitz — Anyscale | https://a16z.com/announcement/why-were-investing-in-anyscale/ | 2019-12-17 | coauthored announcement | Ray/distributed-computing thesis, Series A lead and collective board statement. (reliability: A; access: full; accessed: 2026-08-20; locator: exact byline, thesis and closing)
- ★★★ | Martin Casado — Fishtown Analytics/dbt | https://a16z.com/announcement/investing-in-fishtown-analytics-the-makers-of-dbt/ | 2020-04-22 | investor-authored announcement | Company-name continuity and analytics-engineering thesis. (reliability: A; access: full; accessed: 2026-08-20; locator: identity/thesis and closing)
- ★★★ | Martin Casado — Tecton | https://a16z.com/announcement/investing-in-tecton/ | 2020-04-28 | investor-authored announcement | Michelangelo/feature-store thesis and seed-to-A chronology. (reliability: A; access: full; accessed: 2026-08-20; locator: feature-store body and closing seed/A)
- ★★★ | Martin Casado — Rasa | https://a16z.com/announcement/investing-in-rasa/ | 2020-06-23 | investor-authored announcement | Open-source conversational-AI thesis, B lead and historical board. (reliability: A; access: full; accessed: 2026-08-20; locator: product/community and closing)
- ★★★ | Martin Casado — Material Security | https://a16z.com/announcement/investing-in-material-security/ | 2020-06-30 | investor-authored announcement | Email-security thesis and partnership. (reliability: A; access: full; accessed: 2026-08-20; locator: threat/product body and closing)
- ★★★ | Martin Casado — Isovalent | https://a16z.com/announcement/investing-in-isovalent/ | 2020-11-10 | investor-authored announcement | eBPF/Cilium thesis and founder-network evidence. (reliability: A; access: full; accessed: 2026-08-20; locator: adoption/team and closing)
- ★★★ | Martin Casado — Orbit | https://a16z.com/announcement/investing-in-orbit/ | 2020-12-02 | investor-authored announcement | Developer-community system-of-record thesis. (reliability: A; access: full; accessed: 2026-08-20; locator: community body and closing)
- ★★★ | Martin Casado — Parsec | https://a16z.com/announcement/investing-in-parsec/ | 2020-12-15 | investor-authored announcement | 2017 demo, community/enterprise evidence, B lead and board. (reliability: A; access: full; accessed: 2026-08-20; locator: demo/customer and closing)
- ★★★ | Martin Casado — Tackle | https://a16z.com/announcement/investing-in-tackle/ | 2021-03-09 | investor-authored announcement | Portfolio-board sourcing, references, B lead and board. (reliability: A; access: full; accessed: 2026-08-20; locator: discovery/traction and closing)
- ★★★ | Martin Casado — Tabular | https://a16z.com/announcement/investing-in-tabular/ | 2021-08-31 | investor-authored announcement | Iceberg/open-table thesis and Series A lead. (reliability: A; access: full; accessed: 2026-08-20; locator: team/thesis and closing)
- ★★★ | Martin Casado — EngFlow | https://a16z.com/announcement/investing-in-engflow/ | 2021-10-12 | investor-authored announcement | Build-system thesis, customer evidence and seed lead. (reliability: A; access: full; accessed: 2026-08-20; locator: customer and closing)
- ★★★ | Martin Casado — Truffle Security | https://a16z.com/announcement/investing-in-truffle-security/ | 2021-12-08 | investor-authored announcement | Secret-scanning thesis and A lead. (reliability: A; access: full; accessed: 2026-08-20; locator: risk thesis and closing)
- ★★★ | Martin Casado — Ambient.ai | https://a16z.com/announcement/investing-in-ambient-ai/ | 2022-01-19 | investor-authored announcement | Computer-vision physical-security thesis. (reliability: A; access: full; accessed: 2026-08-20; locator: problem/product and closing)
- ★★★ | Martin Casado — Metronome | https://a16z.com/announcement/investing-in-metronome/ | 2022-02-01 | investor-authored announcement | Usage-billing thesis, portfolio references, A lead and board. (reliability: A; access: full; accessed: 2026-08-20; locator: pricing/references and closing)
- ★★★ | Martin Casado — Convex | https://a16z.com/announcement/investing-in-convex/ | 2022-04-27 | investor-authored announcement | Backend thesis, A lead and board. (reliability: A; access: full; accessed: 2026-08-20; locator: product body and closing)
- ★★★ | Martin Casado — Fly.io | https://a16z.com/announcement/investing-in-fly-io/ | 2022-07-28 | investor-authored announcement | Edge/developer-cloud thesis and B lead. (reliability: A; access: full; accessed: 2026-08-20; locator: architecture and closing)
- ★★★ | Martin Casado and Jennifer Li — MotherDuck | https://a16z.com/announcement/investing-in-motherduck/ | 2022-11-15 | coauthored announcement | DuckDB/hybrid analytics thesis and A lead. (reliability: A; access: full; accessed: 2026-08-20; locator: exact byline, thesis and closing)
- ★★★ | Martin Casado and Matt Bornstein — Coactive | https://a16z.com/announcement/investing-in-coactive/ | 2023-03-21 | coauthored announcement | Visual-data thesis and seed+A chronology. (reliability: A; access: full; accessed: 2026-08-20; locator: exact byline, product/founder and closing)
- ★★★ | Martin Casado and Matt Bornstein — Distributional | https://a16z.com/announcement/investing-in-distributional/ | 2023-12-14 | coauthored announcement | AI-testing thesis, 25+ interviews and SigOpt relationship. (reliability: A; access: full; accessed: 2026-08-20; locator: exact byline, diligence/relationship and closing)
- ★★★ | Martin Casado — Tigris | https://a16z.com/announcement/investing-in-tigris/ | 2024-02-20 | investor-authored announcement | Distributed object-storage thesis. (reliability: A; access: full; accessed: 2026-08-20; locator: storage body and closing)
- ★★★ | Martin Casado and Jennifer Li — Ideogram | https://a16z.com/announcement/investing-in-ideogram/ | 2024-02-28 | coauthored announcement | Generative-media thesis and seed+A chronology. (reliability: A; access: full; accessed: 2026-08-20; locator: exact byline, model/product and closing)
- ★★★ | Matt Bornstein, Marco Mascorro, Rajko Radovanovic, and Martin Casado — Cursor | https://a16z.com/announcement/investing-in-cursor/ | 2024-08-22 | four-author announcement | Workflow/model-choice thesis and Series A; preserves team credit. (reliability: A; access: full; accessed: 2026-08-20; locator: exact byline, usage/model/founder body and closing)
- ★★★ | Martin Casado and Sarah Wang — World Labs | https://a16z.com/announcement/investing-in-world-labs/ | 2024-09-13 | coauthored announcement | Spatial-intelligence thesis and partnership. (reliability: A; access: full; accessed: 2026-08-20; locator: exact byline, world-model body and closing)
- ★★★ | Martin Casado — Braintrust | https://a16z.com/announcement/investing-in-braintrust/ | 2024-10-08 | investor-authored announcement | AI-evaluation thesis, product use and Series A lead. (reliability: A; access: full; accessed: 2026-08-20; locator: eval body and lead/user sentence)
- ★★★ | Yoko Li, Jennifer Li, and Martin Casado — Resend | https://a16z.com/announcement/investing-in-resend/ | 2024-12-04 | three-author announcement | Developer-email thesis, A lead and collective board statement. (reliability: A; access: full; accessed: 2026-08-20; locator: exact byline, product body and closing)
- ★★★ | Justine Moore, Marco Mascorro, and Martin Casado — WaveForms AI | https://a16z.com/announcement/investing-in-waveforms-ai/ | 2024-12-09 | three-author announcement | Audio-model thesis and investment. (reliability: A; access: full; accessed: 2026-08-20; locator: exact byline, model/team and closing)
- ★★★ | Yoko Li, Martin Casado, and Jennifer Li — Phota Labs | https://a16z.com/announcement/investing-in-phota-labs/ | 2025-09-16 | three-author announcement | Identity-preserving photo thesis and seed lead. (reliability: A; access: full; accessed: 2026-08-20; locator: exact byline, identity/context and closing)
- ★★★ | Yoko Li, Guido Appenzeller, and Martin Casado — Relace | https://a16z.com/announcement/investing-in-relace/ | 2025-10-08 | three-author announcement | Coding-agent thesis, $23M A lead and collective board statement. (reliability: A; access: full; accessed: 2026-08-20; locator: exact byline, stack body and closing)
- ★★★ | Justine Moore, Marco Mascorro, and Martin Casado — Shizuku AI | https://a16z.com/announcement/investing-in-shizuku-ai/ | 2026-02-09 | three-author announcement | AI-companion thesis and seed lead. (reliability: A; access: full; accessed: 2026-08-20; locator: exact byline, thesis and closing)
- ★★★ | Yoko Li, Guido Appenzeller, and Martin Casado — QuiverAI | https://a16z.com/announcement/investing-in-quiverai/ | 2026-02-25 | three-author announcement | SVG-model thesis and seed lead. (reliability: A; access: full; accessed: 2026-08-20; locator: exact byline, SVG body and closing)
- ★★★ | Marco Mascorro and Martin Casado — Deeptune | https://a16z.com/announcement/investing-in-deeptune/ | 2026-03-19 | coauthored announcement | RL-environment thesis and Series A lead. (reliability: A; access: full; accessed: 2026-08-20; locator: exact byline, thesis and closing)
- ★★★ | Martin Casado, Yoko Li, and Guido Appenzeller — Runta | https://a16z.com/announcement/investing-in-runta/ | 2026-07-16 | three-author announcement | Agent-compute thesis, prior founder relationship and seed lead. (reliability: A; access: full; accessed: 2026-08-20; locator: exact byline, relationship and closing)
Previously mapped outcome and adverse controls
- ★★★ | Tackle CEO — company update | https://tackle.io/blog/tackle-company-update/ | 2023-06-21 | first-person company statement | Records 75 separations and admits 2021–22 overbuilding; adverse operating evidence, not proof of investor loss. (reliability: A for company statement; access: full; accessed: 2026-08-20; locator: “Today is a tough day,” “overbuilt,” runway, and model paragraphs)
- ★★★ | Unity Software Form 10-K — Parsec acquisition | https://www.sec.gov/Archives/edgar/data/1810806/000181080622000004/unity-20211231.htm | 2022-02-23 | SEC-filed acquisition note | $332.729M company cash consideration; no a16z cost, ownership, proceeds, or return. (reliability: A; access: full; accessed: 2026-08-20; locator: Note 6, Parsec table)
- ★★★ | Fivetran and dbt Labs — completed all-stock merger | https://www.fivetran.com/press/fivetran-dbt-labs-complete-merger-to-create-the-data-infrastructure-for-trusted-ai-agents | 2026-06-01 | issuer transaction announcement | Completed all-stock combination; exchange ratio, value, liquidity, and gain/loss undisclosed. (reliability: A for issuer claim; access: full; accessed: 2026-08-20; locator: opening and transaction-description paragraphs)
T100.4 vehicle, outcome, adverse, and base-rate controls
- ★★★ | a16z — Fund V | https://a16z.com/fund-v/ | 2016-06-10 | firm fundraising announcement | $1.5B multi-stage platform context; no performance or Casado-specific allocation. (reliability: A; access: full; accessed: 2026-08-20; locator: announcement and stage-allocation paragraphs)
- ★★★ | a16z — Fund VII and Growth II | https://a16z.com/fund-vii-and-growth-fund-ii/ | 2020-11-20 | firm fundraising announcement | $1.3B/$3.2B rounded amounts and separate-team description. (reliability: A; access: full; accessed: 2026-08-20; locator: opening allocation and team paragraphs)
- ★★★ | SEC — Fund VII Form D alternate XML | https://www.sec.gov/Archives/edgar/data/1829358/000182935820000001/xslFormDX01/primary_doc.xml | 2020-11-20 | regulatory filing | Exact $1.25B, 154 investors, first-sale date and managing chain; automated recheck may return 403. (reliability: A; access: full historically/automated 403 on 2026-08-20; accessed: 2026-08-20; locator: Items 3, 5, 12–14)
- ★★★ | SEC — Fund IX AI Infrastructure Form D | https://www.sec.gov/Archives/edgar/data/2011182/000110465924045700/xslFormDX08/primary_doc.xml | 2024-04-16 | regulatory filing | Vehicle identity, GP chain, offering and management-fee entitlement; not performance. (reliability: A; access: full; accessed: 2026-08-20; locator: Items 1, 3, 13, 15)
- ★★★ | SEC — Fund X AI Infrastructure Form D | https://www.sec.gov/Archives/edgar/data/2085104/000110465926002072/xslFormDX01/primary_doc.xml | 2026-01-09 | regulatory filing | Successor vehicle identity, GP chain, offering and fee entitlement. (reliability: A; access: full; accessed: 2026-08-20; locator: Items 1, 3, 13, 15)
- ★★★ | SEC/IAPD — A16Z Capital Management Form ADV | https://reports.adviserinfo.sec.gov/reports/ADV/160489/PDF/160489.pdf | amended 2026-03-30 | regulatory PDF | Ownership/control schedules, RAUM, Fund IX/X GAV/owners/valuation fields and multiplexer double-counting warning. (reliability: A; access: full; accessed: 2026-08-20; locator: Item 5.F; Schedules A/B; Schedule D §7.B.(1) fund IDs; Miscellaneous)
- ★★★ | Cursor — Series C | https://cursor.com/blog/series-c | 2025-06-06 | issuer financing post | $900M/$9.9B and issuer metrics; financing mark not proceeds. (reliability: A for issuer claim; access: full; accessed: 2026-08-20; locator: opening financing and ARR/customer paragraphs)
- ★★★ | Cursor — Series D | https://cursor.com/blog/series-d | 2025-11-13 | issuer financing post | $2.3B/$29.3B and issuer annualized revenue; unaudited. (reliability: A for issuer claim; access: full; accessed: 2026-08-20; locator: opening financing/revenue paragraphs)
- ★★★ | SpaceX — Cursor merger 8-K | https://www.sec.gov/Archives/edgar/data/1181412/000162828026043411/spaceexplorationtechnologi.htm | 2026-06-18 | SEC filing | All-stock mechanics and $60B implied Cursor equity value; not holder proceeds. (reliability: A; access: full; accessed: 2026-08-20; locator: Item 1.01, “Merger Consideration”)
- ★★★ | Cursor — Joining SpaceX | https://cursor.com/blog/joining-spacex | 2026-08-14 | issuer transaction post | Confirms completion; no holder allocation/return. (reliability: A; access: full; accessed: 2026-08-20; locator: opening two paragraphs)
- ★★★ | Yubico — ACQ Bure transaction archive | https://investors.yubico.com/en/investors/listing-nasdaq-first-north-growth-market/ | 2023/live | issuer transaction archive | Merger/listing chronology and documents; no security-level a16z realization. (reliability: A; access: full; accessed: 2026-08-20; locator: opening chronology and linked documents)
- ★★★ | Yubico/ACQ Bure — transaction announcement | https://investors.yubico.com/en/acq-bure-ab-is-merging-with-yubico-ab-merged-companies-intend-to-go-public-on-swedens-nasdaq-first-north-growth-market/ | 2023-04-19 | issuer transaction release | Approximate $800M company transaction value and structure; expected 6.1% combined-company a16z ownership and conditional 180-day lockup; not actual closing shares, sales, proceeds, distributions, or return. (reliability: A; access: full; accessed: 2026-08-20; locator: transaction overview and consideration lines; “Ownership structure” table; Andreessen Horowitz 180-day lockup paragraph)
- ★★★ | Yubico — first trading day | https://investors.yubico.com/en/first-day-of-trading-in-yubicos-shares-on-nasdaq-first-north-growth-market-following-completion-of-merger-with-acq-bure/ | 2023-09-20 | issuer release | Confirms merger completion/listing; listing is not realization. (reliability: A; access: full; accessed: 2026-08-20; locator: opening completion/trading paragraphs)
- ★★★ | Parsec — Series B | https://parsec.app/blog/about-our-series-b-and-parsecs-year-of-transformation | 2020-12-15 | issuer financing post | $25M round, syndicate and board relationship. (reliability: A for issuer claim; access: full; accessed: 2026-08-20; locator: opening financing/board paragraphs)
- ★★★ | Tackle — Series B | https://tackle.io/blog/tackle-series-b-funding/ | 2021-03-09 | issuer financing post | $35M B and issuer operating claims. (reliability: A for issuer claim; access: full; accessed: 2026-08-20; locator: opening and ARR/customer/volume paragraphs)
- ★★★ | Tackle — Series C | https://tackle.io/company-news/tackle-series-c-funding/ | 2021-12 | issuer financing post | Preemptive round and scaling intent; not outcome evidence. (reliability: A for issuer claim; access: full; accessed: 2026-08-20; locator: financing/scaling paragraphs)
- ★★★ | AppDirect — agreement to acquire Tackle | https://www.appdirect.com/about/press/releases/appdirect-and-tackle-io-to-unite-to-extend-leadership-in-b2b-subscription-commerce-with-native-hyperscaler-marketplace-integration | 2025-12-01 | acquirer release | Confirms transaction and omits terms. (reliability: A; access: full; accessed: 2026-08-20; locator: opening transaction paragraphs)
- ★★★ | Cisco — Isovalent acquisition completed | https://investor.cisco.com/news/news-details/2024/Cisco-Completes-Acquisition-of-Isovalent-to-Define-the-Future-of-Multicloud-Networking-and-Security/default.aspx | 2024-04-12 | acquirer release | Completion/rationale; consideration undisclosed. (reliability: A; access: full; accessed: 2026-08-20; locator: opening paragraphs)
- ★★★ | Postman — Orbit acquisition | https://blog.postman.com/announcing-postman-has-acquired-orbit/ | 2024-04-11 | acquirer post | Acquisition and 90-day product sunset; sunset not proof of loss. (reliability: A; access: full; accessed: 2026-08-20; locator: acquisition and final sunset paragraphs)
- ★★★ | Convex — Series A | https://news.convex.dev/series-a/ | 2022-04 | issuer financing post | Distinguishes Casado's prior angel/adviser role from firm Series A and board. (reliability: A for issuer statement; access: full; accessed: 2026-08-20; locator: opening financing/relationship paragraphs)
- ★★ | Forbes — Astranis decision-date profile | https://www.forbes.com/sites/alexknapp/2018/03/01/andreessen-horowitz-makes-its-first-space-investment-with-satellite-startup-astranis/ | 2018-03-01 | contemporaneous reported profile | Financing, board, architecture and prototype control. (reliability: B; access: full; accessed: 2026-08-20; locator: opening financing/board and architecture/prototype passages)
- ★★★ | Astranis — Arcturus anomaly | https://www.astranis.com/blog/arcturus-satellite-anomaly-alaska-service-update | 2023-08-10 | issuer technical update | Mission-impacting anomaly, reproduced supplier failure and fix. (reliability: A for issuer account; access: full; accessed: 2026-08-20; locator: opening anomaly and reproduced-failure paragraphs)
- ★★★ | Astranis — Series E/debt | https://www.astranis.com/blog/series-e-raise-advanced-high-orbit-spacecraft | 2026-05-06 | issuer financing post | Equity/debt and operating claims; not value/return. (reliability: A for issuer claim; access: full; accessed: 2026-08-20; locator: opening capital and five-satellite/backlog paragraphs)
- ★★★ | Tecton — Series C | https://www.globenewswire.com/news-release/2022/7/12/2478423/0/en/Tecton-Reports-Record-Demand-for-Its-Machine-Learning-Feature-Platform-as-It-Raises-100-Million-in-Funding-Led-by-Kleiner-Perkins-With-Participation-from-Strategic-Investors-Databr.html | 2022-07-12 | issuer-distributed release | $100M round/syndicate; issuer metrics unaudited. (reliability: A/B; access: full; accessed: 2026-08-20; locator: “Tecton Raises $100 Million” section)
- ★★★ | Databricks — Tecton joining | https://www.databricks.com/blog/tecton-joining-databricks-power-real-time-data-personalized-ai-agents | 2025-08-22 | acquirer post | Strategic transaction; terms absent. (reliability: A; access: full; accessed: 2026-08-20; locator: summary/opening and “Tecton + Databricks”)
- ★★★ | Uniphore — ActionIQ acquisition overview | https://www.uniphore.com/actioniq/ | transaction announced 2024-12; live page accessed 2026-08-20 | primary acquirer page | Confirms ActionIQ combination/product integration; transaction terms and investor proceeds undisclosed. (reliability: A for acquirer claim; access: full; accessed: 2026-08-20; locator: acquisition/integration overview; mutable page)
- ★★★ | NVIDIA — DeepMap acquired-status update | https://blogs.nvidia.com/blog/isaac-amr-platform/ | 2022-01-04 | primary acquirer post | Describes NVIDIA's recent acquisition of DeepMap and its integration into NVIDIA DRIVE; terms and holder proceeds absent. (reliability: A; access: full; accessed: 2026-08-20; locator: “DeepMap Delivers Mapping Advances,” first paragraph)
- ★★★ | Stripe — Metronome acquisition completed | https://stripe.com/gb/newsroom/news/stripe-completes-metronome-acquisition | 2026-01-14 | primary acquirer release | Confirms completion and product rationale; financial terms and shareholder allocations undisclosed. (reliability: A; access: full; accessed: 2026-08-20; locator: opening completion and integration paragraphs)
- ★★★ | Intel — SigOpt acquisition | https://download.intel.com/newsroom/archive/2025/en-us-2020-10-29-intel-to-acquire-sigopt-to-scale-ai-productivity-and-performance.pdf | 2020-10-29 | primary acquirer release PDF | Confirms acquisition announcement and rationale; terms and investor proceeds absent. (reliability: A; access: full; accessed: 2026-08-20; locator: p. 1, heading and opening transaction paragraphs)
- ★★★ | Intel — SigOpt acquired-status update | https://community.intel.com/t5/Blogs/Tech-Innovation/Artificial-Intelligence-AI/Kisaco-Research-designates-SigOpt-as-a-Leader-in-AI-Software/post/1335688 | 2021-05-14 | official Intel employee-domain post | States that Intel acquired SigOpt in October 2020; terms and investor proceeds remain absent. (reliability: A/B; access: full; accessed: 2026-08-20; locator: opening acquired-status paragraph)
- ★★★ | Databricks — agreement to acquire Tabular | https://www.prnewswire.com/news-releases/databricks-agrees-to-acquire-tabular-the-company-founded-by-the-original-creators-of-apache-iceberg-302163561.html | 2024-06-04 | issuer-distributed transaction release | Confirms announced agreement and strategic rationale; completion, consideration, and holder proceeds are not established by this release. (reliability: A/B; access: full; accessed: 2026-08-20; locator: headline and opening transaction paragraphs)
- ★★★ | Nokia — Rapid technology-assets and R&D-unit acquisition | https://www.nokia.com/newsroom/nokia-acquires-rapid-technology-and-rd-unit-to-strengthen-development-of-network-api-solutions-and-ecosystem/ | 2024-11-13 | primary acquirer release | Confirms technology-asset and R&D-unit acquisition, not clearly a whole-company acquisition; terms and holder proceeds absent. (reliability: A; access: full; accessed: 2026-08-20; locator: opening and acquired-assets/R&D-unit paragraph)
- ★★ | Tackle — company status | https://tackle.io/company/ | live; accessed 2026-08-20 | mutable issuer page | Identifies Tackle as acquired by AppDirect; no transaction price or holder economics. (reliability: A/B; access: full; accessed: 2026-08-20; locator: company-status/acquisition text)
- ★★★ | Preset — Series C | https://preset.io/blog/preset-series-c/ | 2026-03-09 | issuer financing post | $7.27M C; amount alone cannot prove down round. (reliability: A; access: full; accessed: 2026-08-20; locator: opening financing paragraphs)
- ★★ | TechCrunch — RapidAPI workforce reduction | https://techcrunch.com/2023/04/25/rapidapi-valued-at-1-billion-last-year-cuts-staff-by-50/ | 2023-04-25 | adverse-event report | Company-confirmed ~50% cut/CEO change; no shutdown or return evidence. (reliability: B; access: full; accessed: 2026-08-20; locator: opening/company-confirmation paragraphs)
- ★ | Fly.io founder comments | https://news.ycombinator.com/item?id=41441218 | 2024-09-04 | direct participant on third-party forum | Workforce adjustment preceding Casado's disclosed board role. (reliability: C; access: full; accessed: 2026-08-20; locator: founder comments)
- ★★★ | Fly.io — Series D/board | https://fly.io/news/fly-io-launches-computers-for-agents/ | 2026-07 | issuer post | $25M D, current claims and Casado board timing. (reliability: A for issuer claim; access: full; accessed: 2026-08-20; locator: financing/board and metrics paragraphs)
- ★★ | TechCrunch — WaveForms acquisition report | https://techcrunch.com/2025/08/08/meta-acquires-ai-audio-startup-waveforms/ | 2025-08-08 | transaction report | Acquisition/undisclosed terms; primary confirmation missing. (reliability: B; access: full; accessed: 2026-08-20; locator: opening/terms paragraphs)
- ★★ | Fortune — Deeptune acquisition report | https://fortune.com/2026/07/09/ai-unicorn-mercor-acquires-deeptune-brendan-foody-investor-a16z-openai-anthropic/ | 2026-07-09 | transaction report | Acquisition/undisclosed terms; primary confirmation missing. (reliability: B; access: full/partial publisher; accessed: 2026-08-20; locator: opening/terms paragraphs)
- ★★★ | Resend — Sunsetting new.email | https://resend.com/blog/sunsetting-new-email/ | 2026-07-08 | issuer product postmortem | Separate-brand/stack costs and integration into parent; product lesson only. (reliability: A; access: full; accessed: 2026-08-20; locator: “Why” and separate-stack paragraphs)
- ★★★ | World Labs — $1B new funding | https://www.worldlabs.ai/blog/funding-2026 | 2026-02-18 | issuer financing announcement | Confirms $1B in new funding but does not disclose a valuation or identify a16z in the named investor list. (reliability: A for issuer claim; access: full; accessed: 2026-08-20; locator: opening funding paragraph)
- ★★★ | NVCA/PitchBook — Q4 2021 Venture Monitor | https://nvca.org/wp-content/uploads/2022/01/Q4_2021_PitchBook_NVCA_Venture_Monitor.pdf | 2022-01 | industry report PDF | 2021 financing/exit regime. (reliability: A/B; access: full; accessed: 2026-08-20; locator: Executive Summary $329.6B/17,054/$774.1B)
- ★★★ | NVCA — Q1 2022 ecosystem update | https://nvca.org/press_releases/u-s-venture-ecosystem-normalizes-after-record-year-in-2021/ | 2022 | industry release | Exit reset at $33.6B after three >$192B quarters. (reliability: A/B; access: full; accessed: 2026-08-20; locator: exit-market paragraph)
- ★★★ | NVCA/PitchBook — Q4 2025 Venture Monitor | https://nvca.org/wp-content/uploads/2026/01/q4-2025-pitchbook-nvca-venture-monitor.pdf | 2026-01 | industry report PDF | Fundraising, close-ratio and LP-liquidity context. (reliability: A/B; access: full; accessed: 2026-08-20; locator: Executive Summary/fundraising/liquidity)
- ★★★ | NVCA/PitchBook — Q1 2026 Venture Monitor | https://nvca.org/wp-content/uploads/2026/04/Q1-2026-PitchBook-NVCA-Venture-Monitor.pdf | 2026-04 | industry report PDF | AI deal-value/count concentration. (reliability: A/B; access: full; accessed: 2026-08-20; locator: Executive Summary AI concentration)
Completed-peer comparison controls
- ★★ | David H. Hsu and Martin Kenney — Organizing Venture Capital: The Rise and Demise of American Research & Development Corporation, 1946–1973 | https://kenney.faculty.ucdavis.edu/wp-content/uploads/sites/332/2018/03/Organizing-Venture-Capital_-The-Rise-and-Demise-of-American-Research-and-Development-Corporation.pdf | 2005 | peer-reviewed historical study | Completed-peer evidence for ARD sourcing, instrument mix, portfolio concentration, and the DEC/non-DEC return boundary; Casado comparison only. (reliability: B; access: full; accessed: 2026-08-20; locator: p. 594 and n. 11 for sourcing; Table 3 for instruments/portfolio construction; p. 599 for DEC and non-DEC return estimates)
- ★★ | Harvard Business School Baker Library — Financing New Ideas | https://www.library.hbs.edu/hc/doriot/innovation-vc/financing-new-ideas/ | 2014 exhibit | institutional archive exhibit with primary-source excerpts | Reproduces Doriot's selection and company-building language; completed-peer comparison only. (reliability: B; access: full; accessed: 2026-08-20; locator: “Financing New Ideas” exhibit panels and reproduced Doriot passages on patents/know-how, technical defensibility, construction, and speculation)
- ★★ | Tom Nicholas — The Origins of High-Tech Venture Investing in America | https://www.hbs.edu/ris/Publication%20Files/VC_Tech_4b7a1b2a-ef2a-4867-a41e-2ba84cb120f2.pdf | 2016 | scholarly chapter | Completed-peer evidence for ARD selection criteria, operating intervention, staged DEC financing, and Island Packers' adverse economics. (reliability: B; access: full; accessed: 2026-08-20; locator: printed pp. 230–231 for selection criteria; pp. 231–232 for intervention and Island Packers; p. 234 for staged DEC financing)
- ★★ | Aulikki Olsen — Aulikki Olsen Oral History | https://bitsavers.org/pdf/dec/history/Oral_Histories/Aulikki_Olsen_910305_910618.pdf | interviews 1991-03-05 and 1991-06-18 | approved oral-history transcript mirror | First-person completed-peer evidence on Doriot's demanding diligence, mentorship, family interviews, and founder-control tension. (reliability: B for archive mirror of retrospective testimony; access: full; accessed: 2026-08-20; locator: transcript p. 9 and surrounding diligence/mentorship discussion)
- ★★ | U.S. House of Representatives — Small Business Investment Incentive Act Hearings, Part 2 | https://demo.sechistorical.org/collection/papers/1970/1979_1107_HouseIncentive_02.pdf | 1979-11-07 | government-hearing record mirror | Completed-peer evidence on ARD's public-company constraints and affiliate/employee incentive problems. (reliability: B for archive mirror of a government record; access: full; accessed: 2026-08-20; locator: printed pp. 339–340, including p. 339 n. 12)
- ★★ | Reid W. Dennis — Reid Dennis: Pioneer Venture Capitalist | https://digicoll.lib.berkeley.edu/record/218448/files/dennis_reid.pdf#page=19 · https://digicoll.lib.berkeley.edu/record/218448/files/dennis_reid.pdf#page=33 · https://digicoll.lib.berkeley.edu/record/218448/files/dennis_reid.pdf#page=41 | interviews 2009-01-13 and 2009-02-10; published 2009 | interviewee-reviewed Bancroft Library oral-history transcript | Completed-peer evidence for inherited/personal access, referrals, syndication, portfolio philosophy, vehicle evolution, authority, and succession. (reliability: A for authenticated Dennis testimony and interview metadata; B for retrospective chronology, causality, and unaudited economics; access: full; accessed: 2026-08-20; locator: printed pp. 13–28/PDF pp. 19–34 for access, referrals, and The Group; printed pp. 27–28/PDF pp. 33–34 for portfolio philosophy; printed pp. 35–48/PDF pp. 41–54 for IVA/IVP vehicle evolution and succession)
- ★★ | Reid W. Dennis — Something Ventured Interview, Transcript 2 | https://stacks.stanford.edu/file/mj877gg1809/Reid_Dennis_Transcript_2.pdf#page=17 · https://stacks.stanford.edu/file/mj877gg1809/Reid_Dennis_Transcript_2.pdf#page=37 | recorded 2008-09-25; transcript file dated 2009-08-27 | raw Stanford/Smithsonian filmed-interview transcript | Completed-peer evidence for technical-to-customer-to-security underwriting, Reference Technology, held-to-zero positions, and the Apple price pass. (reliability: A for directly recorded testimony and repository metadata; B for retrospective claims; C for exact spellings/numbers in the unpolished transcript; access: full; accessed: 2026-08-20; locator: transcript 2 PDF pp. 17–18 for Reference Technology and held-to-zero discussion; pp. 37–42 for technical/customer/security sequencing and the Apple-price account)
- ★★ | Burton J. McMurtry — Early Bay Area Venture Capitalists Oral History | https://digicoll.lib.berkeley.edu/record/218493/files/mcmurtry_burt.pdf#page=40 | interviews 2009-06-09 and 2009-06-30; published 2009 | participant Bancroft Library oral-history transcript | Completed-peer evidence separating sourcing, disclosure/recusal, collective approval, and board work in the ROLM case. (reliability: A for authenticated participant testimony; B for retrospective accuracy; access: full; accessed: 2026-08-20; locator: printed pp. 30–32/PDF pp. 40–42)
Coverage assessment
Corpus, categories, and search variants
- Mapped corpus: 220 starred/priority source rows plus 16 supporting annotated route groups yield 236 annotated rows and 274 unique external URLs. They span official identity/archives; biography and public service; all 11 direct-corpus research works; Nicira/VMware records; 16 direct writings; 31 spoken appearances; the 43-record official deal-announcement corpus; vehicles, boards, outcomes, failures, market context, skeptical controls, and eight completed-peer comparison works. The direct-corpus sweep separately remains 60 unique works/routes: two official archives, 16 writings, 11 research papers, and 31 spoken appearances. Supplementary deal, profile, version, attribution, counterevidence, and peer-comparison routes do not add to that direct-work denominator.
- Names and date variants searched:
Martin Casado,Martín Casado, Nicira, Illuminics/Illuminics Systems, Quova, VMware NSX, OpenFlow, Open vSwitch, SANE, Ethane, NOX, Onix, MuralNet, Andreessen Horowitz/a16z, Infrastructure, board/director, investment/led/Series/exit/acquired/IPO, podcast/interview/transcript/video, lawsuit/complaint/SEC/enforcement/criticism/layoff/shutdown/write-off. Chronology searches tested 1976 birthplace, 1998–2003 versus 2000–2006 LLNL tenure, 2005 versus 2007 MS, 2007 Nicira formation, 2009 a16z encounter, 2012 acquisition measures, 2014 versus 2015 NEC award, and 2016 a16z start. - Source classes searched: official/personal/firm archives; university and laboratory pages; peer-reviewed papers and award indexes; SEC EDGAR and adviser databases; issuer/acquirer and portfolio-company announcements; congressional testimony; nonprofit records; publisher transcripts/audio/video; high-quality press; legislative/regulator records; venture benchmarks; practitioner criticism; legal/enforcement keyword searches. No credible person-specific lawsuit or enforcement record surfaced; that is a no-result, not proof of absence.
Direct voice, archives, and access boundaries
- Exhausted or mapped direct routes: the live a16z author/team archive, a16z podcast and video pages, the Stanford personal archive and publication index, LLNL histories, House and Senate statements, MuralNet, Software Engineering Daily transcripts, Invest Like the Best transcripts, direct company announcements, academic proceedings, and SEC filings were searched. Available full pages, PDFs, transcripts, audio, and video were opened; quotation use must bind versions and exact timestamps.
- Access barriers: the dynamic a16z investment list did not yield a stable complete person-linked export; the current Form ADV PDF was retrieved and mapped, while one Fund VII SEC XML route returned an automated-client 403 on recheck after earlier retrieval; the Wall Street Journal, Economist, and The Information routes remain paywalled/partial; several podcast pages expose full audio but only show notes. No blocked body was reconstructed from search snippets.
- Archival gaps: no original Illuminics–Quova transaction announcement, exact Nicira incorporation/first Form D, complete Nicira cap table, archived VMware title chronology, private a16z investment-committee record, LP communication, or Casado-specific cash-flow record was located. Historical snapshots of the a16z profile, portfolio, and investment-list databases remain the best public route to roster drift and omitted positions.
Candidate deal denominator, attribution, and economics
- Final candidate reconciliation: as of 2026-08-20, 43 announcement claims plus 25 current/former board claims, less 22 overlapping companies, yield 46 included companies. The three board-only companies are DeepMap, Netlify, and Pindrop. Adding two excluded founder/operator candidates—Nicira and Illuminics—produces 70 candidate claim records across 48 candidate companies. The board roster is therefore neither a complete investment denominator nor a person-role ledger; the exact profile and investment-list URLs are mapped once in their canonical source rows above.
- Inclusion boundary: Illuminics and Nicira are founder/operator outcomes, not investments selected by Casado. Firm investment, Infrastructure-team participation, Casado authorship, board service, Casado-led sponsorship, sole approval, vehicle, check, ownership, reserves, exit influence, company consideration, investor proceeds, and LP distributions are separate fields. Every silent role remains unknown.
- Economic boundary: the public record does not support a personal hit rate, MOIC, IRR, DPI, or complete loss count. Acquisition values and private marks are company outcomes; “acquired,” “IPO,” or public listing does not prove profitability or realization. The highest-value missing records are fund/check/ownership/dilution/preference/distribution data and a complete searched set of passes, shutdowns, down rounds, recaps, write-offs, secondaries, and below-cost exits.
Historical context, peers, and highest-value retrieval leads
- Historical context: the dated technical papers and independent SDN history establish the pre-Nicira architecture and collaboration set; contemporaneous 2012 reporting and SEC filings freeze financing, product, competition, and transaction measures; PitchBook-NVCA vintages supply later venture-market conditions; FTC, legislative, cloud-cost, policy, and benchmark records provide external tests of AI and infrastructure claims. Later data must never be leaked into an earlier decision record without a retrospective label.
- Completed peers: Trae Stephens is the closest completed modern operator/founder-investor comparison for attribution, conflicts, private marks, and missing returns. Georges Doriot and Reid Dennis provide completed long-duration vehicle and governance contrasts but are not technology-era peers. Marc Andreessen, Ben Horowitz, and Peter Thiel remain incomplete in this repository and therefore are people/institution sources, not completed-peer comparators.
- Highest-value next retrievals: export and archive the a16z investment database; recover historical Form ADV/IAPD snapshots; reconcile every Casado announcement and board date to a company-primary source; obtain official transcripts/captions for audio-only priority talks; legitimately retrieve the two paywalled guest essays; find original Illuminics/Quova and Nicira incorporation/financing instruments; search acquirer filings for purchase-price notes; audit every candidate company for adverse outcomes; and map fund, decision rights, reserves, ownership, seller liquidity, and LP cash flows. These are named unresolved evidence requirements, not grounds to infer a clean record today.
Source notes
[t] 20VC: a16z's Martin Casado on Whether the Venture Model Is Broken
- URL: https://thetwentyminutevc.libsyn.com/20vc-a16zs-martin-casado-on-how-the-venture-model-is-broken-why-vcs-should-be-running-wall-st-who-wins-and-who-loses-in-the-next-generation-of-venture-investing-lessons-from-marc-andreesen-ben-horowitz-and-chris-dixon | Published: 2022-12-05 | Format: long-form interview (Harry Stebbings and Martin Casado) | Reliability: A for direct official audio, B for publisher framing and automated navigation text | Access: full official audio; partial public transcript routes; bounded offline ASR used only for timestamped paraphrase | Accessed: 2026-08-20 | Locator scheme: Libsyn episode/audio elapsed timestamps | Version: official 20VC RSS GUID
298a8a82-d502-4e22-b70b-fbca97a8311b, 51:52
Takeaways
- [investor-stated | strong] Casado calls the inherited venture model obsolete because private technology capital and software markets have grown while many firms retain small, generalist structures. His proposed replacement is specialized research plus several stage- and risk-specific products, not indiscriminate fund expansion. 09:30–11:31
- [investor-stated | strong] His market-structure forecast is a barbell: a few scaled platforms can finance companies across their lifecycle, while focused boutiques can retain domain or stage alpha; undifferentiated firms in the middle face pressure. The episode supplies a thesis, not comparative fund-return evidence. 11:31–12:55
- [investor-stated | strong] Casado argues that innovation-oriented investors should serve companies from seed through public markets and debt instead of ceding later capital to investors optimizing predictable cash flows. This is normative advocacy and aligns with a16z's expansion; it is not evidence that technology specialists deliver superior risk-adjusted returns in every product. 12:55–14:15
- [investor-stated | moderate] Casado says separate seed, venture, and growth teams reduce the conflict between a founder's board disclosure and the next financing decision. The structural separation is described but no decision-rights policy, recusal record, or founder sample tests whether it works. 14:15–15:33
- [investor-stated | strong] Casado rejects deal-time omniscience. He calls company selection underdetermined and says the team spends most of its time mapping spaces before a fast process begins; vigorous debate, accumulated research, and junior-partner input are the operating controls. 18:47–19:22 and 33:35–36:17
- [investor-stated | strong] Category creation is financeable only with trend alignment, time, and a credible plan for a long go-to-market march. In a contraction, founders should rebuild the operating plan from bear/base/bull scenarios and company solvency rather than apply a generic percentage cut. 23:00–29:23
- [investor-stated | strong] His board boundary is explicit: investors should provide market maps, competitive information, recruiting, and other work founders cannot easily duplicate, but should not prescribe how to run the company. Casado says he violated this rule early by overfitting Nicira's path. 31:10–33:20
- [researcher inference | moderate] Decision rule: require a pre-existing market map, named disconfirming views, a stage-specific capital path, and three operating scenarios; define what the board uniquely contributes and what remains management's decision. Reject scale for its own sake when products, teams, and conflicts are not separated. 09:30–15:33 and 27:30–36:17
- [researcher inference | moderate] Modern VC translation (as of 2026-08-20): specialization, pre-work, scenario planning, and board-role limits transfer. The forecast that specialist venture should run all of finance does not transfer without product-level net returns, liquidity, and conflict evidence. Changed assumptions include larger evergreen/private-capital pools and AI compute financing. Signals are research completed before a process, independent growth underwriting, founder candor, and scenario-linked runway; likely misuse is using mission rhetoric to excuse price or fiduciary discipline. Current example: a16z's multi-stage structure is the stated application, not a causal performance test. 09:30–19:22 and 33:35–39:30
Quotes
- [researcher inference | insufficient public record] No verbatim quotation is promoted. The publisher supplies complete audio but no transcript; public transcript routes are gated or incomplete, and offline ASR was used only to locate and paraphrase passages. official episode and player
Biography and decision evidence
- [retrospective witness | moderate] Casado recounts moving from national-laboratory computational physics to Stanford systems research, founding Nicira in 2007, surviving the 2008 contraction, selling to VMware, and running a business he describes as reaching roughly $600 million. This is direct memory with rounded economics, not an audited operating history. 03:48–04:40
- [retrospective witness | moderate] He credits Ben Horowitz as the model for a useful operator-board member and says Mark Andreessen helped him replace a systems engineer's aversion to previously failed ideas with a more future-positive investment posture. These are mentor accounts, not proof that either person caused later investment performance. 05:41–06:30 and 37:48–38:35
- [investor-stated | moderate] Casado says capable junior partners and a16z operating specialists perform substantial research, recruiting, and sales work for which he may receive public credit. The statement is valuable team-credit evidence but does not allocate source, sponsor, vote, carry, or outcome by deal. 07:18–08:18
Philosophy signals
- firm design: [investor-stated | strong] combine scaled stage-specific pools with specialized research teams, while recognizing a viable boutique path. 09:30–12:55
- picking: [investor-stated | strong] treat a single deal as underdetermined; build conviction through prior market work, founder comparison, and structured disagreement. 18:47–19:22 and 33:35–36:17
- portfolio / vehicle: [investor-stated | moderate] separate risk buckets and decision teams across early, growth, debt, and public capital; do not assume the board sponsor controls every follow-on. 14:15–17:32
- founder support: [investor-stated | strong] contribute information and functions the company cannot efficiently reproduce, while leaving operating choices to management. 31:10–33:20
- failure handling: [investor-stated | strong] use scenario-linked operating plans and board risk appetite rather than reflexive hiring freezes or arbitrary layoffs. 27:30–31:00
Contradictions, counterevidence, and access limits
- [researcher inference | strong] Casado says he does not strictly optimize dollar returns and frames venture as an index of innovation, yet scaled multi-product asset management still owes each vehicle a return and conflict discipline. Mission does not substitute for product-level DPI, loss, fee, and benchmark evidence. 16:15–17:32
- [researcher inference | moderate] Separate teams can reduce sponsor control but do not remove information asymmetry, signaling, valuation, allocation, or internal-pressure conflicts. The source offers no founder survey, recusal policy, rejected follow-on cohort, or related-vehicle minutes. 14:15–15:33
- [researcher inference | moderate] The barbell forecast benefits a16z's scale narrative and can be self-fulfilling through fundraising, brand, and allocation access. No matched boutique, middle-market, and scaled-firm return series is presented. 09:30–14:15
- [researcher inference | moderate] “Markets in” and space mapping can still become retrospective category selection unless maps, passes, changing definitions, and losing themes are preserved ex ante. The episode does not publish that denominator. 18:47–19:22 and 33:35–36:17
- [contemporaneous record | strong] The complete 51:52 official RSS audio is available. Tapesearch exposes only an initial segment without login, and no official transcript was located; timestamped claims therefore rely on official-audio review aided by bounded local ASR, with no ASR wording promoted as a quote. official episode · public transcript route
Open questions
- [researcher inference | insufficient public record] Do a16z's scaled, stage-specific products outperform comparable boutiques and specialist middle-market firms net of fees, losses, and liquidity timing? Official episode, 09:30–17:32
- [researcher inference | insufficient public record] Which investment maps, passes, and disagreements were recorded before deal processes, and did they improve selection relative to a matched baseline? Official episode, 18:47–19:22 and 33:35–36:17
- [researcher inference | insufficient public record] How often did separate growth teams reject a board sponsor's company, and did founders report that the separation improved candor? Official episode, 14:15–15:33
- [researcher inference | insufficient public record] What return, conflict, and governance constraints bound the aspiration to finance technology companies across their full lifecycle? Official episode, 12:55–17:32
[t] Martin Casado: AI's Hard Limits and Open Problems
- URL: https://www.fromthenew.world/p/martin-casado-ai-hard-limits | Published: 2024-09-02 | Format: From the New World podcast interview (Brian Chau interviewing Martin Casado) | Reliability: A for the publisher audio and speaker-labelled publisher transcript; transcript is machine-generated and selected wording was checked against audio | Access: full official audio and full publisher transcript | Accessed: 2026-08-19 | Locator scheme: publisher elapsed timestamps;
SPEAKER_00is Brian Chau andSPEAKER_01is Martin Casado | Version: Substack post148386249; podcast uploadaa5fd314-8b08-4e82-82f7-e02bf5480202fromftnw10-martinfixed.wav; transcript approved2024-09-01T23:05:53Z; audio duration00:48:08.098
Takeaways
- No natural model monopoly [investor-stated | moderate]: Casado expects a hardware-like market with dominant vendors and a specialized long tail, not a network-effect monopoly. He attributes Nvidia's concentration to interconnects and CUDA rather than an industry-wide AI law. Publisher episode, Brian question and Martin answer at
00:01:57–00:04:13 - Perverse scale economics [investor-stated | moderate]: leaders face declining marginal value from scarce new data and high training spend, while distillation lets challengers draft on leader output; Casado expects catch-up to weaken concentration. This is an economic hypothesis, not market-share evidence. Publisher episode, Martin at
00:04:13–00:05:27and00:16:56–00:19:18 - National research infrastructure [investor-stated | moderate]: drawing on late-1990s DOE simulation work, he supports an Apollo-like public investment in compute and researchers for questions without immediate commercial payoff, while disclaiming that AI offers a single moon-landing-style objective. Publisher episode, Brian and Martin at
00:20:12–00:22:37 - AI as a third programming primitive [investor-stated | moderate]: imperative systems require instructions, declarative systems require a specified answer, and machine learning can address problems where neither is known by learning from examples—at the cost of more compute and weaker bounds. Publisher episode, Martin at
00:23:19–00:25:06 - Agent skepticism [investor-stated | strong]: Casado rejects AGI as a privileged endpoint and argues that current LLMs lack reliable correctness, integrated memory, and internal-state guarantees for autonomous control loops. He prefers human guidance as an external source of information and correction. Publisher episode, Brian and Martin at
00:25:09–00:34:21 - Little-tech policy [investor-stated | moderate]: he argues compliance costs and restricted M&A disproportionately burden startups, citing GDPR and his own two exits; his prescription is to regulate applications and bad conduct through the existing software-policy tradition rather than constrain general primitives. Publisher episode, Brian and Martin at
00:34:25–00:42:42 - Modern VC translation (as of 2026-08-19) [researcher inference | moderate]: underwrite model companies for catch-up and diminishing returns; require agent products to show bounded tasks, external verification, and human correction; treat regulatory compliance and M&A availability as explicit capital and exit risks rather than generic macro commentary. Publisher episode, Martin at
00:16:56–00:19:18,00:25:09–00:34:21, and00:34:25–00:42:42
Quotes
- “I don't think there's a natural monopoly here.” — Martin Casado,
00:02:27. [investor-stated | strong] Publisher episode - “AGI is this kind of arbitrary, weird, non-goal.” — Martin Casado,
00:25:55. [investor-stated | strong] Publisher episode - “This is a new primitive and a new tool.” — Martin Casado,
00:25:00. [investor-stated | strong] Publisher episode
Biography and decision evidence
- Casado says he worked on the late-1990s DOE ASCI project, using then-leading computers for physics simulation and national-security work. [investor-stated | strong] He explicitly identifies that experience as the bias behind his support for national compute and research infrastructure. Publisher episode, Martin at
00:20:23–00:21:42 - He characterizes himself as a computer-systems PhD, distributed-systems programmer, and computational-physics practitioner rather than an AI-native researcher. [investor-stated | strong] That background is the stated source of his focus on correctness, state, control loops, and information bounds. Publisher episode, Martin at
00:25:22–00:26:29 - Casado says he founded two companies and sold both: one “great” exit and one “modest” exit. [retrospective witness | moderate] He uses that biography to argue M&A is necessary for founder recycling, but gives no company attribution, price, ownership, or proceeds in this episode. Publisher episode, Martin at
00:40:23–00:41:14 - He says he helped create and teach a 2003 Stanford cybersecurity-policy course with former US defense secretary William Perry. [investor-stated | moderate] This is presented as evidence that software policy already has a long innovation-versus-risk discourse; the course record is not independently verified here. Publisher episode, Martin at
00:41:58–00:42:42 - No a16z fund, investment, check, security, ownership, reserve, board action, or portfolio return is identified. [researcher inference | strong] The source is unusually strong for background-to-philosophy links and weak for deal attribution. Publisher episode, full recording
Philosophy signals
- Picking / risk [investor-stated | moderate]: the strongest model need not own the market because distillation and diminishing returns can make leadership expensive to maintain. Publisher episode, Martin at
00:04:13–00:05:27and00:16:56–00:19:18 - People / picking [researcher inference | moderate]: Casado's systems background supplies a repeatable questioning frame—what is the correctness target, where does new information enter, how is state represented, and what happens in the tail? Publisher episode, Martin at
00:25:22–00:34:21 - Macro / portfolio [investor-stated | moderate]: public compute can explore socially useful but commercially weak questions; private portfolio economics alone may underfund them. Publisher episode, Martin at
00:20:12–00:25:06 - Exits / risk [investor-stated | strong]: an M&A-hostile regime can reduce founder incentives and block recycling after outcomes short of an IPO; Casado regards acquisition liquidity as an ecosystem requirement. Publisher episode, Martin at
00:40:23–00:41:31 - Boards [researcher inference | insufficient public record]: the interview gives no portfolio-company board example showing how these technical or policy views changed a product, financing, governance, or exit decision. Publisher episode, full recording
Contradictions, counterevidence, and access limits
- The publisher transcript is machine-generated even though speaker-separated and approved; it misspells Casado's first name in places. [contemporaneous record | strong] Selected quotations were checked against the publisher audio, but punctuation and nonquoted wording remain transcription artifacts. Publisher episode
- Casado says AI is probably terrible for physics simulation immediately after offering physics simulation as a candidate for publicly funded research. [investor-stated | strong] He acknowledges the weak example and reframes the case around broad research spillovers rather than a validated use case. Publisher episode, Martin at
00:21:42–00:23:17 - His information-theoretic argument against closed agent loops understates that tools, environments, tests, memory stores, and users can inject task-relevant information; Brian raises code compilation and error correction as partial counterexamples. [researcher inference | moderate] Casado responds that formal correctness is available in constrained channels but often absent for open-ended LLM tasks. Publisher episode, Brian and Martin at
00:30:39–00:34:21 - The claim that GDPR was especially beneficial to Meta and that policy generally helps incumbents is plausible regulatory-incidence reasoning but unsupported by comparative compliance costs, concentration trends, or causal identification here. [investor-stated | provisional] Publisher episode, Martin at
00:35:41–00:36:43 - The anti-monopoly thesis depends on distillation remaining effective and leaders not converting scale into proprietary data, distribution, capital, or platform control. [researcher inference | moderate] The interview supplies mechanism but no market-share forecast or falsification threshold. Publisher episode, Martin at
00:01:57–00:05:27and00:16:56–00:19:18
Open questions
- What market-share, price, or performance evidence would falsify the predicted fragmented model market?
- Which ASCI project and deliverables did Casado work on, and how did that experience shape later investment decisions rather than only policy views?
- What research charter, access rules, and evaluation standards would keep a national AI resource scientifically useful without entrenching incumbents?
- Which agent tasks have sufficiently formal correctness targets to overcome his objection, and what intervention rate would count as economic autonomy?
- How have M&A restrictions changed founder formation, follow-on financing, and venture returns after controlling for rates and the 2021 valuation cycle?
- Which existing software rules map cleanly to foundation models, and where do model-specific capabilities create genuinely new liability questions?
[t] AI Innovation and AGI (Turpentine VC E70 replay)
- URL: https://metacast.app/podcast/turpentine-vc-venture-capital-and-investing/LUJoKypp/e70-martin-casado-of-a16z-on-ai-innovation-and-agi/zb2A3RvL | Published: 2024-12-24 | Format: Turpentine VC E70 replay of The Cognitive Revolution interview (Nathan Labenz and Martin Casado) | Reliability: A for the original publisher transcript and audio; A for replay identity/duration from the official Turpentine VC feed | Access: full E70 audio; full original publisher audio, video, and speaker-labelled transcript | Accessed: 2026-08-19 | Locator scheme: original publisher transcript/video elapsed time is used for claim pinpoints; the shortened E70 replay has a different edit and clock | Version: E70 RSS GUID
1dd7895a-c15b-11ef-9ce7-0f3770c280e5, duration01:43:40; replay of The Cognitive Revolution'sAI Safety Regulations: Prudent or Paranoid?, published2024-06-28, original duration01:48:20
Takeaways
- Steady progress, moving goalpost [investor-stated | moderate]: Casado sees eighty years of AI as cumulative progress rather than an impending discontinuity; tasks stop being called AI after they become routine, making AGI a moving goalpost. Original publisher transcript/video, Martin at
00:04:06–00:05:20 - Heavy-tail thesis [investor-stated | moderate]: general systems confront rare and economically expensive exceptions even when common-task accuracy is high. Self-driving and support chatbots are his analogies for why headline averages can obscure the unresolved tail. Original publisher transcript/video, Martin at
00:12:30–00:18:36 - Meaning is not just compression [investor-stated | provisional]: Casado argues that predicting the next representation from a human corpus does not supply the embodied, causal meaning needed for many unique tasks; Labenz counters that human abstraction and protein-folding systems offer evidence that useful shortcuts need not simulate the universe. Original publisher transcript/video, Nathan and Martin at
00:28:36–00:51:09 - Regulate applications, not primitives [investor-stated | strong]: Casado says “AI” is too broad to distinguish from software and urges policymakers to extend existing application, product, and conduct rules rather than impose model- or compute-level restrictions. He supports regulation and self-policing for harmful behavior while resisting general-purpose-tool liability. Original publisher transcript/video, Nathan and Martin at
01:00:30–01:16:42 - Historical analogy as method [investor-stated | strong]: his default reasoning draws from distributed systems, cybersecurity, Internet openness, and software liability; he asks for demonstrated model-specific harm before abandoning those precedents. Labenz disputes whether trained systems' unknown capabilities make the analogy incomplete. Original publisher transcript/video, Nathan and Martin at
01:01:58–01:09:27 - Fragmentation bet [investor-stated | moderate]: Casado expects diminishing returns and distillation to produce a model “slugfest” rather than an enduring winner; he offers a two-year one-dollar bet that no leader will hold roughly 80% of the market. Labenz argues scaling and economic value could create a divide. Original publisher transcript/video, Nathan and Martin at
01:36:20–01:41:48 - Modern VC translation (as of 2026-08-19) [researcher inference | moderate]: diligence tail cases, verification costs, and economic reliability rather than average benchmark scores; treat model concentration, regulation, and recursive improvement as explicit competing scenarios with observable triggers. Do not infer a policy conclusion solely from Casado's historical analogy. Original publisher transcript/video, Martin and Nathan at
00:12:30–00:18:36,01:00:30–01:21:22, and01:36:20–01:41:48
Quotes
- “This whole AGI thing has been a moving goalpost for 70 years.” — Martin Casado,
00:04:45. [investor-stated | strong] Original publisher transcript - “You regulate the applications. You regulate the industries.” — Martin Casado,
01:03:33. [investor-stated | strong] Original publisher transcript - “I will bet you a dollar in 2 years that, like, this has turned out to be relatively fragmented.” — Martin Casado,
01:36:59. [investor-stated | strong] Original publisher transcript
Biography and decision evidence
- Casado anchors his skepticism in a systems career: computer-science PhD work beginning at Stanford in 2003, three decades building distributed systems, and prior computational-physics work. [investor-stated | strong] These facts explain his reliance on tails, bounds, and historical analogy but do not validate each forecast. Original publisher transcript/video, Martin at
00:06:34–00:08:54 - He says that after nearly a decade as a professional investor and roughly three times longer with complex systems, the model market does not resemble a normal network or first-mover scale effect. [retrospective witness | moderate] He turns that judgment into a dated, falsifiable two-year concentration bet, though the precise market denominator remains undefined. Original publisher transcript/video, Martin at
01:36:20–01:41:48 - Casado says he was in Japan when his parents nearly paid a fake imprisonment demand and later learned the scheme used a muffled human voice, not AI. [retrospective witness | moderate] He uses the incident to demonstrate how observers can incorrectly attribute existing harms to AI. Original publisher transcript/video, Martin at
01:21:22–01:23:48 - No specific a16z deal, fund, check, ownership, reserve, board action, exit, or return is disclosed. [researcher inference | strong] The source supports investment-worldview evidence and one forecast, not investment attribution. Original publisher transcript/video, full episode
Philosophy signals
- Picking / risk [investor-stated | strong]: evaluate the exception distribution and cost to resolve the tail; aggregate task accuracy can conceal the work that remains economically decisive. Original publisher transcript/video, Martin at
00:12:30–00:18:36 - Macro / risk [investor-stated | moderate]: regulatory posture should change when demonstrated capability or harm changes, not merely because a thought experiment is frightening. Original publisher transcript/video, Nathan and Martin at
01:18:11–01:31:41 - Picking / portfolio [investor-stated | moderate]: foundation-model leadership is expected to be temporary and capital-intensive; application-level value can therefore remain fragmented even when one model briefly leads. Original publisher transcript/video, Nathan and Martin at
01:36:20–01:41:48 - People [researcher inference | moderate]: a systems founder/investor may notice bounds and tails that benchmark-centered analysis misses, but may also overweight historical analogy when trained models introduce new properties. Original publisher transcript/video, Nathan and Martin at
01:01:58–01:09:27 - Boards / exits [researcher inference | insufficient public record]: the episode does not connect the technical or policy thesis to governance, follow-on, sale, or distribution decisions. Original publisher transcript/video, full episode
Contradictions, counterevidence, and access limits
- E70 is not the original release: the Turpentine VC feed republishes a shortened
01:43:40edit on 2024-12-24, while the original Cognitive Revolution page published 2024-06-28 has a01:48:20version and full transcript. [contemporaneous record | strong] Claim pinpoints bind to the original publisher version and must not be applied to the replay clock. E70 listing Original publisher page - Labenz supplies substantive counterevidence: humans are an existence proof for abstraction, protein-folding work shows useful shortcuts, model capabilities are discovered rather than fully engineered, and autonomous interfaces may enlarge harms. [contemporaneous record | strong] Casado accepts uncertainty and specialized progress but rejects a demonstrated general discontinuity. Original publisher transcript/video, Nathan and Martin at
00:00:00–00:03:24,00:28:36–00:59:57, and01:05:08–01:21:22 - Casado initially argues general-tool providers should not be liable, then agrees it is fair to impose safeguards where a service has substantially completed a criminal act and the use case is narrow. [investor-stated | strong] That concession limits a simple “applications only” slogan and points toward gradations of autonomy and purpose. Original publisher transcript/video, Nathan and Martin at
01:12:14–01:16:42 - Self-driving investment, unit economics, brain/model compute, and scaling claims are uncited oral figures. [investor-stated | provisional] They should be independently sourced before use as facts; the heavy-tail mechanism does not depend on their exact values. Original publisher transcript/video, Martin at
00:06:34–00:18:36and01:11:51–01:20:07 - The “no step change” view can coexist uneasily with Casado's description of models as a new primitive and his willingness to invest in a superintelligence venture. [researcher inference | moderate] His consistent position is that useful advances continue without evidence of one general, exponential endpoint. Original publisher transcript/video, Martin at
00:04:06–00:05:20,00:51:09–00:59:57, and01:26:18–01:31:41
Open questions
- What exact market, revenue denominator, and measurement source would settle the two-year model-fragmentation bet?
- Which tail cases in production LLM systems determine labor cost, liability, retention, or gross margin, and how quickly are they improving?
- What demonstrated model capability would Casado accept as a paradigm shift requiring primitive-level regulation?
- Where should liability move from the end user to an agent service as autonomy, purpose-specific training, and provider control increase?
- Which historical Internet analogy failed, and how does Casado prevent analogy selection from merely confirming his prior?
- Did these views change any a16z model-company investment, follow-on, conflict, or governance decision before the interview?
[t] AI Is Upending SaaS Pricing
- URL: https://a16z.com/podcast/ai-is-upending-saas-pricing/ | Published: 2025-07-18 | Format: two-person firm podcast (Martin Casado and Metronome CEO Scott Woody) | Reliability: A for official audio, B for navigation transcript | Access: full official audio; partial public transcript plus speaker-checked local ASR used as a locator | Accessed: 2026-08-20 | Locator scheme: official-audio elapsed timestamps | Version: AI + a16z Simplecast episode
62ee5a37-37e5-461a-9194-fd45f0fb58fa, 42:52
Takeaways
[investor-stated | strong]Casado and Woody describe three monetization eras: perpetual on-premises licenses, cloud subscriptions priced by seats, and AI software priced increasingly by work or output. AI can reduce the user count while increasing work performed, breaking the seat-to-value link. 08:00–10:17, speaker-checked official audio[investor-stated | strong]They expect hybrid pricing to bridge the transition: a subscription or platform minimum preserves customer and vendor predictability, while a variable component captures additional delivered value. They do not claim that every product should move to pure consumption. 10:42–12:11[investor-stated | strong]Usage billing is an operating system, not a price-list change. It requires near-real-time metering, financially accurate event data, flexible contract logic, sales compensation tied to realized use, technical customer success, product metrics aligned to value, and faster finance feedback. 12:11–16:32 and 16:32–25:00, speaker-checked official audio[investor-stated | strong]Woody's implementation test is executive authority: if the CEO will not align sales, product, support, engineering, and finance, a usage transition is not real. He prefers a responsible pricing decision-maker over a council because cross-functional incentives otherwise stall the change. 19:59–20:45 and 29:43–32:25[investor-stated | moderate]The episode proposes segmentation rather than one universal model: subscription remains useful in consumer products where repeated purchase decisions create friction; human-facing B2B tends toward hybrids; agent-facing or infrastructure layers can move closer to pure usage; enterprise outcome pricing may use a measured proof-of-concept. 26:25–29:13[researcher inference | moderate]Decision rule: identify the customer value event; test whether it can be measured accurately and quickly; model vendor COGS, customer budget variance, and gross margin at several use levels; then align sales compensation and post-sale ownership before changing the metric. 12:11–25:00[researcher inference | moderate]Modern VC translation (as of 2026-08-20): value-metric diligence, metering integrity, incentive alignment, and pricing agility transfer. Pure usage does not transfer where customers demand budget certainty or value is not attributable. Changed assumptions include agents, volatile inference COGS, and shrinking seats. Signals are usage expansion, spend predictability, time-to-price change, and workload retention; misuse is relabeling variable COGS as alignment. Current example: Woody's Metronome is a financially interested billing vendor, so its playbook requires independent customer evidence. 25:00–34:00 and episode disclosure
Quotes
[investor-stated | strong]“Now I would call the AI era, or the value era.” — Woody. 08:00–08:29[investor-stated | strong]“You don't want a pricing council. You want a pricing dictator.” — Woody. 29:43–30:03, speaker-checked official audio
Biography and decision evidence
[retrospective witness | moderate]Casado recalls Nicira attempting usage pricing despite a strong distributed-systems team and finding it unexpectedly hard. The episode provides an operating lesson, not contemporaneous Nicira billing data. 12:11–12:47[investor-stated | moderate]Casado says he sits on multiple AI-company boards whose teams are actively reconsidering usage billing. No company list, board decision, adoption result, or Casado-specific intervention is disclosed. 07:01–08:00[documented behavior | strong]The source is an a16z-produced interview with the CEO of Metronome, an a16z portfolio company whose product benefits from greater pricing complexity. Both the investor and vendor interests are visible in the episode framing. episode description and contributors
Philosophy signals
- picking:
[investor-stated | strong]prefer companies whose revenue metric corresponds to customer value and whose metering, data, and contract systems can support that correspondence. 12:11–19:59 - boards / operations:
[investor-stated | strong]treat pricing migration as CEO-owned business transformation with explicit sales, customer-success, product, engineering, and finance responsibilities. 19:59–25:00 and 29:43–32:25 - risk:
[investor-stated | strong]protect against runaway spend, inaccurate billing, enterprise-contract exceptions, fake booked usage, negative-margin heavy users, and slow pricing iteration. 12:47–16:32 and 20:45–25:00 - learning:
[investor-stated | strong]move from quarterly optimization to continuous pricing exploration because model capability, cost, and competitor offers change quickly. 32:25–34:42
Contradictions, counterevidence, and access limits
[researcher inference | moderate]Usage pricing can align revenue with use while misaligning it with outcome: token, query, or message volume may rise because the product is inefficient or because the customer is failing. The episode's own emphasis on a core value metric supports this distinction. 20:45–25:00[researcher inference | moderate]The “pricing dictator” solves coordination by concentrating authority but creates governance and customer-fairness risks. The episode specifies no approval, experimentation-ethics, audit, or rollback controls. 29:43–32:25[researcher inference | strong]Metronome's examples are selected vendor observations, not a representative cohort. No matched evidence shows that usage or hybrid models produce higher retention, margins, valuation, or returns after controlling for product and market. episode description and speaker context[researcher inference | moderate]Casado's 2025 optimism about pricing agility sits in tension with the 2020 warning that AI's variable costs and service intensity can structurally weaken margins; value pricing cannot remove COGS. New Business of AI, “Gross Margins” sections[contemporaneous record | strong]The official audio is complete. Podscan exposes only an initial transcript preview; local tiny.en ASR was used only to navigate and timestamps were checked against official audio. No ASR-only wording beyond the two short checked quotes is promoted. Simplecast episode record
Open questions
[researcher inference | insufficient public record]Which pricing migrations improved cohort retention, gross margin, net revenue retention, and customer budgeting outcomes? Official episode[researcher inference | insufficient public record]What guardrails constrain the centralized pricing authority and protect customers during experiments? Official episode[researcher inference | insufficient public record]How should outcome pricing handle causality, shared human contribution, reversals, and tail risk? Official episode[researcher inference | insufficient public record]Which a16z board decisions used this framework, and what changed after implementation? Official episode
[t] All About Microservices
- URL: https://a16z.com/podcast/a16z-podcast-all-about-microservices/ | Published: 2016-09-01 | Format: firm podcast with official speaker-labeled transcript (Adrian Cockcroft with Martin Casado and Frank Chen; Sonal Chokshi introduction) | Reliability: A for each speaker's direct views; company and market generalizations are not independently verified | Access: full official transcript and audio | Accessed: 2026-08-19 | Locator scheme: official transcript named headings plus official-audio timestamps | Version: Simplecast episode 6ba139be-7068-4116-97c3-2e56cb6c82f2, 128 kbps asset, runtime 27:05; official a16z transcript rendered on canonical page
Takeaways
[investor-stated | strong]Speaker separation: Cockcroft supplies the Netflix migration, organization, database, security, container, and serverless operating evidence; Casado supplies the infrastructure-market and investing interpretations; Chen moderates and contributes some company examples. Netflix experience must not be reassigned to Casado. Official transcript, introduction through “Moving to a microservices architecture”[retrospective witness | moderate]Cockcroft says Netflix combined a cloud move, monolith breakup, and organizational redesign because streaming growth exceeded data-center capacity and the existing development process was losing productivity. He calls database decomposition the hardest transition and warns that services sharing one database remain a fragile “distributed monolith.” Cockcroft, official transcript “Moving to a microservices architecture”[investor-stated | strong]Casado's core technical claim is that microservices lift infrastructure from low-semantic compute/network/storage primitives into the application layer. Structured application context can then support new security, debugging, operations, discovery, naming, and routing tools. Casado, about 08:13–09:35[investor-stated | moderate]He separates an internal architecture trend from an industry-structure trend: one company can decompose its product, while other companies can sell one narrow API as a product. The latter permits applications assembled from external functions and creates a possible “function per company” market. Casado, about 14:13–16:06[investor-stated | strong]Casado immediately states the economic boundary: narrow functions raise unresolved questions about ownership, dependability, and total market size. Cockcroft adds that cheap, rapidly changing components can make proprietary billion-dollar software companies harder to build. Casado and Cockcroft, about 15:27–18:22[investor-stated | moderate]Casado predicts that closed-source shipped distributed systems will lose ground because customer environments, versions, QA matrices, and scarce cluster operators create heavy post-sales burden; operating the system as a service centralizes that burden. He does not claim that hosting removes infrastructure cost or guarantees attractive margins. Casado, about 17:08–18:22[retrospective witness | moderate]Cockcroft describes the progression from stable machines to VMs, minute-scale containers, and request-scale serverless execution. His operational conclusion is that monitoring, billing, scheduling, and tracing must become fast enough that their overhead does not dominate the work. These are Cockcroft's practitioner observations, not Casado's portfolio results. Cockcroft, official transcript “Advantages for development teams”[investor-stated | moderate]Casado offers a disruption-sequencing rule: application decomposition and developer velocity arrive first; visibility, security, and day-two operations ecosystems fill the resulting vacuum. He therefore views missing tooling both as risk and as a map of future company opportunities. Casado, about 22:26–23:06[investor-stated | moderate]He identifies platform engineering or DevOps as a new product-aligned infrastructure buying center with budget and technical authority, distinct from traditional IT procurement. The episode supplies observation rather than buyer counts, budget data, or conversion evidence. Casado, about 24:25–24:44[researcher inference | moderate]Decision rule: a microservices-infrastructure investment needs both an architectural pain map—semantics, coordination, security, observability, billing—and a company-size map showing ownership, dependency control, durable distribution, and venture-scale spend. Component novelty alone is insufficient. Casado and Cockcroft, official transcript “Security advantages” through “Advantages for development teams”
Quotes
[investor-stated | strong]“Every single function, or a logical function, becomes an independent company.” — Casado. (10 words) Official transcript, “Market trends toward microservices”; audio about 15:27[investor-stated | strong]“The disruption happens first and then all the day-2 Ops happens second.” — Casado. (12 words) Official transcript, “Advantages for development teams”; audio about 22:26
Biography and decision evidence
[investor-stated | strong]The episode captures Casado in 2016 applying his networking/infrastructure lens to application architecture: richer application semantics become insertion points for security and operations. It is intellectual-position evidence, not proof that Nicira work caused this view. Casado, official transcript “Security advantages”[contemporaneous record | moderate]Chen identifies company 21 as an a16z portfolio example in machine-to-machine API billing and mentions Bitcoin as a possible mechanism. The remark is Chen's, not Casado's; no sourcing, sponsor, board role, ownership, product result, or deal economics are provided. Chen, official transcript “Advantages for development teams”[researcher inference | moderate]Casado's questions about function-level market size and tooling gaps show an investor separating technical inevitability from company economics within his first year at a16z. The episode does not reveal an investment-committee process or later decisions. Casado, about 15:27–18:22 and 22:26–25:55
Philosophy signals
- Tags: sourcing / picking.
[investor-stated | strong]Architectural decomposition creates investable gaps where application semantics permit better security, observability, operations, discovery, routing, and debugging. Casado, about 08:13–09:35 and 25:21–25:55 - Tags: risk / portfolio.
[investor-stated | strong]Do not confuse a technically useful function with a venture-scale company; ownership, dependency, service reliability, delivery model, and reachable market remain separate underwriting questions. Casado, about 15:27–18:22 - Tags: people / boards.
[retrospective witness | moderate]Cockcroft's Netflix evidence supports product-aligned teams owning and operating services, but the episode gives no Casado board action applying that organization design. Cockcroft, official transcript “Moving to a microservices architecture” and close - Tags: macro / self-interest.
[researcher inference | moderate]Calling each new operational gap an ecosystem opportunity expands a16z's infrastructure investment surface. The episode itself supplies the useful counterweight that functions may remain too small and component markets may be cheap and unstable. Casado, Chen, and Cockcroft, official transcript “Market trends toward microservices”
Contradictions, counterevidence, and access limits
[retrospective witness | strong]Cockcroft's “distributed monolith” warning is a direct counterexample to architecture-by-label: splitting code without splitting data and decision boundaries retains coupling and fragility. Cockcroft, official transcript “Moving to a microservices architecture”[investor-stated | strong]Casado's function-per-company excitement is explicitly checked by unresolved market-size, ownership, and dependability questions. A synthesis that records only the opportunity would reverse the episode's balance. Casado, official transcript “Market trends toward microservices”[researcher inference | moderate]Service delivery removes some customer-side version and operator problems but can concentrate reliability, security, capital, and cost responsibility in the vendor. The episode recognizes coordination and day-two gaps but does not publish service economics or failure data. Official transcript, “Security advantages” through “Advantages for development teams”[contemporaneous record | strong]The canonical page supplied a full speaker-labeled transcript and the Simplecast API supplied a 27:05 runtime. The page's named sections are stable content locators; detailed seconds were aligned to the official audio using show-note anchors and a public ASR timing aid. Official episode page
Open questions
[researcher inference | insufficient public record]Which 2016 microservices tooling categories became venture-scale companies, and which remained features, open-source projects, or small functions? Official episode[researcher inference | insufficient public record]What company and fund evidence connects Casado personally to any investment arising from the semantic-infrastructure thesis? Official episode[researcher inference | insufficient public record]How should an IC measure dependency concentration, incident blast radius, gross margin, and switching cost in a narrow-API company? Official episode[researcher inference | insufficient public record]Which documented failures test the episode's sequence that day-two tooling reliably follows architectural disruption? Official episode
[t] Cloud Cost with Martin Casado
- URL: https://softwareengineeringdaily.com/2021/06/25/cloud-cost-with-martin-casado/ | Published: 2021-06-25 | Format: long-form publisher interview (Jeff Meyerson interviewing Martin Casado) | Reliability: A for Casado's direct voice; modeled market-value figures, anonymized company observations, and portfolio claims are not independently verified | Access: full publisher transcript and official audio | Accessed: 2026-08-20 | Locator scheme: publisher-transcript timestamps and PDF pages; official audio timing aligns within one second | Version: Software Engineering Daily episode SED1287, 21-page transcript; Megaphone asset SED6949261638, 128 kbps, runtime 49:26.100; transcript final speaker timestamp 49:25
Takeaways
[investor-stated | strong]Speaker separation: Meyerson supplies questions, hypotheticals, and some framing statistics; Casado supplies the three-stage company model, cloud-cost analysis, repatriation boundaries, optimization-market thesis, and investing observations. Show-note assertions are not treated as Casado evidence unless he states them in the interview. Publisher transcript, 00:03:24; p. 3[investor-stated | strong]Casado says the cloud is the right growth substrate during product discovery because it provides fast infrastructure and managed services while a company develops innovation and sales muscles. The cost problem becomes strategically salient when growth saturates and operations, cash flow, and margin receive more weight. Casado, 00:03:39–00:05:11; pp. 3–4[investor-stated | provisional]He describes an analysis of fifty public software companies, 76% of which had IPOed in the preceding five years: under a modeled 50% cloud-cost reduction, approximately $100 billion of aggregate market value was depressed by cloud expense. Roughly eight interviewed companies all had or planned repatriation efforts and estimated 2–3x savings. The sample, identities, valuation model, and estimates are not reproduced in the transcript. Casado, 00:05:44–00:10:23; pp. 4–5[investor-stated | strong]Casado defines repatriation as moving selected workloads from a major cloud to lower-level hosted or bare-metal infrastructure, not necessarily owning and racking servers. Dropbox illustrates workload-specific decomposition—storage moved while metadata could remain in cloud—rather than an all-or-nothing cloud reversal. Casado, 00:07:19–00:10:23; pp. 4–5[investor-stated | strong]He explicitly does not recommend repatriation for a given company. The nearer-term rule is to make cloud cost a first-order KPI, expose it throughout engineering, reward optimization where appropriate, preserve architectural options, and consider hybrid infrastructure early enough that switching remains possible. Casado, 00:13:44–00:15:25 and 21:50–24:57; pp. 7 and 10–11[investor-stated | moderate]His historical analogy is the hyperscalers' own decision to replace high-margin server and network OEMs with internal hardware once cost of goods became large enough. The analogy demonstrates that non-core engineering can become rational at scale; it does not show that SaaS repatriation has the same talent, capital, reliability, or workload economics. Casado, 00:10:41–00:13:29 and 22:30–24:57; pp. 5–7 and 10–11[investor-stated | moderate]Casado says cloud-cost optimization remained fragmented because platforms were still growing, lowering unit prices, and differentiating rapidly while preserving roughly 30% margins. He predicts a stronger opening when innovation slows and lower-margin substitutes can challenge the oligopoly, but repeatedly says he does not know whether clouds cut margins, workloads move, or repatriation wins. Casado, 00:16:00–00:19:53 and 27:04–30:58; pp. 8–9 and 12–14[investor-stated | provisional]He calls the problem investable across cost visibility, optimization, marketplaces, alternative infrastructure, and repatriation paths, citing an estimated $500 billion to $1 trillion of value transfer. Those ranges derive from the same a16z analysis and broad market-cap comparisons, not audited revenue pools or a demonstrated startup-addressable market. Casado, 00:19:53–00:21:50; pp. 9–10[investor-stated | strong]Kubernetes is not a standalone cost or portability solution in Casado's view. It can help a capable team, but cross-cloud portability spans a much larger architecture and operating model; tool adoption should not be mistaken for credible switching leverage. Casado, 00:30:58–00:31:55; p. 14[investor-stated | strong]Casado sharply limits the analysis to public SaaS businesses for which cloud is a material cost of goods and valuation multiples are observable. He says it probably does not apply to an ordinary enterprise's digital transformation and still believes most enterprise workloads should move toward cloud. Casado, 00:47:32–00:49:23; pp. 20–21[researcher inference | moderate]Decision rule: quantify cloud as a percentage of product COGS, forecast its effect when growth slows, distinguish optimizable code from irreducible platform margin, preserve workload-specific exit options, and invest only where a startup captures savings without recreating cloud complexity. The five-step rule is reconstructed from the interview. Casado, 00:05:44–00:31:55
Quotes
[investor-stated | strong]“I'm not sure I would ever argue for repatriation.” — Casado. (9 words) Publisher transcript, 00:13:44; p. 7[investor-stated | strong]“cloud costs have to be a core metric that is tracked” — Casado. (10 words) Publisher transcript, 00:22:30; p. 10
Biography and decision evidence
[retrospective witness | provisional]Casado invokes having run an approximately $600 million VMware data-center software business to argue that sophisticated non-cloud data-center operations were viable. The claim is first-person experience, but the transcript supplies no period, revenue definition, margin, or team attribution. Casado, 00:10:41–00:13:29; pp. 5–7[investor-stated | provisional]He says the first ten significant Nicira customers came through a16z's market-development network, using this to explain how portfolio concentration can support deal winning and market education. The statement does not identify customers, dates, contract value, partner credit, or a comparison against unaffiliated channels. Casado, 00:38:17–00:40:16; pp. 17–18[investor-stated | moderate]Casado says a16z studies data subspaces before investing and uses like-company portfolio groupings for customer introductions. This is direct process testimony; it does not establish which partner sourced or sponsored individual deals, ownership, conflicts, or whether portfolio “synergy” improved outcomes. Casado, 00:37:33–00:40:16; pp. 16–18
Philosophy signals
- Tags: picking / macro.
[investor-stated | moderate]Look for economic pressure that becomes acute at maturity, but distinguish a future inevitability from the uncertain mechanism—optimization software, alternative providers, cloud margin compression, or workload repatriation. Casado, 00:16:00–00:30:58; pp. 8–14 - Tags: boards / risk.
[investor-stated | strong]Put cloud cost into product and engineering telemetry before it becomes a financing constraint, while keeping growth and product-market fit ahead of indiscriminate cost cutting. Casado, 00:03:48–00:05:11 and 13:44–15:25; pp. 3 and 7 - Tags: portfolio / sourcing.
[investor-stated | moderate]Develop a subcategory map deeply enough to teach founders and convene qualified customer conversations; treat portfolio adjacency as an operating and sourcing advantage rather than assuming one data market. Casado, 00:37:33–00:42:03; pp. 16–18 - Tags: self-interest.
[researcher inference | moderate]The article and interview define a large new infrastructure investment surface for Casado while selected portfolio and Nicira examples support a16z's market-network claim. His narrow SaaS scope and repeated uncertainty temper the promotion but do not independently validate the market-size model. Casado, 00:19:53–00:25:19 and 37:33–40:16
Contradictions, counterevidence, and access limits
[investor-stated | strong]The episode is often framed as pro-repatriation, but Casado repeatedly calls repatriation one possible mechanism and says he cannot prescribe it. A synthesis that converts the analysis into “leave the cloud” would contradict his stated scope and enterprise-cloud support. Casado, 00:13:44–00:15:25 and 47:32–49:23; pp. 7 and 20–21[researcher inference | strong]The $100 billion, 50-company, 76%, 50% cost-reduction, 2–3x savings, and $500 billion–$1 trillion claims are components of one modeled a16z thesis, not independent corroborations. Company interviews are anonymized and Casado approximates their count, so the evidence is directional. Casado, 00:05:44–00:10:23 and 19:53–21:50; pp. 4–5 and 9–10[researcher inference | moderate]Cloud-provider OEM substitution is an imperfect analogy: hyperscalers possessed exceptional scale, engineering talent, standardized workloads, and capital. A SaaS vendor can lose product focus, reliability, elasticity, or security while pursuing nominal infrastructure savings. Casado, 00:10:41–00:13:29; pp. 5–7[contemporaneous record | strong]Software Engineering Daily supplies a complete, speaker-coded 21-page transcript and official audio. The transcript's last response is 49:25 and the current Megaphone asset is 49:26.100, so its page-and-time locators are stable; no raw transcript or media was retained in the repository. Publisher episode page
Open questions
[researcher inference | insufficient public record]Which fifty public companies, valuation-multiple assumptions, COGS classifications, and counterfactual costs generated the $100 billion estimate? Publisher transcript, pp. 3–20[researcher inference | insufficient public record]Which interviewed SaaS companies actually repatriated workloads, what was the full transition cost, and what reliability, margin, and product-velocity outcome followed? Publisher transcript, pp. 3–20[researcher inference | insufficient public record]Which cloud-cost startups did Casado fund, what ex-ante mechanism did each pursue, and did realized customer savings support venture-scale margins? Publisher transcript, pp. 3–20[researcher inference | insufficient public record]What customer and contract records corroborate the claim that a16z's market-development network produced Nicira's first ten significant customers? Publisher transcript, pp. 3–20
[t] Cloud Wars, Company Wars, and Innovating Through Change
- URL: https://a16z.com/podcast/cloud-wars-company-wars-and-innovating-through-change/ | Published: 2022-09-07 | Format: edited roundtable podcast with Martin Casado, Michael Dell, Marc Andreessen, and Sonal Chokshi | Reliability: A for speaker-attributed views and biography; B for uncited market counts, margin figures, and causal forecasts | Access: full official audio; publisher description only, with an unofficial ASR transcript used for navigation and checked against the audio | Accessed: 2026-08-20 | Locator scheme: elapsed time in the 00:53:44 official Simplecast episode (episode 675; GUID fa66734b-feea-4dc3-bb7f-495aee7e5525) | Version: recorded October 2021 for Michael Dell's Play Nice But Win launch; publisher page dated 2022-09-07 and modified 2023-10-20
Takeaways
- Cloud Wars 2.0.
[investor-stated | moderate]Casado distinguishes the first cloud contest—public cloud versus internal IT—from a second contest in which SaaS and infrastructure vendors must manage cloud inside cost of goods sold. Flexibility and workload placement become economic choices, not merely developer preferences. Official audio, 00:05:30–00:08:32 - Scale changes the build-versus-buy calculation.
[investor-stated | provisional]He says public cloud is usually right for startups and new projects, but predictable, high-volume workloads can justify internal infrastructure once a company can hire operations talent and cloud becomes a large cost line. The episode supplies no company-level cost curves. Official audio, 00:15:32–00:20:39 - Concentration is part of the underwriting.
[investor-stated | provisional]Casado argues that an infrastructure oligopoly can preserve margin even while unit prices fall. His spoken examples—roughly 18% to 30% margins and cloud approaching half of large SaaS COGS—are uncited illustrations, not verified market statistics. Official audio, 00:15:32–00:17:25 - Capital regimes reveal hidden architecture costs.
[investor-stated | provisional]He cites 126 cloud-native IPOs during six years of cheap capital and predicts that tighter financing will force mature software firms to revisit infrastructure concentration and cost. The episode predates the later rate shock, so this is useful ex-ante reasoning but not outcome proof. Official audio, 00:18:35–00:20:39 - Dell's complementary view is hybrid and distributed.
[retrospective witness | moderate]Dell says customer demand points to public cloud, private infrastructure, and edge deployments, with placement shaped by sovereignty, security, latency, and cost; he also describes Kubernetes as a portability layer. These are Dell's operating views, not Casado's. Official audio, 00:03:22–00:04:57 and 00:20:39–00:21:33 - Transformation requires permission and narrative.
[researcher inference | moderate]Casado asks whether founders survive discontinuities because they possess a special truth or accumulated credibility. Dell answers that founders can earn permission to create urgency while inspiring a better future. This informs Casado's people lens but remains one founder's retrospective account. Official audio, 00:40:05–00:41:19
Quotes
[investor-stated | strong]“I would call this Cloud Wars 2.0.” — Casado, official audio, 00:08:10–00:08:22 (7 words)[investor-stated | strong]“So prices will drop 100%, but I don't think margins will.” — Casado, official audio, 00:16:20–00:16:38 (11 words)
Biography and decision evidence
[investor-stated | strong]Casado says that during Dell's 2015 EMC announcement he ran VMware's network and security business unit. He recalls the deal as simultaneously exciting and frightening and describes learning the tracking-stock structure. Official audio, 00:27:19–00:29:06[investor-stated | moderate]He frames Dell and VMware as neutral hardware and software layers within an earlier “battle of titans” among full-stack infrastructure companies. That is an insider's contemporaneous industry position recalled six years later, not an independent reconstruction of the transaction. Official audio, 00:27:19–00:29:06[researcher inference | insufficient public record]The episode contains no identified Casado-led investment, check size, ownership, board decision, realized return, or rejected deal. Its decision evidence is a market screen: test workload predictability, operating competence, COGS exposure, portability, and supplier concentration before underwriting cloud-dependent software. Official audio, 00:15:32–00:20:39
Philosophy signals
- Tags: picking / risk / macro.
[investor-stated | moderate]Architecture can become an investment variable when capital costs rise: a technically convenient supplier choice may later constrain gross margin or bargaining power. Official audio, 00:15:32–00:20:39 - Tags: portfolio / risk.
[investor-stated | moderate]Casado favors conditional rather than categorical infrastructure decisions; startup speed and developer simplicity can dominate early, while scale, workload stability, and concentration matter later. Official audio, 00:18:35–00:20:39 - Tags: people / boards.
[researcher inference | moderate]His questions emphasize whether a leader has earned credibility to force a painful transition and whether conduct compounds trust. The episode does not show how he tests these traits before investing. Official audio, 00:40:05–00:45:27 - Tags: people / self-interest.
[researcher inference | strong]Casado, Andreessen, and Dell benefit from narratives that sustain investment and purchasing across infrastructure layers; publisher and participant attribution therefore matter when using their market forecasts. Official page, participants and episode context
Contradictions, counterevidence, and access limits
[researcher inference | moderate]Casado's portability thesis is technically plausible, but later FTC analysis found that cloud–AI partnerships can impose spending commitments, exclusivity, and technical or contractual switching costs. Kubernetes alone therefore does not establish commercial portability. FTC staff report, “Summary of Findings,” printed pp. 2–3; §§4.3 and 5.2, printed pp. 19 and 32–34[contemporaneous record | moderate]The FTC's 2023 cloud inquiry collected concerns about concentration, outages, egress fees, and switching; the agency also cautioned that public comments were not a complete market study. This supports testing Casado's concentration concern without validating his specific margins or COGS figures. FTC, “Cloud Computing RFI: What We Heard and Learned”[researcher inference | strong]The claim that falling prices need not reduce oligopoly margins is directionally coherent but underspecified: price, mix, utilization, depreciation, committed-use discounts, and customer bargaining power are not separated. The oral figures should not enter an investment model without primary filings or invoices. Official audio, 00:15:32–00:17:25[contemporaneous record | strong]The official audio and descriptive page were accessible. The publisher supplied no full transcript; an unlabeled third-party ASR transcript was used only to locate passages, with speaker identity and selected wording checked against official audio. No raw transcript or media was retained in the repository. Official episode page
Open questions
[researcher inference | insufficient public record]Which of Casado's 126 cloud-native IPOs later repatriated workloads, and how did total infrastructure cost and gross margin change? Official episode[researcher inference | insufficient public record]At what utilization, workload stability, and staffing level does internal infrastructure beat committed-use public-cloud pricing? Official episode[researcher inference | insufficient public record]Were the cited margin and COGS figures drawn from public filings, private portfolio data, or illustrative estimates? Official episode[researcher inference | insufficient public record]How did Casado apply this architecture screen to a named investment before the decision, including an ordinary or failed case? Official episode
[t] a16z Podcast: Creating a Category, from Pricing to Positioning
- URL: https://a16z.com/podcast/a16z-podcast-creating-a-category-from-pricing-to-positioning/ | Published: 2018-02-24 | Format: three-speaker a16z podcast; Sonal Chokshi interviews Martin Casado and Michel Feaster | Reliability: A for the complete official audio, speaker self-identification, direct handoffs, and publisher metadata; B for local ASR used only to navigate and locate passages | Access: full — official 31:50 audio acquired and reviewed; official page and feed available; no publisher transcript or chapters located | Accessed: 2026-08-20 | Locator scheme: elapsed time in the 31:50 Simplecast audio; Casado-only claims are limited to self-reference, direct address, named handoff, or acoustically continuous turns | Version: a16z page modified 2023-08-29; Simplecast episode 362, UUID
66a48cde-3c51-4c06-8068-f7efcb78f191, tokenMD2mN_Du, legacy RSS GUIDtag:soundcloud,2010:tracks/404591538; publisher duration00:31:50; reviewed MP3 duration1,910.987750seconds, 22,931,914 bytes, 96 kbps
Takeaways
- [investor-stated | strong] Casado reduces category creation to two linked jobs: implant a previously absent concept in the buyer's mind, then assign value to it. Creating the playing field lets the vendor influence its rules, but the later discussion shows that incumbents and customer processes still constrain that control. Official audio, Casado at 02:06–02:55
- [contemporaneous record | strong] Feaster opens with a pricing definition: improving an established monitoring category inherits its price, whereas defining a new problem and solution can redirect budget and reset contract value. This is Feaster's operating thesis, not Casado's independent evidence. Official audio, Feaster at 01:15–01:37
- [investor-stated | strong] Casado's direct-enterprise unit-economics mechanism is finite seller capacity: if a seller can close only a bounded number of deals and labor has a market price, annual contract value drives contribution margin. His $200,000–$300,000 examples are hurdles for that motion, not a universal startup pricing rule. Official audio, Casado at 03:53–05:16
- [contemporaneous record | moderate] Feaster says early visionary buyers can accept the unproven narrative, while risk falls and attainable ACV rises once roughly 20–50 enterprise customers include recognizable leaders in multiple verticals. The threshold is experience-based and no denominator is supplied. Official audio, Feaster at 05:55–06:41
- [investor-stated | strong] Casado advises portfolio companies to postpone price discussion until technical close: expose the newly recognized problem, run SE-led proofs or pilots, establish technical value, and only then price. Publishing list price first can cap value before the customer understands its risk. Official audio, Casado at 06:42–07:38
- [contemporaneous record | strong] Feaster treats product marketing as category infrastructure: define the buying box, translate differentiation, arm sales, and convert the first 20 customers into references, case studies, community evidence, and ROI tools. Casado explicitly agrees that this function is critical for early enterprise go-to-market. Official audio, Feaster at 08:09–09:16 and Casado at 09:16–09:21
- [investor-stated | strong] Casado describes enterprise sales as an algorithm with conditional branches rather than a deck or battle card. High-end enterprise and telecom sales can require multi-year cycles, several actors, and navigation from sub-organizations to the C-suite; product marketing should encode that repeatable play. Official audio, Casado at 12:24–13:11
- [investor-stated | strong] Casado warns that founder charisma can create paid meetings and local “brush fires” without product-market fit. Money and engagement are insufficient signals because customers may pay to learn; the test is whether the motion can scale beyond the founder. Official audio, Casado at 13:41–14:40
- [investor-stated | strong] He gives three concrete product-market-fit indicators: production use rather than paid pilots or shelfware; similar use cases across deployments; and a repeatable sale executed by a non-expert without the founder. These are diagnostic signals, not a claim that all three guarantee retention or attractive economics. Official audio, Casado at 16:12–17:23
- [investor-stated | strong] Casado's category-entry sequence has two phases. First reverse-engineer the incumbent context—budget, buyer, procurement, relationships, and criteria. Then, if the new category takes hold, define a new context that later entrants must navigate. Nicira tested whether network virtualization belonged to networking, security, or virtualization budgets and discovered a new owner. Official audio, Casado at 19:33–20:39
- [retrospective witness | strong] Casado says Nicira's technical narrative did not make selling easy because its academic founders arrived with a solution before customers recognized the problem. His correction is to map to the buyer's current mental model and then change it incrementally rather than begin ten steps ahead. Official audio, Casado at 21:29–22:30
- [investor-stated | strong] In diligence, Casado treats improvised internal or low-quality workarounds as positive problem evidence: willingness to build a patch shows acuity and budget intent. Feaster adds the counterweight that some core users will still build, so the vendor must win the broader segment on opportunity cost, maintenance, and pooled R&D. Official audio, Feaster and Casado at 24:27–25:41
- [investor-stated | strong] For products used by nontechnical business teams, Casado says the organizational transition is incomplete: today's sale often needs a value narrative for the line of business and a different control/integration narrative for IT. A board company he cites literally used two pitches depending on who was in the room. Official audio, Casado at 28:32–29:12
- [researcher inference | moderate] The integrated decision rule is sequence-sensitive: verify an acute workaround and a reachable buyer, prove technical value before anchoring price, distinguish founder-assisted interest from repeatable production use, and build product marketing early enough to encode the emerging sales algorithm. Official audio, Casado at 06:42–07:38, 10:46–11:13, 13:41–17:23, and 24:39–24:52
Quotes
- [researcher inference | insufficient public record] No verbatim quotation is retained. The publisher supplies complete audio but no transcript; local ASR and isolated passage checks support navigation and careful paraphrase, but do not meet the repository's human-transcript quote-verification gate. Official episode and audio · Official Simplecast player
Biography and decision evidence
- [retrospective witness | strong] Casado recalls that he and Feaster each had Ben Horowitz on their boards and that Horowitz impressed on him the unusually direct connection between pricing and company valuation. Casado says the significance became clear only after he had built a startup. This is firsthand recollection, not board minutes. Official audio, Casado at 03:53–04:15
- [investor-stated | strong] Casado explicitly frames the technical-close pricing sequence as advice he repeatedly gives his companies. That is direct portfolio-operating evidence: he intervenes on sales sequencing, not merely on abstract market narratives. Official audio, Casado at 06:42–07:38
- [investor-stated | moderate] When evaluating early enterprise companies, Casado says one of his first checks is whether a product-marketing function exists; he estimates many sales problems are actually missing positioning and enablement tools. The stated 70% frequency is an unaudited personal estimate. Official audio, Casado at 10:46–11:13
- [retrospective witness | strong] Casado describes his pre-Nicira academic environment as a source of naivety: the founders had reasoned through technical properties but failed to start from the customer's recognized problem. This is explicit learning-from-error evidence and a mechanism for his later buyer-first advice. Official audio, Casado at 21:29–22:30
- [retrospective witness | strong] At Nicira, Casado says the team tested multiple budget owners and ultimately found an emerging person responsible for the virtual-networking layer. The episode does not name the customers, dates, win rate, or whether this discovery preceded the formal category label. Official audio, Casado at 20:00–20:39
- [investor-stated | strong] Casado says his diligence looks for customer-built patches or poor substitute solutions as evidence of an acute problem. This is the clearest episode-level investing heuristic; Feaster's adjacent build-versus-buy analysis remains her operating evidence. Official audio, Casado at 24:39–24:52
- [investor-stated | moderate] Casado cites a portfolio board company that maintained distinct IT and line-of-business pitches. He does not identify the company, investment date, ownership, performance, or whether the dual pitch improved conversion, so the anecdote supports process but not outcome. Official audio, Casado at 28:32–29:12
- [contemporaneous record | strong] Sonal Chokshi hosts; Casado supplies investor and Nicira evidence; Michel Feaster supplies Usermind and Apptio operating evidence. Feaster's 20-customer council, deal-analysis practice, TBM role creation, and category-competition playbook are not reassigned to Casado. Official audio, introductions at 00:18–01:15
- [researcher inference | insufficient public record] The episode discloses no investment check, valuation, ownership, reserve decision, board vote, mark, realized return, loss, or fund-level attribution for Nicira, Usermind, Apptio, or the unnamed board company. Official episode, complete recording
Philosophy signals
- [investor-stated | strong] tags: picking / pricing — underwrite the go-to-market motion and seller throughput before treating ACV as a cosmetic choice; a category whose mature price cannot support direct-sales economics may require a different motion or market. Official audio, Casado at 03:53–05:16
- [investor-stated | strong] tags: boards / portfolio — delay price anchoring until the buyer has recognized the problem and validated technical value; then price against demonstrated risk rather than an inherited list price. Official audio, Casado at 06:42–07:38
- [investor-stated | strong] tags: people / risk — founder charisma is useful for starting early engagements but dangerous as a metric; test whether production use, use-case similarity, and non-founder selling survive removal of the founder. Official audio, Casado at 13:41–17:23
- [investor-stated | strong] tags: picking / market — treat customer-built workarounds as problem evidence, then separate a build-heavy frontier segment from the broader addressable market that may prefer shared R&D and maintenance. Official audio, Casado and Feaster at 24:27–25:41
- [investor-stated | strong] tags: sourcing / buyers — identify the budget, role, procurement path, and existing criteria before attempting to redefine them; category creation begins inside an organization that already has a structure. Official audio, Casado at 19:33–20:39
- [investor-stated | strong] tags: boards / portfolio — product marketing is the mechanism that turns founder insight into a repeatable conditional sales play, especially in multi-actor enterprise accounts. Diagnose weak enablement before assuming seller incompetence. Official audio, Casado at 10:46–13:11
- [investor-stated | moderate] tags: picking / organization — category evidence strengthens when software changes ownership, budgets, roles, or daily work, but Feaster—not Casado—makes the strongest explicit new-role claim in this episode. Official audio, Feaster at 17:49–19:33 and Casado at 19:33–20:39
- [investor-stated | moderate] tags: people / learning — prefer founders with conviction about the problem but adaptability about the buyer's current mental model; Nicira's academic certainty without customer translation is Casado's negative example. Official audio, Casado at 21:29–22:30
- [researcher inference | insufficient public record] tags: exits — the conversation links price to valuation but supplies no exit-timing, acquirer, liquidity, ownership, dilution, or realized-return framework. Official audio, Casado at 03:53–05:16
Contradictions, counterevidence, and access limits
- [contemporaneous record | strong] The canonical page, Simplecast API/player, and RSS enumerate one episode and one 31:50 program version, but none exposes a publisher transcript, captions, or chapter map. A complete local timestamped ASR was used for navigation; speaker assignment was restricted to direct address, self-reference, named handoff, and continuous turns, and no raw media or transcript was added to the repository. Official page · Simplecast player record
- [contemporaneous record | strong] The publisher reports 1,910 seconds; the reviewed MP3 is 1,910.987750 seconds, 22,931,914 bytes, and 96 kbps. Timestamp citations bind to that exact artifact. Current dynamic enclosure routing can change advertising bytes without creating a new editorial interview version. Official Simplecast player record
- [researcher inference | moderate] Casado's advice to defer pricing and Feaster's statement that early ACV starts below its eventual level are compatible, not contradictory: one concerns sequencing within a sale and the other maturity across a customer base. Neither establishes that delayed pricing or 20–50 customers causally raises ACV. Official audio, Feaster at 05:55–06:41 and Casado at 06:42–07:38
- [researcher inference | moderate] Early relationships play two roles that can be confused. Feaster uses the first 20 customers as product and proof inputs, while Casado warns that relationship- or founder-driven deals can mimic fit. The reconciliation is to mine relationships for hypotheses but require production, repeated use cases, and non-founder execution before treating them as market evidence. Official audio, Feaster at 08:09–09:16 and Casado at 13:41–17:23
- [researcher inference | moderate] “Set the rules” overstates category control if read literally. Feaster later describes status-quo ownership, fast followers, incumbent account control, discounting, and copied positioning; category leaders can frame evaluation criteria but cannot unilaterally control adoption or competition. Official audio, Casado at 02:06–02:55 and Feaster at 22:30–27:20
- [researcher inference | moderate] The $200,000–$300,000 ACV hurdle, 20–50-customer inflection, and 70% product-marketing estimate are practitioner heuristics without samples, cohort definitions, time periods, or failure denominators. They should guide questions, not valuation models. Official audio, Casado at 03:53–05:16 and 10:46–11:13; Feaster at 05:55–06:41
- [researcher inference | moderate] Nicira and Apptio are selected successful examples. The episode supplies no comparison set of attempted categories that failed, so its mechanisms are vulnerable to survivorship bias and cannot establish a base rate for category creation. Official episode, complete recording
- [contemporaneous record | strong] a16z is both publisher and financially interested investor; examples and portfolio advice document Casado's stated process but do not independently validate commercial outcomes. a16z disclosure
Open questions
- [researcher inference | insufficient public record] What seller capacity, implementation burden, gross margin, retention, and expansion assumptions justified Casado's $200,000–$300,000 direct-sales hurdle, and when would a lower-price motion be superior? Official audio, Casado at 03:53–05:16
- [researcher inference | insufficient public record] What observable event defines technical close, and how often does delaying price improve realized ACV versus increasing cycle time or disqualifying budget-mismatched buyers late? Official audio, Casado at 06:42–07:38
- [researcher inference | insufficient public record] Across Casado's portfolio, how predictive were production deployment, repeated use case, and non-founder selling for retention, expansion, and eventual returns; what false positives survived all three tests? Official audio, Casado at 16:12–17:23
- [researcher inference | insufficient public record] Which Nicira customer interviews or lost deals revealed the emerging virtual-networking buyer, and how did the team change product, price, or messaging after that discovery? Official audio, Casado at 19:33–22:30
- [researcher inference | insufficient public record] How should diligence distinguish a widespread, budgeted internal workaround from bespoke customer engineering that signals a narrow services market rather than scalable software? Official audio, Casado and Feaster at 24:27–25:41
- [researcher inference | insufficient public record] When does the temporary two-pitch IT/line-of-business structure converge, and which party ultimately controls budget, security approval, deployment, and renewal? Official audio, Casado and Feaster at 28:32–30:25
- [researcher inference | insufficient public record] What investment terms, ownership, reserves, board actions, and realized outcomes would connect these operating heuristics to venture-return evidence rather than founder and investor recollection? Official episode, complete recording
[t] The Economic Case for Generative AI (presentation)
- URL: https://a16z.com/the-economic-case-for-generative-ai/ | Published: 2023-09-25 | Format: solo conference presentation by Martin Casado with full publisher transcript and official a16z YouTube video | Reliability: A for Casado's stated framework; B/C for illustrative cost ratios, biological analogies, and forecasts | Access: full publisher transcript and video page; exact player duration was not exposed to this access path | Accessed: 2026-08-20 | Locator scheme: publisher transcript chapter timestamps spanning 00:00–14:39 and official YouTube elapsed-time links (video 5yC4w4x5DSQ) | Version: September 2023 solo adaptation of the 2023-08-03 coauthored Casado–Sarah Wang essay, not an independent second thesis
Takeaways
- Capability was not the historic bottleneck.
[investor-stated | moderate]Casado argues that AI improved steadily for decades while incumbents captured most monetization because startup economics—tail accuracy, human exception handling, narrow markets, hardware, and competition with cheap human perception—were unattractive. Official video, 00:00–02:30 - The “mediocrity spiral” is organizational.
[investor-stated | moderate]A startup automates common cases, hires people for failures, then gets pushed to grow and adds still more labor. Casado presents this as a recurring pattern, but the talk supplies no cohort, base rate, or named counterexample. Official video, 02:30–06:23 - Generative AI changes the task and the payer.
[investor-stated | provisional]His three categories—creativity, companionship, and copilots—can relax formal correctness or make users perform iterative review, moving some human-in-the-loop cost outside the vendor. Whether that cost disappears or is merely transferred depends on workflow and liability. Official video, 06:23–08:29 - Illustrative unit economics drive the claim.
[investor-stated | provisional]Image and legal-brief examples compare roughly a tenth of a cent and seconds of inference with professional labor, yielding an asserted four-to-five-order cost gap. The examples do not demonstrate equivalent output quality, successful completion, review cost, or willingness to pay. Official video, 09:23–11:13 - The “third epoch” is a cost analogy.
[investor-stated | provisional]Casado links microchips to near-zero marginal compute cost, the internet to near-zero distribution cost, and generative AI to near-zero creation cost. “Zero” is directional rhetoric because training, inference, evaluation, integration, and supervision remain nonzero. Official video, 11:53–13:35 - Elastic demand is the value-creation bridge.
[investor-stated | provisional]Invoking Jevons paradox, he predicts lower creation costs will expand consumption, productivity, jobs, and new products. The talk does not establish where the surplus accrues among users, application vendors, model providers, or distributors. Official video, 13:35–14:39 - Version-aware reading is essential.
[contemporaneous record | strong]The preceding August essay is coauthored by Casado and Sarah Wang and contains the same sequence, examples, and analogies while explicitly calling the cost comparison non-scientific. This solo performance restates that work and must not be counted as independent corroboration. Companion essay and repository note
Quotes
[investor-stated | strong]“The capabilities have all been there, but the economics just haven't for startups.” — Casado, official video, 02:10–02:30 (12 words)[investor-stated | strong]“The human in the loop has moved out.” — Casado, official video, 07:55–08:10 (8 words)[investor-stated | strong]“We could be entering a third epoch of compute.” — Casado, official video, 11:50–12:02 (9 words)
Biography and decision evidence
[documented behavior | strong]Casado converted a coauthored a16z essay into a solo public presentation within two months, showing active category formation and founder-facing thesis distribution. Repetition across those two formats is behavioral evidence of emphasis, not two independent observations. Presentation page and byline and earlier essay byline[investor-stated | moderate]His disclosed decision rule is to distinguish technical capability from scalable economics, then test error tolerance, human review, labor substitution, market breadth, unit cost, and demand elasticity. He does not name a deal selected, rejected, or repriced by this rule. Official video, 00:00–11:50[researcher inference | insufficient public record]No check size, ownership, board role, fund attribution, exit, or realized return is disclosed. The presentation is thesis evidence only; portfolio success cannot be inferred from its examples. Publisher presentation page
Philosophy signals
- Tags: picking / risk.
[investor-stated | strong]A model benchmark is not an investment thesis; the complete workflow must be economically superior after failures and human intervention. Official video, 00:00–06:23 - Tags: picking / portfolio.
[investor-stated | moderate]Casado looks for new task categories where probabilistic output is acceptable and user iteration absorbs review, rather than merely replacing an incumbent's deterministic feature. Official video, 06:23–08:29 - Tags: macro / exits.
[investor-stated | provisional]Falling creation cost can expand markets, but the presentation does not connect that expansion to durable application-level margins, defensibility, or exit outcomes. Official video, 11:53–14:39 - Tags: sourcing / people / self-interest.
[researcher inference | strong]A venture investor publicly argues that generative-AI startups can escape earlier AI economics. The category-building incentive raises the burden for independent retention, margin, and outcome evidence. Publisher presentation page
Contradictions, counterevidence, and access limits
[contemporaneous record | strong]A 2023 field study of 5,179 customer-support agents found AI assistance raised issues resolved per hour by 14% on average and 34% for novice or lower-skilled workers, with minimal impact for experienced workers. It supports real productivity gains but shows heterogeneous, far smaller effects than the talk's illustrative four-to-five orders. NBER Working Paper 31161, Abstract[contemporaneous record | moderate]A later randomized study of 16 experienced open-source developers found early-2025 AI tools made completion 19% slower on its narrow task set. METR cautions against broad generalization, but the result demonstrates that cheaper generation need not lower end-to-end completion cost. METR, July 2025 study and limitations[researcher inference | strong]The silicon-versus-human-brain comparison uses asserted power figures and evolutionary history outside Casado's expertise and without sources. Energy at inference is not equivalent to training cost, cognition, task quality, or labor substitution; it should not anchor valuation. Official video, 08:33–09:20[contemporaneous record | strong]The publisher page exposed the full transcript and chapter markers through 14:39, but not an exact player-duration field; the YouTube endpoint was access-limited. The 13:35 source-map figure is the final chapter start, not verified duration. No raw transcript or video was retained in the repository. Publisher transcript
Open questions
[researcher inference | insufficient public record]For which tasks does user iteration truly remove vendor labor rather than transfer uncompensated review and liability to the customer? Official presentation[researcher inference | insufficient public record]What are successful-outcome costs after training, inference, evaluation, integration, retries, and human review? Official presentation[researcher inference | insufficient public record]Does elastic demand improve application gross profit, or does competition pass savings to users and infrastructure suppliers? Official presentation[researcher inference | insufficient public record]Which named Casado investment used this framework ex ante, and what failed or ordinary case would falsify it? Official presentation[researcher inference | insufficient public record]Which claims belong specifically to Casado rather than coauthor Sarah Wang, given the earlier essay's shared byline? Official presentation
[t] Entering Uncharted AI Territory
- URL: https://colossus.com/episode/casado-entering-uncharted-ai-territory/ | Published: 2024-07-09 | Format: Invest Like the Best podcast interview (Patrick O’Shaughnessy interviewing Martin Casado) | Reliability: A for speaker-attributed statements checked against official audio; B for unofficial ASR wording | Access: full official audio; partial current publisher transcript; full unofficial third-party ASR transcript | Accessed: 2026-08-19 | Locator scheme: elapsed time in the current official audio enclosure; current publisher chapter links are approximately one minute later and are not used as the controlling clock | Version: episode 381; RSS GUID
0c9c4e62-3d41-11ef-ad76-83a4e85f8c9a; current Megaphone enclosureCLS6894817101.mp3?updated=1767957746; RSS duration01:08:03
Takeaways
- Demand can lag supply [investor-stated | moderate]: Casado uses the fiber glut to argue that enormous eventual demand does not prevent near-term infrastructure overbuild; GPU and data-center investment can be directionally right yet badly timed. Official episode, Martin at
00:03:33–00:04:43 - AI expands creation before replacing workflows [investor-stated | provisional]: his bullish case begins with falling marginal costs of content, distribution, and digital creation, while his enterprise skepticism targets attempts to force models into old automation use cases. The proposed creative and companionship explosion is a forecast, not measured demand. Official episode, Martin at
00:01:40–00:03:20,00:04:43–00:09:50, and00:59:27–01:00:50 - Physical AI requires vertical knowledge [investor-stated | strong]: Casado says board service at drone and robotics companies taught him that strong software judgment does not substitute for domain economics, regulation, hardware, and operating expertise; he gives that gap as a reason a16z formed a separate American Dynamism team. Official episode, Martin at
00:23:13–00:25:30 - Moats migrate away from the model [investor-stated | moderate]: early model advantages decay as competitors catch up and distillation lets followers learn from leaders. He expects defensibility to come from integration, community, workflow, brand, and other conventional product advantages rather than model access alone. Official episode, Martin at
00:26:00–00:30:31 - Market annealing [investor-stated | moderate]: in a new category, a technical founder must co-evolve product and buyer understanding, effectively educating the market until the category becomes legible. Casado says this matters less in mature markets with known buyers and budgets. Official episode, Martin at
00:42:28–00:45:45 - Agents are an explicit dissent [investor-stated | strong]: he is personally bearish on autonomous agents because probabilistic correctness, memory outside the reasoning fabric, planning, and internal-state guarantees make long control loops fragile; he notes his own team disagrees and says he may be wrong. Official episode, Martin at
00:56:32–00:58:41 - Modern VC translation (as of 2026-08-19) [researcher inference | moderate]: separate model novelty from durable workflow control; test whether demand survives model substitution, whether a founder can make a new market legible, and whether physical-domain specialists can validate system economics. Underwrite AI infrastructure against both a supercycle and a demand-lag/overbuild case. Official episode, Martin at
00:03:33–00:04:43,00:23:13–00:30:31, and00:42:28–00:45:45
Quotes
- “It will not just be on the model.” — Martin Casado,
00:28:45. [investor-stated | strong] Official episode - “Market annealing is for category creation.” — Martin Casado,
00:44:34. [investor-stated | strong] Official episode - “I'm very open to be totally wrong on this point.” — Martin Casado,
00:57:13. [investor-stated | strong] Official episode
Biography and decision evidence
- Casado describes earlier AI-startup investing as a “bloodbath” because specialized models were expensive to build and difficult to monetize; he says generative foundation models changed those economics. [retrospective witness | moderate] No vintage, portfolio set, loss ratio, or fund attribution is disclosed. Official episode, Martin at
00:21:02–00:23:13 - He says experience on drone and robotics boards exposed his lack of vertical knowledge and affected a16z's organization of expertise. [documented behavior | strong] This is unusually specific evidence of board learning changing division of labor, though the source does not name the companies or exact organizational decision date. Official episode, Martin at
00:23:13–00:25:30 - Casado discloses a technical-founder bias rooted in his own background while acknowledging an active internal debate over technical versus commercial founders. [investor-stated | strong] The admission identifies a possible selection bias, not a measured superiority claim. Official episode, Martin at
00:42:28–00:43:41 - The episode names no fund, check, security, ownership, reserve, board vote, exit, or realized return. [researcher inference | strong] It records mid-2024 category judgments and a board-derived correction, not deal-level performance. Official episode, full recording
Philosophy signals
- Macro / risk [investor-stated | moderate]: secular demand and attractive investment timing are different questions; overbuilding can occur inside a genuine supercycle. Official episode, Martin at
00:03:33–00:04:43and00:50:34–00:52:34 - Picking / people [investor-stated | strong]: technical founders receive a default positive prior in category creation because product and market must co-evolve, but Casado explicitly limits and questions his bias. Official episode, Martin at
00:42:28–00:45:45 - Boards / portfolio [documented behavior | strong]: board exposure is treated as a learning channel that can reveal domain incompetence and justify specialist teams rather than broadening one partner's remit. Official episode, Martin at
00:23:13–00:25:30 - Picking / risk [investor-stated | moderate]: model performance is a transient advantage unless it compounds through a traditional moat; distillation can make leader spending partially subsidize followers. Official episode, Martin at
00:26:00–00:30:31 - Exits [researcher inference | insufficient public record]: neither the supercycle thesis nor the warning about overbuild is connected to holding period, exit window, or return targets. Official episode, Martin at
00:03:33–00:04:43and00:50:34–00:52:34
Contradictions, counterevidence, and access limits
- The current publisher page makes only its introduction and first exchange available as transcript text. [contemporaneous record | strong] A full third-party ASR transcript was used for navigation and speaker reconstruction; selected wording was checked against the official enclosure, and obvious ASR errors were not promoted into quotes. Official episode Unofficial transcript
- The publisher page and official enclosure use clocks offset by roughly one minute. [contemporaneous record | strong] This note uses the enclosure/RSS clock throughout; page chapter labels should not be mixed with these pinpoints. Official episode
- Casado offers a companionship revenue-share estimate while immediately saying he does not know the true numbers. [investor-stated | insufficient public record] It is preserved only as evidence of uncertainty and is not repeated here as market fact. Official episode, Martin at
00:08:37–00:09:50 - The autonomous-vehicle investment, power-use, and video-game production figures are uncited oral estimates. [investor-stated | provisional] Their directional arguments may be useful, but the numbers require independent sources before use. Official episode, Martin at
00:04:43–00:07:32and00:09:50–00:17:13 - Casado's bearish agent view conflicts with his team's view and is framed as falsifiable personal judgment. [contemporaneous record | strong] That disagreement is stronger evidence of epistemic humility than of agents' eventual technical ceiling. Official episode, Martin at
00:56:32–00:58:41 - His “Baptists and bootleggers” account imputes motives to AI-regulation supporters without evidence about individual actors. [investor-stated | provisional] It should not substitute for analysis of a specific rule's text, incidence, and beneficiaries. Official episode, Martin at
01:01:26–01:05:04
Open questions
- Which prior AI investments constitute the stated “bloodbath,” and what loss, follow-on, or shutdown evidence supports that characterization?
- Which board experiences changed Casado's view of physical AI, and what decisions were reassigned to the American Dynamism team?
- What quantitative test distinguishes temporary model leadership from a durable workflow, community, distribution, data, or brand moat?
- What observable milestones would falsify his agent skepticism—task horizon, intervention rate, state consistency, or economic reliability?
- How does a16z price demand-lag and overbuild risk across model, application, chip, and data-center investments?
- When has a technical-founder prior caused a missed commercial founder or a false positive, and how is that bias corrected in an investment committee?
[t] The Future of Software Development: Vibe Coding, Prompt Engineering & AI Assistants
- URL: https://a16z.com/podcast/the-future-of-software-development-vibe-coding-prompt-engineering-ai-assistants/ | Published: 2025-07-21 | Format: multi-speaker a16z podcast/video; Erik Torenberg interviews Martin Casado, Jennifer Li, and Matt Bornstein | Reliability: A for official media, date, speakers, and publisher timecodes; B for unlabeled third-party ASR used only to navigate speaker turns | Access: full official audio and video; publisher show notes and timecodes; no publisher transcript located | Accessed: 2026-08-20 | Locator scheme: elapsed time in official a16z audio/video; Casado-only claims are restricted to turns whose speaker is identifiable from direct address, named handoff, or surrounding dialogue | Version: Simplecast episode
16504cbc-f140-4caf-9ff4-3a58bf304166, episode 890, duration00:44:23; official a16z YouTubeEIPxf7rgIPI; current enclosure and video carry the same title
Takeaways
- [investor-stated | strong] Casado calls models a new infrastructure layer because they change both how computers are programmed and the surrounding requirements for compute, data, networking, latency, and system guarantees. The deeper discontinuity is that programmers now delegate some application logic—not merely resources—to a probabilistic component. Official video, Casado at 04:01–05:29
- [investor-stated | moderate] He treats AI as software disrupting software: the old compute, networking, storage, database, and distributed-systems layers persist, but a new layer changes the programming model above them. This is an architectural analogy, not evidence that every model provider is an investable infrastructure company. Official video, Casado and panel at 05:29–06:57
- [investor-stated | moderate] Casado's supercycle model is marginal-cost reduction → market expansion → new users and behaviors → whitespace incumbents are not organized to serve. He compares the pattern with the internet and microprocessor, while acknowledging that analogy cannot identify the winners. Official video, Casado at 07:16–08:20
- [investor-stated | strong] He says natural-language coding finally realizes the low-code promise: it lowers the burden of syntax and frameworks without eliminating the need to specify what should be built. The later professional-formalism caveat is essential to the claim. Official video, Casado at 09:06–09:48 and 32:41–34:15
- [retrospective witness | moderate] Casado describes a16z's organizational shift from treating infrastructure as “enterprise” to a separate infrastructure practice. His rationale is that technical buyers, developer-led adoption, horizontal markets, and technical diligence require a different team and analytical process from vertical SaaS. Official video, Casado at 10:19–13:10
- [investor-stated | moderate] The panel rejects “small TAM” as a sufficient objection to developer tools: infrastructure can create its own market as new technical work and users appear. This is a directional selection heuristic; no denominator of small-TAM failures is supplied. Official video, panel at 17:17–18:08
- [investor-stated | strong] Casado's defensibility model separates expansion from contraction. During expansion, zero-sum reasoning can miss multiple growing layers; when growth slows, consolidation tends toward oligopoly or monopoly, with value persisting unless an adjacent layer successfully verticalizes into it. Official video, Casado at 23:43–26:07
- [investor-stated | provisional] He expects reinforcement-learning specialization to create tradeoffs: a model optimized for code may not dominate every other task, leaving room for specialist models and multi-model systems. He explicitly calls this an observation that may be wrong. Official video, Casado at 27:27–28:39
- [investor-stated | strong] Casado reframes prompt engineering as context engineering: performance depends on selecting, prioritizing, and supplying the right context, which reintroduces indexing, data pipelines, observability, tools, and other conventional computer-science components. Official video, Casado at 29:44–31:07
- [investor-stated | strong] His medium-term software thesis is neither “AI does not work” nor “the model does everything.” Professionals remain necessary where specifications, guarantees, and operational judgment matter because formal systems emerged to remove ambiguity from natural-language requirements. Official video, Casado at 32:41–34:15
- [investor-stated | strong] Lower code-generation cost does not eliminate software products: customers buy encoded workflow, domain decisions, data choices, and operating logic. Casado argues that requirement discovery and deciding what to build remain harder than mechanically producing code. Official video, Casado at 36:05–37:36
- [investor-stated | moderate] Casado's agent rule is error correction: loops compound small mistakes unless the environment supplies executable feedback. Code is unusually tractable because tests, linters, interpreters, and compilers can check work; he says bounded coding tasks are already useful but does not generalize that result to open-ended agents. Official video, Casado at 40:33–41:51
- [researcher inference | moderate] The integrated decision rule is to invest around new programming primitives and behavior, but diligence the actual buyer, context/data path, verification loop, and durable workflow—not the mere availability of code generation or a foundation-model API. Official video, 04:01–05:29, 23:43–31:07, and 32:41–41:51
Quotes
- [researcher inference | insufficient public record] No verbatim quote is retained. The publisher supplies full audio/video but no transcript, while the accessible full transcript route is unlabeled third-party ASR; that is adequate for navigation and paraphrase, not the repository's quote-verification gate. Official episode and media · Unofficial navigation transcript
Biography and decision evidence
- [retrospective witness | moderate] Casado says Nicira was either a16z's first infrastructure investment or one of the first two alongside Okta, and recalls that the two founders were used in early first-fund LP presentations. This is firsthand recollection, not a dated fund ledger. Official video, Casado at 10:19–10:46
- [retrospective witness | strong] He says that when he joined a16z, the firm classified the work as enterprise; over time, different go-to-market motions and the need for technical market diligence led to separate applications and infrastructure funds. This is direct organizational-history evidence, not proof that Casado alone made the decision. Official video, Casado at 10:46–11:58
- [investor-stated | moderate] The panel identifies technical users—developers, data scientists, analysts, security and operations professionals—as the infrastructure constituency, and Casado describes technical buyers as more centralized and educated than the many distinct buyers in vertical SaaS. Official video, panel at 01:49–03:15 and Casado at 12:46–13:45
- [investor-stated | moderate] Casado describes the AI transformation as the most dramatic change in roughly 30 years in the industry and contrasts it with cloud's business-model transition and COVID's forced remote-sales shift. These are personal comparisons, not measured cycle magnitudes. Official video, Casado at 14:34–16:07
- [contemporaneous record | strong] The publisher names Torenberg as interviewer and Li, Casado, and Bornstein as guests; the RSS author field names the three guests. Co-speaker claims remain individually attributed and are not converted into a unified Casado or firm view. Publisher page, contributors and description
- [researcher inference | insufficient public record] No check, valuation, ownership, reserves, board vote, exit, loss ratio, or realized return is disclosed for Cursor, GitHub, Databricks, Fivetran, dbt, Hex, or other examples. Official episode, full recording
Philosophy signals
- [investor-stated | strong] tags: picking / macro — distinguish a new programming primitive from an application wrapper; ask whether it changes system architecture, developer behavior, or the market boundary. Official video, Casado at 04:01–08:20
- [investor-stated | strong] tags: picking / risk — in expansion, avoid treating layers as zero-sum; in contraction, underwrite consolidation, switching cost, and the possibility of verticalization by an adjacent layer. Official video, Casado at 23:43–26:48
- [investor-stated | strong] tags: sourcing / picking — context engineering implies opportunities in data movement, retrieval, prioritization, tool discovery, guarantees, and observability around models. Official video, Casado and panel at 29:44–31:32
- [investor-stated | strong] tags: people / risk — favor builders who retain specification and system judgment while using AI for implementation leverage; natural language does not remove professional responsibility for guarantees. Official video, Casado at 32:41–34:15
- [investor-stated | moderate] tags: boards / portfolio — the agent test should be task-boundedness and error-correction evidence, not the “agent” label. A board can ask which feedback loop detects and reverses compounding failure. Official video, Casado at 40:33–41:51
- [researcher inference | insufficient public record] tags: exits — the episode provides no exit-timing framework or evidence about how software-generation cost changes terminal ownership, multiple, or liquidity. Official episode, full recording
Contradictions, counterevidence, and access limits
- [contemporaneous record | strong] The official page and Simplecast feed provide full media and detailed chapters but no transcript resource; direct YouTube caption enumeration was blocked by an anti-bot gate on the access date. A third-party ASR page is complete but has merged, unlabeled turns, so it was used for navigation only and no raw transcript or media was stored. Official episode · Simplecast player record
- [contemporaneous record | strong] A randomized study published eleven days before this episode found early-2025 tools made 16 experienced open-source developers 19% slower across 246 tasks in mature repositories. The authors limit the result to that setting and model vintage; it directly cautions against treating enthusiasm or self-estimated speed as universal productivity evidence. METR study, summary and methodology
- [researcher inference | moderate] Casado's expansion/contraction model explains why several layers can grow simultaneously, but it does not measure total profit pools, transfer pricing, subsidy, or survival. Growing revenue at each layer can coexist with poor venture returns after entry price and dilution. Official video, Casado at 23:43–26:07
- [researcher inference | moderate] The claim that infrastructure “creates TAM” is vulnerable to survivorship bias: GitHub and Cursor are visible winners, while the episode supplies no denominator of developer-tool companies whose markets remained small or were absorbed by platforms. Official video, panel at 17:17–18:08
- [investor-stated | provisional] Casado expressly qualifies the RL-specialization claim as an observation that may be wrong. Future generalization or routing improvements could reduce the specialist-model whitespace he identifies. Official video, Casado at 27:27–28:39
- [contemporaneous record | strong] a16z is a financially interested publisher and states that it or affiliates may hold investments in discussed companies. Portfolio examples are therefore evidence of Casado's stated thesis, not independent validation of company quality or returns. Publisher disclosure
Open questions
- [researcher inference | insufficient public record] Which observable changes in programming behavior, buyer budgets, or system architecture qualify a model/tool as infrastructure rather than an application feature? Official video, 01:49–05:29
- [researcher inference | insufficient public record] What revenue-pool, market-share, and gross-profit data would falsify the expansion/contraction and persistent-layer-value model? Official video, 23:43–26:07
- [researcher inference | insufficient public record] Which context-engineering components are independent businesses versus features that model, cloud, or data incumbents can bundle? Official video, 29:44–31:32
- [researcher inference | insufficient public record] What evaluation suite separates bounded coding-agent tasks with reliable error correction from open-ended loops whose errors compound? Official video, 40:33–41:51
- [researcher inference | insufficient public record] What were the ex-ante decision memo, sponsor, valuation, ownership, and falsification milestones for the portfolio examples invoked in the discussion? Official episode, full recording
[t] “This Feels Like 1996”: Why a16z's Martin Casado Believes the AI Boom Still Has Years to Run
- URL: https://www.generalist.com/p/this-feels-like-1996-martin-casado | Published: 2025-10-07 (original); a16z replay 2025-12-30 | Format: long-form interview (Mario Gabriele and Martin Casado) | Reliability: A for official audio, B for publisher chapter map and third-party transcript | Access: full original audio, complete chapter map, and full third-party replay transcript | Accessed: 2026-08-20 | Locator scheme: Generalist original chapter times | Version: Generalist original 1:24:44; a16z replay Simplecast
84b68524-3d31-4fc0-b584-87e0cbae7d2b, 1:22:20
Takeaways
[investor-stated | strong]Casado's “1996” comparison means early commercialization rather than absence of exuberance: capital can already produce new capability and revenue, but he does not see the utilization overhang that characterized the late dot-com bubble. It is a forecast, not a dated market-cycle fact. 38:42–47:10[investor-stated | strong]His current investment sequence is “markets in”: first identify the market and structural demand, then ask whether the founder is the right person for it. He says the framework is fallible but believes it can beat the market norm; no supporting cohort is supplied. 26:26–33:14[investor-stated | strong]Casado separates adoption from capability. Individual coding use can move rapidly while enterprise deployment remains constrained by organizational workflow, data, permissions, and change management. That lag supports a longer cycle but also delays proof of broad economic value. 47:10–50:29[investor-stated | strong]AI solves a startup's bootstrap or customer-acquisition problem by making a new product initially magical, but it supplies no inherent long-run moat. Once attention normalizes, a company still needs workflow, integration, marketplace, distribution, brand, or another traditional defense. 01:01:14–01:03:30[investor-stated | moderate]Casado is skeptical of AGI as an investment category because it collapses heterogeneous capabilities and markets into one endpoint. He prefers a continuum of products and tasks, preserving space for application and infrastructure investment. 01:11:50–01:16:28[researcher inference | moderate]Decision rule: start with a market map, identify the adoption bottleneck and current revenue-bearing use, then test whether the chosen team can build a conventional moat before the novelty advantage decays. 26:26–33:14 and 47:10–01:03:30[researcher inference | moderate]Modern VC translation (as of 2026-08-20): market-first search, adoption-lag analysis, and post-bootstrap moat requirements transfer. Calendar analogies and trillion-dollar forecasts do not. Changed assumptions include model commoditization, Chinese open-source capability, and enterprise agent deployment. Signals are paid expansion, workflow penetration, retention after model parity, and organizational rollout; misuse is calling every boom “1996.” Current examples Cursor and World Labs are interested portfolio illustrations, not realized-return proof. 38:42–01:16:28
Quotes
[researcher inference | insufficient public record]No verbatim quotation is promoted: the public wording route is a third-party replay transcript, and this review did not establish a direct official-audio wording check. The note retains timestamped paraphrases only. Generalist original chapter map
Biography and decision evidence
[retrospective witness | moderate]Casado recounts moving from games and national-lab simulation to Stanford networking research, founding Nicira during an economic downturn, VMware, and a16z. The episode is direct memory but does not resolve every date or team-credit boundary. 04:50–19:49[retrospective witness | moderate]He describes a16z's change from a small generalist partnership to a roughly 600-person specialist organization and credits Ben Horowitz's advice in his transition. This is organization history from an interested current partner. 17:55–26:26[investor-stated | moderate]Cursor and World Labs are used as examples tied to Casado's current portfolio and technical interests. The interview shows thesis articulation and access, not check mechanics, ownership, attribution among the team, or return. 58:33–01:11:50
Philosophy signals
- sourcing:
[investor-stated | strong]map structurally expanding markets before evaluating individual companies, using strong founder formation as one signal rather than the whole thesis. 26:26–33:14 - picking:
[investor-stated | strong]prefer teams with product experience and the ability to exploit a new behavior, not technical prestige alone. 22:20–33:14 - risk / moat:
[investor-stated | strong]treat AI novelty as acquisition fuel, then require ordinary defensibility and enterprise adoption evidence. 47:10–01:03:30 - macro:
[investor-stated | provisional]underwrite an extended AI supercycle rather than a near-term late-1990s-style bubble; define observable cycle-breakers before using the analogy. 38:42–47:10
Contradictions, counterevidence, and access limits
[researcher inference | strong]A calendar analogy cannot distinguish a durable cycle from a bubble. Required counterevidence includes capacity utilization, financing dependence, customer ROI, retention, and whether revenue is circular or subsidized. 38:42–47:10[researcher inference | moderate]“Markets in” can become narrative-first hindsight if the market definition shifts after the winner appears. The interview provides neither failed maps nor an ex-ante scored company cohort. 26:26–33:14[researcher inference | moderate]Market-supercycle confidence and the admission of no inherent AI moat create a real tension: rapid category growth can support many companies while fast model diffusion erodes individual-company advantage. 38:42–01:03:30[researcher inference | moderate]a16z and Casado invest in the examples and benefit from continued capital formation. Current private revenue and valuation narratives are not realized cash returns or independent adoption studies. episode contributor and portfolio framing[contemporaneous record | moderate]The Generalist page labels itself “Transcript” but its accessible body provides a full chapter map rather than verbatim text. Full wording was checked against StationLM's public replay transcript; the original and replay clocks differ, so citations use original chapter times and disclose the route. Generalist chapter map
Open questions
[researcher inference | insufficient public record]What utilization, revenue-quality, and financing thresholds would falsify the 1996 analogy? Generalist original[researcher inference | insufficient public record]Which market-first selections and passes form the matched cohort behind Casado's claimed edge? Generalist original[researcher inference | insufficient public record]How do Cursor and World Labs retain advantage after model and product behavior diffuse? Generalist original[researcher inference | insufficient public record]Which enterprise adoption barriers persisted, and which were solved, by cohort after the interview? Generalist original
[t] Going to Market When No Market Exists
- URL: https://a16z.com/going-to-market-when-no-market-exists/ | Published: 2017-06-09 | Format: single-speaker talk/video with slides | Reliability: A for Casado's direct voice; commercial heuristics and operating figures are self-reported | Access: full video with English auto-captions | Accessed: 2026-08-20 | Locator scheme: YouTube timestamps | Version: official a16z page (modified 2023-04-28) embedding a16z YouTube
21-q1JILYK0, uploaded 2018-10-26, runtime 28:35; the page publication predates the embedded upload
Takeaways
- [investor-stated | strong] Casado defines market-category creation operationally: the customer lacks a concept, budget, buying process, and sometimes awareness of the problem, so conventional comparison, research, and pricing techniques have no stable reference point. Talk, 00:52–02:13 · Talk, 03:11–04:21
- [investor-stated | moderate] His core economic claim is that enterprise go-to-market is at least as important as technology because R&D becomes relatively fixed or sublinear while direct sales scales with customers; pricing therefore determines ACV, contribution margin, and ultimately valuation. The logic is useful, but the talk does not test alternative distribution models or margin definitions. Talk, 02:15–03:10
- [investor-stated | strong] He tells founders to design price backward from the sales motion required to create the market. His 2017 example uses a $300,000 on-target salesperson, roughly six deals, and a need for approximately $150,000-plus ACV to sustain direct evangelical selling; those figures are dated heuristics, not natural laws. Talk, 06:47–08:18
- [investor-stated | moderate] Casado argues that low pricing rarely fixes an early sales problem: it may confuse lack of readiness or fit with price resistance, train the market to a low reference value, and make the later direct-sales model uneconomic. Talk, 05:34–06:36 · Talk, 08:20–09:58
- [investor-stated | strong] His early pricing rules are deliberately simple: protect the ACV needed for the motion, anchor high, avoid premature SKU proliferation, separate the product from a mature bundle, discount only against explicit customer value, and delay public pricing until repeated sales reveal willingness to pay. Talk, 10:01–13:41
- [investor-stated | strong] Marketing has three functions in his model—product story/sales enablement, demand generation, and brand—and the founder's initial story is scarce currency. He says Nicira spent about six months simplifying the value narrative and warns that positioning requires sacrificing technically true but nonessential detail. Talk, 13:42–15:47
- [investor-stated | moderate] For category creation, he ranks direct customer contact above articles or press, treats analysts as increasingly important after early adopters, and identifies developer influence as a route around incumbent account control. He explicitly says open source, freemium, and hackathons are not proven causal recipes. Talk, 15:48–18:58
- [investor-stated | strong] Developer adoption is top-of-funnel rather than a complete business model: budgets may be fragmented, and Casado says the successful pattern he observed often added direct sales into central IT to reach larger ACV. Talk, 18:59–20:05
- [investor-stated | strong] He separates early from mature sales. Early sellers and sales engineers must educate, qualify, coordinate a technical close, and behave like “mini CTOs”; scaling quota capacity before repeatability can distort product feedback and consume engineering on unqualified deals. Talk, 20:05–24:20
- [investor-stated | moderate] Professional services and channels have stage-specific roles: services may be required to implement a pre-chasm product and create a later partner market, while resellers generally cannot create demand before a pull-based market exists. Talk, 25:22–27:38
- [researcher inference | moderate] The decision rule is to preserve option value without mistaking experiments for scale: set a viable economic envelope, run founder-led discovery, qualify for repeatability, and add sales/channel leverage only when customer behavior—not attention—supports it. Talk, 22:20–25:19
Quotes
- [investor-stated | strong] “Things in people’s brains don’t have intrinsic value.” — Casado, 09:41–09:47. (Official auto-caption wording; punctuation normalized.)
- [investor-stated | strong] “Positioning and story is sacrifice.” — Casado, 15:19–15:27. (Official auto-caption wording; punctuation normalized.)
- [investor-stated | strong] “Your limited resource is often your startup capacity.” — Casado, 24:20–24:39. (Official auto-caption wording; punctuation normalized.)
Biography and decision evidence
- [investor-stated | provisional] Casado describes Nicira as an a16z first-fund portfolio company founded when he left his PhD path, operated for five years, and then acquired by VMware. The sequence is direct recollection; precise fund, incorporation, and acquisition dates require contemporaneous records. Talk, 00:02–00:24
- [investor-stated | strong] He frames the talk as a technical founder's failure record: business, marketing, and pricing were non-intuitive, and the lessons are what he would change in another category-creation company. Talk, 00:24–00:52
- [investor-stated | moderate] Casado identifies Ben Horowitz as a Nicira board member and attributes to that board context the lesson that enterprise pricing is the single most important valuation decision. This records advice and governance access, not who approved individual pricing decisions. Talk, 04:24–05:13
- [investor-stated | moderate] His advice combines experience across three product launches, extended field selling, and observation of roughly ten portfolio companies. The samples are small, selected, and unnamed; they cannot establish a category-wide base rate. Talk, 05:34–05:42 · Talk, 12:14–13:41
Philosophy signals
- [investor-stated | strong] tags: picking / risk / people — distinguish discovery-stage evidence from scale-stage economics; price to the required motion; and protect scarce founder, engineer, and sales-engineer attention through aggressive qualification. Talk, 06:47–09:58 · Talk, 24:20–25:19
- [investor-stated | strong] tags: sourcing / picking — developer adoption can reveal demand and bypass incumbent distribution, but only conversion into an organizational budget tests whether it is a venture-scale business. Talk, 16:41–20:05
- [researcher inference | moderate] tags: boards / portfolio / risk — a board should stage hiring and compensation against repeatability signals, audit whether custom work compounds into product, and keep low-price or channel experiments from silently resetting the company's economic ceiling. Talk, 22:20–27:38
Contradictions, counterevidence, and access limits
- [investor-stated | provisional] Casado calls the VMware business “about a billion-dollar run-rate” here, while the earlier-published security talk reports about $600 million at departure. Neither talk defines the measure; the conflict must not be averaged or resolved from recollection alone. Go-to-market talk, 00:15–00:24 · Security talk, 00:24–00:38
- [researcher inference | moderate] “Anchor high” can protect unit economics but can also reduce adoption, learning, or customer surplus. The talk supplies no failed high-price case, willingness-to-pay distribution, or randomized comparison, so the rule is a boundary-conditioned heuristic rather than a universal prescription. Talk, 10:38–11:55
- [researcher inference | moderate] The direct-sales prescription reflects 2017 enterprise infrastructure. Product-led adoption, cloud marketplaces, usage-based pricing, and remote procurement can change the feasible motion; applying the dollar thresholds today without current CAC, payback, gross-margin, and sales-cycle evidence would be misuse. Talk, 06:47–08:18
- [contemporaneous record | strong] The page was published 2017-06-09, while its currently embedded YouTube copy was uploaded 2018-10-26. Claims are bound to the 28:35 video ID and not assumed to represent later revisions. Official page, video and metadata
- [contemporaneous record | moderate] The only text route located was YouTube's English auto-caption track, which misrenders Nicira and other proper nouns. Summaries use surrounding context, and quotes are restricted to short unambiguous phrases. No raw transcript or media is stored in the repository. Official embedded video
Open questions
- [researcher inference | insufficient public record] What were Nicira's initial list prices, realized ACV, discount distribution, quota attainment, CAC payback, and pricing changes—and which decisions were attributable to Casado, Horowitz, or the sales team? Talk, 04:24–13:41
- [researcher inference | insufficient public record] Which approximately ten portfolio companies informed the low-price conclusion, and what happened to companies that anchored high but failed to create demand? Talk, 05:34–06:36
- [researcher inference | insufficient public record] What observable conversion threshold should trigger the shift from developer adoption to direct enterprise sales, and how does that threshold vary by gross margin and product criticality? Talk, 18:59–20:05
[t] Gross Margins, Early to Late: What They Do (and Don’t) Tell You
- URL: https://a16z.com/podcast/a16z-podcast-gross-margins-early-to-late-what-they-do-and-dont-tell-you/ | Published: 2020-06-26 | Format: firm podcast (Martin Casado, David George, and Sarah Wang; Amelia Salyers introduction/moderation) | Reliability: A for each speaker's direct voice; company examples, board observations, and margin figures are not independently verified | Access: full official audio plus complete third-party ASR locator aid; no official transcript | Accessed: 2026-08-20 | Locator scheme: official-audio timestamps with speaker turns reconstructed from explicit introductions and handoffs; ASR wording used only to locate/paraphrase passages | Version: Simplecast episode f9ee0f02-9d52-4d69-b7de-bca69e09c8e1, audio file 2020-06-26-grossmargins-v1-sm.mp3, 128 kbps, runtime 36:01
Takeaways
[investor-stated | strong]Speaker separation: Salyers frames and asks questions; George supplies the late-stage benchmarking and return-on-capital lens; Wang supplies growth-stage modeling and marketplace examples; Casado supplies most early-stage, technical-cost, implementation, AI/ML, and company-phase arguments. Explicit handoffs and name references anchor attribution; ambiguous transitions remain joint rather than assigned solely to Casado. Introduction, 00:00–01:35[investor-stated | strong]Casado says early gross margin is often unknowable because founders cannot yet separate fixed product work from customer-variable engineering, infrastructure, licenses, integration, and support. The mature accounting category can conceal an unresolved product architecture rather than merely imprecise bookkeeping. Casado and handoff, 04:22–07:21[retrospective witness | provisional]He recalls that roughly 40% of costs in a business he ran were maintenance and that R&D continued growing sublinearly with sales. This challenges the simplification that R&D becomes fully fixed, but the episode supplies no ledger, period, allocation method, or comparison company. Casado, 07:21–08:24[investor-stated | strong]Cloud converts infrastructure into a usage-linked variable cost. Casado says growth-first boards and engineers rationally optimize feature velocity rather than efficiency, accumulating architectural debt whose reducible and irreducible portions may be unknown when later investors evaluate margins. Casado, 08:24–10:05[investor-stated | moderate]His proposed early-board control is not premature optimization: track material cloud cost, distinguish a “law of margin physics” from a reversible shortcut, document both, and avoid architectural decisions that cannot later be unwound. He reports this discussion occurring on his Series A and B boards but gives no company names or outcome data. Casado, 10:31–11:11[investor-stated | strong]Casado describes an implementation-cost continuum: bespoke core engineering, connector scripting, configuration, and self-service have different variable-cost profiles. Founders cannot assume early customer work becomes repeatable; the long tail of enterprise systems can remain an intrinsic cost of goods sold. Casado, 12:35–14:08[investor-stated | strong]SaaS changes the margin structure from shipped software: the vendor now bears operations, infrastructure consumption, and continuous feature delivery, while subscription revenue improves predictability. Casado's point is not that SaaS is worse, but that the old compact-disc intuition cannot set its steady-state margin automatically. Casado and joint discussion, 14:42–18:41[investor-stated | strong]Casado resists treating implementation as a temporary product defect. Where the customer interface is eclectic—legacy systems, data cleaning, or ETL—the complexity may be inherent; the company should acknowledge it and price the work rather than forecast a speculative software fix. George adds that hard implementation can also increase stickiness. Casado and George, 21:27–24:18[investor-stated | moderate]He argues AI/ML may not converge to traditional SaaS margins: incremental accuracy can require disproportionately more data and compute, while automation vendors can internalize customers' formerly variable labor. He reports roughly 50% margins as common on relevant boards, but supplies neither a denominator nor accounting definitions. Casado, 24:18–27:45[investor-stated | strong]Casado divides company development into product, sales, and operations. Product-market fit and repeatable selling dominate the first two phases; margin optimization becomes a first-order operational concern later. His boundary condition is to remain conscious of irreversible cost architecture without over-optimizing a business that does not yet work. Casado, 34:21–35:40[researcher inference | moderate]Decision rule: model both reported and economic gross margin, classify each major cost as structurally variable or plausibly optimizable, test whether integration is intrinsic to product-market fit, and demand evidence that the margin path improves without stopping product discovery. The checklist synthesizes Casado with George and Wang rather than attributing their later-stage framework solely to him. Full conversation
Quotes
[researcher inference | insufficient public record]No verbatim quote is retained: the official version is audio-only, while the complete public text route located was third-party ASR without creator verification. Official audio, version f9ee0f02-9d52-4d69-b7de-bca69e09c8e1
Biography and decision evidence
[retrospective witness | provisional]Casado's claimed $600 million operating-business experience and maintenance-cost recollection show him importing a mature infrastructure P&L into early-stage board discussions. The source does not identify the exact reporting period or provide audited cost allocation. Casado, 07:21–08:24[investor-stated | moderate]He says cloud-cost review had begun appearing on all his Series A and B boards by 2020, with architectural reversibility documented before margin optimization became urgent. This is direct board-practice testimony, but there are no minutes, portfolio names, comparison cases, or later outcomes. Casado, 10:31–11:11[investor-stated | provisional]The exchange stages a deliberate a16z handoff: Casado jokes that his growth-first Series A advice can create the cost structure George and Wang later scrutinize. It is useful evidence of a claimed multistage firm process, not proof that partner incentives or follow-on decisions were aligned in practice. Casado, George, and Wang, 09:04–11:53
Philosophy signals
- Tags: picking / risk.
[investor-stated | strong]Low early margins are not automatically disqualifying; the investable question is whether their causes are known, structurally necessary, or reversible without impairing the product. Casado, 04:22–14:08 - Tags: boards / portfolio.
[investor-stated | moderate]An early board should preserve feature velocity while documenting cloud-cost and architecture decisions that can become later-stage margin constraints. Casado, 08:24–11:11 - Tags: macro / pricing.
[investor-stated | strong]New delivery models change the economic baseline: SaaS bears operations and compute; AI/ML can require rising data work; integration-heavy products may need explicit services pricing rather than fictional software margins. Casado, 14:42–27:45 - Tags: self-interest / people.
[researcher inference | moderate]The episode markets a16z's early-to-growth partner continuum while Casado's framework also excuses early inefficiency. That makes the insistence on documentation and later show-versus-tell evidence important safeguards, not proof of the firm's efficacy. George, Wang, and Casado, 00:48–11:53
Contradictions, counterevidence, and access limits
[investor-stated | strong]Casado says early gross margin is difficult to know and not worth optimizing heavily, yet also says early boards should track cloud cost and irreversible architecture. The consistent boundary is awareness without optimization; the episode provides no threshold for when observation should become intervention. Casado, 08:24–11:11 and 34:21–35:40[researcher inference | moderate]Margin can improve through pricing or customer stickiness even when implementation remains costly, but concentrated services work can also constrain scale. Selected Workday, ETL, SaaS, AI/ML, Google, and marketplace examples do not establish category base rates. Joint discussion, 06:10–33:56[researcher inference | strong]George and Wang own the late-stage benchmarking, return-on-invested-capital, freemium accounting, marketplace, and much of the valuation framework. Those claims contextualize Casado's views but cannot be converted into his sole-authored philosophy. Explicit speaker handoffs throughout official audio[contemporaneous record | strong]The official a16z page and 36:01 Simplecast audio were accessible in full, but no official transcript or creator captions were exposed. A complete PodScripts ASR rendering was used only for passage and speaker-turn alignment; wording and punctuation were not treated as quote-grade evidence. Official episode page
Open questions
[researcher inference | insufficient public record]Which Series A and B boards tracked cloud cost, what “margin physics” did each identify, and which documented shortcuts were successfully reversed? Official episode[researcher inference | insufficient public record]What portfolio denominator, accounting policy, and period support the reported roughly 50% AI/ML margin observation? Official episode[researcher inference | insufficient public record]Which implementation-heavy companies improved price, retention, and cash generation without converting into non-scalable services businesses? Official episode[researcher inference | insufficient public record]How did a16z reconcile early growth-first advice with later margin underwriting when follow-on ownership, reserves, and partner incentives differed? Official episode
[t] a16z Podcast: Infrastructure… Is Everything
- URL: https://a16z.com/podcast/a16z-podcast-infrastructure-is-everything/ | Published: 2016-02-25 | Format: firm podcast (Martin Casado interviewed by Sonal Chokshi and Michael Copeland) | Reliability: A for Casado's direct voice; self-reported company figures and recollections are not independently verified | Access: full official audio plus complete third-party ASR locator aid; no official transcript | Accessed: 2026-08-19 | Locator scheme: official-audio timestamps; ASR wording used only to locate passages | Version: Simplecast episode 3c51f0fa-1cf6-4341-8754-33133c4bd56e, 128 kbps asset, runtime 37:06; official a16z YouTube mirror hiwGlzUof-4 also identified
Takeaways
[investor-stated | strong]Speaker separation and central frame: Chokshi and Copeland ask the questions; Casado supplies the substantive first-person account. He treats infrastructure as the hidden site of major engineering work, not a residual category made irrelevant by consumer software. Casado, 01:19–02:23[investor-stated | strong]Casado traces a crooked technical path: astronomy and microbiology research led him toward computational work; Lawrence Livermore put him in large physics simulations; after 9/11 he moved toward intelligence problems and took Stanford networking courses because remote systems work required understanding networks. The sequence is direct testimony, while the interview does not independently document dates, roles, or clearances. Casado, 02:42–06:38[investor-stated | strong]His intellectual rule is applied rather than disciplinary: he describes computer science as an engineering means for solving real-world problems, then says the intelligence setting exposed a practical asymmetry—servers were programmable, but network hardware arrived with vendor software and no comparable programming model. Casado, 04:53–08:02[investor-stated | strong]Casado defines the original SDN problem as two linked design tasks: make an individual switch sufficiently general-purpose to program, then create a discipline for programming a network of switches so security, mobility, and operations can be reasoned about across the collection. He explicitly distinguishes that architecture from the later marketing label. Casado, 08:02–10:07[investor-stated | moderate]He says Nicira joined two observed vectors: hyperscalers were moving load balancing, security, and management from simple physical networks to software at the edge, while compute virtualization was creating software network ports at scale. Nicira's product sought to let enterprises with legacy applications use that architecture without rewriting their applications. Casado, 12:50–15:48[investor-stated | provisional]Casado retrospectively names AT&T, NTT, eBay, Rackspace, and Fidelity as launch customers and says their technical leaders understood an unfamiliar architecture before the market did. This supports a thesis about visionary early adopters, but the episode supplies no contracts, decision dates, customer testimony, or failed-customer denominator. Casado, 16:03–17:07[investor-stated | strong]His security rule is defense in depth plus least privilege: retain the perimeter, add enforcement within the data center, and give each workload only the communications access needed for its job. Because a modern application is a network of services rather than one host, infrastructure enforcement must wrap the distributed application rather than rely on one firewall. Casado, 20:25–24:48[investor-stated | strong]Casado identifies three nonexclusive industry shifts: developers increasingly consume infrastructure as software objects; infrastructure is delivered as a service to avoid version and field-support burdens; and developers' open-source, low-friction buying aesthetic changes how vendors reach an account. Casado, 25:44–29:45[investor-stated | moderate]He calls open source a marketing and insertion mechanism that creates familiarity and credibility before purchase, but warns that free software plus professional services can yield lower-margin, harder-to-scale economics. A hosted service may preserve software-like economics, though the episode provides no cohort evidence that this path succeeds. Casado, 29:02–31:56[researcher inference | moderate]Decision rule: favor infrastructure founders who can connect a technical abstraction to a concrete adoption discontinuity, demonstrate why an incumbent appliance or installed-software model cannot match it, and pair developer insertion with a scalable monetization path. The episode supports the ingredients, not evidence that Casado used this exact checklist in an investment committee. Casado, 08:02–10:31 and 25:44–31:56
Quotes
[researcher inference | insufficient public record]No verbatim quote is retained: the official version is audio-only, and the complete public transcript route located was third-party ASR rather than a creator transcript. Official audio, version 3c51f0fa-1cf6-4341-8754-33133c4bd56e
Biography and decision evidence
[investor-stated | strong]Casado says the 2008 downturn left Nicira at about twelve people for roughly two years and forced him to replace long-horizon PhD instincts with incremental, low-risk actions that could win customers, financing, and employee survival. This is formative evidence from the founder, not an independently reconstructed company history. Casado, 32:13–34:38[investor-stated | provisional]He recalls pitching Marc Andreessen at Ning during the downturn, says Andreessen and Ben Horowitz invested before the a16z fund existed, and attributes his move into venture to wanting broad participation in the infrastructure transformation through the operating-support model he had experienced. The account leaves investment entity, terms, partner roles, and contemporaneous records unresolved. Casado, 35:21–36:50[investor-stated | provisional]Casado says VMware acquired Nicira in 2012 and refers to a later approximately $600 million run-rate business under his management. These are self-reported operating figures in an introductory interview, not verified economics or evidence of his individual investment performance. Casado, 17:07 and 32:13
Philosophy signals
- Tags: picking / people.
[investor-stated | strong]Technical depth matters when it reveals a newly programmable layer, but Casado's own founder lesson says abstractions must become concrete products, customer adoption, and short-cycle survival work. Casado, 06:38–12:50 and 32:43–34:38 - Tags: sourcing / macro.
[investor-stated | moderate]Look for changes in the deployment substrate and buying center—virtualization, services, developers, open source—not only a feature improvement inside the old delivery model. Casado, 25:44–31:56 - Tags: risk / boards.
[researcher inference | moderate]A board should test whether easy developer insertion actually converts to durable revenue and whether service delivery reduces field complexity without merely shifting cost into hosting and support. Casado describes the tradeoff but does not state this board practice. Casado, 29:02–31:56 - Tags: people / self-interest.
[researcher inference | moderate]As a newly announced a16z general partner, Casado benefits from framing infrastructure as both technically exciting and a large investable transformation. That incentive does not invalidate the mechanisms, but it raises the bar for independent market and outcome evidence. Episode introduction and close, 00:37 and 35:21–36:50
Contradictions, counterevidence, and access limits
[researcher inference | strong]The episode's strongest evidence is Casado's direct account of how he reasoned; its weakest is efficacy. Named customers, Nicira traction, company run rate, and formative causation are retrospective and lack customer, board, financial, or failed-case corroboration. Casado, 16:03–17:07 and 32:13–36:50[researcher inference | moderate]“Software” and “as a service” lower some production, distribution, upgrade, and support costs, but the interview does not measure cloud cost, reliability, security, gross margin, procurement, or integration burdens that can replace the removed hardware and field-support costs. Casado, 25:44–31:56[researcher inference | moderate]Open source is presented as insertion and credibility, yet Casado simultaneously describes monetization and services economics as unresolved. Adoption is therefore not evidence of a scalable company or a sufficient investment rule. Casado, 28:35–31:56[contemporaneous record | strong]The official a16z page and Simplecast audio were accessible in full. No official transcript or creator captions were exposed; a complete PodScripts ASR page was inspected for timestamps and paraphrase checking, so exact wording and punctuation were not treated as quote-grade evidence. Official episode page
Open questions
[researcher inference | insufficient public record]Which contemporaneous LLNL, Stanford, intelligence-community, and Nicira records confirm the chronology and separate institutional/team contribution from Casado's later synthesis? Official episode, 01:19–10:07[researcher inference | insufficient public record]What did AT&T, NTT, eBay, Rackspace, and Fidelity buy, when did each commit, who at Nicira sourced and served them, and which pilots failed? Official episode, 22:55–29:43[researcher inference | insufficient public record]What gross margin, retention, field-support, and hosting evidence distinguishes a scalable infrastructure service from a services business? Official episode, 29:43–34:38[researcher inference | insufficient public record]Which a16z investments can be linked ex ante to the programmability, least-privilege, developer-insertion, or service-delivery rules articulated here? Official episode, 10:07–34:38
[t] AI’s Capital Flywheel: Models, Money, and the Future of Power
- URL: https://a16z.com/podcast/ais-capital-flywheel-models-money-and-the-future-of-power/ | Published: 2026-02-19 | Format: four-person interview (Martin Casado, Sarah Wang, Alessio Fanelli, Shawn “swyx” Wang) | Reliability: A for direct publisher audio/transcript | Access: full original transcript and audio | Accessed: 2026-08-20 | Locator scheme: Latent Space original timestamps | Version: original “Bitter Lessons in Venture vs Growth…,” 55:18; a16z replay Simplecast
59e995ea-faf7-4728-93a9-154634ad965f, 57:52
Takeaways
[investor-stated | strong]Casado and Wang describe an unusual capital flywheel: funding purchases compute, compute produces a stronger model on a relatively short clock, capability unlocks demand, and revenue supports a larger next round. The mechanism depends explicitly on scaling continuing and paid demand following capability. 03:19–09:39[investor-stated | moderate]Casado distinguishes the cycle from unused dot-com fiber by saying there are no “dark GPUs”: purchased accelerators are being used. Utilization alone does not establish economic return, additionality, or non-circular customer demand. 03:19–05:24[investor-stated | strong]The structural risk is vertical expansion. A frontier lab able to raise more than the application ecosystem can move into adjacent products and compete with its own customers, blurring infrastructure and application layers. 05:24–11:24[investor-stated | strong]Casado frames two mutually different futures: abundant fragmented software with perverse economies of scale as models diffuse, or increasingly general models that absorb applications and leave an oligopoly. He says the answer remains unknown and notes that current model economics may borrow against the next training round. 29:12–32:48[investor-stated | moderate]The pair warns that AI attention can underprice ordinary enterprise software and overprice talent or hardware categories. Casado calls a steadily growing, large-market software company a good investment even without token-driven hypergrowth; Wang says robotics funding may assume a hardware “ChatGPT moment” not yet observed. 17:33–22:42[researcher inference | moderate]Decision rule: model the financing-capability-revenue loop with explicit lags, outside capital required per capability step, compute utilization, gross margin after next-model training, and the probability that a supplier expands into the application. 03:19–11:24 and 29:12–32:48[researcher inference | moderate]Modern VC translation (as of 2026-08-20): capital-to-capability mapping, supplier-platform conflict, and two-scenario underwriting transfer. “No dark GPUs” does not transfer as proof of productive economics. Changed assumptions include billion-dollar training runs and strategic compute deals. Signals are utilization, independent customer cash, training-adjusted margin, model diffusion, and ecosystem revenue; misuse is treating fundraising as product evidence. Current examples Anthropic, Cursor, and World Labs are interested illustrations, not audited returns. 03:19–11:24 and 29:12–44:05
Quotes
[investor-stated | strong]“We don't have a supply overhang. Like, there's no dark GPUs.” — Casado. 03:47–04:25[investor-stated | strong]“The entire industry kind of hinges on two potential futures.” — Casado. 29:12–30:18
Biography and decision evidence
[investor-stated | strong]Casado and Wang speak as a16z's infrastructure and growth investors about how the firm connects stages and portfolio layers. The source demonstrates a shared current framework, not Casado-only authorship or unilateral authority. 00:00–06:24[investor-stated | moderate]Casado describes AI tools changing his own investor workflow and uses Cursor and World Labs as portfolio-linked cases. The episode does not disclose source, sponsor, vote, check, terms, ownership, or realized proceeds. 26:48–29:12 and 38:55–47:20[retrospective witness | moderate]His comparison with dot-com fiber draws on lived technology-cycle experience, but the inference from accelerator utilization to a different investment outcome remains prospective. 03:19–05:24
Philosophy signals
- capital allocation:
[investor-stated | strong]evaluate whether each funding increment can produce a timely capability and demand increment rather than financing an indefinite research story. 03:19–09:39 - portfolio construction:
[investor-stated | strong]map dependencies and conflict paths across foundation models, infrastructure, and applications before investing in several layers. 05:24–11:24 - picking:
[investor-stated | moderate]resist AI-fashion filters; ordinary enterprise software may offer adequate venture outcomes, while hardware must be diligenced as the vertical market it ultimately serves. 17:33–22:42 - risk / scenarios:
[investor-stated | strong]underwrite both fragmented expansion and model oligopoly; gross margin should include current spend on the next model, not only prior-model revenue. 29:12–32:48
Contradictions, counterevidence, and access limits
[researcher inference | strong]Accelerator utilization is necessary but not sufficient evidence of productive demand. Training can be funded by investors or strategic suppliers, and current customers may themselves be subsidized; independent cash and durable unit economics are the stronger tests. 03:19–05:24[researcher inference | strong]The flywheel can reverse: if scaling slows, demand fails to follow, financing tightens, or a lab cannot raise the next round, capability and revenue expectations may fall together. Wang explicitly names scaling as an assumption. 04:25–05:06 and 06:24–09:39[researcher inference | moderate]The “two futures” framing is useful but incomplete. Regulation, open-source coordination, customer multi-homing, sovereign models, and differentiated vertical data can produce intermediate structures. 29:12–32:48[researcher inference | moderate]a16z invests across the stack and benefits from large rounds, continued capital formation, and portfolio cross-selling. The discussion discloses interests but no fund-level cash outcomes. episode disclosure and contributor framing[contemporaneous record | strong]The Latent Space page provides the complete speaker-labeled original transcript and 55:18 audio. The a16z version is a longer replay with inserted material; this note counts the underlying interview once and uses the original clock. original title, timestamp map, and transcript
Open questions
[researcher inference | insufficient public record]How much foundation-model revenue is independent end-customer cash rather than strategic or ecosystem recycling? Official a16z replay[researcher inference | insufficient public record]What are training-adjusted gross margins after allocating the next-model run and compute commitments? Official a16z replay[researcher inference | insufficient public record]Which supplier/app conflicts have changed an a16z investment or reserve decision? Official a16z replay[researcher inference | insufficient public record]Which observable metrics decide between fragmentation, oligopoly, and intermediate market structures? Official a16z replay
[t] Monopolies vs Oligopolies in AI (20VC interview)
- URL: https://thetwentyminutevc.libsyn.com/20vc-a16zs-martin-casado-on-anthropic-vs-openai-where-value-accrues-cursor-vs-replit-vs-lovable-who-wins-and-who-loses-the-one-sin-in-ai-investing-why-open-source-is-a-national-security-risk-with-china | Published: 2025-07-28 (20VC original); a16z feed drop 2025-08-28; a16z web wrapper 2026-03-20 | Format: Harry Stebbings interview with Martin Casado, later distributed by a16z as “Monopolies vs Oligopolies in AI” | Reliability: A for official publisher identities, audio, dates, durations, and original chapter map; B for unlabeled third-party ASR used only to navigate the a16z distribution | Access: full original and a16z-distributed audio; original publisher agenda; no publisher transcript located | Accessed: 2026-08-20 | Locator scheme: elapsed time in a16z's 2025-08-28 feed-drop audio for claim pinpoints; 20VC's original chapter map is separately identified because its clock/edit differs | Version: 20VC RSS GUID
116ccff5-9336-4d72-8501-8a0a5205b3e7, duration01:10:37; a16z Simplecastf0811877-b86d-4180-89b1-2831d1f054b9, episode 913, duration01:17:25; one underlying interview, not a new 2026 recording
Takeaways
- [investor-stated | strong] Casado says his old intuition is least reliable where software creation itself is being disrupted, so he starts from observed business growth rather than a fixed map of where value “should” accrue. His warning is against zero-sum assumptions across chips, hosting, models, tools, and applications. a16z feed-drop audio, Casado at 01:26–02:43
- [investor-stated | strong] He distinguishes 2025 from the 2021 market by saying behavior should follow operating business—users, revenue, and value creation—not public-market marks or the volume of capital deployed. This is a discipline rule, but the interview supplies no audited operating series. a16z feed-drop audio, Casado at 02:43–03:47
- [investor-stated | moderate] For coding models, Casado considers both monopoly and oligopoly cases. His base guess is oligopoly because model advantages are episodic, knowledge can be distilled, and Google, OpenAI, and other well-financed players can subsidize entry—analogous to Azure and Google Cloud catching AWS. a16z feed-drop audio, Casado at 04:06–09:17
- [investor-stated | strong] He rejects “models” as a single investment class: speech, image, diffusion, code, and frontier-language businesses have different model sizes, subsidy, capital needs, and competitive economics. Frontier language can create enormous winners while forfeiting capital in non-leaders. a16z feed-drop audio, Casado at 10:03–13:47
- [investor-stated | moderate] Casado describes AI venture as a high-risk requirement rather than voluntary risk appetite: leaders across multiple stack layers are growing, but non-leaders have already been wiped out, so refusing the category and entering indiscriminately are both costly. a16z feed-drop audio, Casado at 12:03–13:47
- [investor-stated | provisional] His brand-effects thesis is that rapid market expansion continually adds uneducated users, and the first household name they hear captures adoption. As growth slows, users see competing messages and product differentiation matters more. He labels this early and falsifiable. a16z feed-drop audio, Casado at 14:02–18:28
- [investor-stated | moderate] Geographic regulation, language, and culture can create regional AI markets. Casado says a European company need not beat a U.S. leader globally if the European segment is independently large and defensible, but he provides no sizing evidence for the specific medical-transcription example. a16z feed-drop audio, Casado at 21:27–22:28
- [investor-stated | strong] Low current gross margin can be a deliberate board-level trade of margin for distribution during a land grab, not a permanent property of an AI application. To later gain pricing power, a company still needs brand, marketplace, workflow/domain integration, or technical differentiation. a16z feed-drop audio, Casado at 22:28–25:10
- [investor-stated | provisional] Casado expects task-specialized training to give application companies room to build models that outperform general models in their domain. The thesis depends on specialization tradeoffs persisting rather than frontier models or routing systems absorbing them. a16z feed-drop audio, Casado at 24:20–25:10
- [investor-stated | moderate] On open models, he separates two propositions: Chinese open models can create U.S. security dependence, while the response should be more U.S. open research and distribution, not retreat. He favors funding universities, national labs, and both closed and open programs. a16z feed-drop audio, Casado at 30:01–32:47
- [investor-stated | strong] Casado concedes the ecosystem was moving away from open releases even as policy rhetoric became more favorable. He expects open weights to persist because releasing smaller models can buy distribution without exposing the data, training pipeline, or most capable model. a16z feed-drop audio, Casado at 35:19–37:33
- [investor-stated | strong] His largest updated belief is the speed of coding-model progress. He says the tools make programming pleasant again by absorbing package, framework, hosting, and environment work, letting experienced programmers focus on logic. a16z feed-drop audio, Casado at 37:33–40:40
- [investor-stated | strong] He nevertheless estimates the effect on a strong engineer nearer 2× than 10× and says product-release velocity has not risen comparably across his companies. For infrastructure, the likely gain may be tests, documentation, maintainability, and fewer bugs because frontier experimentation and product judgment remain hard. a16z feed-drop audio, Casado at 40:40–42:23
- [investor-stated | strong] Casado continues to recommend computer science for people building computer systems. He hopes tools remove accidental framework/language complexity so programmers can focus on logic and fundamental tradeoffs, not that systems knowledge becomes unnecessary. a16z feed-drop audio, Casado at 46:40–49:21
- [investor-stated | strong] He takes job displacement seriously and explicitly supports government involvement. His working observation is that monetized AI uses still have human handlers, so work shifts toward review and control; he says the scale of displacement remains unknown and should be measured. a16z feed-drop audio, Casado at 49:55–52:19
- [investor-stated | strong] On venture mechanics, Casado says price is market-set while ownership is the binding early-stage variable: the expected median outcome must return a meaningful fraction of the fund. Very large, obvious markets and growth-stage checks can relax the ownership constraint. a16z feed-drop audio, Casado at 53:38–54:51
- [investor-stated | moderate] He sees two viable venture strategies: specialize deeply enough to win and keep ownership, or operate multiple products/stages so entry can adapt as the market changes. He places a16z in the latter camp and identifies the infrastructure fund he runs as roughly $1.2 billion in this interview. a16z feed-drop audio, Casado at 54:51–57:09
- [investor-stated | strong] His selection philosophy is that technology-market prediction is weak but relative company diligence is tractable once multiple companies have traction. Missing the category is tolerable; choosing the wrong company within a viable category is the “sin” the firm tries to avoid. a16z feed-drop audio, Casado at 01:00:32–01:05:27
Quotes
- [researcher inference | insufficient public record] No verbatim quote is retained. Both publishers provide audio but no transcript, and the accessible complete transcript route is third-party ASR. It supports navigation and conservative paraphrase, not verbatim preservation under the repository's quote gate. 20VC original listing and chapter map · a16z distribution · Unofficial navigation transcript
Biography and decision evidence
- [retrospective witness | strong] Casado says he worked for the intelligence community and Lawrence Livermore, spent roughly half his PhD work on security, and taught cybersecurity policy. He invokes this experience to compare internet and AI risk; it is relevant background, not independent validation. a16z feed-drop audio, Casado at 26:16–27:32
- [retrospective witness | strong] He says his first post-college job was at Lawrence Livermore in 1999 on the ASCI program, which simulated nuclear weapons, and uses that episode to support investment in national labs and academia despite export-control concerns. a16z feed-drop audio, Casado at 31:44–32:47
- [investor-stated | moderate] Casado supports equal-or-greater public science funding while also accepting that indirect-cost rules need reform; he calls the implementation path complex and says he does not know the answer. a16z feed-drop audio, Casado at 33:07–35:19
- [documented behavior | moderate] He describes ongoing evening programming with Cursor, old-game side projects, and direct observation of portfolio-company coding-agent commits. This is evidence of hands-on tool use, but not a controlled productivity measurement. a16z feed-drop audio, Casado at 37:33–42:23
- [investor-stated | strong] Casado states that he runs an approximately $1.2 billion infrastructure fund and that ownership—not headline price—is central to early-stage fund math. The contemporaneous a16z 2024 fund announcement uses $1.25 billion for Infrastructure, so the spoken figure is rounded. a16z feed-drop audio, 53:38–57:09 · a16z fund announcement
- [investor-stated | moderate] He says conflicts are a major reason a16z declines investments and describes a rule, borrowed from Chris Dixon, under which a portfolio founder may designate one “mortal enemy” the investor will not back. He also concedes pivots can create conflicts after investment. a16z feed-drop audio, Casado at 57:09–59:35
- [retrospective witness | moderate] Casado attributes persistent work drive to growing up with food stamps on a dirt road in Montana, says Nicira's sale made retirement financially possible, and recalls turning back from a planned Hollywood move because he preferred technology. These are personal recollections, not investment-performance evidence. a16z feed-drop audio, Casado at 01:06:54–01:10:27
- [contemporaneous record | strong] The underlying publisher identifies Stebbings as interviewer and Casado as guest. The 2026 a16z page byline names only Casado, but the audio remains Stebbings's 20VC interview and must not be recast as a solo Casado talk. 20VC original listing · a16z wrapper
Philosophy signals
- [investor-stated | strong] tags: picking / macro — start with observed users, revenue, and value creation; do not declare a stack layer uninvestable solely because another layer has bargaining power. a16z feed-drop audio, Casado at 01:26–03:47
- [investor-stated | strong] tags: portfolio / risk — capital intensity produces winner concentration and forfeited capital in non-leaders; portfolio construction must accept both multi-layer upside and substantial wipeout risk. a16z feed-drop audio, Casado at 10:03–13:47
- [investor-stated | moderate] tags: picking / risk — distinguish temporary margin sacrifice for distribution from structurally weak unit economics; underwrite the later source of pricing power explicitly. a16z feed-drop audio, Casado at 22:28–25:10
- [investor-stated | strong] tags: people — domain and systems judgment remain scarce even when code generation improves; the strongest builders use models to remove accidental complexity, not to outsource the hard problem definition. a16z feed-drop audio, Casado at 37:33–49:21
- [investor-stated | strong] tags: portfolio / ownership — price follows the market, but ownership must fit fund-return math; a multi-product platform can adapt stage and instrument to obtain sufficient exposure. a16z feed-drop audio, Casado at 53:38–57:09
- [investor-stated | strong] tags: picking — predict broad viable spaces cautiously, then concentrate diligence on which team, product, and technical approach is best among observable competitors. a16z feed-drop audio, Casado at 01:00:32–01:05:27
- [investor-stated | moderate] tags: boards / conflicts — conflict policy is partly relational and path-dependent; the stated “one mortal enemy” rule supplies a boundary, but post-investment pivots can still create unresolved competition. a16z feed-drop audio, Casado at 57:09–59:35
- [researcher inference | insufficient public record] tags: exits — despite discussing ownership and fund-return thresholds, the interview provides no reserve schedule, distribution history, write-off rate, exit timing, or realized multiple. Underlying interview, full recording
Contradictions, counterevidence, and access limits
- [contemporaneous record | strong] This row contains three dates, not three talks: 20VC's official RSS publishes the original on 2025-07-28; a16z's RSS distributes its longer copy on 2025-08-28; the a16z web page is dated 2026-03-20. The source-map phrase “2026 replay/2025 underlying” is directionally correct, but 2025-08-28 is the a16z feed-drop date, not the underlying 20VC publication date. 20VC original listing · a16z wrapper
- [contemporaneous record | strong] The exact official runtimes differ:
01:10:37in 20VC's RSS versus01:17:25in a16z Simplecast. The edits/clocks are not interchangeable; this note cites the a16z feed-drop clock and identifies the original chapter map separately. 20VC original listing · Simplecast player record - [contemporaneous record | strong] Neither publisher exposes a transcript. A complete third-party ASR page was used only for navigation; Stebbings/Casado separation is simple because there are two speakers, but merged turns and wording were not treated as quote-grade. No raw media or transcript is stored. Unofficial navigation transcript
- [researcher inference | strong] Casado's “every layer gets value” claim is about operating value, not investor return. Entry price, later dilution, subsidy, capital intensity, and the stated wipeouts can make a growing layer unattractive to a particular fund. a16z feed-drop audio, 01:26–03:47 and 10:03–13:47
- [researcher inference | moderate] The cloud analogy supports oligopoly as one path but does not prove model markets share cloud's switching costs, infrastructure intensity, regulatory structure, or cross-subsidy equilibrium. Casado calls oligopoly a guess and notes that the market is early. a16z feed-drop audio, Casado at 04:06–09:17
- [contemporaneous record | strong] A randomized July 2025 study found early-2025 AI tools slowed experienced developers 19% in one mature-repository setting. That does not refute Casado's personal use or quality thesis, but it supports his own later admission that tool adoption has not translated into comparable release velocity. METR study, “Core Result” and limitations table · a16z feed-drop audio, Casado at 40:40–42:23
- [researcher inference | strong] Casado discusses Cursor, OpenAI, model companies, and other markets as the leader of a16z's infrastructure practice. The interview is high-quality evidence of his thesis and decision process, but it is financially interested advocacy and does not disclose audited portfolio returns. a16z disclosure
Open questions
- [researcher inference | insufficient public record] What market-share and unit-economic evidence would distinguish a durable coding-model oligopoly from a temporary leader after a major model launch? a16z feed-drop audio, 04:06–09:17
- [researcher inference | insufficient public record] How does a16z quantify the probability-weighted loss from non-leaders against the upside from holding leaders across several stack layers? a16z feed-drop audio, 10:03–13:47
- [researcher inference | insufficient public record] Which AI companies improved gross margin after prioritizing distribution, and how much of the improvement came from price, routing, model cost, or proprietary technical work? a16z feed-drop audio, 22:28–25:10
- [researcher inference | insufficient public record] What objective measures would test whether coding agents improve maintainability and defects even when release cadence does not rise? a16z feed-drop audio, 40:40–42:23
- [researcher inference | insufficient public record] What exact ownership targets and median-outcome assumptions does the infrastructure fund use by stage, and how are reserves and follow-ons incorporated? a16z feed-drop audio, 53:38–57:09
- [researcher inference | insufficient public record] How often has the “one mortal enemy” conflict rule led a16z to decline a deal, and what process governs conflicts created by later pivots? a16z feed-drop audio, 57:09–59:35
[t] Is Non-Consensus Investing Overrated?
- URL: https://a16z.com/podcast/is-non-consensus-investing-overrated/ | Published: 2025-09-04 (a16z canonical; full publisher transcript posted 2025-09-05) | Format: three-person podcast debate (Martin Casado, Leo Polovets, Erik Torenberg) | Reliability: A for direct voice and publisher transcript | Access: full transcript and full audio | Accessed: 2026-08-20 | Locator scheme: publisher transcript timecodes 00:00:30–00:53:06 | Version: a16z Simplecast episode
768831f6-5750-455f-ad3d-95253e96dc31, 54:51
Takeaways
[investor-stated | strong]Casado's position is narrower than the title: a product can and often should be non-consensus to customers, but an investor or founder who ignores financing-market consensus creates follow-on risk. He explicitly disclaims consensus investing as a positive rule. 00:00:30–00:02:20 and 00:48:07–00:49:02[investor-stated | strong]His mechanism is market feedback, not imitation. If capable founders and investors repeatedly reject a thesis, that may expose a missing constraint; the correct response is to investigate the disagreement and form a plan for reaching later consensus, not automatically reverse the decision. 00:06:38–00:11:04 and 00:43:06–00:49:02[investor-stated | moderate]Casado says his view comes from almost 200 investments over ten years, including direct involvement and running a fund. This is a self-reported activity count, not a disclosed cohort or proof that consensus awareness improved returns. 00:00:54–00:02:20[investor-stated | moderate]He distinguishes standalone-company underwriting from acquisition-option underwriting. Humanoid robotics remains difficult for him because present unit economics, manufacturing verticalization, and competitive boundaries are unclear; buzz and possible M&A do not make a scalable standalone case. 00:28:20–00:32:46[investor-stated | strong]Stage and fund design change the feasible degree of contrarianism. Casado describes himself as a Series A investor who may need $30–40 million to reach a meaningful position, so follow-on access and market validation matter differently than for a small seed check. 00:52:10–00:53:06[researcher inference | moderate]Decision rule: record the strongest informed objection, expected next-financing audience, milestones that should convert skepticism, and a financing fallback. Pass when disagreement identifies an unpriced fatal constraint or when the company cannot survive long enough to prove the thesis. 00:00:54–00:11:04 and 00:43:06–00:53:06[researcher inference | moderate]Modern VC translation (as of 2026-08-20): what transfers is explicit consensus mapping and stage-aware financing risk; what does not transfer is treating aggregate VC opinion as ground truth. Present markets include larger multi-stage funds and faster narrative cycles. Observable signals are repeated independent objections, milestone-to-round timing, and reserve needs; likely misuse is trend chasing. Current example: Casado's humanoid-robotics hesitation is a stated application, not a validated return result. 00:28:20–00:32:46 and 00:52:10–00:53:06
Quotes
[investor-stated | strong]“I did not say, and I would never say consensus investing is a good idea.” — Casado. 00:00:54–00:02:20[investor-stated | strong]“The best companies themselves are non-consensus to customers.” — Casado. 00:48:07–00:49:02
Biography and decision evidence
[investor-stated | moderate]Casado reports almost 200 directly involved or fund-run investments across a decade. The mixed unit means it cannot be converted into a person-level deal denominator. 00:00:54–00:02:20[retrospective witness | moderate]He uses Nicira as an example of a product that looked irrational to outsiders but later became a major VMware business. The episode gives retrospective operating outcomes, not Nicira's investment-date memo or a venture selection record. 00:36:00–00:43:06[documented behavior | moderate]Casado publicly retracts the strongest reading of his own viral tweet and asks for cohort analysis; the publisher records that an analyst was working on the comparison but that results were not ready. 00:00:54–00:06:38 and 00:06:38–00:11:04
Philosophy signals
- picking:
[investor-stated | strong]seek disruptive products that are non-consensus to customers while remaining aware of capital-market and informed-peer objections. 00:43:06–00:49:02 - risk:
[investor-stated | strong]require a standalone scale case and legible unit economics; do not underwrite a company mainly to a possible acquisition. 00:28:20–00:32:46 - portfolio / vehicle:
[investor-stated | strong]check size and stage shape which disagreements a fund can finance through; Casado's $30–40 million position requirement is a vehicle constraint, not a universal rule. 00:52:10–00:53:06 - learning:
[documented behavior | moderate]state the thesis publicly, invite an informed counterparty, and propose a falsifiable cohort analysis rather than defend a slogan. 00:00:30–00:11:04 and 00:50:25–00:53:06
Contradictions, counterevidence, and access limits
[researcher inference | moderate]Casado's market-efficiency claim can become circular: later financing is partly produced by investor coordination and access, so consensus may measure network position as much as business quality. Polovets's seed-stage examples expose this boundary. 00:02:20–00:11:04 and 00:49:02–00:53:06[researcher inference | strong]“Almost 200 investments” supplies no passes, write-offs, realized distributions, stage mix, ownership, or matched consensus score. The proposed empirical test was unfinished in the episode. 00:00:54–00:06:38 and 00:50:25–00:53:06[researcher inference | moderate]The position can favor established multi-stage funds: their brand, reserves, and follow-on networks reduce the very financing risk used to caution smaller contrarian investors. Casado acknowledges stage and check-size dependence. 00:49:02–00:53:06[researcher inference | moderate]Casado and a16z have a financial interest in presenting scale, specialization, and later-stage capital as advantages. This does not invalidate the mechanism, but it raises the value of a matched fund-level test. 00:52:10–00:53:06[contemporaneous record | strong]Full publisher transcript and audio were available. The canonical a16z date is September 4, while the transcript post is September 5 and its player is slightly longer than the Simplecast version; claims are bound to the transcript timecodes above. publisher post metadata and timecode list
Open questions
[researcher inference | insufficient public record]What did the promised consensus/non-consensus cohort analysis find, and how were consensus, stage, access, and outcome defined? Official episode[researcher inference | insufficient public record]Which of Casado's nearly 200 activity records were direct sponsorships, IC votes, boards, follow-ons, passes, or fund-level exposure? Official episode[researcher inference | insufficient public record]How often did consensus awareness prevent a loss versus cause a missed outlier? Official episode[researcher inference | insufficient public record]What financing or reserve threshold makes a non-consensus thesis survivable at each stage? Official episode
[t] On Fear and Leadership: Product to Sales CTOs & CEOs
- URL: https://a16z.com/podcast/a16z-podcast-on-fear-and-leadership-product-to-sales-ctos-ceos/ | Published: 2020-12-04 | Format: firm podcast/hallway conversation (Martin Casado and Armon Dadgar with Sonal Chokshi) | Reliability: A for each speaker's direct voice; company history and operating outcomes are retrospective and not independently verified | Access: full official audio plus complete third-party ASR locator aid; no official transcript | Accessed: 2026-08-20 | Locator scheme: official-audio timestamps with speaker turns reconstructed from explicit introduction and conversational handoffs; ASR wording used only to locate/paraphrase passages | Version: Simplecast episode 84c19641-f901-491f-ae65-6e538d208985, audio file a16z-dadgarcasado-edit-v5.mp3, 128 kbps, runtime 42:47; recorded pre-pandemic and published later
Takeaways
[investor-stated | strong]Speaker separation: Chokshi introduces, probes, and synthesizes; Casado supplies Nicira history and his product/sales/operations framework; Dadgar supplies HashiCorp history and the pioneer/town-settler/city-planner analogy. Similar experiences are kept joint or separately named rather than reassigned to Casado. Introduction, 00:00–00:50[investor-stated | strong]Casado divides a company into product, sales, and operations phases. Product leadership finds fit by connecting technology, user, and need; sales establishes a repeatable motion with solvent unit economics; operations scales products, customers, channels, partnerships, and M&A. Leaders must either transform with the phase or recruit the missing capability. Casado, 00:50–04:48[investor-stated | strong]He treats the phases as changing “energy states,” not a linear maturity ladder: different geographies or functions can occupy different states, and a market discontinuity can return a sales-stage company to product discovery. His leader test is whether the person's daily attention matches the company's current bottleneck. Casado, Dadgar, and Chokshi, 07:37–09:07[retrospective witness | moderate]Casado says he repeatedly declined the Nicira CEO role because he naively saw it as clerical and wanted to remain in product creation. Once the company found product-market fit, he concluded that enterprise go-to-market knowledge was the scarce capability and preferred an excellent outside CEO to learning through a subordinate role. Casado, 09:07–10:42[retrospective witness | strong]His academic-to-founder lesson is to reverse the direction of reasoning: Nicira began with an elegant general networking theory, did not know the most important use case, and took roughly two years to let concrete customer problems determine the product mechanism. Saying the customer was “everybody” meant the company had no customer definition. Casado, 10:42–12:49[retrospective witness | moderate]Casado says Steve Mullaney brought product-marketing and enterprise go-to-market craft that Casado could not intuit, while low ego and title indifference reduced fear of a takeover. The board's explicit support for founder continuity made the transition less adversarial; these are participant recollections without Mullaney, board, or employee corroboration. Casado and Dadgar, 17:11–20:13[investor-stated | strong]Accountability must follow decision rights. Casado warns against one executive choosing a hire who reports to another: advice without consequences is less disciplined, the manager inherits someone else's decision, and an outside CEO can become a figurehead. Shared consultation is compatible with one accountable owner. Casado and Dadgar, 22:59–25:38[retrospective witness | strong]He now rejects interim CEOs: at Nicira the interim arrangement let him avoid a responsibility he was already performing de facto, while the temporary leader could not make durable decisions under the same consequences. Casado calls hiring Mullaney as permanent CEO probably his best Nicira decision, but supplies no formal comparison or causal outcome evidence. Casado, 27:37–29:30[investor-stated | strong]Founding status is not a permanent authority claim. Casado says technical founders must remain relevant by learning the current phase; his own response to the sales phase was to get on planes and sell. Dadgar similarly describes rediscovering his job, but that formulation belongs to Dadgar rather than Casado. Casado and Dadgar, 32:40–34:00[investor-stated | moderate]Repeatable sales mechanics do not eliminate founder selling in core infrastructure. Casado says a concentrated minority of deals drives most dollars and claims he still handled $10–30 million deals at a roughly $600 million run rate because buyers needed the company's technical genesis, strategic trajectory, and founder commitment. The figures are self-reported and unnamed. Casado and Dadgar, 35:42–39:30[investor-stated | strong]Executive diligence should be an extended, problem-specific “anti-sell”: expose the actual company, learn from the candidate, reference across reporting directions, test disagreement and frustration, and select for behavior under bad times. Casado's final boundary is symmetrical—fear can cause a founder either to abdicate too early or to block a needed CEO. Casado and Dadgar, 40:02–42:47[researcher inference | moderate]Decision rule: identify the company's present bottleneck, test whether the founder is genuinely retooling for it, recruit complementary expertise when not, bind autonomy to accountability, and evaluate the partnership under downside conditions before changing control. The five-part rule synthesizes the conversation and is not a stated Casado checklist. Full official audio
Quotes
[researcher inference | insufficient public record]No verbatim quote is retained: the official version is audio-only, while the complete public text route located was third-party ASR without creator verification. Official audio, version 84c19641-f901-491f-ae65-6e538d208985
Biography and decision evidence
[retrospective witness | moderate]Casado reports that Nicira had three CEOs, periods with no formal CEO when he acted de facto, and an interim appointment he later considered an abdication. This establishes his own evolving judgment, not the full governance chronology or each leader's contribution. Casado, 09:07–10:24 and 27:37–29:30[retrospective witness | provisional]He names cofounders Scott Shenker and a second professor, says Shenker initially received the CEO title and later returned to Berkeley, and credits Andy Rachleff with connecting Nicira to Mullaney. Titles, timing, search alternatives, board votes, and employment records are not supplied in the episode. Casado, 27:37–29:30[retrospective witness | moderate]Casado calls Mullaney central to Nicira's success and says the shared customer and press work became an apprenticeship in enterprise leadership. This is strong formative evidence from Casado but leaves Mullaney's own account, other executives, and team-level attribution missing. Casado, 17:11–18:27 and 25:06–26:35
Philosophy signals
- Tags: people / picking.
[investor-stated | strong]Evaluate leaders against the present company bottleneck and their demonstrated willingness and ability to transform, not founding status, title, or prior technical authority. Casado, 05:55–09:07 and 32:40–34:00 - Tags: boards / governance.
[investor-stated | strong]Support founders through a CEO transition while making roles explicit and pairing each executive's autonomy with the consequences of their hiring and operating decisions. Casado, 19:06–25:38 - Tags: portfolio / risk.
[investor-stated | strong]Interim authority and fear-driven compromise are failure modes; prolonged compatibility testing and downside-oriented references are worth the delay because a failed CEO insertion is more disruptive. Casado, 27:37–29:30 and 40:02–42:47 - Tags: self-interest / sourcing.
[researcher inference | moderate]The episode turns a selected successful leadership transition into a16z portfolio guidance and firm differentiation. Casado's admissions of naivety, interim-CEO error, and fear add useful disconfirming evidence, but no failed-transition denominator tests the prescription. Casado, 09:07–20:13 and 27:37–29:30
Contradictions, counterevidence, and access limits
[researcher inference | strong]Casado says leaders must transform with the phase, yet his own recommended solution was often to recruit capability rather than become CEO. The noncontradictory boundary is company value: transformation is required to retain authority, but title is optional and specialization can be rational. Casado, 05:55–10:42 and 32:40–34:00[researcher inference | moderate]Founder reassurance from the board can enable a productive CEO partnership, but it can also entrench founder vetoes or obscure fiduciary duties. The episode presents compatible, low-ego pairings and does not examine a case where control conflict or leadership replacement was necessary. Joint discussion, 17:11–25:38[researcher inference | moderate]The 20/80 account concentration, $10–30 million deal sizes, $600 million run rate, and “best decision” causal claim are retrospective and self-reported. No contracts, financial records, customer testimony, counterfactual, or team attribution is provided. Casado, 29:11 and 35:42–39:30[contemporaneous record | strong]The official a16z page and 42:47 Simplecast v5 audio were accessible in full, but no official transcript or creator captions were exposed. A complete PodScripts ASR rendering was used only for timestamp and speaker-turn alignment; exact wording and punctuation were not treated as quote-grade evidence. Official episode page
Open questions
[researcher inference | insufficient public record]What was Nicira's complete CEO chronology, who held formal decision rights in each gap, and what documented outcome followed the interim appointment? Official episode, 09:07–29:30[researcher inference | insufficient public record]Which board records show how Casado, the professors, Rachleff, Mullaney, and other executives evaluated or approved the permanent CEO transition? Official episode, 09:07–29:30[researcher inference | insufficient public record]Across Casado's portfolio, how often did an outside CEO improve product, sales, retention, and company value, and how often did the insertion fail? Official episode, 09:07–29:30[researcher inference | insufficient public record]What objective evidence distinguishes a founder who is retooling for the next phase from one narrating activity without acquiring the capability? Official episode, 29:30–39:42
[t] The Past, Present, and Future of Digital Infrastructure
- URL: https://colossus.com/episode/casado-the-past-present-and-future-of-digital-infrastructure/ | Published: 2022-06-07 | Format: Invest Like the Best podcast interview (Patrick O’Shaughnessy interviewing Martin Casado) | Reliability: A for speaker-attributed statements checked against the official audio; B for the third-party transcript rendering | Access: full official audio; partial current publisher transcript; full third-party transcript excerpt | Accessed: 2026-08-19 | Locator scheme: elapsed time in the current official audio enclosure; current publisher chapter links run about four seconds later in the opening section | Version: Invest Like the Best episode 280; RSS GUID
16aafc86-d341-4db6-b5f9-45a7d6ead63f; current Megaphone enclosureCLS7826028060.mp3?updated=1767968159; RSS duration00:56:44
Takeaways
- Cloud-era model [investor-stated | moderate]: Casado divides cloud adoption into internal IT, experimental cloud use around 2005–2010, mainstream migration around 2012–2016, and financial optimization by 2018–2019. The dates are his retrospective periodization, not adoption data. Official episode, Martin at
00:04:15–00:06:11 - Cloud-cost mechanism [investor-stated | moderate]: when infrastructure becomes a SaaS input, its cost moves into cost of goods sold and can materially affect gross margin; Dropbox's decision to build infrastructure is his example of a workload whose scale allegedly made generic S3 economics unattractive. The interview supplies no Dropbox cost ledger. Official episode, Martin at
00:06:49–00:09:15 - Investment evidence over prior theory [documented behavior | moderate]: Casado says his team repeatedly talked itself out of companies despite strong usage, later elevating product-usage graphs over their initial market theory; he identifies Hugging Face as an example. This is a useful stated correction mechanism, but the source names no rejected deal, decision date, or counterfactual return. Official episode, Martin at
00:29:03–00:31:48 - Workload specialization [investor-stated | provisional]: he argues Mighty, Fly.io, and MosaicML can compete with hyperscalers by optimizing around a narrower workload rather than reproducing a general cloud. His claims about founder quality and traction are portfolio promotion and are not independently tested here. Official episode, Martin at
00:17:43–00:19:42 - API-company underwriting [investor-stated | moderate]: as infrastructure is sold in smaller usage-based units, Casado says diligence should emphasize consumption and monetization curves rather than only buyer identity, annual contract value, and seat count. Pricing should follow the product's natural unit and surrounding ecosystem, not a universal formula. Official episode, Martin at
00:19:58–00:21:35and00:29:03–00:34:18 - Open-source boundary [investor-stated | moderate]: he expects operated infrastructure services to reduce customers' need to inspect source while increasing the importance of open standards; developer tools remain a stronger open-source domain. This is a category-dependent thesis, not a claim that open source broadly loses value. Official episode, Martin at
00:23:35–00:28:34 - Modern VC translation (as of 2026-08-19) [researcher inference | moderate]: for infrastructure investments, pair usage cohorts with gross-margin sensitivity, workload-specific cost curves, cloud-commit exposure, switching costs, and pricing-unit durability. Treat a compelling usage graph as a prompt to revise a thesis, not as sufficient evidence of defensibility or return. Official episode, Martin at
00:06:49–00:10:32,00:17:43–00:21:35, and00:29:03–00:34:18
Quotes
- “The graph in almost every case is just smarter than our theorying.” — Martin Casado,
00:30:39. [investor-stated | strong] Official episode - “Pricing often just isn't up to you.” — Martin Casado,
00:33:08. [investor-stated | strong] Official episode - “The broader the market, the finer grain the monetization units are.” — Martin Casado,
00:20:28. [investor-stated | strong] Official episode
Biography and decision evidence
- Casado says he and colleagues built a counterfactual model comparing cloud spend with market capitalization and concluded that some large software companies could justify internal infrastructure. [investor-stated | provisional] The model, assumptions, companies, and decision use were not published, so it is process testimony rather than reproducible evidence. Official episode, Martin at
00:10:32–00:14:24 - His Hugging Face account is retrospective decision evidence: strong usage reportedly conflicted with the team's theory, and the team learned to trust the observed graph more. [documented behavior | moderate] The interview does not establish whether a16z invested at that moment, which partner sponsored it, or whether the lesson improved later outcomes. Official episode, Martin at
00:29:03–00:31:48 - Casado discusses Mighty, Fly.io, MosaicML, and Hugging Face as examples in fields where a16z had investment exposure or active interest. [contemporaneous record | moderate] Company examples should therefore be read as thesis-bearing portfolio commentary, not independent product comparisons. Official episode, Martin at
00:17:43–00:19:42and00:29:03–00:31:48 - The interview names no a16z fund, check size, security, price, ownership, reserve decision, board action, loss, distribution, or realized multiple. [researcher inference | strong] It supports a June 2022 infrastructure thesis and a claimed decision-process correction, not deal-level attribution or performance. Official episode, full recording
Philosophy signals
- Picking / risk [investor-stated | strong]: actual usage can falsify a neat category thesis; Casado's stated response is to privilege observed adoption and then rebuild the theory around it. Official episode, Martin at
00:29:03–00:31:48 - Picking / macro [investor-stated | moderate]: specialization can reopen layers that appear consolidated because a narrow workload may support a better cost/performance envelope than a general hyperscaler. Official episode, Martin at
00:17:43–00:19:42 - Risk / portfolio [investor-stated | moderate]: cloud cost is not merely an engineering line item when it enters COGS; it can change gross margins, capital needs, and strategic choices across a software portfolio. Official episode, Martin at
00:06:49–00:14:24 - People [investor-stated | provisional]: Casado repeatedly highlights repeat founders as a positive signal, but the episode offers praise rather than a comparison against first-time founders or a documented selection rule. Official episode, Martin at
00:17:43–00:19:42 - Boards / exits [researcher inference | insufficient public record]: no evidence reveals how the cloud-cost thesis changed board guidance, financing cadence, exit timing, or realized returns. Official episode, full recording
Contradictions, counterevidence, and access limits
- The current Colossus page exposes only an introduction and opening exchange as transcript text, while a third-party archival excerpt supplies the fuller speaker-labelled wording. [contemporaneous record | strong] Selected quotations and claims were checked against the current official enclosure; the mirror remains a secondary transcription layer and may contain punctuation errors. Official episode Third-party transcript excerpt
- The current page's opening chapter markers are about four seconds later than the corresponding early position in the enclosure/mirror. [contemporaneous record | strong] This note binds locators to the current official audio and does not silently combine the two clocks. Official episode, opening chapter markers
- The cloud-versus-self-host model is Casado's unpublished analysis and can be highly sensitive to utilization, staffing, depreciation, migration, egress, negotiated discounts, and reliability. [researcher inference | strong] Its conclusion should not be generalized from company scale alone. Official episode, Martin at
00:10:32–00:14:24 - Casado's belief that machine learning makes all human problem domains software-addressable is a technology-maximalist forecast, not demonstrated evidence that software captures value or can economically solve each domain. [investor-stated | provisional] He partly narrows it by asking whether value belongs to software or the vertical business. Official episode, Martin at
00:40:45–00:45:31 - His crypto taxonomy and claim that distributed-system constraints cannot be hidden under a thin API are conceptual judgments; the interview provides no adoption or return data. [investor-stated | provisional] Official episode, Martin at
00:45:58–00:51:20
Open questions
- Which companies and assumptions were in the cloud-cost counterfactual model, and how accurate were its forecasts against later gross margins and market values?
- Which investment did the team initially reject despite usage, who changed the decision, and what return did the corrected process produce?
- What usage shape distinguishes durable pull from subsidized experimentation, and how does Casado test retention, pricing power, and workload portability?
- When does workload specialization create a lasting cost curve rather than a feature a hyperscaler can copy or bundle?
- Which open standards create enforceable portability in operated infrastructure, and what evidence would falsify the claim that source access matters less there?
- How did the stated infrastructure thesis affect reserves, board decisions, or exits in Mighty, Fly.io, MosaicML, or Hugging Face?
[t] Pricing, Pricing, Pricing
- URL: https://a16z.com/podcast/a16z-podcast-pricing-pricing-pricing/ | Published: 2016-08-13 | Format: firm podcast with official speaker-labeled transcript (Martin Casado and Mark Cranney, moderated by Scott Kupor) | Reliability: A for each speaker's direct views; recollections, private POC figures, and portfolio observations are not independently verified | Access: full official transcript and audio | Accessed: 2026-08-19 | Locator scheme: official transcript named headings plus official-audio timestamps | Version: Simplecast episode 7682df77-3481-47b7-809c-0f060a5f747c, 128 kbps asset, runtime 36:54; official a16z transcript rendered on canonical page
Takeaways
[investor-stated | strong]Speaker separation: Casado supplies the technical-founder and Nicira experience; Cranney supplies most formal sales, packaging, contracting, and review practices; Kupor frames questions and summarizes. Shared agreement is not assigned to Casado alone. Official transcript, introduction and “Price aggressively”[investor-stated | strong]Casado says technical founders often confuse technological usefulness with established willingness to pay. In a pre-chasm category with no accepted buyer or budget, an initially low price can teach the market to undervalue the product; he therefore favors starting high and learning through live selling. Casado, 00:44–02:16[investor-stated | strong]Casado's discovery mechanism is sales, not desk research: strong early salespeople remain connected to product development, test an aggressive price with actual prospects, and reveal who values the product and what the market will bear. Cranney adds that mature-market comparables can help, whereas new categories require iterative customer work. Casado and Cranney, 07:20–09:40[investor-stated | moderate]Casado warns that paid proofs of concept can be learning budgets rather than product-market-fit evidence. He says hot-area startups may receive $100,000–$200,000 engagements because enterprises want access to expertise; higher pricing and constrained customer capacity can force a stronger demand signal. The figures are illustrative and not tied to a published cohort. Casado, 12:54–13:51[investor-stated | strong]He distinguishes early-category “hunters” from mature-market route sellers. The early salesperson must surface bad news and product-market-fit evidence, not rely on relationships or report every meeting as progress; Cranney describes the same profile as intellectually curious and capable of creating the playbook. Casado and Cranney, official transcript “Choosing the right salespeople”[investor-stated | strong]Cranney owns the principal packaging framework: map value by buyer, use case, product module, and enterprise expansion; preserve optionality to package features later; fence lighthouse contracts; and align the small proof, medium deployment, and full-enterprise economics. Casado adds that preplanned product modularity prevents a lower tier from cannibalizing the original offer. Cranney and Casado, 20:57–25:51[investor-stated | moderate]Casado recalls coming close to granting nearly free site licenses to organizations with roughly 100,000 people after easy technical POC engagement met professional procurement. His lesson is that startup-outreach programs do not remove adversarial contracting or guarantee a path to purchase. The episode names no customer or final outcome. Casado, official transcript “Packaging products effectively” and “Correcting mistakes”[investor-stated | strong]Casado says early pricing mistakes can sometimes be repaired because categories take time to stabilize; functional differentiation and packaging create paths to raise price. Cranney adds that contracts, metering, modular product controls, measured realized value, and frequent win/loss reviews determine whether correction is practical. Casado and Cranney, 25:51–29:16[investor-stated | moderate]Go-to-market cost must fit deal economics. Casado says inside sales suits educated buyers, simpler products, and lower integration; field sales may be required for new or technically complex categories. He reports portfolio companies experimenting with both, but supplies no names, cost data, or comparative outcomes. Casado, official transcript “Pricing reviews and sales strategies”[researcher inference | moderate]Decision rule: ask whether a paid pilot proves use, willingness to pay, or merely curiosity; whether price maps to buyer-level realized value; whether the product and contract preserve expansion; and whether gross deal size supports the required sales motion. The checklist synthesizes Casado and Cranney and should not be attributed entirely to either. Official transcript, all named sections
Quotes
[investor-stated | strong]“there’s nothing that can do it except for sales.” — Casado. (9 words) Official transcript, “Gathering intel from salespeople”; audio about 12:15[investor-stated | strong]“So much of the early customer engagement should be, like, figuring out the product-market fit.” — Casado. (15 words) Official transcript, “Choosing the right salespeople”
Biography and decision evidence
[retrospective witness | moderate]Casado recalls that Nicira board member Ben Horowitz challenged his plan to enter at a low price because pricing would materially affect company valuation. The episode is Casado's later recollection; Horowitz's exact advice, meeting date, board materials, and ensuing decision are not independently available here. Casado, official transcript “Price aggressively”; audio 01:04[investor-stated | moderate]Casado presents himself as a convert: his PhD/technical-founder intuition favored broad use first, while enterprise selling taught him to use price and sales as market-discovery instruments. This is direct intellectual-development evidence, but the episode offers no before/after Nicira pricing ledger. Casado, 00:44–02:16 and 11:35–13:51[retrospective witness | provisional]Cranney and Casado refer to Cranney correcting Casado and Nicira's early selling choices, including salesperson profile and large-enterprise contracting. Their joint memory establishes an advisory relationship, not which person owned final decisions or what economics resulted. Official transcript, “Choosing the right salespeople” and “Correcting mistakes”
Philosophy signals
- Tags: picking / risk.
[investor-stated | strong]Price is a diagnostic instrument: aggressive pricing helps distinguish curiosity from demand and prevents scarce early implementation capacity from being consumed by weak accounts. Casado, 12:54–13:51 - Tags: people / boards.
[investor-stated | strong]Match sales talent to category maturity and demand evidence, not adjacent-product résumé; boards should want learning-rich market feedback rather than relationship-driven activity reports. Casado, official transcript “Choosing the right salespeople” - Tags: portfolio / exits.
[researcher inference | moderate]Pricing and packaging affect revenue quality, sales cost, expansion rights, and thus company value, but the episode does not connect the framework to ownership, exit timing, or realized venture returns. Official transcript, “Packaging products effectively” through “Pricing reviews and sales strategies” - Tags: self-interest.
[researcher inference | moderate]a16z's go-to-market practice is presented as the intervention that helped technical founders avoid pricing and contracting mistakes. That is relevant operating evidence and firm marketing; no untreated comparison demonstrates causal portfolio value. Official byline, transcript introduction, and contributor context
Contradictions, counterevidence, and access limits
[researcher inference | moderate]Starting high may create information, but it can also suppress trials, select only well-funded early adopters, or disguise weak repeatability behind a few custom enterprise contracts. The speakers give boundary conditions but no failure-rate comparison of high versus low entry pricing. Official transcript, “Price aggressively” and “Gathering intel from salespeople”[researcher inference | strong]Most packaging, contracting, cadence, and salesperson-selection prescriptions belong to Cranney, not Casado. They are useful context for Casado's learning but cannot be cited as his sole-authored investment philosophy. Official speaker-labeled transcript[researcher inference | moderate]The POC prices, nearly free site-license anecdote, and portfolio experiments are unnamed. Without contract terms, customer conversion, retention, margin, and alternative cases, they illustrate failure modes rather than establish thresholds. Casado, official transcript “Gathering intel,” “Correcting mistakes,” and “Pricing reviews”[contemporaneous record | strong]The canonical page supplied the full speaker-labeled transcript and the Simplecast API supplied a 36:54 runtime. Transcript headings are stable locators; detailed seconds were aligned to the official audio using the page's show-note anchors and a public ASR timing aid. Official episode page
Open questions
[researcher inference | insufficient public record]What was Nicira's original price, who approved it, how did it change, and what happened to win rate, ASP, cycle time, gross margin, and retention? Official episode[researcher inference | insufficient public record]How many $100,000–$200,000 POCs converted into repeatable deployments, and what controls distinguish learning spend from product-market fit? Official episode[researcher inference | insufficient public record]Which 100,000-person site-license negotiations does Casado reference, and what contract and price were ultimately signed? Official episode[researcher inference | insufficient public record]Across a16z's portfolio, when did inside versus field sales experiments improve unit economics, and which pricing systems failed? Official episode
[t] a16z Podcast: Selling to Developers & Open Source Business Models
- URL: https://a16z.com/podcast/a16z-podcast-selling-to-developers/ | Published: 2016-04-13 | Format: firm podcast (Martin Casado and Peter Levine with Sonal Chokshi) | Reliability: A for each named speaker's direct views; examples and market generalizations are not independently verified | Access: full official audio plus complete third-party ASR locator aid; no official transcript | Accessed: 2026-08-19 | Locator scheme: official-audio timestamps with speaker-separated passages; ASR wording used only as a locator aid | Version: Simplecast episode 2409d20f-daf0-4f87-b0fc-d58b6077de1f, 128 kbps asset, runtime 25:27; official a16z YouTube mirror Ily92aKqDQM also identified
Takeaways
[investor-stated | strong]Speaker separation: Chokshi moderates. Levine supplies the portfolio-wide operating and sales-practice claims, while Casado supplies the developer-infrastructure, market-category, and first-person Nicira/open-source organizational claims. Joint agreement is identified as such rather than assigned to Casado alone. Introductions, 00:00–00:43[investor-stated | moderate]Levine argues that developers shifted from having no purchasing power to being an influential adoption wedge because software entered every organization and cloud/open-source tools became easy to try. Casado adds that developers increasingly consume infrastructure abstractions directly, using containers as the example. These are related but separately voiced mechanisms. Levine and Casado, 00:43–05:36[investor-stated | strong]Levine's go-to-market sequence is bottom-up adoption followed by top-down monetization: open source or SaaS creates product use and pipeline; sales expands the footprint and makes growth predictable. Casado sharpens the boundary—developers influence budget but are often not the buying center, so the company must appeal to the user and sell to engineering, IT, or executive authority. Levine and Casado, 06:47–11:35[investor-stated | strong]Casado treats open source as marketing to a technical audience: it lets developers inspect, use, and trust a product before a formal sale. He does not say open source eliminates sales; in this episode it is the top of the funnel and an insertion mechanism. Casado, 11:35–12:54[investor-stated | moderate]Levine says the Red Hat support-and-maintenance model was unusually difficult to repeat and favors operating open source as a cloud service, where the customer pays for the service rather than a free/paid bit distinction. Casado separately argues that historic open-source successes often commoditized mature markets, so founders must distinguish market entry by cheaper substitution from genuine category creation. Levine and Casado, 13:24–16:27[investor-stated | moderate]Levine offers moving above commoditized open-source infrastructure into applications as another business model, but notes that moving up the stack fragments demand. Casado's corresponding diligence rule is to identify what remains monetizable, whether the company is really becoming services-heavy, and whether it is entering a known category or attempting category creation simultaneously. Levine and Casado, 16:27–20:42[investor-stated | strong]The two speakers agree that developer adoption must be earned technically. Levine recommends an early community function; Casado says he assigned his best engineer to the open-source product because credibility and adoption came from product quality, not community management alone. The tradeoff is that this engineer is not building the proprietary core. Levine and Casado, 20:42–21:53[investor-stated | strong]Casado describes an organizational tension rather than a clean “open wins” rule: if the open-source team reports to the proprietary product, monetization may starve the community; if open source controls the proprietary product, it can erase the upsell boundary. His personal solution was separate teams with a senior arbiter enforcing the go-to-market dividing line. Casado, 21:53–24:58[researcher inference | moderate]Decision rule: require a founder to show the user, buyer, budget owner, open-source adoption surface, paid control point, sales escalation path, and organizational owner of each roadmap. Viral use without this map is distribution evidence, not business-model proof. This synthesis combines separately attributed statements and is not quoted as Casado's checklist. Levine and Casado, 07:24–24:58
Quotes
[researcher inference | insufficient public record]No verbatim quote is retained: the official version is audio-only, and the complete public transcript route located was third-party ASR rather than a creator transcript. Official audio, version 2409d20f-daf0-4f87-b0fc-d58b6077de1f
Biography and decision evidence
[investor-stated | moderate]Casado says that at Nicira he put his best developer on the open-source work and ultimately used separate open and proprietary teams with an executive arbiter. This is direct evidence of an operating choice; the episode does not name the engineer, repository, decision date, paid-product boundary, or outcome. Casado, 21:21–24:58[investor-stated | provisional]Levine cites an a16z investment then called Arimo, formerly Dato, as a company building applications over Spark and Hadoop rather than supporting those projects. The example is Levine's and must not be converted into Casado deal attribution; sourcing, sponsorship, board work, ownership, and economics are not stated. Levine, 17:43–18:28[researcher inference | moderate]The discussion occurred within months of Casado joining a16z and shows him translating a founder-side organizational problem into an investment and portfolio-support lens. Chronology supports the transition, but not a causal claim that this view determined later investments. Official date, byline, and audio
Philosophy signals
- Tags: sourcing / picking.
[investor-stated | strong]Treat open-source traction as evidence of technical attention and account insertion, then separately test buyer authority, paid value, and enterprise expansion. Casado, 11:35–16:27 - Tags: people / boards.
[investor-stated | strong]The best technical talent and explicit organizational decision rights are part of open-source strategy; community activity cannot compensate for a weak product or an unmanaged open/paid roadmap conflict. Casado, 21:21–24:58 - Tags: risk / portfolio.
[researcher inference | moderate]A services-heavy model, fragmented higher-layer market, or open core with no defensible paid boundary should lower confidence even when adoption is high. The risk synthesis is supported by both speakers but is not tied to portfolio outcomes here. Levine and Casado, 12:54–20:42 - Tags: self-interest / macro.
[researcher inference | moderate]The speakers are a16z partners explaining a16z-style enterprise company building and use selected portfolio experience. The episode contains no failed-company denominator, so the advice may reflect firm strategy and survivor selection as well as generalizable evidence. Official contributor context and disclosure
Contradictions, counterevidence, and access limits
[investor-stated | strong]Developer-led distribution is deliberately bounded: the speakers reject the idea that a free product will simply spread and monetize itself, while still calling open source a powerful adoption wedge. Any synthesis that reduces the episode to “sell to developers” loses the actual two-motion argument. Levine and Casado, 07:24–11:35[researcher inference | moderate]The Red Hat, open-core, services-margin, and mature-market claims are asserted from partner experience without published samples, financial comparisons, or counterexamples. They are useful hypotheses, not established base rates. Levine and Casado, 12:54–20:42[researcher inference | moderate]Separate open and proprietary teams may clarify incentives but also duplicate work, create governance conflict, or weaken community trust. Casado reports personal preference, not comparative evidence that the structure outperforms other models. Casado, 21:53–24:58[contemporaneous record | strong]The official a16z page and Simplecast audio were accessible in full. No official transcript or creator captions were exposed; a complete PodScripts ASR page was used for speaker-turn and timestamp alignment, so its punctuation and word choices were not retained as verified quotation. Official episode page
Open questions
[researcher inference | insufficient public record]Which Nicira open-source project, engineer, proprietary boundary, and organizational chart does Casado's first-person account describe, and what adoption/revenue result followed? Official episode, 06:47–16:27[researcher inference | insufficient public record]What portfolio denominator supports Levine's claims about Red Hat, open core, hosted open source, services economics, and moving up the stack? Official episode, 16:27–24:58[researcher inference | insufficient public record]At what usage, account concentration, security requirement, or contract size should a developer-led company add direct enterprise sales? Official episode, 21:21–24:58[researcher inference | insufficient public record]Which later Casado investments show the two-motion model ex ante, and which high-adoption developer products failed to monetize? Official episode, 06:47–24:58
[t] Software Chasms with Martin Casado
- URL: https://softwareengineeringdaily.com/2019/01/28/software-chasms-with-martin-casado/ | Published: 2019-01-28 | Format: long-form publisher interview (Jeff Meyerson interviewing Martin Casado) | Reliability: A for Casado's direct voice; named company examples, market figures, and recollections are not independently verified | Access: full publisher transcript and official audio | Accessed: 2026-08-20 | Locator scheme: publisher-transcript timestamps and PDF pages; current dynamically served audio has shifted ad timing | Version: Software Engineering Daily episode SED756, 30-page transcript; Megaphone asset SED6359497909, 128 kbps, current runtime 55:37.796; transcript's final interview timestamp is 01:01:29
Takeaways
[investor-stated | strong]Speaker separation: Meyerson asks the questions and supplies the introduction; Casado supplies the interview's technical history, Nicira operating recollections, enterprise go-to-market prescriptions, and investing views. Introductory claims are not reassigned to Casado. Publisher transcript, pp. 1–3 and 00:05:48[retrospective witness | moderate]Casado says the original programmability problem emerged from intelligence-community work in 2001–2003, but his later technical conclusion is narrower than “programmable switches”: move load balancing, security, and related functions into software at endpoints while treating the network as connectivity plumbing. This is his 2019 reconstruction, not a contemporaneous research record. Casado, 00:06:03–00:08:00; pp. 3–4[retrospective witness | strong]Nicira initially tried OEM and partnership distribution with companies including Citrix, Google, and NEC; Casado says those routes failed and the company took roughly two years to learn that a complex, category-creating product required direct founder-led selling. He distinguishes the operating lesson from cloud-native products that can spread bottom-up. Casado, 00:08:10–00:11:36; pp. 4–6[investor-stated | strong]His diagnostic for a struggling company is to separate execution failure from absent or premature product-market fit. Founder selling reduces ambiguity: if the visionary team cannot sell a complex direct-sale product, adding channel partners or sales capacity hides rather than solves the causal question. Casado, 00:09:24–00:11:36; pp. 5–6[retrospective witness | moderate]During the VMware acquisition, early Nicira investor Diane Greene advised Casado to retain Nicira's sales team because VMware's existing server-oriented reps did not yet know networking and security. He calls retaining that team one of the best decisions, but the interview supplies no acquisition documents, counterfactual, or independent sales results. Casado, 00:11:46–00:13:19; pp. 6–7[investor-stated | strong]Casado's enterprise-buying model is a barbell: teams need bounded discretion to select useful technology bottom-up, procurement consolidates vendor leverage, and CIO intervention is reserved for organization-wide discontinuities that practitioners trapped in a local optimum cannot initiate. He rejects both unilateral executive selection and uncontrolled tool-chain fragmentation. Casado, 00:18:57–00:26:22; pp. 9–13[investor-stated | strong]Bottom-up adoption is an incumbent-bypass mechanism, not a complete revenue model. Casado recommends product/community-led entry where possible, followed by direct enterprise sales for concentrated account dollars; the marketing-led and field-sales motions have different unit economics and should be designed deliberately. Casado, 00:26:48–00:30:39; pp. 13–15[investor-stated | strong]He says founders over-rotate on open source: source availability matters when developers integrate code, but freemium SaaS can produce the same product-led discovery. The higher-order question is delivery—who operates, updates, and supports the service—and whether the company supplies valuable integration into the customer's larger system. Casado, 00:31:44–00:40:41; pp. 15–20[investor-stated | moderate]The “endless chasm” arises when technology and competitors change before a category becomes a stable known object. Casado permits paid customer integration but draws the failure boundary at customer-specific core-engineering forks; a disciplined vendor can instead buffer buyers from technical change and later move mature integration work to partners. Casado, 00:40:47–00:48:29; pp. 20–24[investor-stated | moderate]Cloud platforms are simultaneously substrate and unusually informed incumbents: they see workload demand and can reproduce open-source functionality sooner than older hardware vendors. Casado therefore treats hyperscaler response as an explicit startup-strategy question rather than assuming incumbents ignore pre-chasm markets. Casado, 00:15:00–00:17:02 and 00:43:00–00:45:41; pp. 7–8 and 21–22[researcher inference | moderate]Decision rule: underwrite infrastructure across five linked tests—founder-led demand discovery, bottom-up insertion, enterprise conversion, integration without product forks, and defense against a platform that can observe the category forming. The components are Casado's; the five-part checklist is reconstructed rather than quoted. Casado, 00:09:24–00:48:29
Quotes
[investor-stated | strong]“If I couldn't sell it, nobody could sell it.” — Casado. (8 words) Publisher transcript, 00:08:10; p. 5[investor-stated | strong]“creating a market is incredibly hard.” — Casado. (6 words) Publisher transcript, 00:59:12; p. 29
Biography and decision evidence
[retrospective witness | moderate]Casado says Nicira survived the 2008 financing collapse at roughly twelve people while competitors died, then had to reverse years of austerity when the market improved. He credits survival materially but warns that a survivalist identity can prevent timely investment when the inflection arrives. Casado, 00:59:12–01:01:27; pp. 29–30[retrospective witness | provisional]He says Diane Greene was an early Nicira investor, Ben Horowitz served on its board, and the retained sales organization helped build a significant VMware business. The episode does not establish investment terms, decision rights, ownership, team credit, or realized economics. Casado, 00:08:10–00:13:19; pp. 4–7[investor-stated | provisional]Casado identifies a16z portfolio relationships with Databricks, DigitalOcean, RapidAPI, and other infrastructure companies while explaining horizontal infrastructure, cloud differentiation, and API-market expansion. These remarks establish public association or board involvement only where he states it; they do not establish sourcing, sponsorship, ownership, or returns. Casado, 00:15:00, 00:52:14, and 00:55:39; pp. 7, 25, and 28
Philosophy signals
- Tags: picking / risk.
[investor-stated | strong]A founder should create clean causal evidence: sell the category personally before scaling sales, and do not let partners make execution indistinguishable from missing demand. Casado, 00:09:24–00:11:36; pp. 5–6 - Tags: sourcing / macro.
[investor-stated | moderate]Look for technical markets large enough to support narrow components or APIs, but favor founders able to survive a slow market and accelerate when demand inflects. Market creation itself is treated as difficult, not an automatic product virtue. Casado, 00:55:39–01:01:27; pp. 27–30 - Tags: boards / people.
[researcher inference | moderate]Board work should preserve category-specific founder and sales knowledge through acquisition while challenging distribution shortcuts and the founder's readiness to switch from austerity to growth. The interview supplies the operating episodes, not a documented Casado board protocol. Casado, 00:08:10–00:13:19 and 00:59:12–01:01:27 - Tags: self-interest / portfolio.
[researcher inference | moderate]Casado benefits from defining integration, services, and rapid technical change as venture opportunities for a16z infrastructure companies. His explicit cautions—product forks, platform copying, services discipline, and premature markets—make the thesis falsifiable but do not supply a portfolio denominator. Casado, 00:38:51–00:48:29; pp. 19–24
Contradictions, counterevidence, and access limits
[researcher inference | strong]Casado endorses integration services while warning against the endless chasm. The operational boundary—repeatable integration versus customer-specific core engineering—is clear, but the transcript offers no gross-margin, code-fork, retention, or customer-concentration thresholds for applying it. Casado, 00:38:51–00:48:29; pp. 19–24[researcher inference | moderate]Bottom-up products can bypass incumbent account control, yet Casado says concentrated enterprise dollars still demand costly direct sales and procurement. Adoption should therefore not be treated as proof of efficient monetization or durable margin. Casado, 00:26:48–00:30:39; pp. 13–15[researcher inference | moderate]Nicira, GitHub, Slack, Elastic, Databricks, and other named successes are selected examples. No failed-company denominator, ownership data, or independent outcome comparison establishes that the reconstructed rules generated venture returns. Publisher transcript, pp. 7–29[contemporaneous record | strong]The publisher provides a complete, speaker-coded 30-page transcript. Its timestamps include historical sponsor segments and end at 01:01:29, while the current dynamically served Megaphone asset is 55:37.796; transcript page and embedded timestamp are therefore the stable locators, and no raw artifact was retained in the repository. Publisher episode page
Open questions
[researcher inference | insufficient public record]Which Nicira OEM and partnership contracts failed, what did each test, and how did direct-sales conversion change after the pivot? Publisher transcript[researcher inference | insufficient public record]What product-fork, services-margin, retention, or expansion evidence distinguishes a valuable integration layer from an endless-chasm consultancy? Publisher transcript[researcher inference | insufficient public record]Which platform responses defeated a16z-backed infrastructure startups, and which defensibility mechanisms survived hyperscaler replication? Publisher transcript[researcher inference | insufficient public record]Which contemporaneous records allocate credit for Nicira's survival, retained sales team, VMware growth, and acquisition outcome across founders, executives, investors, and employees? Publisher transcript
[t] Software Secures the World
- URL: https://a16z.com/software-secures-the-world/ | Published: 2017-02-12 | Format: single-speaker talk/video | Reliability: A for Casado's direct voice; self-reported operating figures remain uncorroborated | Access: full video with English auto-captions | Accessed: 2026-08-20 | Locator scheme: YouTube timestamps | Version: official a16z page (modified 2023-04-16) embedding a16z YouTube
ulPKaIfG77o, uploaded 2017-07-15, runtime 20:10; page labels the presentation “Summit 2016,” but does not print a recording day
Takeaways
- [investor-stated | strong] Casado rejects the standard “arms race” frame for cybersecurity and substitutes misalignment: a change in the battlefield can invalidate tactics on both sides and force a wholesale retool, rather than merely escalating the same weapons. Talk, 01:20–03:53
- [investor-stated | moderate] He treats the move from client-server systems to cloud and mobile as a decade-scale misalignment: compute and valuable data became concentrated, access paths multiplied, and attackers became more sophisticated, producing new security categories across the attack chain. The causal account is coherent but offered without comparative adoption or breach data. Talk, 03:55–05:40
- [investor-stated | strong] His canonical attack sequence is human reconnaissance → target-specific exploit and delivery → endpoint compromise → human-operated command and control → lateral movement with redundant malware strains → discovery and gradual exfiltration. This is a workflow map, not evidence that every attack follows the sequence. Talk, 05:43–09:08
- [investor-stated | moderate] Casado says the industry's response created a product category at nearly every link in that chain, but that the resulting point-product and alert proliferation moved the bottleneck from threat detection to human consumption inside security operations centers. Talk, 09:22–12:03
- [investor-stated | moderate] His 2016-era investment thesis is a “self-driving” security operations center: use large-scale data systems, machine learning, automation, and distributed-systems abstractions to codify scarce domain expertise and reduce operator load. Mentioned company counts and labor-shortage measures are directional, self-reported, and not sourced in the talk. Talk, 12:05–14:05
- [investor-stated | moderate] He extends the same misalignment lens into physical security: digital identity, revocable access, audit logs, computer vision, and autonomous systems can replace keys, manual video review, and guard-only workflows. Talk, 14:14–16:03
- [investor-stated | provisional] A 2011 Nicira server-theft story supplies the motivating observation: employees spent days manually reviewing footage before finding a masked intruder, whereas Casado argues searchable vision systems could narrow the same review by time, behavior, or employee identity. It is a retrospective founder anecdote, not an independently documented efficacy comparison. Talk, 16:05–19:11
- [researcher inference | moderate] The operable venture screen is to ask whether a startup removes a new workflow bottleneck created by the last wave of tools—not merely whether it detects another threat—and whether its automation preserves auditable human control. The second condition is an analyst-added boundary; Casado does not discuss false positives, model drift, or accountability here. Talk, 10:46–12:47
Quotes
- [investor-stated | strong] “Almost all attacks have a human in the loop.” — Casado, 08:08–08:12. (Official auto-caption wording; punctuation normalized.)
- [investor-stated | strong] “We can't really consume the technologies that are being created.” — Casado, 11:28–11:40. (Official auto-caption wording; punctuation normalized.)
- [investor-stated | strong] “We’re seeing this age of automation and simplification.” — Casado, 13:54–14:04. (Official auto-caption wording; punctuation normalized.)
Biography and decision evidence
- [investor-stated | provisional] Casado dates his security work to roughly 17 years before the talk, connecting intelligence-community cybersecurity work in Afghanistan/Iraq, a Stanford security PhD, Nicira, and VMware into one formation narrative. The auto-caption garbles several proper nouns, so only the clearly audible chronology is retained. Talk, 00:00–00:39
- [investor-stated | provisional] He reports that the VMware product had reached about a $600 million run rate by his departure and says roughly half was security. These are retrospective, unaudited speaker claims and do not identify revenue definition, period, or individual contribution. Talk, 00:24–00:38
- [investor-stated | moderate] He says he and a former RSA security executive constructed the talk's canonical kill chain after reviewing attacks, including intelligence-community cases, and explicitly calls it canonicalized rather than a literal single incident. Individual cases and sample construction are not disclosed. Talk, 05:43–06:07
- [investor-stated | moderate] Casado says the next investment signal came from both company flow into a16z and buyer response: security teams appeared saturated with products and alerts, shifting startup formation toward automation. That is useful process evidence but is selected from a venture firm's inbound pipeline. Talk, 10:27–10:56
Philosophy signals
- [investor-stated | strong] tags: picking / risk / people — look for discontinuities that force a new operating model, map the entire workflow before selecting the bottleneck, and treat scarce expert attention as a first-class constraint. Talk, 02:12–02:32 · Talk, 11:18–12:23
- [investor-stated | moderate] tags: sourcing / picking — company formation and buyer fatigue are leading indicators of a category transition, but their use requires correction for a16z's pipeline and portfolio exposure. Talk, 10:27–10:56
- [researcher inference | moderate] tags: risk / boards — for automation businesses, diligence should test alert precision, operator override, auditability, and whether automation reduces total incident cost rather than only headcount. These governance tests are not stated in the talk; they are necessary boundaries on its thesis. Talk, 12:05–13:53
Contradictions, counterevidence, and access limits
- [investor-stated | provisional] Casado says adopted technology could deal with “most” attacks before describing overload as the next bottleneck, but supplies no denominator for attacks, deployments, or prevented losses. The efficacy premise should remain unproven. Talk, 10:30–10:49
- [contemporaneous record | strong] The official page was published 2017-02-12 and tags the presentation to Summit 2016; its embedded YouTube copy was uploaded 2017-07-15. The note therefore binds claims to the 20:10 embedded version and does not invent a more precise recording date. Official page, video and metadata
- [researcher inference | moderate] The prediction that physical security would experience a flight-scale discontinuity is directional advocacy, not a measured outcome. The talk does not address surveillance privacy, discrimination, adversarial examples, or regulation—material counterweights to the opportunity thesis. Talk, 18:27–20:03
- [contemporaneous record | moderate] The only text route located was YouTube's English auto-caption track. It contains obvious proper-noun errors; summaries were reconstructed against surrounding caption context, and quotations are limited to short, unambiguous phrases. No transcript or raw media is stored in the repository. Official embedded video
Open questions
- [researcher inference | insufficient public record] What attack corpus and outcome definition supported the “most attacks” claim, and how did prevention rates compare before and after the product-category expansion? Talk, 10:30–10:49
- [researcher inference | insufficient public record] Which automation investments were made from this thesis, what decision role did Casado have, and did they reduce mean time to detect/respond or merely shift analyst work? Talk, 12:05–14:05
- [researcher inference | insufficient public record] Can contemporaneous Nicira incident or law-enforcement records corroborate the server-theft episode and distinguish the proposed computer-vision capability from a later retrofit? Talk, 16:05–19:11
[t] The State of American AI Policy: From ‘Pause AI’ to ‘Build’
- URL: https://a16z.com/podcast/the-state-of-american-ai-policy-from-pause-ai-to-build/ | Published: 2025-08-15 | Format: multi-speaker a16z policy podcast/video; Erik Torenberg interviews Martin Casado and Anjney Midha | Reliability: A for official media, date, speakers, and publisher timecodes; B for unlabeled third-party ASR used only to navigate speaker turns; policy judgments are advocacy by financially interested investors | Access: full official audio and video; publisher show notes and timecodes; no publisher transcript located | Accessed: 2026-08-20 | Locator scheme: elapsed time in official a16z audio/video; Casado claims are limited to directly addressed or dialogue-separated turns, and policy-document comparisons use page/section locators | Version: Simplecast episode
7b0c14a0-e574-47cc-8383-98719c2f1e6a, episode 904, duration00:42:01; official a16z YouTubeL5za2B9p448; recorded after the 2025-07-23 release of America's AI Action Plan
Takeaways
- [investor-stated | moderate] Casado frames the central change as cultural and institutional: in his account, the earlier posture treated innovation itself as dangerous, while the 2025 posture makes continued U.S. development an explicit national objective. This is his characterization of two administrations, not a neutral content analysis of their policies. Official video, Casado at 01:23–04:06
- [investor-stated | moderate] He contrasts AI with the early internet: worms and critical-infrastructure attacks produced concrete new harms, yet the U.S. response still emphasized building capability. He uses that precedent to require stronger empirical justification before restricting a general-purpose technology. Official video, Casado at 03:12–04:06
- [investor-stated | provisional] Casado argues that claims equating open models with weapons confused a general-purpose technology with harmful applications and often relied on theoretical rather than demonstrated marginal risk. The episode does not itself present a systematic risk review. Official video, Casado and Midha at 06:39–10:22
- [investor-stated | strong] His policy decision rule is marginal risk: first ask what risk is new relative to existing computer, network, and stochastic systems; reuse established controls where they fit; create new controls only when a novel risk and the insufficiency of existing tools are articulated. Official video, Casado at 39:25–41:23
- [investor-stated | moderate] Casado says speculative discourse can become costly when policymakers treat it as settled evidence because laws are much harder to revise than software. He concedes existential risk is non-zero but disputes leaping from that concession to sweeping ex-ante restrictions. Official video, Casado and Midha at 15:30–17:45
- [investor-stated | strong] On open models, Casado distinguishes source code from model weights: releasing weights does not recreate the data or training pipeline, so a company can distribute smaller models while retaining a more capable closed model and proprietary production capability. Official video, Casado at 22:59–25:26
- [investor-stated | moderate] He therefore treats open weights as a business instrument—distribution, recruiting, brand, ecosystem, and market entry—not only an ideology. He expects the separation between open smaller models and paid frontier models to support more sustainable “open core” economics than conventional software. Official video, Casado at 23:14–26:06
- [investor-stated | moderate] The episode separates closed-frontier and open/sovereign markets by customer requirement: leading capability and convenience versus control, on-premises operation, security, support, and regulatory needs. Casado and Midha expect winners in both rather than a single open-versus-closed outcome. Official video, panel at 21:41–28:27
- [investor-stated | strong] Casado welcomes the Action Plan's evaluation agenda but says implementation is the hard part: risk claims should be preceded by measurement frameworks, testbeds, and agreed evaluation methods rather than grand proclamations. Official video, Casado and Midha at 31:05–32:49
- [investor-stated | strong] He distinguishes alignment to a stated task from ideological alignment imposed on users. Making unruly models more reliable for an explicit goal is desirable; a top-down mandate deciding what information or ideas users may encounter is a separate political choice. Official video, Casado at 32:49–34:31
- [investor-stated | moderate] Casado's answer to “what's the rush?” is opportunity cost: delaying a beneficial technology can itself impose health, scientific, economic, and security losses. He still says identified marginal risks should be addressed directly rather than ignored. Official video, Casado and panel at 37:35–39:56
- [researcher inference | moderate] The operative framework is evidence-before-novel-liability, not no regulation: define the new harm, test whether existing law and controls cover it, measure benefits forgone by delay, then target residual risk. Official video, 37:35–41:23
Quotes
- [researcher inference | insufficient public record] No verbatim quote is retained. The publisher supplies full media but no transcript, and the accessible complete transcript is unlabeled third-party ASR; paraphrases are speaker-separated conservatively, but the repository's verbatim-quote gate was not met. Official episode and media · Unofficial navigation transcript
Biography and decision evidence
- [retrospective witness | moderate] Casado says the lack of technologist opposition to restrictive proposals was why “we got involved,” and later recalls calling Midha at night when new rules appeared. This documents personal/firm advocacy activity but not its budget, authorization, counterparties, or causal effect on policy. Official video, Casado at 01:23–02:35 and 19:19–19:54
- [retrospective witness | strong] He uses early-career internet-security experience, work for the intelligence community and Lawrence Livermore, PhD security research, and teaching a cybersecurity-policy course to explain his risk baseline. These are self-reported credentials and do not settle the policy claims. Official video, Casado at 03:12–03:51 · Related direct account, 20VC at 26:16–27:32
- [retrospective witness | moderate] Casado calls himself a roughly 20-year student of open-source business models and uses that experience to distinguish open weights from reproducible open software. The episode supplies no portfolio-wide return comparison between open and closed strategies. Official video, Casado at 22:59–26:06
- [contemporaneous record | strong] The publisher names Torenberg as host and Casado and Midha as guests. Midha's claims about policy engagement, sovereign customers, and model investments remain Midha's; the note does not collapse them into Casado's biography or a unanimous firm view. Publisher page, contributors and description
- [researcher inference | insufficient public record] No investment decision memo, company-level ownership, lobbying filing, policy-drafting role, or financial outcome is disclosed. Advocacy and investment incentives must therefore remain visible rather than being converted into causal evidence. Official episode, full recording
Philosophy signals
- [investor-stated | strong] tags: macro / risk — require an empirically specified marginal harm before creating a new liability regime; prefer existing cybersecurity, sector, and product-safety tools where they cover the risk. Official video, Casado at 39:25–41:23
- [investor-stated | strong] tags: picking / macro — open weights can be an investable distribution strategy because training data, pipelines, frontier capability, and operational service remain scarce even after weights are released. Official video, Casado at 22:59–26:06
- [investor-stated | moderate] tags: portfolio / risk — treat open and closed models as customer-segment choices rather than mutually exclusive ideologies; sovereign and regulated customers may pay for control while developers may pay for frontier convenience. Official video, panel at 26:56–28:27
- [investor-stated | strong] tags: people / boards — distinguish task-level alignment and measurable reliability from unbounded ideological mandates; governance should state the objective, evaluation, and residual risk explicitly. Official video, Casado at 32:49–34:31
- [researcher inference | moderate] tags: sourcing / macro — policy capability becomes part of infrastructure-company diligence where customer access, open-model distribution, export rules, or sovereign deployment depend on government choices. Official video, full discussion
- [researcher inference | insufficient public record] tags: exits — the episode does not connect policy scenarios to exit timing, liquidity, ownership dilution, or realized fund returns. Official episode, full recording
Contradictions, counterevidence, and access limits
- [contemporaneous record | strong] The official page and Simplecast feed contain full media and timecodes but no transcript resource; direct YouTube caption enumeration hit an anti-bot gate. The third-party transcript merges unlabeled turns and misrenders names, so it was used only to navigate and speaker boundaries were accepted only when the dialogue made them explicit. No raw transcript or media is stored. Official episode · Simplecast player record
- [contemporaneous record | strong] The Action Plan itself does call for an evaluations ecosystem, NIST guidance, federal research coordination, academic partners, and DOE/NSF testbeds. That supports the panel's evaluation point but narrows Casado's claim that academia is largely omitted: broad university investment may be absent, yet academic participation is expressly present. America's AI Action Plan, “Build an AI Evaluations Ecosystem,” p. 10
- [contemporaneous record | strong] California's governor vetoed SB 1047 because its controls were keyed to model size rather than high-risk deployment, but simultaneously reported signing 17 narrower AI bills and expanding critical-infrastructure risk assessment. The official record therefore fits targeted-risk regulation better than a simple pause-versus-build binary. Governor's record, opening “What you need to know” and first two body paragraphs; SB 896/SB 1047 paragraphs
- [researcher inference | moderate] The internet analogy cuts both ways: concrete harms justified sustained investment, but they also produced cybersecurity institutions, liability, procurement rules, and defense controls. “Keep building” does not by itself answer who bears AI externalities or which sector-specific controls are warranted. Official video, Casado at 03:12–04:06
- [researcher inference | strong] Casado and Midha are investors advocating policy that can affect portfolio-company costs, distribution, and competition. Their direct voice is high-reliability evidence of their philosophy, not independent evidence that a preferred policy maximizes public welfare. a16z disclosure
- [investor-stated | provisional] The episode concedes non-zero existential risk, unresolved interpretability, and the need for new controls if novel marginal risk is demonstrated. Those concessions limit any reading of the discussion as “no new AI governance.” Official video, 17:10–17:45 and 34:31–41:23
Open questions
- [researcher inference | insufficient public record] What empirical threshold would Casado accept as a demonstrated new marginal risk, and who should set it? Official video, 39:25–41:23
- [researcher inference | insufficient public record] Which existing laws and controls cover model-enabled cyber, biological, fraud, discrimination, and critical-infrastructure harms, and where are the measured gaps? Official video, 06:39–13:39 and 39:25–41:23
- [researcher inference | insufficient public record] How should evaluations remain scientifically useful and politically legitimate when government, labs, deployers, and investors have different incentives? Official video, 31:05–32:49
- [researcher inference | insufficient public record] What market, security, and audit evidence distinguishes a genuinely open model from a weight release that cannot be reproduced or independently governed? Official video, 22:59–26:06
- [researcher inference | insufficient public record] What role did a16z personnel have in drafting, advising, lobbying for, or responding to the Action Plan, and how were portfolio conflicts governed? Official episode, full recording
[t] The World Through an API
- URL: https://a16z.com/the-world-through-an-api/ | Published: 2018-03-09 | Format: single-speaker Summit talk/video | Reliability: A for Casado's direct voice; company-growth and market-size claims are uncorroborated speaker assertions | Access: full video with English auto-captions | Accessed: 2026-08-20 | Locator scheme: YouTube timestamps | Version: talk delivered at the a16z Summit in November 2017; official page published 2018-03-09 (modified 2024-04-12) embedding a16z YouTube
xd5EoVc3I_Y, uploaded 2018-03-09, runtime 17:55
Takeaways
- [investor-stated | strong] Casado's historical model is progressive disaggregation: as an ecosystem matures, the minimum unit capable of supporting a viable company shrinks—from an integrated car or mainframe, to components and applications, and then to functions exposed through APIs. Talk, 01:01–03:35
- [investor-stated | strong] He argues that reusable application functions such as messaging, email, payments, identity, and data services can become independent API businesses because software—not a human—is the immediate consumer. Talk, 03:37–05:18
- [investor-stated | moderate] APIs lower the application-builder's required systems expertise by packaging difficult functions behind a programmable interface. Casado illustrates the contrast with his undergraduate video-game work, when he had to understand keyboard and display handling before focusing on story, art, or music. Talk, 05:19–06:46
- [investor-stated | moderate] He predicts two broad effects: more domain experts can create software, and infrastructure specialists can launch narrower companies without building a complete human-facing application. The direction is plausible; the talk provides no entry-cost or startup-success comparison. Talk, 07:42–09:20
- [investor-stated | strong] Casado divides the investment opportunity into three layers: companies whose product is an API, new infrastructure required by the API abstraction, and aggregation/marketplace layers that make a proliferating ecosystem navigable. Talk, 09:22–10:09
- [investor-stated | strong] His screen for an API company is a function sufficiently complex to specialize and sufficiently common across applications to create repeat demand. SigOpt is his example of codifying expert hyperparameter optimization into a callable service. Talk, 10:10–12:48
- [investor-stated | moderate] Every new abstraction, he argues, demands new security, performance, visibility, debugging, and control infrastructure. He uses Kong's API gateway—logging, rate limiting, authentication, key management, and deployment control—as the example. Talk, 12:50–14:59
- [investor-stated | moderate] Disaggregation also creates a discovery and governance problem, which can support a new aggregator. RapidAPI is presented as the API marketplace/intermediary that helps developers find and connect to services while mediating operational functions. Talk, 15:01–16:27
- [investor-stated | moderate] The operating implication is that IT must manage remote service dependencies rather than only installed applications, physical servers, VMs, or containers. His reported average of 17 remote APIs per mobile app is not sourced in the talk. Talk, 16:29–17:50
- [researcher inference | moderate] The reusable investment test is two-sided: determine whether specialization produces a durable independent value pool, then identify the security, observability, reliability, and aggregation layers the new boundary necessarily creates. Talk, 09:22–10:09 · Talk, 12:50–16:27
Quotes
- [investor-stated | strong] “As markets grow, the unit for which you can create a viable company shrinks.” — Casado, 01:49–02:02. (Official auto-caption wording; punctuation normalized.)
- [investor-stated | strong] “Every time we have a new abstraction, we have to build particular infrastructure components to support it.” — Casado, 12:50–13:08. (Official auto-caption wording; punctuation normalized.)
- [investor-stated | strong] “APIs are going to be the new way of consuming computer science.” — Casado, 08:12–08:27. (Official auto-caption wording; punctuation normalized.)
Biography and decision evidence
- [investor-stated | moderate] Casado says he paid for much of his undergraduate education by writing video games, using that experience to explain how abstraction changes which skills can create software. The employment and income details are not independently documented here. Talk, 05:19–06:06
- [investor-stated | moderate] He recalls running large natural-phenomenon simulations at Lawrence Livermore National Laboratory, where each run could take about two weeks; the story motivates SigOpt's tuning example but does not establish measured performance for the company. Talk, 10:43–11:09
- [investor-stated | strong] Casado explicitly describes the three examples—SigOpt, Kong, and RapidAPI—as portfolio companies selected to illustrate three layers of the API thesis. The talk does not identify who sourced, sponsored, approved, negotiated, or governed the investments. Talk, 09:22–10:09
- [investor-stated | strong] He identifies his decision role only at the strategy level: “as an infrastructure investor,” he expects narrower infrastructure companies to launch faster because a machine-facing API avoids some human-interface work. Talk, 08:29–09:20
Philosophy signals
- [investor-stated | strong] tags: sourcing / picking — search for a newly viable company boundary where a complex, frequently reused function can be separated from a larger application. Talk, 10:10–10:31
- [investor-stated | strong] tags: picking / portfolio — invest across the stack created by a new abstraction: the atomic service, the control infrastructure, and the aggregation layer. Talk, 09:22–10:09
- [researcher inference | moderate] tags: risk / boards — diligence should test dependency concentration, service reliability, switching costs, data rights, security, and whether an API captures value or is commoditized by adjacent platforms. These countertests are absent from the bullish talk. Talk, 16:29–17:50
Contradictions, counterevidence, and access limits
- [investor-stated | provisional] Casado cites an Ovum market measure and a rough tenfold expansion after disaggregation while openly questioning the estimate's accuracy. Neither the measure, period, nor base is visible in the transcript, so no numeric market-size claim should be carried forward. Talk, 07:19–07:35
- [investor-stated | provisional] Claims that Kong was the fastest-growing open-source project a16z had seen and that RapidAPI was the world's leading API marketplace use no fixed date, denominator, or independent measure. They are contemporaneous enthusiasm, not durable rankings. Talk, 14:16–14:59 · Talk, 15:42–16:27
- [researcher inference | moderate] Disaggregation does not guarantee an independent profit pool: hyperscalers can bundle the function, open-source substitutes can compress price, and cross-service dependencies can raise reliability and security costs. The talk does not present a failed API company or an integration counterexample. Talk, 03:12–05:18
- [researcher inference | moderate] The SigOpt “factor of ten” and six-month-to-six-week examples are presented as an outcome and an illustration without study design, customer denominator, or source. They should not be interpreted as verified portfolio performance. Talk, 12:24–12:48
- [contemporaneous record | strong] The official page says the talk was delivered at the November 2017 a16z Summit, then published with the current embedded YouTube version on 2018-03-09. Claims are dated to that event/version rather than treated as current. Official page, closing description
- [contemporaneous record | moderate] The available transcript route is an English auto-caption track with proper-noun errors. Short quotes are limited to unambiguous phrases; no raw transcript or media is stored in the repository. Official embedded video
Open questions
- [researcher inference | insufficient public record] For SigOpt, Kong, and RapidAPI, what were Casado's specific sourcing, sponsorship, diligence, board, follow-on, and exit roles, and which vehicle held each investment? Talk, 09:22–10:09
- [researcher inference | insufficient public record] Which API functions created durable standalone economics, which were bundled or commoditized, and what ex-ante signal separated the two groups? Talk, 10:10–10:31
- [researcher inference | insufficient public record] How should the 2017 thesis be revised for AI-generated code, model APIs, cloud-platform consolidation, data residency, software-supply-chain security, and service-outage concentration? Talk, 16:29–17:50
[t] Trends in—and the Future of—Infrastructure
- URL: https://a16z.com/trends-in-and-the-future-of-infrastructure/ | Published: 2016-08-21 | Format: solo talk/video | Reliability: A for Casado's direct views; market and company figures are speaker claims without cited datasets | Access: full official video route and complete third-party caption aid; legacy Vimeo asset no longer resolves directly | Accessed: 2026-08-19 | Locator scheme: official-video timestamps; caption wording used only to locate passages | Version: a16z legacy Vimeo ID 179360082, page-declared watch time 23 minutes; official a16z YouTube mirror 1MAmSACkidg, final spoken timestamp 22:51
Takeaways
[investor-stated | strong]Casado rejects the “death of infrastructure” framing and predicts a transformation favorable to startups. His mechanism is not market size alone: three reinforcing shifts—hardware to software, installed software to services, and operator-led procurement to developer influence—reduce different incumbent advantages. Casado, 00:45–03:53[investor-stated | provisional]He frames the 2016 opportunity using an approximately $4 trillion IT market, $220–240 billion of SaaS plus public cloud, and roughly 6% penetration. The talk supplies no underlying dataset, category definitions, or reconciliation, so these numbers establish his contemporary framing rather than a verified market denominator. Casado, 01:25–01:51[investor-stated | moderate]The software-defined mechanism is a ubiquitous, general platform with stable insertion points. When functionality can run entirely in software at the hypervisor, operating-system, application-platform, or cloud-management layer, a startup can avoid appliance supply chains, distribute trials cheaply, and focus resources on software. Casado, 03:53–07:45[investor-stated | provisional]Casado uses Nicira as proof of the software transition, saying it raised about $40 million, became a billion-dollar company, and had a roughly $600 million run-rate product six months before the talk. These are first-person promotional figures without cited financial records, and the talk does not separate Nicira, VMware, team, or market contributions. Casado, 07:55–09:40[investor-stated | strong]Software distribution does not remove operational burden. Casado says heterogeneous customer environments, skill variation, remote debugging, and multiple deployed versions enlarge R&D and post-sales work; service delivery addresses this by centralizing upgrades, operations, and versions. Casado, 10:22–13:56[investor-stated | strong]Moving infrastructure abstractions into developers' application stacks shifts product influence and budget. Casado distinguishes developers' preference for community, open source, technical elegance, and rapid self-service from incumbent routes built on certifications, analysts, channels, procurement, and long sales relationships. Casado, 14:14–19:19[investor-stated | strong]Developer attention is not revenue. Casado calls developer usage a replacement for product marketing or the top of the funnel; he says most enterprise companies still need direct sales to convert account credibility and traction into substantial revenue. Casado, 19:35–20:38[investor-stated | moderate]The three shifts form a reinforcing loop: software and services enter the developer domain; developer demand creates markets for more software and services; startups align with open source, community, and technical elegance. The talk does not establish that the loop protects margins, ownership, retention, or returns. Casado, 21:17–22:18[researcher inference | moderate]Decision rule: test a startup's advantage separately at four layers—technical insertion point, delivery/operations, developer discovery/adoption, and enterprise monetization. Passing the first three without a credible fourth layer is not a complete infrastructure-company thesis. Casado, 03:42–20:38
Quotes
[researcher inference | insufficient public record]No verbatim quote is retained: the official page exposes video but no creator transcript, while the complete public text route located was a third-party caption rendering. Official talk page and video identifier
Biography and decision evidence
[investor-stated | moderate]Casado uses Nicira's 2007 product choice as a founder case: deliver traditional networking functions in hypervisor software rather than build an appliance, despite an investor warning that customers only knew how to consume unified hardware. The story records his retrospective thesis; it does not identify the investor or preserve the ex-ante memo. Casado, 07:55–09:11[investor-stated | strong]The talk shows Casado, in his first year at a16z, explicitly linking a founder experience to the firm's stated model of backing a technical phenomenon and surrounding the founder with go-to-market capability. This is firm philosophy and biographical positioning, not proof of an investment outcome. Casado, 19:35–20:38[researcher inference | moderate]The company invitation at the close makes the talk partly a sourcing artifact: it publicly defines the categories of infrastructure founder Casado wanted to meet. The inference concerns purpose, not evidence that any later deal originated here. Casado, 22:18–22:51
Philosophy signals
- Tags: sourcing / picking.
[investor-stated | strong]Search where a standard software insertion point permits a small technical team to attack functionality previously bound to proprietary hardware or installed software. Casado, 03:53–10:08 - Tags: risk / portfolio.
[investor-stated | strong]Underwrite the delivery and monetization system alongside the technology: shipped software can create version/support debt, while developer adoption without direct sales may not generate enterprise revenue. Casado, 10:22–13:56 and 19:35–20:38 - Tags: people / boards.
[researcher inference | moderate]The proposed company-building complement is technical-founder strength plus deliberate go-to-market capability. The talk does not specify partner roles, board interventions, or whether a16z services caused portfolio outcomes. Casado, 20:21–20:38 - Tags: macro / self-interest.
[researcher inference | moderate]A newly arrived infrastructure partner has a sourcing and category-creation incentive to declare a “golden era.” Independent customer economics and incumbent-response evidence are needed before treating the rhetoric as a base rate. Official byline, contributor block, and talk
Contradictions, counterevidence, and access limits
[investor-stated | strong]Casado's own developer-budget caveat limits the headline disruption: developer influence can bypass some incumbent marketing and procurement advantages, but enterprise sales, operational integration, and purchasing authority remain. Casado, 19:35–20:38[researcher inference | strong]Nicira is a selected success used to demonstrate the mechanism. The talk provides no comparable software-defined failures, customer cohort, incumbent adaptation, ownership/dilution, or net investment return, so it cannot establish a startup-wide unfair advantage. Casado, 07:55–10:08[researcher inference | moderate]The 2016 market figures and predictions are time-bound. Cloud mix, open-source commercialization, developer procurement, platform concentration, and infrastructure capital intensity can change the transferability of the thesis. Casado, 01:25–03:42 and 22:18–22:51[contemporaneous record | strong]The a16z page identifies legacy Vimeo 179360082 and states a 23-minute watch time, but that Vimeo endpoint returned 404 in this run. The official a16z YouTube mirror and complete third-party caption aid were accessible; the latter's last spoken timestamp is 22:51 and was not treated as quote-grade text. Official talk page
Open questions
[researcher inference | insufficient public record]What data source and category definitions generated the $4 trillion, $220–240 billion, and 6% figures in August 2016? Official talk, 00:45–20:38[researcher inference | insufficient public record]Which Nicira financing, VMware revenue, and customer records corroborate the funding, valuation, run-rate, and causal product claims? Official talk, 00:45–20:38[researcher inference | insufficient public record]Which infrastructure startups passed the software/service/developer tests but failed because of market size, gross margin, distribution, reliability, or incumbent bundling? Official talk, 00:45–20:38[researcher inference | insufficient public record]Which later Casado investments were explicitly underwritten with the four-layer decision rule reconstructed here? Official talk, 00:45–20:38
[t] Jack Altman & Martin Casado on the Future of VC
- URL: https://a16z.com/podcast/jack-altman-martin-casado-on-the-future-of-vc/ | Published: 2025-09-03 original; 2025-09-04 a16z republication | Format: Uncapped interview (Jack Altman interviewing Martin Casado) plus a16z feed-drop edit | Reliability: A for official audio, B for third-party navigation transcript | Access: full official audio and full timestamped navigation transcript | Accessed: 2026-08-20 | Locator scheme: a16z edit elapsed time; navigation transcript timestamps 00:00:00–00:52:32 | Version: original Uncapped GUID
df6fdb44-887f-11f0-94e9-b3e2a6697529, 52:10; a16z Simplecast editac6fc175-2685-49b6-b64b-1d66e87b4ae4, 53:28; claims use the a16z edit clock unless stated otherwise
Takeaways
[investor-stated | strong]Casado argues that a larger technology market requires specialist coverage: a generalist partnership may work when only a few infrastructure companies exist, but market breadth now permits an investor to spend a career in one technical subcategory. 00:05:49–00:09:59[investor-stated | strong]His firm-design mechanism joins specialization to delegated coverage. A consensus organization of generalists cannot reliably know which spaces are covered, allocate domain work, or scale decisions; specialization creates accountable market maps and founder services. 00:08:27–00:10:30[investor-stated | strong]Casado's selection algorithm separates space formation from company picking: several strong founders committing careers can validate that a space is real; the investment team then maps all credible companies and picks one, because a premature rival investment can conflict the fund out of the winner. 00:45:03–00:46:29[investor-stated | moderate]In very fast markets, he places less weight on stated TAM and price and more on identifying the strongest team, sometimes waiting until the fund believes it can distinguish that team. He calls these rough heuristics and says the fund is often wrong. 00:46:29–00:48:38[investor-stated | strong]Casado decouples fiduciary board work from company help: boards protect the corporation and shareholders, while sourcing, recruiting, customers, and operating assistance can occur without a seat. The a16z platform is presented as the scalable delivery mechanism. 00:50:55–00:52:32[researcher inference | moderate]Decision rule: establish a named specialist, enumerate the credible founder set, delay until differentiating evidence appears, and treat any first check as consuming conflict capacity. Record why the chosen team is better and what evidence would reopen the map. 00:08:27–00:10:30 and 00:45:03–00:48:38[researcher inference | moderate]Modern VC translation (as of 2026-08-20): specialist mapping, conflict budgets, and explicit board-versus-service roles transfer. TAM dismissal and “best team” judgment do not transfer without unit economics, price discipline, and ex-ante criteria. Changed assumptions include AI market velocity and larger multi-stage funds. Signals are multiple credible founders, technical differentiation, conflict density, and customer pull; misuse is post-hoc winner labeling. Current example: Casado applies the algorithm to AI, but no complete cohort is disclosed. 00:45:03–00:52:32
Quotes
[investor-stated | strong]“The only sin is picking the wrong company in a certain space.” — Casado. 00:45:03–00:45:39[investor-stated | strong]“The hard thing is: how do you add a lot of value?” — Casado. 00:51:47–00:52:18
Biography and decision evidence
[retrospective witness | moderate]Casado contrasts the generalist a16z he joined with the later specialist platform. This is direct organizational memory, but the episode supplies no internal staffing ledger, decision-right document, or performance comparison. 00:04:56–00:10:30[investor-stated | strong]He says founder experience is more persuasive in competitive deals than the specialist label alone, connecting his Nicira operating history to access rather than proving better selection. 00:09:59–00:12:20[investor-stated | moderate]He reports spending substantial time with some companies where he has no board seat and less time with some where he does. This is useful role-boundary evidence but remains unaudited self-report. 00:50:55–00:52:18
Philosophy signals
- sourcing:
[investor-stated | strong]use clusters of strong founders committing time and reputation as evidence that a technical space deserves coverage. 00:45:39–00:45:58 - picking:
[investor-stated | strong]map the whole credible team set and pick the strongest technical team at the earliest point the distinction is defensible. 00:45:58–00:48:38 - portfolio construction:
[investor-stated | strong]one investment can consume a conflict lane; selection error inside a good space may be more costly than selecting a space that later fails. 00:45:03–00:45:39 - boards:
[investor-stated | strong]separate fiduciary governance from platform services and founder assistance; neither a seat nor service activity alone proves influence or outcome. 00:50:55–00:52:32
Contradictions, counterevidence, and access limits
[researcher inference | strong]Declaring the “best team” after a market develops invites hindsight. The episode provides no ex-ante ranking sheet, all-company map, rejected-team record, or realized cohort proving that specialist coverage improves hit rate. 00:45:03–00:48:38[researcher inference | moderate]Conflict avoidance can improve focus but can also reduce experimentation, syndication, and learning. The episode specifies no exception, information-barrier, or conflict-release rule. 00:45:03–00:45:39[researcher inference | moderate]Throwing away TAM and valuation is bounded to highly uncertain, rapidly expanding markets; applied broadly it would erase price and outcome discipline. Casado himself calls the heuristics rough and acknowledges frequent mistakes. 00:46:29–00:48:22[researcher inference | moderate]a16z benefits from the claim that scale plus specialization plus services is the future of VC. The source provides advocacy and operating description, not a matched comparison against smaller specialist or generalist firms. 00:05:49–00:10:30 and 00:51:47–00:52:32[contemporaneous record | strong]The official Uncapped original is 52:10; the official a16z republication is a 53:28 edit. The navigation transcript is third-party and contains transcription errors, including names. Quotes were kept short and speaker-checked against official audio; all substantive claims are bound to the a16z edit clock.
Open questions
[researcher inference | insufficient public record]What are the ex-ante criteria and error rates for “legit space” and “best team” classifications? Official a16z republication[researcher inference | insufficient public record]How does a16z document conflict capacity, releases, exceptions, and missed later winners? Official a16z republication[researcher inference | insufficient public record]Which services change company outcomes, and how are board fiduciary duties separated from platform activity in practice? Official a16z republication[researcher inference | insufficient public record]Does specialist coverage improve realized cash returns after controlling for firm brand, access, fund size, stage, and price? Official a16z republication
[t] Where Value Will Accrue in AI
- URL: https://a16z.com/podcast/where-value-will-accrue-in-ai-martin-casado-sarah-wang/ | Published: 2025-05-27 | Format: a16z annual LP Summit panel (Erik Torenberg moderating Martin Casado and Sarah Wang) | Reliability: A for official audio and speaker identities; B for unofficial ASR wording used to navigate the audio | Access: full official audio; publisher page has no transcript; full unofficial third-party ASR transcript | Accessed: 2026-08-19 | Locator scheme: elapsed time in the current official Simplecast enclosure; speakers were separated against the audio because the unofficial transcript is not reliably labelled | Version: Simplecast episode
a5a0836e-768a-4874-b2f7-5e45ff9561c2; official duration00:21:41; recorded live at a16z's annual LP Summit
Takeaways
- There is no single AI market [investor-stated | moderate]: Casado argues different technical and commercial subspaces require different strategies; AI should be analyzed as a software-sized set of markets rather than one category. Official panel, Martin at
00:02:45–00:03:20 - Expansion and fragmentation [investor-stated | moderate]: he says fast-growing markets fragment into specialized code, image, video, and text products, so one company's share loss in a submarket does not prove value destruction. The examples are directional and not accompanied by market-share data. Official panel, Martin at
00:03:55–00:05:10 - Wrappers versus software [investor-stated | strong]: a thin prompt wrapper has little independent value, but an application that adds workflow, integration, data, distribution, or brand can accrue value above a commoditizing model. Official panel, Martin at
00:06:49–00:07:21and00:09:51–00:11:37 - Bootstrap is not retention [investor-stated | strong]: generative AI can create fast initial adoption, but Casado says model capability solves only the bootstrap problem; durable value still requires traditional retention and defensibility. He cautions that the available cohort data is noisy. Official panel, Erik question and Martin answer at
00:09:21–00:11:37 - Cursor as market-timing case [retrospective witness | moderate]: Casado attributes Cursor's emergence to market education by GitHub Copilot and VS Code, better coding models, and a strong team, product, and brand—not to a model monopoly. This is favorable portfolio commentary, not an independent attribution study. Official panel, Martin at
00:11:37–00:12:48 - Capital discipline and conflicts [investor-stated | strong]: Sarah Wang—not Casado—warns that very large pre-traction rounds should be “show, not tell,” and that an early weak investment can block a fund from backing a later winner. Casado separately says frontier-model investing requires exceptional teams and capital access and must be approached carefully. Official panel, Sarah at
00:15:57–00:18:22; Martin at00:19:02–00:19:47 - Modern VC translation (as of 2026-08-19) [researcher inference | moderate]: disaggregate AI by market, require retention after the novelty spike, identify a moat outside model access, and model conflict cost before a large early check. Separate Casado's framework from Wang's capital-discipline and conflict observations. Official panel, Martin and Sarah at
00:02:45–00:07:21,00:09:21–00:18:22, and00:19:02–00:20:55
Quotes
- “It just solves the bootstrap problem.” — Martin Casado,
00:10:09. [investor-stated | strong] Official panel - “You have to be very, very careful before you go into it.” — Martin Casado,
00:19:02. [investor-stated | strong] Official panel - “This is a market where heat cannot be confused with momentum.” — Sarah Wang,
00:20:55. [investor-stated | strong] Official panel
Biography and decision evidence
- The publisher identifies the session as a live a16z annual LP Summit panel with Erik Torenberg moderating general partners Martin Casado and Sarah Wang. [contemporaneous record | strong] Co-speaker claims cannot be attributed to Casado or converted into a unified firm view without naming the speaker. Publisher page, title and description
- Casado uses Cursor to describe how category education, platform precedent, model readiness, and team quality can converge at company formation. [retrospective witness | moderate] The discussion does not state the investment date, sponsor, security, price, ownership, or whether these were the ex-ante reasons for a16z's decision. Official panel, Martin at
00:11:37–00:12:48 - Wang describes the portfolio opportunity cost of entering a category too early: conflicts can prevent backing the eventual winner. [investor-stated | strong] This is direct decision-process evidence from Wang and a firm-level risk signal, not proof of Casado's personal practice. Official panel, Sarah at
00:15:57–00:18:22 - Casado says firms that remain too skeptical can become irrelevant, while firms that invest too aggressively can become conflicted and stuck with weak companies. [investor-stated | strong] The stated solution is sophistication and selectivity, but he gives no scoring rule or outcome set. Official panel, Martin at
00:20:17–00:20:55 - No fund, check, security, ownership, reserves, board action, exit, distribution, or realized multiple is disclosed for any company. [researcher inference | strong] Official panel, full recording
Philosophy signals
- Picking / macro [investor-stated | moderate]: avoid one zero-sum AI map; category expansion can support many specialist winners with different technical and commercial moats. Official panel, Martin at
00:02:45–00:05:10 - Picking / risk [investor-stated | strong]: early adoption is insufficient; retention, workflow integration, community, marketplace, brand, and other traditional moats remain the diligence center. Official panel, Martin at
00:09:21–00:11:37 - Portfolio / risk [investor-stated | strong]: category conflicts have option value and opportunity cost; a premature investment may prevent a later, better investment. The evidence belongs to Wang. Official panel, Sarah at
00:15:57–00:18:22 - People [investor-stated | moderate]: Casado treats the quality and capital credibility of the founding team as an especially high bar in frontier models, where financing needs can overwhelm an otherwise promising technical plan. Official panel, Martin at
00:19:02–00:19:47 - Boards / exits [researcher inference | insufficient public record]: the panel discusses value accrual but does not provide governance evidence, exit paths, fund-duration constraints, or realized outcomes. Official panel, full recording
Contradictions, counterevidence, and access limits
- The a16z page offers official audio but no transcript. [contemporaneous record | strong] A full unofficial ASR transcript was used for navigation; selected quotes and speaker boundaries were checked against the official enclosure, and its unlabeled/merged turns were not trusted for attribution. Official panel Unofficial transcript
- Casado says markets are fragmenting but offers no consistent market definition, share series, or revenue pool. [investor-stated | provisional] The claim can be made true or false by changing the boundary between foundation models, modalities, tools, and applications. Official panel, Martin at
00:02:45–00:05:10 - Cursor is an a16z-linked success example presented at the firm's LP event. [contemporaneous record | strong] The causal account is retrospective and promotional; it does not compare failures that also had market education, capable models, and strong teams. Official panel, Martin at
00:11:37–00:12:48 - Casado's China discussion combines upside from open models with a broad claim about weak Chinese enterprise software. [investor-stated | provisional] The panel gives no market data, company sample, or definition of enterprise-software success. Official panel, Martin at
00:18:22–00:19:02 - Wang's caution about huge pre-traction rounds and conflicts complements but also tensions Casado's warning that excessive skepticism creates irrelevance. [researcher inference | strong] The panel identifies both failure modes without specifying how a16z calibrates between them. Official panel, Sarah and Martin at
00:15:57–00:20:55
Open questions
- What revenue and market-share series define the claimed fragmentation across models, modalities, developer tools, and applications?
- What retention horizon and cohort behavior distinguish a solved bootstrap problem from durable product-market fit?
- Which moat outside model access has survived a foundation-model upgrade, and how is its incremental value measured?
- What were a16z's ex-ante Cursor decision memo, sponsor, valuation, ownership, and falsification milestones?
- How does the firm price conflict option value before entering a crowded category, and who can approve an exception?
- What financing threshold, team credentials, and technical evidence make a frontier-model company investable under Casado's “very careful” rule?
- How do board strategy and exit timing differ between fast-fragmenting applications and capital-intensive frontier models?
[t] Why America Must Lead in AI Investment with Senator Young (R-IN)
- URL: https://a16z.com/why-america-must-lead-in-ai-investment/ | Published: 2024-03-05 | Format: Martin Casado interview with U.S. Senator Todd Young; full publisher speaker-labelled transcript and official video, later official podcast edit | Reliability: A for each speaker's views and Casado's biography; B/C for policy forecasts, causal claims, and uncited economic magnitudes | Access: full publisher transcript/video page and full 00:24:55 official podcast edit; unofficial ASR used only for detailed navigation and checked against publisher wording | Accessed: 2026-08-20 | Locator scheme: elapsed time in the official podcast edit (episode 782; GUID 4e317294-f5af-426f-a5e4-327489170cb9; audio UUID 1c1571e1-e2e7-4715-a68f-e503343eedd3), cross-checked to speaker-labelled page transcript | Version: canonical video/page published 2024-03-05; later audio edit published 2024-04-22 adds an editorial introduction/outro and shifts elapsed times
Takeaways
- The policy position is cautious enablement, not no regulation.
[investor-stated | moderate]Young favors technology-agnostic, outcome-focused rules, more government expertise, national-security investment, privacy and consumer protection, allied standards, and study before costly restrictions. Casado's questions are more skeptical of broad precaution, but the two positions should not be collapsed. Official podcast edit, 05:47–07:50, 09:28–10:23, and 20:53–22:35 - Casado sees a doctrine shift from harnessing to fearing technology.
[investor-stated | provisional]Drawing on his government research experience, he argues that U.S. institutions historically invested deeply in talent and technology but now risk treating speculative harm as the starting point. This is a political diagnosis, not a measured time series of federal investment or regulation. Official podcast edit, 08:10–09:08 - His strongest deregulation claim outruns the evidence supplied.
[investor-stated | provisional]Casado says policymakers import internet-era concerns about asymmetric or exponential harms into AI and asserts those risks do not exist with AI. The conversation defines neither risk class nor evidence threshold and later acknowledges low-probability, high-cost scenarios. Official podcast edit, 10:23–12:24 - The growth case is explicitly a forecast.
[investor-stated | provisional]Casado predicts near-zero marginal creation cost will produce another tenfold expansion in value. No horizon, denominator, attribution mechanism, or distribution between labor, users, incumbents, and startups is provided. Official podcast edit, 12:24–12:55 - Young offers a public-investment theory.
[investor-stated | moderate]He treats federal support for basic and applied research, semiconductor capacity, and technical talent as national-security and growth infrastructure while preferring neutral rules around downstream uses. His CHIPS figures are oral advocacy claims and do not establish incremental causal impact. Official podcast edit, 16:16–20:20 - Casado rejects a simple libertarian label.
[investor-stated | strong]He cites Lawrence Livermore, the Department of Energy, and wartime technology programs when calling himself a strong believer in government and national institutions. His disagreement concerns where government should invest versus constrain, not whether it has a role. Official podcast edit, 20:20–20:53
Quotes
[investor-stated | strong]“This is going to be another 10x expansion in value for sure.” — Casado, official podcast edit, 12:24–12:42 (11 words)[investor-stated | strong]“I'm a huge believer in the government.” — Casado, official podcast edit, 20:20–20:40 (7 words)[investor-stated | strong]“They're low probability, high cost, and we need to hedge against them.” — Young, official podcast edit, 22:46–23:22 (12 words)
Biography and decision evidence
[investor-stated | strong]Casado says that as an undergraduate at Northern Arizona University in Flagstaff he conducted Defense Department-funded supercomputing research, which led to a Lawrence Livermore National Laboratory role in a weapons program and later intelligence-community work. Official podcast edit, 08:10–09:08[investor-stated | moderate]He presents those public-institution experiences as the basis for favoring government investment in talent, science, and infrastructure while resisting indiscriminate technology restrictions. That connects biography to a policy judgment, not to a disclosed venture decision. Official podcast edit, 08:10–09:08 and 20:20–20:53[researcher inference | insufficient public record]The event discloses no Casado-led investment, check size, ownership, board action, fund, exit, or realized return. It offers a policy screen—prefer capacity building and use-specific rules—but no evidence that the screen determined a portfolio decision. Full publisher transcript
Philosophy signals
- Tags: macro / risk.
[investor-stated | moderate]Casado prefers institutional capacity, technical expertise, and public R&D over broad ex-ante limits based on speculative harms. Official podcast edit, 08:10–12:24 and 20:20–20:53 - Tags: picking / macro.
[investor-stated | provisional]He treats collapsing creation cost as a large market-expansion signal, but the conversation does not translate gross social value into startup defensibility, margins, or price. Official podcast edit, 12:24–12:55 - Tags: people / boards.
[researcher inference | moderate]Casado values policymakers who learn technical details, distinguish use cases, and revise policy as evidence changes; the interview does not show how he evaluates analogous judgment in founders or boards. Official podcast edit, 04:01–07:50 and 09:28–12:24 - Tags: sourcing / self-interest.
[researcher inference | strong]The interview occurred at an a16z American Dynamism event while a16z invests in AI and policy-relevant companies. That advocacy context does not invalidate the views, but it raises the burden for independent risk and outcome evidence. Publisher page and event framing
Contradictions, counterevidence, and access limits
[contemporaneous record | strong]NTIA's July 2024 open-model report found insufficient evidence for immediate restrictions on widely available model weights, aligning with caution against premature controls. It also recommended audits, disclosures, risk monitoring, government expertise, and preserving the option of future restrictions—more active governance than a simple wait-and-see reading. NTIA report, “Executive Summary,” policy-conclusion and numbered recommendations[researcher inference | strong]Casado's assertion that internet-like asymmetric or exponential risks “do not exist” with AI is not reconciled with Young's acknowledgment of low-probability, high-cost scenarios. Their shared support for study and expertise is better supported by the conversation than categorical safety. Official podcast edit, 10:23–12:24 and 22:46–24:06[researcher inference | moderate]Young's claim that more than $200 billion in private semiconductor investment followed CHIPS before $1 billion of federal release establishes timing, not causation or additionality. Announcements, committed capital, completed capacity, subsidies paid, and counterfactual investment require separate evidence. Official podcast edit, 18:40–20:20[contemporaneous record | strong]The canonical page transcript is complete and speaker-labelled but has sparse timestamps; the later official audio has a stable 24:55 duration. Detailed times came from an unlabeled third-party ASR navigation copy and were checked against publisher text/audio. No raw transcript or media was retained in the repository. Publisher page and transcript
Open questions
[researcher inference | insufficient public record]Which AI risks does Casado regard as genuinely asymmetric, scalable, or unacceptable, and what evidence would change his position? Official episode[researcher inference | insufficient public record]How should policymakers measure whether public research and semiconductor subsidies are additional rather than transfers to investment that would occur anyway? Official episode[researcher inference | insufficient public record]What policy triggers would justify moving from monitoring to mandatory audits, access controls, liability, or restrictions? Official episode[researcher inference | insufficient public record]Which a16z investments benefit from the advocated policy posture, and how are those interests disclosed in policy engagement? Official episode[researcher inference | insufficient public record]How does Casado convert predicted social value expansion into investable company-level value capture? Official episode
[w] AI Talks Leave “Little Tech” Out
- URL: https://www.wsj.com/articles/ai-talks-leave-little-tech-out-homeland-security-adversaries-open-source-board-46e3232d | Published: 2024-05-15 | Format: coauthored opinion essay | Reliability: A for Martin Casado's and Katherine Boyle's visible authorship and headline-level position; content support is insufficient without the article body | Access: partial/paywalled | Accessed: 2026-08-19 | Locator scheme: publisher headline/deck and visible opening only; official a16z author-archive item for title/byline; no stable paragraph locator available and no full body retrieved
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Verified accessible record [contemporaneous record | strong]: Casado's official a16z archive indexes AI Talks Leave “Little Tech” Out and identifies Martin Casado and Katherine Boyle as coauthors; the canonical destination is the WSJ URL dated 15 May 2024. a16z Casado archive, item titled
AI Talks Leave ‘Little Tech’ OutWSJ canonical route, headline-level access - Headline-level position [investor-stated | insufficient public record]: the title asserts that AI-policy conversations omit a constituency called “Little Tech.” The accessible record does not define that term, name the conversations or participants, specify the harm, or expose the authors' proposed remedy; none of those elements may be reconstructed from the headline or URL slug. WSJ canonical route, headline
- Argument, mechanism, and evidence [researcher inference | insufficient public record]: no legitimate full text was retrieved. The WSJ route returned HTTP 403 during this run; a16z's legacy internal route alternates between 301 redirects to
/ai-talks-leave-little-tech-out-2and back; and the attempted public Wayback index/snapshot routes yielded no retrievable text. Therefore this note does not infer a reasoning chain, examples, causal mechanism, or policy test. WSJ canonical route a16z archive, surviving title/byline record - Chronology, not reconstruction [researcher inference | moderate]: seven months later, Casado's fully accessible Base AI Policy on Evidence, Not Existential Angst advocated regulating demonstrated marginal risk rather than hypothetical risk and warned that overreach could impair innovation and competitiveness. That later essay confirms a recurring deregulatory policy concern, but it cannot establish the May article's examples, exact open-source claims, division of authorship, or recommendations. Later primary essay, opening,
Avoiding spurious AI regulations, andAI policy based on reality - Decision evidence [researcher inference | insufficient public record]: the accessible portion supplies no investment-selection rule, no regulatory-cost model, no named company, no ex-ante deal record, and no portfolio outcome. Treating “Little Tech” as an investable category or inferring that regulatory exclusion creates venture alpha would exceed the source. WSJ canonical route, access boundary
- Modern VC translation (as of 2026-08-19) [researcher inference | insufficient public record]: a conditional analyst hypothesis—not an attributed Casado/Boyle rule—is to measure whether proposed AI compliance imposes fixed costs, compute thresholds, reporting duties, or liability burdens that fall differently on startups and incumbents. The source cannot support that checklist until the full essay shows which mechanism the authors actually argued. WSJ canonical route, headline-level access
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- No body-text quotation is promoted. The complete article was not legitimately accessible, and a headline is metadata rather than evidence for an unobserved reasoning chain. [researcher inference | strong] WSJ canonical route
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The official archive establishes a May 2024 collaboration between Casado and Boyle on AI policy. [contemporaneous record | strong] It does not allocate research, drafting, claims, or recommendations between them, so the work must remain jointly attributed. a16z Casado archive, article item
- Boyle's official biography identifies her as an a16z general partner and cofounder of its American Dynamism practice; Casado's official biography identifies him as an a16z general partner leading infrastructure. [contemporaneous record | strong] Their column is financially and institutionally interested advocacy, not an independent policy study. a16z Boyle profile, description a16z Casado profile, description
- The article's place between Casado's December 2023 Senate AI-forum statement and his December 2024 evidence-based-policy essay is relevant intellectual chronology. [researcher inference | moderate] Chronology alone does not prove continuity in mechanism, change in view, or personal primacy over the jointly authored argument. a16z Casado archive, 2024 item Later primary essay
- No accessible material identifies an a16z vehicle, company, check, ownership, sponsor, board action, follow-on, or result. [researcher inference | strong] The article should not be used as evidence that either author acted on the position in an investment decision. WSJ canonical route, access boundary
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- Macro / people [investor-stated | insufficient public record]: the title elevates representation of “Little Tech” in AI discourse, but the constituency, selection principle, and causal importance remain undefined in accessible text. WSJ canonical route, headline
- Risk / macro [researcher inference | provisional]: Casado's later full essay supports a recurring concern that broad AI rules can enable regulatory capture and harm innovation, but backfilling that later reasoning into this jointly authored May essay would be anachronistic. Later primary essay, opening and
Avoiding spurious AI regulations - Sourcing / picking / portfolio / boards / exits [researcher inference | insufficient public record]: none of these investment-process dimensions is visible in the accessible WSJ material. The title cannot support a sourcing preference for startups, a price rule, a portfolio-construction rule, a governance stance, or an exit view. WSJ canonical route, access boundary
Contradictions, counterevidence, and access limits
- The repository's SCOUT annotation records the visible publisher material as touching open source and startup competition, but the exact deck/opening was not recoverable during this run. [contemporaneous record | insufficient public record] This note therefore preserves that topic only as a retrieval lead and does not treat it as content-analyzed evidence. WSJ canonical route, publisher metadata boundary
- Both authors invest through a16z in sectors that may be affected by AI regulation. [contemporaneous record | strong] The accessible article record does not disclose which holdings could benefit, which opponents were considered, or whether the policy would shift risks to users, workers, creators, or competitors. a16z Boyle profile a16z Casado profile
- The headline frames exclusion as a problem, but without the body it is impossible to test whether the authors establish actual exclusion, representative legitimacy, policy capture, or a better decision procedure. [researcher inference | insufficient public record] WSJ canonical route, headline-level access
- A later Casado essay supplies a compatible anti-overreach position, not independent corroboration that the May article's empirical claims were correct. [researcher inference | strong] Repetition shows consistency only after the earlier text is retrieved. Later primary essay
Open questions
- What exact deck and opening paragraphs were publicly visible, and can a legitimate library database, author copy, licensed WSJ access, or archived a16z page recover the full text?
- How do Casado and Boyle define “Little Tech,” which AI-policy venues excluded it, and what evidence establishes exclusion rather than ordinary stakeholder selection?
- What mechanism connects the alleged representation gap to competition, security, open-source development, or startup formation?
- Which regulations or proposals do the authors evaluate, against which counterarguments, and what evidence would falsify their position?
- What did each coauthor contribute, and were any a16z portfolio companies or prospective investments used as examples?
- Does the essay propose an operational rule for investors or policymakers, and did either author later revise it after observed outcomes?
[w] America Cannot Lose the Robotics Race
- URL: https://www.a16z.news/p/america-cannot-lose-the-robotics | Published: 2025-09-26 | Format: coauthored newsletter/op-ed | Reliability: A for Martin Casado's and Anne Neuberger's stated views; factual and policy claims require independent verification | Access: full | Accessed: 2026-08-19 | Locator scheme: named headings (
The impossible,Micron tolerance,How the West lost “open vs. closed”,We know where this ends,What we need to do); paragraphs within headings are not numbered
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Central argument [investor-stated | strong]: Casado and Neuberger divide the AI contest into software-based “soft power,” where they say the United States leads, and robotics-based “hard power,” where they say China has assembled a compounding advantage. They advocate lighter US deployment rules, domestic experimentation, and an allied supply-chain strategy spanning the United States, Germany, Japan, and South Korea. Primary op-ed,
The impossibleandWhat we need to do - Mechanism [investor-stated | moderate]: the proposed causal chain runs from manufacturing clusters to colocated component makers and customers; colocation accelerates iteration and tacit process knowledge; deployment generates physical-world training data; better data improves generalist robot policies; improved systems drive more deployment. This is the essay's strongest investable mechanism, but it does not quantify the marginal contribution of cluster density, data, subsidies, labor cost, regulation, or model quality. Primary op-ed,
The impossibleandHow the West lost “open vs. closed” - Hardware bottleneck [investor-stated | moderate]: harmonic reducers illustrate the authors' claim that robotics advantage depends on precision components, integration, and supplier proximity—not merely foundation models. They extend the point across bearings, boards, encoders, sensors, motors, shielding, thermal materials, and housings, arguing that a weak link can disable the system. Primary op-ed,
Micron tolerance - Evidence used [contemporaneous record | provisional]: the essay cites robot-density rankings, dark factories, harmonic-reducer market shares and prices, Unitree product prices, industrial clustering, US productivity declines, automation at Tesla Nevada, KUKA's acquisition, and component dependencies. Embedded links create retrievable leads, but the article does not reconcile definitions, measurement dates, competing datasets, or the difference between announced capability and sustained production performance. Primary op-ed,
The impossiblethroughWe know where this ends - Policy theory [investor-stated | provisional]: the authors attribute part of the US disadvantage to “permission-first” regulation, union resistance, and new AI or copyright requirements. Their remedy assumes deregulation will increase both robotics supply and customer adoption without unacceptable safety, labor, security, or concentration costs. No policy comparison estimates the size of those effects or tests less sweeping reforms. Primary op-ed,
How the West lost “open vs. closed”,We know where this ends, andWhat we need to do - Decision rule [researcher inference | moderate]: for a robotics investment, diligence the whole learning system—component access, supplier geography, integration yield, deployment permissions, customer sites, real-world data rights, serviceability, and iteration speed—not the demo or model alone. The rule is derived from the essay's cluster-and-data mechanism; the authors do not present it as an explicit IC checklist. Primary op-ed,
The impossible,Micron tolerance, andWe know where this ends - Modern VC translation (as of 2026-08-19) [researcher inference | moderate]: require a bill-of-materials risk map, single-country and single-supplier exposure, observed component failure rates, production yield, repair time, deployment utilization, teleoperation burden, data-rights contract, regulatory milestones, and a learning-curve experiment. Treat allied re-shoring as a scenario with cost and schedule sensitivities, not as a guaranteed policy tailwind. Primary op-ed,
Micron toleranceandWhat we need to do
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “the country with more robots gains flywheel momentum” — Casado and Neuberger,
The impossible, final paragraph. [investor-stated | strong] Primary op-ed - “Ecosystems can’t be built in a day.” — Casado and Neuberger,
What we need to do, paragraph 3. [investor-stated | strong] Primary op-ed - “We need to go from permission-first to permissionless.” — Casado and Neuberger,
What we need to do, paragraph 2. [investor-stated | strong] Primary op-ed
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The page identifies Martin Casado and Anne Neuberger as joint authors; its author metadata describes Neuberger as an a16z strategic adviser. [contemporaneous record | strong] The public text does not allocate research, drafting, quantitative claims, or policy recommendations between them, so none should be attributed to Casado alone. Primary op-ed, byline and author metadata
- The essay extends Casado's 2024 open-source and AI-policy advocacy into a September 2025 thesis about physical AI, industrial capacity, and national security. [researcher inference | moderate] Chronology establishes an expansion of subject matter, but not whether Casado changed his investment process or whether Neuberger supplied the national-security framing. Primary op-ed,
The impossibleandWhat we need to do - The authors name World Labs as a US leader in spatial-intelligence models; Casado's current a16z biography lists him on World Labs' board. [contemporaneous record | strong] The mention is therefore not neutral sector commentary, and the article does not disclose company-specific economics or how World Labs entered the portfolio. Primary op-ed,
The impossiblea16z Casado profile, current board list - The piece names no investment date, a16z vehicle, sourcing role, sponsor, check, security, ownership, reserves, governance action, or exit. [researcher inference | strong] It is evidence of a jointly authored sector thesis and policy preference, not proof that the thesis drove a particular deal or produced returns. Primary op-ed, full text and disclosures
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- Picking / macro [investor-stated | moderate]: strategic advantage emerges from a stack—models, precision parts, integrators, manufacturing customers, infrastructure, labor, deployment data, and permissive rules. A startup with an impressive model but no route into that stack may lack the iteration loop the authors value. Primary op-ed,
The impossiblethroughHow the West lost “open vs. closed” - Sourcing / picking [researcher inference | moderate]: cluster proximity is a sourcing signal because it can expose supplier knowledge, use cases, and faster build-test cycles. The article supports this industrial mechanism but does not show that Casado sources companies geographically or that cluster location independently predicts venture outcomes. Primary op-ed,
The impossibleandHow the West lost “open vs. closed” - Risk [investor-stated | strong]: robotics supply-chain diligence must reach component level; nominal US assembly can still depend on Chinese refiners, lenses, sensors, or other upstream inputs. Primary op-ed,
Micron toleranceandWe know where this ends - Portfolio / boards [researcher inference | insufficient public record]: the World Labs mention and Casado board role create a disclosed-in-the-record exposure, but the essay offers no rule for concentration, conflicts, information sharing, capital allocation, follow-ons, or governance across a robotics portfolio. Primary op-ed,
The impossiblea16z Casado profile, current board list - Exits [researcher inference | insufficient public record]: a national effort to build decade-scale industrial capacity may conflict with venture fund time horizons, yet the authors do not address capital duration, exit markets, hardware working capital, or the return profile needed to finance the proposed ecosystem. Primary op-ed,
The impossibleandWhat we need to do
Contradictions, counterevidence, and access limits
- The essay credits China simultaneously with state subsidies and an “open,” intensely competitive domestic market while also calling that market opaque and controllable by the CCP. [researcher inference | strong] Those conditions can coexist, but “open” is being used as low-friction entry and competition inside a politically bounded market, not transparent or reciprocal access. Primary op-ed,
How the West lost “open vs. closed” - The argument favors competition from Chinese suppliers, then warns those suppliers may oversupply niches until competitors become uneconomic. [researcher inference | strong] The policy prescription needs a missing boundary between productivity-enhancing imports and dependencies that destroy domestic capacity. Primary op-ed,
We know where this endsandWhat we need to do - Robot density, component share, automation, productivity, and price claims use different denominators and dates. Full text was accessible, but this note does not promote those figures into verified facts without opening and reconciling each underlying dataset. [contemporaneous record | provisional] Primary op-ed,
The impossiblethroughWe know where this ends - The “more robots → more data → better policies → more robots” loop assumes deployers can legally collect, combine, and reuse representative data and that real-world data is a binding constraint. It may be weakened by simulation, shared foundation models, privacy limits, task heterogeneity, data silos, or hardware reliability. [researcher inference | moderate] Primary op-ed,
The impossible - Casado has a current World Labs board role, and both authors are associated with a16z; the publisher's general disclosure says posts may mention portfolio companies and are financially interested material. [contemporaneous record | strong] Readers should not treat the industrial-policy thesis or company example as independent research. Primary op-ed,
The impossibleand disclosures a16z Casado profile
Open questions
- Which robot-density dataset, robot definition, population or worker denominator, and observation year support each country ranking?
- How much of China's advantage is explained by cluster density, subsidies, labor, domestic demand, procurement, regulation, trade policy, or access to components, and what evidence separates those effects?
- What portion of a representative humanoid or industrial robot's bill of materials can the proposed allied bloc supply today at required cost, yield, volume, and lead time?
- What specific “permission-first” rules delayed US deployments, by how long and at what cost, and which safety or labor outcomes would change under the proposed alternative?
- What data rights and feedback metrics distinguish a compounding deployment loop from mere installed-base scale, and can a startup retain that advantage when customers own the data?
- Which Casado-linked robotics or spatial-intelligence investments were made under this thesis, who sponsored and approved them, and what ex-ante milestones would falsify the thesis?
- How do ten-year industrial capacity goals fit a16z vehicle duration, reserves, follow-on needs, hardware working capital, and plausible exit paths?
[w] Base AI Policy on Evidence, Not Existential Angst
- URL: https://a16z.com/base-ai-policy-on-evidence-not-existential-angst/ | Published: 2024-12-16 on a16z; originally 2024-12-14 in Fortune | Format: first-person policy commentary/republication | Reliability: A for Martin Casado's stated view; empirical and policy claims require independent support | Access: full on a16z; Fortune original not required for content and version parity was not independently line-compared | Accessed: 2026-08-19 | Locator scheme: “Avoiding spurious AI regulations,” “AI policy based on reality,” and linked original-publication note; no stable paragraph numbers
Takeaways
- Authorship and version boundary [contemporaneous record | strong]. Martin Casado is the sole named author on the full a16z republication dated December 16, 2024; the page says it originally appeared in Fortune, whose source-map record is dated December 14. This note analyzes the accessible republication and does not assume word-for-word parity with the original. Base AI Policy, byline and original-publication note
- Central argument.
[investor-stated | moderate]New AI-specific regulation should address demonstrated marginal risk—harm added by AI relative to existing computer systems—rather than fears attached to the technology category. Attribution is direct, while the policy support is mixed; the single moderate grade reflects the complete claim. Existing law should remain the baseline until evidence shows a new risk class requires a different regime. Base AI Policy, opening and “AI policy based on reality” - Mechanism.
[investor-stated | moderate]A marginal-risk screen is intended to concentrate research and enforcement on incremental harms, avoid duplicative rules, reduce regulatory capture, and avoid approaches that Casado analogizes to failed attempts to regulate mathematics or mandate cryptographic backdoors. Base AI Policy, “Avoiding spurious AI regulations” - Supporting examples. Casado points to GPT-2 release fears, predicted 2024 election deepfake effects, safer autonomous driving, medical diagnosis, and benefits in creative work/biotechnology.
[investor-stated | provisional]These examples do not share a common outcome measure, and an absence of a cited “meaningful” election case is not a comprehensive risk denominator. Base AI Policy, “AI policy based on reality” - Policy source [researcher inference | moderate]. The expert statement Casado cites also recommends a marginal-risk framework, but it calls for comprehensive study spanning discrimination, scams, misinformation, sexual abuse material, cybersecurity, environmental, biosecurity, and extreme risks. It therefore supports evidence-building more clearly than a blanket conclusion of safety or nonregulation. A Path for Science- and Evidence-based AI Policy, recommendation
- SB 1047 context. Governor Newsom's veto message rejected a compute-threshold design that ignored deployment risk, but also said California must not wait for catastrophe, safety protocols and proactive guardrails are needed, and empirical regulation remains legitimate.
[contemporaneous record | strong]The veto supports risk-sensitive design, not the proposition that AI regulation generally lacks a problem to solve. Newsom SB 1047 veto message, pp. 1–2 - Decision evidence.
[researcher inference | moderate]For policy diligence, define the baseline technology, incremental capability/exposure, affected population, harm severity/probability, and why existing law cannot handle it; then choose a deployment- and risk-sensitive intervention with measurement and revision. That operationalization is consistent with the essay but is researcher-created, not a quoted Casado checklist. Base AI Policy, “Avoiding spurious AI regulations” and “AI policy based on reality” - Modern VC translation (as of 2026-08-19).
[researcher inference | moderate]A venture investor should map each company's compliance exposure by use case and jurisdiction, fund measurable safety/evaluation work, and model both regulatory overreach and under-regulation. “No demonstrated marginal risk” should trigger research and monitoring, not be treated as proof of zero risk—especially when systems are hard to evaluate and consequences may be asymmetric. The 2024 international scientific report found well-evidenced present harms alongside debated severe future risks and limited assurance methods. International AI Safety Report interim, Executive summary and §5
Quotes
[investor-stated | strong]“focus on marginal risk and apply our regulatory energy there.” — Casado, opening (10 words)[investor-stated | strong]“We should only depart from the existing regulatory regime” — Casado, “AI policy based on reality” (9 words)
Biography and decision evidence
- The contributor block identifies Casado as a general partner leading a16z's infrastructure practice while he advances a deregulatory, pro-investment AI argument. [researcher inference | moderate] That is direct evidence that policy became part of his public investing-era agenda by late 2024. Base AI Policy, contributor block
[documented behavior | strong]Casado intervened in a live post-SB-1047 debate with a reusable analytical distinction—marginal versus inherited risk—and linked an expert statement supporting study of that distinction. Base AI Policy, opening through “AI policy based on reality”; expert statement[researcher inference | provisional]The article may support a policy environment favorable to a16z AI portfolio companies, but the public record here does not establish Casado's lobbying role, any company-specific benefit, or personal financial effect. Base AI Policy, byline and contributor block
Philosophy signals
- Tags: risk / macro.
[investor-stated | strong]Compare a technology's incremental harm with the baseline before designing a new regime. Base AI Policy, “Avoiding spurious AI regulations” - Tags: picking / risk.
[researcher inference | moderate]Evidence quality, not narrative intensity, should determine whether a risk changes an investment or policy decision; uncertainty still requires explicit monitoring and a threshold for action. Base AI Policy, marginal-risk argument - Tags: portfolio / macro.
[investor-stated | provisional]Casado prioritizes innovation, competitiveness, and AI's benefits when marginal harm remains unproved. The leap from selected positive examples to “tremendously safe” is broader than the evidence presented. Base AI Policy, “AI policy based on reality” - Tags: people / self-interest.
[researcher inference | strong]A general partner in an AI/infrastructure investor has an institutional economic interest in avoiding rules that raise portfolio-company costs or protect incumbents. That conflict warrants disclosure and adversarial evidence; it does not by itself refute the marginal-risk framework. Base AI Policy, byline/contributor block
Contradictions, counterevidence, and access limits
- Casado asks for evidence-based policy but makes broad negative claims (“not a single meaningful” election example; AI appears “tremendously safe”) without defining meaningfulness, exposure, denominator, or the search used. [researcher inference | moderate] Those assertions do not meet the measurement standard he demands from regulators. Base AI Policy, “AI policy based on reality”
- The cited expert statement calls for study of current and extreme risks across many domains; it does not say policy should wait for realized catastrophe. Newsom's veto likewise supports proactive guardrails while criticizing SB 1047's proxy. [researcher inference | moderate] Expert statement; veto message, pp. 1–2
- The 2024 international report records well-documented fake-content, scam, bias, and privacy harms, plausible cyber risks, disputed catastrophic scenarios, and an inability to guarantee safety. [researcher inference | strong] This counters a unitary “safe versus dangerous” frame while agreeing that evidence and uncertainty must be explicit. International AI Safety Report interim, Executive summary, “Malicious use,” and §5
- Marginal-risk analysis can miss cumulative scale effects, distributional harm, irreversibility, and low-probability/high-severity events when evidence arrives only after deployment. Conversely, broad model-size rules can miss dangerous small/deployed systems—the defect Newsom identified. [researcher inference | moderate] Both failure modes belong in policy design. Veto message, p. 1
- Full a16z text was accessible. The Fortune original was not independently diffed, and the article's external examples were not all audited; this note relies on official/expert counter-sources only for the material policy boundary. [contemporaneous record | moderate] Base AI Policy, byline and original-publication note
Open questions
- What operational threshold of evidence would make Casado support a new AI-specific rule before a realized catastrophe?
- How should marginal risk incorporate exposure growth, correlated failures, irreversibility, and catastrophic severity when frequencies are uncertain?
- What was the defined dataset behind the election-deepfake and GPT-2 outcome claims?
- Which existing laws adequately cover each named harm, where are enforcement gaps, and which risks genuinely require new authority?
- What a16z lobbying, portfolio exposure, or company-specific costs create conflicts around this policy position, and what independent evidence would discriminate public benefit from private advantage?
[w] Bottom Up Pricing & Packaging: Let the User Journey Be Your Guide
- URL: https://a16z.com/bottom-up-pricing-packaging-let-the-user-journey-be-your-guide/ | Published: 2021-03-11 | Format: coauthored operating essay | Reliability: A for the authors' views; company anecdotes and private benchmarks are not independently verified | Access: full | Accessed: 2026-08-19 | Locator scheme: numbered sections #1–#9 and named tier framework; no stable paragraph numbers
Takeaways
- Authorship and scope [investor-stated | strong]. Jennifer Li and Martin Casado jointly write from their experience as board members of early B2B companies. They address product-led/open-source/infrastructure/SaaS pricing, acknowledge product and market dependence, and offer guideposts rather than a universal formula. Bottom Up, byline and opening
- Central argument.
[investor-stated | strong]Pricing and packaging should map the organic path from casual user to professional, team, and enterprise buyer. Unlike top-down sales, the initial user may not control the budget, so the company must identify where value, buying authority, and revenue appear along the journey. Bottom Up, “#1 – Start with the user journey” and “#2 – Figure out where money comes from” - Tier mechanism.
[investor-stated | moderate]Free use creates awareness/qualification; prosumer monetizes individuals where they receive most value; team packaging sells collaboration; enterprise packaging sells security, compliance, administration, integrations, and service. The authors mapped 50 bottom-up company price plans and say many converge on some subset, while noting open-source and prosumer products often omit tiers. Bottom Up, four-tier framework - Sequencing rule.
[investor-stated | moderate]Start with few tiers, observe usage and budget, then add packaging. New tiers are easier to add than remove; the journey is discovered as well as shaped. This preserves learning capacity and avoids an R&D/GTM team serving every segment prematurely. Bottom Up, “#3 – Start simple and expand over time” - Continuity rule.
[investor-stated | moderate]A separate top-down sales motion can sever user acquisition from the buyer funnel, raise friction, and damage organic adoption. Sales should engage qualified accounts emerging from product usage rather than operate as an independent channel. Bottom Up, “#4 – Avoid a discontinuous user journey” - Monetization rule.
[investor-stated | moderate]The authors favor user-base growth over aggressive early charging until repeatable usage or paid-feature boundaries appear. Start with custom high-interest contracts or limited tests; use pricing not only for revenue but to qualify demand and rate-limit distracting enterprise work. Bottom Up, “#5 – Know when to monetize” and “#6 – Use pricing for qualification” - Price metric and iteration.
[investor-stated | strong]Prefer usage pricing when customer value grows with usage, seats when collaboration value grows with users, otherwise established category expectations; avoid a metric that punishes expansion. Test with interviews/A-B experiments and back-test migrations against existing usage to prevent price shock. Bottom Up, “#7 – Figure out the best units,” “#8 – Set the unit price,” and “#9 – Test and iterate” - Decision evidence. The essay cites Superhuman, Airtable, Figma, Notion, Dropbox, HashiCorp, Pulumi, Sentry, Fishtown Analytics, Databricks, GitHub, and Salesforce as illustrations.
[investor-stated | provisional]They demonstrate possible packaging patterns, not causal proof that the recommended rule produced each outcome. Bottom Up, numbered sections #1–#9 - Modern VC translation (as of 2026-08-19).
[researcher inference | moderate]Ask a founder to diagram user, team, buyer, budget, trigger, tier, and sales handoff; then show conversion, expansion, churn, support cost, and gross margin at every transition. Stress whether usage-based charges align value or create bill shock and whether free/AI-heavy use is economically supportable. The framework transfers; the named companies' 2021 packages and anonymous ARR transitions do not. Bottom Up, journey, monetization, and iteration sections
Quotes
[investor-stated | strong]“the user journey is as much something to discover as it is something to shape.” — Li and Casado, “#3 – Start simple…” (14 words)[investor-stated | strong]“Use pricing for qualification (not just monetization)” — Li and Casado, section #6 heading (7 words)
Biography and decision evidence
- Li and Casado identify board work with early B2B companies as the recurring context for the pricing question. [investor-stated | moderate] This is direct evidence of the kind of operating issue they say they encountered, while no board, company, or author-specific intervention is named. Bottom Up, opening
[documented behavior | strong]The coauthors produced an explicit nine-part operating framework and a 50-company pricing-plan map, showing an empirical-comparative orientation to portfolio support. The page does not publish the full coded dataset, longitudinal outcomes, or counterfactuals. Bottom Up, tier map and numbered sections[researcher inference | provisional]The preference for delayed monetization may reflect experience with developer/open-source adoption, but attribution to Casado alone and causal linkage to a particular successful investment remain unestablished. Bottom Up, opening and “#5 – Know when to monetize”
Philosophy signals
- Tags: boards / people / picking.
[investor-stated | strong]Start with observed user behavior and buying authority, not a copied SaaS price page. Bottom Up, sections #1–#3 - Tags: risk / portfolio.
[investor-stated | moderate]Preserve the bottom-up growth engine before extracting revenue; monetization that breaks adoption can destroy the option to reach larger buyers. Bottom Up, sections #4–#5 - Tags: picking / boards.
[investor-stated | strong]Pricing is an experiment and routing signal as well as a revenue mechanism; evaluate willingness to pay, qualification, churn, conversion, and expansion together. Bottom Up, sections #6–#9 - Tags: people / self-interest.
[researcher inference | moderate]Portfolio-support content can help a16z companies and attract product-led founders. The authors' firm affiliation does not prove the advice is biased, but the successful-company examples and absence of a failure denominator make promotional selection plausible. Bottom Up, opening, examples, and contributor blocks
Contradictions, counterevidence, and access limits
- “Grow users before monetization” can conflict with capital efficiency, free-user compute/support costs, and evidence of willingness to pay. [researcher inference | moderate] The authors bound the rule by recommending monetization once repeatable use or paid-feature separation appears, but supply no failure rate for waiting too long. Bottom Up, “#5 – Know when to monetize”
- Enterprise sales is described as dangerous when disconnected from product adoption yet necessary for security, service, and large deployments. [researcher inference | moderate] The actionable distinction is continuity of journey, not “sales bad/product good.” Bottom Up, tier framework and “#4 – Avoid a discontinuous user journey”
- The essay reports anonymous transitions—enterprise overtaking self-service at $10 million ARR for one company and at $2 million for another—without company identity, sample, contract basis, or margin. [researcher inference | moderate] These are examples, not thresholds. Bottom Up, “#2 – Figure out where money comes from”
- The company cases are selected successes and price-page observations; they do not establish that tier design caused growth, nor reveal companies whose similar design failed. Full text was accessible, but the linked 50-company Airtable base was not independently re-coded in this note. [researcher inference | provisional] Bottom Up, opening and linked 50-company pricing map
Open questions
- What is the complete 50-company sample, coding date, and outcome distribution, including failed or revised packaging?
- Which Casado/Li board decisions changed pricing ex ante, and what happened to activation, conversion, NRR, CAC, gross margin, and sales efficiency?
- When do high marginal service or compute costs make delayed monetization destructive rather than protective?
- How should a company detect that the initial user will never bridge to the budget-owning buyer?
- How do contract commitments, usage volatility, and procurement requirements alter the preferred pricing unit today?
[w] The Cloud Killed Infrastructure, Long Live Infrastructure!
- URL: https://a16z.com/the-cloud-killed-infrastructure-long-live-infrastructure/ | Published: 2022-06-09 | Format: first-person essay | Reliability: A | Access: full | Accessed: 2026-08-19 | Locator scheme: opening thesis and distinctive example paragraphs; the page exposes no substantive named H2 sections or numbered figures
Takeaways
[investor-stated | strong]Casado’s central claim is not that hyperscale cloud is ending. He argues that its success creates a second-order market for “vertical clouds”: specialized infrastructure services that optimize a particular workload more deeply than a general platform designed for the mean. opening thesis, paragraphs beginning “However, like all architectural epochs” and “However, for the most part”[investor-stated | strong]The proposed causal chain has two enabling conditions. Loosely coupled cloud applications let developers compose services from multiple providers, and aggregate cloud demand has become large enough that a formerly subordinate component can support an independent company. Specialization can then justify workload-specific software, operations, networking, and physical infrastructure. opening thesis, paragraphs beginning “These companies are now able to do this” and “And so, in many ways”[investor-stated | moderate]Three examples illustrate rather than validate the thesis: Fly.io and Cloudflare place databases/rendering/collaboration workloads near users on next-generation CDNs; MosaicML represents AI-specific compute and systems; and Mighty integrates selected hardware with Chromium for a browser service. The essay publishes no selection denominator, customer economics, survival comparison, or return outcome. example paragraphs beginning “Front end devs,” “AI is driving,” and “App platforms”[investor-stated | strong]Workload fit is the mechanism of advantage. An AI cloud may change silicon, scheduler, interconnect, and failure handling together; a generalized hyperscaler can offer AI, but must place it beside hundreds of services and may not optimize as deeply for customers whose cost/performance depends on that workload. “AI is driving new hardware build-outs” example[investor-stated | moderate]Casado claims specialized providers tend to be more sophisticated, cost-effective, and performant, and says large centralized clouds are structurally disadvantaged. Those are directional assertions: the article supplies examples but no matched benchmark showing that specialization’s utilization, financing, support, distribution, reliability, or procurement costs are lower in aggregate. opening thesis, paragraphs beginning “Vertical clouds” and “And so, in many ways”[investor-stated | strong]The company-building boundary is unusually explicit: this opportunity is for infrastructure teams able to build scalable systems “from hardware on up,” and easier bare-metal deployment plus OpEx hardware arrangements reduce the financing barrier. Expertise and market size are therefore prerequisites, not afterthoughts. closing paragraphs beginning “Before we wrap it” and “We also want to make the point”[researcher inference | moderate]Investment decision rule: test whether a candidate owns a workload-specific full-stack advantage that a hyperscaler cannot cheaply match without harming generality; whether the reachable service slice is independently venture-scale; whether multi-provider composition is real; and whether utilization, supply, reliability, and GTM survive without hyperscaler cross-subsidy. opening thesis and all three example groups[researcher inference | moderate]Modern VC translation (as of 2026-08-19): use a counterfactual benchmark against the hyperscaler’s best committed price and native service, including developer time, egress, capacity guarantees, financing, uptime, and migration. Observable applicability signals are persistent workload-specific performance-per-dollar, repeatable utilization, portable interfaces, and a market large enough to sustain an independent control plane. paragraphs beginning “Vertical clouds,” “These companies,” and “AI workloads differ”[researcher inference | strong]A likely misuse is to treat every cloud component as a company. Casado’s own logic requires loose coupling, enough aggregate demand, a meaningful specialization frontier, and a team capable of owning the whole infrastructure burden; absent one, the hyperscaler’s distribution and bundling can dominate. opening thesis and closing qualification
Quotes
[investor-stated | strong]“Vertical clouds are on the rise, as traditional clouds give way to specialization.” — opening deck. opening deck[investor-stated | strong]“The large centralized clouds are just another waypoint on the long arc of IT infrastructure.” — opening thesis. paragraph beginning “However, like all architectural epochs”
Biography and decision evidence
[investor-stated | strong]The sole-authored June 2022 essay records Casado, then identified as leading a16z’s infrastructure practice, arguing publicly for specialized infrastructure businesses and direct competition with hyperscaler services. title/byline, thesis question, and contributor block[investor-stated | moderate]The technical frame resembles an operator-engineer’s decomposition—hardware, scheduler, networking, failure modes, and service boundary—yet the essay itself does not attribute that frame causally to Nicira or a named prior experience. AI-specific example[researcher inference | insufficient public record]Fly.io, Cloudflare, MosaicML, and Mighty are showcased, but the article does not identify who sourced or approved any investment, when a16z invested, Casado’s ownership or board role, ex-ante thesis, follow-ons, or outcome. three example groups and disclosure
Philosophy signals
- sourcing / picking:
[investor-stated | strong]seek expert infrastructure teams whose vertical optimization spans enough of the stack to produce a measurable workload advantage. AI example and closing qualification - risk:
[researcher inference | moderate]the diligence burden includes hyperscaler response, component bundling, market size, interface portability, hardware supply/financing, utilization, and operational depth. Casado states only part of this list; financing/utilization risk is an analyst extension of the mechanism. opening thesis and closing paragraphs - portfolio / boards:
[researcher inference | moderate]boards should require workload-level price/performance benchmarks and proof that specialized economics persist after sales, support, reliability, and capacity costs. The essay documents no Casado board implementation. three example groups - macro / exits:
[investor-stated | moderate]hyperscaler scale creates a viable addressable market for component specialists; no exit path, ownership target, or realized return is supplied. paragraph beginning “These companies are now able”
Contradictions, counterevidence, and access limits
[investor-stated | strong]Casado expressly says traditional clouds are not failing, remain early in consuming traditional IT, and should continue growing for decades. That caveat contradicts a literal reading of the headline and confines the thesis to specialized slices. paragraph beginning “This shift, by the way”[investor-stated | moderate]Hyperscalers can and do provide specialized AI services; the proposed disadvantage is organizational breadth, not technical impossibility. The page does not test whether their distribution, procurement position, integrated tooling, or cross-subsidy outweighs a vertical provider’s depth. AI-specific example[researcher inference | strong]The examples are success-selected and outcome-thin. Mighty is described as a favorite and MosaicML as growing in popularity, but the article gives no failures, cohort denominator, comparable economics, or later outcome. three example groups[researcher inference | moderate]As leader of a16z’s infrastructure practice, Casado benefits from broadening the investable surface beyond hyperscalers and from promoting companies in the category. a16z’s disclosure says mentioned investments are nonrepresentative and offers no assurance of profitability. contributor block and article disclosure- Access was full on 2026-08-19. The article’s rendered body has almost no substantive named section headings, so locators use distinctive opening words and example labels; no stable paragraph IDs or numbered figures are exposed. [contemporaneous record | strong] Primary essay, rendered-page locator boundary
Open questions
- What matched price/performance, reliability, utilization, and customer-retention evidence supports each named vertical-cloud example?
- Which component markets were large enough in 2022, and which specialists were later bundled, acquired, or competed away by hyperscalers?
- Which named investment decisions or board actions are attributable to Casado rather than the broader a16z infrastructure team?
- How should an investment committee price hardware supply, capacity financing, and demand volatility against specialization gains?
[w] The Cost of Cloud, a Trillion Dollar Paradox
- URL: https://a16z.com/the-cost-of-cloud-a-trillion-dollar-paradox/ | Published: 2021-05-27 | Format: coauthored analytical essay (Sarah Wang and Martin Casado) | Reliability: A | Access: full | Accessed: 2026-08-19 | Locator scheme: named section/subsection headings, described charts, and linked filing exhibits; figures are not stably numbered
Takeaways
[investor-stated | strong]Wang and Casado frame cloud as a life-cycle tradeoff, not a binary ideology: on-demand capacity and managed services maximize early speed and experimentation, but mature, stable workloads can bear a “flexibility tax” large enough to justify optimization, hybrid deployment, or selective repatriation. opening through “The paradox of cloud”[contemporaneous record | strong]Dropbox is the strongest named exhibit. The essay links the company’s 2018 S-1, which reported nearly $75 million of two-year savings and attributed much of a 33% to 67% gross-margin rise from 2015–2017 to infrastructure optimization plus revenue growth. That record supports a Dropbox case, not the essay’s cross-company generalization. “Unit economics of cloud repatriation: The case of Dropbox, and beyond”[investor-stated | moderate]The general cost case combines practitioner estimates and disclosed commitments: interviewees converged on repatriation costing one-third to one-half of equivalent cloud operation; the selected public-software sample’s committed spend averaged 50% of cost of revenue; and the authors assumed a 50% savings rate. The page does not publish a company-level replication table. “Unit economics…” and “The true cost of cloud”[investor-stated | provisional]The headline valuation bridge is explicitly back-of-envelope: estimated $8 billion cloud spend across 50 selected public software companies, 50% savings, $4 billion recovered gross profit, and a 24–25x 2021 estimated gross-profit multiple imply roughly $100 billion of market capitalization. Extending beyond that sample yields a stated potential greater than $500 billion, not an audited loss or causal outcome. “The true cost of cloud,” charts sourced to filings/a16z analysis and CapIQ as of May 2021[investor-stated | strong]The decision framework is more durable than the headline estimate: make infrastructure spend a KPI visible to engineers; align incentives with recurring savings; optimize continuously; architect portability before lock-in; and repatriate incrementally only for resource-intensive workloads when warranted. Even aggressive interviewees reportedly retained 10–30% or more in cloud. considerations under “The paradox of cloud”[researcher inference | moderate]Investment decision rule: model a company’s workload-by-workload cost frontier across public cloud, committed discounts, owned/colocated hardware, specialized providers, engineering headcount, reliability, latency, security, and migration risk. The option to move has value even if it is never exercised. “The paradox of cloud,” “Think about repatriation up front,” and “Incrementally repatriate”[researcher inference | moderate]Modern VC translation (as of 2026-08-19): do not carry forward the May 2021 gross-profit multiple or 50% savings assumption. Recalculate with current provider pricing, financing, accelerators, workload utilization, depreciation, staffing, outage risk, and valuation regime; use contribution-margin sensitivity rather than a static market-cap multiplier. “The true cost of cloud” and CapIQ date note[researcher inference | strong]The essay’s likely misuse is “leave cloud at scale.” Its explicit position is narrower: cloud remains valuable, full repatriation is an extreme modeling case, and the correct answer varies by company and workload. opening caveat, “The paradox of cloud,” and “Incrementally repatriate”
Quotes
[investor-stated | strong]“You’re crazy if you don’t start in the cloud; you’re crazy if you stay on it.” — “The paradox of cloud.” paradox statement[investor-stated | strong]“When you’re building a company at scale, there’s little room for religious dogma.” — “The paradox of cloud.” first-class-metric prescription
Biography and decision evidence
[investor-stated | strong]In May 2021, Wang and Casado publicly connected infrastructure architecture to company valuation and described their work as an initial decision framework, while expressly declining to recommend repatriation for every company. opening through “The true cost of cloud”[investor-stated | moderate]Their evidence combines public filings, CapIQ, named operators such as Thomas Dullien, and unnamed company/practitioner interviews. The acknowledgements confirm a practitioner network but not a representative sample. “Unit economics…,” “The true cost of cloud,” and acknowledgements[researcher inference | insufficient public record]The essay discloses no Casado-specific sourcing, IC decision, board instruction, company ownership, realized savings, or investment return tied to the thesis. Named vendors and companies are illustrations, not attribution evidence. article and disclosure
Philosophy signals
- picking / risk:
[investor-stated | strong]underwrite architecture as an economic choice with path dependence; penalize systems that cannot move high-cost workloads without a rewrite. opening and “Think about repatriation up front” - sourcing:
[researcher inference | moderate]optimization software, specialized hardware/services, portability, and the layer between cloud hardware and unoptimized code are framed as opportunity zones. This is category advocacy, not performance evidence. “Optimization, optimization, optimization” and conclusion - portfolio / boards:
[investor-stated | strong]expose cloud spend alongside reliability and performance, give engineers economic feedback, and align rewards to recurring savings. “Cloud spend as a KPI” and “Incentivize the right behaviors” - exits / macro:
[investor-stated | provisional]the 2021 valuation argument assumes public markets capitalize extra gross profit at then-prevailing multiples; it should not be treated as a permanent exit rule. “The true cost of cloud,” CapIQ as-of note
Contradictions, counterevidence, and access limits
[researcher inference | strong]The valuation estimate multiplies modeled cost savings by contemporaneous gross-profit multiples; it does not subtract every migration cost, execution delay, reliability/security risk, lost developer velocity, or revenue effect. The authors call it rough and say full repatriation is an extreme case. opening framing and “The true cost of cloud”[contemporaneous record | strong]Dropbox’s gross-margin improvement had two cited causes—infrastructure optimization and revenue growth—so the full 34-point increase cannot be assigned to repatriation. “Unit economics…”[researcher inference | strong]Selection required companies to disclose some cloud use or commitment; private-company claims and practitioner estimates are not independently auditable. The broader >$500 billion extension adds another assumption that half of overall cloud spend belongs to scale technology companies able to benefit. “The true cost of cloud” and company-selection note[researcher inference | moderate]As infrastructure investors, the authors and firm benefit from expanding the perceived opportunity for optimization, portability, specialized hardware, and non-hyperscaler services. a16z discloses that mentioned investments are nonrepresentative and some third-party information is unverified. article disclosure- Access was full on 2026-08-19. The page links key filings, but the 50-company input table, interview transcripts, and model workbook are not provided; figures have no stable numbering. [contemporaneous record | strong] Primary essay, rendered-page access boundary
Open questions
- What were the 50 companies, their disclosed commitments, actual spend, hybrid mix, and observed post-2021 savings?
- How do realized migration cost, depreciation, engineering headcount, reliability, and lost roadmap velocity compare with the assumed 50% savings?
- Which a16z portfolio or board decisions adopted cloud-spend KPIs or portability architecture because of this framework?
- Under what utilization stability, scale, financing, and workload-specialization thresholds does selective repatriation beat discounted cloud today?
[w] The Economic Case for Generative AI and Foundation Models
- URL: https://a16z.com/the-economic-case-for-generative-ai-and-foundation-models/ | Published: 2023-08-03 | Format: coauthored analytical essay/presentation | Reliability: A for the authors' views; illustrative cost comparisons and private-company observations require independent validation | Access: full | Accessed: 2026-08-19 | Locator scheme: named section headings, figures, and examples; no stable paragraph numbers
Takeaways
- Authorship and context [contemporaneous record | strong]. Martin Casado and Sarah Wang jointly wrote the essay in August 2023. It extends an earlier Wall Street Journal argument and contrasts generative AI with prior AI startups; it is not Casado-only evidence and does not disclose a systematic dataset. Economic Case, byline and opening
- Historical diagnosis.
[investor-stated | moderate]Traditional AI could create technical capability without attractive startup economics because rare-case accuracy became disproportionately expensive, errors were costly, humans remained in the loop, human labor was competitive for perception tasks, and incumbent products captured much of the value. Economic Case, “Capability != economics” - Mediocrity-spiral mechanism.
[investor-stated | moderate]A startup automates common cases, hires humans for the tail, prioritizes growth, and then becomes organizationally locked into services-heavy delivery. Revenue can grow while gross margins and scalability remain below software. This is a causal operating model offered by the authors; no cohort outcome analysis is supplied. Economic Case, “The dreaded AI mediocrity spiral…” - Why generative AI might differ.
[investor-stated | moderate]The authors argue that creative, companionship, and iterative copilot uses relax formal correctness; foundation models address many markets; high-value cognitive tasks are expensive in labor terms; and new behaviors plus rapid user/revenue adoption give startups room before incumbents fully respond. Economic Case, “How generative AI and foundation models are different” - Evidence used [researcher inference | moderate]. The essay cites ChatGPT, Midjourney, Character.AI, Janitor AI, Stable Diffusion, and Llama 2 for adoption, then uses image generation and legal summarization as cost illustrations. Several usage/revenue figures are estimates or self-reports, and the authors explicitly call their broad cost comparison “not scientific.” Economic Case, adoption examples and “Let's run the numbers”
- Creation-cost thesis.
[investor-stated | provisional]Their headline analogy is that the microchip lowered marginal compute cost, the internet lowered distribution cost, and generative AI could lower creation cost toward zero. They estimate idealized tasks at three to four orders of magnitude cheaper and two to three orders faster, conditional on task quality and continued scaling. Economic Case, “Let's run the numbers” and “The third epoch of compute?” - Demand/defensibility thesis.
[investor-stated | provisional]Even without an endemic technical moat, falling creation cost plus elastic demand could expand total use enough for firms to build distribution, brand, network, community, or enterprise-sales moats. The Jevons-paradox analogy is a forecast, not proof that every efficiency gain produces jobs, expansion, or investable value capture. Economic Case, “What about defensibility?” - Decision evidence.
[investor-stated | moderate]The implied investment test is to compare the AI system with the full incumbent workflow: error tolerance, human review, time/cost saved, willingness to pay, new behavior, and the path from capability to gross margin and defensibility. The essay contains no disclosed case where this test determined a Casado-led investment. Economic Case, “Capability != economics” through “What about defensibility?” - Modern VC translation (as of 2026-08-19).
[researcher inference | moderate]Underwrite saved workflow cost, not raw token cost. Demand a task-level quality threshold, human-review burden, net retention, inference-inclusive gross margin, and evidence of new or expanded consumption; then stress whether lower prices accrue to the startup, customer, model supplier, or incumbent distributor. The article's strongest transferable contribution is separating capability from economics; its century-scale analogies are not valuation evidence. Economic Case, “Capability != economics,” “Let's run the numbers,” and “What about defensibility?”
Quotes
[investor-stated | strong]“Capability != economics” — Casado and Wang, section heading (3 words)[investor-stated | strong]“Correctness is overrated” — Casado and Wang, “How generative AI and foundation models are different” (3 words)[investor-stated | strong]“None of this is scientific, mind you” — Casado and Wang, “Let's run the numbers” (7 words)
Biography and decision evidence
- The byline establishes collaboration between Casado, then described as leading a16z's infrastructure practice, and Wang, then described as a growth investor across AI, enterprise applications, and infrastructure. [contemporaneous record | strong] This joins technical-market and growth-economics perspectives without revealing which author originated each claim. Economic Case, byline and contributor blocks
[documented behavior | strong]Casado and Wang publicly revisited their earlier skepticism about AI-first startup economics and argued a technological/behavioral discontinuity could change the answer. That is evidence of an evolving public market thesis, not evidence that prior investments succeeded or that the new forecast was correct. Economic Case, opening through “How generative AI…”[researcher inference | provisional]The emphasis on startup value capture and the closing invitation to founders can support sourcing and category formation for a16z. The article does not establish individual financial benefit, decision rights, ownership, or portfolio return. Economic Case, “What about defensibility?” and conclusion
Philosophy signals
- Tags: picking / risk.
[investor-stated | strong]Technical performance is not an investable thesis until correctness, labor substitution, gross margin, scale, and user behavior work economically. Economic Case, “Capability != economics” - Tags: picking / people.
[investor-stated | moderate]A product can avoid services lock-in when users supply iterative feedback and the task tolerates probabilistic output; safety-critical or tail-heavy workflows remain a boundary case. Economic Case, correctness discussion - Tags: macro / portfolio.
[investor-stated | provisional]A large cost discontinuity can create new behavior and markets, allowing many startups to form moats outside the core model. Economic Case, “The third epoch of compute?” and “What about defensibility?” - Tags: people / self-interest.
[researcher inference | strong]Two a16z investors argue that founders should start companies in a category their firm finances. That makes disclosed authorship and optimistic selection important; it does not invalidate the framework, but raises the burden for independent outcomes and downside cases. Economic Case, byline, contributor blocks, and conclusion
Contradictions, counterevidence, and access limits
- The essay's foundational warning—capability does not equal economics—also constrains its bullish conclusion. [researcher inference | moderate] Cheap inference is not cheap reliable completion after evaluation, human review, integration, sales, and liability; the authors acknowledge the models must actually be good enough and do not claim all work will be replaced. Economic Case, “Capability != economics” and “Let's run the numbers”
- The “marginal cost of creation to zero” analogy conflicts with the paper's own nonzero compute examples and with the capital/labor needed to train, evaluate, distribute, and supervise models. [researcher inference | strong] Read “zero” as directional rhetoric, not an accounting claim. Economic Case, “Let's run the numbers” and “The third epoch of compute?”
- Several comparisons hold output scope and quality constant without demonstrating equivalence: one generated image versus professional design, brief summarization versus legal work, or asset generation versus a complete game. [researcher inference | moderate] The essay labels its numbers rough/non-scientific, so an IC must rebuild them around successful outcomes and total workflow cost. Economic Case, “Let's run the numbers”
- Rapid user/revenue anecdotes can show demand but not retention, margin, durable willingness to pay, or venture returns. [researcher inference | strong] Some cited numbers are estimated or self-reported and no denominator of failed products appears. Economic Case, adoption and revenue examples
- Full text and figures were accessible on 2026-08-19. The linked Wall Street Journal precursor was not needed to reconstruct this essay and was not treated as separately analyzed content. [contemporaneous record | strong] Economic Case, rendered-page access boundary
Open questions
- Which 2023 usage and revenue estimates survived later company reporting, and what were retention and inference-inclusive margins?
- For which workflows did generative AI actually eliminate rather than relocate human review and liability?
- Does falling task cost expand consumption enough to improve startup gross profit, or does competition transfer the surplus to users and infrastructure/model suppliers?
- Which new behaviors became durable independent markets rather than features distributed by incumbents?
- Which Casado/Wang investments used this economic test ex ante, and what ordinary or failed cases challenge it?
[w] Emerging Architectures for Modern Data Infrastructure: 2020
- URL: https://a16z.com/emerging-architectures-for-modern-data-infrastructure-2020/ | Published: 2020-10-15 | Format: coauthored technical market map and reference-architecture essay | Reliability: A for the authors' views; third-party market figures and practitioner observations require separate verification | Access: full (original 2020 route; the mapped landing page now foregrounds a later update and links this version) | Accessed: 2026-08-19 | Locator scheme: named section headings, reference-architecture diagrams, and blueprint numbers; no stable paragraph numbers
Takeaways
- Authorship and version boundary [contemporaneous record | strong]. The original page credits Matt Bornstein, Martin Casado, and Jennifer Li and is dated October 15, 2020. The source map's shorter URL now serves an updated version that points back to this original; this note analyzes only the 2020 information set and does not import the update's later observations. Original 2020 essay, byline and opening; updated landing page, version notice
- Central argument.
[investor-stated | moderate]Data infrastructure was becoming a distinct, fast-growing layer because value increasingly came from analyzing and operationalizing data rather than software code alone. The authors sought a common architecture and vocabulary after speaking with hundreds of founders/experts and interviewing more than 20 practitioners about current stacks. Original 2020 essay, opening - Evidence base [contemporaneous record | moderate]. The authors cite 2019 spending, venture-financing, and employment indicators, then derive reference architectures from practitioner interviews. Their headline market figures—$66 billion of 2019 spending, $8 billion raised by 30 selected startups, and $35 billion aggregate value—come from Gartner/PitchBook rather than a reproducible table in the essay. Original 2020 essay, “Massive Growth of the Data Infrastructure Market”
- Architectural mechanism.
[investor-stated | moderate]Analytics systems organized around warehouses and operational/ML systems organized around lakes were beginning to share storage, scale, semi-structured data, transactions, and SQL. The unresolved question was convergence versus persistent parallel ecosystems caused by language and workload differences. Original 2020 essay, “Analytics, AI/ML, and the Great Convergence?” - Three decision blueprints.
[investor-stated | strong]Modern BI minimizes upfront complexity for SQL-centric analytics; multimodal processing trades greater flexibility and large-data cost advantage for time, money, and expertise; a full AI/ML stack maximizes control for scaled, differentiated machine learning but is inappropriate for experiments and low-scale internal work. The authors explicitly frame each blueprint with strengths and disqualifying conditions. Original 2020 essay, “Blueprints for Building Modern Data Infrastructure” - Investment logic.
[researcher inference | moderate]The map turns architectural transition into a sourcing taxonomy: find unstable boundaries, new operational capabilities, and tooling required by complex stacks. But category formation alone does not establish vendor durability; convergence can collapse categories, managed platforms can absorb tools, and practitioner enthusiasm can overstate independent markets. Original 2020 essay, architectural shifts, emerging capabilities, and convergence sections - Decision evidence.
[investor-stated | moderate]For a prospective infrastructure company, ask which blueprint and customer maturity it serves, whether the system is analytic or operational, what indispensable workload it owns, whether warehouse/lake convergence helps or erases it, and how much customer expertise it demands. The essay offers the classification but no disclosed investment outcome validating it. Original 2020 essay, three blueprints - Modern VC translation (as of 2026-08-19).
[researcher inference | moderate]Rebuild the architecture from current deployments rather than treating a 2020 diagram as current. A useful IC test is whether a product removes an operational bottleneck, owns a durable control point, and reduces total system complexity after integration/egress/people costs. The 2020 blueprint remains valuable as a historical baseline and falsifiable forecast; its vendor categories and market totals do not transfer automatically. Original 2020 essay, “Looking ahead”; later updated route, “Updated reference architectures”
Quotes
[investor-stated | strong]“are data warehouses and data lakes on a path toward convergence?” — Bornstein, Casado, and Li, “Analytics, AI/ML, and the Great Convergence?” (12 words)[investor-stated | strong]“doing machine learning at scale is among the most challenging data problems today.” — Bornstein, Casado, and Li, Blueprint 3 (12 words)
Biography and decision evidence
- The contributor block places Casado as a general partner leading a16z's infrastructure practice; the byline names Bornstein and Li as equal coauthors. [researcher inference | moderate] The essay therefore documents a team research program, not individual Casado authorship or decision rights. Original 2020 essay, byline and contributor blocks
[documented behavior | strong]The authors report a two-year field-research process using founder/expert conversations and practitioner stack interviews to move from market growth to technical architecture and actionable deployment blueprints. That is evidence of research method and category mapping, not evidence of returns. Original 2020 essay, opening and “A Unified Data Infrastructure Architecture”[researcher inference | provisional]Casado's infrastructure background plausibly made architecture-first mapping natural, but the source does not allocate interviews, analysis, or investment responsibility among the three authors. Original 2020 essay, byline, opening, and contributor blocks
Philosophy signals
- Tags: sourcing / picking / infrastructure.
[investor-stated | moderate]Architecture change can reveal investable control points, but products must be matched to actual customer sophistication and workloads. Original 2020 essay, architecture and blueprint sections - Tags: risk / portfolio.
[investor-stated | strong]More control and flexibility impose operating costs; an impressive full stack is a poor fit when a simpler managed pattern solves the job. Original 2020 essay, Blueprint strengths and limitations - Tags: macro.
[investor-stated | provisional]Growth in spend, funding, roles, and data use suggested a structural market expansion. The cited figures establish contemporaneous enthusiasm, not independent startup economics or future growth. Original 2020 essay, “Massive Growth…” - Tags: people / self-interest.
[researcher inference | strong]a16z infrastructure investors published a map that can attract founders in a sector they finance. The page's disclosure says portfolio examples may be nonrepresentative and third-party information unverified, which raises selection-bias and promotional-interest limits. Original 2020 essay, disclosures
Contradictions, counterevidence, and access limits
- The essay celebrates proliferating tools while its convergence thesis points toward stack simplification. [researcher inference | moderate] Both can occur sequentially, but a venture thesis must specify whether fragmentation is a temporary exploration phase or a durable source of independent vendors. Original 2020 essay, convergence and “Looking ahead”
- The unified architecture deliberately contains more than most production systems and excludes OLTP, log processing, and SaaS analytics. [researcher inference | strong] It is a possibility space, not an instruction to buy or deploy every box. Original 2020 essay, “A Unified Data Infrastructure Architecture”
- Practitioner interviews are relevant but can bias toward sophisticated early adopters; the essay does not disclose the participant denominator, selection procedure, raw responses, or vendor conflicts. The market-size and funding claims also depend on paid third-party databases. [researcher inference | provisional] Original 2020 essay, practitioner-interview and market-size method
- Full access was obtained through the original
-2020route. The mapped landing page contains a later updated version and should not be cited as if all of its observations were known in October 2020. Image-based vendor labels were not treated as analyzed prose. [contemporaneous record | strong] Original 2020 essay, full version updated landing page, version notice
Open questions
- Which 2020 categories became independent durable vendors, which were absorbed into platforms, and which disappeared?
- Did warehouse/lake convergence simplify purchasing or merely move complexity into new orchestration and governance layers?
- What practitioner sample, company sizes, workloads, and conflicts produced the reference architecture?
- Which Casado-linked investments were sourced through this map, and which ordinary or failed deals test the category thesis?
- How did the authors' later update revise the original forecasts, and what exact evidence caused each change?
[w] The Empty Promise of Data Moats
- URL: https://a16z.com/the-empty-promise-of-data-moats/ | Published: 2019-05-09 | Format: coauthored essay (Martin Casado and Peter Lauten) | Reliability: A | Access: full | Accessed: 2026-08-19 | Locator scheme: named section and subsection headings; figures are embedded without stable figure numbers
Takeaways
[investor-stated | strong]Casado and Lauten separate a true network effect—direct interaction among nodes through an interface or protocol—from a data scale effect, where a larger corpus may improve predictions without making participants directly more valuable to one another. Their falsifiable test is structural: ask what interaction or dependency becomes stronger as each node joins, rather than calling any data flywheel a network. “Data + network effects ≠ data network effects”[investor-stated | strong]Their mechanism against automatic data defensibility has two linked curves: marginally novel data tends to cost more to acquire, secure, clean, and label, while overlapping or long-tail observations tend to add less product value. A rival can therefore approach the useful-data asymptote while the leader bears rising maintenance costs. “Most data network effects are really scale effects” and “Data Acquisition Cost”–“Incremental Data Value”[investor-stated | moderate]The principal empirical exhibit is a permission-shared Eloquent Labs customer-support distribution: the authors report that 20% of data effort yielded roughly 20% use-case coverage and that intent coverage approached a 40% asymptote. This illustrates one domain, not a general base rate for enterprise AI. “Most data network effects are really scale effects,” chatbot figure and accompanying paragraphs[investor-stated | strong]The proposed diligence sequence is operational: identify the minimum viable corpus, estimate the marginal acquisition-cost curve, estimate incremental data value, model freshness/decay, inspect the distribution and error tolerance, compare algorithmic/product improvements with more data, and decide whether quality or quantity matters most. “A practical framework for understanding the data journey”[investor-stated | moderate]Data can still support a moat when access is structurally scarce, exclusive, regulated, trust-mediated, or costly to reproduce; when small accuracy gains materially change adoption; or when hard-won domain learning becomes embedded in product and selling. Equifax, LexisNexis, Experian, pharma, government buyers, and a cancer-screening example define boundary conditions rather than proving a universal rule. “When IS data defensible, and what can you do to manage this?”[investor-stated | strong]The authors’ decision implication is to underwrite the whole defensibility system—differentiated technology packaging, vertical product knowledge, go-to-market control, customer trust, brand, account control, and talent—instead of capitalizing a raw-data claim as if it were self-reinforcing. opening paragraphs and “Wither data moats…”[researcher inference | moderate]Modern VC translation (as of 2026-08-19): request measured learning curves by corpus size, marginal labeling/acquisition cost, decay rate, rights and portability, model sensitivity, customer switching, and competitor catch-up time. Treat “proprietary data” as a hypothesis until those curves reveal either persistent separation or a durable acquisition bottleneck. “Data Acquisition Cost,” “Incremental Data Value,” “Data Freshness,” and “Secure proprietary data sources”[researcher inference | moderate]A likely misuse is to invert the essay into “data never matters.” Its actual claim is conditional: data alone rarely guarantees durability, while certain distributions, access regimes, accuracy thresholds, custody relationships, and product embeddings can make data valuable. “Understand the extent to which data improves your product” and “Secure proprietary data sources”
Quotes
[investor-stated | strong]“There generally isn’t an inherent network effect that comes from merely having more data.” — “Data + network effects ≠ data network effects.” paragraph after the interaction/protocol test[investor-stated | strong]“Data, in this sense, is like a commodity.” — “Data Freshness.” closing sentence of subsection
Biography and decision evidence
[investor-stated | strong]The 2019 essay records Casado and Lauten saying enterprise startups are their focus and acknowledging that they had previously discussed data network effects themselves; this is evidence of a contemporaneous correction or refinement, not proof that Casado alone changed an investment rule. opening paragraphs[investor-stated | moderate]They describe observations across startups and one disclosed Eloquent Labs study, but publish no sample denominator, company identities for most observations, investment memoranda, deal decisions, ownership, or later outcomes. “Most data network effects are really scale effects” and “When IS data defensible…”[researcher inference | insufficient public record]The essay is useful ex-ante underwriting evidence for Casado’s infrastructure/enterprise practice, but it cannot establish which named a16z investment was sourced, approved, priced, or governed according to this framework. article and contributor disclosure
Philosophy signals
- picking / risk:
[investor-stated | strong]prefer mechanisms that keep differentiation from converging; test the cost and value of the next unit of data rather than the current corpus size. “Data Acquisition Cost” and “Incremental Data Value” - sourcing / people:
[investor-stated | moderate]complex vertical markets may reward teams willing to accumulate domain “scar tissue,” provided that learning becomes product or commercial control rather than perpetual bespoke work. “Know the distribution of the data” - portfolio / boards:
[researcher inference | moderate]a board using this model would monitor corpus coverage, acquisition cost, freshness, error tolerance, competitive parity, and alternative moats as operating metrics. The essay does not document Casado imposing that dashboard at a portfolio company. “A practical framework for understanding the data journey” - macro / exits:
[researcher inference | provisional]commoditizing data and algorithms may shift value toward distribution, workflow, brand, trust, and rights; the essay contains no exit timing or return evidence. “Wither data moats…”
Contradictions, counterevidence, and access limits
[investor-stated | strong]The strongest internal counterexamples are explicit: proprietary datasets can dominate for decades, industry structure can restrict supply, compliance can gate access, and small accuracy gains can transform product adoption. These conditions weaken any categorical anti-data-moat reading. “Understand the extent to which data improves your product” and “Secure proprietary data sources”[researcher inference | strong]The central quantitative illustration is a single customer-support study shared by a startup, while many other claims are based on what the authors had observed. The page gives no sampling frame, confidence intervals, matched competitors, or longitudinal outcome test. chatbot figure and surrounding paragraphs[researcher inference | moderate]The authors advise companies and invest in enterprise technology, creating an incentive to frame alternative product, GTM, and verticalization moats as investable work. a16z’s page warns that referenced investments are nonrepresentative and third-party information may not be independently verified. article disclosure- Access was full on 2026-08-19. The HTML supplies stable section headings but no stable paragraph IDs or numbered figures, so locators use headings plus distinctive exhibit descriptions. [contemporaneous record | strong] Primary essay, rendered-page locator boundary
Open questions
- Across what fraction of the authors’ observed enterprise startups did data advantages converge, persist, or reverse, and over what horizon?
- Which portfolio decisions were changed by the minimum-viable-corpus and marginal-data-value framework, and what counterfactual deals were passed?
- How should an investment committee measure exclusivity when customers own, can export, or can license substantially similar data?
- Which later generative-AI writings revise the 2019 assumptions about open models, synthetic data, inference feedback, and customer-data rights?
[w] Growth+Sales: The New Era of Enterprise Go-to-Market
- URL: https://a16z.com/growthsales-the-new-era-of-enterprise-go-to-market/ | Published: 2020-07-29 | Format: coauthored operating essay (Peter Lauten and Martin Casado) | Reliability: A | Access: full | Accessed: 2026-08-19 | Locator scheme: named section headings, numbered failure-mode labels, and linked company exhibits; charts are embedded without stable figure numbers
Takeaways
[investor-stated | strong]Lauten and Casado define “growth+sales” as a sequence, not a compromise: a product-led, bottom-up adoption motion earns end-user pull, then top-down sales converts and expands that installed demand. The claimed shift is rooted in buyer behavior rather than a new technical capability. opening paragraphs[investor-stated | moderate]Their historical/company set—shareware, Netscape, Salesforce, then GitHub, Zoom, Qualtrics, Slack, Atlassian, PagerDuty, Yubico, Stripe, and Plaid—illustrates a pattern but is success-selected. It shows plausibility across categories, not that the motion is predominant or causally superior without a market denominator. opening and “The old world of enterprise go-to-market”[investor-stated | strong]The mechanism attacks three incumbent dependencies. End-user trial can replace months of relationship-led education; simple usability can replace RFP-driven feature accumulation; and internal usage/word of mouth can improve vendor discovery before procurement. Sales still matters for enterprise budget, security, rollout, and expansion. “The old world of enterprise go-to-market” and “New buyer, new motion”[investor-stated | strong]Product quality becomes distribution only when the user can independently reach value. Viral loops, trusted brand, community, an easy adoption/payment journey, and a product that works before heavy implementation are operating requirements—not decorative “PLG” labels. “New buyer, new motion” and Failure Mode #1[investor-stated | strong]The six failure modes form a usable falsification checklist: the product cannot self-serve; paid acquisition buys low-retention users; customer-level revenue hides weak engagement; sales is layered before users pull it in; free usage does not connect to an enterprise buyer or premium value; or sales success causes product/UX neglect. “Growth+Sales in reality: common failure modes,” Failure Modes #1–#6[investor-stated | strong]Measurement must join consumer and enterprise funnels. MAU/WAU/DAU, engagement, retention, persona, and within-logo spread indicate whether free use is durable and approaching an enterprise conversion; ARR, logos, paid seats, and sales metrics alone can conceal inactive deployments and renewal risk. Failure Mode #3[investor-stated | moderate]The timing rule is customer pull: add sales when users request department-wide rollout, premium features, and IT engagement, not merely when management wants faster revenue. GitHub’s reported repository growth is the positive illustration, but the essay does not supply a failed matched company. Failure Mode #4[researcher inference | moderate]Investment decision rule: reconstruct the entire user-to-budget path. Verify independent time-to-value, organic retention and cohort quality, within-account propagation, buyer identity, security/procurement bridge, premium conversion, CAC by motion, and whether adding sales increases conversion without degrading product velocity. “New buyer, new motion” and Failure Modes #1–#6[researcher inference | moderate]Modern VC translation (as of 2026-08-19): what transfers is the dual-funnel method; what does not automatically transfer is the 2020 presumption that end users can bypass centralized controls. Observable applicability requires low-friction authorized trial, persistent organic engagement, multi-user spread, and a premium/security need that maps to a budget owner. “New buyer, new motion” and Failure Modes #1, #3, and #5[researcher inference | strong]The most likely misuse is to optimize free-user volume as if it were distribution. The essay repeatedly makes product love, retention, buyer connection, monetization, sequencing, and continued end-user investment the actual gate. Failure Modes #2–#6
Quotes
[investor-stated | strong]“In growth+sales, all the complexity of the traditional sales cycle collapses into a single decision maker: the end user.” — “New buyer, new motion.” opening paragraph of section[investor-stated | strong]“You don’t change your priorities; you sign up for new ones.” — Failure Mode #6. opening of Failure Mode #6
Biography and decision evidence
[investor-stated | strong]The July 2020 byline is Peter Lauten first and Martin Casado second. The essay says growth+sales changes how “we as investors” evaluate early rounds, making it evidence of joint a16z enterprise-investing criteria rather than a sole-Casado doctrine. byline and opening paragraphs[investor-stated | strong]The operating analysis connects product, user behavior, marketing, sales sequencing, procurement, and investor measurement; it shows Casado’s public scope extending beyond infrastructure architecture to enterprise distribution. “New buyer, new motion” and all six failure modes[researcher inference | insufficient public record]The named companies and exhibits do not establish Lauten’s or Casado’s sourcing, sponsorship, diligence, approval, ownership, board work, follow-on decisions, or realized returns. company examples and article disclosure
Philosophy signals
- picking / sourcing:
[investor-stated | strong]look for independent end-user value, organic love, retention, word of mouth, and an enterprise expansion bridge before paying for a generic PLG narrative. “New buyer, new motion” and Failure Modes #1–#3 - risk:
[investor-stated | strong]identify security/system-of-record constraints, low-retention paid growth, sales mistiming, non-monetizing free use, and product neglect as kill or correction conditions. Failure Modes #1–#6 - portfolio / boards:
[researcher inference | moderate]manage two linked funnels and protect product velocity after sales hiring; require cohort and persona engagement beside revenue dashboards. The essay is prescriptive but documents no Casado-led board implementation. Failure Modes #3, #4, and #6 - exits / macro:
[investor-stated | provisional]the authors predict growth+sales will remain a dominant attack vector through the 2020s, but provide no valuation, exit, or outcome test. “Advantage, startup”
Contradictions, counterevidence, and access limits
[investor-stated | strong]The essay’s strongest boundary is Failure Mode #1: centralized authorization, heavy integration, and department-wide systems of record may make bottom-up adoption structurally unsuitable. This prevents a universal “PLG wins” interpretation. Failure Mode #1[researcher inference | strong]The company cases are selected winners and the causal counterfactuals are not observed. GitHub’s organic growth does not prove sales would have harmed it; Twilio, Slack, Zoom, and Atlassian exhibits show outcomes but not comparable failures or the incremental effect of sequencing. Failure Modes #1–#4 and #6[researcher inference | strong]“The end user” does not literally replace security, procurement, executive budget, or technical deployment. The article later restores those functions through the sales layer; the opening compression is a distribution model, not a full enterprise-buying description. “New buyer, new motion” and Failure Mode #4[researcher inference | moderate]The authors and a16z benefit from presenting a broad new enterprise formation window and from advising startups on how investors evaluate it. The page’s disclosure says referenced investments are nonrepresentative and charts should not support investment decisions. opening investor statement and article disclosure- Access was full on 2026-08-19. Company charts link to contemporaneous presentations/posts but are not stably numbered; their underlying metrics were not independently re-audited for this source note. [contemporaneous record | strong] Primary essay, rendered-page access boundary
Open questions
- What denominator supports the assertion that growth+sales was becoming predominant, and how did cohort outcomes compare with top-down-only companies?
- Which leading indicators best distinguish organic usage that will convert from usage that permanently cannibalizes paid tiers?
- Which Casado or Lauten investments were accepted, rejected, or repriced because of this dual-funnel framework?
- How should the model change where security, data governance, regulated procurement, or AI inference cost prevents low-friction self-service?
[w] Navigating the High Cost of AI Compute
- URL: https://a16z.com/navigating-the-high-cost-of-ai-compute/ | Published: 2023-04-27 | Format: coauthored technical and operating essay | Reliability: A for the authors' views; estimates and anonymous company observations are not independently verified | Access: full | Accessed: 2026-08-19 | Locator scheme: named section headings, dated pricing table, equations, and footnotes; no stable paragraph numbers
Takeaways
- Authorship and scope [contemporaneous record | strong]. Guido Appenzeller, Matt Bornstein, and Martin Casado jointly wrote a dated cost framework for transformer training and inference. It combines simplified FLOP/memory arithmetic, April 7, 2023 cloud-price observations, and private company conversations; it is not a benchmark run or audited cost survey. High Cost, byline, “Why are AI models…” and “Comparing the cloud service providers”
- Central argument.
[investor-stated | moderate]Generative AI was compute-bound because model quality scaled with compute while scarce supply made access and total cost decisive. The authors say they heard demand exceeded supply tenfold and saw companies spend over 80% of raised capital on compute, but openly acknowledge they did not know the true market-wide numbers. High Cost, opening - Cost mechanism.
[investor-stated | moderate]Transformer compute scales with parameter and token counts; memory capacity and bandwidth force model partitioning; training adds backward-pass work across very large corpora; interconnect and utilization then separate theoretical FLOPs from realized cost. The framework is strongly supported as a decomposition, while the numerical estimates remain provisional; the single moderate grade reflects the combined claim. High Cost, “Why are AI models…” and “The time and cost argument for GPUs” - Build-versus-buy rule.
[investor-stated | moderate]Most application startups should initially use hosted models to search for product-market fit; direct infrastructure becomes rational when the model is the product, fine control changes capability or marginal cost, scale is very large, hardware needs are unusual, or geopolitics constrains cloud choice. Their rough owned-data-center threshold is more than $50 million of annual infrastructure spend, explicitly dependent on geography and configuration. High Cost, “External vs. in-house infrastructure” and “The cloud vs. data center build out” - Procurement rule.
[investor-stated | moderate]Compare providers on negotiated all-in price, availability, delivery model, interconnect, egress, and support—not list price alone. In April 2023 the authors observed up to a roughly fourfold on-demand A100 price spread, large-cloud commitments of one to three years, and sometimes better access or terms at specialty clouds. High Cost, “Comparing the cloud service providers” - Workload-fit rule.
[investor-stated | moderate]Choose the smallest model and cheapest hardware that meet the task; latency-insensitive jobs may accept lower-end GPUs, spiky low-retention traffic may merit cheaper service, and optimization/quantization/batching can dominate hardware choice. The authors report 3–4x hardware cost differences and occasional 10x software gains, but those figures are workload-specific observations. High Cost, “Comparing GPUs” and “Optimizing and scheduling models” - Decision evidence.
[investor-stated | moderate]An IC can convert the essay into a compute diligence schedule: workload and latency; training versus inference mix; model/sequence sizes; utilization; provider and chip concentration; commitments; power/egress/interconnect; optimization roadmap; and cost per successful user outcome. The source supplies a framework, not evidence that compute-heavy companies using it outperformed. High Cost, “Considerations for AI infrastructure” - Modern VC translation (as of 2026-08-19).
[researcher inference | moderate]Re-price the entire model with current hardware, token mix, utilization, and contracts; do not copy 2023 A100/H100 availability or dollar thresholds. Stress the business under 10x model-price declines, loss of reserved capacity, a demand spike, and migration to a competing chip/model. What transfers is the workload-level decomposition; the historical price table does not. High Cost, dated price-table caveat and “How will AI infrastructure cost evolve?”
Quotes
[investor-stated | strong]“This means you want to pick the smallest model that solves your use case.” — Appenzeller, Bornstein, and Casado, “Why are AI models so computationally expensive?” (13 words)[investor-stated | strong]“model optimization is still a bit of a black art” — Appenzeller, Bornstein, and Casado, “Optimizing and scheduling models” (10 words)
Biography and decision evidence
- The contributor block identifies Casado as a general partner leading a16z's infrastructure practice, but the three-author byline prevents allocating individual claims. [contemporaneous record | strong] High Cost, byline and contributor block
[documented behavior | strong]The team translates systems concepts—FLOPs, memory, interconnect, precision, scheduling, and utilization—into founder operating choices. This is direct evidence of technical diligence vocabulary within Casado's investing context, not proof of a unique individual edge. High Cost, equations through “Considerations for AI infrastructure”[researcher inference | provisional]The essay favors specialty infrastructure opportunities and notes that infrastructure management can become a competitive advantage, which aligns with the authors' investment remit. It names no deal rationale, decision right, check, board action, or result that would establish documented application. High Cost, hosted-versus-in-house and provider-comparison sections
Philosophy signals
- Tags: picking / risk / infrastructure.
[investor-stated | strong]Unit economics should be derived from the actual workload rather than generic “cost per GPU” or model-size prestige. High Cost, technical framework and GPU-selection criteria - Tags: portfolio / risk.
[investor-stated | moderate]Preserve option value early with hosted services; internalize infrastructure only when control or scale produces a measurable capability or cost advantage. High Cost, “External vs. in-house infrastructure” - Tags: sourcing / picking.
[investor-stated | provisional]Scarcity, heterogeneous workloads, and weak GPU virtualization create openings for specialty clouds and optimization vendors. The essay does not establish duration or returns from those openings. High Cost, provider comparison and optimization sections - Tags: people / self-interest.
[researcher inference | strong]a16z investors who focus on AI/infrastructure are diagnosing markets in which their funds may invest. The page discloses that referenced investments are nonrepresentative and third-party information can include unverified portfolio-company data. High Cost, disclosures
Contradictions, counterevidence, and access limits
- The opening says more compute directly improves product quality and relief is not near, while the ending concedes parameter/data growth may slow, optimization gains matter, and open-source models could erode training cost as a moat. [researcher inference | moderate] Underwrite these as competing scenarios rather than one deterministic curve. High Cost, opening and “How will AI infrastructure cost evolve?”
- The calculation of roughly $560,000 for one GPT-3 training run excludes multiple runs and imperfect utilization; the authors cite a contemporaneous range from $500,000 to $4.6 million. [researcher inference | strong] That spread demonstrates sensitivity to hardware and efficiency assumptions and bars false precision. High Cost, “The time and cost argument for GPUs”
- Anonymous claims—10x excess demand, 80% of capital on compute, $50 million ARR hosted-model apps—lack named samples, denominators, and verification. [researcher inference | strong] They are useful diligence hypotheses but weak outcome evidence. High Cost, opening and “External vs. in-house infrastructure”
- Full text, equations, footnotes, and dated table context were accessible. Some embedded table cells are not stable text locators, so no exact provider price from a graphic is reproduced here. [contemporaneous record | strong] High Cost, rendered-page access boundary
Open questions
- What were the sample size, period, and definitions behind the 10x demand, 80%-of-capital, and hosted-model company observations?
- Which workloads actually achieved the cited optimization gains, at what quality and engineering cost?
- When did owned infrastructure outperform hosted services after depreciation, financing, staffing, power, networking, and idle capacity?
- Did specialty-cloud advantages survive normalization of large-cloud discounts, reliability, and switching cost?
- Which Casado-linked investments used this framework ex ante, and what evidence shows the cost thesis rather than scarcity drove the decision?
[w] Keep the Code Behind AI Open, Say Two Entrepreneurs
- URL: https://www.economist.com/by-invitation/2024/07/29/keep-the-code-behind-ai-open-say-two-entrepreneurs | Published: 2024-07-29 | Format: coauthored guest opinion essay | Reliability: A for The Economist's public attribution to Martin Casado and Ion Stoica and the headline-level position; article-body reasoning remains unresolved | Access: partial/paywalled | Accessed: 2026-08-19 | Locator scheme: canonical publisher headline plus The Economist LinkedIn post body, sentence above the linked By Invitation card; official a16z author-archive item titled
Keep the Code Behind AI Open; no full body or stable article-paragraph locator retrieved
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Verified accessible record [contemporaneous record | strong]: Casado's official a16z archive indexes Keep the Code Behind AI Open under Martin Casado and points to The Economist. The Economist's own public post identifies Martin Casado and Ion Stoica as the two guest-essay writers; the canonical URL dates the essay to 29 July 2024. a16z Casado archive, item titled
Keep the Code Behind AI OpenThe Economist publisher post, body sentence above the linked card Economist canonical route, headline-level access - Headline/excerpt-level position [investor-stated | moderate]: the title advocates keeping the code behind AI open, while The Economist's attributed excerpt says the coauthors argue open source will power AI innovation and remain the most secure software-development approach. The accessible material does not define “open,” distinguish source code from weights or training data, state exceptions, or expose the supporting evidence and policy mechanism. The Economist publisher post, body sentence above the linked card Economist canonical route, headline
- Argument, mechanism, and evidence [researcher inference | insufficient public record]: the Economist route returned an HTTP 403 Cloudflare challenge, and no legitimate full copy, licensed reprint, or responsive Wayback text was recovered. Consequently this note does not infer the article's reasoning, examples, assumptions, counterarguments, or recommendations from search snippets or from the wording of its slug. Economist canonical route, access boundary
- Earlier primary context, not article reconstruction [investor-stated | strong]: Casado's December 2023 Senate statement explicitly argued that open-source AI supports security through public scrutiny, limits regulatory capture, enables academic research, and helps US technological leadership. That statement makes an open-source position visible before the Economist essay, but it does not prove that the July co-speaker, examples, scope, or reasoning were the same. Casado Senate statement, pp. 1–4, especially
Prohibition of Open Source AI - Decision evidence [researcher inference | insufficient public record]: neither the accessible Economist metadata nor the Senate comparison establishes an investment rule, named deal, vehicle, price, ownership, board action, or outcome. A belief that openness benefits competition is not by itself evidence that Casado selected or governed a company because of licensing architecture. Economist canonical route, headline-level access Senate statement, pp. 1–4
- Modern VC translation (as of 2026-08-19) [researcher inference | insufficient public record]: a conditional diligence exercise—not an attributed rule from the inaccessible essay—is to specify which layers are open (code, weights, data, evaluation, interface), the license and revocation rights, reproducibility, contribution governance, security-response process, hosted-service advantage, and monetization path. The full article is needed before claiming that Casado or Stoica endorsed any part of that checklist. Economist canonical route, access boundary
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “Open-source will power innovation in AI” — Casado and Stoica, excerpt attributed by The Economist. [investor-stated | strong] The Economist publisher post, body sentence above the linked card (6 words)
- No article-body quotation is promoted. The publisher excerpt is the only verified text attributed to both coauthors in the accessible record. [researcher inference | strong] Economist canonical route, paywalled body
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- The official a16z archive indexes the route under Casado, while The Economist's public post names Casado and Stoica as the writers. [contemporaneous record | strong] That resolves coauthorship but not which author supplied the thesis, examples, evidence, or wording inside the gated body. a16z Casado archive, article item The Economist publisher post, attribution sentence
- The essay sits within a documented sequence: Casado's December 2023 Senate statement opposed inhibiting open-source AI; the May 2024 WSJ item with Katherine Boyle framed “Little Tech” as excluded from AI talks; and the July Economist headline advocated openness. [contemporaneous record | moderate] This establishes repetition and widening public venues, not independent truth, sole intellectual ownership, or an unchanged mechanism. Senate statement, pp. 1–4 a16z Casado archive, WSJ and Economist items
- Casado's a16z biography identifies him as the firm's infrastructure-practice leader with AI and infrastructure board exposure. [contemporaneous record | strong] His advocacy can align with portfolio and fundraising interests, but the inaccessible essay does not name any benefited company or disclose who selected the examples. a16z Casado profile, biography and board list
- No accessible Economist material identifies an a16z vehicle, company, sourcing or approval role, security, ownership, governance action, follow-on, exit, or result. [researcher inference | strong] The record supports policy chronology only. Economist canonical route, access boundary
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- Macro / risk [investor-stated | insufficient public record]: the headline records a preference for openness, but not its boundary conditions or risk tradeoffs. The full text is required to know whether the authors distinguish research release, commercial deployment, dangerous capability, or regulated use. Economist canonical route, headline
- Macro / people [investor-stated | moderate]: Casado's earlier Senate statement supplies a directly attributable mechanism—distributed scrutiny, resistance to incumbent capture, academic access, and US competitiveness. Those are genuine Casado philosophy signals, but they belong to the Senate record and cannot be quoted as the Economist coauthors' joint reasoning. Senate statement, pp. 1–4
- Picking / sourcing / portfolio / boards / exits [researcher inference | insufficient public record]: the accessible essay metadata contains no company-selection, licensing-diligence, ownership, construction, governance, or exit rule. Open-source advocacy must not be converted into a portfolio strategy without deal evidence. Economist canonical route, access boundary
Contradictions, counterevidence, and access limits
- Coauthorship is resolved to Casado and Stoica, but internal contribution remains unresolved because the article body is gated. [contemporaneous record | strong] The public attribution cannot allocate research, drafting, examples, or reasoning between them. The Economist publisher post, attribution sentence Economist canonical route
- “Open” can describe materially different artifacts and permissions. [researcher inference | strong] Without the body, it is impossible to test whether the article confronts model-weight misuse, dual-use capability, data rights, security disclosure, license enforceability, compute concentration, or the fact that public code alone may not make training reproducible. Economist canonical route, headline-level access
- The Senate statement claims open scrutiny can improve security and that industry advances had solved the “blackbox” concern. [investor-stated | provisional] Those are broad empirical claims requiring adversarial technical evidence; they are not validated merely because a later headline repeats an openness preference. Senate statement, pp. 1–2
- Casado's financial interest as an AI and infrastructure investor strengthens the need for counterevidence on safety, market power, labor, data, and national-security costs. [researcher inference | moderate] The accessible Economist record does not show whether such objections were considered. a16z Casado profile Economist canonical route, access boundary
Open questions
- How does the gated article allocate the thesis, examples, and reasoning between Casado and Stoica, and what contributor descriptions accompany the full byline?
- What does the essay mean by “code”: source code, model architecture, weights, training scripts, data, evaluations, or some combination?
- Which openness mechanism—security, competition, academic access, innovation, national security, or another—does the article prioritize, and what evidence supports it?
- What exceptions or safeguards do the authors accept for dual-use capability, privacy, intellectual property, or operational security?
- Can the full text be recovered through licensed Economist access, an authorized author copy, a library database, or a legitimate archive without bypassing the paywall?
- Which a16z investments or passes applied an open-source diligence rule ex ante, who made the decision, and did later governance or economics validate it?
- Did Casado later revise the 2023 claim that industry advances had solved the AI “blackbox” problem, and what technical evidence would falsify that claim?
[w] Market Annealing: Getting to $10M ARR in Very Early Markets
- URL: https://a16z.com/market-annealing-getting-to-10m-arr-in-very-early-markets/ | Published: 2023-01-11 | Format: coauthored operating essay (Martin Casado and Peter Levine) | Reliability: A | Access: full | Accessed: 2026-08-19 | Locator scheme: named section/subsection headings, numbered quota list, and distinctive metric paragraphs; no stable paragraph IDs
Takeaways
[investor-stated | strong]Casado and Levine define market annealing as a two-sided feedback process: the company changes product, sales, marketing, pricing, and positioning while its actions educate and soften an immature market. It rejects the idea that product-market fit is simply discovered or that naming a category automatically creates pull. opening definition through “Company-market annealing and sales”[investor-stated | strong]The mechanism is iterative rather than scalable at first: product vision produces customer conversations, selling reveals buyer/use-case/pricing constraints, and those observations return to product and messaging. Locking in headcount, quota, channel, or a bottom-up motion before this loop stabilizes magnifies an unproven model. opening feedback-cycle paragraphs and “Learn the right GTM from the market”[investor-stated | moderate]Their central GTM claim qualifies the 2020 Growth+Sales thesis: bottom-up is efficient when it fits, but early technical markets often cannot demonstrate value without a conversation. The market’s buying process, not founder preference for a cheaper/product-led motion, should choose the initial route. “Learn the right GTM from the market”[investor-stated | strong]Founder sales is both distribution and discovery. The authors say founders can often remain central through roughly $4 million ARR and, in examples they observed, through $10 million before a sales leader; two or three differently experienced “renaissance reps” broaden experiments, while weekly cross-functional meetings keep market feedback from fragmenting. “Start with founder sales” and “Scaling sales”[investor-stated | strong]Role design protects technical truth. Account executives qualify opportunities, find budget, position commercials, and navigate procurement; founders or sales engineers take the technical close. Assigning an early AE the whole job risks confusing procurement competence with a repeatable technical sale. “What AEs do in early markets”[investor-stated | moderate]Quotas are hypotheses. The essay suggests first-year quota near 1x loaded rep cost, at least two quarters of base plus commission, incentive pay for completed deals rather than activity, and adjustment after six months; it describes 4–5x loaded cost as the productivity pressure the company may approach. These are experience-derived heuristics, not published cohort percentiles. “Annealing quotas,” numbered list[investor-stated | moderate]The proposed scaling gate is evidence across reps: with three or four senior reps, use the median reaching roughly 70% of quota or 2x loaded cost to reduce outlier distortion. The authors say core infrastructure may take four to five years and place a typical sales-leader hire at $2–4 million ARR for enterprise ACVs of $45,000–$120,000; these figures require context-specific validation. “Scaling sales”[investor-stated | strong]Marketing should amplify learning, not simulate demand. Early product-marketing generalists join field feedback and execution; founders own core messaging; MQL programs, paid acquisition, press, and outsourced demand generation rarely create qualified demand before buyers understand the problem. Limited tests are acceptable where the problem is already searched and the product demonstrates value quickly. “Company-market annealing and marketing” subsections[researcher inference | moderate]Investment decision rule: separate discovery economics from scale economics. Ask which GTM variables remain unknown, what each founder/repetition experiment learned, whether multiple reps reproduce the result, whether technical close and procurement are separately staffed, and what evidence—not board impatience—justifies a sales leader or quota expansion. sales subsections and “Where to go from here”[researcher inference | moderate]Modern VC translation (as of 2026-08-19): retain the staged evidence gates but re-estimate every dollar, ACV, quota, ramp, and time threshold for the product and market. Applicability signals are founder-led technical closes, recurring buyer/use-case patterns, a converging message, and median rep productivity; failure signals are activity without dollars, MQL volume without conversion, and a sales leader hired to discover the motion. “Annealing quotas,” “Scaling sales,” and marketing subsections
Quotes
[investor-stated | strong]“It’s important to remember that the most expensive sales model is one that doesn’t work.” — “Learn the right GTM from the market.” closing sentence of subsection[investor-stated | strong]“If the founder can’t sell it, nobody can.” — “Start with founder sales.” opening of subsection
Biography and decision evidence
[investor-stated | strong]The January 2023 essay is jointly authored by Martin Casado and Peter Levine and repeatedly grounds its rules in companies “we” have seen or worked with. It records a shared a16z infrastructure operating framework, not a solely Casado-authored causal history. byline, sales subsections, and contributor blocks[investor-stated | strong]Relative to 2020’s Growth+Sales essay, this source makes Casado’s public GTM position more conditional: bottom-up is not a default in very early markets, and founder-led outbound learning may precede product-led scale. “Learn the right GTM from the market”[researcher inference | insufficient public record]No named company, full sample, board minute, investment memorandum, IC decision, sales intervention, ownership, or outcome is attached to the reported thresholds. The article cannot attribute a deal result or board action to either coauthor. sales and marketing subsections
Philosophy signals
- picking / sourcing:
[investor-stated | strong]favor founders willing and able to sell, learn, message, and change the company before the market supplies an obvious playbook. opening definition and “Start with founder sales” - risk:
[investor-stated | strong]treat premature specialization of GTM, sales leadership, quota, or demand generation as scaling risk; test replication across several reps and real dollars. “Learn the right GTM,” “Annealing quotas,” and “Scaling sales” - portfolio / boards:
[investor-stated | strong]keep founders involved, use weekly shared-context meetings, hire exploratory generalists, and adjust quotas as evidence changes. “Start with founder sales” through “Annealing quotas” - macro / exits:
[researcher inference | provisional]immature markets may support large companies without ever becoming effortless pull markets; the essay supplies no ownership, reserve, exit, or return rule. opening and “Where to go from here”
Contradictions, counterevidence, and access limits
[researcher inference | strong]The title promises getting to $10 million ARR, while the opening text describes annealing toward the first $30 million and sometimes $100 million; the conclusion returns to the first $10 million. These are rhetorical ranges, not one consistent validated threshold. title, opening definition, and “Where to go from here”[researcher inference | moderate]The essay challenges a generalized bottom-up default, creating a productive tension with Casado and Lauten’s 2020 Growth+Sales account. It resolves the tension conditionally—bottom-up when independent value and buyer behavior permit it; founder-led sales when education and technical close are necessary—but supplies no comparative decision tree or outcome dataset. “Learn the right GTM from the market”[researcher inference | strong]ARR, ACV, quota, ramp, rep count, and elapsed-time thresholds derive from undisclosed experience. Without distributions, failure cohorts, sector/stage splits, gross margin, churn, or capital efficiency, they should be treated as starting hypotheses rather than base rates. “Start with founder sales,” “Annealing quotas,” and “Scaling sales”- “Market annealing” can rationalize years of weak pull after the fact. A disciplined application needs precommitted learning milestones, burn limits, and kill criteria; those are
[researcher inference | moderate]additions because the essay emphasizes endurance but does not specify when to stop. opening and “Where to go from here” [researcher inference | moderate]The authors and a16z benefit from defining prolonged struggle as a fundable company-building process and from positioning investor networks as early pipeline. The disclosure says mentioned investments are nonrepresentative and offers no profitability assurance. “Pipeline rarely comes from marketing early on” and article disclosure- Access was full on 2026-08-19; locators use headings and numbered quota items. The underlying company observations, quota records, and sales outcomes are not provided for independent audit. [contemporaneous record | strong] Primary essay, rendered-page access boundary
Open questions
- What denominator and outcome distribution produced the $4 million, $10 million, 70%, 2x, four-to-five-year, and $2–4 million thresholds?
- What precommitted evidence should distinguish productive annealing from a market that will never support venture-scale economics?
- Which Casado or Levine portfolio decisions hired, delayed, or removed sales leadership under this framework, and what happened?
- How do product-led, open-source, regulated, hardware, and AI-consumption markets require different annealing gates?
[w] The New Business of AI (and How It’s Different From Traditional Software)
- URL: https://a16z.com/the-new-business-of-ai-and-how-its-different-from-traditional-software/ | Published: 2020-02-16 | Format: coauthored essay (Martin Casado and Matt Bornstein) | Reliability: A | Access: full | Accessed: 2026-08-19 | Locator scheme: named section headings and numbered opening list; figures are embedded without stable figure numbers
Takeaways
[investor-stated | strong]Casado and Bornstein argue that many AI companies combine repeatable software with service-like production: material inference/training infrastructure, recurring data work, human review or failover, and customer-specific edge-case handling. Their classification predicts lower margins, less linear deployment, and weaker automatic moats than a conventional “build once, sell many times” SaaS model. opening numbered list and “Software + services = AI?”[investor-stated | moderate]Their financial observations are explicitly anecdotal: AI gross margins often appeared in a 50–60% range versus a stated 60–80%+ SaaS benchmark; cloud could consume 25% or more of revenue; and ongoing manual data work could consume 10–15%. The source note at the end says the AI estimates came from founder interviews, not an identified representative sample. opening paragraphs, “Gross Margins” Parts 1–2, and “Sources”[investor-stated | strong]The cost mechanism has four parts: changing data requires retraining; inference is compute-intensive; rich media expands storage and processing; and regional transfer/serving adds operational expense. Specialized processors and compression may reduce constants, but the authors warn that rising model complexity and accuracy demands could absorb those gains. “Gross Margins, Part 1”[investor-stated | strong]Human labor and compute are substitutes only at the margin, not paths to zero COGS: more automation raises compute, while less automation raises review/failover. Safety, fairness, trust, and then-emerging regulation also make complete human removal an unsafe base assumption. “Gross Margins, Part 2”[investor-stated | moderate]Apparent product-market fit can be false when five to ten early customers conceal a ballooning ML backlog. Open-ended inputs and customer-specific distributions make the long tail a deployment tax; the authors report that 40–50% of intended functionality in products they reviewed could sit in that tail, without publishing the denominator. “Scaling AI systems can be rockier than expected”[investor-stated | strong]Their operator playbook is to minimize per-customer model forks, narrow the problem domain, budget high variable cost, expose model maintenance and human failover in COGS rather than hiding them in R&D, accept a coherent services model when required, preserve architectural optionality, and build ordinary product/distribution/switching moats. “Building, scaling, and defending great AI companies”[researcher inference | moderate]Investment decision rule: diligence AI companies on contribution margin after compute and humans; implementation time and variance by cohort; model reuse across customers; edge-case backlog; data rights; and cost per successful task—not on recurring revenue labels alone. “Gross Margins” Parts 1–2 and “Scaling AI systems…”[researcher inference | moderate]Modern VC translation (as of 2026-08-19): rerun the 2020 cost decomposition with current model/API prices and actual workload mix, but retain its measurement discipline. Falling unit inference cost does not by itself prove improving company margin if usage, reasoning depth, human escalation, or provider dependence rises. “Plan for high variable costs” and “Plan for change in the tech stack”
Quotes
[investor-stated | strong]“But every input needs to be handled, one way or the other.” — “Gross Margins, Part 2.” cost-substitution argument[investor-stated | strong]“Don’t wait for scale, or outside tech advances, to solve the problem.” — “Plan for high variable costs.” practical-advice section
Biography and decision evidence
[investor-stated | strong]In February 2020, Casado and Bornstein identified themselves through a16z as believers actively investing in applied AI and AI infrastructure while publicly challenging software-like margin and moat assumptions. This is a contemporaneous firm-practice statement, not a sole-Casado investment record. opening paragraphs and contributor block[investor-stated | strong]The essay explicitly links its defensibility thesis back to Casado and Lauten’s 2019 data-moat analysis, demonstrating intellectual continuity from marginal data value to AI company economics. “The playbook for defending AI businesses is still being written”[researcher inference | insufficient public record]The source names no complete company sample and discloses no Casado-specific sourcing, sponsorship, IC vote, terms, board intervention, reserve decision, or realized outcome. “Sources” and article disclosure
Philosophy signals
- picking / risk:
[investor-stated | strong]prefer problems with bounded input distributions, shareable models, tolerable accuracy requirements, and measurable automation economics; penalize hidden bespoke labor. “Scaling AI systems…” and practical-advice section - sourcing:
[researcher inference | moderate]infrastructure tools that automate training, improve inference efficiency, standardize workflows, or monitor and secure models are positioned as picks-and-shovels opportunities. The essay predicts a category; it does not establish returns. “Plan for change in the tech stack” - portfolio / boards:
[investor-stated | strong]track real variable cost, model reuse, data distribution, human failover, deployment cycle, and architectural dependence early enough to change product and GTM. “Building, scaling, and defending…” - exits / macro:
[researcher inference | provisional]lower structural gross margins should affect valuation and exit comparables, but the essay provides neither a valuation rule nor outcome evidence. opening margin comparison and conclusion
Contradictions, counterevidence, and access limits
[investor-stated | strong]The authors concede that specialized processors, model compression, active learning, drift detection, and improving models could reduce costs. Their stronger claim is that zero-variable-cost SaaS economics should not be assumed, not that AI economics cannot improve. both “Gross Margins” sections[researcher inference | strong]The 50–60%, 25%+, 10–15%, and 40–50% figures are anecdotal or sample-bounded and date to the pre-generative-AI 2020 stack. They require cohort-matched remeasurement before use as present base rates. opening, both “Gross Margins” sections, “Scaling AI systems…,” and “Sources”[researcher inference | moderate]The conclusion says unfamiliar economics may create large opportunities, which tempers the negative screen: service intensity can generate customer knowledge and market formation, but it can also remain non-scalable custom work. “Embrace services” and conclusion[researcher inference | moderate]Casado and Bornstein were investors advocating continued AI investment, so they had an incentive both to legitimate the category and to define infrastructure/operating gaps as opportunities. a16z warns that examples are nonrepresentative and third-party data may be unverified. opening investment statement and article disclosure- Access was full on 2026-08-19; section headings are stable, but the embedded figures have no persistent numbers and the private-company observations cannot be independently audited from the page. [contemporaneous record | strong] Primary essay, rendered-page access boundary
Open questions
- How did the identified gross-margin and deployment cohorts perform after 2020, and which costs moved from COGS to R&D or vice versa?
- Which current AI workloads share models across customers, and which exhibit persistent customer-specific forks or human escalation?
- Which a16z investment or board decision used this cost decomposition, and what was known at the investment date?
- How do usage-based pricing and third-party model-provider margins change the company-level unit economics described here?
[w] Questioning Margins Is a Boring Cliché
- URL: https://a16z.com/questioning-margins-is-a-boring-cliche/ | Published: 2025-08-21 | Format: coauthored essay | Reliability: A for Sarah Wang's and Martin Casado's stated views; ungraded for uncited market claims | Access: full | Accessed: 2026-08-19 | Locator scheme: named claim headings (
AI apps are not permanently low margin,Unprofitable cohorts do not define overall economics,Apps are not at the mercy of model pricing,Subsidies do not cloud product market fit,AI apps are not just thin wrappers on models,Conclusion); paragraphs within headings are not numbered
Takeaways (evidence-complete bullets in your words; no arbitrary count)
- Central argument [investor-stated | strong]: Wang and Casado reject a static gross-margin screen for AI applications. Their narrower, defensible claim is not that low margins are harmless, but that a point-in-time margin can change through pricing tiers, rate limits, model routing, inference-cost declines, enterprise mix, and product expansion. The essay concedes in its conclusion that persistently low or negative margins can be fatal and should affect valuation. Primary essay, opening and
Conclusion - Reasoning chain [investor-stated | provisional]: introductory unlimited plans create expensive usage; companies segment users, meter heavy consumption, and route tasks to cheaper models; paid-team and enterprise conversion then shifts the revenue mix; higher-value features and proprietary product context may add pricing power. The mechanism is coherent, but the essay provides no company-level cohort table, cost bridge, or audited margin history demonstrating the complete sequence. Primary essay,
AI apps are not permanently low margin,Unprofitable cohorts do not define overall economics, andAI apps are not just thin wrappers on models - Evidence used [contemporaneous record | strong]: the authors invoke Amazon, Netflix, Uber, and DoorDash as earlier businesses that attracted premature margin criticism, then offer unnamed observations from AI applications and model providers. They mention movement from Claude to GPT-5, DeepSeek V3.1, and a claimed 10x–100x-plus range for inference-cost decline over 18 months. None of those quantitative or company claims has a linked dataset in the essay, and historical survivor examples do not establish the base rate for startups that never repaired margins. Primary essay, opening and
Apps are not at the mercy of model pricing - Key assumptions [researcher inference | moderate]: the thesis requires competitive model supply, substitutability across models for enough workloads, sustained willingness to pay, inexpensive distribution from individual users into teams, retention after limits or price increases, and application control over routing and packaging. If frontier quality concentrates, customers resist lower-cost models, enterprise expansion stalls, or supplier prices rise, the proposed margin levers weaken. These assumptions follow from the dependencies the authors themselves identify. Primary essay,
Apps are not at the mercy of model pricingandSubsidies do not cloud product market fit - Decision evidence [investor-stated | moderate]: the essay substitutes a metric sequence for a blanket margin veto: paid conversion, enterprise conversion, cohort usage, revenue retention, and expansion should be tested before deciding whether a subsidized tier is productive acquisition or value destruction. This is usable IC guidance, although the authors publish no thresholds, observation periods, payback requirements, or treatment of shared inference and support costs. Primary essay,
Subsidies do not cloud product market fit - Modern VC translation (as of 2026-08-19) [researcher inference | moderate]: underwrite a margin bridge, not a margin aspiration. Ask for cohort-level inference cost, gross profit after support, rate-limit sensitivity, model-routing quality loss, conversion by plan, enterprise expansion, churn after repricing, and supplier concentration. Approve a low-margin entry tier only if dated experiments show a path to positive contribution margin without damaging retention; do not use prior-cycle winners as a substitute for the applicant company's unit economics. The translation operationalizes the essay's levers while adding falsification tests the article omits. Primary essay, all five claim headings and
Conclusion - Authorship and interest boundary [contemporaneous record | strong]: the page metadata and visible byline identify Sarah Wang and Martin Casado as coauthors. Both are a16z general partners, and the argument concerns the investability of AI applications, so it should be read as financially interested venture advocacy rather than independent margin research. The page does not allocate individual sentences or portfolio observations between them. Primary essay, page byline and contributor biographies
Quotes (each ≤25 words, verbatim, with timestamp or paragraph anchor)
- “margins alone don’t tell the full story.” — Sarah Wang and Martin Casado,
Conclusionparagraph 1. [investor-stated | strong] Primary essay - “pricing and packaging are more strategic margin levers than ever” — Wang and Casado,
Unprofitable cohorts do not define overall economics, paragraph 2. [investor-stated | strong] Primary essay - “Not all startups will succeed.” — Wang and Casado,
Conclusionparagraph 1. [investor-stated | strong] Primary essay
Biography and decision evidence (dated facts, ex-ante information, people/vehicle attribution)
- Published in August 2025, the essay shows Casado working jointly with a16z growth partner Sarah Wang on AI-application economics rather than speaking only from his infrastructure remit. [contemporaneous record | strong] That is evidence of coauthored firm-level thesis work, not proof that Casado originated every claim or led any referenced investment. Primary essay, byline and contributor biographies
- The authors say “many of the leading app companies we're aware of” route queries for margin optimization and that professional users exceeded internal willingness-to-pay models. [investor-stated | provisional] This indicates access to private company information and internal modeling, but the companies, samples, periods, vehicle exposures, and model errors are undisclosed, so neither investment attribution nor forecast accuracy is testable from the essay. Primary essay,
AI apps are not permanently low marginandUnprofitable cohorts do not define overall economics - The article's observable decision rule is to distinguish productive customer-acquisition subsidy from uneconomic consumption using downstream conversion, retention, and expansion. [investor-stated | moderate] It supplies the variables but not the hurdle rates or evidence that these variables governed a named investment decision. Primary essay,
Subsidies do not cloud product market fit - The piece is retrospective about prior technology winners and contemporaneous about 2025 AI applications. It does not freeze an ex-ante information set for a specific deal, identify the a16z fund, name the sponsor, or disclose check, ownership, approval, reserves, or outcome. [researcher inference | strong] It is philosophy evidence, not deal evidence. Primary essay, opening through
Conclusion
Philosophy signals (tags: sourcing / picking / portfolio / boards / risk / exits / people / macro)
- Picking / risk [investor-stated | strong]: do not reject an AI application solely because its current gross margin is low; test whether the cause is a reversible packaging or usage-mix choice and whether users retain and expand after economic controls. Primary essay,
AI apps are not permanently low margin,Subsidies do not cloud product market fit, andConclusion - Picking / macro [investor-stated | moderate]: model-layer competition and declining inference costs create an option for application margins to improve. The piece acknowledges that frontier models can remain more expensive, making the rule conditional rather than a universal secular-cost claim. Primary essay,
Apps are not at the mercy of model pricing - Sourcing / people [researcher inference | provisional]: product-led adoption may function as both product validation and enterprise distribution when individual users introduce a tool into teams. The article supports the mechanism rhetorically, but it does not establish whether Casado uses it for sourcing or which founders executed it successfully. Primary essay,
Subsidies do not cloud product market fit - Picking / risk [investor-stated | moderate]: application differentiation can arise from broader workflow, orchestration across multiple models, product-specific models, and feedback data unavailable to an API provider. This is a proposed path to pricing power, not proof of a durable moat; the article supplies no switching-cost, retention, or competitor-response evidence. Primary essay,
AI apps are not just thin wrappers on models - Portfolio / exits [researcher inference | insufficient public record]: the essay contains no construction, ownership, reserve, governance, or exit rule. It should not be used to infer that a16z tolerates low margins indefinitely, concentrates in such companies, or prices them without a margin discount. Primary essay,
Conclusion
Contradictions, counterevidence, and access limits
- The rhetoric attacks investor pessimism as click-seeking and “ill informed,” yet the conclusion admits low margins can be fatal and should reduce valuation. [researcher inference | strong] The substantive disagreement is therefore about diagnosing transition paths and company-specific evidence, not whether margins matter. Primary essay, opening and
Conclusion - The argument says short-term margin screens would have missed famous winners, but it does not provide the denominator of low-margin startups that failed. [researcher inference | strong] Survivor selection makes the historical analogy inadequate as standalone picking evidence. Primary essay, opening
- The essay invokes an 80/20 enterprise-revenue concentration pattern and 10x–100x-plus inference-cost decline without methods or sources. [investor-stated | provisional] Treat both as authors' claims, not verified base rates or universal forecasts. Primary essay,
Apps are not at the mercy of model pricingandSubsidies do not cloud product market fit - Private observations are not named or reproducible; no gross-margin bridge, cohort table, cash-burn reconciliation, model-quality test, or sensitivity analysis is published. [contemporaneous record | strong] This limits support for the forecast even though access to the full essay and its authorship is clear. Primary essay, all claim headings
- Casado and Wang may hold or advise investments that benefit from a more permissive interpretation of AI-app margins. [researcher inference | provisional] The page establishes their a16z roles but does not disclose which observations concern portfolio companies; any company-specific self-interest remains unresolved rather than presumed. Primary essay, contributor biographies and article body
Open questions
- Which named AI applications underpin the observations about routing, rate limits, enterprise conversion, and professional willingness to pay, and what period-level cohort data can be published?
- What quantitative hurdle converts the authors' metric list into an IC decision: contribution-margin target, payback period, retention floor, enterprise-conversion rate, and time allowed to reach each?
- Do gross margins improve after price tiering and model routing once support, sales, evaluation, and reliability costs are consistently allocated?
- How did customers respond to the cited movements between Claude, GPT-5, and DeepSeek—did model substitution preserve product quality, retention, and willingness to pay?
- Which a16z investments or passes applied this rule ex ante, who sponsored them, and did later company economics validate or falsify the initial margin bridge?
- What failed AI applications form the proper comparison denominator, and which failure modes—supplier concentration, churn, weak expansion, or cash burn—were visible early?
[w] Who Owns the Generative AI Platform?
- URL: https://a16z.com/who-owns-the-generative-ai-platform/ | Published: 2023-01-19 | Format: coauthored market-map essay | Reliability: A for the authors' views; underlying company observations and estimates are not independently verified | Access: full | Accessed: 2026-08-19 | Locator scheme: named section headings and stack diagram; no stable paragraph numbers
Takeaways
- Authorship and information set [contemporaneous record | strong]. Matt Bornstein, Guido Appenzeller, and Martin Casado jointly wrote the essay. It is a January 2023 snapshot built from meetings with “dozens” of founders and large-company operators, not a sole-Casado doctrine or audited market study. The authors explicitly say the stack diagram is an analytical framework rather than a comprehensive market map. Who Owns, opening and “High-level tech stack”
- Central argument.
[investor-stated | moderate]The authors divide generative AI into applications, models, and infrastructure, then ask which layer can both create and capture value. Their provisional answer is asymmetric: infrastructure was receiving much of the money, applications showed rapid revenue but weak retention/differentiation/margins, and model providers had not yet reached comparable commercial scale. Who Owns, opening and “High-level tech stack” - Mechanism.
[investor-stated | moderate]Shared models make many applications substitutable; shared data and architectures threaten model differentiation; shared GPUs make cloud workloads portable. Durable value therefore has to come from specific mechanisms—distribution, workflows, proprietary interaction data, ecosystem, supply, scale, or direct network effects—rather than the label “AI.” Who Owns, app/model/infra sections and “So… where will value accrue?” - Application economics.
[investor-stated | provisional]The authors report observed app gross margins ranging from roughly 50–60% in many cases to 90% in a few, largely because of inference cost, while warning that novelty-driven acquisition and retention were already weakening. The sample, definitions, and company-level data are undisclosed, so these figures are directional private-market observations rather than a base rate. Who Owns, “The first wave of generative AI apps…” - Infrastructure economics.
[investor-stated | provisional]Their rough flow-of-funds estimate is that apps spend about 20–40% of revenue on inference/fine-tuning and model providers about half their revenue on cloud infrastructure, leading them to guess that 10–20% of total generative-AI revenue reached cloud providers. They also claim early model-training rounds could send 80–90% of capital to clouds. These are explicitly rough estimates and must not be promoted into verified unit economics. Who Owns, “Infrastructure vendors touch everything…” - Decision evidence.
[investor-stated | moderate]A venture screen implied by the essay is: map the company's dependency layer; measure retention and gross margin after inference; identify the precise moat; test graduation/vendor-substitution risk; and distinguish temporary GPU scarcity from durable infrastructure advantage. The text supplies the diagnostic questions but no disclosed investment decisions or comparative outcomes proving the screen works. Who Owns, questions in the app, model, and infrastructure sections - Modern VC translation (as of 2026-08-19).
[researcher inference | moderate]Treat the three-layer map as a dependency and bargaining-power worksheet, not a prediction that one layer must win. An IC should request cohort retention, gross margin after all inference/fine-tuning, provider concentration, switching time/cost, owned data rights, and a sensitivity table for model and compute price changes. The essay itself says horizontal and vertical businesses may both succeed depending on end users, which is the boundary condition against a simplistic “infra always wins” reading. Who Owns, “So… where will value accrue?”
Quotes
[investor-stated | strong]“There don’t appear, today, to be any systemic moats in generative AI.” — Bornstein, Appenzeller, and Casado, “So… where will value accrue?” (12 words)[investor-stated | strong]“We’re all learning the rules in real time” — Bornstein, Appenzeller, and Casado, conclusion (8 words)
Biography and decision evidence
- The byline and contributor block identify Casado as one of three authors and, at publication, a general partner leading a16z's infrastructure practice. [researcher inference | moderate] This places the piece inside a collaborative AI/infrastructure research program; it does not allocate particular claims or diligence to Casado individually. Who Owns, byline and contributor block
[documented behavior | strong]The essay records a market-mapping method: interviews with dozens of founders/operators, layer-by-layer economics, explicit unknowns, and falsifiable questions about commoditization, graduation, scarcity, and vertical integration. That documents how the team framed a market in January 2023, not whether subsequent investments followed the framework. Who Owns, opening and section-end question lists[researcher inference | provisional]The repeated emphasis on infrastructure cash flows is consistent with Casado's infrastructure remit, but the public essay does not establish sourcing, approval, ownership, board work, or performance for any a16z deal. Any deal linkage must be proved separately from contemporaneous investment records. Who Owns, infrastructure section and contributor block
Philosophy signals
- Tags: picking / risk / portfolio.
[investor-stated | moderate]Growth without retention, margin, and differentiation is not sufficient evidence of a durable software company. Who Owns, application section - Tags: picking / infrastructure / risk.
[investor-stated | moderate]Underwrite the source and durability of differentiation at every stack layer; do not confuse capital intensity, supply allocation, or early performance leadership with a permanent moat. Who Owns, model and infrastructure sections - Tags: portfolio / macro.
[investor-stated | moderate]A very large end market can support multiple horizontal and vertical winners even when no systemic winner-take-all moat is visible. Who Owns, conclusion - Tags: people / self-interest.
[researcher inference | strong]The authors are a16z investors writing about sectors in which their firm invests. The page's own disclosure says examples may include portfolio companies and that such investments are not representative; readers should treat the map as informed advocacy with potential selection bias, not neutral industry accounting. Who Owns, disclosures
Contradictions, counterevidence, and access limits
- The piece simultaneously calls infrastructure lucrative and defensible while arguing that clouds share GPUs, workloads are often stateless, scarcity will end, and systematic moats are hard to find. [researcher inference | strong] This is a productive tension: observed near-term value capture is not the same claim as durable long-term defensibility. Who Owns, infrastructure section and conclusion
- Its app critique sits beside an explicit concession that margins may improve, hype-driven users may leave, retention may rise, and vertically integrated apps may differentiate. [researcher inference | moderate] The authors therefore present hypotheses and questions, not a stable layer ranking. Who Owns, application section
- The quantitative observations are anonymous, non-reproducible, and drawn partly from companies the authors met; there is no denominator, distribution, cohort definition, or independent audit. [researcher inference | strong] The a16z disclosure further states that third-party information, including portfolio-company information, was not independently verified. Who Owns, opening, app/infra estimates, and disclosures
- Access was full on 2026-08-19, including text and diagram descriptions. Dynamic graphics may contain company labels not represented in extracted text; no claim here depends on an unread image label. [contemporaneous record | strong] Who Owns, rendered-page access boundary
Open questions
- Which January 2023 estimates can be tested against named-company filings or audited unit economics, and how did the 50–60% app-margin observation evolve?
- Did application retention and model-provider graduation risk develop as predicted, and which firms became counterexamples?
- Which a16z investments were actually sourced or led by Casado under this framework, with what ownership, governance, and outcome?
- After normalizing for rebates, commitments, and GPU depreciation, did infrastructure capture remain structurally superior after scarcity eased?
- Can the stack be redrawn around distribution, data rights, and workflow ownership rather than vendor category, and would that better predict bargaining power?