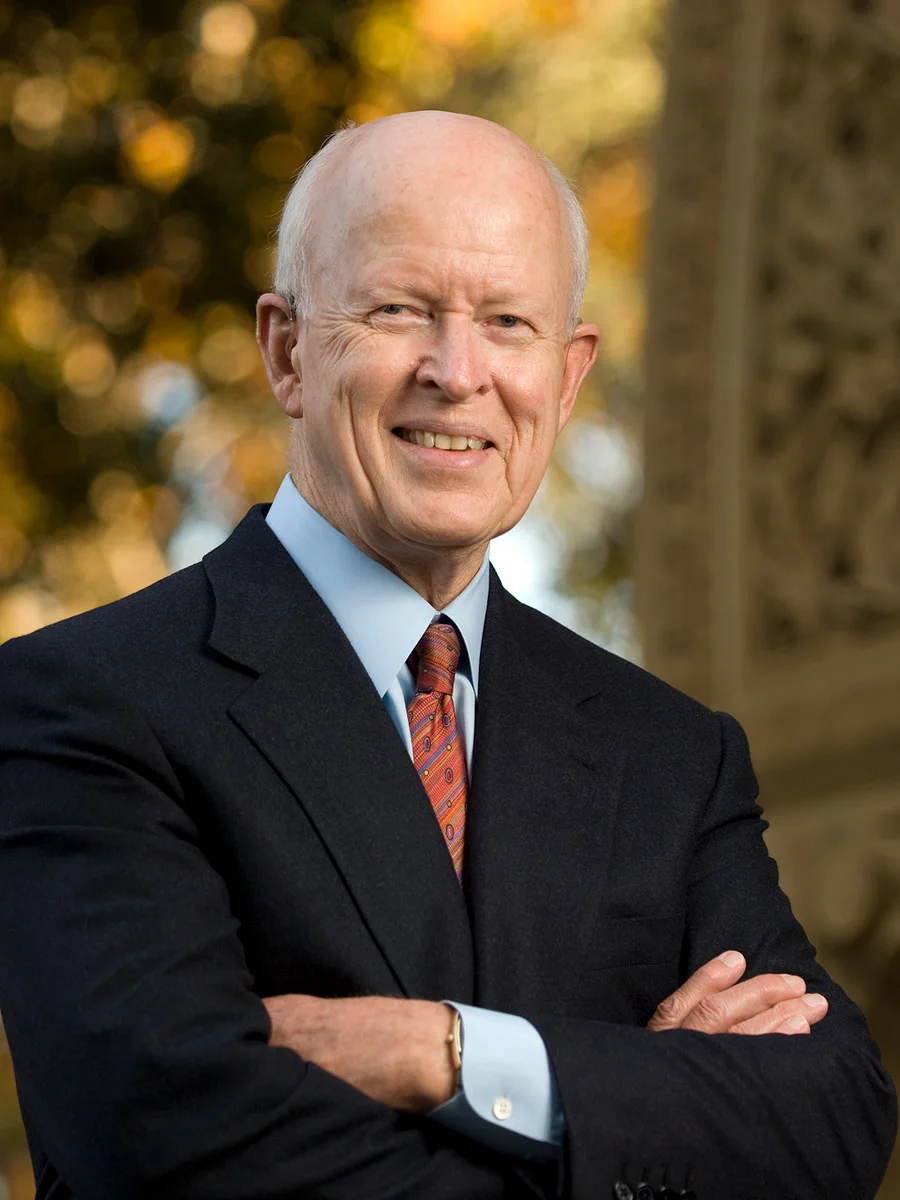
Burt McMurtry
Engineer-investor who helped build PAIC, IVA, and TVI; direct roles include ROLM, Intuit, and VeriFone, while Microsoft/Sun were Marquardt-led.
An engineer enters a capital-starved Valley
Burton J. “Burt” McMurtry's venture career began with engineering, not finance. At Rice, he completed a broad liberal-and-technical course—BA after four years and the then-five-year electrical-engineering program—while participating in the committee that designed Rice's residential-college system. In 1957 he moved to the Bay Area for a Sylvania job that let him study through Stanford's Honors Cooperative Program; working full time, he earned an MS in 1959 and a PhD in 1962 under laser researcher Anthony Siegman. Bancroft oral history, printed pp. 10–19, 01-00:28:37–01-00:53:31. His 1962 paper with Siegman shows an engineer testing a practical photomixing method with available apparatus, but the surviving record does not show McMurtry later claiming that laboratory improvisation as an investment rule. Any lab-to-venture link is researcher inference · provisional. Applied Optics 1(1), pp. 51–53.
Sylvania/GTE supplied a second education: McMurtry moved from microwave and electro-optics research into laboratory and organizational management, and he recruited Rice engineers to the Bay Area. Three future ROLM founders worked for him; he tried to recruit the fourth. Bancroft, printed pp. 24–29. This gave him access to unusually strong technical people before they became founders. It would be easy—but unsupported—to call that access proof of selection skill. The defensible causal chain is narrower: formative technical work → ability to know and assess engineers → access to founder teams combines [documented behavior · moderate] [researcher inference · provisional]; access → superior returns remains unproved without a complete deal denominator.
Melchor, ROLM, and the discipline of attribution
Jack Melchor brought McMurtry into venture capital in 1969. The most famous early case is also the cleanest warning against a lone-genius biography. ROLM's four founders left GTE in 1968–69; Melchor personally became a cofounder, supplied the initial cash and a large loan, and joined a three-person board. In McMurtry's later account, Palo Alto Investment Company was formed around the same month but did not participate in ROLM initially. Bancroft, printed pp. 29–33, 02-00:26:09–02-00:35:02. The founders built the product and business; Melchor supplied original capital and mentoring; McMurtry's contribution at that stage was prior recruiting connection, not original-financier credit. His personal shares and PAIC involvement enter the documented record by the 1975 conflict disclosure; their acquisition date is unknown.
The second ROLM decision came in 1975. After ROLM had a profitable rugged-computer business, it prepared to enter electronic PBX systems. McMurtry spent substantial time on the expansion, judged it promising, and proposed that Institutional Venture Associates invest. Because he already owned shares through his personal/PAIC involvement, he disclosed the conflict, withheld himself from approval, and gave the work to partners Reid Dennis, Burge Jamieson, and Jim Norris. They approved; McMurtry joined ROLM's board. Bancroft, printed pp. 31–32, 02-00:31:55–02-00:33:57. This two-stage case supports a more interesting claim than “McMurtry backed ROLM”: he paired technical-market diligence with explicit conflict-clean decision rights. The process claim is documented behavior · strong for this case; whether it generalized across IVA/TVI remains provisional.
ROLM went public in 1976 and IBM acquired it in 1984. McMurtry later observed that a public buyer could have earned approximately fortyfold by holding from the IPO to the IBM sale, but that is not IVA's audited multiple, does not establish dilution or cash-flow timing, and cannot be used as a personal return. Bancroft, printed pp. 34–35, 02-00:39:47–02-00:41:29. The case is historically important and process-rich; its exact contribution to any fund is not public.
From IVA to a partnership-built TVI
McMurtry formed IVA with Dennis, Jamieson, and Norris in 1973–74, when fundraising and exits were scarce. The $19 million vehicle took about fifteen months to make its first investment, and McMurtry later recalled that the earlier PAIC portfolio had completed sixteen startups, lost money on half, and lost all capital on half—valuable denominator evidence against a smooth-success narrative. Bancroft, printed pp. 34–46. Reid Dennis provides an independent speaker's route for the IVA fund and early market, though both interviews were recorded in 2009 rather than contemporaneously. Dennis oral history.
In 1980 McMurtry, James Bochnowski, and David Marquardt founded Technology Venture Investors. McMurtry said he deliberately sought younger, smarter colleagues for the next phase; all seven IVA institutional LPs, Stanford, and Hewlett-Packard retirement plans entered the first TVI vehicle. Bancroft, printed pp. 46–47, 03-00:15:22–03-00:18:35. Marquardt independently remembered the same three-person founding. Marquardt oral history, p. 22. TVI raised four funds in 1980, 1982, 1984, and 1988; Bob Kagle joined in 1984, biotech work spun into Delphi after Bochnowski left in 1988, and John Johnston joined the information-technology team. Bancroft, printed pp. 47–49.
The team distinction changes the headline deals. Marquardt—not McMurtry—originated TVI's investment in profitable, six-year-old Microsoft and served on its board; McMurtry explicitly credited him in 2009. Marquardt also led the six-month-old Sun Microsystems relationship and served on that board. Bancroft, printed pp. 48–50, 03-00:24:46–03-00:27:21. Microsoft's prospectus identifies TVI 1/2/3 holdings and Marquardt, but the disclosed shares are entity holdings, not Marquardt's or McMurtry's personal property. Microsoft prospectus, “Principal and Selling Stockholders,” p. 30. Microsoft and Sun therefore support TVI access and Marquardt-led selection, not a McMurtry-specific deal-picking edge.
McMurtry's clearer individual operating case at TVI is Intuit. Intuit was already profitable when it raised capital in 1990. Gordon Davidson later recalled five offers at roughly $50 million to $75 million valuations and advising founders Scott Cook and Tom Proulx to accept the two lowest-priced offers—John Doerr and McMurtry—because anticipated board value could exceed the price difference. Davidson, “The Ins and Outs of Financing a Company,” PDF p. 1. A 1997 proxy contemporaneously confirms McMurtry had joined Intuit's board in August 1990 and served on its audit committee; his reported shares were a family trust and options, not TVI holdings. Intuit 1997 DEF 14A, “Directors/Nominees,” “Board of Directors Meetings,” and beneficial-ownership footnote 6. The sources support selection for perceived board value and long governance tenure, but not a causal claim that McMurtry produced Intuit's success or a public TVI return multiple.
An operating system with an admitted blind spot
McMurtry stated his ordering plainly in 1984: the people were the critical element, followed by the market and then technology. JEC hearing, printed p. 203/PDF p. 207. The 1990 TVI presentation adds three contemporaneous firm criteria—differentiated technology, an opportunity to dominate a market, and outstanding management—plus an active-investor posture that offered advice without operating the company. TVI presentation, pp. 5–9. Together these sources make the philosophy [investor-stated · strong] [contemporaneous record · strong]. They do not establish its return efficacy.
The important qualification comes from McMurtry himself. In the 2009 oral history, he said his attraction to people led him to mistakes when he was insufficiently realistic about market opportunity. Bancroft, printed pp. 37–38, 02-00:48:12–02-00:54:12. DAVID Systems is the clearest self-critique: McMurtry recalled joining its board around 1984 and spending roughly a decade trying to find a compelling application despite effort and capital. Bancroft, printed pp. 50–51, 03-00:29:05–03-00:32:43. That is evidence that a people/technology preference needed an independent market veto; it is not proof he institutionalized one afterward.
TVI also framed partner attention as scarce. McMurtry said the team should raise only what it could deploy effectively and warned that excess capital pushes funds toward larger checks and later stages. Bancroft, printed pp. 47–48, 03-00:19:00–03-00:22:37. The 1990 deck's active-support promise is consistent with that account. The mechanism—board-intensive help consumes partner capacity—is investor-stated · moderate; the searched public record lacks time-allocation data and cannot show that TVI's fund-sizing choices caused returns.
Wins, ordinary outcomes, and failures
Public reputation clusters around Microsoft, Sun, ROLM, and Intuit, but fame is not an economic ranking. The deal reconstruction searched 33 raw company/alias rows and still cannot compute coverage against August Capital's claim that TVI's four funds invested in more than 100 companies. Microsoft is a partially quantified ownership snapshot, not a proven largest realized return; Sun is Marquardt-led; ROLM crosses personal/PAIC/IVA stages; Intuit has strong board evidence but no public TVI cash-flow record.
The one public LP schedule supplies a less heroic fund-level view. As of March 31, 2003, the University of California's own positions showed TVI 2 at 1.69x/9.2% net IRR, TVI 3 at 1.67x/7.2%, and TVI 4 at 3.27x/24.1%. UC Regents schedule, p. 1 and mandatory footnotes. These figures are one LP's experience, net of fees/expenses/carry; the schedule warns that residual NAV was GP-determined, valuation standards varied, pace altered IRR, and cross-fund comparisons could mislead. TVI 1—the Microsoft-bearing vehicle—is absent. The evidence establishes three dated LP observations whose stated values differ; it does not support a cross-fund rank, company attribution, or McMurtry personal record.
Failures matter because they test whether the method had a usable stop rule. Mindset, launched with advanced graphics into an IBM-compatibility market, entered bankruptcy proceedings in 1985 and was liquidated. The Los Angeles Times identified McMurtry as a former board member and reported that TVI lost about $2 million; his contemporaneous reflection was that sometimes it was time to move on. Los Angeles Times, 1987-12-18. The dollar figure is [contemporaneous record · moderate], and the record does not yet show the original sponsor, follow-on votes, or exact stop decision. DAVID supplies a different failure: patience without a compelling application. VeriFone litigation adds adverse-search discipline but not wrongdoing: shareholders alleged forecasting/nondisclosure problems, and the Ninth Circuit affirmed dismissal with prejudice. In re VeriFone Securities Litigation, 11 F.3d 865.
Falsifiable thesis of McMurtry's edge
Proposed edge — [researcher inference · moderate]: between roughly 1969 and 1995, in West Coast electronics, systems, and early software, McMurtry's repeatable contribution was board-intensive judgment of technical founder teams, improved by structured dissent, conflict-clean approvals, and reciprocal reference diligence. The mechanism is specific: engineering and operating networks produced access and informed evaluation; references tested character and working fit; non-unanimous partnership debate reduced affinity bias; small-enough vehicles preserved partner time; boards supplied help after investment. ROLM supports the conflict/diligence mechanism, Intuit supports founder selection for board value, and the 1984 testimony plus 1990 presentation establish the stated people/market/technology and active-support framework. Bancroft, printed pp. 31–38 and 56–59; JEC, printed p. 203/PDF p. 207; TVI presentation, pp. 5–9.
The thesis predicts observable evidence in unseen deals: McMurtry should repeatedly document founder references, a dissenting or independent approval path, manageable board load, explicit market/application tests, and post-investment interventions that founders valued. Ordinary cases—not only famous wins—should show better survival or governance outcomes when those controls were present. Failures should cluster where market evidence overruled too late, partner capacity was stretched, or the process controls were absent.
The thesis weakens materially if TVI/IVA investment memos and board records show that McMurtry rarely used the claimed reference/dissent system; if his attributed ordinary deals perform no differently when controls are present; if partner sourcing and founder execution explain the record without a distinct McMurtry contribution; or if economics excluding Marquardt-led Microsoft/Sun and Melchor-originated ROLM are unexceptional. It is overturned as a return edge if a complete, attribution-clean denominator shows no relationship between the mechanism and outcomes. It may still survive as a governance craft even if it fails as an economics claim.
The strongest skeptical explanation
The skeptical case is substantial. First, public narratives attach firm outcomes to a senior partner. Microsoft and Sun were Marquardt-led; original ROLM financing was Melchor's; founders and later partners did most company execution. Second, the searched denominator is radically incomplete and biased toward successes. Third, the only public schedule contains three dated, non-comparable one-LP observations, while the missing TVI 1 prevents testing the Microsoft outlier. Fourth, McMurtry admitted the people bias could override markets, and DAVID/Mindset demonstrate that technological quality and attractive people did not ensure application or distribution. Finally, the era itself supplied privileged university/company networks, expanding semiconductor/computer markets, favorable institutional-capital changes, and scarce professional competition. Bancroft, printed pp. 34–50; UC schedule.
The favorable and skeptical accounts are not decided by reputation. The decisive evidence would be fund-level cash flows by company, contemporaneous investment memoranda, attribution-clean partner work logs, board minutes, reference files, and a complete set of wins, ordinary outcomes, and losses. Until then, the strongest conclusion is narrower: McMurtry was an early institution builder and active director with a candid, testable process vocabulary; the magnitude and individuality of his investment alpha remain insufficient public record.
From investor to institutional governor
In 1994 McMurtry decided not to join another general-partner vehicle, though he spent roughly eight further years working out TVI companies. Marquardt and Johnston formed August Capital, while Kagle joined the Benchmark founding group in 1995. Bancroft, printed pp. 48–49. This succession reinforces the team story: TVI did not simply become “McMurtry's next fund.”
McMurtry redirected increasing attention to Rice, Stanford, and Carnegie Science governance. Carnegie elected him to its board in December 1996 and made him a senior trustee in May 2004. Carnegie Science Year Book 2011–2012, p. 20; Carnegie Year Book 2003–2004, p. 16. Stanford's 2004–2007 annual reports carry signed chair messages, and Stanford later reported eleven years as a trustee from 1997 to 2008, including four as chair. Those contemporaneous reports and the institutional obituary control the broad 2004–2008 chair chronology; the 2009 oral-history wording is retained only as a date anomaly, with exact transition months unresolved. Stanford annual reports; Stanford obituary; Bancroft, printed pp. 68–70.
The governance chapter is not proof of investing edge, but it does show continuity in institution-building, listening, and decision structure. Stanford colleagues remembered him encouraging questions and seeking the best answer in the room. That is retrospective witness · moderate and consistent with the partnership/dissent hypothesis; it cannot establish the earlier causal mechanism by itself. Stanford obituary, “A thoughtful and effective leader”. McMurtry died in Palo Alto on September 2, 2018, at age 83. Stanford obituary; Rice obituary.
Verified chronology
| Date | Verified event | Evidence boundary |
|---|---|---|
| 1935 | Burton J. McMurtry was born and raised in Houston, Texas. | Stanford obituary, “Silicon Valley pioneer” confirms place and age-at-death context; no day/month is asserted here. |
| 1952–1957 | He attended Rice, received a BA after four years and completed the then-five-year electrical-engineering course for the BSEE; he and Ann Meck graduated and married in 1956. | Bancroft oral history, printed pp. 10–14, 01-00:28:37–01-00:40:54; the degree sequence is McMurtry's 2009 recollection. |
| 1955–1957 | As a student representative, he participated in the Rice committee that designed the residential-college system; implementation began during his fifth year. | Bancroft, printed pp. 12–14, 01-00:34:51–01-00:40:03; Rice obituary independently confirms the committee role. |
| 1957–1962 | Recruited by Sylvania, he moved to the Bay Area, worked full time, and studied through Stanford's Honors Cooperative Program; he earned an MS in 1959 and PhD in electrical engineering in 1962 under Anthony Siegman. | Bancroft, printed pp. 14–19, 01-00:40:25–01-00:53:31; Stanford obituary, “Silicon Valley pioneer”. |
| 1961–1962 | McMurtry and Siegman submitted and published a photomixing experiment using a ruby optical maser and traveling-wave microwave phototube. | Applied Optics 1(1), pp. 51–53, manuscript received 1961-10-06. This verifies technical work, not a later investment rule. |
| 1957–1969 | He worked in engineering and management at Sylvania/GTE, including electro-optics, laser/microwave research, and laboratory management. | Bancroft contents and printed pp. 21–29; Carnegie Science Year Book 2011–2012, p. 20 independently gives the 1969 transition. |
| 1969 | Jack Melchor personally supplied ROLM's initial financing and a loan; Palo Alto Investment Company, formed around June 1969 with McMurtry and Don Smith as employees, had no initial role in ROLM. | Bancroft, printed pp. 29–33, 02-00:26:09–02-00:35:02. This is the controlling attribution boundary: McMurtry had hired or tried to hire the founders at GTE, but did not provide the original ROLM financing. |
| 1973–1974 | McMurtry, Reid Dennis, Burge Jamieson, and Jim Norris formed Institutional Venture Associates; the institutional raise closed in 1974 after a difficult market. | Bancroft, printed pp. 36–38 and 44–46; Reid Dennis oral history, description and fund discussion. |
| 1975 | After diligencing ROLM's electronic-PBX expansion, McMurtry disclosed his personal shareholding and PAIC connection, removed himself from approval, and presented the work to Dennis, Jamieson, and Norris; they approved IVA's investment and McMurtry joined the board. | Bancroft, printed pp. 31–32, 02-00:31:55–02-00:33:57. The later IVA investment must not be collapsed into Melchor's 1969 personal backing. |
| 1976–1984 | ROLM went public in 1976 and was acquired by IBM in 1984. | Bancroft, printed pp. 34–35, 02-00:39:47–02-00:41:29. McMurtry retrospectively described an approximately 40x public-share comparison; it is not IVA's audited return. |
| 1980 | McMurtry, James Bochnowski, and David Marquardt founded Technology Venture Investors; the first fund was reported by McMurtry as roughly $24 million with nine institutional partners. | Bancroft, printed pp. 46–47, 03-00:15:22–03-00:18:35; Marquardt oral history, p. 22 independently identifies the three founders. |
| 1981 | TVI became Microsoft's only outside institutional investor. David Marquardt originated and led the relationship and joined Microsoft's board; the record does not support crediting McMurtry as the deal lead. | Bancroft, printed pp. 48–49, 03-00:24:46–03-00:26:21; Microsoft prospectus, “Principal and Selling Stockholders,” p. 30 identifies TVI entities and Marquardt. |
| 1982–1988 | TVI raised successor funds in 1982, 1984, and 1988; McMurtry later described four funds totaling $270 million. | Bancroft, printed pp. 47–48, 03-00:18:35–03-00:22:37. The $270 million is investor-stated retrospective evidence, not an audited fund schedule. |
| August 1982 | TVI invested in six-month-old Sun Microsystems through a relationship McMurtry expressly attributed to Marquardt, who served on Sun's board. | Bancroft, printed p. 49, 03-00:26:24 onward. Firm participation is verified; McMurtry-lead attribution is not. |
| 1984 | McMurtry testified before Congress as a TVI general partner and NVCA vice president/secretary. His live opening emphasized team biographies, early-company work, and a people-first sequence; the attached prepared statement was presented jointly by three NVCA witnesses. | JEC hearing, printed pp. 145–165 and 203; PDF pp. 149–169 and 207. Authorship should remain “McMurtry-presented/NVCA-associated,” not assumed sole authorship. |
| 1984–1995 | TVI's team changed: Bob Kagle joined in 1984; biotech work split into Delphi Ventures after Bochnowski left in 1988; John Johnston joined in 1988. | Bancroft, printed pp. 48–49; 1990 TVI presentation, pp. 2–4. |
| August 1990–December 8, 2000 | McMurtry joined Intuit's board alongside John Doerr after the profitable company chose investors partly for expected board value; a 1997 proxy confirms his audit-committee role, and the 2000 proxy says he was not standing for reelection at the December 8 annual meeting. | Intuit 1997 proxy, “Directors/Nominees” and “Board of Directors Meetings”; Intuit 2000 proxy, meeting notice and nominees. The contemporaneous proxy controls over McMurtry's approximate 2009 recollection that he left in 2001. |
| 1994–2002 | McMurtry declined to become a general partner in another fund but continued working out TVI investments and board roles; Marquardt/Johnston formed August Capital and Kagle joined Benchmark's founding team in 1995. | Bancroft, printed pp. 48–49. This is a wind-down, not an instantaneous 1994 retirement. |
| 1996–2004 | He was elected to Carnegie's board in December 1996 and became a senior trustee in May 2004. | Carnegie Science Year Book 2011–2012, p. 20; Carnegie Institution Year Book 2003–2004, p. 16. |
| 1997–2008 | McMurtry served eleven years on Stanford's Board of Trustees, including approximately 2004–2008 as chair. | Stanford obituary, opening and “A thoughtful and effective leader” · signed 2004–2007 chair messages. Exact transition months remain unresolved; the four consecutive signed reports control over anomalous 2009 wording. |
| 2002 | He appeared with six other pioneers on the Computer History Museum panel and discussed early venture scarcity and ROLM. | CHM event page; video, 18:00–18:50, 33:25–35:53, 48:56–50:28. Captions are automatic and require verification before quotation. |
| 2003–2004 | A UC Regents disclosure reported its own positions in TVI 2, 3, and 4 at 1.69x/9.2%, 1.67x/7.2%, and 3.27x/24.1% respectively as of March 31, 2003. | UC schedule, p. 1 and mandatory footnotes. These are one LP's net figures, include GP-valued residuals, omit TVI 1, and are not comparable final fund rankings. |
| 2004–2008 | In the governance phase, McMurtry chaired Stanford's board, supported the Stanford Challenge, and helped advance the arts district; he also left the Rice and Carnegie boards to focus on Stanford. | Signed 2004–2007 chair messages; Stanford Challenge announcement; Bancroft, printed pp. 68–70. Exact chair transition months are not public. |
| 2018-09-02 | McMurtry died at home in Palo Alto at age 83. | Stanford obituary; Rice obituary. |
Identity and scope
- Name variants: Burton J. McMurtry; Burton McMurtry; Burt McMurtry; B. J. McMurtry.
- Primary eras: engineer/manager at Sylvania-GTE (1957–1969); PAIC (1969–1973/74); IVA (1973/74 onward while investments matured); TVI (formed 1980, last fund 1988, active wind-down into the early 2000s); university/science governance and philanthropy (overlapping, especially 1980s–2018).
- Geography: Houston/Rice formation; then the Stanford–Mountain View–Menlo Park/Silicon Valley ecosystem. Bancroft, printed pp. 1–19.
- Vehicle boundary: PAIC, IVA, TVI funds, TVI management entities, personal holdings, and companies' boards are different attribution units. A university obituary's phrase “helped fund” cannot decide which unit or partner acted. Stanford obituary, “Silicon Valley pioneer”; Synaptics prospectus, “Principal and Selling Stockholders,” pp. 66–68.
People and institutional influence map
| Person or institution | Verified relationship | Attribution boundary |
|---|---|---|
| Jack Melchor / PAIC | Recruited McMurtry into venture capital; personally financed ROLM before PAIC's formation. | PAIC decisions require deal-level proof of who sourced, approved, governed, and narrated them. |
| Reid Dennis, Burge Jamieson, Jim Norris / IVA | IVA partners; the other three approved the conflicted 1975 ROLM investment. | Dennis's policy work and partnership decisions cannot be relabeled as McMurtry's. |
| James Bochnowski, David Marquardt / TVI | Cofounded TVI with McMurtry in 1980. | Marquardt led Microsoft and Sun; Bochnowski led biotechnology work that became Delphi. |
| Bob Kagle, John Johnston, Mark Wilson / later TVI | Later partners and shared decision/voting actors. | Sourcing, board, follow-on, and exit roles remain company-specific; Synaptics voting power was shared. |
| ROLM founders Gene Richeson, Ken Oshman, Walter Loewenstern, Bob Maxfield | McMurtry recruited three and tried to recruit the fourth at GTE; founders executed the company. | Recruiting connection and a later board role are not founder or original-financier credit. |
| Scott Cook, Tom Proulx, John Doerr, Gordon Davidson / Intuit | Founders, co-investor/director, and outside counsel/witness around the 1990 financing. | Witness memory establishes expected board value, not causal outcome or TVI return. |
| Anthony Siegman / Stanford | PhD adviser and technical coauthor. | Laboratory-to-investing transfer remains researcher inference unless direct evidence establishes it. |
| Stanford, Rice, Carnegie Science | Later governance and philanthropy institutions. | Governance evidence cannot backfill earlier investment causality; exact Stanford chair transition months remain unresolved. |
Unresolved evidence
- Contemporaneous PAIC and IVA formation documents have not established legal structure, capital sources, compensation, or complete decision rights.
- Stanford board minutes are needed only to recover exact chair transition months; four consecutive signed annual-report messages and Stanford's obituary establish the four-year tenure.
- Rice registrar/alumni records could fix the exact BA/BSEE dates compressed by institutional obituaries.
- Most TVI/IVA companies still lack attribution-clean evidence for sourcing, diligence, sponsorship, board work, follow-ons, and exits.
- A complete ordinary-and-failed-deal record could decide whether the people-first system added value beyond Microsoft/Sun access, partners, and era.
- No public record yet shows a documented process change after DAVID Systems, Mindset, Synapse, or Daisy/Cadnetix.
- TVI's claimed company count cannot yet be reconciled fund by fund across follow-ons, aliases, acquisitions, and partner-career examples.
- Public routes did not surface McMurtry's own LP letters, personal investment memos, or a named archive box/folder containing TVI records.
Learning path through the package
- Read the chronology and attribution map above, then use the source map to understand the direct-voice, filing, and archive boundaries.
- Read writings and talks to separate McMurtry's public statements from partner and witness accounts.
- Work through the no-hindsight cases, denominator, and fund evidence in investments, especially ROLM, Intuit, DAVID Systems, and Mindset.
- Use the 17-section investment philosophy as the operating-system synthesis and the mental models as the decision-ready field guide.
- Finish with the adversarial review, which tests the edge thesis, ordinary claims, transfer limits, and unresolved evidence.
1. Snapshot and testable edge thesis
| dimension | evidence-bounded conclusion |
|---|---|
| Investor / vehicles | Engineer-manager; joined Jack Melchor's PAIC in 1969; co-founded IVA and TVI; four TVI funds; active investing wound down around 1994–95. profile |
| Proposed edge | [researcher inference · moderate] Relationship and technical ground truth → contrary references and forced dissent → conflict-clean approval → board work, bounded by partner attention. |
| Domain / period | West Coast electronics, systems, and software, roughly 1969–1995; not a universal all-sector or all-geography doctrine. JEC, printed pp. 145–147 |
| Supporting observations | ROLM role separation, Intuit founder demand for board value, McMurtry's reference/dissent account, and high reported TVI board exposure. deal labs |
| Disconfirming observations | DAVID and Mindset failures, admitted overdeployment, Microsoft/Sun partner attribution, and no matched board-efficacy set. |
| Predictions | Unseen ordinary files should show McMurtry-specific work, consequential negative evidence, an assigned skeptic, application falsifiers, conflict disposition, capacity compliance, and measured interventions. |
| Falsifiers | Partner-led selection, ignored contrary evidence, ceremonial boards, capacity breaches, no matched outcome difference, or economics dominated by partner-led outliers after controls. |
TVI reports more than 100 investments, while the searched ledger dispositions 33 raw rows containing candidates, unresolved vehicles, exclusions, and a pass. Personal hit rate, portfolio coverage, and McMurtry alpha are not computable. [researcher inference · strong] denominator
2. Core philosophy
The direct record places entrepreneurs before capital and treats venture as active company building. McMurtry later described examining people, market, technology/product, and price; following references until a negative view appeared; letting founders reference the investor; and assigning a supporter to challenge unanimous enthusiasm. [investor-stated · moderate] [researcher inference · provisional] JEC, printed p. 203 · Bancroft, printed pp. 51–57
The reconstructed sequence is: earn ground truth → require important application and defensibility → test people with reciprocal, contrary evidence → engineer dissent and conflicts → price partner attention → finance while a testable recovery path exists → preserve roles and denominators. [researcher inference · moderate] It is not a recovered TVI handbook. mental models
3. Sourcing
Sylvania/GTE relationships connected McMurtry to the ROLM founders; Melchor supplied entry to PAIC; institutional relationships moved several IVA investors into TVI-1. In 1984 TVI reported 80% Bay Area and 99% Western concentration. [retrospective witness · moderate] [contemporaneous record · moderate] Bancroft, printed pp. 27–46 · JEC opening
Access is not selection skill. A repeatable process records who introduced whom, what unique evidence the relationship adds, which non-network cases were sampled, and whether independent customer/technical checks survive. ROLM supports relationship access; Intuit supports founder selection of board partners; Microsoft and Sun are negative controls because David Marquardt led them. [researcher inference · moderate] decision-rights grid
4. Picking
| gate | supported rule | boundary / kill evidence |
|---|---|---|
| People | Chain role-relevant references to disconfirming evidence and invite reciprocal diligence. [investor-stated · moderate] Bancroft | Familiarity and pedigree are not proof; DAVID is the people-first counterexample. |
| Application / market | The McMurtry-presented/NVCA-associated exhibit required important use rather than novelty alone. [contemporaneous record · strong] [researcher inference · insufficient public record] JEC prepared statement | Name buyer, urgency, paid behavior, alternatives, and kill threshold. |
| Defensibility / product | The exhibit said existing technology may qualify if application and proprietary position matter. [contemporaneous record · strong] [researcher inference · insufficient public record] writings | “High technology” is not itself a moat; original IP analyses are missing. |
| Price | Price was named as a dimension, but no repeatable valuation rule survives. [investor-stated · insufficient public record] Bancroft | Intuit proves founder choice of board value, not McMurtry price discipline or return. |
| Decision | Assign a skeptic; disclose and remove conflicted voters. [investor-stated · moderate] [documented behavior · moderate] ROLM case | No ordinary TVI IC file proves consistent use. |
5. Deal and portfolio mechanics
No public record establishes a universal security, check, ownership target, reserve ratio, diversification rule, follow-on formula, loss budget, or exit doctrine. Microsoft is an ownership snapshot: TVI-1/2/3 held 1,378,901 shares before the offering, listed 294,893 as shares to be sold, and 1,084,008 as retained after the offering; cost history, closing evidence, distributions, and realized multiple are absent. [contemporaneous record · strong] [researcher inference · insufficient public record] Microsoft prospectus, printed/PDF p. 30
Attention construction is better supported: about 70% of forty companies reportedly had board representation in 1984, and McMurtry later bounded one partner at roughly six to eight active boards. That is a historical constraint, not a universal optimum; early-1980s overdeployment is the counterexample. [investor-stated · moderate] JEC · Bancroft, printed pp. 47–53
6. Vehicle and incentive fit
| vehicle | enabling feature | constraint / missing economics |
|---|---|---|
| PAIC | Melchor's committed platform enabled early-company work | Melchor owned capital; compensation, rights, and audited cash flows absent |
| IVA | pooled institutional capital, duration, and unconflicted ROLM approvers | terms, reserves, fees/carry, votes, and individual allocation absent |
| TVI-1–4 | successive institutional funds, boards, and partner succession | fundraising/deployment could outrun attention; GP commitment, key-person, allocation, reserve and carry terms absent |
The UC schedule reports one LP's net experience through March 31, 2003: TVI-2 at 1.69x/9.2%, TVI-3 at 1.67x/7.2%, and TVI-4 at 3.27x/24.1% with residual NAV. Net IRR is after fees, expenses, and carry; the schedule warns about GP valuation, pacing, incomplete realization, and cross-fund comparison. These are not company, GP, or personal returns. [contemporaneous record · strong] UC schedule and footnotes
Vehicle fit matches duration, reserves, partner hours, rights, geography, liquidity, regulation, succession, and stakeholder incentives to the work. [researcher inference · moderate]
7. Team attribution and work with founders
Source, sponsor, diligence, approval, negotiation, board work, recruiting, follow-on, exit, and narration remain separate. ROLM: Jack Melchor initial financing; McMurtry relationships and later IVA diligence; Dennis/Jamieson/Norris approval after recusal; McMurtry board; founder execution. Microsoft/Sun: Marquardt-led. Intuit: founders chose proposals; McMurtry/Doerr boarded; TVI approval/economics unknown. Synapse: company failure is bounded but the TVI/partner bridge is unproved. Synaptics: shared filing-level authority among five TVI principals. [retrospective witness · moderate] [contemporaneous record · strong] people and rights
Recruiting, prioritization, governance, and stop decisions can be investor products, but a director title does not prove source, intervention, causal value, or return. DAVID and Mindset preserve that limit. [researcher inference · strong]
8. Views on the craft
- Entrepreneurs before capital — [investor-stated · strong]. JEC, printed p. 203
- Asymmetric payoff — [contemporaneous record · strong] [researcher inference · insufficient public record]. The McMurtry-presented/NVCA-associated exhibit says upside must compensate for failures and duration, but no personal application or power-law calculation is public. JEC prepared statement
- Access versus selection — [researcher inference · moderate]. Networks create information and also bias/conflict. ROLM
- Governance — [retrospective witness · moderate]. Board service is active work whose efficacy must be measured. Bancroft, printed pp. 55–57/PDF pp. 65–67
- Scale — [retrospective witness · moderate]. Capital abundance cannot override attention capacity; McMurtry said TVI's pacing did. Bancroft, printed pp. 47–48/PDF pp. 57–58
- Exits — [investor-stated · provisional]. Long company building can conflict with quick-IPO incentives, but no universal hold/sale rule survives. talks
9. Signature bets and decision process
The eleven no-hindsight labs separate the decision from the reveal:
- ROLM — relationship access, disclosure, recusal, and founder credit; an excluded IVA control, not TVI.
- Microsoft — profitable-company access and a negative McMurtry attribution control.
- Intuit — founder willingness to accept a lower valuation for expected board value, with return unknown.
- DAVID Systems — team/technology confidence without a falsifiable application.
- Mindset — staged evidence and stopping under a thin ex-ante record.
- Sun — Marquardt-led early-stage attribution control.
- Synaptics — filing-rich ownership but missing original decision record.
- Synapse — company failure with no verified TVI or partner bridge.
- Tandem — IVA pass tested without importing later success.
- VeriFone — operating help plus allegations dismissed with prejudice.
- SpectraLink — adverse-governance control without a located merits finding.
Each reader states invest/pass, kill criteria, ownership/terms, and evidence for the next check before reading the sourced outcome. Generic risks in thin cases are labeled researcher-created exercises.
10. Mental models and maxims
| model | origin | decision use |
|---|---|---|
| Follow builders with earned ground truth | JEC people emphasis + later references | distinguish relationship access from verified founder evidence |
| Require important application and defensibility | JEC doctrine + DAVID failure | kill technology-push without paid use |
| Engineer dissent and clean rights | Bancroft skeptic rule + ROLM recusal | prevent consensus and sponsor conflict from owning approval |
| Price partner attention | board exposure + capacity ceiling | budget governance work before adding companies |
| Be patient while recovery is testable | duration doctrine + DAVID/Mindset | join reserves/duration to milestones and stop branches |
| Underwrite asymmetry with honest denominators | JEC payoff + filing/LP controls | separate opportunity size, paper marks, cash flows, and role owners |
The inventory merges geography into ground truth, boards into attention, and duration into recovery. Candidate slogans without reusable multi-case evidence remain in the exclusion ledger.
11. Evolution and contradictions
| period | position | contradiction / update |
|---|---|---|
| 1962 | experimental technical work | provenance only; no demonstrated venture causation |
| 1969–75 | relationships, scarce capital, patience | ROLM required recusal and distributed roles |
| 1984 | people/board doctrine and national policy advocacy | local capital abundance; tax response conceded unproved |
| 1980s | successive-fund scale | later overdeployment admission violated capacity logic |
| 1984–94 | active DAVID board work | no compelling application emerged |
| 2002–09 | reciprocal diligence and modesty about investor mystique | retrospective narratives may make process look cleaner |
No located record dates the skeptic rule or a process change to DAVID, Mindset, or overdeployment. Durable beliefs and stronger late self-critique are supported; organizational learning is not. [researcher inference · moderate]
12. Failures and limits
DAVID tests people/application error; Mindset tests terminal judgment; Synapse is a company failure with an unresolved investor vehicle; Tandem is a pass without executable terms or lost-return arithmetic; overdeployment is a portfolio-process failure. No original memos or dated rule changes survive. [retrospective witness · moderate] [contemporaneous record · moderate] postmortems
Adverse matters preserve allegations and disposition. In re VeriFone named McMurtry, but dismissal with prejudice was affirmed and the located opinion establishes no wrongdoing. SpectraLink allegations later settled through D&O insurance without a located admission; Intuit complaint disposition remains unresolved. VeriFone opinion
13. Historical operating environment
Capital shifted from relationship/family platforms toward institutional partnerships. McMurtry's 1984 record described a geographically concentrated early-stage portfolio and policy conditions he believed affected risk capital; he could not prove the tax causal claim. No matched financing, valuation, failure-rate, or board-efficacy base rate was located. [contemporaneous record · strong] [researcher inference · provisional] JEC live/prepared/Q&A
A contemporary could see scarce early institutional capital, emerging computing/communications markets, incumbents, long commercialization, and limited liquidity. Later dominance or failure is excluded from the frozen decision. [researcher inference · moderate]
14. Modern VC translation (as of 2026-08-24)
| lesson | transfers | does not transfer | signal | likely misuse | adapted action |
|---|---|---|---|---|---|
| Earn ground truth | traceable introductions, independent references, founder reverse diligence | literal Valley radius/prestige network | tacit technical/customer facts | closed-network homophily | audit non-network funnel and evidence added [researcher inference · moderate] |
| Application before novelty | paid urgency, workflow fit, switching cost, falsifiable adoption | technical novelty/model access as moat | repeated paid use and buyer budget | demos relabeled demand | pre-register buyer, alternative, retention, kill threshold [researcher inference · moderate] |
| Engineered dissent | independent skeptic, conflict register, sponsor/approver split | performative contrarian text | consensus precedes evidence closure | AI “red team” without incentives | store pre-vote, falsifier, conflict, owner [researcher inference · strong] |
| Price attention | named hours, interventions, milestones, handoff | universal six-to-eight-seat rule | thesis needs senior labor | collecting seats | capacity-plan stressed portfolio [researcher inference · moderate] |
| Patient recovery | risk calendar, reserves, branch points | unconditional follow-ons | measurable risk retirement | sunk-cost patience | write continue/repair/sell/stop branches [researcher inference · moderate] |
| Honest asymmetry | ownership/dilution/reserve scenarios and ex-outlier stress | celebrity lists/IPO marks as alpha | rare-win portfolio thesis | paper-value rankings | build vehicle cash-flow and role ledgers [researcher inference · strong] |
Examples are explicitly hypothetical because no separate 2026 market census was conducted: an AI application should demonstrate proprietary workflow adoption rather than generic model access; a deep-tech company should connect technical milestones to runway; a distributed fund should reproduce local ground truth through independent experts/customers.
15. Comparison with completed peers
The valid set is Reid Dennis, McMurtry's IVA partner and unconflicted ROLM approver; Paul Wythes, a same-era local/team/board comparator; and Bob Kagle, a TVI successor who later practiced service-first governance at Benchmark. Shared histories are not independent validation.
| dimension | McMurtry | Dennis | Wythes | Kagle |
|---|---|---|---|---|
| Sourcing | Sylvania/Melchor/local ground truth | engineering-finance/referral network | local reciprocal team platform | service/team sourcing; later era |
| Picking | people + application/market + technology/product + price | people/technical-to-customer learning | people/expert/customer/remediability | founder/service with explicit team credit |
| Portfolio | attention ceiling; universal targets absent; overdeployment | successive vehicles; case holdings | evergreen structure; incomplete economics | equal-partnership constraints differ |
| Governance | boards, recruiting, dissent/recusal | active boards; approved ROLM | recruiting/monitoring/conflict controls | service-first boards; Benchmark institution |
| Vehicles | PAIC → IVA → four finite TVI funds | personal/corporate/IVA/IVP | pre-existing SBIC/evergreen | TVI → equal Benchmark partnership |
| Failure boundary | DAVID, Mindset, pacing | people errors/passes/dispersion | escalation/remediability; weak chains | selected cases and team economics bounded |
Claim-local peer evidence: Dennis's sourcing, picking, vehicle, and team/governance sections rest principally on his Bancroft oral history. Wythes's sourcing, picking, vehicle, and team/governance comparisons are bounded by his oral-history corpus and participant-specific Measurex and Diablo/Qume notes. Kagle's sourcing, picking, vehicle, and team/governance use his Kagle talk synthesis, Done Deals record, and public deal evidence. [researcher inference · moderate]
Dennis is the closest rights control; Wythes tests whether local patient boards were era-wide rather than distinctive; Kagle tests succession into a different partnership. Similarity does not prove alpha. [researcher inference · moderate]
16. The strongest case against greatness
McMurtry may have been a capable engineer, fundraiser, director, and institution builder inside an advantaged network without demonstrably superior personal selection. Melchor supplied entry/capital; partners supplied approvals and signature deals; founders supplied execution; geography, policy, and exits supplied regime; Microsoft can dominate memory while being Marquardt-led; and the public set hides ordinary outcomes. DAVID, Mindset, Synapse, Tandem, adverse controls, and overdeployment prevent hagiography but cannot establish a failure rate. [researcher inference · strong] ledger
The favorable thesis wins if ordinary files show repeated McMurtry-specific evidence/dissent, conflict-clean decisions, application falsifiers, capacity compliance, measured interventions, and superior ex-Microsoft matched cash flows. The skeptic wins if partners own decisions, boards are nominal, negative evidence is ignored, capacity is breached, or outcomes disappear after controlling access, team, vehicle, vintage, founders, and luck. The public evidence cannot decide.
17. Analyst study guide, glossary, and go deeper
Path: profile → sources → writings → talks → eleven decision labs → mental models → review. In each lab answer invest/pass, kill criteria, terms/ownership, and next-check evidence before the reveal; DAVID, Mindset, Synapse, Tandem, VeriFone, and SpectraLink are failure, miss, or adverse-control exercises.
| term | meaning |
|---|---|
| PAIC | Jack Melchor-backed Palo Alto Investment Company; not McMurtry's personal fund |
| IVA | Institutional Venture Associates, organized 1973/closed 1974; later ROLM vehicle |
| TVI | Technology Venture Investors; four finite institutional funds and a multi-partner team |
| role fence | source, sponsor, diligence, approval, board, follow-on, exit, narration separation |
| capacity budget | named partner hours/interventions, not a universal seat number |
| recovery set | credible product, financing, leadership, sale, or liquidation branches |
| raw row | research disposition, not necessarily a unique TVI portfolio company |
| reported return | sourced figure with object/basis stated; not audited here |
Checklist: sourcing—provenance/evidence/non-network sample; diligence—people roles/references, buyer/application, defensibility, price/security, alternatives/falsifiers; IC—vehicle, source/sponsor/approver, conflict/recusal, skeptic, milestones, reserves, kill criteria; governance—intervention owner, hours, recruiting, customer learning, runway, stop branches; economics—cost, ownership, dilution, follow-ons, distributions, NAV, fees/carry, attribution, denominator.
Best routes: (1) Bancroft oral history, detailed but retrospective and permission-bound for publication quotation; (2) 1984 JEC hearing, contemporaneous but split live/prepared/Q&A; (3) CHM panel, automatic captions only; (4) Microsoft/Intuit/Synaptics/SpectraLink filings for entities, holdings, boards, and adverse controls; (5) UC schedule, one LP's net vehicle evidence with integral warnings. Highest-value missing records are partnership agreements, complete LP/company cash flows, sourcing/reference/IC files, cap tables, board/conflict minutes, intervention outcomes, and personal distributions.
Pareto 80/20 — what drove the record
[researcher inference · strong] A literal 80/20 split, career hit rate, or McMurtry-personal return is not computable. TVI's four funds reportedly invested in over 100 companies, while this bounded search found only 33 raw company/opportunity rows and no complete company-level cash-flow schedule. The two partially quantified public ownership snapshots are Microsoft at its 1986 offering and Synaptics at its 2002 offering; neither is a realized TVI return or comparable economic rank. August Capital, Marquardt biography, TVI paragraph · Microsoft prospectus, principal and selling stockholders · Synaptics 424B4, principal and selling stockholders
Economic contribution — directional and not a personal-return ranking
| rank | observable measure | attribution and support | mechanism that can be supported | denominator boundary | case |
|---|---|---|---|---|---|
| Microsoft · partially quantified public snapshot | TVI 1, 2 and 3 jointly held 1,378,901 shares, or 6.1% pre-offering; 294,893 were listed as shares to be sold and 1,084,008, or 4.4%, as retained after the offering. | Firm/three-fund position; David Marquardt sourced the relationship and held the board seat. McMurtry receives no individual deal-lead credit. [contemporaneous record · strong] | A profitable growth company chose a small outside investor for help, then reached a public liquidity event. [documented behavior · strong] | An offering table is not closing evidence, original cost, distributions, net MOIC, or hold-through proceeds; it cannot be ranked against Synaptics. | Lab 2 |
| Not company-rankable · TVI IV | One UC LP reported $12.000m cash in, $38.060m cash out, $1.205m NAV and 3.27x/24.1% net IRR as of 2003-03-31. | UC's interest in one TVI fund; no company contributors or partner allocation. [contemporaneous record · strong] | The row reports net value for UC in a non-Microsoft vehicle as of one date but names no contributors. [contemporaneous record · strong] | Fund result cannot rank companies or funds; residual NAV, valuation policy, vintage, and cash-flow timing affect the measure. | UC LP schedule |
| Not rankable · Intuit | Profitable company; five term sheets at roughly $50m–$75m valuations; founders selected the two lowest offers for expected board value. | TVI/Kleiner/Sierra financing; McMurtry and John Doerr board roles; founder/operator execution remains primary. [retrospective witness · moderate] | Reputation, reference diligence and board help traded against headline valuation. [retrospective witness · moderate] | Check, TVI ownership, dilution, proceeds and vehicle distribution are not public. | Lab 3 |
| Not rankable · Synaptics | TVI-affiliated entities held 2,077,339 shares (11.5% pre/9.0% post) and offered 154,169 in the over-allotment scenario, retaining 1,923,170 (8.4%). | TVI 3/IV group; shared voting/dispositive power among Wilson, McMurtry, Marquardt, Kagle and Johnston. [contemporaneous record · strong] | Multi-round ownership and follow-on participation are visible. [documented behavior · strong] | Paper ownership and shares offered do not establish sale completion, realized proceeds, fees/carry, or McMurtry's economics. | ledger row 16 |
Dominant-outlier test — [researcher inference · strong]. An ex-Microsoft TVI 1–3 return cannot be calculated because the public record does not provide those funds' company cash flows. TVI IV's different dated UC observation cannot be assigned to any company or ranked against the other funds under the schedule's footnotes. Removing Microsoft therefore leaves the company ranking not computable, rather than proving or disproving repeatability.
Historical importance — ranked separately from economics
| rank / case | historical basis | credit boundary and support | learning value | reconstruction |
|---|---|---|---|---|
| 1 · Microsoft and Sun | Two early TVI relationships later central to software and workstation computing. | Marquardt sourced both and served on both boards; founders and operators retain company-building credit. [investor-stated · strong] Bancroft oral history, printed pp. 37–38 and 49–50 / PDF pp. 47–48 and 59–60 | Shows why firm history is not McMurtry-personal history. | Microsoft lab |
| 2 · Intuit | A profitable, founder-financed software company selected investors partly for governance value rather than highest price. | Cook/Proulx selected; Davidson advised; McMurtry/Doerr joined the board; TVI, Kleiner and Sierra provided capital. [retrospective witness · moderate] eCorner transcript, PDF p. 1 | Makes reference diligence and investor selection observable. | Intuit lab |
| 3 · ROLM, excluded IVA control | A formative McMurtry case with unusually explicit conflict disclosure and recusal. | Jack Melchor personally supplied initial funding in 1969; IVA invested in 1975 after Dennis, Jamieson and Norris approved; ROLM's founders executed. [investor-stated · strong] Bancroft, printed pp. 30–33 / PDF pp. 40–43 | Tests governance and attribution without importing it into TVI economics. | ROLM lab |
| 4 · Synaptics | A rare filing-grade bridge from preferred rounds to a public offering. | TVI 3/IV group ownership and shared partner control, not a sole-person holding. [contemporaneous record · strong] Synaptics 424B4, certain transactions and footnote 12 | Demonstrates how to read grouped beneficial ownership without inventing realized return. | ledger |
| 5 · DAVID Systems and Mindset | Two failures expose market/application and compatibility/stop-rule risk. | McMurtry had board evidence in both; founders, managers, partners and co-investors retain separate responsibility. [retrospective witness · moderate] [contemporaneous record · moderate] | Prevents celebrated-company survivorship from defining the doctrine. | DAVID · Mindset |
Decision-learning value — ranked for replayability
| rank | case and tension | evidence status | decision use |
|---|---|---|---|
| 1 | DAVID Systems: sophisticated technology versus failure to find a large application. | McMurtry's direct retrospective, independently bounded by the absence of a memo or dollar loss. [investor-stated · moderate] | Require application/customer proof before continuing to fund technical progress. |
| 2 | Mindset: differentiated graphics versus an IBM-compatible market and escalating capital. | Contemporary reporting gives $18m total venture funding and about $2m TVI loss. [contemporaneous record · moderate] | Define compatibility and distribution gates, then enforce a stop decision. |
| 3 | Intuit: lowest valuation versus board-value selection. | Davidson's witness account plus Intuit's proxy and McMurtry's oral history. [retrospective witness · strong] | Diligence the investor as intensively as the company; price board value explicitly but do not assume it caused the outcome. |
| 4 | ROLM: sponsor enthusiasm plus personal conflict. | McMurtry describes disclosure, recusal and partner approval. [investor-stated · strong] | Separate diligence from voting authority when the sponsor is conflicted. |
| 5 | Microsoft: famous firm win versus absent McMurtry deal role. | McMurtry repeatedly credits Marquardt; the prospectus shows the firm/fund position. [investor-stated · strong] [contemporaneous record · strong] | Attribute source, board work, vehicle ownership and economics separately. |
Evidence boundary and searched denominator
Scope and inclusion rules
- Career and vehicle scope — [researcher inference · strong]. The search covered McMurtry-associated PAIC/IVA/TVI names from 1969 through TVI wind-down, but the accepted TVI candidate set is confined to 1980–1995 firm activity and later realization/governance records. PAIC/IVA cases remain explicit controls or exclusions.
- Raw rows, not a portfolio census — [researcher inference · strong]. The 33 rows are search units drawn from the official McMurtry portfolio biography, the 1990 “Examples of Investments by TVI Partners” presentation, filings, oral histories, failure/adverse searches and one documented pass. TVI reportedly invested in over 100 companies, so no coverage fraction can be claimed. August Capital, TVI paragraph
- Vehicle boundary — [researcher inference · strong]. “TVI partner example” can include a partner's pre-TVI career: ROLM and Seagate appear in the 1990 presentation but are not thereby TVI investments. 1990 TVI presentation, PDF pp. 4–5
- Role boundary — [researcher inference · strong]. Sourcing, diligence, approval, negotiation, board service, executive recruiting, follow-on authority, exit influence and later narration are distinct. Unknown remains unknown.
- Economics boundary — [researcher inference · strong]. Company exit value, beneficial ownership at one date, shares offered, a public stock-price change and an LP fund multiple are not interchangeable with realized net return or McMurtry's personal economics.
- Alias control — [researcher inference · moderate]. PMC-Sierra and Sierra Semiconductor share one search row because sources route them together, but the public materials opened here do not prove a legal successor/portfolio duplicate; the lineage stays unresolved. Rearden is kept separate from Visio and excluded absent a supported TVI vehicle bridge.
Reconciliation and coverage
| state | count | treatment |
|---|---|---|
| publicly claimed/known company count | over 100 | August Capital's Marquardt biography says four TVI funds invested in over 100 start-up and emerging-growth companies; no names or fund allocation. |
| raw rows searched | 33 | 18 strong TVI candidate families + 8 vehicle-unresolved routes + 6 non-TVI exclusions + 1 documented pass. |
| researched to a public boundary | 33/33 | Every row has a classification, role/vehicle statement and missing-fields note below. |
| sufficiently reconstructed for bounded no-hindsight lab | 11/33 | ROLM, Microsoft, Intuit, DAVID Systems, Mindset, Sun, Synaptics, Synapse, Tandem, VeriFone, and SpectraLink. “Sufficient” means useful bounded replay, not a complete cash-flow chain. |
| complete legal-vehicle → decision-right → security/cost → ownership/dilution → follow-on → governance → exit/distribution chain | 0/18 strong TVI candidates | Synaptics comes closest on security/ownership but lacks distributions and partner-specific economics. |
| vehicle-unresolved | 8 | Synapse, Archive, Grand Junction, Symantec, Cadnetix, Outbound Systems, Stratus and Sybase. |
| excluded from TVI denominator | 6 | KLA, NBI, ROLM and Triad are PAIC/IVA-era; Seagate is a partner-career example; Rearden lacks a TVI bridge. |
| passes | 1 | Tandem was an IVA pass, not a TVI investment. |
| unresolved material fields | 33/33 | Every row lacks at least one of original security/cost, individual decision right, dilution, follow-on, exit proceeds or fund distribution. |
| career coverage fraction | not computable | The denominator's exact company names and follow-on/dedup rules are absent; 33 raw rows cannot be divided into “over 100” as if both were comparable unique-company counts. |
Selection bias is severe: public issuers, remembered successes, board seats, litigation and named failures survive; ordinary private outcomes and quiet write-offs do not. The 18 strong rows mean only that a primary/official route supports a TVI association—not that the deal is fully reconstructed, McMurtry-led or profitable.
Historical market, regulatory, and base-rate context
- 1973–1975 financing drought — [investor-stated · moderate]. IVA raised $19m from seven institutions after six months of work and then waited fifteen months for its first investment. McMurtry's 1984 live testimony called $19m about one-third of U.S. venture capital invested in 1974; his 2009 oral history called it more than one-fifth of money raised that year. The unlike denominators and conflicting proportions are preserved rather than averaged. JEC hearing, printed pp. 145–147 / PDF pp. 149–151 · Bancroft, printed pp. 41–44 / PDF pp. 51–54
- 1978–1979 policy change — [retrospective witness · moderate]. McMurtry linked lower capital-gains rates and pension-fund prudence changes to more venture capital, but his 1984 Q&A conceded he could not prove tax causality. The prepared statement was presented by him in an NVCA-associated advocacy setting, not established as a sole-authored personal manifesto. JEC hearing, prepared statement printed pp. 148–165 and Q&A
- 1980–1984 capital acceleration — [investor-stated · moderate]. TVI's $24m first fund was followed by 1982 and 1984 funds; McMurtry later said rapid investment amid froth produced a punishing 1983 cohort. No vintage-level loss rate is public. Bancroft, printed pp. 46–48 / PDF pp. 56–58
- Technology markets broadened — [investor-stated · moderate]. McMurtry described chips, minicomputers, PCs and disk drives expanding addressable markets enough to support billion-dollar companies, unlike many earlier niches. That is retrospective context, not an ex-ante base-rate series. Bancroft, printed pp. 47–48 / PDF pp. 57–58
- Base-rate limit — [researcher inference · strong]. No contemporaneous TVI memo archive, rejected-deal register, loss schedule or full portfolio cash-flow series was found. McMurtry acknowledged many losses and an inability to reduce their count, but the public record cannot calculate a TVI hit rate. Bancroft, printed p. 48 / PDF p. 58
Vehicle economics, incentives, and succession
Entity and capital chronology
| period | vehicle | capital and decision evidence | incentive/constraint interpretation |
|---|---|---|---|
| 1969–1973 | Palo Alto Investment Company / Melchor personal capital | Melchor personally financed ROLM; PAIC had no initial role. McMurtry and Don Smith worked for PAIC. | Personal and company capital could overlap, creating attribution and conflict risk. [researcher inference · strong] |
| 1973/74 onward | Institutional Venture Associates | $19m from seven institutions; 10-year fund logic; Dennis, Jamieson and Norris approved ROLM after McMurtry recused. | Institutional fiduciary duties constrained personal conflicts and new investing late in fund life. [documented behavior · strong] |
| 1980–1995 | TVI 1–4 | First fund reportedly $24m; four funds raised in 1980, 1982, 1984 and 1988; $270m total. LPs included seven IVA institutions, Stanford and HP pension/profit-sharing plans. | Fundraising reputation increased supply; hands-on board capacity limited how much capital the team believed it could deploy. [investor-stated · moderate] Bancroft, printed pp. 46–48 / PDF pp. 56–58 |
| 1988 onward | TVI information technology / Delphi biotech split | Bochnowski left to form Delphi; TVI stayed information-technology focused with McMurtry, Marquardt, Kagle and Johnston. | Sector specialization and key-person departure changed the team and opportunity set. [investor-stated · moderate] |
| 1994–2002 | wind-down / August and Benchmark successors | McMurtry stopped raising new funds, continued old TVI boards for about eight years; Marquardt/Johnston formed August and Kagle co-founded Benchmark. | A finite fund tail preserved old-board obligations but ended new-TVI continuity; successor-firm results are not TVI results. [investor-stated · strong] |
The partnership agreement, management fee, carry, GP commitment, key-person clause, reserve policy, recycling, geographic authority, LP advisory rights and distribution policy are not publicly established. A 10-year limited partnership and external institutional LPs imply fundraising, liquidity and fiduciary constraints, but their causal effect is [researcher inference · provisional]. By contrast, McMurtry's six-to-eight-board capacity estimate and his fund-sizing arithmetic are directly stated. Bancroft, printed pp. 56–58 / PDF pp. 66–68
One-LP cash-flow snapshot — not a fund ranking
UC reported the following for its own interests as of 2003-03-31 (dollars in thousands):
| fund | vintage | cash in | cash out | current NAV | cash out + NAV | multiple | net IRR |
|---|---|---|---|---|---|---|---|
| TVI 2 | 1982 | $4,000 | $6,744 | $0 | $6,744 | 1.69x | 9.2% |
| TVI 3 | 1984 | $8,000 | $13,333 | $0 | $13,333 | 1.67x | 7.2% |
| TVI 4 | 1988 | $12,000 | $38,060 | $1,205 | $39,265 | 3.27x | 24.1% |
The report's integral footnotes control interpretation: net IRR includes cash-on-cash return net of fees, expenses and carried interest plus UC's NAV as determined by the GP; GP valuation policies lacked a common industry standard; investment pace materially affects IRR; IRR should not measure performance until fully realized; and cross-fund IRR comparison ignores those differences. TVI 4 still had residual NAV, TVI 1 is absent, and this is one LP's experience—not audited firm-wide performance or McMurtry's economics. No average or rank is calculated.
People, capital, and decision-rights map
| person/entity | supported role | unsupported inference explicitly rejected |
|---|---|---|
| Burt McMurtry | TVI co-founder; direct board evidence for Intuit, DAVID, Mindset, VeriFone and SpectraLink; ROLM diligence/sponsorship followed by recusal. | Not the source/board owner of Microsoft or Sun; not sole owner of grouped TVI filing positions; not sole author of TVI outcomes. |
| David Marquardt | TVI co-founder; sourced Microsoft and Sun; held both boards; shared voting/dispositive power in Synaptics group. | Microsoft/Sun execution still belongs to founders/operators; group ownership is not his personal ownership. |
| Jim Bochnowski | TVI co-founder; operating background; later biotech focus and Delphi formation. | No public route opened here establishes a TVI/Bochnowski bridge to Synapse, a McMurtry-specific Synapse decision, or a loss allocation. |
| Bob Kagle | Joined TVI in 1984; shared Synaptics group control; later Benchmark co-founder. | Later Benchmark wins are not TVI or McMurtry wins. |
| John Johnston | Joined in 1988; shared Synaptics control; later August co-founder; TVI-backed Altamira evidence is Marquardt/Johnston-specific. | No automatic McMurtry credit for late TVI deals. |
| Mark Wilson | Administrative partner; shared voting/dispositive power in the Synaptics filing. | Administrative/group control does not prove sourcing or IC sponsorship. |
| TVI funds / management entities | Legal holders visible at Microsoft and Synaptics; LP fund results partly visible through UC. | Fund shares are not partner-personal holdings; company value is not distributed value. |
| Founders and executives | ROLM founders Richeson, Oshman, Loewenstern and Maxfield; Microsoft founders/operators; Intuit's Cook/Proulx; VeriFone's team; Synapse's Leslie; DAVID/Mindset teams drove company execution. | Board help must not be promoted into founder or causal company-creation credit. |
| Co-investors | Intuit included Kleiner Perkins and Sierra Ventures; Synaptics included Sprout, Oak, Kleiner and Delphi; ROLM's later IVA decision involved Dennis/Jamieson/Norris. | Syndicate participation does not reveal each party's check, vote, reserve or intervention. |
The 1990 presentation calls TVI “tightly-knit” with responsive decision-making, but it does not disclose formal voting thresholds, vetoes, reserves or deal-by-deal sponsor rules. 1990 TVI presentation, “Tightly-knit Partnership” slide
Comprehensive 33-row searched ledger
| # | company / classification | vehicle, person and contemporaneous evidence | outcome/economics control | reconstruction status |
|---|---|---|---|---|
| 1 | Adaptec — strong TVI candidate | Official biography and 1990 TVI-partner example; lead, check, security and board role unknown. | Public-company fame is not TVI proceeds. | unresolved economics/attribution |
| 2 | Altera — strong | Official biography, oral history and 1990 list; McMurtry later described TVI as an investor, without sponsor allocation. | Outcome and distributions not reconstructed. | unresolved |
| 3 | Cirrus Logic — strong | McMurtry oral history plus 1990 TVI list; vehicle/fund and lead unknown. | Public outcome cannot rank return. | unresolved |
| 4 | Compaq — strong | Official biography and 1990 partner-example list; no McMurtry-specific role. | No TVI cap table/cash flows. | unresolved |
| 5 | DAVID Systems — strong / failure lab | McMurtry joined the board around 1984 and worked roughly a decade; capital was substantial but no amount is public. | Company lost; no write-off ledger. | bounded reconstruction; Lab 4 |
| 6 | Intuit — strong / lab | 1990 financing; TVI with Kleiner/Sierra; McMurtry and Doerr boards. | McMurtry did not stand for reelection at the December 8, 2000 annual meeting; TVI return unknown; personal 1997 holdings were trust/options, not TVI. | bounded reconstruction; Lab 3 |
| 7 | Linear Technology — strong | Official biography, oral history and 1990 TVI list. | Lead, fund, security, ownership and proceeds unknown. | unresolved |
| 8 | Microsoft — strong / attribution-control lab | TVI 1–3 holder; Marquardt sourced and served on board. | 1986 snapshot: 1,378,901/6.1% pre, 294,893 listed as shares to be sold, 1,084,008/4.4% post; closing and realization unknown. | bounded reconstruction; Lab 2 |
| 9 | Mindset — strong / failure lab | LA Times names McMurtry as former board member and TVI investor. | $18m total venture funding; reported about $2m TVI loss; liquidation. | bounded reconstruction; Lab 5 |
| 10 | Nellcor — strong | Official biography and McMurtry's direct board-work recollection. | Vehicle, investment terms, interventions and proceeds unknown. | unresolved |
| 11 | PMC-Sierra / Sierra Semiconductor — strong route, lineage unresolved | Official biography says PMC Sierra; oral history says Sierra Semiconductor. | Legal successor/duplicate not proved; no company-level economics. | unresolved identity/economics |
| 12 | Quantum — strong | Official biography and 1990 TVI list; partner lead unknown. | No security, ownership, realization or distribution. | unresolved |
| 13 | SpectraLink — strong / adverse | Official biography; Intuit proxy names McMurtry as director; 2002 filing names him in derivative action. | Company litigation later settled through insurer; no wrongdoing finding located; TVI economics unknown. | partial governance/adverse reconstruction |
| 14 | Sun Microsystems — strong | Marquardt sourced at six months old and held board; TVI firm role. | No McMurtry deal role or TVI cash-flow bridge. | bounded attribution, unresolved economics |
| 15 | Synapse Computer — vehicle-unresolved / failure route | Public founder account says $35m total raised, product sold poorly, capital ran out, CEO removed, and assets sold cheaply; no opened route establishes a TVI investment or Bochnowski lead. | Investor identities, check/loss, vehicle, and board votes are not public in the processed record. | company failure bounded; vehicle unresolved |
| 16 | Synaptics — strong | TVI 3/IV and management entities bought A/B and D/E/F preferred; five named TVI people shared control. | 2,077,339/11.5% pre and 9.0% after the base offering assuming no over-allotment; if fully exercised, 154,169 offered and 1,923,170/8.4% retained; no realized net. | strongest filing reconstruction, incomplete economics |
| 17 | Synopsys — strong | Official biography, oral history and TVI association; individual sponsor unknown. | No check/ownership/distribution. | unresolved |
| 18 | VeriFone — strong / adverse | McMurtry says TVI backed it, helped recruit Tyabji and he served on board. | IPO litigation allegations dismissed with prejudice; Ninth Circuit affirmed; no wrongdoing finding. | partial governance/adverse reconstruction |
| 19 | Visio — strong | Official McMurtry portfolio biography; no fund or person role in opened primary record. | No transaction economics. | unresolved |
| 20 | Archive — vehicle-unresolved | Public partner-career/portfolio lead only; no TVI legal-vehicle bridge established. | Unknown. | excluded from strong TVI set |
| 21 | Grand Junction Networks — vehicle-unresolved | Marquardt career association; TVI versus later August route unresolved. | Cisco acquisition is not a TVI return without vehicle evidence. | vehicle unresolved |
| 22 | Symantec — vehicle-unresolved | Partner-career association; no TVI fund/security proof opened. | Unknown. | vehicle unresolved |
| 23 | Cadnetix — vehicle-unresolved | 1990 “TVI Partners” example; could be prior partner career. | Lead, vehicle and economics unknown. | vehicle unresolved |
| 24 | Outbound Systems — vehicle-unresolved | 1990 partner-example list only. | Unknown. | vehicle unresolved |
| 25 | Stratus — vehicle-unresolved | 1990 partner-example list; sector adjacency is not vehicle proof. | Unknown. | vehicle unresolved |
| 26 | Sybase — vehicle-unresolved | 1990 partner-example list only. | Unknown. | vehicle unresolved |
| 27 | KLA — non-TVI exclusion | McMurtry worked from 1975; IVA invested in a 1978 round. | Historically important, but excluded from TVI count. | IVA control |
| 28 | NBI — non-TVI exclusion | IVA investment/board work beginning 1975. | Excluded from TVI count. | IVA control |
| 29 | ROLM — non-TVI exclusion / lab | Melchor personal funding in 1969; IVA investment in 1975 after McMurtry recusal. | The approximately fortyfold public-stock recollection is an investor-at-IPO hypothetical, not IVA return. | Lab 1 |
| 30 | Triad Systems — non-TVI exclusion | IVA secondary purchase around 1979. | Excluded from TVI count. | IVA control |
| 31 | Seagate — non-TVI exclusion | 1990 partner-career example; Bochnowski/Marquardt operating-network relevance but no TVI investment proof. | Excluded absent vehicle bridge. | partner-career control |
| 32 | Rearden — non-TVI exclusion | Search lead lacks a supported TVI security/vehicle link; not silently merged with Visio. | Unknown. | excluded |
| 33 | Tandem — pass | IVA declined an opportunity offered by Kleiner Perkins. | No TVI investment; later success does not prove ex-ante irrationality. | documented IVA pass |
Sources for the ledger's public-name boundary: official Stanford PACS biography · 1990 TVI presentation, partner examples · Bancroft oral history, printed pp. 43 and 49–57 / PDF pp. 53 and 59–67. A table citation supports only those route/classification claims; individual numbers and adverse outcomes carry their own sources above and below.
Ex-ante decision labs
Decision lab 1 — ROLM: excluded IVA attribution-boundary control
Freeze the information set
In 1969 four young Rice/Stanford engineers proposed multiple products. Jack Melchor personally provided initial financing and a loan, and focused the plan; PAIC had no initial role. By 1975 ROLM was profitable in rugged minicomputers and preparing an electronic PBX for a market dominated by large firms and littered with failures. McMurtry diligenced the expansion while already owning shares. [investor-stated · strong] Bancroft, printed pp. 29–33 / PDF pp. 39–43
Decision, risks, alternatives, and rights
McMurtry disclosed the conflict, gave Dennis, Jamieson and Norris his work, recused from the IVA decision, and offered to serve if they independently approved. They did, and he joined the board. Supported risks were founder inexperience, product sprawl and a PBX market with incumbents. Passing, waiting for launch/customer evidence, or funding with milestones are [researcher inference · moderate] alternatives; terms, ownership and follow-on authority are unknown.
No-hindsight worksheet: Would you invest in the 1975 expansion? What PBX customer/field-reliability evidence kills or unlocks the deal? What security and ownership compensate for incumbent risk? Who may vote when the sponsor already owns shares?
Reveal
ROLM went public in 1976 and was acquired by IBM in 1984. McMurtry said an IPO buyer could have earned approximately fortyfold by the IBM sale, but that is not IVA's cost, ownership or distributed return. Founders Gene Richeson, Ken Oshman, Walter Loewenstern and Bob Maxfield retain execution credit. [investor-stated · moderate] Bancroft, printed pp. 34–36 / PDF pp. 44–46
Decision lab 2 — Microsoft: Marquardt-led negative attribution control
Freeze the information set
In 1980–81 Microsoft was about five years old, profitable and growing. It did not need rescue capital; it sought an outside investor it believed could help. McMurtry explicitly says Marquardt developed the relationship and TVI became the only outside investor beyond family and friends. He also says the team did not foresee the eventual scale. [investor-stated · strong] Bancroft, printed pp. 37–38 and 49 / PDF pp. 47–48 and 59
Decision, risks, alternatives, and rights
The supported favorable facts are people, profitability and growth; original valuation, check, security, downside memo, competitive analysis and IC dissent are absent. Paying for an already profitable company, staging a smaller investment, syndicating, or declining are [researcher inference · provisional] alternatives. Marquardt's board role is supported; McMurtry's direct sourcing, negotiation or board role is not.
No-hindsight worksheet: Would you invest in a profitable BASIC-language vendor before knowing the PC software outcome? What valuation/ownership would compensate for platform dependence? Which customer concentration or governance fact kills it? What milestone earns a follow-on?
Reveal
At the 1986 offering, TVI 1–3 jointly held 1,378,901 shares (6.1%); the prospectus listed 294,893 as shares to be sold and 1,084,008 (4.4%) as retained after the offering. The prospectus separately listed Marquardt-associated management shares; those were entity holdings, not proof of his personal ownership. The table supplies no closing or distribution record. [contemporaneous record · strong] Microsoft prospectus, principal and selling stockholders
Decision lab 3 — Intuit: board value versus higher valuation
Freeze the information set
By late 1990 Intuit was profitable and growing after founder-financing. Gordon Davidson recalled five offers at roughly $50m–$75m valuations; the stock sold was founder secondary intended to repay debt, not company growth capital. Scott Cook withheld the valuation/firm matching while asking Davidson's advice. [retrospective witness · moderate] eCorner transcript, PDF p. 1, lines 20–39
Decision, risks, alternatives, and rights
Davidson recommended the two lowest valuations because they came from McMurtry and Doerr and he expected their board value to outweigh price. Cook asked each for ten references and a long essay on responding to Microsoft competition; Davidson thought Doerr wrote it and McMurtry did not. The founders could instead choose a higher valuation, sell less, defer the round, or contract for advisory help—[researcher inference · moderate] alternatives. No public record quantifies expected board value or proves it caused the later outcome.
No-hindsight worksheet: Choose the $50m-quality-board offer or $75m-price offer. What references would overturn the lower-price choice? What board covenant protects founder autonomy? What Microsoft/customer evidence unlocks the next check?
Reveal
TVI, Kleiner Perkins and Sierra Ventures invested; McMurtry and Doerr joined the board. Intuit's 1997 proxy confirms McMurtry had served since August 1990 and sat on the audit committee. His reported 114,748 shares were 110,686 in a family trust plus 4,062 option shares—not TVI's position. The 2000 proxy says he was not standing for reelection at the December 8 annual meeting; that contemporaneous boundary controls over his approximate 2009 recollection of 2001. [contemporaneous record · strong] Intuit 1997 proxy, director biography and beneficial-owner footnote 6 · Intuit 2000 proxy, meeting notice and nominees
Decision lab 4 — DAVID Systems: technology without a large application
Freeze the information set
Around 1984 DAVID pursued integrated voice/data communications over telephone wiring using technically capable data-transmission methods. McMurtry joined the board. The original memo, check, security, customer pipeline, market estimate and alternatives do not survive publicly. [investor-stated · moderate] Bancroft, printed pp. 50–51 / PDF pp. 60–61
Decision, risks, alternatives, and rights
The known tension was strong engineering without an application large enough to support a company. Customer discovery before product expansion, licensing the technology, narrowing to one vertical, pausing follow-ons, or replacing the go-to-market plan are [researcher inference · moderate] alternatives. No board minutes show what was debated, and a later people-first doctrine cannot be retrofitted as the ex-ante rationale.
No-hindsight worksheet: Invest/pass? Name the first three paid-use proofs, the customer-need finding that kills the deal, a staged security/ownership plan, and the next-check milestone. At what cumulative spend should the board force an application reset?
Reveal
McMurtry said the board/company spent roughly a decade, large but unspecified capital and great effort without finding a sufficiently attractive market position; the company was ultimately lost. His claimed lesson was to ask where distinctive technology has a significant application rather than push a product into an invented market. This supports self-critique, not a dollar write-off, and does not prove a general people-first bias caused the failure. [investor-stated · moderate] Bancroft, printed pp. 50–51 / PDF pp. 60–61
Decision lab 5 — Mindset: innovation versus compatibility and stop rules
Freeze the information set
Mindset began in 1982 and built a stylish enhanced-graphics computer; the later LA Times account reports $18m of venture funding. What the TVI IC knew about compatibility, channels, applications, price and burn at each check is not public. Contemporary product praise cannot substitute for a decision memo. [contemporaneous record · moderate] Los Angeles Times, 1987 retrospective
Decision, risks, alternatives, and rights
The later outcome identifies IBM compatibility and distribution as decisive, but treating those as obvious ex-ante facts would be hindsight. A compatibility milestone, licensed graphics subsystem, vertical-video niche, smaller initial build, or stop after weak sell-through are [researcher inference · moderate] alternatives. McMurtry was a board member; the public record does not disclose the sponsor, vote, follow-ons or whether he controlled the stop decision.
No-hindsight worksheet: Would you finance a differentiated but nonstandard PC? What channel orders and software-compatibility tests unlock production? What liquidation preference/ownership fits hardware inventory risk? Which burn or sell-through result ends funding?
Reveal
Mindset entered bankruptcy proceedings in August 1985 and its assets were liquidated in 1987. The LA Times reported TVI lost about $2m and attributed to former director McMurtry the view that the investment had reached a stopping point. That is the strongest public deal-loss figure in this record, but it is a press report, not audited fund cash flows, and it does not prove the stop timing was optimal. [contemporaneous record · moderate] Los Angeles Times, “Bidding for ‘Chips’”
Decision lab 6 — Sun Microsystems: Marquardt-led early-stage control
Freeze the information set
Sun was about six months old when TVI invested in August 1982. McMurtry's later account says David Marquardt developed the relationship and served on the board. The original memo, valuation, security, ownership, customer pipeline, technical benchmark, syndicate, and McMurtry role are absent. [retrospective witness · moderate] Bancroft, printed p. 49/PDF p. 59
Decision, risks, alternatives, and rights
A young workstation company faced platform, manufacturing, channel, and incumbent risk. Waiting for reference customers, staging against a production milestone, syndicating, or passing were available in principle, but the contemporaneous choice set is unproved. Marquardt gets sourcing/board credit; TVI gets vehicle credit only at firm level; no public evidence assigns McMurtry a vote or direct work.
No-hindsight worksheet: Would you invest at six months? Which customer and system-reliability evidence unlocks the check? What price, ownership, and security compensate for platform/manufacturing risk? Who owns the board work and next-check decision?
Reveal
Sun became a famous TVI outcome, but the public record processed here supplies neither cost-to-distribution economics nor McMurtry-specific contribution. The claimed lesson is attribution discipline, not that an early-stage label predicts success; no documented process change follows. A counterfactual Marquardt absence cannot be evaluated. [researcher inference · strong]
Decision lab 7 — Synaptics: filing-rich economics, decision-poor history
Freeze the information set
Synaptics developed human-interface semiconductor and software technology, but the original TVI 3/TVI IV thesis, round-date information set, price analysis, references, and sponsor record are not public. The 2002 prospectus is a later offering record, not an ex-ante memorandum. [contemporaneous record · strong] [researcher inference · insufficient public record] Synaptics prospectus, business and principal-stockholder sections
Decision, risks, alternatives, and rights
Relevant risks would have included technical adoption, customer concentration, semiconductor cycles, manufacturing dependence, and financing duration. Passing, staging by design win, or reserving against production milestones are analytical alternatives, not recovered TVI choices. Five TVI-associated actors later shared dispositive control; the filing does not identify source, IC sponsor, or individual vote.
No-hindsight worksheet: Would you invest before knowing the IPO path? Which independent design-win and manufacturing-yield tests are required? What ownership and reserve budget fit the cycle risk? Which customer loss or burn result stops follow-on funding?
Reveal
Before the offering, the TVI group held 2,077,339 shares (11.5%). Assuming no over-allotment, the prospectus gives a 9.0% base-offering stake; in the separate full-over-allotment scenario, 154,169 shares are offered and 1,923,170 (8.4%) retained, with shared control among five associated people. It does not establish exercise, closing, later sale, distributions, or McMurtry economics. No specific original warning, capital response, governance intervention, stop rule, or later process change can be reconstructed. [contemporaneous record · strong] Synaptics prospectus, principal and selling stockholders
Decision lab 8 — Synapse Computer: vehicle-unresolved company failure
Freeze the information set
The only detailed processed account is founder Mark Leslie's retrospective company history: advanced multiprocessor transaction technology, a proprietary operating system, demanding customer requirements, and about $35m of total company fundraising. No source establishes a TVI security, Bochnowski sponsorship, McMurtry participation, original price, or decision memo. [retrospective witness · moderate] [researcher inference · insufficient public record] Leslie oral history, printed pp. 36–40/PDF pp. 38–42
Decision, risks, alternatives, and rights
The knowable risks would have included platform scope, customer-specific engineering, sales-resource burden, runway, and governance succession. Licensing components, using an existing operating system, narrowing the target segment, staging by repeatable deployments, or passing are reconstructed alternatives. Because the investor and vehicle are unresolved, no TVI vote, reserve authority, or board responsibility can be assigned.
No-hindsight worksheet: Would you invest, and through which verified vehicle? What repeatable-customer and operating-system milestones unlock funding? Which security/ownership fits platform risk? Who can change the CEO or stop capital if requirements keep expanding?
Reveal
Leslie recalled that resource consumption and exhausted capital preceded investor dissatisfaction, his removal as CEO, and a low-price asset sale. The original thesis, warning dates, round-by-round capital response, votes, and exit authority remain unknown. The claimed lesson—bound platform scope and customer variability—is a researcher reconstruction; no TVI or McMurtry process change is documented. A narrower-product counterfactual is plausible but untestable. [researcher inference · moderate]
Decision lab 9 — Tandem: IVA pass without a recovered memo
Freeze the information set
McMurtry later called Tandem IVA's major miss and said Kleiner Perkins offered the opportunity. The original team assessment, product plan, market, valuation, ownership, memo, capacity, and reason for passing were not recovered. [retrospective witness · moderate] Bancroft, printed pp. 43–44/PDF pp. 53–54
Decision, risks, alternatives, and rights
Investing, syndicating, delaying for technical/customer proof, or passing were possible, but no rationality judgment survives without the information set. Tandem belongs to IVA, not TVI; Kleiner Perkins gets referral credit, and the approving or dissenting IVA partner is unknown.
No-hindsight worksheet: Decide invest/pass without knowing Tandem's success. Which product, customer, and founder evidence is decisive? What price/ownership and staged milestone would change the answer? Which partner has capacity and voting authority?
Reveal
Tandem's later success makes the pass look costly but does not reveal whether the contemporaneous decision was wrong. There was no capital response, board intervention, or stop decision because IVA did not invest. McMurtry's retrospective description of Tandem as a major IVA miss supplies the claimed lesson; no dated process change is documented, and a funded counterfactual cannot assign IVA ownership or return. [researcher inference · strong]
Decision lab 10 — VeriFone: operating help plus dismissed allegations
Freeze the information set
McMurtry's retrospective account supports TVI backing VeriFone, his participation in recruiting a chief executive, and his board service. The original thesis, check, price, security, customer evidence, sponsor, IC vote, reserve plan, and disclosure controls are not public. [retrospective witness · moderate] Bancroft, printed pp. 49–50/PDF pp. 59–60
Decision, risks, alternatives, and rights
The reconstructed risks are payments adoption, customer/forecast volatility, executive fit, disclosure quality, and board oversight. Staging by installations, recruiting before investment, syndicating, or passing are alternatives, but none is established as TVI's ex-ante debate. McMurtry gets only the recruiting/board roles he described; company and other partner execution remain separate.
No-hindsight worksheet: Would you invest before knowing the IPO and litigation? Which merchant/customer and reporting controls unlock funding? What security, ownership, and reserves fit adoption risk? Who owns CEO recruitment, forecasts, disclosure review, and the stop/exit decision?
Reveal
After the 1990 IPO, shareholders alleged forecast and market-change nondisclosures. The district court dismissed with prejudice and the Ninth Circuit affirmed; the record is not a fraud or McMurtry-misconduct finding. The public record does not show the warning dates, capital response, board deliberation, exit economics, or any later process change. The claimed lesson is to audit forecast/disclosure governance while preserving the difference between allegations and findings. A counterfactual disclosure policy cannot be tested from the opinion. [contemporaneous record · strong] Ninth Circuit opinion
Decision lab 11 — SpectraLink: adverse-governance control without merits finding
Freeze the information set
Public biographies and later filings place McMurtry on SpectraLink's board, but the original TVI thesis, vehicle, check, price, ownership, sponsor, customer evidence, and control design are not public. A 2002 10-Q records later allegations; it cannot reconstruct what the IC knew at investment. [contemporaneous record · moderate] SpectraLink 10-Q, legal proceedings
Decision, risks, alternatives, and rights
Relevant reconstructed risks include enterprise-wireless adoption, forecast reliability, insider-sales optics, disclosure controls, and director oversight. Passing, milestone financing, independent forecast review, or enhanced trading/disclosure rules are analytical alternatives. Board membership establishes exposure, not investment sponsorship, control of challenged statements, or wrongdoing.
No-hindsight worksheet: Would you invest before the forecast revision? Which customer-retention and forecast-quality tests are required? What ownership and governance rights fit disclosure risk? Who may approve guidance, insider sales, follow-ons, and settlement?
Reveal
The 10-Q described class and derivative allegations and the company's merits defense. A 2004 report said an insurer paid a $1.5m class settlement; the processed record supplies no admission, merits finding, individual wrongdoing, original capital response, board vote, stop/exit economics, or later McMurtry process change. The claimed lesson is evidentiary: distinguish allegation, defense, payment source, and disposition. A counterfactual forecast policy remains untestable. [contemporaneous record · moderate] SpectraLink 10-Q · RCR Wireless settlement report
Portfolio-level forensics
| dimension | observed 33-row record | honest interpretation |
|---|---|---|
| Stage | Microsoft, Intuit and IVA-era ROLM were profitable exceptions; Sun was about six months old; many rows lack stage. | TVI preferred startups but accepted later profitable companies; no stage allocation is computable. |
| Sector | Semiconductors, systems, storage, networking and software dominate; TVI separated biotech into Delphi. | Information-technology focus is supported; company-list survival may exaggerate public hardware/software names. |
| Geography | Named companies are primarily U.S./West Coast, with some Colorado/Hawaii origins. | No geographic allocation or formal mandate is public. |
| Check size | Mindset's reported TVI loss is about $2m; Synaptics consideration can be partly reconstructed; most checks unknown. | No stable check policy or median can be calculated. |
| Ownership | Microsoft and Synaptics provide offering-date group snapshots. | Neither snapshot is initial target, peak ownership or realized ownership. |
| Concentration | Microsoft and Synaptics supply differently dated, partially quantified ownership snapshots; TVI IV reports net value for UC in a non-Microsoft vehicle without naming contributors. | No comparable company-contribution ranking or literal Pareto percentage. |
| Reserves/follow-ons | Synaptics shows TVI 3 and IV across rounds; DAVID and Mindset imply continued capital. | Reserve ratio, pro-rata policy and follow-on decision rights are unknown. |
| Governance | McMurtry described active service capped around six to eight boards; direct roles exist at Intuit, DAVID, Mindset, VeriFone and SpectraLink. | Board presence is a capacity constraint and exposure, not proof of causal value creation. |
| Exit/failure | IPOs, acquisitions, bankruptcy, asset sales and unresolved private outcomes all appear. | Public-success and adverse-event selection prevent a hit rate. |
| Vehicle performance | UC: TVI2 1.69x, TVI3 1.67x, TVI4 3.27x for one LP as of 2003-03-31. | Do not average/rank across funds or attribute to partners/companies; footnotes and realization state control. |
Failure, miss, and adverse-matter postmortems
DAVID Systems — application failure, not quantified write-off
Original public thesis evidence is limited to voice/data integration and capable transmission technology. The warning signal was repeated inability to find a large application despite more capital and effort. The governance response and exact stop decision are absent; McMurtry accepted substantial personal responsibility in hindsight. No later process change is documented beyond the stated marketing/application lesson. Counterfactual success in a later-evolving market cannot prove the company should have survived. Bancroft, printed pp. 50–51 / PDF pp. 60–61
Mindset — compatibility and escalation
The company had product distinction and substantial capital but lost against the IBM standard; later niche repositioning and layoffs did not save it. TVI's reported roughly $2m loss and McMurtry board role make this a material failure, while the absence of staged financing and board minutes prevents a causal allocation. Los Angeles Times, 1987
Synapse Computer — founder/board transition and long-tail product burden
Founder Mark Leslie said Synapse raised $35m, built advanced multiprocessor transaction technology, but wrote its own operating system and faced a long tail of customer requirements. Sales consumed resources, capital ran out, unhappy investors removed him as CEO, and the company was soon sold for assets at a low price. This supports product-complexity and capital-escalation lessons at the company level. No processed source establishes a TVI investment, a Bochnowski lead, McMurtry participation, an $18m TVI exposure, or who cast the removal vote. [retrospective witness · strong] [researcher inference · insufficient public record] Mark Leslie CHM oral history, printed pp. 36–40 / PDF pp. 38–42
Tandem — documented IVA pass
McMurtry called Tandem IVA's one big miss and said Kleiner Perkins offered the opportunity. Hindsight success does not recover the original memo, price, team concerns or capacity constraints, so no rationality verdict is possible. It is excluded from TVI economics. [investor-stated · moderate] Bancroft, printed pp. 43–44 / PDF pp. 53–54
VeriFone — allegations dismissed, no wrongdoing finding
McMurtry's direct account supports TVI backing, CEO recruitment participation and his board service. Shareholders later alleged forecast/market-change nondisclosures after the 1990 IPO; McMurtry appeared in the case caption. The district court dismissed with prejudice and the Ninth Circuit affirmed, holding the forecast-nondisclosure allegations nonactionable. The case is adverse governance evidence, not a finding of fraud or McMurtry misconduct. [contemporaneous record · strong] In re VeriFone Securities Litigation, 11 F.3d 865, summary and facts
SpectraLink — allegations and insurer-funded settlement, no located merits finding
SpectraLink's 2002 10-Q described class and derivative allegations over public statements, revised forecasts and insider sales; McMurtry was named in a derivative action. The company disputed merit. A 2004 report says an insurer paid a $1.5m class settlement; the opened record does not establish a wrongdoing admission or merits finding against McMurtry. [contemporaneous record · moderate] SpectraLink 10-Q, legal proceedings · RCR Wireless, 2004 settlement report
Uncertainty and retrieval ledger
| unresolved item | routes attempted / result | what would change the assessment |
|---|---|---|
| Full TVI denominator | Official McMurtry/Marquardt biographies, 1990 TVI presentation, oral histories, filings and company/partner variants; only “over 100” aggregate plus 33 raw rows. | Fund-by-fund schedules, write-off registers and follow-on dedup rules. |
| Company contribution | Microsoft/Synaptics prospectuses and UC schedule; snapshots/fund totals only. | Company cash flows, distribution notices and audited fund ledgers. |
| Individual decision rights | Oral histories, presentation and proxies; direct roles only in selected cases. | IC minutes, partner memos, board minutes and allocation records. |
| TVI terms/incentives | Vehicle history and UC LP disclosure; no partnership agreement. | LPA, fee/carry/GP-commitment, key-person, reserve and distribution terms. |
| Microsoft realized return | 1986 prospectus searched; no later TVI distribution series. | Dated sales/distributions for TVI 1–3 and original cost. |
| Synaptics realized return | 2002 424B4 gives securities, group holders and shares offered/retained. | Closing sale confirmation, later sales, distributions and fee/carry bridge. |
| Intuit economics and causal board value | Oral history, eCorner and 1997 proxy processed. | 1990 financing documents, TVI cap table, board minutes and founder contemporaneous evaluation. |
| DAVID capital/stop chronology | McMurtry's detailed retrospective processed; no company filings or memo archive located. | Financing rounds, customer data, board minutes and liquidation record. |
| Synapse TVI amount/partner action | Leslie CHM and historical company routes processed; $35m company-wide total only. | Cap table, TVI records and board minutes; an unsupported “$18m TVI involvement” must not be repeated. |
| PMC-Sierra/Sierra lineage | Official biography and oral-history names opened; legal bridge not proved. | Merger/acquisition or corporate-history filing connecting the two. |
| Archive/Grand Junction/Symantec/Cadnetix/Outbound/Stratus/Sybase | Partner-career and 1990 examples searched; fund bridge absent. | Contemporaneous financing filing, prospectus holder table or TVI schedule. |
| Adverse matters | VeriFone opinion and SpectraLink filings/settlement report processed; broad lawsuit/SEC/complaint searches also found no adjudicated McMurtry wrongdoing. | Complaints, final judgments, settlement agreements or regulatory orders assigning individual findings. |
The record is sufficient to teach attribution, governance, market/application risk and evidence discipline. It is insufficient to claim a McMurtry personal track record, rank TVI companies by realized return, compute a hit rate, or prove that a people-first style caused TVI's economic results.
Written record and evidence base
McMurtry left a small, heterogeneous written record rather than a sustained body of venture essays. This phase analyzes ten priority artifacts: two 1962 technical works, the 1984 NVCA-associated exhibit, a 1990 TVI presentation, four Stanford Board of Trustees chair messages, a short 2006 campaign statement, and one Houston speech known only through the Bancroft interview. Nine priority routes are mapped directly; the Houston item remains an unlocated artifact rather than a counted source route. Six artifacts are full text, two are abstract/catalog-level, one is a short institutional statement, and one is metadata/indirect-reference only. [contemporaneous record · strong] [researcher inference · insufficient public record] Optica abstract; Stanford report catalog; JEC hearing; Bancroft catalog
| Priority writing | Date | Attribution and legitimate access | Phase disposition |
|---|---|---|---|
| “Photomixing Experiments with a Ruby Optical Maser…” | 1962 | B. J. McMurtry and A. E. Siegman; abstract and metadata, not full article | Partial; substantive abstract-level note |
| “Modulation and Direct Demodulation of Coherent and Incoherent Light” | 1962 | Burton J. McMurtry; Stanford report catalog/preview, not full text | Partial; access boundary and formation note |
| NVCA prepared statement to the Joint Economic Committee | 1984 | Presented by McMurtry as NVCA secretary/board member; full official exhibit | Full; analyzed as association advocacy, separate from live testimony and Q&A |
| “Meet the Venture Capitalists — Technology Venture Investors” | 1990 | Firm/partner presentation; full deck | Full; analyzed as contemporaneous positioning, not a fund ledger or sole-McMurtry text |
| “Passing the Torch” | 2004 | McMurtry as Stanford board chair; full annual report | Full; governance writing |
| “A Wise Investment” | 2005 | McMurtry as Stanford board chair; full annual report | Full; governance writing |
| “Setting a Bold Agenda” | 2006 | McMurtry as Stanford board chair; full annual report | Full; governance writing |
| Stanford Challenge launch statement | 2006 | Short quotation attributed to chair McMurtry in an institutional publication | Full short statement; governance chronology only |
| “One Year Into The Stanford Challenge” | 2007 | McMurtry as Stanford board chair; full annual report | Full; governance writing |
| Houston Philosophical Society talk text | date/title unknown | Mentioned by the Bancroft interviewer; original text not found | Metadata/indirect only; exact boundary recorded |
These documents do not support a claim that McMurtry personally authored every sentence. The 1984 exhibit speaks for an industry association, while the Stanford messages are institution-facing chair communications and may have been collaboratively edited. Their safest use is to identify arguments he publicly sponsored in named roles. [researcher inference · moderate] JEC hearing, prepared statement masthead, printed p. 148/PDF p. 152; Stanford 2004 Annual Report, printed p. 16/PDF p. 18
Source-by-source analysis
1962 — “Photomixing Experiments with a Ruby Optical Maser and a Traveling-Wave Microwave Phototube”
McMurtry and A. E. Siegman report an experiment that used an improvised S-band traveling-wave phototube to observe photobeats among the modes of a coherent ruby laser. The abstract says the apparatus detected several nearest-neighbor mode separations and presents the method as potentially useful for optical-communications research. [contemporaneous record · strong]. Applied Optics 1(1), pp. 51–53, abstract and metadata
The reasoning visible in the abstract is experimental: adapt available equipment, make otherwise difficult structure measurable, report the observed range, and delimit possible applications. That is evidence of early technical practice, not evidence that McMurtry later used an identical venture-selection rule. [documented behavior · moderate] [researcher inference · provisional] Optica abstract
The accessible record does not expose the full apparatus description, error analysis, assumptions, or discussion. The decision implication is therefore narrow: technical credentials can improve a financier’s ability to ask whether a claimed signal is observable and whether the measurement setup matches the claim. It does not establish superior picking, market judgment, or returns. [researcher inference · provisional] Optica access boundary
1962 — “Modulation and Direct Demodulation of Coherent and Incoherent Light”
The Stanford Electronics Laboratories catalog identifies this report under McMurtry's name and places it in the same doctoral-era optical-communications setting as the photomixing paper. The preview does not expose enough text to reconstruct apparatus, results, error bounds, or applications. [contemporaneous record · strong] [researcher inference · insufficient public record] Google Books catalog
Its legitimate analytical contribution is chronological: McMurtry was producing advanced experimental-engineering work at Stanford in 1962. It cannot independently support later market judgment, an investment rule, or superior outcomes; those bridges remain [researcher inference · provisional].
1984 — NVCA prepared statement to the Joint Economic Committee
The written exhibit was presented by McMurtry as secretary and a board member of the National Venture Capital Association. It argues that professionally managed venture capital helps form young companies, that the entrepreneur is the indispensable actor, and that tax and compensation rules affect the supply of risk capital and entrepreneurial incentives. It supports the case with then-current descriptions of capital sources and with employment and innovation statistics attributed to government and industry studies. [contemporaneous record · strong] JEC hearing, prepared statement, printed pp. 148–165/PDF pp. 152–169
Its reasoning chain is: entrepreneurial firms produce socially valuable innovation and employment; these firms require specialized equity and governance; expected after-tax reward affects the willingness of investors and managers to accept exceptional risk; therefore a capital-gains differential and incentive-stock-option treatment should be preserved or improved. The central assumptions are behavioral sensitivity to tax rates, a meaningful funding gap for young firms, and a causal contribution from professional venture capital rather than mere selection of already-promising firms. [contemporaneous record · strong] [researcher inference · moderate] JEC hearing, printed pp. 150–165/PDF pp. 154–169
This source yields a public-policy rule, not a complete firm-level underwriting method: protect incentives for people supplying scarce entrepreneurial labor and patient risk capital. The live Q&A supplies an important check. When pressed on whether capital-gains changes had caused investment to dry up, McMurtry said he could not prove the relationship and characterized it as a strong impression. [investor-stated · strong] JEC Q&A, printed p. 192/PDF p. 196
That concession lowers the support for the exhibit’s causal policy claim without erasing the contemporaneous belief. It also shows a useful distinction between an advocacy document’s confident institutional rhetoric and McMurtry’s more qualified oral epistemics. [researcher inference · strong] Prepared statement, printed pp. 148–165/PDF pp. 152–169; Q&A, printed p. 192/PDF p. 196
1990 — “Meet the Venture Capitalists — Technology Venture Investors”
The six-page presentation publicly positions TVI as an information-technology partnership providing equity capital and active board assistance. Its selection language joins differentiated technology, important markets, capable management, and close investor involvement. [contemporaneous record · strong] TVI presentation, PDF pp. 1–6
The example list is investments “by TVI partners,” not investments by numbered TVI funds. ROLM and other prior-career examples therefore cannot be converted into a fund denominator, and the deck identifies neither individual sponsor nor cost, ownership, reserves, or proceeds. [researcher inference · strong] TVI presentation, PDF pp. 4–5
2004 — “Passing the Torch”
In his first annual-report message as Stanford’s board chair, McMurtry frames trusteeship as stewardship across leadership generations. He credits outgoing chair Isaac Stein, highlights university leadership and donor participation, and presents endowment growth, gifts, undergraduate initiatives, interdisciplinary research, and graduate education as mutually reinforcing inputs to institutional strength. [contemporaneous record · strong] Stanford 2004 Annual Report, “Passing the Torch,” printed p. 16/PDF p. 18
The message reasons from durable mission to resource allocation: a long-lived institution must preserve financial capacity while investing in people and programs that compound its ability to teach and discover. Its examples are the Campaign for Undergraduate Education, the Hewlett challenge, interdisciplinary initiatives, and graduate support; its implicit assumptions are that leadership continuity and philanthropic breadth improve execution. [contemporaneous record · strong] [researcher inference · moderate] Stanford 2004 Annual Report, printed p. 16/PDF p. 18
The operational signal is to treat governance as custody rather than personal authorship and to credit predecessor, operating leadership, faculty, and donors explicitly. Transferring that stance to venture boards is plausible but not stated in this document. [researcher inference · provisional] Stanford 2004 Annual Report, printed p. 16/PDF p. 18
2005 — “A Wise Investment”
McMurtry describes Stanford’s investments in people, undergraduate education, graduate support, and cross-school initiatives alongside a 19.5% one-year endowment return, a 15.3% three-year annualized figure, $603.6 million of gifts, and a Campaign for Undergraduate Education total of $1.1 billion. These are university figures, not McMurtry venture-fund performance. [contemporaneous record · strong] Stanford 2005 Annual Report, “A Wise Investment,” printed p. 16/PDF p. 18
The argument is portfolio-like at an institutional level: financial returns matter because they sustain investments in talent and programs, while donor participation validates and expands the resource base. Health, environment, and international initiatives illustrate a preference for problems that cross established organizational boundaries. The message assumes that financial capacity and intellectual ambition reinforce one another. [contemporaneous record · strong] [researcher inference · moderate] Stanford 2005 Annual Report, printed p. 16/PDF p. 18
The title’s “investment” language should not be reverse-engineered into a personal venture doctrine. The document supports a stewardship and human-capital orientation; it does not disclose picking criteria, price discipline, ownership targets, or exit rules. [researcher inference · strong] Stanford 2005 Annual Report, printed p. 16/PDF p. 18
2006 — “Setting a Bold Agenda”
The 2006 message connects strong recent finances to the launch of the Stanford Challenge and identifies human health, environmental sustainability, and international peace and security as major interdisciplinary priorities. It reports a 19.5% one-year endowment return and compares a 12.3% five-year annualized return with a 3.0% U.S.-stock figure, while explicitly warning that past results do not guarantee future performance. [contemporaneous record · strong] Stanford 2006 Annual Report, “Setting a Bold Agenda,” printed p. 16/PDF p. 18
The reasoning is sequencing-sensitive: favorable resources create capacity, but the institution should direct that capacity toward long-horizon missions and broad participation rather than infer effortless continuation. The past-performance warning is an unusually explicit limit on extrapolation in this writing set. [researcher inference · strong] Stanford 2006 Annual Report, printed p. 16/PDF p. 18
A historically grounded decision rule is therefore “do not confuse a strong realized period with a guaranteed prospective distribution; use capacity to pursue mission under acknowledged uncertainty.” That rule is reconstructed from a university context and is not a verbatim McMurtry venture rule. [researcher inference · moderate] Stanford 2006 Annual Report, printed p. 16/PDF p. 18
2006 — Stanford Challenge launch statement
Stanford Magazine attributes a short campaign-launch statement to board chair McMurtry. It supports his public sponsorship of long-horizon, interdisciplinary university priorities and corroborates his 2006 chair role. It does not disclose a venture investment method or establish sentence-level authorship of the surrounding institutional article. [contemporaneous record · moderate] Stanford Challenge announcement
The safe decision implication is limited to governance: name the long-duration mission that financial capacity is intended to serve. Mapping that principle to startup investing is [researcher inference · provisional] because university campaigns have different actors, fiduciary duties, and time horizons.
2007 — “One Year Into The Stanford Challenge”
One year into the campaign, McMurtry reports $832 million of gifts, a $2.9 billion campaign total, a 23.4% twelve-month endowment return, and a 17.7% five-year annualized return versus 10.7% for U.S. stocks. He credits President John Hennessy, the university team, alumni, parents, and friends, and argues that Stanford’s ability to work across disciplines is an institutional advantage. [contemporaneous record · strong] Stanford 2007 Annual Report, “One Year Into The Stanford Challenge,” printed p. 16/PDF p. 18
The reasoning combines milestones with capability: fundraising and investment performance are inputs; teams and boundary-crossing organization turn them into mission outcomes. The assumptions are that cross-disciplinary coordination produces work unavailable within silos and that broad constituency support improves durability. [contemporaneous record · strong] [researcher inference · moderate] Stanford 2007 Annual Report, printed p. 16/PDF p. 18
Across the four messages, increasing reported financial scale does not produce increasingly personal credit; the rhetoric remains distributed across management, faculty, donors, and trustees. That consistency is evidence of public governance style, not proof of private investment behavior. [documented behavior · moderate] 2004 message, printed p. 16/PDF p. 18; 2007 message, printed p. 16/PDF p. 18
Undated — Houston Philosophical Society talk text
The only located evidence is indirect: during McMurtry’s 2009 Bancroft oral history, the interviewer said she had read a Houston Philosophical Society talk and used it to ask about founder primacy. The original title, date, text, venue record, and publication status were not found in targeted exact-name, society-domain, and archive searches. [retrospective witness · moderate] [researcher inference · insufficient public record] Bancroft transcript, printed pp. 55–56 and interview timestamp 03-00:45:37 onward
The Bancroft transcript permits research use but reserves literary rights and requires written permission for publication quotation. This package therefore paraphrases the exchange and publishes no quotation from it. The reported gist—companies are built by groups rather than a lone heroic founder—can guide retrieval, but it cannot substitute for analysis of the missing speech. [retrospective witness · provisional] Bancroft transcript, rights notice at printed p. ii and discussion at printed pp. 55–56
Cross-source synthesis
People are necessary; institutions make their effort durable
The 1984 exhibit places the entrepreneur at the center of company formation, while the Stanford messages repeatedly link accomplishment to teams, leaders, faculty, donors, and governance continuity. Taken together, the stable belief is not lone-founder worship but the primacy of capable people inside enabling capital and institutional systems. [contemporaneous record · strong] [researcher inference · moderate] JEC prepared statement, printed pp. 150–153/PDF pp. 154–157; Stanford 2004 message, printed p. 16/PDF p. 18; Stanford 2007 message, printed p. 16/PDF p. 18
This supports a sourcing and governance implication: evaluate the team’s capacity to recruit, coordinate, and accept shared credit, then ask whether the board and capital design expand that capacity. It does not support ignoring market evidence merely because the people are impressive. [researcher inference · moderate] JEC prepared statement, printed pp. 148–165/PDF pp. 152–169; Stanford 2007 message, printed p. 16/PDF p. 18
Capital is an enabling input, not the protagonist
The NVCA statement argues that specialized equity and incentive structures enable entrepreneurial activity. The Stanford messages similarly describe endowment returns and gifts as means to education and research rather than terminal scores. [contemporaneous record · strong] JEC prepared statement, printed pp. 151–159/PDF pp. 155–163; Stanford 2005 message, printed p. 16/PDF p. 18
The actionable implication is to trace a dollar of capital to the specific capability or milestone it buys. The documents do not reveal McMurtry’s reserve ratios, ownership targets, or valuation ceilings, so extending the principle to those mechanics would exceed the corpus. [researcher inference · moderate] JEC prepared statement, printed pp. 148–165/PDF pp. 152–169
Measurement discipline coexists with causal humility
The 1962 abstract centers an apparatus that makes a phenomenon measurable; the 2006 chair message warns against extrapolating past financial performance; and McMurtry’s 1984 Q&A admits that a strongly held policy impression was not proved. [contemporaneous record · strong] [investor-stated · strong] Optica abstract; Stanford 2006 message, printed p. 16/PDF p. 18; JEC Q&A, printed p. 192/PDF p. 196
The resulting analyst discipline is to separate observed signal, mechanism, and advocacy. A measured correlation or a persuasive theory should not be reported as a demonstrated causal effect. [researcher inference · strong] JEC prepared statement and Q&A, printed pp. 148–165 and 192/PDF pp. 152–169 and 196
Intellectual chronology, evolution, and contradictions
- 1962 — experimental engineer. McMurtry’s co-authored paper and Stanford report catalog document work on optical measurement. They establish technical formation but no direct bridge to a venture doctrine. [documented behavior · strong] [researcher inference · insufficient public record] Optica bibliographic record · Stanford report catalog
- 1984 — industry advocate and practitioner. The prepared statement makes an ecosystem case for entrepreneurs, specialized capital, and economic incentives. The adjacent live record is more personal and more qualified, so the exhibit should not be collapsed into McMurtry’s sole-authored philosophy. [contemporaneous record · strong] JEC prepared statement, printed pp. 148–165/PDF pp. 152–169; live testimony and Q&A, printed pp. 145–147, 192, and 203/PDF pp. 149–151, 196, and 207
- 1990 — public firm positioning. The TVI deck makes technology, market, management, and board help visible as partnership criteria, but its “by TVI partners” list warns against treating marketing examples as a numbered-fund ledger. [contemporaneous record · strong] TVI presentation
- 2004–2007 — institutional steward. The chair messages and short campaign statement shift the public subject from venture formation to intergenerational governance. The recurring emphases—people, distributed credit, long horizons, and financial capacity in service of mission—are compatible with the 1984 people-centered account, but the different setting prevents a direct identity claim. [researcher inference · moderate] Stanford 2004–2007 annual-report archive items
The major contradiction is epistemic rather than philosophical: the 1984 written advocacy implies policy causation more confidently than McMurtry could defend orally. A second tension is between celebrating recent Stanford returns and warning that they cannot be projected; the warning is the stronger prospective decision rule. A third unresolved tension is authorship: public sponsorship is verified, individual sentence-level composition is not. [researcher inference · strong] [researcher inference · insufficient public record] JEC record, printed pp. 148–165 and 192/PDF pp. 152–169 and 196; Stanford 2006 message, printed p. 16/PDF p. 18
Decision playbook and modern VC translation
Historical rules reconstructed from the corpus
| Historical rule | Diagnostic questions | Boundary condition and failure mode |
|---|---|---|
| Back people, but specify the enabling system. [researcher inference · moderate] JEC, printed pp. 150–153/PDF pp. 154–157 | Who can recruit, learn, and share work? Which capital, governance, or incentive constraint blocks them? | Charisma can masquerade as capability; the writings do not authorize overlooking market or reference evidence. |
| Treat capital as milestone-producing capacity. [researcher inference · moderate] JEC, printed pp. 151–159/PDF pp. 155–163 | What new evidence or capability will the next financing buy? Why is specialized equity required? | More capital may defer a negative market verdict; no reserve or valuation rule is disclosed here. |
| Keep observation separate from causal belief. [investor-stated · strong] JEC Q&A, printed p. 192/PDF p. 196 | What is measured? What mechanism is hypothesized? What evidence would falsify it? | Advocacy incentives can harden an impression into a claim. |
| Do not project a favorable realized period automatically. [contemporaneous record · strong]. Stanford 2006 message, printed p. 16/PDF p. 18 | Which conditions generated the result? Which are repeatable? What breaks under normalization? | A disclaimer without changed sizing or hurdle rates is merely rhetorical. |
| Govern as a custodian and distribute credit. [documented behavior · moderate] Stanford 2004 and 2007 messages, printed p. 16/PDF p. 18 | Whose mission and assets are being stewarded? Are decision rights, succession, and accountability clear? | Diffuse credit must not become diffuse responsibility. |
Modern VC translation (as of 2026-08-24)
- Transfer test — people and system. What survives is the need to assess founders and the system around them; what does not transfer is using a people-first slogan as a substitute for market validation. Observable applicability signals are repeat recruiting, fast learning after disconfirming evidence, and clear decision rights. Likely misuse: funding a magnetic team indefinitely despite a missing use case. Analyst-created hypothetical: require a technically exceptional enterprise team to name the customer workflow, reference checks, and a six-month adoption falsifier before approving a Series A. [researcher inference · moderate] JEC prepared statement, printed pp. 150–153/PDF pp. 154–157
- Transfer test — capital and incentives. The enduring question is whether financing and compensation attract scarce contributors and buy a testable milestone. The historical policy prescriptions do not transfer unchanged across jurisdictions, tax regimes, or security types. Observable applicability signals are explicit hiring/technical/commercial milestones and incentive duration aligned with the build cycle. Likely misuse: invoking “patient capital” to avoid shutdown criteria. Analyst-created hypothetical: stage a deep-tech follow-on around an independently reproduced performance threshold rather than elapsed time alone. [researcher inference · moderate] JEC prepared statement, printed pp. 151–165/PDF pp. 155–169
- Transfer test — measurement. Experimental discipline survives; a 1962 apparatus does not itself validate a 2026 market. Observable applicability signals are reproducible technical benchmarks, customer-side measurements, and predeclared kill criteria. Likely misuse: optimizing a laboratory metric that users do not value. Analyst-created hypothetical: demand both third-party model-efficiency tests and evidence that the improvement reduces a buyer’s total cost. [researcher inference · provisional] Optica abstract
- Transfer test — performance humility. The non-extrapolation rule survives any market; the relevant assumptions now depend on the fund’s vintage, entry prices, liquidity path, and concentration. Observable applicability signals are scenario-weighted underwriting and an outlier-excluded portfolio view. Likely misuse: adding a disclaimer while retaining a boom-period valuation. Analyst-created hypothetical: re-underwrite an extension round using both a prior-vintage case and a slower-exit case before deciding reserves. [researcher inference · strong] Stanford 2006 message, printed p. 16/PDF p. 18
- Transfer test — stewardship. Long-horizon custody and distributed credit transfer to boards and investment partnerships. University governance does not map directly onto fiduciary duties, fund terms, or startup urgency. Observable applicability signals are explicit decision rights, succession planning, and minutes that identify owners and dissent. Likely misuse: equating consensus with accountability. Analyst-created hypothetical: record the partner sponsor, board owner, recruiting commitments, and next-check conditions at approval. [researcher inference · moderate] Stanford 2004 message, printed p. 16/PDF p. 18
Best writings and unresolved record
- NVCA prepared statement (1984): the most extensive contemporaneous written argument on entrepreneurs, venture capital, and policy, best read beside the live Q&A that qualifies causation. JEC record, printed pp. 148–165/PDF pp. 152–169
- “Setting a Bold Agenda” (2006): the clearest prospective caution against extrapolating realized performance, embedded in a long-horizon stewardship message. Stanford 2006 Annual Report, printed p. 16/PDF p. 18
- “Passing the Torch” (2004): strongest evidence of succession, custody, and distributed-credit language at the start of his chairmanship. Stanford 2004 Annual Report, printed p. 16/PDF p. 18
- 1962 photomixing paper: earliest direct evidence of McMurtry’s experimental engineering formation, with the decisive limitation that only abstract and metadata were available. Optica abstract
- “One Year Into The Stanford Challenge” (2007): clearest late-chair example of pairing quantitative milestones with team credit and cross-disciplinary capability. Stanford 2007 Annual Report, printed p. 16/PDF p. 18
The highest-value unresolved item is the Houston Philosophical Society speech: neither the original nor trustworthy metadata was found, so its content remains insufficient public record. Full access to the 1962 paper could materially refine the account of McMurtry’s experimental method. Drafting/editing records for the NVCA exhibit and Stanford messages would clarify authorship. No public corpus located here resolves pricing, ownership, reserve, or exit rules; those should be learned from deal and oral-history evidence rather than invented from governance prose.
Spoken record and coverage boundary
The priority spoken-source denominator contains three content-bearing direct-voice records and three archival/event routes. McMurtry’s 2009 Bancroft oral history, his live opening and Q&A in the 1984 Joint Economic Committee hearing, and the 2002 Computer History Museum panel can be analyzed. A 2009 Stanford trustees event survives only in a reported article. Rice’s 2009 “Sneak Peek” and François Mitterrand’s 1984 Stanford visit have event or image evidence but no verified McMurtry speaking turn; they are included to prevent metadata from becoming a fabricated appearance. [contemporaneous record · strong] [researcher inference · insufficient public record] Bancroft catalog; JEC official hearing; CHM event page; Rice event notice; Stanford Engineering Mitterrand visit page
| Priority appearance or route | Date | Access and transcript status | Disposition |
|---|---|---|---|
| JEC live testimony and Q&A | 1984-08-28 | Full official record, printed pp. 145–147 plus Q&A; separate written exhibit at pp. 148–165 | Deeply analyzed; direct contemporaneous voice |
| Mitterrand visit to Stanford CIS | 1984 | Official retrospective page and group photo only | Route note; McMurtry’s presence is visible, speaking turn unverified |
| CHM “Pioneers of Venture Capital” | 2002-09-30 | Full video; machine-generated YouTube captions | Deeply analyzed; caption wording treated cautiously |
| Bancroft oral history | interviews in 2009 | Full transcript; cataloged audiovisual media not reviewed | Deeply analyzed through paraphrase; publication quotation requires permission |
| Stanford Historical Society trustees event | reported 2009-12-03 | Secondary news report; no recording/transcript found | Partially analyzed as reported remarks |
| Rice colleges “Sneak Peek” | 2009-09-08 | News notice plus archive DVD catalog metadata; content not digitized | Route note; McMurtry appearance or remarks unverified |
The JEC split is essential. Printed pp. 145–147/PDF pp. 149–151 are McMurtry’s live opening; printed pp. 148–165/PDF pp. 152–169 are a prepared NVCA exhibit analyzed in writings.md; later pages are committee Q&A. A claim found in the prepared exhibit is not automatically a spontaneous statement, while the people-first answer at printed p. 203 is PDF p. 207—not printed p. 207. JEC official hearing
Source-by-source guide
1984 Joint Economic Committee — live opening and Q&A
McMurtry’s live opening gives a compact contemporaneous biography: Rice and Stanford education, work at GTE/Sylvania, entry into venture capital in 1969, involvement with ROLM, and a 1973–1974 fundraising effort that closed at $19 million. He described that vehicle as roughly one-third of all venture capital invested in 1974 and said its early-stage focus was primarily in the western United States. [investor-stated · strong] [researcher inference · provisional] The statement is contemporaneous; the market-share estimate lacks a supplied denominator. Live opening, printed pp. 145–147/PDF pp. 149–151
His live causal account places entrepreneurs, not financiers, at the center of company formation. During Q&A he elaborates on the geographic and educational mobility of entrepreneurs and tells the committee that the people are the critical element. [investor-stated · strong] Q&A, printed pp. 200–203/PDF pp. 204–207; people line at printed p. 203/PDF p. 207
The oral exchange is also more epistemically cautious than the prepared exhibit. Asked about the effect of capital-gains policy, McMurtry said he could not prove the proposed causal relationship and presented it as a strong impression. [investor-stated · strong] Q&A, printed p. 192/PDF p. 196
The practical lesson is to distinguish a people-centered selection belief from an ecosystem-policy mechanism. The former is direct and repeated; the latter is asserted with an explicit proof limitation. [researcher inference · strong] Live opening and Q&A, printed pp. 145–147, 192, and 203/PDF pp. 149–151, 196, and 207
1984 Mitterrand visit — presence verified, turn unverified
Stanford Engineering’s history of the Center for Integrated Systems identifies a 1984 visit by French President François Mitterrand and includes a group photo in which McMurtry is identified among many attendees. That supports presence, not a conference speech or conversation. [contemporaneous record · strong] [researcher inference · insufficient public record]. Stanford Engineering, “Bridging Worlds: Chips, Code and Cosmos,” Mitterrand visit section
No program, transcript, recording, or remarks attributable to McMurtry were located. The event therefore contributes network and institutional context only; it yields no philosophy or decision rule. [researcher inference · strong] Stanford Engineering visit page
2002 Computer History Museum — “Pioneers of Venture Capital”
The official event page lists McMurtry with William Draper III, Franklin “Pitch” Johnson, Thomas Perkins, Arthur Rock, and Don Valentine, moderated by Gordon Davidson. [contemporaneous record · strong] CHM event page, event metadata and speaker list
At approximately 33:25–35:53, McMurtry says he spent about twelve years at Sylvania/GTE, wanted to work with small companies, joined Jack Melchor in 1969 without expecting venture capital to become a permanent career, and learned patience in a capital-starved era: the group waited six years and two months for its first realized gain. [investor-stated · moderate] The account is retrospective and the available captions are machine-generated. CHM video, 33:25–35:53
At approximately 48:56–50:28 he treats ROLM as the first large success, describes four founders and separates Jack Melchor's early personal financing from IVA's later participation, recalls a 1976 public offering and an extended period below the offer price, and gives a buyer-return illustration through the later IBM sale. [retrospective witness · moderate] CHM video, 48:56–50:28
The panel is useful for timing, capital scarcity, and patience, but not reliable enough for an unaudited return figure. Its ROLM buyer-return recollection differs from the later Bancroft recollection, so both are preserved as retrospective claims rather than reconciled by choosing the larger number. [researcher inference · strong] CHM video, 48:56–50:28; Bancroft transcript, buyer illustration at printed pp. 34–35/PDF pp. 44–45
2009 Bancroft oral history — the richest retrospective record
The oral history gives McMurtry’s most detailed public retrospective account of firm formation, people, diligence, boards, and individual deals. The catalog describes interviews recorded in 2009, a transcript of x plus 71 pages, and four videodiscs; it also warns that oral history is partisan and is not a final, verified, complete account. [retrospective witness · moderate] Bancroft catalog
On ROLM, McMurtry describes two distinct stages: Jack Melchor personally financed and helped form the company in 1969, while the Palo Alto Investment Company was not an initial investor; in 1975 McMurtry investigated a PBX opportunity, disclosed his personal conflict, recused himself from IVA’s decision, and later joined the board after his partners approved the investment. [retrospective witness · moderate] Bancroft transcript, printed pp. 29–33; interview timestamps 02-00:24:48–02-00:34:22
He recalls an early vehicle of roughly $3 million, sixteen startups, losses on about half, and more than six years before the first distribution. Later he credits Dave Marquardt for Microsoft and Sun rather than absorbing partner work into his own record. [retrospective witness · moderate] Bancroft transcript, printed pp. 34–40 and 49–51
The decision process he recounts combines people, market, technology, and references; he says compelling people could bias him into mistakes, cites DAVID Systems as a decade-long failure to find a market application, and describes a rotating skeptic when TVI partners were unanimous. [retrospective witness · moderate] Bancroft transcript, printed pp. 37–40 and 49–54; interview timestamps 02-00:47:01–02-00:56:58 and 03-00:25:30–03-00:44:14
His board model is active but capacity-limited: help build the company, do not displace the operating team, and limit active boards to roughly six to eight. [retrospective witness · moderate] Bancroft transcript, printed pp. 55–57; interview timestamps 03-00:45:37–03-00:54:18
No transcript quotation is reproduced here. The rights notice permits research use but reserves literary rights and requires written permission for publication quotation. Bancroft transcript, rights notice at printed p. ii
2009 Stanford Historical Society — trustees and institutional governance
A Stanford Review report says McMurtry and Leslie Hume discussed how the Board of Trustees works. The article attributes to McMurtry a custodial view of the university’s endowment and property, shared trustee authority and liability, the presidential-search structure, and concern that tuition lacked a sustainable long-term program. [contemporaneous record · moderate]. Stanford Review, “Trustees Share Inner Workings of Board,” 2009-12-03
This source reinforces long-horizon stewardship and decision-rights themes but is a secondary report, not a verbatim transcript. It is evidence of governance views, not direct evidence of venture picking or board outcomes. [researcher inference · moderate] Stanford Review event report
2009 Rice “Sneak Peek” — archive route, not a verified appearance
Rice announced an open house at Duncan and McMurtry colleges for September 8, 2009. The notice names the buildings and event logistics, not Burt McMurtry as an attendee or speaker. [contemporaneous record · strong] [researcher inference · insufficient public record] Rice News, 2009-09-03
Rice’s archive catalog lists a DVD titled for the Burton and Deedee McMurtry College “Sneak Peek” ceremony, dated 2009-09-08, in Box 38. The catalog is a legitimate retrieval route but does not expose the video’s content online. [contemporaneous record · strong] Woodson Research Center catalog, Box 38/top container record
Until the DVD is reviewed, no appearance, quotation, or philosophy can be attributed to McMurtry. [researcher inference · strong]
Recurring frameworks, evolution, and contradictions
From entrepreneur centrality to a four-part diligence system
The 1984 record says entrepreneurs drive company formation and identifies people as the critical element. The 2009 oral history adds the limiting mechanism: people must be tested alongside market, technology, and references, and McMurtry’s attraction to capable people could itself cause errors. [investor-stated · strong] [retrospective witness · moderate] JEC, printed pp. 145–147 and 203/PDF pp. 149–151 and 207; Bancroft, printed pp. 37–40 and 51–54
The evolution is better read as added guardrails than a reversal: people remain central, but DAVID Systems becomes a counterexample showing that effort, talent, and capital cannot manufacture a use case. [researcher inference · moderate] Bancroft, printed pp. 49–54
Patience is conditioned by scarce capital and board capacity
CHM and Bancroft both recall more than six years before the first realized gain, placing patience inside an early market with little available venture capital. Bancroft then adds a capacity constraint—only six to eight active boards—and says fund size followed the work the partners could do. [retrospective witness · moderate] CHM video, 33:25–35:53; Bancroft, printed pp. 34–36 and 55–57
This is not a general rule to wait indefinitely. The DAVID Systems account is counterevidence: long support without a market can consume a decade. [researcher inference · moderate] Bancroft, printed pp. 49–51
Team attribution and dissent mechanisms
McMurtry credits Marquardt for Microsoft and Sun, attributes ROLM’s initial financing to Melchor, and describes recusing himself when IVA later considered a conflicted ROLM investment. He also recalls TVI appointing a skeptic when consensus arrived too easily. [retrospective witness · moderate] Bancroft, printed pp. 29–33, 49–54
The supported decision rule is to name the sponsor, separate personal and fund decisions, disclose conflicts, and institutionalize dissent. The record does not establish how consistently these practices operated across the full portfolio. [researcher inference · moderate] Bancroft, printed pp. 29–33 and 51–54
Retrospective numbers conflict
The 1984 live testimony calls IVA’s $19 million roughly one-third of venture capital invested in 1974; the 2009 oral history recalls more than one-fifth of money raised in that year. The measures may differ—invested versus raised—but neither denominator is supplied, so the discrepancy remains unresolved. [investor-stated · strong] [retrospective witness · moderate] [researcher inference · provisional] JEC live opening, printed p. 146/PDF p. 150; Bancroft, printed pp. 44–45
CHM and Bancroft also give different retrospective ROLM buyer-return multiples. Those figures should never appear as bare audited returns. [retrospective witness · provisional] CHM video, 48:56–50:28; Bancroft, printed pp. 34–35/PDF pp. 44–45
Biography and deal-rationale ledger
| Event or deal | What the spoken record supports | Attribution limit |
|---|---|---|
| Entry to VC, 1969 | After Sylvania/GTE, McMurtry joined Jack Melchor seeking small-company work; he did not initially expect a permanent VC career. CHM 33:25–35:53 | Retrospective; exact employment transition should be checked against records. |
| ROLM, 1969 | Melchor personally financed and helped form it; PAIC was not the initial investor. Bancroft printed pp. 29–33 | McMurtry was connected personally, but this was not initially an IVA deal. |
| ROLM PBX investment, 1975 | McMurtry investigated the opportunity, disclosed a personal conflict, recused from IVA approval, then served on the board. Bancroft printed pp. 29–33 | Partners Dennis, Jamieson, and Norris held approval credit in McMurtry’s account. |
| Microsoft and Sun | McMurtry assigns principal venture credit to Dave Marquardt. Bancroft printed pp. 37–40 and 49–51 | Do not list these as McMurtry-led without independent evidence. |
| DAVID Systems | Approximately decade-long effort failed to find a market application despite work and capital. Bancroft printed pp. 49–51 | Retrospective postmortem; financing, decision chronology, and shutdown details remain missing. |
Listen or read these five first
- Bancroft oral history: richest decision-process and attribution evidence; read with the catalog’s oral-history warning and the transcript’s no-publication-quotation condition. Catalog
- JEC live opening and Q&A: best contemporaneous direct voice and the cleanest check against later memory; use printed/PDF page mapping. Official hearing
- CHM panel: best audible retrospective on entry, capital scarcity, patience, and ROLM; auto-captions require checking the video around every locator. Official event
- Stanford trustees event report: concise governance complement, but read as journalist-mediated speech rather than transcript. Stanford Review
- Rice archive catalog route: not listenable online; consult fifth because reviewing the Box 38 DVD is the most concrete path to confirm or reject a claimed appearance. Rice archive catalog
Only three items are presently listenable/readable direct-voice records; padding the list with the Mitterrand photo or asserting five substantive talks would misstate the archive.
Unresolved appearances and retrieval priorities
- Rice, 2009-09-08: request or review the Box 38 DVD through the Woodson Research Center before attributing attendance or remarks. Archive route
- Mitterrand, 1984: seek a CIS program, contemporaneous press, or audiovisual collection; the official photograph verifies presence only. Stanford Engineering route
- Bancroft audiovisual media: the transcript was processed, but the cataloged four videodiscs were not reviewed; they could resolve tone or transcription issues, not publication rights. Bancroft catalog
- CHM transcript: creator-provided subtitles or an official transcript were not found; available captions were machine-generated and material wording should be checked against audio.
- Stanford trustees event: no recording or verbatim transcript was located; the secondary article cannot support fine-grained quotation or full-context analysis.
Follow builders with earned ground truth, not capital
- Rule — Treat capital as enabler, not enterprise origin; source capable builders through traceable relationships, then require independent customer, technical, and role evidence.
- Evidence status — [investor-stated · strong] [retrospective witness · moderate]. Relationships and geography are access mechanisms, not proven alpha.
- Provenance and origin — The 1984 hearing made people the critical element and described a locally concentrated book; the 2009 oral history supplied reciprocal and contrary-reference mechanics. JEC, printed pp. 145–147 and 203 · Bancroft, printed pp. 51–57
- Mechanism and reasoning — Relationships reveal tacit evidence and lower search cost; reciprocal diligence tests investor value; independent references prevent familiarity from becoming the conclusion. Access without falsifiable information does not work.
- Historical and vehicle context — The rule emerged in a small 1969–84 West Coast electronics network under Melchor's PAIC, then institutional IVA/TVI. TVI's reported 80% Bay Area/99% West mix is behavior and constraint, not a timeless radius. JEC
- When to use — Use when team quality and technical/customer facts are tacit and the investor offers specific work. Do not use relationship strength as integrity, market, price, or inclusion proxy.
- How to apply it — Log provenance and unique evidence; sample outside the network; run role/customer references; invite founder reverse diligence; name reversal evidence; reject if relationship confidence fails independent facts.
- Examples —
- ROLM — documented relationship; researcher-applied model. Sylvania ties created ground truth, but Melchor supplied initial capital, unconflicted IVA partners approved later, and founders built. McMurtry, printed pp. 30–33 · Maxfield, around p. 77
- Intuit — independent retrospective witness. Founders reportedly chose lower-valued Doerr/McMurtry proposals for expected board value after references; expectation is not causal outcome proof. Davidson, PDF p. 1 · proxy
- DAVID — counterexample. Long board involvement and people/technology confidence did not create a compelling application. Bancroft, printed pp. 50–51
- Evidence — Four placements across JEC, McMurtry/Maxfield ROLM accounts, Davidson/Intuit, and DAVID support belief, selected behavior, and failure boundaries; they do not establish a matched return advantage.
- Limits, failure modes, and exception ledger — DAVID defeats “people are enough”; local sourcing can create homophily; founder choice does not prove board efficacy; Microsoft/Sun are Marquardt-led controls. Complete non-network funnels and ordinary reference files are missing.
- Evolution and contradictions — The 1984 people/capital view persists in 2009, but DAVID and overdeployment make the mature story less absolute; national shortage advocacy also sits beside local abundance. [researcher inference · moderate] talks
- Modern VC translation (as of 2026-08-24) — [researcher inference · moderate]. Preserve traceable ground truth, reciprocal diligence, and non-network audits; discard literal Valley radius. Signals: tacit facts and specific help. Misuse: prestige underwriting. Hypothetical: a distributed fund names local experts/customers able to falsify remote enthusiasm.
Require important application and defensibility; novel science is optional
- Rule — Fund technology only when it serves an important paid application and has a supportable proprietary advantage; novelty is neither necessary nor sufficient.
- Evidence status — [contemporaneous record · strong] [retrospective witness · moderate]. The first component is a McMurtry-presented/NVCA-associated position; personal and systematic application remains [researcher inference · insufficient public record].
- Provenance and origin — The 1984 McMurtry-presented/NVCA-associated statement emphasized application/proprietary position; the 2009 DAVID account supplied the failure boundary. JEC, printed pp. 148–165 · Bancroft, printed pp. 50–51
- Mechanism and reasoning — Paid urgency turns capability into workflow value; defensibility preserves surplus. Technical elegance without a buyer encourages repositioning and sunk-cost financing.
- Historical and vehicle context — Electronics/systems faced incumbents, manufacturing, distribution, long commercialization, and finite funds. McMurtry's 1962 photomixing work proves technical training only, not doctrine causation. Optica abstract
- When to use — Use for deep tech, systems, infrastructure, and software where differentiation can be mistaken for business. Demand stage-appropriate evidence, not mature revenue at inception.
- How to apply it — Name buyer/job/alternative/adoption cost; define proprietary element; pre-register paid-use, reliability, retention, and margin gates; stage capital; narrow or stop after repeated application failure.
- Examples —
- ROLM — researcher-applied. PBX expansion mapped computing to telecommunications amid incumbents; original customer/moat work is absent. ROLM lab
- DAVID — documented failure boundary. McMurtry later said substantial effort never found a compelling application. Bancroft, printed pp. 50–51
- Mindset — researcher-applied boundary. Graphics differentiated, while manufacturing/platform/distribution risks are reconstructed; bankruptcy/liquidation is contemporaneously documented. Los Angeles Times
- Evidence — JEC doctrine, DAVID self-critique, Mindset reporting, and McMurtry/Maxfield ROLM accounts supply four placements across four source families; only DAVID explicitly links failure to missing application.
- Limits, failure modes, and exception ledger — Application does not prove moat, price, execution, or return. Microsoft illustrates profitable application only at TVI/Marquardt level. No original ROLM/DAVID/Mindset threshold files survive.
- Evolution and contradictions — Technical formation makes the rule plausible, not causal. The affirmative 1984 doctrine becomes a sharper 2009 failure lesson; no dated process change is documented. [researcher inference · moderate]
- Modern VC translation (as of 2026-08-24) — [researcher inference · moderate]. Transfer buyer urgency, paid adoption, defensibility, and staged milestones; common AI-model access is not a moat. Signals: repeated paid use, proprietary rights, switching cost. Misuse: mature metrics on science. Hypothetical: fund a pilot against reliability/customer gates.
Engineer dissent and conflict-clean decision rights
- Rule — Assign an independent skeptic before consensus hardens, chase contrary references, disclose conflicts, and separate sponsor from approver when impartiality is impaired.
- Evidence status — [retrospective witness · moderate] [researcher inference · provisional]. ROLM documents one conflict pattern; ordinary TVI IC use is unproved.
- Provenance and origin — The 1975 ROLM disclosure/recusal is earliest observed; the 2009 oral history is the earliest located articulation of assigned skepticism and negative references. Bancroft, printed pp. 30–32 and 51–57
- Mechanism and reasoning — Independent incentives reduce sponsor bias/cascades; explicit rights keep a conflicted source from approval; stored falsifiers enable learning. Performative objection without authority does not.
- Historical and vehicle context — Small partnerships mixed personal holdings, relationships, diligence, votes, and boards. Recusal worked only if unconflicted partners retained real authority.
- When to use — Use for unanimity, related interests, competitive overlaps, founder secondary, follow-ons after bad news, and board/LP conflicts. Appoint a skeptic with time, access, and independence.
- How to apply it — Store pre-votes; name sponsor/skeptic/approver/legal right; disclose holdings; set recusal/barriers; state falsifier/owner; minute resolution; reopen at follow-on/exit.
- Examples —
- ROLM — documented application. McMurtry disclosed personal shareholding/PAIC-related involvement and withdrew; Dennis, Jamieson, and Norris approved; he then boarded. McMurtry · Maxfield
- DAVID — exception/unknown. No evidence shows an assigned skeptic, negative reference, or application veto at entry/follow-on. Bancroft
- Stanford presidential search — cross-domain behavior. A report describes extensive references/equal trustee responsibility; it is not TVI investment application evidence. Stanford Review
- Evidence — McMurtry's ROLM/process account, Maxfield's independent ROLM history, Stanford's report, and a Synaptics filing showing five principals shared authority provide four placements; shared authority is not dissent proof.
- Limits, failure modes, and exception ledger — No IC memo names a skeptic/reference/vote change; later narrative may clean up tension. Attempted routes/results: Bancroft—rule/ROLM only; JEC—people advocacy, no IC mechanics; CHM—compressed ROLM; 1990 TVI presentation—names, no votes; Microsoft/Intuit/Synaptics filings—entities/holdings, no dissent; university/museum catalogs—no TVI files; adverse searches—no IC archive. Missing proof: an ordinary dated skeptic assignment that changed a decision.
- Evolution and contradictions — Observed 1975 recusal predates articulated 2009 rule; no adoption date. DAVID/overdeployment show non-use or insufficiency; friendly shared authority can suppress dissent. [researcher inference · provisional]
- Modern VC translation (as of 2026-08-24) — [researcher inference · strong]. Assign dissent before consensus; split sponsor/approver; log conflicts/falsifiers. Signals: concentrated advocacy/related economics/sunk cost. Misuse: AI red-team text without independent incentives. Hypothetical: sponsor supplies evidence then leaves the vote.
Price partner attention: active governance is the product and capacity is the constraint
- Rule — Accept active governance only when a named partner has time and a specific intervention thesis; size portfolio/fund to that attention budget, not available capital.
- Evidence status — [investor-stated · strong] [researcher inference · moderate]. Board presence is not causal value.
- Provenance and origin — In 1984 McMurtry reported boards in about 70% of forty companies and active seven-to-ten-year work; in 2009 he remembered six-to-eight boards per partner and admitted overdeployment. JEC · Bancroft, printed pp. 55–57/PDF pp. 65–67
- Mechanism and reasoning — Senior time can improve recruiting, prioritization, financing, and crises only with skill/authority. More companies dilute observation and intervention speed; attention becomes scarce reserve.
- Historical and vehicle context — Small partnerships paired boards with hardware/system companies; successive funds scaled capital faster than partner time. Modern platform/observer structures redistribute work but need accountable owners.
- When to use — Use when thesis needs recruiting, enterprise/customer, regulatory, or technical milestone work. Do not take status seats or promise work delegated without ownership.
- How to apply it — Name board owner, intervention thesis, hours, rights, support, milestones, travel, conflicts, handoff; stress downside capacity; reject/resize breaches.
- Examples —
- ROLM — documented board; efficacy inferred. McMurtry served after unconflicted approval; founders and intervention effects remain separate. CHM, 48:56–50:28
- Intuit — founder-priced expectation. Davidson recalled founders accepting lower valuation for expected Doerr/McMurtry help; proxy proves board date, not causality. Davidson · proxy
- DAVID — counterexample. Roughly a decade of board work did not produce a compelling application. Bancroft
- Evidence — JEC board snapshot, Bancroft capacity/overdeployment, Davidson/Intuit, and contemporary Mindset reporting provide four source families; they support practice/limits, not matched efficacy.
- Limits, failure modes, and exception ledger — TVI violated capacity logic; DAVID/Mindset show attention cannot create demand/rescue; SpectraLink is adverse board control. Calendars, intervention logs, fund construction, and matched inactive cases are missing.
- Evolution and contradictions — 1984 scale/board claim precedes later ceiling/self-critique; no proof the ceiling was enforced or learned from a specific case. Stanford governance is cross-domain only. [researcher inference · moderate]
- Modern VC translation (as of 2026-08-24) — [researcher inference · moderate]. Transfer owners, stressed hours, interventions, handoffs; not six-to-eight universal. Signal: thesis depends on senior work and rights. Misuse: seat collection/hidden delegation. Hypothetical: IC drops a deal that breaches downside-hour capacity.
Be patient only while a testable recovery path exists
- Rule — Match capital/duration to company building, but continue only while explicit product, customer, leadership, financing, sale, or liquidation branches remain credible and testable.
- Evidence status — [contemporaneous record · strong] [researcher inference · moderate]. The duration premise is McMurtry-presented/NVCA-associated; the joined stop rule is synthesis and original kill criteria/minutes are absent.
- Provenance and origin — The 1984 McMurtry-presented/NVCA-associated statement described seven-to-ten-year building; CHM supplied ROLM patience; Mindset supplied recovery framing; DAVID exposed escalation. JEC · CHM · Mindset
- Mechanism and reasoning — Long risks require time; staged falsifiers distinguish duration from sunk cost; alternative branches preserve option value and force terminal judgment.
- Historical and vehicle context — PAIC reportedly waited over six years for cash; IVA waited roughly fifteen months after close before investing; finite TVI funds then met boom/exit pressure. These are remembered, not audited returns. Bancroft
- When to use — Use where technical/regulatory/enterprise risk retires through dated evidence. Do not use when application is undefined, learning stops, leadership cannot adapt, or reserves cannot fund the next falsifier.
- How to apply it — Build risk calendar/reserves; define continue/repair/recruit/narrow/sell/stop; set customer/reliability/hiring/cash gates; hold independent follow-on reviews; stop when no funded branch remains.
- Examples —
- ROLM — researcher-applied successful duration. Participant accounts describe a long build; exact milestones/follow-ons/economics are absent. CHM · Maxfield
- DAVID — escalation counterexample. Roughly a decade and substantial unquantified capital did not yield compelling application. Bancroft
- Mindset — terminal case. Bankruptcy/liquidation followed about $18m reported funding; the record cannot prove liquidation timing optimal. Los Angeles Times
- Evidence — JEC duration doctrine, CHM ROLM, Bancroft DAVID/overdeployment, and Mindset report provide four placements across four families.
- Limits, failure modes, and exception ledger — Patience becomes sunk cost; closed exits can force duration; liquidation can be early/late. Original reserves, votes, milestones, alternatives, recoveries, and process changes are missing.
- Evolution and contradictions — Strong 1984 patience becomes balanced through DAVID/Mindset/overdeployment; no dated change proves learning. The combined rule is synthesis, not a quote. [researcher inference · moderate]
- Modern VC translation (as of 2026-08-24) — [researcher inference · moderate]. Transfer duration/reserve matching, falsifiers, recovery branches; reject unconditional follow-ons. Signals: measurable risk retirement/financed optionality. Misuse: endurance as evidence. Hypothetical: next check requires reliability/customer gates or executes narrow/sale branch.
Underwrite asymmetric payoffs with honest denominators
- Rule — Require upside sufficient for duration/failures, but rank only from attributable cash flows; separate company, vehicle, LP, partner, and paper-value evidence.
- Evidence status — [contemporaneous record · strong] [documented behavior · moderate] [researcher inference · insufficient public record]. The payoff premise is McMurtry-presented/NVCA-associated; complete TVI/personal cash flows are absent.
- Provenance and origin — The 1984 McMurtry-presented/NVCA-associated statement said winners compensate for failures/time; filings and UC data bound evidence instead of validating personal performance. JEC · UC
- Mechanism and reasoning — Many failures are tolerable only if ownership/dilution/reserves/exits permit rare gains; honest denominators prevent survivor lists/IPO marks/firm associations becoming alpha.
- Historical and vehicle context — Four TVI funds and >100 reported investments; Microsoft crossed TVI-1/2/3; UC shows only TVI-2/3/4 for one LP; TVI-1/company contributions are absent. Microsoft prospectus
- When to use — Use for construction, reserves, attribution, and winner claims. Do not rank from entry/exit valuations without ownership, dilution, cash flow, timing, and fee basis.
- How to apply it — Build vehicle/company ledger; record role owners; model check/ownership/dilution/reserves/proceeds/timing/fees/carry/NAV; label paper/realized; stress ex-outlier; say not computable when fields fail.
- Examples —
- Microsoft — firm snapshot/personal negative control. TVI held 1,378,901 shares before the offering; the prospectus listed 294,893 as shares to be sold and 1,084,008 as retained after the offering. Marquardt led; closing, distribution, and realized multiple remain unknown. prospectus · Marquardt
- Mindset — bounded loss. Press reported roughly $2m TVI loss, not audited cash flow. Los Angeles Times
- DAVID / UC — failure and vehicle layers. DAVID capital unquantified; UC reports net LP results with integral warnings. Bancroft · UC
- Evidence — JEC payoff statement, Microsoft filing/Marquardt attribution, UC LP schedule, and Mindset provide at least four placements and four source families.
- Limits, failure modes, and exception ledger — >100 is inexact firm floor; 33 raw rows are not coverage; TVI-1 absent; Microsoft spans three funds; UC is one LP; paper shares are not distributions; carry unknown. No ex-Microsoft test is possible.
- Evolution and contradictions — The 1984 payoff doctrine survives, but later many-losers/no-improvement admissions weaken mastery claims. Ownership snapshots exceed realized-performance evidence. [researcher inference · strong]
- Modern VC translation (as of 2026-08-24) — [researcher inference · strong]. Transfer ownership/reserve math, cash-flow attribution, ex-outlier stress; reject famous-winner résumé transfer. Signals: concentrated thesis/incomplete marks. Misuse: valuation multiplication or DPI/TVPI/IRR collapse. Hypothetical: allocator removes largest paper mark and refuses partner inference without roles.
Evidence gaps and candidate models
The six-model inventory reconciles writings, talks, investments, and the philosophy index. Entrepreneur primacy/references/geography merge into ground truth; capital/boards/fund size merge into attention; duration/liquidation merge into recovery; payoff/attribution merge into denominator honesty.
| excluded candidate | why not standalone | attempted route / missing proof |
|---|---|---|
| 1962 experimental reuse | coauthored abstract; no three venture links | Optica/Stanford; division of labor and causal use absent |
| Capital-gains/options policy | advocacy with conceded uncertainty | JEC live/prepared/Q&A; no response ledger |
| Stanford stewardship | one non-venture institution | 2004–07 messages/2009 report; no TVI application chain |
| Succession/bounded agendas | no three investment cases | Stanford/Carnegie/Rice; no TVI succession decisions |
| Overseas avoidance | one historical behavior | JEC/Bancroft; merged into ground truth |
| Founder reverse diligence | supported but duplicate | Bancroft/Intuit; merged into ground truth/dissent |
| Quick-IPO discipline | cycle commentary only | CHM/Bancroft; merged into recovery |
| Person/team attribution | research discipline, not own maxim | filings/oral histories; no direct rule |
| “Technical founders win” / “boards create alpha” | counterevidence and matched controls absent | DAVID, Mindset, overdeployment reject promotion |
Add a model only if original IC/reference/board files or independent ordinary cases establish a reusable rule, three grounded applications including failure, four useful citation placements, and two independent source families.
What the evidence supports
The defensible thesis is narrower than the pioneer legend. McMurtry brought engineering and operating experience into early Silicon Valley finance, helped build PAIC, IVA, and TVI, and described a process that paired people judgment with market/application tests, references, dissent, conflict disclosure, and capacity-limited board work. The record supports that institutional and process contribution; it does not establish a complete McMurtry-only return series or repeatable personal alpha. [researcher inference · strong] Profile thesis · Bancroft oral history, printed pp. 29–57 · JEC testimony, printed pp. 145–165 and 203/PDF pp. 149–169 and 207
The strongest direct evidence is procedural. McMurtry separated Melchor's 1969 personal ROLM backing from IVA's 1975 decision, disclosed his own position, and left approval to Reid Dennis, Burge Jamieson, and Jim Norris. He credited David Marquardt for Microsoft and Sun. He also recalled using contrary references and a rotating skeptic when partners agreed too easily. Those episodes support attribution discipline and engineered dissent, not proof that the practices were universal or outcome-causing. [retrospective witness · moderate] Profile chronology · ROLM lab · Microsoft lab
His most credible investing tension is people versus application. In 1984 he called people the critical element; in 2009 he admitted that compelling people could bias him and used DAVID Systems as the counterexample—years of work and capital without a sufficiently important application. Mindset supplies a separate failure involving compatibility and distribution. [investor-stated · strong] [retrospective witness · moderate] Talk synthesis · DAVID lab · Mindset lab
The economic record is bounded. Microsoft's and Synaptics' prospectuses provide ownership snapshots, not realized TVI proceeds; the UC schedule reports one LP's net observations for TVI 2–4, omits TVI 1, and includes residual value for TVI 4. The three rows are dated observations, not a valid cross-fund dispersion or ranking, company attribution, partner attribution, or career multiple. [contemporaneous record · strong] Portfolio-level forensics · Microsoft prospectus, principal and selling stockholders · Synaptics 424B4, principal and selling stockholders · UC schedule and footnotes
What could falsify the thesis
The favorable thesis predicts observable records: McMurtry-specific sourcing or diligence in more than famous cases; contemporaneous application tests; reference files that changed decisions; dissent or recusal minutes; board actions tied to diagnosed constraints; and matched ordinary/failure cases in which those procedures improved decisions after price, ownership, partner work, era, and access were controlled. [researcher inference · strong] Predictions and falsifiers · Uncertainty ledger
It would weaken if complete opportunity logs showed that elite technical/university access and partner relationships selected nearly every attractive deal, if original memoranda contained generic rather than discriminating analysis, or if board records assigned the consequential work to founders and other partners. It would fail as a return thesis if complete fund/company cash flows showed ordinary ex-outlier performance after attribution and vintage controls. [researcher inference · strong] Skeptical profile · Skeptical philosophy
Disconfirming evidence already exists. Microsoft and Sun were Marquardt-led; Melchor funded ROLM initially; TVI's public company count exceeds 100 while only 33 raw rows were bounded here; DAVID, Mindset, and Synapse resist a simple technical-judgment story; and McMurtry's people preference was self-identified as a source of mistakes. [researcher inference · strong] Searched denominator · Failure postmortems
The strongest skeptical explanation is access plus team plus era plus survivor narration. McMurtry entered a small, relationship-dense market, worked alongside several later-famous investors, operated during expanding electronics/computer markets and institutional venture supply, and narrated the record after outcomes were known. Missing losses, ordinary outcomes, ownership histories, and TVI 1 economics leave that alternative live. [researcher inference · provisional] Historical context · Profile skeptical explanation
Attribution and denominator audit
The package separates personal holdings, Melchor/PAIC, IVA, TVI numbered funds and management entities, company boards, partner-career examples, and later governance roles. It does not convert shared dispositive power into sourcing, a board seat into investment ownership, an IPO stake into proceeds, a company outcome into a fund return, or a firm result into McMurtry economics. [researcher inference · strong] People and decision-rights map · Vehicle analysis
| Material case | Controlling evidence | Audit result |
|---|---|---|
| ROLM | Melchor's personal 1969 backing; McMurtry's 1975 diligence, disclosed position, recusal, partner approval, and board service are distinct. Bancroft, printed pp. 29–33 | PASS — original finance, IVA vote, and governance are not collapsed. |
| Microsoft | TVI entities held shares; McMurtry assigns sourcing and board work to Marquardt. Bancroft, printed pp. 48–49 · 1986 prospectus | PASS — firm exposure is not McMurtry-lead credit or realized return. |
| Sun | McMurtry attributes the six-month-old-company relationship and board role to Marquardt. Bancroft, printed p. 49 | PASS — no McMurtry deal lead is asserted. |
| Intuit | The 1997 proxy verifies McMurtry's board/audit role and separately lists trust/options; Davidson supplies the financing-choice account. 1997 proxy | PASS — personal holdings are not TVI holdings; board value is expected, not causal outcome. |
| Synaptics | TVI 3, TVI Management-3, and TVI IV held 2,077,339 shares under shared control among five named people. Synaptics 424B4, footnote 12 | PASS — snapshot and shared control are not McMurtry sourcing or realization. |
| VeriFone | The Ninth Circuit describes allegations and affirms dismissal with prejudice. In re VeriFone Securities Litigation | PASS — allegation, defendant status, disposition, and wrongdoing finding remain distinct. |
The named-deal funnel reconciles to 33 raw searched rows: 18 strong TVI candidates, eight vehicle-unresolved routes, six non-TVI exclusions, and one documented pass. Synapse is vehicle-unresolved because no processed source bridges it to TVI or a named TVI partner. All 33 were researched to a stated boundary; eleven have full no-hindsight decision labs, while zero of the 18 strong candidates has a complete cost-to-distribution chain. Because institutional biographies say four TVI funds backed more than 100 companies and no fund-by-fund schedule surfaced, career coverage and hit rate are not computable. [researcher inference · strong] 33-row ledger · Evidence boundary
The source map has 58 unique routes: eleven direct writings/institutional statements, twelve oral/testimony/talk routes, ten biography/governance routes, nine firm/peer routes, eight deal/vehicle routes, and eight skeptical/failure routes. Route count is not source independence; transcript/catalog, archive index/document, and landing-page/PDF pairs are disclosed rather than double-counted analytically. [researcher inference · strong] Source coverage
Transfer limits for modern VCs
The transferable procedures are modest and testable: separate technical efficacy from important application; distinguish source, sponsor, vote, board work, ownership, and realization; record conflicts and force dissent; test references in both directions; cap boards and reserves to real partner capacity; and condition patience on learning milestones and a live recovery path. These are reconstructions, not McMurtry-authored universal rules with measured efficacy. [researcher inference · moderate] Decision-ready models · Decision playbook
Historical conditions do not transfer mechanically. Early rounds, scarce venture supply, tight geographic networks, less mature electronics markets, and the developing institutional-fund regime differ from a 2026 market. Proximity can become a closed funnel; people-first can become charisma bias; patient board work can become escalation; and an IPO snapshot can hide price, dilution, reserves, carry, and ultimate distributions. [researcher inference · moderate] Historical operating environment · Modern translation, as of 2026-08-24
The practical transfer test, as of 2026-08-24, is observable: freeze what is known, unknown, believed, and disputed; name the actor and legal vehicle; state the application, customer proof, price, ownership, next milestone, reserve burden, kill criteria, and dissent; then report company outcome separately from gross/net and realized/unrealized investor economics. [researcher inference · strong] Eleven decision labs · Mental-model field guide
Unresolved evidence
- TVI partnership agreements, LP letters, capital calls, fees, carry, GP commitments, reserves, extensions, key-person provisions, and complete company schedules remain unavailable. Retrieval ledger
- TVI 1 is absent from the UC schedule; Microsoft company-level cash flows and TVI 1 net distributions are therefore unknown. Portfolio forensics
- Most strong TVI candidates lack check, security, price, ownership, sponsor, votes, dilution, follow-ons, proceeds, and net contribution. 33-row ledger
- Contemporaneous PAIC/IVA formation records and complete decision-rights documents have not surfaced. Profile unresolved evidence
- DAVID Systems, Mindset, Synapse, SpectraLink, Intuit, and VeriFone still lack complete board-minute, capital-response, and person-level economic records. Failure postmortems
- The Houston Philosophical Society speech, Rice event DVD, Bancroft audiovisual media, and a verbatim Stanford trustees transcript require archive access. Talk retrieval priorities · Writing boundary
- Stanford board minutes are needed only for exact chair transition months; signed 2004–2007 messages and the institutional obituary establish the four-year tenure. Profile chronology
Central-claim citation audit trail
| ID | High-risk claim family | Controlling source and locator | Result |
|---|---|---|---|
| C01 | Engineer/manager formation and 1969 venture transition | Bancroft, printed pp. 10–29 · Stanford obituary | PASS — chronology supported; psychological causation labeled inference. |
| C02 | ROLM two-stage attribution | Bancroft, printed pp. 29–33 | PASS — Melchor 1969 and IVA 1975 remain distinct. |
| C03 | IVA raise and conflicting market-share proportions | JEC, printed pp. 145–147/PDF pp. 149–151 · Bancroft, printed pp. 44–45 | PASS — one-third invested versus more-than-one-fifth raised remain unreconciled. |
| C04 | TVI formation and four-fund total | Bancroft, printed pp. 46–48 · Marquardt oral history, p. 22 | PASS — founder roster corroborated; $270m remains retrospective. |
| C05 | People as critical element | JEC, printed p. 203/PDF p. 207 | PASS — corrected locator; no efficacy inference. |
| C06 | Capital-gains causality concession | JEC Q&A, printed p. 192/PDF p. 196 | PASS — advocacy is not presented as proved causation. |
| C07 | Microsoft attribution and ownership snapshot | Bancroft, printed pp. 48–49 · Microsoft prospectus, p. 30 | PASS — Marquardt-led; prospectus lists shares to be sold, not a closing or realized multiple. |
| C08 | Sun attribution | Bancroft, printed p. 49 | PASS — TVI association does not become McMurtry lead credit. |
| C09 | Intuit financing choice, board role, and holdings | Intuit 1997 proxy · Intuit lab | PASS — witness account, board record, personal holdings, and unknown TVI economics separated. |
| C10 | DAVID Systems failure lesson | Bancroft, printed pp. 50–51/PDF pp. 60–61 | PASS — no dollar write-off or proven process change invented. |
| C11 | Mindset funding, failure, and reported TVI loss | Los Angeles Times, 1987-12-18 | PASS — $18m is total company funding and roughly $2m is reported TVI loss, not audited McMurtry economics. |
| C12 | Synapse failure and attribution boundary | Mark Leslie CHM oral history, printed pp. 36–40/PDF pp. 38–42 | PASS — $35m is company-wide; no processed source bridges Synapse to TVI, Bochnowski, or McMurtry. |
| C13 | Synaptics ownership and control | Synaptics 424B4, table and footnote 12 | PASS — 9.0% base-offering and 8.4% full-over-allotment scenarios separated; shared control and realization boundary retained. |
| C14 | TVI 2–4 LP performance observations | UC schedule, p. 1 and footnotes | PASS — one LP, net figures, residual and comparison limitations explicit. |
| C15 | VeriFone adverse matter | Ninth Circuit opinion | PASS — allegations and affirmed dismissal do not become a wrongdoing finding. |
| C16 | 33-row denominator | Mechanical ledger | PASS — 18 + 8 + 6 + 1; not a career census. |
| C17 | Direct-voice/writing denominator | Writing accounting · Talk accounting | PASS — partial, metadata-only, and unverified-turn routes are explicit. |
| C18 | Six mental models | Mental models | PASS — all are reconstructed/labeled and retain failures or limits. |
Ordinary-claim citation audit trail
The sample was fixed at two claims from each of the eight core documents before results were recorded.
| ID | Document and ordinary claim | Source / locator | Result |
|---|---|---|---|
| O01 | _profile.md — McMurtry earned Stanford MS and PhD degrees after Rice |
Stanford obituary · Bancroft, printed pp. 14–19 | PASS |
| O02 | _profile.md — he died 2018-09-02 at age 83 |
Stanford obituary · Rice obituary | PASS |
| O03 | sources.md — the source map contains 58 routes split 11/12/10/9/8/8 |
Source coverage | PASS — mechanically reproduced; routes are not independent works. |
| O04 | sources.md — the Bancroft catalog exposes transcript/media metadata while publication quotation requires permission |
Bancroft catalog · transcript rights notice, printed p. ii | PASS — paraphrase policy retained. |
| O05 | writings.md — the 1962 paper verifies technical work but not an investing rule |
Optica abstract | PASS — transfer is labeled inference. |
| O06 | writings.md — the prepared statement is McMurtry-presented/NVCA-associated, not safely sole-authored |
JEC contents and pp. 148–181/PDF pp. 152–185 | PASS |
| O07 | talks.md — CHM lists McMurtry as a participant on 2002-09-30 |
CHM event page | PASS |
| O08 | talks.md — the Rice notice does not verify McMurtry's appearance or remarks |
Rice notice · archive route | PASS |
| O09 | investments.md — TVI entities held 2,077,339 Synaptics shares before the offering |
Synaptics 424B4 | PASS — snapshot, not proceeds. |
| O10 | investments.md — UC reported TVI 4 at 3.27x and 24.1% with residual value as of 2003-03-31 |
UC schedule | PASS — one-LP/net footnotes retained. |
| O11 | investmentphilosophy.md — active board capacity was roughly six to eight |
Bancroft, printed pp. 55–57 | PASS — retrospective estimate, not universal optimum. |
| O12 | investmentphilosophy.md — Microsoft and Sun are attributed to Marquardt |
Bancroft, printed pp. 48–49 | PASS |
| O13 | mental-models.md — people judgment is paired with independent references |
JEC, printed p. 203/PDF p. 207 · Bancroft, printed pp. 51–54 | PASS |
| O14 | mental-models.md — patience is limited by a testable recovery path |
DAVID and Mindset cases | PASS — reconstructed rule labeled inference. |
| O15 | review.md — the people statement is printed p. 203/PDF p. 207 |
Official JEC scan | PASS |
| O16 | review.md — the 33-row ledger classifies 18 + 8 + 6 + 1 |
Ledger | PASS — mechanical count reproduced. |
Twenty-point acceptance matrix
| # | Result | Auditable evidence | Correction or remaining boundary |
|---|---|---|---|
| 1 | PASS | Narrative profile connects formation, belief, process, action, outcome, and later governance. | Causal bridges remain labeled. |
| 2 | PASS | Falsifiable thesis and skeptical test. | Personal alpha remains unproved. |
| 3 | PASS | Eleven ex-ante labs freeze evidence, alternatives, risks, governance, terms, and unknowns before the reveal. | Missing original packets are explicit. |
| 4 | PASS | Pareto opening separately ranks economics, history, and learning without a literal 80/20 claim. | Career economics not computable. |
| 5 | PASS | Eight substantive root documents and 34 notes; no empty or status-only phase stub. | None. |
| 6 | PASS | Denominator and 33-row ledger reconcile aliases, vehicles, inclusions, exclusions, selection bias, and not computable. |
Full >100-company census remains archival. |
| 7 | PASS | Writings gives all ten priority artifacts their own analysis and exact barriers for partial or missing bodies. | Houston speech remains metadata-only. |
| 8 | PASS | Six mental models each contain 12 labeled components, three grounded cases, a failure/limit, four-plus citation placements, and two-plus sources. | Candidate exclusions disclosed. |
| 9 | PASS | Modern translation dated 2026-08-24 plus dated transfer tests in every model. | Current examples are labeled hypothetical where appropriate. |
| 10 | PASS | Failure/adverse postmortems cover DAVID, Mindset, Synapse, VeriFone, SpectraLink, and unresolved matters without inventing cash flows or fault. | Original board books remain absent. |
| 11 | PASS | People map and decision-rights map separate source, vote, board work, ownership, and narration. | Unknown roles remain unknown. |
| 12 | PASS | Vehicle analysis covers capital form, duration, fundraising, carry gaps, governance, reserves, succession, and incentives. | Partnership terms unavailable. |
| 13 | PASS | Historical context distinguishes contemporaneous conditions from hindsight and says when base rates are absent. | No invented comparison set. |
| 14 | PASS | Source coverage, writings boundary, and talk boundary log legitimate routes and barriers. | Named archive retrievals remain queued as evidence gaps, not unfinished analysis. |
| 15 | PASS | Central and ordinary audits above verify adjacent canonical links with pages, tables, timestamps, or exact access boundaries. | Bancroft is paraphrased. |
| 16 | PASS | Material theses, rules, comparisons, and transfers distinguish investor statement, witness, record, behavior, and researcher inference with support grades. | No retrospective story is promoted to contemporaneous fact. |
| 17 | PASS | Strongest skeptical case and falsifiers test access, team/vehicle credit, denominator, survivorship, economics, era, contradictions, and outliers. | Favorable claim is narrowed, not declared proved. |
| 18 | PASS | Completed-peer comparison uses Reid Dennis, Paul Wythes, and Bob Kagle with incompatible-economics limits. | No synthetic ranking. |
| 19 | PASS | Every decision lab asks invest/pass, kill criteria, ownership/terms, and next-check questions before a separate reveal; failures, a pass, and adverse controls are included. | Eleven cases, not a portfolio census. |
| 20 | PASS | Chronology, learning path, glossary/checklists in philosophy, cross-links, and people/capital maps form the reader path. | No bespoke site component required. |
Citation and link QA
Mechanical QA reproduced the 58-route source map, 33-row investment ledger, eleven decision labs, 17 philosophy sections, six mental models with twelve labeled fields apiece, and 34 deep source notes (18 source/deal/profile, ten writing, six talk). [researcher inference · strong] Source coverage · Ledger · Model inventory
Representative primary routes were reopened during review: the JEC scan supports the printed/PDF page split and people statement; the Synaptics filing supports the exact entity holdings and shared-control footnote; the UC schedule supports the TVI 2–4 rows and limitations; the CHM page supports the 2002 panel metadata; and the Bancroft catalog supports the oral-history access boundary. A 403 on the direct Bancroft PDF through one automated fetch was treated as an access-control state because the catalog route resolves and the document had already been processed, not as evidence that the source is missing. [documented behavior · strong] JEC · Synaptics · UC · CHM · Bancroft catalog
Reader conclusion
Read McMurtry as an engineer-investor and institution builder whose public record supports a useful, self-critical process: people matter, but important application, independent references, dissent, clean conflicts, and finite board capacity constrain that judgment. Do not read Microsoft, Sun, ROLM, or pooled-fund snapshots as lone-picker proof. Partners, founders, vehicles, access, era, survivor selection, and missing cash flows remain material rival explanations. [researcher inference · strong] Profile thesis · Skeptical philosophy
Direct writings and institutional statements
- ★★★ | Photomixing Experiments with a Ruby Optical Maser and a Traveling-Wave Microwave Phototube | https://opg.optica.org/ao/abstract.cfm?uri=ao-1-1-51 | 1962-01-01 | journal article | McMurtry and Anthony Siegman's primary technical paper, useful for verifying his engineering formation without inferring an investing philosophy from technical work.
- ★★ | Modulation and Direct Demodulation of Coherent and Incoherent Light | https://books.google.com/books/about/Modulation_and_Direct_Demodulation_of_Co.html?id=ZUgFAAAAIAAJ | 1962 | Stanford Electronics Laboratories report | Catalog/preview route for McMurtry's doctoral-era research; full text is not exposed in the preview.
- ★★★ | Venture Capital and Innovation | https://files.eric.ed.gov/fulltext/ED255720.pdf | 1984-08-27–28 | congressional-hearing PDF | Contemporaneous live testimony and an NVCA-associated prepared statement; printed pp. 145–165 and 203 are central to people, markets, policy, and fund-size claims.
- ★★ | Passing the Torch | https://bondholder-information.stanford.edu/sites/g/files/sbiybj21416/files/media/file/stanford-annual-financial-report-2004.pdf | 2004 | university annual report | McMurtry's signed board-chair statement at printed p. 16/physical PDF p. 18; direct institutional voice rather than venture-investment doctrine.
- ★★ | A Wise Investment | https://bondholder-information.stanford.edu/sites/g/files/sbiybj21416/files/media/file/stanford-annual-financial-report-2005.pdf | 2005 | university annual report | Signed board-chair message on financial capacity, people, programs, and cross-school initiatives; physical PDF p. 18.
- ★★ | Setting a Bold Agenda | https://bondholder-information.stanford.edu/sites/g/files/sbiybj21416/files/media/file/stanford-annual-financial-report-2006.pdf | 2006 | university annual report | Signed board-chair message linking the Stanford Challenge to interdisciplinary priorities while warning against projecting past performance; physical PDF p. 18.
- ★★ | One Year Into The Stanford Challenge | https://bondholder-information.stanford.edu/sites/g/files/sbiybj21416/files/media/file/stanford-annual-financial-report-2007.pdf | 2007 | university annual report | Signed board-chair message reporting campaign milestones and distributing credit across university participants; physical PDF p. 18.
- ★ | Stanford annual reports archive | https://bondholder-information.stanford.edu/annual-reports | accessed 2026-08-24 | university archive index | Canonical route connecting the 2004–2007 annual reports; an access route, not an additional authored work.
- ★★ | Meet the Venture Capitalists — Technology Venture Investors | https://static.bslabs.net/wwdc/1990/Meet%20the%20Venture%20Capitalists%20-%20Technology%20Venture%20Investors.pdf | 1990 | partner presentation | Contemporaneous firm positioning, team roster, investment examples, active-board posture, and stated selection criteria; the list is explicitly “by TVI partners,” not a fund ledger.
- ★★ | University Launches $4.3 Billion Campaign to Address Global Challenges | https://stanfordmag.org/contents/university-launches-4-3-billion-campaign-to-address-global-challenges | 2006 | university statement/press | Short direct quotation by board chair McMurtry on the Stanford Challenge; useful for later governance-era chronology only.
- ★ | Stanford Energy and Climate Plan | https://news.stanford.edu/__data/assets/pdf_file/0029/127496/E_C_Plan_2015.pdf | 2015 | university plan | Retrospectively preserves McMurtry's public statement that Y2E2 should be a model for sustainable campus construction.
Oral histories, testimony, talks, and video
- ★★★ | Burton McMurtry: Early Bay Area Venture Capitalists | https://digicoll.lib.berkeley.edu/record/218493 | 2009 | oral-history catalog and full transcript | Best direct source for his life, PAIC/IVA/TVI chronology, method, deal credit, failures, and governance; retrospective and permission-limited for publication quotation.
- ★★★ | Burton McMurtry oral-history transcript PDF | https://digicoll.lib.berkeley.edu/record/218493/files/mcmurtry_burt.pdf | 2009 | 71-page transcript PDF | Pinpointable version of the Bancroft interviews conducted June 9 and June 30, 2009.
- ★★ | Burton J. McMurtry library catalog record | https://digicoll.lib.berkeley.edu/record/103606 | 2009 | Bancroft catalog/finding aid | Confirms the cataloged interview object and associated audiovisual holdings; route should be checked before claiming public video access.
- ★★★ | Pioneers of Venture Capital | https://computerhistory.org/events/pioneers-venture-capital/ | 2002-09-30 | event video | Direct multi-investor panel featuring McMurtry; supports early-industry and ROLM recollections while allowing peer comparison.
- ★★★ | Pioneers of Venture Capital full video | https://www.youtube.com/watch?v=ult7VFgxiKo | 2002-09-30 | video with automatic captions | Public video route; useful anchors are approximately 18:00–18:50, 33:25–35:53, and 48:56–50:28, with auto-caption caveat.
- ★★★ | Venture Capital and Innovation — official JEC record | https://www.jec.senate.gov/public/index.cfm/1984/12/report-33ffb302-3ee1-4acf-91ab-98a384f0a7b6 | 1984-08-27–28 | official hearing record | Canonical government landing page for the same hearing; separates the live panel, prepared exhibit, and later Q&A.
- ★★★ | The Ins and Outs of Financing a Company | https://stvp.stanford.edu/wp-content/uploads/sites/3/2024/09/the-ins-and-outs-of-financing-a-company-transcript.pdf | 2004-05-26 | transcript | Gordon Davidson's detailed witness account of Intuit's financing choice; valuable but not McMurtry's own testimony.
- ★ | Generations of Rice Grads | https://business.rice.edu/owl-have-you-know/generations-of-rice-grads | 2022 | podcast transcript | Later Rice-network recollection; useful as a lead, but it incorrectly centers McMurtry in Microsoft's board rationale and must not override primary attribution.
- ★★ | Trustees share inner workings of board | https://stanfordreview.org/trustees-share-inner-workings-of-board/ | 2009-12-03 | student-press event report | Contemporary account of McMurtry discussing Stanford trustee process; governance evidence rather than venture-method proof.
- ★ | Sneak a peek at Duncan and McMurtry colleges Sept. 8 | https://news2.rice.edu/2009/09/03/sneak-a-peek-at-duncan-and-mcmurtry-colleges-sept-8/ | 2009-09-03 | university notice | Contemporary Rice event notice that helps bound later governance and philanthropic activity.
- ★ | Rice University Archives container 10793 | https://archives.library.rice.edu/repositories/2/top_containers/10793 | accessed 2026-08-24 | archive container record | Retrieval lead for McMurtry College and related university material; no investment inference drawn.
- ★★ | Bridging worlds: Chips, code and cosmos | https://engineering100.stanford.edu/stories/bridging-worlds-chips-code-and-cosmos | accessed 2026-08-24 | institutional retrospective | Stanford engineering history that preserves McMurtry's technical and institutional context; retrospective, not transaction evidence.
Biography, education, governance, and archival context
- ★★★ | Burt McMurtry, longtime Stanford leader and champion for the arts, dies at 83 | https://news.stanford.edu/stories/2018/09/burt-mcmurtry-longtime-stanford-leader-champion-arts-dies-83 | 2018-09-13 | institutional obituary | Strong chronology for Stanford education, trusteeship, later influence, and death; its portfolio list is firm-level and not individual deal attribution.
- ★★★ | Rice mourns trustee emeritus Burt McMurtry | https://news2.rice.edu/2018/09/10/rice-mourns-trustee-emeritus-burt-mcmurtry/ | 2018-09-10 | institutional obituary | Independent university chronology for Rice education, 17-year trusteeship, gifts, and later governance.
- ★★ | Burt McMurtry | https://pacscenter.stanford.edu/person/burt-mcmurtry/ | undated | institutional biography | Concise identity, degrees, firms, boards, and broad portfolio inventory; not adequate for individual deal credit.
- ★★ | Burton and Deedee McMurtry | https://carnegiescience.edu/sites/carnegiescience.edu/files/yearbooks/YB11-12FINComboToPrtint2-6-13.pdf | 2011–2012 | Carnegie Science yearbook | Institutional account of GTE-to-venture chronology, election to Carnegie's board in December 1996, and later philanthropy.
- ★★ | Carnegie Institution Year Book 2003–2004 | https://carnegiescience.edu/sites/carnegiescience.edu/files/yearbooks/YB03-04Printer%27sFINCompletePDFMay2005.pdf | 2004 | institutional yearbook | Contemporary record that McMurtry became a senior trustee in May 2004.
- ★★ | Remarks at the McMurtry Building Groundbreaking | https://arts.stanford.edu/john-etchemendy-mcmurtry-building-groundbreaking-ceremony/ | 2013 | institutional remarks | Establishes McMurtry's board/advisory roles and university-art influence from an identified Stanford speaker.
- ★★ | Construction on Anderson Collection art museum begins | https://anderson.stanford.edu/in-the-news/construction-on-anderson-collection-art-museum-begins/ | 2012 | institutional news | Contemporary witness credit for reopening the Anderson collection discussion in 2004.
- ★ | McMurtry Building to be completed in spring 2015 | https://stanforddaily.com/2014/09/17/mcmurtry-building-for-the-department-of-art-and-art-history-to-be-completed-in-spring-2015/ | 2014-09-17 | student press | Direct comments on the building plus gift and project context; use Stanford records for any monetary figure.
- ★ | Stanford art and art history faculty, staff making plans for McMurtry Building | https://news.stanford.edu/stories/2015/06/mcmurtry-art-opening-062615 | 2015-06-26 | institutional news | Later evidence of the facility's intended interdisciplinary role and opening plans.
- ★ | Text of President Hennessy's annual address to the Academic Council | https://news.stanford.edu/stories/2011/04/text-president-john-hennessys-annual-address-academic-council | 2011-04-14 | institutional address | Corroborates McMurtry-building support within the university campaign; not investment evidence.
Firm, partner, peer, and historical-industry records
- ★★★ | David F. Marquardt oral history | https://archive.computerhistory.org/resources/access/text/2021/05/102792229-05-01-acc.pdf | 2021 | oral-history transcript | Independent partner account of TVI's three-person founding and partnership dynamics; decisive for Microsoft and Sun attribution.
- ★★★ | David Marquardt — August Capital biography | https://www.augustcap.com/team/david-marquardt/ | undated; accessed 2026-08-24 | firm biography | Reports four TVI funds and over 100 companies, attributes Microsoft and its board relationship to Marquardt, and lists his other investments; self-reported firm history, not a fund ledger.
- ★★ | Reid Dennis oral history | https://digicoll.lib.berkeley.edu/record/218448/files/dennis_reid.pdf | 2009 | oral-history transcript | IVA cofounder's independent view of the fund, its $19 million raise, incentives, and the early venture market.
- ★★ | Reid Dennis oral-history catalog record | https://digicoll.lib.berkeley.edu/record/218448 | 2009 | archive record | Canonical metadata and access route for the Dennis interviews.
- ★★ | Venturing Forth: The Exponential Center Launches a Venture Capital Initiative | https://computerhistory.org/blog/venturing-forth-the-exponential-center-launches-a-venture-capital-initiative/ | 2018 | archive-method article | Explains CHM collection scope, artifacts, and oral-history biases; useful retrieval context, not deal evidence.
- ★ | NVCA Oral History Collection Unveiled | https://computerhistory.org/press-releases/nvca-collection/ | 2019-03-28 | archive announcement | Documents the public collection route and named peers; McMurtry is not among its 17 NVCA interviews.
- ★ | Remembering David Morgenthaler | https://computerhistory.org/blog/remembering-david-morgenthaler-leadership-learned-under-fire/ | 2016 | historical profile | Context for capital-gains/ERISA advocacy and a peer route that can test McMurtry's retrospective policy account.
- ★★★ | Mark Leslie oral history | https://archive.computerhistory.org/resources/access/text/2017/10/102738310-05-01-acc.pdf | 2017 | oral-history transcript | Founder account of Synapse's technology, $35 million company-wide funding, operating-system burden, resource consumption, CEO removal, and asset sale; does not establish a TVI or McMurtry bridge.
- ★★★ | Robert Maxfield oral history | https://archive.computerhistory.org/resources/access/text/2012/07/102702237-05-01-acc.pdf | 2012 | oral-history transcript | ROLM founder account that independently tests company formation, early financing, product evolution, and participant credit.
Deal, vehicle, ownership, and performance records
- ★★★ | Intuit 1997 definitive proxy statement | https://investors.intuit.com/sec-filings/all-sec-filings/content/0000891618-97-004780/DEF_14A.txt | 1997-11-26 | SEC filing | Confirms board service since August 1990, audit-committee role, and personal/family-trust holdings; does not prove TVI ownership or investment economics.
- ★★ | Intuit 2000 definitive proxy statement | https://investors.intuit.com/sec-filings/all-sec-filings/content/0001095811-00-004263/0001095811-00-004263.pdf | 2000-11-03 | SEC filing | Shows McMurtry was not standing for reelection and gives a late board/ownership snapshot.
- ★★★ | Synaptics 2002 final prospectus | https://www.sec.gov/Archives/edgar/data/817720/000095015302000114/p65342b4e424b4.htm | 2002-01-29 | SEC 424B4 | Primary TVI-3/TVI-IV ownership, financing, shared voting power, and selling-stockholder evidence; a paper snapshot, not a realized return.
- ★★★ | Synaptics filing index | https://www.sec.gov/Archives/edgar/data/817720/000095015302000114/0000950153-02-000114-index.html | 2002-01-29 | SEC filing index | Canonical accession and component-document verification for the prospectus.
- ★★★ | Microsoft IPO prospectus | https://www.begintoinvest.com/wp-content/uploads/2018/03/Microsoft_prospectus.pdf | 1986-03-13 | prospectus mirror | Contemporaneous TVI 1/2/3 and Marquardt ownership table; mirror provenance requires preservation and independent attribution cross-check.
- ★★★ | UC Regents alternative investments as of March 31, 2003 | https://regents.universityofcalifornia.edu/regmeet/nov03/603spreadsheetnov.pdf | 2003-03-31 | institutional LP schedule | Net cash-flow snapshot for TVI 2–4 with mandatory valuation/IRR cautions; one LP's experience, not complete fund economics.
- ★★ | Starting Up Silicon Valley | https://books.google.com/books?id=Exu5BAAAQBAJ | 2014 | book preview/catalog | ROLM history and founder-side context; full-text access varies, so only previewed passages may be used.
- ★★ | The Ins and Outs of Financing a Company | https://ecorner.stanford.edu/wp-content/uploads/sites/2/2004/05/885.pdf | 2004-05-26 | Stanford eCorner transcript | Alternate canonical transcript route for Gordon Davidson's Intuit financing recollection.
Failures, criticism, litigation, and skeptical evidence
- ★★★ | Bidding for “Chips”: Mindset Corp. Goes Under the High-Tech Gavel | https://www.latimes.com/archives/la-xpm-1987-12-18-fi-19877-story.html | 1987-12-18 | contemporary press | Names McMurtry as former board member, reports roughly $2 million lost by TVI, and records his stop-loss reflection; monetary figure is single-source reporting.
- ★★ | Mindset Computer Files for Chapter 11 Relief | https://www.bitsavers.org/pdf/mindset/First_Mindset_Users_Group_Newsletters_1984-1986.pdf | 1985 | archived trade-press packet | Contemporary financing, layoffs, product/channel trouble, and Chapter 11 context; supports a team/market failure rather than sole-McMurtry blame.
- ★★★ | In re VeriFone Securities Litigation | https://law.justia.com/cases/federal/appellate-courts/F3/11/865/488523/ | 1993 | Ninth Circuit opinion | McMurtry appears as defendant-appellee in shareholder allegations; dismissal with prejudice was affirmed, so the case is not a wrongdoing finding.
- ★★ | SpectraLink 2002 Form 10-Q legal proceedings | https://www.sec.gov/Archives/edgar/data/894268/000095013402014158/d01019e10vq.htm | 2002 | SEC filing | Records securities and derivative allegations naming directors after a forecast reduction; allegations require later disposition research.
- ★★ | In re Daisy Systems Corporation | https://law.justia.com/cases/federal/appellate-courts/F3/97/1171/554835/ | 1996 | Ninth Circuit opinion | McMurtry appears as a creditor-appellee; opinion supplies bankruptcy/transaction context but no basis to infer personal misconduct.
- ★★ | Intuit–Microsoft merger litigation disclosure | https://microsoft.gcs-web.com/static-files/1a91acd9-1e16-4064-b512-eb37c2a6c689 | 1994–1995 | merger filing | Records fiduciary-duty allegations against Intuit directors including McMurtry; status and merits require separate disposition evidence.
- ★★ | Venture capital: funding for fresh ideas is on the rise | https://www.csmonitor.com/1985/0311/fvent1.html | 1985-03-11 | contemporary press | Period evidence of 1983–85 technology overfunding, shrinking prices, and large-fund pressure; contextual, not evidence of McMurtry's particular decision.
- ★★ | SpectraLink settles lawsuit with $1.5M payment | https://www.rcrwireless.com/20041008/archived-articles/spectralink-settles-lawsuit-with-1-5m-payment | 2004-10-08 | contemporary trade press | Reports an insurer-funded settlement; the located report does not establish an admission, merits finding, or individual wrongdoing by McMurtry.
Coverage assessment
This map contains 58 unique public routes across direct writings and institutional statements (11), oral/testimony/talk routes (12), biography/governance (10), firm/peer context (9), deal/vehicle evidence (8), and skeptical/failure evidence (8). Counts are route counts, not independent-source counts: the Bancroft transcript/catalog, JEC landing page/PDF, eCorner transcripts, Stanford annual-report index/PDFs, and some archive landing/document pairs are deliberately disclosed as multiple access routes to fewer underlying works.
The search covered Burt McMurtry, Burton McMurtry, Burton J. McMurtry, B. J. McMurtry, Technology Venture Investors, TVI, Institutional Venture Associates, IVA, Palo Alto Investment Company, and company/date combinations from 1962 through 2018. Categories swept were technical writings, prepared testimony, live testimony, oral history, archival video/captions, university statements and annual reports, museum/library catalogs, partner oral histories, SEC filings, LP disclosures, contemporary press, bankruptcy, securities litigation, and obituaries.
Direct-voice routes attempted include the Bancroft transcript and catalog, CHM's public panel/video, the official Joint Economic Committee hearing and ERIC scan, Stanford annual reports, the 1990 TVI presentation, and the technical-paper catalog. No public McMurtry shareholder letters, LP letters, personal blog, memoir, or standalone investment book were located. The Bancroft transcript's printed p. ii permits research use but directs publication quotation requests to the Bancroft director; this package therefore paraphrases the transcript throughout and records the permission boundary rather than calling the work unusable. The catalog describes audiovisual holdings, but a separate downloadable creator transcript or video was not established from that route. The CHM YouTube captions are automatic, so quotations require audiovisual verification.
The candidate portfolio denominator begins with institutional portfolio names and expands with partner-level examples in the 1990 TVI presentation and filing/company searches. It is not a complete TVI portfolio: August Capital's Marquardt biography says the four funds backed more than 100 companies, public lists mix PAIC, IVA, TVI, personal, partner-career, and board roles, and follow-ons or renamed/acquired companies complicate deduplication. Coverage fraction: not computable until the firm/fund denominator is reconstructed. The 33-row ledger resolves to 18 strong TVI candidates, eight vehicle-unresolved routes, six non-TVI exclusions, and one pass; Synapse remains vehicle-unresolved. Microsoft and Sun must remain Marquardt-led; ROLM requires a two-stage attribution boundary—Jack Melchor's personal 1969 financing first, then the 1975 IVA investment after McMurtry disclosed his conflict and left approval to Reid Dennis, Burge Jamieson, and Jim Norris.
Historical-context anchors include the 1984 JEC hearing, contemporary 1985 venture-market reporting, the UC LP schedule, Reid Dennis's oral history, and the TVI presentation. Completed peers worth later comparison are Reid Dennis, Paul Wythes, and Bob Kagle only where their canon pages are already marked complete; direct source evidence must still support the comparison. Highest-value later retrieval leads are the underlying Microsoft prospectus provenance, complete ROLM financing/board records, TVI fund partnership documents and portfolio schedules, public exit/dilution records for ordinary and failed companies, resolution of the SpectraLink and Intuit complaints, the Houston Philosophical Society and Rice event archives, and any Stanford archive box/folder containing McMurtry board materials.
Source notes
[w] David Marquardt — August Capital biography
- URL: https://www.augustcap.com/team/david-marquardt/ | Published: undated | Format: firm biography | Reliability: B | Access: full | Accessed: 2026-08-24 | Locator scheme: TVI paragraph and investment-list paragraph; no stable paragraph identifiers
Takeaways
- Reports that Marquardt cofounded TVI in 1980 and that four TVI funds invested in over 100 startup and emerging-growth companies.
- Calls TVI Microsoft's sole investor and says Marquardt served on Microsoft's board from 1981 to 2014.
- Lists Marquardt's other prior investments separately, useful for preventing firm- or partner-career examples from becoming McMurtry attributions.
Quotes
- No quotation retained; the relevant claims are paraphrased.
Biography and decision evidence
- Provides the only located public aggregate company-count claim for the four TVI funds.
- Supports Marquardt's Microsoft role but remains a retrospective biography published by his later firm.
Philosophy signals
- Tags: team / attribution / boards / denominator / sourcing.
Contradictions, counterevidence, and access limits
- “Over 100” has no fund-by-fund names, deduplication rule, follow-on treatment, or audited schedule; it cannot be a denominator for a coverage percentage.
- “TVI was the sole investor” is firm-level shorthand and does not mean McMurtry personally led or owned the position.
Open questions
- Retrieve TVI fund schedules and Microsoft's original financing/board records to replace firm-biography shorthand.
[t] Burton McMurtry: Early Bay Area Venture Capitalists
- URL: https://digicoll.lib.berkeley.edu/record/218493/files/mcmurtry_burt.pdf | Published: 2009 | Format: oral-history transcript | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: printed page plus interview timestamp; PDF pagination is offset by front matter
Takeaways
- Four sessions across interviews on June 9 and June 30, 2009 reconstruct Houston/Rice, Stanford/Sylvania, PAIC, IVA, TVI, deals, method, failures, and nonprofit governance.
- McMurtry describes a people-first sequence, then market, then technology, but openly concedes that attraction to people led him to tolerate weak markets (printed pp. 37–38, 02-00:48:12–02-00:54:12).
- The record is retrospective memory recorded decades after most decisions; it is primary for what McMurtry said in 2009, not automatically contemporaneous proof of ex-ante rationales.
Quotes
- None reproduced. The transcript permits research use but requires written permission for publication quotation; no permission was sought. Paraphrased findings: PAIC did not participate in ROLM's initial financing; McMurtry recused from IVA's 1975 approval; and he assigned Microsoft sourcing credit to David Marquardt. (printed pp. 32 and 49)
Biography and decision evidence
- McMurtry completed Rice's BA/five-year BSEE sequence, entered Sylvania's Stanford cooperative program, earned an MS in 1959 and PhD in 1962, then remained in GTE/Sylvania engineering and management until 1969 (printed pp. 10–29).
- Jack Melchor personally financed ROLM in 1969; PAIC was formed around the same time but had no initial ROLM role (printed pp. 29–33).
- In 1975 McMurtry diligenced ROLM's PBX expansion, disclosed personal/PAIC ownership, recused from approval, and supplied his work to Reid Dennis, Burge Jamieson, and Jim Norris; they approved IVA's investment and he joined the board (printed pp. 31–32).
- McMurtry, Jim Bochnowski, and David Marquardt formed TVI in 1980; successor funds followed in 1982, 1984, and 1988 (printed pp. 46–48).
- Marquardt led Microsoft and Sun. McMurtry served on Intuit's board from 1990 and recalled leaving in 2001 (printed pp. 48–50).
Philosophy signals
- Tags: people / sourcing / picking / boards / portfolio / risk / vehicle / exits.
- Investor-stated signals include people-first evaluation, early-stage preference with profitable-company exceptions, negative-reference diligence, capacity-limited fund size, active board support, patience, and willingness to stop.
Contradictions, counterevidence, and access limits
- The transcript reports IVA's $19 million fund as more than one-fifth of the annual US total, while 1984 testimony said roughly one-third; preserve both versions.
- McMurtry's approximate fortyfold ROLM public-share comparison is not an audited IVA return.
- Printed p. ii permits research use but states that publication quotation requires written permission from the Bancroft director. Paraphrase by default; do not misstate this as a ban on research use.
Open questions
- Obtain contemporaneous PAIC/IVA/TVI partnership documents, portfolio schedules, and board minutes.
- Reconcile Stanford chair dates and Intuit board departure against institutional records.
[t] Pioneers of Venture Capital
- URL: https://computerhistory.org/events/pioneers-venture-capital/ | Published: 2002-09-30 | Format: event video | Reliability: A | Access: full video, automatic captions | Accessed: 2026-08-24 | Locator scheme: video timestamp; event page has no paragraph anchors
Takeaways
- McMurtry appears with William Draper, Pitch Johnson, Thomas Perkins, Arthur Rock, Donald Valentine, and Gordon Davidson.
- Useful McMurtry sections are approximately 18:00–18:50 (introduction), 33:25–35:53 (entry into venture and scarce early capital), and 48:56–50:28 (ROLM).
- The panel is direct voice but retrospective and conversational; captions are machine-generated.
Quotes
- No quotation promoted from automatic captions pending audio verification.
Biography and decision evidence
- Supports the 1969 entry into venture capital and early-capital scarcity.
- The ROLM story should be cross-checked against the more detailed Bancroft account, which distinguishes Melchor's initial financing from IVA's later investment.
Philosophy signals
- Tags: sourcing / people / boards / history / vehicle.
Contradictions, counterevidence, and access limits
- The panel's compressed storytelling can collapse distinct financing stages; use it as corroboration, not the sole attribution source.
- YouTube route: https://www.youtube.com/watch?v=ult7VFgxiKo. Captions are automatic.
Open questions
- Determine whether CHM holds a creator transcript or cataloged event recording with stable segment metadata.
[w] Intuit 1997 definitive proxy statement
- URL: https://investors.intuit.com/sec-filings/all-sec-filings/content/0000891618-97-004780/DEF_14A.txt | Published: 1997-11-26 | Format: SEC DEF 14A | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: filing heading, table, and footnote
Takeaways
- Confirms McMurtry had been an Intuit director since August 1990 and a TVI general partner since July 1980.
- Identifies him and Christopher Brody as audit-committee members in fiscal 1997.
- Reports 114,748 personal beneficial shares: 110,686 held by a family trust and 4,062 option shares; these are not TVI fund holdings.
Quotes
- No quotation necessary; filing facts are paraphrased.
Biography and decision evidence
- Board and committee evidence is contemporaneous and stronger than retrospective tenure summaries.
- A separate 2000 proxy says he was not standing for reelection, while the 2009 oral history recalls leaving in 2001.
Philosophy signals
- Tags: boards / governance / ownership / team.
Contradictions, counterevidence, and access limits
- The filing does not establish who sourced Intuit, TVI's entry economics, causal board value, or realized return.
- Do not attribute family-trust and option shares to TVI.
Open questions
- Locate Intuit's 1990 financing documents and board minutes; reconcile the exact board-departure date.
[t] Venture Capital and Innovation — Joint Economic Committee hearing
- URL: https://files.eric.ed.gov/fulltext/ED255720.pdf | Published: 1984-08-27–28 | Format: congressional-hearing transcript and prepared exhibit | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: printed page and PDF page; printed 145 begins at PDF 149
Takeaways
- McMurtry's live panel opening runs at printed pp. 145–147/PDF pp. 149–151; the NVCA-associated prepared testimony appears at printed pp. 148–165/PDF pp. 152–169; Q&A continues later.
- The live remarks identify McMurtry as TVI general partner and NVCA vice president/secretary and emphasize backgrounds, work with young companies, and a people-first hierarchy.
- The attached statement advocates a supportive tax/regulatory environment but is presented for three NVCA witnesses; it should not be treated as McMurtry's sole-authored personal manifesto.
Quotes
- “The critical element is the people.” (printed p. 203/PDF p. 207)
- In later Q&A, McMurtry said the hearing record could not prove a direct causal relationship between capital-gains taxation and venture investment. (printed p. 192/PDF p. 196)
Biography and decision evidence
- The hearing provides contemporaneous 1984 evidence of McMurtry's TVI and NVCA offices, not later obituary shorthand.
- His live biography says the 1974 $19 million IVA fund was about one-third of that year's US venture total (printed p. 146/PDF p. 150).
Philosophy signals
- Tags: people / picking / boards / vehicle / regulation / macro.
- Investor-stated · strong for the people-market-technology ordering as articulated publicly in 1984; insufficient for its efficacy across the portfolio.
Contradictions, counterevidence, and access limits
- The “one-third” fund-share estimate conflicts with McMurtry's 2009 “more than one-fifth” recollection.
- Policy advocacy is interested testimony. McMurtry also conceded that tax causality could not be proved, which should accompany any policy lesson.
Open questions
- Identify drafting records for the prepared statement and any contemporaneous NVCA minutes.
[t] Mark Leslie oral history — Synapse Computer
- URL: https://archive.computerhistory.org/resources/access/text/2017/10/102738310-05-01-acc.pdf | Published: 2017 | Format: founder oral-history transcript | Reliability: A for direct retrospective voice | Access: full | Accessed: 2026-08-24 | Locator scheme: printed pp. 36–40/PDF pp. 38–42
Takeaways
- Leslie recalls that Synapse raised about $35 million company-wide, developed advanced multiprocessor transaction technology, wrote its own operating system, and faced a long tail of customer requirements.
- He describes resource-intensive sales, exhausted capital, investor dissatisfaction, his removal as CEO, and a later asset sale at a low price.
- The source establishes a company failure narrative but does not identify TVI, Jim Bochnowski, or McMurtry as investor, sponsor, director, or voter.
Quotes
- None reproduced; paraphrase avoids turning a later founder account into a contemporaneous decision memo.
Biography and decision evidence
- Leslie is a direct participant in Synapse's operating history. His evidence is strongest for the company's product, resource, management, and outcome sequence.
- No processed primary source bridges Synapse to a TVI legal vehicle or assigns the CEO-removal decision to a named TVI partner.
Philosophy signals
- Tags: Synapse / product complexity / capital intensity / customer requirements / governance / attribution.
- Retrospective witness / moderate: custom-platform burdens and fragmented requirements can consume runway before a repeatable market emerges.
Contradictions, counterevidence, and access limits
- The $35 million figure is total company fundraising, not a TVI exposure.
- The account is retrospective and cannot reveal the original investor thesis, price, security, reserve policy, or individual votes.
Open questions
- Can financing filings, a cap table, board minutes, or TVI records establish the investor and vehicle identities?
- What customer milestones and stop conditions were used at each financing?
[t] David F. Marquardt oral history
- URL: https://archive.computerhistory.org/resources/access/text/2021/05/102792229-05-01-acc.pdf | Published: 2021 | Format: oral-history transcript | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: transcript page
Takeaways
- Provides an independent TVI-partner perspective on IVA's sometimes contentious diversity of views and TVI's formation.
- Identifies McMurtry, Marquardt, and Jim Bochnowski as TVI's 1980 founding trio (p. 22).
- Essential control against lone-investor storytelling: Marquardt was the Microsoft and Sun relationship lead.
Quotes
- “It was the three of us.” (p. 22)
Biography and decision evidence
- Marquardt recalls joining TVI from Stanford GSB and describes Bochnowski's operating/venture background and McMurtry's prior IVA experience.
Philosophy signals
- Tags: team / dissent / picking / sourcing / vehicle.
- Retrospective witness · moderate for partnership dynamics; cross-check deals against filings and McMurtry's own attribution.
Contradictions, counterevidence, and access limits
- Oral history is decades after the events and may privilege the speaker's own perspective.
Open questions
- Extract the exact Microsoft and Sun origin chronology and compare with their corporate records.
[t] Robert Maxfield oral history — ROLM
- URL: https://archive.computerhistory.org/resources/access/text/2012/07/102702237-05-01-acc.pdf | Published: 2012 | Format: oral-history transcript | Reliability: A for founder recollection | Access: full | Accessed: 2026-08-24 | Locator scheme: printed and PDF pages
Takeaways
- Maxfield supplies a founder-side account of ROLM's formation, early financing, product focus, and development, independent of McMurtry's later recollection.
- The account helps allocate company-formation and execution credit to the founders and initial financing credit to Jack Melchor; it is not a TVI record.
Quotes
- None reproduced; the source is represented through paraphrase and pinpointable metadata.
Biography and decision evidence
- Maxfield was one of ROLM's four founders. His account is relevant to the 1969 formation stage, which must remain separate from IVA's 1975 PBX investment.
- Founder execution evidence cannot establish IVA terms, ownership, or realized return.
Philosophy signals
- Tags: ROLM / founders / formation / financing / product focus / attribution.
- Retrospective witness / moderate: compare founder and investor recollections before assigning source, sponsor, or board credit.
Contradictions, counterevidence, and access limits
- The interview was recorded decades after formation and is subject to outcome knowledge and participant memory.
- No complete 1975 IVA memorandum, cap table, or distribution record appears in this source.
Open questions
- Can ROLM corporate or founder archives recover the 1969 and 1975 securities, cap tables, and board approvals?
- Which claims converge across Maxfield, McMurtry, and contemporaneous company records?
[w] Bidding for “Chips”: Mindset Corp. Goes Under the High-Tech Gavel
- URL: https://www.latimes.com/archives/la-xpm-1987-12-18-fi-19877-story.html | Published: 1987-12-18 | Format: contemporary press | Reliability: B | Access: full | Accessed: 2026-08-24 | Locator scheme: paragraph; archive page has no stable paragraph numbers
Takeaways
- Reports Mindset was founded in 1982 with $18 million in venture funding, entered bankruptcy proceedings in August 1985, and underwent facility liquidation in 1987.
- Identifies McMurtry as a former board member and reports TVI lost about $2 million.
- Contemporary trade-press archives separately describe advanced graphics, limited software compatibility, weak retail sales, layoffs, and a vertical-market pivot.
Quotes
- “It is time to move on.” (McMurtry, quoted near article end)
Biography and decision evidence
- Provides a public failure and stop-decision anchor that can test any people/technology-first narrative.
Philosophy signals
- Tags: failures / stop rules / market / follow-ons / boards.
- McMurtry's reflection is investor-stated · moderate for the lesson; the article does not document when or how the board actually stopped funding.
Contradictions, counterevidence, and access limits
- The roughly $2 million loss is single-source reported, not audited and not necessarily net of recoveries.
- Timing does not prove McMurtry led the original thesis or stop decision.
Open questions
- Retrieve financing/board records, milestones, follow-ons, and liquidation distributions.
[w] Photomixing Experiments with a Ruby Optical Maser and a Traveling-Wave Microwave Phototube
- URL: https://opg.optica.org/ao/abstract.cfm?uri=ao-1-1-51 | Published: 1962-01-01 | Format: journal article | Reliability: A | Access: abstract/metadata full, article PDF access-controlled | Accessed: 2026-08-24 | Locator scheme: Applied Optics 1(1), pp. 51–53; DOI 10.1364/AO.1.000051
Takeaways
- B. J. McMurtry and Anthony E. Siegman reported using an improvised microwave phototube to study coherent output from a ruby laser.
- The abstract describes a practical method, observed photobeats, and communications implications.
Quotes
- No quotation retained; the abstract is short and the article is access-controlled.
Biography and decision evidence
- Manuscript received October 6, 1961 and published January 1, 1962, corroborating McMurtry's doctoral-era laser/microwave work.
Philosophy signals
- Tags: technology / experimentation.
- Any connection from experimental improvisation to later venture diligence is researcher inference · provisional, not investor-stated.
Contradictions, counterevidence, and access limits
- Metadata and abstract do not establish later investing behavior. Do not retrofit an investment model from a successful experiment.
Open questions
- Check a legitimately accessible library copy for the full argument and McMurtry/Siegman division of work.
[t] Reid Dennis: Early Bay Area Venture Capitalists
- URL: https://digicoll.lib.berkeley.edu/record/218448/files/dennis_reid.pdf | Published: 2009 | Format: oral-history transcript | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: printed page and interview timestamp
Takeaways
- Independent partner route for IVA formation, fundraising, decision rights, portfolio, and early-venture context.
- Dennis recalls the first IVA fund at $19 million in 1973–74 and later discusses fund-size/management-fee incentives.
Quotes
- No quotation retained until the relevant sections are reconciled with McMurtry's account.
Biography and decision evidence
- Catalog description identifies Dennis as an IVA founder in 1974 and institutional investor since the early 1950s.
- Use for IVA attribution and the policy work McMurtry himself credits to Dennis, not merely as a second citation to McMurtry's recollection.
Philosophy signals
- Tags: vehicle / team / incentives / history / portfolio.
Contradictions, counterevidence, and access limits
- Like McMurtry's oral history, this is retrospective memory; it is independent in speaker, not contemporaneous in date.
Open questions
- Compare each IVA deal and fund claim with legal documents, board records, and contemporaneous press.
[w] Rice mourns trustee emeritus Burt McMurtry
- URL: https://news2.rice.edu/2018/09/10/rice-mourns-trustee-emeritus-burt-mcmurtry/ | Published: 2018-09-10 | Format: institutional obituary | Reliability: B | Access: full | Accessed: 2026-08-24 | Locator scheme: paragraph; page has no stable paragraph identifiers
Takeaways
- Provides independent evidence of Rice education, residential-college committee work, seventeen-year trusteeship, honors, and philanthropy.
- Describes him as a founding partner of TVI and IVA and a private investor.
Quotes
- No quotation necessary; institutional praise is not used as investment evidence.
Biography and decision evidence
- Says the McMurtrys graduated in 1956 and moved to California, then McMurtry earned Stanford engineering graduate degrees.
- Confirms seventeen years on the Rice board, eleven on Stanford's, and seven on Carnegie's.
Philosophy signals
- Tags: governance / education / networks.
Contradictions, counterevidence, and access limits
- Its portfolio examples mix firms and partner credit and even include KLA-Tencor, for which personal attribution remains unresolved.
- “Both graduated in 1956” compresses McMurtry's fifth-year engineering degree sequence described in the oral history.
Open questions
- Obtain Rice registrar/alumni records for exact BA/BSEE dates and board rosters for exact tenure.
[t] SpectraLink settles lawsuit with $1.5M payment
- URL: https://www.rcrwireless.com/20041008/archived-articles/spectralink-settles-lawsuit-with-1-5m-payment | Published: 2004-10-08 | Format: trade-press report | Reliability: B | Access: full | Accessed: 2026-08-24 | Locator scheme: article text
Takeaways
- RCR Wireless reported a $1.5 million insurer-funded settlement of the SpectraLink shareholder action.
- The report does not establish an admission, merits adjudication, or finding of individual wrongdoing against McMurtry.
Quotes
- None reproduced; the settlement amount and legal boundary are paraphrased.
Biography and decision evidence
- The report completes a later disposition lead raised by SpectraLink's 2002 Form 10-Q.
- It is adverse-governance context, not evidence of the original TVI investment thesis, McMurtry's sponsor role, or investment economics.
Philosophy signals
- Tags: SpectraLink / litigation / governance / disclosure / settlement / adverse evidence.
- Contemporaneous record / moderate: record allegations, defense posture, payment source, and disposition separately from any merits claim.
Contradictions, counterevidence, and access limits
- The article is secondary reporting; the settlement agreement and final court order were not located.
- An insurer-funded payment does not by itself determine liability or individual conduct.
Open questions
- Can the settlement agreement, dismissal order, or insurer record establish releases and whether any admission was made?
- Do board minutes reveal McMurtry's role in the disclosures or response?
[w] Burt McMurtry, longtime Stanford leader and champion for the arts, dies at 83
- URL: https://news.stanford.edu/stories/2018/09/burt-mcmurtry-longtime-stanford-leader-champion-arts-dies-83 | Published: 2018-09-13 | Format: institutional obituary | Reliability: B | Access: full | Accessed: 2026-08-24 | Locator scheme: section heading and paragraph
Takeaways
- Provides a compact Stanford-centered chronology, education, trustee service, later advisory work, philanthropy, and death.
- Reports eleven years on Stanford's board, including four as chair, and extensive advisory roles.
Quotes
- Bruce Dunlevie said McMurtry “encouraged people to ask questions.” (“A thoughtful and effective leader”)
Biography and decision evidence
- Confirms MS 1959 and PhD 1962, cofounding IVA/TVI, 1997–2008 trusteeship, September 2, 2018 death, and later university service.
- Its company list says McMurtry “helped fund” companies but does not identify vehicle or partner.
Philosophy signals
- Tags: governance / people / learning.
- Witness descriptions of ethics, curiosity, and open questioning are retrospective witness · moderate, not direct evidence of investment decisions.
Contradictions, counterevidence, and access limits
- The broad portfolio list cannot support Microsoft/Sun personal lead credit.
- The four-year chair claim conflicts with the 2009 oral-history wording and needs board-minute reconciliation.
Open questions
- Locate Stanford trustee rosters/minutes for exact chair dates.
[w] Synaptics 2002 final prospectus
- URL: https://www.sec.gov/Archives/edgar/data/817720/000095015302000114/p65342b4e424b4.htm | Published: 2002-01-29 | Format: SEC 424B4 | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: HTML lines/section and printed prospectus page
Takeaways
- TVI-3, TVI Management-3, and TVI-IV held 2,077,339 shares, 11.5% before and 9.0% after the offering (Principal and Selling Stockholders, printed pp. 66–67; HTML lines 3352–3402).
- McMurtry, Mark Wilson, Marquardt, Kagle, and Johnston shared voting and dispositive power; this is team/entity evidence, not sole-McMurtry ownership.
- If the over-allotment were fully exercised, the entities would sell 154,169 and retain 1,923,170 shares (printed p. 68; lines 3419–3443).
Quotes
- No quotation necessary; tables and footnotes are paraphrased.
Biography and decision evidence
- Financing table shows TVI-3 purchased Series A/B and TVI-IV purchased Series D/E/F (printed p. 64; lines 3120–3153).
- Prospectus establishes a pre/post-IPO paper snapshot, not net fund cash flows or who originated the investment.
Philosophy signals
- Tags: ownership / follow-ons / team / portfolio / exits.
Contradictions, counterevidence, and access limits
- Shared power prevents individual credit. IPO shares and offer price do not establish realized proceeds, dilution-adjusted multiple, carry, or net return.
Open questions
- Locate board history, original investment memo, cash-flow distributions, and partner role evidence.
[w] Meet the Venture Capitalists — Technology Venture Investors
- URL: https://static.bslabs.net/wwdc/1990/Meet%20the%20Venture%20Capitalists%20-%20Technology%20Venture%20Investors.pdf | Published: 1990 | Format: firm presentation | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: PDF page
Takeaways
- Lists TVI as founded in 1980, with $270 million under management and four investment partners (pp. 1–4).
- Describes a software/systems focus, active advice without running companies, and selection for differentiated technology, market-domination opportunity, and outstanding management (pp. 5–9).
- The investment list is headed “Examples of Investments by TVI Partners” and includes pre-TVI ROLM and Seagate, so it is not a fund portfolio.
Quotes
- “We don't want to run your business” (p. 6).
- “Outstanding management” (p. 8).
Biography and decision evidence
- Identifies McMurtry, Marquardt, Kagle, and Johnston as the 1990 partner team and gives experience summaries (pp. 2–4).
- Adds Cadnetix, Outbound Systems, Stratus, and Sybase as research leads but leaves vehicle and personal roles unresolved (pp. 4–5).
Philosophy signals
- Tags: picking / market / technology / boards / team / portfolio.
- Contemporaneous firm positioning · strong for what TVI marketed in 1990; moderate for actual behavior until deal records corroborate it.
Contradictions, counterevidence, and access limits
- “Outstanding track record” is self-description without economics.
- Partner-career examples must not be counted mechanically as TVI fund holdings.
Open questions
- Locate a provenance record for this WWDC-era artifact and fund-level portfolio schedules.
[w] UC Regents alternative investments as of March 31, 2003
- URL: https://regents.universityofcalifornia.edu/regmeet/nov03/603spreadsheetnov.pdf | Published: 2003-11 meeting packet; values as of 2003-03-31 | Format: institutional LP schedule | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: PDF page and fund row; mandatory footnotes on pp. 1–2
Takeaways
- UC's TVI-2 row reports $4.000 million cash in, $6.744 million cash out, zero NAV, 1.69x, and 9.2% net IRR.
- TVI-3 reports $8.000 million cash in, $13.333 million cash out, zero NAV, 1.67x, and 7.2% net IRR.
- TVI-4 reports $12.000 million cash in, $38.060 million cash out, $1.205 million NAV, 3.27x, and 24.1% net IRR.
Quotes
- No quotation; numerical rows and footnotes are paraphrased.
Biography and decision evidence
- This is one LP's net experience, not audited whole-fund or McMurtry-personal economics.
- TVI-1 is absent, preventing a direct Microsoft-dominance test across all four funds.
Philosophy signals
- Tags: vehicle / portfolio / returns / incentives.
Contradictions, counterevidence, and access limits
- Footnotes say net IRR includes fees, expenses, carry, and GP-determined NAV; valuation policies lacked a common industry standard, pace affects IRR, and cross-fund comparisons can mislead.
- TVI-4 retained residual NAV and was not fully realized at the snapshot.
Open questions
- Obtain TVI-1 data and company-level contribution schedules for all funds; do not rank companies from fund-only results.
[w] In re VeriFone Securities Litigation
- URL: https://law.justia.com/cases/federal/appellate-courts/F3/11/865/488523/ | Published: 1993 | Format: Ninth Circuit opinion | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: reporter citation and opinion section
Takeaways
- In re VeriFone Securities Litigation, 11 F.3d 865 (9th Cir. 1993), arose from shareholder forecast/nondisclosure allegations.
- McMurtry appears in the caption as a defendant-appellee.
- The Ninth Circuit affirmed dismissal with prejudice; the opinion is adverse-search evidence but not a wrongdoing finding against McMurtry.
Quotes
- No quotation needed; procedural posture is paraphrased.
Biography and decision evidence
- Confirms McMurtry's legal-caption connection to VeriFone and the disposition of this case.
Philosophy signals
- Tags: governance / criticism / litigation / disclosure.
Contradictions, counterevidence, and access limits
- Allegations are not findings. Dismissal does not independently prove every forecast was accurate or establish McMurtry's board conduct.
Open questions
- Locate company board tenure, contemporaneous proxy statements, related actions, and any separate disposition records.
[t] Joint Economic Committee Live Testimony and Q&A
- URL: https://files.eric.ed.gov/fulltext/ED255720.pdf | Published: 1984-08-28 | Format: congressional testimony and Q&A | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: printed pages plus PDF pages; live opening printed pp. 145–147/PDF pp. 149–151; Q&A later in record
Takeaways
- McMurtry’s live opening is distinct from the prepared NVCA exhibit that follows. The live portion covers Rice and Stanford, Sylvania/GTE, his 1969 venture entry, ROLM, and IVA’s 1973–1974 fundraising. Printed pp. 145–147/PDF pp. 149–151
- He says the $19 million vehicle represented roughly one-third of venture capital invested in 1974 and describes an early-stage, western-U.S. focus. Evidence: investor-stated / strong that he made the claim; provisional for the proportion because no denominator is supplied. Printed p. 146/PDF p. 150
- He places entrepreneurs at the center of company formation. In Q&A, the “people” line appears at printed p. 203/PDF p. 207—not printed p. 207. Evidence: investor-stated / strong. Printed pp. 200–203/PDF pp. 204–207
- Pressed on the capital-gains mechanism advanced by the written exhibit, McMurtry concedes that he cannot prove it and describes it as a strong impression. Evidence: investor-stated / strong. Printed p. 192/PDF p. 196
Quotes
- “The critical element is the people.” — McMurtry, Q&A, printed p. 203/PDF p. 207. Official record
Biography and decision evidence
- Contemporaneous chronology: Rice and Stanford education; twelve years with Sylvania/GTE; venture work from 1969; ROLM involvement; IVA fundraising begun in 1973 and completed in 1974.
- The testimony gives ecosystem and people beliefs, not a deal-by-deal approval ledger. It does not assign Microsoft, Sun, or other partner-led work.
- Separate evidentiary objects:
- live opening: printed pp. 145–147/PDF pp. 149–151;
- prepared written exhibit: printed pp. 148–165/PDF pp. 152–169;
- Q&A: later hearing pages, including printed p. 192/PDF p. 196 and printed pp. 200–203/PDF pp. 204–207.
Philosophy signals
- Tags: people / entrepreneurs / capital formation / geography / macro / evidence.
- Investor-stated / strong: people are the critical company-building element.
- Researcher inference / strong: distinguish a repeated selection belief from a policy causal claim that its proponent explicitly could not prove.
Contradictions, counterevidence, and access limits
- The later Bancroft oral history describes IVA’s 1974 scale as more than one-fifth of money raised; the 1984 testimony says one-third of capital invested. Different measures may explain the divergence, but neither denominator is shown. Bancroft printed pp. 44–45
- The prepared exhibit is associated with McMurtry’s NVCA role and should not be quoted as spontaneous live testimony.
Open questions
- Which published 1974 capital series, if any, matches McMurtry’s denominator?
- Does an audiovisual hearing recording survive that would distinguish read remarks from extemporaneous statements?
[t] Burt McMurtry: Venture Capitalist and Technology Investor
- URL: https://digicoll.lib.berkeley.edu/record/103606 | Transcript: https://digicoll.lib.berkeley.edu/record/218493/files/mcmurtry_burt.pdf | Published: interviews recorded 2009; transcript cataloged by Bancroft Library | Format: oral history transcript with cataloged audiovisual media | Reliability: A for direct retrospective voice | Access: full transcript; four cataloged videodiscs not reviewed | Accessed: 2026-08-24 | Locator scheme: printed page plus interview timestamp; PDF page is ten pages higher than printed page in cited body locations
Takeaways
- ROLM has two stages in McMurtry’s account. Jack Melchor personally financed and helped form it in 1969; PAIC did not initially participate. In 1975 McMurtry examined a PBX opportunity, disclosed his conflict, recused himself from IVA’s approval, and joined the board after partners Dennis, Jamieson, and Norris approved. Printed pp. 29–33; timestamps 02-00:24:48–02-00:34:22
- McMurtry recalls an early vehicle of roughly $3 million, sixteen startups, losses on about half, and six years and two months before the first returned dollar. Evidence: retrospective witness / moderate. Printed pp. 34–36
- He says people were his leading factor but acknowledges that compelling people could bias him into mistakes; startup stage was a preference, not an absolute rule, with Microsoft and ROLM as later-stage exceptions. Evidence: retrospective witness / moderate. Printed pp. 37–40; timestamps 02-00:47:01–02-00:56:58
- He credits Dave Marquardt for Microsoft and Sun, describes his own Intuit board role, and uses DAVID Systems as a failure where a long effort and substantial capital never found a market application. Evidence: retrospective witness / moderate. Printed pp. 49–51; timestamps 03-00:25:30–03-00:32:33
- He recalls multi-part diligence across market, product/technology, people, and references; a negative-reference test; reciprocal founder diligence; and a rotating skeptic when TVI partners were unanimous. Evidence: retrospective witness / moderate. Printed pp. 51–54; timestamps 03-00:33:23–03-00:44:14
- He describes boards as constructive company-building bodies and limits active service to roughly six to eight boards, connecting partner capacity to fund size. Evidence: retrospective witness / moderate. Printed pp. 55–57; timestamps 03-00:45:37–03-00:54:18
Quotes
- None reproduced. The transcript rights notice permits research use but reserves literary rights and requires written permission for publication quotation. No permission was sought or obtained. Rights notice, printed p. ii
Biography and decision evidence
- Vehicle/team attribution: Melchor gets ROLM formation and initial personal-capital credit; IVA partners get later approval credit; Marquardt gets Microsoft and Sun credit; McMurtry’s described role includes ROLM diligence/board work and Intuit board work.
- Process attribution: the rotating skeptic is described as a TVI partnership practice rather than solely McMurtry’s invention.
- Ex-ante clue: McMurtry says he investigated the PBX opportunity before the IVA check, but the transcript does not provide a complete 1975 memo, market forecast, price, ownership, or term sheet.
Philosophy signals
- Tags: people / market / technology / references / conflicts / dissent / boards / portfolio capacity / failures.
- Retrospective witness / moderate: people lead, but market evidence is an independent gate; DAVID Systems is the strongest disclosed counterexample.
- Researcher inference / moderate: good process separates sponsor, approver, conflict, and board owner, and makes dissent explicit before approval.
Contradictions, counterevidence, and access limits
- The catalog warns that oral history is partisan and not a final, verified, complete account. Catalog description
- The 2009 recollection put the IVA raise above one-fifth of money raised in 1974, while the 1984 live statement put it near one-third of capital invested. Different measures may explain the unlike proportions; neither denominator is supplied. Printed pp. 44–45; JEC printed p. 146/PDF p. 150
- ROLM return recollection differs from the 2002 CHM panel; neither is audited here.
- Full audiovisual comparison was not performed.
Open questions
- Can vehicle documents reconstruct the 16-company denominator and outcomes?
- Do ROLM/Intuit/DAVID board records expose decision rights, stop conditions, and follow-on logic?
- Can Bancroft authorize publication quotation or provide legitimate access to the audiovisual media?
[t] Pioneers of Venture Capital
- URL: https://computerhistory.org/events/pioneers-venture-capital/ | Video: https://www.youtube.com/watch?v=ult7VFgxiKo | Published: 2002-09-30 | Format: panel video | Reliability: A for direct voice, caption accuracy limited | Access: full video; machine-generated English captions, no creator transcript located | Accessed: 2026-08-24 | Locator scheme: video timestamps
Takeaways
- The official event page places McMurtry on a six-pioneer panel with William Draper III, Franklin “Pitch” Johnson, Thomas Perkins, Arthur Rock, and Don Valentine, moderated by Gordon Davidson. CHM event metadata
- Around 33:25–35:53, McMurtry recalls twelve years at Sylvania/GTE, a wish to work with small companies, joining Jack Melchor in 1969 without intending a permanent venture career, and a capital-starved environment that demanded collaboration and patience. He dates the first realized gain to six years and two months after the investment effort began. Evidence: investor-stated / moderate because retrospective and auto-captioned. Video, 33:25–35:53
- Around 48:56–50:28, he calls ROLM the first large success, describes four founders and staged participation by Melchor’s vehicle and IVA, recalls a 1976 IPO and an extended post-offering period below the offer price, and gives a retrospective buyer-return multiple through the IBM acquisition. Evidence: retrospective witness / moderate for sequence; provisional for the multiple. Video, 48:56–50:28
Quotes
- No verbatim quote used. The only available captions are automatically generated and contain recognition errors; all material wording is paraphrased after checking the video interval.
Biography and decision evidence
- The account connects McMurtry’s operating career to his interest in small-company work and assigns the initial opportunity to Jack Melchor.
- ROLM is described as a staged history, not a single IVA-originated check. The account reinforces the need to separate company formation, personal/vehicle financing, later fund investment, board service, public offering, and final acquisition.
- The panel moderator’s introduction around 18:00–18:50 contains biographical and deal claims but is not McMurtry direct voice; caption errors further reduce its weight.
Philosophy signals
- Tags: patience / capital scarcity / people / team attribution / exits / historical context.
- Retrospective witness / moderate: early venture building required patient collaboration because replacement capital was scarce.
- Researcher inference / moderate: patience must be conditioned on a continuing evidence path; this clip alone supplies no stop rule.
Contradictions, counterevidence, and access limits
- The CHM ROLM buyer-return multiple differs from McMurtry’s 2009 Bancroft recollection. Neither is treated as audited; both are labeled reported retrospective figures.
- Auto-captions are not a verbatim transcript. Names, numbers, punctuation, and speaker turns require audio review.
- Recollection occurred decades after the initial investment and after the outcome was known.
Open questions
- Does CHM hold a curator transcript or creator subtitles?
- Can contemporaneous ROLM offering/acquisition records resolve the sequence and buyer return without relying on memory?
[t] François Mitterrand Visit to Stanford CIS — Presence Route
- URL: https://engineering100.stanford.edu/stories/bridging-worlds-chips-code-and-cosmos | Published: retrospective Stanford Engineering history; event occurred 1984 | Format: institutional history and captioned photograph | Reliability: A for institutional record and identified image | Access: partial — page and photograph only; no program, recording, or transcript located | Accessed: 2026-08-24 | Locator scheme: Mitterrand visit section and photo caption
Takeaways
- Stanford Engineering records that French President François Mitterrand visited the Center for Integrated Systems in 1984 and identifies Burt McMurtry among a large group in the accompanying photograph. “Bridging Worlds: Chips, Code and Cosmos,” visit section
- The page verifies presence in an institutional network. It does not say McMurtry delivered remarks, participated in a panel, or spoke with Mitterrand. [contemporaneous record · strong] [researcher inference · insufficient public record].
Quotes
- None; no McMurtry remarks were located.
Biography and decision evidence
- Presence at the CIS visit is consistent with McMurtry’s Stanford and technology connections.
- A group photograph supplies no evidence about his purpose, decision role, or substantive contribution.
Philosophy signals
- None supportable. Network proximity cannot be converted into an investment belief.
Contradictions, counterevidence, and access limits
- Any label such as “Mitterrand conference talk” overstates the record.
- No contemporaneous program, press report naming McMurtry as a speaker, transcript, or audiovisual segment was found.
Open questions
- Do Stanford CIS or presidential-visit archives retain a participant program or recording?
- Was McMurtry present as trustee, donor, engineer, investor, or another role?
[t] Burton and Deedee McMurtry College “Sneak Peek” — Archive Route
- URL: https://news2.rice.edu/2009/09/03/sneak-a-peek-at-duncan-and-mcmurtry-colleges-sept-8/ | Archive: https://archives.library.rice.edu/repositories/2/top_containers/10793 | Published: event 2009-09-08; notice 2009-09-03 | Format: event notice and audiovisual archive metadata | Reliability: A for Rice records | Access: metadata-only for DVD content | Accessed: 2026-08-24 | Locator scheme: news article; Woodson Research Center Box 38/top-container record
Takeaways
- Rice announced a September 8 open house at Duncan and McMurtry colleges. The notice describes informal access and the buildings; it does not name Burt McMurtry as an attendee or speaker. Rice News event notice
- The Woodson Research Center catalog lists a DVD for the Burton and Deedee McMurtry College “Sneak Peek” Ceremony, dated 2009-09-08, in Box 38. The content is not exposed online. Archive top-container record
- Contemporaneous record / strong for event and archive object; insufficient public record for McMurtry’s appearance or speaking turn.
Quotes
- None; no speech content was accessed.
Biography and decision evidence
- The event concerns a college bearing Burton and Deedee McMurtry’s names and is relevant to their Rice institutional relationship.
- Naming context is not evidence that either donor attended, spoke, or made a claim at the event.
Philosophy signals
- None supportable from the accessible event notice or catalog metadata.
Contradictions, counterevidence, and access limits
- Event marketing and archival title can be misread as an appearance record; neither verifies the person’s presence.
- The DVD must be legitimately reviewed before making content or speaker claims.
Open questions
- Does Box 38 contain the complete ceremony, and does its catalog/folder description list speakers?
- Can the Woodson Research Center provide a lawful viewing route or transcript?
[t] Trustees Share Inner Workings of Board
- URL: https://stanfordreview.org/trustees-share-inner-workings-of-board/ | Published: 2009-12-03 | Format: reported event article | Reliability: B | Access: partial — secondary report; no recording or transcript located | Accessed: 2026-08-24 | Locator scheme: article paragraphs; no stable paragraph numbers supplied by interface
Takeaways
- The Stanford Review reports that McMurtry and Leslie Hume spoke to the Stanford Historical Society about the Board of Trustees. The article attributes to McMurtry a custodial view of the endowment and university property and says trustees share authority, responsibility, and liability. Article opening and governance discussion
- It reports McMurtry’s account of the presidential-search process, including a broad search committee and board approval, and his concern that tuition lacked a sustainable long-term program. Presidential search and tuition paragraphs
- Reported speech / moderate: governance requires custody, shared formal responsibility, and long-horizon financial attention. The article does not establish his exact wording or full context.
Quotes
- No quotation reproduced because the source is a journalist-mediated report rather than a transcript.
Biography and decision evidence
- This source documents McMurtry speaking publicly about Stanford governance after his board chair period.
- It offers evidence about institutional decision structure, not a venture investment committee or startup board.
Philosophy signals
- Tags: governance / stewardship / decision rights / succession / long horizon.
- Researcher inference / provisional for VC transfer: make authority and liability explicit and treat assets as mission-bound rather than personally owned.
Contradictions, counterevidence, and access limits
- The report may select or compress remarks; no audio, transcript, agenda, or complete Q&A was located.
- Shared trustee authority does not imply consensus decision-making or show how dissent was handled.
- University governance cannot be mapped directly to a fund partnership or startup board without adjustment.
Open questions
- Does the Stanford Historical Society hold a recording, transcript, program, or event notes?
- What specific tuition alternatives or governance reforms did McMurtry propose, if any?
[w] Modulation and Direct Demodulation of Coherent and Incoherent Light
- URL: https://books.google.com/books/about/Modulation_and_Direct_Demodulation_of_Co.html?id=ZUgFAAAAIAAJ | Published: 1962 | Format: Stanford Electronics Laboratories report | Reliability: A for catalog metadata | Access: partial — catalog/preview only | Accessed: 2026-08-24 | Locator scheme: title and bibliographic record
Takeaways
- The record identifies a 1962 Stanford Electronics Laboratories report by Burton J. McMurtry on optical modulation and demodulation.
- It strengthens the chronology of McMurtry's doctoral-era experimental engineering but exposes too little text for a substantive technical or philosophical reconstruction.
Quotes
- None reproduced; no sufficiently complete legitimate full-text route was located.
Biography and decision evidence
- The report places McMurtry in coherent/incoherent-light research around completion of his Stanford doctorate.
- Catalog authorship does not establish individual experimental contributions, later venture judgment, or investment results.
Philosophy signals
- Tags: optics / measurement / communications / technical formation / access limit.
- Researcher inference / insufficient public record: any link from demodulation research to venture diligence remains hypothetical.
Contradictions, counterevidence, and access limits
- The Google Books route supplies metadata and limited preview, not enough content to test methods, claims, limitations, or citations.
- The separate photomixing paper provides usable abstract-level evidence; it should not be conflated with this report.
Open questions
- Can Stanford Libraries or another legitimate archive provide the full report?
- Does the report acknowledge collaborators or describe applications that later appear in McMurtry's engineering work?
[w] Photomixing Experiments with a Ruby Optical Maser and a Traveling-Wave Microwave Phototube
- URL: https://opg.optica.org/ao/abstract.cfm?uri=ao-1-1-51 | Published: 1962-01-01 (manuscript received 1961-10-06) | Format: co-authored technical article | Reliability: A | Access: partial — abstract and bibliographic metadata; full article not accessed | Accessed: 2026-08-24 | Locator scheme: journal volume/issue/pages and abstract
Takeaways
- B. J. McMurtry and A. E. Siegman used a standard oxide-cathode S-band traveling-wave phototube in an improvised experiment on a coherent ruby laser. The abstract reports frequency components separated by roughly 600 Mc/s and photobeats for the third through seventh nearest-neighbor modes. Applied Optics 1(1), pp. 51–53, abstract
- The contribution is a measurement technique: convert optical-mode relationships into observable microwave signals and identify possible communications applications. [contemporaneous record · strong].
- This is strong evidence of early experimental-engineering work. It is not direct evidence of a later venture-selection rule or investment result. Evidence: documented behavior / strong for formation; researcher inference / insufficient public record for investment causation.
Quotes
- No quotation reproduced: the accessible abstract is short, and paraphrase preserves the source’s copyright while carrying the relevant evidence.
Biography and decision evidence
- Publication in January 1962 places McMurtry in optical-maser/photomixing research before his venture career. Authorship is shared with A. E. Siegman; no individual division of experimental or writing work is stated in the accessible record.
- The experiment’s improvised use of existing apparatus shows resourceful technical practice, but the abstract does not expose the decision process that selected the problem or equipment.
Philosophy signals
- Tags: technology / measurement / evidence / communications.
- Researcher inference / provisional: make technical claims observable before treating them as decision inputs. The bridge from laboratory method to venture diligence remains unverified.
Contradictions, counterevidence, and access limits
- Full text was not accessed. Apparatus details, uncertainty, limitations, underlying citations, and the paper’s complete reasoning cannot be assessed.
- A technical publication does not establish market judgment, governance skill, or investing efficacy.
Open questions
- Can a legitimate library route expose the full paper?
- What work did each co-author perform, and did McMurtry later describe this research as formative?
[w] Prepared Statement Presented to the Joint Economic Committee
- URL: https://files.eric.ed.gov/fulltext/ED255720.pdf | Published: 1984-08-28 | Format: prepared congressional-hearing exhibit | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: printed pages and PDF pages; prepared statement printed pp. 148–165/PDF pp. 152–169
Takeaways
- The exhibit identifies McMurtry as secretary and a board member of the National Venture Capital Association. It is safest attributed to the NVCA position he presented, not assumed to be a sole-authored personal manifesto. Masthead, printed p. 148/PDF p. 152
- It argues that entrepreneurs are central to forming young companies and that venture capital supplies specialized equity, governance, and access to resources. Printed pp. 150–153/PDF pp. 154–157
- It uses government and industry employment/innovation evidence to make a public-policy case for preserving a capital-gains differential and improving incentive-stock-option treatment. Printed pp. 153–165/PDF pp. 157–169
- Contemporaneous record / strong: this was the association position placed into an official record. Researcher inference / moderate: the causal chain assumes that tax treatment materially changes the supply of venture capital and entrepreneurial effort.
Quotes
- No quotation necessary; the argument is summarized from the official exhibit.
Biography and decision evidence
- McMurtry was speaking in a formal industry-policy role, giving evidence of his participation in national venture-capital advocacy by 1984.
- This exhibit is distinct from his live opening at printed pp. 145–147/PDF pp. 149–151 and from committee Q&A. Those sections contain personal biography and a less certain causal statement.
Philosophy signals
- Tags: people / capital formation / incentives / boards / macro / policy.
- Contemporaneous record / strong: entrepreneurs, specialized capital, and incentives are presented as complementary parts of a company-formation system.
- Researcher inference / moderate: at firm level, capital should be tied to capabilities and people rather than treated as an end in itself; the exhibit does not disclose pricing, ownership, reserve, or exit rules.
Contradictions, counterevidence, and access limits
- In Q&A, McMurtry said he could not prove the claimed capital-gains mechanism and described it as a strong impression. Printed p. 192/PDF p. 196 That statement weakens causal confidence but not the existence of the contemporaneous belief.
- Employment and innovation statistics do not by themselves distinguish venture capital’s incremental effect from selection, sector, vintage, or macro conditions.
- Drafting and editing responsibility inside the NVCA is not disclosed.
Open questions
- Are NVCA drafting files or contemporaneous board minutes public?
- Which of the exhibit’s policy positions did McMurtry advocate before or after this hearing?
[w] Meet the Venture Capitalists — Technology Venture Investors
- URL: https://static.bslabs.net/wwdc/1990/Meet%20the%20Venture%20Capitalists%20-%20Technology%20Venture%20Investors.pdf | Published: 1990 | Format: partner presentation | Reliability: B+ | Access: full | Accessed: 2026-08-24 | Locator scheme: PDF pp. 1–6
Takeaways
- The deck positions TVI as an information-technology partnership that supplies equity capital and active board assistance to young companies.
- Its example list is explicitly investments by TVI partners, so pre-TVI ROLM and partner-career examples cannot be treated as a TVI fund ledger.
- Selection language emphasizes differentiated technology, important markets, capable management, and close investor involvement.
Quotes
- None reproduced; the short deck is paraphrased with page-level citation in the root analysis.
Biography and decision evidence
- The 1990 team roster and company examples are contemporaneous evidence of public firm positioning.
- The deck does not name sponsor, approving partner, legal vehicle, check, ownership, reserve, or realized cash flows for each company.
Philosophy signals
- Tags: TVI / positioning / technology / market / management / boards / attribution.
- Contemporaneous record / strong: separate firm-sponsored criteria from proof that McMurtry personally authored or consistently applied them.
Contradictions, counterevidence, and access limits
- Marketing materials select favorable examples and omit losses, passes, ordinary outcomes, and denominator detail.
- “By TVI partners” mixes institutional and prior-career experience, limiting performance inference.
Open questions
- Who drafted and presented each slide, and were criteria used in formal investment memoranda?
- Can a fund schedule map every example to a vehicle, partner, date, cost, and outcome?
[w] Houston Philosophical Society Talk — Retrieval Route
- URL: https://digicoll.lib.berkeley.edu/record/218493/files/mcmurtry_burt.pdf | Published: unknown; referenced in interviews recorded in 2009 | Format: unlocated talk text referenced in an oral history | Reliability: B for existence, C/insufficient for content | Access: metadata/indirect reference only | Accessed: 2026-08-24 | Locator scheme: Bancroft printed pp. 55–56; interview timestamp 03-00:45:37 onward; rights notice printed p. ii
Takeaways
- The Bancroft interviewer said she had read a talk McMurtry gave to the Houston Philosophical Society and used it to frame a question about founders and company-building. The original title, date, text, host record, and publication status were not located. Bancroft transcript, printed pp. 55–56
- Exact-name, name-variant, society-domain, and general web/archive searches found no public original as of 2026-08-24. Evidence: retrospective witness / moderate for existence; insufficient public record for substantive content.
- The oral-history exchange supports only a provisional paraphrase that McMurtry resisted a lone-genius account of company creation. It does not make the missing speech content-analyzed.
Quotes
- None. The Bancroft transcript’s rights notice permits research use but requires written permission for publication quotation; this note uses paraphrase only. Rights notice, printed p. ii
Biography and decision evidence
- The reference suggests McMurtry once addressed a Houston intellectual audience, consistent with his Rice/Houston ties, but date and setting are unknown.
- No decision, deal, audience response, or contemporaneous publication has been verified.
Philosophy signals
- Tags: founders / teams / company building / attribution.
- Retrospective witness / provisional: company creation may be better explained by groups of contributors than a single hero.
Contradictions, counterevidence, and access limits
- The interviewer’s recollection and framing are not the original text.
- The oral history is retrospective and the Bancroft catalog warns that oral histories are partisan and not a final, verified, complete account. Catalog record
- Quoting the transcript for publication requires permission; no such permission was sought or obtained.
Open questions
- Does the Houston Philosophical Society retain a program, member paper, or privately circulated text?
- What were the title and date, and did McMurtry prepare or publish the text himself?
[w] Passing the Torch
- URL: https://bondholder-information.stanford.edu/sites/g/files/sbiybj21416/files/media/file/stanford-annual-financial-report-2004.pdf | Published: 2004 | Format: annual-report board-chair message | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: “Passing the Torch,” printed p. 16/PDF p. 18
Takeaways
- Newly elected board chair McMurtry frames trusteeship as an intergenerational stewardship role and credits outgoing chair Isaac Stein, university leadership, faculty, donors, and volunteers. Printed p. 16/PDF p. 18
- He places endowment growth to nearly $10 billion and $524 million in gifts beside undergraduate, interdisciplinary, and graduate-education initiatives. These are Stanford figures, not McMurtry venture-fund returns. Printed p. 16/PDF p. 18
- Contemporaneous record / strong: strong resources and broad participation are presented as enablers of mission. Researcher inference / moderate: the message reconstructs a rule of preserving capacity while investing in people and programs.
Quotes
- No quotation captured; the source is adequately represented through paraphrase and pinpoint citation.
Biography and decision evidence
- This is the first chair message in the four-report sequence and documents the succession from Isaac Stein to McMurtry.
- It evidences public governance style—distributed credit and continuity—but not private venture-board behavior.
Philosophy signals
- Tags: governance / stewardship / people / succession / long horizon / institutions.
- Researcher inference / provisional for VC transfer: govern as custodian of mission and assets rather than as sole author; pair continuity with investment in new capability.
Contradictions, counterevidence, and access limits
- Annual-report prose may be collaboratively drafted or edited; sentence-level authorship is not public.
- University governance has different duties, time horizons, and stakeholder structures from venture partnerships and startup boards.
Open questions
- Are board minutes or chair drafts available in Stanford archives?
- Did McMurtry explicitly connect university stewardship with venture governance elsewhere?
[w] A Wise Investment
- URL: https://bondholder-information.stanford.edu/sites/g/files/sbiybj21416/files/media/file/stanford-annual-financial-report-2005.pdf | Published: 2005 | Format: annual-report board-chair message | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: “A Wise Investment,” printed p. 16/PDF p. 18
Takeaways
- McMurtry reports a 19.5% one-year endowment return, a 15.3% three-year annualized return, $603.6 million in gifts, and $1.1 billion for the Campaign for Undergraduate Education. These are institutional figures, not personal or venture-fund results. Printed p. 16/PDF p. 18
- He presents financial capacity as supporting people, graduate and undergraduate education, and cross-school work on health, environment, and international problems. Evidence: contemporaneous record / strong. Printed p. 16/PDF p. 18
- Researcher inference / moderate: the reasoning treats money as an enabling input and organizational boundary-crossing as a capability.
Quotes
- No quotation captured.
Biography and decision evidence
- The message documents McMurtry’s second year as chair and the university priorities he publicly sponsored.
- It does not reveal his role in selecting Stanford’s investments or programs, nor decision rights among trustees, management, and faculty.
Philosophy signals
- Tags: people / portfolio / institutions / mission / interdisciplinary work.
- Researcher inference / provisional for VC transfer: ask what capability the capital funds and whether the team can work across technical and organizational boundaries.
Contradictions, counterevidence, and access limits
- The title’s investment metaphor must not be treated as a disclosed venture-picking framework.
- No price discipline, ownership target, reserve policy, or exit rule appears.
- Collaborative annual-report authorship remains possible.
Open questions
- What committee material explains how the board chose among competing uses of capital?
- Which initiatives produced measurable outcomes, and under whose operational leadership?
[w] Setting a Bold Agenda
- URL: https://bondholder-information.stanford.edu/sites/g/files/sbiybj21416/files/media/file/stanford-annual-financial-report-2006.pdf | Published: 2006 | Format: annual-report board-chair message | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: “Setting a Bold Agenda,” printed p. 16/PDF p. 18
Takeaways
- McMurtry links Stanford’s financial capacity to the Stanford Challenge and to interdisciplinary priorities in human health, environmental sustainability, and international peace and security. Printed p. 16/PDF p. 18
- The message reports a 19.5% one-year endowment return and a 12.3% five-year annualized return versus a 3.0% U.S.-stock comparison, while explicitly warning that past performance does not guarantee future performance. Printed p. 16/PDF p. 18
- Researcher inference / strong: the prospective rule is not to extrapolate a favorable realized period automatically; financial capacity should be deployed toward mission under uncertainty.
Quotes
- No quotation captured; the caution and figures are paraphrased with the exact page locator.
Biography and decision evidence
- The message shows McMurtry publicly sponsoring a multi-year campaign and long-horizon institutional priorities as board chair.
- It identifies broad donor participation but does not allocate causal credit for campaign design or investment performance.
Philosophy signals
- Tags: risk / portfolio / stewardship / long horizon / institutions.
- Researcher inference / moderate for modern practice: separate realized performance from prospective distribution and name the conditions that may not repeat.
Contradictions, counterevidence, and access limits
- Celebrating performance while warning against projection is a deliberate tension, not a contradiction to erase.
- The endowment comparison is not a controlled test of governance skill and cannot be transported to venture returns.
- Drafting responsibility is undisclosed.
Open questions
- What scenario or risk analysis accompanied the board’s campaign commitments?
- Was the past-performance warning standard Stanford language or selected by McMurtry?
[w] University Launches $4.3 Billion Campaign to Address Global Challenges
- URL: https://stanfordmag.org/contents/university-launches-4-3-billion-campaign-to-address-global-challenges | Published: 2006 | Format: university statement/news | Reliability: A for institutional publication | Access: full | Accessed: 2026-08-24 | Locator scheme: McMurtry attribution in article body
Takeaways
- The article records a short statement by board chair McMurtry supporting the Stanford Challenge and its long-horizon global priorities.
- It confirms public sponsorship in a governance role; it is not a venture investment memo or sole-authored essay.
Quotes
- None reproduced; the brief statement is paraphrased to avoid over-weighting a short institutional quotation.
Biography and decision evidence
- The route corroborates McMurtry's chair role during the 2006 campaign launch.
- It supplies no evidence about TVI sourcing, price, ownership, governance interventions, or returns.
Philosophy signals
- Tags: Stanford / campaign / governance / long horizon / interdisciplinary work / public sponsorship.
- Contemporaneous record / moderate: institutional capacity should be directed toward explicitly named, long-duration missions.
Contradictions, counterevidence, and access limits
- Institutional communications may be edited collaboratively, and the short statement cannot establish sentence-level authorship or a general decision doctrine.
- University fundraising differs materially from venture underwriting and fund governance.
Open questions
- Is a longer McMurtry campaign speech or chair draft preserved in Stanford archives?
- How did trustees divide campaign approval, oversight, and execution rights?
[w] One Year Into The Stanford Challenge
- URL: https://bondholder-information.stanford.edu/sites/g/files/sbiybj21416/files/media/file/stanford-annual-financial-report-2007.pdf | Published: 2007 | Format: annual-report board-chair message | Reliability: A | Access: full | Accessed: 2026-08-24 | Locator scheme: “One Year Into The Stanford Challenge,” printed p. 16/PDF p. 18
Takeaways
- McMurtry reports $832 million in gifts and $2.9 billion toward the campaign, alongside a 23.4% twelve-month endowment return and a 17.7% five-year annualized return versus 10.7% for U.S. stocks. These are Stanford metrics. Printed p. 16/PDF p. 18
- He credits President John Hennessy, the university team, alumni, parents, and friends and presents cross-disciplinary work as an institutional advantage. Evidence: contemporaneous record / strong. Printed p. 16/PDF p. 18
- Researcher inference / moderate: milestones measure resources accumulated; organization and people determine whether those resources become mission outcomes.
Quotes
- No quotation captured.
Biography and decision evidence
- The message documents McMurtry’s continuing chair role and one-year campaign milestone.
- Distributed credit is visible in the public rhetoric. The record does not reveal whether it mirrors his investment committee or portfolio-board practice.
Philosophy signals
- Tags: teams / governance / milestones / institutional advantage / long horizon.
- Researcher inference / provisional for venture application: pair quantitative milestones with an account of the capability and people that produced them.
Contradictions, counterevidence, and access limits
- High realized returns are contextual inputs, not evidence that McMurtry personally made investment decisions.
- Cross-disciplinary rhetoric does not demonstrate that every such program succeeds.
- Annual-report editing and attribution mechanics are unknown.
Open questions
- Which Stanford Challenge initiatives were stopped or changed after weak evidence?
- What was the chair’s actual role relative to the president, investment office, and committees?