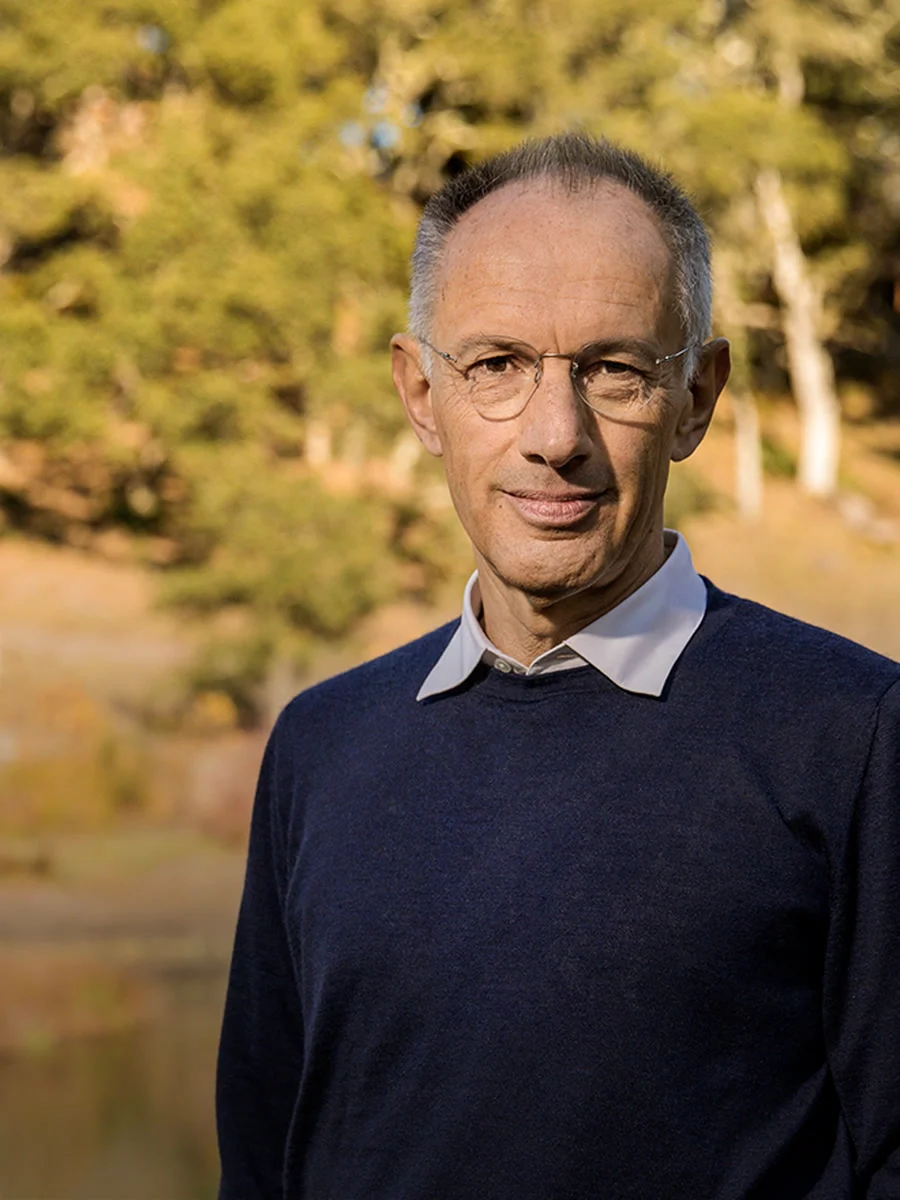
Michael Moritz
Long-run Sequoia steward with documented Yahoo, Google, PayPal, and governance roles; personal returns remain uncomputable.
An outsider learns to read institutions
Michael Jonathan Moritz was born in Cardiff in 1954 to parents who had escaped Nazi Germany as children. The official publisher biography places that family history, his later emigration, his reporting career, thirty-five years at Sequoia, and the Crankstart foundation in one verified chronology; it does not itself establish that exile caused a particular investment rule. Simon & Schuster author biography, “About the Author” [researcher inference · moderate] The supportable connection is narrower: in a 2016 Stanford conversation Moritz identified moving from Britain to the United States and joining Sequoia as the two professional decisions from which the rest of his career “rippled,” while warning how social expectations can suppress independent choice. Stanford eCorner transcript, PDF pp. 1 and 4 [investor-stated · strong]
Oxford, a Wharton MBA, and journalism at TIME preceded venture capital. His 1984 book, The Little Kingdom, came from close reporting on Apple while it was still a young company; its 2009 revision returned after Apple and Jobs had become canonical. Simon & Schuster author biography, book list At 13:43–16:13 of Money Maze, Moritz directly credits Oxford tutorials and journalism with training him to gather facts quickly, judge unfamiliar subjects under incomplete information, and form a defensible view. Money Maze episode/audio [investor-stated · strong on self-described training] The claim that this produced an investment advantage is his self-assessment; public evidence does not isolate its effect on returns.
From publisher to partnership
Moritz founded Technologic Partners, a technology-information business, before joining Sequoia in the 1980s. By his own 2016 account, Don Valentine had built a firm whose survival depended on renewing both its investment ideas and its partnership; Moritz later led Sequoia from 1995 to 2012. YC transcript, “Maintain a fresh team” Simon & Schuster author biography, “About the Author”
The transition is easy to romanticize as reporter-turned-oracle. The record instead shows apprenticeship inside an existing franchise. Google’s 1999 release described Sequoia as formed in 1972 and named Apple and Cisco among its prior financings, documenting institutional history and access before the Google decision. Google release, “About Sequoia Capital” When Moritz said in 2016 that “yesterday is irrelevant,” he was describing an organizational discipline: refresh products, refuse to treat past wins as entitlement, evaluate whether partners still possess competitive drive, promote people early, and expand only through capable local teams. YC transcript, “Yesterday is irrelevant,” “Maintain a fresh team,” and “Change with the market” [investor-stated · strong] That philosophy belongs to Moritz’s public record; claims that it generated exceptional returns remain untestable without fund cash flows and a complete denominator.
Yahoo and the first internet cycle
Moritz described Yahoo as Sequoia’s first internet software investment “of note.” He rejected the later myth of a grand design: at the decision date, Jerry Yang and David Filo were two Stanford PhD dropouts surrounded by AOL, Netscape, Microsoft, and other stronger incumbents; the near-term question was survival. Digital Riptide transcript, opening and Yahoo discussion [investor-stated · strong] His account also records how a Reuters corporate investment created a distribution relationship and pulled Yahoo opportunistically into news. This matters because the actual mechanism was not merely “spot a giant market.” It was backing an unusually focused product, using relationships to add distribution, and letting a narrow service widen after adoption. [researcher inference · moderate]
The Yahoo case exposes an attribution rule used throughout this package. A Moritz board role and his retrospective narration support sponsorship and governance credit; they do not prove sole sourcing, sole approval, or personal investment economics. Yahoo’s public filings are used for issuer-verified ownership and board evidence, while unknown team roles remain unknown. Yahoo 2002 proxy, security ownership and director sections
Google and the discipline of not inventing precision
Google’s June 1999 announcement records a joint $25 million financing by Sequoia and Kleiner Perkins and names Michael Moritz and John Doerr as new directors. It does not split the $25 million between the firms. Google announcement, June 7, 1999 Google’s 2004 registration statement later reported 23,893,800 shares for the Sequoia block associated with Moritz and separately disclosed the funds composing that block; Moritz disclaimed beneficial ownership except to his pecuniary interest. Google S-1, printed pp. 84–85, footnote 3
Moritz’s contemporaneous decision thesis is not fully public. In a 2013 oral-history interview he said the investment centered on superior search technology rather than media and stressed that the founders were vulnerable to vastly stronger companies. Digital Riptide transcript, Google discussion [retrospective witness · moderate] This supports a “technical advantage plus extreme uncertainty” reading, not a precise return multiple, check attribution, or lone-picker story. The later ownership block shows that the Sequoia vehicles held a material position; it cannot be converted into Moritz’s personal return without cash-flow, carry, dilution, distribution, and fund-allocation data.
PayPal, governance, and the difference between cash into a company and cash to a seller
PayPal’s filing says Moritz joined its board in August 1999 as a condition of Sequoia-affiliated entities completing their Series A investment. The same filing identifies the relevant Sequoia entities and their pre-offering ownership. PayPal S-1, director biography and related-party sections An earlier amendment records a $5 million purchase of 15 million Series A shares from Elon Musk; it was a secondary purchase, not $5 million of primary company financing. PayPal S-1/A, principal-stockholder notes and “Certain Transactions”
This case is unusually useful because it punishes careless narrative compression. Moritz had a documented board and fund-management connection, but Peter Thiel, Max Levchin, Elon Musk, Roelof Botha, employees, other investors, and successive boards shaped the outcome. Adapting to Endure recounts a later Sequoia story about difficult follow-on decisions, but it was presented by Roelof Botha in 2022 and is neither Moritz-authored nor contemporaneous PayPal evidence. Team Sequoia, Adapting to Endure, 2022 [retrospective witness · moderate]
Learning through the crash: LinkExchange, the misses, and Zappos
Sequoia’s oral history of Zappos gives the clearest public bridge between an ordinary operating problem, losses, and a later investment. Moritz and Alfred Lin recount Moritz spending extensive time at LinkExchange, briefly acting as interim chief executive, and helping recruit a permanent leader before Microsoft acquired the company. They then recount Sequoia repeatedly passing on Zappos after the Webvan, eToys, and PlanetRx wounds made inventory-heavy ecommerce unattractive. Sequoia Zappos oral history, LinkExchange and pass sequence
The 2004 decision changed only after Zappos had visible customer evidence: reliable availability and rapid delivery created an experience better than physical shoe retail. Alfred Lin attributes continued sponsorship to Moritz, while also attributing cohort analysis and a Kiva introduction to Roelof Botha and later team work to Lin himself. Sequoia Zappos oral history, 2004 decision and governance [retrospective witness · strong on speaker attribution; moderate on causal efficacy] The learning is not “ignore prior losses.” It is “let scars define the questions, then allow new evidence to answer them.” [researcher inference · moderate]
A multi-partner, multi-geography institution
Moritz’s strongest public operating claim is institutional: enduring venture performance requires a living partnership rather than monuments to yesterday’s deals. In 2016 he credited the China franchise to people on the ground and explicitly denied that its achievement belonged to him. YC transcript, “Change with the market” [investor-stated · strong] That credit discipline applies to YouTube, which Sequoia attributes to Roelof Botha, and Instacart, whose official roster names four Sequoia partners. Sequoia YouTube page Sequoia Instacart page Stripe remains attribution-unresolved: the direct witness establishes a Moritz–Collison conversation, not the partner roster or transaction roles. Money Maze, 10:18–12:05
The organizational thesis has tension. Organic renewal can preserve craft, but it can also concentrate informal power and obscure decision rights. Sequoia’s 2023 firm essay says its five business units decided in early 2023 to become fully independent partnerships; that official position shows that the geographic federation was not a permanent structure, but it does not establish Moritz’s personal role or agreement. Team Sequoia, “Crucible Moments,” separation paragraph [contemporaneous record · strong on firm decision; insufficient on personal role] The public corpus does not disclose fund-by-fund voting, partner compensation, carry attribution, reserves, or full IC minutes; any strong statement about Moritz’s personal economics or sole approval authority would exceed the record.
Klarna, later stewardship, and unresolved governance evidence
Klarna states that Sequoia’s original 2010 investment was led by Moritz. Its governance materials record that he joined the board in July 2010 and became chair in December 2020; current filings and leadership pages should be treated as of-dated rather than timeless. Klarna board announcement, January 2024 Klarna leadership page, accessed 2026-08-22
Klarna also supplies the strongest current adversarial evidence. Nayak v. Klarna Group plc, filed December 22, 2025, names Moritz among issuer/director defendants and alleges Securities Act violations tied to the IPO registration statement. As of the docket snapshot used here, it is pending; the record does not establish liability, a merits judgment, or class certification. Justia docket, case 1:25-cv-07033, entries through May 8, 2026 Complaint, Document 1, pp. 2–22 [contemporaneous record · strong on filing and allegations; insufficient public record on merits] It would be equally misleading to omit the case or to write as if allegations had been proved.
Current voice after Sequoia: founders, compounding, and AI
Money Maze supplies the most current long-form direct voice in the package. At 08:41–09:31 Moritz restates founder selection as unusual subject depth, clear command and communication, and sustained hunger to make the product real. This strengthens the observable founder screen, but it does not validate hunger as a return predictor; references, customer evidence, and bias controls still decide whether intensity is substance or theater. [investor-stated · strong on criteria; efficacy unproved] Money Maze episode/audio
The same appearance separates a later capital-allocation view from historical venture doctrine. At 24:42–26:26 he favors long-lived operations that repeatedly expand cash and profit and describes the capacity to remain inactive through temporary setbacks, while distinguishing long horizon from unlimited patience. At 27:09–27:34 he declines to discuss Heritage specifics. At 29:41–30:35 he predicts extreme AI value concentration in one or two dominant companies, potentially including incumbents, with widespread failure elsewhere. [investor-stated · strong on preference and forecast; insufficient on holdings, performance, or construction] These statements are useful because they are falsifiable and current; they do not disclose Heritage allocation, prove a “hold forever” rule, or identify the winners ex ante.
At 35:58–37:52 and 49:16–50:21 Moritz explains that Ausländer grew from family papers received after his mother's death, then underwent four rewrites, trusted-reader feedback, and deletion of at least 35,000 words. Money Maze episode/audio That supports an evidence/revision habit. Turning family history or writing discipline into deal causality would still exceed the record.
Falsifiable thesis of the edge
Proposed edge. Within early and growth-stage technology investing from the mid-1990s through the 2010s, Moritz appears to have combined unusually close founder observation, willingness to underwrite a narrow product before platform expansion, active governance, and partnership renewal. The mechanism should produce advantage only when the firm has credible access, can distinguish obsession from performance theater, secures enough ownership or governance influence to matter, and keeps updating after contrary evidence. [researcher inference · moderate]
Supporting observations.
- Yahoo and Google fit narrow initial products whose distribution or technical advantage widened over time; Moritz’s public accounts preserve the original uncertainty. Digital Riptide transcript, Yahoo and Google discussions
- LinkExchange and Zappos document hands-on recruiting, repeated passes, decision revision, and team contribution rather than a single flash of recognition. Sequoia Zappos oral history
- The YC transcript shows an explicit institutional process for discarding laurels, refreshing talent, and giving local teams authority. YC transcript, 2016
Disconfirming observations and denominator limit. Webvan, eToys, PlanetRx, and repeated Zappos passes show that domain experience did not generate stable prediction. Public successes are selected and heavily narrated; ordinary investments and write-offs are under-disclosed. The available company filings show ownership blocks and governance roles, not personal alpha or a complete fund return series. A record excluding Google cannot be recomputed from public data.
Predictions. If the edge is real, unseen decision records should show: product-specific evidence before broad market stories; founder-reference work before charisma claims; explicit updates after misses; meaningful partner credit; and governance actions tied to milestones rather than reputation. Falsifiers include complete IC records showing fame-driven selection, no systematic updating, materially weaker ordinary-deal results than comparable access cohorts, or economics dominated by one outlier after correcting for team and vehicle credit.
People and influence map
| Person or institution | Documented relationship | What may be credited | What remains unknown |
|---|---|---|---|
| Don Valentine / Sequoia | Founder of the partnership Moritz joined | Institutional platform and succession model YC transcript | Moritz’s early fund voting and carry |
| Jerry Yang and David Filo / Yahoo | Founders; Moritz-backed company | Board sponsorship and retrospective deal narration Digital Riptide | Full sourcing, approval, check, dilution, personal economics |
| Larry Page, Sergey Brin, John Doerr / Google | Founders and KPCB co-investor/director | Joint round and Moritz board seat Google announcement | Firm check split and sole-investor credit |
| Elon Musk, Peter Thiel, Max Levchin, Roelof Botha / PayPal | Founders/executives and later Sequoia partner | Moritz board and fund connection; Botha’s later team account PayPal S-1 | Individual causal share of the outcome |
| Tony Hsieh, Alfred Lin, Roelof Botha / LinkExchange and Zappos | Founder/operators and Sequoia partners | Moritz intervention and sponsorship; Lin/Botha operating work Zappos oral history | Partnership vote and complete follow-on allocation |
| Neil Shen and China team | Local franchise builders | Local team’s work, expressly credited by Moritz YC transcript | Detailed cross-entity economics and governance |
| Patrick Collison / Stripe | Founder; Moritz recalls their initial conversation | Remembered simplify-PayPal and global-ecommerce product framing at 10:18–12:05 Money Maze | Sourcing, approval, check, security, ownership, other partner roles, follow-ons, and economics |
| Sebastian Siemiatkowski / Klarna | Founder/CEO; Moritz chair | Original 2010 lead and board stewardship Klarna announcement | Merits of pending securities allegations |
| Harriet Heyman / Crankstart | Spouse and foundation co-founder | Co-creation of Crankstart in 2001 publisher biography | Private foundation decision process outside public filings |
Strongest skeptical reading
The skeptical account is that the favorable story confuses a privileged seat inside Sequoia with personal repeatable skill. An established brand can see stronger founders, buy meaningful stakes, recruit through a deep network, retain winners across rounds, and selectively publish its best stories. Google may dominate any economic ranking; PayPal, YouTube, Stripe, Instacart, and Zappos each contain material team credit; and no public denominator permits a clean comparison with peers. Moritz’s 2015 remarks about women partners and 2018 praise of Chinese work intensity drew contemporary criticism about institutional pipeline, output, welfare, and labor assumptions. Bloomberg original video Vanity Fair critique FT China column TechCrunch critique [investor-stated · strong on remarks; researcher inference · moderate on implications] A reported 2024 Klarna board dispute and the pending Nayak complaint further complicate any claim that demanding governance is uniformly beneficial; neither is an adjudicated misconduct finding. FT boardroom report Nayak docket
That case is credible. It is not proved merely by the absence of data, just as greatness is not proved by famous logos. The discriminating evidence would be fund cash flows by deal, complete opportunity and pass logs, contemporaneous IC records, partner-role ledgers, founder references including failed companies, and comparable access-adjusted outcomes. Until those exist, this package treats the edge as a testable hypothesis, not a measured personal-alpha conclusion.
Sourced chronology
| Date | Event | Evidence and interpretation |
|---|---|---|
| 1954 | Born in Cardiff | Official publisher biography. Simon & Schuster |
| 1970s–1980s | Oxford, Wharton, TIME reporting, technology publishing | Public publisher biography and his later direct account establish sequence; investment causality is inference. Simon & Schuster |
| 1984 | The Little Kingdom published | Early company reporting becomes part of the direct written corpus. MIT Press Bookstore record |
| 1980s | Joins Sequoia | Moritz later identifies the hire as one of two decisive professional choices. Stanford transcript, PDF p. 1 |
| 1995–2012 | Leads Sequoia | Official author biography. Simon & Schuster |
| 1995 | Yahoo era begins | Retrospective direct account preserves the competitive uncertainty. Digital Riptide |
| 1999 | Google round and board seat | Joint $25 million round; no firm split disclosed. Google announcement |
| 1999 | PayPal Series A and board seat | Board condition and fund entities appear in issuer filing; $5 million secondary purchase is not company financing. PayPal S-1/A |
| 2001 | Crankstart formed with Harriet Heyman | Official publisher biography. Simon & Schuster |
| 2004 | Sequoia partners with Zappos | Decision follows repeated passes and visible operating evidence. Zappos oral history |
| 2008 | Blood-cancer diagnosis | Moritz corrects the host's 2006 date to 2008 at 57:42–57:54. Money Maze |
| 2010 | Sequoia invests in Klarna; Moritz joins board | Klarna says the original investment was led by Moritz. Klarna announcement |
| 2016 | Publicly articulates partnership-renewal system | Direct YC transcript. YC |
| 2020 | Becomes Klarna chair | Current governance biography, accessed 2026-08-22. Klarna leadership |
| July 2023 | Ends Sequoia partnership tenure | Current governance biography identifies his later Heritage role. Klarna leadership |
| 2025–2026 | Named defendant in pending Nayak securities complaint | Filing and docket status only; no liability finding. Justia docket |
| September 2026 | Ausländer scheduled for publication | Publisher metadata; future date as of this package. Simon & Schuster |
Learning path
- Read writings.md to see what Moritz actually authored and where access stops.
- Use talks.md for his direct statements about uncertainty, founders, technology, and institutional renewal.
- Work the no-hindsight exercises in investments.md, including the Webvan/Zappos failure-recovery lab.
- Test the operating synthesis in investmentphilosophy.md against the evidence-backed rules in mental-models.md.
- Finish with review.md, which records what survived the central-claim, ordinary-claim, denominator, and adverse-evidence audits.
Evidence limits
No public source reviewed supplies Moritz’s personal audited returns, fund-level deal cash flows, complete pass log, IC minutes, or a comprehensive attribution ledger. The record supports board roles, fund ownership blocks, selected decision narratives, authored work, and public philosophy. It does not support a claim of personal alpha, an exact Google/PayPal contribution, or a complete portfolio hit rate. Current titles, ownership, and litigation status are frozen at 2026-08-22.
1. Snapshot and testable edge thesis
| Dimension | Evidence-bounded conclusion |
|---|---|
| Investor | Michael Moritz; journalist and technology publisher before a thirty-five-year Sequoia partnership. Official publisher biography |
| Era and scope | Internet, software, consumer, payments, ecommerce, and firm-building from the 1980s through July 2023; current governance facts are frozen at 2026-08-22. Klarna leadership biography |
| Proposed edge | Close founder/product observation, underwriting a narrow initial wedge under uncertainty, active governance, and continuous partnership renewal. [researcher inference · moderate] |
| Mechanism | Direct work exposes purpose and product evidence; a narrow wedge reduces speculative platform underwriting; board work and recruiting improve adaptation; renewal prevents old victories from becoming decision credentials. Stanford transcript, PDF pp. 1–4 YC transcript, “Yesterday is irrelevant” and “Maintain a fresh team” |
| Evidence for | Yahoo/Google direct accounts, LinkExchange/Zappos oral history, and public partnership doctrine recur across independent records. Digital Riptide, Yahoo/Google Zappos oral history YC transcript [researcher inference · moderate] |
| Evidence against | Webvan, eToys, PlanetRx, repeated Zappos passes, selected public storytelling, missing ordinary-deal denominator, and material team/vehicle credit. Sequoia Zappos oral history |
| Predictions | Unseen records should show product-specific evidence, founder references, milestone-based updating, explicit partner roles, and governance linked to company needs. |
| Falsifiers | Complete records showing reputation-led selection, no updating, ordinary-deal underperformance versus access-matched peers, or economics overwhelmingly explained by one outlier and institutional access. |
This is a falsifiable hypothesis about a process, not a claim of audited personal alpha. Public filings disclose company ownership and board positions, not Moritz’s cash flows, carry, or deal-level returns.
2. Core philosophy
Moritz’s own words begin with uncertainty. In 2013 he said that believing success is assured at the original investment is self-delusion; a properly examined decision rests on a “narrow knife edge.” Digital Riptide transcript, Yahoo discussion [investor-stated · strong] In 2016 he said important investment decisions require imagining what could happen if good things occur, while entering business with founders one barely knows. Stanford transcript, PDF p. 1 [investor-stated · strong]
The synthesis is four-part: start from a specific product and unusually committed people; preserve the downside case rather than converting possibility into probability; help the company recruit and adapt; and keep the investing institution younger than its trophy case. [researcher inference · moderate] None of those rules guarantees a winner. Their value is to make uncertainty explicit and the next update observable.
3. Sourcing
Moritz’s public cases show several sourcing channels rather than one proprietary funnel:
- Institutional co-investor network. Google emerged from Stanford research; its announcement names Stanford and other prior investors and records a shared Kleiner Perkins/Sequoia round. The release does not establish who sourced the investment. Google announcement, June 1999 [contemporaneous record · strong on network participants; insufficient on sourcing]
- Earned founder relationship. Tony Hsieh returned with Zappos after Moritz’s work at LinkExchange, and Alfred Lin says that relationship kept Sequoia in the conversation through repeated passes. Zappos oral history, LinkExchange-to-Zappos sequence [retrospective witness · strong]
- Partnership and alumni network. Alfred Lin and Roelof Botha moved from portfolio-company operations into Sequoia, creating knowledge and sourcing capacity that cannot be credited solely to Moritz. Zappos oral history, conclusion YC transcript, “Maintain a fresh team”
- Geographic local teams. Moritz credited Sequoia China’s results to the people on the ground, not to US partners. YC transcript, “Change with the market” [investor-stated · strong]
Repeatability depends on the Sequoia brand, alumni, geography, and prior founder references. An analyst without those assets cannot copy the surface behavior by sending more cold emails. The transferable act is to trace how trust was earned and who owns each relationship.
4. Picking
Founder and product evidence
Moritz described successful founders as having a real sense of the product or service, a direct connection to users, and an ability to exclude distraction through deep, genuine obsession. Stanford transcript, PDF pp. 1–2 In Money Maze at 08:41–09:31, he restates the screen as unusual depth that can educate the investor, clear command and communication, and sustained hunger to make the product real. Money Maze episode/audio [investor-stated · strong] Obsession and hunger are hypotheses, not personality adjectives: they should appear in product cadence, customer knowledge, and choices made when attention is scarce.
Google’s direct-voice account emphasizes superior search technology; Yahoo’s emphasizes a small service facing powerful incumbents; Zappos required evidence that availability and delivery created a superior customer experience. Digital Riptide transcript, Yahoo/Google discussion Zappos oral history, 2004 decision [documented behavior · moderate]
Diligence and red flags
The public record does not expose a standard Moritz diligence memo or scoring rubric. At 13:43–16:13 of Money Maze, Moritz directly credits Oxford tutorials and journalism with learning to gather facts and judge unfamiliar subjects under incomplete information; that is self-described process, not measured efficacy. Money Maze episode/audio It reveals recurring questions: Is the initial offering unmistakably better? Do users return or grow without purchased attention? Can the founder describe the need precisely? Are adverse unit economics structural or changing? Does contrary evidence update the team? [researcher inference · moderate]
Red flags include platform stories without a narrow wedge, reputation mistaken for current performance, and growth that cannot support sound economics. The Zappos passes show legitimate concerns about returns, inventory, cash flow, and geography; the later investment shows that a red flag is a question to update, not a permanent label. Zappos oral history
Decision rights
Board seats establish governance, not sole investment approval. Google’s announcement identifies both Moritz and John Doerr; PayPal’s filing identifies Moritz’s board condition and Sequoia entities; Zappos names Moritz, Lin, and Botha contributions. Google announcement PayPal S-1, board and ownership sections Zappos oral history Unknown sourcing, diligence, partnership-vote, and follow-on rights remain unknown.
5. Deal and portfolio mechanics
Public evidence supports meaningful ownership and board involvement in selected companies, but not a general target-ownership rule. Google’s 2004 S-1 reported a 23,893,800-share Sequoia block associated with Moritz and enumerated the funds; PayPal’s filing reported an 8.8% pre-offering Sequoia block in one later version. Those are issuer-defined beneficial-ownership snapshots, not entry ownership, distributed proceeds, or personal holdings. Google S-1, printed pp. 84–85, footnote 3 PayPal S-1, principal stockholders note 2
Price discipline, reserves, follow-on thresholds, security selection, and exit rules are insufficiently public at the portfolio level. The PayPal record is a warning: the August 1999 $5 million transaction bought shares from Elon Musk; calling it primary financing would misstate company cash and deal structure. PayPal S-1/A, “Certain Transactions”
Operational rule: record separately the issuer cash, secondary liquidity, shares/security, pre- and post-money ownership, dilution, board rights, reserves, distributions, and the person or entity receiving proceeds. If any term is absent, write unknown. At 17:03–17:49 of Money Maze, Moritz adds a relationship principle: a financing should leave founder and investor aligned for a long partnership rather than feeling extracted. Money Maze episode/audio [investor-stated · moderate] That is not a valuation formula; test it against actual terms, control rights, and later behavior.
6. Vehicle and incentive fit
Moritz invested through a multigenerational Sequoia fund complex, not a disclosed personal account. Company filings name distinct Sequoia partnerships, principals funds, international vehicles, and management entities. Google S-1, printed pp. 84–85, footnote 3 PayPal S-1, principal-stockholder note
| Vehicle dimension | Publicly supportable conclusion | Decision implication |
|---|---|---|
| Capital source/form | Closed-end partnership entities are named in issuer filings; LP identities and fund agreements are not public here. | Fund ownership cannot be collapsed into Moritz ownership. |
| Duration/liquidity | Venture holdings remained through private growth and public registration in examples; exact fund life and distributions are unavailable. | Patient ownership is plausible but not quantified. |
| Compensation/carry | Not publicly established. | No personal-return claim. |
| Governance/decision rights | Board seats documented; partnership voting and reserve authority unknown. | Distinguish company governance from fund approval. |
| Geography | Local China team credited by Moritz; later organizational separation requires period-specific analysis. | Local authority and economics cannot be assumed identical to US funds. |
| Reserves/follow-ons | Selected later accounts discuss follow-on behavior, but no complete policy is public. | Do not infer a universal pro-rata rule. |
| Succession/key person | Moritz publicly favors organic renewal and removal of disengaged partners. YC transcript | Institutional continuity is itself an investment capability, with cultural and governance costs. |
Money Maze adds a later vehicle-specific boundary. At 24:42–26:26 Moritz favors long-lived operations that repeatedly expand cash and profit and describes the capacity to remain inactive through temporary setbacks; he explicitly distinguishes a long horizon from unlimited patience. At 27:09–27:34 he declines to discuss Heritage specifics. Money Maze episode/audio [investor-stated · strong on preference; insufficient on application/performance] This cannot be backfilled as Sequoia's historical venture rule, a disclosed Heritage portfolio, or a sell discipline.
Compared with a 2026 LP-backed venture fund, the transferable dimensions are explicit role credit, ownership math, reserve gates, and succession. Sequoia’s brand access, historical carry pool, multi-fund data, and alumni network are not portable assumptions. [researcher inference · moderate]
7. Team attribution and work with founders
Moritz’s direct and witness evidence supports active board work: LinkExchange interim leadership and CEO recruitment; Zappos banking and board recruitment; POPSUGAR recruiting, introductions, mobile pressure, and between-meeting advice. Zappos oral history Stanford transcript, PDF pp. 2 and 4 [retrospective witness · strong on actions; moderate on effect]
His own credit language is equally important. At Stanford he interrupted personal praise with “It’s Sequoia,” and he told the audience that POPSUGAR belonged to Lisa and Brian Sugar. Stanford transcript, PDF pp. 2 and 4 [investor-stated · strong] The correct operating model is therefore not founder-friendly versus governance-first. It is founder ownership plus specific help, with intervention intensity matched to a documented problem.
8. Views on the craft
- Uncertainty: early decisions sit near a knife edge; retrospective inevitability is false. Digital Riptide [investor-stated · strong]
- Power law: at 29:41–30:35 of Money Maze, Moritz predicts that AI value will concentrate in one or two dominant companies, potentially including incumbents, while most others fail. Money Maze episode/audio [investor-stated · strong on qualitative forecast] The record still supplies no complete sizing, reserve, probability, or mathematical portfolio-construction doctrine.
- Access versus selection: institutional access matters; he nevertheless emphasizes decision quality over social-media profile. Stanford transcript, PDF p. 4 [investor-stated · strong]
- Governance: practical recruiting, financing credibility, technology vigilance, and leadership change can matter more than ceremonial board presence. Zappos oral history
- Firm building: partnership product, talent, and geographic reach must be renewed before decline becomes visible. YC transcript
- Humility: public profile cannot protect a bad decision; success should not become evidence for the next decision. Stanford transcript, PDF p. 4
9. Signature bets and decision process
The cases are reconstructed in investments.md:
- Yahoo freezes the 1995 competitive set before platform language.
- Google separates the joint round from later ownership and unknown economics.
- PayPal separates secondary liquidity from company financing.
- LinkExchange and Zappos tests whether prior failures sharpened rather than froze judgment.
- Webvan and the ecommerce failure set is the required failure/miss lab.
Each case asks for an invest/pass decision, kill criteria, terms/ownership, and next-check evidence before revealing the sourced outcome.
10. Mental models and maxims
- Underwrite the wedge, not the imagined platform
- Put every early decision on the knife edge
- Test obsession through product and customer evidence
- Turn scars into questions, not prohibitions
- Make governance concrete and preserve founder ownership
- Treat yesterday as irrelevant evidence
- Credit the actual partner, team, and vehicle
These are normalized decision rules. Some are Moritz-stated; others are researcher reconstructions from multiple cases, labeled as such in the field guide.
11. Evolution and contradictions
| Period | Public position or behavior | Tension |
|---|---|---|
| 1980s | Close company reporting and Apple history | Observation preceded capital allocation; causal investment benefit remains inference. |
| 1995–1999 | Yahoo/Google/PayPal under extreme uncertainty | Later fame makes early vulnerability easy to erase. |
| 2000–2004 | Ecommerce losses followed by repeated Zappos passes and eventual investment | Learning can improve diligence or harden a false veto; only the later update is visible. |
| 2000s–2010s | Geographic expansion and local-team credit | Institutional breadth creates access and complexity; later separation tests federation limits. |
| 2013–2016 | Publicly emphasizes narrow wedges, founder obsession, humility, and renewal | Direct philosophy is retrospective and selected; efficacy is not independently measured. |
| 2020s | Klarna chair and later Sequoia transition | Governance responsibility sits beside a board dispute record and pending securities allegations; no merits conclusion is available. |
| 2026 | Current founder screen, cash-compounder preference, and AI concentration forecast | Later long-duration allocation differs from seed venture; Heritage specifics and predictive results remain unavailable. |
The durable beliefs are uncertainty, people, product evidence, and renewal. The unresolved contradictions are demanding governance versus founder autonomy, local partnership authority versus global integration, and humility language versus public comments criticized as culturally or gender insensitive.
12. Failures and limits
Webvan, eToys, and PlanetRx matter because Moritz himself connected those experiences to skepticism about Zappos. The public record supports the prior wounds and decision delay; it does not expose complete original theses, ownership, capital escalation, stop decisions, or losses. Zappos oral history [retrospective witness · moderate]
The largest analytic limits are:
- no complete opportunity, investment, write-off, or fund-return denominator;
- no audited personal deal attribution or economics;
- selected firm oral histories with retrospective and marketing incentives;
- incomplete lawful access to the FT corpus and books;
- current governance and litigation facts that may change after 2026-08-22.
These limits prevent a personal hit rate, exact 80/20 calculation, or causal claim that board intervention generated returns.
13. Historical operating environment
Yahoo was financed when portals, proprietary networks, browsers, broadcasters, and Microsoft looked formidable. Google’s 1999 announcement emphasized word-of-mouth traffic and university research rather than a mature search-advertising model. Digital Riptide, Yahoo/Google Google announcement, company description
The 2000 crash changed ecommerce underwriting. Inventory, returns, cash use, and financing risk were visible in Zappos and were not irrational concerns after Webvan, eToys, and PlanetRx. Zappos oral history By 2013 Moritz argued that media incumbents lacked software engineers and needed to shrink legacy operations, treating digital distribution as an opportunity rather than defending print. Digital Riptide transcript, legacy-media discussion
No contemporaneous numerical venture base-rate dataset was found that is both decision-date appropriate and specific to these cases. Qualitative competitive context is therefore used; later outcomes are revealed only after each case exercise.
14. Modern VC translation (as of 2026-08-22)
The table is a set of [researcher inference · hypothetical · moderate] transfer tests. Its current-market premises must be revalidated for the target deal; they are not represented as empirical findings about the whole 2026 market.
| Historical lesson | What transfers | What changed or fails | Observable applicability signal | Likely misuse |
|---|---|---|---|---|
| Underwrite a narrow wedge | Demand an intense user need and specific superiority. | In a hypothetical low-cost AI-prototyping market, demos and early usage may be less defensible. | Retention and workflow depth persist after novelty. | Calling any small TAM a wedge. |
| Decisions sit on a knife edge | Write the failure case and milestone updates before investing. [researcher inference · strong] | Large multi-stage funds can blur seed learning with later price support. | IC memo contains symmetric evidence and dated kill criteria. | Using uncertainty to avoid taking a position. |
| Obsession matters | Test product cadence, customer language, and trade-offs. | A founder can stage visible intensity without sustained learning. | References describe consistent behavior under bad news. | Rewarding burnout, aggression, or demographic familiarity. |
| Scars become questions | Convert a failure into explicit diligence, then accept new evidence. [researcher inference · strong] | Market structure and unit economics can change faster. | A prior veto has a measurable reversal condition. | Reflexive “this time is different.” |
| Governance is work | Tie board involvement to recruiting, financing, product, and leadership needs. | A hypothetical regulated product adds fiduciary and compliance complexity. | Help has an owner, deadline, and founder-agreed objective. | Intervention as status or control. |
| Yesterday is irrelevant | Re-underwrite partners, theses, and portfolio reserves prospectively. [researcher inference · strong] | Brand and platform services create real compounding assets. | Past logos are excluded from current decision evidence. | Destroying institutional memory in the name of renewal. |
| Credit roles explicitly | Maintain partner/company/vehicle attribution ledgers. [researcher inference · strong] | Team deals and scout ecosystems make credit more diffuse. | Every IC memo names source, sponsor, dissent, board owner, and narrator. | Treating attribution as internal politics rather than accuracy. |
| Treat AI concentration as a forecast | Start from Moritz's dated one-or-two-winner view, then specify probabilities and loss budget. [investor-stated premise; researcher translation] | Incumbents, private models, open source, and application layers can split value differently. | IC memo fixes winner definition, horizon, concentration cap, and disconfirming milestones. | Using “power law” to excuse any price or missing portfolio math. |
Money Maze supplies a Moritz-stated 2026 concentration premise, but the following AI infrastructure seed deal remains a hypothetical rather than a Moritz case: require a narrow workflow with repeat use, identify which cost/performance improvement is proprietary, set a next-check retention and gross-margin threshold, and do not elevate founder fluency into proof. [researcher inference · hypothetical · moderate]
15. Comparison with completed peers
The defensible completed set is Doug Leone (the same Sequoia institution and a later leadership era), Andy Rachleff (a same-era partnership and explicit decision doctrine), and Scott Sandell (a long-duration multi-stage practitioner with similarly difficult personal attribution). This compares public systems, not compatible return series. The underlying direct-voice controls are Leone's Acquired institutional interview, Rachleff's Pattern Breakers transcript, and Sandell's CHM/NVCA oral history; each remains retrospective and is checked against the completed peer's filings and adverse record. [researcher inference · moderate]
| Dimension | Michael Moritz | Doug Leone | Andy Rachleff | Scott Sandell |
|---|---|---|---|---|
| Sourcing | Founder relationships, Sequoia alumni, co-investors, local teams; funnel incomplete | Partner/referral network, direct hunting, regional franchises | Stanford/MPAE/Benchmark networks plus inflection mapping | NEA/domain/founder routes with prominent partner credit |
| Picking | Narrow product, purpose, uncertainty, update evidence | Founder behavior plus customer/GTM reality | Market change, non-consensus insight, and pull before growth | Mechanism, customer evidence, people, and magnitude |
| Ownership/portfolio | Selected filing-visible fund blocks; full weights/cash flows absent | Scaled multi-stage vehicles and large stakes; cash flows incomplete | Filing-visible stakes and equal-partnership attribution problems | Case-specific ownership and two-vehicle scale; weights incomplete |
| Governance | Recruiting, interim leadership, financing credibility, vigilance | Recruiting, founder/CEO roles, succession, local authority | Strategic questions, written context, staged learning | Board-intensive bad-news, principles, and recruiting work |
| Vehicle/incentives | Multigenerational Sequoia fund complex; carry/IC rights private | Same franchise’s later growth/global architecture and succession | Small equal-economics Benchmark plus MPAE/personal entities | Long-duration multi-stage NEA and later vehicle structure |
| Failure controls | Webvan/eToys/PlanetRx, Zappos passes, Green Dot/Klarna disputes | Color, Facebook pass, cycles, global/succession controls | PointCast/Ipsilon, anti-portfolio, product/entity controls | Dot-com failures/misses, attention conflicts, regulated-entity risk |
| Attribution risk | Moritz narration can obscure founders, partners, local teams, and funds | Especially high across Sequoia partners/regional vehicles | Equal economics blur individual contribution | NEA scale and shared roles blur causality |
Comparison result. [researcher inference · moderate] Moritz and Leone share institutional advantages and succession complications; Rachleff provides the clearest doctrine control; Sandell provides the closest long-tenure attribution control. Across all four, public evidence proves access, selected boards, and institution building more readily than repeated personal alpha. Leone primary-source comparison controls Rachleff comparison controls Sandell comparison controls
16. The strongest case against greatness
The steelman is that Moritz’s record is Sequoia’s record viewed through a famous narrator. The firm’s historical brand, Stanford proximity, prior wins, fund duration, founder references, and partner bench created access that would make many competent investors look exceptional. Google may dominate economic contribution; public stories omit the ordinary denominator; and ownership blocks belong to funds. PayPal, Zappos, YouTube, Stripe, Instacart, and geographic expansion all require team credit. A demanding culture may generate renewal while also producing insensitive public claims or harmful governance conflict. Pending Nayak allegations add current scrutiny but do not establish wrongdoing. Nayak docket
The favorable and skeptical hypotheses diverge on evidence. Contemporaneous IC records showing product-specific reasoning, systematic updates, and contribution across ordinary deals would support skill. Access-adjusted results dominated by a single outlier, post-hoc narratives, and diffuse team work would support the skeptic. The public record cannot yet decide.
17. Analyst study guide, glossary, and go deeper
Recommended path
- _profile.md: formation, eras, edge hypothesis, people map, and chronology.
- writings.md: authored evidence and access boundary.
- talks.md: direct voice and retrospective-bias controls.
- investments.md: denominator, three Pareto views, and no-hindsight labs.
- mental-models.md: apply and challenge each rule.
- review.md: verify what survived adversarial acceptance.
Glossary
| Term | Meaning here |
|---|---|
| Wedge | The narrow initial product/use case evidenced before a platform claim. |
| Knife edge | A decision with meaningful support and meaningful failure reasons, not false certainty. |
| Ownership block | Issuer-reported fund/entity shares; not personal ownership or return. |
| Secondary purchase | Cash paid to an existing holder rather than to the company. |
| Partner attribution | Separate source, sponsor, diligence, approval, board, follow-on, exit, and narration roles. |
| Vehicle attribution | Identify the fund/entity owning the security and its period; never substitute the individual’s name. |
| Update gate | Evidence specified in advance that changes invest/pass/follow-on judgment. |
| Retrospective witness | A later participant account, useful but not contemporaneous proof. |
Reusable checklists
Sourcing
- Who introduced the company, and why did the founder take the meeting?
- Which access advantage belongs to the firm rather than the individual?
- What comparable companies never reached this investor?
Diligence and IC
- What is the narrow wedge, user evidence, and specific superiority?
- What was known, unknown, believed, and disputed on the decision date?
- What would kill the deal? What evidence reverses a veto?
- Who sources, sponsors, dissents, approves, and owns the next update?
Terms and portfolio
- Separate primary from secondary cash and company from seller.
- Record security, check, ownership, dilution, reserves, and vehicle—or unknown.
- Test the portfolio story with and without the dominant outlier.
Governance
- Name the founder-owned objective, board action, accountable person, and deadline.
- Record hiring, financing, product, compliance, and leadership interventions separately.
- Predefine when help becomes control and when the investor should step back.
Best sources, ranked
- Digital Riptide transcript — direct discussion of Yahoo, Google, platforms, uncertainty, and media.
- YC “Maintaining Success” transcript — clearest public partnership operating system.
- Stanford eCorner transcript — founder criteria, board work, biography, humility, and direct founder corroboration.
- Sequoia Zappos oral history — failure-to-update chain with explicit Moritz/Lin/Botha roles.
- Google and PayPal filings — ownership, entity, board, and related-party controls.
- Official publisher biography — authorship, tenure, Crankstart, and dated biography.
- Nayak live docket — current adverse-evidence route; allegations and disposition must remain separate.
Pareto 80/20 — what drove the record
The public record does not support a literal 80/20 calculation. It lacks fund cash flows, entry checks for most companies, dilution, distributions, write-offs, carry, and a complete opportunity denominator. The tables therefore use Pareto as a prioritization lens and keep three questions separate: what probably mattered economically to Sequoia vehicles, what mattered historically, and what teaches the most about decisions. Every ranking is directional and belongs to a fund/team unless a personal role is documented.
Economic-contribution view
| Rank | Company or tier | Basis/measure | Attribution | Support | Mechanism and denominator caveat |
|---|---|---|---|---|---|
| 1 | Google’s April 29, 2004 S-1 principal-stockholder table reported 23,893,800 Sequoia shares as of March 31; footnote 3 itemized five vehicles, and later cash flows are unavailable. Google S-1, printed pp. 84–85 | Sequoia VIII and related entities; Moritz board since May 1999; joint financing with KPCB | [contemporaneous record · strong on ownership; provisional on contribution] | Likely dominant observable outlier, but no entry-cost, dilution, distribution, or fund-return series permits a multiple. | |
| 2 | Yahoo / PayPal | Both became public/acquired and have issuer ownership/board records; only selected ownership snapshots survive here. Yahoo 2002 proxy PayPal S-1/A | Sequoia entities and teams; Moritz board roles | [contemporaneous record · moderate] | Directional tier; no relative contribution or personal return is computable. |
| 3 | Zappos / Kayak / LinkedIn / Instacart / Klarna | Public acquisition/listing or current market routes establish outcomes, not fund cash return. Zappos oral history Kayak 10-K LinkedIn proxy Instacart S-1 Klarna 20-F | Multi-partner Sequoia/company teams; company-specific roles below | [contemporaneous record · provisional on relative contribution] | Famous outcomes cannot be ranked economically without cash flows. |
| — | Record excluding Google | Not computable | — | [insufficient public record] | No public fund series supports a counterfactual return or reordered ranking. |
Historical-importance view
| Rank | Company | Why it matters historically | Attribution | Support |
|---|---|---|---|---|
| 1 | Yahoo | Sequoia’s first internet software investment “of note” in Moritz’s account and an early web directory/distribution business. Digital Riptide | Moritz/Sequoia board sponsorship; founders Jerry Yang and David Filo | [retrospective witness · strong on statement, moderate on full credit] |
| 2 | Search-technology inflection, joint KPCB/Sequoia round, and a major disclosed Sequoia ownership block. Google announcement | Page, Brin, Shriram, Moritz, Doerr, Stanford, and firm vehicles | [contemporaneous record · strong] | |
| 3 | PayPal | Payments, founder network, board governance, and a transaction whose primary/secondary distinction corrects common histories. PayPal S-1/A | Founders/executives, Moritz board, Sequoia entities, later Botha role | [contemporaneous record · strong] |
| 4 | LinkExchange → Zappos | Connects operating intervention, dot-com losses, repeated passes, decision revision, and Sequoia partner formation. Zappos oral history | Moritz, Hsieh, Lin, Botha, founders, banks, and team | [retrospective witness · strong on roles] |
| 5 | Klarna | Long-duration European governance from 2010 through a public 2026 record and active legal scrutiny. Klarna 2024 announcement | Moritz as original Sequoia lead/chair; Klarna board and shareholders | [contemporaneous record · strong on roles, unresolved on merits/outcome] |
Decision-learning view
| Rank | Case | Learning value | Attribution | Support |
|---|---|---|---|---|
| 1 | Webvan/eToys/PlanetRx → Zappos | Converts losses into explicit inventory, returns, cash-flow, and geography questions, then shows evidence-based reversal after repeated passes. Zappos oral history | Sequoia team; Moritz sponsor; Lin/Botha operating contributions | [retrospective witness · strong] |
| 2 | Teaches joint-credit, technology-specific thesis, incumbent risk, and refusal to invent a check split or return. | Founders, KPCB, Sequoia vehicles, Moritz/Doerr boards | [contemporaneous record · strong] | |
| 3 | PayPal | Teaches transaction anatomy: secondary share purchase, board condition, vehicle block, and multi-person governance. | Sequoia entities/Moritz plus company actors | [contemporaneous record · strong] |
| 4 | Green Dot proxy fight | Gives interested arguments on both sides of long board tenure, performance, and governance value. Dissident deck Issuer response | Harvest, Green Dot, Moritz, board/shareholders | [contemporaneous record · strong on claims, insufficient on causal verdict] |
| 5 | Klarna | Tests current chair responsibility, Crankstart’s indirectly held ordinary shares versus Moritz’s directly held RSUs, governance dispute, and allegations-versus-disposition language. | Moritz, board, Crankstart, Sequoia-related holders, plaintiffs/defendants | [contemporaneous record · strong on records, unresolved on merits] |
Evidence boundary and searched denominator
Scope
This denominator covers 21 named company routes publicly connected to Moritz or commonly misattributed to him, from 1993 through 2026, across Sequoia venture/growth entities and later associated capital. It uses issuer filings, official company/firm histories, direct transcripts, and adverse records. It includes a company when a source documents a Moritz board, sponsorship, fund-control, governance, or commonly claimed deal connection. Follow-ons do not create a second company. A board role is not sourcing; an entity block is not personal ownership; an exit value is not a fund return.
The 21 candidates are Yahoo, Google, PayPal, LinkExchange, Zappos, Webvan, eToys, PlanetRx, POPSUGAR, Saba, Green Dot, Kayak, LinkedIn, Flextronics, Stripe, Instacart, Klarna, Getir, Netezza, Ikanos, and YouTube. YouTube is searched but excluded from Moritz’s included set because official Sequoia attribution belongs to Roelof Botha.
Mechanical reconciliation
| State | Count | Definition and result |
|---|---|---|
| Publicly claimed/known candidates | 21 | Named routes above, including the misattribution control. |
| Searched | 21 | Each checked in the registry through a filing, official history/page, direct transcript, or attribution route. |
| Included after attribution rules | 20 | YouTube excluded from Moritz scope; multi-partner cases retained with roles bounded. |
| Researched | 20 | At least one claim-supporting public route reviewed for each included company. |
| Sufficiently reconstructed | 7 | Yahoo, Google, PayPal, LinkExchange, Zappos, Green Dot, and Klarna have enough decision/governance evidence for extended analysis. |
| Unresolved for full reconstruction | 13 | Included but missing original thesis, role matrix, economics, and/or failure/exit decision. |
| Excluded | 1 | YouTube: Sequoia result, officially attributed to Botha rather than Moritz. |
Scoped route coverage: 20 researched / 20 included = 100% of this named public route set. Deep-reconstruction coverage: 7 sufficiently reconstructed / 20 included = 35.0%. Neither is a career-portfolio coverage fraction. Career coverage fraction: not computable, because the number of all investments, passes, write-offs, and vehicles is unknown. The sample is selected toward public companies, board roles, and stories Sequoia chose to publish.
Five attribution axes
For every case, attribution is split into: (1) opportunity source, (2) investment sponsor/diligence/approval, (3) security-owning entity, (4) board and operating work, and (5) later narrator. “Unknown” is an evidentiary result.
Historical market, regulatory, and base-rate context
| Decision period | What a diligent contemporary could know | Later fact kept separate |
|---|---|---|
| Yahoo, 1995 | AOL, Netscape, broadcasters, Microsoft, and other portals had resources; the founders had a narrow directory and no assured news business. Digital Riptide | Yahoo’s later platform role and decline. |
| Google, 1999 | Search quality and word-of-mouth traffic were visible; the press release reported 50% monthly traffic growth and a three-year Stanford research lineage. Google announcement | Search advertising economics and 2004 ownership outcome. |
| PayPal, 1999–2002 | Company/founder transitions, securities rounds, merger, and payments risks were live; filing terms identify actual parties and shares. PayPal S-1 | eBay acquisition and “mafia” narrative. |
| Ecommerce, 2000–2004 | Inventory, product returns, cash flow, and financing availability were central after Webvan/eToys/PlanetRx failures. Zappos oral history | Zappos’s $1.2 billion Amazon acquisition. |
| Klarna, 2010–2026 | Consumer credit, regulation, funding, governance, IPO disclosure, and voting control matter; current facts come from the 20-F and court docket. Klarna 20-F | Complaint allegations remain unproved; post-IPO price movement is not a liability finding. |
No decision-date numerical venture base-rate series specific to these cohorts was found. Qualitative context is used rather than manufacturing a success rate.
Vehicle economics and incentives
Entity and incentive matrix
| Dimension | Evidence | What it supports | What it does not support |
|---|---|---|---|
| Legal capital form | Google, PayPal, Netezza, Ikanos, Kayak, and Green Dot filings name multiple Sequoia funds and management entities. Google S-1 PayPal S-1/A Netezza 13G | Fund/entity ownership and shared control | Personal shares, personal return, one unified vehicle |
| Duration/liquidity | Private positions remained to public filings or acquisitions in selected cases | Ability to hold through company-building | Exact fund life, distributions, continuation mechanics |
| Fundraising pressure | No public fund agreements in this package | Insufficient public record | Any causal statement about investment timing |
| Compensation/carry | Not disclosed | Insufficient public record | Moritz personal economics |
| Governance | Board seats at Google, Yahoo, PayPal, Green Dot, LinkedIn, Flextronics, Klarna and others | Formal company role at a date | Sole sourcing, approval, or performance causality |
| Decision rights | Managing-member relationships in ownership notes | Shared legal control over listed holdings | Internal IC vote or unilateral authority |
| Geographic authority | Moritz credits China’s local team; a 2009 joint-filer exhibit maps entities. Sequoia joint-filer exhibit | Distinct entities and local credit | Identical economics or authority across regions |
| Reserves/follow-ons | Selected firm retrospectives describe support; complete policy absent | Case-specific follow-on context | Universal reserve ratio |
| Regulation | SEC ownership/reporting and DOJ policy transcript constrain public records | Disclosure and competition context | A regulator’s endorsement of Moritz’s views |
| Succession/key person | Moritz publicly describes organic renewal; partner role ended July 2023. YC Klarna leadership | Institutional continuity doctrine and dated transition | Seamless or conflict-free succession |
Vehicle inference. Long-duration partnership capital plus an established brand plausibly enabled meaningful ownership, follow-ons, recruiting, and patience. [researcher inference · moderate] The same design creates attribution opacity: partners, funds, management entities, and narrators differ. Compared with a 2026 LP-backed fund, only dimension-matched comparisons—fund term, ownership target, reserve ratio, board rights, geography, and succession—are legitimate.
People, capital, and influence map
| Case | Source | Sponsor/diligence/approval | Vehicle/capital | Board/operating work | Exit/follow-on/narration |
|---|---|---|---|---|---|
| Yahoo | Unknown publicly; Stanford network context | Moritz sponsorship; full IC unknown | Sequoia entity/check unknown | Moritz board chronology in issuer proxy | Moritz narrates in Riptide; exit influence unknown |
| Founders/prior network; exact introduction not fixed here | Joint KPCB/Sequoia round; Moritz and Doerr boards; IC unknown | Sequoia VIII family; joint $25m aggregate only | Moritz board since May 1999 | Distribution/return unknown; Moritz narrates technical rationale | |
| PayPal | Company/Elon Musk transaction route | Sequoia commitment; full IC unknown | Sequoia IX family; $5m secondary shares from Musk | Moritz board from Aug. 1999 | Botha later narrates team follow-on story; exit influence unknown |
| LinkExchange | Tony Hsieh/Sanjay Madan company | Sequoia/Moritz; IC unknown | Unknown | Moritz interim CEO and recruiter; founder/employee mentoring | Microsoft acquisition; Moritz/Lin later narrate |
| Zappos | Hsieh relationship from LinkExchange | Moritz repeatedly pushes after passes; vote unknown | Sequoia vehicle/check/ownership unknown | Moritz board recruitment/bank support; Lin operations; Botha cohorts/Kiva | Amazon acquisition; team narrative |
| POPSUGAR | Founders Brian and Lisa Sugar | Sequoia decision, individual roles incomplete | Unknown | Moritz recruiting, introductions, mobile pressure | Outcome/economics unknown; Lisa and Moritz narrate |
| Green Dot | Unknown | Sequoia/fund role and board; original IC unknown | Sequoia entities | Moritz board from 2003; contributions disputed in 2016 proxy fight | Issuer and dissident offer opposing narrations |
| Stripe | Patrick Collison conversation; exact source unknown | Moritz recalls first meeting and two product propositions; sponsor/IC vote unknown | Check, security, entity, ownership, and economics unknown | Board, recruiting, and other partner roles unknown | Retrospective narration only; no sole-credit or return inference |
| Instacart | Company/founder route | Firm later calls Moritz lead; official page lists Lin, Gupta, Flynn too | Sequoia entities; ownership in issuer filing | CEO recruitment story; role shared | IPO; individual economics unknown |
| Klarna | Company route | Issuer says 2010 Sequoia investment led by Moritz | Sequoia-related/associated entities; current direct/indirect holdings separate | Director from 2010; chair from 2020 | Current governance, purchases, litigation; outcome unresolved |
| YouTube | Official Sequoia route | Roelof Botha | Sequoia | Botha | Excluded from Moritz deal set |
Comprehensive scoped deal ledger
| Company | Chronology/stage | Entity and terms | Documented thesis/role | Outcome/status | Evidence and uncertainty |
|---|---|---|---|---|---|
| Flextronics | Board 1993–2005 | Unknown investment terms | Long board tenure | Public company; Moritz retired from board | Issuer-filed release; board ≠ source |
| Yahoo | 1995 early internet | Check/security/ownership at entry unknown | Small directory facing incumbents; Moritz board | Public company | Digital Riptide, 2002 proxy |
| LinkExchange | 1990s | Unknown | Company needed leadership; Moritz intervened/recruited | Microsoft acquisition reported $265m | Zappos oral history; fund economics unknown |
| 1999 venture round | Joint $25m; Sequoia split unknown; 2004 disclosed block | Superior search technology; Moritz board | 2004 IPO/public | Announcement, S-1 | |
| PayPal | 1999 Series A | $5m bought 15m shares from Musk; later block disclosed | Board appointment condition | IPO/eBay acquisition | S-1/A; primary cash and return not inferred |
| Webvan | Pre-2001 ecommerce | Unknown | Later named as scar | Failed | Zappos oral history; thesis/capital/stop gaps |
| eToys | Dot-com ecommerce | Unknown | Later named as scar | Failed/weak outcome in retrospective | Same; exact loss not claimed |
| PlanetRx | Dot-com ecommerce | Unknown | Later named as scar | Failed/weak outcome in retrospective | Same; exact loss not claimed |
| Saba | Board record through 2003 | Unknown | Board intervention/role list | Public-company leadership reset | Issuer-filed release; board ≠ source |
| Green Dot | Board since 2003 | Sequoia entity block; terms incomplete | Governance role contested in 2016 | Public; proxy contest | S-1/A, Moritz letter |
| Zappos | Passed several times; partnered 2004 | Check/security/ownership unknown | User evidence reverses ecommerce veto | Amazon acquired for reported $1.2bn | Zappos oral history; issuer/fund cash flow absent |
| POPSUGAR | Series A / 2000s | Unknown | Product purpose, audience, media experience | Private/changed ownership record not reconstructed | Stanford transcript |
| Netezza | By 2008 ownership filing | Sequoia X entities | Original thesis/source unknown | Public-company filing route | Schedule 13G |
| Ikanos | By 2005 ownership filing | Sequoia entities | Original thesis/source unknown | Public-company filing route | Form 3 |
| Kayak | By 2012 filing | Fund entities, terms incomplete | Board/role evidence; source unknown | Public then acquired | 2012 10-K, Form 4 |
| Klarna | Original Sequoia investment 2010 | Check/entry ownership unknown; later direct/indirect positions separate | Issuer says led by Moritz; chair | Public; active complaint | 2024 announcement, 20-F |
| Board since 2011 | Unknown original terms | Board role; sourcing not proved | Acquired by Microsoft | 2016 proxy | |
| Stripe | Initial conversation recalled in 2026 | Check/security/ownership and Sequoia entity unknown | Patrick Collison proposed simpler payments after PayPal and globally enabling ecommerce; all decision roles unresolved | Private; no economic claim | Money Maze, 10:18–12:05; direct retrospective thesis, not a transaction record |
| Instacart | Multi-round; 2023 S-1 | Issuer ownership record; exact personal attribution barred | Firm lists Moritz, Lin, Gupta, Flynn | 2023 IPO/public | S-1, Sequoia page |
| Getir | Later delivery investment | Family-office/Sequoia sequence unresolved | Moritz-linked on firm page/reporting | Outcome pressured; reconstruction incomplete | Sequoia page, transition reporting |
| YouTube | 2000s | Sequoia | Official partner attribution is Roelof Botha | Acquired by Google | Excluded from Moritz set; mention in firm narrative is not personal credit |
Ex-ante case 1 — Yahoo: a directory before a platform
Freeze before outcome
Known: In Moritz’s account, Yang and Filo were Stanford PhD dropouts organizing web destinations; AOL, Netscape, Microsoft, broadcasters, and other networks were powerful. Yahoo did not begin with a purposeful news strategy. Digital Riptide, Yahoo section [retrospective witness · moderate]
Unknown: Durable monetization, platform scope, competition response, original check/security/ownership, and whether user behavior could survive. Believed: a useful narrow directory could build audience; a Reuters relationship could add distribution and content. Disputed: later platform language was not decision-date evidence.
Roles: Moritz/Sequoia board sponsorship is supported; source, IC vote, exact check, and sole approval are unknown.
No-hindsight IC worksheet
- Invest or pass? Choose using only directory usefulness, founder evidence, audience behavior, and incumbent threat.
- Kill criteria: declining repeat use; inability to organize expanding web supply; incumbent bundling destroys discovery; founders cannot recruit.
- Ownership/terms: seek enough ownership and governance to justify recruiting/distribution work, but write the missing pricing evidence.
- Next-check milestones: direct repeat use, search/navigation quality, a distribution partnership, and a credible monetization experiment.
Actual decision and outcome
Sequoia invested and Moritz later described Yahoo as its first internet software investment of note. Yahoo became a major public internet company; the long-run outcome also demonstrates that early success does not ensure durable adaptation. Digital Riptide Yahoo 2002 proxy
Ex-ante case 2 — Google: superior search without a disclosed firm split
Freeze before outcome
Known in June 1999: Google had grown from three years of Stanford research; its release reported traffic growing 50% per month by word of mouth. Sequoia and Kleiner Perkins jointly supplied $25 million, and Moritz and Doerr joined the board. Google announcement
Unknown: the firm-by-firm check split, a durable business model, competitive response, later ownership/dilution, and fund return. Believed retrospectively: search technology was superior. Digital Riptide, Google section [retrospective witness · moderate]
Risks: incumbent distribution, browser/platform power, unclear monetization, infrastructure costs, and founder scaling. Roles: Page/Brin built the technology; Shriram and Stanford were in the prior network; KPCB/Sequoia co-invested; Doerr/Moritz joined the board; IC details unknown.
No-hindsight IC worksheet
- Invest or pass? Decide whether observable search quality and organic traffic justify business-model uncertainty.
- Kill criteria: quality advantage disappears in blind tests; repeat use stalls; distribution requires uneconomic payments; founders reject key hires.
- Ownership/terms: model the joint round without inventing a split; require governance and future-financing rights appropriate to the capital need.
- Next-check milestones: query retention, index/latency improvement, user acquisition without paid marketing, and one monetization test that preserves relevance.
Actual decision and outcome
The joint financing closed; Moritz served on the board from May 1999. The April 29, 2004 S-1 principal-stockholder table reported 23,893,800 Sequoia shares as of March 31, itemized across five vehicles in footnote 3. Google S-1, Management and printed pp. 84–85 That dated ownership snapshot does not yield an entry multiple or Moritz return.
Ex-ante case 3 — PayPal: a secondary purchase and a board condition
Freeze before outcome
Known: Sequoia-affiliated entities’ Series A obligation was conditioned on Moritz joining the board in August 1999. A filing records a $5 million purchase of 15 million Series A shares from Elon Musk. PayPal S-1/A, related transactions
Unknown: how much cash entered the company in that transaction, internal approval, original ownership after all conversions, later dilution, board contribution, and realized economics. Critical distinction: this $5 million is seller liquidity, not primary financing.
Risks: founder/leadership conflict, fraud and regulatory exposure, payments adoption, capital requirements, and competition. Roles: Musk sold the shares; Sequoia entities bought; Moritz joined the board; other founders/executives and later Botha contributions remain distinct.
No-hindsight IC worksheet
- Invest or pass? What user growth, fraud loss, funding need, and founder-governance evidence justify a secondary purchase?
- Kill criteria: loss rates outrun margin; regulatory constraint blocks use; leadership conflict prevents execution; secondary price disconnects from company financing needs.
- Ownership/terms: separate seller proceeds, security rights, converted ownership, board condition, and future primary reserve.
- Next-check milestones: verified transaction volume, loss/fraud trend, leadership responsibilities, compliance capacity, and primary-capital runway.
Actual decision and outcome
The entities bought the shares and Moritz joined the board. PayPal later went public and was acquired by eBay. Later Sequoia materials describe follow-on decisions, but those are Team Sequoia/Roelof Botha retrospectives rather than contemporaneous Moritz records. PayPal S-1 Adapting to Endure
Ex-ante case 4 — Zappos: update after three dot-com wounds
Freeze before outcome
Known before 2004: Tony Hsieh had worked with Moritz at LinkExchange; Zappos had been passed several times. Sequoia’s concerns included high product returns, inventory cost, cash flow, and Nevada. Webvan, eToys, and PlanetRx supplied painful prior context. Zappos oral history
New evidence: by 2004 Zappos was growing and users could reliably find the exact shoe and receive it quickly, producing an experience differentiated from physical stores. [retrospective witness · strong]
Unknown: check, price, security, ownership, detailed dissent, reserve decision, and decision-date cohorts. Roles: Moritz maintained the founder relationship and pushed to invest; Lin and Botha supplied later operating/analytic work; partnership approval is unknown.
No-hindsight IC worksheet
- Invest or pass? Decide whether observed customer value compensates for inventory and return risks.
- Kill criteria: repeat purchase cannot cover returns and fulfillment; inventory turns deteriorate; bank capacity fails; service advantage is copied.
- Ownership/terms: price the working-capital and financing risk; protect enough ownership for follow-on needs without claiming unknown historical terms.
- Next-check milestones: repeat cohorts, contribution margin after returns, inventory turns, delivery reliability, and committed bank capacity.
Actual decision and outcome
Sequoia partnered in 2004. Moritz helped recruit board members and support bank confidence; Botha contributed cohort analysis and Kiva access; Lin became a later Sequoia partner. Amazon acquired Zappos for a reported $1.2 billion in 2009. Zappos oral history, milestones and team The acquisition value is not Sequoia proceeds.
Ordinary governance case — Green Dot
Green Dot’s S-1/A records Moritz on the board from 2003 and supplies issuer ownership/governance context. Green Dot S-1/A, directors and ownership In 2016 Harvest Capital’s dissident deck alleged a stale board and underperformance; Moritz’s issuer-filed letter and Green Dot’s response defended management and his contributions. Harvest deck Moritz letter Issuer response
Both sides are interested. The filings prove positions taken and a governance contest, not which narrative caused performance. [contemporaneous record · strong on dispute; insufficient public record on causal verdict]
No-hindsight governance worksheet: What independent operating metrics would distinguish patience from entrenchment? Which director skills are current? What refresh or strategic milestone must be met? What information would cause the board or shareholder to reverse? The actual record is a proxy contest with competing claims, not a neutral process-change study.
Current adverse case — Klarna
Klarna says Moritz led Sequoia’s original 2010 investment, joined the board in July 2010, and became chair in December 2020. Klarna 2024 announcement Klarna leadership Form 3 Table I reports 3,472,845 ordinary shares held indirectly through Crankstart Foundation and footnote 1 reports $49,913,138.73 paid over March 3–11, 2026; Table II separately reports 37,500 directly held RSUs, vesting in four equal annual installments under footnote 2. Klarna Form 3, PDF p. 1, Tables I–II and footnotes 1–2 The direct, indirect, and Sequoia categories are not combined.
The 2024 FT reported a boardroom dispute connected to Sequoia; it is reporting, not an adjudication. FT, “How Klarna’s boardroom spat exposed a schism at Sequoia Capital” In December 2025, Nayak v. Klarna named Moritz and asserted Securities Act §§11, 12(a)(2), and 15 claims relating to offering materials. As of the docket reviewed, the case remained pending through May 8, 2026; no merits finding, class certification, or liability is represented. Docket Complaint, Document 1
This is not a failure verdict. It is a live governance-and-disclosure test. An IC/board exercise should ask: Which loss, credit, funding, and disclosure indicators were board-visible before the IPO? Which registration-statement statements were challenged? What evidence would prove or rebut material omission? What ownership, independence, and committee rights shape response? The answer must come from filings and adjudicated records, not stock-price hindsight.
Failure and miss lab — Webvan, eToys, PlanetRx, and the Zappos passes
What the record supports
Moritz names Webvan, eToys, and PlanetRx as wounds that made Sequoia skeptical of online shoes; the specific Zappos concerns were product returns, inventory, cash flow, and location. Zappos oral history The record does not expose each original thesis, check, ownership, warning timeline, capital escalation, governance response, write-off, or loss. Those gaps bar a conventional full-loss narrative.
Postmortem
| Required field | Supported conclusion |
|---|---|
| Original thesis/evidence | Insufficient public record for each failed company. |
| Warning signs | Inventory intensity, product returns, cash consumption, financing dependence; case-specific timing unknown. |
| Capital response | Insufficient public record. |
| Governance/stop decision | Insufficient public record. |
| Outcome | Named as prior wounds/failures in the Zappos oral history; exact economics not claimed. |
| Claimed lesson | Prior losses made the partnership skeptical; visible Zappos customer/operating evidence ultimately reversed the veto. |
| Process change | Documented behavior shows updated decision, not a formal firm-wide rule. |
| Attribution | Sequoia-level scars; no sole Moritz loss credit. |
| Counterfactual | Passing Zappos forever could avoid repeated ecommerce risk but forgo evidence that the operating model had changed. |
No-hindsight failure/miss worksheet
- At the first Zappos review, would you pass, invest, or run a milestone pilot?
- Which cohort, contribution-margin, inventory-turn, return-rate, and bank-capacity thresholds would reverse a pass?
- What check and ownership preserve optionality without funding an unbounded inventory experiment?
- If the company misses two gates, do you stop, restructure, or recruit? Assign the decision right now.
Actual decision and lesson
Sequoia passed several times, then invested in 2004 after operating evidence improved. This supports updating after failure; it does not prove that every scar was productive or that the eventual timing was optimal.
Portfolio-level forensics
Across the 20 included public routes, the observable sample spans consumer internet, search, payments, ecommerce, enterprise software, networking, professional media, delivery, and fintech. It is board-role and public-outcome heavy. Stage, check, ownership, reserves, and failure data are missing for most companies, so sector or hit-rate percentages would imply false completeness.
Patterns that survive:
- Stage: Yahoo, Google, PayPal, LinkExchange, and Zappos show early-company exposure; LinkedIn/Klarna/Instacart include later governance and multi-stage records. [documented behavior · moderate]
- Governance: long board tenure recurs, but board lists are selected and do not prove sourcing or causal value.
- Concentration: Google’s disclosed block makes it the likely observable outlier; total fund concentration is unknown.
- Follow-ons: PayPal/Zappos narratives imply continued support, but a reserve policy cannot be reconstructed.
- Geography: US-led record expands to China/Europe and later distinct structures; authority and economics differ by entity and date.
- Failures: public failures are less documented than wins. Webvan/eToys/PlanetRx are valuable precisely because they appear in a later decision account.
No gross/net fund return, vintage cash flow, or personal-return number is reported because period, methodology, and independent triangulation are absent.
Role-by-role decision-rights matrix
| Role | What must be recorded | T027 evidence |
|---|---|---|
| Source | Introducer and relationship owner | Known only in selected founder histories |
| Sponsor | Partner arguing for investment | Moritz supported in selected Google/Zappos/Klarna accounts |
| Diligence | Product, market, references, legal, financial owners | Mostly unknown |
| Approval/dissent | Vote, veto, partnership dissent | Zappos dissent exists generally; exact votes unknown |
| Negotiation | Check, security, price, ownership, rights | Mostly unknown; PayPal transaction terms partially filed |
| Board | Formal service and period | Strong issuer evidence for multiple companies |
| Recruiting | Executives/directors introduced | LinkExchange, Zappos, POPSUGAR examples |
| Follow-on | Reserve owner and milestone | Mostly unknown; later team accounts bounded |
| Exit | IPO/acquisition/secondary influence | Mostly unknown |
| Narration | Person telling the later story | Moritz, Lin, Botha, founders, issuers, dissidents separated |
Uncertainty and retrieval ledger
- Complete Sequoia fund and opportunity denominator: unavailable; career coverage not computable.
- Google joint-round split, entry price, dilution, distributions, and fund contribution: unavailable.
- Yahoo original check/security/ownership and full decision roles: unavailable.
- PayPal primary-company cash associated with the secondary purchase and later cash flows: do not infer.
- LinkExchange/Zappos check, ownership, reserves, and partnership vote: unavailable.
- Webvan/eToys/PlanetRx original theses, warning timelines, stop decisions, and losses: unavailable.
- Green Dot independent causal resolution of proxy claims: no neutral verdict established.
- Klarna complaint merits and class status: pending as of the cited docket; refresh before future publication.
- Getir family-office/Sequoia sequencing, ownership, and economics: unresolved.
- Stripe is admitted as an unresolved direct-witness route: the OpenAI-processed Money Maze audio supports an initial Moritz–Patrick Collison conversation and remembered product thesis, but not sourcing, approval, check, security, entity, ownership, other partner roles, follow-ons, exit decisions, or economics.
- YouTube remains excluded from Moritz credit because official Sequoia attribution belongs to Roelof Botha.
The highest-value future evidence is fund cash-flow data, IC records, partner-role ledgers, failed-founder interviews, stable archive access, and adjudicated legal outcomes. None is simulated with press valuation arithmetic.
Coverage and evidence base
The priority written-source denominator is ten rows, S01–S10 in sources.md. Two are corpus/identity indexes (S01 and S07), eight are distinct works or edition-level works (S02–S06 and S08–S10). One work, “The Dawn of the Profitable Unicorn,” was accessible in full. Six were accessible only through legitimate previews, publisher descriptions, visible metadata, or paywalled headings (S02, S03, S05, S06, S08, S10). Going for Broke was metadata-only. The publisher and FT indexes were fully inspected as catalogs but cannot be content-analyzed as essays. The dated FT sweep found exactly 63 cards = 36 conservatively authored + 27 excluded across three live pages; three ambiguous 2015 cards remain in the excluded group. Exact card ledger
Accounting: 10 priority rows found; 1 full-text work deeply analyzed; 6 partial works analyzed to the exact available boundary; 1 metadata-only work inventoried; 2 indexes reconciled; 10 represented below; 0 treated as fully read when it was not. Fifteen written/evidence notes support the phase: ten authorship/corpus records plus five primary-record and attribution bundles used to test whether rhetoric matched decisions. The FT interface showed exactly 63 cards in the dated sweep, but 27 were reporting, reviews, compilations, third-party work, or byline-unresolved; only 36 are conservatively admitted as authored.
Official publisher biography and authorship index
Context and access. Simon & Schuster’s current author page is full metadata, not an authored essay. It verifies Cardiff in 1954, former TIME work, regular FT contribution, thirty-five years as a Sequoia partner, 1995–2012 leadership, Crankstart with Harriet Heyman in 2001, and a book route. Publisher biography, “About The Author”
Argument/reasoning/evidence. There is no argument to analyze. The page is promotional metadata and offers no method, denominator, or investment evidence. Its “most successful” framing is excluded because no fund, vintage, cash-flow series, or attribution method is supplied. [researcher inference · strong]
Decision and biography implication. Use the record to anchor chronology and locate books; never use it to prove investment skill. Its visible book carousel is incomplete, so library and publisher records remain necessary. Publisher page, “Books by Michael Moritz”
Evolution/contradiction. A thirty-five-year “partner” description and a public 1986–2023 career span can coexist only if leadership, partner, and later advisory roles are not collapsed. Klarna leadership, Michael Moritz
The Little Kingdom (1984)
Context and access. The original ISBN route identifies Moritz’s reported history of Apple while it was still a young private company. Only catalog/preview material was lawfully available, so no chapter is represented as read. Google Books, ISBN 9780688039738
Central project. The supportable project is company history built from proximity to early Apple. The full reasoning chain, interviews, scenes, and assumptions cannot be reconstructed from metadata. [contemporaneous record · strong on authorship; insufficient public record on content]
Evidence/examples and assumptions. The transferable research hypothesis is to form a narrative from interviews, documents, products, and institutional history; that description is [researcher inference · provisional], not a fully analyzed book argument. The hidden assumption is that reporting access improves judgment rather than merely storytelling.
Decision implication. Preserve decision-date documents before a company becomes legendary; build founder/product claims from primary evidence; keep proximity separate from predictive skill. The first two rules are analyst translations, not quoted Moritz doctrine. Digital Riptide, Yahoo hindsight discussion
Evolution/contradiction. The book predates Moritz’s 1986 Sequoia entry. Chronology supports a possible research apprenticeship; it does not prove that Apple observation caused later Yahoo or Google outcomes. DOJ transcript, career-entry discussion, printed pp. 5–7
Return to the Little Kingdom (2009)
Context and access. The 2009 edition is revised and expanded; only a discovery/preview route was available. Google Books, revised-title route
Central project and reasoning boundary. The revision revisits Apple after twenty-five years of company and Jobs history. Without full text, this package does not claim which chapters, judgments, or evidence changed. [contemporaneous record · strong on edition; insufficient public record on change set]
Decision implication. Maintain separate contemporaneous and retrospective files. Compare what a writer knew in 1984 with what a reviser knew in 2009 before treating either as an ex-ante lesson. [researcher inference · strong]
Evolution/contradiction. Later framing can benefit from Apple’s outcome and Jobs’s return. That does not invalidate the revision, but it prevents its later causal account from being silently imported into the 1984 evidence set.
Going for Broke: The Chrysler Story (1981)
Context and access. WorldCat identifies a 1981 Doubleday edition coauthored by Michael Moritz and Barrett Seaman; a later 1984 edition uses the Lee Iacocca subtitle. The record was metadata-only. WorldCat, OCLC 7460014
Argument, reasoning, and examples. Not analyzed. Publisher/library metadata cannot establish the book’s thesis, evidence, assumptions, or conclusions. Nor can it assign specific passages to Moritz rather than Seaman.
Decision and biography implication. The reporting subject—a company rescue under operational, capital, political, and governance pressure—is relevant to his pre-venture formation. Any link to later runway or board practice is [researcher inference · insufficient public record].
Evolution/contradiction. Preserve the 1981/1984 edition distinction and coauthorship. Calling it a 1984 sole-authored Moritz investment book would create both chronological and attribution errors.
Leading: Learning from Life and My Years at Manchester United (2015)
Context and access. Hachette attributes the work to Alex Ferguson and Michael Moritz. Its visible description centers on hiring, firing, transition, teamwork, boards, failure, and adversity; the cited US paperback page is dated September 20, 2016, while the original work is commonly dated 2015. Hachette, byline, description, and product details
Central argument and evidence. The accessible description presents sustained leadership through Ferguson’s management experience, with Moritz as collaborator and synthesizer. No chapter-level reasoning or example is claimed without licensed text. [contemporaneous record · strong on framing; partial on content]
Assumptions. The analogy assumes elite-sport team renewal and business/venture institutions share useful talent, performance, succession, and adversity problems. Survivor selection and different labor/competition regimes make that transfer nonautomatic. [researcher inference · strong]
Decision implications. Evaluate current contribution rather than historic reputation; plan succession before decline; treat the boardroom and talent system as operating work. These are [researcher inference · moderate], supported independently by Moritz’s YC transcript rather than attributed solely to the book. YC, “Yesterday is irrelevant” and “Maintain a fresh team”
Evolution/contradiction. Stanford used the book to ask Moritz about consequential life decisions, creating a direct bridge to his own biography. Stanford transcript, PDF p. 1 The book’s evidence remains chiefly Ferguson’s, and analogical recurrence does not prove Sequoia performance.
Ausländer: One Family’s Story of Escape and Exile (2026)
Context and access. The US publisher page gives a September 1, 2026 date and describes a family/history memoir built from papers and photographs concerning relatives murdered by the Nazis and Moritz’s parents’ escape to Britain. Simon & Schuster, “About The Book” and “Product Details” UK discussion appeared earlier; dates must retain market/edition labels.
Central project and evidence. The publisher description supports an archival family reconstruction, not the chapter-level argument. In Money Maze at 35:58–37:52, Moritz directly says the project grew during Covid after his mother's death and the arrival of four or five cartons of family papers. At 49:16–50:21 he describes four rewrites, trusted-reader feedback, and cutting at least 35,000 words. Money Maze episode/audio [investor-stated · strong on process; full book still unavailable]
Assumptions and implications. Institutional fragility and outsider identity may inform Moritz’s worldview; tying either to a specific deal is [researcher inference · provisional]. Family trauma must not be rewritten as a deterministic source of ambition or risk tolerance.
Evolution/contradiction. The memoir extends late-career writing beyond technology and sport into family history and political warning. Its documented method—archival paper chase, external experts, multiple rewrites, trusted criticism, and aggressive deletion—echoes journalism's evidence discipline, but any investment application remains inference.
Financial Times author/topic stream
Context and access. The FT stream is a mixed discovery interface. The August 22, 2026 sweep inspected all three visible pages—25 + 25 + 13 cards—and reconciled 63 cards into 36 conservatively authored and 27 excluded. Exclusions cover reporting about Moritz, reviews, compilations, third-party pieces, and byline-unresolved cards; three ambiguous 2015 items remain excluded. FT stream Exact 63-card title/date/byline/disposition ledger
Corpus method. Each piece enters the authored denominator only after a visible Moritz byline or an explicit card deck saying he wrote it. July 2023 departure reporting and the February 2024 Klarna dispute are subject reporting, not Moritz works. Page/card ordinals are locators only for this dated sweep; the interface is not treated as a stable manifest. Card ledger and access code
| Reconciliation | Count | Disposition |
|---|---|---|
| Visible cards | 63 | Three pages: 25 + 25 + 13 |
| Conservatively authored | 36 | Visible Moritz byline or explicit “writes Michael Moritz” deck |
| Excluded | 27 | Reporting, review, compilation, third-party, or unresolved byline |
| Ambiguous 2015 cards within excluded | 3 | Remain excluded pending licensed byline access |
Visible thematic range. Verified titles span technology finance, private valuations, pandemic acceleration, extremism, sport, tax, homelessness, SVB, immigration, and politics. FT stream [contemporaneous record · strong on metadata] Full arguments are not reconstructed from headlines.
Decision implication. The stream demonstrates broad public commentary, not a unified investment manual. A theme becomes part of Moritz’s investing system only when a full bylined text and independent decision evidence support the bridge.
Evolution/contradiction. The FT role becomes more civic and political over time, while reporting about Sequoia and Klarna becomes interleaved in the same interface. That is exactly why author and topic archives must remain separate.
The subprime “unicorns” column (2015)
Context and access. A Techmeme origin index fixes the October 16, 2015 title/date route to a paywalled FT column. Techmeme origin trace A contemporaneous report preserves the related Bloomberg context. Business Journals report, October 19, 2015
Central argument and reasoning boundary. The accessible record supports concern that private status can delay scrutiny and that fragile valuations remain subject to business gravity. The full column’s examples, assumptions, and wording are not content-analyzed. [investor-stated · moderate]
Decision implications. Demand public-company-grade cohort, margin, governance, and capitalization evidence before paying a late-stage private price. Specify which information is unavailable because the company is private. [researcher inference · moderate]
Evolution/contradiction. The warning sits alongside Moritz’s participation in private markets and cannot establish that his own late-stage pricing escaped the problem. Getir and other later outcomes are required tests, not rhetorical footnotes.
The Dawn of the Profitable Unicorn (2015)
Context and access. Moritz posted the full December 11, 2015 essay on LinkedIn and identified it as originally published by the FT. LinkedIn, title/byline/date and body
Central argument. Comparing the fifteen largest technology companies in 2000 with a newer set by 2015, Moritz argues that technology leadership turns over dramatically and highlights novelty, software/cloud shifts, China, patience, and capital efficiency. He closes by proposing that billion-dollar companies requiring less capital and reaching profit may form a distinctive class. LinkedIn, body paragraphs beginning “First, the bad news” through “Finally” [investor-stated · strong]
Reasoning and evidence. The essay cites a Francisco Partners analysis, market-cap changes, sector displacement, and then-current company examples. It distinguishes destroyed incumbents from new software/platform leaders and connects lower capital consumption to strategic endurance. LinkedIn, market-cap and capital-efficiency paragraphs
Assumptions. Market capitalization is a useful but period-sensitive proxy for corporate success; the selected top-fifteen endpoints are informative but exposed to selection, classification, inflation, and survivorship. The assertion that Google consumed only $8 million before profitability is single-source within this corpus and is not converted into a fund return. [investor-stated · moderate on figure]
Decision rules.
- Ask whether the company benefits from a durable cost/architecture shift rather than category fashion.
- Model how much capital is required before gross profit and self-financing.
- Preserve ownership-weighted outcomes under a downside financing case.
- Treat China as a source of competitors and customers, not an undifferentiated hours proxy.
These are [researcher inference · moderate] from the essay. They become investable only with company-specific unit economics.
Biography and behavior link. The software/platform thesis is consistent with Moritz’s Google and legacy-media remarks, but consistent rhetoric does not prove deal efficacy. Digital Riptide, Google and media-engineering sections
Evolution/contradiction. Capital efficiency and patience can conflict: patient investors may rationalize repeated financing in companies whose economics never mature. The essay’s praise of Chinese ambition also foreshadows a more controversial 2018 argument about work intensity.
Silicon Valley would be wise to follow China’s lead (2018)
Context and access. The canonical FT column is dated January 2018 and paywalled. FT canonical page TechCrunch and VentureBeat preserve critical responses but are not neutral substitutes for the body. TechCrunch criticism VentureBeat founder/operator response
Central argument and evidence boundary. The supportable position praises extreme Chinese startup work intensity and contrasts it with US practice. Full reasoning, examples, and qualifiers are only partially accessible. [investor-stated · moderate]
Assumptions and counterevidence. The comparison risks treating hours as output and countries as homogeneous. Critics highlight health, family, welfare, bargaining power, legal conditions, productivity, and different development stages. Those critiques are themselves arguments, not controlled evidence. [researcher inference · moderate]
Decision implication. Never use hours, physical presence, or cultural stereotype as a founder-quality measure. Measure learning velocity, shipped product, retention, error rates, team sustainability, and legal compliance. [researcher inference · strong]
Evolution/contradiction. The column sharpens a long-running Moritz emphasis on intensity but conflicts with the inclusive, evidence-based interpretation of “standards” a modern partnership requires. The 2015 gender exchange supplies a separate warning that ostensibly neutral standards can encode pipeline and affinity bias. Bloomberg original video Vanity Fair critique
Companion written evidence: rhetoric versus records
The writings cannot be evaluated only against other writings. Five note bundles test claims against primary and adversarial records:
- Google: joint $25 million round, Moritz/Doerr board seats, 2004 fund block, and explicit beneficial-ownership limits. Google announcement Google S-1, printed pp. 84–85
- PayPal: $5 million secondary purchase from Musk, not company financing; Sequoia vehicle and board facts. PayPal S-1/A, “Certain Transactions”
- Yahoo/Zappos: public governance plus a failure-to-update oral history with Moritz/Lin/Botha role separation. Yahoo proxy Zappos
- Green Dot: a Moritz shareholder letter must be read against both dissident and issuer filings. Moritz letter Harvest deck
- Klarna/Nayak: current board, ownership, and complaint facts constrain any broad governance claim. Klarna 20-F Nayak docket
This companion set is not counted as additional authored works.
Cross-source synthesis
Foundational versus occasional ideas
| Idea | Written support | Behavioral/direct-voice test | Assessment |
|---|---|---|---|
| Preserve decision-date history | Little Kingdom edition boundary; later revision | Digital Riptide rejects hindsight inevitability | [researcher inference · moderate] |
| Capital efficiency and patience | “Profitable Unicorn” full text | PayPal/Zappos cash and survival stories are retrospective | [investor-stated · moderate; efficacy unproved] |
| Technology architecture changes leadership | “Profitable Unicorn” | Google and legacy-media remarks | [investor-stated · moderate] |
| Institutions require renewal | Leading partial record | YC direct transcript | [investor-stated · strong in talk; writing attribution shared] |
| Global competition matters | 2015/2018 columns | YC credits local China team | [investor-stated · moderate; cultural generalization contested] |
| Public institutions and politics matter | Later FT titles; Ausländer | Money Maze directly documents the archival/revision process | [investor-stated · strong as interest/process; insufficient as investment rule] |
Sourcing, picking, portfolio, governance, and exits
- Sourcing: reporter-style primary work may improve question quality. At 13:43–16:13 of Money Maze, Moritz directly credits Oxford tutorials and journalism with fact-gathering and judgment under incomplete information; whether that improved outcomes remains unmeasured, and no writing establishes a proprietary sourcing channel. Money Maze episode/audio [investor-stated · strong on self-described training; efficacy provisional]
- Picking: product/architecture shifts and capital efficiency recur, but a full scoring method is absent. “Profitable Unicorn,” architecture and capital paragraphs [researcher inference · moderate]
- Pricing/ownership: private-market scrutiny appears in 2015; public writings do not disclose Moritz’s price or ownership thresholds. 2015 origin trace [researcher inference · provisional]
- Portfolio construction: patience is advocated; concentration, reserves, and sell discipline remain insufficiently public. “Profitable Unicorn,” patience paragraph [investor-stated · moderate]
- Governance: Leading and FT governance columns are suggestive; Green Dot and Klarna demonstrate why interested counterrecords are necessary. Hachette description Green Dot opposing filings [researcher inference · moderate]
- Exits: no priority writing supplies a systematic exit rule. The DOJ talk adds a qualitative hold-winners view, but that belongs to the spoken record. DOJ transcript, returns/exit passage [insufficient public record]
Intellectual chronology, evolution, and contradictions
| Period | Written record | Development and contradiction |
|---|---|---|
| 1981–1984 | Chrysler and Apple company histories | Deep company reporting precedes venture; causal edge remains unproved. |
| 2009 | Apple revision | Revisits a prior record after outcomes; creates a built-in hindsight audit. |
| 2015 | Leading, subprime-unicorn warning, profitable-unicorn essay | Moves from company narrative to institutions, capital regimes, and durable leadership. |
| 2018 | China work-intensity column | Global competition becomes a cultural prescription; critics expose output, welfare, and labor assumptions. |
| 2020–2025 | FT civic, political, tax, immigration, sport, and technology columns | Public focus broadens; not every opinion belongs in an investment system. |
| 2026 | Ausländer | Family archive and institutional fragility become central; the Money Maze interview, 35:58–37:52 and 49:16–50:21 documents four rewrites, trusted-reader feedback, and at least 35,000 words cut, while investment causality remains provisional. |
The durable thread is close attention to how institutions adapt under technological and capital change. The unresolved tension is whether demanding intensity and renewal are evidence-based standards or rhetoric that can obscure bias, power, and sustainability.
Decision playbook and modern VC translation
Historical rules
The six historical rules below are [researcher inference · moderate] distilled from the cited source subsections, not quotations or claims that Moritz used a formal checklist:
- Reconstruct before narrating. Separate primary documents, participant memory, and later outcome. Apple edition records Digital Riptide
- Underwrite capital to a self-sustaining milestone. Track gross margin, runway, and financing dependence. “Profitable Unicorn”
- Test architecture, not category labels. Identify the cost/performance shift that displaces incumbents. “Profitable Unicorn”
- Re-underwrite institutions prospectively. Past status does not earn a current board or IC role. Leading description YC transcript
- Treat global comparisons dimension by dimension. Compare product speed, talent, capital, law, and market maturity separately. FT China column VentureBeat countercase
- Pair every governance claim with an adversarial record. Read dissident, issuer, founder, employee, court, and regulator evidence. Green Dot dissident deck Nayak docket
Modern VC translation (as of 2026-08-22)
Every row below is an analyst-created hypothetical transfer test, not a documented Moritz application.
| Rule | What transfers | What fails/changed | Applicability signals | Likely misuse |
|---|---|---|---|---|
| Reconstruct before narrating | Store decision-date artifacts and version every thesis. [researcher inference · strong] | Digital archives create volume, not truth. | Claims have source, date, locator, and role label. | Treating AI summaries as primary evidence. |
| Capital to sustainability | Unit economics and financing gates remain essential. [researcher inference · strong] | Different sectors require different capital intensity. | Runway-to-milestone and downside dilution are explicit. | Calling all capital use bad. |
| Architecture over labels | Technical cost/performance can create a wedge. [researcher inference · moderate] | A demo or model wrapper may be easily copied. | Retention and workflow depth survive competitor entry. | Equating novelty with defensibility. |
| Prospective institutions | Partner and board contribution must be current. [researcher inference · strong] | Abrupt renewal can destroy trust and memory. | Roles have measurable objectives and succession coverage. | “Yesterday is irrelevant” as license for arbitrary removal. |
| Dimension-matched geography | Local teams and conditions matter. [researcher inference · strong] | Hours and national stereotypes are invalid proxies. | Output, law, retention, capital, and user behavior are measured separately. | Glorifying 996 or dismissing other ecosystems. |
| Adversarial governance | Opposing records reveal falsifiers. [researcher inference · strong] | Litigation allegations are not findings. | Claims and dispositions are in separate fields. | Treating a complaint as proof or absence of judgment as exoneration. |
Current examples are analyst-created transfer tests, not documented Moritz applications. Their factual premises should be validated for the target market at the decision date.
Best writings and unresolved record
Read these five first
- “The Dawn of the Profitable Unicorn” (2015) — only priority investing essay available in full; exposes capital-efficiency thesis and its endpoint assumptions.
- The Little Kingdom (1984) — earliest company-research record; obtain a licensed copy before claiming chapter lessons.
- Leading (2015) — institutional renewal and talent bridge, with Ferguson/Moritz attribution kept separate.
- “The subprime ‘unicorns’…” (2015) — private-market scrutiny; full access remains necessary.
- Ausländer (2026) — deepest biographical worldview route, not an investment manual.
The China column is essential adverse reading, but it ranks below the five as a transferable investing source because the body was partial and its generalized productivity prescription is heavily contested.
Unresolved record
- Licensed full text and page locators for both Apple editions, Going for Broke, Leading, and Ausländer.
- Full lawful FT bodies, beginning with the 2015 private-market and 2018 China columns.
- Stable year-by-year FT author export separating bylines, subject reporting, reviews, and duplicates.
- Exact coauthorial division in Going for Broke and Leading.
- Current evidence testing whether capital efficiency, patience, standards, and institutional renewal improved ordinary outcomes.
- A decision-date portfolio and pass denominator capable of checking rhetoric against behavior.
The access failures are specific and exhausted for the routes listed; no paywall bypass, snippet reconstruction, or metadata-as-content substitution was used.
Coverage and evidence base
The spoken-corpus denominator is ten priority appearances, S21–S30 in sources.md: eight ★★★ and two ★★. Six are deeply content-analyzed from full human-readable or OpenAI API timestamped text (Digital Riptide, Stanford eCorner, YC, DOJ, Visionaries Club, and Money Maze); four remain access-bounded (Oxford, Charlie Rose, Founders Space, and Stanford GSB). The three Stanford clip transcripts are child excerpts of the 2016 event and do not inflate the appearance count.
The resulting accounting is: 10 found; 6 deeply content-analyzed; 4 bounded to partial media, unstable locators, or unvalidated captions; 10 represented below; 0 silently omitted. Direct speech is reliable evidence of what Moritz said in that venue, not proof that a rule worked or that a retrospective deal account was contemporaneous.
Audio method: the 65:27 Money Maze source exceeded OpenAI's 25 MB upload limit, so the original MP3 was split losslessly into eight 480-second chunks and one 87.14-second tail. All nine gpt-4o-transcribe-diarize calls succeeded; 701 segments were offset to episode time. Machine wording is paraphrased by default, speaker identity is checked from conversational continuity, and no local or non-OpenAI transcription was used. Method ledger
Oxford Campaign interview (2008)
Context and access. Oxford’s official page provides a 5:53 audio/video route and was added September 16, 2008. Oxford podcast record, metadata It is a short education/philanthropy appearance rather than a venture masterclass.
Contribution. The appearance helps verify Moritz’s continuing Oxford relationship and the institutional logic around education giving. [investor-stated · moderate] It should not be used to infer a picking rule or investment return. The later Oxford announcement is stronger for the £75 million Moritz-Heyman gift and scholarship terms. Oxford announcement, July 11, 2012
Decision use and limit. Treat education and talent access as separate from venture performance. The useful IC prompt is whether the fund is mistaking elite-institution proximity for founder quality. No quote is retained because a timecoded transcript was not validated.
Charlie Rose (2013)
Context and access. The official broadcast page dates the interview February 15, 2013 and exposes a transcript interface, but the interface did not provide stable locators in the accessible route. Charlie Rose episode record
Contribution. The appearance maps the journalist-to-investor journey, selection, and Sequoia durability. [investor-stated · provisional] Its claims are used only where independently supported by the full Digital Riptide, Stanford, YC, or filing record; no quotation is retained from an unstable interface.
Decision use and limit. “Famous interview exists” is not “appearance fully processed.” A licensed or stable transcript with timestamp alignment could change the synthesis; until then, Charlie Rose contributes corpus breadth and corroboration, not unique decision evidence.
Digital Riptide oral history (2013)
Context. Recorded April 2, 2013, the full lightly edited transcript focuses on journalism and the internet. It is the richest account of Yahoo and Google, but it remains an eighteen-year retrospective on the first Yahoo decision. Digital Riptide transcript, opening and Yahoo/Google sections
Core reasoning.
- Moritz rejects a grand internet design: early investments asked how a small company could survive the next year. Digital Riptide, opening answer [investor-stated · strong]
- Yahoo’s move into news was opportunistic: a Reuters relationship added more than money and opened distribution. Digital Riptide, Yahoo/Reuters passage [investor-stated · strong]
- A platform is usually a later result of a narrow service becoming popular, not a credible starting label. Digital Riptide, platform passage [investor-stated · strong]
- Google’s rationale centered on superior search technology, not a media thesis. Digital Riptide, Google passage [retrospective witness · moderate]
- Legacy media’s strategic deficiency was not merely content; it lacked software talent and defended print scale instead of rebuilding digital distribution. Digital Riptide, legacy-media/software-engineer passage [investor-stated · strong]
Evidence and assumptions. Yahoo, Google, Time, and legacy media supply examples. The causal assumption is that narrow user adoption and technical superiority can widen into distribution power. The transcript itself supplies no complete alternative set, ownership math, or return comparison.
Contradictions. Moritz includes YouTube in Sequoia’s media record, but official firm attribution assigns the investment to Roelof Botha; inclusion in a firm narrative is not Moritz deal credit. His hindsight warning also constrains his own later recollection.
Decision rule. Reject a “platform” pitch unless a narrow use already earns repeated behavior. Freeze the incumbent set and failure reasons before learning the outcome. [researcher inference · strong]
Founders Space — “The King of All VCs” (circa 2012)
Context and access. The interview page is available only in part, and its flattering title is a warning about editorial framing. Founders Space interview
Contribution. It supplies a secondary route into founder-selection and board-role claims. [investor-stated · provisional] No unique quotation or unsupported superlative enters the synthesis.
Decision use and limit. Compare any founder heuristic with Lisa Sugar’s contemporaneous countervoice at Stanford and the Zappos multi-witness account. Do not let reputation-bearing questions become proof of efficacy.
Stanford eCorner with Lisa Sugar (2016)
Context. The January 20, 2016 processed official transcript gives both investor and founder perspectives. Stanford's former PDF route moved during final review, so the citation resolves to the live official page/video while retaining the processed transcript's page locators. It is unusually valuable because Lisa Sugar supplies specific operating corroboration while Moritz repeatedly redirects credit to the founders and Sequoia. Stanford eCorner official record; processed transcript PDF pp. 1–7
Core reasoning.
- Moritz identifies emigration to the United States and joining Sequoia as his two consequential professional choices. Stanford transcript, PDF p. 1 [investor-stated · strong]
- Early investment requires imagining the upside while entering business with people not yet well known. Stanford transcript, PDF p. 1 [investor-stated · strong]
- Successful founders show specific product purpose, a real user connection, and sustained obsession that excludes distraction. Stanford transcript, PDF pp. 1–2 [investor-stated · strong]
- Investment performance matters more than social-media visibility, and humility matters because public profile cannot rescue bad decisions. Stanford transcript, PDF pp. 3–4 [investor-stated · strong]
- Mature companies must stay alert to platform shifts; POPSUGAR’s delayed mobile response is a concrete boundary case. Stanford transcript, PDF p. 4 [retrospective witness · moderate]
Founder countervoice and governance. Sugar says Moritz helped recruit, connect, and advise between meetings, and repeatedly pushed mobile. Moritz insists the company and credit belong to Lisa and Brian Sugar. Stanford transcript, PDF pp. 2 and 4 [retrospective witness · strong on described actions]
Decision rule. Replace the charisma question with evidence: What product does the founder understand unusually well? Which users recur? What did the founder notice before the market? How do references describe the person under distraction and bad news? [researcher inference · moderate]
Limit. “Obsession” can rationalize overwork or affinity bias. The test must be behavior and customer knowledge, never hours, aggression, gender, or cultural familiarity.
Y Combinator — “Maintaining Success for the Long Term” (2016)
Context. Sam Altman published this transcript from a normally private YC dinner on February 26, 2016. YC transcript, publication note
Core reasoning chain.
- An investor must build the investment organization as deliberately as a portfolio company. YC, opening institutional answer
- Past success is irrelevant to the next decision; trophies promote complacency. YC, “Yesterday is irrelevant”
- The partnership must evaluate present drive and refresh talent organically. YC, “Maintain a fresh team”
- Market geography changes; the firm must create capable local teams rather than exporting credit. YC, “Change with the market”
- Institutional insecurity can sustain vigilance, though it can also become an unhealthy cultural norm. YC, mistakes/going-out-of-business passage
Each is [investor-stated · strong] as a public belief. Their performance effect is [researcher inference · provisional] because no controlled comparison or complete fund series is public.
Evidence/examples. Moritz cites Steve Jobs, Larry Page, Jeff Bezos, Reed Hastings, younger Sequoia partners, and the China franchise. He expressly credits the China team and acknowledges many mistakes. YC transcript, “Yesterday is irrelevant,” “Maintain a fresh team,” and “Change with the market”
Contradictions. Clinical performance management can renew a partnership or conceal opaque power. China expansion later existed alongside organizational separation, so the 2016 federation claim should be read as period-specific, not a permanent equilibrium.
Decision rule. For every partner and thesis, ask what current evidence—not logos—earns another decision right. Preserve an institutional-memory ledger so renewal does not become amnesia. [researcher inference · strong]
Stanford GSB video (2019)
Context and access. Stanford GSB uploaded the official video February 7, 2019. The route is full video with automated captions but no validated human transcript in the evidence set. Stanford GSB video
Contribution. The appearance covers refugee-family history, venture talent, and the Manchester United analogy. [investor-stated · provisional until timestamp validation] It corroborates the intellectual bridge to Leading and the later memoir but supplies no verbatim quote here.
Decision use and limit. Automated captions are discovery aids, not quotation evidence. Specific claims must be replayed and timestamped, or supported through the official Stanford 2016, YC, publisher, and book records.
DOJ venture capital and antitrust workshop (2020)
Context. This February 12, 2020 government transcript places Moritz’s account inside a policy workshop rather than a firm-marketing interview. DOJ transcript, fireside-chat section
Contribution. The discussion addresses career entry, early-stage uncertainty, outlier economics, governance, exits, and the relationship between venture financing and competition. [investor-stated · strong] The regulatory venue matters: statements are views offered in a workshop, not agency findings or fund disclosures.
Reasoning and assumptions. Venture supports experiments that incumbents may not fund internally; company outcomes are highly uneven; board participation can help scarce young teams; acquisition and IPO routes affect incentives. The assumption is that the venture structure adds competitive entry rather than only redistributing ownership. [researcher inference · moderate]
Decision rule. In a regulated or concentrated market, add a competition memo: incumbent power, distribution foreclosure, acquisition dependence, likely remedies, and whether the startup remains viable without a strategic buyer. [researcher inference · moderate]
Limit. A policy defense of venture capital cannot establish Moritz’s deal performance. Printed-page and PDF-page locators must be preserved in the underlying note before quoting.
Visionaries Club conversation with Robert Lacher (2023)
Context. A hosted transcript published October 31, 2023 records a conversation from the year of Moritz’s Sequoia transition. The origin-video relationship requires cross-checking, so direct claims are graded A/B rather than treated as a court transcript. Hosted transcript
Core themes. “Unexpected” outcomes, hiring, Sequoia Heritage, global technology, and reinvention extend the 2016 institutional-renewal account into a transition year. [investor-stated · moderate]
Evolution. The emphasis moves from building Sequoia’s active venture partnership to stewarding longer-duration capital and explaining transition. That change can reflect vehicle role as much as changed philosophy. [researcher inference · moderate]
Decision rule. Before transferring a lesson across vehicles, compare duration, liquidity, governance, concentration, compensation, and stakeholder rights. [researcher inference · strong]
Limit. No Heritage performance, full asset allocation, or decision-rights record is public in this route.
Money Maze (2026)
Context and method. The official episode page identifies a current 65:27 interview and exposes audio and show notes, but displays a date inconsistency: April 2 versus April 9, 2026. Money Maze episode page The original 63.3 MB MP3 was split losslessly to meet OpenAI's 25 MB limit. Nine successful diarized transcript chunks produced 701 segments covering 00:00.27–65:26.33 after deterministic offsets. The publisher's April 14 adaptation is only a secondary cross-check. Method and timestamp ledger
Founder screen and Stripe. At 08:41–09:31 Moritz names three founder signals: unusual depth that can educate the investor, clear command and communication, and sustained hunger to make the product real. At 10:18–12:05 he recalls Patrick Collison presenting Stripe as a simpler continuation from PayPal and payment infrastructure for anyone starting online commerce. Money Maze episode/audio [investor-stated · strong on criteria; retrospective witness · moderate on Stripe] The episode proves an initial Moritz–Collison conversation and remembered thesis, not sourcing, approval, check, security, ownership, partner roles, or return.
How he says he learned to decide. At 13:43–16:13 Moritz credits Oxford tutorials and journalism with training him to gather facts quickly, judge unfamiliar subjects under incomplete information, and form a defensible view. That upgrades the formation mechanism from researcher-only inference to direct self-attribution; the performance advantage remains unmeasured. At 17:03–17:49 he says a financing bargain should leave founder and investor aligned for a long relationship rather than feeling extracted. Money Maze episode/audio [investor-stated · strong on process; moderate on terms principle] No price or ownership rule follows.
Geography, people, and governance. At 20:55–23:21 he attributes Europe's venture disadvantage to fragmented customer/business habits, a thinner accumulated pattern of scale success, and boards without fast-growth technology experience. At 23:42–24:13 he says portfolio hires should be Sequoia-caliber and emphasizes hunger and competitiveness. Money Maze episode/audio [investor-stated · moderate] These broad judgments require country-specific evidence and safeguards against hours, aggression, or cultural familiarity becoming proxies for quality. Klarna's contested governance record also prevents the Europe-board claim from functioning as self-validating expertise.
Compounding and AI. At 24:42–26:26 Moritz describes a current bias toward long-lived operations that increase cash and profit through cycles, combined with the capacity to remain inactive; he distinguishes a long horizon from unlimited patience. At 27:09–27:34 he declines to disclose Heritage specifics. At 29:41–30:35 he predicts that AI value will concentrate in one or two dominant companies, potentially including incumbents, with extensive failure elsewhere. Money Maze episode/audio [investor-stated · strong on preferences/forecast; insufficient on efficacy or portfolio construction] The first is a current capital-allocation view, not proof of historical Sequoia practice or Heritage performance; the second is a dated qualitative forecast without selection, sizing, reserve, or probability math.
Writing and biography. At 35:58–37:52 he says Ausländer emerged during Covid after his mother's death and the arrival of family papers; at 49:16–50:21 he describes four rewrites, trusted-reader feedback, and cutting at least 35,000 words. At 57:42–57:54 he corrects the host's diagnosis year from 2006 to 2008. Money Maze episode/audio [investor-stated · strong] These statements strengthen biography and writing-process evidence without turning family history into deal causality.
Contradictions and decision use. The appearance sharpens five tests: founder depth must survive behavioral evidence; non-extractive terms need actual term comparisons; European board claims need local counterexamples; compounding must be kept vehicle-specific; and the AI concentration forecast should be scored prospectively. No host praise, closing summary, teaser duplication, sponsor segment, or garbled ASR name is treated as Moritz evidence.
Cross-appearance synthesis
Durable themes
| Theme | Direct evidence | Decision use | Status |
|---|---|---|---|
| Early uncertainty | Digital Riptide; Stanford; DOJ | Write symmetric upside/downside and update gates. | [investor-stated · strong] |
| Narrow product before platform | Digital Riptide, Yahoo/Google | Demand a wedge with specific user or technical evidence. | [investor-stated · strong] |
| Founder purpose and obsession | Stanford, PDF pp. 1–2 | Test behavior, product cadence, and customer language. | [investor-stated · strong; application evidence moderate] |
| Governance as work | Stanford, PDF pp. 2 and 4; Zappos | Define recruiting, financing, product, and leadership actions. | [documented behavior · moderate] |
| Institutional renewal | YC; Visionaries Club | Re-underwrite partners and markets prospectively. | [investor-stated · strong] |
| Technology inside incumbent industries | Digital Riptide; DOJ | Evaluate software capability and incumbent response. | [investor-stated · moderate] |
| Explicit credit | Stanford; YC | Attribute founders, partners, local teams, and vehicles. | [investor-stated · strong] |
| Current compounding and AI concentration | Money Maze, 24:42–30:35 | Separate vehicle-specific cash-compounder preference from a scoreable qualitative power-law forecast. | [investor-stated · strong on view; efficacy unknown] |
Repetition establishes consistency across venues, not truth or return efficacy.
Evolution and unresolved tensions
- 2013 → 2016: company-level uncertainty and narrow products broaden into a partnership operating system.
- 2016 → 2020: founder/firm practice gains a policy frame around competition and exits.
- 2023 → 2026: public discussion shifts toward stewardship, history, and longer-duration capital. Money Maze, 24:42–30:35 directly adds a cash-compounder preference and a qualitative AI concentration forecast, while Moritz's refusal to discuss Heritage specifics keeps vehicle performance unknown.
- Humility versus harshness: warnings against headlines coexist with criticized public comments about women and Chinese work intensity. Consistent belief in demanding standards does not make every formulation accurate or transferable.
- Local-team credit versus federation: the 2016 China account emphasizes local people; later structural separation shows that geographic coordination and incentives need date-specific evidence.
- Active governance versus founder ownership: POPSUGAR and Zappos show helpful intervention; Green Dot and Klarna supply contested governance records.
Listen to these five first
- Digital Riptide (2013) — best deal-date uncertainty and Yahoo/Google reconstruction.
- Money Maze (2026) — best current founder screen, compounding boundary, AI forecast, and writing-process evidence.
- Stanford eCorner (2016) — best founder criteria plus a founder’s corroborating and limiting voice.
- YC (2016) — clearest partnership renewal and succession doctrine.
- DOJ workshop (2020) — strongest policy, competition, and governance context.
Charlie Rose should enter the five only after stable transcript locators are recovered; Money Maze now enters because the OpenAI transcript is complete and timestamp-reconciled.
Corpus and access ledger
| Route | Access | Analysis result | Remaining work |
|---|---|---|---|
| Oxford | Official short media/metadata | Partial, no quotation | Timestamp relevant passages if used |
| Charlie Rose | Official interface | Partial | Recover stable transcript/timecodes |
| Digital Riptide | Full transcript | Deep | Cross-check remembered chronology against filings |
| Founders Space | Partial page | Partial | Recover original media/transcript |
| Stanford eCorner | Full official transcript | Deep | None material |
| YC | Full released transcript | Deep | None material |
| Stanford GSB | Full video/auto captions | Partial | Human validation and timestamps |
| DOJ | Full official transcript | Deep | Preserve printed/PDF page locators in note |
| Visionaries Club | Full hosted transcript | Deep/qualified | Cross-check origin video |
| Money Maze | Full audio + nine-chunk OpenAI timestamped transcript | Deep/qualified | Re-check any future exact quotation against audio |
The last targeted searches mostly returned these same interviews, machine-caption mirrors, or child clips. Material remaining routes are explicitly named rather than hidden as “future research.”
Underwrite the wedge, not the imagined platform
- Rule — Invest only when a narrow product or service already demonstrates specific user or technical superiority; treat “platform” as a possible later state, not decision-date evidence.
- Evidence status — [investor-stated · strong] for Moritz’s direct rejection of platform-first narratives; [documented behavior · moderate] across Yahoo, Google, and Zappos because original IC records are incomplete.
- Provenance and origin — The earliest supportable direct articulation in this record is Moritz’s April 2013 Digital Riptide account: small companies begin as narrow offerings, and platform scope arrives after popularity. Digital Riptide, platform discussion
- Mechanism and reasoning — A narrow wedge permits direct comparison: quality, speed, availability, repeat use, or another customer outcome. Underwriting a future platform before that evidence multiplies market, product, and execution assumptions. Wedge adoption can create distribution and learning that later widen the opportunity. Digital Riptide, Yahoo/Google sections
- Historical and vehicle context — Yahoo and Google operated when portals, browsers, proprietary networks, and Microsoft held substantial distribution power; Sequoia’s network and patient fund entities supplied access and governance, but the public filings do not reveal entry ownership or return. Google announcement, June 1999
- When to use — Use at seed/Series A and at platform-transition follow-ons when a startup claims a much wider market than its current product. Do not use it to dismiss infrastructure whose initial buyer is narrow but whose architecture necessarily serves a broad control point.
- How to apply it — (1) Name one user and job. (2) State the measurable superiority. (3) Identify incumbent response. (4) Write a twelve-month survival case. (5) Set retention/quality milestones. (6) Reject platform revenue not earned by the wedge. Kill the deal if superiority disappears in blind use or repeat behavior stalls.
- Examples —
- Yahoo — documented application, retrospective: Moritz describes a narrow directory and later opportunistic Reuters news distribution, not an original media platform plan; Yahoo later widened. Digital Riptide, Yahoo discussion
- Google — researcher-applied illustration: the 1999 release documented word-of-mouth traffic and Stanford research, while Moritz later emphasized superior search technology; the final advertising system was not the disclosed underwriting. Google announcement Digital Riptide, Google discussion
- Zappos — documented application, retrospective: repeated passes reversed only after availability and delivery created a visible customer advantage. Zappos oral history, 2004 decision
- POPSUGAR mobile delay — counterexample/boundary: a successful wedge still required vigilance when distribution moved to mobile; initial fit did not guarantee platform adaptation. Stanford transcript, PDF pp. 2 and 4
- Evidence — Independent underlying sources include the full Digital Riptide transcript, Google’s contemporaneous company announcement, Stanford’s official transcript, and Sequoia’s multi-witness Zappos record. They support the rule, three cases, and its adaptation limit; none provides a controlled portfolio result.
- Limits, failure modes, and exception ledger — A small product can be a niche with no expansion path; adoption may be subsidized; a technical lead can vanish; and “focus” can rationalize a tiny market. Yahoo/Google hindsight creates selection bias. YouTube is not used as Moritz evidence because official Sequoia attribution belongs to Roelof Botha. Attribution note, Sequoia routes
- Evolution and contradictions — The 2013 platform account is consistent with 2016 founder-purpose remarks, but Moritz’s later public discussions span larger institutions and global franchises. The rule evolved from company wedge to institutional alertness, not into a universal small-market preference. YC, “Change with the market”
- Modern VC translation (as of 2026-08-22) — [researcher inference · moderate] Require repeat workflow depth and an economic or technical advantage that persists after novelty. For a hypothetical AI application, test retained task completion, switching cost, inference economics, and proprietary feedback; do not call a model wrapper a platform. The likely misuse is to relabel any narrow TAM a wedge without expansion evidence.
Put every early decision on the knife edge
- Rule — Write the strongest invest and pass cases from the same decision-date evidence, assign falsifiers, and refuse language of inevitability.
- Evidence status — [investor-stated · strong] for Moritz’s knife-edge warning; [researcher inference · strong] for the explicit symmetric IC procedure.
- Provenance and origin — In the April 2013 Riptide interview Moritz said that certainty at the initial decision is self-delusion and a properly examined investment rests on a narrow knife edge. At 13:43–16:13 of Money Maze he directly attributes comfort forming fact-armed judgments under incomplete information to Oxford tutorials and journalism. Digital Riptide, founder-selection exchange Money Maze episode/audio
- Mechanism and reasoning — Symmetric evidence prevents outcome knowledge from laundering a speculative thesis into “obvious.” Dated falsifiers force updates, while a written alternative set distinguishes calibrated risk-taking from luck. The procedure does not eliminate uncertainty; it makes later learning auditable.
- Historical and vehicle context — Early internet companies faced incumbent and financing risks that later winners make easy to forget. A closed-end venture vehicle can tolerate long uncertainty, but missing fund agreements, reserves, and cash flows mean patience cannot be quantified. Google S-1, vehicle footnote, printed pp. 84–85
- When to use — Use for every initial and follow-on IC decision, especially when a famous founder, hot category, or prior firm win creates social certainty. Do not use symmetry to pretend all cases are 50/50 or to avoid making a recommendation.
- How to apply it — Freeze date, known/unknown/believed/disputed fields; list alternatives; quantify only sourced facts; write three kill criteria; assign next-check evidence and owner; reveal the outcome only after the vote. Kill when a specified core premise fails and no new evidence changes the model.
- Examples —
- Yahoo — documented retrospective warning: the two founders faced AOL, Netscape, Microsoft, and broadcasters; later platform success does not remove the original survival risk. Digital Riptide, Yahoo discussion
- Google — researcher-applied illustration: superior search and reported 50% monthly traffic growth supported investment, while monetization, distribution, and the KPCB/Sequoia check split remained unknown. Google announcement
- POPSUGAR — documented application, retrospective: Moritz describes imagining upside while entering business with people barely known; the later mobile delay supplies a non-inevitable path. Stanford transcript, PDF pp. 1–4
- Getir — boundary case: public attribution and later outcome routes remain too incomplete for a clean decision reconstruction, demonstrating that a famous association is not evidence. Sequoia Getir page
- Evidence — Digital Riptide supplies the stated rule; Google supplies contemporaneous facts; Stanford supplies a separate direct formulation and founder countervoice; the DOJ transcript provides independent discussion of early-stage uncertainty and outlier economics. DOJ transcript, fireside-chat section
- Limits, failure modes, and exception ledger — Teams can fabricate balanced memos after deciding, overfit kill criteria, or treat unknowns as harmless. Public records favor winners and do not show whether Moritz used this method prospectively. Full Yahoo/Google IC memos, pass logs, and ordinary-deal comparisons were searched but not found.
- Evolution and contradictions — The 2013 company-level warning coexists with the 2016 claim that exceptional investment decisions sustain Sequoia. Humility language is credible only if current partner and governance records remain open to disconfirmation. YC transcript, performance and renewal sections
- Modern VC translation (as of 2026-08-22) — [researcher inference · strong] Version the IC memo, lock decision-date sources, record base/upside/downside probabilities separately from conviction rhetoric, and audit calibration annually. Likely misuse: treating “uncertain” as a shield from falsifiable forecasts.
Test obsession through product and customer evidence
- Rule — Treat founder obsession as a hypothesis verified by product specificity, user knowledge, sustained execution, and behavior under bad news—not by charisma, hours, demographic familiarity, or self-description.
- Evidence status — [investor-stated · strong] for product purpose/user connection/obsession; [researcher inference · moderate] for the anti-bias operational test.
- Provenance and origin — Stanford’s January 2016 transcript records Moritz describing successful founders as deeply connected to the product and audience and able to shut out distraction. At 08:41–09:31 of Money Maze he restates the screen as unusual subject depth that educates the investor, clear command and communication, and sustained hunger to make the product real. Stanford transcript, PDF pp. 1–2 Money Maze episode/audio
- Mechanism and reasoning — Deep product attention can accelerate learning where data are scarce, but observable customer knowledge is the discriminating signal. Hours and intensity are noisy proxies that can reward performance theater, overwork, or affinity bias.
- Historical and vehicle context — Sequoia’s brand gave access to ambitious founders, and Moritz’s public “standards” and China-hours comments later drew criticism. This makes process validity—not the slogan—central. Bloomberg video FT China column
- When to use — Use in founder references, product review, hiring, and follow-on assessment. Do not use when domain regulation, team health, or execution requires balanced delegation rather than monomania.
- How to apply it — Ask the founder to diagnose a user session, explain an unpopular trade-off, show product changes driven by evidence, and describe a failed assumption. Take references from subordinates, customers, and former collaborators. Kill if intensity produces no learning, ethics failures, chronic team loss, or fabricated customer claims.
- Examples —
- POPSUGAR — documented application: Lisa Sugar described writing daily, seeing unknown audiences grow, and maintaining product/editorial involvement; Moritz tied investment to founder purpose and audience connection. Stanford transcript, PDF pp. 1–3
- Zappos — researcher-applied illustration: Tony Hsieh’s returning relationship mattered, but the investment waited for customer and operating evidence; person belief alone did not close the case. Zappos oral history
- Yahoo — researcher-applied illustration: founders maintained and expanded a narrow service despite powerful incumbents; direct product/user data at decision date remain incomplete. Digital Riptide, Yahoo
- Women-partner/China-hours controversies — counterexample: candidate “standards” and extreme hours can embed pipeline, welfare, and cultural assumptions rather than identify output. Vanity Fair TechCrunch
- Evidence — Stanford supplies direct rule and founder countervoice; Zappos supplies a multi-witness behavior case; Riptide supplies independent founder/product uncertainty; original/critical controversy routes expose the model’s most important misuse.
- Limits, failure modes, and exception ledger — Obsession can coexist with poor judgment, misconduct, or a tiny market. References are selected; customer enthusiasm can be subsidized. No complete founder-scorecard or rejected-founder denominator was found. The 2015 and 2018 records prevent treating intensity as a universal rule.
- Evolution and contradictions — Founder obsession in 2016 sits uneasily beside a 2018 hours comparison. The reconcilable version measures learning and product focus; the irreconcilable version treats work regimen or demographic pipeline as quality.
- Modern VC translation (as of 2026-08-22) — [researcher inference · strong] Score evidence of learning, product judgment, ethics, and sustainable recruiting separately. A current analyst should blind parts of references and record pipeline conversion by stage. Likely misuse: celebrating burnout or culturally familiar aggression as commitment.
Turn scars into questions, not prohibitions
- Rule — Convert each failure into explicit diligence questions and reversal evidence; do not convert category pain into a permanent veto.
- Evidence status — [retrospective witness · strong] for the Zappos sequence; [researcher inference · moderate] as a general model because no formal Sequoia rule or complete failure set is public.
- Provenance and origin — The Sequoia Zappos oral history recounts Webvan, eToys, and PlanetRx wounds, repeated Zappos passes, and a 2004 reversal after customer/operating evidence improved. Zappos oral history, Moritz/Lin sections
- Mechanism and reasoning — Failure exposes which variables mattered: returns, inventory, cash flow, geography, financing, governance. Turning those into thresholds preserves learning while allowing changed business models and evidence to reverse the prior.
- Historical and vehicle context — The dot-com crash made ecommerce financing and inventory risk salient. Sequoia’s capacity to revisit a company over several years was an institutional advantage; the public record lacks check, reserve, and opportunity-cost data.
- When to use — Use after a write-off, missed milestone, sector crash, fraud, or pass later challenged by new evidence. Do not reverse merely because the market reheats or a founder persists.
- How to apply it — Write the prior failure’s causal map; distinguish structural from execution causes; turn each into a metric; predefine reversal thresholds; rerun the IC with new data; assign a smaller check or staged milestone if uncertainty remains. Kill if the new company reproduces the causal failure without compensation.
- Examples —
- Zappos — documented application: visible availability and delivery evidence answered some ecommerce concerns and changed the decision after repeated passes. Zappos oral history, 2004 decision
- PayPal runway — retrospective witness illustration: a later Team Sequoia/Botha account attributes to Moritz an instruction to extend runway and prove business-model discipline; no contemporaneous memo was found. Adapting to Endure, PayPal slide
- Green Dot — boundary/counterexample: long tenure and performance became a proxy-fight dispute; issuer and dissident records disagree, so reputation cannot substitute for a current update test. Harvest deck Moritz letter
- Klarna — current researcher-applied test: new capital purchases may signal conviction, while governance conflict and a pending complaint require fresh disclosure/risk evidence; neither price nor allegations settle the thesis. Klarna Form 3 Nayak docket
- Evidence — Zappos provides the central multi-witness chain; PayPal provides a separate cash-survival account; Green Dot provides opposing interested filings; Klarna supplies current issuer/court controls.
- Limits, failure modes, and exception ledger — Survivors narrate scars more often than unrepaired failures. Teams can redefine thresholds after the outcome. Webvan/eToys/PlanetRx checks, losses, warning timelines, and stop decisions were not publicly recovered, so the causal map is incomplete.
- Evolution and contradictions — The model moves from dot-com category pain to a broader “yesterday is irrelevant” institutional rule. Yet renewal without memory repeats mistakes, while memory without reversal fossilizes them.
- Modern VC translation (as of 2026-08-22) — [researcher inference · strong] Maintain a failure register with causal variables, evidence owners, and expiration/reversal conditions. For a hypothetical delivery startup, test contribution after refunds, density, working capital, and financing rather than applying a generic “delivery failed” label. Likely misuse: “learning” as permission to re-enter without changed evidence.
Make governance concrete and preserve founder ownership
- Rule — Define board work as specific recruiting, financing, product, leadership, compliance, or succession actions while preserving that founders and operators own the company and most value creation.
- Evidence status — [documented behavior · strong] for selected LinkExchange, Zappos, and POPSUGAR actions; [researcher inference · moderate] as a portfolio-wide model.
- Provenance and origin — The LinkExchange/Zappos oral history records interim operating help and recruiting; Stanford records Lisa Sugar’s description of advice/recruiting and Moritz’s insistence that POPSUGAR was the founders’ company. Zappos Stanford transcript, PDF pp. 2 and 4
- Mechanism and reasoning — Young companies may lack networks, financing credibility, and management experience. A board member can close those gaps, but vague involvement creates control without accountability and retrospective credit inflation.
- Historical and vehicle context — Meaningful fund ownership and board rights can align support with long-duration outcomes; partnership and fiduciary obligations also constrain intervention. Public records show roles, not full board minutes or causal effect.
- When to use — Use when a company needs a named executive, financing plan, strategic update, compliance control, or leadership decision. Do not intervene to satisfy investor ego or substitute for founder product judgment.
- How to apply it — Agree on the problem with founders; name the action owner; set a deadline and success metric; record conflicts and decision rights; review whether the help changed evidence; step back when complete. Kill or escalate only under pre-agreed fiduciary, ethical, runway, or leadership thresholds.
- Examples —
- LinkExchange — documented application: Moritz temporarily acted as CEO, mentored employees, and worked to recruit a permanent leader; Microsoft later acquired the company. Zappos oral history, LinkExchange sections
- Zappos — documented application: Moritz helped recruit directors and reassure banks; Lin attributes cohort and Kiva work to Botha, preserving team roles. Zappos oral history, governance sections
- POPSUGAR — documented application: Lisa Sugar describes between-meeting advice, recruiting, introductions, and mobile pressure; Moritz gives founders the credit. Stanford transcript, PDF pp. 2 and 4
- Green Dot/Klarna — counterexamples: proxy conflict and boardroom dispute show long tenure and active influence can be interpreted as value or entrenchment; pending litigation adds disclosure scrutiny without a merits finding. Green Dot opposing filings FT Klarna report
- Evidence — Two independent multi-party accounts support concrete actions; SEC-filed opposing records and current court/issuer routes test the favorable story. Board appointments alone are not counted as application evidence.
- Limits, failure modes, and exception ledger — Founder gratitude and firm histories are selected; an intervention can correlate with outcome without causing it. Board work can become shadow management, founder dependency, or entrenchment. Private minutes, recusal records, and failed-founder accounts were not recovered.
- Evolution and contradictions — Moritz’s LinkExchange intensity and later founder-credit language can coexist if intervention is temporary and role-specific. Green Dot and Klarna show why duration, nomination/removal rights, and independent metrics must be explicit.
- Modern VC translation (as of 2026-08-22) — [researcher inference · moderate] Keep a board-action ledger with owner, founder consent, fiduciary basis, outcome, and expiration. Add regulatory/compliance expertise for fintech and AI. Likely misuse: counting introductions or board attendance as value creation.
Treat yesterday as irrelevant evidence
- Rule — Re-underwrite every partner, thesis, market, and portfolio reserve from current forward evidence; preserve history as data, never as entitlement.
- Evidence status — [investor-stated · strong] for partnership renewal; [documented behavior · moderate] across geography, mobile adaptation, and succession.
- Provenance and origin — Moritz’s February 2016 YC transcript explicitly frames past successes as irrelevant to the future and calls for continuous team refresh. YC, “Yesterday is irrelevant” and “Maintain a fresh team”
- Mechanism and reasoning — Markets and people change. Laurels create confirmation bias; current contribution and new capabilities preserve adaptive capacity. Yet history contains causal lessons and trust, so the rule is prospective re-underwriting, not erasure.
- Historical and vehicle context — Multi-generational partnerships face key-person, carry, brand, geography, and succession problems absent from a solo account. Moritz led Sequoia for years and later transitioned; internal economics remain private. Official publisher biography Klarna leadership
- When to use — Use in annual partner reviews, reserve decisions, thesis updates, geographic structures, and board succession. Do not use to discard legal obligations, institutional memory, or earned founder trust.
- How to apply it — Remove company logos from evaluation; list forward contribution; compare required versus current capabilities; define transition support; audit conflicts and economics; record what memory must transfer; set review dates. Kill a role/thesis only after evidence and a governed transition process.
- Examples —
- Sequoia team — documented doctrine: Moritz advocates organic younger hires and objective present-performance review. YC transcript, “Maintain a fresh team”
- China franchise and separation — documented behavior/boundary: in 2016 Moritz credited local people; a 2023 Team Sequoia essay says five units chose independence. YC, “Change with the market” Sequoia, “Crucible Moments”
- POPSUGAR mobile — documented application: Moritz pushed attention to mobile after a delayed adaptation; company success did not remove distribution risk. Stanford transcript, PDF pp. 2 and 4
- Green Dot — counterexample: dissident allegations that tenure had become stale and issuer defenses of current contribution show why forward evidence must be independently measurable. Harvest deck Issuer defense
- Evidence — YC provides the direct rule; Stanford provides a company application; Sequoia’s 2023 essay provides institutional change; SEC proxy materials provide an adverse test across independent source families.
- Limits, failure modes, and exception ledger — “Clinical” renewal can rationalize opaque power, discrimination, or loss of trust. Annual performance may be noisy in power-law portfolios. Full partner evaluation, carry, transition, and dissent records were not public.
- Evolution and contradictions — Moritz’s renewal doctrine is consistent from Leading-era discussion through 2016, but geography separation and Klarna conflict show renewal is contested rather than mechanical. The 2015 women-partner remarks challenge whether “standards” were sufficiently validated.
- Modern VC translation (as of 2026-08-22) — [researcher inference · strong] Use forward role scorecards, independent pipeline audits, explicit succession economics, and a written memory-transfer plan. Likely misuse: weaponizing “renewal” against dissenters or underrepresented candidates without validating criteria.
Credit the actual partner, team, and vehicle
- Rule — Before extracting a lesson or return, identify source, sponsor, diligence, approval, security-owning entity, board/operating work, follow-on, exit, and later narrator; leave unknown fields unknown.
- Evidence status — [contemporaneous record · strong] for entity/board facts; [researcher inference · strong] for the reusable role ledger.
- Provenance and origin — Google’s 1999 announcement names a joint KPCB/Sequoia round and two directors; its 2004 S-1 itemizes Sequoia vehicles. PayPal’s S-1/A separates the share seller, buyer entities, board role, and ownership. Google release Google S-1, printed pp. 84–85 PayPal S-1/A
- Mechanism and reasoning — Role separation prevents fund ownership from becoming personal return, board service from becoming sourcing, and institutional storytelling from becoming lone-investor causality. Accurate attribution also improves internal learning because the team knows which action actually mattered.
- Historical and vehicle context — Sequoia used multiple funds, principals/international/growth entities, shared managers, local teams, and later associated capital. Beneficial-ownership disclaimers and pecuniary-interest language are legal fields, not narrative decoration.
- When to use — Use for every deal memo, portfolio review, public biography, compensation decision, and case study. Do not collapse roles merely because one partner is famous or tells the story.
- How to apply it — Create nine columns before writing prose; attach dated source/locator to each; map legal entity and security; separate primary from secondary cash; identify unknown vote and carry; compare founder/partner accounts; forbid return calculations without cash flows.
- Examples —
- Google — documented application: joint $25 million aggregate round; Moritz and Doerr boards; 23,893,800 Sequoia shares in the April 2004 table across five vehicles; firm split and cash return unknown. Google release Google S-1, printed pp. 84–85
- PayPal — documented application: $5 million bought 15 million Series A shares from Musk, so cash went to a seller; Moritz’s board role and Sequoia entities remain separate. PayPal S-1/A, “Certain Transactions” and principal stockholders
- Stripe — direct-witness boundary: Moritz recalls first meeting Patrick Collison and the initial simplify-PayPal/global-ecommerce propositions; the transcript supplies no sourcing, vote, security, ownership, partner-role, or return evidence. Money Maze, 10:18–12:05
- Instacart — documented team boundary: Sequoia lists Moritz, Alfred Lin, Ravi Gupta, and James Flynn; a later “Moritz-led” story does not erase the roster. Sequoia Instacart page Fidji Simo profile
- YouTube — counterexample: the official Sequoia company page, “Partner” field attributes the investment to Roelof Botha, so the company is excluded from the Moritz-led ledger despite loose firm-level association.
- Klarna — current application: Form 3 separates 3,472,845 ordinary shares held indirectly through Crankstart Foundation from 37,500 directly held RSUs; Sequoia voting holdings are a third category. Klarna Form 3, PDF p. 1
- Evidence — Independent issuer filings, company announcements, firm rosters, and multi-witness histories establish the role problem across more than three companies. The deal role matrix records unknowns rather than allocating fame.
- Limits, failure modes, and exception ledger — Legal filings may aggregate shared control; firm pages are curated and can change; internal sourcing and vote records remain private. Role ledgers can become political scorekeeping. No public source supplies Moritz’s personal carry or a complete attribution denominator.
- Evolution and contradictions — Moritz publicly redirects praise to Sequoia and founders, yet press and retrospective formats repeatedly recenter a famous individual. Later team and associated-vehicle complexity makes the rule more necessary, not less.
- Modern VC translation (as of 2026-08-22) — [researcher inference · strong] Put role fields and entity/security fields in the IC system, require co-owner confirmation, and publish attribution with uncertainty. Likely misuse: counting introductions or titles while ignoring founder execution and legal ownership.
Evidence gaps and candidate models
Model inventory reconciliation
Signals were reconciled across all twenty-six notes, writings.md, talks.md, investments.md, and the index in investmentphilosophy.md. “Narrow wedge” and “platform later” were merged; “uncertainty,” “knife edge,” and “no hindsight” were merged; founder purpose and obsession were kept together; renewal and role attribution remain distinct because one governs updating and the other credit.
Plausible exclusions
- Patience/capital efficiency as a separate model — “Profitable Unicorn” supports the belief, but public cases do not supply three distinct Moritz-connected applications with cash-flow and ownership evidence. It remains a lesson in writings.md, not a completed model.
- Follow your instincts — directly stated in a life-advice context, but no operational threshold distinguishes trained judgment from bias across three deals.
- Globalize early — local-team credit and China expansion are documented, but later partnership separation and missing regional economics prevent a stable decision rule.
- Extreme work intensity — excluded as an operative model because hours are not validated output and the public argument has serious legal, health, family, bargaining-power, and cultural boundary failures.
- Buy the best regardless of price — insufficient public record; no complete Moritz price/ownership/return set supports it.
- AI winner concentration — Money Maze records a dated 2026 forecast that one or two dominant companies may capture most value, but it provides no selection, sizing, reserve, probability, or three-case application record. Track it prospectively rather than promoting it to a model.
- Long-horizon compounding without inexhaustible patience — Money Maze at 24:42–27:34 now supplies a direct current preference and an explicit refusal to disclose Heritage specifics; the 2015 essay adds a second first-person placement. Three reconstructed Moritz cases, vehicle-consistent cash flows, ownership, sell rules, and performance evidence still do not exist, so this remains a candidate rather than a twelve-field model.
Attempted-route ledger
The source run checked official books/publishers; FT and LinkedIn; Stanford, YC, Oxford, Charlie Rose, Digital Riptide, DOJ, Visionaries Club, Money Maze, and YouTube; Sequoia histories; SEC filings; court dockets; criticism; succession; and geography. Books/FT remain partial and Charlie Rose lacks stable locators; Money Maze is complete through the OpenAI Audio API. These are exact access limits, not evidence waivers. Any future model must satisfy the same three-case, four-placement, two-independent-source bar.
What the evidence supports
The package supports a bounded conclusion: Michael Moritz was a material Sequoia steward and documented board/sponsor in selected companies; his direct record consistently emphasizes early uncertainty, narrow product evidence, founder purpose, practical governance, and partnership renewal. A processed 2026 Money Maze interview adds a current founder screen, long-duration cash-compounder preference, and qualitative AI concentration forecast without supplying transaction economics or personal alpha. Digital Riptide, Yahoo/Google and knife-edge passages YC, renewal sections Stanford, PDF pp. 1–4 Money Maze episode/audio
Primary records establish a joint Google round and dated Sequoia entity block, a PayPal secondary share purchase and board condition, Yahoo/Green Dot/Klarna governance facts, and distinct current Klarna ownership categories. Google release Google S-1, printed pp. 84–85 PayPal S-1/A, “Certain Transactions” Klarna Form 3, PDF p. 1
The favorable edge thesis is [researcher inference · moderate], not measured personal alpha. The repeatable object is a decision process: preserve uncertainty, test a product wedge and founder behavior, update after contrary evidence, perform concrete governance work, and renew the institution. Public data do not establish that Moritz alone sourced or approved each company, generated superior access-adjusted returns, or personally owned the disclosed fund stakes.
What could falsify the thesis
The edge thesis would weaken or fail if:
- complete IC records show reputation or category heat driving decisions more often than product/user evidence;
- ordinary and failed deals do not show the same update behavior visible in selected Yahoo/Google/Zappos stories;
- partner-role records assign sourcing, diligence, approval, and company work primarily to others while later narration recenters Moritz;
- complete fund cash flows show that Google or another outlier explains nearly all performance and the ex-outlier record is ordinary;
- access-matched peers perform similarly without the proposed process;
- founder/employee records show board intervention caused dependence, entrenchment, or harm more often than measurable help;
- partnership records show renewal rhetoric masking opaque, biased, or poorly governed succession.
The strongest skeptical case remains viable: a privileged seat in Sequoia, brand access, fund duration, founder execution, local teams, other partners, favorable technology regimes, and survivorship may explain more than personal selection skill. The 2015 gender remarks, 2018 work-intensity prescription, 2023 geographic separation, 2024 Klarna dispute, and pending Nayak complaint prevent a frictionless institution/governance story. Vanity Fair TechCrunch Team Sequoia, “Crucible Moments” FT Klarna report Nayak docket
Attribution and denominator audit
The scoped route set is mechanically reproducible:
| State | Audited count | Result |
|---|---|---|
| Named candidates | 21 | Yahoo, Google, PayPal, LinkExchange, Zappos, Webvan, eToys, PlanetRx, POPSUGAR, Saba, Green Dot, Kayak, LinkedIn, Flextronics, Stripe, Instacart, Klarna, Getir, Netezza, Ikanos, YouTube |
| Searched | 21 | Each has a filing, official page/history, transcript, or attribution route |
| Included | 20 | YouTube excluded from Moritz credit because official attribution belongs to Roelof Botha |
| Researched | 20 | At least one claim-supporting public route reviewed |
| Sufficiently reconstructed | 7 | Yahoo, Google, PayPal, LinkExchange, Zappos, Green Dot, Klarna |
| Unresolved | 13 | Included companies without sufficient original thesis, role, economics, or failure/exit evidence |
| Excluded | 1 | YouTube |
Thus route research is 20/20 and deep reconstruction is 7/20 = 35.0% of the scoped named set. Career-portfolio coverage is not computable because all investments, passes, write-offs, follow-ons, and vehicles are unknown. Deal evidence boundary
The role audit rejects six common errors:
- Google’s aggregate $25 million joint round is not split between Sequoia and KPCB. Google release
- The April 2004 Google table reports 23,893,800 Sequoia shares across five vehicles; it is not Moritz personal ownership or a return. Google S-1, printed pp. 84–85
- PayPal’s $5 million record is a purchase of 15 million Series A shares from Elon Musk, not $5 million of company financing. PayPal S-1/A, “Certain Transactions”
- Instacart’s official roster is multi-partner; YouTube belongs to Botha; Adapting to Endure is Team Sequoia/Botha rather than Moritz authorship. Instacart page Adapting to Endure
- Klarna’s Form 3 separates Crankstart’s 3,472,845 indirectly held ordinary shares from Moritz’s 37,500 directly held RSUs and from Sequoia holdings. Klarna Form 3, PDF p. 1
- Money Maze proves an initial Moritz–Patrick Collison conversation and remembered Stripe product framing, not sourcing, approval, check, security, entity, ownership, other partner roles, or return. Money Maze, 10:18–12:05
Adverse-evidence and disposition audit
| Matter | Evidence | Correct disposition |
|---|---|---|
| 2015 women-partner remarks | Original Bloomberg video plus contemporary criticism | Direct remark and criticism; no causal hiring finding |
| 2018 China/work-intensity thesis | Moritz FT column plus TechCrunch/VentureBeat counterarguments | Normative view with contested output/welfare/legal assumptions |
| Green Dot proxy fight | Dissident deck, Moritz letter, issuer defense | Interested opposing claims; no adjudicated causal verdict |
| Sequoia geography | 2023 Team Sequoia essay | Firm says five units chose independent partnerships; Moritz’s personal role unknown |
| Klarna board dispute | FT reporting plus issuer/filing records | Reported governance conflict; no misconduct adjudication |
| Nayak v. Klarna | Complaint and live docket | Pending Securities Act allegations only; no merits judgment, class certification, or liability finding identified through May 8, 2026 |
The review neither omits allegations nor converts them into facts. Nayak complaint, Document 1 Docket
Transfer limits for modern VCs
The models transfer as procedures, not personality worship:
- preserve decision-date sources and symmetric failure cases;
- measure product/customer learning rather than founder performance theater;
- turn prior losses into explicit reversal thresholds;
- define governance actions, owners, consent, and expiration;
- re-underwrite roles prospectively while preserving institutional memory;
- store partner, vehicle, security, and cash-recipient attribution separately.
They do not transfer as “work longer,” “follow instinct,” “use the Sequoia network,” or “hold forever.” Current fund duration, market, technology, regulation, ownership, and competition must be validated for the actual decision. Every 2026 translation in the package is labeled researcher inference or hypothetical where it lacks a documented current Moritz application.
Audio-transcription and spot-check audit
The 63,294,825-byte official MP3 exceeded OpenAI's 25 MB file limit. The successful path split the original losslessly into eight 480-second chunks and one 87.14-second tail, then submitted all nine to gpt-4o-transcribe-diarize with diarized JSON and automatic chunking. All returned HTTP 200; 701 segments cover 00:00.27–65:26.33 after deterministic offsets. The failed whole-file response was excluded. Method ledger
Five source-audio windows—founder criteria, uncertainty training, compounding, AI concentration, and writing revision—were independently re-transcribed with gpt-transcribe. Each confirmed the retained paraphrase and corrected noisy names/segment splits. No exact quotation depends on unverified ASR, no local or non-OpenAI recognizer was used, and the full machine transcript is not committed.
Unresolved evidence
- Licensed full text/page locators for the Apple books, Going for Broke, Leading, Ausländer, and priority FT bodies.
- Stable Charlie Rose transcript locators.
- Complete Sequoia opportunity/pass/write-off/fund cash-flow and partner-role ledgers.
- Google/Yahoo/PayPal entry economics, dilution, distributions, and IC records.
- Full Webvan/eToys/PlanetRx theses, warning timelines, follow-ons, stop decisions, and losses.
- Green Dot independent causal resolution and complete Klarna governance/disclosure disposition.
These gaps limit claims but do not justify filler. If licensed archives or primary decision records become available, affected access-bounded rows must be reopened rather than silently treated as analyzed.
Central high-risk claim audit
| # | Claim audited | Document/section | Source and locator | Result |
|---|---|---|---|---|
| C1 | Proposed edge is process, not measured alpha | _profile.md, Falsifiable thesis | Riptide; Stanford; YC; denominator table | PASS — inference/moderate retained |
| C2 | Google round was joint $25m with no firm split | investments.md, Google case | Google 1999 announcement, financing/board paragraphs | PASS |
| C3 | April 2004 Google table = 23,893,800 shares, five vehicles | investments.md, Pareto/Google case | Google S-1, printed pp. 84–85, footnote 3 | CORRECTED — stale later-table figures removed |
| C4 | PayPal $5m was secondary purchase from Musk | investments.md, PayPal case | PayPal S-1/A, “Certain Transactions” | PASS |
| C5 | Zappos roles are Moritz/Lin/Botha/team, not solo | investments.md, Zappos | Sequoia named-speaker sections | PASS — retrospective label retained |
| C6 | Scoped denominator reconciles 21/20/7/13/1 | investments.md, Mechanical reconciliation | Registry, S30 and ledger recount | CORRECTED — 7/20 = 35.0% |
| C7 | No literal 80/20 or personal return | investments.md, Pareto | Missing cash-flow/complete-denominator fields | PASS — not computable |
| C8 | Klarna ownership categories are distinct | investments.md, Klarna | Form 3 PDF p. 1, Tables I–II, footnotes 1–2 | CORRECTED — Crankstart/direct RSU wording explicit |
| C9 | Nayak is pending allegations, not liability | _profile.md, Klarna | Docket through May 8, 2026; complaint counts | PASS |
| C10 | FT stream = 63 cards, 36 conservative authored, 27 excluded | writings.md, FT stream | Three-page card ledger, dated 2026-08-22 | PASS after mechanical expansion |
| C11 | Talk denominator = 10, eight ★★★ + two ★★ | talks.md, Coverage | sources S21–S30 | CORRECTED |
| C12 | Comparators are completed peers only | investmentphilosophy.md, §15 | Live index: Doug Leone 033, Andy Rachleff 031, Scott Sandell 041 complete | CORRECTED — queued peers removed |
| C13 | Stripe direct witness does not become sole-credit/economics evidence | investments.md, scoped ledger | Money Maze 10:18–12:05; attribution note | CORRECTED — unresolved route added; economic rank unchanged |
| C14 | Heritage compounding and AI power-law claims remain bounded | investmentphilosophy.md, §§6 and 8 | Money Maze 24:42–30:35 | PASS — vehicle preference and dated forecast; no holdings/performance/math inferred |
Ordinary-claim citation audit
Selection rule: take the first externally checkable factual claim after the second substantive H2 in each of the seven core synthesis documents, then add the second claim from investments, philosophy, and mental models to reach ten. This avoids choosing only famous claims.
| # | Claim/document | Source/locator reopened | Result |
|---|---|---|---|
| O1 | Moritz identifies emigration and Sequoia hire as consequential — _profile.md | Stanford transcript, PDF p. 1 | PASS |
| O2 | Publisher records Cardiff 1954, FT/TIME, tenure, Crankstart — writings.md | Publisher “About The Author” | PASS; promotional superlative excluded |
| O3 | Oxford route duration/date — talks.md | Oxford official metadata | PASS; no unvalidated quote |
| O4 | Google’s release reported word-of-mouth/Stanford research — investments.md | Google 1999 company description | PASS |
| O5 | Flextronics board span 1993–2005 — investments.md | Issuer-filed retirement release | PASS; board not sourcing |
| O6 | Moritz direct philosophy begins with early uncertainty — investmentphilosophy.md | Digital Riptide founder-selection passage | PASS |
| O7 | Google/PayPal ownership blocks are entities, not personal returns — investmentphilosophy.md | Google S-1 pp. 84–85; PayPal principal stockholders | PASS |
| O8 | Platform is a later state of a narrow offering — mental-models.md | Digital Riptide platform passage | PASS; model scope narrowed |
| O9 | Google example uses 23,893,800 and five vehicles — mental-models.md | Google S-1 pp. 84–85, footnote 3 | PASS |
| O10 | Money Maze founder hallmarks — talks.md | OpenAI transcript 08:41–09:31 plus independent gpt-transcribe spot check | PASS — paraphrase retained; no noisy exact quote |
Cross-checks of six material deal/team attributions were also reopened: Google (company release + S-1), PayPal (S-1/A + later Team Sequoia account), Zappos (multi-witness history), Stripe (direct witness plus explicit missing transaction fields), Instacart (firm roster + issuer S-1), and Klarna (issuer attribution + 20-F/Form 3). No sole-person economics claim survived.
Twenty-point acceptance evidence
| # | Requirement | Evidence inspected | Result/correction |
|---|---|---|---|
| 1 | Deep chronological biography | _profile.md, formation through 2026 chronology | PASS — causal inferences labeled |
| 2 | Falsifiable edge | Profile and philosophy §1 | PASS — mechanism, predictions, falsifiers, skeptic, denominator |
| 3 | Ex-ante reconstruction | Yahoo, Google, PayPal, Zappos freezes/labs | PASS — known/unknown/believed/disputed before outcomes |
| 4 | Three Pareto views | investments.md opening | PASS — directional; literal contribution not computed |
| 5 | No placeholders/premature completion | All eight root docs inspected | PASS — substantive H2 follows every H1 |
| 6 | Searched denominator | 21/20/7/13/1 table, inclusion/dedup rules | PASS — scoped fractions named; career not computable |
| 7 | Comprehensive writings | 10 priority rows; 15 evidence notes; FT card ledger | PASS, access-bounded — one full work, exact partial/metadata limits |
| 8 | Detailed mental models | Seven models, twelve bullets each, 3+ cases, 4+ placements, 2+ sources | PASS — exclusions and attempted routes disclosed |
| 9 | Dated modern translation | Writings, philosophy §14, every model | PASS — 2026-08-22; hypothetical/researcher labels |
| 10 | Failure postmortems | Webvan/eToys/PlanetRx table and lab; Green Dot/Klarna adverse cases | PASS within exhausted record — missing original fields explicit |
| 11 | Team/decision attribution | Profile people map; deals role matrix/ledger | PASS — unknown roles preserved |
| 12 | Vehicle economics/incentives | Deal entity matrix; philosophy §6 | PASS — personal economics never inferred |
| 13 | Historical context/base rates | Deals historical table; philosophy §13 | PASS — qualitative where numerical series absent |
| 14 | Direct voice/archive exhaustion | 85 rows/83 unique URLs; 22 checked/63 open; 26 notes; all 10 priority talks represented (6 deeply analyzed, 4 access-bounded) | PASS — S30 processed through nine OpenAI diarized chunks (701 segments) and five independent gpt-transcribe audio spot checks; no local/non-OpenAI substitute or long transcript committed |
| 15 | Pinpoint citations | Central and ordinary audit tables | PASS — section/page/table/heading or no-stable-locator boundary |
| 16 | Two-axis labels | Writings/talks/deals/synth spot and central audit | PASS after labels added to cross-source rules |
| 17 | Strongest case against | Profile, philosophy §16, this review | PASS — access, team, vehicle, outlier, survivorship, culture, legal |
| 18 | Completed peers | Philosophy §15 | PASS — Leone, Rachleff, Sandell verified complete |
| 19 | IC exercises | Four signature cases plus failure/miss and governance labs | PASS — invest/pass, kill, terms, next check before outcome |
| 20 | Learning architecture | Profile path, glossary, checklists, cross-links, people/capital maps | PASS — Markdown-native, no bespoke component required |
Acceptance conclusion. All twenty rows pass after S30 transcription, five independent OpenAI audio spot checks, and reconciliation across source accounting, talks, deals, biography, writings, philosophy, mental models, and attribution controls. The package remains evidence-bounded: 20/20 is acceptance of the research process and learning architecture, not proof of personal alpha or source completeness.
Authored books, essays, columns, and direct written record
- ★★★ | S01 Michael Moritz — official publisher biography and authorship index | https://www.simonandschuster.com/authors/Michael-Moritz/262020703 | current; accessed 2026-08-22 | publisher biography; reliability A for publisher-held metadata, B for promotional superlatives; access full | Identity, 1954 Cardiff origin, 35-year Sequoia tenure, 1995–2012 leadership claim, Crankstart, and book route.
- ★★★ | S02 The Little Kingdom: The Private Story of Apple Computer | https://books.google.com/books?vid=ISBN9780688039738 | 1984 | book/catalog-preview route; reliability A for authored text, B for remembered scenes; access partial | Earliest long-form evidence of Moritz's reporting craft; original edition must not be silently merged with the 2009 revision.
- ★★★ | S03 Return to the Little Kingdom: Steve Jobs, the Creation of Apple, and How It Changed the World | https://books.google.com/books?q=%22Return+to+the+Little+Kingdom%22+%22Michael+Moritz%22 | 2009 | revised-book discovery/preview route; reliability A for accessible authored text, C for snippets; access partial | Later reworking and prologue; compare edition-level chronology and changed interpretation.
- ★★ | S04 Going for Broke: The Chrysler Story | https://search.worldcat.org/title/going-for-broke-the-chrysler-story/oclc/7460014 | 1981 first edition | coauthored book catalog; reliability A for bibliographic metadata, content unavailable; access metadata only | Reporting apprenticeship in a troubled company; do not confuse the 1981 first edition with the 1984 Anchor subtitle/date.
- ★★★ | S05 Leading: Learning from Life and My Years at Manchester United | https://www.hachettebookgroup.com/titles/alex-ferguson/leading/9780316268103/ | 2015 original; US paperback page dated 2016 | coauthored book/publisher description; reliability A for authorship and edition metadata; access partial | Leadership, renewal, standards, listening, and succession; Ferguson's experience and Moritz's synthesis require separate attribution.
- ★★★ | S06 Ausländer: One Family's Story of Escape and Exile | https://www.simonandschuster.com/books/Auslander/Michael-Moritz/9798897101924 | UK publication reported 2026; US publisher page says 2026-09-01 | memoir/publisher record; reliability A for authorship and US metadata; access partial | Family/refugee history and late-life worldview; publication-date and market-edition differences are explicit.
- ★★★ | S07 Michael Moritz — Financial Times author/topic stream | https://www.ft.com/stream/2f2708a5-f7e1-4ef8-87a2-65e89ea14685 | 2007–2026 across three visible pages; accessed 2026-08-22 | mixed author/topic index; reliability A for bylines/dates shown, not a clean corpus denominator; access partial | Exact live sweep found 63 cards (25 + 25 + 13): 36 conservatively classified as Moritz-authored from a visible byline/deck and 27 excluded as reporting, reviews, compilations, third-party work, or byline-unresolved cards; see card ledger.
- ★★ | S08 The subprime 'unicorns' that do not look a billion dollars — origin trace | https://www.techmeme.com/151016/h2355 | 2015-10-16 | headline/origin index to paywalled FT column; reliability B for title/date, C for snippets; access partial | Public-versus-private scrutiny and fragile late-stage valuations; “gravity” phrasing belongs to the accompanying Bloomberg interview, not necessarily the column title.
- ★★ | S09 The Dawn of the Profitable Unicorn | https://www.linkedin.com/pulse/dawn-profitable-unicorn-michael-moritz | 2015-12-11 | Moritz-posted essay, noted as originally FT; reliability A for text/authorship; access full | Capital efficiency, patience, profits, and China competition; promotional examples need outcome checks.
- ★★ | S10 Silicon Valley would be wise to follow China's lead | https://www.ft.com/content/42daca9e-facc-11e7-9bfc-052cbba03425 | 2018-01-17/18 | FT opinion column; reliability A for Moritz's view; access partial/paywalled | Work-intensity thesis and a major public contradiction/criticism node; cannot be turned into a timeless productivity rule.
- ★ | S11 The business world can never go back to the way things were | https://www.ft.com/content/7e43172e-8d62-11ea-a8ec-961a33ba80aa | 2020-05-04 | FT opinion; reliability A for byline/thesis, access partial | Pandemic-era acceleration thesis; later outcomes must remain separate.
- ★ | S12 Business must set aside self-interest to battle extremism | https://www.ft.com/content/143c7577-5e6a-4804-92ce-4b58f25a59cb | 2021-01-12 | FT opinion; reliability A for byline/thesis, access partial | Family history used in a political warning; not investment-performance evidence.
- ★ | S13 The Lionel Messi saga is a lesson in how not to handle a prize asset | https://www.ft.com/content/bd11f9d3-2f11-4fd8-b54b-fd3d7019642f | 2021-08-16 | FT opinion; reliability A for view, access partial | Retention, compensation, and asset-management analogy; sports-to-venture translation is inference.
- ★ | S14 An online sales tax will further blight the high street | https://www.ft.com/content/9bc83a2b-8d3b-4a46-a9db-b6c667d109f3 | 2022-05-15 | FT opinion; reliability A for view, access partial | Tax/geography view; no direct deal rule without separate support.
- ★ | S15 Lyft wants a free ride from California's richest | https://www.ft.com/content/968a8e17-c98b-40bb-bdda-672019636f25 | 2022-10-11 | FT opinion; reliability A for view, access partial | California tax and corporate advocacy; distinguish policy opinion from board conduct.
- ★ | S16 San Francisco's drug and homeless crises can't go on | https://www.ft.com/content/ed059d9a-8a4c-4d4d-abf7-3692ad93f127 | 2023-02-08 | FT opinion; reliability A for view, access partial | Civic-governance critique; context for local philanthropy, not evidence of investment edge.
- ★ | S17 SVB provided for tech when everyone else ignored us | https://www.ft.com/content/e8926841-88ff-4cf5-8c45-4d1879f7ff4b | 2023-03-12 | FT opinion; reliability A for retrospective view, access partial | Venture-banking ecosystem argument after SVB's failure; interested retrospective.
- ★ | S18 Manchester United is a tarnished trophy asset | https://www.ft.com/content/2184e6d8-1bbc-4974-a2bc-436ad906166b | 2023-10-19 | FT opinion; reliability A for view, access partial | Governance, ownership, and institutional renewal analogy.
- ★ | S19 Silicon Valley's Trump supporters are making a big mistake | https://www.ft.com/content/14f0a270-5143-4c75-b1d0-fa302467d73f | 2024-08-05 | FT opinion; reliability A for byline/thesis, access partial | Political-institutional view and a late-career contrast with parts of the Valley.
- ★ | S20 Trump's H-1B visa caper will backfire | https://www.ft.com/content/9fc8f69e-52dc-4552-bcde-e39eb6b0df84 | 2025-09-24 | FT opinion; reliability A for byline/thesis, access partial | Immigration and talent thesis; current policy facts require date-bounded support.
Talks, interviews, oral histories, and audio/video
- ★★ | S21 Interview with Michael Moritz — Oxford Campaign | https://podcasts.ox.ac.uk/interview-michael-moritz | added 2008-09-16; duration 00:05:53 | official university audio/video; reliability A for direct voice, access full metadata/media | Education, philanthropy, and Oxford asset-management gift; limited venture detail.
- ★★★ | S22 Mike Moritz — Charlie Rose | https://charlierose.com/videos/17831 | 2013-02-15 | broadcast interview with transcript interface; reliability A for direct remarks; access partial because stable transcript locators were unavailable | Journey from journalism, venture selection, and firm durability; transcript interface must be checked before quoting.
- ★★★ | S23 Mike Moritz — Riptide | https://www.digitalriptide.org/person/mike-moritz/ | interview 2013-04-02 | full lightly edited transcript; reliability A for direct remarks, B for recalled chronology; access full | Best ex-ante/hindsight warning, Yahoo/Google media transition, technology judgment, and board perspective.
- ★★ | S24 An Interview with Michael Moritz — The King of All VCs | https://www.foundersspace.com/fund-raising/an-interview-with-michael-moritz-the-king-of-all-vcs/ | circa 2012 | embedded/direct interview page; reliability A/B; access partial | Founder-selection and board-role route; flattering title is not evidence.
- ★★★ | S25 Follow Your Instincts and Find Your Path — entire talk | https://stvp.stanford.edu/av/follow-your-instincts-and-find-your-path-entire-talk | event 2016-01-20; site route refreshed 2026 | official Stanford page/video plus previously processed Stanford transcript; reliability A for direct speech; access full video, former transcript-PDF URL now moved | Biography, consequential choices, instincts, founders, long-term institutions, and Lisa Sugar countervoice; citations preserve the processed transcript's page locators while resolving to the live official record.
- ★★★ | S26 Maintaining Success for the Long Term | https://www.ycombinator.com/blog/michael-moritz-sequoia-success | 2016-02-26 | YC-released transcript by Sam Altman; reliability A; access full | Sequoia renewal, internal competition, standards, motivation, and institutional survival.
- ★★★ | S27 Michael Moritz, Partner, Sequoia Capital — Stanford GSB | https://www.youtube.com/watch?v=ZTNFQeYEdvc | 2019-02-07 upload | official Stanford GSB video; reliability A for audio, C for automated caption text; access full video/partial transcript | Biography, refugee family, Manchester United analogy, and venture talent; no unvalidated machine-text quotes.
- ★★★ | S28 DOJ Public Workshop on Venture Capital and Antitrust — fireside chat | https://www.justice.gov/d9/pages/attachments/2020/03/04/public_workshop_on_venture_capital_and_antitrust_transcript_final_002.pdf | event 2020-02-12 | official transcript; reliability A; access full | Career entry, early-stage uncertainty, outlier returns, governance, exits, and antitrust context, with printed/PDF pages.
- ★★★ | S29 Conversation with Michael Moritz and Robert Lacher | https://aletteraday.substack.com/p/letter-134-michael-moritz-and-robert | conversation 2023; published 2023-10-31 | hosted transcript of Visionaries Club conversation; reliability A/B pending origin-video cross-check; access full | “Unexpected,” hiring, Sequoia Heritage formation, global technology, and reinvention.
- ★★★ | S30 From the Shadow of the Death Camps to Leading Sequoia — Money Maze | https://www.moneymazepodcast.com/podcast/michael-moritz | 2026-04-02 page metadata; episode page also renders 2026-04-09 | official episode/audio/show notes; reliability A for direct audio, B for machine wording and show-note paraphrase; access full audio plus OpenAI API diarized transcript | Nine contiguous transcript chunks, 701 segments and episode-level timestamps support current founder criteria, Stripe recollection, uncertainty training, terms, Europe, compounding, AI, capital allocation, and memoir; attribution/economics limits preserved.
- ★ | S31 Moritz says Sequoia looks hard for women partners, but won't lower standards | https://www.youtube.com/watch?v=1i-RXdi15Bg | 2015-12-03 | Bloomberg Originals video; reliability A for direct audio, C for machine captions; access video | Primary controversy evidence; contextualize full exchange and later response.
- ★ | S32 Seek Out Excellence — Stanford eCorner clip transcript | https://stvp.stanford.edu/wp-content/uploads/sites/3/2024/09/seek-out-excellence-transcript.pdf | event 2016-01-20 | official excerpt transcript; reliability A; access full | Clip-level locator into S25; not an independent appearance.
- ★ | S33 Following Instincts and Interests — Stanford eCorner clip transcript | https://stvp.stanford.edu/wp-content/uploads/sites/3/2024/09/following-instincts-and-interests-transcript.pdf | event 2016-01-20 | official excerpt transcript; reliability A; access full | Biographical excerpt from S25; do not count as independent source breadth.
- ★ | S34 Performance Trumps Social Media — Stanford eCorner clip transcript | https://stvp.stanford.edu/wp-content/uploads/sites/3/2024/09/performance-trumps-social-media-transcript.pdf | event 2016-01-20 | official excerpt transcript; reliability A; access full | Performance/reputation excerpt from S25; not independent.
- ★ | S35 Some unicorns will fall by the wayside — Times of India interview | https://timesofindia.indiatimes.com/tech-news/some-unicorns-will-fall-by-the-wayside-michael-moritz/articleshow/48243942.cms | 2015-07-28 | edited direct interview; reliability A/B; access full | Valuation cycles, India/China, gross margins, and uncertainty; contemporaneous but press-edited.
- ★ | S36 Michael Moritz warns on subprime unicorns — reporting on Bloomberg interview | https://www.bizjournals.com/orlando/bizwomen/news/latest-news/2015/10/sequoia-moritz-theranos-fb-goog-yhoo-subprime-tech.html | 2015-10-19 | reported interview summary; reliability B; access partial | Preserves context for “gravity” and Theranos/private-market scrutiny; not a substitute for the original video.
- ★ | S37 Crucible Moments: The Pivotal Decisions That Define Us | https://sequoiacap.com/article/crucible-moments-essay | 2023-09-07 | Roelof Botha/Sequoia essay; reliability A for Sequoia's stated decision, B for institutional rationale; access full | Says the five business units collectively decided in early 2023 to become fully independent partnerships; not Moritz-authored and not proof of his personal position.
- ★ | S38 Money Maze adaptation — Judgement, Compounding and the Weight of History | https://www.moneymazepodcast.com/blog/michael-moritz | 2026-04-14 | publisher-produced written adaptation; reliability B for paraphrase, A only where direct wording can be checked; access full | Secondary adaptation cross-checked against S30; useful for discovery but not a substitute for the direct audio/transcript.
Company, firm, deal, board, and outcome records
- ★★★ | S39 Google receives $25 million in equity funding | https://googlepress.blogspot.com/1999/06/google-receives-25-million-in-equity.html | 1999-06-07 | contemporaneous Google press release; reliability A; access full | Aggregate joint Kleiner Perkins/Sequoia round and Doerr/Moritz board seats; no firm-by-firm split.
- ★★★ | S40 Google Form S-1 | https://www.sec.gov/Archives/edgar/data/1288776/000119312504073639/ds1.htm | 2004-04-29 | SEC registration statement; reliability A; access full | Moritz board since May 1999; the principal-stockholder table at printed p. 84 reports 23,893,800 Sequoia shares as of 2004-03-31 and footnote 3 itemizes five vehicles; Moritz disclaims beneficial ownership beyond his pecuniary interest. Later filing percentages belong to their own dated tables.
- ★ | S41 Google 2005 proxy | https://www.sec.gov/Archives/edgar/data/1288776/000119312505072803/ddef14a.htm | 2005-04-08 | SEC proxy; reliability A; access full | Later board/holdings cross-check and ownership disclaimer; not personal economics.
- ★★★ | S42 PayPal Form S-1/A | https://www.sec.gov/Archives/edgar/data/1103415/000091205702005893/a2060419zs-1a.htm | 2002-02-14 | SEC registration amendment; reliability A; access full | Moritz director, Sequoia entities, 9.9% pre-offer block, and $5m secondary share purchase from Musk.
- ★★★ | S43 Yahoo 2002 proxy | https://www.sec.gov/Archives/edgar/data/1011006/000091205702010171/a2073396zdef14a.htm | 2002-03-18 | SEC proxy; reliability A; access full | Board chronology and governance/ownership snapshot; cannot establish original check, sole sourcing, or realized return.
- ★★★ | S44 Zappos — Sequoia oral history | https://articles.sequoiacap.com/zappos-story | current oral history; accessed 2026-08-22 | firm-hosted multi-witness account; reliability A for attributed testimony, B for retrospective framing; access full | LinkExchange intervention, repeated passes, Webvan/eToys/PlanetRx scars, 2004 Zappos investment, and Alfred Lin/Roelof Botha/team attribution.
- ★ | S45 PayPal: A Merger of Enemies That Reshaped Silicon Valley | https://sequoiacap.com/podcast/crucible-moments-paypal | current; accessed 2026-08-22 | firm retrospective/podcast; reliability A for attributed testimony, B for synthesis; access full page | Moritz board role in 1999 and team chronology; not contemporaneous financing evidence.
- ★ | S46 Adapting to Endure | https://sequoiacap.com/wp-content/uploads/sites/6/2022/06/Adapting-to-Endure_Sequoia-Capital-2022.pdf | 2022-05 | Team Sequoia deck presented by Roelof Botha; reliability A for the deck and Botha retrospective, not Moritz authorship; access full | PayPal runway story and reset playbook; explicitly not a Moritz talk or 2000 memo.
- ★ | S47 Saba founder returns as chairman and CEO | https://www.sec.gov/Archives/edgar/data/1070380/000119312503052341/dex991.htm | 2003-09-18 | issuer-filed release; reliability A for board/quote/then-current role list, B for issuer promotion; access full | Moritz board intervention language plus useful public-company denominator; board membership does not prove sourcing.
- ★★★ | S48 Green Dot Form S-1/A | https://www.sec.gov/Archives/edgar/data/1386278/000095012310062399/v55076a4sv1za.htm | 2010-07 | SEC registration statement; reliability A; access full | Board since 2003 and fund ownership/governance record; check and personal economics remain unestablished.
- ★★★ | S49 Moritz letter to Green Dot shareholders | https://www.sec.gov/Archives/edgar/data/1386278/000138627816000148/a2016-05x16defa14amoritzle.htm | 2016-05-16 | issuer-filed shareholder letter; reliability A for his argument, interested; access full | Direct governance defense; read against dissident evidence, not as neutral fact.
- ★★★ | S50 Harvest Capital Strategies Green Dot proxy-fight presentation | https://www.sec.gov/Archives/edgar/data/1226355/000092189516004252/ex991dfan14a10670001_042716.pdf | 2016-04-27 | dissident-filed deck; reliability A for allegations/claimed analysis, interested; access full | Stale-board and underperformance allegations; not adjudicated findings.
- ★★★ | S51 Green Dot issuer response to dissident campaign | https://www.sec.gov/Archives/edgar/data/1386278/000119312516584603/d148272ddefa14a.htm | 2016-05 | issuer-filed defense; reliability A for issuer position, interested; access full | Claimed Moritz contributions and countercase; requires symmetric skepticism.
- ★ | S52 Kayak 2012 Form 10-K | https://www.sec.gov/Archives/edgar/data/1312928/000131292813000005/kayakq4201210-k.htm | 2013-02-14 | SEC annual report; reliability A; access full | Public outcome, governance, and ownership context; issuer figures are not Sequoia cash returns.
- ★ | S53 Kayak Form 4 — Moritz/Sequoia entities | https://www.sec.gov/Archives/edgar/data/1312928/000118143112042358/xslF345X03/rrd351558.xml | 2012-07-26 | SEC ownership filing; reliability A; access full | Fund-entity structure, shared management, and beneficial-ownership disclaimer.
- ★ | S54 LinkedIn 2016 proxy | https://www.sec.gov/Archives/edgar/data/1271024/000104746916012483/a2228356zdef14a.htm | 2016-04-22 | SEC proxy; reliability A; access full | Board since 2011 and listed past boards; appointment is not proof of original sourcing or sole deal leadership.
- ★ | S55 Flextronics announces Moritz retirement from board | https://www.sec.gov/Archives/edgar/data/866374/000119312505205021/dex991.htm | 2005-10-18 | issuer-filed release; reliability A for 1993–2005 board chronology, B for praise; access full | Long governance tenure and an additional denominator company.
- ★ | S56 Instacart Form S-1 | https://www.sec.gov/Archives/edgar/data/1579091/000119312523232080/d55348ds1.htm | 2023-08-25 | SEC registration statement; reliability A; access full | Company economics, board, risks, and ownership; attribution remains multi-person/team.
- ★ | S57 Instacart — Sequoia company page | https://sequoiacap.com/companies/instacart | current; accessed 2026-08-22 | firm portfolio record; reliability A for current claimed partner roster, B for promotional thesis; access full | Partners Moritz, Alfred Lin, Ravi Gupta, and James Flynn are listed; prevents sole-credit inflation.
- ★ | S58 Fidji Simo: Delivering Instacart's Next Chapter | https://sequoiacap.com/article/fidji-simo-instacart-spotlight | 2024-02-26 | firm-produced profile; reliability A for attributed witness remarks, B for narrative; access full | Moritz-led investment claim and CEO recruitment story; interested retrospective.
- ★ | S59 Google — Sequoia company page | https://sequoiacap.com/companies/google | current; accessed 2026-08-22 | firm portfolio record; reliability A for current attribution, B for retrospective “why”; access full | Moritz partner attribution; reasoning is retrospective and must be paired with 1999/2004 records.
- ★ | S60 Getir — Sequoia company page | https://sequoiacap.com/companies/getir | current; accessed 2026-08-22 | firm portfolio record; reliability A for current attribution, B for promotion; access full | Moritz-linked later delivery bet; use with reporting on family-office/Sequoia sequencing and outcome.
- ★★★ | S61 Matthew Miller appointed to Klarna boards | https://investors.klarna.com/News--Events/news/news-details/2024/Matthew-Miller-appointed-to-Klarna-Holding-AB-and-Klarna-Bank-AB-Boards/default.aspx | 2024-01-30 | issuer announcement; reliability A for appointment and company-stated history, B for promotional claims; access full | Says original 2010 Sequoia investment was led by Moritz; does not disclose check/ownership.
- ★★★ | S62 Klarna leadership — Michael Moritz | https://investors.klarna.com/governance/leadership/default.aspx | current; accessed 2026-08-22 | issuer governance record; reliability A for current role/board chronology; access full | Director since July 2010, chair since December 2020, Sequoia partner through July 2023, current Heritage/Crankstart roles.
- ★★★ | S63 Klarna 2025 Form 20-F | https://www.sec.gov/Archives/edgar/data/2003292/000200329226000007/klar-20251231.htm | filed 2026 | SEC annual report; reliability A; access full | CIK 2003292, chair signature, voting-control and compensation/equity context; no personal-return inference.
- ★ | S64 Klarna Form 3 — Moritz | https://d18rn0p25nwr6d.cloudfront.net/CIK-0002003292/359e31c3-4706-41a3-9052-1dc9ce9c6677.pdf | event 2026-03-12; filing page dated 2026-03-17 | SEC Form 3; reliability A; access full | Table I, PDF p. 1 reports 3,472,845 ordinary shares indirectly through Crankstart Foundation; Table II reports 37,500 RSUs held directly; footnotes 1–2 give purchase range/consideration and four-year vesting.
- ★ | S65 Klarna Board Chair acquires 3.47m shares for $50m | https://investors.klarna.com/News--Events/news/news-details/2026/Klarna-Board-Chair-Michael-Moritz-Acquires-3-47-Million-Shares-for-50-Million/default.aspx | 2026-03-13 | issuer release tied to SEC forms; reliability A for disclosed transactions; access full | 3,472,845 shares for $49,913,138.73; exact ownership form comes from S64: indirect through Crankstart Foundation, separate from 37,500 directly held RSUs.
Vehicle, legal, archival, and denominator routes
- ★★★ | S66 Nayak v. Klarna Group plc et al — live docket | https://dockets.justia.com/docket/new-york/nyedce/1%3A2025cv07033/540168 | filed 2025-12-22; active through at least 2026-05-08 | federal docket mirror; reliability A/B for docket metadata, not merits; access full docket list | Moritz is a named defendant; pending allegations only, no adjudication or class certification represented.
- ★★★ | S67 Nayak v. Klarna — complaint mirror | https://www.bernlieb.com/wp-content/uploads/2026/01/20260108-31d0e635181a.pdf | complaint filed 2025-12-22 | complaint PDF; reliability A for allegations made, not truth; access full | Securities Act §§11, 12(a)(2), and 15 allegations tied to offering materials/signatories; legal posture must remain explicit.
- ★ | S68 Klarna securities complaint — alternate public mirror | https://zlk.com/wp-content/uploads/2025/12/KLAR-Complaint.pdf | 2025-12 | complaint mirror; reliability A for pleaded text if identical, C until pagination/hash reconciliation; access full | Redundant access route, not independent corroboration of allegations.
- ★ | S69 Netezza Schedule 13G | https://www.sec.gov/Archives/edgar/data/1132484/000095000508000039/p20305sc13g.htm | 2008-02-14 | SEC ownership filing; reliability A; access full | Sequoia X entities, shared managers including Moritz, and ownership/control disclaimer; denominator route.
- ★ | S70 Ikanos Form 3 filing | https://www.sec.gov/Archives/edgar/data/1195580/000110465905045196/xslF345X02/doc3.xml | 2005-09-16 | SEC ownership filing; reliability A; access full | Sequoia entities and shared management; evidence against treating fund blocks as Moritz's personal shares.
- ★ | S71 Sequoia China/U.S. Growth joint filer exhibit | https://www.sec.gov/Archives/edgar/data/789868/000095000509000294/p20670ex991.htm | 2009-04-14 | SEC exhibit; reliability A; access full | Entity and signatory map across Sequoia China and U.S. growth structures; signature is not deal sourcing.
- ★ | S72 Green Dot Form 4 — Moritz | https://www.sec.gov/Archives/edgar/data/1386278/000120919114071978/xslF345X03/doc4.xml | 2014-12-01 | SEC ownership filing; reliability A; access full | Shared fund-control relationships and beneficial-ownership disclaimer.
- ★ | S73 DOJ Venture Capital and Antitrust transcript — regulatory cross-list | https://www.justice.gov/d9/pages/attachments/2020/03/04/public_workshop_on_venture_capital_and_antitrust_transcript_final_002.pdf | 2020-02-12 | official government transcript; reliability A; access full | Intentionally cross-listed with S28 because it is both a talk and a regulatory-policy record; one underlying work.
- ★ | S74 Crankstart — organization record | https://www.crankstart.org/ | current; accessed 2026-08-22 | foundation website; reliability A for self-description, B for impact claims; access full | Family foundation route; foundation assets/actions are not venture-fund investments.
- ★ | S75 Oxford announces Moritz-Heyman gift and Crankstart scholarships | https://www.ox.ac.uk/news/2012-07-11-%C2%A375-million-gift-support-poorest-students | 2012-07-11 | university announcement; reliability A for gift/program terms, B for impact projection; access full | Philanthropy and family-history context; separate from investment performance.
- ★ | S76 Zappos oral history — governance cross-list | https://articles.sequoiacap.com/zappos-story | current | firm multi-witness record; reliability A/B; access full | Intentionally cross-listed with S44 for the governance/people map; one underlying work.
- ★ | S77 Forbes Midas 2008 — Michael Moritz index/profile | https://www.forbes.com/lists/2008/99/biz_08midas_Michael-Moritz_9X00.html | 2008 | Forbes ranking/profile; reliability B, link may be archival/fragile; access partial | Historical reputation signal, not audited personal or fund performance.
Skeptical reporting, criticism, succession, and current context
- ★ | S78 Silicon Valley VC firm can't find any women | https://www.vanityfair.com/news/2015/12/michael-moritz-sequoia-women-partners-tech | 2015-12-03 | critical reporting/commentary quoting Bloomberg exchange; reliability B; access full | Strongest contemporary criticism of his standards/pipeline framing; pair with original video and later hiring facts.
- ★ | S79 In Brotopia, sex parties are the least of Silicon Valley's problems | https://techcrunch.com/2018/02/05/in-brotopia-sex-parties-are-the-least-of-silicon-valleys-problems/ | 2018-02-05 | interview with Emily Chang; reliability B; access full | Retrospective context on 2015 exchange and gender/institutional criticism; not evidence of a personal legal finding.
- ★ | S80 Mike Moritz and the declining American worker | https://techcrunch.com/2018/01/20/mike-moritz-and-the-declining-america-worker/ | 2018-01-20 | critical commentary with short excerpts; reliability B/C; access full | Steelman/countercase around hours, productivity, welfare, and China comparison; columnist has his own viewpoint.
- ★ | S81 What Sequoia's Mike Moritz doesn't understand about startups in China | https://venturebeat.com/technology/what-sequoias-mike-moritz-doesnt-understand-about-startups-in-china | 2018-02-11 | founder/operator criticism; reliability B for lived counterargument, C for generalization; access full | China-specific institutional and labor boundary conditions against a universal work-intensity lesson.
- ★ | S82 Sequoia Capital shakes up leadership | https://www.axios.com/2017/12/15/sequoia-capital-shakes-up-leadership-1513300220 | 2017-12-15 | reported leadership history with Leone quotation; reliability B/A for attributed quote; access full | Valentine-to-Moritz/Leone succession, steward role, and no-sale handoff claim; institutional not solo narrative.
- ★ | S83 Michael Moritz moves on, book-ending a long chapter at Sequoia | https://techcrunch.com/2023/07/19/michael-moritz-moves-on-bookmarking-a-long-chapter-at-sequoia-capital/ | 2023-07-19 | reported transition; reliability B; access full | 2023 departure, Heritage advisory role, health-era chronology, and Getir family-office/Sequoia sequencing; attribution needs first-party cross-check.
- ★ | S84 How Klarna's boardroom spat exposed a schism at Sequoia Capital | https://www.ft.com/content/46c0cd45-bb77-46f1-898c-6b479ac5d279 | 2024-02-24 | Financial Times reporting; reliability B; access partial | Governance and succession dispute; no side's allegation is treated as adjudicated fact.
- ★ | S85 Silicon Valley midas investor Michael Moritz on AI, venture capital, and just about everything | https://www.livemint.com/global/silicon-valley-midas-investor-michael-moritz-on-ai-venture-capital-and-just-about-everything-11784278870430.html | 2026-07 | syndicated/reported interview; reliability A/B for attributed direct remarks and B for context; access full | Current role, HRTG, capital glut, AI concentration, and board governance; post-cutoff evidence explicitly date-stamped.
Coverage assessment
- Registry denominator: 85 rows and 83 unique canonical URLs. S28/S73 and S44/S76 are intentional cross-category references to two underlying works; they do not increase independent-source breadth.
- Priority denominator: 34 rows are designated ★★★ or ★★: 10 authored/book/FT routes (S01–S10), 10 spoken appearances (S21–S30), 12 company/deal/governance records (S39, S40, S42–S44, S48–S51, S61–S63), and two litigation records (S66–S67). Priority is an evidence grade; it is not the note-file denominator.
- Source state: 22 rows are checked
[x]because the accessible source content was processed; 63 remain[ ]. The open set comprises 12 priority routes plus 51 lower-priority routes. Exact priority barriers are: S02–S03 book previews only; S04 catalog metadata only; S05–S06 publisher excerpts/metadata rather than full books; S07 card metadata but paywalled bodies; S08 an origin index/snippets but no licensed FT body; S10 a paywalled FT body; S21 reachable university media/metadata but no validated full transcript; S22 a transcript interface without stable locators; S24 a partial embedded interview page; and S27 reachable video but unvalidated automated captions. S30 was processed through the OpenAI Audio API; none of the remaining routes is marked processed merely because metadata was reachable. - Corpus reconciliation: the 26-note target is one research frame, 15
w-written/evidence notes, and 10t-talk notes. Every priority row maps to a note even where related records are analyzed together:w-publisher-biography→ S01;w-little-kingdom→ S02–S03;w-going-for-broke→ S04;w-leading→ S05;w-auslander→ S06;w-ft-authored-corpus→ S07–S10;w-google-primary-record→ S39–S40;w-paypal-primary-record→ S42;w-yahoo-zappos-governance→ S43–S44;w-green-dot-proxy-fight→ S48–S51;w-klarna-current-record→ S61–S63;w-nayak-complaint→ S66–S67;w-attribution-boundaries,w-vehicle-denominator, andw-criticism-successionprocess lower-priority corroboration and skeptical evidence. The tent-notes map one-to-one to S21–S30. Stanford clips S32–S34 are child excerpts of S25, not independent appearances. The Money Maze adaptation S38 is a secondary cross-check, not a substitute for the processed S30 audio/transcript. - Route-to-destination parity: the 15 written/evidence notes feed
writings.mdsource-by-source coverage where authored works are involved and feed the cited primary-record, attribution, vehicle, failure, and adversarial sections of_profile.md,investments.md,investmentphilosophy.md, andreview.mdfor filings/company/court records. The ten talk notes feedtalks.md, with cross-links into the same core sections. No source is counted as deeply processed merely because it appears here. - FT stream: the live interface was swept across all three pages on 2026-08-22: exactly 63 visible cards (25 + 25 + 13), of which 36 were conservatively classified as Moritz-authored from a visible byline or explicit deck and 27 were excluded as reporting, reviews, compilations, third-party work, or byline-unresolved cards. The card-level ledger in
w-ft-authored-corpus.mdprevents topic-stream count inflation; one card is not one analyzed work. - Source categories searched: official/publisher books; FT/LinkedIn essays; Stanford, YC, Oxford, Charlie Rose, Digital Riptide, Money Maze, YouTube and government transcripts; Sequoia/company histories; EDGAR S-1/proxy/ownership filings; court complaints/dockets; governance disputes; criticism, underperformance, lawsuit and succession queries.
- Name/date variants: Michael Moritz, Michael J. Moritz, Michael Jonathan Moritz, Mike Moritz, Sir Michael Moritz; 1981/1984 book-edition conflict; 2015/2016 Leading editions; 2026 UK/US Ausländer timing; 2026 Money Maze page-date conflict.
- Attribution controls: YouTube belongs to Roelof Botha in official Sequoia attribution. Google was an aggregate joint $25m round with Kleiner Perkins. PayPal's $5m record is a secondary share purchase from Musk. Yahoo's proxy proves governance facts, not original economics. Stripe and Instacart are multi-person/team cases. Adapting to Endure is Team Sequoia/Botha, not Moritz authorship.
- Vehicle controls: fund blocks and managing-member relationships are not personal holdings or economics. Klarna Form 3 Table I explicitly reports 3,472,845 ordinary shares indirectly through Crankstart Foundation; Table II separately reports 37,500 RSUs held directly. Those positions remain distinct.
- Access barriers: FT bodies and some books are partial; Charlie Rose offers a transcript interface without stable scrape locators. Stanford S25's former transcript-PDF URL moved during final review, so its citations now resolve to the live official video page while retaining the page locators from the processed transcript. Money Maze was transcribed only through the OpenAI Audio API in nine lossless source chunks; no paywall bypass, local Whisper, non-OpenAI transcription, or unvalidated caption quotation was used.
- Adversarial record: Green Dot's dissident and issuer filings are interested opposing accounts. Nayak contains pending allegations only. The 2015 gender and 2018 China-work-culture criticism are preserved. The 2024 Klarna dispute remains a governance/account-attribution issue, not a legal finding.
- Candidate portfolio denominator: official Sequoia partner pages and the issuer/ownership records above capture Google, Yahoo, PayPal, Zappos, Saba, Green Dot, Kayak, LinkedIn, Flextronics, Instacart, Klarna, Getir, Netezza, and Ikanos, with more company routes still discoverable. Board-role lists are discovery aids, not a complete or attribution-clean deal set.
- Saturation boundary: priority public routes were mapped and the last targeted searches mainly returned known interviews, mirrors, or child excerpts. Material remaining work is licensed book/FT access, exact Charlie Rose transcript locators, and fund cash-flow/denominator evidence.
Source notes
[w] Michael Moritz research frame and evidence controls
- URL: https://www.simonandschuster.com/authors/Michael-Moritz/262020703 | Published: current publisher record; accessed 2026-08-22 | Format: research protocol anchored to official biography and live evidence routes | Reliability: A for publisher-held authorship metadata; this note is researcher-authored | Access: full for the cited metadata, mixed for the wider corpus | Accessed: 2026-08-22 | Locator scheme: named section, filing item/table, transcript page/timestamp, or explicit none-available statement
Takeaways
- Guiding question 1: Which formative facts are documented, and which proposed links from refugee-family history, reporting, or historical study to investment behavior remain inference?
- Guiding question 2: What did Moritz actually say about sourcing, founder assessment, uncertainty, governance, ownership, follow-ons, and exits—and did documented behavior match?
- Guiding question 3: Which celebrated deals can be attributed to Moritz personally, which belong to Sequoia teams or vehicles, and which are commonly misattributed?
- Guiding question 4: What does the public denominator contain beyond Yahoo, Google, and PayPal, including ordinary outcomes, failures, misses, and disputed interventions?
- Guiding question 5: Which patterns recur across direct testimony and contemporaneous filings without treating recurrence as proof of repeatable returns?
- Guiding question 6: What is the strongest skeptical account—access, team/vehicle advantages, survivorship, hindsight, cultural criticism, governance disputes, or pending litigation—and what evidence could discriminate it?
- Guiding question 7: How did the public philosophy change from the 1990s internet cycle through the 2000 crash, growth-era financing, China expansion, the 2022 reset, and the 2023 Sequoia transition?
- Guiding question 8: Which historical lessons transfer to a 2026 venture fund, and which depend on period-specific capital, platform, market, or institutional conditions?
Quotes
- No quotation retained. This note defines questions and controls rather than attributing claims to Moritz.
Biography and decision evidence
- Classification: modern internet-era investor with a pre-venture journalism career; direct voice is available but uneven; legal vehicle is a multigenerational partnership/fund complex rather than a personal account; controversy searches produced cultural criticism, a 2024 Klarna governance dispute, and a pending 2025 securities complaint. [researcher inference · strong] publisher biography, Nayak docket
- Evidence hierarchy for this package: issuer and court records; official/full transcripts and authored works; contemporaneous firm/company records; high-quality reported interviews; metadata-only and partial-access routes. Marketing lists, retrospective recollection, and press attribution are never treated as audited personal economics.
- Identity control: Michael Jonathan Moritz / Michael J. Moritz / Mike Moritz / Sir Michael Moritz refer to the subject. Roelof Botha, Alfred Lin, Doug Leone, Neil Shen, and Sequoia entities remain separate actors.
Philosophy signals
- sourcing / picking: seek direct statements plus decision-date records; never infer a thesis solely from a famous outcome.
- portfolio / vehicles: distinguish company capitalization and fund holdings from Moritz's personal ownership or economics.
- boards / people: board service demonstrates governance position, not sole sourcing, approval, intervention, or return credit.
- risk / exits: reported valuations, purchase prices, and IPO ownership blocks are separate facts; no fund multiple is derived without cash-flow, dilution, and timing evidence.
Contradictions, counterevidence, and access limits
- Google announced a joint $25 million Kleiner Perkins/Sequoia round; the public record reviewed does not split the check between firms. Google press release
- PayPal's August 1999 $5 million record is a purchase of 15 million Series A shares from Elon Musk, not primary company financing. PayPal S-1/A, principal-stockholder notes
- YouTube is officially attributed in Sequoia materials to Roelof Botha; it is not counted as a Moritz-led investment. Stripe and Instacart also require multi-partner attribution rather than lone-investor narration.
- Adapting to Endure is a 2022 Team Sequoia deck presented by Roelof Botha; it contains a retrospective story about Moritz but is not Moritz-authored or contemporaneous PayPal evidence. deck
- The Financial Times author/topic stream mixes bylined Moritz columns with articles about him, reviews, compilations, and byline-unresolved cards. The exact live sweep on 2026-08-22 found 63 cards across three pages (25 + 25 + 13): 36 conservatively admitted as authored from a visible Moritz byline/deck and 27 excluded. The card ledger is in
w-ft-authored-corpus.md; 63 interface cards are not 63 authored works. - The Money Maze route was processed through the OpenAI Audio API in nine contiguous chunks totaling 701 segments and 3,927.045 seconds. Timestamped paraphrases are admitted; noisy machine wording, host praise, and vehicle/team inferences are not.
- Nayak v. Klarna names Moritz as a defendant and asserts Securities Act claims. Those are pending allegations only: no merits adjudication, class certification, or liability finding is represented. live docket
- Klarna Form 3 Table I reports 3,472,845 ordinary shares indirectly through Crankstart Foundation; Table II separately reports 37,500 RSUs held directly. Form 3, PDF p. 1
Open questions
- Obtain licensed/full editions of Moritz's books and reconcile original versus reissue dates, subtitles, and added material.
- Obtain lawful full FT article access for each priority column; do not reconstruct paywalled arguments from stream summaries.
- Preserve the Money Maze chunk-offset ledger and re-check any future exact quotation against the audio; do not commit or republish the machine transcript.
- Locate partnership- or fund-level denominator evidence that can test the record after removing Google and other dominant successes.
[t] Mike Moritz — Charlie Rose
- URL: https://charlierose.com/videos/17831 | Published: 2013-02-15 | Format: broadcast video with “See Transcript” interface | Reliability: A for direct audio/video and program metadata | Access: partial; transcript interface exists but stable extract/locators unavailable | Accessed: 2026-08-22 | Locator scheme: program date/title/description; timestamps require direct player validation
Takeaways
- The program description says Moritz discusses leading Silicon Valley companies, venture capital, and his path from journalism to investing. [contemporaneous record · strong] program page
- Because stable transcript text/timestamps were not acquired, this note inventories the appearance without treating its thematic description as content analysis. [researcher inference · strong] program page
Quotes
- No quotation retained; the “See Transcript” interface was not available in a stable, pinpointable form.
Biography and decision evidence
- The February 2013 date places the appearance near the April 2013 Digital Riptide interview, creating a useful same-period comparison once the transcript is retrieved. [contemporaneous record · strong] Charlie Rose, Riptide
Philosophy signals
- sourcing / picking / institutions: candidate themes only; no rule is attributed until the primary words and locators are available. [researcher inference · insufficient public record] program description
Contradictions, counterevidence, and access limits
- Program metadata is not a transcript. Third-party quote attributions to this appearance are excluded unless checked against video.
- Later retellings may conflate this program with Moritz's other 2013 interviews.
Open questions
- Retrieve the transcript through the public interface or manually timestamp the video without storing a full transcript.
- Compare its Sequoia-success account with Riptide's explicit hindsight warning.
[t] Mike Moritz — Digital Riptide
- URL: https://www.digitalriptide.org/person/mike-moritz/ | Published: interview 2013-04-02 | Format: full, lightly edited interview transcript | Reliability: A for direct remarks, B for recalled chronology | Access: full | Accessed: 2026-08-22 | Locator scheme: named interviewer turns and distinctive topic paragraphs; interface supplies no stable paragraph numbers
Takeaways
- Moritz says venture narratives acquire grand design only in retrospect; at investment, teams are often trying to survive the next year. [investor-stated · strong] opening answer
- On Yahoo, he recalls a differentiated belief that a large free internet audience could eventually support advertising, at a time when free consumer services perplexed investors. [retrospective witness · moderate] Yahoo/free-services passage
- On Google, he says the investment centered on superior search technology and that Yahoo's licensing relationship was part of Sequoia's path to the company; he distinguishes this from a media-first thesis. [retrospective witness · moderate] Google passage
- He rejects early certainty: properly considered venture decisions rest on a narrow edge because many failure paths are visible. [investor-stated · strong] “secret sauce” answer
Quotes
- “There’s only a grand design in retrospect.” — Moritz, opening answer. transcript
- “The decision rests on a narrow knife edge.” — Moritz, founder-selection answer. transcript
Biography and decision evidence
- The interview explicitly joins his journalism/media background with Sequoia's Yahoo and Google history, while separating the companies' initial theses. [retrospective witness · moderate] full transcript
- The transcript's own notice says it was lightly edited and may contain typos/incorrect names; names and numbers require primary-record cross-checks. [contemporaneous record · strong] editorial note
Philosophy signals
- picking: identify a narrow product or market truth without pretending the full path is knowable. [investor-stated · strong] Google/Yahoo passages
- risk: make the survival problem and failure paths explicit before narrating a large future. [investor-stated · strong] opening/knife-edge passages
- hindsight: later coherence is not evidence of initial foresight. [investor-stated · strong] opening answer
Contradictions, counterevidence, and access limits
- Direct speech proves what Moritz said in 2013, not what the 1995/1999 investment memos said. Google/Yahoo filings and announcements bound timing/ownership.
- A memorable narrative selects successes; the interview does not enumerate failed internet bets or fund economics.
Open questions
- Find contemporaneous Yahoo and Google IC/board records that test the retrospective account.
- Identify ordinary investments in which the same knife-edge framing produced a weak outcome.
[t] DOJ Public Workshop on Venture Capital and Antitrust — Michael Moritz fireside chat
- URL: https://www.justice.gov/d9/pages/attachments/2020/03/04/public_workshop_on_venture_capital_and_antitrust_transcript_final_002.pdf | Published: event 2020-02-12 | Format: official government workshop transcript | Reliability: A for direct remarks and event record | Access: full | Accessed: 2026-08-22 | Locator scheme: printed/PDF pages; fireside chat begins at printed p. 5
Takeaways
- Moritz traces his path from Wales and TIME reporting to Silicon Valley and Sequoia, describing himself as initially nontechnical. [investor-stated · strong] transcript, printed pp. 5–7
- The conversation distinguishes early venture financing, governance, exit timing, and antitrust implications from large incumbent behavior. [investor-stated · strong] fireside chat
- Moritz says a very small number of companies drive a large share of venture returns and links capturing that value to not selling too early. This is a qualitative power-law statement, not a Sequoia return table. [investor-stated · strong] fireside chat, returns/exit passage
Quotes
- “A very small number of companies drive a huge percentage of the returns.” — Moritz. official transcript, returns passage
Biography and decision evidence
- The government-hosted setting creates a high-quality direct transcript but also a policy context: Moritz is explaining venture's social/economic role during an antitrust workshop. [researcher inference · strong] workshop title and fireside chat
- The source supports his stated view that early-stage outcomes are uncertain and that patient ownership matters. It does not quantify his personal record or identify each company he held/sold. [researcher inference · strong] fireside chat
Philosophy signals
- portfolio / exits: preserve exposure to rare compounding winners when evidence supports continuing upside; avoid turning the statement into a universal “never sell” rule. [researcher inference · moderate] returns/exit passage
- macro / governance: venture and incumbent conduct operate under different scale, acquisition, and competition dynamics. [investor-stated · moderate] antitrust discussion
Contradictions, counterevidence, and access limits
- Power-law rhetoric can justify survivorship and concentration after the fact. A fund-level denominator, reserve history, loss cohort, and liquidity constraints are absent.
- Regulatory-policy advocacy is interested testimony even when the transcript is exact.
Open questions
- Which Sequoia distribution decisions document holding or selling dominant winners?
- What ordinary/failure cases test the “hold winners” mechanism?
[t] An Interview with Michael Moritz — Founders Space
- URL: https://www.foundersspace.com/fund-raising/an-interview-with-michael-moritz-the-king-of-all-vcs/ | Published: circa 2012; page accessed 2026-08-22 | Format: interview page with embedded media and editorial biography | Reliability: A for direct media if playable; B/C for page copy and flattering framing | Access: partial | Accessed: 2026-08-22 | Locator scheme: page headings and visible biography; embedded-media timestamps not recovered
Takeaways
- The page inventories then-current board roles including Green Dot, Klarna, Kayak, LinkedIn, Sugar, and others, offering a denominator lead rather than verified deal attribution. [contemporaneous record · provisional] page biography
- Its headline calls Moritz “the king of all VCs”; that is promotional framing and excluded from evidence of greatness. [researcher inference · strong] page title
Quotes
- No quotation retained; direct embedded-media text/timestamps were not recovered.
Biography and decision evidence
- The visible biography supports the broad Time → Technologic Partners → Sequoia sequence but should be cross-checked against direct transcripts and filings. [contemporaneous record · provisional] page biography
Philosophy signals
- No investment rule is retained from metadata/editorial copy. [researcher inference · insufficient public record] page
Contradictions, counterevidence, and access limits
- Board lists can be stale, incomplete, and unrelated to original sourcing. The page supplies no audited economics.
- Embedded-media custody and exact date require verification before calling this a fully processed direct interview.
Open questions
- Recover the original upload, duration, and transcript/captions.
- Cross-check each listed board against dated issuer records.
[t] From the Shadow of the Death Camps to Leading Sequoia — Money Maze
- URL: https://www.moneymazepodcast.com/podcast/michael-moritz | Published: page metadata shows 2026-04-02 and 2026-04-09; Audioboom post 8881576 | Format: podcast audio and show notes; episode 197; duration 3927.14 seconds (about 65:27) | Reliability: A for direct audio, B for show-note/adaptation paraphrase | Access: full official audio plus OpenAI API diarized transcript | Accessed: 2026-08-22 | Locator scheme: episode-level mm:ss, produced by offsetting nine contiguous OpenAI transcript chunks at 480-second intervals and checking their first/last segment coverage against the 65:27 audio
Takeaways
- At 08:41–09:31 Moritz reduces founder selection to three observable signals: unusual subject depth that educates the investor, clear command and communication, and sustained hunger to make the product real. This is a direct 2026 restatement of the purpose/obsession test in the 2016 Stanford record. [investor-stated · strong] episode page/audio
- At 10:18–12:05 he recalls Patrick Collison framing Stripe as a simpler continuation from PayPal and as payment infrastructure for anyone starting an online business. This is retrospective founder-thesis evidence, not proof of who sourced, approved, priced, or economically owned the deal. [retrospective witness · moderate] episode page/audio
- At 13:43–16:13 he says Oxford tutorials and journalism trained him to form a defensible opinion quickly under incomplete facts; the explicit advantage claimed is comfort with uncertainty, not superior technical expertise. [investor-stated · strong] episode page/audio
- At 17:03–17:49 he frames financing terms as a long relationship in which neither founder nor investor should feel stripped by the bargain. That supports a relationship-preserving negotiation principle but supplies no valuation rule or outcome test. [investor-stated · moderate] episode page/audio
- At 20:55–23:21 he identifies Europe's fragmented customer/business habits, thinner success pattern, and weaker fast-growth board experience as structural constraints. The third point is a broad judgment, not a measured cross-country governance study. [investor-stated · moderate] episode page/audio
- At 24:42–26:26 he describes a current bias toward long-duration businesses that repeatedly expand cash and profit, plus the rare capacity to remain inactive through temporary setbacks. He distinguishes long horizon from unlimited patience. [investor-stated · strong; efficacy unverified] episode page/audio
- At 29:41–30:35 he predicts extreme AI value concentration in one or two very large winners, potentially including incumbents, with widespread loss elsewhere. This is a dated forecast, not a base-rate estimate or investable selection method. [investor-stated · strong on view; predictive validity unknown] episode page/audio
- At 36:01–37:47 he explains that Ausländer grew from family papers received after his mother's death and pandemic-era research; at 49:16–50:13 he says he rewrote it four times and discarded at least 35,000 words. This converts the adaptation's summary into direct process evidence. [investor-stated · strong] episode page/audio
- Audioboom metadata identifies post 8881576, episode 197, and duration 3927.14 seconds. [contemporaneous record · strong] Audioboom post
Quotes
- No verbatim quotation is required for the synthesis. Timestamped paraphrases above preserve the evidence while avoiding false precision from machine transcription.
Biography and decision evidence
- At 02:47–04:55 Moritz says he left Britain for the United States in 1976 without a grand plan, pursued journalism after Oxford/Wharton, joined TIME, and encountered Silicon Valley after transfers through Detroit, Los Angeles, and San Francisco. This is direct retrospective sequence evidence; exact employment dates still rest on publisher/archival records. [retrospective witness · moderate]
- At 05:23–06:48 he recalls that Kleiner Perkins then appeared stronger than Sequoia, whose small, confrontational culture reflected Don Valentine and Pierre Lamond's Fairchild backgrounds. This constrains the myth that he entered an already dominant Sequoia, but it remains a participant's later comparison. [retrospective witness · moderate]
- At 57:42–57:54 the host says 2006 for Moritz's blood-cancer diagnosis; Moritz immediately corrects the year to 2008. The correction controls later chronology. [investor-stated · strong]
- The speaker-diarization labels reset across chunks, so identity was assigned from question/answer continuity rather than raw letter labels alone. No claim is based on a sponsor segment or host summary.
Philosophy signals
- Picking: depth, grasp, communication, and hunger are observable founder hypotheses, to be tested against product/customer behavior rather than charisma. [investor-stated · strong]
- Diligence: Moritz explicitly links his own training to forming a fact-armed view under incomplete information. The boundary is that comfort with uncertainty can become overconfidence. [investor-stated · strong; researcher boundary · strong]
- Terms: durable counterpart relationships matter more than extracting the last unit of price. No term sheet or realized comparison is supplied. [investor-stated · moderate]
- Governance/geography: market homogeneity, accumulated operator experience, and board capability interact; the Europe claim requires country- and sector-specific testing. [investor-stated · moderate]
- Compounding: current long-duration capital allocation favors businesses with persistent cash/profit expansion and tolerates temporary patches, but this route does not publish Heritage holdings, returns, or sell rules. [investor-stated · strong; application evidence insufficient]
- AI: concentration is the forecast; the transcript does not reveal how to identify the eventual winners ex ante. [investor-stated · strong on view; insufficient on method]
Contradictions, counterevidence, and access limits
Page-date conflict: the episode page renders both 2/4/2026 and 9/4/2026; the note preserves both rather than choosing a date without feed metadata.
The source MP3 was 63,294,825 bytes, SHA-256
6636644e607f2c7f44c289f7d3b5fc3ab0f789f77a85482de116368b95d15c5c, above OpenAI's 25 MB file limit. A first 16.2 MB mono re-encode was rejected as unreadable. The successful route split the original MP3 losslessly into eight 480-second chunks and one 87.14-second tail, then usedgpt-4o-transcribe-diarize,diarized_json, and automatic chunking. All nine calls returned HTTP 200; 701 segments cover 00:00.27–65:26.33 after deterministic offsets. No local or non-OpenAI speech recognizer was used.Automated diarization is not human stenography. It changed speaker letters at chunk boundaries and garbled some names, so the package retains paraphrases, checks identity from conversational continuity, and preserves exact episode-level windows.
The Stripe passage confirms Moritz's recollection of the initial product framing, not sole attribution or transaction economics. The compounding passage confirms a current preference, not a three-case realized-performance record. The AI passage is a forecast and should be scored prospectively.
Moritz declines to disclose Heritage specifics at 27:09–27:34. Current general-allocation preferences must not be rewritten as a disclosed Heritage portfolio, historical venture-fund rule, or performance record.
Five source-audio windows covering founder criteria, uncertainty training, compounding, AI concentration, and writing revision were independently re-transcribed with
gpt-transcribe; each confirmed the retained paraphrase and repaired the diarized output's noisy names or segment splits.
Open questions
- Resolve the publication date from the podcast RSS/Audioboom feed.
- Recover contemporaneous Stripe sourcing, approval, security, price, ownership, and partner-role records before upgrading its unresolved witness-only ledger row into a reconstructed transaction or attributed Moritz investment.
- Test the 2026 AI concentration forecast against an explicit future scorecard rather than using eventual winners to rewrite the prediction.
[t] Interview with Michael Moritz — Oxford Campaign
- URL: https://podcasts.ox.ac.uk/interview-michael-moritz | Published: added 2008-09-16 | Format: official university audio/video, 00:05:53 | Reliability: A for direct audio and university metadata | Access: full media/metadata; no official transcript | Accessed: 2026-08-22 | Locator scheme: page title, description, date, duration; media elapsed time when manually reviewed
Takeaways
- Oxford describes the interview as Moritz discussing his and Harriet Heyman's gift to Christ Church and asset management at Oxford. [contemporaneous record · strong] episode information
- The appearance is strongest for philanthropy/institutional context and too short/narrow to carry a general venture philosophy. [researcher inference · strong] episode description
Quotes
- No quotation retained because no official transcript or validated timestamped extraction was created.
Biography and decision evidence
- The 2008 route predates the larger 2012 Oxford scholarship announcement and shows a continuing institutional relationship. It does not establish investment performance or Crankstart ownership. [contemporaneous record · moderate] Oxford interview, 2012 Oxford announcement
Philosophy signals
- institutions / capital: long-horizon asset management and educational access are possible worldview signals, but no venture rule is claimed from the metadata. [researcher inference · insufficient public record] episode page
Contradictions, counterevidence, and access limits
- The page has media downloads but no transcript; show description is not treated as Moritz's wording.
- Philanthropic capital, Oxford endowment assets, Crankstart, personal capital, and Sequoia funds remain distinct.
Open questions
- Produce a timestamped note after direct media review if Oxford's player/download remains accessible.
- Which gift/asset-management details were legally implemented, and through what entity?
[t] Follow Your Instincts and Find Your Path — Stanford eCorner
- URL: https://stvp.stanford.edu/av/follow-your-instincts-and-find-your-path-entire-talk | Published: event 2016-01-20; site route refreshed 2026 | Format: official page/video plus previously processed Stanford full transcript, conversation with Lisa Sugar and Emily Ma | Reliability: A for direct remarks; B for recollection | Access: full video; former transcript-PDF URL moved during final review | Accessed: 2026-08-22 | Locator scheme: processed transcript PDF page plus speaker turn; clip transcripts are child excerpts, not independent works
Takeaways
- Moritz frames careers and institutions around a small number of consequential choices, while Lisa Sugar supplies an operator/founder countervoice. [investor-stated · strong] transcript, opening question and answers
- His biography emphasizes Welsh upbringing, historical study, journalism, and unplanned proximity to Silicon Valley; the source supports chronology but not deterministic causation. [retrospective witness · moderate] transcript, biography section
- The event connects Leading to choices, excellence, performance, founder/investor relationships, and institutional renewal. The book's Ferguson-derived lessons and Moritz's own practice must remain distinct. [researcher inference · moderate] transcript
Quotes
- “Follow your instincts and follow your interests.” — Moritz, career-path answer. official transcript
Biography and decision evidence
- The talk is direct evidence of how Moritz narrated his career in 2016, not a contemporaneous record of his 1970s/1980s motives. [retrospective witness · strong] full transcript
- Lisa Sugar's presence makes founder-investor dynamics less one-sided, but this is still a selected successful relationship rather than a denominator sample. [researcher inference · moderate] full transcript
Philosophy signals
- people: seek unusually strong performance and self-direction, then preserve room for founders' instincts. [investor-stated · moderate] performance and founder sections
- career/sourcing: accumulated interests and proximity can create opportunity without a master plan. [investor-stated · strong] career-path section
Contradictions, counterevidence, and access limits
- “Instinct” can become an unfalsifiable label after success; decision records must identify inputs, alternatives, and kill criteria.
- The three Stanford clip transcripts duplicate portions of this full appearance and add locators, not independent evidence breadth.
- The original Stanford transcript-PDF URL returned 404 during final review. Citations now resolve to the live official page/video and retain the processed PDF page locators; the moved file is a pinpoint-access regression, not a waiver for claims that were not already validated.
Open questions
- Which deal records show instinct overriding consensus before outcome?
- Which failures expose the limits of performance-based or instinctive selection?
- Can Stanford provide a new stable public route for the processed full transcript PDF?
[t] Michael Moritz, Partner, Sequoia Capital — Stanford GSB
- URL: https://www.youtube.com/watch?v=ZTNFQeYEdvc | Published: 2019-02-07 upload | Format: official Stanford GSB video | Reliability: A for direct audio/video; C for automated captions until audio-validated | Access: full video, partial transcript route | Accessed: 2026-08-22 | Locator scheme: official video elapsed time; no machine-caption wording retained without validation
Takeaways
- Stanford's appearance covers Moritz's childhood in Wales, refugee-family history, career path, and venture/leadership analogies. [contemporaneous record · moderate] official video
- Search-result/third-party transcript text is useful for navigation but is not treated as a verified transcript. [researcher inference · strong] official video
Quotes
- No quotation retained because official captions were not independently validated against the audio with timestamps.
Biography and decision evidence
- The appearance corroborates recurring self-narration about family history and nontechnical training. Recurrence establishes consistency, not a causal bridge to investment outcomes. [researcher inference · strong] official video, Stanford 2016 transcript
Philosophy signals
- people / teams: elite-sports talent development is a candidate analogy for venture partnership renewal, but the full audio needs timestamped extraction before making it decision-ready. [researcher inference · provisional] official video
Contradictions, counterevidence, and access limits
- No local/non-OpenAI transcription was run. Automated captions can misrecognize names and numbers.
- A university-hosted career talk is retrospective and selection-biased toward coherent biography.
Open questions
- Review the official video manually and record timestamps for every retained claim.
- Compare the sports analogy with actual Sequoia promotion, turnover, and failed-hire evidence.
[t] Michael Moritz and Robert Lacher — Visionaries Club conversation
- URL: https://aletteraday.substack.com/p/letter-134-michael-moritz-and-robert | Published: conversation labeled 2023; transcript posted 2023-10-31 | Format: hosted conversation transcript | Reliability: A/B for attributed direct speech pending origin-video/provenance check | Access: full transcript | Accessed: 2026-08-22 | Locator scheme: question/topic headings and speaker turns; no stable timestamps
Takeaways
- The conversation covers formative history, “looking for the unexpected,” hiring partners, Sequoia Heritage formation/fundraising, reinvention, and global technology. [retrospective witness · moderate] transcript introduction and speaker turns
- Moritz's reported emphasis on the unexpected is not a screen by itself; it becomes operational only when paired with a non-consensus observation, falsifier, and evidence milestone. [researcher inference · moderate] conversation
- Hiring recollections about Roelof Botha and Alfred Lin support an institutional people map but remain the senior partner's retrospective account. [retrospective witness · moderate] hiring discussion
Quotes
- No quotation retained until the hosted transcript is checked against the origin recording.
Biography and decision evidence
- This is a key bridge from Sequoia venture work to Heritage and later capital allocation. It does not disclose legal terms, decision rights, fees, returns, or a complete client/asset denominator. [researcher inference · strong] Heritage discussion
- The posting date follows the July 2023 Sequoia transition; statements may describe the new status with hindsight. [contemporaneous record · moderate] post date, transition report
Philosophy signals
- sourcing / picking: search for evidence that violates the conventional category narrative, then specify why it matters. [researcher inference · moderate] unexpected discussion
- people: hire future partners for demonstrated judgment/operating behavior, while separating Moritz's selection claim from their independent accomplishments. [retrospective witness · moderate] hiring discussion
Contradictions, counterevidence, and access limits
- A hosted transcript can contain edits or transcription errors; origin custody and date should be recovered before verbatim quotation.
- “Unexpected” can reward novelty theater or hindsight if no prospective falsifier is written.
Open questions
- Recover the original Visionaries Club recording and timestamps.
- Obtain public legal/organizational evidence for Sequoia Heritage's structure and launch chronology.
[t] Maintaining Success for the Long Term — Y Combinator
- URL: https://www.ycombinator.com/blog/michael-moritz-sequoia-success | Published: 2016-02-26 | Format: YC-released transcript of Sam Altman Q&A | Reliability: A for direct remarks | Access: full | Accessed: 2026-08-22 | Locator scheme: two Sam Altman questions and Moritz answer paragraphs; interface has no stable paragraph numbers
Takeaways
- Altman asks how Sequoia repeatedly innovated and stayed strong over decades; Moritz answers in institutional rather than single-deal terms. [contemporaneous record · strong] introduction and first question
- Moritz emphasizes continual renewal, internal standards, not resting on prior success, and giving new generations real scope rather than preserving incumbent authority. [investor-stated · strong] first answer
- The follow-up on motivation ties persistence to insecurity/competition and unfinished work. Stated motivation is direct evidence of self-conception, not proof of superior performance. [investor-stated · moderate] second question/answer
Quotes
- “We’ve always been afraid of going out of business.” — Moritz, institutional-durability answer. YC transcript
Biography and decision evidence
- The transcript is unusually focused: it explains Moritz's 2016 public account of Sequoia as a renewing partnership, not a hero-centered investment shop. [investor-stated · strong] full transcript
- Later leadership and geography conflicts test the durability claim; they do not erase the 2016 account. [researcher inference · moderate] Axios succession, 2023 Sequoia essay
Philosophy signals
- people / succession: future leaders need economic, reputational, and decision authority, not symbolic inclusion. [researcher inference · moderate] first answer
- risk: institutional complacency is a failure mode even after large wins. [investor-stated · strong] full transcript
Contradictions, counterevidence, and access limits
- This is selected public testimony with no partnership economics, turnover denominator, or failed succession cases.
- Renewal rhetoric sits in tension with the 2015 gender exchange and 2024 Klarna dispute; those contradictions require explicit treatment rather than averaging.
Open questions
- Which partnership agreements and promotion/economic records test whether authority truly transferred?
- How did the independent geography partnerships alter the institutional model?
[w] Deal and firm attribution boundaries
- URL: https://sequoiacap.com/companies/instacart | Published: current; accessed 2026-08-22 | Format: firm portfolio/retrospective records with issuer and filing cross-checks | Reliability: A for current claimed rosters, B for retrospective rationale | Access: full | Accessed: 2026-08-22 | Locator scheme: company-page Partner/Team/Milestones headings; named-speaker sections; filing tables
Takeaways
- Instacart's Sequoia page lists Michael Moritz, Alfred Lin, Ravi Gupta, and James Flynn as partners. Moritz-led language in a later profile does not erase the multi-partner roster or founder/board roles. [contemporaneous record · strong] Instacart company page, Fidji Simo profile
- Official Sequoia material attributes YouTube to Roelof Botha, not Moritz. YouTube is excluded from the Moritz-led ledger even where press profiles loosely associate him with Sequoia's portfolio. [contemporaneous record · strong] Sequoia company index
- Adapting to Endure is a Team Sequoia deck presented by Botha. Its PayPal passage is a retrospective witness account about Moritz, not Moritz authorship or a contemporaneous 2000 memo. [retrospective witness · strong] deck cover and PayPal slide
- At 10:18–12:05 of Money Maze, Moritz recalls first meeting Patrick Collison and the initial simplify-PayPal/enable-global-ecommerce thesis. That direct retrospective account still does not establish Stripe sourcing, approval, security, ownership, partner roster, or sole credit; Instacart likewise requires the multi-partner roster. [retrospective witness · moderate; researcher attribution rule · strong] Money Maze episode/audio, Instacart page
Quotes
- No quotation retained.
Biography and decision evidence
- The public record supports Moritz involvement across several cases but frequently leaves sourcing, sponsorship, approval, negotiation, reserve decisions, and exit influence split or unknown. [researcher inference · strong] Sequoia company pages
- Board membership is governance evidence, not proof that the director sourced or led the original investment. [researcher inference · strong] LinkedIn proxy
Philosophy signals
- people / attribution: construct a role matrix before converting a company outcome into an investor lesson. [researcher inference · strong] Instacart page
- portfolio: firm-level brand and vehicle access can be causal advantages distinct from personal selection skill. [researcher inference · moderate] Google release
Contradictions, counterevidence, and access limits
- Firm pages are curated and can update partner labels retrospectively. Filings provide stronger dated ownership/board facts but still rarely reveal internal credit.
- Narrators have institutional and personal incentives; repetition across Sequoia-owned media is one source family, not independent corroboration.
Open questions
- Recover internal-decision testimony or founder accounts for Stripe, Instacart, and Getir.
- For each ledger company, identify sourcing, approval, board, recruiting, follow-on, and exit roles or mark unknown.
[w] Ausländer: One Family's Story of Escape and Exile
- URL: https://www.simonandschuster.com/books/Auslander/Michael-Moritz/9798897101924 | Published: UK reviews/availability in 2026; US publisher date 2026-09-01 | Format: memoir/publisher page | Reliability: A for authorship and publisher metadata; B for publisher synopsis/reviews | Access: partial | Accessed: 2026-08-22 | Locator scheme: About The Book, About The Author, and Product Details headings
Takeaways
- The publisher says Moritz reconstructed relatives' persecution and murder from family papers and photographs, following his parents' escape to Britain and later Cardiff life. [contemporaneous record · moderate] About The Book
- The work is a family/history memoir rather than an investment manual. Its relevance is biographical worldview and research method, not a direct deal rule. [researcher inference · strong] About The Book
- In Money Maze at 35:58–37:52, Moritz directly says the project grew during Covid after his mother's death and the arrival of four or five cartons of family papers; at 49:16–50:21 he describes four rewrites, trusted-reader feedback, and cutting at least 35,000 words. [investor-stated · strong] episode/audio
Quotes
- No quotation retained; the book body remains unavailable, while the processed audio supports only the timestamped origin and writing-process claims above.
Biography and decision evidence
- The memoir supplies a later-life account of refugee-family history that also appears in Stanford/DOJ direct testimony. Recurrence establishes consistency of the biography, not a causal proof of investment hunger or risk tolerance. [researcher inference · strong] publisher page, Stanford transcript
- The US product page says September 1, 2026 even though UK discussion and interviews appeared earlier in 2026; publication claims need territory/edition labels. [contemporaneous record · strong] Product Details
Philosophy signals
- risk / macro: history can sensitize an investor to institutional fragility, but applying that claim to specific deals requires decision-date evidence. [researcher inference · provisional] publisher synopsis
Contradictions, counterevidence, and access limits
- The publisher page and a direct podcast interview were available; no chapter-level argument, archive citation, or complete book analysis is claimed.
- Family trauma should not be retrofitted as a deterministic explanation for ambition or investment decisions. [researcher inference · strong] publisher synopsis
Open questions
- Obtain the correct UK and US editions and create a page-located note without reproducing protected text.
- Which specific archival collections are cited in the book and publicly accessible?
[w] Criticism, succession, geography, and institutional counterrecord
- URL: https://www.vanityfair.com/news/2015/12/michael-moritz-sequoia-women-partners-tech | Published: 2015-12-03; paired records through 2024 | Format: original-video route, criticism, firm succession essays, and governance reporting | Reliability: A for direct audio/firm statements; B for reported criticism | Access: mixed | Accessed: 2026-08-22 | Locator scheme: video exchange; dated article/essay headings and named claims
Takeaways
- Bloomberg's 2015 exchange records Moritz saying Sequoia looked hard for women but would not lower standards. Critical reporting argued that the framing treated an institutional pipeline/culture problem as candidate deficiency. [investor-stated · strong for words; insufficient for causal claim] original video, Vanity Fair
- The 2018 China column praised extreme work intensity; critics argued it confused hours with output and ignored family, health, labor-power, legal, and country-stage differences. [investor-stated · moderate] FT column, TechCrunch, VentureBeat
- Axios's 2017 account says Don Valentine handed leadership to Moritz and Doug Leone without selling it, while later steward roles broadened succession. This is institutional/team history, not solely Moritz's achievement. [retrospective witness · moderate] Axios, Leone quotation
- Botha's September 2023 Sequoia essay says the five business units collectively decided in early 2023 to become fully independent partnerships. This is the official firm position, is not Moritz-authored, and does not prove his personal support or role. [contemporaneous record · strong for firm statement] Crucible Moments, separation paragraph
- The 2024 Klarna board dispute exposed tension between former and current Sequoia leadership. Reporting about attempted removal/reversal is not a misconduct finding and must be separated from the later Nayak complaint. [contemporaneous record · moderate] FT boardroom report
Quotes
- No quotation retained; controversial remarks are paraphrased and linked to their primary video/column route.
Biography and decision evidence
- These records falsify a frictionless succession/standards narrative: renewal can coexist with exclusionary framing, geographic separation, and governance conflict. [researcher inference · strong] Axios, Sequoia essay
- Sequoia's later hiring or institutional changes can test process evolution but do not erase the original comments. [researcher inference · strong] Vanity Fair
Philosophy signals
- people: “standards” require validated criteria and a pipeline/process audit; otherwise the label can preserve incumbent networks. [researcher inference · moderate] original video
- macro / modern translation: hours are a weak proxy for learning velocity unless output, sustainability, retention, and legal conditions are observed. [researcher inference · moderate] TechCrunch criticism
- succession: durable institutions need explicit economic, brand, geography, and decision-rights separation, not merely new titles. [researcher inference · moderate] Sequoia essay
Contradictions, counterevidence, and access limits
- Critics also generalize from a short exchange or column; no cited source supplies a controlled productivity or hiring study specific to Sequoia.
- The official separation essay supplies Sequoia's rationale but not all economic arrangements, dissent, or geopolitical pressures.
- Klarna reporting is paywalled/partial; core legal and governance claims must use issuer/SEC/court records where available.
Open questions
- What measurable changes followed Sequoia's 2015 hiring controversy?
- Which documents specify the completed 2024 geography separation's economics, shared systems, and legacy interests?
- What board instruments and communications resolve the Klarna nomination dispute?
[w] Michael Moritz Financial Times corpus — byline and access reconciliation
- URL: https://www.ft.com/stream/2f2708a5-f7e1-4ef8-87a2-65e89ea14685 | Published: visible stream spans 2007–2026 across three pages; accessed 2026-08-22 | Format: mixed author/topic stream | Reliability: A for visible dates/bylines/headlines; not a clean authored-work denominator | Access: partial/paywalled | Accessed: 2026-08-22 | Locator scheme: page/card ordinal, card date, exact visible headline, visible byline/deck; individual canonical content UUID where recovered
Takeaways
- The live interface exposed exactly 63 cards across three pages on 2026-08-22 (25 + 25 + 13). The ledger below conservatively admits 36 cards to the authored set because a Michael Moritz byline or explicit “writes Michael Moritz” deck was visible, and excludes 27 reporting, review, compilation, third-party, or byline-unresolved cards. It cannot be reported as “63 Moritz essays.” [contemporaneous record · strong] FT stream
- The interface is a topic/author stream rather than a bibliography: it contains reporting about Moritz, an Ausländer review, profiles, a Booker Prize announcement, and several older cards without a displayed author. Ambiguous cards are excluded rather than inferred into the authored denominator. [researcher inference · strong] FT stream cards
- Reporting cards such as the July 2023 Sequoia departure and February 2024 Klarna dispute are about Moritz but lack his byline; they belong in press evidence, not the authored corpus. [contemporaneous record · strong] FT stream, 2023-07 and 2024-02 cards
- The 2018 China column is a distinct bylined work with a recovered canonical URL. Its normative praise of long hours generated serious counterarguments about productivity, welfare, labor power, and country-level overgeneralization. [investor-stated · moderate] FT column, TechCrunch criticism
- The full 2015 LinkedIn repost of The Dawn of the Profitable Unicorn is a processed direct-written route: Moritz argues for patience, profit discipline, and attention to Chinese competitors. Company examples remain selected and require outcome tests. [investor-stated · moderate] LinkedIn essay
Card-level reconciliation — exact live sweep on 2026-08-22
Access code M/P means the stream-card metadata was inspected but the article body remained unreviewed behind the FT subscription barrier. “Authored” requires a visible Michael Moritz byline or an explicit card deck saying he wrote the item; missing bylines are not backfilled from inference. Page ordinals are stable locators only for this dated sweep.
| # | Date | Exact visible title | Visible byline / disposition | Access |
|---|---|---|---|---|
| 1 | 2026-05-17 | In America, wealth taxes mean wealth flight | Michael Moritz — authored | M/P |
| 2 | 2026-01-20 | Ausländer by Michael Moritz — a Holocaust story with echoes in the present | No Moritz byline; review of his book — excluded | M/P |
| 3 | 2026-01-13 | California’s billionaire tax plan will backfire | Michael Moritz — authored | M/P |
| 4 | 2025-09-25 | US philanthropists bring big-money giving habit to UK institutions | No Moritz byline; reporting that includes his philanthropy — excluded | M/P |
| 5 | 2025-09-24 | Trump’s H-1B visa caper will backfire | Michael Moritz — authored | M/P |
| 6 | 2025-08-10 | Intel must not bow to Trump’s attack on its CEO | Michael Moritz — authored | M/P |
| 7 | 2025-06-08 | Musk vs Trump is a cautionary tale for Silicon Valley | Michael Moritz — authored | M/P |
| 8 | 2025-05-07 | Trump’s sovereign wealth fund idea is born of envy rather than sense | Michael Moritz — authored | M/P |
| 9 | 2025-04-15 | Want a winning economic policy for America? Learn from Andy Grove | Michael Moritz — authored | M/P |
| 10 | 2024-08-05 | Silicon Valley’s Trump supporters are making a big mistake | Michael Moritz — authored | M/P |
| 11 | 2024-02-24 | How Klarna’s boardroom spat exposed a schism at Sequoia Capital | No Moritz byline; subject reporting — excluded | M/P |
| 12 | 2024-02-20 | Sequoia abandons effort to oust Michael Moritz from Klarna board | No Moritz byline; subject reporting — excluded | M/P |
| 13 | 2024-02-17 | Sequoia looks to oust Moritz from Klarna in boardroom dispute | No Moritz byline; subject reporting — excluded | M/P |
| 14 | 2024-02-16 | Jim Ratcliffe could be just what Manchester United needs | Michael Moritz — authored | M/P |
| 15 | 2023-10-19 | Manchester United is a tarnished trophy asset | Michael Moritz — authored | M/P |
| 16 | 2023-07-19 | Michael Moritz leaves Sequoia Capital after almost 40 years | No Moritz byline; subject reporting — excluded | M/P |
| 17 | 2023-03-12 | SVB provided for tech when everyone else ignored us | Michael Moritz — authored | M/P |
| 18 | 2023-02-08 | San Francisco’s drug and homeless crises can’t go on | Michael Moritz — authored | M/P |
| 19 | 2022-10-11 | Lyft wants a free ride from California’s richest | Michael Moritz — authored | M/P |
| 20 | 2022-05-15 | An online sales tax will further blight the high street | Michael Moritz — authored | M/P |
| 21 | 2022-03-09 | Tim Cook pay vote shows ISS should not be judge and jury | Michael Moritz — authored | M/P |
| 22 | 2021-09-02 | Can Big Tech be tamed? And can we trust those doing the taming? | No Moritz byline; review card — excluded | M/P |
| 23 | 2021-08-16 | The Lionel Messi saga is a lesson in how not to handle a prize asset | Michael Moritz — authored | M/P |
| 24 | 2021-01-12 | Business must set aside self-interest to battle extremism | Michael Moritz — authored | M/P |
| 25 | 2020-12-01 | Michael Moritz named chairman of Swedish fintech Klarna | No Moritz byline; subject reporting — excluded | M/P |
| 26 | 2020-05-04 | The business world can never go back to the way things were | Michael Moritz — authored | M/P |
| 27 | 2020-04-24 | A Race with Love and Death — Britain’s pioneering Grand Prix driver | No Moritz byline; review card — excluded | M/P |
| 28 | 2020-01-15 | Michael Moritz backs Turkish grocery start-up | No Moritz byline; subject reporting — excluded | M/P |
| 29 | 2019-11-12 | Uber is treated as a modern utility to be regulated like the rest | Michael Moritz — authored | M/P |
| 30 | 2019-10-24 | Winners in Silicon Valley put in the hard yards | Michael Moritz — authored | M/P |
| 31 | 2019-08-18 | Investment banks are losing their grip on IPOs | Michael Moritz — authored | M/P |
| 32 | 2019-08-02 | Geraint Thomas is the true champion of the Tour de France | Michael Moritz — authored | M/P |
| 33 | 2019-07-04 | Lee Iacocca: a storyteller disguised as a business leader | Michael Moritz — authored | M/P |
| 34 | 2019-05-21 | The cloud kitchen brews a storm for local restaurants | Michael Moritz — authored | M/P |
| 35 | 2019-04-01 | A Swedish newspaper’s reinvention points the way for the industry | Michael Moritz — authored | M/P |
| 36 | 2019-03-01 | Michael Moritz, the tech investor backing books | No Moritz byline; profile — excluded | M/P |
| 37 | 2019-02-28 | Venture capitalist Michael Moritz to sponsor Booker Prize | No Moritz byline; subject reporting — excluded | M/P |
| 38 | 2018-11-23 | Best books of 2018: critics’ picks | No single Moritz byline; multi-contributor compilation — excluded | M/P |
| 39 | 2018-06-17 | China is winning the global tech race | Michael Moritz — authored | M/P |
| 40 | 2018-01-17 | Silicon Valley would be wise to follow China’s lead | Michael Moritz — authored | M/P |
| 41 | 2017-12-05 | US tax reform will benefit shareholders more than workers | Michael Moritz — authored | M/P |
| 42 | 2017-09-10 | China is leaving Donald Trump’s America behind | Michael Moritz — authored | M/P |
| 43 | 2017-01-30 | Silicon Valley chiefs are right to condemn Trump’s irrational ban | Michael Moritz — authored | M/P |
| 44 | 2017-01-19 | The ‘internet of bicycles’ is China’s latest export | Michael Moritz — authored | M/P |
| 45 | 2016-06-17 | Alphaville. Silicon Valley vs. Trump | Kadhim Shubber — third-party commentary — excluded | M/P |
| 46 | 2016-06-16 | To the bright and the rich of Silicon Valley, Trump is a loser | Michael Moritz — authored | M/P |
| 47 | 2016-04-22 | Europe should forget Google and investigate its own shortcomings | Michael Moritz — authored | M/P |
| 48 | 2016-04-08 | Investors, first catch your unicorn then hang on to it | Michael Moritz — authored | M/P |
| 49 | 2016-03-24 | FT Weekend Oxford Literary Festival highlights | No Moritz byline; event roundup — excluded | M/P |
| 50 | 2015-12-03 | The fall and rise of technology juggernauts | Card deck says “writes Michael Moritz” — authored | M/P |
| 51 | 2015-11-10 | #techFT – Job One for Jobs emulators | No Moritz byline; format/relationship unresolved — excluded | M/P |
| 52 | 2015-11-10 | Cutting through a web of wires | No visible byline/deck attribution — excluded pending byline access | M/P |
| 53 | 2015-11-02 | When a leader is not a manager and other modern myths | No visible byline/deck attribution — excluded pending byline access | M/P |
| 54 | 2015-09-25 | The striking partnership of Alex Ferguson and Michael Moritz | No Moritz byline; subject/interview feature — excluded | M/P |
| 55 | 2015-03-25 | ‘Becoming Steve Jobs’, by Brent Schlender and Rick Tetzeli | No Moritz byline; review card — excluded | M/P |
| 56 | 2015-03-11 | Alex Ferguson reveals secrets of his success | No Moritz byline; subject/book reporting — excluded | M/P |
| 57 | 2015-02-03 | Technology’s next 25 years belong to the world, not the US | Card deck says “writes Michael Moritz” — authored | M/P |
| 58 | 2014-08-17 | Swedish online payments group Klarna hires former Asos executive | No Moritz byline; company reporting — excluded | M/P |
| 59 | 2014-07-07 | How united is UK business on Brexit? | Brian Groom — third-party reporting — excluded | M/P |
| 60 | 2013-06-14 | Queen’s birthday honours list gets back to business | No Moritz byline; honours reporting — excluded | M/P |
| 61 | 2009-03-11 | Cotendo a contender in crowded CDN market | Chris Nuttall — third-party reporting — excluded | M/P |
| 62 | 2008-05-12 | Silicon Valley VC: the cash keeps rolling in | Richard Waters — third-party reporting — excluded | M/P |
| 63 | 2007-03-26 | Google: exit of the VCs | Richard Waters — third-party reporting — excluded | M/P |
The resulting card denominator is 63 = 36 authored + 27 excluded. It is a dated interface observation, not a claim that the FT hosts only 36 Moritz works: three ambiguous 2015 cards remain excluded pending licensed byline access, and a later interface revision could add, remove, or reorder cards.
Quotes
- No quotation retained from paywalled bodies. Headlines and short deck text are used only as metadata.
Biography and decision evidence
- The corpus demonstrates that Moritz became a recurring public commentator on technology, capital, governance, cities, immigration, politics, and sport. Frequency does not establish that every topic formed his venture process. [researcher inference · strong] FT stream
- The 2015 subprime-unicorn material and later 2023 SVB column show continuing interest in financing regimes and institutional scrutiny, but full-body access is required before asserting stable reasoning across them. [researcher inference · provisional] 2015 origin index, 2023 article
Philosophy signals
- risk / valuation: private status can delay external scrutiny; capital abundance does not repeal business-quality constraints. [investor-stated · moderate] 2015 contemporaneous report
- macro / people: Moritz repeatedly connects technology outcomes to institutions, talent migration, work norms, and public policy; whether each link survives causal testing varies by column. [researcher inference · moderate] FT stream
Contradictions, counterevidence, and access limits
- The stream is a discovery interface, not an archive manifest: result counts and ordering can drift, author and subject cards co-mingle, and older pagination can change.
- Paywalled articles were not reconstructed from snippets or syndication. Only title/date/byline and lawfully visible summaries are treated as known.
- The 2018 hours thesis may confuse hours with output and omit labor-law, family, health, and bargaining-power conditions. Contemporary critics also generalize; neither side supplies a prospective productivity study. [researcher inference · strong] TechCrunch, VentureBeat
Open questions
- Obtain licensed article bodies and create one note per decision-relevant bylined column with paragraph locators.
- Export the FT author page year by year to produce a stable, deduplicated authored denominator without counting subject reporting.
[w] Going for Broke: The Chrysler Story
- URL: https://search.worldcat.org/title/going-for-broke-the-chrysler-story/oclc/7460014 | Published: 1981 first edition; later 1984 Anchor edition carries “Lee Iacocca's Battle to Save Chrysler” subtitle | Format: coauthored book catalog | Reliability: A for bibliographic metadata; content reliability not assessed without text | Access: metadata only | Accessed: 2026-08-22 | Locator scheme: WorldCat title, author, edition, publisher, and OCLC fields
Takeaways
- WorldCat identifies Michael Moritz and Barrett Seaman as coauthors of a 1981 Doubleday first edition. The frequently seen 1984 date refers to a later edition, not the original publication. [contemporaneous record · strong] WorldCat record
- The subject—a corporate rescue under capital, operational, political, and governance pressure—is potentially relevant to later board work, but no investment rule is extracted without the text and corroborating later behavior. [researcher inference · insufficient public record] WorldCat record
Quotes
- No quotation retained; book text was not lawfully available in full.
Biography and decision evidence
- The record adds a corporate-turnaround reporting project to Moritz's pre-venture biography and preserves Seaman's coauthorship. It cannot be described as a sole-authored Moritz book. [contemporaneous record · strong] WorldCat authorship/edition fields
Philosophy signals
- boards / risk: a plausible later link is attention to cash survival and leadership under stress, but this remains a research hypothesis, not an investor-stated rule from the inaccessible book. [researcher inference · insufficient public record] WorldCat record
Contradictions, counterevidence, and access limits
- Edition conflict: 1981 first edition versus 1984 later edition/subtitle. Both are valid metadata for different editions; silently choosing one creates false chronology.
- Content was not analyzed from reviews, snippets, or unrelated similarly titled books. No claimed reasoning chain, evidence set, or conclusion is attributed to Moritz.
Open questions
- Obtain a licensed copy and isolate Moritz versus Seaman attribution where the collaboration record permits.
- Test whether any cash, governance, or leadership observations recur in contemporaneous board records rather than retrospective analogy.
[w] Google — financing, board, and ownership primary record
- URL: https://googlepress.blogspot.com/1999/06/google-receives-25-million-in-equity.html | Published: 1999-06-07; paired S-1 filed 2004-04-29 | Format: company press release plus SEC registration statement | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: release body; S-1 Management and Principal and Selling Stockholders, printed pp. 69 and 84–85
Takeaways
- Google announced $25 million in aggregate equity funding from Kleiner Perkins and Sequoia and said John Doerr and Michael Moritz joined the board. It did not disclose a firm-by-firm check split. [contemporaneous record · strong] 1999 release
- The April 2004 S-1 says Moritz had served as a director since May 1999. [contemporaneous record · strong] S-1, Management
- The S-1's March 31, 2004 principal-stockholder table reports 23,893,800 Sequoia shares. Footnote 3 itemizes five Sequoia-linked vehicles and says Moritz disclaimed beneficial ownership beyond his pecuniary interest. [contemporaneous record · strong] S-1, printed pp. 84–85
Quotes
- No quotation retained; facts are paraphrased from the release and filing.
Biography and decision evidence
- This pair establishes timing, board seat, aggregate round size, and a later fund-vehicle block. It does not prove Moritz alone sourced or approved the investment, Sequoia's exact initial check, personal ownership, realized proceeds, or a return multiple. [researcher inference · strong] 1999 release, S-1, printed pp. 84–85
- Digital Riptide later recalled the investment as centered on superior search technology and an early Yahoo licensing relationship. That is Moritz's 2013 retrospective, not evidence written in 1999. [retrospective witness · moderate] Digital Riptide, Google discussion
Philosophy signals
- picking: superior product technology can be investable before the final business model is settled. [investor-stated · moderate] Digital Riptide, Google discussion
- boards / attribution: co-investor board seats and fund vehicles imply distributed governance and capital, not a lone-genius case. [researcher inference · strong] 1999 release
Contradictions, counterevidence, and access limits
- Do not repeat 23,894,106 or later percentage figures as if they came from this S-1; this dated table says 23,893,800. Any difference in later filings must be reconciled by filing date and table.
- The official Sequoia company page supplies a retrospective rationale and Moritz attribution, but it is not independent of Sequoia and cannot reveal rejected alternatives or fund cash flows. [researcher inference · strong] Sequoia Google page
Open questions
- What contemporaneous memo or founder testimony fixes Sequoia's check, ownership at investment, and partner decision rights?
- What distribution/sale filings permit a fund-level, dilution-aware economic reconstruction?
[w] Green Dot — issuer/dissident proxy-fight evidence
- URL: https://www.sec.gov/Archives/edgar/data/1386278/000138627816000148/a2016-05x16defa14amoritzle.htm | Published: 2016-05-16; paired 2010 S-1 and 2016 dissident/issuer materials | Format: SEC-filed shareholder communications | Reliability: A for what each side filed; interested and not neutral on disputed performance | Access: full | Accessed: 2026-08-22 | Locator scheme: filing headings, proxy-deck pages, and named claims
Takeaways
- Green Dot's 2010 S-1 says Moritz had served as a director since 2003 and supplies fund/ownership context. [contemporaneous record · strong] S-1/A, Management and stockholder sections
- Harvest's 2016 dissident deck alleged underperformance and stale governance; those are proxy-contest allegations and analyses, not adjudicated facts. [contemporaneous record · moderate] Harvest deck
- Moritz's issuer-filed letter and Green Dot's defense argued that his experience and contributions justified continuity. They are direct/issuer positions, not independent proof of value creation. [investor-stated · moderate] Moritz letter, issuer defense
Quotes
- No quotation retained; opposing claims are paraphrased symmetrically.
Biography and decision evidence
- The four-record set creates an informative ordinary/governance case outside the best-known wins and tests whether long tenure reflects useful institutional memory or entrenchment. [researcher inference · moderate] S-1/A, Harvest
- Public filings establish service and arguments but do not disclose Moritz's private board work, full causal effect, or Sequoia's investment cash flows. [researcher inference · strong] issuer defense
Philosophy signals
- boards: tenure should be justified by current, observable contribution rather than reputation alone. [researcher inference · moderate] opposing filings
- risk / governance: an adversarial proxy record is more diagnostic than an issuer biography because it exposes competing interpretations and falsifiers. [researcher inference · strong] Moritz letter
Contradictions, counterevidence, and access limits
- Both sides are interested. Share-price or operating comparisons can be sensitive to endpoints, peer sets, strategy horizons, and market conditions; none is adopted without reproducing the method.
- No court/regulator found that either proxy narrative was true. A vote outcome would show shareholder choice, not causal proof.
Open questions
- Reconstruct the shareholder vote and subsequent operating/board changes using issuer filings.
- Which claimed Moritz interventions have independent contemporaneous support?
[w] Klarna — current board, ownership, and 2026 transaction record
- URL: https://www.sec.gov/Archives/edgar/data/2003292/000200329226000007/klar-20251231.htm | Published: Form 20-F filed 2026 | Format: SEC annual report plus issuer governance/transaction pages | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: 20-F beneficial ownership, board/compensation, signature; issuer Leadership and dated news release headings
Takeaways
- Klarna's leadership page says Moritz has been a director since July 2010, chair since December 2020, and a Sequoia partner through July 2023; it lists his current Heritage and Crankstart roles separately. [contemporaneous record · strong] Leadership, Michael Moritz
- Klarna's January 2024 announcement says the original 2010 Sequoia investment was led by Moritz. This is issuer attribution, not a disclosed check, ownership, or internal approval record. [contemporaneous record · moderate] Matthew Miller appointment release
- The 2025 20-F uses CIK 2003292 and supplies current Sequoia voting-control, board, compensation/equity, risk, and chair-signature evidence. It must not be confused with similarly named entities or stale private-company records. [contemporaneous record · strong] 20-F
- Form 3 Table I reports 3,472,845 ordinary shares held indirectly through Crankstart Foundation; footnote 1 says the March 3–11 purchases cost $49,913,138.73 at $13.1791–$16.1128 per share. Table II separately reports 37,500 RSUs held directly, with four equal annual vesting installments under footnote 2. [contemporaneous record · strong] Form 3, PDF p. 1, Tables I–II and footnotes 1–2
Quotes
- No quotation retained; legal/transaction facts are paraphrased.
Biography and decision evidence
- Klarna is both a long-duration board case and a live post-Sequoia financial exposure. It can test governance/compounding claims, but unrealized market value and new purchases are not realized venture returns. [researcher inference · strong] 20-F
- The 2024 board dispute exposes succession and decision-rights tensions between past and current Sequoia leaders; reported conflict does not itself establish misconduct. [contemporaneous record · moderate] FT boardroom report
Philosophy signals
- boards / succession: long-term governance depends on explicit nomination, removal, and ownership rights, not prestige. [researcher inference · moderate] 20-F governance sections
- portfolio: a large later purchase may signal conviction but cannot validate price, future return, or the original thesis. [researcher inference · strong] 2026 transaction release
Contradictions, counterevidence, and access limits
- Crankstart's 3,472,845 indirectly held ordinary shares, Moritz's 37,500 directly held RSUs, and Sequoia entities' voting block are distinct categories. Collapsing them would fabricate ownership or economics.
- Current stock-price change is period-dependent and is not included without a dated market source and calculation method.
- The 2024 conflict reporting presents contested accounts; the later Sequoia reversal/settlement of position requires exact source-local treatment.
Open questions
- What entity made the March 2026 purchase, and what beneficial-ownership footnote identifies it?
- What documents resolve the 2024 nomination/removal dispute and any continuing Sequoia rights?
[w] Leading: Learning from Life and My Years at Manchester United
- URL: https://www.hachettebookgroup.com/titles/alex-ferguson/leading/9780316268103/ | Published: 2015 original; publisher page for 2016 US trade paperback | Format: coauthored book/publisher description | Reliability: A for authorship, edition metadata, and visible description; content access partial | Access: partial | Accessed: 2026-08-22 | Locator scheme: title/byline, description, product-details, and author headings
Takeaways
- Hachette attributes the book to Alex Ferguson and Michael Moritz and frames it around sustained leadership: hiring/firing, transition, teamwork, boards, failure, and adversity. [contemporaneous record · strong] description and byline
- The evidentiary subject is chiefly Ferguson's management experience, with Moritz as collaborator/synthesizer. A lesson from the book is not automatically a Moritz investment rule. [researcher inference · strong] publisher description
- Stanford's 2016 event explicitly used the book to ask about a few consequential decisions, creating a direct Moritz bridge from leadership themes to his own biography. [contemporaneous record · strong] Stanford transcript, opening pages
Quotes
- No book quotation retained because the licensed body was unavailable. Direct Stanford remarks are handled in the separate talk note.
Biography and decision evidence
- Moritz's collaboration with Ferguson reflects an interest in institutional durability and talent systems after decades at Sequoia. That timing is documented; causation between the book and Sequoia practice is not. [researcher inference · moderate] Hachette description, YC transcript
- Edition control: the original is commonly dated 2015, while the cited US trade-paperback page says September 20, 2016. Both dates must be labeled by edition/market. [contemporaneous record · strong] product details
Philosophy signals
- people: continually refresh a team and distinguish durable standards from incumbent entitlement. [researcher inference · moderate] publisher description, YC transcript
- boards / succession: leadership quality includes renewal and transition, not merely a founder's or investor's tenure. [researcher inference · moderate] publisher description
Contradictions, counterevidence, and access limits
- Publisher copy cannot support the book's full reasoning chain, examples, assumptions, or exceptions. No chapter is represented as deeply analyzed.
- Elite-sports analogies risk survivorship and selection bias: Ferguson's documented success does not validate the same rule in venture portfolios. [researcher inference · strong] publisher description
Open questions
- Obtain licensed full text and assign each substantive claim to Ferguson, Moritz, or joint synthesis.
- Which Sequoia succession records corroborate the book's renewal themes, and which contradict them?
[w] The Little Kingdom and Return to the Little Kingdom
- URL: https://books.google.com/books?vid=ISBN9780688039738 | Published: 1984 original; revised/expanded edition 2009 | Format: authored book with catalog/preview routes | Reliability: A for accessible authored text; B for scenes based on reporting and later prologue recollection | Access: partial | Accessed: 2026-08-22 | Locator scheme: original-edition ISBN 9780688039738; revised-title search route https://books.google.com/books?q=%22Return+to+the+Little+Kingdom%22+%22Michael+Moritz%22
Takeaways
- The 1984 book is Moritz's reported history of Apple while it was still a young private company; it is evidence of his pre-Sequoia research practice, not an investing memoir. [contemporaneous record · strong] original-edition catalog route
- The 2009 Return edition is revised and expanded. Treating its later framing as what Moritz or Apple knew in 1984 would leak hindsight into the record. [researcher inference · strong] revised-edition discovery route
- The transferable research behavior is hypothesis formation from interviews, documents, product observation, and company history; whether Moritz operationalized that process in venture decisions needs independent deal evidence. [researcher inference · provisional] publisher biography
Quotes
- No quotation retained because full licensed text and stable page locators were unavailable.
Biography and decision evidence
- The original work establishes proximity to early Apple and a deep reporting project before Moritz joined Sequoia in 1986. Proximity creates possible access/pattern-recognition advantages but does not prove investment judgment. [researcher inference · moderate] original-edition route, DOJ transcript, printed pp. 5–7
- Edition boundary: 1984 The Little Kingdom and 2009 Return to the Little Kingdom are related but not identical works; analysis must cite the edition actually read. [contemporaneous record · strong] original route, revised route
Philosophy signals
- sourcing: cultivate subject proximity and primary interviews before forming a narrative. [researcher inference · provisional] original-edition route
- risk: preserve the decision-date version of a story before later success makes the path appear inevitable. [researcher inference · moderate] Digital Riptide, opening/Yahoo discussion
Contradictions, counterevidence, and access limits
- Only catalog/preview material was available. No chapter-level argument, example, or wording beyond visible metadata is represented as fully processed.
- A journalist's access can improve information collection while also creating narrative-selection bias; the book alone cannot decide which effect dominated. [researcher inference · moderate] original-edition route
Open questions
- Obtain licensed copies of both editions and build a chapter-level change ledger.
- Which reported Apple observations recur in Moritz's documented Yahoo, Google, or PayPal decisions?
[w] Nayak v. Klarna — pending securities allegations
- URL: https://dockets.justia.com/docket/new-york/nyedce/1%3A2025cv07033/540168 | Published: filed 2025-12-22; docket active through at least 2026-05-08 | Format: federal docket mirror plus complaint PDF | Reliability: A/B for docket metadata; A for allegations pleaded, not their truth | Access: full public mirror | Accessed: 2026-08-22 | Locator scheme: docket filing number/date; complaint paragraphs and counts
Takeaways
- The EDNY docket identifies Nayak v. Klarna Group plc et al., case 1:25-cv-07033, filed December 22, 2025, and names Michael J. Moritz among defendants. [contemporaneous record · strong] docket header
- The complaint asserts Securities Act claims under §§11, 12(a)(2), and 15 concerning offering materials and named signatories/control persons. Those are plaintiff allegations, not established facts. [contemporaneous record · strong for pleading; insufficient for truth] complaint
- The docket showed appearances and a May 2026 briefing-order sequence; no merits judgment, liability finding, or class-certification order was identified in the reviewed public docket. [contemporaneous record · moderate] docket entries through 2026-05-08
Quotes
- No quotation retained; allegations are summarized with legal posture.
Biography and decision evidence
- The case belongs in a current risk/governance record because Moritz was chair/signatory defendant. It does not retroactively prove or disprove the 2010 investment thesis or board performance. [researcher inference · strong] complaint caption/counts
Philosophy signals
- boards / risk: a public-company chair faces disclosure and signatory exposure different from private-company venture governance. [researcher inference · moderate] complaint
Contradictions, counterevidence, and access limits
- No allegation is stated as fact, no absent adjudication is called exoneration, and no procedural order is characterized as a merits decision.
- Public mirrors may lag PACER. The alternate complaint mirror must be hash/pagination checked before treating it as a separate document; it is not independent corroboration.
Open questions
- Monitor the amended complaint, motion-to-dismiss briefing, class-certification posture, and any merits order.
- Compare each challenged statement with the exact registration statement/prospectus page and defense filings when available.
[w] PayPal — 1999 secondary purchase, board role, and pre-IPO ownership
- URL: https://www.sec.gov/Archives/edgar/data/1103415/000091205702005893/a2060419zs-1a.htm | Published: 2002-02-14 | Format: SEC Form S-1/A | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: Management, Certain Transactions, Principal and Selling Stockholders, and footnotes
Takeaways
- The filing says that in August 1999, Sequoia Capital purchased 15 million Series A preferred shares from Elon Musk for $5 million. It was a secondary purchase from Musk, not $5 million of primary financing to the company. [contemporaneous record · strong] S-1/A, Certain Transactions
- The principal-stockholder table reports Sequoia-linked holdings of 9.9% before the offering and identifies Moritz as a director/managing member through entity footnotes. [contemporaneous record · strong] S-1/A, Principal and Selling Stockholders
- A 2022 Sequoia deck says Roelof Botha remembered Moritz urging runway extension and business-model discipline in 2000. The source is Botha/Team Sequoia, not Moritz-authored or contemporaneous. [retrospective witness · moderate] Adapting to Endure, “Why We're Here” slide
Quotes
- No quotation retained; the filing and retrospective are paraphrased.
Biography and decision evidence
- The evidence supports an early Sequoia position, Moritz board role, and an unusually specific secondary transaction. It does not by itself establish the full financing sequence, personal economics, or every 2000 board decision. [researcher inference · strong] S-1/A
- The firm retrospective credits Moritz for the crisis instruction and Botha for narration; later Sequoia success and Botha's subsequent partnership create retrospective/institutional incentives that require labeling. [researcher inference · strong] 2022 deck
Philosophy signals
- risk / boards: when runway collapses, translate product use into gross-margin/cash evidence rather than preserving growth theater. [retrospective witness · moderate] Adapting to Endure, PayPal slide
- vehicles: secondary purchases can create fund ownership without adding company cash; financing labels matter. [researcher inference · strong] S-1/A, Certain Transactions
Contradictions, counterevidence, and access limits
- Treating the $5 million as a company investment overstates primary capital; calling 9.9% Moritz's personal ownership ignores the filing's entity structure.
- The Sequoia podcast/history page is a later firm product and cannot replace the issuer filing for financing facts. [researcher inference · strong] Sequoia PayPal retrospective
Open questions
- What exact ownership, dilution, distributions, and proceeds did each Sequoia vehicle realize?
- Is there a contemporaneous 2000 board memo supporting the runway story?
[w] Michael Moritz — official publisher biography
- URL: https://www.simonandschuster.com/authors/Michael-Moritz/262020703 | Published: current; accessed 2026-08-22 | Format: publisher biography and book index | Reliability: A for publisher-held identity/authorship metadata; B for career superlatives | Access: full | Accessed: 2026-08-22 | Locator scheme: “About The Author” and “Books by Michael Moritz” headings
Takeaways
- The publisher record dates Moritz's birth to Cardiff in 1954, identifies his former TIME role, calls him a regular FT contributor, and names The Little Kingdom among his books. [contemporaneous record · strong] About The Author
- It says he spent 35 years as a Sequoia partner and led the business from 1995 through 2012. This is useful publisher-vetted chronology, not a legal partnership ledger or audited performance record. [contemporaneous record · moderate] About The Author
- It says Moritz and Harriet Heyman formed Crankstart in 2001. That establishes a family-foundation route but does not identify the foundation as an owner of any Sequoia or Klarna security. [contemporaneous record · strong] About The Author
Quotes
- No quotation retained; the short publisher copy is paraphrased.
Biography and decision evidence
- The record supports a journalist-to-investor-to-author/philanthropist scaffold. It does not itself support a causal claim that journalism produced investment skill. [researcher inference · strong] About The Author
- The page currently lists only Ausländer in the visible books carousel while its biography says “several books”; the corpus therefore requires independent catalog reconciliation. [contemporaneous record · strong] Books by Michael Moritz
Philosophy signals
- people / institutions: the biography foregrounds institution building and philanthropy, but offers no investment-selection or portfolio rule. [researcher inference · insufficient public record] About The Author
Contradictions, counterevidence, and access limits
- “Most successful” is promotional language without a fund, vintage, cash-flow denominator, or method and is excluded from economic analysis. [researcher inference · strong] publisher biography
- The 35-year partner figure and 1986–2023 public career span can coexist only if “partner” and later transition/status dates are defined carefully; later issuer records say partner through July 2023. [researcher inference · moderate] Klarna leadership
Open questions
- Which Sequoia legal/LP record best fixes leadership and partner-status dates?
- Which publisher or library records reconcile every edition of all four books?
[w] Vehicle, ownership, and denominator control ledger
- URL: https://www.sec.gov/Archives/edgar/data/1312928/000118143112042358/xslF345X03/rrd351558.xml | Published: 2012-07-26 and paired filing dates | Format: SEC ownership/issuer records | Reliability: A | Access: full | Accessed: 2026-08-22 | Locator scheme: ownership tables, relationship footnotes, board biographies, and disclaimers
Takeaways
- Kayak's Form 4 maps Sequoia growth and venture entities to shared managers and carries a beneficial-ownership disclaimer. The reported blocks are not Moritz's personal shares. [contemporaneous record · strong] Kayak Form 4, footnotes 9–10
- Netezza, Ikanos, Green Dot, and China/U.S. growth filings add denominator companies and entity relationships but not personal sourcing or cash-flow returns. [contemporaneous record · strong] Netezza 13G, Ikanos Form 3, Sequoia exhibit
- Saba's filed 2003 release gives a useful then-current/prior board list, but board service cannot be counted as a complete portfolio or attributed investment set. [contemporaneous record · moderate] Saba release, About Michael Moritz
- Klarna Form 3 provides an exact current separation: 3,472,845 ordinary shares indirectly through Crankstart Foundation versus 37,500 directly held RSUs. [contemporaneous record · strong] Form 3, PDF p. 1
Quotes
- No quotation retained.
Biography and decision evidence
- Public filings support a searched denominator extending beyond famous wins: Saba, Green Dot, Kayak, LinkedIn, Flextronics, Netezza, Ikanos, Klarna, and others. It remains incomplete because private deals and internal attribution are not exhaustively disclosed. [researcher inference · strong] Saba release
- Flextronics records a 1993–2005 board span, illustrating long governance duration outside the internet flagship cases. [contemporaneous record · strong] issuer-filed release
Philosophy signals
- vehicles: legal control, beneficial ownership, pecuniary interest, and personal ownership are different fields. [researcher inference · strong] Kayak Form 4
- denominator: an investor thesis must survive ordinary board/deal cases, not only Google/Yahoo/PayPal. [researcher inference · strong] Saba record
Contradictions, counterevidence, and access limits
- A board-role denominator overcounts companies never sourced by the director and undercounts investments without a seat. It is a discovery set, not a portfolio denominator.
- Issuer acquisition values and market capitalizations are not Sequoia proceeds. No return multiple is computed without cash flows, ownership, dilution, and timing.
Open questions
- Reconcile official partner pages with every filing/company alias and follow-on rule.
- Obtain fund-level distributions or credible LP reporting to test economics after dominant outliers.
[w] Yahoo and Zappos — governance evidence and attribution limits
- URL: https://www.sec.gov/Archives/edgar/data/1011006/000091205702010171/a2073396zdef14a.htm | Published: Yahoo proxy 2002-03-18; Zappos oral history current | Format: SEC proxy plus firm-hosted multi-witness oral history | Reliability: A for proxy facts and attributed testimony; B for retrospective synthesis | Access: full | Accessed: 2026-08-22 | Locator scheme: Yahoo board/ownership tables and footnotes; Zappos named-speaker sections
Takeaways
- Yahoo's proxy supports board and ownership facts at the filing date but does not disclose the original Sequoia check, initial ownership, sole sourcing, or fund return. [contemporaneous record · strong] Yahoo proxy
- Moritz's 2013 Riptide recollection says Yahoo was Sequoia's first notable internet software/media investment and the differentiated belief was that a large free audience could support advertising. This is direct retrospective testimony, not a 1995 memo. [retrospective witness · moderate] Digital Riptide, Yahoo discussion
- The Zappos oral history assigns roles across Tony Hsieh, Alfred Lin, Moritz, Roelof Botha, and the partnership. It describes earlier LinkExchange governance, repeated Zappos passes, and scar tissue from Webvan/eToys/PlanetRx before the 2004 investment. [retrospective witness · moderate] Zappos oral history, named-speaker sections
Quotes
- No quotation retained; the multi-witness source is paraphrased by speaker/episode.
Biography and decision evidence
- Together, the records show evolution from an early free-to-consumer media bet to a later e-commerce case influenced by prior failures. They do not prove a mechanically repeatable Moritz-only method. [researcher inference · moderate] Riptide, Zappos
- The Zappos story says Moritz served temporarily as LinkExchange's interim CEO and later highlights Alfred Lin's operating role and eventual move to Sequoia. This is a people/influence chain, not sole-investor attribution. [retrospective witness · moderate] Zappos, Moritz/Lin sections
Philosophy signals
- picking: a free service can be viable if audience attention supports a credible monetization path. [investor-stated · moderate] Riptide, Yahoo advertising discussion
- risk / learning: prior category failures can sharpen diligence without requiring a permanent sector ban. [retrospective witness · moderate] Zappos oral history
- people / boards: governance may include recruiting or interim operating help, but the team map must preserve who actually performed each role. [researcher inference · moderate] Zappos named-speaker sections
Contradictions, counterevidence, and access limits
- Yahoo's later success makes the original advertising thesis look obvious; Riptide explicitly warns that early outcomes rested on a knife edge.
- Zappos is a curated Sequoia retrospective and lacks the full rejected-company denominator, terms, ownership, and internal dissent.
Open questions
- Recover contemporaneous Yahoo financing documents and exact Sequoia vehicle economics.
- Which Zappos partner sourced, sponsored, approved, negotiated, and authorized each follow-on?